Rollins: The Pest-Control Empire That Has to Find Its Customers Again
I. The Search Result That Changed the Story
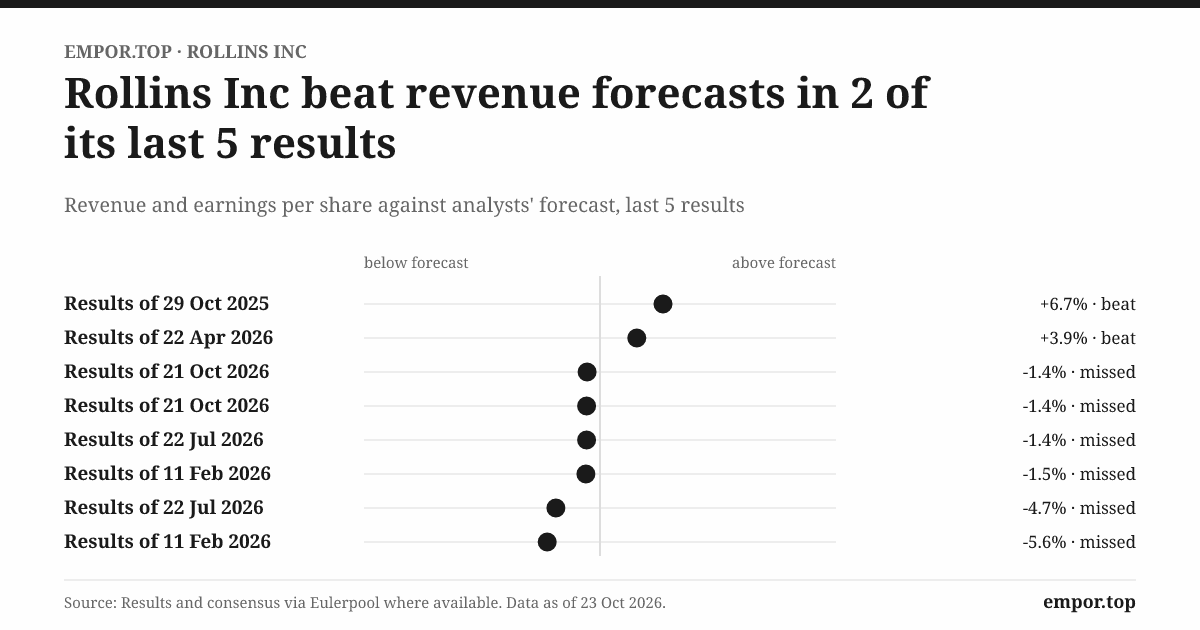
At 8:30 on the morning of October 22, 2026, Jerry Gahlhoff opened Rollins's third-quarter earnings call with a sentence chief executives usually try to avoid. "Our third quarter performance did not meet our expectations," he said, "and we are not satisfied with these results."1 The night before, the company's results release had put the same mood in writing: management was "disappointed" and "acting with urgency."2
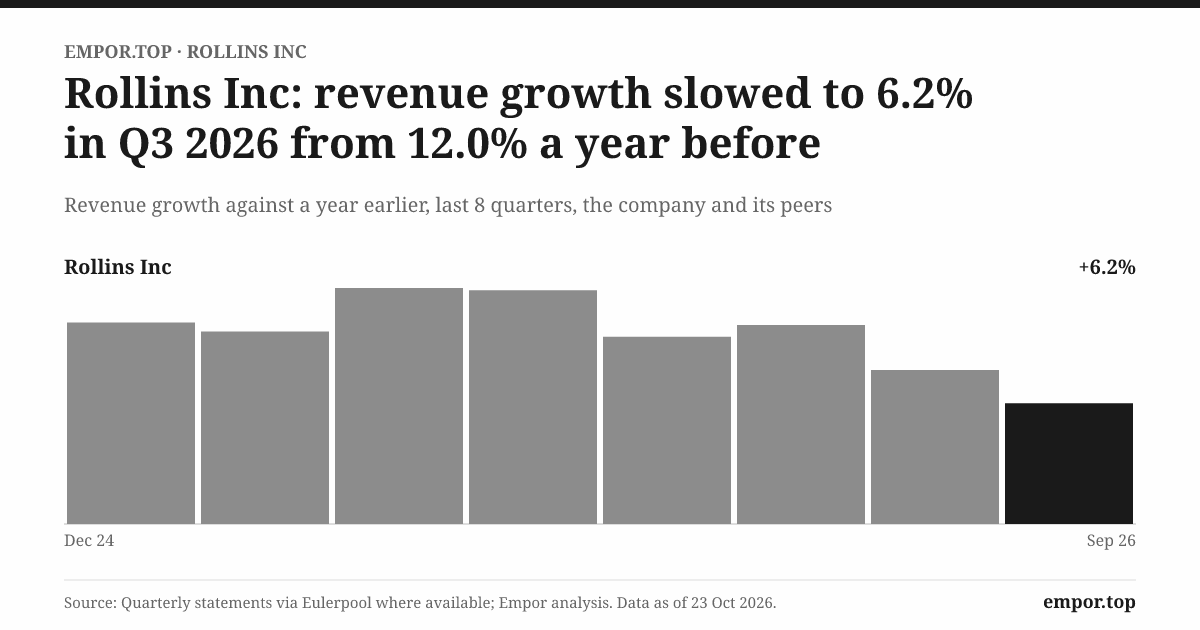
What makes the moment strange is that nothing visibly broke. No plant closed, no customer walked away, no product failed. Rollins still sent technicians to homes and restaurants and warehouses on schedule, still sprayed baseboards and checked bait stations and inspected crawl spaces for termites. Revenue rose 6.2% in the quarter, to about $1.09 billion.2 In most industries a 6% quarter would not require an apology. But strip out the businesses Rollins had bought over the previous year and organic growth was 4.4%, and in the residential business, the part of the company that knocks on the most doors, organic growth was 2.3%.2
Gahlhoff's explanation was the most modern thing anyone has said about pest control in a long time. People who discover ants in the kitchen no longer only type "exterminator near me" into a search box and click one of the first few links. More and more of them ask an AI model, and the large language models behind those answers recommend a wider and less predictable set of providers, varying by platform, by market and, as he put it, even by day.1 Management said the leads that used to arrive at Orkin's website in a steady, measurable stream had thinned. Management insisted that this was "not a deterioration in underlying demand for our services." It also said, tellingly, "we are not assuming a return to historical patterns."1
That pairing of phrases is the whole puzzle of this story. Rollins is a company built on repetition. Roughly three-quarters of its 2025 business was recurring service, visits scheduled monthly, every other month or quarterly, which is about as close to an annuity as a business with trucks and uniforms can get.3 Its results release reminded investors that the company had posted 100 consecutive quarters of revenue growth.2 Yet recurring revenue only recurs for customers you already have. Every year some customers move, sell the house, decide the spiders are tolerable, or switch to a cheaper local operator, and every year the company has to win new ones to replace them and grow. The third quarter of 2026 showed what happens when the front door of that machine starts to stick.
The numbers behind the mood were modest but real. Operating income slipped about 1%, and operating margin fell 140 basis points to 20.5%, as insurance and claims costs roughly doubled as a share of revenue and fuel pushed up fleet costs.2 Management cut its full-year organic growth outlook to a range of 4% to 6%, down from about 6% before, and said the midpoint simply assumed lead volumes stayed where they were in the third quarter.1 Meanwhile the company's own medium-term ambition, restated with some fanfare at an investor conference in May, was organic growth of 7% to 8% a year.4
So four questions sit on the table, and they will run through everything that follows. Can Orkin and the other Rollins brands keep winning customers as the way people discover a pest-control company fragments? Can the company get back to the growth rate that its history and its own medium-term targets imply? Can acquisitions and share buybacks keep compounding value per share now that the company carries real debt? And can a labor-intensive business adjust to a June 2026 Federal Trade Commission order that took away its ability to enforce noncompete agreements against most of its American workforce?
It helps to be clear at the outset about what Rollins is and is not. It is not a conglomerate with separately reported divisions whose values can be added up. It reports a single operating segment: pest control, termite protection and related services, sold under Orkin and a constellation of other brands, plus fees from franchisees who run their own businesses under the Orkin name.3 In 2025 that segment produced about $3.8 billion of revenue.3 Residential customers accounted for roughly $1.7 billion of it, commercial customers for about $1.2 billion and termite and ancillary work for nearly $800 million.3 Every question about Rollins is ultimately a question about that one business.
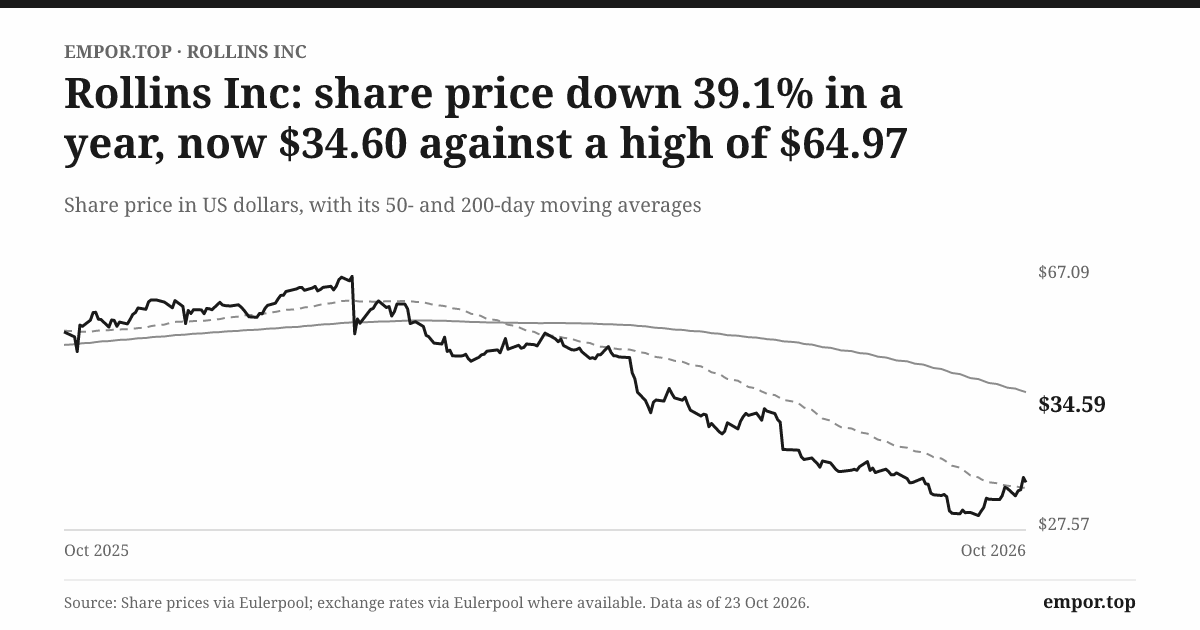
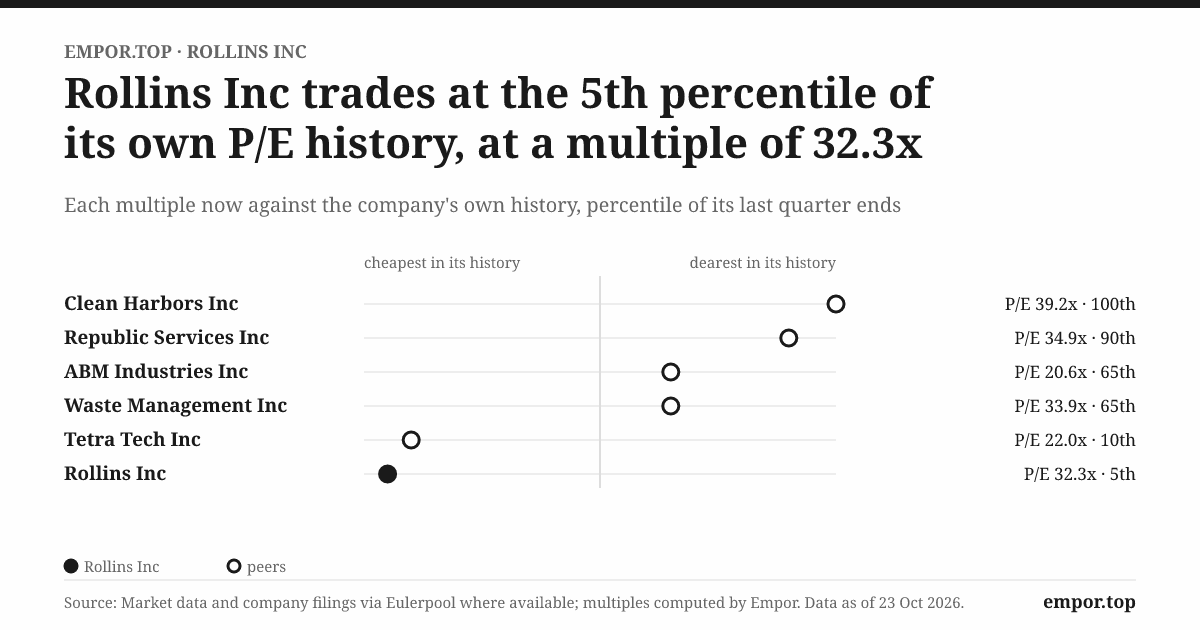
The stock market had already begun to answer the questions in its own blunt way. On October 23, 2026, Rollins shares traded at $34.60, about 47% below their 52-week high of nearly $65, leaving the company with a market value of about $17 billion.5 Even after that fall, investors paid about 32 times trailing earnings. That was well below Rollins's own five-year median of roughly 50 times, a multiple that once put a bug-spraying company in the valuation neighborhood of fast-growing software firms. But 32 times earnings is still a price for durable quality, not for a business in decline. The market had stopped paying for perfection; it had not stopped paying for reliability.
That leaves the paradox at the heart of Rollins in 2026. Its service routes are intensely local: a technician, a truck and a few hundred customers within a short drive. Its brands are national, and in Orkin's case known to almost every American who has ever seen a cockroach. And its next customer may now arrive through an answer generated by a machine that has never seen a cockroach at all. To understand why that matters so much, and why investors have been willing to pay so richly for so long, the story has to start with a radio company that made an outrageous bet on a man who called himself the Rat Man.
 Subscribe on LinkedIn
II. A Radio Company Bets on the Rat Man
Otto Orkin started the business that would carry his name in 1901, selling poison door to door, and he earned a nickname that a modern brand consultant would probably have vetoed: "The Rat Man."6 By the early 1960s the company he built, Orkin Exterminating, was a substantial, profitable Atlanta enterprise. It was also the kind of company that a pair of Southern entrepreneurs in the radio business had no obvious reason to own.
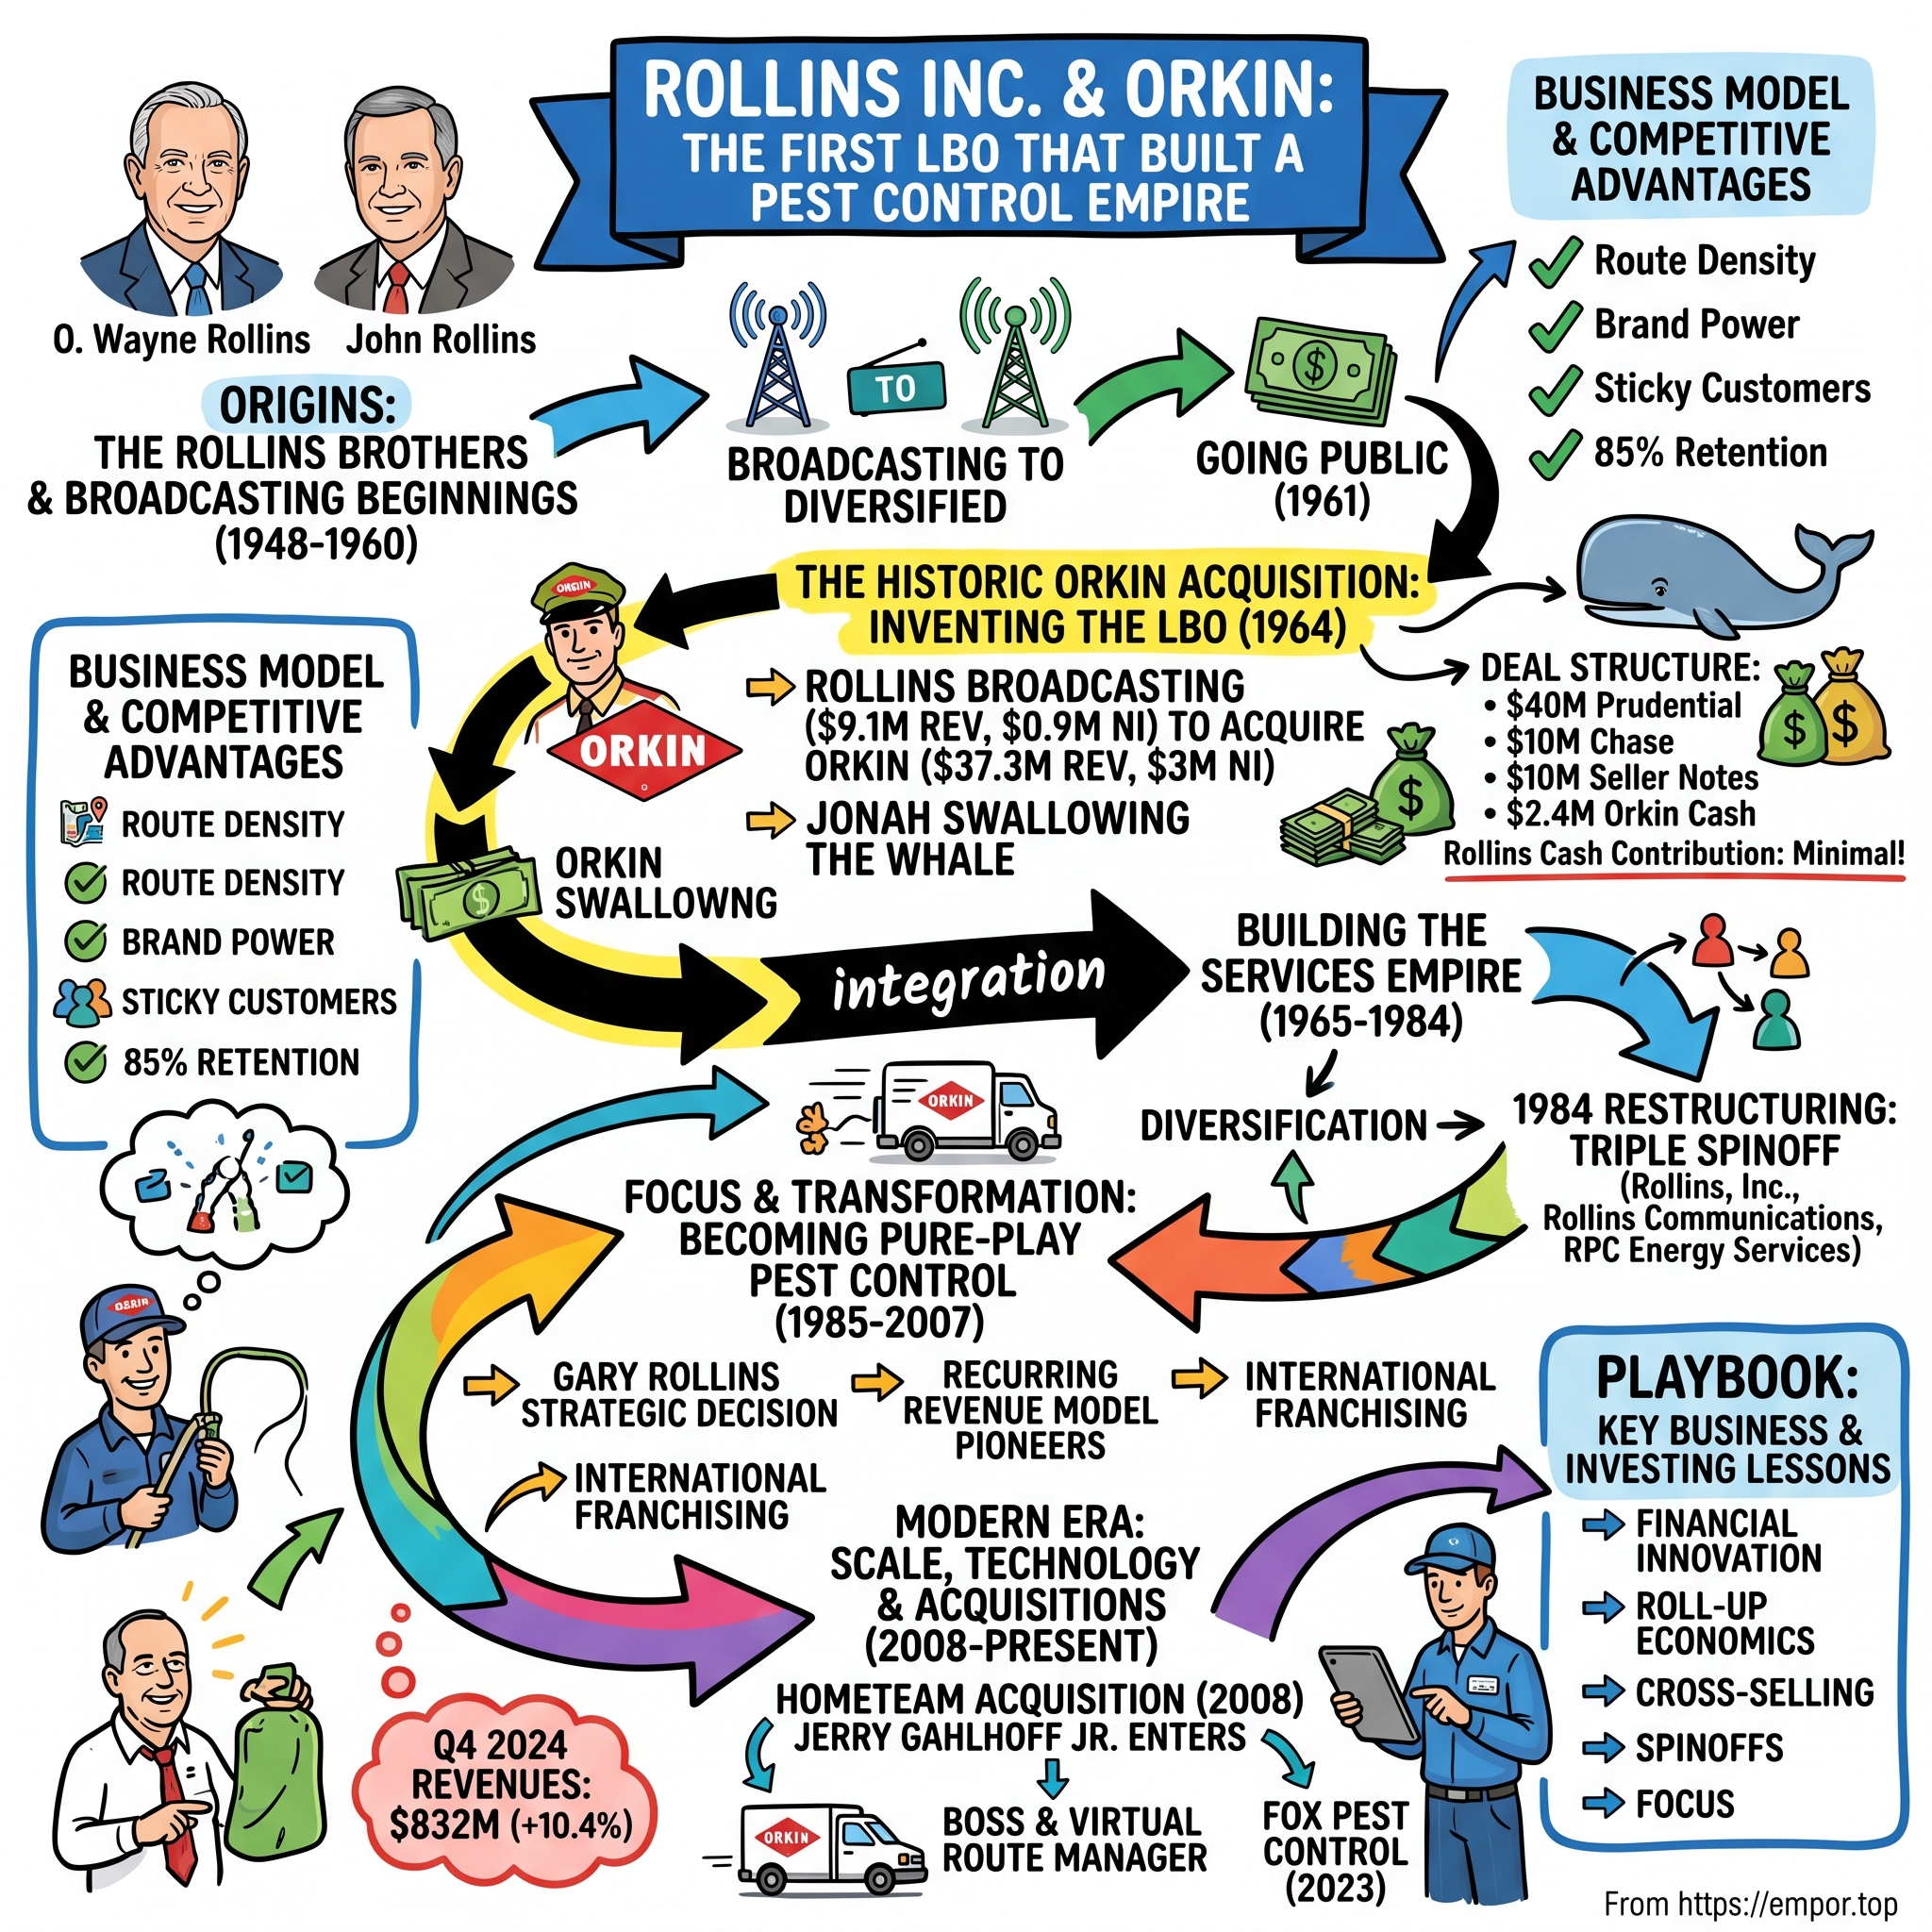
Those entrepreneurs were the brothers O. Wayne Rollins and John W. Rollins. They had started a string of businesses, among them a radio station, truck leasing and outdoor advertising, and the family enterprise that became Rollins, Inc. was founded in 1948.6 Wayne's son Randall, who would one day chair the company, went to work for his father and uncle straight out of high school in their start-up businesses in Delaware, later returning from the Coast Guard to Rollins Leasing and Rollins Broadcasting in Wilmington.7 Rollins Broadcasting went public in 1961, its shares trading on the American Stock Exchange.6 It was a growing, ambitious media company. It was also small.
In 1964 the brothers agreed to buy Orkin for $62.4 million.6 At the time Rollins had revenue of about $9 million.6 Put those two numbers next to each other and the audacity becomes clear: the buyer was paying roughly seven times its own annual sales to acquire a business much larger than itself. A company cannot pay for a deal like that out of its cash drawer. It has to borrow against the target, using the acquired company's own profits to service the debt. Rollins's own account, written decades later, calls the purchase "the first leveraged buyout in American business history."7
That label deserves a raised eyebrow. "First" is a claim that historians of finance argue about, and leveraged acquisitions of one kind or another existed long before 1964. The safer and still remarkable description is that Rollins pulled off an early, very bold leveraged buyout, buying a bigger company with the bigger company's own future cash flows. What it did not do was follow the modern private-equity playbook, with its fund structures, fixed holding periods and planned exits. The Rollins family was not buying Orkin to flip it. The family was buying a new identity.
The deal quickly reshaped the buyer. The company changed its name from Rollins Broadcasting to Rollins, Inc. in 1965, moved its headquarters from Wilmington to Atlanta, Orkin's home, in 1967, and listed its shares on the New York Stock Exchange in 1968.36 The listing gave Rollins a public-market platform for raising capital and a currency for later deals. The Orkin acquisition gave it something more important: an operating business with a recognized brand, a field workforce and a customer base that paid for the same service over and over.
It is worth pausing on why a radio company might have seen something in pest control that others missed. Broadcasting and extermination look unrelated, but both reward a business that can sell to a large audience repeatedly and build a name people remember. A radio station sells the same airtime every day; a pest-control company sells the same protection every season. Both depend on local presence, whether a transmitter or a branch office, and both benefit when the brand is familiar before the customer needs it. In buying Orkin, the Rollins brothers were buying a recurring revenue machine at a time when that phrase had not yet become an investor cliché.
What the deal did not settle was what kind of company Rollins would become. After Orkin, the family diversified into other service industries, including security and lawn care, alongside the broadcasting, outdoor advertising and oil-and-gas services businesses it already had or acquired.7 For two decades Rollins was a family-controlled collection of businesses with a pest-control giant in the middle. The question the 1964 deal left behind was whether pest control would remain one asset among many, or become the business that mattered. The family's answer came twenty years later, and it involved taking the company apart.
III. From Conglomerate to Pest-Control Specialist
In 1984 the Rollins family did something that conglomerate builders rarely do willingly: it broke its empire into pieces. Rollins, Inc. was split into three separate public companies.7 Pest control stayed with Rollins, Inc. Broadcasting and outdoor advertising went to Rollins Communications. The oil and gas services business became RPC Energy Services, later known as RPC, Inc.7 Randall Rollins took executive roles at the two new companies, while the family kept a grip on all three.7
The split matters to a 2026 investor for a simple reason. When someone buys a share of Rollins today, the economics they are buying are pest-control economics. The broadcasting towers and oilfield equipment are long gone from the balance sheet, even if the family ties linger; John Wilson, Rollins's executive chairman, also sits on the boards of RPC and Marine Products, the companies that trace back to the same family tree.8 The 1984 separation clarified what Rollins was. It did not, by itself, guarantee that the company would be good at it.
The decades that followed were about building the pest-control business outward, and two moves stand out. The first was franchising. Rollins opened its first Orkin franchise in 1995, then took Orkin abroad through franchises in Mexico in 2000 and later in China and Africa.6 Franchising lets a brand reach markets where owning branches would be too costly or too unfamiliar. But it also changes the accounting picture in a way that matters for anyone reading the company's numbers. Franchisees are independent businesses. Their technicians are not Rollins employees, and the service revenue they collect from homeowners is theirs; Rollins books the royalties and fees it earns from them.3 When Rollins describes more than 800 company-owned and franchised locations in roughly 70 countries, the franchised locations extend the brand's reach far more than they extend the company's income statement.3
The second move was a slow change in acquisition philosophy. For years the instinct was to buy local operators and paint their trucks Orkin orange. Then, in 2004, Rollins bought Western Pest Services and, for the first time with a major acquisition, kept the acquired brand rather than folding it into Orkin.6 That sounds like a minor branding decision. It was really a bet that local reputation can be worth more than national recognition, that a customer in New Jersey who has trusted Western for decades may not want a different name on the truck. That bet would shape the next twenty years, as Rollins assembled a portfolio that came to include HomeTeam, Clark, Northwest, Crane, Critter Control, Fox, Saela and others, many of them still selling under their own names.63
The compounding that resulted is impressive by any standard. From 2015 to 2025, Rollins grew revenue at about 9.7% a year and net profit at about 13.2% a year.3 Over the most recent three years of that stretch, revenue growth accelerated to almost 12% a year, helped by a heavier pace of acquisitions.3 For a business that sells something as unglamorous as termite inspections, that is a remarkable record. Profit grew faster than revenue because margins widened and, in the later years, a lower U.S. corporate tax rate lifted net income. The pattern made Rollins a favorite of investors who wanted steady growth without technology risk.
Then came 2026. By the third quarter, reported growth had slowed to about 6% and organic growth to 4.4%, below the long-run pace that had defined the company for a decade.2 The record did not vanish, but it stopped being a forecast.
It also helps to look at what "recurring" really means inside Rollins. The company said that in 2025 about 75% of its business was recurring service, 10% was ancillary and 15% was one-time work.3 Ancillary services are add-ons such as insulation or moisture control sold to existing customers; one-time services are jobs like clearing out a wasp nest or a single rodent treatment. Recurring service is the majority, but a quarter of the business has to be sold fresh, job by job, and even the recurring share depends on initial contracts that are generally for one year.3 That is why the third-quarter call spent so much time on cross-selling: when fewer new residential customers come in, there are also fewer homes in which to sell a termite plan or an attic job later.1
So the history leaves a more demanding definition of the word "recurring." It does not mean guaranteed. It means a customer who has to be won once, served well enough on every visit to renew, and offered enough additional value to stay for years. The 1984 split gave Rollins a clear identity as a pest-control company. Whether that identity is a moat depends on what happens at a much smaller scale: one technician, one truck, one route.
IV. The Route Is the Product
Picture a technician pulling into a driveway on a Tuesday morning. The customer probably will not be home. The technician walks the perimeter, treats the foundation, checks the bait stations along the fence line, knocks down a few cobwebs under the eaves, leaves a note on the door and is back in the truck in well under an hour, heading to the next house a few streets away. The homeowner is not buying a spray. The homeowner is buying the absence of a problem: no ants in the pantry, no scorpions in the shoes, no termites quietly eating the floor joists. And Rollins is buying something too, every time that truck turns onto the next street. It is buying density.
The service cadence is the foundation of the model. Residential and commercial customers are generally served monthly, every other month or quarterly, and many sign an initial contract for one year; termite renewal programs can run longer.3 Rollins recognizes revenue as it performs the work, and most multi-year agreements are billed annually.3 Notably, there is no standard published price per visit. Prices are set in each customer's contract, and the company does not disclose an average ticket, a minimum commitment or a lifetime value per customer.3 That absence matters. It means anyone who models Rollins as a subscription software company with a known churn rate and a known price per seat is building on assumptions the company has never confirmed.
What can be said is how the economics are supposed to work. A pest-control route is a bundle of fixed costs: the technician's wages and benefits, the truck, fuel, insurance, the branch office, the manager. Most of those costs are incurred whether the technician visits eight homes a day or twelve. Every additional customer on an existing route, especially one a few doors from another customer, adds revenue with relatively little added driving time. Route density, in other words, is the pest-control equivalent of an airline's load factor. The plane flies anyway; the profit is in filling the seats.
That is why a brand, a field workforce and acquisitions fit together. Recognizable brands make it more likely a homeowner calls Rollins rather than a stranger. Trained technicians make it more likely the homeowner stays, because a pest-control customer usually judges the company by the person who shows up. Local managers fill the routes, and acquired companies add customers in places where Rollins wants more density. Each is a plausible mechanism for advantage. None of them, on its own, is proof of a moat. The proof would be customer retention, technician utilization and route-level margins, and Rollins does not publish those numbers in its annual report.3
What the company does publish is the shape of its cost base, and it is unmistakably a people business. Rollins ended 2025 with 21,946 employees, about 19,700 of them in the United States and most of those in branch offices.3 Headcount had been about 19,000 at the end of 2023.3 In 2025 headcount rose about 8% while revenue rose 11%, a sign that each employee was supporting a little more revenue, which is exactly the kind of operating leverage a route business promises.3 Research spending, by contrast, is "not significant," and capital spending on property and equipment was about $28 million in 2025, under 1% of revenue.3 Much of the real estate and fleet is leased rather than owned, and the chemicals are bought.9 The capital that matters is human and commercial: technicians, sales staff, marketing and acquired customer books.
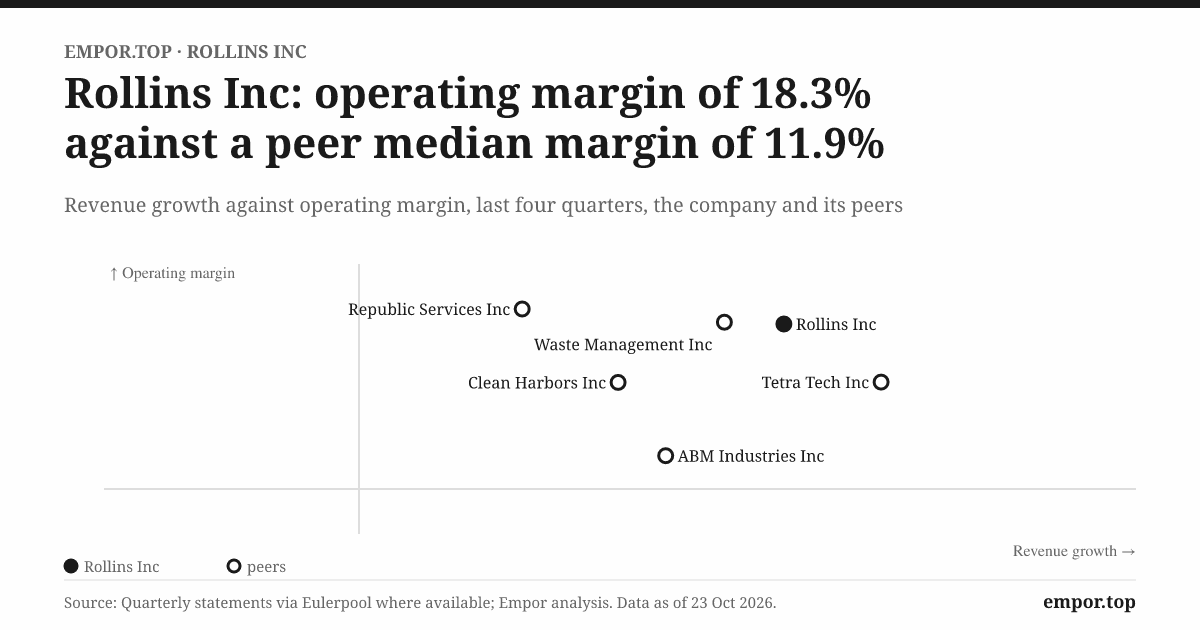
That cost structure produced an operating margin of about 19% in 2025, roughly where it had been for a decade.3 A business that keeps margins near 20% while doubling in size is not obviously gaining operating leverage at the corporate level, even if individual routes become denser. The gains from density seem to have been reinvested in wages, marketing, insurance and acquisitions rather than piling up as ever-wider margins. That is not a criticism; it may be the price of growth. But it tempers the idea that scale automatically makes Rollins more profitable.
The competitive landscape helps explain why. Rollins's largest rival in North America is Rentokil Initial, the British group that bought Terminix in 2022. Rentokil reported about $4.15 billion of North American pest-control services revenue in 2025, compared with Rollins's roughly $3.8 billion of total company revenue.103 Those figures are not a clean market-share comparison, because the two companies' mixes of residential, commercial and termite work differ and Rollins's total includes international operations. But they establish the essential fact: Rollins is not a monopolist. It has a giant rival of comparable size and, beyond the two leaders, thousands of local operators, some of them a single owner with a sprayer and a pickup truck. Rollins itself described the market it addresses as worth more than $20 billion.4 Even a company with almost $4 billion of revenue is a minority of that.
Customers, on the other side, have little individual bargaining power. Rollins serves millions of households and businesses and states that its results do not depend on any single customer.3 It does not disclose what share of revenue its biggest accounts represent, how many customers use more than one provider, or how often commercial customers put their contracts out to bid.3 So the fragmentation that protects Rollins from any one customer's leverage does not tell us much about switching costs. A restaurant chain can change pest-control vendors at contract renewal; a homeowner can cancel after the first year. The question is not whether customers can leave, but how often they do, and the company publishes only qualitative statements about that.
Suppliers are an even smaller worry. Rollins says the chemicals and equipment it uses are generally available from multiple sources.3 That keeps any single supplier from squeezing the company, though it does not make input costs irrelevant. Fuel, vehicles and insurance are the inputs that moved margins in 2026, not pesticides.
Those cost lines are where the 2026 margin story lives, and it is worth decomposing rather than hand-waving. In the third quarter, gross margin fell 90 basis points to 53.5%.1 Insurance and claims costs inside cost of services rose to 2.1% of revenue from 1.1% a year earlier, accounting for about a full percentage point of pressure, and fleet costs rose to 4.2% of revenue from 3.8%, mainly because of fuel.21 Employee costs actually improved slightly as a share of revenue, because management aligned staffing with lower volumes.1 Below gross margin, selling, general and administrative expenses rose to 30.0% of revenue from 29.4%, with insurance and claims again a visible driver, while selling and marketing spending held at about 13.4% of revenue.2 In plain English, the margin squeeze was not mostly about paying technicians more or spending wildly on advertising. It was about claims, accidents and fuel, costs that come with having thousands of trucks on the road.
That decomposition also contains an uncomfortable implication. Insurance and claims can be lumpy, and management said its incremental margin would have exceeded 25% if those items were normalized.1 But a company with tens of thousands of field workers and vehicles will always carry claims risk. Whether the 2026 spike was a bad patch or a new baseline is one of the things the next few quarters will reveal.
Now put the durability claim under the hardest test its own record allows. The bull case for Rollins has always been that the business is so reliable that its past growth is a reasonable guide to its future. Over the decade to 2025, revenue compounded at almost 10% a year and profits at about 13%.3 That is the strongest affirmative evidence there is. The strongest disconfirming evidence is recent and specific: by the third quarter of 2026, organic growth had fallen to 4.4%, slower than the total growth Rollins had reported in any full year since at least 2014, even allowing for the fact that those annual figures included acquisitions.23 The history does not reject the durability claim; demand for pest control did not collapse, and the recurring base kept growing. But it narrows it. Rollins's durability lies in keeping existing customers and serving them profitably. Its ability to add customers at the old pace turns out to be more fragile than a 100-quarter streak implied.
There is one boundary worth drawing clearly, because "AI disruption" is a phrase that invites exaggeration. Management's account is that AI is disrupting how customers discover providers, not what those providers do.1 Nobody is suggesting that a chatbot can seal a crawl space or bait a rodent. The field treatment remains physical, local and labor-intensive. What changed is the step before the technician arrives: the search, the recommendation and the decision about whom to call. For Rollins, that step had become as important as the route itself.
V. The New Customer No Longer Arrives the Old Way
For most of the internet era, the path from a cockroach to a contract was well worn. A homeowner noticed a problem, typed a few words into a search engine, and clicked one of the top results. Orkin, with its national brand, decades of web content and a marketing budget of nearly half a billion dollars a year, was very good at being one of those top results.3 The leads arrived on a schedule a marketing department could plan around. Spend a certain amount, earn a certain number of calls, convert a certain share into customers. It was not glamorous, but it was predictable, and predictability was what Rollins sold to investors.
In 2026 that path started to bend. On the third-quarter call, Gahlhoff described a customer who increasingly asks an AI assistant for a recommendation, and gets a different answer depending on which assistant, which city and which day.1 Instead of a list of ten blue links, the customer sees a short paragraph naming a few providers, sometimes a national brand, sometimes a local operator with glowing reviews. If Orkin is not in that paragraph, the customer may never see Orkin at all. The leads did not disappear; they scattered.
The prepared remarks were frank about the damage. Management said residential customer acquisition was the main problem, that the pressure was concentrated in digital lead flow, and that it was not broad-based across the portfolio.1 The brands that rely on relationships rather than search held up well. HomeTeam and Fox, which sell door to door and, in HomeTeam's case, through partnerships with home builders, grew well above the company average, with Fox growing at a double-digit pace.1 That contrast is the most useful clue in the whole quarter. If demand for pest control had weakened, door-to-door sales would have struggled too. They did not, which supports management's claim that the problem sits in one channel rather than in the underlying need.
The analyst questions were where the live version of the story came out. Tim Mulrooney of William Blair asked how lead flow had moved through the quarter. Gahlhoff called it "consistently weak, steadily weak," with some signs of improvement in September: organic website traffic, down 13% year over year in August, was down only 4% in September, and leads from organic search had risen about 5% since July.1 He was careful not to call that a turn. Greg Parrish of Morgan Stanley asked how long it takes to change how a brand appears in AI answers. The most concrete reply concerned pricing: Orkin had added price ranges to its web content that language models had been missing, a change that took "literally weeks."1 That is a revealing detail. AI systems summarize what they can find, and a brand that hides its prices may simply be left out of an answer to "how much does pest control cost?"
JPMorgan's Tomo Sano pressed on the obvious risk in that strategy. If AI-driven search makes prices more transparent, does it erode the premium Rollins charges? CFO Will Harkins said pricing was running at roughly 3% to 4% across the portfolio, weighted toward commercial customers, and that the company had seen no meaningful increase in customers rolling back prices or canceling.1 Gahlhoff argued that brand spending must continue precisely so that customers understand why Orkin is worth more.1 It is a reasonable answer, but it is also an untested one. A premium brand in a world of comparison-shopping assistants has to prove its value more explicitly than it did when a click on the top search result often decided the matter.
Stephanie Moore of Jefferies asked the question an aggressive competitor might ask: why not spend more on marketing and take share while rivals are confused? Gahlhoff's answer was discipline. The company could not reliably predict the return on extra spending, so it preferred to protect margins and reallocate money toward channels that were working.1 Harkins put it plainly: "it's really not about us spending more in our mind."1 That restraint is defensible, because buying leads in a channel whose rules change daily could turn marketing into an expensive guessing game. It is also a choice with a cost. If the new channels reward early, heavy investment, a cautious incumbent could cede ground it later finds hard to recover.
The response management outlined has three parts. Rollins is working to improve its visibility across traditional and AI search, through local content, listings, reviews and the sources language models draw on. It is trying to make its differences clearer, such as pricing transparency and same-day or next-day availability. And it is testing, learning and moving money, including paid advertising on AI platforms such as ChatGPT and Google Gemini.1 Harkins described the shift as reallocating marketing resources away from the traditional digital playbook toward higher-return channels.2 None of that is a technology breakthrough. It is a marketing operation rebuilding its map. The proof will not be an announcement; it will be lead volumes and residential organic growth.
Put the guidance record beside the ambition and the gap is stark. Rollins grew organically by about 6.9% in 2025.3 At its May 2026 investor conference, management reaffirmed a medium-term algorithm of 7% to 8% organic growth a year, plus 2 to 3 points from acquisitions, with incremental adjusted EBITDA margins of roughly 30% to 35%.4 By October the full-year organic outlook had been cut to 4% to 6% from about 6%, and the midpoint assumed no improvement in leads.1 Through the first nine months of 2026, organic growth was 5.5% and operating margin was down 140 basis points from a year earlier.2 Asked by Goldman Sachs's George Tong whether 7% to 8% was still achievable without a return of digital leads to their old levels, Gahlhoff said it was, but only if all three service lines performed, with residential needing the most improvement.1
That is the honest framing of management credibility in this episode. The company did not hide the miss or blame the weather. It identified a specific cause, described specific actions, gave guidance that explicitly assumed no recovery, and declined to give 2027 guidance until its fourth-quarter report.1 Those are signs of a management team that is not pretending. But the 7% to 8% target was restated in May and the year's organic outlook fell sharply within five months, which means the medium-term algorithm should now be treated as an aspiration rather than a base case. The streak of 100 consecutive quarters of revenue growth is a fine slogan; the gap between 4.4% and 7% to 8% is the number that matters.
Three measures will settle this part of the story. The first is residential organic growth, which was 2.3% in the third quarter.2 The second is the trend in customer additions and retention, which management describes but does not quantify: it said residential recurring customer count grew and retention remained strong, without giving the figures.1 The third is operating margin, because growth bought with unproductive marketing would simply swap one problem for another. With margins already squeezed by insurance and fuel, Rollins does not have the luxury of fixing its lead flow by spending its way there.
There was always another way to add customers, of course, one that does not depend on search engines at all. You can buy them.
VI. The Roll-Up: What Does a Customer Book Cost?
On April 1, 2025, Rollins closed the purchase of Saela Holdings, a pest-control company whose sales force had grown up knocking on doors in neighborhoods across the country, for $207.1 million.11 It paid with cash on hand and borrowings under its new commercial-paper program.11 The company's history page ranks Saela as the 23rd-largest pest-control business in the industry, the kind of descriptor that tells you how fragmented the field is: the 23rd-largest player was still big enough to cost over $200 million.6
Saela was not an isolated deal. Rollins completed 26 acquisitions in 2025 and 94 over the three years to the end of that year.3 Acquired businesses contributed about $139 million of revenue in 2025, or 4.1 percentage points of that year's 11% growth.3 In other words, more than a third of Rollins's growth in its last full year came from buying customers rather than winning them one at a time. The pace did not slow in 2026. In April the company bought Romex Pest Control, ranked 39th in the industry, for about $96 million, and by the end of September it had completed another 15 smaller deals worth about $87 million.96
Acquisitions have long been part of the Rollins playbook, but the model shifted over time, and HomeTeam Pest Defense is the best place to see how. In March 2008 Rollins agreed to buy HomeTeam from subsidiaries of the homebuilder Centex for about $137 million in cash.12 HomeTeam was then the third-largest residential pest-management company in the United States, serving about 400,000 customers and performing more than a million services a year.12 What made it interesting was not just its customers but how it got them. HomeTeam worked with more than 1,000 home builders and installed its Taexx system, a network of tubes built into the walls of new homes that lets technicians deliver treatment without drilling or spraying inside, in tens of thousands of new homes a year.12 Gary Rollins, then chief executive, called it an opportunity to leverage HomeTeam's proprietary technology.12
The strategic point was subtle. A homeowner who moves into a new house with Taexx already in the walls has, in effect, been introduced to a pest-control provider before ever searching for one. HomeTeam was a distribution channel as much as a customer book. Rollins chose to run it separately from its other subsidiaries rather than paint it Orkin orange.12 That decision looks prescient in 2026, when the brands selling through relationships rather than search are the ones holding up best.1 It also had a human consequence. One of HomeTeam's managers in 2008 was a former entomologist named Jerry Gahlhoff, who had joined Wilson Pest Control in North Carolina in 1999, stayed on when HomeTeam acquired it in 2001, and became HomeTeam's president after the Rollins deal.8 The man now trying to fix Rollins's customer acquisition came up through the acquired business that taught it a different way to find customers. In 2024 HomeTeam itself became the buyer, acquiring Fox Pest Control, a door-to-door specialist ranked 13th in the industry, on Rollins's behalf.6
So acquisitions can add more than revenue. They can add channels, people and know-how. The harder question is price. Saela offers a rare chance to try the arithmetic, because Rollins disclosed its first quarter of results. In the three months to June 2025, its first quarter under Rollins ownership, Saela contributed $18.9 million of revenue and $2.7 million of net earnings.11 Multiply by four and you get annual revenue of about $76 million and net earnings of about $11 million. Against a $207 million price, that implies roughly 2.7 times revenue and about 19 times earnings.
Those screens need careful handling. The second quarter is peak pest season, so annualizing it probably overstates a full year's revenue, which would make the true revenue multiple higher. On the other hand, the net earnings figure is after amortization of the acquired customer contracts, valued at about $52 million and written off over roughly six and a half years, which depresses reported profit in a way that does not reflect cash generation.11 Most of the price, about $133 million, was recorded as goodwill, the premium paid above identifiable assets, and the deal included about $9 million of contingent consideration tied to Saela's performance over two years.11 Rollins did not disclose Saela's EBITDA, so the multiple that acquirers actually negotiate over is not available. The honest conclusion is that Saela looks fully priced on a simple earnings screen, about where Rollins's own shares trade today, and that the public data cannot establish whether Rollins overpaid.
That limit applies to the whole program. Management describes its acquisition approach in confident language. At the May investor conference, Gahlhoff summed up the strategy: "We find the very best stand-alone businesses, fund their growth, and generate attractive returns on our investments."4 But Rollins does not publish deal-level returns, payback periods or purchase multiples.3 Investors can see that goodwill rose from about $1.16 billion to about $1.37 billion during 2025, which tells them how much premium the company paid, but not how much value it earned back.3 Revenue growth by itself proves nothing about acquisition quality; any company can grow by paying enough. A skeptical investor would ask for at least a cohort view: how acquired businesses grew organically after their first year, and how their margins compared with the company average.
There is a little evidence in the company's favor and a little against. In its favor, return on invested capital has stayed around 23% to 24% in recent years even as acquisitions piled up, which suggests the deals have not been dragging returns down dramatically.3 Against it, that return was in the high 40s before 2019, and it has not recovered to those levels since 2019, the year Rollins bought Clark Pest Control with borrowed money and new lease accounting brought leased offices and vehicles onto the balance sheet.36 The record does not reject the claim that acquisitions create value, but it narrows it: they have kept returns healthy rather than lifted them, and the margin of safety on each deal depends on price discipline the company does not disclose.
Every acquisition dollar also competes with other uses. In 2025 Rollins paid about $327 million in dividends and spent about $310 million in cash on acquisitions, most of it on Saela.3 It also repurchased shares, at a pace that accelerated sharply in 2026. A customer book bought for 19 times earnings competes directly with Rollins's own shares, which at the October price trade at about 32 times earnings but come with a business the company already knows intimately.
One more point keeps the acquisitions in proportion. They are not separate businesses with their own reported revenue, profit or value. Saela, Fox and Romex all disappear into the single pest-control segment, adding routes, customers and brands to the same income statement.3 You cannot value Rollins by adding up its brands. You can only judge whether the whole keeps compounding, which brings the story to the cash.
VII. Cash Comes In; the Capital Choices Go Out
Lay twelve years of Rollins's cash-flow statements side by side, from 2014 through 2025, and a clear pattern appears. Over that stretch the company reported about $3.5 billion of net profit and generated about $4.6 billion of cash from operations.3 For every dollar of accounting profit, roughly $1.31 of cash came through the door. After capital spending, free cash flow over the twelve years came to about $4.2 billion.3 And yet the company's cash and short-term investments at the end of 2025, about $100 million, were slightly lower than they had been at the end of 2013.3 Some $4 billion of free cash had passed through the business and almost none of it stayed. The story of Rollins as an investment is the story of where that money went.
Start with why cash exceeded profit, because it is not a trick. A pest-control company carries large noncash expenses. In 2025 Rollins added back about $125 million of depreciation and amortization, much of it the amortization of customer contracts acquired in deals like Saela, plus about $40 million of stock-based compensation and about $36 million of provisions for credit losses.3 None of those items consumed cash in the year they were expensed. Working capital pulled the other way: growing trade and financed receivables used about $58 million of cash in 2025.3 One accounting judgment deserves a note. Rollins capitalizes sales commissions and amortizes them over time, and the unamortized balance rose to about $39 million at the end of 2025 from about $23 million a year earlier.3 That is standard practice, but it means some of the cost of winning customers sits on the balance sheet rather than flowing straight through the income statement, and its rapid growth is worth watching in a year when customer acquisition has become harder.
Receivables are the other place where a service company's profit can drift away from its cash, and here the picture is broadly reassuring. Rollins took about 24 days to collect its revenue in 2025, slightly faster than the 26-day peak of 2019.3 It wrote off about $27 million of trade receivables and about $10 million of financed receivables in 2025, against total credit-loss provisions of about $36 million; financed receivables, typically termite and other larger jobs paid over time, had about $17 million at least 30 days past due at year-end.3 Those are modest amounts for a company of this size, but they are not zero, and they are a reminder that some customers pay for protection in installments.
Then follow the cash out. Dividends took about $2.2 billion of the $4.2 billion in free cash flow over the twelve years, or roughly half.3 Rollins paid out between about 55% and 75% of its profit as dividends in each of those years, with a median of about 61% and about 62% in 2025.3 That is a generous payout for a company that also wants to grow by acquisition. The quarterly dividend paid in the third quarter of 2026 was about 10% higher than a year earlier, even in a quarter of disappointing growth.2 The rest of the free cash went to acquisitions and, increasingly, to buying back stock. When free cash is not enough for all three, the gap is filled with debt.
That is what happened. Rollins carried no borrowings at the end of 2018. By the end of 2025 it had about $1.0 billion.3 The turning point came in 2019 with the Clark purchase, and the pace accelerated in 2025, when Rollins issued $500 million of 5.25% senior notes due 2035 and launched a $1 billion commercial-paper program.313 Those moves followed the company's first investment-grade credit ratings, announced in February 2025: BBB+ from Fitch and BBB from S&P, both with stable outlooks.14 By the end of September 2026, Rollins owed $500 million on the notes and about $240 million in commercial paper, with an undrawn $1 billion revolving credit line behind it.9 Separately, it carried about $400 million of lease liabilities.9
Commercial paper deserves a plain explanation, because it sounds more exotic than it is. It is short-term borrowing sold directly to money-market investors, often for days or weeks at a time, and companies roll it over continuously. At the end of September, Rollins's commercial paper had an average remaining term of just 6.5 days and an average interest rate of about 4.2%.9 That makes it cheap and flexible, but it also means the company depends on continuous access to short-term credit markets. The revolver exists precisely to backstop that dependence: if the commercial-paper market froze, Rollins could draw on the bank line instead. The revolver matures in February 2028, and the company's covenant caps net debt at 3.5 times EBITDA, a ceiling far above its current leverage of about 1 times.31 There is no sign of distress here. The risk is not insolvency; it is that leverage becomes a habit at exactly the moment growth slows.
The buyback record is where capital allocation meets price discipline, and the timing is worth examining closely. In November 2025, two family holding companies, LOR, Inc. and Rollins Holding Company, sold about $1 billion of Rollins shares in a secondary offering; Rollins received none of the proceeds and repurchased about $200 million of shares in connection with the sale.15 Then, through September 2026, the company spent another $140 million on open-market repurchases, buying about 3.5 million shares at an average of roughly $40 each.9 Most of that, about $120 million, came in the third quarter alone, compared with less than $4 million in the same quarter a year earlier.2 Management said its financial flexibility and its view of the business's intrinsic value supported the larger buybacks.2
On October 23, the shares traded at $34.60.5 So the 2026 buybacks are, for now, underwater: the company paid about 16% more per share than the market price a few weeks later. That alone does not prove the buybacks were a mistake; repurchases are judged over years, not weeks, and buying after a sharp fall is closer to good discipline than buying at the top. But an activist would ask two pointed questions. Why did a company with slowing growth and rising debt choose this moment to accelerate repurchases, in the same year it was also spending on acquisitions? And how did the company's purchase alongside the family's 2025 secondary sale serve outside shareholders, beyond helping to absorb the supply of stock the family was selling?
Valuation frames the choice. Rollins trades at about 21 times EV/EBITDA.5 Rentokil, the closest listed peer, traded at about 24 times trailing earnings and about 11 times EV/EBITDA on the same day.16 That comparison is rough, because Rentokil operates across many countries, includes hygiene services and has carried the cost of integrating Terminix. But it shows the scale of the premium: investors still pay about twice as much per dollar of EBITDA for Rollins. The free-cash-flow yield of about 3.6% tells the same story from the other side.5 At this price, the market is still assuming that Rollins's growth will recover toward its old pace. The buybacks are a bet that it will.
A few smaller items round out the money trail and can be kept in proportion. Other income was about $3 million in 2025 against about $700 million of pretax profit, so treasury income is not a hidden earnings driver.3 About 7% of 2025 revenue came from international operations, and the company does not disclose a hedging policy; currency is a secondary exposure.3 And the third quarter's strong cash flow came with an asterisk. Operating cash flow of about $242 million included a $63 million benefit from the timing of a tax refund, tied to the company's purchases of transferable federal tax credits.9 Excluding it, free cash conversion was about 109% rather than 149%.1 That is still healthy, but it is not a run rate. The cash engine is strong. The capital decisions it now funds are harder than they used to be, and they rest increasingly on people: the board, the family and the technicians in the field.
VIII. The Technician, the Family and the CEO
For decades, a new hire at Rollins signed a promise along with the paperwork. Under a longstanding company policy, the Federal Trade Commission alleged, all newly hired employees had to agree to a noncompete clause, regardless of their job.17 The typical version barred them, for two years after leaving, from working in pest control within about 75 miles of the Rollins location where they had worked, and sometimes across a multi-county region.17 According to the complaint, the clauses covered the vast majority of Rollins's more than 18,000 U.S. employees, including technicians and customer-service representatives earning relatively low wages, and the company had sent hundreds of cease-and-desist letters to former employees and filed multiple lawsuits against some of them.17 The complaint described workers asked to sign in the field, on the job, after their employer had been acquired by Rollins, with little chance to read what they were signing.17
In June 2026 the FTC finalized an order that ends all of that. For ten years, Rollins may not impose or enforce noncompete agreements against covered U.S. employees, and it must notify workers and report on its compliance.18 Rollins settled without admitting the allegations.18 The complaint's reasoning is worth noting because it goes to the heart of the business model. The FTC argued that Rollins did not need noncompetes to protect its methods, which it publishes on its website and on YouTube, or its training, which it provides at the same level in places where it does not use noncompetes, and that narrowly drawn non-solicitation agreements could protect customer relationships instead.17
On the third-quarter call, Gahlhoff called the matter a "non-event," saying the agreements were rarely enforced and had been rolled back.1 That claim sits awkwardly beside the complaint's account of hundreds of warning letters and multiple lawsuits, and the two cannot both be the whole picture. The fair reading is that the direct financial charge is small; the company has not disclosed one. The strategic effect is harder to dismiss. In a route business, the technician is the relationship. A skilled technician who knows a few hundred customers by name, and who can now start a competing business or join a local rival down the road, carries real value out the door. The FTC's own theory was that noncompetes suppressed exactly that kind of competitive entry.17
If that is right, retention, training and pay become more important levers than legal restraint. Rollins does not publish technician turnover or vacancy rates, so there is no way yet to measure whether the order changes anything.3 The third-quarter call did mention staffing and capacity constraints in some markets, which held back termite and ancillary work.1 That is not evidence that the FTC order caused them. It is a reminder that labor is the binding constraint in a business where every dollar of revenue requires a person on a route.
The people at the top of the company are the other half of this story, and here the family looms large. Gary Rollins, son of the co-founder Wayne, long led the company as chief executive and later chairman, and stepped off the board at the 2026 annual meeting, remaining as honorary chairman emeritus and a non-voting participant at board meetings.8 John Wilson, a career Orkin operator who ran the brand as president from 2009 and as president and chief operating officer through 2020, became executive chairman in 2025.8 Gahlhoff, now 53, became chief executive in 2023, completing a path from field entomologist to the corner office.8 It is a leadership team of operators who grew up inside pest control, which is a strength in a business of routes and branches. Whether operators who built the business in the search era can redesign customer acquisition for an AI-driven one is a fair question, and the answer will show up in the numbers, not the résumés.
Ownership explains why the family still matters. The Rollins Significant Shareholder Group, the family's collective holdings, beneficially owned about 37.9% of the company in early 2026, after the secondary sales.8 Two family voting trusts each reported about 33.3% through shared-control arrangements; those figures overlap and should not be added together.8 The R. Randall Rollins Voting Trust still held about 33.3% in September 2026.19 Among outside holders, Vanguard held about 7.9% and BlackRock about 5.9%.8 In practice, no outside shareholder can force a change the family opposes.
That concentration makes related-party dealings worth watching, even when the sums are small. In 2025 Rollins paid about $0.7 million to GWR LLC, an entity of Gary Rollins, for access to aircraft, and charged LOR about $0.4 million for shared pilot services and training.3 Orkin also received about $0.5 million of franchise revenue from Wilson Pest Management, owned by John Wilson's son.3 Each of those amounts is well below a tenth of a percent of revenue, and an older aircraft lease with a family trust ended in 2024.3 None of them changes the economics. They are a governance matter because they involve payments between the company and the people who control it.
Pay is the other test. Gahlhoff's reported compensation was about $9.0 million in 2025, up from about $6.7 million in 2023.8 Over the same two years, net profit rose from about $435 million to about $527 million.83 Profit grew by about a fifth while pay grew by about a third, though much of the pay came in equity and performance-based awards that rise and fall with results.8 That comparison is context, not a verdict on whether incentives worked. Shareholders, however, sent a signal. At the April 2026 annual meeting, about 33.3 million votes were cast against the say-on-pay proposal and about 31.9 million votes were withheld from Louise Sams, the lead independent director and a former general counsel of Turner Broadcasting.208 Both proposals passed comfortably, as they must with the family's stake. But dissent of that size from outside holders is a governance signal worth tracking, particularly as performance slipped later in the year.
The finance seat also changed hands. Kenneth Krause, the chief financial officer, resigned effective June 15, 2026, to take another role; the company reported no disagreement, and William Harkins, previously chief accounting officer, succeeded him.21 Harkins was the voice on the third-quarter call explaining the guidance cut, a demanding debut. For what it is worth, the auditor gave the company an unqualified opinion for 2025 and found its internal control over financial reporting effective.3 That is bounded assurance about the books for that period, not a guarantee about operating results or governance. With the people and the money in view, the case can now be weighed in full.
IX. Analysis & Bull vs. Bear Case
In May 2026, Rollins gathered investors and analysts to hear its medium-term plan: 7% to 8% organic growth, 2 to 3 points more from acquisitions, free cash conversion above 100% and consistent double-digit growth in earnings and cash flow.4 Five months later, the company was reporting 4.4% organic growth, cutting its full-year outlook, and watching its stock fall sharply.215 Put those two moments side by side and the investment question becomes precise. Is the May algorithm still the right description of Rollins, temporarily interrupted by a channel shock? Or was the third quarter the first glimpse of a slower company?
The industry structure is the place to start, and it is best judged force by force. Rivalry is persistent, with Rentokil and thousands of local operators competing on price, responsiveness and personal reputation.10 The FTC order may make that rivalry a little fiercer, because it removes a legal barrier that had discouraged Rollins technicians from starting their own businesses.17 The threat of new entrants is real at the local level, because starting a pest-control business requires a license, a truck and some chemicals, not a factory. What new entrants lack is scale in brand, training, insurance and back-office systems, which is why the industry consolidates even as it keeps regenerating small players. Buyer power is weak at the individual level, but strong at the moment of renewal, when a household or restaurant can switch with little friction.3 Supplier power is low, because chemicals and equipment are available from multiple sources.3 And the threat of substitutes is mostly do-it-yourself: a homeowner with a spray bottle from the hardware store. AI is not a substitute for the service; it is a new gatekeeper in front of it.
Hamilton Helmer's seven powers offer a sharper lens on what, if anything, makes Rollins durably better. Scale economies exist mainly at the route level, through density, and at the corporate level through marketing, insurance purchasing and systems; but a decade of roughly flat operating margins suggests those economies have been shared with customers and employees rather than retained.3 Switching costs are modest. A recurring customer faces little more than the inconvenience of finding someone new, although for termite protection, where a provider's warranty and inspection history matter, the stickiness may be higher. Rollins does not publish retention rates, so the strength of this power is unproven.3 Branding is the most plausible power. Orkin is one of the few pest-control names a typical American can recall unprompted, and a trusted brand matters when a stranger is about to walk around your house. But a brand's value in this industry has historically been expressed through search rankings and click-through rates, and the third quarter showed how quickly that expression can change. Counter-positioning, cornered resources, network economies and process power are hard to find in the evidence; the FTC complaint itself noted that Rollins publishes its methods openly.17 The honest verdict is that Rollins has a real but narrower set of powers than its valuation once implied: brand, route density and the operating discipline of an experienced management team, none of them so strong that the company is exempt from competition for each new customer.
The bull case begins with the record. About three-quarters of the business is recurring service, which gives Rollins a revenue base that does not need to be resold every quarter.3 The company compounded revenue and profit at strong rates over a decade and consistently converted profit into cash.3 Its non-search brands grew strongly even in a bad quarter.1 Management's diagnosis is specific and its response is measurable, with early signs in September that web traffic declines were narrowing.1 The company said pricing of about 3% to 4% held up without visible customer pushback.1 Leverage leaves room to keep buying smaller operators in a fragmented market.1 And the valuation, while still demanding, has fallen far enough that a recovery toward the old growth rate is not fully priced at the old premium.
The bear case begins with the same quarter. Organic growth slowed to 4.4%, and residential organic growth to 2.3%.2 Costs that management describes as unusual, insurance and claims in particular, compressed margins, and in a business with tens of thousands of drivers they may prove more persistent than hoped.2 The customer-discovery shift is, in management's own word, dynamic, and it has said it is not assuming a return to historical patterns.1 That candor cuts both ways: a company that cannot predict its own lead flow cannot promise its own growth. The medium-term organic target now looks far from current reality, and the gap will be filled, if at all, partly with acquisitions whose returns the company does not disclose.
Put the labor and capital risks where they belong. The FTC order may increase technician mobility in a business that already reported staffing constraints in some markets.181 Acquired growth adds integration risk and the risk of paying full price for customers who may not stay.11 Commercial paper and accelerated buybacks make the balance sheet more active than it used to be, which means purchase-price discipline matters more than ever.9 None of these risks is existential. Together they describe a company whose margin for error has narrowed.
An activist looking at Rollins would not find much to break up; it is a single business. The challenges would be about disclosure and capital allocation. Publish retention rates, customer counts and organic growth for acquired cohorts, so investors can judge the moat and the roll-up on evidence rather than faith. Explain why buybacks accelerated in a year of slowing growth and rising debt, and at what price the company believes its stock is cheap. Show how the marketing reallocation is performing in lead volumes, not just traffic. And justify executive pay growth that outran profit growth, given the dissent at the annual meeting.20 With the family's control, such pressure can only persuade, not compel.
Three numbers will tell investors which story is true. The first is residential organic growth; until it turns up, the AI disruption remains a live threat rather than a solved problem.2 The second is operating margin, which shows whether insurance and fuel costs are settling and whether growth is being bought.2 The third is the split of growth between organic and acquired, alongside net debt. Acquisitions are guided at 2 to 3 points a year; if they begin to carry more of the load while debt rises, the compounding is becoming more expensive.1
The valuation argument ends without a recommendation, but with a clear statement of what the price assumes. Rollins is cheaper than it has been for most of the past five years, measured against its own earnings.5 It is still priced at a large premium to its closest rival, a premium that only makes sense if slower growth recovers.16 The market has stopped paying for a perfect compounder. It is still paying for a very good one.
X. Playbook: Business & Investing Lessons
Go back to 1964 for a moment. Two brothers from the radio business sign a deal to buy a company several times their size, betting that a pest exterminator built by the Rat Man could become the center of their fortune.6 Now jump forward sixty years, to a technician walking a fence line in a subdivision, and then to a homeowner typing a question into a chatbot. Everything Rollins has to teach sits somewhere between those three scenes.
The first lesson is buy the route, then earn the renewal. The Orkin deal made Rollins a pest-control company, and every acquisition since, from HomeTeam to Saela, has been an attempt to buy more routes and more customers. But a route is only an asset if the customers on it keep saying yes. Recurring revenue is a habit the customer renews, not a contract the company owns, and a quarter of Rollins's business has to be sold fresh every year anyway.3 For founders building service businesses, the lesson is that the asset is not the customer list but the probability of renewal attached to each name on it. For investors, it is that a company that does not publish that probability is asking to be trusted on its most important number.
The second lesson is that the brand gets you considered; the technician gets you kept. Orkin's national name has long brought homeowners to the door, but the person who walks around the house every quarter is what makes them stay. The FTC order, which removed the legal leash on those technicians, turns that truth into a business problem.18 A service company's moat walks around in boots. Rollins publishes far more about its revenue than about the retention of either its customers or its technicians, which means the half of the model that keeps customers is the half investors can see least.
The third lesson is that a roll-up is a price, not a strategy. Twenty-six deals in a single year sound like momentum, and in a fragmented industry they may well be sensible.3 But Saela, bought for something like 19 times its early earnings, shows that the value of a roll-up is decided at the moment of purchase, not in the press release.11 HomeTeam proved that an acquisition can bring a new way of reaching customers, and twenty years later it is one of the brands holding Rollins up.121 That is the standard every deal should be held to, and it is a standard that can only be judged when the company shows its returns.
The fourth lesson is that cash is a choice. Rollins turned more than $4 billion of free cash into dividends, acquisitions and buybacks over twelve years and kept almost none of it.3 That is not a flaw; a business that does not need much capital should not hoard it. But it means every dollar of buyback at $40 a share is a dollar not spent on a customer book or a technician's raise, and the market price a few weeks later is a quick, unforgiving grade on the decision.95 Authorizing a buyback is easy. Buying cheaply is the skill.
The fifth lesson is the one that belongs to 2026. A century of habit does not exempt you from a new channel. Orkin's brand is older than commercial radio, and for decades the company mastered whatever medium sent customers its way: the phone book, the television ad, the search result. The AI answer is simply the newest medium, and it does not care how old the brand is.1 The incumbents that survive channel shifts are the ones that treat each new front door as if they were a start-up trying to get noticed. Rollins's quick experiment with publishing price ranges so that language models could find them is a small, telling example of what that humility looks like.1
XI. Epilogue
Tonight, Rollins stands at an awkward point in a long story. The company says its recurring base is growing, but residential growth and margins have weakened, leaving its targets more distant than they did in May.24 Its stock is down by almost half from its high.5 The company has given no guidance beyond 2026 and will not offer a 2027 outlook until it reports the fourth quarter.1 That report will be the first real verdict on the plan Gahlhoff laid out on October 22.
The first thing to watch is whether residential organic growth and customer additions improve as Rollins moves marketing money toward direct, local and AI-driven discovery. If the September improvement in web traffic turns into more leads, and more leads into customers, the third quarter will look like a channel shock that a capable incumbent absorbed. If lead volumes stay flat, management's own guidance implies something like 5% organic growth, and the gap from the old 7% to 8% target becomes the new normal.1
The second is whether margins recover from the pressure of claims and fuel.2 If they settle, and if growth returns without a surge in marketing spending, operating margins should recover toward their recent range. If they do not, Rollins faces the uncomfortable combination of slower growth and lower margins, the one outcome its premium valuation does not allow for.
The third is acquisitions. Rollins has said its pipeline remains strong and its strategy unchanged.1 The question for the coming year is whether deals keep adding growth at returns that justify their prices, and whether the company starts disclosing enough to let outsiders judge. A roll-up that works should be able to show it.
The fourth is the workforce. The FTC order runs until 2036, and its effect on technician turnover, vacancy rates and customer retention will take years to emerge.18 Management calls it a non-event; the complaint describes a company that once relied on noncompetes heavily.117 The truth will show up in whether routes stay staffed and customers stay served.
The fifth is the balance sheet. Rollins's short-term borrowing and the maturity of its revolver in February 2028 make its debt and buyback prices worth watching.9 None of it is alarming today. All of it matters more when growth is slower.
Set those signposts against the questions that opened this story and the shape of the uncertainty becomes clear. Rollins's core business is not in doubt; people will continue to need someone to deal with termites and rodents, and Rollins remains one of the two largest providers in North America. What is in doubt is execution: whether the company can find its customers again in a world that no longer delivers them in a predictable stream. A temporary channel shock or a lower-growth regime. That is the question the next four quarters will answer.
XII. Outro
Return to that driveway on a Tuesday morning. One technician, one route, one customer who is probably not home. The truck pulls away, the note is on the door, and somewhere in the next few months the customer will decide, without much thought, whether to keep the service or search for someone else.
Rollins built its empire through repetition, as its 100-quarter growth streak suggests.2 The old radio company's bet was on repetition.6 Its heirs are learning the harder half of the same lesson: repetition has to be renewed, one customer at a time, and the next customer may now meet Rollins first through an answer written by a machine. The pest-control empire was built by showing up. Its next chapter depends on being found.
References
-
Rollins Q3 2026 Earnings Call Transcript — StockAnalysis, 2026-10-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Rollins, Inc. Reports Third Quarter 2026 Financial Results — Rollins, Inc., 2026-10-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
2025 Form 10-K — Rollins, Inc., 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Rollins Reinforces Long-Term Value Creation Strategy and Medium-Term Growth Algorithm — Rollins, Inc., 2026-05-14 ↩↩↩↩↩↩
-
Investor Relations, stock information — Rollins, Inc., 2026-10-23 ↩↩↩↩↩↩↩↩
-
Rollins, Inc. Announces Passing of Chairman of the Board R. Randall Rollins, Form 8-K Exhibit 99.1 — SEC, 2020-08-18 ↩↩↩↩↩↩
-
2026 Proxy Statement — Rollins, Inc., 2026-03-17 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Rentokil Initial Annual Report 2025 — Rentokil Initial plc ↩↩
-
Rollins to Acquire HomeTeam Pest Defense, Form 8-K Exhibit 99 — SEC, 2008-03-31 ↩↩↩↩↩↩
-
Commercial Paper Program, Form 8-K — Rollins, Inc., 2025-03-21 ↩
-
Rollins Receives Inaugural Investment-Grade Credit Ratings — Rollins, Inc., 2025-02-13 ↩
-
2025 Form 424B5, Secondary Offering Prospectus Supplement — Rollins, Inc., 2025-11-10 ↩
-
Rentokil Initial Valuation Statistics — StockAnalysis, 2026-10-23 ↩↩
-
In the Matter of Rollins, Inc., Complaint — Federal Trade Commission, 2026-06-22 ↩↩↩↩↩↩↩↩↩
-
In the Matter of Rollins, Inc., Final Decision and Order — Federal Trade Commission, 2026-06-22 ↩↩↩↩↩
-
Schedule 13D/A, R. Randall Rollins Voting Trust — SEC, 2026-09-21 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube