NextEra Energy: The Clean Energy Colossus
I. The Sunshine Utility and the Trillion-Watt Gamble
On a stretch of Atlantic coastline in Juno Beach, Florida, a short drive north of Palm Beach, sits the headquarters of a company that most Americans have never thought about and most of Florida pays every month. The building is low and unremarkable. The numbers attached to it are not. On October 8, 2026, the stock market valued NextEra Energy at about $160bn, and once its debt is added the whole enterprise was priced at roughly $267bn.1 For a power company, that is an extraordinary figure. It places a utility that began life selling ice and electricity to Florida farm towns in the same weight class as oil supermajors and ahead of the historic electric holding companies of the Northeast and Midwest.
Look a little closer and the picture gets more interesting, and more nervous. At the end of 2025 NextEra carried about $95.6bn of borrowings on its balance sheet, almost double the figure of four years earlier.1 Its free cash flow yield, the cash left after running and building the business measured against the share price, was negative 6.4%.1 And in May 2026 the company agreed to swallow Dominion Energy, the dominant utility in Virginia, in a stock-and-cash deal worth more than $65bn.4 So the most valuable clean energy company in the world was, at the same moment, one of the most indebted companies in American infrastructure and the buyer in the largest utility merger in a generation.
That is the paradox at the heart of this story. Through its regulated subsidiary Florida Power & Light, NextEra delivers electricity to more than six million customer accounts across the Sunshine State, a business that by law earns a return set by state regulators.1 Utilities like that normally trade like bonds with a pulse. Yet for most of the past decade investors priced NextEra like a growth company: its median price-to-earnings multiple over the last five years was about 24 times, against the mid-teens that a typical regulated utility commands.1 The reason for the premium had a name, NextEra Energy Resources, or NEER, which grew into the largest developer of wind, solar and battery storage in North America.10
The architecture is the whole trick, so it is worth stating plainly. FPL is the anchor. It is a monopoly in a fast-growing state, its prices are set by the Florida Public Service Commission at a level designed to earn shareholders a return on equity of about 10.6%, and its credit rating is strong.7 NEER is the engine. It builds renewable plants across roughly 40 states and four Canadian provinces and sells their output under contracts that typically run 15 to 25 years.1 The anchor's steady cash and the group's investment-grade standing let the engine borrow cheaply and build at a scale no independent developer could match. When it works, it is a beautiful machine: a utility's cost of money attached to a developer's growth.
The question that hangs over Juno Beach in the autumn of 2026 is whether the machine still works when money is no longer cheap. Between 2026 and 2030 NextEra has about $41.6bn of long-term debt coming due, and roughly $37.2bn of that sits not at FPL but at the holding company and at NEER, where there is no regulator to pass higher interest costs through to customers.1 Its yieldco, the publicly traded vehicle it once used to recycle capital, broke under rising rates and has cost it billions in write-downs.1 And the Dominion deal will issue hundreds of millions of new NextEra shares.2
Four questions run through everything that follows. Can NextEra refinance its holding company debt without crushing the earnings that equity holders own? Without a functioning yieldco, how does NEER fund its pipeline? How much of the company's reported profit is economic cash, and how much is the product of tax credits and partnership accounting? And is Dominion a masterstroke that turns NextEra into the power supplier to the artificial intelligence economy, or an expensive retreat into regulated rate base by a company whose financial engineering has hit its limits? To answer any of them, it helps to go back to a swamp, a land boom, and an ice plant.
 Subscribe on LinkedIn
II. From Frontier Ice Plants to the Deming Prize (1925–1998)
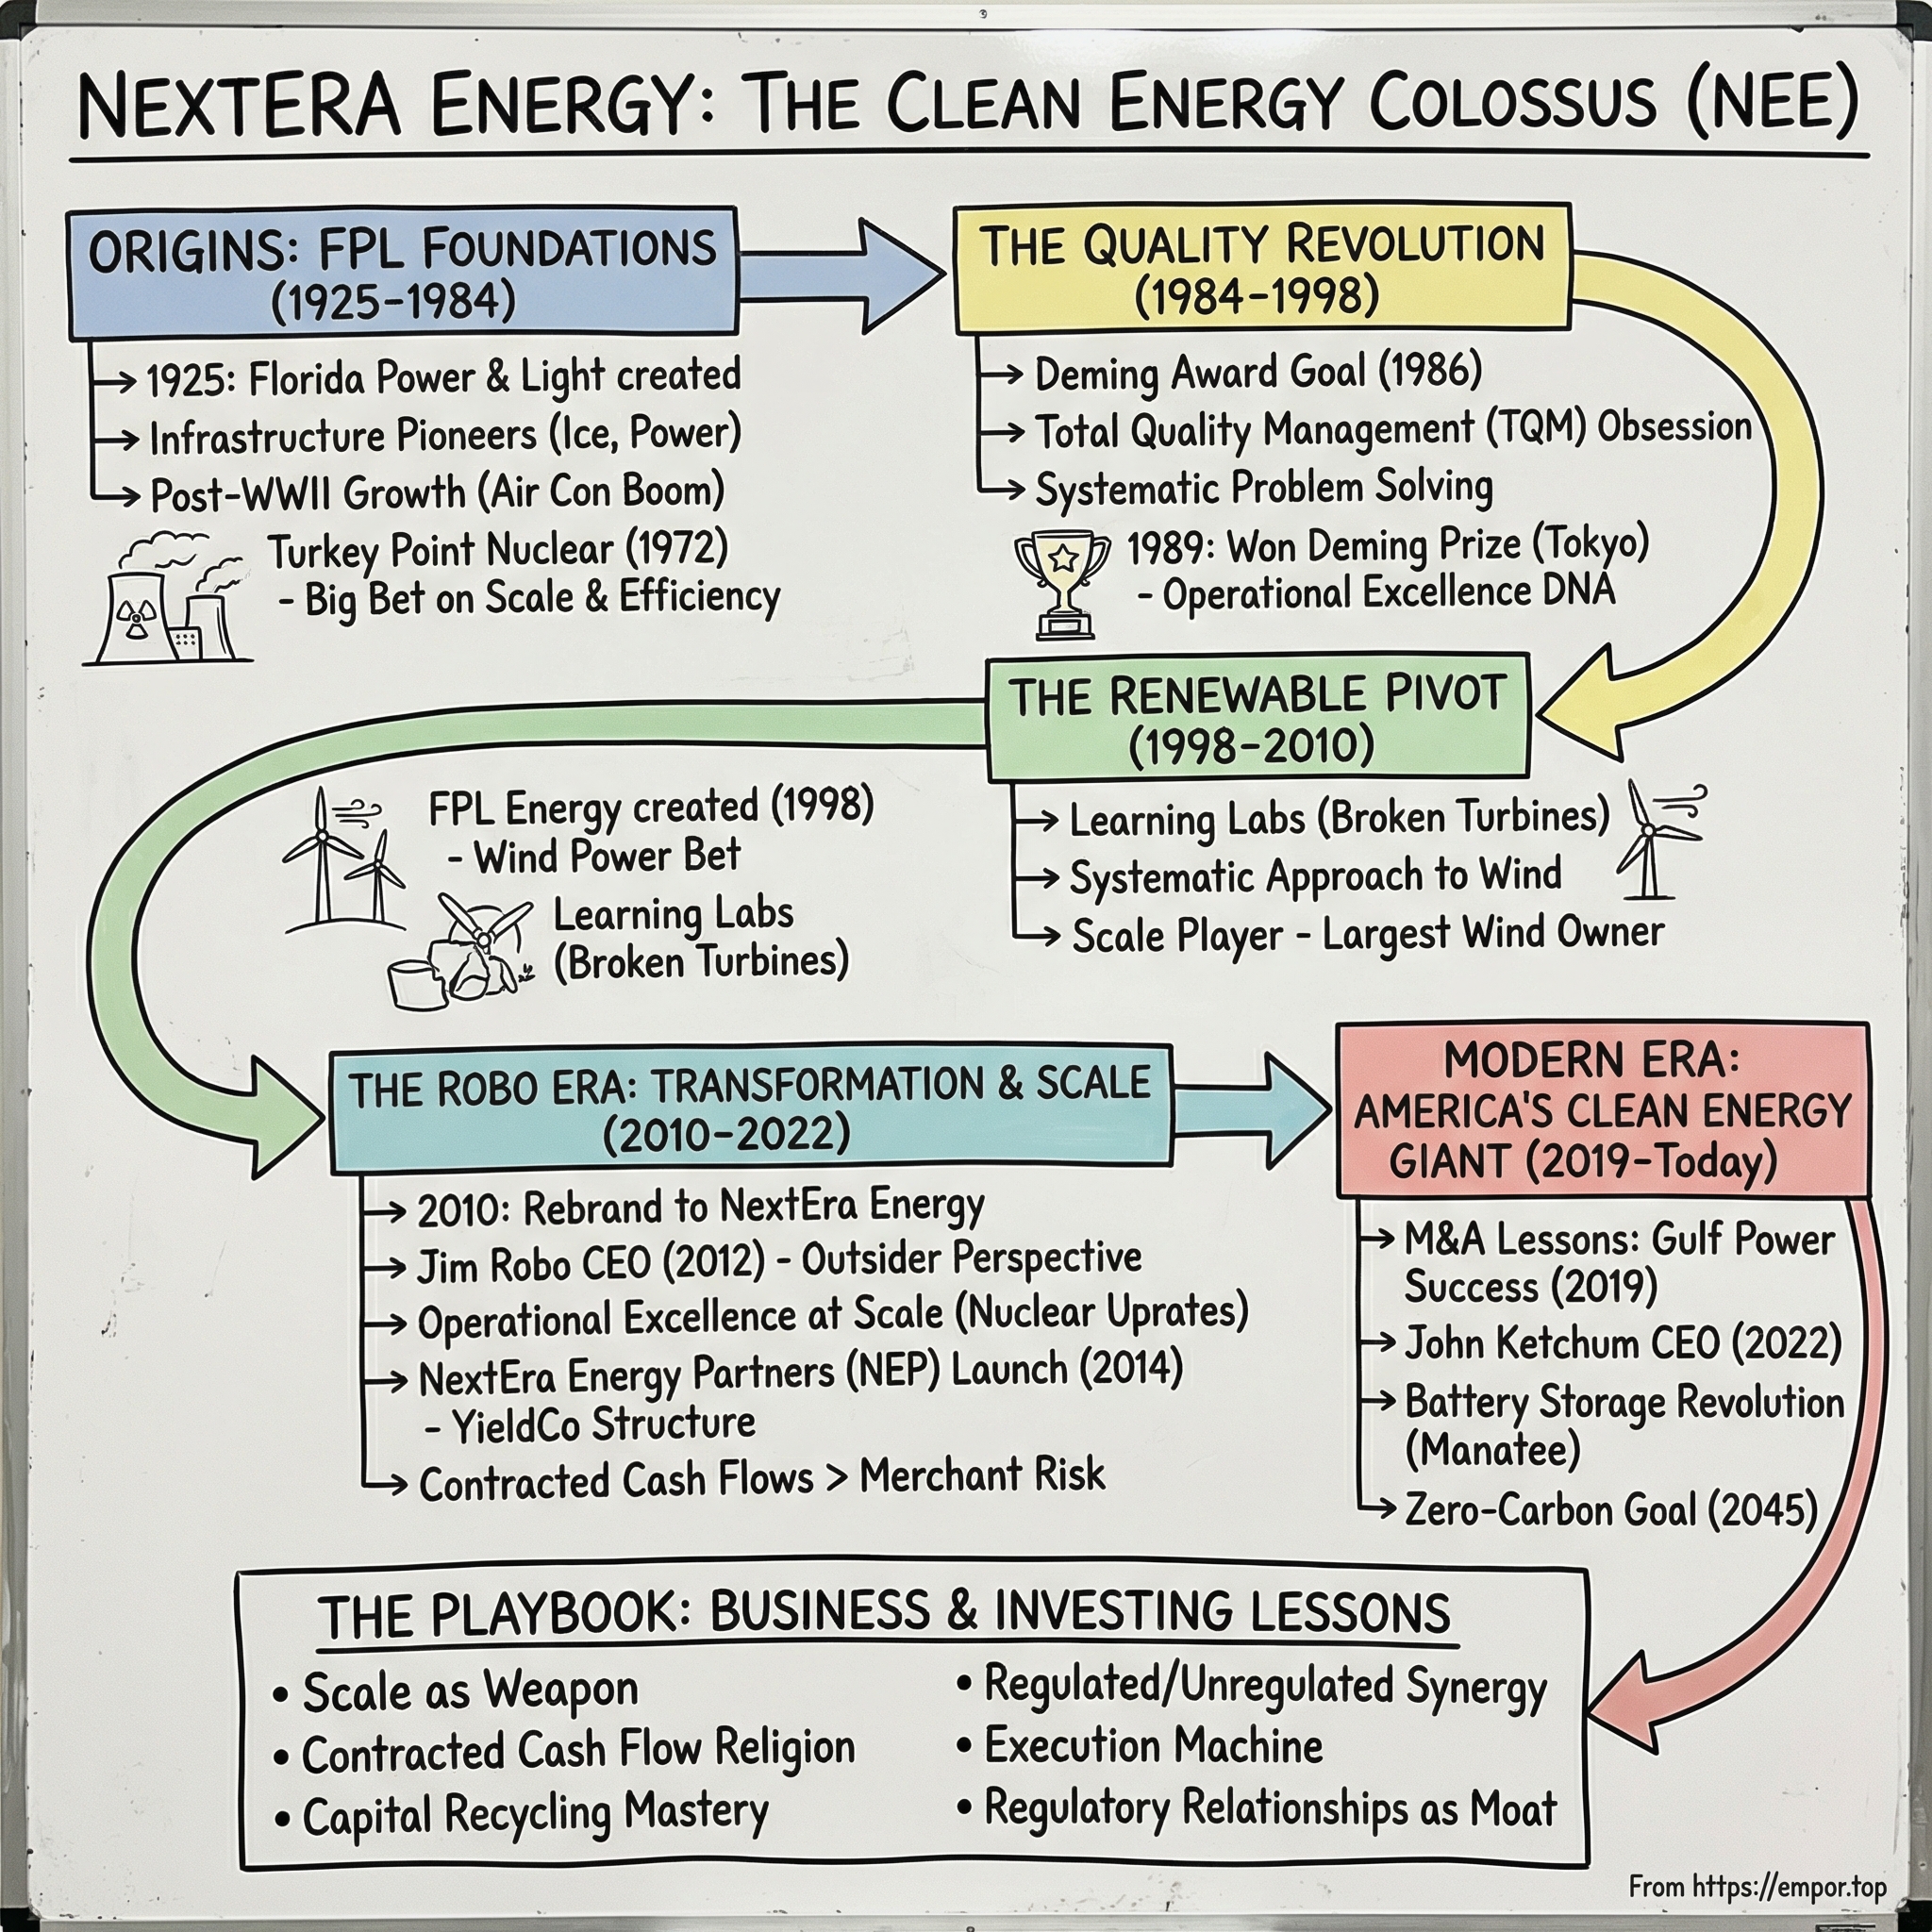
Florida in 1925 was a fever dream. Land was changing hands several times in a single afternoon, Miami was being sold lot by lot to buyers who had never seen it, and the electric grid, such as it was, consisted of dozens of little plants serving individual towns. Some of those plants made ice as well as electricity, because in a state built on citrus and vegetables, ice was what kept a harvest alive on its way north. On December 28, 1925, the American Power & Light Company, part of the sprawling Electric Bond and Share holding empire, pulled a collection of these scattered properties together into a single company: Florida Power & Light.10
The timing was terrible. Within a year the land boom collapsed, and a vicious hurricane flattened Miami in 1926. Another struck in 1928. Then came the Depression. The young utility spent its first decade stringing wire between towns that had stopped growing, which taught it the two lessons that would define it ever since: Florida grows in violent bursts, and the weather will try to destroy whatever you build.
The bursts eventually came in its favor. After the Second World War, two inventions turned Florida from a winter retreat into a year-round place to live: the mosquito control program and, more importantly, cheap residential air conditioning. Population surged, and every new household arrived with a machine that ran hard for half the year. FPL's job became building generation fast enough to keep up. By the early 1970s that meant nuclear power, and in 1972 the first unit at Turkey Point, south of Miami, entered commercial service as Florida's first commercial nuclear reactor.10 Nuclear plants are unforgiving machines that punish sloppy operators, and running them well would later shape the company's culture as much as any management theory.
The 1980s brought the classic utility mistake. Flush with cash and bored by regulated returns, management created a holding company, FPL Group, in 1984 and went shopping outside its competence.10 The marquee purchase was Colonial Penn, a Philadelphia insurer that sold policies by mail to older Americans, bought in 1985.10 An electric utility knows how to build power lines; it knows nothing special about underwriting life insurance. Colonial Penn disappointed, and FPL Group sold it in 1991 at a loss.10 The lesson was expensive and it was learned: the company's later ventures stayed close to power generation.
What happened inside the utility at the same time was far more consequential. Under chairman John Hudiburg, FPL embraced total quality management, the statistical process discipline that Japanese manufacturers had adopted from W. Edwards Deming. FPL sent teams to Japan, rebuilt its processes around measuring defects, and drove thousands of quality improvement teams through its workforce. In 1989 it became the first company outside Japan to win the Deming Prize, the most prestigious quality award in Japanese industry.10 It was a strange sight: a Florida utility beating the world's manufacturers at their own game.
The prize came with a backlash. The program generated an enormous bureaucracy, and Hudiburg's successor, James Broadhead, dismantled much of the paperwork soon after he arrived in 1989, keeping the measurement culture while scrapping the ritual.10 That distinction matters. The consensus story is that FPL "won the Deming Prize and became efficient." The record suggests something messier: the prize itself became a cautionary tale about process for its own sake, and what survived was an engineering habit of measuring unit costs relentlessly. That habit, more than the trophy, is the inheritance that matters for investors, because it is what let FPL keep its non-fuel operating costs among the lowest in the industry for decades afterwards.
In 1998 the company planted the seed of everything that followed. It set up FPL Energy, an unregulated subsidiary built to own and operate power plants outside Florida.10 At first it looked like another diversification. The difference was that this time the company was diversifying into the one thing it knew how to do, building and running generation, and it was about to arrive in that market just as the merchant power industry around it went up in flames.
III. The Pioneer's Advantage: Wind, Scale, and the Jim Robo Era (1998–2018)
In late 2001 the American power business was in a state of panic. Enron had collapsed in a few weeks, and with it went the idea that electricity was best traded like a commodity on screens in Houston. Merchant generators that had built gas plants on borrowed money to sell into spot markets were sliding toward distress. At almost exactly the same time, along the border between Oregon and Washington, FPL Energy was finishing the Stateline Wind Energy Center, then among the largest wind farms in the world.10 It was not a glamorous project. It was rows of turbines on dry wheat land, with the electricity sold under a long-term contract. That contrast, quiet contracted assets while the traders burned, is the origin of NextEra's modern business model.
The man most associated with what came next arrived the following year. James Robo, a General Electric executive who had run GE's capital businesses in Asia and absorbed the Jack Welch gospel of scale and relentless cost discipline, joined FPL Group in 2002.10 He became chief operating officer in 2006 and chief executive in 2012.1 Robo's conviction was simple and, at the time, contrarian among utility executives: wind and later solar would stop being green experiments and become the cheapest electricity available. If that was true, the company that could build them at the lowest cost, at the largest scale, would win a structural advantage that coal and gas utilities could not easily copy.
The commercial discipline mattered as much as the vision. Merchant players such as Calpine and Dynegy had bet on wholesale price spikes. NEER did something more boring. Before it poured concrete, it typically signed a power purchase agreement, a long-term contract under which a utility, cooperative or corporation agreed to buy the output at a set price for 15, 20 or 25 years.1 The returns were locked in before the risk was taken. Think of it as building an apartment block only once every unit is pre-leased for two decades.
Then there was the tax code. American renewables were built on two federal subsidies: the production tax credit, which paid a project for every megawatt-hour it generated, and the investment tax credit, which returned a slice of the project's cost. The catch was that a credit is only valuable if you owe taxes, and a young wind farm owes none. NEER became a master of tax equity, the arrangement in which banks with large tax bills invest in a project in exchange for most of its credits.1 Others did this too. NEER did it at a volume that made it the market's most important counterparty.
Scale fed on itself. Because NEER was buying more turbines and panels than almost anyone else in the country, it could negotiate harder with suppliers such as GE, Vestas and First Solar, and it standardized construction so that each project was cheaper than the last. Management summarized the advantage in a line it repeated for years: NextEra builds cheaper and buys better than anyone.[^6] That is a management claim, and the precise size of its procurement discount is not disclosed. But the outcome is visible. By the early 2020s the company had become the largest generator of wind and solar energy in the world, with a large share of the US utility-scale market.10
In 2010 FPL Group renamed itself NextEra Energy, a deliberate signal that it no longer saw itself as a Florida company.10 In 2014, Robo added the piece of financial engineering that would later haunt his successor. He listed NextEra Energy Partners, or NEP, a "yieldco" designed to buy operating wind and solar plants from NEER, pay out most of their cash to unitholders, and grow its distributions every year.1 The idea was elegant. Income investors would pay a high price for stable contracted cash flows; NEER would sell them finished projects, take the proceeds and build more. It was capital recycling, a conveyor belt that turned completed assets back into development money.
The market loved the results. Under Robo, net income rose from about $1.9bn in 2012 to about $3.6bn in 2021, and the market value of the company grew several-fold, at one point passing ExxonMobil's.110 The question is whether that was a durable advantage or a well-timed ride on falling turbine costs and generous subsidies. The honest answer is both. Falling equipment costs and federal credits lifted the whole industry, and NextEra did not invent the turbine or the panel. But it captured a disproportionate share of that tide because it had the balance sheet, the procurement volume, and the contracting discipline before anyone else. That is a real advantage. It is also one that depended heavily on cheap leverage and a yieldco whose model required rising unit prices.
The strongest piece of evidence against the idea that NextEra could do anything it wanted came from its attempts to buy other regulated utilities. In 2016 the Hawaii Public Utilities Commission rejected its roughly $4.3bn bid for Hawaiian Electric, concluding the deal did not adequately serve the public interest.10 A year later Texas regulators blocked its roughly $18bn attempt to acquire Oncor, the largest transmission and distribution utility in the state, after NextEra refused to accept the ring-fencing conditions that would have walled Oncor off from its new parent.10 Two big swings, two rejections, both at the hands of state regulators skeptical of an aggressive out-of-state acquirer. The company did eventually buy Gulf Power in the Florida Panhandle in 2019 and folded it into FPL.1 But the record taught a clear lesson that matters enormously in 2026: regulated scale outside Florida had proven harder to buy than renewable scale was to build. To understand why buying more rate base is so attractive anyway, you have to see how the two halves of the company actually make money.
IV. The Dual Engines: Regulated Florida Monopoly Meets Wholesale Powerhouse
There are two rooms that explain NextEra. One is a hearing room in Tallahassee, where FPL's lawyers and the state's Office of Public Counsel argue over the cost of capital, depreciation schedules and how much a household should pay per kilowatt-hour. The other is the commercial operation in Juno Beach, where NEER's teams negotiate long-term contracts with utilities and technology companies and manage a fleet of plants spread across the continent. One room is about permission. The other is about price.
The Tallahassee room produces the larger share of the money. In 2025 FPL generated about $18.3bn of revenue, two-thirds of the group total, and about $5.0bn of segment net income, nearly three-quarters of the total.1 NEER, together with the transmission business, brought in about $8.8bn of revenue and about $2.5bn of net income.1 Those shares add up to more than 100% of profit because the corporate center, loaded with holding company interest, loses money. Hold onto that detail; it is the crack that runs through the whole story.
FPL's economics are a regulated bargain. The utility invests in plants, poles, wires and solar farms, and the Florida Public Service Commission allows it to charge rates that recover its costs plus a return on the equity it has invested. Under the settlement approved in 2021, that return had a midpoint of 10.6%, inside a band from 9.7% to 11.7%.7 Fuel and purchased power costs pass straight through to customers through adjustment clauses, so when natural gas prices spike, customers' bills move rather than FPL's margins.1 In practical terms, FPL is closer to a toll road with a growing number of lanes than to a business that has to win customers.
The quality of the money shows in the receivables. At the end of 2025 customers owed about $4.1bn, and the company held just $82m, about 2%, against the chance it would never be paid.1 About $705m of FPL's receivables was simply unbilled electricity, power already delivered but not yet invoiced because meter-reading cycles do not line up with month-end.1 A utility with the legal right to cut off power to non-payers does not have a collections problem.
Florida's demography is the volume engine. FPL serves more than six million accounts, residential customers provide the majority of its revenue, and the state continues to add residents on a scale few other states match.1 Every new subdivision, every new air conditioner, becomes rate base. That is why FPL's capital spending, about $8.9bn in 2025, is less a cost than a growth plan: each dollar invested, once approved, earns the regulated return.1 The skeptic's point is that this formula depends entirely on the generosity of Florida regulators, and that a political climate turning against high utility bills could narrow the band. For now the record is of constructive outcomes, and the credit agencies treat Florida as one of the best regulatory jurisdictions in the country.5
NEER is a different animal. It owns and operates more than 38 gigawatts of generation, the vast majority wind, solar and battery storage, with more than 85% of its capacity contracted to utilities, cooperatives and companies.1 In recent years the most coveted buyers have been the hyperscale technology firms building data centers, which want enormous quantities of power and increasingly want it to be clean. NEER spent about $15.7bn on capital projects in 2025, nearly twice what FPL spent, which tells you where the company's growth ambitions sit.1
Is NEER's revenue as safe as the contracts imply? The best test is what happens when a customer goes bust. In January 2019 PG&E, California's largest utility and a big buyer of renewable power, filed for Chapter 11 after its equipment was blamed for catastrophic wildfires. The fear was that a bankrupt utility would tear up above-market renewable contracts. NextEra fought that possibility hard, including at federal regulators, and when PG&E emerged from bankruptcy its renewable power contracts were assumed rather than rejected.1 One case does not prove every contract is bulletproof, but it was the most severe stress the model had faced, and the contracts held. The verdict on durability, at least for creditworthy utility buyers, is intact.
So the operating businesses are strong. FPL is one of the best regulated utilities in North America and NEER is a scale developer with durable contracts. The trouble is not in either room. It is in the space between them, in the holding company that borrows to fund NEER's growth, and in how the company reports what that growth earns. To see it, you have to read the cash flow statement.
V. The Financial Machine: HLBV, Tax Equity, and the Free Cash Flow Deficit
Start with the puzzle. In 2025 NextEra reported net income of about $6.8bn and cash from operations of about $12.5bn, nearly twice as much.1 Over twelve years from 2014 to 2025 the pattern holds: cumulative net profit of about $55.6bn against about $100bn of operating cash.1 Usually, when cash runs far ahead of profit, it is a sign of conservative accounting and a healthy business. Here the story is more complicated, because almost all of that cash goes straight back into the ground.
The first clue is depreciation. NextEra owns about $156bn of plant and equipment, and in 2025 it charged about $6.6bn of depreciation and amortization against earnings.1 Depreciation is a real economic cost, because turbines wear out and panels degrade, but it does not leave the bank account in the year it is recorded. That explains most of the gap between profit and operating cash.
The second clue is where it gets subtle. Remember tax equity: banks invest in NEER's projects to harvest their tax credits. Accounting for those partnerships uses a method called hypothetical liquidation at book value, or HLBV. The name is forbidding; the idea is not. At each reporting date the accountants imagine the partnership being sold for its book value and ask who would get what. Because tax equity investors receive most of the tax benefits, the method often allocates large paper losses to them, and those losses are subtracted from consolidated income to arrive at the profit attributable to NextEra's own shareholders. In 2025, losses allocated to these noncontrolling investors totaled about $1.5bn, which means NextEra's reported profit was about $1.5bn higher than it would have been if those partners shared income in proportion to their cash.1 Meanwhile the investors' cash contributions, about $3.3bn in 2025, arrived through the financing section of the cash flow statement, not through operations.1
The third clue is the tax rate. In 2025 NextEra's effective tax rate was negative 17.7%.1 A negative rate means the company booked a tax benefit rather than a tax charge on its pre-tax profit, because production and investment tax credits under the Inflation Reduction Act exceeded the tax otherwise owed. Measured against what the statutory rate would have produced, the credits added roughly $2bn to the year's earnings.1 Since the Inflation Reduction Act of 2022, these credits can also be sold for cash to other taxpayers, and NextEra realized about $1.5bn from such transfers in 2025.1 These are real dollars, but they are subsidy dollars. They depend on federal law, and the 2025 budget legislation already began phasing down credits for new wind and solar projects later in the decade.1
The fourth clue sits in accounts payable. NextEra runs a structured payables program under which banks pay suppliers on the company's behalf, and NextEra repays the banks later.1 At the end of 2025 about $4.2bn of vendor obligations were financed this way.1 They appear as payables rather than debt, which helps explain why the company's days payable have stretched to about 271, an extraordinary figure for any business.1 Economically, a bank-funded payable looks a lot like a short-term loan. Credit analysts can see it, but it does not show up in the headline borrowings figure.
Now the reveal. After capital spending, which reached about $24.6bn in 2025, almost 90% of revenue, free cash flow was about $3.2bn.1 Dividends that year were about $4.7bn.1 Over the twelve years to 2025, cumulative free cash flow of about $20.2bn covered only about 62% of the $32.4bn paid out as dividends.1 The difference, plus everything spent on growth, came from outside: about $23.4bn of new debt was issued in 2025 alone, alongside tax equity and periodic share sales.1
What does that mean in plain English? NextEra is not a company that generates surplus cash and returns it. It is a company that borrows and raises money to build assets that earn regulated or contracted returns, and pays a dividend partly funded by that external capital. There is nothing illegitimate about that; most growing utilities run negative free cash flow. But it means the dividend's safety and the earnings growth both depend on the price and availability of capital. When capital was cheap, the model compounded beautifully. The first place it broke when capital got expensive was the vehicle Jim Robo had built to recycle it.
VI. The YieldCo Trap: The Collapse and Impairment of XPLR (2022–2025)
On September 27, 2023, NextEra Energy Partners told investors something its unitholders had been taught never to expect. The partnership had long promised to grow its distributions by 12% to 15% a year. Now it cut that target to 5% to 8%.[^5] The units fell sharply that day and kept falling. Over the following two years, as the outlook darkened further and distributions were ultimately suspended, the units slid from above $80 at their peak to around $9.50.1 A vehicle designed to be the safest way to own contracted clean energy became one of the worst-performing securities in the utility universe.
To understand why, picture the conveyor belt. NEP bought finished wind and solar farms from NEER. To grow its distribution, it had to keep buying, and to keep buying it needed cheap capital. It got that capital two ways: by issuing new units at a high price, and through a set of structured financings, notably convertible equity portfolio financings with private investors, which provided money up front in exchange for a claim that had to be bought out or refinanced years later.[^5] The model worked only if NEP's units stayed expensive and interest rates stayed low, so that each new acquisition yielded more than the capital cost to buy it.
Then the Federal Reserve raised rates from near zero to above 5% in barely a year, and the renewable growth story collided with the cost of money.9 NEP's cost of capital rose above the yields on the assets it was buying. The buyouts due on its structured financings, once assumed to be easily refinanced, became a cliff. Management responded by slowing growth, then selling assets to address the financing obligations, then, after the partnership was rebranded XPLR Infrastructure in early 2025, suspending distributions to retain cash.1[^5]
For NextEra, which owned a controlling economic stake in the partnership's operating company, the cost showed up as impairments. Under equity-method accounting, NextEra carried its investment at a value on its books, and as the market value fell, it wrote that value down. It took pre-tax charges of about $1.2bn in the third quarter of 2023, about $0.8bn in the fourth quarter of 2024, and about $0.7bn in the first quarter of 2025, cutting the carrying value from about $4.2bn to about $1.0bn.1 Cumulatively, about $2.7bn before tax and $2.0bn after.1 That is the honest price tag of a capital recycling strategy built for a zero-rate world.
The write-downs did not end the relationship. NEER still operates essentially all of XPLR's plants, and the reimbursed costs it bills for that work jumped from about $255m in 2024 to about $1.4bn in 2025, mostly because of extensive work to repower old wind turbines on XPLR's sites.1 At the end of 2025 XPLR owed NextEra about $681m, and NextEra's subsidiaries backed roughly $1.8bn of XPLR obligations with guarantees and letters of credit, some stretching to 2063.1 An activist reading those lines would ask a pointed question: why is the parent still extending credit and services to an affiliate whose equity it has written down by two-thirds? Management's answer, implicit in the filings, is that these are operating relationships on assets it built and knows. That answer may be right, but the exposure is real and the company has not yet said how the chapter ends.
Lawyers have also arrived. In July 2025 a securities class action was filed in the Southern District of California against XPLR, NextEra and certain executives, alleging that investors were misled about the partnership's distribution growth and access to capital before the cut.1 Its outcome is uncertain, and the claims are allegations, not findings.
The verdict here is clear. NEP owned good assets, contracted wind and solar farms with creditworthy buyers. What broke was the capital structure layered on top of them. NextEra survived the collapse comfortably; $2bn of after-tax write-downs is painful but not dangerous for a company earning more than $6bn a year. But it lost its cheapest way to recycle capital at exactly the moment its capital needs were growing fastest. That loss, combined with turbulence at the top of the company, set the stage for the most audacious decision of the Ketchum era.
VII. The Ketchum Era, Boardroom Turmoil, and the Virginia Gambit (2022–Today)
On May 15, 2026, NextEra announced it had agreed to buy Dominion Energy.4 For a company whose last two attempts at large regulated acquisitions had been rejected by state commissions, it was an astonishing return to the scene of past defeats, and on a far bigger scale. Dominion is the dominant electric utility in Virginia, and Virginia, specifically the corridor of Loudoun and Prince William counties outside Washington, is home to the densest concentration of data centers on earth.11 NextEra was betting that the future of American electricity demand would be written there.
The man making the bet is John Ketchum. A lawyer by training who joined NextEra in 2002 and rose through the general counsel's office, the CFO's chair and leadership of NEER, Ketchum succeeded Jim Robo as chief executive in March 2022.13 Where Robo was the GE-trained operator, Ketchum is the deal architect who knows every clause of the tax equity structures and the regulatory filings. His 2025 compensation was about $24.2m, and shareholders approved the company's pay practices with about 88% support, a passing grade but not an overwhelming one for a large-cap utility.3 He leads a twelve-member board on which he is the only insider.3
His tenure has not been calm. In the space of about three years, NextEra's finance leadership turned over repeatedly. Rebecca Kujawa moved from CFO to lead NEER in 2022; Kirk Crews became CFO; in 2024 the company recruited Brian Bolster from Goldman Sachs into the role while Crews moved to chief risk officer; Bolster resigned after roughly six months; and treasurer Michael Dunne became CFO in November 2024.3 Some of these moves reflect normal succession. Taken together, at a company whose investment case depends on financial credibility, they unsettled investors, and the company did not publicly explain Bolster's rapid exit in any detail.
The political overhang has been stickier. In January 2023 Eric Silagy, FPL's long-time chief executive, retired amid reporting about the role of consultants paid by FPL in Florida political campaigns, including allegations around so-called ghost candidates.8 Shareholders sued, alleging NextEra misled them about these risks. A federal court in Florida dismissed the case in 2024, but on November 26, 2025 the Eleventh Circuit reversed the dismissal and sent the lawsuit back for further proceedings.8 Shareholder derivative suits remain stayed behind it.1 Nothing has been proven, but it is a live legal question about the conduct of the crown-jewel subsidiary.
It is against that backdrop of a broken yieldco, executive churn, litigation and a heavy debt load that the Dominion deal makes sense, and also looks daring. The terms: each Dominion share becomes 0.8138 NextEra shares plus a modest cash component, which means NextEra will issue roughly 685 million new shares, a dilution of roughly a third of its existing share count.24 To win over Virginia and the other jurisdictions, NextEra committed about $2.25bn in bill credits to Dominion's utility customers.2 If the deal fails for certain regulatory reasons, NextEra could owe a termination fee of between $4.8bn and $6.5bn; Dominion's fee runs the other way at about $2.2bn.2 Closing is expected in the second half of 2027, pending approvals from federal regulators, the Nuclear Regulatory Commission and state commissions including Virginia's.2
The industrial logic is easy to grasp. Data center load in Dominion's territory has grown faster than almost anywhere in America, and a regulated utility serving it can invest heavily in generation and transmission and earn an approved return on every dollar. Combine Dominion with FPL and the share of NextEra's earnings coming from regulated utilities rises well above three-quarters, which, if rating agencies agree, should make the group's debt safer and cheaper to roll.4 Moody's and S&P both affirmed NextEra's ratings after the announcement, a meaningful vote of confidence.56
The skeptical reading is equally clear. A company that has relied on non-regulated growth to justify a premium multiple is buying a lower-growth, more heavily regulated business with its own shares at a time when those shares are cheap by its own historical standards. It is paying customers a large sum up front to secure approval. And its history in exactly this kind of transaction is two rejections in two attempts. The deal may be the right strategic answer to the end of cheap capital. It is also an admission that the old answer, building renewables and recycling them through a yieldco, no longer pays as well. Whether NextEra's advantages survive that shift depends on what those advantages really are.
VIII. Moat Analysis: Porter's Five Forces and Hamilton Helmer's 7 Powers
Imagine laying a map of the North American grid on a table and marking where NextEra's rivals stand. To the north and west, Duke Energy and Southern Company, regulated giants with territories of their own. Across the map, renewable developers such as Brookfield Renewable, AES and Invenergy, plus well-capitalized European utilities and Ørsted, all chasing the same corporate buyers and the same grid connections. The question is what NextEra has that they cannot copy.
Hamilton Helmer's framework of seven sources of durable advantage is a useful lens. Start with scale economies. NEER's case rests here: a company that builds more wind, solar and storage than almost anyone can spread engineering, procurement and financing costs over more megawatts and negotiate harder with suppliers.[^6] The evidence is real, though the precise discount it extracts is not disclosed, and scale in buying commodity equipment is an advantage competitors can narrow by growing. Call it strong but not unassailable.
The most durable power is a cornered resource. FPL's Florida franchise cannot be replicated; it is granted by the state and comes with a monopoly on retail distribution. NEER, too, holds something hard to rebuild: years of queue positions to connect new plants to the grid in the major regional markets, and transmission rights that take a decade to assemble.1 In an era when interconnection queues stretch for years, an approved spot on the grid is worth almost as much as the plant that will occupy it.
Switching costs are high at FPL, where customers have no alternative supplier, and moderate at NEER, where buyers are locked into long contracts but free to choose someone else for their next one. Process power, the Deming-era operating discipline, still shows in FPL's low costs and its storm restoration record, but the yieldco collapse and the rapid turnover in finance leadership suggest it extends less fully to the capital markets side than it once did. Network effects and branding barely apply: electrons carry no logo. Counter-positioning was NextEra's great power from roughly 2002 to 2012, when it built wind while incumbents defended coal, but every major utility now builds renewables, so that advantage has largely been spent.
Michael Porter's five forces tell a consistent story. New entrants face high barriers, because gigawatt-scale development needs billions in balance sheet, access to tax equity and years in interconnection queues. Supplier power is moderate: turbine and panel makers have pricing power in tight markets, which NextEra offsets with volume and, as the structured payables show, by using banks to stretch its payment terms.1 Buyer power splits in two. FPL's customers are captive, though Florida's regulators act as their proxy. NEER's most important new buyers, the hyperscale technology companies, are among the most sophisticated purchasers of power in the world, run competitive tenders and buy from multiple suppliers. Substitutes are a slow-moving threat: nuclear life extensions, small modular reactors and on-site generation could compete for data center demand over the long term. Rivalry among developers is intense and compresses margins on contracts.
Put together, the verdict is that NextEra's strongest moats are the ones that are regulatory or physical, the Florida franchise and the grid positions, while the advantages that once set NEER apart, scale buying and financial engineering, have narrowed. The most important thing a moat does for a utility, though, is let it borrow cheaply, and that is where the map becomes worrying. NextEra has about $41.6bn of debt maturing between 2026 and 2030, and roughly $37.2bn of it sits outside FPL.1 A moat that protects revenue does not, by itself, protect the cost of refinancing. The lessons of the century so far are about exactly that distinction.
IX. Playbook: Business and Investing Lessons
Three moments frame what NextEra has to teach. In 1985 a Florida utility bought a mail-order insurance company and learned it did not know insurance. In 2001 its unregulated arm finished a wind farm on the Oregon border while the merchant energy world burned. In 2023 its yieldco told investors that the growth they had been promised was gone. Each moment carries a lesson that belongs to this company and no other.
The first lesson is that a moonshot needs a monopoly underneath it. NEER's bets on wind and solar in the early 2000s were enormous for their time, and they were only possible because FPL's steady, regulated cash and strong credit made lenders comfortable lending to the whole group. Most clean energy developers of that era did not have a Florida utility behind them, and many of them did not survive. For founders and investors, the lesson is about financing structure more than vision: the company that can borrow against something dull will outlast the company that has only something exciting. NextEra's growth engine ran on its boring twin.
The second lesson is that in a commodity business, scale is the only moat that pays. NEER never had a better turbine or a cleverer panel than anyone else. It had more orders, more projects and more contracting experience, and it converted that volume into a lower cost per megawatt-hour. That works until competitors grow too, which is why the advantage has narrowed. Volume buys time, not immortality.
The third lesson is the one the yieldco wrote in red ink: good assets do not make good capital structures. NEP owned contracted wind and solar farms with creditworthy buyers, and it still lost the vast majority of its unit value, because its promise to grow distributions depended on issuing units at high prices and refinancing at low rates. When rates normalized, the assets kept working and the structure stopped. The $2.7bn of impairments NextEra absorbed is the tuition.1 A yieldco is a bet on the cost of money dressed up as a bet on sunshine.
The fourth lesson is that tax credits are a currency. NextEra's mastery of tax equity, HLBV accounting and credit transfers let it effectively mint development capital from the federal tax code, and in 2025 it reported a negative tax rate as a result.1 That is a genuine skill, and a genuine source of value. It also means the earnings stream has a policy dependency that investors must price, and accounting that most of them struggle to read. When a company's profit depends on which partner the accountants imagine walking away with what, the multiple should reflect the imagination involved.
The fifth lesson is the newest: when the cost of capital rises, the rate base is the shelter. Faced with expensive money and a broken recycling vehicle, NextEra reached for the one asset class where higher financing costs can eventually be passed to customers by regulators, buying Dominion's Virginia franchise. It is a logical move. It is also a retreat from the strategy that earned the premium. The company that taught Wall Street utilities could grow like developers is now teaching it that developers, in the end, want to be utilities. Whether investors will pay a premium for that lesson is the question the valuation now poses.
X. Bull vs. Bear Case: The Trillion-Dollar Balance Sheet Test
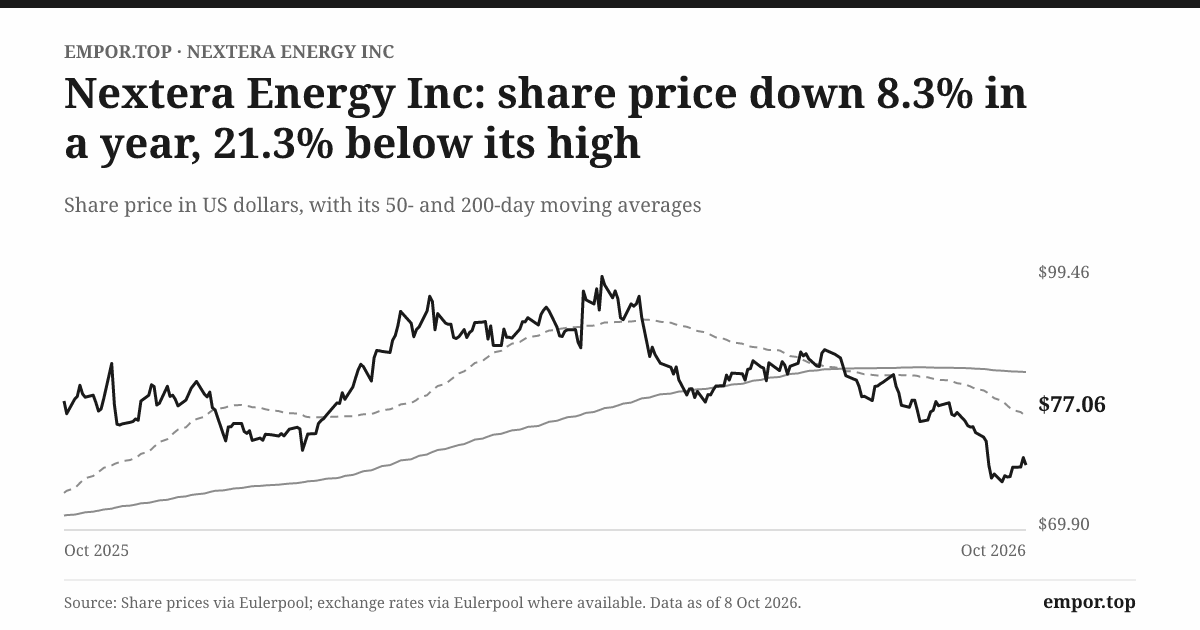
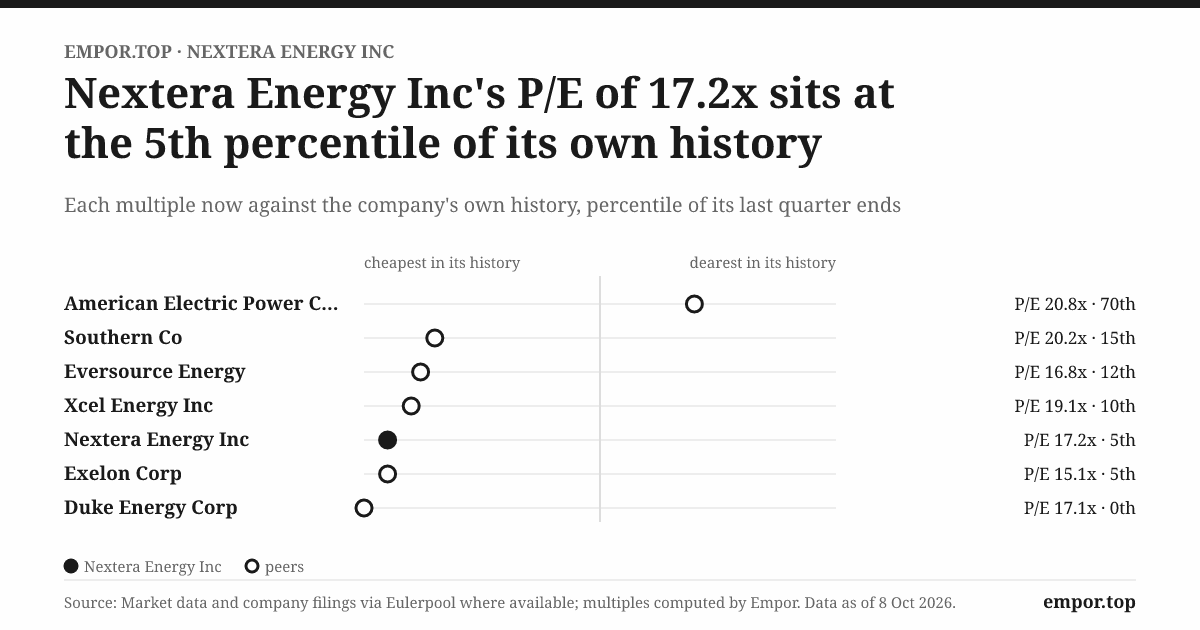
On October 8, 2026, NextEra shares closed at $77.06, about 21% below their 52-week high.1 At that price the market valued the company at about 17 times trailing earnings, against a five-year median of about 24 times.1 For comparison, Duke Energy and Southern Company, the archetypal regulated utilities, traded at roughly 16 to 17 times forward earnings.1 In other words, the market had largely stopped paying NextEra a growth premium on earnings. It still paid a premium on enterprise value relative to operating cash earnings, about 15 times EBITDA against roughly 10 to 12 for those peers, which reflects how much debt sits beneath the equity.1 The price appears to assume that NextEra is now something close to a very large, very indebted regulated utility, with the renewable business valued as an add-on rather than an engine.
The bull case starts with demand. If artificial intelligence drives a decade of electricity growth, the most valuable assets in American power will be the ones that can deliver new capacity quickly to data centers. A combined NextEra and Dominion would own both the largest renewable development platform in the country and the utility franchise in the most important data center market in the world.4 Florida keeps growing and FPL keeps investing within a constructive regulatory regime.7 Credit transfers under the Inflation Reduction Act have given NEER a direct way to turn tax credits into cash, about $1.5bn in 2025.1 And at 17 times earnings, against a history of 24, a smooth Dominion integration could invite the market to pay more again; the PEG ratio of about 1.05 says the multiple roughly matches recent earnings growth.1
The bear case starts with the debt. NextEra's interest expense reached about $4.6bn in 2025, inflated partly by derivative losses but rising fundamentally because borrowings keep climbing.1 The maturities peak at about $10.3bn in 2027 and $10.6bn in 2028.1 Much of the holding company debt was issued at coupons well below today's rates; NEECH's plain debentures carried a weighted average rate around 4.2%.1 Every refinancing at a higher coupon is a direct deduction from earnings that FPL's regulator will never make up. Then there is dilution: roughly 685 million new shares for Dominion, plus a $4bn at-the-market program established at the end of 2025, mean existing holders' slice of future earnings will shrink.12 The $2.25bn in bill credits and the threat of a termination fee of up to $6.5bn set the price of regulatory failure.2 XPLR still owes money and leans on parental guarantees.1 And earnings that benefit from a negative tax rate and HLBV allocations are exposed to every change in federal tax policy, as the 2025 legislation phasing down new wind and solar credits already demonstrated.1
An activist looking at this company would ask a few hard questions. Why does a group with negative free cash flow keep raising its dividend, funding part of it with borrowed money? Why are the holding company's financing costs not more clearly disclosed by segment, given that they are the main drag on returns? What is the endgame for XPLR? And why should shareholders trust a regulated acquisition track record that, before Gulf Power, consisted of two public rejections? None of those questions has a decisive answer yet.
Weighing it all, the history narrows rather than rejects the bull case. NextEra's operating assets are excellent, and its regulated franchise is among the best in the country. But the premium multiple of the 2010s was built on cheap capital and financial engineering that the company's own record shows can fail. What remains is a smaller, more credible claim: NextEra can be a large-scale regulated and contracted infrastructure compounder, earning modestly above peers, if it refinances well and integrates Dominion cleanly.
Three readings will tell investors which version is coming true. The first is the coupon NextEra Energy Capital Holdings pays on new debt as it refinances the 2027 and 2028 maturities; the existing debentures average about 4.2%, and the gap between that figure and new issuance rates measures the earnings headwind directly.1 The second is the return on equity and capital structure the Virginia State Corporation Commission allows Dominion's utility in its approval of the merger, which will define the economics of the largest asset NextEra has ever bought.2 The third is the pace at which NEER adds new contracted capacity, especially with hyperscale technology buyers, because that is the only proof that the growth engine still runs without a yieldco behind it.[^7][^8] The coming eighteen months will deliver all three.
XI. Epilogue
Tonight NextEra stands between two calendars. On one, regulators in Richmond, Tallahassee and Washington will work through the Dominion approval, in proceedings where consumer advocates are likely to question whether $2.25bn of bill credits is enough and whether a Florida company should own Virginia's grid.2 The Nuclear Regulatory Commission must approve the transfer of Dominion's nuclear licenses. The company expects to close in the second half of 2027.2 On the other calendar, NextEra's treasury team faces its heaviest refinancing years yet, with roughly $10bn of debt maturing in 2027 and again in 2028.1
If the deal closes on reasonable terms and the debt rolls at manageable spreads, NextEra emerges as something genuinely new: a regulated utility empire spanning the fastest-growing state in the Southeast and the most important data center region in the world, with a renewable developer attached. Its earnings would lean overwhelmingly on regulated returns, its credit would be sturdier, and its holding company debt problem would shrink as a share of the whole. In that world the first central question, whether the holding company can refinance without crushing returns, gets a yes.
If regulators impose harsh conditions, or the deal stalls, the outcome is darker. NextEra would face either a less profitable Dominion or a termination fee of several billion dollars, on top of a refinancing wall it would then have to climb alone. A failure in Virginia would also confirm the lesson from Hawaii and Texas: that regulated scale outside Florida is not NextEra's to buy.
Two legal threads will run alongside. In Florida, the shareholder case over political spending, revived by the Eleventh Circuit, returns to the district court.8 In California, the XPLR securities class action proceeds.1 Neither is likely to threaten the company financially, but both speak to governance at moments when trust matters most.
And then there is the loose end from 2014. NextEra still operates XPLR's plants, holds its receivables and guarantees its obligations. Whether it eventually buys back those assets, walks away, or lets the affiliate wind down on its own, the decision will close the yieldco chapter and tell investors what kind of capital allocator John Ketchum really is. The tension that remains is simple to state: NextEra knows how to build power plants better than almost anyone, but the next two years will be decided by how well it borrows.
XII. Outro
In 1925 Florida Power & Light was a patchwork of ice plants and small power stations serving towns that the land bust was about to empty. A century later the company it became is valued at more than a quarter of a trillion dollars, runs one of the best utilities in America, has built more wind and solar than almost anyone on earth, and is reaching north to power the server halls of the artificial intelligence economy.
What makes NextEra unlike any other company is that it mastered two arts that rarely live in the same building: the engineering of cheap clean power and the regulatory craft of the rate base. Its one undefeated opponent has been the cost of money. NextEra proved to Wall Street that clean energy could be built at massive industrial scale. Now it has to prove that a giant built on cheap capital can still rule the grid now that money is expensive again.
References
-
Form 10-K Annual Report for the Fiscal Year Ended December 31, 2025 — NextEra Energy, Inc., 2026-02-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Form 10-Q Quarterly Report for the Period Ended June 30, 2026 — NextEra Energy, Inc., 2026-07-24 ↩↩↩↩↩↩↩↩↩↩
-
Definitive Proxy Statement on Schedule 14A — NextEra Energy, Inc., 2026-04-01 ↩↩↩↩
-
NextEra Energy Announces Agreement to Acquire Dominion Energy — NextEra Energy News Release, 2026-05-15 ↩↩↩↩↩
-
Credit Opinion: NextEra Energy, Inc. Rating In-Depth Update — Moody's Investors Service, 2026-05-18 ↩↩
-
Research Update: NextEra Energy, Inc. Ratings Affirmed Following Dominion Merger Announcement — S&P Global Ratings, 2026-05-16 ↩
-
NextEra Energy and Florida Power & Light 2021 Base Rate Settlement Agreement Order — Florida Public Service Commission, 2021-12-02 ↩↩↩
-
Eleventh Circuit Court of Appeals Opinion Reversing Dismissal of Securities Action (Case No. 24-13102) — U.S. Court of Appeals for the 11th Circuit, 2025-11-26 ↩↩↩
-
NextEra's Renewable Growth Strategy Meets High Interest Rates — Wall Street Journal, 2023-10-02 ↩
-
How NextEra Built America's Largest Renewable Energy Developer — Financial Times, 2022-03-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dominion Energy Agrees to Acquisition by NextEra Energy in Multi-Billion Utility Deal — Reuters, 2026-05-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube