Morgan Stanley: The Survivor's Fortress
I. Forty-Eight Hours From Extinction
On the Monday of Columbus Day weekend in October 2008, American commercial banks were closed for the holiday and the wire systems that normally move billions of dollars in seconds were quiet. Morgan Stanley could not wait for Tuesday. Its share price had fallen by more than half in a handful of trading days, hedge funds were pulling their balances out of its prime brokerage, and the market was openly betting that it would be the next Lehman Brothers.1 Mitsubishi UFJ Financial Group had agreed to put $9 billion into the firm, but the deal had wobbled all weekend, and the Japanese bank wanted the money delivered before the markets could vote again.2
So the money arrived the old-fashioned way. Robert Kindler, Morgan Stanley's vice chairman and a veteran deal lawyer, waited at the Manhattan offices of Wachtell, Lipton, Rosen & Katz while MUFG's representatives handed over a single paper check for $9 billion, reported to be the largest amount ever written on a physical check.31 A piece of paper, signed by a Tokyo bank, was what stood between a 73-year-old American institution and the bankruptcy court.
It is worth sitting with how close it was. A few weeks earlier, according to accounts of the crisis, Treasury Secretary Hank Paulson had sounded out JPMorgan Chase's Jamie Dimon about taking Morgan Stanley over, and Dimon had passed.1 On September 21, 2008, Morgan Stanley and Goldman Sachs gave up their status as stand-alone investment banks and became bank holding companies supervised by the Federal Reserve, trading their old freedom for access to the central bank's balance sheet.[^4] The MUFG check sealed the second half of the rescue.2
That weekend is the hinge of this story, because almost everything Morgan Stanley is today was built as an answer to it. The firm that nearly died was a trading house running roughly $800 billion of balance sheet on thin equity.1 The firm that exists in October 2026 is valued at about $302 billion, oversees about $9.3 trillion of client assets in its wealth business, and trades at about 2.7 times its book value, a richer multiple than Goldman Sachs at about 2.1 times.4 The market is paying a premium for stability at a company whose defining memory is instability.
Three questions run through the rest of the story. The first is whether the wealth management engine can hold pre-tax margins near 29% while lawsuits and regulators push up the interest it pays on client cash.45 The second is whether the surge in trading and banking profits under chief executive Ted Pick is market share the firm will keep or a cyclical high it will give back.6 The third is whether the next round of bank capital rules will force the firm to retain more equity and slow the buybacks that have helped lift returns.4
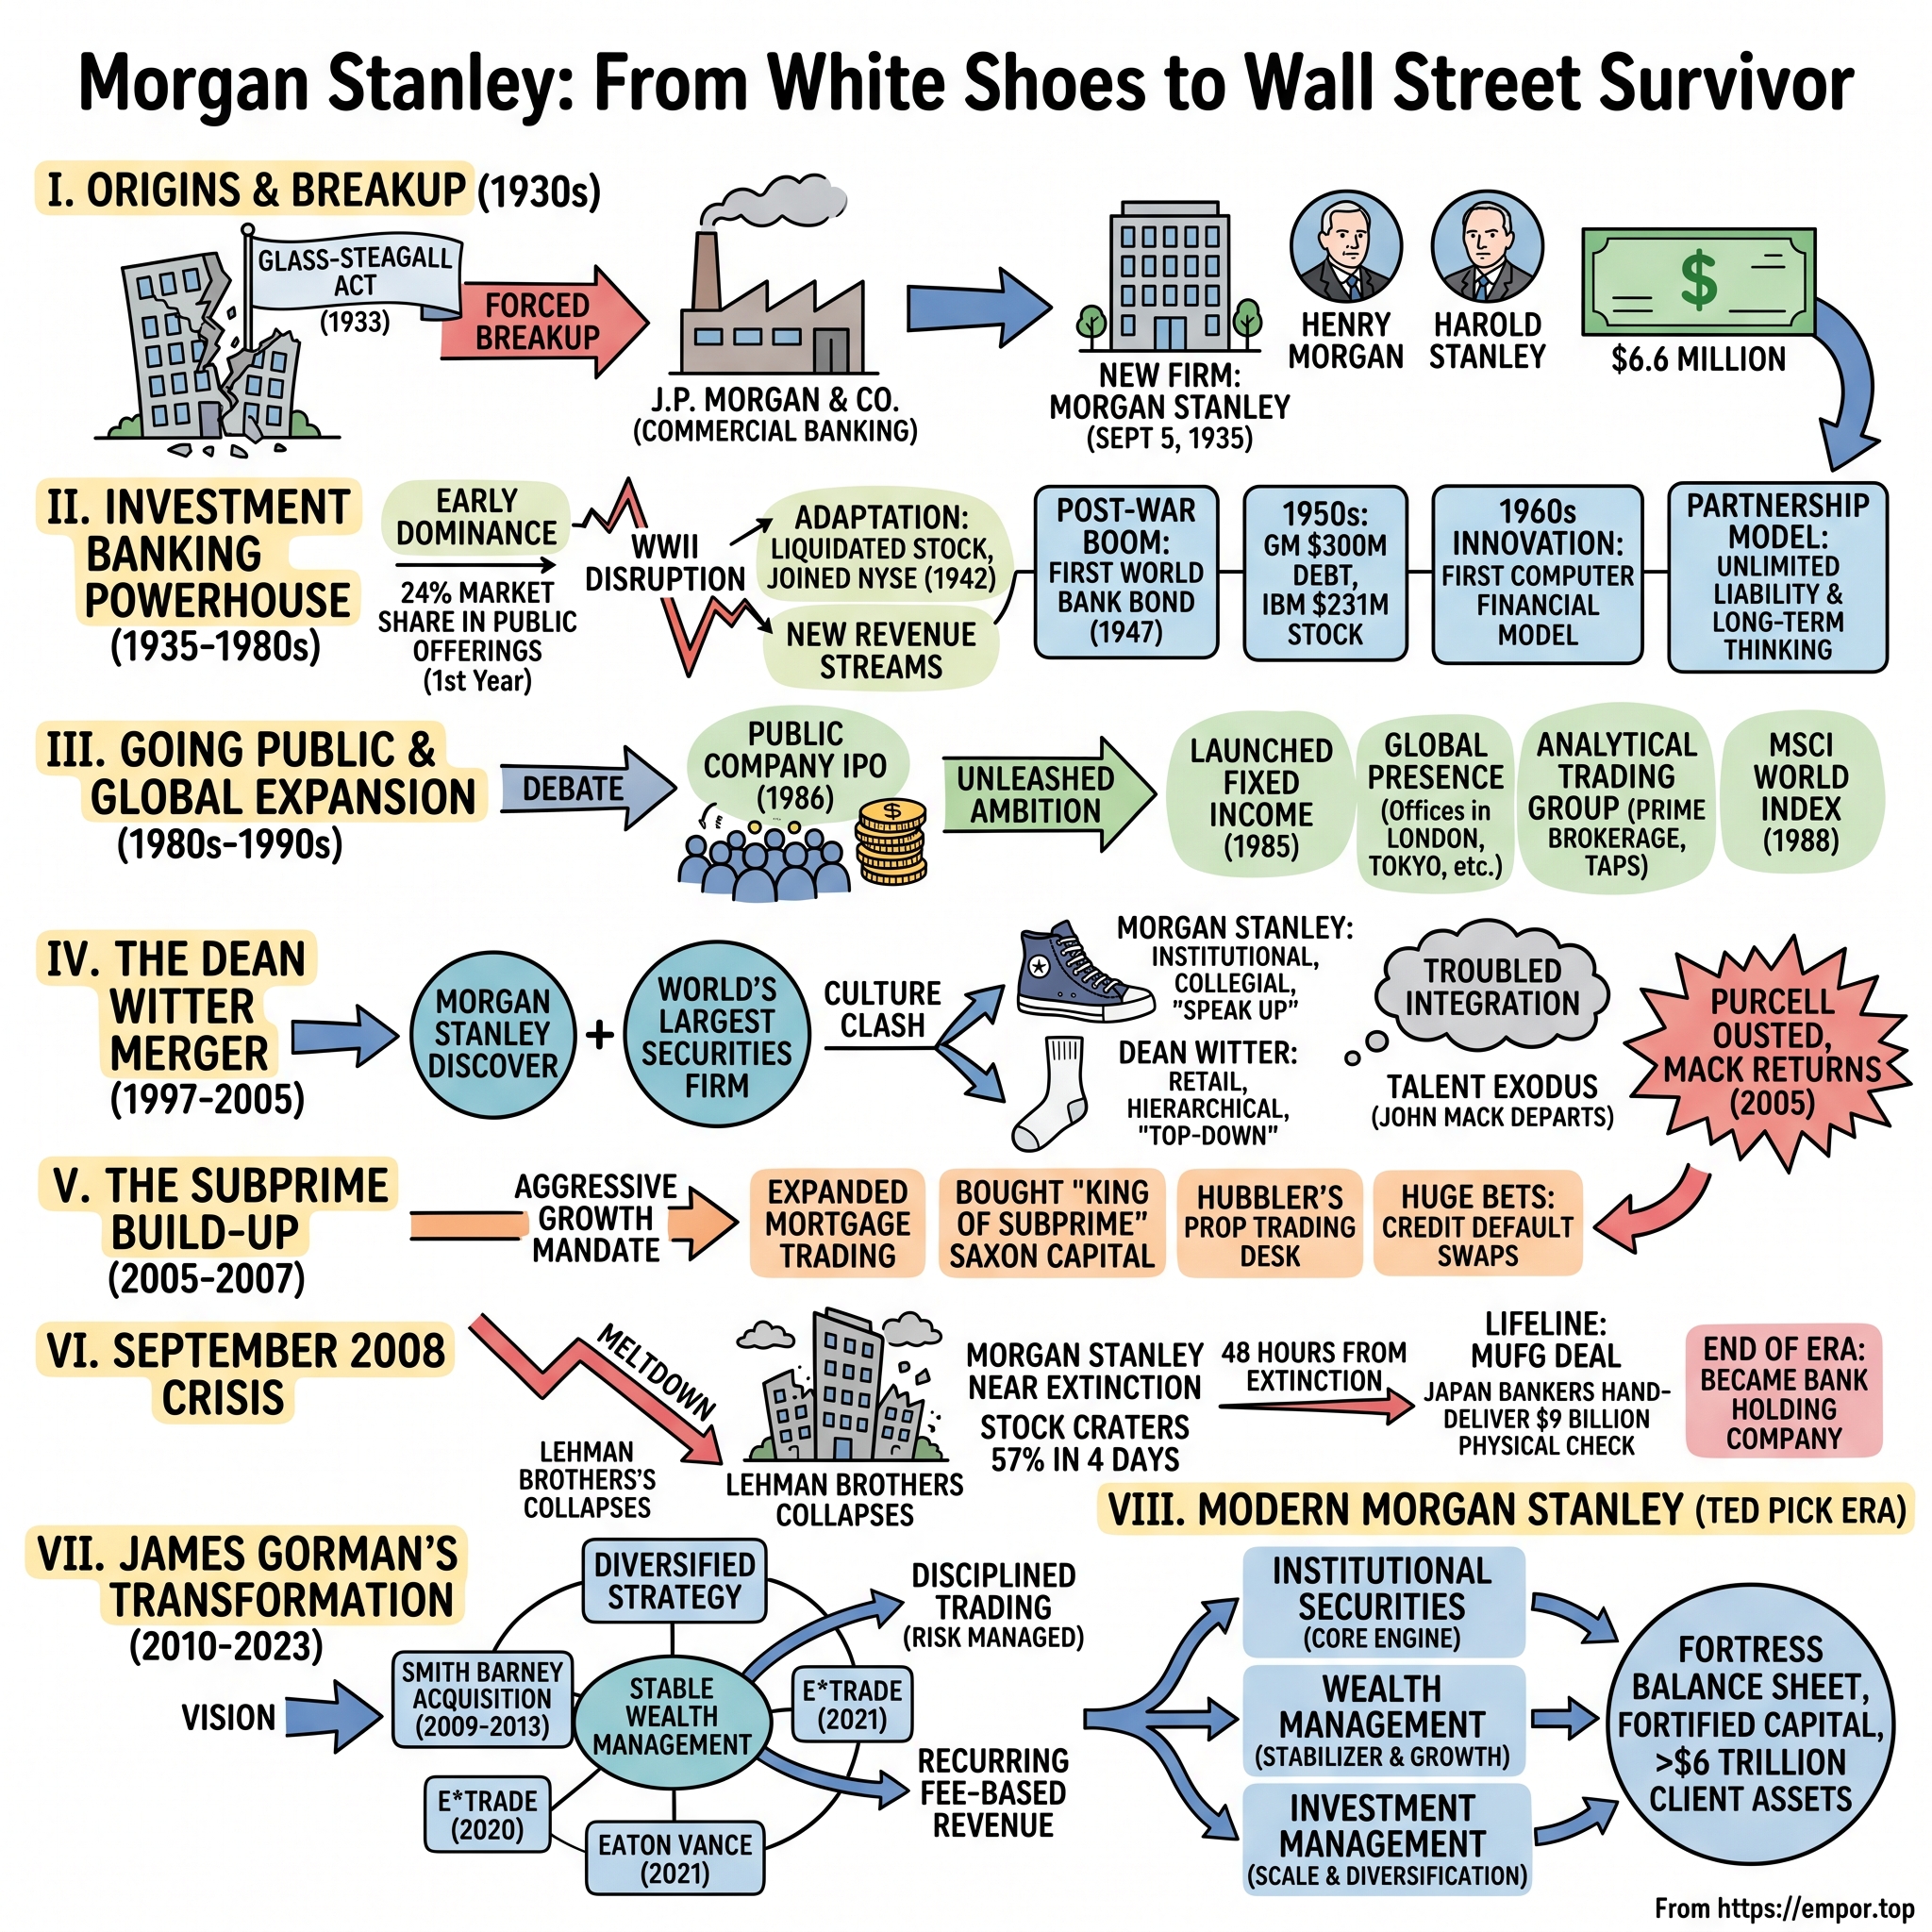
To answer them, the story has to go back to a forced divorce in 1935, through a merger that tore the firm's culture apart, into the mortgage trade that nearly finished it, and then forward through James Gorman's long bet on wealth management and Ted Pick's reignition of the trading floor. It starts with a law that told the House of Morgan it could no longer be two things at once.
 Subscribe on LinkedIn
II. The Sons of J. Pierpont: Glass-Steagall and the White-Shoe Aristocracy (1935–1985)
In the early 1930s, a Senate committee counsel named Ferdinand Pecora spent months grilling the titans of Wall Street about the stock market crash, and the House of Morgan was among the institutions put on display. Out of that public reckoning came the Banking Act of 1933, better known as Glass-Steagall, which forced American banks to choose: take deposits, or underwrite securities, but not both. J.P. Morgan & Co. chose deposits. Its underwriting relationships, the most valuable list of corporate clients in America, needed a new home.
That home opened on September 16, 1935. Henry Sturgis Morgan, a grandson of J. Pierpont Morgan, and Harold Stanley, a Morgan partner with a reputation as the most polished deal-maker of his generation, left with a group of colleagues to found Morgan Stanley.3 The firm took no deposits and kept a modest balance sheet; what it had was the Morgan name, a phone book of the best boardrooms in the country, and a promise to do what the parent bank was no longer allowed to do.
The bet paid immediately. In its first year, Morgan Stanley handled about $1.1 billion of public offerings and private placements, roughly a quarter of the American market.3 That is a remarkable number for a start-up in the middle of the Depression, and it says less about Morgan Stanley's capital than about its relationships. Corporate treasurers did not hire the firm because it had the biggest balance sheet. They hired it because the people who used to do their deals at J.P. Morgan now did them across the street.
The post-war decades turned that relationship franchise into an aristocracy. Morgan Stanley co-managed bond issues for the World Bank in the early 1950s, helping the new institution fund reconstruction, and in 1954 it ran General Motors' $300 million debt offering and IBM's $231 million stock sale, deals that were enormous for their time.3 The firm's internal motto, often summarized as first-class business in a first-class way, captured a posture as much as a strategy: Morgan Stanley was the banker that insisted on being sole manager, refused to share the top line of a tombstone ad, and treated its clients as long-term confidants rather than counterparties.
This is the origin of the brand premium that still shows up in the stock price, and it is worth being precise about what it was. It was not a moat in the sense of something a rival could not copy. It was trust, accumulated one board meeting at a time, and it was only as valuable as the deal flow corporate America chose to send. Because the firm took little balance-sheet risk, it also earned little recurring income. When underwriting dried up, the revenue dried up with it, and the partners simply earned less.
For decades that did not matter, because the partnership's capital was small and its costs were mostly its people. But by the 1970s and 1980s the business of Wall Street was changing underneath the aristocrats. Fixed commissions were abolished, institutional investors began demanding that banks trade with them and hold inventory, and rivals with bigger balance sheets started winning mandates by putting their own capital at risk. A firm built on relationships was about to discover that relationships needed financing.
III. Going Public, Trading Floor Envy, and the Dean Witter Civil War (1986–2005)
In 1986, Morgan Stanley did the thing its founders had never needed to do: it sold shares to the public. The logic was simple and, at the time, unanswerable. A trading floor that competed with Salomon Brothers and Goldman Sachs needed permanent capital that a private partnership could not provide, and the only place to get it was the stock market.3 With the IPO, the partners stopped being owners of their own risk, and the firm started the long drift from adviser to principal.
The next decade looked like a triumph of that choice. Morgan Stanley built an index and analytics business that would later become MSCI, moved into a gleaming tower at 1585 Broadway in Times Square, and expanded its institutional trading and research to match any rival on the Street.3 Yet the old weakness remained. Advisory and trading revenue swung with the markets, and a public company is judged every quarter in a way a partnership never was.
The answer, in 1997, was a merger that looked like strategic genius on paper. Dean Witter Discover was a retail brokerage with thousands of brokers selling stocks and funds to Middle America, plus the Discover credit card, a steady consumer lending franchise. Combining it with Morgan Stanley in a deal valued at about $10 billion created Morgan Stanley Dean Witter Discover, an institution that married lumpy investment banking fees to the dependable cash flows of retail commissions and card interest.3 With hindsight, the thesis was about twenty years early and basically right. Stable retail money was exactly what Morgan Stanley would need to survive the next crisis.
The execution was a disaster, and the reason was people. Dean Witter's chief executive, Philip Purcell, a former McKinsey consultant from Salt Lake City, became chief executive of the combined firm. Morgan Stanley's John Mack, a North Carolina-born bond salesman known for his loud, egalitarian, trading-floor style, became president. The bankers had a name for the mismatch, white shoes versus white socks, and the condescension was mutual. Purcell ran the firm from the top down, with an eye on costs and control; Mack ran it from the floor, with an eye on deals and people. Within a few years only one of them could stay.
It was Purcell. Mack left in 2001, and the firm dropped Dean Witter from its name the same year, as if a change of letterhead could settle the argument.3 Senior bankers and traders followed Mack out the door. The firm lost ground in investment banking, its share price lagged, and legal problems piled up. The most spectacular came in 2005, when a Florida jury ordered Morgan Stanley to pay about $1.45 billion to the financier Ronald Perelman over its role in the sale of Coleman to Sunbeam, after the firm had been sanctioned for failing to produce documents. An appeals court later threw out the verdict, but in 2005 it looked like a symbol of a firm that had lost its grip.3
Then came the revolt. A group of eight retired Morgan Stanley partners, including former leaders such as Robert Scott and Parker Gilbert, took out full-page newspaper advertisements calling for Purcell's removal, an extraordinary public attack by the old guard on a sitting chief executive.3 The pressure worked. Purcell resigned in June 2005, and the board brought back John Mack to restore the culture of the trading floor.
The lesson the firm drew from that civil war was the wrong one. The Dean Witter merger had been a good idea badly managed. The firm treated it as a bad idea, put the retail business in the back seat, and asked its returning hero to do the thing he knew best: take more risk and catch Goldman Sachs.
IV. Mack the Knife and the Subprime Abyss (2005–2008)
John Mack came back with a mandate and a nickname. They called him Mack the Knife for his willingness to cut costs and people, but his first priority in 2005 was growth. Goldman Sachs and Lehman Brothers were earning returns on equity that made Morgan Stanley look sleepy, and the gap was largely about leverage and proprietary trading. Mack set out to close it, and the balance sheet swelled until Morgan Stanley was running roughly thirty-odd dollars of assets for every dollar of equity, a ratio that left almost no room for error.1
The error arrived on a proprietary credit desk run by a star trader named Howie Hubler. His team had made a smart bet against the riskiest slices of subprime mortgage securities. To pay for that bet, it sold insurance on roughly $16 billion of higher-rated, supposedly safe tranches, on the theory that those slices would never default. When the housing market broke in 2007, they did, and the trade produced a loss widely reported at around $9 billion, one of the largest single trading losses in Wall Street history.1 The short was right; the hedge was a catastrophe. Risk limits had measured the desk as roughly neutral, which is exactly why nobody stopped it.
That loss weakened the firm, but it was not what nearly killed it. What nearly killed it was funding. A broker-dealer finances its inventory and client loans with short-term borrowing, and it holds hedge fund cash in its prime brokerage that clients can withdraw on demand. When Lehman Brothers filed for bankruptcy on September 15, 2008, every client and lender of every investment bank asked the same question at once: is my money safe here? At Morgan Stanley, hedge funds moved balances elsewhere, counterparties shortened their terms, and the share price fell by more than half in about four trading days.1 At its worst point the firm leaned on tens of billions of dollars of emergency Federal Reserve lending to keep paying out.1
The weekend negotiations that followed have become Wall Street legend. Mack and his team explored combinations with Wachovia, with China's state investment vehicle CITIC and others, and with sovereign wealth funds, while Paulson's Treasury canvassed possible acquirers.1 Dimon's JPMorgan declined to take the firm. On September 21 the Federal Reserve approved Morgan Stanley's conversion into a bank holding company, which gave it access to the Fed and signaled to the market that Washington would not let it fail by a funding run alone.[^4]
The Japanese bank was the missing piece. Mitsubishi UFJ Financial Group agreed in late September to invest $9 billion for about a fifth of the company, mostly in convertible preferred stock.23 When Morgan Stanley's shares kept falling into October, the terms were reworked so that MUFG took a larger share of preferred paying a 10% dividend, and the money was handed over in that famous check on October 13, 2008.21
The verdict on this period is uncomfortable for anyone who prizes Wall Street's trading culture. Morgan Stanley did not survive 2008 because its risk management was good; the Hubler trade proved otherwise. It survived because it had a brand worth rescuing, a government that changed the rules overnight, and a foreign bank willing to bet that the franchise would be worth more than the check. The price of survival was the old model itself. A Fed-regulated bank holding company could not run at thirty times leverage, and the next leader would have to find a different way to make money.
V. The Gorman Doctrine: Buying the Street's Largest Annuity (2009–2020)
Even before the panic had fully passed, Morgan Stanley went shopping. In January 2009, it agreed to combine its brokerage with Citigroup's Smith Barney, whose parent was being kept alive by the government and needed to raise capital. The deal created Morgan Stanley Smith Barney, a joint venture in which Morgan Stanley owned 51% at the start, with a path to buy out the rest.37 Citi was a forced seller. Morgan Stanley was a buyer that had just been rescued itself. It was a strange moment to make the biggest bet in the firm's history.
The man behind it was James Gorman, an Australian lawyer turned McKinsey consultant who had come to Wall Street to run brokerage at Merrill Lynch before joining Morgan Stanley's wealth business in 2006. He became chief executive in January 2010, and he brought an outsider's coldness to the place.7 Gorman looked at the firm's history and saw a business whose earnings disappeared whenever markets did. He looked at the post-crisis rulebook and saw a world in which trading inventory would carry punishing capital charges. And he looked at wealth management and saw something rare in finance: revenue that came back every quarter whether or not the markets cooperated.
Integrating Smith Barney was slow and unglamorous. Two brokerage forces with different technology platforms, pay plans and cultures had to be merged, and the work took years. Morgan Stanley bought out Citigroup's remaining stake in stages, finishing in 2013 on terms that valued the whole venture at about $13.5 billion.37 By the time it was done, the firm controlled one of the largest adviser forces in the world, and the margin of the wealth business had begun its long climb from the low single digits of the crisis toward the high twenties.7
The harder decision was what to take away. In late 2015, Gorman cut deeply into fixed income trading, eliminating about a quarter of the staff in that business and shrinking the capital devoted to it.7 Analysts and rival executives saw a retreat. Fixed income had been the profit engine of the pre-crisis Street, and walking away from it looked like conceding the field to Goldman Sachs and JPMorgan. Gorman's answer was arithmetic. Every dollar of capital pulled out of bond trading was a dollar that could fund wealth management lending or be returned to shareholders, and wealth management did not need a bailout when markets froze.
The mechanics of the new model are worth spelling out, because they explain the valuation premium. Instead of charging clients a commission on each trade, advisers increasingly charged a fee measured as a small percentage of the assets in the account. A client with a $5 million portfolio paying a typical advisory fee generates income every quarter, rising and falling with markets but never collapsing to zero the way an IPO calendar can. The client's uninvested cash, meanwhile, flowed into Morgan Stanley's own banks, where it funded mortgages, securities-backed loans to the same clients and other low-risk lending. Morgan Stanley became, in effect, a bank whose depositors were wealthy investors who had come for advice.
The results came slowly, then clearly. Return on equity, which had sat in the mid-single digits in 2014, climbed to about 11% by 2019, and the market began paying a higher multiple for earnings it trusted more.4 That was still short of the returns the firm earned in the bubble years, and a skeptic in 2019 could fairly argue that Gorman had made a safe bank rather than a great one. The next move would test whether the strategy could scale.
VI. Doubling Down on Scale: E*TRADE, Eaton Vance, and the Workplace Funnel (2020–2023)
In February 2020, weeks before the pandemic shut down offices around the world, Gorman announced that Morgan Stanley would buy E*TRADE Financial in an all-stock deal worth about $13 billion. It was the largest acquisition by a big American bank since the financial crisis.3[^9] Eight months later, with markets still convulsing, he agreed to buy the Boston asset manager Eaton Vance for about $7 billion in cash and stock.[^10] The two deals closed in October 2020 and March 2021.[^9][^10]
ETRADE was the more radical purchase, because it brought Morgan Stanley clients it had never served. Its customers were self-directed investors who traded on their phones and did not want an adviser, at least not yet, plus millions of employees who received stock compensation through ETRADE's corporate stock-plan platform.[^9] Combined with Solium, a Canadian stock-plan administrator Morgan Stanley had bought in 2019 and rebranded Shareworks, the firm now sat at the moment when a young engineer at a tech company first receives shares. The theory was a funnel: capture that employee at the stock-plan stage, serve them digitally, and convert the ones who become wealthy into full-service advisory clients. E*TRADE also brought tens of billions of dollars of low-cost deposits from client cash, which fed straight into the bank.[^9]
Eaton Vance served a different purpose. Its Parametric unit was the leader in direct indexing, which builds a custom version of an index inside a client's own account so the investor can harvest tax losses stock by stock, and it ran large books of municipal bond and floating-rate loan strategies.[^10] For a wealth manager whose richest clients care intensely about taxes, owning the factory that makes tax-efficient portfolios was a way to keep more of the fee chain in-house. After the closing, the firm counted about $5.4 trillion of client assets across wealth and investment management.3[^10]
Did Morgan Stanley overpay? The honest answer is that it paid full prices at buoyant valuations, with stock that was itself richly valued, and booked substantial goodwill as a result. The deals added to the equity base, which rose to about $105 billion by 2021, so the return the acquisitions earn has to be judged against a larger denominator.4 The best available test is what happened to returns afterward. Return on equity reached about 14% in 2021, fell back to about 9% in 2023 as rates and markets turned, and then rose to about 15% in 2025 and about 18% over the twelve months to June 2026.46 That record does not prove the deals created value above the cost of capital, because the recovery owes a great deal to the trading rebound, but it does reject the bear argument of 2021 that the firm had diluted itself into mediocrity.
There is a cost hidden in the deposit logic, and it would surface within a few years. The cash that made E*TRADE attractive was cheap partly because clients were paid very little on it. When interest rates rose, that spread became extraordinarily profitable, and it also became a target. Gorman set a goal of reaching $10 trillion of client assets, a milestone that would convert Morgan Stanley from a distributor of financial products into one of the largest stewards of private wealth on earth.7 Before following that thread forward, it helps to look at the machine as it stands today.
VII. The Three Engines Today: Segment Economics and the Revenue Engine
Picture the finance team at 1585 Broadway closing the books on 2025. The firm reported about $70.6 billion of net revenue, the measure Morgan Stanley itself uses, which strips out interest expense from the gross revenue of about $115 billion that data providers show.4 Split by segment, the picture looks almost too symmetrical to be true. Institutional Securities, the trading and banking business, brought in about $33.1 billion. Wealth Management brought in about $31.8 billion. Investment Management added about $6.5 billion.4
The two big engines are similar in size and very different in character. The institutional business is the explosive one. In 2025 it earned a pre-tax margin of about 34%, and its equity trading revenue alone was about $11.9 billion, the product of market making for hedge funds and asset managers and of lending to them against their portfolios.4 Advisory and underwriting fees, around $5.4 billion, swing with the deal calendar.4 When markets are busy this segment prints money; when they are not, its revenue can fall by a third in a year.
The wealth business is the steady one. It earned a pre-tax margin of about 29% on its $31.8 billion, and most of its revenue came from asset management fees of about $18.6 billion, charged as a slice of client assets that stood at about $9.3 trillion at year-end.4 Another $7.9 billion came from net interest income, the spread between what the bank earns on loans and securities and what it pays on client cash.4 Investment Management, the smallest engine, earns fees on mutual funds, institutional mandates, private markets and Parametric's custom portfolios, at a pre-tax margin of around 21%.4
How much of this is truly recurring? Add the asset management fees across wealth and investment management and the total is about $25 billion, or a bit over a third of net revenue.4 Add net interest income and commissions, which are steadier than trading but not fixed, and the share rises to almost three-fifths.4 That is the honest version of the fortress claim. Morgan Stanley is not an annuity business; it is a business in which a third of revenue behaves like an annuity and another quarter behaves like a utility with interest-rate risk, sitting next to a trading floor that behaves like a trading floor.
The pricing units tell the same story. In wealth, the firm is paid in basis points on assets, so its revenue rises with markets and with the money clients bring in, and it falls only gradually when markets drop. In the institutional business it is paid in success fees and in the spread between bid and ask prices, which can vanish in a quarter.
Where the barbell has really paid off is in costs. The firm spends heavily on technology, around $4.4 billion a year on information processing and communications plus another $2.9 billion on premises, equipment and software, which together exceed $7 billion.4 Yet compensation, the biggest cost on Wall Street, fell from about 45% of net revenue in 2023 to about 41% in 2025.4 That decline is operating leverage: revenue grew much faster than headcount, which rose only about 4% to roughly 83,000 people.4 It also contains a warning. A compensation ratio that falls when revenue booms can rise just as quickly when revenue shrinks, because bankers' pay is sticky in a downturn. The accounting of a bank also hides its strength in unexpected places, which is where the numbers start to look very strange.
VIII. Forensic Anatomy: Capital, Cash Flow, and Receivables Reality
Imagine an analyst who has spent a career studying manufacturers opening Morgan Stanley's 2025 cash flow statement. Net income was about $17 billion. Operating cash flow was negative, about minus $17.9 billion.4 A stock screener on the same company flashes a negative free cash flow yield of about 5% and claims customers take 364 days to pay their bills.4 By the standards of an industrial company, this looks like a firm burning cash and failing to collect.
It is nothing of the sort, and understanding why is the key to reading any bank. For Morgan Stanley, the operating cash flow line is mostly a record of how much the firm expanded its trading book and its loans to clients. In 2025, trading assets grew faster than trading liabilities, absorbing about $68 billion of cash, and the firm lent more securities and more margin to clients, consuming tens of billions more; customer payables and repo financing offset part of it.4 When hedge funds borrow more, operating cash flow falls; when they deleverage, it rises. Data providers using different definitions even report the same year as a positive $49 billion.4 Neither number says anything about whether earnings are real.
The receivables puzzle dissolves the same way. Most of what screeners call receivables are margin loans: about $84 billion at the end of 2025, split between roughly $53 billion lent to institutional clients through prime brokerage and $31 billion lent to wealth clients.4 These loans are secured by marketable securities that are priced every day, and if collateral falls below its threshold the client must post more or be sold out. The receivables that do resemble unpaid bills, fees owed by corporate and asset management clients, were only about $3 billion.4 The 364-day figure is a measure of how much the firm lends, not of how slowly it collects.
The figures that actually describe strength are elsewhere. Morgan Stanley ended 2025 with about $112 billion of cash and about $164 billion of investment securities, mostly Treasuries and agency mortgage bonds, and its average liquidity resources in the fourth quarter were about $386 billion.4 Its common equity tier 1 ratio, the core measure of loss-absorbing capital against risk-weighted assets, was 15.0% on the standardized basis, well above its requirement.4 Its allowance for credit losses on about $269 billion of loans held for investment was only about $1.1 billion, a coverage ratio of about 0.4%, which reflects a loan book dominated by mortgages and securities-backed loans to wealthy clients.4 Low coverage is defensible for that kind of lending; it would be alarming for a credit card book.
Two caveats keep the picture honest. The loan book has grown quickly, and growth in collateralized lending tends to look safest just before collateral values fall. And Deloitte, the firm's auditor, issued a clean opinion but flagged one critical audit matter: the valuation of so-called Level 3 assets and liabilities, instruments priced by models rather than markets, at about $8 billion and $5 billion respectively.4 Relative to an equity base above $110 billion, those amounts are manageable, but they are exactly the category of asset that hid the Hubler trade's true risk. The fortress is real. Whether the people who run it will keep it that way is the question of the current era.
IX. The Ted Pick Era: Re-Igniting the Institutional Flame
On January 1, 2024, Edward "Ted" Pick became Morgan Stanley's chief executive, and a year later he added the chairman's title when Gorman retired from the board.48 The handover was notable for what did not happen. Gorman had named three internal candidates years earlier: Pick, the head of institutional securities; Andy Saperstein, who ran wealth management; and Dan Simkowitz, who ran investment management. When Pick got the job, both runners-up stayed, as co-presidents, rather than leaving with their teams for rivals.7 Anyone who remembered the Purcell years understood how unusual that was.
Pick is a career Morgan Stanley trader, a Princeton graduate who joined the firm in 1990, ran global equities through the 2008 crisis and later oversaw the shrunken fixed income business after Gorman's cuts.7 If Gorman was the outsider who made Morgan Stanley safe, Pick is the insider who is trying to make it fast again without making it fragile.
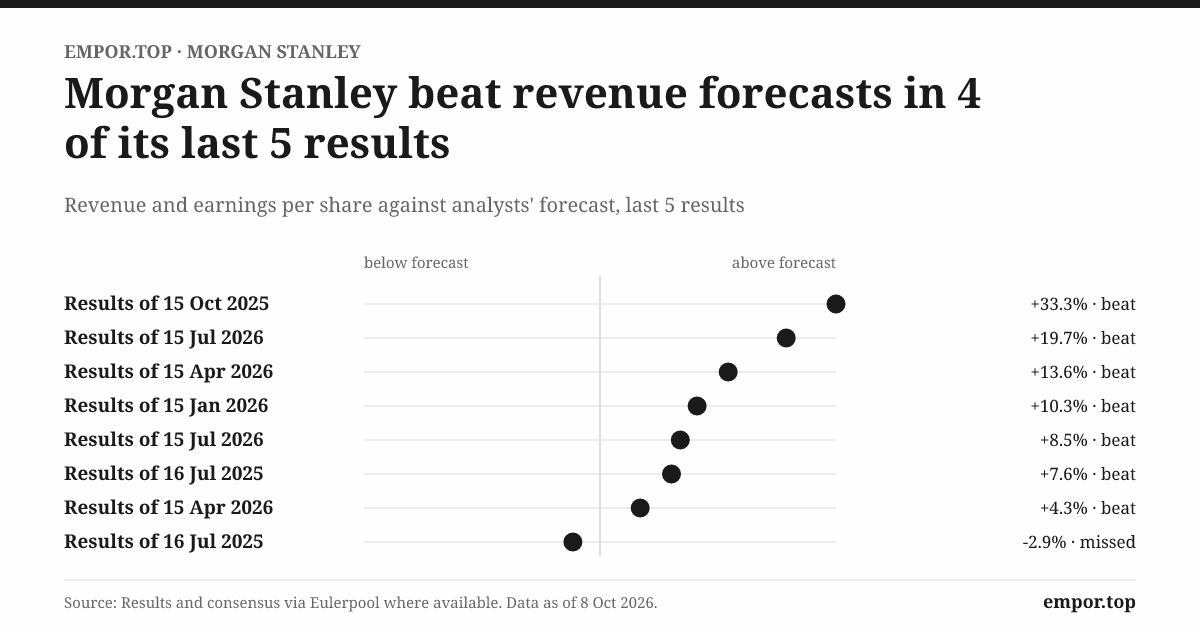
The numbers since he took over are striking. Diluted earnings per share rose from about $5.59 in 2023 to $12.70 over the twelve months to June 2026.46 In the second quarter of 2026, gross revenue rose about 22% from a year earlier and operating profit about 60%, to roughly $7.4 billion.6 On the second-quarter call, management attributed the strength to its institutional franchise, wealth inflows and a recovery in underwriting.[^12]
Under the headline is a very specific kind of growth. Margin lending in the institutional business nearly doubled in 2025, from about $28 billion to about $53 billion, as hedge funds concentrated their borrowing at Morgan Stanley's prime brokerage.4 That is market share in the business that served the firm worst in 2008, when the same hedge fund clients ran. Today the clients are better collateralized and the firm is far better capitalized, but the shape of the risk has returned.
Shareholders, for now, are content. Pick's pay for 2025 was set at $45 million, up from $32 million for 2024, and the say-on-pay vote at the May 2026 annual meeting passed with about 96% support.89 Fourteen of fifteen directors are independent, with Thomas Glocer as lead director, and a shareholder proposal to separate the chairman and chief executive roles won only about 27% of the votes.89 That minority is not trivial: more than a quarter of voting shareholders wanted a check on a combined chair and CEO, at a firm whose history includes a chief executive the board could not control.
So is the surge durable? The evidence narrows the bull claim rather than confirming it. Revenue growth in the latest quarter was well above the firm's ten-year average of about 12% a year, and operating margins rose from about 13% in 2023 to above 21%, a gain that owes much to a busy market.64 Some of the equity trading share looks sticky, because prime brokerage relationships are hard to move once a fund's collateral and financing are built around a counterparty. But the advisory and underwriting rebound is cyclical by nature. The test is whether institutional quarterly revenue can hold above roughly $6.5 billion through the next real downturn; until that happens, the market share is promising rather than proven. And part of what makes the firm's position unusual sits not in New York but in Tokyo.
X. The Japanese Alliance: MUFG's Billion-Dollar Moat
The check of October 2008 turned into a marriage. MUFG converted its preferred stock into common shares in 2011 and has owned roughly a fifth to a quarter of Morgan Stanley ever since. As of early 2026 it held about 380 million shares, or 24.0% of the company, by far the largest holding, and it designated two directors to Morgan Stanley's board.48
In 2010 the two firms combined their Japanese securities operations into two ventures. Mitsubishi UFJ Morgan Stanley Securities, which serves Japanese retail and corporate clients, is 40% owned by Morgan Stanley and accounted for as an investment, contributing its share of profit to other revenues. Morgan Stanley MUFG Securities, which handles institutional business, is controlled by Morgan Stanley with 51% of the votes and consolidated in its accounts.4 The arrangement pairs Morgan Stanley's advisory and markets franchise with Japan's largest bank's corporate relationships and lending capacity, and it has become an important channel into Japanese corporate restructuring and cross-border deals.
Why has MUFG never simply bought the rest? Owning a controlling stake in a systemically important American bank would subject MUFG to a regulatory regime it has no reason to accept, and the two sides operate under a standstill arrangement limiting its voting influence.8 The result is a shareholder that behaves like permanent capital. Business between the two is conducted on the same commercial terms as with unrelated counterparties, according to the company.48
The alliance cuts both ways. A quarter of the equity in friendly hands makes a hostile bid or a break-up campaign almost unthinkable, which protects a long-term strategy and also shields management from the discipline that activists sometimes supply. For investors, MUFG's stake is less a moat than an anchor: it steadies the ship, and it also means minority holders cannot easily force a change of course. That matters more now, because the forces bearing down on the firm come from courtrooms and regulators rather than raiders.
XI. The Battle for the Balance Sheet: Cash Sweeps, Litigation, and Basel III
In 2024, a wave of lawsuits hit the brokerage industry with a deceptively simple complaint. When a brokerage client sells a stock and leaves the proceeds uninvested, the money is usually swept automatically into a bank deposit. At several big firms, including Morgan Stanley's ETRADE, plaintiffs alleged that clients were paid very little on that cash while the affiliated bank earned market rates on it, and that this breached the firm's duties to its clients.5 The consolidated cases, styled In re ETRADE Cash Sweep Litigation, are pending in federal court in Washington state.54
To understand why this matters, recall how the wealth bank works. When the Federal Reserve lifted rates above 5%, a firm paying a fraction of a percent on client cash and earning several percent on it was collecting one of the widest spreads in finance. Clients noticed; many moved cash into money market funds on their own. Regulators noticed too, and the SEC and state authorities asked questions about advisory sweep balances.4 In the third quarter of 2024, Morgan Stanley raised the rates it pays on certain advisory sweep tiers, a change that cost it an estimated $350 million a year of net interest income.4
That number is modest against $7.9 billion of wealth net interest income, and it is the honest starting point. The risk is not the first concession; it is the precedent. If courts or regulators conclude that advisory clients are owed something close to money-market rates on all their swept cash, the spread that helped lift wealth margins could shrink much further, and the deposit base that funds the firm's lending would become more expensive. The company says it does not expect pending proceedings in aggregate to have a material adverse effect on its financial condition; that is a statement about solvency, not about margins.4
The firm has already shown it is not immune to conduct risk. In January 2024 it paid about $249 million to settle DOJ and SEC investigations into how its block-trading desk had handled confidential information about large share sales, and it entered a three-year non-prosecution agreement.10 The episode was small in dollars and large in what it revealed: the equities franchise that Pick built is also the place where the firm most recently fell short of its own information barriers.
The second pressure is capital. To satisfy the Federal Reserve's total loss-absorbing capacity rules, which require large banks to hold long-term debt that can be converted to equity in a failure, Morgan Stanley's borrowings rose to about $349 billion at the end of 2025 and about $393 billion by June 2026.46 Meanwhile the long-delayed American version of the Basel III endgame rules could raise the risk weights on trading books and client lending. If that happens, the firm would have to hold more equity against the same business, which would slow buybacks and pull return on equity back toward the mid-teens. In 2025 it repurchased about $4.6 billion of stock.4 The fight over the balance sheet, in other words, is a fight over how much of the fortress belongs to shareholders. That raises the deeper question of whether the fortress is a moat at all.
XII. Strategic Moat Analysis: Porter's Five Forces and Hamilton Helmer's 7 Powers
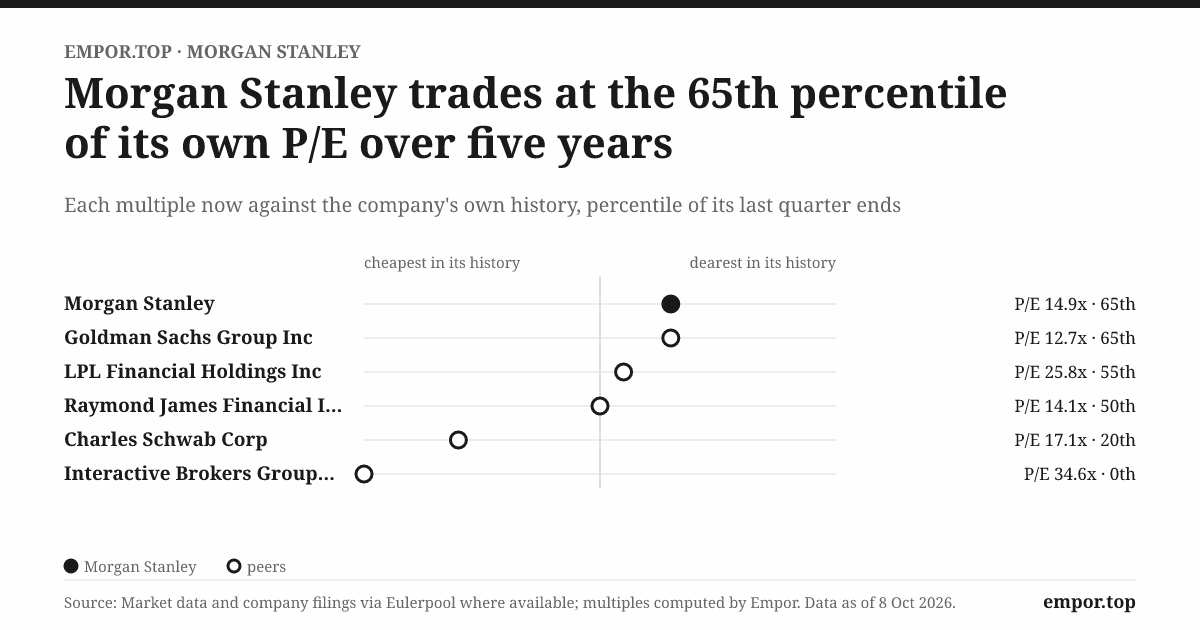
Set the two great rivals side by side. Morgan Stanley trades at about 2.7 times book value; Goldman Sachs at about 2.1 times.4 Their price-to-earnings ratios are similar, so the gap mostly reflects the market's belief that Morgan Stanley earns higher returns on its equity, more reliably. The question is whether that belief rests on competitive advantages that rivals cannot copy, or on a good run.
Start with the industry. New full-service entrants are almost impossible: the capital rules, the licenses and the trust required keep the threat of entry very low. Suppliers, in this business, are people, and star bankers, traders and advisers capture a large share of revenue; the fall in the compensation ratio to about 41% suggests the firm has gained some leverage over them, though that gain is partly cyclical.4 Buyers split in two. Hedge funds and institutions are powerful, price-sensitive and willing to move business, while wealthy families rarely switch advisers once their trusts, tax lots and loans are set up. Substitutes are real at the low end, where index funds and trading apps have crushed commissions, and weaker at the top, where estate planning, structured lending and access to private deals are hard to replicate. Rivalry with Goldman Sachs, JPMorgan and Bank of America's Merrill Lynch is intense in every business.
Through Hamilton Helmer's lens, the strongest power is switching costs in wealth management. Moving a $20 million household means re-papering accounts, unwinding securities-backed loans, possibly realizing taxable gains and, above all, leaving a trusted adviser. Those frictions are why asset fees grew to a record even as competitors fought for clients.4 The sweep litigation, though, is a reminder that switching costs protect assets more than they protect pricing: clients who would never leave the firm still moved their idle cash to higher yields.
Scale economies come second. A technology budget above $7 billion spread across about $9.3 trillion of client assets is a cost per dollar that smaller wealth managers cannot match, and the same is true of the prime brokerage and risk systems.4 Network effects are present but narrow, mostly in equities market making, where order flow and liquidity reinforce each other. The MUFG alliance is the nearest thing to a cornered resource, though it is more a distribution advantage in Japan than a barrier everywhere. Counter-positioning was Gorman's original edge: for years Goldman defended a trading-centric model that made it awkward to copy the wealth pivot, and Goldman's later push into consumer banking, which it largely abandoned, shows how hard the catch-up proved.
The weighed conclusion is that Morgan Stanley does have durable power in wealth management, built on switching costs and scale, and that much of the institutional business is a very well-run cyclical franchise without a comparable moat. The valuation premium is justified to the extent the first engine dominates the earnings mix, and vulnerable whenever the second engine's boom makes the whole look more stable than it is. The firm's long history offers some sharp lessons about the difference.
XIII. Playbook: Business and Investing Lessons
The first lesson begins on the bond trading floor in 2015, when Gorman shrank the business everyone on Wall Street still thought of as the main event. Trading profits are rented; client assets are owned. Morgan Stanley's earnings multiple rose from the low teens of its trading-house years to the mid-teens of today because a third of its revenue now arrives whether or not anyone trades, and the firm's dividends grew from under $1 billion in 2014 to about $6.6 billion in 2025 on that base.4[^15] Founders building anything cyclical should ask which of their revenues they would still collect in the worst quarter of the decade, and pay up for more of that kind.
The second lesson is the Columbus Day check. In a run, survival is a balance-sheet decision, not a model output. Lehman Brothers spent its final months negotiating for a better price; Morgan Stanley accepted a dilutive deal from MUFG on the terms available, and lived.2 The share of the firm MUFG still owns is the permanent cost of that choice, and it has been worth every basis point.
The third lesson is the contrast between Purcell's merger and Gorman's. Both men bought retail franchises to steady a volatile bank. One treated integration as an exercise in command and lost the firm's culture; the other spent years merging Smith Barney's systems and people before buying the next thing. A merger's thesis is a promise; its integration is the proof.
The fourth lesson is about capital. In 2025 the firm returned about $11 billion to shareholders through dividends and buybacks while keeping its standardized CET1 ratio at 15%.4 That record was made in a good year, and the real test of capital discipline comes when regulators ask for more and earnings fall at the same time. The best capital return policy is the one that never has to be reversed.
The fifth lesson is the quiet handover of 2024, in which the two losing candidates for chief executive stayed on. At a firm whose last succession fight ended with retired partners buying newspaper ads, that was a strategic asset in its own right. Succession is the one strategy a company cannot outsource.
XIV. Analysis and Bear vs. Bull Case
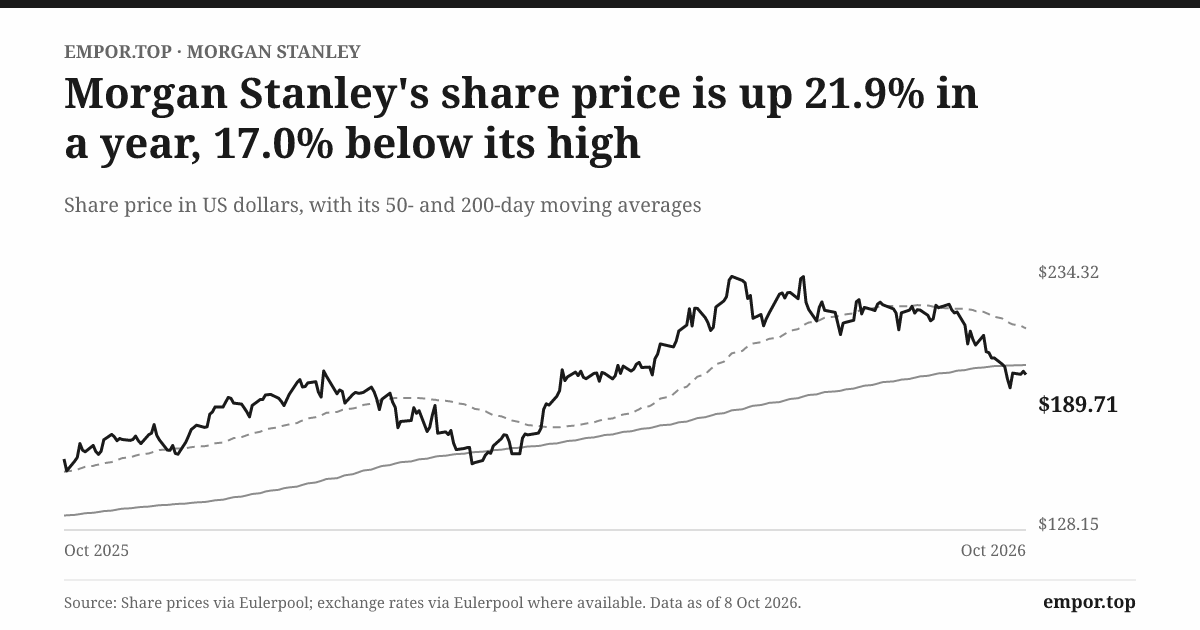
At about $190 a share in early October 2026, Morgan Stanley is valued at about $302 billion, or roughly 15 times trailing earnings and 2.7 times book value, against a five-year median earnings multiple of about 14.4 The shares are about 17% below their 52-week high, and the dividend yields a bit over 2%.4 Over the past decade, the multiple has re-rated from the 10-to-12 range of the trading-house years toward today's mid-teens as wealth fees grew into a larger share of earnings.4 Goldman Sachs trades on a similar earnings multiple but a lower book multiple, and JPMorgan's universal bank earns comparable returns at a slightly lower earnings multiple.4 The market, in short, already treats Morgan Stanley as a higher-quality bank. The question is what that price assumes.
The bull case starts with the asset base. If client assets compound past $10 trillion, the fee line grows with them, independent of the deal calendar, and every new client funnelled in from E*TRADE or a corporate stock plan adds to a revenue stream that lasts decades.4 Bulls add that the prime brokerage share gains are sticky, because funds rarely move their financing once it is embedded. They point to surplus capital: with a 15% CET1 ratio and about $14 billion of buyback authorization remaining at mid-2026, the firm has shrunk its diluted share count by about 4.5% in two and a half years and can keep doing so.64 And they argue that a price-to-earnings-to-growth ratio below one implies the market still prices Morgan Stanley's earnings as if they were as cyclical as they used to be.
The bear case attacks each of those pillars with evidence from the firm's own record. Earnings growth in 2024 to 2026 came disproportionately from the institutional business at a cyclical high, and the last time capital markets turned, in 2022 and 2023, net profit fell about 40% from its 2021 peak.4 A low PEG ratio built on peak-cycle growth is not evidence of cheapness. The sweep litigation could force further repricing of client cash, eroding hundreds of millions more of high-margin interest income.5 Basel III endgame rules could raise capital requirements and cap returns in the low-to-mid teens. And a 2.7 times book multiple leaves little margin for a wealth-management stumble, because the premium over Goldman rests almost entirely on that business.
Weighed together, the evidence narrows rather than rejects the premium. The wealth franchise is a genuine competitive advantage, and the firm's capital position is strong enough to withstand a downturn without cutting the dividend, but today's earnings are not today's normal. The firm's 2022 and 2023 record shows how much of the institutional surge can disappear in two years.
Three readings will decide which story wins. The first is the wealth management pre-tax margin, about 29% in 2025; holding it above 28% as sweep rates normalize would confirm that the moat protects pricing as well as assets.4 The second is quarterly institutional revenue, now well above $6.5 billion; staying above that level in the next weak quarter for capital markets would turn Pick's share gains from a cycle into a franchise.6 The third is the standardized CET1 ratio, 15.0% at year-end 2025, set against whatever stress capital buffer and Basel rules the Fed finally imposes.4
XV. Epilogue
Tonight, the ticker wrapped around 1585 Broadway shows a firm worth about $300 billion with around 83,000 employees, a long way from a converted office at 2 Wall Street in 1935 and further still from the frantic phone calls of September 2008.4 On trailing earnings of $12.70 a share, it is one of the most profitable institutions in global finance.6
Three moments ahead will test how much of that is permanent. The first is in a federal courtroom in Seattle, where the cash sweep cases will decide whether brokerage firms can keep earning wide spreads on client cash. A narrow outcome would leave Morgan Stanley's wealth margins largely intact; a broad one would reset the economics of every wealth bank in America.5 The second is in Washington, where the Federal Reserve's final version of the Basel III endgame and each year's stress capital buffer will determine how much of the firm's earnings can leave the building as buybacks. The third is a number on an earnings slide: the day client assets cross $10 trillion, the target Gorman set and Pick inherited, would mark the point at which Morgan Stanley's identity as a wealth manager is no longer a strategy but a fact.7
The tension that remains is cultural. Gorman made the firm safe by making it a little boring. Pick, the trader, has made it exciting again, and the market is rewarding him for it. The challenge for the next downturn is whether an institution engineered for stability can keep its appetite without forgetting what happened the last time it let a trading desk set the pace.
XVI. Outro
Go back to that office at Wachtell Lipton on Columbus Day 2008, to Robert Kindler holding a piece of paper worth $9 billion. The check was a symbol of how far the firm had fallen: the aristocrats of Wall Street, rescued by a Japanese commercial bank on a holiday when American banks were closed. It was also the first payment on a very different future, one in which the deposits and retail clients that Morgan Stanley had once looked down on became the foundation of its value.
The pure investment banks that mocked deposit-taking either disappeared or spent the next decade trying to imitate the firm that embraced it. Morgan Stanley began as Wall Street's most aristocratic relationship bank, nearly died trying to be its most aggressive trading house, and triumphed by becoming its most disciplined wealth manager.
References
-
How Morgan Stanley Survived 2008 and Rebuilt for the 21st Century — Wall Street Journal, 2018-09-12 ↩↩↩↩↩↩↩↩↩↩
-
Mitsubishi UFJ Financial Group to Invest $9 Billion in Morgan Stanley — U.S. SEC Form 8-K, 2008-10-14 ↩↩↩↩↩
-
Morgan Stanley 2025 Form 10-K Annual Report — SEC EDGAR, 2026-02-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
In re E*TRADE Cash Sweep Litigation Complaint — U.S. District Court for the Western District of Washington, 2024-05-03 ↩↩↩↩↩
-
Morgan Stanley Q2 2026 Form 10-Q Quarterly Report — SEC EDGAR, 2026-08-04 ↩↩↩↩↩↩↩↩↩
-
James Gorman's Strategic Legacy and Wall Street Transformation — Financial Times, 2023-12-20 ↩↩↩↩↩↩↩↩↩
-
Morgan Stanley DEF 14A Notice of 2026 Annual Meeting of Shareholders — SEC EDGAR, 2026-04-02 ↩↩↩↩↩↩
-
Morgan Stanley Form 8-K Results of 2026 Annual Meeting of Shareholders — SEC EDGAR, 2026-05-15 ↩↩
-
Morgan Stanley to Pay $249 Million for Fraudulent Block Trading — U.S. Securities and Exchange Commission, 2024-01-12 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube