Meta Platforms: The Machine That Prints $200 Billion, and the $140 Billion Question About What It Buys Next
I. Cold Open & Episode Roadmap
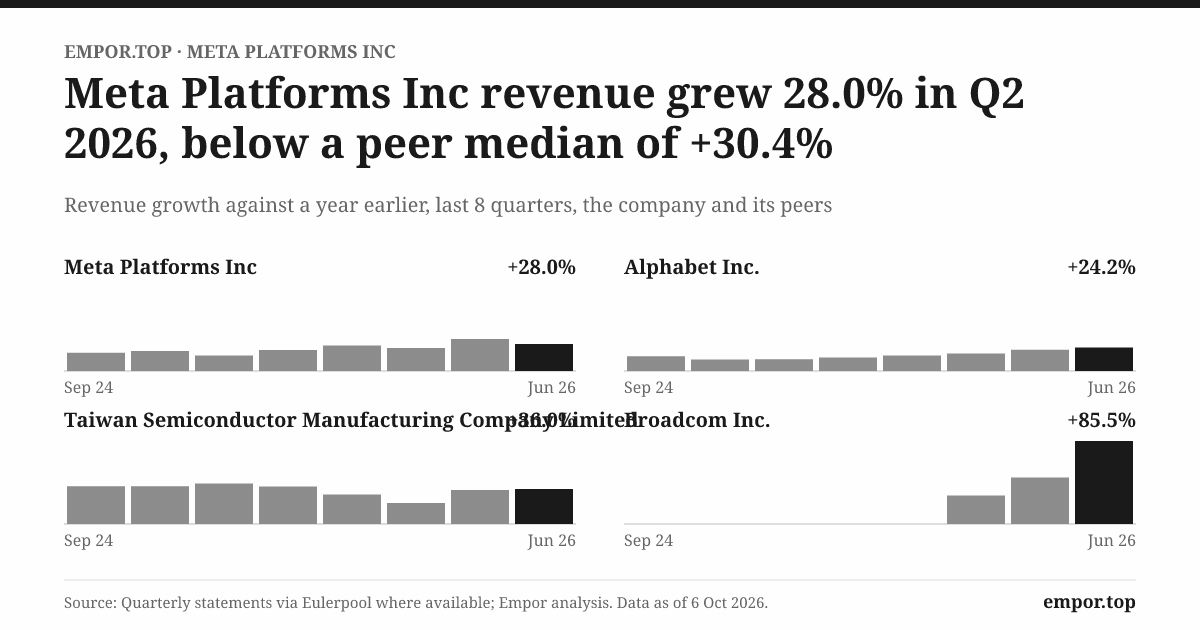
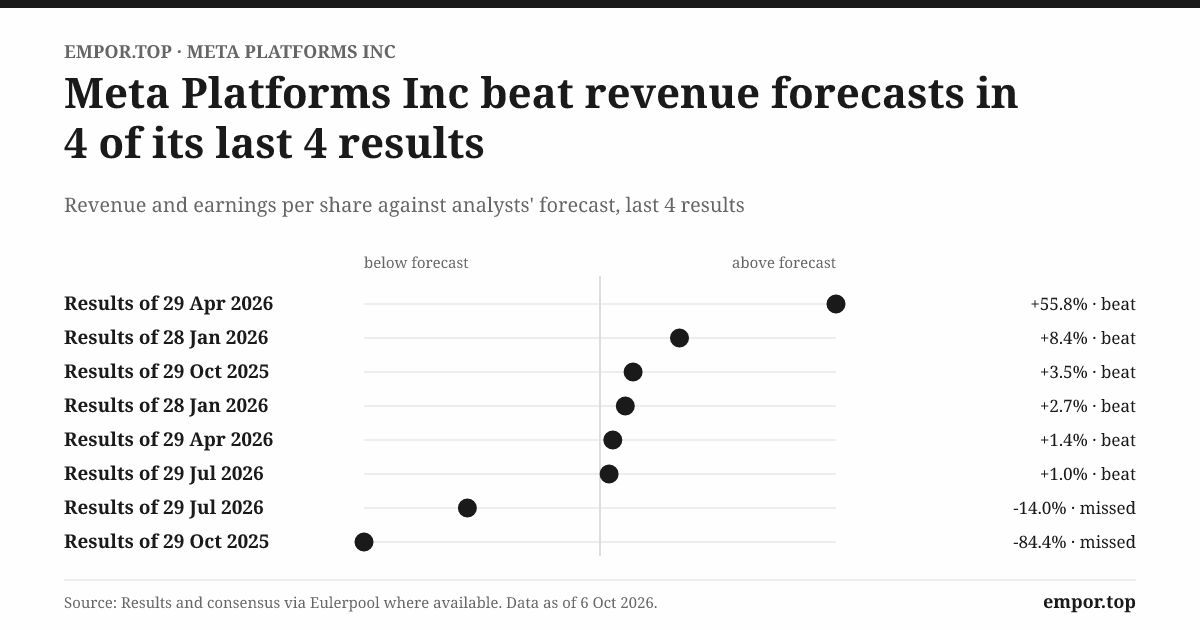
It is the last week of July 2026, and Meta Platforms has just published the kind of quarter that, at almost any other company, would end the conversation. Revenue for the three months to June rose 28% to about $60.8 billion1. That is not a start-up growing off a small base. It is a company that already sells more advertising than almost anyone on earth, accelerating.
Then the reader reaches the next lines. Operating margin fell to about 31%, from 43% a year earlier1. And free cash flow, the cash left after paying for the servers, buildings and chips, came to $784 million for the whole quarter1. A year before, the same line had read about $8.5 billion1. Revenue was up by more than $13 billion; the cash left over for owners fell by nearly $8 billion.
That is the tension at the heart of this story. The advertising engine Mark Zuckerberg built has never been stronger. It has also never been more expensive to run, because Meta is pouring its profits into artificial-intelligence infrastructure at a pace without precedent in its history. Management guided 2026 capital spending to between $130 billion and $145 billion1. For scale, Meta's entire revenue in 2025 was about $201 billion2, and its trailing twelve-month revenue is about $228 billion1.
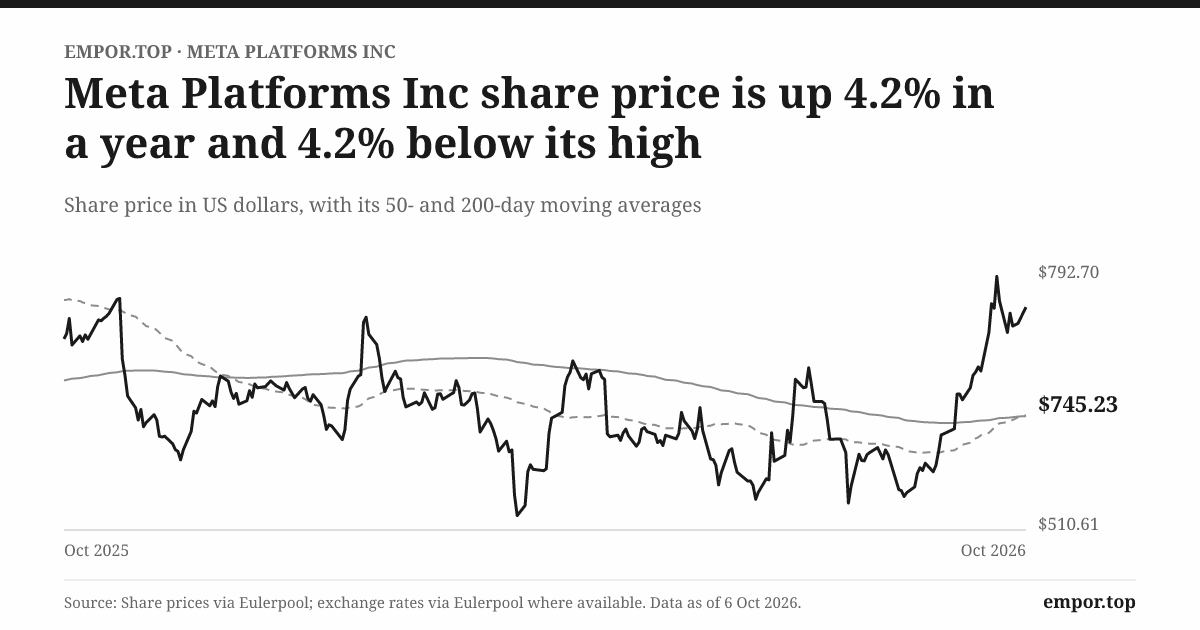
On 6 October 2026, the market values Meta at about $1.9 trillion, with the shares at about $745, roughly 4% below their 52-week high5. In other words, investors are not panicking about that $784 million quarter. They are paying a premium for the bet.
This story asks four questions, and returns to them at the end.
First, does the AI capital spending earn its return, or does it compress margins for years? Second, is the profit trend as strong as the headlines suggest, or are the reported numbers flattering or hiding something? Third, how leveraged is Meta becoming, including through structures that do not sit on its balance sheet? And fourth, can regulators or courts change the advertising model that pays for everything else?
A warning before the story begins: Meta's reported profits over the past year are unusually noisy. A US tax law passed in July 2025 forced a charge of roughly $15.9 billion, which crushed one quarter's net profit to about $2.7 billion23. In the first quarter of 2026 the tax line swung the other way, to a benefit, which lifted net profit to about $26.8 billion4. And the June quarter carried about $2.4 billion of legal charges1. Anyone reading the net-profit line alone would think the business had lurched up and down. It did not. The operating engine moved steadily; the accounting around it did not.
To understand why the engine is so strong, and why its owner is willing to spend so much of its output, the story has to go back to a dorm room.
 Subscribe on LinkedIn
II. Dorm Room to Network Effect: The Short Origin
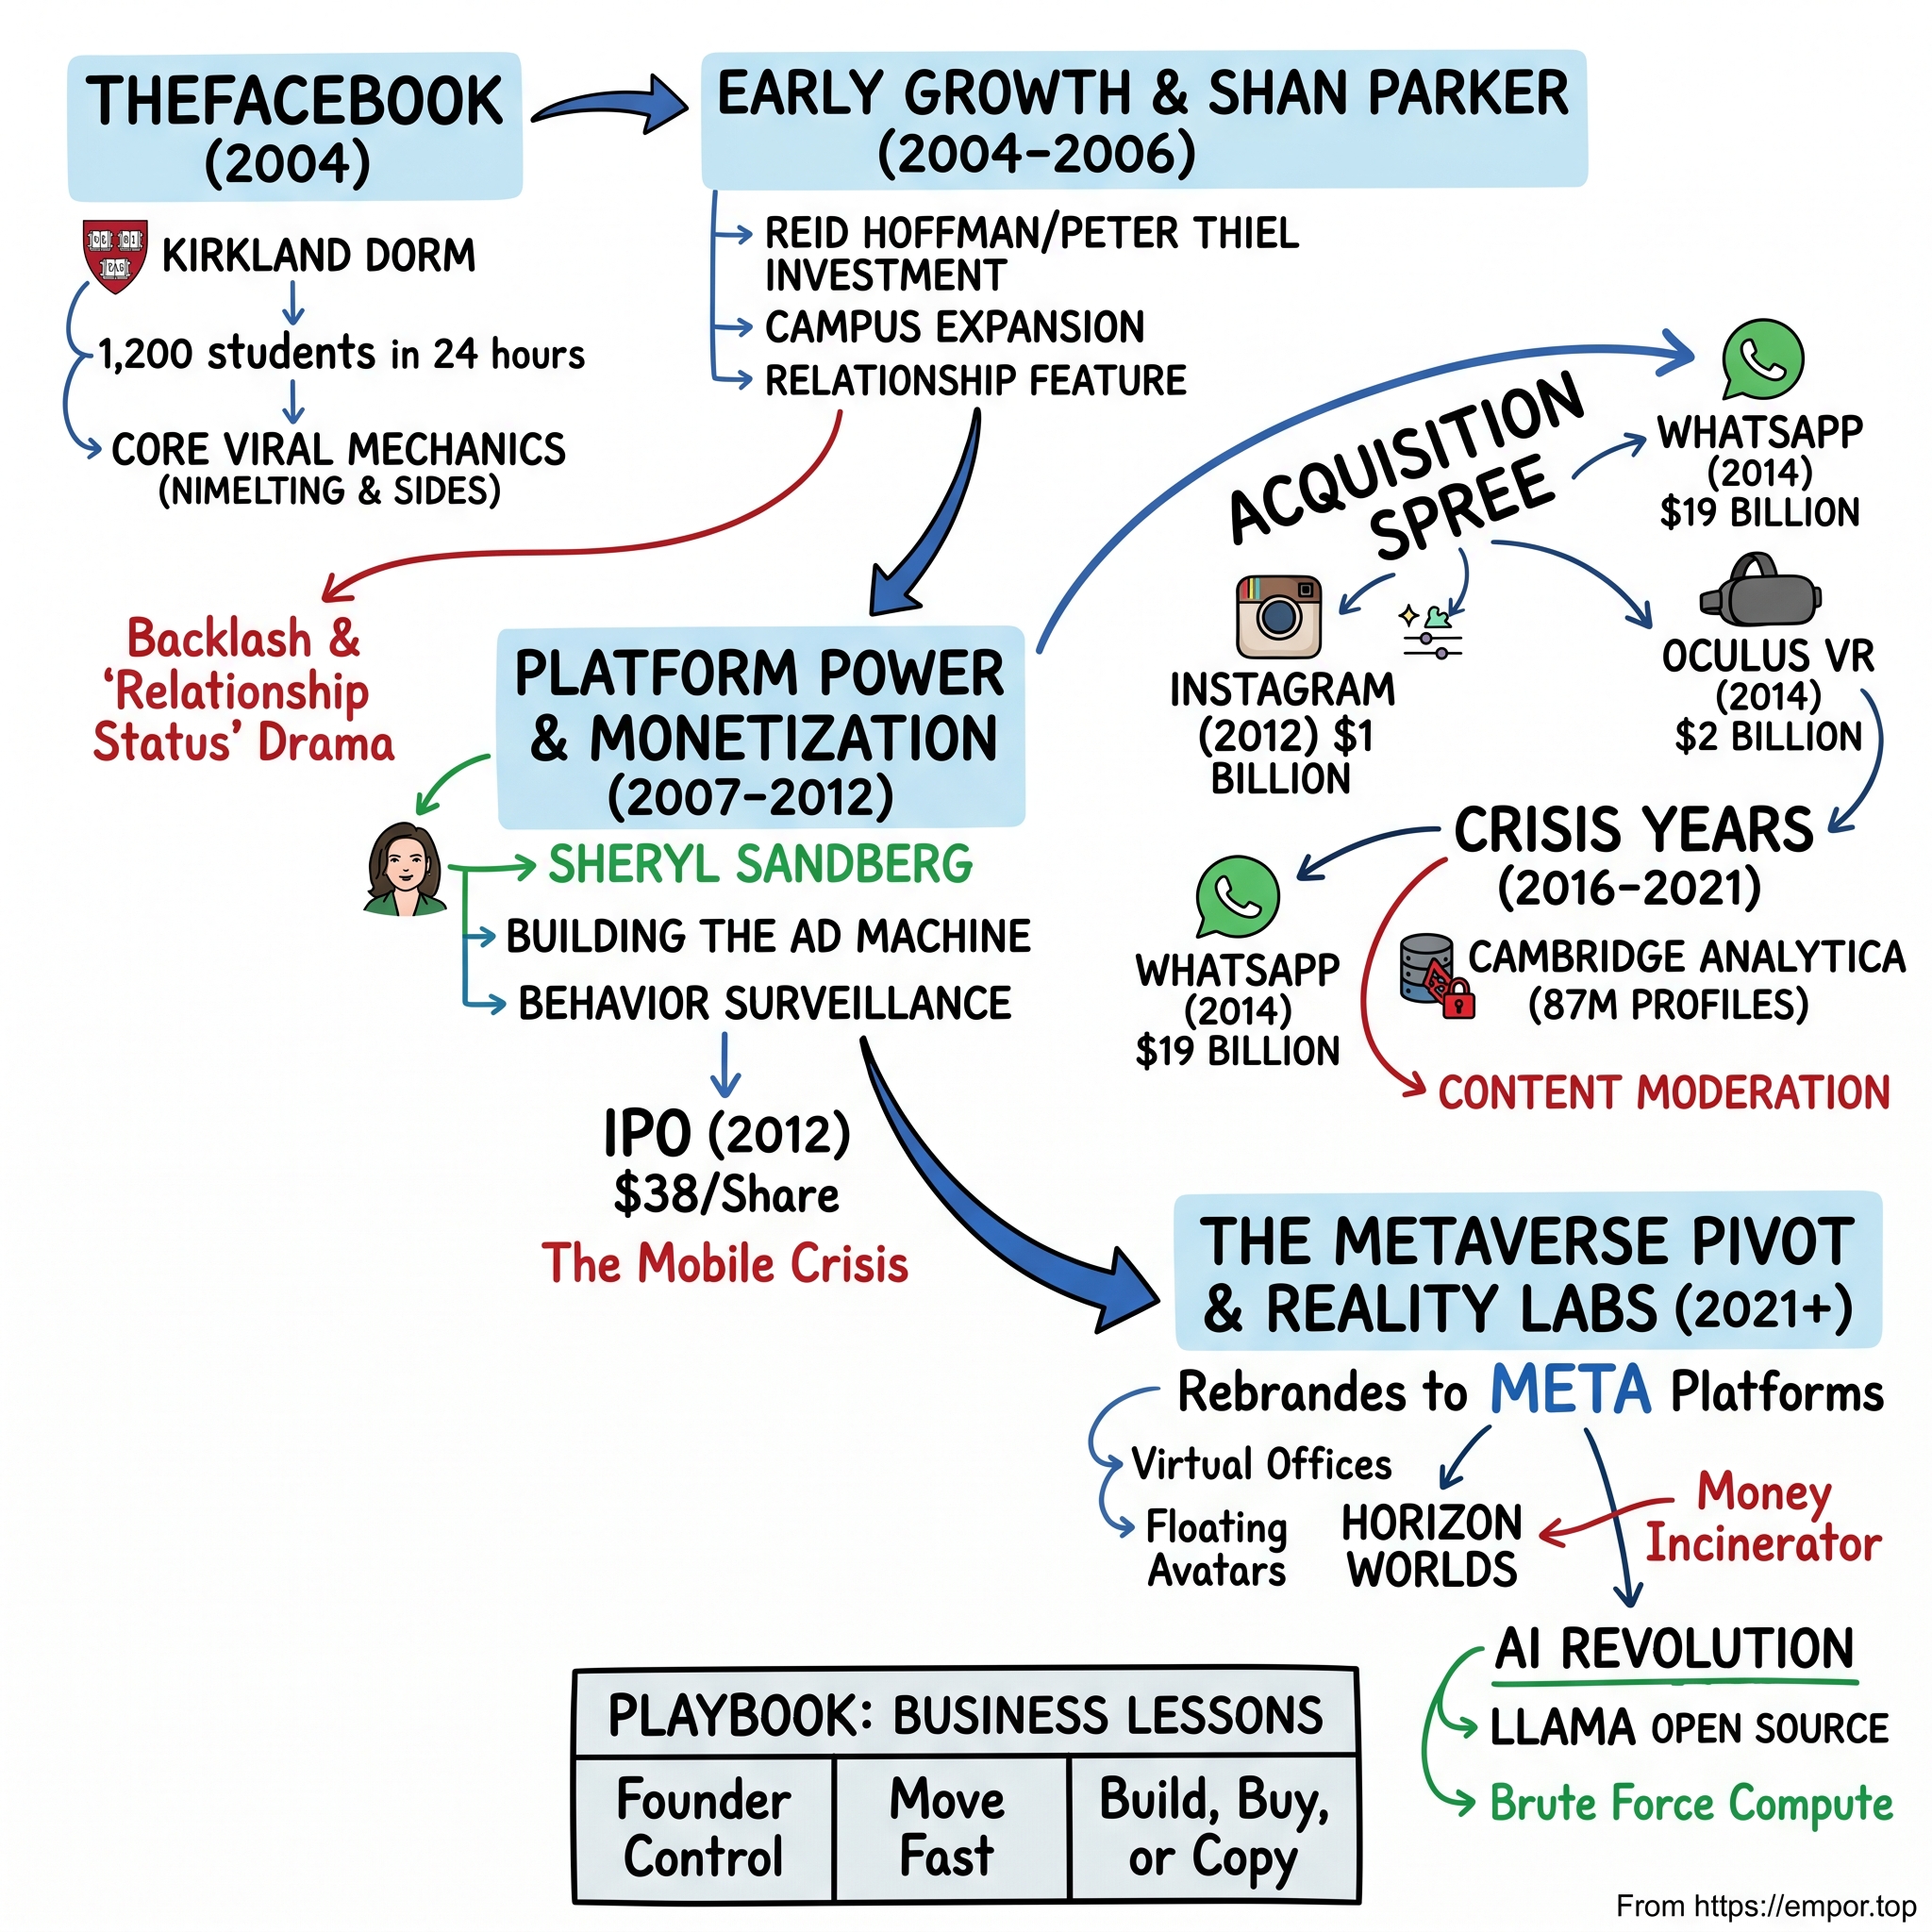
In February 2004, a Harvard sophomore launched a website called TheFacebook from his dormitory. It was not the first social network. Friendster and MySpace were already there. What made it different was a constraint that looked like a weakness: at first, only people with a Harvard email address could join6.
That constraint was the whole trick. A social network is worth what your friends on it are worth to you. By opening one campus at a time, Facebook made sure that each new school arrived with a dense web of real people who already knew each other. A student at Stanford or Yale did not join an empty room; they joined their classmates. The rollout became a template for what economists call network effects: every additional user makes the product more valuable to every existing one.
The founding cast was small and, later, quarrelsome. Mark Zuckerberg wrote the code and kept control. Eduardo Saverin put up early money and handled business matters, before a dispute in 2005 saw his stake diluted and his role ended; the case was later settled. Dustin Moskovitz, Chris Hughes and Andrew McCollum rounded out the early team. Meanwhile the Winklevoss twins and a classmate claimed Zuckerberg had taken their idea, a dispute also later settled. These episodes are colourful, but their lasting significance is narrower: they show a founder who, from the start, protected his own control above almost everything else.
Silicon Valley noticed quickly. Peter Thiel wrote the first outside cheque, an investment of about half a million dollars in 2004. Sean Parker, the Napster co-founder, became president and helped Zuckerberg structure the company so that control stayed with the founder. That design choice echoes through every decision since.
In September 2006, Facebook introduced News Feed, a running stream of what friends were doing. Users revolted; groups protesting the feature attracted large memberships. Yet those protest groups spread through News Feed itself, which was the best possible proof that the feature worked. Engagement rose. It was an early lesson the company would keep relearning: users complain loudly about changes they end up using constantly.
By 2008 Facebook had overtaken MySpace as the world's largest social network. In October 2007, Microsoft paid $240 million for 1.6% of the company6, a deal that implied a valuation of about $15 billion for a business with modest revenue. At the time, critics called it absurd. In hindsight it was a cheap ticket.
Today the company counts about 3.6 billion people who use at least one of its apps every day1. Revenue grew from about $12.5 billion in 2014 to about $201 billion in 20252. The point of this short origin is that the moat was never an ad system. It began as a map of who knows whom, a social graph, and the advertising business was built on top of it later.
The final piece of the origin, and the most important one for investors today, is founder control. Meta's Class B shares carry ten votes each, and Zuckerberg's holdings of them give him a majority of the voting power27. No board vote, shareholder resolution or activist campaign can overrule him. That fact explains why Meta can make enormous long-term bets. It also explains why those bets can't be stopped when they go wrong.
That combination was tested for the first time in public in 2012, when a company that had conquered the desktop discovered its users had moved to their phones.
III. The Mobile Crisis That Built the Ad Machine
On 18 May 2012, Facebook listed on Nasdaq. It was supposed to be a coronation. Instead, it became a cautionary tale. Trading opened late because of technical problems at the exchange, and the shares struggled to stay above the $38 offer price. Within months they had fallen by about half.
The IPO had valued the company at roughly $104 billion and raised about $16 billion, making it one of the largest technology listings in history6. Zuckerberg kept voting control through the dual-class structure6. But the prospectus also carried a sentence that frightened investors: usage was shifting to mobile devices faster than Facebook could earn money from them, and the company did not show ads on phones in any meaningful way6.
That was the existential question of 2012: was Facebook a desktop company stranded in a mobile world?
The pivot
The answer came fast, and it is still the single best piece of evidence that this management can reverse course under pressure. Zuckerberg reorganised engineering around mobile. The company placed ads directly inside the mobile News Feed, the one place users actually looked. It built ads that encouraged people to install apps, which turned every mobile game and start-up into a customer. And it gave advertisers tools to upload their own customer lists and find matching users (Custom Audiences), or find people who resembled their best customers (Lookalike Audiences).
Sheryl Sandberg, hired from Google in 2008 as chief operating officer, built the sales and operating machine around these products. Her background in Google's advertising business mattered: she understood that the product being sold was not banner space but measurable results.
The numbers that followed were extraordinary. Revenue grew 58% in 2014, then 44%, 54% and 47% in the following three years2. Operating margin reached 45% by 20162. A company that investors feared could not make money on phones became one of the most profitable businesses ever built on them.
How the machine actually sells
To understand Meta today, a listener needs to grasp its unit of sale. Meta does not sign advertising contracts. An advertiser sets a budget and a goal, perhaps a click, an app install or a purchase, and Meta's system runs an auction every time an ad could be shown. Advertisers bid per impression or per action, with no minimum commitment, and can cut spending at any moment2.
This has two consequences. The good one is that Meta can serve millions of small advertisers who would never sign an agency contract, and the auction sets prices automatically, so better targeting translates directly into higher prices. The uncomfortable one is that none of Meta's revenue is contracted. It is all earned again every day.
The June 2026 quarter shows how the machine grows now. Ad impressions rose 14% and average price per ad rose 12%, while daily active people rose only about 3%1. Growth is coming from showing more ads to roughly the same people and charging more for each. That is better monetisation of a user base that is close to saturated, not new users.
The base rate for bad years
The lack of contracts cuts both ways, and 2022 is the record of what happens in a downturn. Revenue fell about 1% that year, the first annual decline in the company's history, while operating profit fell 38% and operating margin dropped to about 25%2. Costs kept rising while revenue stalled. For investors, that is the base rate: a modest revenue stumble can produce a severe profit fall, because the cost base is built for growth.
The mobile pivot proves that the engine can be rebuilt under fire. The 2022 record proves that it can also be hit hard. Both lessons matter today, because the engine is again being rebuilt, this time around AI, and the costs are again running ahead.
Before that, though, there is the question of how Meta came to own most of the places where the auction now runs.
IV. Buy, Copy or Bury: Instagram, WhatsApp, Oculus and the Capital-Allocation Record
In April 2012, a few weeks before the IPO, Zuckerberg agreed to buy Instagram for about $1 billion in cash and stock6. Instagram had 13 employees and no revenue. Many observers thought the price was a symptom of a bubble. The deal was negotiated largely by Zuckerberg himself, reportedly over a weekend, with his board informed rather than consulted. It was the founder-control model in action.
Two years later, in February 2014, Facebook agreed to buy WhatsApp for about $19 billion in cash and stock8. WhatsApp had roughly 450 million monthly users at the time and tiny revenue. A month after that came Oculus, the virtual-reality headset maker, for about $2 billion8.
Benchmarking the prices
How good were these deals? Judge by the price per user and what each property became.
Instagram cost about $1 billion for a network of around 30 million users, or roughly $33 a user. WhatsApp cost about $19 billion for around 450 million users, or roughly $42 a user. For comparison, Google paid $1.65 billion for YouTube in 2006, and Snapchat's founders turned down a reported $3 billion offer from Facebook in 2013.
Today Instagram has well over two billion users and is a central part of Meta's advertising business; Meta does not break out Instagram revenue in its filings2. WhatsApp has grown to billions of users and is now beginning to earn money through business messaging and ads in its Updates tab. On price paid against current scale, Instagram and WhatsApp rank among the best acquisitions in corporate history. Few verdicts in this story can be stated with that much confidence.
The record is not clean
But capital allocation is judged by the whole record, not the best two trades.
Oculus has absorbed far more capital than it has ever returned. It became the core of Reality Labs, which, as the next section shows, now loses more than $4 billion a quarter1. Snapchat refused to sell, so Facebook copied it: Instagram Stories, launched in 2016, reproduced Snapchat's signature format and quickly overtook it. When TikTok rose, Meta answered with Reels. The copying worked, but it also shows the strategy plainly: buy the competitor if possible, copy it if not.
That pattern became a legal problem. In December 2020, the Federal Trade Commission sued, arguing that Instagram and WhatsApp were "killer acquisitions" designed to eliminate competitors, and asked the court to unwind them. In November 2025, the district court ruled for Meta, finding that the FTC had not proven Meta currently holds monopoly power in a market that, the judge noted, now includes TikTok and YouTube9. The break-up threat that hung over the company for five years has receded, although the outcome rested on today's market rather than on a finding that the deals were benign when made.
From buying companies to buying compute
The more important shift is what Meta now spends its money on. Net property, plant and equipment, mostly data centres and servers, rose from about $45 billion at the end of 2019 to about $197 billion at the end of 20252. That is now the largest use of Meta's cash by far. The era of $1 billion and $19 billion acquisitions has given way to an era of $100 billion-plus annual capital programmes.
Shareholder returns tell the same story. Meta started paying a dividend only in 2024: about $5.1 billion that year and about $5.3 billion in 2025, or roughly 8% to 9% of net profit2. Across 2014 to 2025, dividends absorbed only about 3% of the roughly $305 billion of free cash the company generated2. Buybacks took far more over those years, but in the June 2026 quarter, Meta bought back no stock at all1. When a company that has spent heavily on buybacks stops, it is telling investors where the cash is going instead.
The capital-allocation verdict is therefore split. The acquisition record includes two of the greatest deals ever made and one very expensive option that has yet to pay. The question now is whether the compute era looks more like Instagram or more like Oculus. Reality Labs is the place to start, because it is the one bet that has already had a decade to prove itself.
V. Reality Labs: The $4.6bn-a-Quarter Option
On 28 October 2021, Zuckerberg appeared on a virtual stage at the company's Connect conference and announced that Facebook would now be called Meta. The company's future, he wrote, lay in the "metaverse," an embodied internet that people would be inside rather than merely look at10.
The timing was awkward. Earlier that year, Apple had introduced App Tracking Transparency, which required apps to ask users for permission before tracking them across other apps. Most users said no. Meta's ad targeting and measurement suddenly got worse, and the company warned that the change would cost it about $10 billion in 2022 revenue. Investors were already worried about the core business when the CEO asked them to fund a new one.
The stock fell through 2022 as revenue stalled, costs rose and the metaverse losses mounted. From peak to trough over the past five years, the share price fell about 74%5.
The pivot back
Then came the course correction. In early 2023, Zuckerberg declared a "Year of Efficiency." Meta cut tens of thousands of jobs, flattened management layers and froze some projects. Operating margin recovered from about 25% in 2022 to about 35% in 2023 and 42% in 20242. The stock recovered with it. And the company's narrative shifted from the metaverse to AI.
But Reality Labs never stopped spending. In the June 2026 quarter, the segment earned about $431 million of revenue and lost about $4.6 billion, slightly more than the $4.5 billion loss a year earlier1. In 2025, Reality Labs accounted for about 18% of Meta's total costs and expenses2.
Sizing it honestly
That last figure explains why Reality Labs gets its own section. It is not a growth business today; its revenue is a rounding error against the Family of Apps. It matters because it consumes nearly a fifth of the company's costs and holds down group margin by several percentage points.
The case for patience rests on technical milestones. The Quest headsets lead the consumer VR market. Ray-Ban Meta smart glasses, built with EssilorLuxottica, have been a genuine consumer success by the standards of the category, and they give Meta's AI assistant a place to live on the user's face rather than inside someone else's phone.
The falsification test
Milestones are not profits, and here the historical record is unusually long. Meta bought Oculus in 2014. More than a decade later, Reality Labs still loses billions every quarter with no sign of the loss shrinking. Apple's Vision Pro, launched in 2024 with Apple's full distribution power behind it, has also had weak uptake, which suggests the problem is the category, not just Meta's execution.
The verdict: the record narrows the optionality claim considerably. Reality Labs has proved it can ship good hardware. It has not proved it can earn a return, and the commercialisation rate over twelve years is the evidence that counts. The one thread that could change this is the link between glasses and AI. If glasses become the device through which people use AI assistants, Meta would own a hardware platform that Apple and Google do not control.
Two measures would confirm or falsify that revised claim: glasses unit volumes, which Meta reports only sporadically, and the quarterly Reality Labs loss, which is still growing. Until the loss turns, Reality Labs is an expensive option, not a business.
Meanwhile, the business that pays for it is in better shape than it has ever been. It is worth looking at why, and at where it could lose.
VI. The Core Engine Today: Why It Wins and Where It Could Lose
Picture a small business owner, a candle maker in Ohio or a clothing brand in Jakarta. She opens Meta's ad manager, uploads a few product photos, sets a daily budget and a goal, perhaps purchases on her website. Meta's AI tools generate variations of the ad, choose the audience and decide where to show it, across Facebook, Instagram, Messenger and WhatsApp. Every time one of her potential customers scrolls, an auction runs in milliseconds, and the price is set by how valuable that particular impression is to every advertiser competing for it.
This scene happens billions of times a day. It is why Meta's Family of Apps earned essentially all the company's revenue and profit, while Reality Labs ran at a loss12.
Why it wins
The evidence for a durable advantage is strong. Start with scale: about 3.6 billion daily active people1. Add the data that comes from watching what they engage with, and the measurement systems that tell advertisers whether ads worked. The strongest proof is the price per ad. In the June 2026 quarter, impressions rose 14% and price per ad rose 12%1. Normally, showing more ads should push prices down. Prices rising alongside volume means advertisers are getting better results and are willing to pay more. That is pricing power demonstrated, not claimed.
Operating profit in 2025 was about $83 billion on a margin of about 41%2. Underlying operating profit rose about 20% that year, even though reported net profit fell slightly2.
Where it could lose
The counterarguments are real, and they narrow rather than reject the moat.
User growth is nearly exhausted; a 3% increase in daily active people is the pace of a mature utility1. Every dollar of future growth must come from price and impressions, which depends on AI-driven targeting keeping its edge.
None of the revenue is contracted. Advertisers can leave instantly, and they have before, in 2022.
And the biggest structural risk is new interfaces. If people increasingly ask AI assistants for recommendations rather than scrolling feeds, the moment where ads are shown could shift to a screen Meta does not own.
The precedent: Apple's tracking change
The best historical test of the moat is the period from 2021 to 2022, when Apple's App Tracking Transparency weakened Meta's ability to measure ad results. It showed that a platform owner can reach into Meta's business and impair its pricing overnight. Meta's response, rebuilding measurement around its own AI models and data, ultimately worked: price per ad is rising again. But the precedent establishes that Apple and Google, which control the phones Meta's apps run on, hold real power over it.
The verdict: the moat is intact on present evidence and narrowed by platform dependence, saturation and the lack of contracts. Price per ad is the single number that would show it weakening.
Profit into cash
The cash record is excellent. Across 2014 to 2025, Meta generated about $549 billion of operating cash flow against about $327 billion of net profit, or roughly 168%2. That gap comes mainly from heavy depreciation charges, which reduce profit but not cash, share-based pay, and favourable working capital: Meta collects from advertisers in about 36 days but pays its suppliers in about 902. In effect, suppliers help fund the business. Receivables are not a concern.
The tax noise explained
Now the tax puzzle that made the net-profit line look so erratic. In July 2025, the US passed a tax law that changed how the corporate alternative minimum tax interacted with Meta's deferred tax assets. Meta had to set aside a valuation allowance of about $14 billion against those assets, part of a total charge of about $15.9 billion23. That produced an effective tax rate of about 88% in the September 2025 quarter and net profit of only about $2.7 billion4. Excluding the charge, the 2025 tax rate would have been about 13%2.
The March 2026 quarter swung the other way, with a negative tax rate of about 23% and net profit of about $26.8 billion4, reflecting a discrete tax benefit. For the rest of 2026, Meta guided to a tax rate of 15% to 17%1. Meanwhile it carries about $11.2 billion of uncertain tax positions, amounts it may owe if tax authorities win disputes2.
The practical lesson: judge Meta on operating profit and cash flow, not net profit. On that basis, 2025 was a strong year.
Which brings the story to the cash flow line that is now under pressure, and the reason why.
VII. The $140 Billion Bet: AI, Capex and the Balance Sheet
In the plains of northern Louisiana, Meta is building Hyperion, a data-centre campus so large that Zuckerberg said it would eventually cover an area comparable to a significant part of Manhattan. It is one of several gigawatt-scale projects. To pay for it, Meta did not simply write a cheque. It formed a joint venture with funds managed by Blue Owl Capital, which raised the financing for the campus while Meta took a minority stake and agreed to lease the capacity2.
That structure is the story of this section in miniature. Meta is spending more than ever, and it is beginning to reach for other people's money to do it.
The scale of the bet
Management guided 2026 capital expenditure to $130–145 billion1, with total expenses guided to $165–169 billion1. Research and development in the June quarter alone was about $21.7 billion, up 67% on the year, or about 36% of revenue1. Free cash flow fell from about $54 billion in 2024 to about $46 billion in 20252, and then collapsed to $784 million in the June 2026 quarter1.
Decomposing the margin drop
The quarter's operating margin fell about 12 points, from 43% to 31%1. How much of that is the AI bet, and how much is one-off?
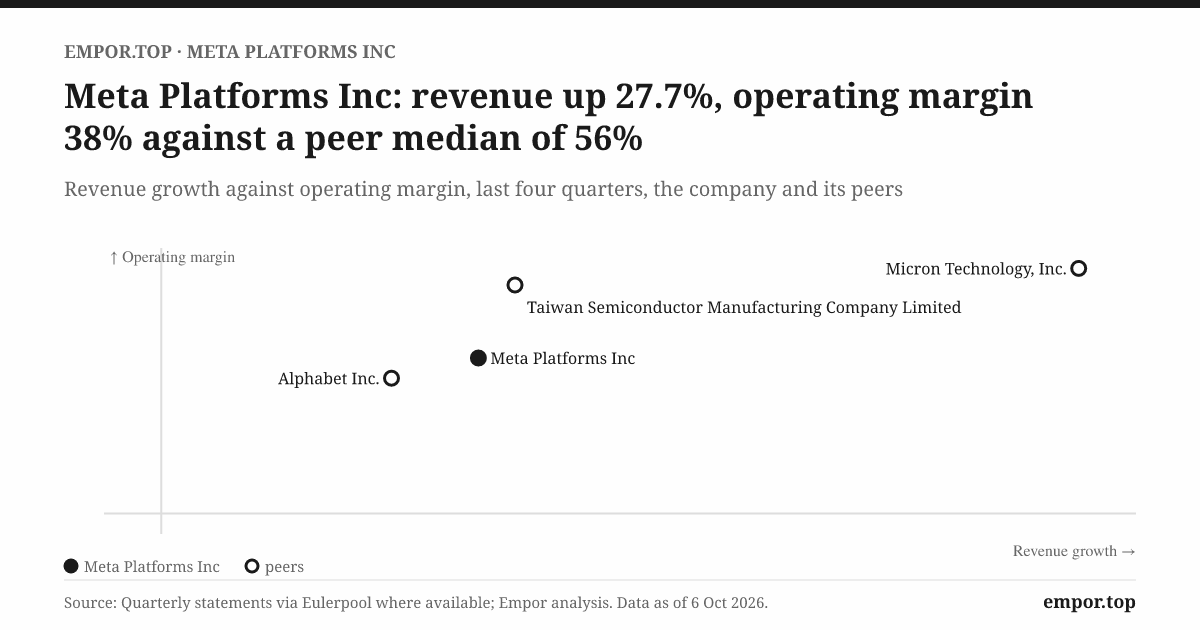
Start with the one-offs. Legal charges were about $2.4 billion and severance from the May 2026 restructuring about $1.2 billion1. Together that is about $3.6 billion, or about 5.9 points of margin on $60.8 billion of revenue. That leaves about 6 points of underlying compression, driven by depreciation on new servers, AI researcher pay and Reality Labs.
So the honest description is: half the margin drop was the bill for the past (legal cases and layoffs), and half was the cost of the future (AI infrastructure). The second half will not go away next quarter.
Where AI already pays
Is there evidence the spending earns a return? Yes, in the ad business. Meta has applied AI to ranking content in feeds, which increases time spent; to targeting ads; to generating ad creative; and to measuring results. The 14% impression growth and 12% price growth are the clearest evidence the spending is working1. Revenue growth accelerated from about 16% in early 2025 to 33% in early 20264.
What has not yet been proven is whether frontier AI models, the largest part of the spending, earn their own return. Zuckerberg argued in July 2024 that open-source AI was "the path forward," releasing Llama models freely so that the industry would standardise on Meta's architecture11. That brought developer goodwill but no direct revenue, and the company's later moves suggest it reconsidered: in 2025 it invested in Scale AI and recruited its founder to lead a new superintelligence effort, offering pay packages that became industry news2.
Headcount: the other half of the cost base
Notably, Meta has held people flat while spending on machines. Headcount was about 78,900 at the end of 2025 and about 75,500 at the end of June 202612. The May 2026 restructuring affected about 8,000 people1. The company is substituting compute for people, a bet that AI tools will let a smaller workforce run a larger business.
How leveraged is Meta becoming?
Here the balance sheet matters. Borrowings rose from about $49 billion at the end of 2024 to about $84 billion at the end of 20252. At the end of June 2026, long-term debt was about $83.7 billion against about $90.3 billion of cash and marketable securities1. Net cash is therefore close to zero, for a company that held tens of billions of net cash for most of the past decade.
The reported debt-to-equity ratio of about 0.39 looks comfortable2. But it would not capture the Hyperion structure, in which the debt sits with the joint venture rather than with Meta, even though Meta's lease payments service it and Meta has given a residual-value guarantee on the campus2. Investors should treat these commitments as debt-like. Meta has issued senior notes repeatedly, in August 2022, May 2023, August 2024 and November 2025212, and the cadence is accelerating.
Falsifying the financial-strength claim
The record supports one claim firmly: Meta has never needed to issue new shares to survive. But the claim that its financial strength is unshakeable should be tested against 2022, when operating profit fell 38% in a year2, and against the metaverse episode, which showed how quickly management's spending can outrun revenue.
The verdict: revenue acceleration is real evidence for the AI bet, and the margin drop is its cost. Growth capex is now funded partly by debt and lease-like structures. The return is unproven. Two numbers settle it: full-year 2026 operating margin, and free cash flow against the $165–169 billion expense guidance.
All of which raises the question of who decides how much to spend, and why investors should trust him.
VIII. The Founder at the Controls: Credibility, Incentives and Governance
In April 2018, Zuckerberg sat before the US Senate in a dark suit, on a cushioned chair that photographers noted raised him slightly. He was there to explain how Cambridge Analytica, a political consultancy, had obtained data on tens of millions of Facebook users through a personality-quiz app. Over two days of questioning, he apologised repeatedly and promised to do better. Facebook's market value fell sharply that year, by about a quarter at its worst5.
Five years later, in February 2023, he published a memo declaring a "Year of Efficiency," after shareholders had watched the stock collapse through 2022. Between those two moments lies the best way to judge him: not by what he says, but by how often what he says comes true.
Promises versus outcomes
The record has three kinds of entries.
The first is genuine reversals. The mobile pivot of 2012 and 2013 was decisive. The 2023 efficiency drive delivered what it promised: margins recovered from about 25% to about 42% in two years2.
The second is costly bets. The 2021 metaverse pitch promised a new computing platform10. Five years later, Reality Labs' losses are larger than ever and the platform has not arrived.
The third is the current guidance. Capital expenditure guidance has been raised repeatedly over successive calls, from the 2025 outlook through the 2026 range now set at $130–145 billion113. Raising guidance is not dishonest; it may reflect real demand. But the pattern is a company spending more than it first told investors it would, again.
On the earnings calls, management's prepared remarks consistently frame capex as building capacity for future AI demand. When analysts press for concrete returns on that spending, the answers point to ad performance improvements in the core business, which are measurable, and to long-term opportunities in AI assistants and business messaging, which are not yet13. The pattern of evidence is one concrete answer and one hope.
The governance problem
The dual-class structure means none of this can be tested by vote. Zuckerberg controls a majority of the voting power through Class B shares27. Shareholder proposals to equalise votes have been put to the annual meeting year after year and defeated, because the person they target holds the decisive votes12.
Pay is a lesser issue than control. Zuckerberg takes a modest salary and no stock awards; most reported pay relates to personal security costs7. His incentive is his ownership stake, which aligns him with long-term value, if not with any particular holding period.
The activist stress test
A skeptical investor would ask three questions. Why does Reality Labs still lose more than $4 billion a quarter after twelve years? Why is capex guidance rising faster than revenue? And why did buybacks stop just as the stock traded above its historical multiple?
Because no vote can force change, the pressure shows up in the share price instead. That happened in 2022, when the stock's fall arguably helped produce the 2023 efficiency turn. It is the only discipline available.
The team
The operating team is lean at the top. Susan Li became chief financial officer in 2022 and has been the main voice on capex and expense guidance. Javier Olivan succeeded Sheryl Sandberg as chief operating officer. The AI effort was reorganised in 2025 under new leadership recruited from outside2.
The verdict: course corrections have been real, so have the costly bets. A founder who cannot be outvoted is the source of Meta's best long-term decisions and its main governance risk, and both can be true at once.
The founder's decisions are not, however, beyond the reach of courts and regulators.
IX. Regulators, Courts and the Youth-Safety Problem
In 2026, a jury in New Mexico ordered Meta to pay $375 million in a case brought by the state's attorney general, which argued that Meta's platforms had exposed children to harm1. The amount is trivial against Meta's revenue. The case is not trivial, because it is one of many.
The long record
Meta's regulatory history begins with privacy. After Cambridge Analytica, the FTC imposed a $5 billion penalty in July 2019, then the largest privacy fine in its history, along with a consent order that requires an independent privacy assessor and board-level oversight14. The 2016 US election and Russian disinformation campaigns had already made the company a political target.
The June 2026 quarter included about $2.4 billion of legal charges1. Against about $228 billion of trailing revenue, that is about 1%. Fines, on their own, do not threaten the business.
The real mechanism: price per ad
The more serious threat works through the pricing engine described earlier. Europe's Digital Markets Act names Meta as a "gatekeeper" and restricts how it can combine personal data across its services for advertising without explicit consent15. Meta responded with a "pay or consent" model, asking European users to either pay for ad-free service or accept personalised ads; the European Commission found that model non-compliant and fined Meta in 2025159.
The mechanism is simple. If Meta cannot use personal data to target ads, the ads become less effective, and advertisers bid less. Regulation that limits targeting directly reduces price per ad, the very number that proves the moat.
Youth safety
The second front is youth safety. Dozens of US states, school districts and families have sued, alleging that Meta designed its products to be addictive to children and concealed internal research about harm2. Meta disputes the claims. The New Mexico verdict suggests juries are willing to find against the company. The 10-K describes these as material proceedings whose outcomes Meta cannot reasonably estimate2; the sizes of exposure, beyond what has been charged, are not disclosed.
The antitrust threat recedes
The November 2025 ruling in the FTC's antitrust case removed the most dramatic risk: a forced break-up of Instagram and WhatsApp9. That shift matters for valuation, because it means the integrated advertising system, which runs one auction across all the apps, survives intact.
The verdict: fines are small today. The real exposure is cumulative: European limits on targeting and a growing number of youth-safety cases, each of which could cut price per ad or force product changes. Neither has yet changed the engine; both are rising.
Twenty-two years after the dorm room, the story has produced lessons that apply to this company and no other.
X. Playbook: Business & Investing Lessons
"Scale is the moat, but price per ad is the proof." Every platform claims a network effect. Meta's is proven by a single quarter's numbers: impressions up 14%, price per ad up 12%1. When a company can sell more of something and charge more for each unit at the same time, buyers are telling you the product is getting better. For investors in any platform business, the lesson is to look past user counts and find the price.
"Buy the network, not the product." Instagram had a photo filter and 13 employees. WhatsApp had a messaging app and almost no revenue. What Zuckerberg bought, in each case, was hundreds of millions of people who had chosen to gather somewhere new. Products can be copied, and Meta has proved it by copying Stories and short video. Networks cannot. The founder's genius was knowing which was which, and paying for the one that couldn't be copied.
"A founder's vote is a long-term option and a governance risk, and you can't buy one without the other." The same structure that let Zuckerberg buy Instagram over a weekend let him rename the company and spend tens of billions on a metaverse that has yet to arrive. Investors who own Meta are not investing in a company. They are investing in one person's judgment, with no ability to overrule it.
"Cheap growth ends when the compute bill comes due." For a decade, Meta grew by writing software that cost almost nothing to copy. The $784 million quarter is the moment that ended1. AI is not software economics; it is industrial economics, with factories and power plants and debt. Investors who valued Meta as a software company must now decide whether they are willing to value it as a utility.
"Read the tax line before the profit line." In consecutive quarters, Meta's net profit fell to $2.7 billion and rose to $26.8 billion, while its operating business barely changed4. The headlines followed the bottom line. The business did not.
XI. Bull vs. Bear Case & KPIs
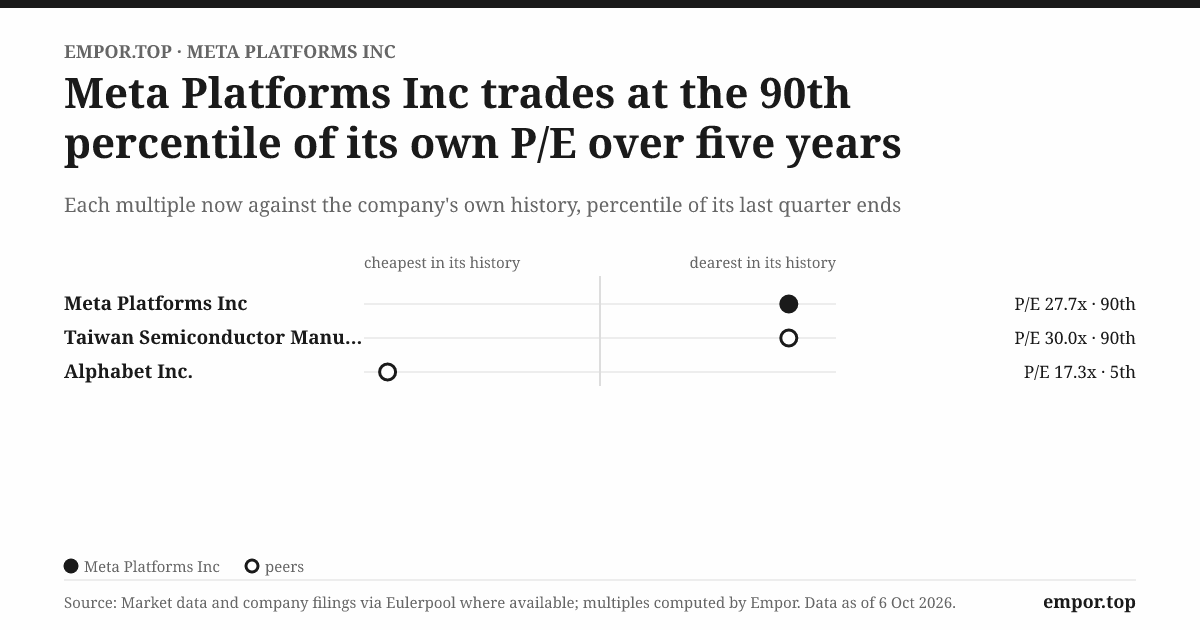
Imagine two analysts looking at the same stock on the same day. The first values Meta on its 2026 earnings and sees a company trading at about 28 times trailing earnings, above its own five-year median of about 245. The second looks at 2028 free cash flow and asks a simpler question: when does the spending stop?
On today's numbers, Meta trades at about 18 times EV/EBITDA, with a free cash flow yield of about 2.2% and a PEG ratio of about 0.75. The multiple is above its own history. The market is paying for the AI bet, not discounting it.
The industry, through Porter's five forces
Buyers are millions of advertisers with no meaningful concentration; no single advertiser is material2. That is good. But each one can reallocate spending instantly, which is why revenue fell in 2022.
Suppliers have grown in power. Nvidia and the other chipmakers supply the hardware for AI, and Meta's dependence on them is rising with every dollar of capex.
Substitutes are the largest long-term threat: AI assistants that answer questions and make recommendations without a feed.
Rivalry is intense. Google and YouTube remain the largest digital-ad sellers; Amazon's ad business has grown into a major competitor at the point of purchase; TikTok competes directly for time spent among younger users. Snap and Pinterest are smaller and less profitable, which suggests scale itself is the key advantage.
New entrants face very high barriers: building a network of billions of people is not a matter of capital alone.
And above the five forces sit Apple and Google, which control the operating systems Meta's apps run on, and have shown they can change the rules.
Hamilton Helmer's 7 Powers
Two of Helmer's powers apply clearly. Network economies: each user makes the platforms more valuable, and each advertiser improves the data that targets ads. Scale economies: the cost of building the AI infrastructure is spread across more revenue than almost any competitor can match. Counter-positioning, switching costs and cornered resources are weaker: users can and do spend time on TikTok, and advertisers can shift budgets overnight.
The bull case
Revenue is accelerating, with growth in the high 20s to low 30s for two quarters14. AI is already improving ad performance. WhatsApp and Threads monetisation remain early. Headcount is flat. And trailing return on invested capital is still about 24%5, which shows that even with the spending, the business earns well above its cost of capital.
The bear case
The June quarter's operating margin was about 31%; free cash flow was close to zero1. Debt rose by about $35 billion in a year2. Regulatory and youth-safety risk is growing. Advertising is cyclical, and 2022 showed what a downturn does. And AI interfaces could bypass social apps entirely.
Weighing it
The bull case needs revenue growth to outrun capex for several years. The bear case needs only a margin that does not recover. That asymmetry is the core of the debate. The history narrows the bull case without rejecting it: Meta has turned spending into revenue before, but it has also spent for a decade on Reality Labs without a return.
The three KPIs that matter
- Operating margin and free cash flow against capex guidance. Latest: about 31% margin and $784 million of free cash flow in the June quarter, both sharply down1.
- Price per ad and impression growth. Latest: price up 12%, impressions up 14%1, both positive.
- Reality Labs operating loss. Latest: about $4.6 billion a quarter, slightly larger than a year ago1.
XII. Epilogue: What Decides It Next
Tonight, Meta stands at a peculiar point: its core business is stronger than ever and its cash flow weaker than at any time in a decade. The next few months will start to settle which of those facts matters more.
The first test comes at the end of October, when Meta reports its September quarter results and files its 10-Q. Investors will look at the capex run-rate, the legal charges, the tax rate against the 15–17% guidance, and, above all, any early comment on 2027 expenses. If management signals another large step up in spending, the first central question, whether AI earns its return, will stay open for another year. If revenue growth stays near 30% while expense growth eases, the bull case gains real evidence.
The second test arrives with year-end net debt and the 2026 10-K, which will show the full scale of Hyperion-style commitments. If off-balance-sheet obligations rise as fast as capex, the leverage question will become the defining one.
The third test is in Brussels and the state courts. A European ruling that further limits personalised advertising would hit price per ad directly. More youth-safety verdicts, or a large settlement, would show whether the legal charges of the June quarter were a one-off or a new recurring cost.
And beneath all of it sits the question no filing can answer: what does Meta look like when Zuckerberg is no longer at the controls? The Class B shares that give him control will one day pass on, and with them the power to make 12-year bets that no board could stop.
That is the tension that remains. The machine prints money. The founder decides what it buys.
XIII. Outro
Go back to that July day in 2026. Revenue jumped 28%. Advertisers paid more for every ad and bought more of them. And at the end of it, after the servers and the data centres and the lawyers and the severance, Meta was left with $784 million.
There has never been a company quite like it. Meta took a dorm-room social network and turned it into the most effective advertising machine in history, and now it is spending that machine's profits, at a scale no one has attempted before, on whatever comes after it. Whether that is the next Instagram or the next metaverse is the only question that matters, and only one person gets to answer it.
References
-
Meta Reports Second Quarter 2026 Results (Form 8-K, Exhibit 99.1) — SEC, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Meta Platforms Form 10-K for FY2025 — SEC, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Meta Financials, Earnings and Presentations — Meta Platforms ↩↩↩↩↩↩
-
Meta Platforms filings index, S-1 (2012 IPO) — SEC EDGAR ↩↩↩↩↩↩
-
Meta Platforms filings index, proxy statements (DEF 14A) — SEC EDGAR ↩↩↩
-
Open Source AI Is the Path Forward — Mark Zuckerberg, Meta, 2024-07-23 ↩
-
Meta Platforms filings index, 8-K, including item 5.07 voting results — SEC EDGAR ↩↩
-
Meta Investor Events and Earnings Call Webcasts — Meta Platforms ↩↩
-
FTC $5 Billion Penalty and New Privacy Restrictions on Facebook — FTC, 2019-07-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube