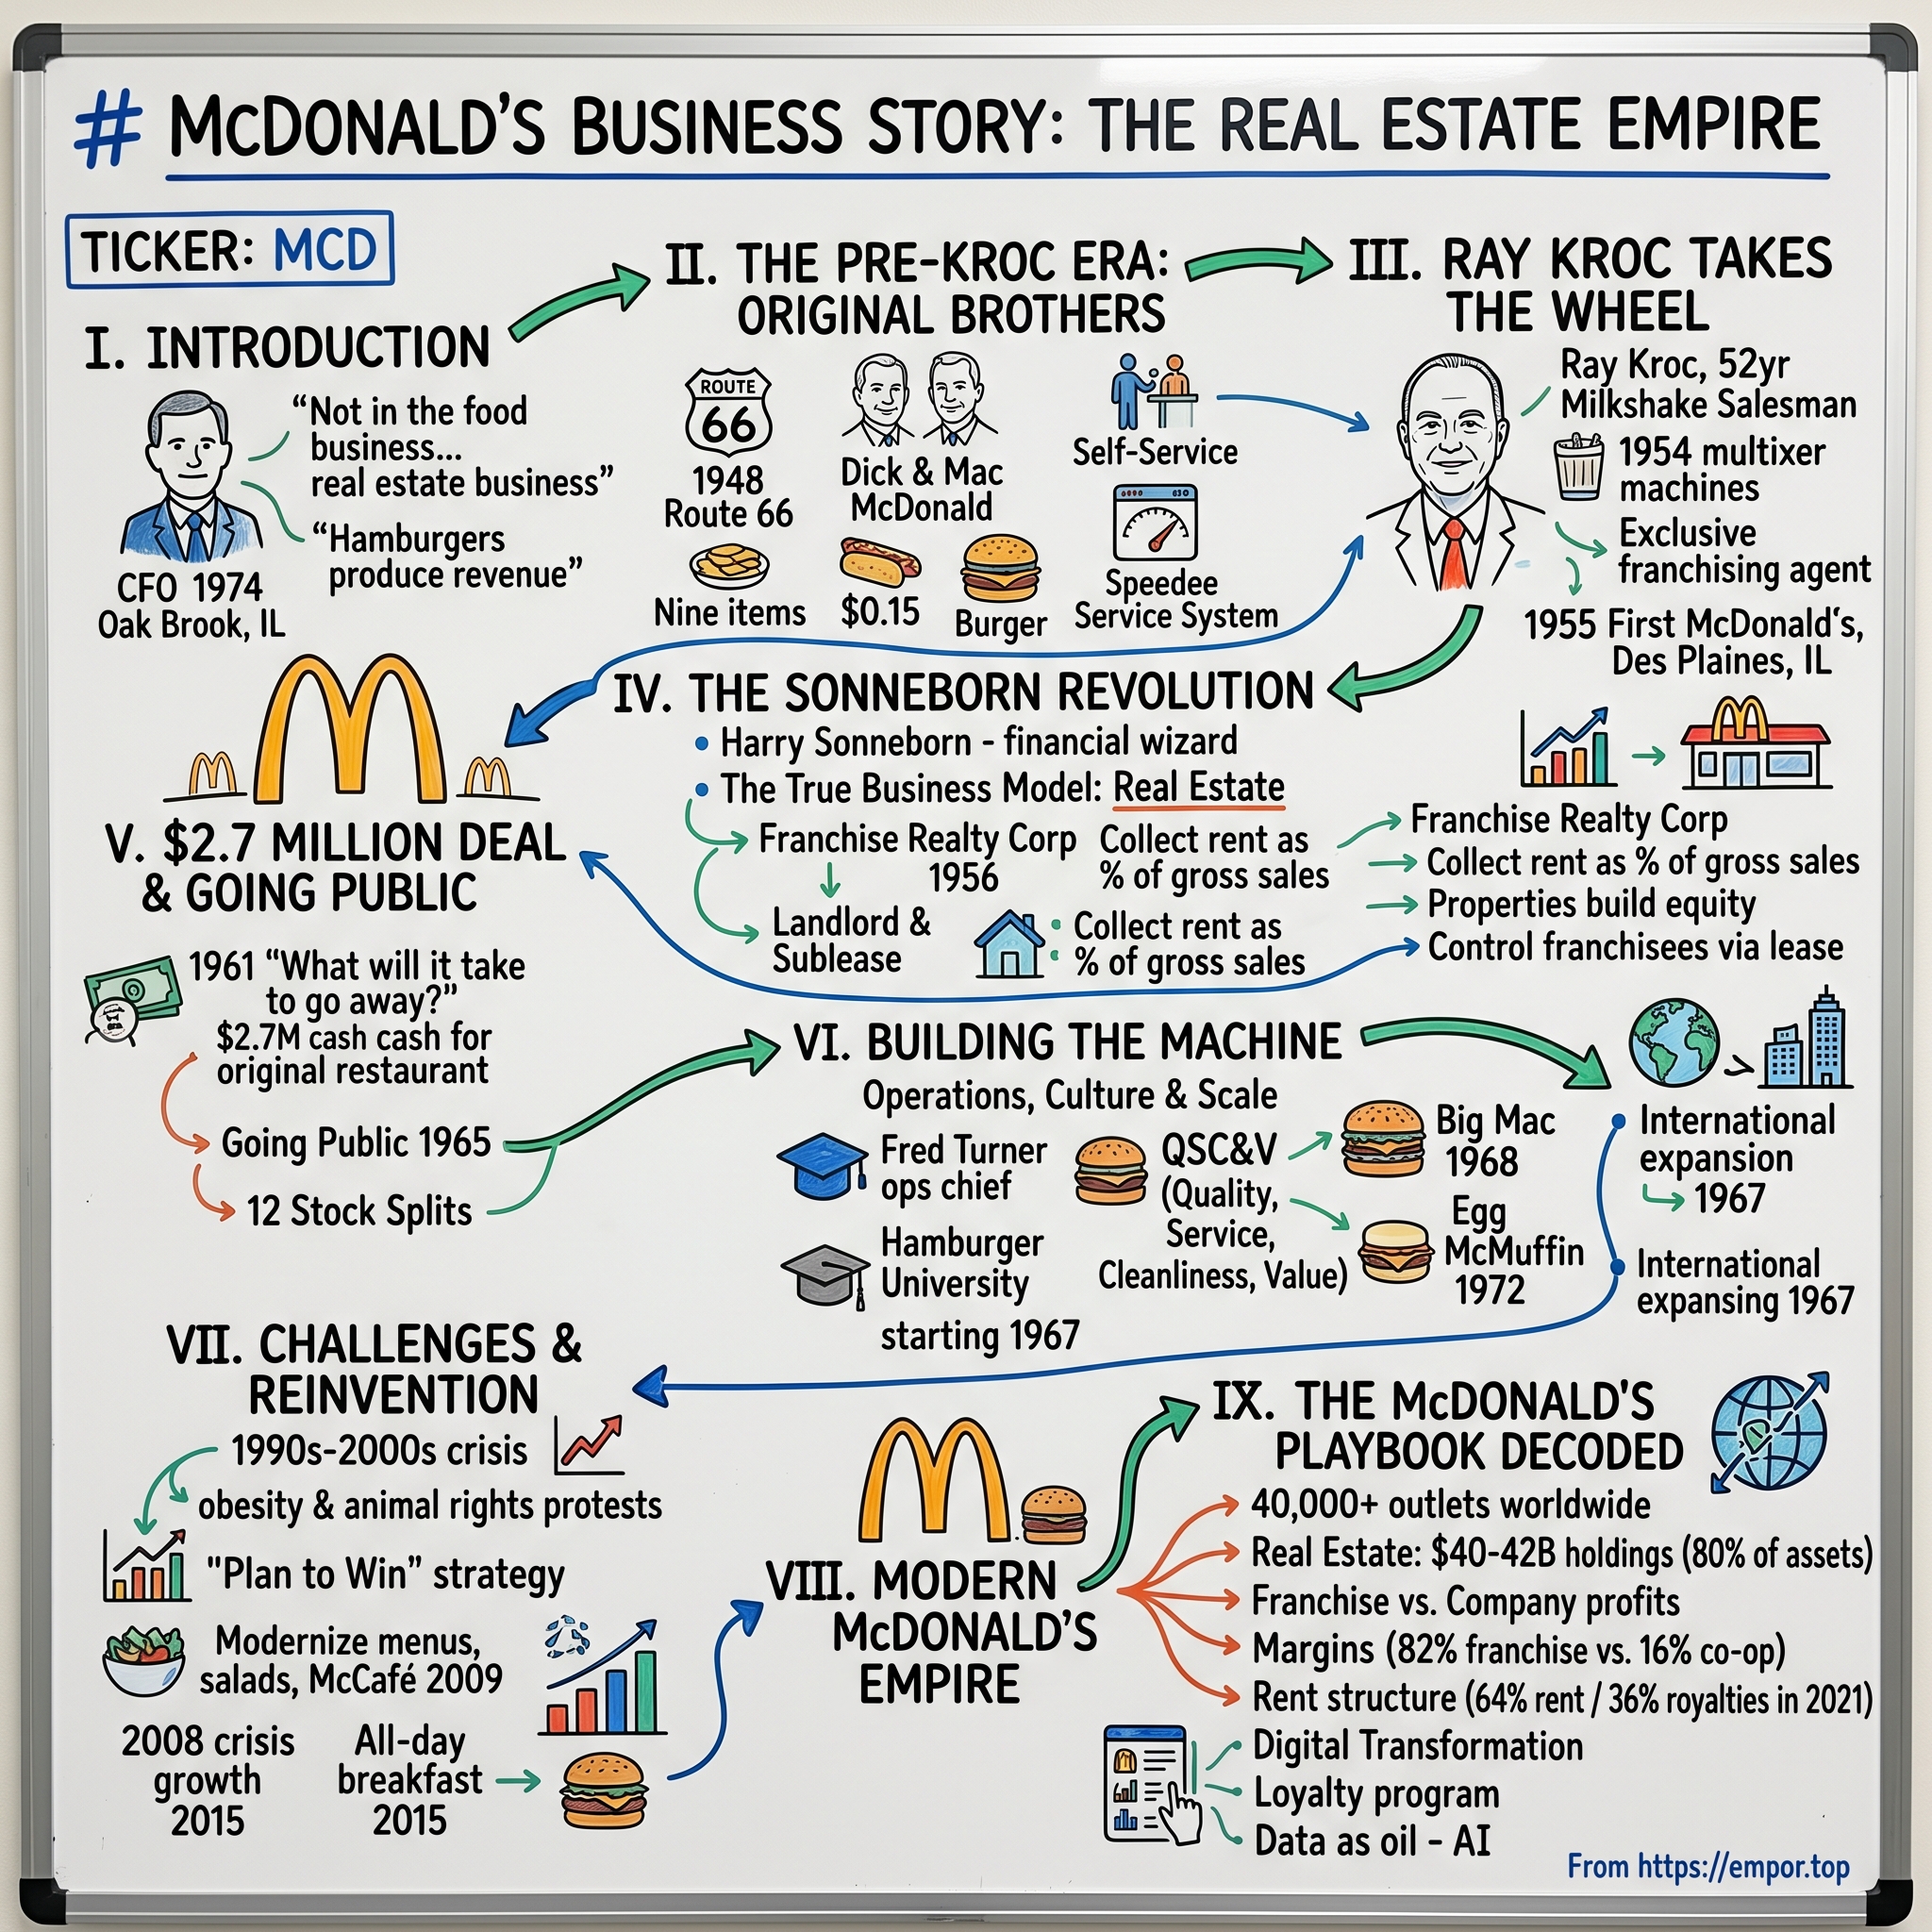
McDonald's: The Landlord Whose Tenants Need Rent Relief
I. Cold Open: A $231 Stock and a Landlord Writing Cheques to Its Tenants
Picture the slide that mattered most at McDonald's Investor Day on 23 September 2026. It was not a new burger, a new app feature or a celebrity meal. It was a number aimed at the people who run the restaurants, not the people who eat in them. Management told investors it would provide about $8.5bn of what it called "NEXT partnering support" to franchisees through 2036, with roughly $5bn of it arriving by 2030 as rent relief and capital support.1
Read that again from the franchisee's side of the counter. For seventy years, the McDonald's operator has paid the corporation two cheques every month: one for the right to use the brand and the system, and one for the building and the ground beneath it. Now the landlord was offering to trim the second cheque. In the language of real estate, it was a rent concession. In the language of a restaurant chain, it was an admission that the store-level economics had become tight enough to need help.
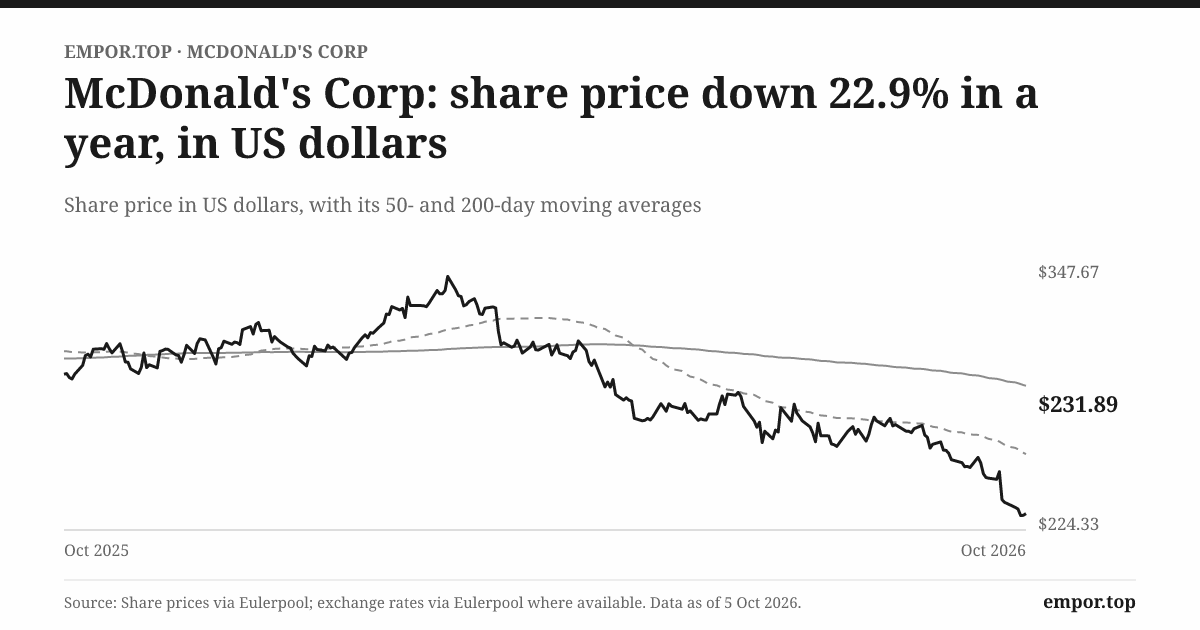
The market's reaction is what turned a strategy slide into a story. The shares had already been sliding after a soft second quarter. By early October they sat at about $232, a whisker above their 52-week low of about $231 and roughly 32% below the high of about $341 set within the past year.2 For a stock famous for being the thing investors buy when they want to stop worrying, a one-third drawdown is close to the biggest fall it has suffered in five years.
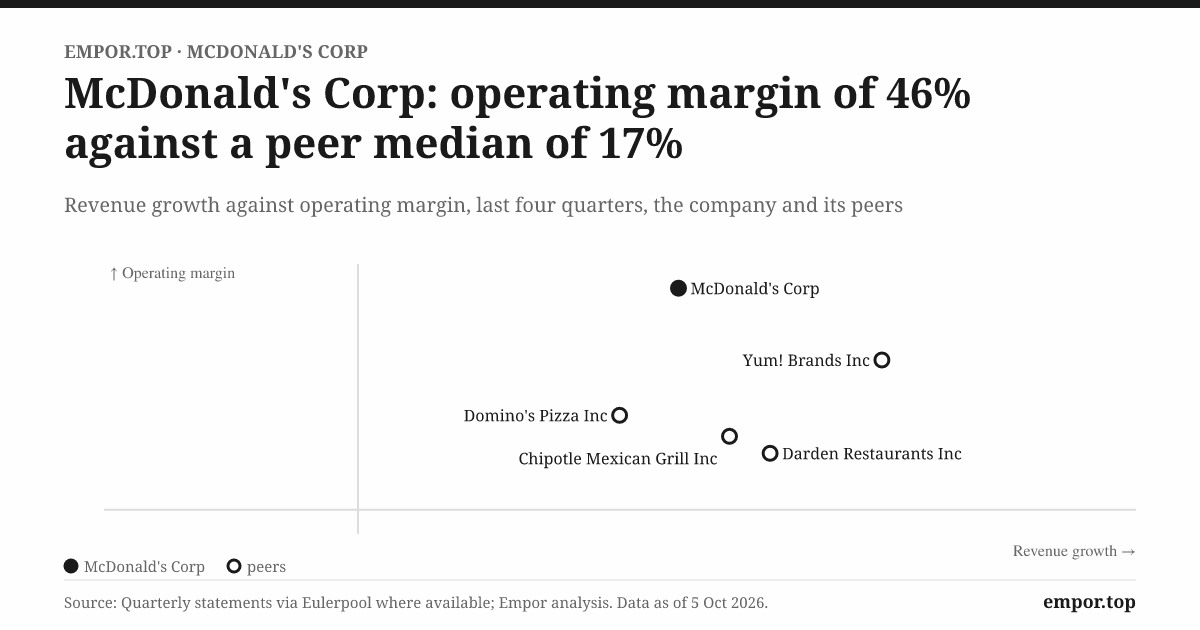
The irony is sharp because, on paper, McDonald's has never looked more profitable. In 2025 it reported revenue of about $26.9bn and kept about 46 cents of every revenue dollar as operating profit.3 That is not a restaurant margin. It is a landlord-and-licensor margin, and it exists because roughly 95% of the 45,356 restaurants open at the end of 2025 were run by someone else.3
That structure has a famous origin line. Harry Sonneborn, the finance mind Ray Kroc hired in the 1950s, saw that the durable money was not in selling hamburgers but in controlling the land the hamburger stands stood on.4 The company has repeated some version of "we are in the real estate business" ever since. This episode is not a history lecture about that line. It is a test of it.
Here is the test. A landlord's margin is only as good as its tenants' ability to pay. When the tenants are thriving, the landlord collects a share of rising sales and bears little of the cost of labour, food or paper cups. When the tenants are squeezed, the landlord faces a choice: hold the rent and risk weaker operators, fewer openings and slower remodels, or cut the rent and accept a smaller slice. On 23 September, McDonald's chose the second path, at least partly.
So four questions run through what follows. Can the rent-and-royalty margin survive when the company is paying franchisees to stay healthy? Can a shareholder-return machine built on dividends, buybacks and negative book equity keep turning when growth slows? Is the share-price fall a temporary execution stumble on value pricing, or a reset of what McDonald's can grow at? And is governance listening, at a company where one person is chairman and chief executive and where his pay rose in a year US traffic fell?
Underneath all four sits a single debate. Management says the summer's weakness was mostly self-inflicted and fixable. Sceptics say a business whose US sales growth in 2025 came mostly from price, not from more customers, has run into the limit of what its customers will pay. The answer will not come from a press release. It will come from guest counts, and from how much the landlord ends up giving back.
To see why rent relief cuts so deep, it helps to go back, briefly, to how rent became the profit engine in the first place.
 Subscribe on LinkedIn
II. The Real-Estate Bargain, Told Fast: How Rent Became the Profit Engine
The origin myth usually starts with the McDonald brothers' speedy kitchen in San Bernardino and Ray Kroc, the milkshake-machine salesman who saw it and could not stop thinking about it. The part that matters for investors is less cinematic. It is a finance executive named Harry Sonneborn, who joined Kroc in the mid-1950s and proposed a simple twist: the company should lease or buy the sites, then sublease them to franchisees at a mark-up.4
That idea did three things at once. It gave the young company a cash stream that did not depend on the thin fees franchising then allowed. It gave Kroc leverage over operators, because a franchisee who broke the rules could lose the building, not just the sign. And it turned McDonald's into a borrower with collateral, which made banks far more willing to finance expansion.4 Kroc bought out the brothers in 1961, and Sonneborn served as the company's first president before leaving after a falling-out with Kroc in 1967 over whether to keep building.4 The man who had argued for caution left; the real-estate machine he designed stayed.
Fast-forward sixty years and the bargain looks almost identical in shape. A conventional franchisee signs an arrangement that combines a lease and a licence, usually for around twenty years. Rent and royalties are charged as a percentage of the restaurant's sales, with a minimum rent so that the landlord still gets paid in a bad month.3 McDonald's takes a cut of the top line. The operator carries the wage bill, the beef, the fryer oil and the utilities.
That is why "systemwide sales" and "revenue" mean very different things at McDonald's. Systemwide sales are what every restaurant under the arches rings up. Revenue is only what lands at the corporation: the full sales of the roughly 2,000 restaurants it runs itself, plus rent and royalties from everyone else.5 Investors who confuse the two overestimate how exposed the company is to food and labour costs, and underestimate how exposed it is to franchisee health.
Look at 2025's revenue of about $26.9bn through that lens. About 61%, roughly $16.5bn, was franchised revenue. About 36%, roughly $9.7bn, was sales at company-operated restaurants.3 Inside the franchised line, rent was about $10.4bn and royalties about $6.0bn.3 Rent is the bigger cheque, which is why a rent concession is not a rounding error.
Now look at profit rather than revenue. Franchised restaurants produced about $13.9bn of margin, roughly 90% of all restaurant margins at the company.3 Company-operated stores generate more revenue per unit but keep only a sliver, because McDonald's pays their costs. The franchise line is where the money lives. Put plainly: the corporation is a property and brand company that happens to run a couple of thousand restaurants, mostly to test equipment, train people and keep a feel for the kitchen.
The geography adds a further wrinkle. At the end of 2025, about 13,700 restaurants were in the US, about 10,800 in what McDonald's calls International Operated Markets (big, mature countries such as the UK, Germany, France, Canada and Australia), and about 20,800 in Developmental Licensed Markets.3 That last group includes China and Japan, which are run through affiliates. McDonald's does not collect their full rent and royalty stream as revenue; instead, it books a share of their earnings, which came to about $190m in 2025.3
That fact explains a quiet asymmetry. The Developmental Licensed segment is where most of the new restaurants are going up, yet it contributes the least revenue. In 2025, franchised revenue was about $7.4bn in the US and $7.3bn in International Operated Markets, against about $1.9bn for Developmental Licensed Markets and corporate combined.3 A new unit in Shanghai adds to the restaurant count and the brand's reach, but much less to the landlord's rent roll than a new unit in Ohio or Manchester.
So who bears the risk? In good times, the arrangement is close to ideal for McDonald's shareholders. A percentage rent means the corporation captures menu price increases automatically, without paying for the higher wages that often prompted them. Minimum rent means the floor is protected. The franchisee sits in the middle, absorbing the squeeze between what customers will pay and what labour and food cost.
But that only holds while the operator can absorb it. A landlord can push rent up as a share of sales for a long time, and the tenant keeps paying. Then, one day, the tenant needs a new kitchen, a new drive-through lane or a remodel to compete, and cannot fund it from a shrinking margin. At that point the landlord either finances the remodel, cuts the rent, or watches the property age. The 2026 relief package is McDonald's choosing among those options.
That is the bargain in its modern form: McDonald's takes the sales upside and passes store-level cost risk to operators, right up to the point where operators cannot carry it. To see how the company got its margin up to today's level, though, you need the next chapter, in which revenue fell for years and profit margin nearly doubled.
III. The Refranchising Pivot: How Falling Revenue Doubled the Margin (2015–2019)
Imagine reading McDonald's income statement from 2014 to 2018 with the labels covered. Revenue falls in every single year, from about $27.4bn to about $21.3bn, a drop of more than a fifth.36 Any analyst would assume a business in decline. Then uncover the operating margin line: it climbs from about 29% to about 42% over the same span.6 That is the refranchising pivot, and it is the single most important thing to understand about McDonald's last decade.
The backdrop was a company in trouble. By 2014 and early 2015, sales were weak, the menu had become bloated, and the brand felt tired next to newer fast-casual chains. A new management team launched a turnaround that included all-day breakfast and a programme of store upgrades with digital ordering kiosks, branded "Experience of the Future". These helped traffic for a while. But the biggest financial move was quieter: selling company-operated restaurants to franchisees.
The logic is mechanical. When McDonald's sells a restaurant it operates, it gives up all of that store's sales and almost all of its costs. In exchange, it keeps the rent and royalty stream, which is a small fraction of the sales but almost pure margin. Revenue falls sharply. Operating profit falls far less, or not at all. The margin percentage leaps.
The clearest single year is the jump from fiscal 2016 to fiscal 2017. Operating margin went from about 31.5% to about 41.9% in one year, while revenue fell about 7%.6 Some of that year also reflected gains on selling restaurants. But the step change stuck: the margin has not gone back below about 38% since, even in the pandemic year of 2020.6
So was the profit growth of the decade real value creation? Take the ten years to 2025. Revenue grew only about 0.6% a year.6 Operating profit grew about 5.7% a year and net profit about 6.6% a year.6 Earnings per share did better still, because the share count kept shrinking. The difference between revenue growth of nearly zero and profit growth of mid-single digits is almost entirely mix, leverage and buybacks.
That is not a criticism of the strategy. Selling stores to experienced operators at good prices and keeping the land is a sensible way to run a mature system. It is a statement about what the numbers can and cannot tell you. The decade's profit growth did not come from selling many more burgers. It came from changing who sells them, and then shrinking the number of shares the profit is divided by.
What about the more flattering recent numbers? Since fiscal 2020, revenue has grown about 7% a year and net profit about 12.6% a year.6 Those figures look strong until you notice the starting point: 2020 was the pandemic trough, when revenue fell about 10% and net profit fell about a fifth.6 Measure from a hole and you will always look like you climbed a hill. Over three years, from 2022, revenue growth was about 5% a year, and much of that was menu prices and currency rather than more customers.6 The honest base rate for revenue at this company, outside of refranchising and recovery years, is low single digits.
The balance sheet tells the second half of the story. At the end of 2014, shareholders' equity was positive, about $12.9bn.6 By the end of 2016 it was negative and it has stayed negative ever since.6 Nothing went wrong. McDonald's borrowed money and spent it, along with cash from operations and refranchising proceeds, on buying back stock and paying dividends. Returning more than the accumulated book value pushes equity below zero.
This is why the fact sheet shows a return on equity of about minus 859% and a book value of about minus $1.43 per share.2 Those numbers are not signs of distress. They are what you get when you divide positive profits by a negative denominator. Any investor screening for "high return on equity" or "low price to book" will get nonsense for McDonald's. Return on invested capital, which counts debt as well as equity, is a better gauge, and it sits at about 19%, close to where it was a decade ago.26
There is one more lesson from history worth carrying forward. McDonald's has tried to be more than McDonald's before. In the 1990s and early 2000s it owned stakes in other restaurant concepts, and it eventually exited them to focus on the core brand. The company's current posture, to buy back stock, hold the land and refranchise, is partly the product of that experience. It is a track record of focus, not of clever acquisitions, and investors should judge capital allocation by that yardstick: did the cash go into the arches, or back to shareholders, and at what returns?
The pivot left the company leaner, more profitable per dollar of revenue and far more dependent on franchisee health. That dependence was abstract while sales rose. It became concrete in the summer of 2026, when the value wars came for McDonald's.
IV. The Value-Wars Miss: Was Q2 2026 Execution or Structure?
The second-quarter results call in August 2026 had a moment that executives rarely allow themselves. Management said, in effect, that the company "simply didn't execute" on value.7 No talk of weather, no blame on the consumer. A plain admission that the value programme, the set of deals meant to bring price-sensitive customers back, had not worked as designed.
The numbers behind the admission were modest, not disastrous. Global comparable sales rose about 1.3% in the quarter, with the US up about 0.8%, International Operated Markets about 1.5% and Developmental Licensed Markets about 1.9%.75 The problem was what sat inside the US number. Guest counts, the number of transactions, were negative.7 Sales rose only because the average check rose. And management said July US comparable sales had been slightly negative.7
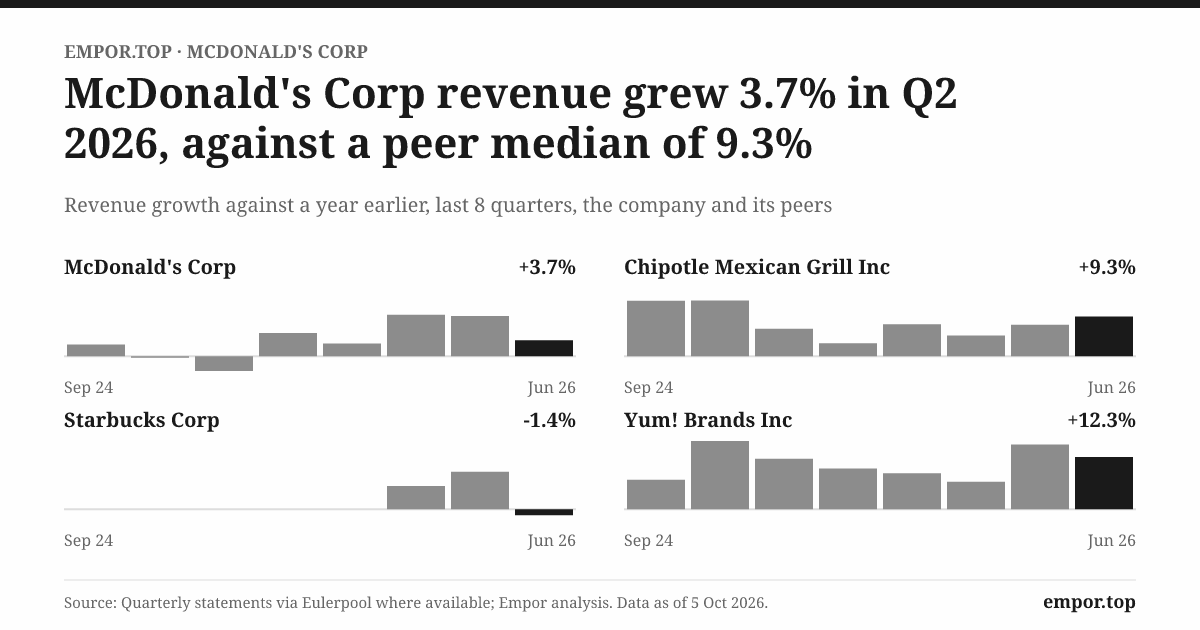
Reported revenue told the same story from a different angle. After growth of roughly 9–10% in each of the two prior quarters, revenue growth in the June quarter slowed to about 3.7%.58 Part of the earlier strength reflected currency and comparisons against weak 2025 quarters, so the deceleration looked worse than the underlying trend. But the direction was what spooked investors.
Prepared remarks vs. Q&A
In the prepared remarks, management laid out the diagnosis. About two-thirds of the shortfall, by its own estimate, came from value-programme execution errors it believed it could fix.7 A key detail: only about 60–65% of US restaurants were running the new pricing architecture during the quarter.7 Because the US system is almost entirely franchised, McDonald's cannot simply order operators to change their prices. It has to persuade them, and many were not yet persuaded.
The Q&A sharpened that point. Analysts pressed on traffic and on the pricing architecture. Management was concrete about the two-thirds attribution and about July. It was much vaguer about timing: when guest counts would turn positive, and how fast the remaining restaurants would adopt the new structure.7 That gap between a precise diagnosis and an imprecise recovery date is worth noting. It is easy to say why something broke. It is harder to say when it will be fixed.
Guidance discipline
Two other pieces of guidance moved in the wrong direction. The expected currency tailwind to 2026 earnings per share was cut from about $0.20–$0.30 to about $0.15.7 And the long-standing target of reaching 50,000 restaurants worldwide slipped from the end of 2027 to 2028.7 Neither change is dramatic alone. Together, with the value miss, they show a management team resetting expectations on several fronts at once, which is what investors listen for when deciding whether a miss is a blip or a pattern.
The competitive battlefield
The value war is not happening in a vacuum. McDonald's competes for the same lower- and middle-income customer as Burger King (owned by Restaurant Brands International), Wendy's, Taco Bell and KFC (owned by Yum! Brands), Chick-fil-A, Domino's and, at the coffee end, Starbucks. Every one of them has spent the past two years advertising bundles and price points aimed at a consumer who feels poorer after years of food inflation. When everyone shouts "value", the customer compares, and a brand that raised prices hardest during the inflation years has the most ground to make up.
Chicken is the clearest flank. Chick-fil-A has built a formidable business with fewer units and higher sales per store, and McDonald's has now put explicit targets on gaining share in chicken and beverages.1 That is an implicit admission that those categories are where it has been losing ground. A company that sets targets in a category is telling you that it does not consider itself the winner there yet.
Myth vs reality
The myth is that McDonald's is immune to price sensitivity because it is already cheap. The reality is more nuanced. In 2025, US comparable sales rose about 2.1%, and that growth was led by price rather than traffic.3 Price-led growth is a perfectly good outcome for a landlord collecting a percentage of sales, until the customers it is pricing up start to visit less often. The second quarter of 2026 suggests that point may have been reached for at least part of the customer base.
Testing the "fixable" claim against history
McDonald's has a record of comebacks, and the record is instructive. The 2015 turnaround, built around all-day breakfast, lifted comparable sales for roughly two years before the benefit faded, as competitors copied and the novelty wore off. That pattern, a real initial lift followed by mean reversion, is the base rate against which any "value fix" should be judged. A better-designed value menu can win back visits. Whether it can sustain them against equally aggressive rivals is a separate question.
What the market is pricing
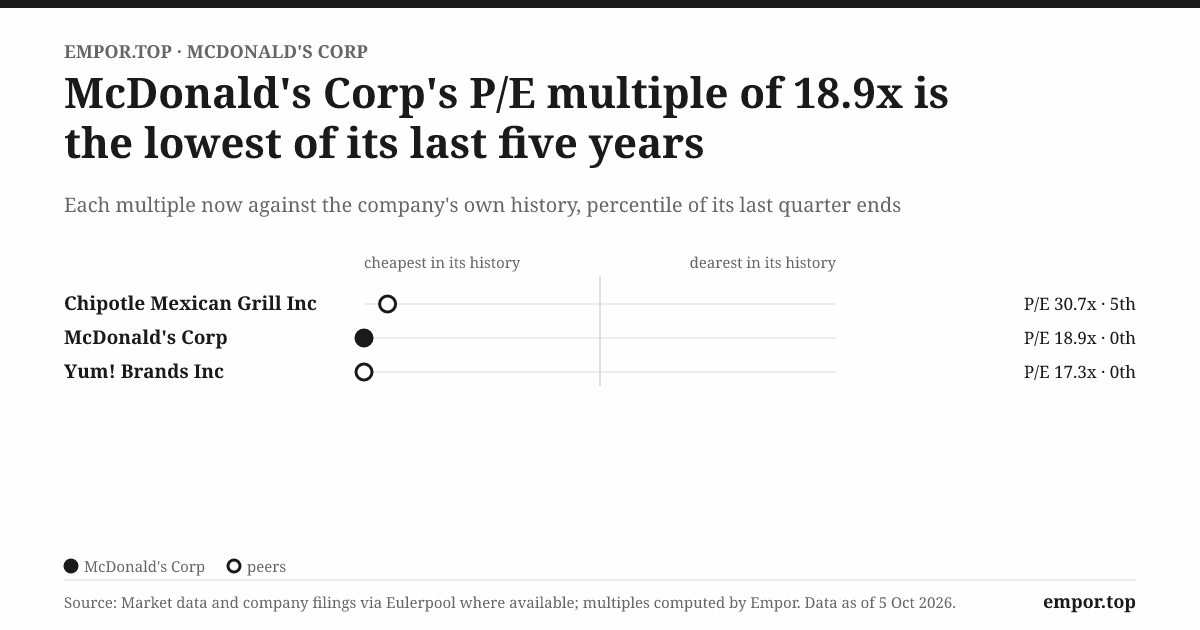
The valuation already reflects scepticism. At the start of October, the shares traded at about 18.9 times trailing earnings, against a five-year median of about 25.5 times.2 That is a discount of roughly a quarter to the company's own recent history, which implies the market no longer believes in the high-single-digit earnings growth that the old multiple assumed. Peer multiples move with each quarter's prints, and a fair comparison needs care because peers mix franchised and company-operated models differently. The narrower point is that McDonald's has gone from premium-priced to merely ordinary-priced relative to its own past.
Verdict
The evidence leaves this question genuinely open. For the "execution slip" reading: management's attribution is specific, a third of US restaurants had not adopted the new pricing, and the multiple already assumes a slower path. For the "reset" reading: 2025's US growth was price-led, traffic has not yet been shown to recover, and the comeback record says lifts fade. Confidence should be set by guest counts, not by comparable sales. A quarter of positive US traffic would favour the slip reading. Another quarter of price-led growth with negative traffic would favour the reset.
Whatever the answer, management did not wait to find out. Six weeks later, it walked onto the Investor Day stage with a plan that went straight at the franchisee's wallet.
V. NEXT: $8.5bn to Keep the Tenants Solvent
Think about the Investor Day from the point of view of a multi-unit franchisee who owns, say, a dozen restaurants in the Midwest. Food and wages are higher than they were three years ago. The value programme asks for lower menu prices. The corporation wants remodels, new kitchen equipment and drive-through upgrades. The franchisee's margin is squeezed from both ends. Then the corporation announces a plan that offers, in plain terms, to share some of the pain.
What was announced
The headline was about $8.5bn of "NEXT partnering support" through 2036.1 About $5bn of that would come by 2030, split between rent relief and capital support.1 On top of that, management planned about $1.5–2bn of additional capital spending, with a baseline of roughly $3bn a year of capex across 2027–2030.1 The company estimated that a franchisee who partners under the programme would see a payback of roughly four years.1
Management also set an ambitious target alongside the relief: a "low-to-mid 50%" operating margin by 2030, against about 46% in 2025.13 It targeted free cash flow conversion of "mid-to-high 80%" of net income, up from about 84% in 2025.13
The tension in plain English
Here is the problem. Rent is the largest piece of franchised revenue, which in turn produces about 90% of restaurant margins. The relief package reduces that rent for years. Yet the company says operating margin will rise by perhaps five to eight percentage points over the same period. Both cannot happen unless something else does a lot of work.
Management's answer is a combination of efficiency and growth. On efficiency, McDonald's has been running a restructuring called "Accelerating the Organization", which aims to cut corporate overhead and speed decisions.3 On growth, the plan rests on more restaurants, better traffic and higher sales per store, which raise the percentage rent even as the percentage itself is trimmed. If sales rise enough, a smaller slice of a bigger pie can still be more dollars.
The release gave no separate target for franchised margins.1 That is the number that would show whether the relief is being paid for by growth or simply absorbed. Without it, investors are being asked to trust the total margin target, which also benefits from refranchising, efficiency and mix, without being able to see the piece most directly affected.
Two statements that don't quite fit
On the second-quarter call, the chief financial officer said franchisees still had "a lot of borrowing capacity".7 Six weeks later, the company committed billions to supporting them. The two statements can both be true. Franchisees may be able to borrow, but borrowing to fund remodels at tight store margins may not earn an attractive return, and the corporation may prefer to share the cost rather than see remodels delayed. But the juxtaposition is worth noting. A company does not usually offer $5bn of relief to customers it describes as financially comfortable.
Reinvestment, not harvest
There is a bullish reading of all this. McDonald's is not harvesting its system. It is spending more on it. Capital expenditure rose about 21% in 2025 to about $3.4bn, roughly 12.6% of revenue.3 The company opened 2,276 restaurants and closed 396 that year.3 For 2026 it guided to capex of about $3.7–3.9bn and about 2,600 gross openings.35 A business preparing for decline does not do that.
The bearish reading is that rising capex, rent relief and slowing traffic all hit at once. Each dollar of capex and each dollar of rent relief comes from the same pool of cash that funds dividends and buybacks. Section VI follows that cash.
Restructuring that recurs
One more detail deserves scrutiny. "Accelerating the Organization" charges were about $221m plus $70m in 2024, about $229m in 2025, and about $250m expected in 2026, of which about $98m came in the first half.35 A restructuring charge that appears every year for three years is not really one-off. Investors comparing "adjusted" earnings that exclude these charges should remember that the cash leaves the company either way.
Technology at its proper size
Delivery is available at roughly 41,000 restaurants.3 The loyalty programme and app are now part of how McDonald's runs value offers, and they matter to franchisee economics because they shape which deals are offered and to whom. But the company does not report a separate revenue or profit figure for digital or artificial intelligence that would justify treating them as a standalone growth engine. They are tools inside the system, not a separate business.
Verdict
The margin target and the rent-relief schedule pull in opposite directions. Management's framing, that relief plus efficiency plus growth will lift margins, is a forecast, not a demonstrated result. The narrowed claim is this: the margin holds or rises only if guest counts and unit growth carry the load. That remains unproven, and it should stay open until franchised margin dollars are reported against the relief schedule across the next several quarters.
If the operating plan is a bet on the franchisee, the financial plan is a bet on the balance sheet. That is where the cash goes next.
VI. Where the Cash Goes: Dividends, Buybacks and Negative Equity
At the end of 2025, McDonald's held about $774m of cash.6 For a company with about $27bn of revenue, that is almost nothing, roughly ten days of sales. Against it sat what the fact sheet labels about $54.8bn of borrowings.6 Taken at face value, it looks like a company living on the edge. Look more closely and it is a deliberately designed machine for passing cash to shareholders.
What the borrowings really are
The $54.8bn figure combines two quite different things. About $40.0bn is financial debt: bonds and loans.3 The rest, roughly $14.7bn, is lease liabilities, the accounting value of the long-term rents McDonald's pays on sites it leases rather than owns.35 Many of those leases are matched by subleases to franchisees, so the company is often a middleman: paying rent to a property owner and collecting a larger rent from the operator.
The financial debt is conservatively structured. About 97% is fixed rate, with a weighted average interest cost of about 4.0%.3 The credit ratings are BBB+ from S&P and Baa1 from Moody's, solidly investment grade.3 The company has a $15bn authorised borrowing facility with about $10.3bn still available, plus a $5bn commercial paper programme.3 Its financing documents contain cross-acceleration provisions and limits on subsidiary mortgages, and no covenant breach has been disclosed.3
A rough leverage check: financial debt minus cash is about $39.2bn, against 2025 EBITDA of about $14.6bn.6 That is about 2.7 times earnings before interest, tax, depreciation and amortisation. Add the leases and it rises to about 3.7 times. That is manageable for a business with stable cash flow, but it is not trivial, and interest expense has been climbing. It rose from about $1.36bn in 2023 to about $1.58bn in 2025.3
Profit into cash
The good news is that McDonald's profits arrive as cash. Over the twelve years from 2014 to 2025, cash from operations totalled about $92.4bn, about 123% of net profit.6 The gap above 100% is mostly depreciation, which reduces reported profit but does not consume cash. In 2025, cash from operations was about $10.6bn and free cash flow, after capex, about $7.2bn.6
Where the free cash went
Over the same twelve years, free cash flow totalled about $65.1bn. About $45.8bn of it, roughly 70%, went out as dividends.6 Buybacks took much of the rest, plus borrowed money and refranchising proceeds. That is how equity went negative while the company stayed solidly investment grade.
In 2025, the dividend alone cost about $5.1bn, comfortably covered by free cash flow of about $7.2bn.6 The dividend has been the anchor. Dividends per share rose from about $6.23 in 2023 to about $6.78 in 2024 and about $7.17 in 2025.3 The quarterly dividend was raised about 5% to $1.86.3 Over the past twelve years, the payout ratio ranged from about 52% to about 79% of net profit, with a median of about 60%.6
The shock absorber
Buybacks tell a different story. They were about $3.1bn in 2023, $2.8bn in 2024, $2.0bn in 2025 and $1.3bn in the first half of 2026.35 That is a decline of about a third from 2023 to 2025. Meanwhile, capex is rising, interest is rising, and the relief package will reduce rent income.
Here is the arithmetic in its simplest form. In the first half of 2026, the company paid about $2.6bn in dividends and about $1.3bn in buybacks, and spent about $1.5bn on capex.5 Free cash flow has to cover all of that or the debt rises. If capex goes up by $300–500m a year and rent relief removes hundreds of millions more by the end of the decade, something has to give. Management is not going to cut the dividend; it is the brand's promise to income investors. The flexible item is the buyback.
So the verdict on the shareholder-return model narrows rather than breaks. Cash conversion is sound and the debt is manageable. But the slack is thinner than it was. The honest description is "intact, with buybacks as the shock absorber". A bigger dividend and bigger capex cannot both be fully funded without the buyback shrinking further or debt rising.
Receivables as a clue
One quieter number hints at franchisee health. Receivables measured in days of revenue rose from about 16 in 2014 to a peak of about 42 in 2018, and stood at about 33 in 2025.6 Most of that rise reflects the shift to franchising: when franchisees owe rent and royalties, the receivable balance grows relative to revenue. The company does not split the balance in a way that shows whether franchisees are paying more slowly. Investors should watch it as a clue, not a conclusion.
Currency
About 39% of McDonald's debt is in foreign currencies, deliberately, to match its overseas cash flows; the largest net asset exposures are in Australian dollars, sterling and Polish zloty.3 Currency added about $198m to operating income in 2025 after a net cost of about $41m in 2024.3 Currency swings move earnings per share from year to year. They do not change the thesis.
The capital-allocation test
The company's stated approach is narrow: buy back stock, hold land and refranchise, rather than build a portfolio of brands. That focus is itself a lesson learned from earlier diversification that was later unwound. The test for the coming years is not whether McDonald's makes a clever acquisition. It is whether money spent on rent relief and remodels earns more than the buybacks it displaces. That is a harder question to answer, and the company will need to disclose more to let investors answer it.
If the balance sheet is the machine, the boardroom is where the people running it are held accountable. In May 2026, shareholders sent a message.
VII. The Vote That Went Against the CEO (Sort Of): Pay, Chair and Credibility
On 20 May 2026, McDonald's held its annual meeting. Most of it was routine. Twelve directors stood for election, the auditor was ratified, executive pay was approved. But one number stood out. Chris Kempczinski, who serves as chairman, president and chief executive, drew about 38.8m votes against his re-election, the largest dissent of any of the 12 nominees.9 He still won comfortably, with about 465.3m votes for.9 But the next-highest dissent was about 23.8m votes, against Miles White.9
At the same meeting, a shareholder proposal to require an independent chair received about 109.7m votes for and about 390.2m against, roughly 22% support.9 A proposal on written consent drew about 210.2m for and about 291.8m against.9 The auditor, EY, was ratified with about 564.4m votes for.9
Pay in a year traffic fell
Say-on-pay passed easily, with about 478.2m votes for and about 24.6m against, roughly 95% support.9 Kempczinski's reported 2025 pay was about $20.6m, up from about $18.2m in 2024, a rise of roughly 13%.10 Most of it was equity: about $8.0m in stock awards and about $8.0m in option awards, plus a salary of about $1.55m and a cash incentive of about $2.37m.10
The pay rise came in a year when US comparable sales grew mainly through price, not traffic, and before the 2026 traffic problem surfaced.3 Shareholders broadly accepted the pay structure. The dissent was directed at the combined chair-CEO role and at the CEO personally, not at the pay framework.
Who is the CEO?
Kempczinski joined McDonald's in 2015 and became CEO in late 2019 after his predecessor was dismissed over a personal conduct issue, a governance event that is background to this story rather than its subject. His tenure since then has had three defining features. First, he continued the refranchising model and expanded unit growth, including the 50,000-restaurant ambition. Second, he oversaw the "Accelerating the Organization" restructuring. Third, he presided over the value-pricing problem that management itself called an execution failure.7
Credibility through behaviour
The best test of management credibility is not what it says but how its forecasts have held up. On that measure the recent record is mixed. The unit target slipped by a year. The currency guidance was cut. The value miss was explained honestly, which counts in management's favour, but the recovery date was not given. That pattern is common for a large company in a tough consumer market. It is not the pattern of a team that consistently under-promises and over-delivers.
The activist stress test
Imagine a sceptical activist investor studying this company in October 2026. What would they ask?
First, disclosure. Publish the franchised margin dollars, and the rent-relief cost, separately each quarter, so shareholders can see whether relief is being paid for by growth or by the margin.
Second, capital allocation. Justify each extra dollar of capex and relief against the buyback it replaces. If remodels and relief earn less than buying back stock at 19 times earnings, say so.
Third, governance. Split the chair and CEO roles, or at least strengthen the lead independent director, given the dissent on the CEO's re-election.
None of these demands would be unreasonable. The company's answer will be visible in the 2027 proxy and in whether franchise margin disclosure improves.
Verdict
Shareholders back pay overall but have registered discontent with the combined chair-CEO role and with the CEO personally. That is not a revolt; it is a warning light. Governance looks responsive enough on pay, but less so on board structure. The 2027 votes will show whether the warning was heard.
Governance is about who runs the company. The moat is about why the company keeps winning, or doesn't. That is the next section.
VIII. Playbook: Moat, Five Forces and Seven Powers
Picture a franchisee sitting at a kitchen table with a 20-year lease renewal in front of them. They could take their capital and buy a Burger King franchise, open a regional chicken chain, or simply cash out. What does McDonald's give them that no one else can?
The answer starts with traffic. The arches are among the most recognised brand marks on earth, and a McDonald's site still draws more customers than most rival fast-food locations. It continues with the system: supply chains, purchasing power, marketing funds, training, equipment design and an app with tens of millions of users. And it ends with the land. McDonald's controls the site, which means the franchisee's choice is not just "which brand" but "which brand on which corner". The best corners are often already McDonald's.
Porter's five forces
Buyer power (consumers): low individually, high collectively. A single customer has no leverage, but switching costs are close to zero. If Wendy's offers a better deal this week, the customer can drive past the arches. The 2026 value miss is direct evidence that consumer price sensitivity is real.
Buyer power (franchisees): high, and rising. Franchisees are both customers of McDonald's (they buy the right to operate) and the source of its profit pool. The relief package shows that when franchisee economics tighten, operators have bargaining power, and the corporation has to respond.1
Supplier power: modest. McDonald's scale in beef, potatoes, chicken and packaging gives it significant buying power, and it audits its suppliers.3 Commodity inflation is a risk, but mostly to the franchisee's margin, which passes it back to the corporation indirectly.
Threat of substitutes: meaningful. Delivery apps let consumers order from thousands of restaurants. Convenience stores sell cheap hot food. Chicken specialists have taken share. The "substitute" for a McDonald's meal is no longer just another burger.
Rivalry: intense. Every major chain is fighting for the same value-conscious customer, and every one of them can copy a promotion within weeks.
Hamilton Helmer's seven powers
Scale economies: real. With about 46,000 restaurants, McDonald's spreads advertising, technology and supply-chain costs over a base no rival matches.5 Delivery availability at roughly 41,000 restaurants is a by-product of that scale.3
Branding: real, but bounded. The brand allows premium site rents and consistent traffic. But branding power does not translate into unlimited pricing power, as 2026 showed.
Counter-positioning: historical. The landlord model was a counter-position against chains that simply sold franchises. Most rivals have now copied parts of it, so the advantage is narrower than it was.
Cornered resource: the land. Control of thousands of prime sites, many owned outright, is the most durable advantage. A rival can copy the menu but not the corner.
Switching costs, network effects, process power: weak to modest. Consumers face no switching cost. The app has some network characteristics but is not a true network effect. Operational know-how is real but not unique.
Falsification: the record of past differentiators
McDonald's has launched many supposed game-changers that faded. All-day breakfast lifted sales for about two years. A plant-based burger trial in several markets did not become a major product. A test of automated drive-through ordering technology was wound down. None of these was a disaster. But together they show that innovation pilots at McDonald's rarely turn into lasting revenue advantages. Pilots are not revenue.
Verdict
The moat is real, but it is narrower than the brand suggests. Scale, the brand and control of the land are evidenced and durable. Pricing power is weaker than the inflation years implied. And the main counter-power sits with the franchisees, who are both the moat's operators and its pressure point. The landlord model is the moat. The tenants are the risk.
With the moat mapped, it's time to put the bull and the bear in the same room.
IX. Bear Case vs. Bull Case
Two analysts look at the same Investor Day slide. One sees a 2030 operating margin of low-to-mid 50%. The other sees $5bn of rent being given away. Both are reading the same page.1
The bull case
The bull starts with demand. People keep eating at McDonald's in good times and bad, and its scale makes it the default choice for value-conscious consumers once the pricing is fixed. The income stream is mostly rent and royalties, with minimum rents protecting the floor. Unit growth is accelerating, with about 2,600 gross openings planned for 2026 and a 50,000-restaurant target for 2028.37
The valuation is undemanding by the company's own standards: about 18.9 times earnings, against a five-year median of about 25.5 times.2 The dividend yield is about 3.2% and the free cash flow yield about 4.7%.2 On enterprise value, the shares trade at about 14.6 times EBITDA.2 For a bull, that is a high-quality business at an ordinary price, with management having diagnosed its own mistakes.
What has to be true for the bull: US guest counts must turn positive within the next few quarters, unit growth must hold, and the relief must be offset by growth so that franchised margin dollars keep rising.
The bear case
The bear starts with growth. Revenue has grown about 0.6% a year over ten years.6 Recent US sales growth has been price-led, and traffic is now negative.7 The value fix may help, but the company's own history says comebacks fade. Rent relief directly reduces the highest-margin income stream. Buybacks are shrinking, debt is about $40bn, and equity is negative. The 2030 margin target depends on optimistic assumptions the company has not broken down.
What has to be true for the bear: franchised margin dollars fall as relief is applied, and US traffic does not recover.
The risk radar
Only a few risks really matter. First, consumer value-seeking: if lower-income customers keep pulling back, traffic suffers across the industry. Second, franchisee cost inflation, especially labour and food, which squeezes operators and makes relief more necessary. Third, refinancing and interest cost: with about $40bn of debt, every percentage point of higher rates on refinanced bonds adds hundreds of millions in interest over time. Fourth, execution on the restructuring and the relief programme. Currency swings matter for reported earnings but not for the thesis.
The KPIs that matter
Two numbers will decide the story.
US comparable guest counts. The latest reading was negative in the second quarter of 2026, with July US comparable sales slightly negative.7 This is the single best measure of whether the value fix is working.
Franchised margin dollars. About $13.9bn in 2025.3 Watch whether they rise or fall as rent relief begins.
A third, optional check: free cash flow against dividends plus buybacks. In the first half of 2026, dividends and buybacks together were about $3.9bn.5
Verdict
Neither case is resolved by the evidence. The bull needs traffic and unit growth to carry the margin. The bear needs relief to eat into it. The shares at a 32% discount to their high already price some of the bear case. The next four quarters will show which analyst read the slide correctly.
What the next four quarters cannot change is what McDonald's story teaches. That's the next section.
X. Lessons for Founders and Investors
Own the ground your customers stand on. Harry Sonneborn's idea in the 1950s, to control the land and sublease it, turned a burger franchise into one of the most durable profit machines in business.4 Seventy years later, the rent cheque is still the largest piece of McDonald's franchised income. The lesson is not about real estate. It is about owning the asset that your partners cannot leave.
Margin is a promise from someone else's profit. McDonald's 46% operating margin is only as good as the franchisee's willingness and ability to pay. The 2026 relief package proved that a landlord's margin has a ceiling, and that ceiling is set by the tenant's P&L.
Buybacks are not growth. A decade of near-zero revenue growth and mid-single-digit profit growth, with negative equity as the residue, is a reminder that financial engineering can lift per-share numbers for a long time. It cannot create customers.
Fix the value proposition before you fix the margin. When management admitted in August 2026 that it "simply didn't execute" on value, it put its finger on the real constraint.7 No amount of rent optimisation helps if the customer drives past.
XI. Epilogue: The Next Four Quarters
Tonight, McDonald's sits at a crossroads it has built for itself. The shares trade near their lowest level in a year. The franchisee relief plan is announced but not yet applied. The value fix is in progress, but traffic has not turned. The next twelve months will decide which story was true.
The first test comes with the third- and fourth-quarter 2026 results. If US guest counts turn positive and stay positive, the "execution slip" reading gains weight, and the multiple has room to recover toward its history. If guest counts stay negative, the "reset" reading becomes the consensus, and the margin target looks like an aspiration.
The second test is the rent-relief schedule as it is first applied. Investors will want to see franchised margin dollars reported clearly, quarter by quarter, against the relief. If the dollars rise, the landlord's bet on its tenants is paying off. If they fall, the margin target is in trouble.
The third test is capital allocation in 2027. Will buybacks shrink further to fund dividends and capex? Will debt rise? The answer will show whether the shareholder-return model is intact or merely surviving.
The fourth test is the 2027 annual meeting. Another year of rising CEO dissent, or a stronger independent-chair vote, would signal that shareholders want change. A calm meeting would suggest the board has done enough.
And the fifth test is the 50,000-restaurant target in 2028. Hitting it would confirm that unit growth can carry the system. Missing it again would undermine the growth story at its foundation.
Each outcome maps onto the central questions. Positive traffic and rising franchised margin dollars would answer the first three questions in the bulls' favour. Falling margin dollars and shrinking buybacks would answer them for the bears. Governance will follow performance either way.
The tension that remains is simple to state and hard to resolve: can a landlord cut the rent and still raise its margin?
XII. Outro
Go back to that Investor Day slide one last time. For seventy years, McDonald's explained to anyone who asked that it was not really in the food business. It was in the real estate business. On 23 September 2026, the real estate business wrote a cheque to keep the food business healthy.
That is the whole story in a single image. McDonald's is the only company whose best customer is also its biggest risk: the franchisee who pays the rent, carries the cost, and now needs the landlord's help to keep the lights on under the arches.
References
-
McDonald's investor update, Exhibit 99.1 — SEC, 2026-09-23 ↩↩↩↩↩↩↩↩↩↩↩
-
McDonald's Corporation Form 10-K for FY2025 — SEC, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Ray Kroc, Not the Founder, but a Financial Engineer — Restaurant Finance Monitor ↩↩↩↩↩
-
McDonald's Corporation Form 10-Q for the quarter ended 2026-06-30 — SEC, 2026 ↩↩↩↩↩↩↩↩↩↩
-
McDonald's SEC filing index (all 10-Ks, 10-Qs, 8-Ks, proxies) — SEC EDGAR ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
McDonald's Q2 2026 earnings call transcript — Motley Fool, 2026-08-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
McDonald's Form 8-K, 2026 annual meeting voting results — SEC, 2026-05-20 ↩↩↩↩↩↩↩
-
McDonald's 2026 proxy statement (DEF 14A) — SEC, 2026-04-07 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube