Marriott International: The Company That Owns Almost Nothing and Gets Paid on Everything
I. Cold Open: The Company With 148,000 Employees and 414,000 Associates
Picture a Courtyard lobby on a Tuesday night. The carpet is the house pattern, the lanyard says Marriott, the screen behind the desk runs Marriott software, and the guest at the counter is reading out a Bonvoy number from an app. Almost nothing in that scene belongs to the company whose name is on the building. The building belongs to a real-estate investment trust, a family office or a regional developer. The person behind the desk is very likely on the owner's payroll. What travels back to Bethesda, Maryland, is a percentage: a slice of every room sold, a slice of every meal, and sometimes a slice of the hotel's profit.
Marriott International describes its workforce as about 414,000 associates. Only about 148,000 of them are employed by Marriott. The other 266,000 or so work for hotel owners, in hotels that Marriott manages on their behalf1. That single line from the annual report is the best way into this company. It is a brand, a reservation system, a loyalty program and a management playbook. The bricks, the mortgages and, mostly, the wage bills belong to someone else.
That has an odd effect on the income statement. In the second quarter of 2026, Marriott reported about $7.1 billion of revenue2. Only about $1.6 billion of that was fees, roughly 22%. About $5.1 billion, roughly 71%, was "cost reimbursement": salaries and other costs that Marriott pays at managed and franchised hotels and then bills straight back to owners, at little or no profit2. It is real money moving through Marriott's accounts, and it is reported as revenue under accounting rules, but it is not what investors are paying for.
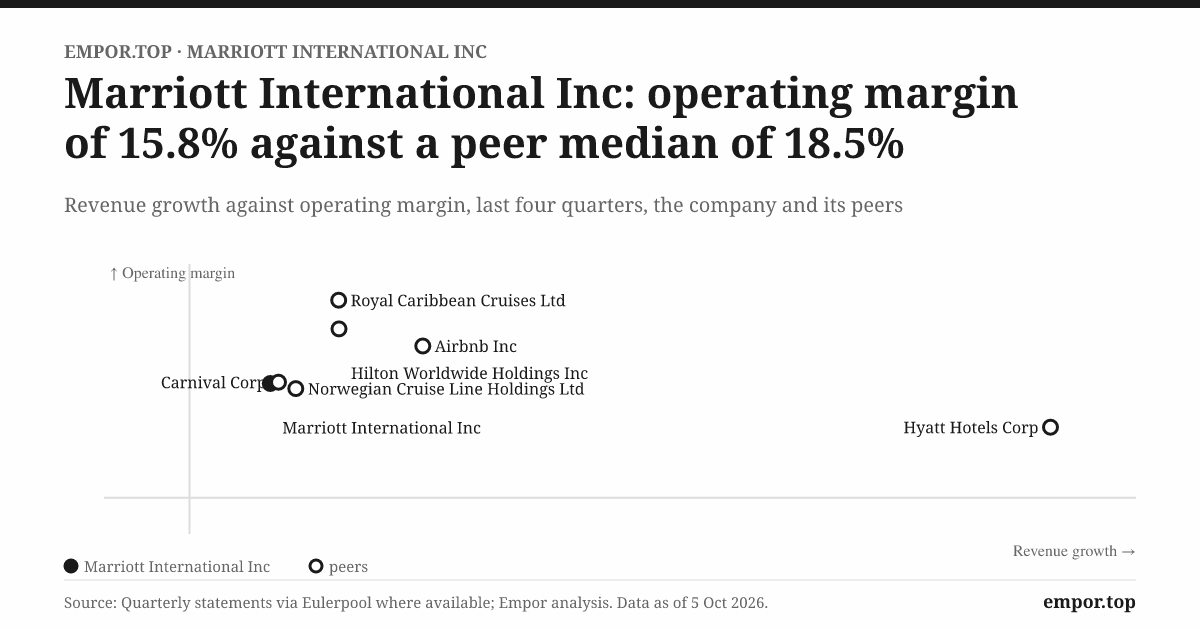
This is the reader's first trap. Marriott's operating margin for 2025 was 15.8%1. For a business that collects tolls on other people's hotels, that sounds pedestrian. It is pedestrian only because the denominator is inflated by billions of dollars of pass-through payroll. Strip the reimbursements out and the fee engine is one of the most profitable machines in consumer services. Leave them in and the company looks like a middling services contractor. Neither picture is the economic truth on its own, and this story will keep the two apart.
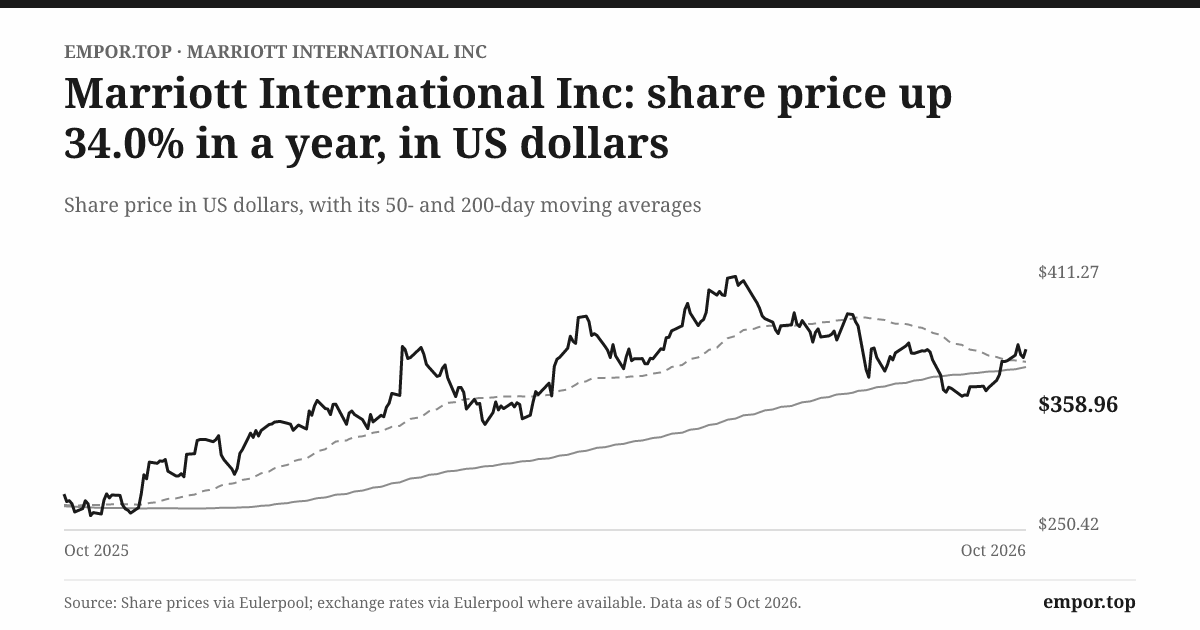
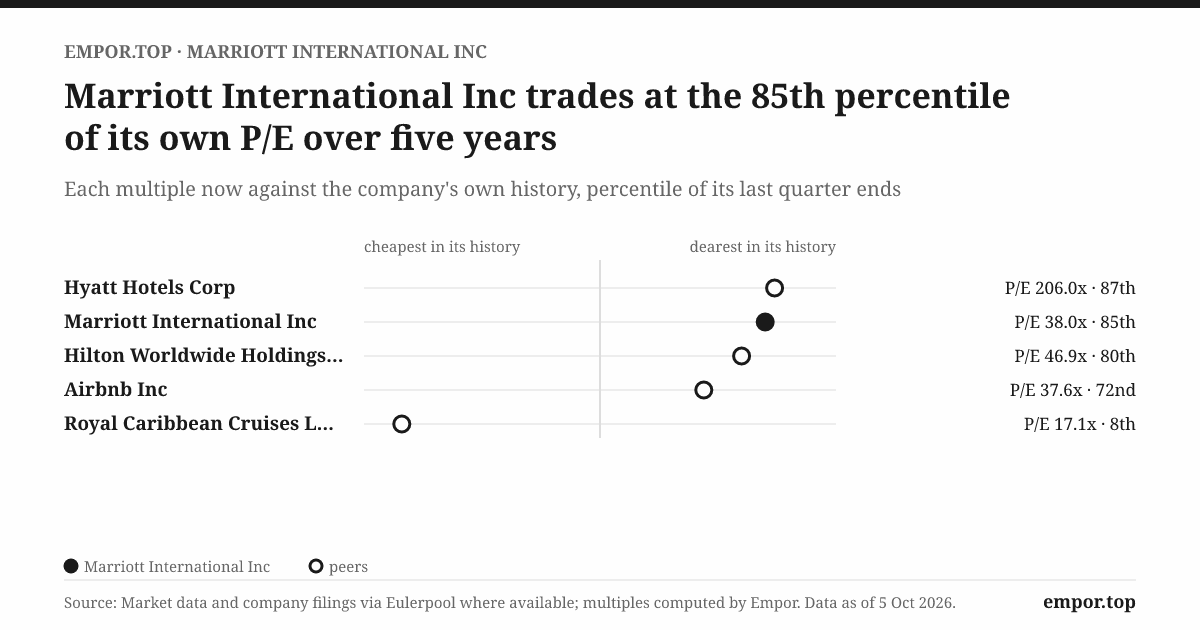
The market has already made up its mind about which picture matters. On 5 October 2026, Marriott was worth about $98 billion at $358.96 a share3. That is about 38 times trailing reported earnings, against a five-year median of about 25 times. Investors are paying a premium that is roughly 50% above the company's own recent history, for a business whose reported net profit has gone sideways for three years.
So four questions run through this story. Is that premium justified by fee growth when reported profit has stalled since 2023? What sits in the gap between the "adjusted" earnings Marriott emphasises and the earnings it actually reports? Can a company with negative shareholders' equity and capex guided to roughly double keep sending more than $4.5 billion a year back to shareholders? And has the risk of owning hotels really gone away, or has it simply moved into guarantees, owner relationships and the loyalty program?
The answers start, improbably, with a nine-stool root beer stand. They end with a business that holds almost no buildings at all. In between is one of the cleanest experiments in corporate history about what happens when a company decides that owning things is the problem.
 Subscribe on LinkedIn
II. The Stand, the Hot Shoppes and the Pivot to Rooms (1927–1972)
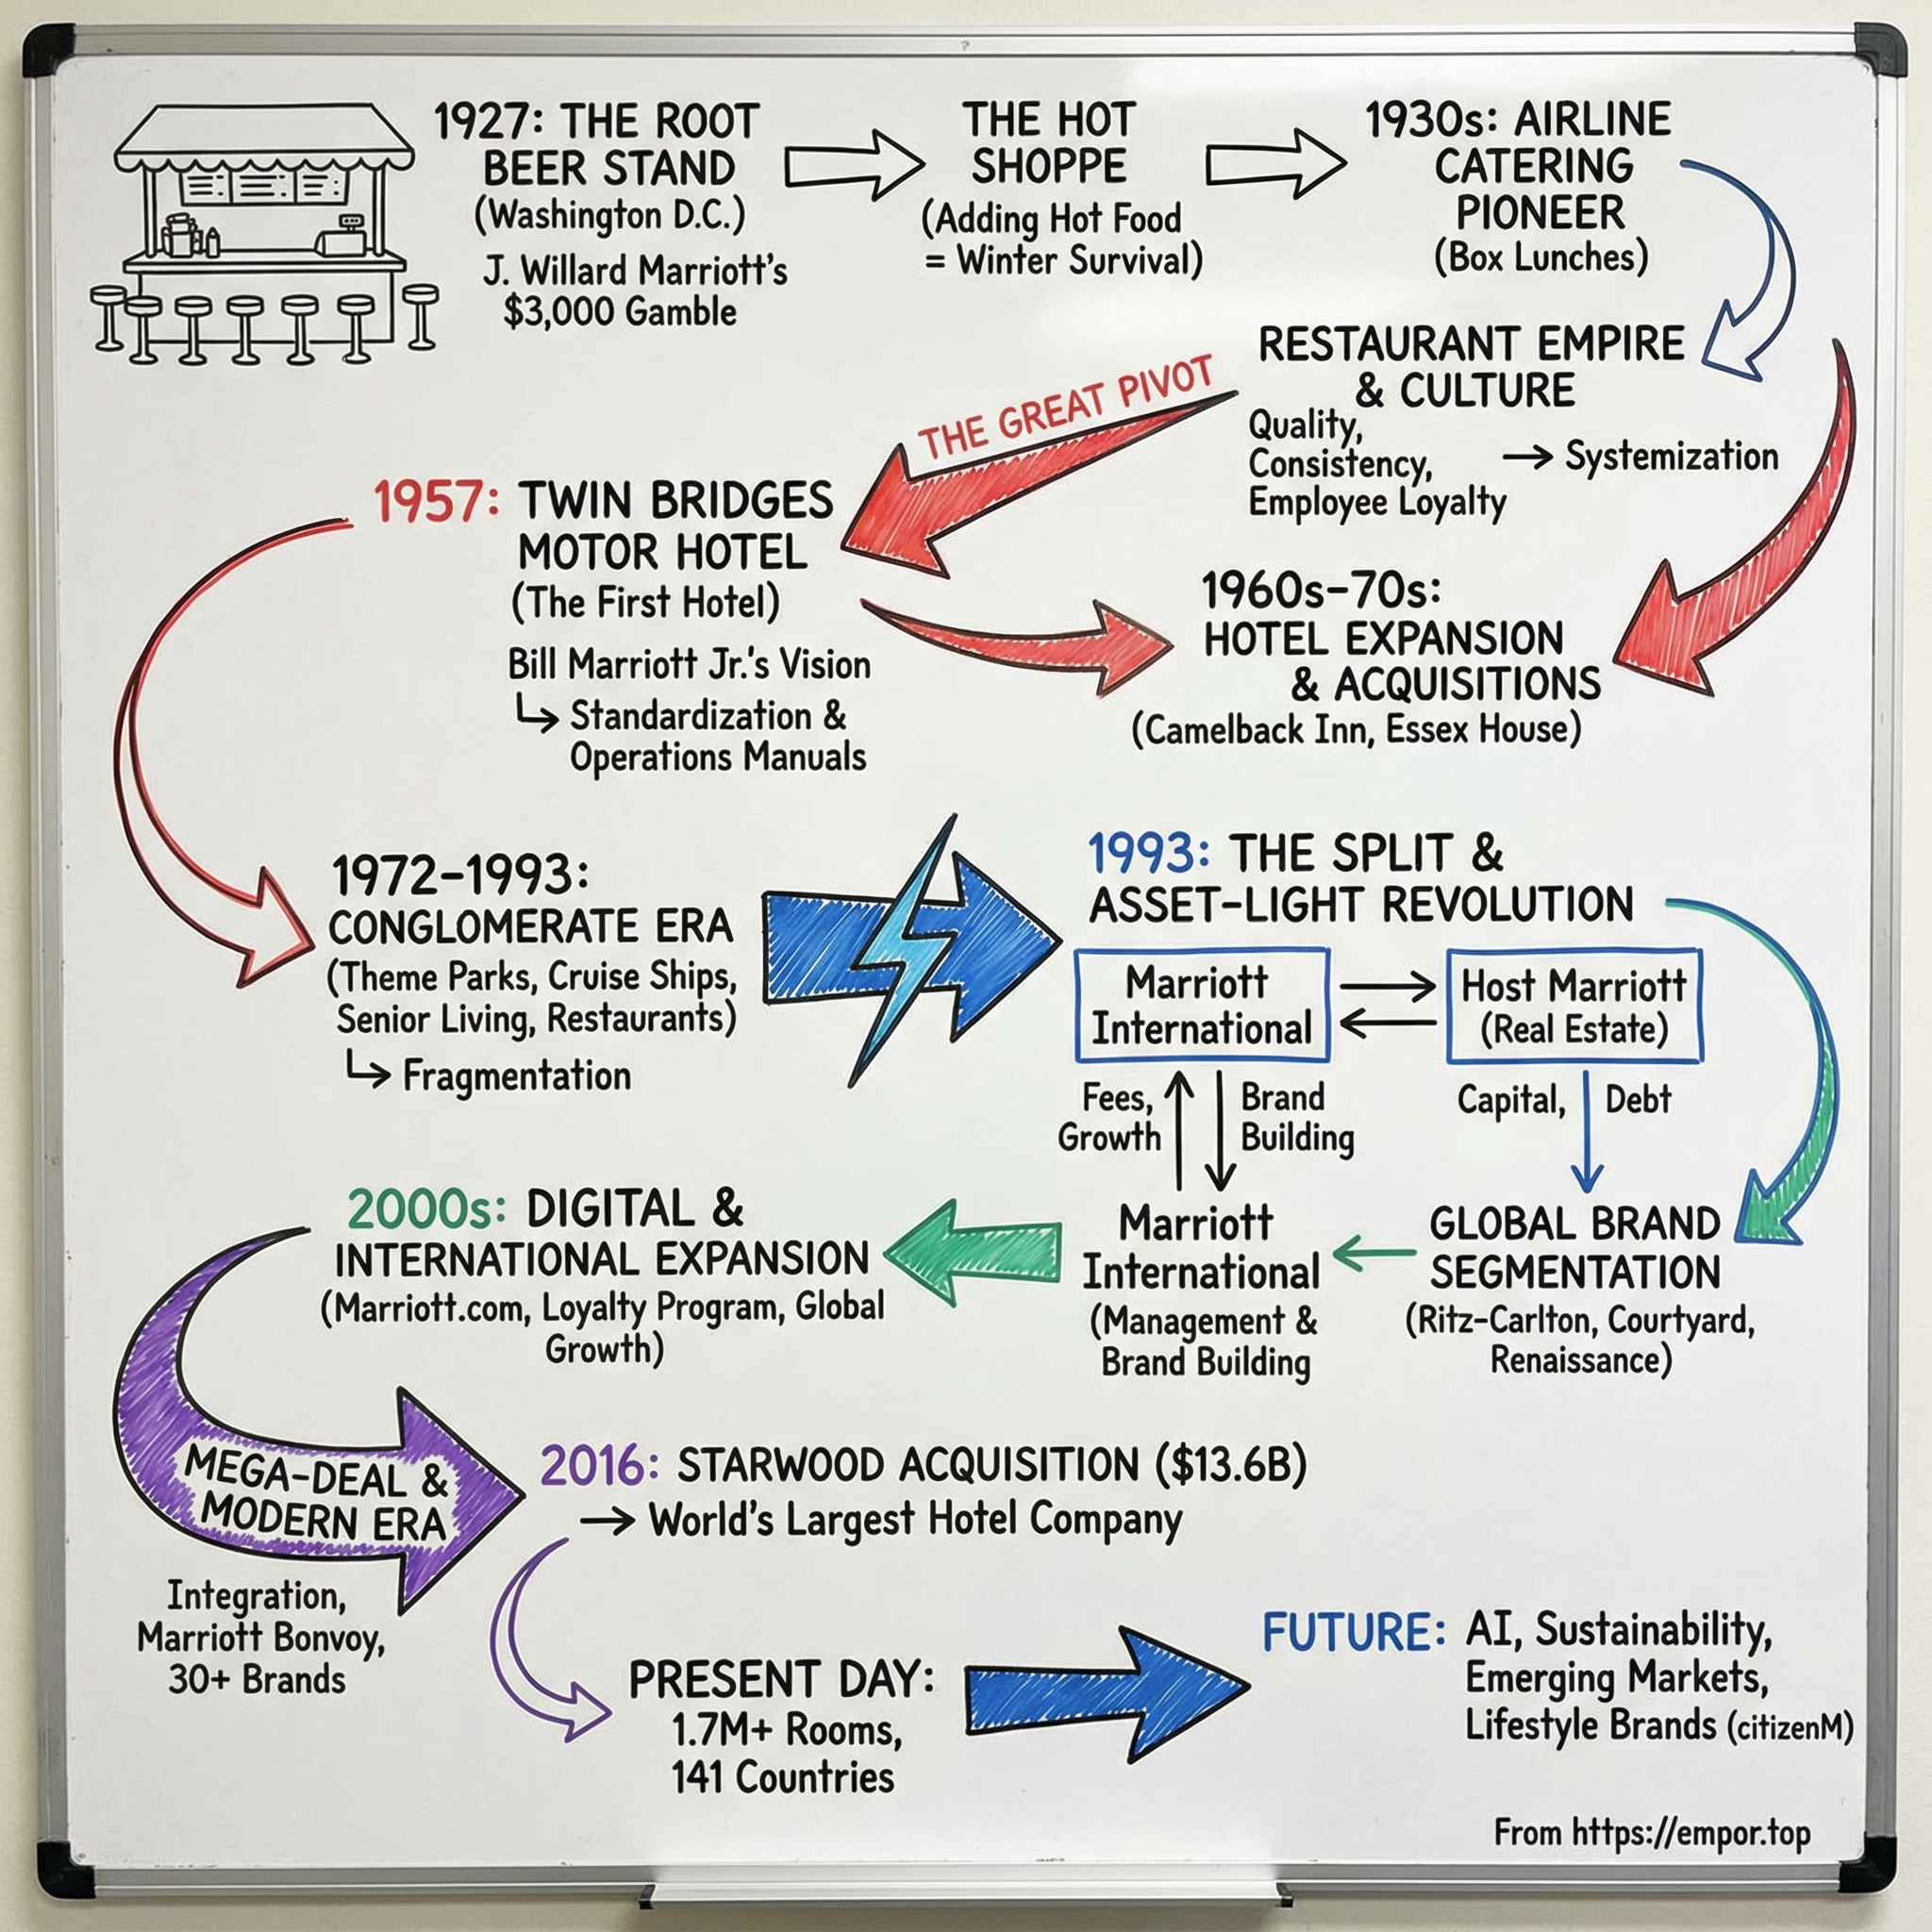
On 20 May 1927, a young Mormon from Utah named J. Willard Marriott and his partner opened a nine-stool A&W root beer stand on 14th Street in Washington, D.C., with about $3,000 of capital[^4]. Washington summers are brutal, and root beer sold. Washington winters are cold, and root beer did not. Rather than close for the season, Marriott and his wife Alice added hot food, chili and tamales on recipes borrowed from the Mexican embassy's cook, and the stand became the Hot Shop, then the Hot Shoppes[^4].
The detail that matters for investors is not the menu. It is the reflex. The first product hit a seasonal wall, and the founder changed the product rather than defend it. That reflex, pivoting from a business that works to one that might work better, recurs three times in this story.
Hot Shoppes grew into a regional restaurant chain known for curb service and obsessive standards. Willard Marriott was famous for touring kitchens, writing rules and visiting restaurants unannounced. By the early 1950s the company ran dozens of restaurants, and it went public in 1953[^4]. In 1937 it had already spotted something odd at Washington's Hoover Field: passengers buying Hot Shoppes boxed lunches to take on planes. Marriott began supplying airlines directly, which became In-Flite catering[^4]. Then came cafeterias for government agencies and institutions.
Those contract-food businesses were the quiet precursors of everything Marriott is today. In airline catering and institutional food, Marriott was running an operation inside somebody else's business, to somebody else's budget, for a fee. It learned to write standards that other people's employees could follow and to get paid for consistency rather than for ownership.
In 1957 the company opened its first hotel, the Twin Bridges Marriott Motor Hotel in Arlington, Virginia, just across the Potomac from the capital[^4]. It was a bet on cars and, soon, on jet travel; the airport hotels that followed sat exactly where the new traveller would land. Willard's son, J.W. "Bill" Marriott Jr., ran the hotel division and became president in 1964. In 1967 the company renamed itself Marriott Corporation[^4]. Food had paid for the rooms. Within a generation, rooms would eclipse food.
Bill Marriott was a different kind of founder's son. He had served in the Navy, was famous for visiting hundreds of hotels a year and reading guest comment cards, and kept his father's operating obsessions while dropping his father's caution about debt. Under him the company grew fast, and for a while it tried to be everything: Big Boy restaurants, Roy Rogers, cruise ships, and Great America theme parks[^4].
That conglomerate era is worth one sentence of moral, not a chapter of narrative. Marriott owned more and more, and the more it owned the more its fortunes depended on property values, interest rates and lenders. It is the cautionary tale against which the rest of the story is written. The stand had taught Marriott to run things for customers; the next lesson, learned the hard way, was that it did not need to own the things it ran.
III. The 1993 Split: When Owning Buildings Became the Problem
By the late 1980s, Marriott Corporation had become a development machine. It built hotels, sold them to investors, kept long management contracts and frequently stayed on the hook through loans and guarantees. The model worked as long as buyers kept arriving. Then the American commercial-property market collapsed. Tax law changed in 1986, savings and loans failed, and the buyers vanished. Marriott was left holding half-sold buildings and a large pile of debt[^4].
The response, announced in 1992 and completed in 1993, was radical. The company split in two. Host Marriott kept the real estate and most of the debt. Marriott International kept the management contracts, the franchise system and the brands[^4]. Bondholders sued, arguing they had been left with the weaker half, and the split was eventually settled. Whatever one thinks of how it treated creditors, the shape it created became the template for the entire industry.
To see why, it helps to understand the three ways Marriott gets paid. In a franchise, an owner runs the hotel and pays Marriott a royalty, typically a percentage of room revenue, for the brand, the reservation system and Bonvoy. In a management contract, Marriott runs the hotel for the owner and collects a base fee, also a percentage of revenue, plus an incentive fee that is a share of the hotel's profit above some threshold1. The owner pays the staff and bears the property risk; Marriott bears operating responsibility and reputational risk.
Think of it as the difference between owning a toll road and running the toll booths. The road owner carries the concrete and the debt. The operator collects a share of every car. When traffic grows, both gain; when traffic collapses, the road owner still owes the bank, and the operator merely collects less.
Three decades later, the balance sheet shows how far the idea has gone. At the end of 2025 Marriott reported total assets of about $27.5 billion, but property, plant and equipment of only about $2.9 billion1. Most of the rest is intangible: brands, goodwill and contract value, much of it from Starwood. A company that operates or franchises roughly 1.7 million rooms owns very little of the hardware12.
Yet asset-light has never meant capital-free. Marriott spends money to win contracts: key money paid to owners to sign, loans, guarantees, and an expensive technology rebuild. For 2026 it has guided capital and technology investment of $1.25 billion to $1.35 billion2. That figure matters later. For now, the point is that the toll operator sometimes pays for a booth.
The brand ladder was built on top of the split. Marriott took a stake in Ritz-Carlton in 1995 and later full control; it bought Renaissance in 1997[^4]. Fairfield, Courtyard, Residence Inn, Marriott, JW Marriott and Ritz-Carlton gave owners a flag at every price point and gave travellers a reason to stay inside one system. The brands were not mainly a collection of hotels. They were shelf space in a distribution engine.
Competitors spent the next generation converging on the same answer. Hilton, after its leveraged buyout by Blackstone in 2007, spun its owned real estate into Park Hotels & Resorts and its timeshares into Hilton Grand Vacations in 20174. Hyatt, long one of the more asset-heavy chains, committed to selling hotels and moving toward fee income5. The industry now argues about who runs the best fee machine, not about whether to run one.
The split solved the problem that had nearly sunk the company: it took property values and mortgages off the shareholders' plate. The next question was what to do with the clean structure. The answer, eventually, was to buy the biggest rival in the business.
IV. The Starwood Bet: Was $13bn a Bargain or the Top of the Market? (2015–2018)
In November 2015, Marriott agreed to buy Starwood Hotels & Resorts, the owner of Westin, Sheraton, W, St. Regis and Le Méridien. It should have been a tidy friendly deal. Then, in March 2016, a consortium led by China's 安邦保险 Anbang Insurance made a higher unsolicited offer, and a rare bidding war broke out over a hotel company. Marriott raised its offer, Anbang withdrew, and the deal closed in September 20166.
The man who won it was Arne Sorenson, Marriott's first chief executive from outside the family. A lawyer who had come to the company through its legal work, he had been CEO only since 2012. He was candid and data-minded, and he bet his tenure on scale: more brands, more rooms, more members and more owners in one system. Sorenson died of pancreatic cancer in February 20217.
The financial footprint of the deal is impossible to miss. Revenue jumped from about $15.4 billion in 2016 to about $20.5 billion in 2017, a 33% leap that no organic plan could have produced1. Operating margin rose from about 9% to about 12% the following year. Total assets quadrupled, from about $6 billion to about $24 billion, and borrowings roughly doubled, from about $4 billion to about $8.5 billion, around the closing1. Shareholders' equity swung from negative to about +$5.4 billion because Marriott paid largely in its own shares.
That is the regime break that every Marriott growth rate has to respect. The five-year revenue growth rate of roughly 20% a year is a COVID artefact: it measures the climb out of a 2020 trough. The ten-year rate of about 6% a year is the fairer base, and even that includes Starwood. Marriott's organic growth engine is more modest than its headline growth history suggests.
Was the price a bargain? The honest answer is that it was neither obviously cheap nor a peak-market blunder. Benchmarked against the obvious disaster of the era, Blackstone's buyout of Hilton in 2007 at the top of the credit bubble, Marriott bought at a calmer point in the cycle and with stock rather than borrowed money. It also bought something that compounding later revealed to be valuable: Starwood Preferred Guest, whose members became part of Bonvoy. Operating margin in 2025 was about 15.8%, against about 9% before the deal, though fee mix, pandemic cost cuts and pricing all contributed1. The multiples paid and the delivered synergy dollars are not set out in Marriott's current filings, so a precise return on the deal cannot be calculated from them. On the evidence of scale gained and margins reached, the bet looks like it created value; the size of that value remains a judgement.
Integration is the part that still is not finished. Merging two reservation systems, two property-management stacks and two loyalty programs is like merging two airlines' booking systems while both keep flying. Marriott combined the loyalty programs under the Bonvoy name in 2019. Yet its latest annual report still describes a multi-year transformation of reservations, property-management and loyalty technology, and lists execution of that program as a risk1. Nearly a decade after closing, the technology tail of the deal is still being paid down.
The breach that came with the database
On 30 November 2018, Marriott announced that Starwood's guest-reservation database had been breached. The intrusion had begun in 2014, two years before Marriott bought the company, and had continued undetected after the acquisition[^9]. The UK Information Commissioner's Office later found that the incident affected about 339 million guest records worldwide, including around 30 million in the European Economic Area, and fined Marriott £18.4 million in October 2020, down from a proposed £99 million[^9]. In October 2024 the U.S. Federal Trade Commission brought an action requiring Marriott and Starwood to build a comprehensive information-security program, and a parallel settlement with state attorneys general carried a $52 million payment[^10]. Class actions over the incident remain listed in Marriott's annual report1.
This is the falsification test for the Starwood thesis. The deal bought Marriott a customer database big enough to turn into a moat, and the same database turned into its largest regulatory embarrassment. The direct penalties are small next to annual net profit of about $2.6 billion1. The reputational cost is harder to measure, and the lesson is sharper: Marriott's diligence evidently tested Starwood's earnings far more rigorously than its servers. The breach does not overturn the case that Starwood was a good deal. It narrows it: the deal bought scale and a loyalty base, and it also bought legacy systems whose risks the acquirer did not see. That legacy is precisely what the still-running technology program is meant to retire.
Once the systems are merged, the question becomes what the combined machine actually sells. The answer is not hotel rooms.
V. The Fee Machine: What Marriott Actually Sells
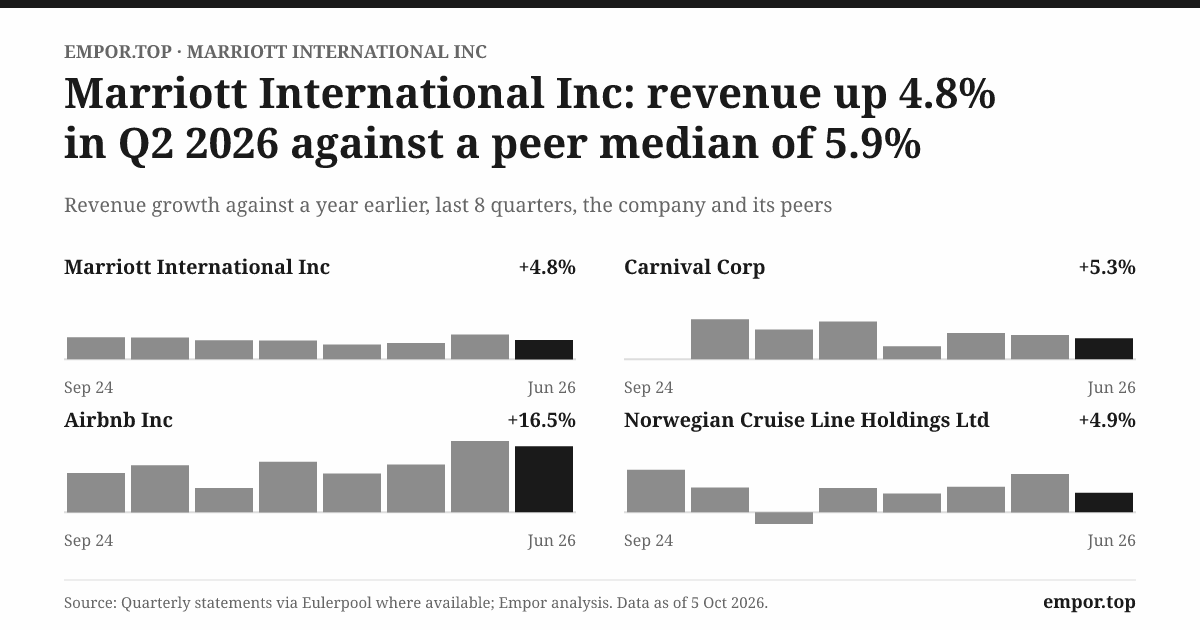
On 3 August 2026, Marriott reported its second quarter. The headline revenue growth was unremarkable, about 5%. Under the headline, the lines told two different stories. Franchise fees rose 19% to about $1.02 billion. Base management fees rose just 1% to about $343 million. Incentive management fees rose 6% to about $212 million2. And cost reimbursements of about $5.1 billion, the pass-through payroll, rose about 3% and dwarfed the lot2.
Add the three fee lines and Marriott collected about $1.58 billion in fees in the quarter, roughly 22% of reported revenue2. That is the business. The fees grew at roughly three times the pace of reimbursements, which is why reported revenue growth and reported margins both understate what is happening in the part of Marriott that earns money.
Four ways to get paid
Each fee line has its own pricing unit, and each behaves differently in a downturn.
Franchise fees are a royalty on hotel revenue, so they move with room rates and occupancy, but the owner bears all the costs. They also include fees from co-brand credit cards with JPMorgan Chase and American Express and from branded residences2. The quarter's 19% jump owed a good deal to new card agreements2. That is a contract step-up, not a sign that hotels suddenly got busier, and it will not repeat at the same rate once the new terms are in the base.
Base management fees are also a percentage of revenue, but at managed hotels, which skew to big-city and full-service properties. Their 1% growth suggests sluggish revenue at those hotels and an owner base that has been converting some managed hotels to franchise.
Incentive fees are a share of hotel profit above a threshold, often after the owner has earned a priority return. They are the most cyclical line by design: when costs rise or revenue falls, the owner's profit shrinks first and Marriott's incentive fee can drop to nothing.
Card fees are something else entirely: a payment from banks for access to a customer base. They depend on member spending and on the terms Marriott can negotiate with its card partners, which makes them more contract-driven than travel-driven.
Two engines: price and units
Every fee model has two engines. One is RevPAR, revenue per available room, which blends occupancy and room rates into a single number. The other is net unit growth, how many rooms join the system after subtracting those that leave.
In the second quarter, global RevPAR rose about 3.4%. In the U.S. and Canada it rose about 5%; internationally it fell about 0.5%2. Net rooms grew about 4.5% from a year earlier, with roughly 17,900 net rooms added in the quarter, and the development pipeline stood near 629,000 rooms, up almost 7%, with about 44% under construction2.
Put the two together and the mix is shifting. With RevPAR growth in low single digits and international markets flat to down, more of Marriott's growth now comes from adding rooms rather than charging more for them. That is a healthier kind of growth in one sense, because it compounds as long as owners keep building and converting. It is also slower to show up: a hotel under construction today may not pay a full fee for years, and a conversion brought in with key money comes with a cost.
How much do fees fall?
The fee model's downside was tested in 2020. Revenue fell by about half, and operating profit fell to about $84 million, from about $1.8 billion the year before1. Owners suffered far more; many had hotels closed while mortgages kept running. But the toll operator also discovered that a percentage of almost nothing is almost nothing. Fee models fall less than owners' profit and loss, and they recover faster, but they do fall.
Contract terms are the other half of the resilience argument. Marriott's management agreements typically run for long initial terms, often decades for managed hotels, and franchise agreements commonly run for about 20 years, with termination rights for both sides tied to performance tests and owner defaults1. Long terms protect the fee stream in a bad year. They also mean that every contract eventually comes up for renewal, and at that moment the owner can shop the hotel to Hilton or Hyatt.
The segment reporting reflects this structure. Marriott reports the U.S. and Canada and International, with owned and leased hotels as a small line. Owned, leased and other revenue was about $466 million in the second quarter2. Small as it is, it is where the quarter's $68 million impairment on a hotel sale appeared2. Even an asset-light company finds that the few assets it does hold generate most of its write-downs.
The fee lines are clearly the right way to look at Marriott. The harder question is why owners keep paying them, and whether they will keep doing so. That leads to the program on the guest's phone.
VI. Bonvoy: The Moat Argued Once
A developer in Dallas has just finished a 200-room select-service hotel near the airport. The money is borrowed and the debt clock is ticking. The developer can put a Courtyard sign on it, a Hilton Garden Inn sign, a Hyatt Place sign, or no sign at all. The developer is not really choosing a typeface. They are choosing whose customers will fill the rooms on Tuesday nights in February.
That is Marriott's sales pitch in one scene, and Bonvoy is its most persuasive slide. About 68% of Marriott's global room nights, and about 75% in the U.S. and Canada, are booked by Bonvoy members1. Across more than 30 brands and about 1.7 million rooms, Marriott can promise an owner a large stream of guests who arrive through its own channels rather than through an online travel agency charging a commission12.
What the moat is made of
Hamilton Helmer's 7 Powers framework helps sort out what is real here.
Scale economies are the clearest power. The cost of a global reservation system, a loyalty program, a sales force that calls on corporate travel managers and a technology rebuild is largely fixed. Spread over 1.7 million rooms, it is cheaper per room than for a smaller chain. Marriott can charge owners competitive fees while spending more than smaller rivals in absolute terms.
Network effects are real but weaker than the word suggests. More hotels make Bonvoy more useful to members, because points can be earned and spent in more places. More members make the flag more valuable to owners. The flywheel spins. But it is not winner-take-all: a traveller can carry a Hilton Honors card and a Bonvoy card at the same time, and many do.
Switching costs are mostly on the owner side. Re-flagging a hotel means new signs, new systems, new standards and often a new loan, and it can only be done when a contract allows. That gives Marriott a long, sticky revenue stream. It does not stop a large owner from walking at renewal.
Brand matters most at the top and bottom of the ladder, at Ritz-Carlton and at St. Regis, where the name itself carries pricing, and least in the middle, where a Courtyard and a Hilton Garden Inn compete largely on location and points.
Counter-positioning against online travel agencies is partial. Marriott's direct-booking pitch to members, through lower member rates and points, is designed to keep bookings away from Booking Holdings and Expedia. It works for loyal travellers. It does not change the fact that the agencies remain the shop window for many leisure guests.
Porter, briefly
Owners are the buyers who matter, and they have real bargaining power at the end of every contract; that caps how far Marriott can push fee rates. The online agencies are powerful suppliers of demand, and their commissions remain a cost that direct booking only partly avoids. Substitutes include Airbnb and extended-stay rentals, which compete hardest for leisure stays and longer trips. Rivalry is intense: Hilton, Hyatt, IHG and Accor fight for the same owners, and abroad Chinese chains such as 华住 Huazhu and 锦江 Jin Jiang dominate their home market. New entrants are rare at global scale, because no one can start with millions of loyalty members.
The falsification test
The claim that Bonvoy is a durable moat should be tested against the mechanism that would break it: distribution. If more travellers start their trips by asking an AI assistant or an agency to "find the best hotel near the convention center," the loyalty program's grip on the first click weakens. Marriott's own risk disclosures focus on executing its technology transformation; the company has not quantified its exposure to AI-agent booking or set out a target for direct-booking share1. The weakest link in the moat claim is therefore not the brands but the channel.
Hilton is the natural benchmark. It runs a similar loyalty program, Hilton Honors, and in recent years has reported net unit growth in the 6% to 7% range, faster than Marriott's 4% to 5%4. That does not prove Marriott is losing; Marriott's base is larger and its luxury mix higher. It does show that Marriott's advantage over its closest rival is one of scale, not structure. Hilton plays the same game with the same tools and is currently adding rooms faster.
The verdict is that the moat is real but narrower than the 68% figure makes it sound. Marriott owns a very large customer database and a cost advantage in running it. It does not own the traveller, who can hold several loyalty cards, and it does not own the owner, who can switch flags at renewal. The two KPIs that would confirm or falsify the claim are Bonvoy's share of room nights over time and Marriott's franchise-fee and net-unit growth relative to Hilton's.
Brand number 38
With more than 30 brands, where does the next one go? Marriott's answer in 2025 was citizenM, a design-led, compact-room lifestyle brand it bought for about $355 million1. Strategically, it fills a gap for younger, urban travellers. Financially, it is a rounding error next to a $98 billion market value. The bigger risk is not this deal but the habit: every new brand adds shelf space for owners and, eventually, confusion for guests.
A loyalty program is valuable only if the company can keep investing in it and in the technology beneath it. That raises the question that most worries the skeptics: where all the cash goes.
VII. Where the Cash Goes: $20bn of Free Cash Flow and a Negative Net Worth
Read Marriott's second-quarter release in one sitting and two numbers seem to belong to different companies. In the first half of 2026 the company bought back about 6.2 million shares for about $2.2 billion, and it expects to return more than $4.5 billion to shareholders for the full year2. At the end of 2025, its shareholders' equity was negative, at about -$3.8 billion1. How does a company with a negative net worth keep writing such large cheques?
The money trail
Start with what the business generates. Over the twelve years from 2014 to 2025, Marriott reported about $18.3 billion of net profit and about $24.9 billion of cash from operations, about 136% of profit1. Cash runs ahead of profit because large non-cash charges, mainly amortisation of contract and brand intangibles and stock compensation, reduce profit without costing cash. After capital spending, free cash flow over those twelve years was about $20.1 billion. Dividends took about $5.0 billion of it, roughly a quarter. Cash on the balance sheet barely moved. Nearly everything else went into buying back stock.
That is the source of the negative equity. It is not accumulated losses; Marriott has been profitable in every year except 2020. It is the accounting result of buying back shares year after year for more than the book value they were recorded at. In 2016, after Marriott issued stock to Starwood holders, equity stood at about +$5.4 billion. By 2025 buybacks had taken it below zero again1. Return on equity is therefore meaningless, and debt-to-equity ratios are useless. Return on invested capital, about 30% over the last twelve months, is the better measure, and it is excellent3.
Where the conversion leaks
There is one subtle weakness in the cash story. Cash from operations was only about 72% of EBITDA in 20251. For a toll collector, that seems low. Three things take the difference. Interest on more than $16 billion of debt is a real cash cost that EBITDA ignores. Tax is paid in cash. And working capital absorbs money, including loyalty-program timing and owner receivables.
Receivables deserve a second look. Debtor days, receivables expressed as days of revenue, were about 41 in 2025, back near the 2019 level after a COVID peak of about 61, but well above about 29 in 20141. Some of that increase is the Starwood business mix. Some of it is money owed by owners, including notes and guarantee advances. Those are the receivables that would sour first in a downturn, and they are where the asset-light model quietly reintroduces credit risk.
Returns above free cash flow
Now the uncomfortable arithmetic. Free cash flow in 2025 was about $2.6 billion1. Planned 2026 shareholder returns are more than $4.5 billion2. Capital and technology spending is guided at $1.25 billion to $1.35 billion, roughly double the 2025 level implied by the gap between cash from operations and free cash flow12. Marriott's reasons for the jump are not broken out in its release; the plausible components are the technology transformation and key money to win contracts.
The gap between cash generated and cash returned is funded with debt. Borrowings rose from about $3.8 billion in 2014 to about $11.1 billion in 2022 and about $17.1 billion in 2025, and total debt was about $16.9 billion at the end of June 202612. Against the 2026 adjusted EBITDA guidance of about $5.97 billion to $6.03 billion, that is about 2.8 times, on Empor's arithmetic; Marriott's own leverage definition, which typically adjusts for leases and other items, may produce a different figure2. The ratio is high for a cyclical industry and comfortable for an investment-grade fee business. The gap between returns and free cash flow can be closed only three ways: EBITDA grows into it, debt keeps rising, or returns slow down.
The stress test that already happened
The best evidence on financial strength is the year the model nearly stopped. In 2020 operating profit collapsed to about $84 million1. Marriott suspended its dividend; payouts were nil in 2021. It drew on credit lines and issued bonds. But it did not issue new equity1. Investment-grade ratings kept the bond market open, and the fee model kept the cash bleed manageable. The balance sheet bent and did not break.
That record supports the claim that Marriott can carry its debt. It also bounds it. In 2020 the cost of survival was paid by shareholders through a suspended dividend and halted buybacks, and the company went into that crisis with lower debt than it carries today. Leverage and credit ratings are the things to watch; a downgrade would raise the cost of every refinancing on a debt stack that has grown by more than half since the pandemic.
The activist's question
A skeptical investor would put the question bluntly. Marriott trades at about 38 times earnings and offers a free cash flow yield of about 3.2%3. Buying back $2.2 billion of stock in six months, at prices near the 52-week high of about $403, is buying a business at a rich price with borrowed money23. Buybacks create value only when the price paid is below the business's intrinsic value. At current multiples, the buyback program is a bet that fee growth will be far faster than the past decade's record. The program flatters earnings per share either way. Whether it creates value for the shareholders who stay depends on that bet.
Buybacks shape one more number: the earnings figure that Marriott prefers to talk about.
VIII. Adjusted vs. Reported: Reading the Earnings Release
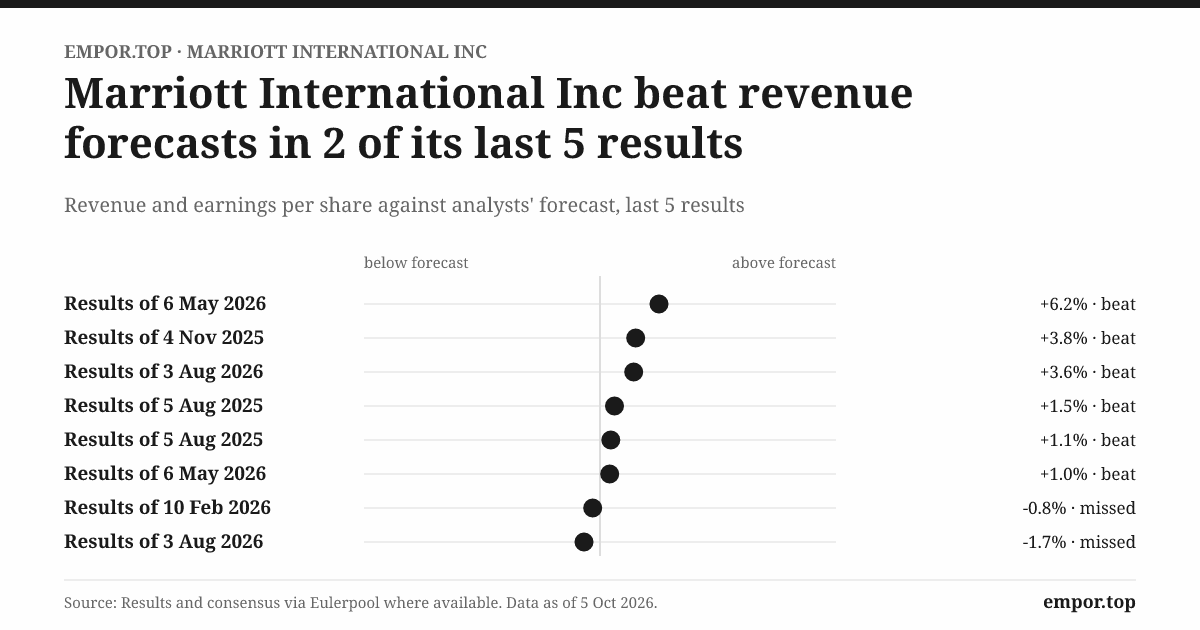
The second-quarter release led with adjusted earnings per share of $3.19. Lower down, the reported, accounting-standard figure was $2.842. The gap is about 12%. That is not unusual for a large company, but it matters at 38 times earnings, because the multiple looks quite different depending on which number an investor divides by.
What is in the gap
Marriott's adjustments mostly fall into a few buckets. It excludes cost-reimbursement revenue and expenses, which roughly offset. It excludes impairments, restructuring and transaction costs, and certain litigation charges. And it typically adds back items such as amortisation of contract-acquisition costs2. In the second quarter the visible one-offs were a $68 million impairment on a U.S. and Canada hotel sale and a $27 million litigation accrual on a property matter2. Those are genuinely unusual items. But the company has reported some impairment or restructuring charge in most recent years, and items that recur this often are arguably part of the cost of doing business.
Reported net profit in the quarter was about $766 million, almost unchanged from a year earlier2. That is the central puzzle of this story. Fee revenue grew strongly; adjusted EBITDA grew by double digits; reported net profit did not move.
Three flat years
Look at the annual series and the pattern is stark. Net profit peaked at about $3.1 billion in 2023, then fell to about $2.4 billion in 2024 and rose to about $2.6 billion in 2025, about where it has stayed over the last twelve months1. Reported earnings per share over the last twelve months were about $9.60, still below 2023's $10.43, despite three years of buybacks13.
The 2023 peak was inflated by an unusually low tax rate of about 9%, thanks to one-off tax benefits1. Adjust for a normal tax rate and the trend is not a decline but a gentle climb: profit before tax rose from about $3.1 billion in 2022 to about $3.4 billion in 2025, roughly 3% a year1. That is respectable. It is not consistent with a multiple 50% above the company's five-year median. Management's 2026 guidance for adjusted EPS of $11.64 to $11.81 implies faster growth, but much of it comes from buybacks shrinking the share count and from the adjustments themselves2. Investors paying 38 times reported earnings are, in effect, paying for the adjusted story to become the reported one.
Management's narrative
Anthony Capuano took over as chief executive in February 2021, weeks after Sorenson's death7. A Marriott lifer who joined in 1995 and spent most of his career in hotel development, signing deals with owners around the world, he brought a dealmaker's emphasis on rooms growth and pipeline. Kathleen Oberg, chief financial officer since 2016, has been the steady voice on capital returns and leverage[^4].
Their story has been consistent in one respect: rooms, fees and capital returns, every quarter. What has shifted is the weight. Earlier post-pandemic calls led with RevPAR recovery. As RevPAR growth slowed, particularly outside North America, the emphasis moved to net unit growth, fee growth, card income and adjusted EBITDA. That is not dishonest; those are the right metrics for a fee business. But it is the kind of shift a careful investor should notice, because the metrics a management team chooses to stress tend to be the ones that are working.
Compensation sharpens the point. Marriott's proxy statements show annual bonuses tied substantially to adjusted EBITDA and long-term awards that include adjusted measures; shareholders have approved pay in recent say-on-pay votes8. A pay design anchored on adjusted EBITDA is better than one anchored on EPS, because EBITDA is not flattered by buybacks. The test for the board is whether it holds management to reported returns as well as adjusted ones.
The reported earnings are flat partly because of costs that the adjusted figures leave out. One of those costs could, in a bad year, become much larger: the promises Marriott makes to owners to win their hotels.
IX. The Guarantee Question: Is Asset-Light Really Risk-Free?
Imagine a new luxury hotel in a secondary European city. The developer has borrowed heavily and the lender wanted comfort. To win the management contract against a rival chain, Marriott agreed to guarantee a level of cash flow to the owner for a few years, or to support part of the loan. Then a recession arrives. The hotel misses its numbers, and the owner calls on the guarantee.
This is how risk creeps back into an asset-light company. Marriott provides guarantees to lenders and owners to win contracts, typically for three to 10 years, and says fundings are generally recoverable from future hotel cash flows or sale proceeds1. The company has said it has taken losses, and could take more, when owners default on loans it has guaranteed1. It also lends to owners and pays key money.
The design is sensible: guarantees are capped, short-dated and tied to specific hotels. The size is the question. Marriott discloses a maximum guarantee exposure and a carrying liability in the notes to its annual report, and recent disclosures put the maximum potential funding at a few hundred million dollars, small relative to EBITDA of about $6 billion1. The risk is therefore bounded by design and modest by size. The caveat is that the exposure grows exactly when Marriott pushes hardest for growth in difficult markets, and the evidence that it is manageable comes from a period, 2020 aside, of strong travel demand.
International markets are where the pressure would show first. International RevPAR was already down about 0.5% in the second quarter2. Marriott earns in dozens of currencies and hedges some of them; a strong dollar reduces the dollar value of its foreign fees and can increase the dollar cost of its obligations1.
The risk radar, kept to what matters, has four points. A demand slowdown would hit incentive fees first and hardest. Cyber and data privacy risk is not theoretical for a company that has already lived through a breach of hundreds of millions of records. Technology execution matters because the systems rebuild is large, long and central to the loyalty promise. And cost of capital matters on a debt stack of about $17 billion, which must be refinanced at whatever rates prevail.
None of these risks looks existential on today's evidence. Together they are the reason asset-light should be understood as risk-shifted rather than risk-free. Those shifts are also where the lessons of this company lie.
X. Playbook: Lessons From Marriott
Own the customer, rent the building. The 1993 split is remembered as a financial manoeuvre, but its real lesson is about what to own. Marriott gave away the concrete and kept the relationship. Three decades later, about two-thirds of its room nights come from members of its own loyalty program1. The wider lesson for founders: when an asset ties up capital but the relationship creates pricing, sell the asset and keep the relationship.
Scale buys you a database, and a database buys you a lawsuit. Starwood gave Marriott the members that turned Bonvoy into a moat. It also gave it a compromised reservation system and years of regulators and class actions[^9][^10]. Acquirers diligence earnings; they should diligence servers. In a data business, the liability arrives with the asset.
Negative equity is a choice, until it isn't. Marriott chose to return almost all of its free cash and more, and its equity turned negative as a result. In 2020, when profit nearly vanished, the dividend was the first thing to go1. A buyback program funded by debt works beautifully in good years and becomes a constraint in bad ones. The balance sheet records the choice; the cycle decides whether it was wise.
Growth that other people pay for is only as good as their balance sheets. Every hotel in the 629,000-room pipeline depends on an owner's ability to finance and complete it2. Guarantees, key money and owner loans are the price of keeping that pipeline full. An asset-light company's real collateral is its owners' credit.
Pivot while you're winning. Hot Shoppes was profitable when the Marriotts opened a motor hotel in 1957. The company later abandoned owning hotels while hotels were still its main business. The willingness to change product before the old one failed is the habit that built the company. The test for the next generation is whether it can make the same move in distribution, before AI-driven booking forces it to.
XI. Analysis: Bull vs. Bear and the KPIs
Picture two charts side by side. On the left, franchise fees climbing 19% in a quarter2. On the right, reported net profit drawn as an almost flat line for three years1. The entire investment debate about Marriott lies in the gap between them.
How the market prices it
At about $359 a share, Marriott trades at about 38 times trailing reported earnings, against a five-year median of about 25 times. Its enterprise value is about 24.5 times EBITDA, its free cash flow yield is about 3.2%, and its PEG ratio, which divides the P/E by earnings growth, is above 43. The shares are about 11% below their 52-week high3.
What does that price assume? A free cash flow yield of about 3% leaves little room unless free cash flow grows at high single digits for many years. The ten-year revenue base rate is about 6% a year. Fee revenue is growing faster than that, so the assumption is not absurd. But the market is paying a premium for fees to keep growing materially faster than the company's long-run record and for reported earnings to catch up with adjusted ones.
How does that compare with peers? Hilton has traded at similar or higher multiples of earnings for most of the past few years, Hyatt at lower ones, and IHG somewhere between459. Marriott's premium is clearer relative to its own history than relative to Hilton. The market is pricing the whole asset-light hotel group as a high-quality fee category, which means a sector-wide de-rating would hit Marriott regardless of its own execution.
The bull case
Net rooms are growing 4% to 5% a year, and every room adds a long-dated fee stream with almost no capital. The fee mix is shifting toward franchise and card income, the highest-margin lines. Card agreements with JPMorgan Chase and American Express have stepped up income. Return on invested capital of about 30% shows how little capital each dollar of profit requires3. And buybacks steadily shrink the share count, about 265 million shares at the start of 2026, so per-share value compounds faster than the business1.
The bear case
Reported earnings have not grown in three years. The multiple is about 50% above its own five-year median. Debt has risen by more than half since 2022 and capital spending is set to roughly double, while shareholder returns exceed free cash flow. International RevPAR is already slipping. Hilton is adding rooms faster. And the loyalty moat depends on owning the first click, which the online agencies and AI assistants are contesting.
Weighing the two
The moat argument made earlier holds: Marriott's scale, database and owner switching costs are real, and they explain why returns on capital are so high. What the history does not support is the idea that this advantage protects the stock from the cycle or from its own price. Fee growth is real; earnings growth is modest; the gap is being bridged by debt-funded buybacks. The bull case is intact but expensive. The bear case does not require a collapse, only a few years of fee growth at the long-run rate.
Three KPIs
The first is net rooms growth, the engine that compounds fees regardless of pricing. It was about 4.5% year on year in the second quarter2. The question is whether it holds near the 4% to 5% range and how it compares with Hilton.
The second is franchise-fee growth, the cleanest read on the fee machine's health. It was 19% in the second quarter, flattered by the new card terms2. The test comes once those terms are in the base.
The third is free cash flow against shareholder returns. Free cash flow was about $2.6 billion in 2025 against planned 2026 returns of more than $4.5 billion12. If that gap does not narrow, the balance sheet is paying for the buybacks.
XII. Epilogue: What Decides It Next
Tonight, Marriott's shares sit about 11% below their summer high, and the company is between earnings reports. The third-quarter release in early November will be the first look at whether the pattern of the spring, strong fees and flat reported profit, still holds.
The first moment that decides the story is the full-year 2026 adjusted EBITDA figure, early next year, against the guidance of about $5.97 billion to $6.03 billion2. A result at the top of the range, with reported net profit finally breaking above the 2023 peak, would start to answer the first central question in Marriott's favour. A miss, or another year of flat reported profit, would make the 38 times multiple look more like hope than evidence.
The second is the cash. When the 2026 cash flow statement arrives, investors will see whether free cash flow rose toward the more than $4.5 billion returned, and where year-end debt landed. If debt climbs again, the third question, whether a company with negative equity can keep this pace, will have its answer: only with more borrowing.
The third is the annual report's note on guarantees, and the next International RevPAR print. If the maximum guarantee exposure rises while international demand softens, the fourth question, whether asset-light risk has simply moved, will start to have a sharper answer.
And beneath all of it, the question that has no release date: whether the traveller of 2030 starts a trip in the Bonvoy app or in an AI assistant that compares every chain at once. The fee machine is built on owning that first moment. The tension that remains is whether Marriott still owns it.
XIII. Outro
Ninety-nine years ago, on 14th Street in Washington, a young couple poured root beer for customers they could see across a counter. They owned the stand, the mugs and the barrels. The company they started now owns almost nothing a guest can touch. It does not own the lobby or the bed, and most of the people who greet you work for someone else.
What it owns is the number on the guest's phone. Marriott's real product is not a hotel room; it is the traveller who walks in already holding a Bonvoy number, and the owner who pays a fee to be sure that traveller comes. Everything else, the buildings, the payrolls and the mortgages, is rented. The question for the next century is whether the one thing Marriott does own can stay its own.
References
-
Marriott International Form 10-K for fiscal year 2025 — SEC EDGAR, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Marriott Q2 2026 earnings release (8-K Exhibit 99) — SEC EDGAR, 2026-08-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Marriott 8-K filings list, including merger and earnings releases — SEC EDGAR ↩
-
Marriott proxy statements (DEF 14A) filing list — SEC EDGAR ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube