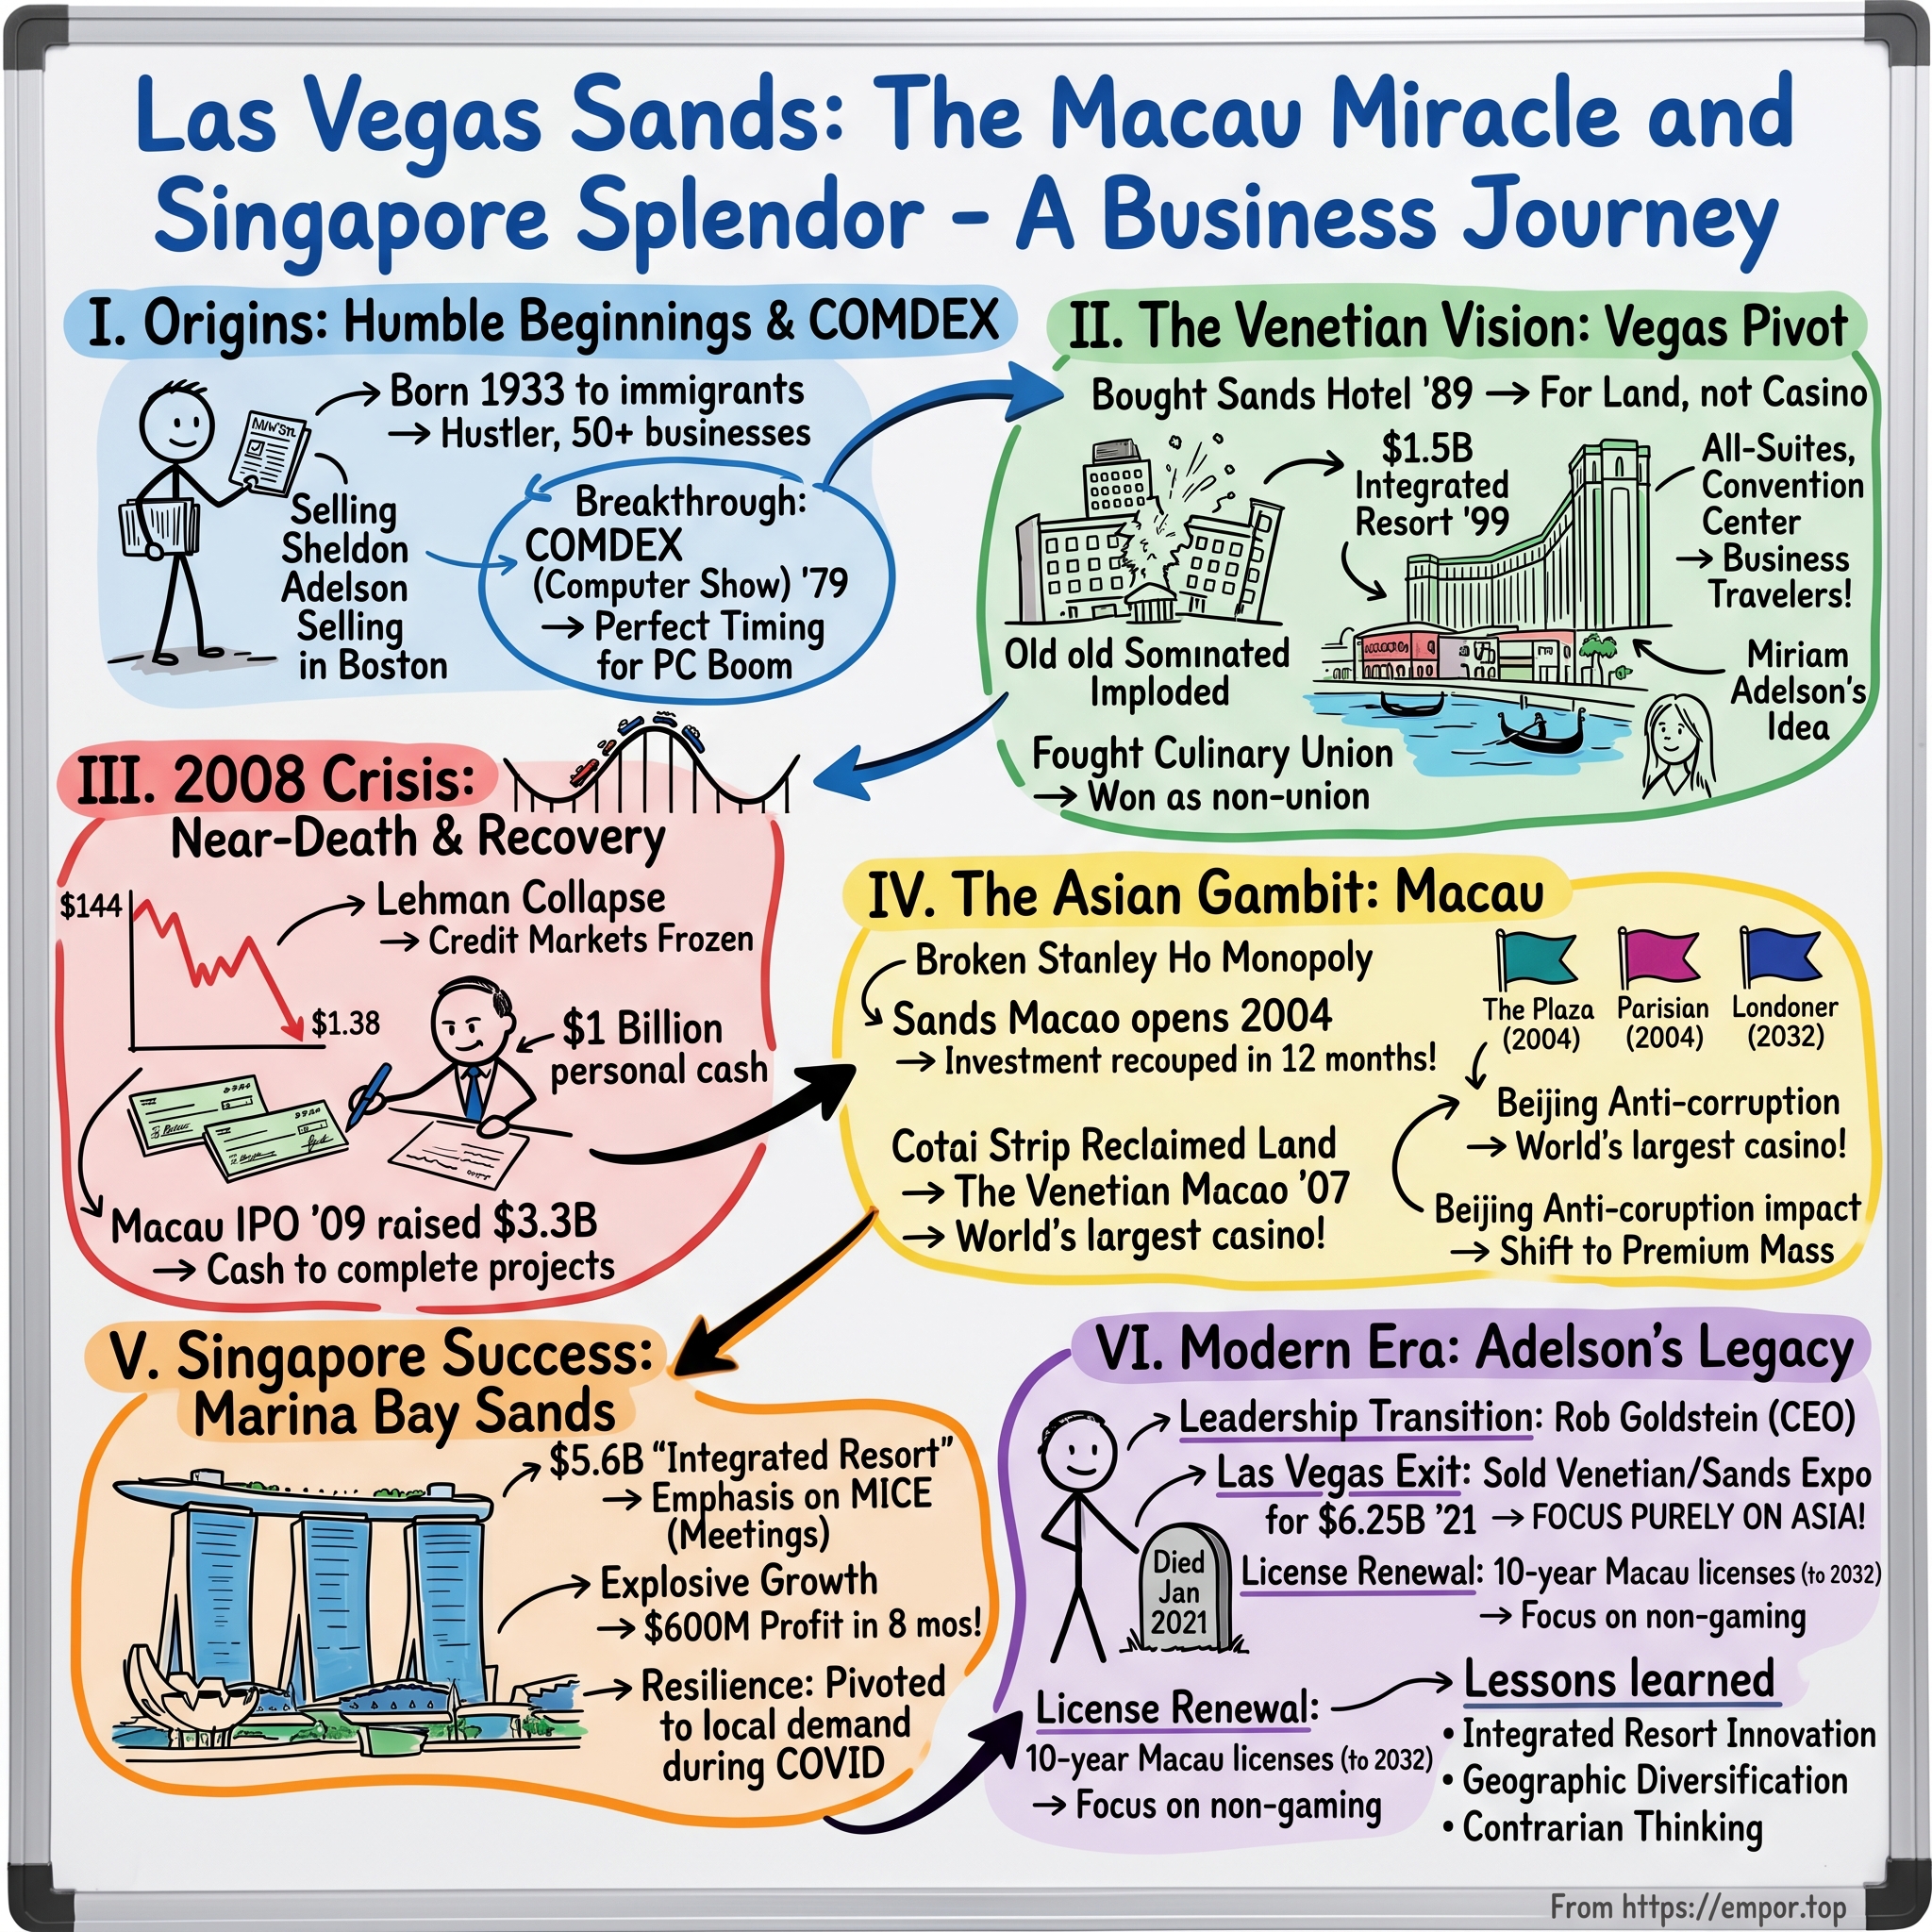
Las Vegas Sands: The Asia-Only Empire
I. Introduction & Episode Roadmap
On February 23, 2022, a deal closed and a piece of Las Vegas history changed hands without much fuss. Las Vegas Sands handed The Venetian Resort, The Palazzo and the Sands Expo and Convention Center to two new owners. VICI Properties took the land and buildings, and Apollo Global Management took the operating business. The headline price was $6.25 billion.1 The gondoliers kept singing and the painted ceilings still glowed over the casino floor. Nothing changed for the tourist walking in off the Strip, but the corporate meaning changed completely. From that day, every dollar of operating cash flow at Las Vegas Sands came from two places on the other side of the Pacific: the Macao Special Administrative Region (澳門特別行政區 Macao SAR) and Singapore.
The result is a company with an odd profile. Las Vegas Sands Corp. is a Nevada corporation, keeps its headquarters in Las Vegas and trades on the New York Stock Exchange under the ticker LVS. Yet it owns no hotel rooms, no roulette wheels and no casino floor in the United States.2 Its US operations now consist of a head office, a bond desk and a tax position. In fiscal 2025 the company booked about $13.0 billion of consolidated net revenue, all of it earned in Asia.2 Marina Bay Sands, one property in Singapore, produced about $2.9 billion of adjusted property EBITDA. That was more than half of what the whole company earned at the property level.2
The argument of this story is that Sheldon Adelson never really built a casino company. He built a real estate business for mass gatherings and put a casino inside it. His formula was convention floor space, all-suite hotel towers and shopping malls, with the gaming tables as the highest-margin item on the menu. The meetings, incentives, conferences and exhibitions trade (MICE) filled hotel rooms on Tuesday nights, when most casino operators were struggling to fill them. That formula worked on the Strip. Then he took it to a swamp in Macao and a reclaimed waterfront in Singapore, where it produced one of the largest profit streams in the history of the industry.
The story also has a less flattering side, and it is current. The company that sold its birthplace is now financing an $8.0 billion expansion in Singapore and a concession commitment of roughly $4.5 billion in Macao. At the same time it has bought back so much stock that consolidated stockholders' equity was about $581 million at June 30, 2026, against more than $15 billion of debt.3 The cash flows are real. So is the thinness of the cushion beneath them.
The story runs in six movements. The first is the trade-show hustle: COMDEX, and the lesson that hotel rooms and convention halls are bets on human congregation. Next comes the reinvention of the Strip, when Adelson knocked down the Rat Pack's Sands to build The Venetian. The third is the Asian frontier, from a Macao concession in 2002 and the paving of the Cotai Strip (路氹金光大道) to Marina Bay Sands. The fourth is 2008, when an empire building on three continents at once nearly ran out of chips. The fifth is the post-Adelson pivot: the sale of Las Vegas, zero-COVID, and the arrest of Macao's junket kings. The sixth is the present squeeze, with two Asian megaprojects, a shrinking share count and a board controlled by one family.
 Subscribe on LinkedIn
II. The Trade Show Hustle: COMDEX and the Sands Acquisition
The origin story of Las Vegas Sands begins in a trade-show hall, not at a craps table.
Sheldon Adelson grew up in Dorchester, a working-class neighborhood of Boston. His father drove a taxi, and the family lived in tight quarters.4 He started working as a boy, selling newspapers on street corners and later running vending machines. He kept going, by his own count, through dozens of businesses: mortgage brokerage, investment advice, toiletry kits, vacation travel. He made money, lost it and made it again.4 People who knew him described the same traits for decades. He was combative and stubborn, impatient with experts, and convinced that the person who owned the physical space set the terms.
That conviction came out of COMDEX. In 1979 Adelson and his partners launched the Computer Dealers' Exhibition in Las Vegas just as personal computing was taking off.4 Within a few years COMDEX had become one of the most important trade shows in the world. IBM, Microsoft and Apple rented booths, and tens of thousands of dealers and engineers filled the city every November. Adelson learned a lesson in Las Vegas that would shape everything afterwards. The casino owners who controlled the hotel rooms treated his attendees as second-class guests, since engineers did not gamble enough, and they raised room rates whenever the show came to town. A promoter who rented someone else's halls and someone else's beds was a tenant, and tenants get squeezed.
So Adelson decided to become the landlord. In 1989 he and his partners Irwin Chafetz and Jordan Shapiro bought the Sands Hotel and Casino, the faded home of Frank Sinatra and the Rat Pack, for about $128 million.4 The casino was almost incidental. Behind it Adelson built the Sands Expo and Convention Center, which opened in 1990. It was the first privately owned convention center in Las Vegas, and it gave him a hall that nobody could reprice against him.4 The established casino operators thought the project was strange. Convention-goers went to bed early, and why would anyone build exhibition halls when slot machines paid better per square foot?
The answer was a matter of filling the calendar. A Strip casino hotel makes money on weekends, when leisure gamblers arrive. From Monday to Thursday, rooms sit empty and restaurant tables go unused. Conventions turn those dead weekdays into paid occupancy at rates set by the event, not by a discount desk. If the base load of the building is filled by trade-show visitors whose employers pay their room bills, the casino becomes the incremental profit on a building that already covers its costs. Adelson saw a hotel bed as a bet on how many people would gather in a city on a given night, and the convention hall was the way to make sure they gathered at his property.
The bet paid off for him personally in 1995. 孫正義 Masayoshi Son's SoftBank agreed to buy the Interface Group's trade-show business, with COMDEX at its center, for about $862 million.5 Adelson's share of the proceeds ran to hundreds of millions of dollars.4 It was capital that answered to no bank, and he was about to stake almost all of it on one address.
The lesson for investors in Las Vegas Sands today starts here. The company's original idea was never to beat other casinos at gambling. It was to own the space where crowds gather and then charge them for everything they do once inside. That idea explains the convention halls in Singapore, the malls in Macao, and the willingness to walk away from Las Vegas once the numbers there stopped being exceptional. Next, he had to prove it on the most competitive strip of land in American gaming.
III. The Venetian Gamble: Rewriting the Strip Playbook
On November 26, 1996, the old Sands came down. The tower that had hosted Sinatra, Dean Martin and Sammy Davis Jr. collapsed in a controlled implosion that television stations broadcast across the country.4 Adelson did not intend to replace it with a better version of the same kind of casino. He meant to build something the Strip had not seen.
He found the inspiration in Venice. Adelson had married Dr. Miriam Ochshorn, an Israeli physician who specialized in addiction treatment, in 1991, and the couple honeymooned in Venice.4 Adelson came home wanting to recreate the city on the Strip, with canals, gondolas, St. Mark's Square and frescoed ceilings, at a cost of roughly $1.5 billion.4 Underneath the theme was a hard operating choice. Every room would be a suite, larger than a standard Strip room, sold at premium rates to business travelers and convention groups as well as to gamblers.
Wall Street was skeptical. Big rooms meant fewer keys per square foot, marble bathrooms meant higher construction costs, and convention customers were thought to gamble less than leisure visitors. The economics only worked if the convention base load arrived as Adelson promised and if suites earned a premium large enough to offset their cost. Adelson also picked a long fight with the Culinary Workers Union, refusing to sign the standard Strip contract.4 Critics called it ideology. It also gave The Venetian unusual flexibility over staffing in its restaurants and banquet halls, which matters a lot to a property whose weekday business depends on feeding thousands of conference attendees.
The Venetian opened on May 3, 1999, with Sophia Loren on hand for the ceremony. The opening was chaotic: parts of the hotel were unfinished, and permits and construction lagged behind the party.4 The property soon settled into what its founder had predicted. The convention hall kept the suites full during the week, the suites commanded strong rates, and the casino, restaurants and shops collected the profit. The Palazzo, a sister tower, opened next door in 2007. Together with the expo center, the complex became one of the largest hotel and convention campuses under a single roof anywhere.4
In December 2004 Adelson took the company public on the NYSE, while he and his family kept firm control.2 The timing was fortunate. Macao, covered in the next section, was already producing cash, and investors soon treated Las Vegas Sands as a growth stock. Adelson's paper fortune briefly made him one of the richest people in the world.4
What did The Venetian prove? It established the integrated resort as a commercial template: lodging, meetings, retail and food designed as one machine, with gaming as one revenue line among several. It did not prove that the model is immune to recessions, as 2008 would show. Nor did it make the Strip an unusually profitable market over the long run. By 2019, Las Vegas was a small share of the company's earnings, as section VIII will show. The Venetian was a proof of concept. The real returns came from exporting it to places where governments limited the number of licenses and demand was far larger.
IV. The Cotai Mudflat: The $15 Billion Macao Miracle
In 2002 the government of Macao ended a monopoly that had lasted about four decades. 何鴻燊 Stanley Ho's gaming empire had held the city's sole casino franchise since the early 1960s. The new regime split the market among concessionaires and sub-concessionaires, and foreign operators came to bid.4 Las Vegas Sands first joined a consortium with 銀河娛樂 Galaxy Entertainment. The partners later separated, and the restructured arrangement left Sands' Macao business with a sub-concession of its own.4
The best downtown sites near the ferry terminal and the old casino district were scarce. Adelson's attention went to a strip of reclaimed land and shallow water between the islands of Taipa and Coloane, called Cotai. At the time it held little besides mud. His plan was to build a Las Vegas Strip on it: a row of themed mega-resorts, each with thousands of rooms and its own convention and retail space, side by side on a boulevard he would effectively invent.4
He started with a smaller test. Sands Macao opened in 2004 in the old downtown, a casino aimed squarely at Mainland Chinese visitors. Demand overwhelmed it. Crowds pressed against the doors on opening day, and the property reportedly earned back its construction cost within about a year.4 Sands Macao told Adelson that demand for gaming in Macao exceeded anything Las Vegas had seen, and that the constraint was building capacity fast enough.
He built it. The Venetian Macao opened on August 28, 2007, a near-copy of its Las Vegas sibling enlarged for a bigger market. It had around 3,000 suites, a casino floor of roughly 550,000 square feet, a large arena, and a mall under painted skies.4 By floor area it was among the largest buildings in the world. The Plaza Macao with its Four Seasons hotel followed. Later came Sands Cotai Central, which has since been rebranded and rebuilt as The Londoner Macao, and in 2016 The Parisian Macao, with its half-scale Eiffel Tower.[^7] The listed subsidiary, 金沙中國有限公司 Sands China Ltd., now operates The Venetian Macao, The Londoner Macao, The Parisian Macao, The Plaza Macao and Four Seasons Macao, and Sands Macao.2
The market they were built for grew enormously. Gross gaming revenue in Macao rose by several multiples in the decade after liberalization. At its 2013 peak it was several times larger than the entire Las Vegas Strip, according to official statistics from the Gaming Inspection and Coordination Bureau.6 The demand came from Mainland China's newly rich and newly mobile middle class, crossing a short border into the only place in China where casino gambling is legal.
Why does Cotai still matter in 2026? Because the room count is a moat that others cannot easily copy. Sands China operates around 12,000 hotel rooms and suites in Macao, by its own account the largest room inventory in the market.[^7] Rooms matter in Macao for a specific reason. A casino operator cannot compete on gaming product: table games are standardized, and the government sets the number of tables. Operators compete on what surrounds the tables, such as a free suite, a show, a luxury mall or a restaurant booking. More rooms mean more inventory to give away to the players worth courting. Land in Cotai is finite and the government controls development, so the advantage tends to persist.
The verdict needs one qualification. Cotai did not prove that big bets on scale always work. It proved that they work when demand is enormous, supply is legally capped, and the government that caps it stays friendly. Those three conditions carry the whole argument. Every one of them was tested in the years after 2019, and the third is the subject of section VII. Before that, Adelson exported the formula once more, to the one jurisdiction in Asia that could match Macao's profits with a far steadier regulator.
V. The Singapore Masterpiece: Marina Bay Sands and the Duopoly Moat
In 2005, Singapore made a decision that went against its own history. The city-state had banned casinos for decades. 李顯龍 Lee Hsien Loong's government concluded that tourism was losing ground to regional rivals, and it decided to allow two "integrated resorts," large developments in which a casino would be one component under strict regulation. Bidders were told that Singapore wanted an architectural landmark and world-class convention facilities, not a gaming hall.
That brief fit Las Vegas Sands better than anyone. The company had spent fifteen years arguing that a casino resort was a convention and real estate business. It won the Marina Bay license with a design by the architect Moshe Safdie: three hotel towers, joined at the top by a cantilevered SkyPark with an infinity pool looking out over the city.4 The other license went to Genting's Resorts World Sentosa, on the resort island of Sentosa.
Building the SkyPark was difficult. The towers lean, the platform overhangs, and the reclaimed ground beneath them complicated the foundations. The project ran over budget and, like everything else the company was building in 2008, ran into the financial crisis. Marina Bay Sands opened in 2010 at a total cost reported at roughly $5.5 billion to $5.7 billion, among the most expensive casino resorts ever built.4 It made money quickly.
The economics rest on a legal structure that is easy to state and difficult to replicate. Singapore has two casino licenses. The regulator, now the Gambling Regulatory Authority of Singapore, enforces safeguards that include entry levies on citizens and permanent residents, exclusion orders and limits on marketing.7 The levy is the important part. It deliberately discourages locals from gambling, so the casino's customers are mostly foreign tourists, business travelers and wealthy regional visitors who arrive by plane. That sounds like a constraint, and it is one. But it pushes the property toward exactly the high-value customer that the SkyPark, the luxury mall and the convention center were designed to attract.
Fiscal 2025 showed how valuable the arrangement has become. Marina Bay Sands generated about $5.6 billion of net revenue and about $2.9 billion of adjusted property EBITDA. That is a margin above 50 percent, and it was more than half of the earnings of the whole company.2 Its EBITDA rose by about 42 percent in the year.2 One building on one waterfront earns more than all five Cotai properties combined. And it does so in a AAA-rated city with the rule of law, a convertible currency and a regulator whose decisions can be predicted.
That last point is what the bull case rests on. Macao's earnings depend on Beijing's tolerance. Singapore's depend on a statute and a government that has kept the duopoly in place for fifteen years, recently extending the exclusivity period while the company commits to the expansion described in section IX.10 As a business asset, a capped license in a stable jurisdiction comes close to what Hamilton Helmer calls a cornered resource. Section XI tests how close.
The qualification is concentration. When one asset produces more than half of the company's EBITDA, the entire group depends on it: its margin, its regulator, and the construction project now attached to it. Singapore went from diversifying Macao to carrying the company. Before either property could carry anything, though, the company had to survive the year it nearly failed.
VI. The 2008 Near-Death: Running Out of Chips
In the autumn of 2008, Las Vegas Sands was building on three continents at once. The Palazzo had just opened in Las Vegas. Marina Bay Sands was rising in Singapore. In Macao, cranes stood over Cotai parcels 5 and 6, the site that would become Sands Cotai Central. Each project consumed hundreds of millions of dollars, and the company had financed much of the program with debt on the assumption that credit would keep flowing and Strip revenue would keep growing.
In September 2008 Lehman Brothers failed and both assumptions collapsed. Credit markets froze. Las Vegas visitation fell as the recession hit American consumers. Las Vegas Sands, with heavy debt and enormous commitments, approached the covenant limits in its loan agreements, and the company warned that a breach was possible.4 In Macao, construction on the Cotai parcels stopped and thousands of workers were laid off.4 The stock, which had traded above $140 in late 2007, fell to a few dollars by early 2009.4 Adelson's personal paper fortune shrank by tens of billions of dollars, by some measures the largest loss of wealth any individual suffered in the crisis.4
Who rescued the company? The man whose name was on the decline. Adelson and his family put roughly $1 billion of their own money into Las Vegas Sands during 2008, in convertible notes and then preferred securities sold alongside a public offering.4 Outside shareholders were diluted. In return the company avoided a restructuring that could have wiped them out. It was an expensive rescue and an effective one, and it depended entirely on the controlling shareholder having enough liquid wealth and enough conviction to write the check while the market would not.
The structural lesson came in 2009. In November of that year the company listed Sands China Ltd. on the Hong Kong Stock Exchange, selling a minority stake to Asian investors and raising billions of dollars.[^7] The listing raised cash, and it also created a lasting design: the Macao business and its debt became a separate credit, and Marina Bay Sands developed its own financing as well. Today subsidiary debt in Macao and Singapore is ring-fenced, with no parent guarantees.2 Las Vegas Sands owns 74.8 percent of Sands China, which was its stake at the end of 2025.2
What did 2008 prove? That this business model, for all its cash generation, cannot be financed like a utility while its developments are in progress. A megaproject consumes cash for years before it produces any, and a resort company in the middle of construction is exposed to the credit cycle. Adelson's personal check was a non-repeatable fix. The ring-fencing he built afterwards is the repeatable one. It is worth remembering that his widow and family trusts still control the company today. The question in section IX is whether the current capital policy leaves room for a similar shock without the same kind of family rescue.
VII. The Beijing Crackdown: The Fall of the Junket and the Premium-Mass Shift
In late November 2021, Macao police arrested 周焯華 Alvin Chau, the head of 太陽城集團 Suncity Group, the largest junket operator in the city.8 Within days, the VIP gaming rooms that Suncity had run inside casinos across Cotai were empty. In January 2023, a Macao court sentenced Chau to 18 years in prison for crimes including illegal gambling.8
To understand why one arrest emptied a whole segment of the industry, it helps to know how the junket system worked. Mainland China caps how much foreign currency an individual can move out of the country each year. That cap is far below what a serious gambler might wager in a weekend. Junket operators solved the problem by recruiting wealthy Mainland players, extending them credit in Macao and collecting the debts back in the Mainland, often through informal money channels. The casino provided the room and split the revenue. The junket took the credit risk and the collection risk, and used methods the casinos preferred not to ask about. It was a shadow banking system with a gaming license at the front.
Beijing's tolerance ended under the banner of 共同富裕 common prosperity. Amendments to China's criminal law made organizing cross-border gambling for Mainland residents an offence, and enforcement against capital flight tightened. The arrests of junket bosses completed the shift. The VIP rolling-chip segment, once the largest piece of Macao gaming revenue, shrank to a fraction of what it had been.6 Macao's 2022 gaming law reform cut the number of licensed junket operators sharply and barred revenue sharing.
Las Vegas Sands was hurt less than many rivals, and the reason goes back to section II. The company had always earned more of its money from the mass market than its peers, and it had the largest supply of rooms, shops and restaurants on Cotai. When the VIP rooms closed, the next tier of wealthy visitors still came. These "premium mass" players wager their own money at high-limit tables without a junket in between. They can be attracted with suites, dining and shopping vouchers, all of which Sands China had in abundance. Premium mass is also more profitable per dollar wagered, because the casino no longer shares the take with a middleman.
There is a catch, and the company's financial statements show it. If the junket is gone and the casino still wants to give a wealthy player credit, the casino has to extend the credit itself. Las Vegas Sands did. Gross casino receivables rose about 79 percent in 2025, from about $462 million to about $828 million.2 The annual provision for credit losses went from $4 million in 2023 to $85 million in 2025, and another $65 million was booked in the first half of 2026 alone.23 Write-offs more than doubled over two years.2
Why does this matter more than the dollar amounts suggest? Gambling debts generally cannot be enforced in Mainland Chinese courts. A marker held against a player from Shanghai is only as good as that player's wish to keep playing in Macao. The company's auditor, Deloitte & Touche, identified the provision for casino receivable credit losses as the sole critical audit matter in the 2025 audit, citing the subjective judgment involved in estimating defaults on aged markers.2 A critical audit matter is not a warning of misstatement. It is the auditor marking the number in the accounts that most depends on management's judgment.
How should this be read? The shift to premium mass is real and suits Sands' assets. The VIP business it replaced will probably not return in its old form, because Beijing's rules, not the market, ended it. But the claim that premium mass is cleaner than VIP needs narrowing. Sands has taken back part of the credit risk that the junkets used to carry, and the provisions show that some of the 2025 growth was bought with credit. In the first half of 2026 the provision ran at an annualized pace well above $100 million. A fall back toward the low tens of millions a year would suggest that 2025 was a one-off ramp-up effect tied to The Londoner's reopening. A steady or rising pace would suggest the underwriting is structurally weaker. Las Vegas did not face this problem, and by the time it peaked, the company had already left town.
VIII. Leaving the Strip: The $6.25 Billion Geographic Divorce
Sheldon Adelson died on January 11, 2021, at the age of 87, from complications of non-Hodgkin's lymphoma.4 He had run the company for three decades as founder, chairman and controlling shareholder, and he was also one of the largest donors in American conservative politics. Robert Goldstein, who had worked alongside him since the Venetian was built and had run the company's global gaming operations, became chairman and CEO. Patrick Dumont, Adelson's son-in-law and the former CFO, became president and chief operating officer.2
Less than two months later, on March 2, 2021, the company agreed to sell its Las Vegas business.1 VICI Properties paid $4.0 billion in cash for the real estate. Apollo paid $2.25 billion for the operating business, partly in cash and partly with a seller financing loan of about $1.2 billion from Las Vegas Sands.1 The deal closed in February 2022.1 In 2022 the company recognized a gain of about $2.9 billion on discontinued operations, enough to turn a heavy loss from continuing operations into a reported profit for that year.2
Was this a betrayal of the founder? The numbers argue no. In 2019, before the pandemic, Las Vegas contributed a modest share of the company's adjusted property EBITDA, below 10 percent of the total.9 It was a mature, competitive market with heavy reinvestment needs and a contested labor relationship, sitting inside a company whose growth and returns came from licensed, capped markets in Asia. Selling it at the height of private-equity enthusiasm for Strip real estate turned a minor profit center into several billion dollars of cash when Macao's borders were closed and the company was losing money.
The seller loan was the risky part. A seller who finances a buyer takes on the buyer's credit risk, and critics asked whether Las Vegas Sands had simply moved its Strip exposure into a subordinated note. That question was answered in the first half of 2026: Apollo repaid the loan in full, and the company received about $1.26 billion in cash.3 That repayment closed the last link between Las Vegas Sands and Las Vegas.
What remains is an irony. The name on the door refers to a city where the company has no operations at all. The more important result is the concentration it created. Las Vegas Sands is now exposed to two regulators, two currencies and one big country's consumers. The sale was sound capital allocation. It also removed the only part of the company that did not depend on Asia, which matters when the next decision is how much to spend there and how much to return to shareholders.
IX. The $16 Billion Asian Squeeze: Singapore IR2, Macao Commitments, and Equity Shrinkage
In April 2025, Marina Bay Sands paid the Singapore government a land premium of about SGD 1.13 billion, roughly $848 million, for the site of its expansion.2 Construction on the project, known as IR2, formally began on May 26, 2025.2 The plan is a fourth hotel tower of luxury suites, an arena with about 15,000 seats, new convention space and additional gaming area, with completion targeted for June 2030.2 The estimated cost is about $8.0 billion.210
That figure has grown. When the expansion was first agreed with Singapore in 2019, it was budgeted at about $3.3 billion.10 The scope, construction costs and inflation pushed the estimate to more than double. By the end of 2025 about $2.5 billion had been incurred, including the land premium, which leaves roughly $5.5 billion to spend over the next four years.2 An eight-figure overrun would be routine for a project like this. A doubling of the budget before the main structure has gone up is a reminder of 2008: megaprojects consume cash for longer and in larger amounts than planned.
Macao imposes a second obligation. The concession Sands China won in December 2022 runs to December 31, 2032, and comes with a mandatory investment plan of about 35.84 billion patacas, roughly $4.5 billion. Most of it, about $4.2 billion, must go into non-gaming projects such as entertainment, conventions, culture and international tourism.2 The commitment was increased by 20 percent under a clause that took effect once Macao's annual gaming revenue passed 180 billion patacas, which happened in 2023.2 Only a small part of it has been spent so far: about 2.5 billion patacas in 2025.2 Most of the commitment still lies ahead. It is the Macao government's price for the license: share the gains by building the diversified tourism economy Beijing wants.
Sands China is also spending money it chose to spend. The Londoner Macao has been rebuilt in phases, converting older towers into larger suites and premium gaming space. The renovation took rooms out of service in 2024 and 2025 and led to asset write-offs, but it should give the company better inventory for the premium-mass player it now competes for.2 Capital spending was about $1.6 billion in 2024 and about $1.2 billion in 2025, split roughly evenly between Macao and Singapore.2
Now comes the puzzle. At the same time, the company has returned cash to shareholders on a large scale. It repurchased about $1.75 billion of stock in 2024, about $2.2 billion in 2025 and another $1.5 billion in the first half of 2026: about $5.5 billion in two and a half years.23 Treasury stock at cost reached about $10.6 billion.3 The dividend went from $0.20 to $0.25 a quarter in 2024, and to $0.30 in early 2026.23 The share count fell sharply, from about 763 million weighted-average shares in 2023 to about 648 million shares outstanding at mid-2026.23
A simple calculation shows the pressure. Operating cash flow was about $3.0 billion in 2025.2 Take away capital spending of about $1.2 billion and dividends of about $0.7 billion, and roughly $1.1 billion was left. Buybacks of $2.2 billion therefore required drawing down cash, raising debt or both. In 2026 the Apollo repayment covered part of the gap. That money will not come again, and capital spending will rise as IR2 reaches peak construction. Cash fell from about $3.97 billion at the end of 2025 to $3.50 billion at June 30, 2026.23
Meanwhile book equity has nearly disappeared. Consolidated stockholders' equity was about $581 million at mid-2026, against about $15.3 billion of debt.3 Book equity is not the same thing as economic value. The market values the company's equity at more than $20 billion, and buybacks reduce book equity by design. But the low figure records a real decision: the board turned the balance-sheet cushion into a smaller share count.
The credit agencies are not alarmed so far. Fitch upgraded Las Vegas Sands, Sands China and Marina Bay Sands to BBB in February 2026, citing net leverage of about 2.5 times EBITDA. It also named the multi-year capital commitments and Chinese consumer volatility as constraints.11 So the people who price the debt see a company that can manage its obligations. The tension is about margin of safety, not solvency.
Then there is governance. Dr. Miriam Adelson and family trusts own about 51.4 percent of the shares, which makes Las Vegas Sands a "controlled company" under NYSE rules.12 Buybacks have a side effect worth stating plainly: each share retired increases the family's percentage stake without the family spending anything. In November 2023 Dr. Adelson sold about $2 billion of stock to help fund the purchase of a majority stake in the Dallas Mavericks, and the company itself bought $250 million of that offering.142 At the May 2026 annual meeting, the say-on-pay vote, which covered CEO Goldstein's 2025 compensation of about $31 million (up from about $22 million) and COO Dumont's of about $18 million, passed with about 91 percent support.1213 Remove the family's votes, though, and roughly one in five unaffiliated votes was cast against the pay package.13 For a controlled company, that is the clearest available signal of how outside owners feel.
An activist could make a strong argument here. A company facing about $10 billion of committed Asian construction and concession spending through 2032, with one asset producing more than half its earnings, has spent more than its free cash flow on buybacks that also raise the controlling family's stake. A defender would answer that leverage is stable at investment-grade levels, that subsidiary debt is ring-fenced, and that buying shares at about eight times EBITDA is a reasonable use of cash. Both arguments are fair. The test comes in 2027 and 2028, when IR2 spending peaks. If buybacks continue at the current pace while capital spending exceeds $2 billion a year, the board will have chosen the share count over the cushion.
X. Playbook: Business & Investing Lessons
Fill the Tuesday-night bed and the casino pays for itself. Adelson's experience at COMDEX taught him that the hard part of the hotel business is the weekday, not the weekend. The convention halls behind the old Sands, then in Venice-on-the-Strip, then on the Singapore waterfront, all served the same purpose: give the building a base load, then let the casino earn the margin on top. Founders in any capacity business can borrow the idea. Find the customer who arrives when nobody else does, and own the asset that brings them. In Las Vegas Sands' own phrase for it, the casino is the amenity, and the convention hall is the anchor.
A capped license is worth more than a big market. Cotai rested on enormous demand and Singapore on a statute. Over the past five years the statute proved more valuable than the demand. Macao generated larger revenue and more headlines, but Marina Bay Sands, in a market with two licenses and a regulator whose decisions can be predicted, came to produce most of the earnings. The lesson for investors: when the government sets the supply, look closely at the government first and at the demand second.
The founder's check is not a strategy. In 2008 Las Vegas Sands survived because one man wrote a check of roughly a billion dollars that no market would. That rescue cannot be repeated, and the company's real response was ring-fencing: separate credits for Macao and Singapore, and a parent that cannot be pulled under by its subsidiaries. Any company running multi-year megaprojects should be judged by its position on the worst day of the credit cycle, not the best.
Credit is the junket you have to keep. Beijing removed the middlemen from Macao gaming, but it did not remove the need to lend money to gamblers. Sands took that business back in-house, and its provisions and the auditor's critical audit matter show the cost. A marker that cannot be enforced across a border is a promise, not a receivable.
Selling the birthplace is easy; being concentrated is hard. Selling Las Vegas for $6.25 billion was a disciplined decision, and Apollo's repayment of the seller loan confirmed it. But every exit also concentrates what remains. Las Vegas Sands traded a small, diversifying American business for a pure bet on two Asian governments. That was the correct decision, and it still has a cost.
XI. Analysis & Bear vs. Bull Case
In early October 2026, Las Vegas Sands shares traded at about $37.3 At that price the equity was worth roughly $24 billion. Adding about $11.8 billion of net debt gives an enterprise value of about $36 billion, or roughly eight times trailing adjusted property EBITDA of about $5.3 billion.3 Wynn Resorts, the closest listed peer with a large presence in Macao, traded at around nine to ten times. Before the pandemic, Las Vegas Sands itself commonly traded at low-teens multiples.3 The market is therefore paying less than it once did, and less than for a comparable rival. What does that discount assume? Roughly, that a large share of the cash flow will be absorbed by construction and concession spending for years, and that the Macao part of the earnings carries political risk that is hard to price.
The moat, tested
Cornered resource. The Singapore license is the strongest moat the company has: two casino licenses in a stable, wealthy city, with exclusivity extended as part of the IR2 agreement.10 Nothing in the record contradicts it. Singapore has kept the duopoly intact since 2010 through COVID and changes of government leadership. The Macao concession runs to 2032 and is valuable, but it is a weaker kind of cornered resource. It is a renewable license granted by a government that has shown, in the junket crackdown and the investment mandates, that it can change the economics of the industry. Verdict: intact in Singapore; narrower and conditional in Macao.
Scale economies. Sands China's room inventory on Cotai, the largest in Macao, lowers the cost of attracting each premium player, because it can offer more inventory as complimentaries.[^7] The test is market share in the segment that matters. The company's stated rationale for the Londoner rebuild is that premium mass requires better rooms, not just more rooms. The heavy renovation spending and the credit expansion suggest scale alone was not enough to win the post-COVID premium player. Verdict: real, but it needs continuing reinvestment to stay real.
Switching costs. Loyalty programs and luxury amenities matter, but a wealthy player can walk from The Londoner to a rival's casino across the street in five minutes. Rivals such as 澳門博彩控股 SJM Holdings, 新濠博亞 Melco, Galaxy and Wynn all court the same customers with the same tools. Verdict: weak. The rising credit provisions suggest that some of the switching cost the company has created consists of credit lines, which is a costly form of loyalty.
Porter's forces. Buyer power is high at the top of the market, where whales and premium players negotiate rebates and credit, and low among ordinary mass players. The threat of substitution inside China is low, because casino gambling is illegal on the Mainland. It is rising regionally, as Thailand debates integrated resorts, the UAE develops commercial gaming and the Philippines expands. Supplier power is modest; no single vendor is critical.2 Competitive rivalry in Macao is intense among the concessionaires. The strongest force by far is the government. Macao's government sets table numbers, labor rules and investment mandates, and Beijing controls visa policy and capital outflows. That bargaining power belongs in the moat analysis, not just the risk section, because it determines how much of the profit the company keeps.
The bull case
Marina Bay Sands is producing about $3 billion of annual EBITDA at margins above 50 percent, and IR2 adds an arena, luxury suites and gaming capacity in the wealthiest city in Southeast Asia, which continues to attract private wealth from across the region.2 The Londoner rebuild is complete, so Sands China has better inventory as Macao's market recovers. The credit rating agencies have upgraded the company, and Moody's affirmed its rating in August 2026.111516 The Apollo repayment provided a one-off boost of cash.3 Buying back shares at about eight times EBITDA, if the earnings hold, concentrates future cash flow on fewer shares.
The bear case
Capital needs over 2027 to 2030 are large and committed. About $5.5 billion remains for IR2 and most of the roughly $4.5 billion Macao commitment is still to be spent.2 The company has about $3.0 billion of debt maturing across 2027 and 2028 alone, and more after that.2 If Chinese consumer spending weakens, free cash flow after dividends could turn negative and force new borrowing at higher rates. The credit numbers are moving the wrong way: provisions of $65 million in just six months suggest that part of the premium-mass growth rested on loans the company may not recover.3 And the equity cushion has largely been spent on buybacks. A pandemic, a Taiwan crisis or a sudden policy change in Beijing would hit a company with very little book equity left.
Weighing it
The history supports the Singapore claim, narrows the Macao claim and leaves the capital-allocation claim unproven. Marina Bay Sands has earned its reputation. Sands China's lead in rooms is real, but it costs money to maintain, and part of its recent growth has been financed by credit. The board's view that it can fund two megaprojects, a rising dividend and multi-billion-dollar buybacks all at once has not yet been tested by a downturn.
The KPIs that decide it
First, Marina Bay Sands adjusted property EBITDA margin, which was above 50 percent in fiscal 2025 and rising.2 Singapore carries the company, and a sustained fall toward the mid-40s would be the first sign that the engine is weakening while IR2 spending peaks.
Second, the provision for casino credit losses, which rose from $4 million in 2023 to $85 million in 2025, with $65 million in the first half of 2026.23 A return toward the low tens of millions would confirm the Londoner ramp-up explanation; a pace above $100 million a year would point to a structural problem.
Third, free cash flow after capital spending and dividends, which was about $1.1 billion in 2025, before buybacks.2 That is the number that decides whether buybacks are paid from surplus or from the balance sheet.
XII. Epilogue: The Next Turn of the Wheel
Tonight, Las Vegas Sands is earning strongly in both of its markets. Marina Bay Sands is producing record revenue, Sands China has its rebuilt Londoner open, and net revenue in the first half of 2026 rose about 12 percent year over year.3 Robert Goldstein and Patrick Dumont run a company that, on most operating measures, is in its best shape since before the pandemic.
The next five years will be decided by construction schedules and policy. Cranes are now visible over Marina Bay. IR2 is due to open in mid-2030, and the years 2027 and 2028 will bring the heaviest spending. If the project comes in at its $8.0 billion estimate and the new arena and suites earn returns anywhere near those of the original towers, the bet on Singapore will be repaid. If the cost rises again, the return falls and the pressure on the buyback program grows. In Macao, the government will judge the concessionaires on whether they deliver their non-gaming commitments, and the 2032 expiry is closer than it seems for a business whose assets last forty years.
Then there is geopolitics, which no capital plan controls. Las Vegas Sands is an American company controlled by one of America's most prominent political families, and it earns a large part of its money in a Chinese special administrative region. So far Beijing has regulated Macao's industry, not punished American operators. That has held through trade wars and pandemic closures. It is the largest risk the company cannot hedge.
The founder's legacy cuts both ways. Adelson was right when he paved Cotai while others called it madness, built convention halls while casino bosses wanted slot machines, and hung a park in the Singapore sky. He also came close to losing everything in 2008, because he built everything at once with borrowed money. His successors are again building in two places at once, and returning record cash to shareholders while they do. The open question is whether that is confidence based on evidence or a repeat of 2008's overreach.
XIII. Outro
Stand on a bridge over the Grand Canal inside The Venetian Macao. Above you is a painted sky that never darkens. Below, gondolas carry tourists from Guangdong and Fujian, steered by gondoliers singing in Italian. Few of the people in those boats know that the whole place started with a trade-show promoter from Dorchester who was tired of paying someone else's room rates.
Las Vegas Sands took the most famous gambling name in the Western world, showed that its real business was a luxury convention and shopping machine, and then left Las Vegas entirely to compete in the gaming capitals of Asia. Its name points to the Nevada desert, while its future depends on a construction site in Singapore and a government in Macao.
References
-
Las Vegas Sands Completes $6.25 Billion Sale of Venetian Resort and Sands Expo — Reuters, 2022-02-23 ↩↩↩↩
-
Form 10-K for the Fiscal Year Ended December 31, 2025 — Las Vegas Sands Corp., 2026-02-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Form 10-Q for the Quarterly Period Ended June 30, 2026 — Las Vegas Sands Corp., 2026-07-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Sheldon Adelson, Casino Mogul and Political Megadonor, Dies at 87 — The New York Times, 2021-01-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
SoftBank Agrees to Buy COMDEX and Computer Trade Show Unit for $862 Million — The Wall Street Journal, 1995-02-14 ↩
-
Gaming Inspection and Coordination Bureau (DICJ) Macao SAR — Official Gross Gaming Revenue Statistics ↩↩
-
Gambling Regulatory Authority of Singapore (GRA) Annual Report and Casino Regulatory Framework ↩
-
Macau Junket Mogul Alvin Chau Sentenced to 18 Years in Prison for Illegal Gambling — Bloomberg, 2023-01-18 ↩↩
-
Form 10-K for the Fiscal Year Ended December 31, 2024 — Las Vegas Sands Corp., 2025-02-07 ↩
-
Singapore Approves $8 Billion Marina Bay Sands IR2 Expansion with Targeted 2030 Opening — The Straits Times, 2024-04-05 ↩↩↩↩
-
Fitch Upgrades Las Vegas Sands' IDR to 'BBB'; Outlook Stable — Fitch Ratings, 2026-02-06 ↩↩
-
Definitive Proxy Statement on Schedule 14A — Las Vegas Sands Corp., 2026-04-01 ↩↩
-
Form 8-K: Submission of Matters to a Vote of Security Holders — Las Vegas Sands Corp., 2026-05-18 ↩↩
-
Miriam Adelson Sells $2 Billion of Las Vegas Sands Shares to Fund Dallas Mavericks Purchase — Bloomberg, 2023-11-28 ↩
-
S&P Global Ratings Upgrades Las Vegas Sands and Sands China to 'BBB' — S&P Global Ratings, 2026-04-30 ↩
-
Moody's Affirms Las Vegas Sands' Baa3 Senior Unsecured Rating; Outlook Stable — Moody's Investors Service, 2026-08-20 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube