Illinois Tool Works: The Anti-Conglomerate
I. Introduction & Episode Roadmap
Picture the last time you picked up a six-pack of soda. The clear plastic rings holding the cans together, the screw that keeps a car's door panel from rattling, the welding gun in a shipyard in Houston, the dishwasher humming in the back of a restaurant kitchen, the machine that pulls a steel sample apart in a quality lab to see where it snaps. None of these objects carries a famous logo. Most people could not tell you who made any of them. A surprising number were made by the same company.
That company is Illinois Tool Works. In fiscal 2025 it generated about $16.0 billion in revenue with roughly 45,000 employees across dozens of countries, and it earned an operating margin of 26.3%, a figure most software companies would be pleased to report.45 Its after-tax return on invested capital ran around 30%, and in 2025 it raised its dividend for the 63rd consecutive year.417 Those are best-in-class numbers for a diversified industrial. They come from fasteners, welders, commercial ovens, adhesives, and testing machines.
The anonymity is part of the strategy. ITW does not build brands for consumers. It builds small, specified-in products for engineers, purchasing managers, and plant supervisors who care about whether a part works on the line tomorrow morning far more than about what it costs. A fastener might be a few cents of a car's bill of materials. If it fails, the line stops. That asymmetry between the cost of a part and the cost of its failure is the quiet economic engine underneath almost everything in this story.
But the ITW of today is not simply the product of a century of patient compounding. Around 2011 the company ran something on the order of 800 semi-autonomous business units, many of them sub-scale, many overlapping, with margins that trailed the better diversified-industrial peers.13 An activist investor showed up. Within a year the company had a new strategy, and within a decade it had one of the highest-margin profiles in its peer group. The central question of this story is uncomfortable for the official narrative: how did a century-old industrial holding company become one of the most efficient capital compounders in the S&P 500, and was it management's plan or an outsider's?
The honest answer, as the evidence will show, is "both." That answer matters for investors, because it shapes how much faith to place in the discipline holding without outside pressure.
The roadmap runs like this. First, the origins and the decentralization instinct that defined ITW for most of its life. Then the Premark era, when the acquisition machine began to outrun itself. Then the 2012 rupture and the "Enterprise Strategy" that followed. From there, the story turns analytical: how the seven-segment portfolio actually makes money, how capital gets allocated, how the 2024 leadership handoff has gone, and whether the growth narrative, especially around electric vehicles and China, survives scrutiny. The piece closes with a competitive-moat analysis, the bull and bear cases, a risk radar, and lessons for operators and investors.
One framing to keep in mind throughout: ITW is a company whose best numbers are well documented and whose deepest claims about its competitive advantage are documented mostly by ITW itself. Both halves of that sentence will come up repeatedly. To see why the operating system matters so much, though, it helps to start where the operating system did not yet exist.
 Subscribe on LinkedIn
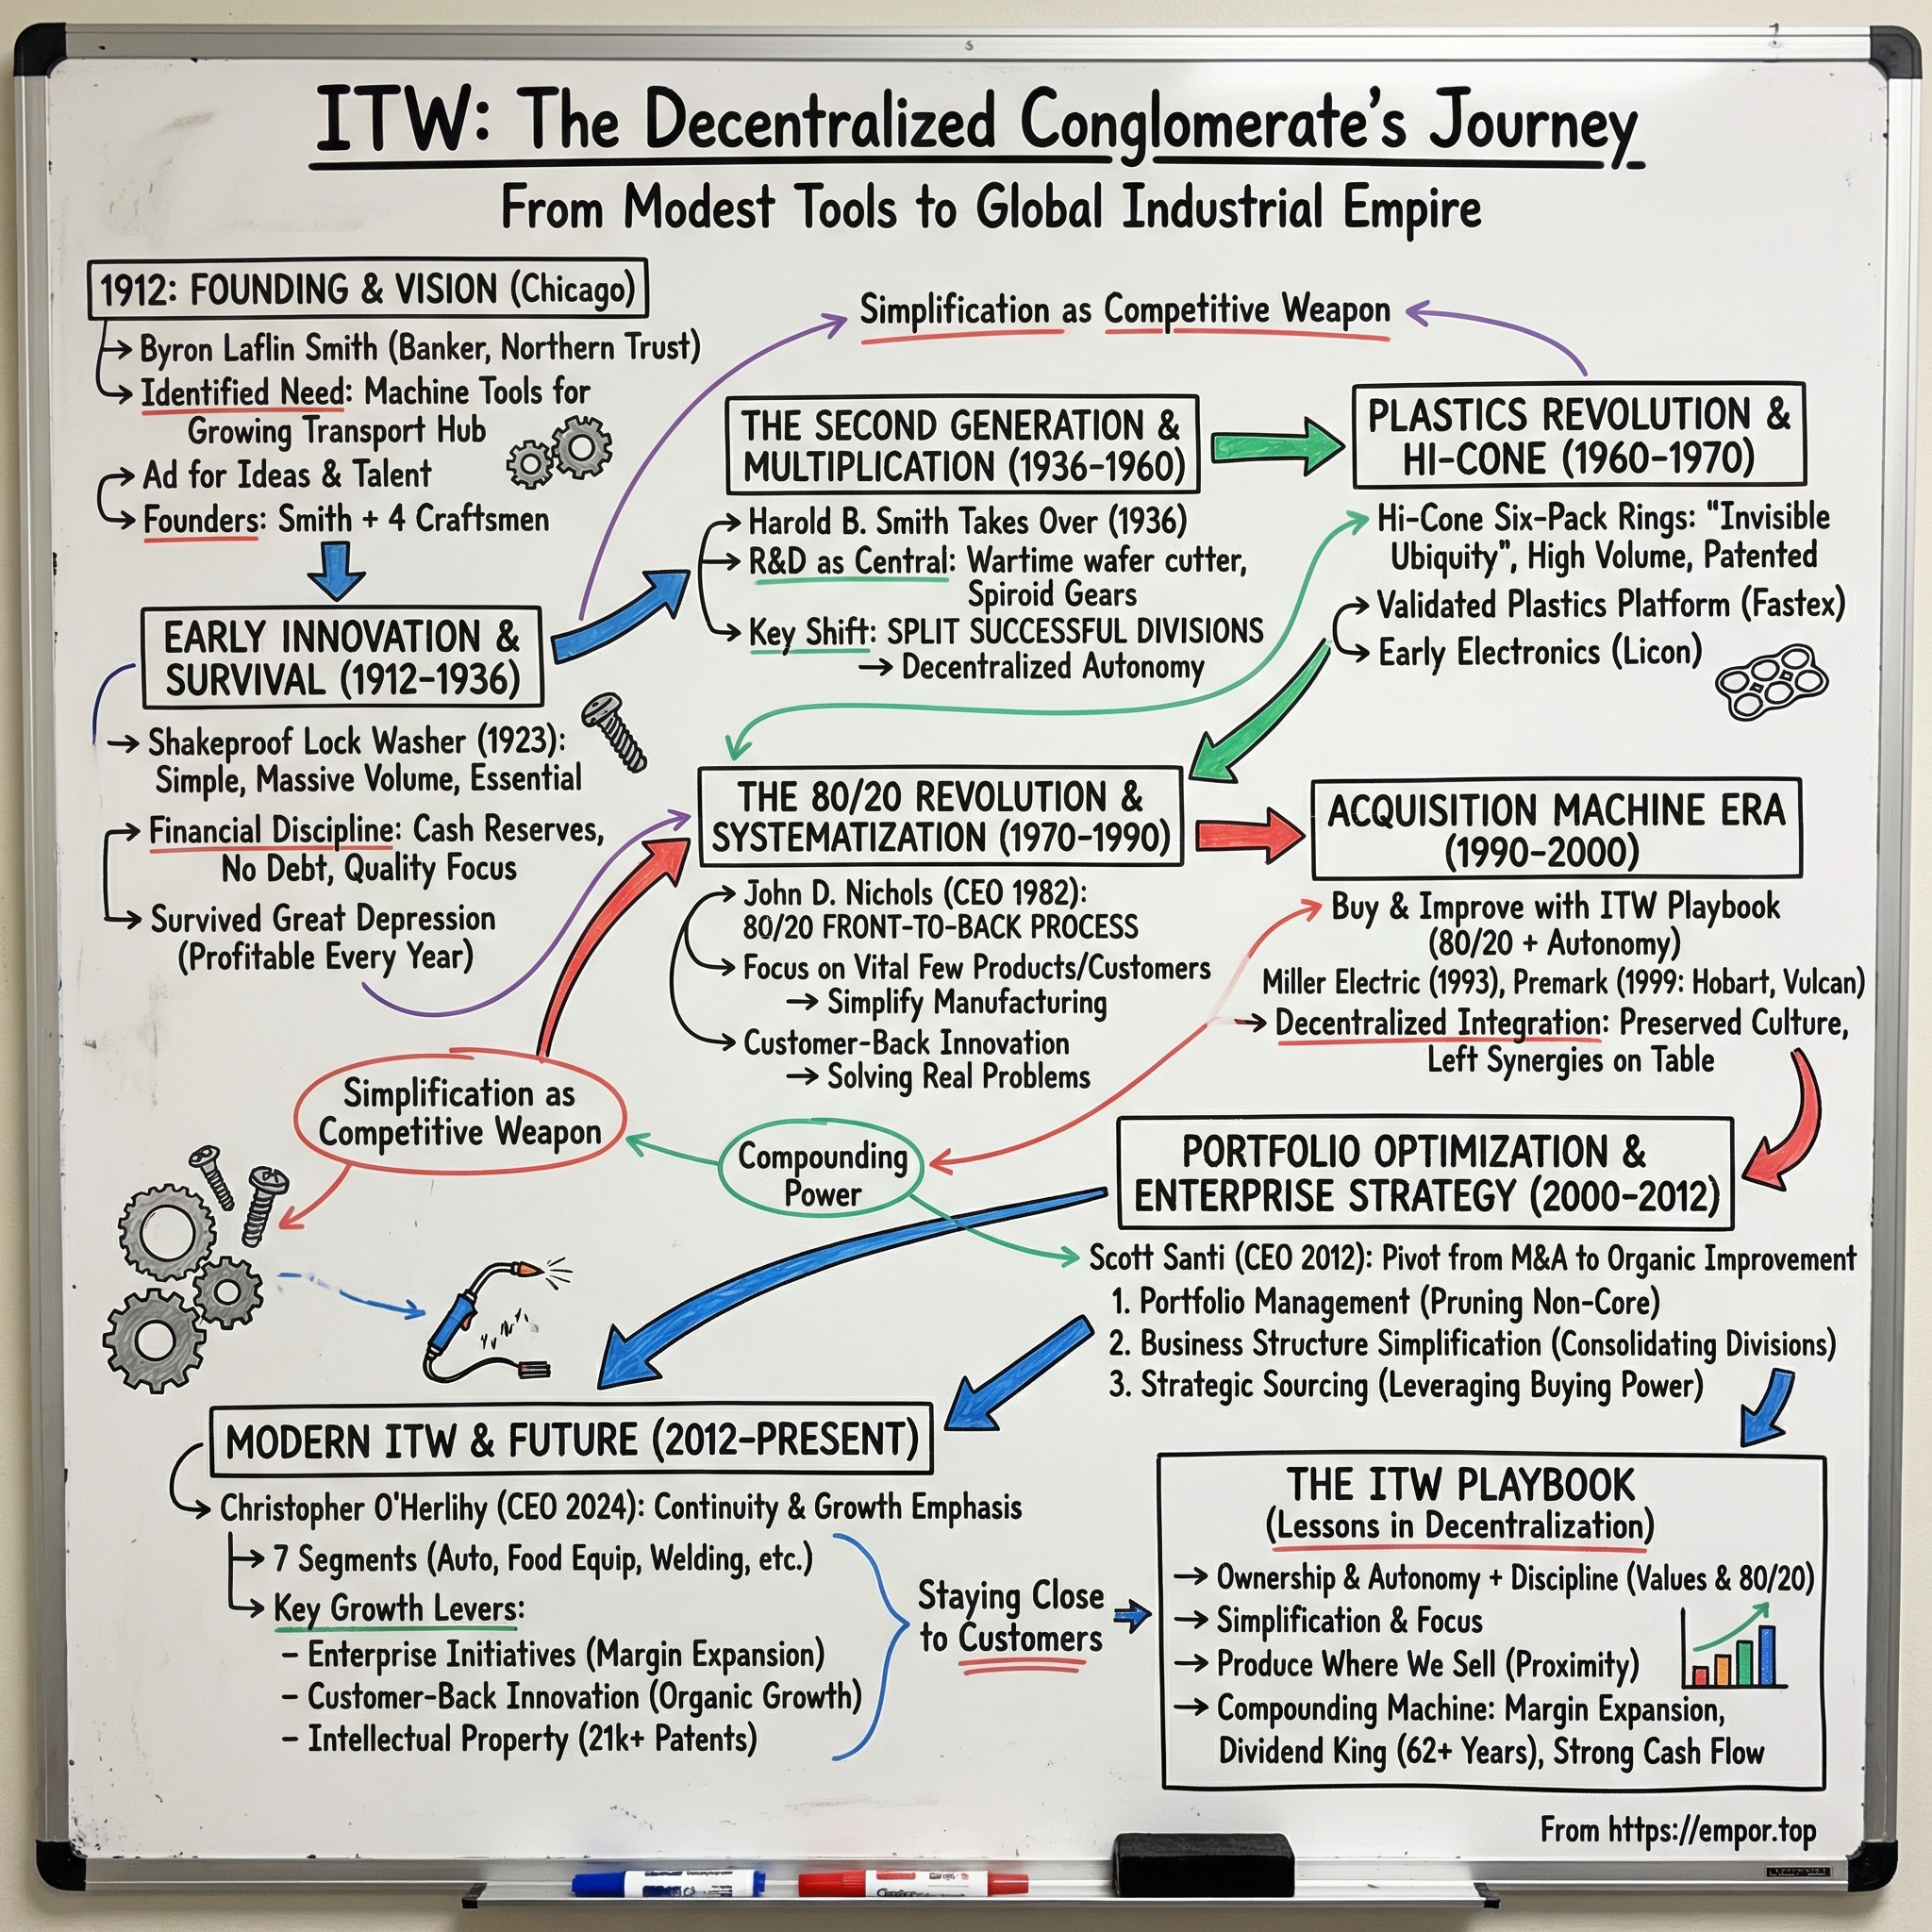
II. Origins and the Decentralization Gene (1912-1990)
Chicago in 1912 was a city of stockyards, rail yards, and machine shops, a place where a banker with an eye for industrial opportunity could find no shortage of bets. Byron Smith was that banker. He put up capital to start a company making metal-cutting tools, and gave it a name so plain it sounds like a placeholder: Illinois Tool Works.18 The name stuck for more than a century, even as the company drifted far from machine tools.
The Smith family's instinct, visible early, was not to dominate one big market but to find small, adjacent niches where engineering mattered and competition was thin. Byron Smith's son Harold, and later his grandson Harold Jr., steered the company into fasteners, specialty metal parts, and eventually plastics. What united these businesses was not technology but economics: products that were cheap to make, painful for customers to get wrong, and too small for giants to bother fighting over.
The six-pack ring template
The purest expression of that logic came in the 1960s with the Hi-Cone plastic multi-pack carrier, the thin plastic rings that hold beverage cans together. It is an almost comically unglamorous product. Yet it captured the ITW template for decades to come: a tiny amount of material, an engineered design that fit neatly into a bottler's high-speed packaging line, and a customer who would rather pay a fair price for something that never jams than save a fraction of a cent on something that might. Once the packaging machinery and the carrier were designed around each other, switching carried real operational risk. The margin lived in that risk.
Post-war decentralization
The organizational choice that would define ITW came after the Second World War. Rather than run the company as a single integrated manufacturer, leadership split it into small, autonomous units, each with its own general manager and its own profit and loss statement. When a product line grew big enough, it was often divided in two, keeping each unit small enough that its manager knew the customers personally.
The logic was compelling. Small units moved fast, stayed close to customers, and made accountability impossible to dodge. A manager could not hide a bad year inside a giant division. For decades this was a genuine advantage over lumbering conglomerates where headquarters made decisions for plants it had never visited.
The serial acquirer
By the 1980s, ITW had turned that structure into an acquisition engine. The logic was simple: buy a niche industrial business, plug it into the decentralized model, let local managers run it lean, and repeat. Under long-serving leadership in that era, including CEO John Nichols and later Jim Farrell, the company became one of America's most prolific buyers of small industrial companies. The 1986 purchase of Signode, a strapping and industrial packaging business, was a signature deal of the period.
What the model lacked was any strong corporate discipline around integration. Each acquired business kept its identity and its back office. Nobody forced common pricing practices, shared purchasing, or a systematic look at which product lines actually earned their keep. In the 1980s, with small deals and a manageable count of units, the costs of this looseness were modest.
This era matters to today's investor mainly as the seed of a structure the 2012 turnaround would later have to dismantle. The decentralization gene gave ITW its entrepreneurial energy. It also, left unchecked, gave it sprawl. The next chapter is where sprawl began to show up in the numbers.
III. Premark and the Limits of the Acquisition Machine (1990s-2000s)
In the autumn of 1999, ITW's leadership was digesting the biggest meal in the company's history. It had agreed to merge with Premark International, a stock deal valued at roughly $3.4 billion that brought in Hobart and Vulcan commercial food equipment, Wilsonart decorative laminates, and a tail of consumer businesses that had very little to do with anything ITW did.15 It was a bold move for a company whose identity rested on small, niche deals.
The 1990s had already been a decade of frenetic buying, with around a hundred acquisitions across the decade. Premark was different in kind, not just in size. Instead of buying one well-understood niche, ITW bought a bundle, and bundles come with both the jewels and the junk.
Admission by divestiture
The tell came quickly. Around the time the deal was being completed, reporting indicated ITW expected to sell Premark businesses that did not fit, including the Precor fitness equipment business, the West Bend small appliance maker, and Florida Tile.15 Treadmills and toasters had no obvious place inside an industrial fastener and equipment company.
This is an underappreciated moment in ITW's history. The "buy and leave alone" philosophy works when each acquisition is individually attractive and small enough that one mistake does not matter. At $3.4 billion, with a bundle of mixed quality, the philosophy stopped being a philosophy and became a hope. The quick decision to shed pieces was, in effect, an admission that the company had paid for assets it did not want.
To be fair, not all of Premark was a mistake. Hobart and Vulcan became the core of ITW's Food Equipment segment, which today earns roughly 28% operating margins.4 Wilsonart was a solid business for years before it was later separated. The lesson is narrower and more important: when an acquirer buys bundles rather than businesses, it has to be willing to disassemble what it bought, and the price paid needs to reflect that.
Eight hundred divisions
The deeper problem was structural. Because the decentralization model split units as they grew and added new ones through acquisition, the number of business units kept climbing. By the late 2000s the count approached roughly 800.13 Each had its own general manager, its own overhead, often its own purchasing and sales functions, and sometimes its own pricing approach for products that competed with a sister division's.
Imagine a restaurant chain where every location sources its own flour, designs its own menu, and negotiates its own rent. Each manager might be excellent, and the chain would still be spending far more on duplicated effort than a coordinated competitor. That was ITW heading into the 2000s.
The recession exposes the fat
The industrial recession of the early 2000s, and then the far deeper one of 2008-2009, laid bare how much structural cost the machine had accumulated. Sub-scale units could not absorb volume drops. Duplicated back offices stayed on the books. The model that had looked lean in good years looked bloated in bad ones.
For investors, the key point for later sections is this: ITW's modern reputation as a disciplined allocator of capital was not inherited from its founders or its golden era of deal-making. It was earned later, after a real episode of overpaying for a mixed bundle and having to unwind parts of it. That is a course correction, not a birthright. And the correction did not begin on its own.
IV. The 2012 Inflection: An Activist, Not a Visionary, Forces the Turn
In 2011, an investment firm based in San Diego began quietly buying ITW shares. Relational Investors, co-founded by Ralph Whitworth and David Batchelder, had a reputation for taking meaningful stakes in underperforming large caps and pushing management, sometimes gently and sometimes not, toward a specific operational agenda. Its stake in ITW eventually reached around 2.1% of the company.13
Relational's diagnosis was not subtle. ITW was too complicated. It had too many divisions, too many small acquisitions that earned too little, and margins that lagged the better diversified-industrial peers. The fix was to consolidate the sprawl, stop buying low-return businesses, and push margins toward where the peer group already sat.
The cooperation agreement
On January 13, 2012, ITW and Relational announced a cooperation agreement.13 The agreement gave Relational the right to have a director nominated to the board, and it was filed with the SEC as a letter agreement.14 In the polite language of corporate governance, this was a truce. In practice, it meant that an outside investor with a specific agenda now had a formal channel into the boardroom.
The timing of what came next matters. In 2012, ITW's leadership changed. CEO David Speer stepped down due to illness, and Scott Santi, a career ITW operator who had run large parts of the business, took the top job. Santi launched what the company calls its "Enterprise Strategy," the single biggest strategic pivot in the company's modern history.18
What actually changed
The Enterprise Strategy had three pillars that mapped almost exactly onto the activist's critique.
First, portfolio management and simplification. Roughly 800 divisions were consolidated into around 85 to 90 larger, scaled businesses.18 Non-core and lower-growth businesses were sold or separated, which over the following years included decorative surfaces and industrial packaging operations. The goal was not just fewer units but units big enough to invest in engineering, sales, and innovation.
Second, the company-wide rollout of the "80/20 Front-to-Back Process."18 The idea is borrowed from the Pareto principle: in most businesses, roughly 20% of customers and products generate roughly 80% of profits. ITW applied that insight ruthlessly. The best customers and products got dedicated resources, simpler supply chains, and faster service. The long tail was simplified, repriced, outsourced, or exited. A useful analogy is a grocery store that discovers most of its profit comes from a few hundred items, then redesigns its shelves, staffing, and supply chain around those items while trimming slow sellers that clog the aisles.
Third, a sharp slowdown in acquisitions in favor of organic execution. The company that had bought roughly a hundred businesses in a decade would now buy only occasionally and selectively.
The results
ITW's own account of the period is striking. The company says the Enterprise Strategy delivered roughly nine percentage points of operating-margin expansion over about a decade, and that after-tax ROIC roughly doubled, from the mid-teens to around 28-30%.184 The FY2025 operating margin of 26.3% is the visible result.4
What this reveals is important. A one-time cost cut produces a step change and then fades. ITW's margin improvement was gradual, sustained across more than one economic cycle, and accompanied by rising returns on capital. That pattern is more consistent with a genuine change in how the businesses are run than with a single restructuring charge.
Myth versus reality
The corporate myth is clean: visionary management designed a strategy and executed it over a decade. The reality is messier. ITW's public telling of its Enterprise Strategy emphasizes internal execution and does not prominently credit the activist campaign that preceded it.18 Yet the timeline is unambiguous. Relational built its stake in 2011, secured a formal board channel in January 2012, and the strategic overhaul launched that same year.13
Both things can be true. The activist named the diagnosis; management executed the cure, and did so for more than a decade after the pressure faded. That second half is itself evidence of capability. Plenty of companies accept an activist's diagnosis, run a two-year program, and then drift back. ITW kept compounding its margin improvement long after the initial truce.
In the public record reviewed for this story, no further activist campaign at ITW surfaced between 2013 and 2026. That is a bounded data point, not a guarantee. It suggests the fix stuck well enough that outside agitators saw no easy target. It does not prove the discipline would hold if returns began to slip. To understand what that discipline actually protects, one has to look inside the modern portfolio.
V. The ITW Business Model Today: Segments, Competitors, Economics
Walk onto a factory floor supplied by ITW and you will not find one product line. You will find seven quite different businesses: plastic clips in a car door, a welding power source on a fabrication shop floor, a commercial dishwasher in a hotel kitchen, a tensile tester in a university lab, a tube of structural adhesive, a pallet of construction fasteners, and a specialty packaging component. What connects them is not what they make. It is how they are run.
That is the core of the investment case. ITW is not a bet on any single end market. It is a bet that one operating system, applied identically across seven segments, produces better economics than the same businesses would earn inside a less disciplined owner.
The segment map
In FY2025, the seven segments broke down roughly as follows.45
Automotive OEM was the largest, at about 20.5% of revenue, with operating margins around 21%. Test & Measurement and Electronics came next at about 17.6% of revenue and roughly 25% margins. Food Equipment contributed about 16.8% of revenue at around 28% margins. Welding was about 11.8% of revenue with margins near 33%. Construction Products contributed about 11.3% at roughly 30%. Specialty Products was about 11.1% at around 31%, and Polymers & Fluids about 11.0% at roughly 28%.
The shape of this matters more than the individual numbers. The biggest segment by revenue is the lowest-margin one. The smaller segments carry the richest economics. That tells an investor something about where ITW's pricing power lives and where it does not.
Automotive OEM: big, cyclical, and squeezed
ITW's automotive business makes engineered plastic and metal fasteners, clips, and small components that go into vehicle interiors, exteriors, and powertrains. The customers are enormous automakers and Tier-1 suppliers. In that world, ITW competes not only with large Tier-1 players such as Magna and Aptiv on some component work, but with dedicated fastener specialists like SFS Group, LISI, and Bulten.
The economics reflect who has bargaining power. Automakers negotiate relentlessly on price, and vehicle production is cyclical. ITW's roughly 21% margin in this segment is respectable for an auto supplier, far above what many Tier-1s earn, but meaningfully below ITW's enterprise average.4 The segment's attraction is scale and a growing content-per-vehicle story; its weakness is that the customer holds much of the leverage.
Welding: the profit engine in an oligopoly
Welding is where ITW's pricing power is easiest to see. Through Miller Electric and Hobart welding brands, ITW sells welding power sources, wire, and consumables to fabricators, contractors, and industrial customers. The global market is dominated by a small number of players. Lincoln Electric is the clear leader, with an estimated global share in the high teens, and ESAB is another major rival. ITW sits as a credible second or third player.
Operating margins near 33% in this segment are the strongest evidence in the portfolio of real pricing power.4 Customers are fragmented, the equipment has strong brand loyalty among welders, and consumables generate recurring revenue. When three companies control much of a market and none of them has an incentive to start a price war, margins tend to stay healthy.
Food Equipment: parts, service, and a concentrated market
Food Equipment, largely inherited from Premark's Hobart and Vulcan, sells commercial dishwashers, ovens, food preparation equipment, and refrigeration to restaurants, institutions, and retailers. The top handful of players, including ITW, Middleby, Ali Group (which absorbed Welbilt), and Rational, control a substantial share of the global market.
The hidden gem here is service. Once a hospital or restaurant chain installs equipment, it needs parts and maintenance for years. That aftermarket revenue is recurring, less cyclical, and typically higher margin than the initial equipment sale. Roughly 28% segment margins reflect both the market structure and that installed-base annuity.4
Test & Measurement and Electronics: embedded in quality processes
This segment includes Instron, whose machines test the strength and durability of materials, and MTS, which ITW acquired in 2021 and which builds test and simulation systems.16 Competitors across its various niches include Fortive, Keysight, and Teledyne.
The economic logic is switching costs of a particular kind. When a customer's quality protocols, certification standards, and calibration routines are built around a particular testing system, replacing that system means re-validating the whole quality process. It is less like changing a supplier and more like changing an operating system. Margins around 25% reflect that stickiness, while also still carrying the drag of an MTS integration that management expected to take years.416
Construction, Polymers & Fluids, and Specialty Products
The remaining three segments are collections of niches: fasteners and tools for residential and commercial construction; adhesives, sealants, lubricants, and automotive aftermarket chemicals; and a grab-bag of specialty components and equipment. Each earns operating margins in the high twenties to low thirties.4 Their shared trait is small, specified products where the customer values reliability far more than a few cents of savings.
The moat claim, tested
ITW presents 80/20 and, more recently, Customer-Back Innovation as durable process advantages.18 The P&L outcome is well documented: rising margins, rising ROIC, and a sharply simplified portfolio.
The honest caveat is that almost all of the evidence is internal. ITW does not publish customer win rates, retention figures, net promoter scores, or third-party studies of market-share shifts. There is no visible pattern in the public record of major lost bids, broad-based discounting, or customer defections, but that is an absence of disclosure, not the result of a documented negative search. The right conclusion is that the moat is demonstrated in outcomes but thinly evidenced from the customer's side.
For peer context, compare ITW with Parker Hannifin, Dover, Roper Technologies, Honeywell, and Emerson. Most of these still rely more heavily on acquisitions to drive growth. ITW is the outlier: an organic-first model with only occasional bolt-ons. That makes capital allocation not a side topic but a central part of the story.
VI. Capital Allocation: Buybacks, Dividends, and Disciplined (Not Absent) M&A
Imagine sitting in ITW's boardroom every quarter with the same problem. The businesses throw off far more cash than they need to reinvest. The question is not whether to deploy that cash but where. For most of its history, ITW answered that question with acquisitions. Since 2012, it has answered it overwhelmingly by handing the money back.
The numbers
Over roughly 2011 to 2025, ITW returned on the order of $26 billion through share repurchases and about $17 billion in dividends, around $43 billion combined, compared with net acquisition spending of under $2 billion over a similar period.5 Put simply, for every dollar ITW spent buying companies, it returned more than twenty dollars to shareholders.
In 2025 the company announced its 63rd consecutive annual dividend increase, and the payout has nearly tripled since 2016.17 That places ITW among the "Dividend Kings," companies with at least 50 consecutive years of increases. Coverage looks real: free cash flow has generally run near or above net income, meaning the dividend is funded by genuine cash generation rather than by borrowing or accounting earnings that do not turn into cash.45
What this reveals is a company that has decided its best use of capital is usually its own stock and its own dividend. That is a defensible choice when the core businesses earn around 30% returns on capital and few acquisition targets could be bought at prices that clear that bar. It is also a choice that shapes the growth ceiling, which the bear case will pick up later.
When ITW does buy
The exceptions are instructive precisely because they are rare and specific. In 2016, ITW acquired the engineered fasteners and components business of ZF TRW for about $450 million, a bolt-on to Automotive OEM. In 2021, it acquired MTS's test and simulation business from Amphenol for about $750 million, a bolt-on to Test & Measurement.16
Both deals fit the post-2012 pattern: modest in size relative to ITW's cash flow, tightly linked to an existing segment, and supported by a thesis about applying 80/20 to a business with room to improve margins.
Stress-testing MTS
MTS is the best test case of whether ITW's integration discipline works as advertised. Management said on the record that it would take five to seven years to bring MTS's margins up to ITW's standard. That is an unusually honest admission. Many acquirers promise synergies within 18 months and then quietly miss.
The segment evidence is broadly consistent with that timeline. Test & Measurement and Electronics posted margins of about 25% in FY2025, below the enterprise average but trending toward it roughly four years after closing.4 The integration appears to be working on approximately the schedule management set. The fair yardstick from here is simple: by around 2027-2028, the end of the stated window, this segment should be at or close to the enterprise margin level. If it stalls in the mid-20s, the "we can fix anything we buy" narrative deserves a haircut.
Discipline as a course correction
This record should be read against Section III. The same company that bought Premark as a bundle and promptly sold pieces of it is now praised for capital discipline. The current behavior is genuinely disciplined by the evidence available. But it is a learned trait, adopted after an expensive lesson and an activist campaign, not an inherited cultural constant. That distinction matters because learned traits can be unlearned under new leadership or new pressure.
"Active but disciplined," or passive?
On 2026 earnings calls, CEO Christopher O'Herlihy described the acquisition posture as "active but disciplined," noting that valuations "haven't come down much" and that ITW was "prepared to wait."23 That is a coherent stance. It is also untested in a real downturn during his tenure.
The falsification test is straightforward. If private-market and public multiples for industrial assets compress meaningfully, a disciplined buyer should step in. If ITW still does not deploy capital into acquisitions at more attractive prices, "discipline" may simply be a polite word for passivity. Investors will learn which it is only when the opportunity arrives. And how that decision gets made depends heavily on the people now in charge.
VII. Leadership Transition: O'Herlihy, Incentives, and the "Next Phase"
On September 7, 2023, ITW announced that Christopher O'Herlihy would succeed Scott Santi as CEO effective January 1, 2024, with Santi moving to Non-Executive Chairman.8 It was the kind of announcement designed to make no news at all, and that was precisely the point.
O'Herlihy is an ITW lifer. Irish-born, he spent more than three decades inside the company, including years running the Food Equipment segment and later serving as Vice Chairman with responsibility for a large part of the portfolio.8 He had lived through the pre-2012 sprawl, participated in the Enterprise Strategy rollout, and ran one of the segments that benefited most from 80/20. The succession was framed explicitly as continuity rather than a strategy reset.
Santi's legacy is substantial. Having taken over in 2012, he led the company through the Enterprise Strategy for more than a decade. Keeping him on as chairman gave the board a way to ensure the handoff did not become a pivot.
The CFO anchor
Michael Larsen has been CFO since 2013, spanning both CEO regimes.8 That matters. The capital-allocation framework described in Section VI has had one consistent financial steward for more than a decade. When investors ask whether the buyback-and-dividend-heavy posture is a Santi-era artifact, the continuity at CFO is a meaningful counterweight.
Incentives aligned to external KPIs
The 2026 proxy statement lays out a compensation structure heavily tilted toward performance. Around 81% of average named-executive-officer target pay is performance-based, and long-term incentives take the form of performance and restricted stock units rather than purely time-vested grants.9 Metrics tie to organic growth, operating margin, after-tax ROIC, and revenue contribution from Customer-Back Innovation.9
This is a credibility point. When the numbers executives are paid on are the same numbers the company reports publicly, it is harder to manage to a private scorecard.
Thin personal ownership
The CEO's stock-ownership guideline is six times salary.9 Aggregate insider ownership across directors and executive officers, however, is thin, roughly a third of one percent of shares outstanding.9 That is typical for a mega-cap, but it means alignment rests more on compensation design than on managers having a large share of their personal net worth riding on the stock.
Governance temperature
Say-on-pay votes drew roughly 93-95% support in 2024, 2025, and 2026.121110 Those are solid, unremarkable results. In 2025, a stockholder proposal seeking shareholder ratification of executive severance or "golden parachute" arrangements was defeated.11 That is a minor friction point rather than a signal of shareholder revolt.
Guidance behavior under the new CEO
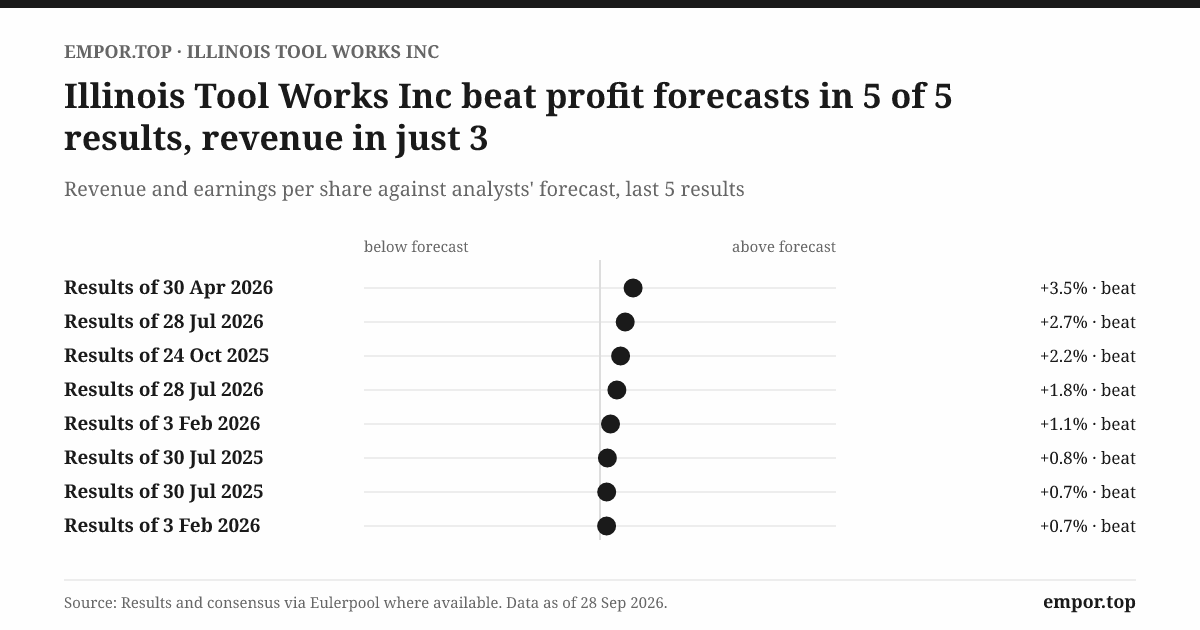
The best way to judge a new CEO's credibility is not what they say but how guidance evolves. In FY2024, ITW trimmed the top end of its guidance mid-year as automotive and industrial demand softened, attributing the change to macro conditions rather than execution.7 In FY2025, guidance was narrowed cautiously through what management repeatedly called a "choppy demand environment."6 In FY2026, by contrast, the company raised guidance after both the first and second quarters.13
The pattern so far leans toward under-promising. That is encouraging, but the sample is short, under three years, and it has not yet included a severe downturn. The more demanding test will come from the growth targets O'Herlihy has personally attached his name to.
VIII. Growth Story Stress Test: EV, China, and Customer-Back Innovation
Every mature industrial eventually faces the same investor question: margins are great, but where does growth come from? ITW's answer, developed through 2023 and 2024 under the "Next Phase" banner, is a set of explicit targets: organic growth of 4% or better through the cycle, and operating margin approaching 30% by 2030.187
The engine for the growth half is a new pillar called Customer-Back Innovation, or CBI. The concept is intuitive. Instead of inventing products in a central lab and hunting for buyers, ITW's businesses start with specific customer pain points, often discovered through the close relationships that 80/20 concentrates on the top customers, and design solutions backward from there. Think of it as a tailor measuring the client first rather than sewing a suit and hoping it fits.
CBI is ahead of its own algorithm
This is one of the few forward KPIs ITW discloses with a number attached, which makes it valuable. CBI contributed roughly 2.4 percentage points to FY2025 revenue growth and about 3 points in the first half of 2026, against a long-term target range of 2 to 3 points.43 So far, the initiative is tracking at or above its own plan.
The caveat is definitional. CBI revenue is measured by ITW itself, based on its internal classification of which sales count as coming from new, customer-driven products. There is no external audit of that classification. The number is useful mainly for tracking trend and consistency over time, not as independent proof of innovation success.
The EV story needs a harder look
Earlier bullish narratives about ITW often cast electric vehicles as a broad tailwind: more content per vehicle, higher-value components, more fasteners for batteries and thermal systems. The recent record forces a narrower version of that claim.
The growth is real but geographically concentrated. ITW has been winning content with Chinese EV makers, and management has cited low double-digit organic growth in China automotive in recent quarters.23 Meanwhile, automotive production in Europe and North America has been flat to down. In a recent quarter, Europe Automotive OEM organic revenue fell roughly 5%, and ITW guided for global vehicle builds to decline for the year.2
That is a direct, management-sourced disconfirmation of a simple "EV tailwind" thesis. ITW's own framing has shifted accordingly. Management now emphasizes content-per-vehicle outperformance versus builds, targeting growth of 200 to 300 basis points above global auto production.27 That is a more defensible claim than betting on EV unit growth. It is also a distinctly less exciting one: ITW can outgrow the auto market, but it cannot escape it.
The revised thesis is therefore: ITW's automotive growth depends on continued content wins, especially in China, offsetting Western production weakness. The confirming evidence would be sustained outperformance of 200-300 basis points above builds across a full cycle. The falsifying evidence would be China growth slowing while Western builds stay weak.
What to watch
Two things will determine whether the growth story matures. First, does China strength continue to offset Western softness, or does it fade as local competition and pricing pressure among Chinese automakers intensify? Second, does CBI keep contributing near 3 points of growth as it matures past its early innings, or does it decelerate once the easiest wins are harvested? Both questions feed directly into how durable ITW's competitive position really is.
IX. Competitive Moat Analysis: Porter's Five Forces and 7 Powers
Imagine a war game. A well-funded competitor decides to attack ITW. Where would it strike? The surprising answer is that there is no single front. ITW is not one business but dozens of niches, and no single rival competes with it across more than a handful. That fragmentation is itself a strategic feature.
Porter's Five Forces
Rivalry is intense in some micro-segments but rarely portfolio-wide. Lincoln Electric fights ITW in welding; Middleby and Ali Group fight it in food equipment; fastener specialists fight it in automotive. None fights it everywhere. That limits the risk of a coordinated competitive assault.
Supplier power is low. ITW's key inputs, such as steel, resins, and chemicals, are largely commodities with multiple sources. Input-cost inflation matters, but no single supplier holds ITW hostage.
Buyer power varies sharply. It is high in Automotive OEM, where a handful of global automakers dictate terms and demand annual price reductions. It is much lower in Welding and Food Equipment, where buyers are fragmented and aftermarket parts and consumables create lock-in. The segment margins mirror this almost perfectly: lowest in auto, highest in welding.4
The threat of substitutes is generally low for engineered, specified-in components. Once a fastener is designed into a vehicle platform or a testing protocol is embedded in a quality system, replacing it requires re-engineering and re-qualification.
The threat of new entrants is modest in most niches. The markets are too small to attract giants and too technical for newcomers to enter cheaply.
Hamilton Helmer's 7 Powers
Helmer's framework asks which of seven sources of durable advantage a company possesses: scale economies, network effects, counter-positioning, switching costs, branding, cornered resource, and process power.
The strongest candidate for ITW is process power. The 80/20 Front-to-Back methodology and now CBI are simple to describe but difficult to replicate consistently across dozens of businesses. Many industrials have tried lean programs and portfolio simplification; few have sustained a decade-long, still-compounding margin gap. The evidence for process power is the persistence of ITW's margin and ROIC advantage over peers that run looser or more acquisition-dependent models.418
Switching costs are a secondary power in specific segments: Test & Measurement, Food Equipment aftermarket, and specified-in automotive components. Branding matters in welding, where Miller has a loyal user base. Scale economies exist within individual niches but are not an enterprise-wide advantage.
The weakest link
The weakest part of the moat story is evidence quality. Process power is inferred from financial outcomes, which is legitimate but indirect. Switching costs are asserted more than documented; ITW does not disclose retention rates or win rates. Claims of counter-positioning or cornered resources are not supported by the public record and should not be overstated.
The calibrated conclusion: ITW's process advantage is real in its outcomes and has survived more than a decade, which is meaningful. Its customer-facing moat is plausible but under-documented. The single best ongoing test is whether ITW keeps expanding margins while CBI adds growth; if margins stall or growth requires discounting, the process-power thesis narrows. That test sits at the heart of the bull and bear debate.
X. Bull Case, Bear Case, and the Activist Shadow
Picture two analysts in the same meeting. One points to a decade of rising margins, a 63-year dividend streak, and a clean CEO transition. The other points to a stock that already trades at a premium, a growth target that is modest even if achieved, and an automotive business caught between Chinese growth and Western weakness. Both are looking at the same company. Both are right about what they see.
The bull case
Margins and ROIC are best-in-class among diversified industrials, and they got there through sustained improvement rather than a single cost cut.418 Capital allocation has been consistent and shareholder-friendly for more than a decade, with overwhelming emphasis on buybacks and dividends.517 The leadership transition has been orderly, with continuity at both the CEO philosophy level and in the CFO seat.8 CBI is running at or above its stated targets, offering a credible, measurable path to better organic growth.3 And in the SEC filings reviewed for this piece, covering recent annual reports, no restatements, material weaknesses, or SEC enforcement actions were identified.5
The bear case
Organic growth remains structurally modest. Even the aspirational target of 4% or better through the cycle is a low-single-digit growth rate.7 Automotive OEM, the largest segment, is also the lowest-margin one and the most exposed to Western production weakness and China concentration.42
The acquisition-light posture cuts both ways. Roper and Danaher-style models redeploy free cash flow into acquisitions that compound earnings at high rates. ITW largely forgoes that option. Whether that is discipline or missed optionality depends on what happens the next time valuations fall.
Insider ownership is thin, so alignment rests heavily on compensation design rather than personal balance-sheet exposure.9
The activist shadow
Now apply an activist's lens. The uncomfortable origin story is that the metrics bulls cite today followed external pressure in 2011-2012.13 No activist has returned since, which is reassuring but not decisive. A skeptical activist today might ask several pointed questions. Is the Automotive OEM segment worth keeping at its margin level, or would a separation unlock value? Is ITW's buyback program being executed at prices that create value, or simply because cash is available? And does "prepared to wait" on acquisitions mean ITW has no pipeline of attractive targets?
None of these are signs of failure today. They are the questions a premium valuation invites, because a premium valuation embeds an assumption that the discipline will hold without outside pressure indefinitely.
The net framing
The numbers are genuinely excellent and well documented. The open question is less whether ITW is a good business and more how much of the next decade's performance is already reflected in expectations. The margin target of approaching 30% by 2030 is not a hidden upside; it is a publicly stated plan that the market can already see.7 The risk, then, is not that ITW is bad but that "very good" is already assumed. That makes the specific risks worth mapping carefully.
XI. Risk Radar
Every quality compounder has a small number of mechanisms that could break its story. For ITW, they are specific and traceable.
Cyclical demand
Automotive OEM and Construction Products are both tied to end-market cycles, and management repeatedly described demand as "choppy" through 2024 and 2025.67 This was not just a hedge phrase; it accompanied guidance trims and narrowing. The mechanism is straightforward: when builds and construction slow, volume drops, and even a highly efficient cost structure cannot fully offset lower volume.
Geographic concentration inside the growth story
As Section VIII showed, automotive growth increasingly depends on China while Western production weakens. The mechanism to watch is whether pricing pressure among Chinese automakers eventually flows down to suppliers, or whether geopolitical tension changes the economics of serving those customers.
Currency
ITW earns a large share of revenue outside the United States. Currency swings have been explicitly quantified in guidance, including a stated foreign-exchange headwind built into FY2025 EPS guidance.7 This is not an existential risk, but it can shift reported earnings meaningfully in a given year.
Competitive discipline in the best segments
Welding and Food Equipment earn the richest margins because they operate in concentrated markets with rational competitors, Lincoln Electric and ESAB in one, Middleby and Ali Group in the other. The mechanism that would hurt ITW most is a shift in competitor behavior: a price war, an aggressive share grab, or a new entrant with a structural cost advantage. There is no sign of this today, but it is the risk that would hit the highest-margin profit pools first.
Execution on 2030 targets and CBI
The 30%-by-2030 margin target and CBI scale-up are still early. With only around two years of CBI contribution data, the key question is whether CBI growth decelerates as the easier opportunities are exhausted. If CBI stalls while margins plateau, the "Next Phase" story would weaken materially.
The KPIs that matter
For investors tracking ITW from here, three KPIs capture most of the story. First, organic revenue growth, the clearest test of whether CBI and content gains can lift ITW above its historical low-single-digit pace. Second, operating margin, the scorecard for whether 80/20 discipline is still compounding toward the 2030 target. Third, CBI's contribution to revenue growth, the leading indicator of whether the new growth engine is real and durable. Those three numbers together answer the question the rest of this story has been circling.
XII. Playbook, Lessons & Closing Reflections
Return, for a moment, to the six-pack ring. A thin loop of plastic, invented to solve a bottler's problem, sold for decades at attractive margins because it quietly did its job. That product embodied ITW's original genius: small things, engineered well, sold to customers who value reliability. What the company lost for a while, and then deliberately rebuilt, was the discipline to keep that genius from drowning in complexity.
Decentralization needs a spine
The core lesson is that decentralization without operating discipline eventually becomes complexity. ITW's history from the 1990s through the late 2000s, the Premark bundle and the drift toward roughly 800 units, is the cautionary case. The 80/20 system and now CBI are the corrective structure, not a philosophy that was right from day one. Autonomy works best when every unit operates under the same demanding rules about where to focus.
Subtraction as strategy
A second lesson is about how returns get made. ITW's roughly doubled ROIC came as much from subtraction as addition: consolidating units, exiting weaker businesses, and trimming the long tail of low-profit products and customers.18 Many companies chase growth by adding. ITW showed that removing can create just as much value, and sometimes more.
What activism can reveal
A third lesson is less comfortable for management teams. Sometimes the best-run version of a company only emerges after outside pressure forces a diagnosis leadership had not prioritized. That does not diminish the decade of execution that followed. It should make investors wary of any "we always knew" narrative that omits the moments when change was demanded rather than volunteered.
The final framing
ITW today is less a growth story than a quality-compounding story. The central open question for the coming years is whether Customer-Back Innovation can give the company back meaningful organic growth without diluting the margin discipline that took more than a decade to build. If organic growth rises while margins keep climbing, the anti-conglomerate will have found its next chapter. If growth stays modest and margins plateau near their targets, ITW will remain an exceptionally well-run industrial whose excellence is already widely understood. Either way, the company that makes the parts nobody notices has become a case study that every industrial operator should notice.
References
-
ITW Reports Second Quarter 2026 Results and Raises Full-Year 2026 Guidance — ITW Investor Relations, 2026-08-06 ↩
-
Earnings call transcript: Illinois Tool Works beats Q2 2026 estimates, lifts outlook — Investing.com, 2026-07-28 ↩↩↩↩↩
-
ITW Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-04-30 ↩↩↩↩↩
-
ITW Reports Fourth Quarter and Full Year 2025 Results — GlobeNewswire, 2026-02-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Illinois Tool Works Q3 2025 shows EPS beat — Investing.com ↩↩
-
Illinois Tool Works (ITW) Q4 2024 Earnings Call Transcript — The Motley Fool, 2025-02-05 ↩↩↩↩↩↩↩
-
ITW Announces CEO Succession Plan — GlobeNewswire, 2023-09-07 ↩↩↩↩
-
ITW 2026 DEF 14A Proxy Statement — SEC EDGAR, 2026-03-27 ↩↩↩↩↩
-
ITW 8-K: 2026 Annual Meeting Voting Results — SEC EDGAR, 2026-05-08 ↩
-
ITW 8-K: 2025 Annual Meeting Voting Results — SEC EDGAR, 2025-05-02 ↩↩
-
ITW 8-K: 2024 Annual Meeting Voting Results — SEC EDGAR, 2024-05-03 ↩
-
Illinois Tool Works and Relational Investors Announce Cooperation Agreement — PR Newswire, 2012-01-13 ↩↩↩↩↩↩
-
ITW 8-K: Relational Investors Cooperation Agreement — SEC EDGAR, 2012 ↩
-
ITW Expected to Sell Premark Businesses — Crain's Chicago Business, 1999-09-11 ↩↩
-
ITW to Acquire MTS Test & Simulation Business From Amphenol — Amphenol Investor Relations, 2021 ↩↩↩
-
Illinois Tool Works Delivers 63rd Straight Dividend Hike, Nearly Tripling Payouts Since 2016 — 24/7 Wall St, 2026-04-10 ↩↩↩
-
ITW Enterprise Strategy Overview — ITW Corporate Site ↩↩↩↩↩↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube