Invitation Homes: The Institutionalization of the American Rental House — and the Law That Just Capped It
I. Introduction & Episode Roadmap
On a July morning in 2026, somewhere in a subdivision outside Atlanta, a maintenance technician in a company-branded van pulled up to a three-bedroom ranch house with a smart lock on the front door and a thermostat that could be adjusted from a phone in Dallas. The house looked like every other house on the street. That was the point. Nobody driving by could tell that it belonged to a publicly traded real estate investment trust in the S&P 500, one of roughly 85,500 homes owned outright by a single company.1 And nobody on that street could have known that, the same month, the United States Congress had just made it illegal for that company to buy the house next door.
That company is Invitation Homes, the largest owner of single-family rental homes in the United States. It operates across 17 markets, overwhelmingly in the Sunbelt, the West, and Florida, and it generated roughly $2.7 billion of revenue in 2025.1 Its market capitalization sits in the neighborhood of $16–17 billion, small for an S&P 500 member but enormous for a business that, fifteen years ago, did not exist as an asset class at all.2
For seventeen years, if you count the pre-history of its co-founder, the company's growth rested on one repeatable move: buy more existing single-family homes than anyone else, fix them up to a standard specification, and rent them out with the operating discipline of an apartment REIT. The move worked. It survived an IPO, a merger, a pandemic housing boom, and a federal consumer-protection case. Then, on July 11, 2026, the 21st Century ROAD to Housing Act became law, and among its provisions was a bar on "large institutional investors" — entities controlling 350 or more single-family homes — purchasing existing single-family homes.34
That creates the central question of this story: how does the company that industrialized buying single-family homes for rent build a second growth engine after Washington told it to stop buying?
The answer runs through four themes that recur across the episode. First, crisis-born scale: Invitation Homes is a child of the 2008 housing collapse, and its balance sheet, footprint, and culture still carry that birthmark. Second, the fragmented-market rollup playbook: the thesis that professional operators can outcompete millions of mom-and-pop landlords, and the question of how much of that thesis is proven versus asserted. Third, the limits of scale economics once politics notices them: the same scale that made the company efficient made it a target, first of the Federal Trade Commission and then of a near-unanimous Congress. Fourth, the forced pivot of a founder-CEO, Dallas Tanner, from acquirer to builder-and-manager.
The article moves chronologically through the origin and the land-grab years, then spends its longest stretch on the machine as it runs today: what the business earns, how it earns it, and whether the claimed competitive advantage holds up against the evidence. It then puts that customer-experience claim through its hardest test, the FTC case, before turning to the ban, the company's response, the management team making that response, and the competitive and risk landscape that will decide whether it works.
One framing point matters up front. This is not a story about a business in operating distress. Occupancy is high, rents are still rising, and the company is profitable. It is a story about a business whose growth model was rewritten by statute while its operations kept humming, which is a stranger and in some ways harder problem. A struggling business knows what to fix. A healthy one that has been told its main growth lever is closed has to invent a new one while the old machine keeps running.
To understand why that lever mattered so much, the story has to start where the company did: in the wreckage of the American housing market.
 Subscribe on LinkedIn
II. Origins: A Post-Crisis Bet and Its Co-Founder
Phoenix, 2010
Picture Phoenix in 2010. Whole subdivisions on the city's edges sat half-finished, their stucco shells baking under a desert sun, their would-be owners gone. The metro area had been one of the epicenters of the subprime boom, and it became one of the epicenters of the bust. Nationally, the Case-Shiller index had fallen by roughly a third from its 2006 peak, and millions of single-family homes moved through foreclosure. The buyers who showed up at the courthouse-step auctions were individuals, small investors, and flippers. There was no institutional buyer for single-family homes, because single-family homes had never been an institutional asset. They were too scattered, too heterogeneous, and too operationally messy for large capital to own.
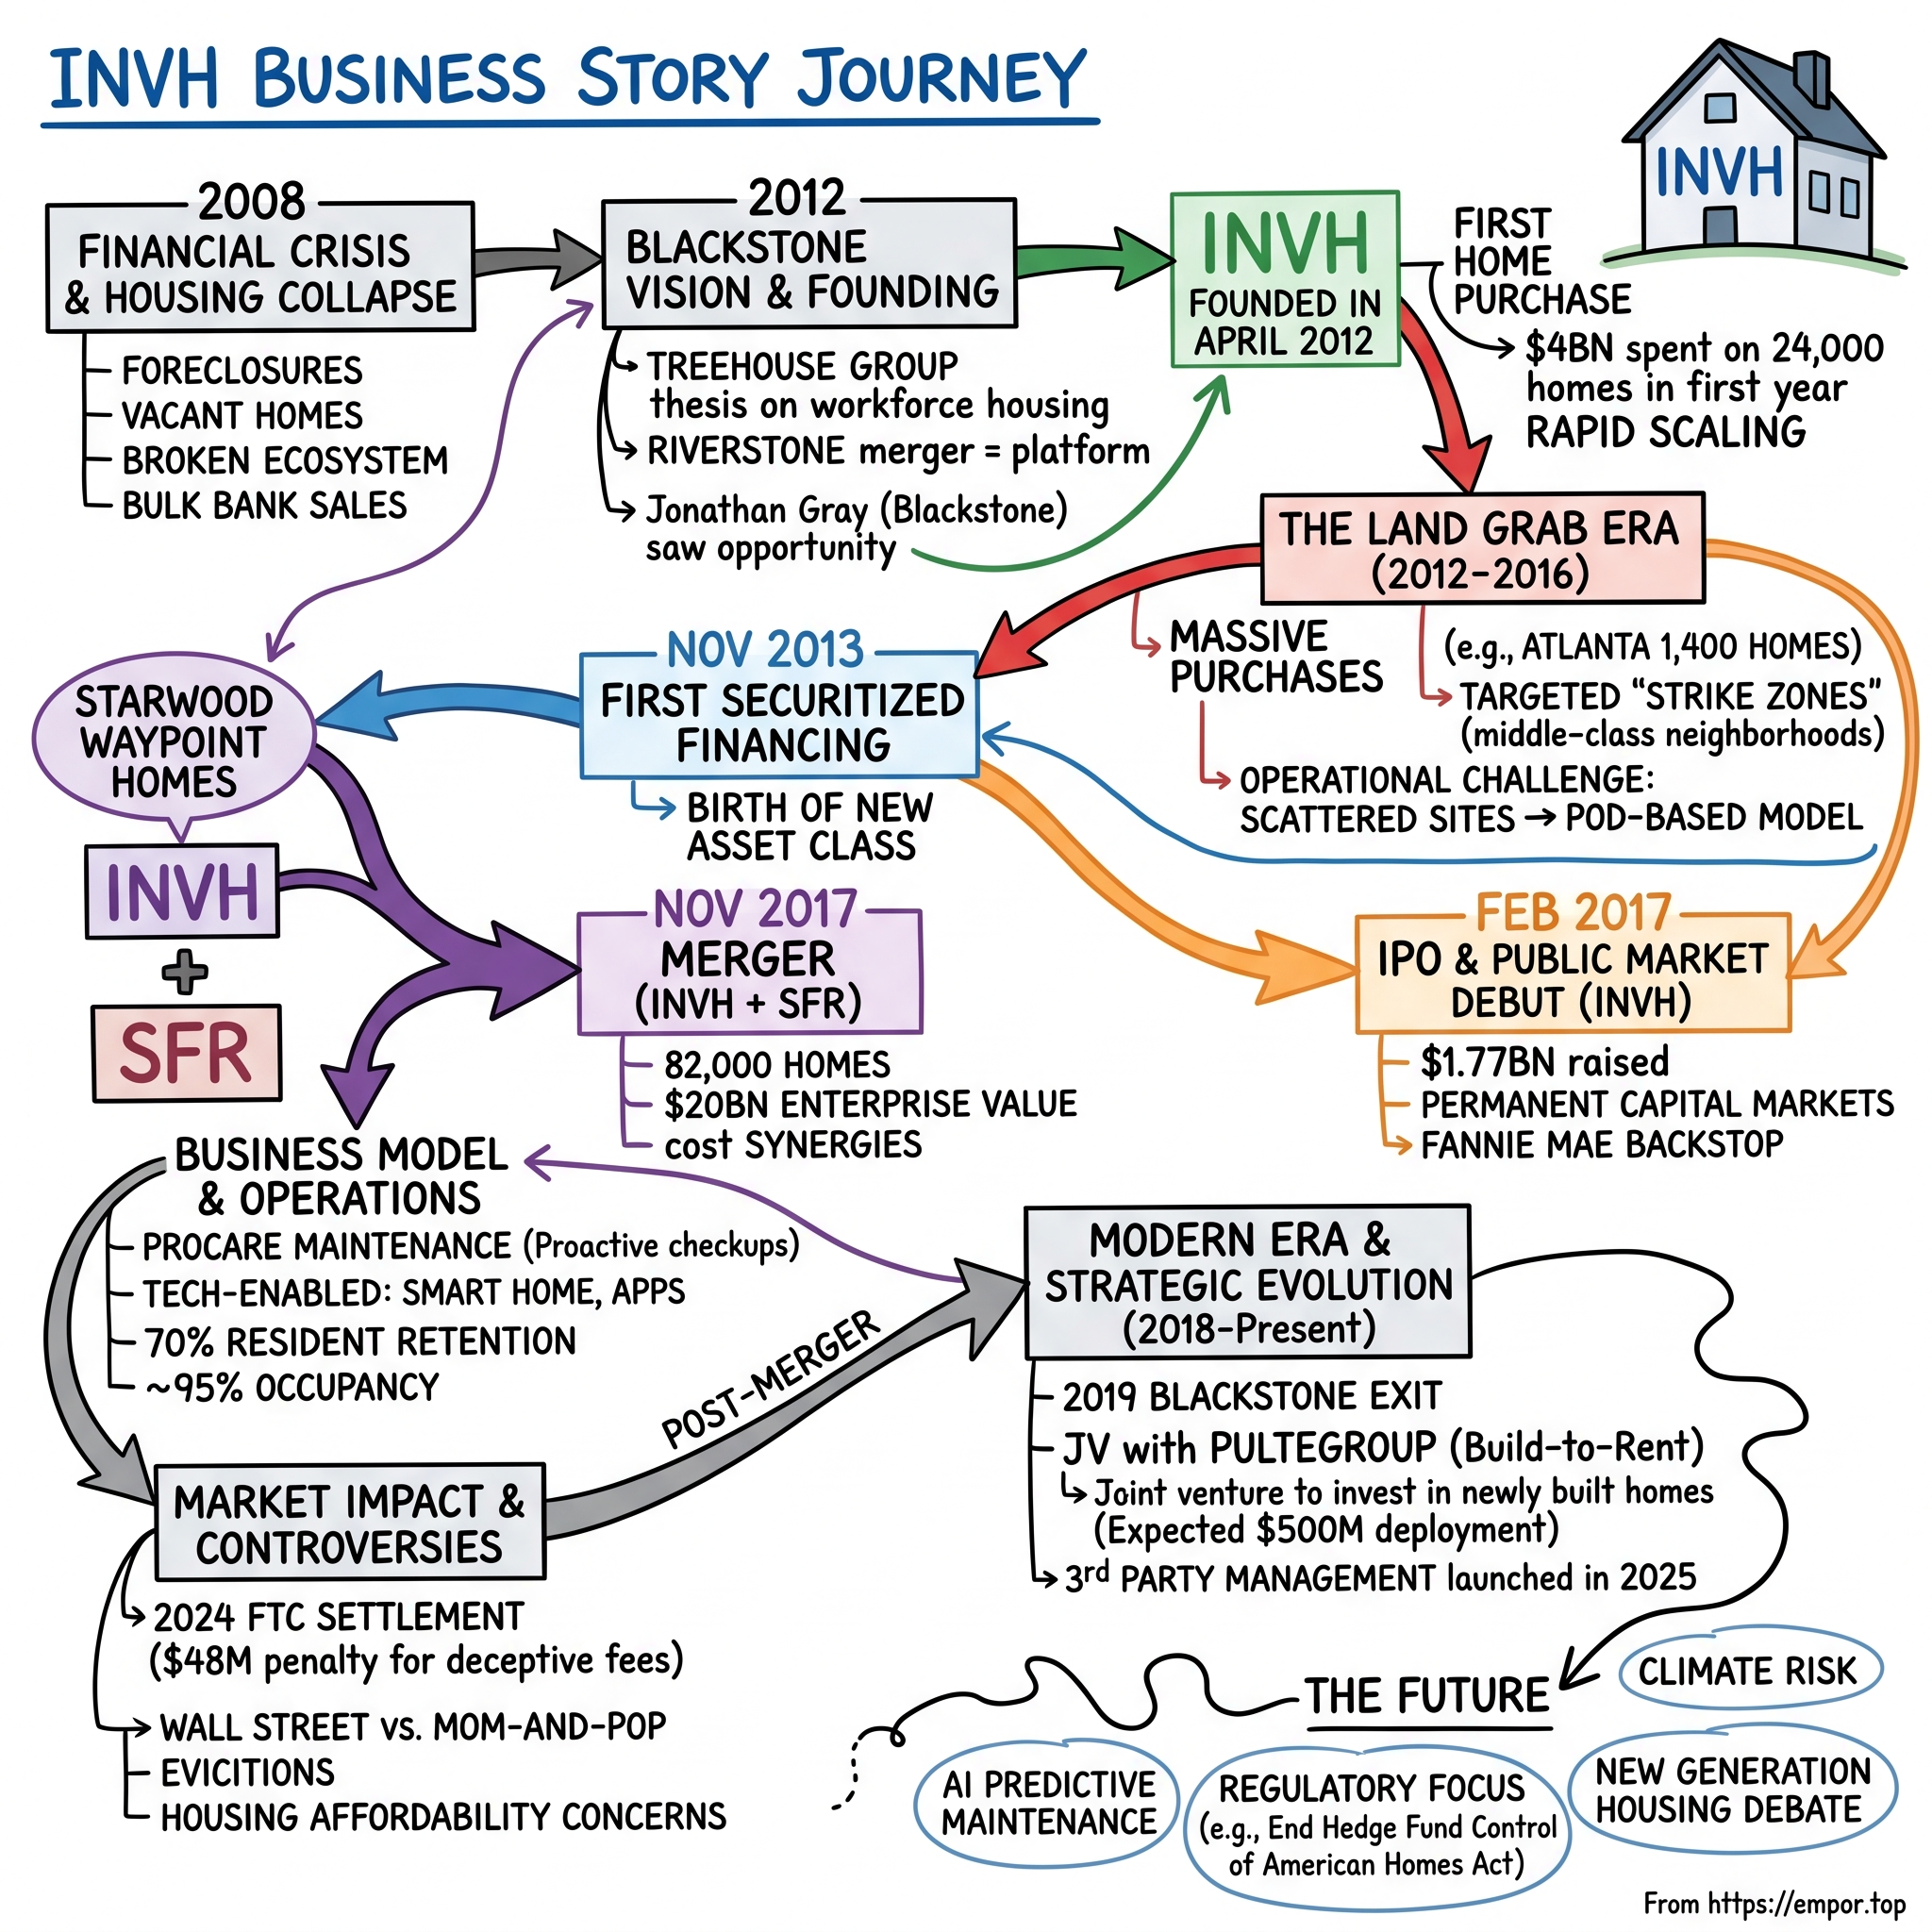
A young operator named Dallas Tanner saw that gap before most of Wall Street did. Tanner had co-founded Treehouse Group in 2005, a small real estate investment firm, and by 2010 and 2011 it was buying distressed homes in Phoenix, one by one.5 Treehouse later combined with Riverstone Residential's single-family efforts, and in 2012 Blackstone folded these operating teams into a new vehicle it called Invitation Homes.56
The detail matters for a reason that goes beyond biography. The person who was buying foreclosed houses in Phoenix in 2011 is the same person running Invitation Homes in 2026. Few large public companies can say their co-founder has been present for every chapter of the story. That continuity will become important later, when the question turns to whether management's pivot away from acquisitions is credible. The CEO is not a hired steward inheriting someone else's playbook. He wrote the playbook that is now being retired.
Blackstone's checkbook
Blackstone brought what Tanner's operation lacked: an almost limitless supply of patient capital at the bottom of a cycle. The first Invitation Homes house was bought in Phoenix in April 2012, and within roughly a year the company had deployed about $4 billion across some 24,000 homes.6 That pace is hard to overstate. It meant buying, on average, dozens of houses every business day, each one requiring an inspection, a renovation scope, a price, and eventually a tenant.
The thesis, stated plainly, was that professional, technology-enabled management could convert a cottage industry into an institutional asset class. Single-family rental housing had always existed, but it was owned by dentists with two rental houses, retirees with one, and small local operators with a few dozen. Blackstone's wager was that scale would bring cheaper financing, cheaper maintenance, better pricing data, and a consistent product, and that those advantages would compound into returns that justified owning tens of thousands of houses on a spreadsheet.
That thesis is now well-trodden history, and its main relevance today is explanatory. It explains why the portfolio is concentrated in the markets that crashed hardest and recovered fastest, why the company carries REIT-typical leverage, and why its CEO has a tenure that stretches back to the courthouse steps. It also explains the core vulnerability that the 2026 law exposed: the company was built as a buyer. The engine was acquisition, and everything else was designed around feeding it.
What kind of operator does that background produce? Distressed-home investing in that era rewarded speed, local knowledge, and a tolerance for messiness: houses frequently bought at auction with limited inspection, renovated by crews assembled quickly, and rented to families who had sometimes just lost homes of their own. It is a background built around acquisition. For most of his career, the core skill was finding and buying houses. The skill now in demand is building and managing them.
For investors, the origin story is less a romance than a map. The footprint drawn in 2012 is still, with modifications, the footprint that determines Invitation Homes' exposure to Florida insurance costs, Sunbelt supply, and state-level politics in 2026. And the man who drew it is still holding the pen. What he did next was scale that footprint into a public company.
III. Building Scale, Going Public, and the Starwood Waypoint Merger
The land-grab years
Between 2012 and 2016, Invitation Homes behaved like a company in a race, because it was. Other large investors, including Colony, Starwood, American Homes 4 Rent, and a handful of private funds, were chasing the same distressed inventory. The winners would be the ones who could underwrite, close, renovate, and lease faster and more consistently than the others.
Invitation Homes' answer was a discipline it called the "strike zone": target homes of a particular size and price band, located near employment centers, good schools, and transportation corridors, in neighborhoods where residents were likely to stay for years.7 The idea was that a standardized product in a predictable location would rent faster, turn over less, and be cheaper to maintain. Operations were organized into local pods of homes clustered tightly enough that a single maintenance technician or leasing agent could cover them efficiently. It is the same logic a pizza chain uses when it decides where to put delivery kitchens: density drives unit economics.
The capital markets innovation was arguably more important than the operating one. In late 2013, Invitation Homes completed the first securitization backed by single-family rental income, pooling the rent streams from thousands of homes into a bond that investors could buy.6 Think of it as turning thousands of individual leases into something that looked, to a bond buyer, like a commercial mortgage. That structure gave the company access to cheaper, longer-dated debt than any individual landlord could obtain, and it helped legitimize single-family rentals as an institutional asset class. It was a genuine first, and it remains one of the clearest examples of scale translating into a durable cost advantage: the cost of capital.
The IPO
On February 1, 2017, Invitation Homes listed on the New York Stock Exchange under the ticker INVH. The IPO raised about $1.77 billion, making it the second-largest REIT IPO in U.S. history at the time.7 For Blackstone, it was the beginning of an exit. For the company, it was the moment it became accountable to public-market investors who would judge it quarterly on occupancy, rent growth, and funds from operations rather than on the eventual sale price of a private fund.
Starwood Waypoint: a merger priced off relative NAVs
Six months later, the company made its defining corporate transaction. In August 2017, Invitation Homes agreed to merge with Starwood Waypoint Residential Trust in a 100% stock-for-stock deal. The combined company had an equity value of about $11 billion and a portfolio of roughly 82,000 homes, and management targeted $45–50 million of annual run-rate cost synergies.7
The structure matters for how investors should judge it. This was not a premium cash acquisition in which one company paid a large control premium and then had to earn it back. It was closer to a merger of equals, with the exchange ratio set largely off the relative net asset values of two portfolios of similar homes in overlapping markets. The combined company got denser footprints in its core cities, which fed directly into the pod-based cost logic described above. That is why the transaction does not belong in the file of acquisitions that destroyed value through overpayment. The integration risk was real, but the price risk was contained by the structure.
The larger lesson is that the merger was the rollup thesis applied to the rollers. If scale economics were real at the house level, they should also be real at the platform level, and combining the two largest portfolios in overlapping markets was the logical next step. The ensuing years, with occupancy consistently in the high 90s, suggest the operational integration held. Whether it produced the full synergy target is less clearly documented in later disclosures, and that gap should be noted rather than filled with assumption.
Myth vs. reality: Blackstone's "control"
A common retrospective narrative casts Invitation Homes as a Blackstone-controlled company for years after the IPO. The record says otherwise. Blackstone sold down through a series of secondary offerings in 2018 and 2019, and in November 2019 it sold its entire remaining position, roughly an 11% stake, for about $1.7 billion.8 Across the sell-down, Blackstone realized on the order of $7 billion from the public company. Since late 2019, Invitation Homes has been a fully independent, widely held public company with no controlling sponsor. That precision matters because it places responsibility for every subsequent strategic decision, including the FTC-era fee practices and the response to the 2026 ban, on the public company's own board and management rather than on a private-equity parent.
The ironic postscript
The sponsor that created Invitation Homes and fully exited it did not stay out of the asset class. In May 2024, Blackstone Real Estate completed its privatization of Tricon Residential, a Toronto-based owner of single-family rental homes in the U.S. Sunbelt, in a transaction with a total equity value of about $3.5 billion.9 Blackstone highlighted Tricon's pipeline of newly built single-family homes as part of the rationale.9 In hindsight, the emphasis on new construction looks prescient. Sophisticated institutional capital was still buying into single-family rentals as a category even as the political risk around existing-home acquisitions was building, and it was tilting that exposure toward new supply.
For investors, the takeaway from this chapter is that Invitation Homes' scale was bought, merged, and securitized into existence with considerable skill, and that the sponsor's full exit five years ago makes the current team the sole owner of the results. The next question is what that scale actually produces today.
IV. The Machine Today: Business Model, Unit Economics, and Industry Structure
A house as a product
Walk into a vacant Invitation Homes house between tenants and it will feel oddly familiar, even if it is in a market the visitor has never seen. The paint colors come from a short list. The flooring is durable vinyl plank rather than carpet. The front door has a smart lock that lets a prospective renter tour the home without an agent, and the thermostat and leak sensors report to a central system. The house has been turned into a product: specified, standardized, and serviced by a company-employed technician rather than a landlord's brother-in-law.
How a rental house makes money
Before weighing the moat, it helps to understand the arithmetic of a single house, because the whole company is that arithmetic multiplied by tens of thousands. A rental home produces rent. From that rent, the owner pays property taxes, insurance, homeowners-association dues, repairs, and the cost of managing the tenant. What is left is net operating income, the property-level profit before financing costs and corporate overhead. Divide that income by what the house is worth and the result is the yield, which real estate investors call a cap rate.
The single most destructive event in that arithmetic is turnover. When a tenant leaves, the house earns nothing for weeks while it is cleaned, repainted, repaired, marketed, and shown. A turnover can easily consume a month or more of rent, and in older homes it often triggers the replacement of worn-out carpet or appliances. A landlord whose tenants stay four years instead of two effectively earns an extra month or more of rent over that span, without raising the price at all.
This is why the institutional operators obsess over retention, standardized finishes, and preventive maintenance. Durable flooring survives more tenants. A smart lock means a vacant house can be toured without paying an agent. Pooling repairs across a pod of nearby homes means a technician drives minutes, not hours, between jobs. None of these is glamorous. Together they are the difference between a margin that works at institutional scale and one that does not.
The product
That productization is the business. Invitation Homes reports a single business that leases and manages single-family homes.1 A nascent third-party management platform, which manages homes owned by other investors for a fee, is real and growing but still accounts for only about 3% of revenue.10 Everything else, which is to say the overwhelming majority of revenue, net operating income, and enterprise value, comes from collecting rent on houses the company owns. Any assessment of Invitation Homes today is fundamentally an assessment of that owned-home rental machine.
Where the houses are
The portfolio is a Sunbelt-and-Florida book. Roughly 35% of homes are in the Western U.S., 31% in Florida, and 22% in other Southeast markets.1 By 2025 revenue, the top five markets were Atlanta at about 12.9%, South Florida at 11.9%, Southern California at 10.9%, Tampa at 10.7%, and Phoenix at 9.5%.1 Put differently, more than half of revenue comes from five metro areas, and Florida alone is nearly a third of the portfolio.
That concentration was a feature during the pandemic, when migration to warm, lower-tax states pushed rents up sharply. It becomes a vulnerability when the conversation turns to hurricane exposure, property insurance premiums, and property-tax reassessments, all of which hit Florida and the Gulf Coast hardest. That thread will return in the risk discussion; for now, it is enough to note that the geography that powered the growth story also defines the expense risk.
The operating cadence: decelerating, not deteriorating
The second quarter of 2026 offers a clean snapshot. Average occupancy was 97.1%.2 Blended rent growth, which combines renewals and new leases, was 2.7%, made up of 3.3% on renewals and just 1.1% on new leases.2 Same-store revenue grew 1.6%, and same-store net operating income grew 1.5%.2
What does that pattern say? First, demand is intact. Occupancy above 97% means almost every house that can be rented is rented, and that is not what a business in a demand crisis looks like. Second, pricing power has faded from the pandemic peak. The gap between renewal growth and new-lease growth is the telling detail. Existing tenants, who face moving costs and the hassle of finding another house, accept 3% increases. New tenants, who can shop the market, are paying barely more than the last tenant did. That suggests the company's leverage over price comes largely from resident inertia, not from a product so differentiated that new customers pay up for it. Third, expenses are growing roughly in line with revenue, which is why same-store NOI growth tracks revenue growth rather than outpacing it. There is no operating leverage showing up in the current numbers.
The honest reading is a healthy but slowing business: growth that is positive, modest, and increasingly dependent on renewals.
The financial shape
Revenue grew from about $2.24 billion in 2022 to about $2.73 billion in 2025, a compound growth rate of roughly 7% a year that includes both rent growth and portfolio additions.61 Net income in 2025 was about $588 million, and EBITDA was roughly $1.47 billion.111 Net debt stood at about 5.6 times EBITDA.11
That leverage figure is typical for a REIT, which is designed to distribute most of its income and fund growth partly with borrowed money. It is not a red flag on its own. But it does mean the equity is sensitive to interest rates in two ways: through the cost of refinancing existing debt as it matures, and through the valuation multiple the market is willing to pay for a stream of rental income when bonds offer competitive yields. A 5.6x ratio leaves room to operate but not much room to be careless.
The claimed moat
Management's case for why Invitation Homes wins rests on scale economics in a fragmented market. The company argues that its technology-driven leasing and revenue management, its in-house maintenance organization (branded ProCare), its standardized smart-home package, and its resident retention of roughly 80% give it cost and service advantages that a landlord with one or two homes cannot replicate.101
Some of that is intuitively persuasive. A company that buys thousands of water heaters negotiates a better price than a retiree who buys one. A company that pre-emptively replaces HVAC filters across a pod of homes spends less on emergency repairs. A company with data on tens of thousands of leases prices each vacant home more precisely than a landlord guessing from Zillow. And turnover is the single most expensive event in a rental home's life, involving vacancy, cleaning, repairs, and marketing, so any system that keeps residents longer saves real money.
Weighing the evidence honestly
The evidence for the moat is strongest where it is most measurable. Occupancy and retention are genuinely high and have been consistently reported for years. The company's cost of debt, a legacy of the securitization and investment-grade credit work, is structurally lower than a small landlord's.
But there are two important limits. The first is market share. Institutional investors own well under 1% of the roughly 16–17 million single-family rental homes in the United States. Invitation Homes, at about 85,500 owned homes, is a large company and a tiny share of its market.1 The "professionalization" opportunity is real, but the company's slice of it is small. That means scale-versus-mom-and-pop economics works as a unit-economics argument, lower turnover cost and better vendor pricing, but not as evidence of pricing power or market control. Invitation Homes sets rents inside local markets priced overwhelmingly by other owners.
The second limit is peer comparison. The relevant competitive question is not whether Invitation Homes beats a retiree with a rental house. It is whether it beats other scaled operators, and on that question the evidence is thin. American Homes 4 Rent, Progress Residential, FirstKey Homes, and Amherst Residential all run standardized, technology-enabled platforms with in-house maintenance and smart-home packages. High occupancy and retention are characteristic of scaled operators generally, not unique to Invitation Homes. No public data point reviewed for this article demonstrates a technology or service edge over those peers.
The conclusion is that the moat claim survives in a narrower form: Invitation Homes has real scale economies versus small landlords, which show up in cost and retention, but has not demonstrated a durable advantage over other institutional operators. The claim is intact but unproven at the level that matters most for relative returns.
The KPIs that matter
Three measures will do most of the work in tracking whether the machine is getting stronger or weaker. The first is blended and same-store rent growth together with same-store NOI growth, which together show whether the company can raise prices faster than costs. The second is average occupancy, the most direct gauge of demand and operational execution. The third is growth in the count of third-party fee-managed homes, the new capital-light growth vector discussed later. The first two measure the old engine; the third measures whether a new one is being built.
The competitive field
American Homes 4 Rent, known as AMH, is the only other large publicly traded pure-play single-family rental REIT, with roughly 60,000 homes and a market capitalization around $11 billion.12 Its most important difference from Invitation Homes is not size but strategy. AMH began building its own homes years ago. In the third quarter of 2021, about 27% of its home additions came from its internal development program; by the third quarter of 2025 that share had risen to 92%.12 In other words, AMH had already largely stopped depending on buying existing homes before the law required it. Invitation Homes is years behind on that specific capability.
Behind the public names sit large private operators, including Progress Residential, FirstKey Homes, and Amherst Residential, each operating tens of thousands of homes. They disclose less, but they compete for the same houses, the same tenants, and increasingly the same third-party management mandates.
The machine, then, is healthy, scaled, and cost-efficient, but not demonstrably superior to its best peers. And one part of the moat argument, the customer experience, faced a very public stress test before the ban ever arrived.
V. Trust, Fees, and the FTC: A Stress Test of the Customer Promise (2021–2024)
The bill after the lease
Imagine signing a lease on a house at a quoted monthly rent that fits the family budget, and then, after the lease is signed and the moving truck is booked, discovering a stack of additional mandatory charges: a fee for the smart-home technology already installed in the house, a fee for utility billing management, a fee for filter delivery. None of them optional. Together they could add close to $2,000 a year.
That, according to the Federal Trade Commission, is what many Invitation Homes renters experienced. In September 2024, after a roughly three-year investigation, the FTC announced a settlement under which Invitation Homes agreed to pay $48 million to be returned to consumers.13 The agency alleged that the company advertised rents that omitted mandatory fees, collecting tens of millions of dollars in undisclosed charges.13 It further alleged that the company failed to disclose the true condition of homes and failed to inspect them properly before move-in, unfairly withheld security deposits by charging departing tenants for normal wear and tear, and used unfair practices around evictions, including during the pandemic.13 The court-approved order required all-in pricing disclosure going forward, and Invitation Homes did not admit wrongdoing.1415
Not a closed chapter
In March 2026, the FTC began mailing refund checks totaling more than $47.2 million to affected renters.16 That timing matters. For an investor reading the file in 2024, the settlement looked like a closed legal matter. For renters opening envelopes in 2026, it was fresh news, landing in the same months that Congress was debating whether companies like Invitation Homes should be allowed to buy houses at all. The remediation is still unwinding, and its political echo arrived at the worst possible time.
Weighing it
How material is this? Financially, not very. The settlement was roughly 2% of a single year's revenue, and the conduct covered a defined window, roughly 2021 through 2023, that has been subject to mandated process changes.13 Nothing in the order impaired the company's ability to operate or required a change to its fundamental business model.
Reputationally and analytically, it is more significant, because of what it tests. The company's brand promise is built around "choice, flexibility, and high-quality single-family living," and management has pointed to strong retention as evidence that residents value the experience.1 The FTC's allegations cut directly against that argument. If part of the economics of the platform came from charges that renters did not know they were agreeing to, then some of what looked like operating excellence was actually fee extraction. High retention is also a weaker argument than it appears when moving is costly and the alternative landlord is similar: people can stay in a house while being unhappy with how they are billed.
The base rate matters too. The "junk fee" push under the prior FTC swept across rental housing, and undisclosed-fee scrutiny hit multiple large landlords and property managers in the same period. That suggests the behavior was an industry pattern rather than a uniquely Invitation Homes management failure. But the base rate cuts both ways. If scaled operators across the sector were layering on similar fees, then fee practices were never a source of differentiation. The evidence narrows the claim that superior customer experience is a durable competitive advantage: it looks less like a moat and more like an industry standard that the regulator pushed everyone toward.
The forward test
Two things will show whether the remediation took. The first is whether renewal rates and retention hold up under all-in pricing, which removes the ability to quote a low headline rent and recover margin through fees. So far, renewal rent growth above 3% and retention around 80% suggest the model survived the change.2 The second is whether follow-on private litigation emerges from the same facts. No such major action was identified in the sources reviewed for this article, but that is a bounded observation, not an assurance.
The FTC case was a warning about something larger than fees. It showed that scale in housing invites scrutiny in proportion to its visibility, and that scrutiny was about to arrive in a far more consequential form.
VI. The Ban: How a Federal Law Rewrote the Growth Playbook (2025–2026)
A post, then an order, then a law
On January 7, 2026, President Trump posted that he wanted to ban large institutional investors from buying single-family homes.4 Thirteen days later, on January 20, he followed with an executive order directing action on the issue.4 For an industry that had spent a decade arguing it was a small and misunderstood participant in the housing market, the speed was jarring. Institutional single-family ownership had become a national political issue, one with the rare distinction of uniting populists on the right and housing advocates on the left.
What happened next was faster still. The 21st Century ROAD to Housing Act passed the House 390 to 9 in February 2026 and the Senate 89 to 10 in March.34 It became law on July 11, 2026.4 Margins like that are almost unheard of for substantive economic legislation. They signal that this is not a policy likely to be reversed by the next election.
Why Washington turned
Why did an industry that owns a sliver of the nation's rental homes become a bipartisan target? Partly because of visibility. In the markets where Invitation Homes and its peers concentrated, institutional buyers were not a sliver; they were a noticeable share of purchases in particular neighborhoods and price bands, often competing with first-time buyers for exactly the starter homes that the strike-zone discipline targeted. A young family outbid by an all-cash offer from a company with a Wall Street pedigree became a potent political image, whatever the aggregate statistics said.
Partly, too, it was timing. Home prices surged during the pandemic and mortgage rates then rose sharply, pricing a generation out of ownership. Politicians looking for a villain with a name found institutional landlords easier to legislate against than zoning codes, construction costs, or interest rates. And the FTC case had already given the public a concrete story about how at least one large landlord treated its tenants.
The industry's defense, that institutions owned a tiny fraction of homes and added professional management to a messy sector, was factually grounded but politically weak. A near-unanimous vote suggests that argument lost decisively.
What the law actually says
The provision that matters to Invitation Homes is narrow in its wording and broad in its consequence. The law bars "large institutional investors," defined as entities controlling 350 or more single-family homes, from purchasing existing single-family homes.4 It carves out an exception for newly built homes, including purpose-built build-to-rent product, and it contains a set of other statutory exceptions whose scope will be shaped in rulemaking.4 Crucially, it does not require divestiture of homes already owned.3
Translated into business terms: Invitation Homes can keep every house it owns. It can sell houses. It can buy newly constructed houses. It can manage houses owned by others. What it cannot do is buy the resale three-bedroom ranch down the street, which is precisely the transaction that built the company.
Why this is the load-bearing fact
From 2012 through 2024, Invitation Homes' portfolio growth came overwhelmingly from buying existing homes, one at a time or in bulk. The bull case that ran through most sell-side models for a decade assumed that the company could keep adding homes through acquisition, deploying capital wherever its underwriting found a spread between rental yield and cost of capital. That lever is now legally capped. A bull case built on continued scale growth through scatter-site acquisition cannot survive in its old form. This is not a generic regulatory risk to be listed alongside hurricanes and interest rates; it is a structural change to the growth model.
The CEO's own words
Management's response is where the story gets interesting, because Dallas Tanner's own statements both qualify the damage and quietly concede how much the old model had already slowed.
Speaking to CNBC in August 2026, Tanner said the ban would lower home prices only "in the medium- to long-term," and argued that "90% of the bill focuses on deregulation," framing the law's supply-side provisions as more consequential than the investor ban.1718 He also noted that the company had already "built or acquired, in our partnerships with builders, over 6,000 new homes in the last five years."18
That last number deserves a second look. Offered as evidence of foresight, it shows that Invitation Homes had been supplementing scatter-site acquisitions with new-construction homes for years before the law forced the issue. That is a point in management's favor: the company was not starting from zero. But the same number implies something less flattering about the old engine. Six thousand new homes over five years, against a portfolio of roughly 85,500, is about 1,200 a year, and if the company was reaching for new-build partnerships, it suggests that buying existing homes at attractive yields had already become harder on its own. High home prices and higher mortgage-era interest rates had compressed the spread between rental yields and acquisition costs well before Congress acted. The ban closed a door that was already narrowing.
The verdict
The claim that Invitation Homes wins from here through continued scale growth via acquisition is not merely narrowed; it is effectively closed off by statute. What remains open is growth through new construction, through third-party management, and through rent growth on the existing portfolio. The bull case must now rest on the pivot, not on buying more houses.
Two things will reveal how the new regime is playing out. The first is rulemaking on the statute's exceptions, which will determine how broadly "newly built" and related carve-outs are interpreted. The second is the company's disposition pace. Management raised its 2026 disposition guidance to as much as roughly $850 million.19 In the old model, selling homes was portfolio recycling: sell lower-growth houses, buy better ones. In the new model, if new-build additions do not keep pace with sales, recycling becomes shrinkage. Watching whether the owned-home count rises, holds, or falls over the next several quarters is the simplest test of whether the pivot is replacing the old engine or merely managing its decline.
The company, to its credit, did not wait for the final vote to begin answering the question. It had already started buying a builder.
VII. Answering the Ban: ResiBuilt, Build-to-Rent, and Fee Management
Buying a builder
In mid-January 2026, days before the executive order, Invitation Homes announced that it had acquired ResiBuilt, an Atlanta-based fee homebuilder, for $89 million plus up to $7.5 million in earn-outs.2021 ResiBuilt had delivered more than 4,200 homes since 2018, came with 23 existing fee-build contracts, and controlled options on roughly 1,500 lots across Georgia, Florida, and the Carolinas.2021
A fee homebuilder is a contractor that builds homes on behalf of owners rather than selling them to individual buyers. It is the plumbing of build-to-rent: institutional owners who want new rental communities hire firms like ResiBuilt to construct them. Owning one gives Invitation Homes control over construction scheduling, cost, and specification, and a pipeline of lots that can become rental homes under the new-construction exception that the law later formalized.
Benchmarking the price
At roughly $90–97 million all-in, ResiBuilt is a small, low-risk bolt-on relative to a market capitalization in the mid-teens of billions. It comes with contracted forward revenue from its existing fee-build book and land optionality through its lot pipeline. Structurally, it is nothing like the Starwood Waypoint merger: it is a capability purchase, not a scale consolidation. The risk here is not overpayment.
The risk is execution against a better-positioned rival. As the competitive discussion showed, AMH has been developing its build-to-rent capability organically for years and now sources the vast majority of its additions from its own construction program.12 Invitation Homes is buying its way into that capability from a much earlier stage. ResiClub's analysis framed the deal as a meaningful strategic bet on homebuilding by a company whose entire identity had been buying existing homes.12 Integrating a builder into a landlord is not trivial: homebuilding involves land risk, entitlement timelines, construction cost inflation, and working capital cycles that a rental operator has never had to manage at scale. INVH is playing catch-up from a standing start, not from parity.
How build-to-rent changes the arithmetic
Buying a new-built rental home differs from buying a resale house in ways that matter for returns. A resale house can be bought, renovated, and leased within weeks, and the price is set by a competitive market of individual buyers. A new-build community takes months or years from land contract to first lease, and capital is tied up in land and construction before a dollar of rent arrives. In exchange, the owner gets homes built to its own specification, clustered together for maintenance efficiency, with lower repair costs in the early years because everything is new.
The trade-off is that build-to-rent competes directly with homebuilders selling to owner-occupants and with apartment developers, both of which bid for the same land and labor. Yields on new construction depend heavily on construction costs, which have been volatile. And because every institutional operator is now funneled toward the same exception, competition for well-located build-to-rent land is likely to intensify. The legal escape hatch is open to everyone above the 350-home threshold, which means it may become crowded.
The second lever: managing other people's houses
The other answer to the ban requires no construction at all. Invitation Homes manages single-family homes owned by other investors, collecting fees for property management, asset management, dispositions, and performance, plus revenue from value-add services such as smart-home packages and internet bundles.10 The number of homes managed for third parties grew from 18,129 in the first quarter of 2024 to more than 25,000 in 2025.1022 This business generated an estimated $85 million of revenue in fiscal 2025, about 3% of the total.10
The economics are different from owning homes. When Invitation Homes manages a house for someone else, it does not need to raise capital to buy the house, it does not carry the mortgage, and it does not bear the risk of the house losing value. It earns fees for running its existing platform over a larger base. That is the definition of capital-light growth, and in principle it lets the company leverage the maintenance, leasing, and technology infrastructure it already pays for.
Why it matters, and why it is not yet transformative
The fee business deserves serious attention because it is the growth vector the ban does not restrict. A large institutional owner's homes are still homes that need managing, and the law's restrictions on buying existing homes do nothing to stop another owner from hiring Invitation Homes to run their portfolio. Management has actively resourced the platform, adding leadership and positioning it as a strategic pillar at its 2025 Investor Day.10 Success would shift the earnings mix toward higher-margin fee income that does not require equity issuance at a discount to asset value.
But proportion matters. At about 3% of revenue, the fee business is early-stage and unproven at scale. Its success depends on winning mandates from institutional capital that has alternatives, including AMH, Progress Residential, and Amherst, each of which can offer comparable platforms. The same caveat from the moat discussion applies here: if Invitation Homes' operating edge over scaled peers is unproven, then its ability to win third-party mandates on the strength of that edge is also unproven. And the ban itself could shrink the pool of potential clients, since large new institutional buyers of existing homes are now legally restricted; the client base will increasingly be owners of build-to-rent communities and existing portfolios.
The pivot, then, is real, cheap, and sensible. It is also small, recent, and untested against the competitor most directly ahead of it. Whether it works will depend heavily on the people running it.
VIII. Current Management: Incentives, Capital Allocation, and Credibility
The founder in the corner office
Dallas Tanner has run Invitation Homes as chief executive since 2019, after earlier serving as president, and he has been with the enterprise since its founding.5 His 2025 total compensation was about $14.1 million, with a base salary of $1 million and the balance overwhelmingly in stock and incentive awards.5 That structure matters more than the headline figure. The vast majority of his pay depends on per-share outcomes and the share price rather than on the absolute size of the portfolio.
What makes Tanner unusual is continuity. He was there for the Phoenix foreclosures, the securitization, the IPO, the Starwood Waypoint merger, Blackstone's exit, the pandemic boom, the FTC case, and now the ban. Very few executives in real estate have led a company through that many regime changes. The flip side of continuity is accountability: the fee practices that the FTC targeted occurred on his watch as CEO, and the acquisition-dependent growth model that the ban capped was his model.
Chief Financial Officer Jonathan Olsen and Chief Operating Officer Timothy Lobner round out a stable executive team.5 The 2025 departure of Charles Young from the president title is worth noting as a leadership transition, but available disclosures present it as normal succession, and there is no evidence in the filings reviewed to suggest otherwise.5
Capital allocation under a discount
The most revealing management decisions of the last two years involve the share price. Invitation Homes' stock has traded at a discount to management's estimate of net asset value, meaning the market values the company's homes at less than they would fetch if sold. Consensus analyst price targets cluster in the low-to-mid $30s against a share price in the high $20s as of September 2026, a gap that mirrors that discount.
Management's response was to buy back stock. The company completed a $500 million repurchase program, executed below its own fair-value estimate, and then authorized a new $500 million program.19 In the second quarter of 2026, Core FFO per share rose about 5%, partly because the buyback reduced the share count.19 When a company's stock trades below the value of its underlying assets, buying back shares is a way of acquiring its own homes at a discount, which is arguably a better use of capital than buying new homes at full price. The raised disposition guidance, up to about $850 million for 2026, fits the same logic: sell houses at private-market values and use the proceeds to retire shares priced below those values.19
That discipline is a genuine point in management's favor. But it should be tested against the record rather than praised on its own terms. A buyback program funded by selling homes also shrinks the company, and in a world where acquisitions of existing homes are prohibited, shrinkage is harder to reverse. The activist-style challenge here would be sharp: if the market persistently values the platform below its assets, and the main growth lever is legally capped, why not sell more homes, return more capital, or consider strategic alternatives? Management's implicit answer is that the new-build and fee-management engines will earn a better return than liquidation. That is a claim that remains to be proven.
Ownership and outside capital
Compensation is heavily equity-weighted, aligning management with per-share results rather than asset growth.5 There is no public evidence of an activist campaign against Invitation Homes, a statement bounded to the company's public filings and 13D disclosures reviewed through September 2026 rather than a general assurance.
Promises versus outcomes
A fair test of any management team is whether the stories it told in earlier years held up. Three stand out in the Invitation Homes record. The Starwood Waypoint merger was sold on synergies and density, and the combined company did go on to report consistently high occupancy, though the full synergy capture is not separately tracked in later disclosures. The customer-experience story, told for years through retention and resident-satisfaction metrics, was complicated by the FTC's findings about fees in the same period. And the acquisition-led growth story, which management defended as recently as the 2025 Investor Day alongside its newer initiatives, has now been overtaken by law.10
None of these amounts to a pattern of broken promises. Occupancy and operations delivered what was advertised. But the record shows that the parts of the story most dependent on external tolerance, fee practices and the political license to buy houses, proved less durable than the operating parts. That is a useful lens for judging the new narrative: the parts that depend on execution are more credible than the parts that depend on regulators and clients cooperating.
The credibility test
Has management explained problems plainly? The record is mixed but improving. The FTC matter was resolved without an admission of wrongdoing, which is standard in such settlements but leaves the company's own account of what went wrong thin.13 The response to the ban has been more direct. On the fourth-quarter 2025 call in February 2026 and again on the second-quarter call in August, management reframed its growth mix around development partnerships, ResiBuilt, and fee management rather than scatter-site acquisitions.1119 The ResiBuilt deal was announced before the executive order and well before the law passed, which suggests the pivot was underway rather than improvised.20
That reads as real-time course correction rather than denial, and it counts in favor of credibility. It is also too early to grade execution. The fair verdict is that management has shown willingness to adapt the narrative quickly and to allocate capital sensibly against a discount, but it has not yet delivered the results that would prove the new model works. The next question is how that model stacks up against competitors who face the same law.
IX. Competitive Landscape, Porter's Five Forces, and 7 Powers
A war game on a fragmented board
Imagine a map of Atlanta's suburbs with a pin for every single-family rental home. Most pins belong to individuals: a nurse with an inherited house, a couple renting out their first home, a local investor with twenty properties. Scattered among them are dense clusters of pins belonging to Invitation Homes, AMH, Progress, FirstKey, and Amherst. In aggregate, the institutional pins are a rounding error. In any given subdivision, they can be the dominant landlord.
That is the industry structure in one picture: overwhelmingly fragmented at the national level, meaningfully concentrated at the neighborhood level. It explains both why institutional operators can achieve local density economics and why they became politically visible.
Porter's Five Forces
Buyer power (renters). Individually, renters have little bargaining power. They need somewhere to live, the supply of single-family rentals in good school districts is limited, and moving is expensive. Collectively, however, renters' political bargaining power has proven high and rising. The FTC case and the ROAD to Housing Act are the clearest evidence of that collective power being exercised, not through the lease negotiation but through the ballot box and the regulator.
Rivalry. Rivalry among scaled operators is moderate. AMH, Progress, FirstKey, and Amherst compete with Invitation Homes for Sunbelt land, build-to-rent opportunities, third-party mandates, and tenants in overlapping markets. The ban redirects that rivalry away from existing-home acquisitions and toward new construction and management contracts, where AMH has the head start.
Threat of substitutes. Apartments are the obvious substitute, and purpose-built build-to-rent communities, rows of single-family homes built specifically for rental, are a growing one. Build-to-rent remains roughly 1% of the multifamily market but is scaling. Homeownership is also a substitute, and if the ban's supporters are right that it will eventually lower home prices, more renters will become buyers.
Threat of new entrants. Here the law creates an unusual twist. New institutional entrants into existing-home buying above the 350-home threshold are now legally foreclosed. That is a rare case of regulation reducing a specific competitive threat: no new fund can show up and outbid Invitation Homes for scattered-site houses at scale. But the same rule caps the incumbent's own growth lever. The barrier protects the portfolio that exists while freezing its expansion through the same channel.
Supplier power. The key suppliers are homebuilders, land sellers, contractors, insurers, and lenders. As the industry pivots to new construction, homebuilders and landowners gain leverage, because every scaled operator now needs them. Insurers in Florida and the Gulf Coast already hold considerable power over expense lines. Lenders are the one supplier group where Invitation Homes' scale and investment-grade access give it a clear advantage over small landlords.
Hamilton Helmer's 7 Powers
Applying Helmer's framework clarifies what kind of advantage Invitation Homes actually has.
Scale economies are the strongest surviving candidate. The company spreads its technology, maintenance organization, and corporate overhead across a large base of homes, and it can extend that infrastructure to third-party homes at low incremental cost. But this is a modest power, because rivals such as AMH and the large private operators have comparable scale.
Network effects are absent. One more tenant in an Invitation Homes house does not make the product more valuable to other tenants.
Counter-positioning is not evident. Incumbents are not structurally prevented from copying Invitation Homes' model; AMH has in fact moved further in the new-build direction.
Switching costs exist for tenants, since moving is expensive, but they are generic to all landlords, not specific to Invitation Homes.
Branding matters least of all. Tenants shop by house, location, school district, and price, not by the name of the landlord. The FTC settlement further weakened any brand premium.
Cornered resource is the most interesting candidate after the ban. The existing portfolio of roughly 85,500 homes in desirable Sunbelt submarkets cannot be replicated by a new institutional entrant through existing-home purchases. In a sense, the law turned the portfolio into a partially cornered resource. But it is a resource that cannot grow through the same channel, and its value accrues to the existing homes rather than to a durable competitive process.
Process power is possible in principle, through operating know-how in scattered-site maintenance and leasing, but it is not demonstrated in any public comparison with scaled peers.
The honest conclusion is that Invitation Homes has one modest power, scale economies, and a newly created quasi-cornered resource in its existing portfolio. Neither provides a clear advantage over its most direct competitor. That frames the bull and bear debate that follows.
X. Bull vs. Bear Case
The bull case
The first pillar of the bull case is demand. The United States has a structural housing shortage, and the cost of owning a home, driven by high prices and mortgage rates, remains elevated. For a family that wants a yard and a school district but cannot afford to buy, a professionally managed single-family rental is a compelling option. That demand does not depend on the company's ability to buy more homes; it supports rents and occupancy on the homes it already owns. Occupancy above 97% is the evidence.2
The second pillar is the pivot. Fee management and build-to-rent open growth paths that the law explicitly leaves available, and management moved on ResiBuilt before the law passed rather than after.20 If fee-managed homes keep compounding and ResiBuilt's pipeline converts into new rental homes, the company can grow without buying existing houses.
The third pillar is capital discipline. Buying back shares below net asset value, funded partly by disposing of lower-growth homes, is a value-accretive way to allocate capital when the stock is cheap relative to the assets, and the 5% Core FFO per share growth in the second quarter shows the arithmetic working.19
The fourth pillar is protection. The ban removes future institutional competition for existing-home acquisitions, which arguably makes the existing portfolio more valuable as a scarce institutional-grade asset. No new fund can replicate it through the same route.
The bear case
The first pillar of the bear case is simply the inverse of the bull's fourth. The engine that powered the last decade is legally capped, and the replacement engines are small. Fee management is about 3% of revenue.10 ResiBuilt was acquired eight months ago. Neither has been proven at the scale needed to replace acquisition-led growth.
The second pillar is competitive position. AMH is years ahead in build-to-rent, sourcing the vast majority of its additions from its own development program while Invitation Homes is still integrating an acquired builder.12 In its own stated pivot, Invitation Homes may be structurally a fast follower rather than a leader.
The third pillar is expense risk. With roughly a third of homes in Florida and much of the rest across the Sunbelt, the portfolio is exposed to insurance and property-tax costs that can compress operating margins regardless of how well rents hold up.1
The fourth pillar is trust. The FTC settlement and the broader junk-fee crackdown undercut the customer-experience differentiation that management has used to justify a premium position.13
The fifth pillar is leverage. At about 5.6 times net debt to EBITDA, the company remains sensitive to refinancing costs in a higher-for-longer rate environment.11
Weighing the two
The bull case is strongest on the existing portfolio: durable demand, a quasi-protected asset base, and sensible capital allocation against a discount. The bear case is strongest on growth: the old engine is gone and the new ones are small and behind a direct rival. Put simply, the market is being asked to value a high-quality, slow-growing portfolio whose growth option depends on an unproven pivot. The next few years will reveal which of those descriptions dominates. Before that, the risks deserve a closer look.
XI. Risk Radar
Regulatory and political risk: now realized
For years, the regulatory risk around institutional single-family ownership was a tail risk that analysts listed and discounted. It is no longer a tail. The ROAD to Housing Act is law, and it is the central strategic constraint on the business.4 Two further developments matter. The first is state-level copycat legislation, which could extend restrictions further than the federal statute, for example to new-build purchases or to operating practices. The second is rulemaking on the statute's exceptions, which will determine how broadly the new-construction carve-out applies and whether bulk portfolio trades or other structures remain available. A narrow interpretation would squeeze the build-to-rent path that the pivot depends on.
Climate and insurance costs
Heavy exposure to Florida and the Sunbelt means that insurance premiums and property taxes are a larger and more volatile share of expenses than for a more geographically diversified landlord.1 These costs are largely outside management's control and cannot always be passed through to tenants immediately, especially when new-lease rent growth is running near 1%.2 A bad hurricane season or a jump in reinsurance costs can show up quickly in same-store NOI.
Refinancing and cost of capital
REIT-typical leverage means that rising borrowing costs flow directly into earnings as debt matures.11 The stock's discount to net asset value compounds the problem: issuing equity below asset value to fund growth would dilute existing shareholders, which effectively closes off equity-funded expansion until the discount narrows. That leaves dispositions, retained cash, and debt as the main funding sources for the pivot.
Reputational and litigation risk
The FTC settlement is still being administered, with refunds reaching renters in 2026.16 A broader overhang hangs over the rental industry in the form of scrutiny of algorithmic rent-pricing tools, including the Department of Justice's antitrust case against RealPage and related private litigation against multiple large landlords. Available reporting reviewed for this article does not confirm Invitation Homes as a named defendant in the primary RealPage price-fixing settlements, so this is a sector risk to monitor rather than an established company-specific liability.
Execution risk
Pivoting from a scattered-site acquisition machine to a builder and fee manager requires capabilities that Invitation Homes is acquiring rather than having built organically: land development, construction management, and third-party client relationships. Integration of ResiBuilt, retention of its key people, and the ability to win and keep management mandates against capable rivals are the practical tests. An acquisition machine and a construction company run on different clocks, and blending them is a cultural as well as operational challenge.
Taken together, the radar shows a business whose main risks are no longer about demand but about constraints: legal, financial, geographic, and organizational. What lessons does that leave for investors and operators?
XII. Playbook: Business & Investing Lessons
Scale attracts the attention that constrains it
Crisis-era capital can build category-defining scale quickly, and Invitation Homes is proof. But the same scale that created the operating advantages eventually attracted the political attention that constrained them. The lesson is not that scale is bad; it is that in politically sensitive categories such as housing, health care, or food, scale has a regulatory ceiling that tends to arrive later than investors expect and faster than companies can adapt.
Founder continuity is a test, not a guarantee
A founder-CEO with continuous tenure through an IPO, a merger, a pandemic, a regulatory settlement, and a market-structure-altering law offers a rare opportunity to judge adaptability. The right question is not whether problems occurred, because they always do, but how fast and how credibly the strategy adapted. On that question, Tanner's early move on ResiBuilt and his reframing of the growth mix are points in his favor, while the FTC-era fee practices are a reminder that operating discipline and customer trust can diverge.
Build the adjacency before the forcing event
Capital-light adjacencies built before a forcing event are worth far more than the same pivot attempted after one. Invitation Homes' fee-management platform, at about 3% of revenue, is small, but it exists. Had the ban arrived with no third-party business in place, the company would be building from nothing in a hostile environment.
Cheap optionality still has to be executed
Buying growth optionality cheaply, before being forced to, is less expensive than building it under regulatory duress. ResiBuilt cost less than 1% of the company's market value. But a cheap acquisition still has to be integrated and out-executed against a rival that has been building the same capability for years. Low price reduces downside; it does not create upside on its own.
XIII. Epilogue & What's Next
The questions that will decide the next chapter
Return to that Atlanta subdivision. The technician is still servicing the house, the tenant is still paying rent, and the company is still profitable. But the next house that Invitation Homes adds to that neighborhood will have to be one it builds, or one it manages for someone else.
Three developments will reveal whether that shift succeeds. The first is the pace of ResiBuilt integration and the growth of fee-managed homes. If third-party management keeps compounding toward real materiality, roughly 10% or more of revenue, the story will have changed from a landlord with a side business to a genuinely hybrid owner-operator. The second is rulemaking under the ROAD to Housing Act. A broad reading of the new-construction exception would give the build-to-rent path room to scale; a narrow one would squeeze it. The third is the discount to net asset value. If it closes, the market will be signaling confidence in the post-ban growth model. If it persists, the market will be saying that it does not yet believe the pivot, and that the portfolio is worth more as a collection of houses than as a growing enterprise.
Invitation Homes spent fourteen years proving that single-family rentals could be institutionalized. It turned a cottage industry into a bond market, a merger, and an S&P 500 constituent. The next chapter tests something different: whether an institution built to buy can become one that builds and manages instead, and whether it can do so before its most direct peer, already further along the same road, gets there first.
References
-
Invitation Homes Inc. — Form 10-K, FY2025 — SEC EDGAR, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Invitation Homes Inc. — Q2 2026 Supplemental Information (Form 8-K) — SEC EDGAR, 2026 ↩↩↩↩↩↩↩
-
Senate passes bipartisan housing bill targeting large investors and easing regulations — NPR, 2026-03-12 ↩↩↩
-
US Senate Advances Housing Legislation That Includes a Ban on Institutional Investors Purchasing Single-Family Homes — Mayer Brown, 2026-03 ↩↩↩↩↩↩↩↩
-
Invitation Homes Inc. — Form DEF 14A, 2026 Proxy Statement — SEC EDGAR, 2026 ↩↩↩↩↩↩↩
-
Invitation Homes Inc. — Form 10-K, FY2017 — SEC EDGAR, 2018 ↩↩↩
-
Blackstone cashes out on Invitation Homes — HousingWire, 2019-11 ↩
-
Blackstone Real Estate Completes Privatization of Tricon — Blackstone, 2024-05-01 ↩↩
-
Invitation Homes Inc. — 2025 Investor Day Presentation (Form 8-K) — SEC EDGAR, 2025 ↩↩↩↩↩↩↩↩
-
Invitation Homes (INVH) Earnings Call Transcript, Q4 2025 — The Motley Fool, 2026-02-19 ↩↩↩↩↩
-
Understanding institutional landlord Invitation Homes' new housing market bet — ResiClub Analytics, 2026 ↩↩↩↩↩
-
FTC Takes Action Against Invitation Homes for Deceiving Renters, Charging Junk Fees, Withholding Security Deposits, and Employing Unfair Eviction Practices — FTC, 2024-09-24 ↩↩↩↩↩↩
-
FTC v. Invitation Homes, Inc. — Case docket, FTC Legal Library ↩
-
Invitation Homes Agrees to Pay $48 Million in FTC Settlement — Bloomberg, 2024-09-24 ↩
-
FTC Sends Checks Totaling More Than $47.2 Million to Consumers Deceived by Invitation Homes — FTC, 2026-03 ↩↩
-
Invitation Homes CEO says ban on institutional homebuying will bring down prices, but not immediately — CNBC, 2026-08-11 ↩
-
CNBC Exclusive: Excerpts — Invitation Homes CEO Dallas Tanner Speaks with CNBC's Diana Olick — CNBC, 2026-08-11 ↩↩
-
Invitation Homes (INVH) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-07 ↩↩↩↩↩↩
-
Invitation Homes Acquires ResiBuilt to Enhance Development Capabilities — Business Wire, 2026-01-16 ↩↩↩↩
-
Invitation Homes' $89 million ResiBuilt buy brings building in-house — HousingWire, 2026 ↩↩
-
Earnings call transcript: Invitation Homes beats Q3 2025 earnings forecast — Investing.com, 2025 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube