Interactive Brokers: The Broker That Automated Itself
I. Introduction & Episode Teaser
Picture an ordinary office park in Greenwich, Connecticut. There is no trading floor roaring with shouted orders, no wall of Bloomberg terminals manned by salespeople in shirtsleeves, no marble lobby built to impress wealthy clients. What there is, mostly, is code. And that code, tended by a remarkably small staff, now runs one of the largest brokerage operations on the planet.
At the end of June 2026, Interactive Brokers Group employed 3,265 people.1 Two months later, at the end of August, it reported 5.46 million client accounts holding $962.8 billion of client equity.2 Do the rough division and each employee, from the receptionist to the chief executive, stands behind something like 1,700 accounts. A traditional full-service brokerage, with branch offices and advisers who take clients to lunch, does not operate anywhere near that ratio. It is not designed to.
That single ratio is the whole story in miniature. Interactive Brokers (IBKR on the NASDAQ Global Select Market) is what happens when a company spends almost fifty years replacing people with software, and then discovers that the software is the product.
The numbers that flow from that design are almost absurd. In the second quarter of 2026, the company converted 77% of its net revenues into pre-tax profit, the seventh consecutive quarter above 70%.1 It was sitting on $10.3 billion of excess capital.1 And when asked on the Q2 2026 call about the investment bankers who keep arriving with acquisition ideas, CEO Milan Galik said the inbound flow had "dramatically increased," but "nothing so far stood out as worthy pursuing."1
That last point deserves a moment. Wall Street's brokerage industry has largely been assembled through mergers: Schwab absorbed TD Ameritrade, Morgan Stanley bought E*Trade, and regional and independent brokerage platforms have been rolled up one after another. Interactive Brokers has grown organically, building rather than buying. That restraint is a real feature of the story, and it is also a question: what will a company that has never done a big deal do if it ever decides to do one?
There is a third character in this story, and he is not a spreadsheet. Thomas Peterffy, the Hungarian-born founder, stepped aside as CEO in 2019 but never really left the stage. Through IBG Holdings LLC, the vehicle that owns roughly three-quarters of the operating partnership, he and his affiliates control the company; the 2025 10-K put their share of IBG Holdings at about 91.4%, and a July 2026 prospectus supplement put it at roughly 91.8%.34 He still takes analyst questions on earnings calls. He is in his early eighties.
This episode follows three threads. First, how a market-maker's automation obsession became the leanest brokerage machine in the world. Second, why the years from 2019 to 2026, with commission wars, a meme-stock crisis, and the steepest rate-hiking cycle in forty years, matter more to today's investment case than the first three decades. Third, what it means to own a minority stake in a company whose destiny is still, legally and practically, in the hands of one man.
The spine of the analysis is simple. Why does Interactive Brokers win from here, and what could break that case? The answer turns out to be more nuanced than either the "tech disruptor" narrative or the "rate-cycle beneficiary" narrative suggests. To see why, the story has to start with a young engineer who could barely speak English and a seat on the American Stock Exchange.
 Subscribe on LinkedIn
II. Origins, Compressed: From Timber Hill to a Public Company (1977–2007)
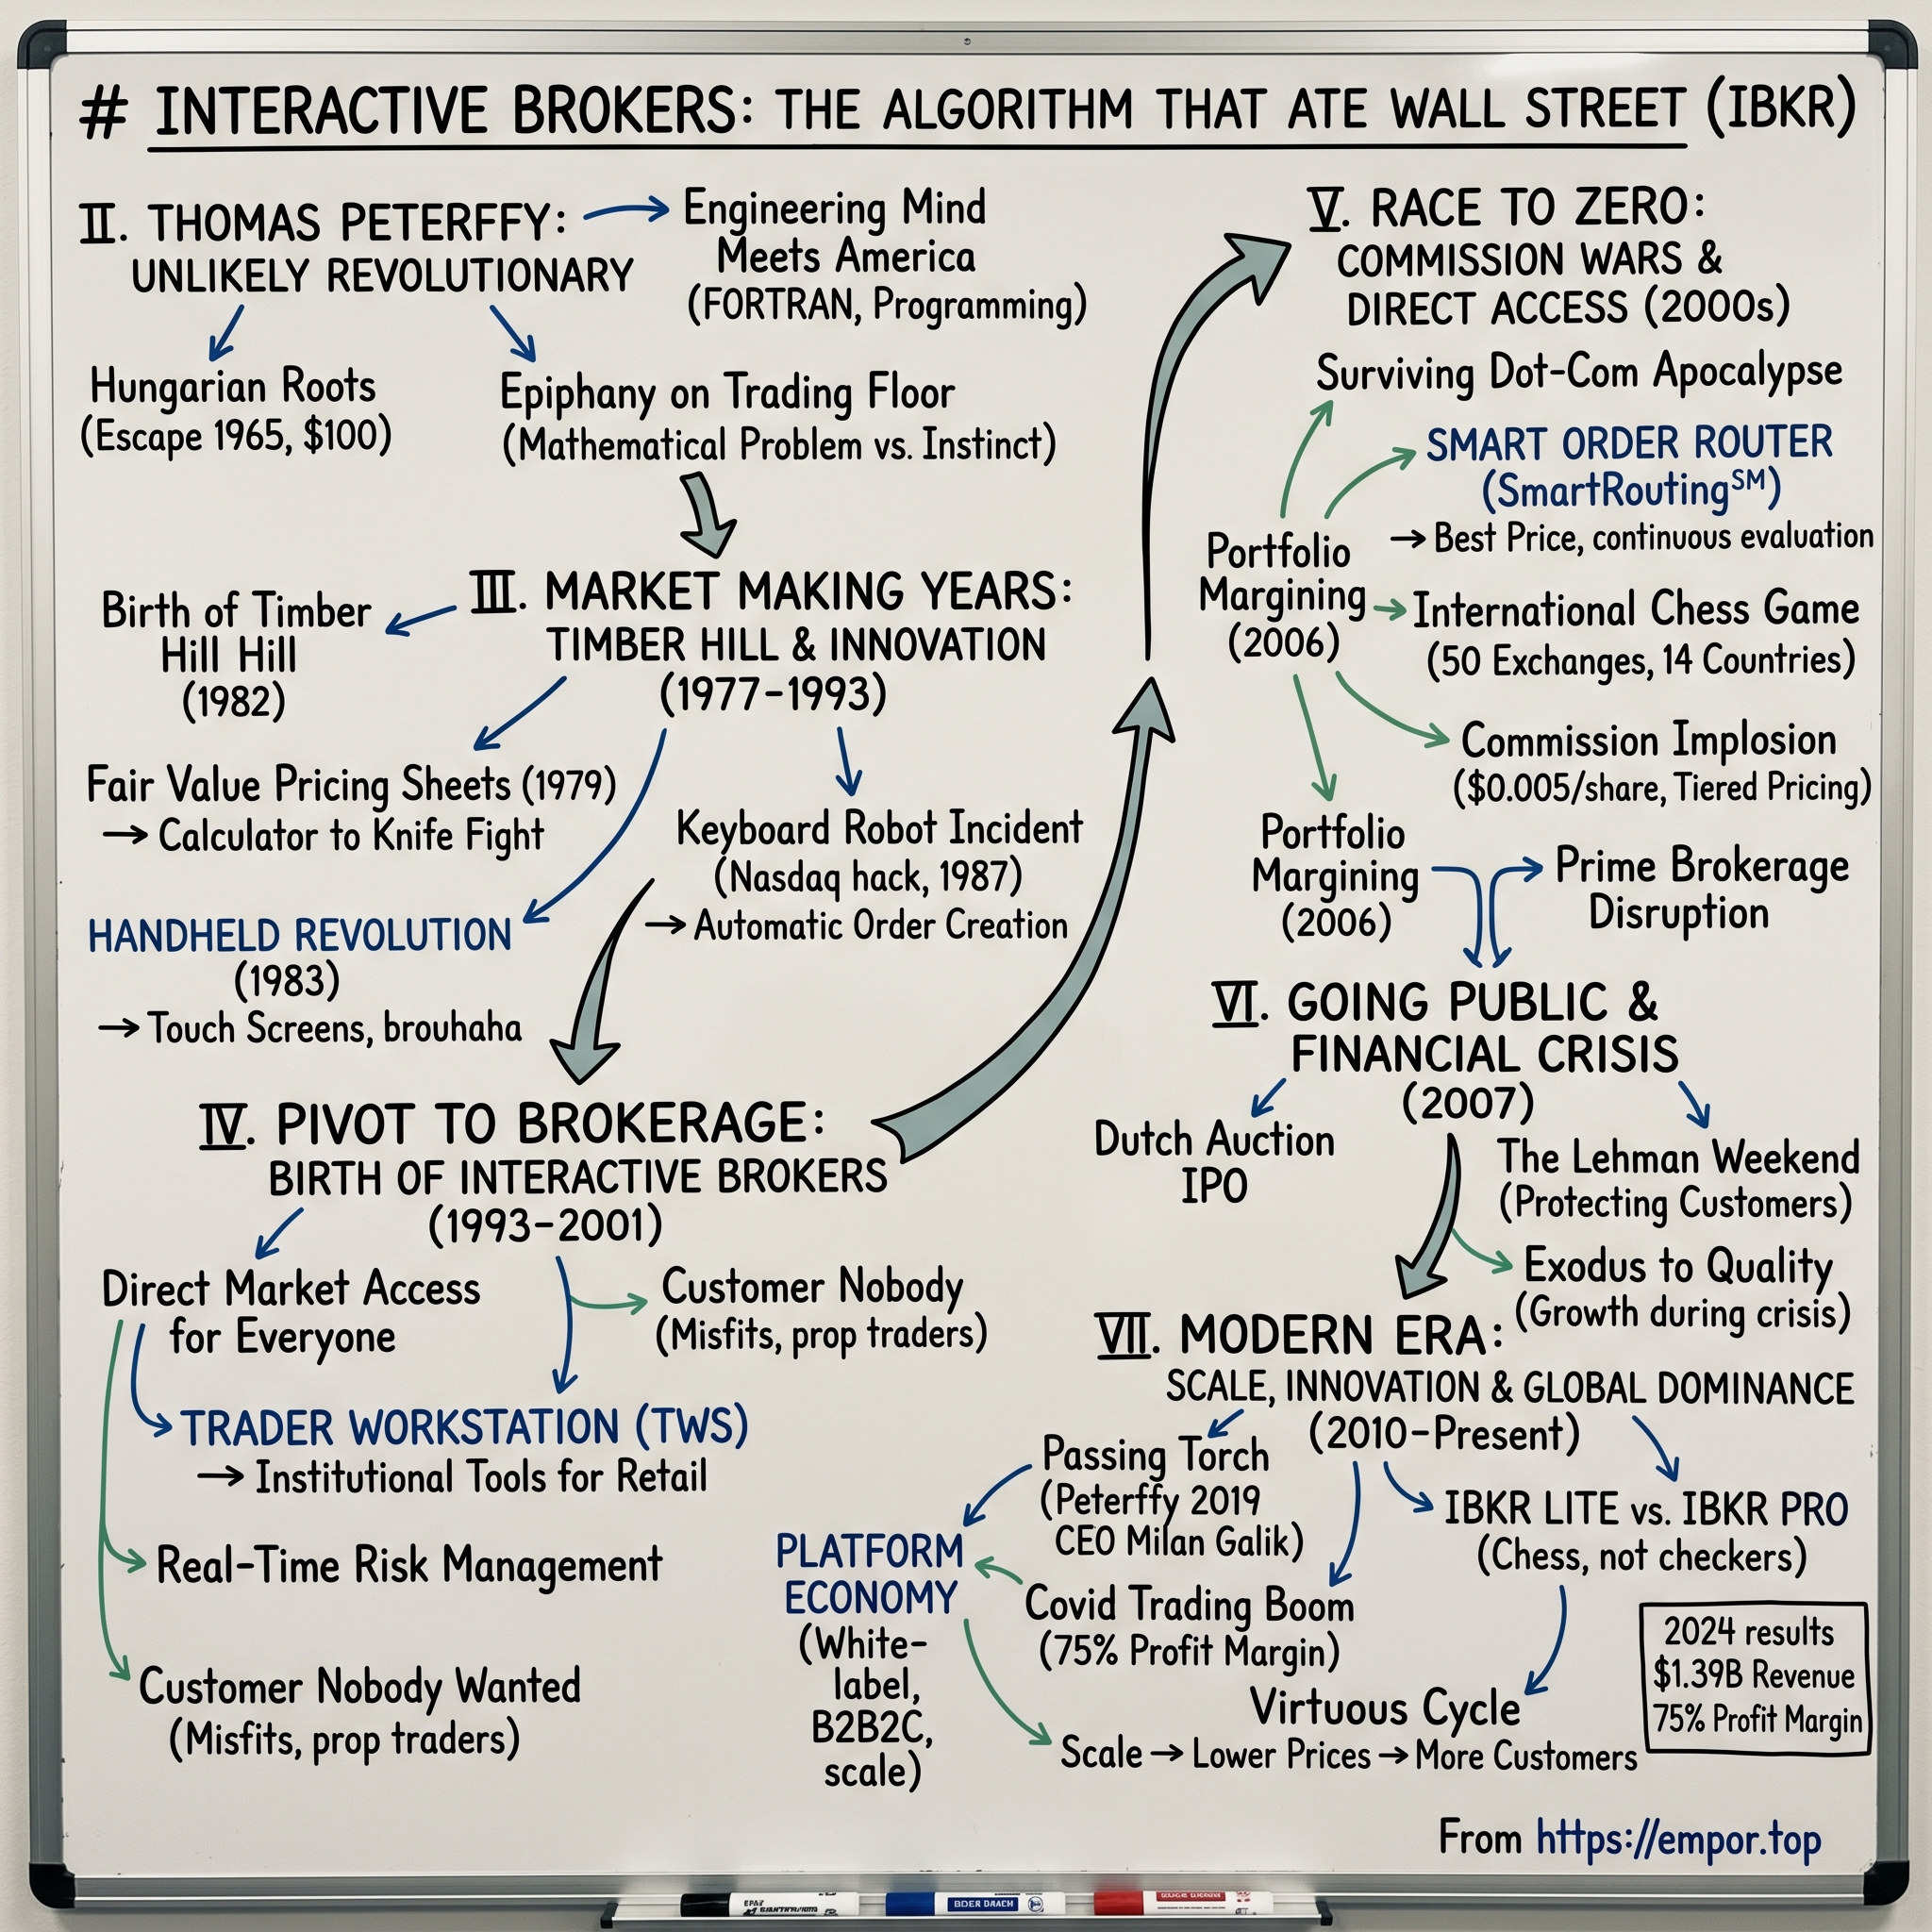
In 1977, Thomas Peterffy bought a seat on the American Stock Exchange and began trading options as a market maker.5 He had arrived in the United States from Hungary in 1965 with little money and less English, taught himself programming, and worked as a draftsman and software developer before deciding that markets were a problem to be engineered rather than intuited.5
That biography matters because it explains the company's temperament. Peterffy grew up in postwar Budapest under a communist regime and has spoken often about the value of free markets and the precariousness of wealth. He approached trading not as a salesman or a gambler, but as someone who distrusted discretion, including his own. Systems were fairer than people, faster than people, and less likely to panic. Almost every distinctive feature of Interactive Brokers today, from its sparse headcount to its automated liquidations of under-margined accounts, flows from that temperament.
The options pits of the late 1970s were a sensory world: floor traders reading each other's faces, pricing contracts with rules of thumb and memory, scribbling on cards. Peterffy's insight was that option pricing was math, and that math could be computed faster and more consistently by a machine than by a person under stress. The trouble was that exchanges did not let traders bring computers onto the floor.
So he built around the rules. His firm, which became Timber Hill, developed handheld computers for its floor traders in 1983, according to the company's own history, and by 1987 it had built what it describes as the first fully automated algorithmic market-making system.5 The famous anecdote from this era, told many times since, is of Peterffy wiring a trading terminal directly into a computer so that no human had to retype the orders. Whatever the precise mechanics, the instinct was clear: if a human was a bottleneck, remove the human.
Market making taught the firm two lessons that still define it. The first was that tiny edges, collected millions of times, compound into large profits only if costs stay microscopic. The second was risk control. A market maker is always exposed to the market; the firms that survive are the ones whose systems measure and limit that exposure continuously, not at the end of the day.
The pivot came in the 1990s. Having built execution and risk technology for its own trading, the firm began offering the same infrastructure to outside customers as a brokerage. Interactive Brokers became the delivery vehicle, and Trader Workstation, the dense, intimidating, deeply capable desktop platform known to its users as TWS, became the front door.5 It was never pretty. Professional traders did not care. It was fast, cheap, and connected to exchanges all over the world.
In May 2007, the company went public in a way that told investors exactly who they were dealing with. Rather than let underwriters price the deal in the usual book-building process, Interactive Brokers used a Dutch auction, in which bidders submit prices and the offering clears at the level where demand meets supply. It offered 40 million shares at $30.01 each and raised about $1.2 billion.6 The subtext was unmistakable: a firm that made its living on price discovery was not going to hand price discovery to a bank syndicate.
The public listing also created the structure that still governs the company. The public bought into Interactive Brokers Group, Inc., which owns a minority slice of the operating partnership, IBG LLC. Peterffy and his fellow insiders kept the majority through IBG Holdings LLC.3 That arrangement, discussed in depth later, is why public shareholders have always been passengers rather than drivers.
Eighteen months after the IPO, the financial system nearly collapsed. Several highly levered investment banks and brokers either failed, were absorbed in forced sales, or needed government support. Interactive Brokers came through the crisis without such rescue, a proof point for the claim that its automated, real-time margining is a form of risk control, not merely a cost-saver. It is worth being precise about what that proves, though. The firm was not a big balance-sheet lender to mortgage markets, so its survival reflects a business model that avoided the most dangerous exposures as much as it reflects superior software.
The final chapter of the origin story is less romantic and more revealing. In 2017, Interactive Brokers exited options market making altogether, selling the Timber Hill business to Two Sigma Securities and focusing entirely on brokerage.2 The founder walked away from the business that had made him rich because the brokerage machine had become the better business: more scalable, more predictable, and less exposed to trading losses.
That decision is the bridge between the history and today. The engineering culture, the low headcount, and the obsession with automated risk control were built in the market-making years. The brokerage now harvests them. When the company reported a record 77% pre-tax margin for full-year 2025, it was cashing a check written in the 1980s.7 The next question is how exactly that check gets written, which means opening up the machine itself.
III. The Machine: Business Model, Industry Structure & Competitive Position
Three engines under one hood
Imagine a client in Seoul who wakes up, opens the IBKR app, and buys shares of a US chip designer, hedges the currency exposure in Korean won, borrows against her portfolio to fund the trade, and leaves some dollars sitting uninvested. In that one sequence, Interactive Brokers has earned money four ways: a commission on the trade, a spread on the currency conversion, interest on the margin loan, and interest on the idle cash it holds on her behalf. Meanwhile, the shares in her account may be quietly lent out to a short seller, generating yet another fee.
That is the business model: a toll road with several booths. It helps to reduce it to three lines.
The first line is commissions. In Q2 2026, commission revenue hit a record $673 million, up 30% from a year earlier.1 This is the line most sensitive to trading activity, and therefore to market mood. When volatility spikes and retail traders pile in, commissions surge. When markets go quiet, they sag.
The second line, and the one the "fintech disruptor" narrative tends to underplay, is net interest income. In the same quarter, net interest income was $1.06 billion, up 23%, making it more than half of the company's $1.9 billion in net revenues.18 It comes from two main sources. Client margin loans had reached $108.5 billion at the end of June, up 67% year over year, and client cash balances stood at a record $182.4 billion, up 27%.1
Here is the simple way to think about the cash piece. When a client leaves dollars uninvested, Interactive Brokers pays that client a benchmark-linked rate on part of the balance and invests the cash in safe, short-term instruments. The spread between what it earns and what it pays is income. The same logic applies to margin loans: the company borrows cheaply, lends to clients at a markup, and the loans are secured by the clients' own securities, which the system monitors in real time.
The third line is everything else: fees on options order flow, exposure fees charged to clients running risky portfolios, market data fees, and especially securities lending. When a hedge fund wants to short a hard-to-borrow stock, someone has to lend it the shares. Interactive Brokers, holding billions of dollars of client securities, is a natural lender. Management put fully loaded securities lending net revenue at about $343 million in Q2 2026, up 37%.1
The rate lever, and why the margin is partly borrowed from the Fed
The most important sentence in any analysis of Interactive Brokers is this: the company's profits are heavily geared to interest rates. Management estimates that each 25 basis-point move in the Fed funds rate is worth about $81 million of annual net interest income, based on June 2026 balances.9 That is a useful, candid disclosure, and it points in both directions.
How violently does a zero-rate world compress this business? Look at the second quarter of 2020. The average Fed funds rate had fallen to 0.06% from 2.40% a year earlier, and net interest income dropped 24% year over year.10 Pre-tax margin fell to 41%, down from 54% in the prior-year quarter. That quarter was also burdened by roughly $103 million of expense to compensate customers hurt in the April 2020 negative-oil-price event, so rates were not the only cause.10 But the direction is clear: when money is free, a large part of this machine's earning power disappears.
Take a longer view and the pattern repeats. In 2016, a period of near-zero rates, net interest income was $527 million and the pre-tax margin was 55%.2 By 2025, net interest income had reached $3.6 billion and the full-year margin was 77%.72 Some of that improvement is real operating leverage: more accounts, more balances, costs that barely move. But a meaningful portion is simply what happens to a cash-rich broker when rates go from zero to four-plus percent.
The honest conclusion is that the seven-quarter streak above 70% is a rate-cycle achievement as much as an operating one. The cost structure makes the margin possible. The rate environment decides how high it goes. Anyone who treats 77% as a structural floor is making a macro bet without realizing it.
There is one important nuance in the company's favor. In 2025 and the first half of 2026, rates were falling, not rising, and net interest income still grew because client balances grew faster than rates fell.9 The average effective Fed funds rate dropped from 4.33% to 3.63% over the year to Q2 2026, yet net interest income rose 23%.9 That is the best evidence that account growth, not just the Fed, is now doing the heavy lifting. It narrows the "it's all rates" critique without refuting it.
Cost structure as the moat
Now to the part of the machine that competitors cannot easily copy. For full-year 2025, general and administrative expense was $247 million against net revenues above $6 billion, and compensation ran at about 10% of adjusted net revenues, down from 11% a year earlier.7 On the Q1 2026 call, the compensation ratio was again 10%.8 Headcount grew about 6% in 2025 while accounts grew more than 30%.7
Hamilton Helmer, in his 7 Powers framework, calls this kind of advantage "process power": an embedded organizational capability, built over years, that rivals cannot replicate quickly even when they can see it clearly. Toyota's production system is the classic example. Interactive Brokers is a services-industry version. Every account-opening check, margin call, corporate action, and compliance screen that it automated decades ago is a person it does not need to hire today. A legacy broker cannot simply buy that; it would have to rebuild its operations from the ground up while still running them.
The analogy is a highway built before the city grew around it. The toll operator who laid the road early has sunk costs that are already paid. A newcomer has to buy land at today's prices.
Five forces, honestly scored
A war-game view of the industry is less flattering than the margin suggests.
Buyer power is high among the most valuable clients. Sophisticated traders and international investors frequently keep accounts at several brokers, routing each trade where execution or financing is best. In Asia, that means Interactive Brokers competes directly with 富途 Futu (Futu Holdings), its moomoo brand, and 老虎证券 Tiger Brokers (UP Fintech). Switching costs exist, since moving a margined portfolio with complex positions is a hassle, but they are lower than those of a bank relationship or an enterprise software contract. This is a genuine weakness in the moat story, not a strength.
Rivalry at the commission line is intense. Since the 2019 price war, commission-free US stock trading has been table stakes for retail brokers. Interactive Brokers' pricing edge now lies in margin rates, the interest paid on idle cash, currency conversion, and global access, not in the headline trade price.
The threat of substitutes is real but slow. Over a longer horizon, brokerages built natively around AI agents, or large platforms such as payment apps bundling investing, could compress the value of a standalone trading interface.
Barriers to entry, however, are high in exactly the places Interactive Brokers is strongest. The firm says it routes and processes trades on more than 170 electronic exchanges and market centers in 40 countries and 29 currencies.3 Behind each of those connections sits a license, a clearing relationship, a regulatory filing, and a compliance process. The SEC, FINRA, and CFTC stack in the US, plus equivalents across Europe and Asia, is expensive and slow for a challenger to assemble. Its IB SmartRouting technology, which scans venues to seek the best available price, is a further, harder-to-measure edge.
Net read: this is not a lock-in business. It is a cost-and-breadth business. Clients stay because the combination of price, financing rates, and global reach is hard to match, and they would leave if a rival matched it.
The competitive map
Charles Schwab is the scale leader and the default American brokerage, with client assets many times larger than Interactive Brokers'. Fidelity, privately held, is the full-service and workplace-retirement incumbent. Robinhood is smaller in assets but fast-growing, and it has been pushing into crypto and prediction markets, areas where it now overlaps directly with Interactive Brokers' newer products. Webull serves high-activity retail traders. Futu and Tiger dominate the Chinese-diaspora and mainland-adjacent investor market, now under regulatory siege, a thread picked up later.
Interactive Brokers deliberately occupies a different lane: the sophisticated, active, global trader and, increasingly, other brokers that need infrastructure. It is not trying to be the place a 25-year-old opens a retirement account with a friendly adviser. That positioning is both a strength and a ceiling. It avoids head-on fights with Schwab and Fidelity for mass-affluent assets, but it also limits how much of the largest wealth pools it can capture.
Geography: the underrated engine
Recent evidence suggests international expansion is a growth engine rather than a talking point. After opening access to the Korean market, Peterffy told analysts on the Q2 2026 call that demand for Korean semiconductor names was strong, with volumes "going straight up" week over week.1 Crypto access has expanded into continental Europe.81 And when Chinese regulators moved against Futu and Tiger, the company saw a "clear uptick in broker transfers," though management cautioned it was "hard to say whether that will continue."1
The strategic logic is that global breadth becomes more valuable as investors outside the US want to own American, Korean, Japanese, and European securities from a single account. Few competitors can offer that at Interactive Brokers' cost.
The introducing-broker channel: the moat that hides inside rivals
The least appreciated part of the machine is wholesale. Through its introducing-broker program, other brokers, fintechs, and crypto or CFD firms plug their own apps into Interactive Brokers' execution, clearing, and custody. The end client sees another brand. Underneath, the trade runs on Interactive Brokers' rails.
On the Q1 2026 call, management described the pipeline as "exceptionally strong" and said it had streamlined onboarding for larger brokers needing customized setups.8 The shift toward established firms rather than start-ups matters because established firms bring existing books of clients rather than hopes.
This is the most interesting moat extension in the company. When a competitor white-labels your infrastructure, you win whether that competitor's customer thinks about you or not. The limit is that introducing brokers can re-platform if a cheaper or more flexible clearing provider appears, so this channel's durability depends on the same cost-and-breadth advantage as the rest of the business.
Myth vs. reality
Myth: Interactive Brokers is a technology company that happens to hold client money. Reality: it is a balance-sheet business wrapped in exceptional technology. More than half of net revenue comes from interest, not from software or trading fees.1 The technology is what makes that balance sheet cheap to run and safe to lend against, but the money is made the way banks have always made money: on the spread.
Myth: zero commissions destroyed the brokerage model. Reality: commission revenue at Interactive Brokers hit a record in Q2 2026, seven years after the price war began.1 Zero commissions reshaped where the money comes from, shifting it toward interest, lending, and professional-tier commissions, but they did not eliminate it. The firms that suffered most were the ones without other booths on the toll road.
Myth: the margin is proof of a moat. Reality: the margin is proof of a moat plus a rate environment. The cost structure is the moat; the difference between a 55% margin and a 77% margin has a lot to do with where the Fed sets rates.27
Myth: professional traders are locked in. Reality: professionals are the most mobile clients in finance. They stay because the product is better on price and breadth, which is a competitive advantage that has to be re-earned continually, not a contractual lock.
Myth: margin lending is where the hidden risk lives. Reality: it is a real risk, but a well-managed one. Interactive Brokers liquidates under-margined positions automatically and in real time rather than issuing a polite call and waiting days for a deposit. That approach occasionally angers clients, but it is the reason margin loans of more than $100 billion have not produced a solvency scare.1 The exception, again, is the scenario the system did not anticipate, such as the night oil went negative.
The machine, then, has three engines, a cost structure rivals cannot quickly match, and a rate lever that flatters today's margins. The next question is which moments in the past seven years actually changed its trajectory.
IV. Modern-Era Inflection Points That Actually Moved the Stock (2019–2026)
2019: the day price stopped being a differentiator
For most of its life, Interactive Brokers could say, with a straight face, that it was the cheapest serious broker in America. Then Robinhood made the price of a US stock trade zero, and in the autumn of 2019 the large incumbents followed. The low-cost champion suddenly had a price problem.
Its answer was IBKR Lite, announced in September 2019: commission-free trading in US-listed stocks and ETFs, monetized in part through payment for order flow, while the existing IBKR Pro tier kept per-share commissions and a focus on execution quality.11 The two-tier structure was clever. It let the company chase younger retail clients without abandoning the professional traders who valued execution over a zero-dollar sticker.
What the move revealed is more important than the move itself. Interactive Brokers conceded that for retail entry, price had become a ticket, not a differentiator. Its competitive argument had to shift to financing rates, cash yields, global access, and the platform itself.
2019: the quiet succession
In the same year, Peterffy, then 75, handed the CEO title to Milan Galik and remained as chairman.12 Galik, like Peterffy, is an engineer by training, a longtime internal technologist who had spent years running software development. There was no outside search and no celebrity hire.
Founder transitions are among the riskiest moments in a company's life, especially when the founder keeps control. This one was deliberately low-drama, and nearly seven years of results since then suggest it has not disrupted the operating model. What it has not tested is the harder question: a succession in which the controlling shareholder is no longer present at all.
January 2021: the GameStop stress test
The week of January 25, 2021, was surreal. Retail traders, coordinating on Reddit, had driven GameStop, AMC, and a handful of other stocks to prices that bore no relation to their businesses. Options activity exploded. Clearinghouses raised collateral demands on brokers overnight.
Interactive Brokers responded by putting options in GameStop, AMC, Koss, and others into closing-only mode and raising margin requirements sharply on long and short positions. Peterffy went on CNBC and explained why: the firm had acted "to protect the market and the clearing system," arguing that if prices collapsed, losses could spill over to brokers and the broader system.13
The backlash was immediate and political. Critics accused brokers of protecting hedge funds at the expense of retail traders. Interactive Brokers soon eased its restrictions.
How should an investor judge this? Against the base rate, it was not an outlier; Robinhood and others restricted trading the same week, and the underlying mechanism was systemic collateral stress rather than a secret favor to short sellers. But it is a real data point on the "customer-first automation" narrative. When its own risk model was under strain, Interactive Brokers chose to protect itself and the clearing system over client access, and it accepted the reputational cost. For long-term shareholders, that is arguably the right priority. For clients who assume the platform will always let them trade, it is a warning.
April 2020: the night oil went negative
A less famous episode is actually more telling for the "automation as risk control" claim. On April 20, 2020, the May West Texas Intermediate crude oil futures contract settled below zero for the first time in history. Interactive Brokers' systems could not display negative prices, clients could not enter negative-priced limit orders, and internal minimum margin checks were not properly enforced before trades executed.14 Hundreds of customer accounts holding long positions lost about $82.6 million, which the firm compensated; the CFTC later fined it $1.75 million for supervision failures, noting it had prior notice that negative prices were possible.14
This matters because it was a technology failure, not a paperwork failure. The company that built its identity on automated risk management was caught by a scenario its automation had not been designed for. It paid clients and absorbed the cost, which speaks well of accountability. But the episode narrows the claim: automation controls the risks it was programmed to anticipate, and the edge cases are where the damage happens.
2022–2023: the rate windfall
Then the Fed did something it had not done in four decades: it raised rates by more than five percentage points in about sixteen months. For a broker sitting on tens of billions of dollars of client cash and margin loans, this was like a landlord waking up to discover every lease had tripled overnight.
The effect on the P&L was enormous. Net interest income, which had been a few hundred million dollars in the zero-rate years, climbed into the billions.27 That is the single largest reason investors now associate Interactive Brokers with 70%-plus margins.
It is worth separating this windfall from the account-growth story that management prefers investors focus on. Both are real. But the rate windfall was granted by the Federal Reserve, and the Federal Reserve can take it back.
2025–2026: buying growth, and saying so
After years of relying on word of mouth, Interactive Brokers began spending materially more on marketing, including hiring a chief marketing officer. Account growth accelerated: more than one million net new accounts in 2025, an annual record, and 34% year-over-year growth by the end of Q2 2026.71
The most interesting part of this chapter is what Peterffy said about it. On the Q2 2026 call, he recalled that he had once said growth would reach 30%, after which growth promptly fell to around 20%, before later recovering above 30%.1 The lesson he drew was to stop giving specific growth numbers. He also said that marketing yield, the number of accounts gained per dollar spent, "is roughly the same" as before.1
That is an unusually candid admission. It means the acceleration is being purchased with proportionally higher spending, not with a better funnel. On the Q1 2026 call, management had also said efforts to scale spend were "going very slowly" as the company looked for channels that met its return hurdles.8 Taken together, the evidence suggests that the current growth rate is partly a function of the marketing budget. If spend growth slows, account growth may follow.
2026: a regulatory gift
Finally, the SEC eliminated the pattern day trader rule, which had required accounts with less than $25,000 to limit how often they day-traded on margin. On the Q1 2026 call, Galik welcomed the change, saying regulators were "replacing an outdated concept."815 For a broker built for active traders, this opens the door to a larger pool of margin-eligible retail clients without requiring any new product. It also, inevitably, expands the population of small, active, leveraged accounts, which is precisely the population whose losses tend to surface in stress events.
These inflection points explain the stock. To judge whether the next decade looks like the last, the next step is to look at the people making the decisions.
V. Current Management: Incentives, Capital Allocation, Credibility
Milan Galik: the engineer as CEO
Milan Galik does not look like a Wall Street chief executive, and does not try to. He joined the firm decades ago as a software developer, rose through the technology organization, and became CEO in 2019.12 His public style is plain and product-focused. On the Q4 2025 call, he summarized the pitch as "No gimmicks, no games, just the best prices and the most comprehensive platforms."7
According to the company's SEC filings, his total 2025 compensation was reported at around $19.7 million, a ratio of roughly 177 times the median employee, with cash compensation of about $5.1 million and the balance in equity.12 The equity-heavy structure aligns him with shareholders, though it is worth noting that for a controlled company, alignment with the public float and alignment with the controlling shareholder are not always identical.
Paul Brody: the transparency proof point
CFO Paul Brody, a long-tenured executive with reported cash compensation of about $3.4 million, runs one of the most granular disclosure programs in the brokerage industry.12 The company publishes monthly brokerage metrics, quantifies its rate sensitivity every quarter, and breaks out securities lending on a fully loaded basis.91 That is evidence, not adjective: management teams that fear scrutiny do not hand investors the tools to model their biggest risk.
Thomas Peterffy: chairman, controller, and still the loudest voice on the call
Peterffy draws a nominal salary of about $766,500, because his real economic interest runs through his stake in IBG Holdings.12 He appears on earnings calls and answers the hardest questions himself, on margin risk, on account growth, on marketing. On the Q2 2026 call, asked about the risk in client margin loans, he said the firm was "very cognizant of our client risk on margins" and "comfortable with the current levels."1 On the Q4 2025 call, asked how long account growth could last, he answered: "As long as I shall live."7
It was a joke, and it was not. His presence is a credibility asset: few controlling shareholders speak this directly. It is also a concentration risk. The company's most substantive public voice is its founder, not its CEO.
Capital allocation: a pile that does not move
Excess regulatory capital rose to $10.3 billion by June 2026.1 The company pays a modest quarterly dividend of $0.08 per share.16 It has made no material acquisitions of other brokerages, and management has repeatedly passed on the deals bankers bring it, including in prediction markets, where it said on the Q4 2025 call that organic growth at ForecastEx made acquisitions unnecessary.7
One structural nuance deserves precision. Interactive Brokers does regularly issue new public shares, but not to raise cash. Each year it issues Class A shares to IBG Holdings in exchange for operating-partnership interests, enabling members of the holding company to redeem part of their stakes. In July 2026, for instance, it registered about 2.5 million shares for this purpose, lifting the public company's share of IBG LLC to about 26.6%.4 That is a slow, orderly sell-down by insiders, not a capital raise, but it does mean public share count rises over time.
Is the M&A restraint discipline? The evidence supports a bounded version of that claim. The multi-decade record shows organic growth, and the company did not chase the consolidation wave that its largest competitors joined. But restraint is only half a test. The other half is what happens with the capital. So far, most of it sits as a buffer, which is defensible for a broker whose clients borrow more than $100 billion against their portfolios. A skeptic would ask why a company with more than $10 billion of excess capital and a 77% margin returns relatively little of it. The forward test is simple: if a first big deal appears, what does it cost, relative to peer precedent multiples, and why?
The counterweight: a recurring regulatory record
The "we automate everything, so we control risk better than anyone" narrative has to be read next to the regulatory file, and the file is not short.
In August 2020, Interactive Brokers agreed to pay $38 million to settle SEC, FINRA, and CFTC actions: $11.5 million to the SEC, $15 million to FINRA, and $11.5 million to the CFTC.1718 The SEC found that it had failed to file more than 150 Suspicious Activity Reports flagging potential manipulation of microcap stocks, in some cases even after compliance staff had identified concerns.17
In September 2021 came the $1.75 million CFTC penalty over the negative-oil episode described earlier.14
In September 2023, the firm paid a combined $55 million to the SEC and CFTC, $35 million and $20 million respectively, in the industry-wide sweep over employees using WhatsApp and personal text messages for business communications. A CFTC commissioner's statement noted that Interactive Brokers was required to admit wrongdoing, and that the firm had previously neither admitted nor denied findings in three prior CFTC enforcement actions.19
And full-year 2024 G&A included a $78 million legal settlement charge, which management cited when explaining why 2025 G&A fell.7
How should this be weighed? The off-channel communications case hit much of Wall Street, so it says more about industry culture than about Interactive Brokers specifically. The AML case is more specific and more serious: it was a failure in exactly the kind of systematic screening that an automation-first firm should be best at. The oil event was a genuine system failure. Taken together, the record does not invalidate the automation thesis; the firm's core risk management has never produced a solvency scare. But it narrows it. Automation has made Interactive Brokers extremely efficient at the tasks it has automated well, and has not prevented repeated compliance and supervision lapses in the tasks it has not. The confirming signal would be several years without a new material enforcement action after the 2023 remediation commitments; the falsifying signal would be another one.
Guidance discipline, as evidence
The Peterffy growth-guidance anecdote belongs here as well, because it is behavioral evidence. A management team that refuses to give growth targets could simply be evasive. This one explained, unprompted, the specific episode that taught it not to, and paired the explanation with an unflattering disclosure about flat marketing yield.1 That combination is more persuasive than a scripted answer would be.
Management, then, is credible, transparent, disciplined about deals, and imperfect on compliance. But management operates inside a governance structure where one person holds the decisive vote, and that structure deserves its own stress test.
VI. Ownership, Control & the Governance Stress Test
Imagine being a public shareholder at the April 2026 annual meeting. The ballot arrives. You can vote on directors, pay, auditors, and a stock plan. Your vote is counted. And before the first ballot is opened, the outcome is already known.
How control actually works
The public owns Class A shares of Interactive Brokers Group, Inc., which in turn owns about 26% of IBG LLC, the operating partnership where the business actually lives. IBG Holdings LLC owns the other roughly 74%.34 IBG Holdings also holds all of the company's Class B common stock, just 400 shares, which carries voting power equal to its economic stake in the partnership: about 73.4% of the combined vote after the July 2026 exchange.34 Peterffy and his affiliates own about 91.8% of IBG Holdings.4
In other words, this is formally a dual-class structure, even if the ticker looks like a single class of stock. It qualifies as a controlled company. The public owns about a quarter of the economics and about a quarter of the vote.
What the April 2026 vote actually says
The headline results look like a landslide. Say-on-pay passed with 98.07% support; all ten directors were re-elected, with the lowest, longtime director Earl Nemser, at 86.44%; Deloitte's ratification passed with 98.98%; and a plan-extension proposal passed with 93.28%.20
But those percentages include the controlling holder's votes. Since IBG Holdings controls roughly three-quarters of the vote and presumably votes with management, the public's own sentiment is hidden inside the remaining quarter. Run the rough arithmetic. If about three-quarters of votes cast were IBG Holdings' in favor, then Nemser's 13.56% opposition came almost entirely from a public vote pool of roughly a quarter of the total, implying that something like half of the public shares voting may have opposed him. By the same logic, opposition to the plan extension might have represented roughly a quarter of public votes, and opposition to say-on-pay under a tenth. These are estimates, since abstentions and broker non-votes are treated differently, but the direction is clear.
That changes the conclusion. Public shareholders broadly support pay and the auditor. They are meaningfully less enthusiastic about at least one long-serving director. Under a control structure like this, dissent cannot change outcomes, so it is easy to miss. It should not be missed.
The founder as public figure
Two recent episodes show how a controlling founder's personal brand can become entangled with the company.
In April 2026, Peterffy told Bloomberg there should be "no bans on insider trading."21 It is an intellectually coherent libertarian position, and one he has voiced before, but it is an unusual thing for the controlling shareholder of a regulated broker-dealer to say publicly, particularly one whose regulators enforce those bans every day.
Separately, Peterffy disclosed a 25.9% stake in Newsmax, the conservative media company, held through Conyers Investments LLC.22 Bloomberg's wealth index reflects his large personal fortune, with the Newsmax holding a notable non-IBKR component following the company's 2025 listing.23 Neither the insider-trading remark nor the Newsmax stake involves Interactive Brokers' balance sheet. But in a company where the founder is also the controller, the market does not always separate the man from the stock.
The slow sell-down and the succession question
The control structure is not static. Each year, IBG Holdings exchanges some of its partnership interests for publicly traded Class A shares, and the public company's slice of the operating partnership edges up. The public stake moved from about 26.3% at the start of 2026 to about 26.6% after the July exchange.34 At that pace, the public would not own a majority of the economics for decades.
The more important question is what happens to the controlling stake eventually. The filings reviewed here describe the ownership structure but do not lay out a public, detailed plan for how voting control would be exercised after Peterffy. That is not unusual for a founder-controlled company, and it is not evidence of a problem. It is, however, the single largest unmodeled variable in the governance picture. A long-term shareholder is effectively betting that the board, Galik, and whoever inherits control of IBG Holdings will run the company with the same cost discipline and aversion to empire-building that Peterffy has enforced.
There is a reasonable argument that the operating culture is now institutional rather than personal. Galik has run the company for nearly seven years, the automation is embedded in systems rather than in any one mind, and the business model does not require founder-level deal-making. There is also a reasonable counterargument: the founder's willingness to say no, to bankers, to marketing excess, and to guidance games, has been the firm's most important governance mechanism, and it has never been tested without him.
The activist lens
A skeptical activist could not win a proxy fight here, but could still ask pointed questions. Why does the company hold so much excess capital relative to peers? What is the long-term plan for the IBG Holdings sell-down, and how will voting control evolve if Peterffy's estate eventually holds the stake? Is the board sufficiently independent of a founder who controls both its composition and its re-election?
The net assessment: the affirmative evidence, meaning high votes on pay and auditors, strong disclosure, and no history of related-party abuse visible in the record reviewed here, supports current governance quality. The concentration of control, the public-float dissent on a director, and the founder's public commentary are real risks, not demonstrated failures. The biggest untested governance event is the one that has not happened yet: the transfer of control after Peterffy. With that frame in mind, the company's newest bets can be sized properly.
VII. New Frontiers: Sized to Their Actual Economic Weight
In the spring of 2026, a client could open IBKR's app, pull up the same screen used to trade Tokyo futures or Frankfurt bonds, and take a position on whether a particular economic statistic would come in above or below a threshold. The contract pays a dollar if the answer is yes and nothing if it is no. Its price is, in effect, the crowd's probability estimate. That is either the future of information markets or a novel way to gamble, depending on who is asked, and the honest answer for investors is that it is too early to know which it will be economically.
The newest initiatives share a pattern. Each extends the core machine into an adjacent market where regulation, technology, or client demand is shifting. Each generates headlines. None, so far, generates a disclosed material revenue line. The discipline required here is proportion.
Prediction markets
In May 2026, Interactive Brokers launched a unified prediction markets offering that brought together contracts from ForecastEx, its own CFTC-regulated exchange, as well as Kalshi and CME Group, behind a single interface.24 The focus is on economic, political, and other event contracts; management has chosen to exclude sports and entertainment, a notable decision given how much of the industry's volume comes from sports.241
The strategic idea is sensible: aggregate liquidity from several venues and become the neutral front end. The 2026 midterm elections are a natural catalyst. But there is no disclosed revenue line for prediction markets, and there is no evidence yet that they are material to group results. This is optionality, and it should be priced like optionality.
Crypto
Crypto trading has expanded to the European Economic Area, and the company now offers crypto perpetual futures through Coinbase's derivatives exchange.81 Perpetuals, contracts that let traders take leveraged crypto positions without an expiry date, have become a significant share of the firm's crypto activity. This is real growth in a small slice of the business, and it overlaps directly with Robinhood's push into the same products. It is not yet a disclosed material revenue line.
AI agents
On the Q2 2026 call, management described IBKR Connector, which lets clients connect AI chatbots such as ChatGPT and Claude to their accounts to analyze portfolios and prepare trades, with a human-in-the-loop approval step before any order goes out.1 Management said fully autonomous agentic trading is a future goal, gated behind guardrails and client competency testing.1
This is a rare case of a company refusing to overpromise on an AI feature, and it fits the firm's DNA. The instinct that put handheld computers in the pits in 1983 is the same one integrating AI agents today. The risk, from a competitive standpoint, is that agent-native brokerages could eventually make the brokerage interface itself less relevant. Being early to connect agents to accounts is a sensible hedge against that.
The trust bank charter
The one new initiative that belongs in the core business rather than the optionality bucket is the national trust bank charter. Interactive Brokers received preliminary approval from the Office of the Comptroller of the Currency and expects the trust bank to be operational by year-end 2026, allowing it to directly custody mutual fund and ETF assets.1 Removing a third-party custodian from the chain lowers cost and dependency, and it may help the firm serve advisers and introducing brokers more completely. This is infrastructure, not a lottery ticket.
Consider the analogy of a logistics company that has always rented warehouse space from a third party. Building its own warehouse does not create a new product, but it removes a fee, a dependency, and a source of friction from every shipment. The trust bank is that warehouse. Its value will show up, if it does, not as a separate revenue line but as slightly better economics and a slightly broader product set across the whole platform. The usual caveat applies: preliminary regulatory approval is not the same as an operating bank, and the year-end target is management's timetable, not a certainty.
Sizing discipline
The honest summary: prediction markets, crypto, and AI monetization are early, plausible, and unproven. None appears as a disclosed material revenue line. The company's own history offers a partial guide. Its track record of converting technical capabilities into revenue has been strong when the new product plugs into the existing brokerage machine, like global market access or securities lending, and less visible when it sits outside it. The press-release cadence around these new products is fast; the P&L contribution, so far, is not visible. Commissions, net interest income, and fees still run the company. With the frontiers sized, the broader lessons of the record come into focus.
VIII. Playbook: What the Record Teaches
Every long-running company leaves behind a set of habits that explain its results better than any mission statement. Interactive Brokers' record offers six.
Cost position compounds silently. For decades, the firm's automation looked like a quirky engineering culture. Only once the business reached scale did it become obvious that it was a cost structure competitors could not match. Many moats look like this from the inside: invisible until they are enormous. The 1983 handheld computer and the 2026 AI connector are the same instinct, forty-three years apart.
Refusing guidance can be discipline, but only with an explanation. Many companies that decline to give targets are simply hedging. Interactive Brokers' refusal is more credible because Peterffy explained the episode that taught him the lesson and paired it with an unflattering admission about marketing yield. Investors should reward candor, not silence.
Passing on M&A is testable discipline. Not buying companies for decades while competitors consolidated is a meaningful signal. But restraint has a second chapter. The real test is what happens the first time the capital moves, and whether the price paid would look reasonable against peer precedents.
Global-first can beat domestic scale in a niche. Schwab and Fidelity won the US mass-affluent market. Interactive Brokers built a global platform for sophisticated traders that those giants never prioritized. The lesson is that in a crowded industry, the valuable niche is often the one the incumbents consider too complex.
A controlling founder's public persona is part of the governance profile. Peterffy's insider-trading remarks and personal media investments involve no company capital, yet they affect how regulators, clients, and investors view the company he controls.
Recurring fines are a tax on an excellence narrative. Automation is not the same as control. The 2020 AML case, the negative-oil failure, and the 2023 recordkeeping case show that an efficient machine can still have gaps where human supervision matters. The measure is whether those gaps stop recurring.
There is also a seventh, quieter lesson: structure outlasts personality, but only if it is designed to. The IPO's Dutch auction, the holding-company structure, and the annual share exchanges with IBG Holdings were all designed so the founder could keep control while gradually selling down.64 That design has worked for nearly two decades. Whether it works after the founder is gone is the open question that hangs over every other lesson.
Those lessons set up the central investor question: how do the bull and bear cases hold up when tested against the evidence?
IX. Bull vs. Bear: The Investment Case, Tested
The bull case, with evidence
Operating leverage is demonstrated, not claimed. A workforce of about 3,265 serves millions of accounts, compensation runs near 10% of revenue, and pre-tax margins have exceeded 70% for seven straight quarters.17 The strongest evidence that this is not purely a rate story is that net interest income grew 23% in a year when average rates fell.9
Growth is running ahead of the company's own "normal." Accounts were up 35% year over year by August 2026, and client equity was up a similar amount.2 Over a decade, the customer base grew from about 370,000 accounts to 5.46 million, nearly fifteen-fold.2
The introducing-broker pipeline is real distribution leverage. It embeds Interactive Brokers' infrastructure inside other companies' apps, extending reach without extending headcount.8
A fortress balance sheet creates optionality. More than $10 billion of excess capital gives room for dividends, buybacks, product investment, or, if discipline ever bends, acquisitions.1
Infrastructure moves strengthen the core. The trust bank charter, the AI connector, and prediction-market aggregation all extend the platform rather than diversify away from it.124
The bear case, with evidence
Margin quality is rate-dependent. The Q2 2020 margin of 41% and the 2016 margin of 55% are the company's own record of what lower rates do to this business.102 The $81 million per 25 basis points sensitivity works in both directions.9
Switching costs are weak among the best clients. Sophisticated, price-sensitive traders multi-home. The inflow from Futu and Tiger clients shows how quickly assets can move when conditions change, and the same mobility works against Interactive Brokers if a rival offers better financing or execution.1
Account growth is being bought. Peterffy's own statement that marketing yield has not improved means the acceleration is spend-driven.1 That is not bad, as long as returns hold, but it is less durable than organic word-of-mouth growth.
The regulatory record recurs. The AML, supervision, and recordkeeping cases span 2020 to 2023, and a large legal settlement charge hit 2024 G&A.1714197
Founder concentration is a single-point dependency. One octogenarian controls the company and remains its most substantive public voice.4
The new frontiers are unproven. None of prediction markets, crypto, or agentic trading is a disclosed material revenue line.
The China wildcard
On May 22, 2026, the China Securities Regulatory Commission announced penalties against Futu, Tiger Brokers, and Longbridge for illegal cross-border business, with combined fines of about RMB 2.26 billion, and set a two-year wind-down period in which existing mainland clients may only sell and withdraw.25 Interactive Brokers has benefited from transfers.1 But the same regulatory logic could, in principle, be applied to any overseas broker serving mainland residents without a local license. The benefit is visible; the potential exposure is not disclosed in detail.
Porter and Helmer, together
On Porter's terms, the industry looks tough: high buyer power among the best clients, fierce rivalry on price, slowly rising substitution threats, but high barriers to entry in global licensing and clearing. On Helmer's terms, Interactive Brokers clearly has process power in its automated operations and scale economies in spreading fixed technology and compliance costs over a growing base. It has partial cornered resources in its global exchange connectivity and regulatory licenses. It has weak switching costs and limited network effects, although securities lending and internalized liquidity gain modestly from scale. Brand power is real among professionals and weak in the mass market. Counter-positioning is its most intriguing power: legacy brokers built around advisers and branches cannot copy Interactive Brokers' cost structure without cannibalizing their own business models.
Peers help calibrate this. Schwab has scale and brand; Robinhood has brand with younger investors and speed; Futu has deep cultural fluency with Chinese-speaking investors, now undermined by regulation. Interactive Brokers' distinctive combination is cost plus global breadth. According to an analysis on Seeking Alpha, that combination is precisely what Robinhood and Schwab cannot easily offer.26
The activist's memo
Imagine a skeptical long/short fund writing a private memo on Interactive Brokers. It would not argue that the business is bad; the numbers make that impossible. It would argue that the stock prices in the wrong things.
First, it would say the market capitalizes peak-cycle interest income as if it were permanent. Every 25 basis points of rate cuts removes roughly $81 million of annual net interest income, and a return to zero rates, however unlikely it looks in September 2026, would compress margins toward the levels of 2016 or 2020.9210
Second, it would note that the capital is trapped by design. A broker must hold large buffers against client leverage, so the headline "$10.3 billion of excess capital" is less deployable than it sounds. A skeptic would press management to quantify how much of it is genuinely surplus under a severe stress scenario.
Third, it would observe that growth is increasingly purchased. If marketing yield is flat, then a slowdown in marketing spend is a slowdown in growth.1
Fourth, it would highlight the governance discount: a controlled company with an octogenarian founder, a public float with roughly a quarter of the vote, and a board that owes its seats to the controller.4
A thoughtful bull would have answers to each point, especially the evidence that balance growth has outrun rate cuts over the past year.9 But these are the right questions, and the Q3 call on October 15 will address at least two of them.
What would confirm or break the case
The claim "automation creates a durable cost moat" survives the evidence intact. The claim "margins are structurally above 70%" is narrowed: they are structurally high, and cyclically very high. The claim "growth is accelerating on its own" is narrowed: it is accelerating with the help of a larger marketing budget. The claim "automation equals control" is narrowed by the regulatory and oil-event record.
The KPIs that matter
Three measures will tell investors most of what they need to know:
- Realized net interest income sensitivity versus the disclosed $81 million per 25 basis points framework, as the Fed moves rates in either direction.
- Net new account growth relative to marketing spend growth, to see whether funnel yield ever improves or growth simply scales with the budget.
- The first material change in capital deployment, whether a large buyback, a special dividend, or a first significant acquisition, and the price and rationale attached.
With the case tested, the final assessment can be framed.
X. Grading & Final Thoughts
A report card is tempting for a company this measurable, but the more useful exercise is to state, dimension by dimension, what the evidence supports and where it runs out.
Execution. The evidence is strong. Cost discipline has held across four-plus decades, multiple rate regimes, a financial crisis, and a meme-stock mania. The record includes real stumbles, notably the negative-oil failure, but the core operating model has never broken.
Capital allocation. Restraint is proven; deployment is not. The company has avoided the consolidation wave that shaped its competitors and has not diluted shareholders to fund growth. The open question is what it will do with more than $10 billion of excess capital, and whether its first big move, whenever it comes, meets the standard its restraint implies.
Governance and controls. Mixed. Disclosure is excellent and shareholder votes on pay and auditors are strong. Against that sit founder control, a noticeable minority dissent on at least one director, and a regulatory record that recurred across several years.
Growth durability. Real but conditional. Account growth is faster than ever, yet management itself says the acceleration is proportional to spend, and the profit line remains exposed to the rate cycle.
Optionality. Too early to assess. Prediction markets, crypto, and AI agents are plausible extensions with no disclosed material revenue. The trust bank charter is the exception: it strengthens the core rather than diversifying away from it.
Step back and the shape of the investment case is clear. Interactive Brokers wins from here if three things remain true: its cost advantage keeps widening as accounts grow, client balances keep growing faster than rates move against it, and the global and wholesale channels keep feeding new accounts that incumbents are not built to serve. It stumbles if rates fall sharply while marketing-driven growth slows, if a regulatory or technology failure hits client trust at scale, or if the transition beyond Peterffy disrupts a governance arrangement that has always depended on one man's judgment.
The record so far argues that the first set of conditions is more likely to hold than the second set is to materialize. But the record also shows that this company's best years have coincided with its most favorable rate environment, and that its biggest self-inflicted wounds have come from scenarios it did not anticipate.
The final thought returns to the ratio from the opening. One employee for every 1,700 or so accounts is not a marketing slogan; it is the result of a strategy pursued for half a century. The question for the next decade is not whether the machine works. It is whether it keeps working as rates change, as marketing budgets grow, and as the man who built it eventually steps away.
XI. Recent News
Interactive Brokers will report third-quarter 2026 results on October 15, 2026, with a conference call at 4:30 p.m. Eastern.27 That call will be the first chance to see whether the account-growth acceleration continued through the summer and whether marketing yield has changed.
On September 16, 2026, the Federal Reserve raised its benchmark rate by 25 basis points to a 3.75%–4.00% range, its first increase since July 2023.9 Using management's disclosed framework, that is worth roughly $81 million a year in additional net interest income, before any change in balances or pass-through to clients.9
Monthly metrics for August showed 5.46 million accounts, up 35% year over year, and client equity of $962.8 billion.2 Meanwhile, the Chinese regulatory crackdown on Futu and Tiger continues to shape cross-border flows; management said in July that transfers had picked up but could not say whether the trend would last.125
References
-
Interactive Brokers (IBKR) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Interactive Brokers Stock Turned $10,000 Into About $110,000 in a Decade; Customer Base Grew Even Faster — The Motley Fool, 2026-09-20 ↩↩↩↩↩↩↩↩↩↩↩
-
Interactive Brokers Group, Inc. — Form 10-K for fiscal year 2025 — SEC EDGAR, 2026 ↩↩↩↩↩↩
-
Interactive Brokers Group, Inc. — Prospectus Supplement (424B5), exchange of shares with IBG Holdings LLC — SEC EDGAR, 2026-07-31 ↩↩↩↩↩↩↩↩↩
-
About the Interactive Brokers Group — company history page — Interactive Brokers ↩↩↩↩
-
Interactive Brokers raises $1.2 billion in IPO — The TRADE, 2007-05 ↩↩
-
Earnings call transcript: Interactive Brokers Q4 2025 beats EPS forecast — Investing.com, 2026-01-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Interactive Brokers Q1 2026 sees record revenue — Investing.com, 2026-04-21 ↩↩↩↩↩↩↩↩
-
The Fed's First Rate Hike Since 2023 Is Worth About $81 Million a Year to Interactive Brokers — The Motley Fool, 2026-09-18 ↩↩↩↩↩↩↩↩↩↩
-
Interactive Brokers Group, Inc. — Form 8-K, 2Q2020 Results — SEC EDGAR, 2020-07 ↩↩↩↩
-
Interactive Brokers to Launch IBKR Lite — Nasdaq press release, 2019-09-26 ↩
-
Interactive Brokers Group, Inc. — SEC EDGAR filing history (CIK 0001381197) ↩↩↩↩↩
-
Interactive Brokers restricted GameStop trading to protect the market, says Chairman Peterffy — CNBC, 2021-01-28 ↩
-
CFTC Orders Interactive Brokers LLC to Pay a $1.75 Million Penalty for Supervision Failures — CFTC press release, 2021-09-28 ↩↩↩↩
-
Interactive Brokers Group, Inc. (IBKR) Q1 2026 Earnings Call Transcript — Seeking Alpha, 2026-04-21 ↩
-
Interactive Brokers Group Announces 4Q2025 Results — TradingView News, 2026-01-20 ↩
-
SEC Charges Interactive Brokers With Repeatedly Failing to File Suspicious Activity Reports — SEC press release, 2020-08-10 ↩↩↩
-
CFTC Orders Interactive Brokers LLC to Pay More Than $12 Million for AML and Supervision Violations — CFTC press release, 2020-08 ↩
-
Statement of Commissioner Christy Goldsmith Romero on Interactive Brokers WhatsApp/Recordkeeping Enforcement — CFTC, 2023-09-29 ↩↩
-
Interactive Brokers Group, Inc. — Form 8-K, 2026 Annual Meeting Voting Results — SEC EDGAR, 2026-04-23 ↩
-
Thomas Peterffy Says There Should Be No Bans on Insider Trading — Bloomberg, 2026-04-09 ↩
-
Interactive Brokers Chairman Thomas Peterffy Discloses 25.9% Stake in Newsmax — MarketScreener ↩
-
Bloomberg Billionaires Index — Thomas Peterffy profile — Bloomberg ↩
-
Interactive Brokers Expands Prediction Markets, Unifying Access to Kalshi, CME Group, and ForecastEx — Interactive Brokers press release, 2026-05-14 ↩↩↩
-
China drops hammer on cross-border stock trading: 5 things to know — KrASIA, 2026-05 ↩↩
-
Interactive Brokers Offers What Robinhood And Schwab Simply Can't — Seeking Alpha, 2026-09-09 ↩
-
Interactive Brokers Group to Host Third Quarter Earnings Conference Call — Stock Titan, 2026-09-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube