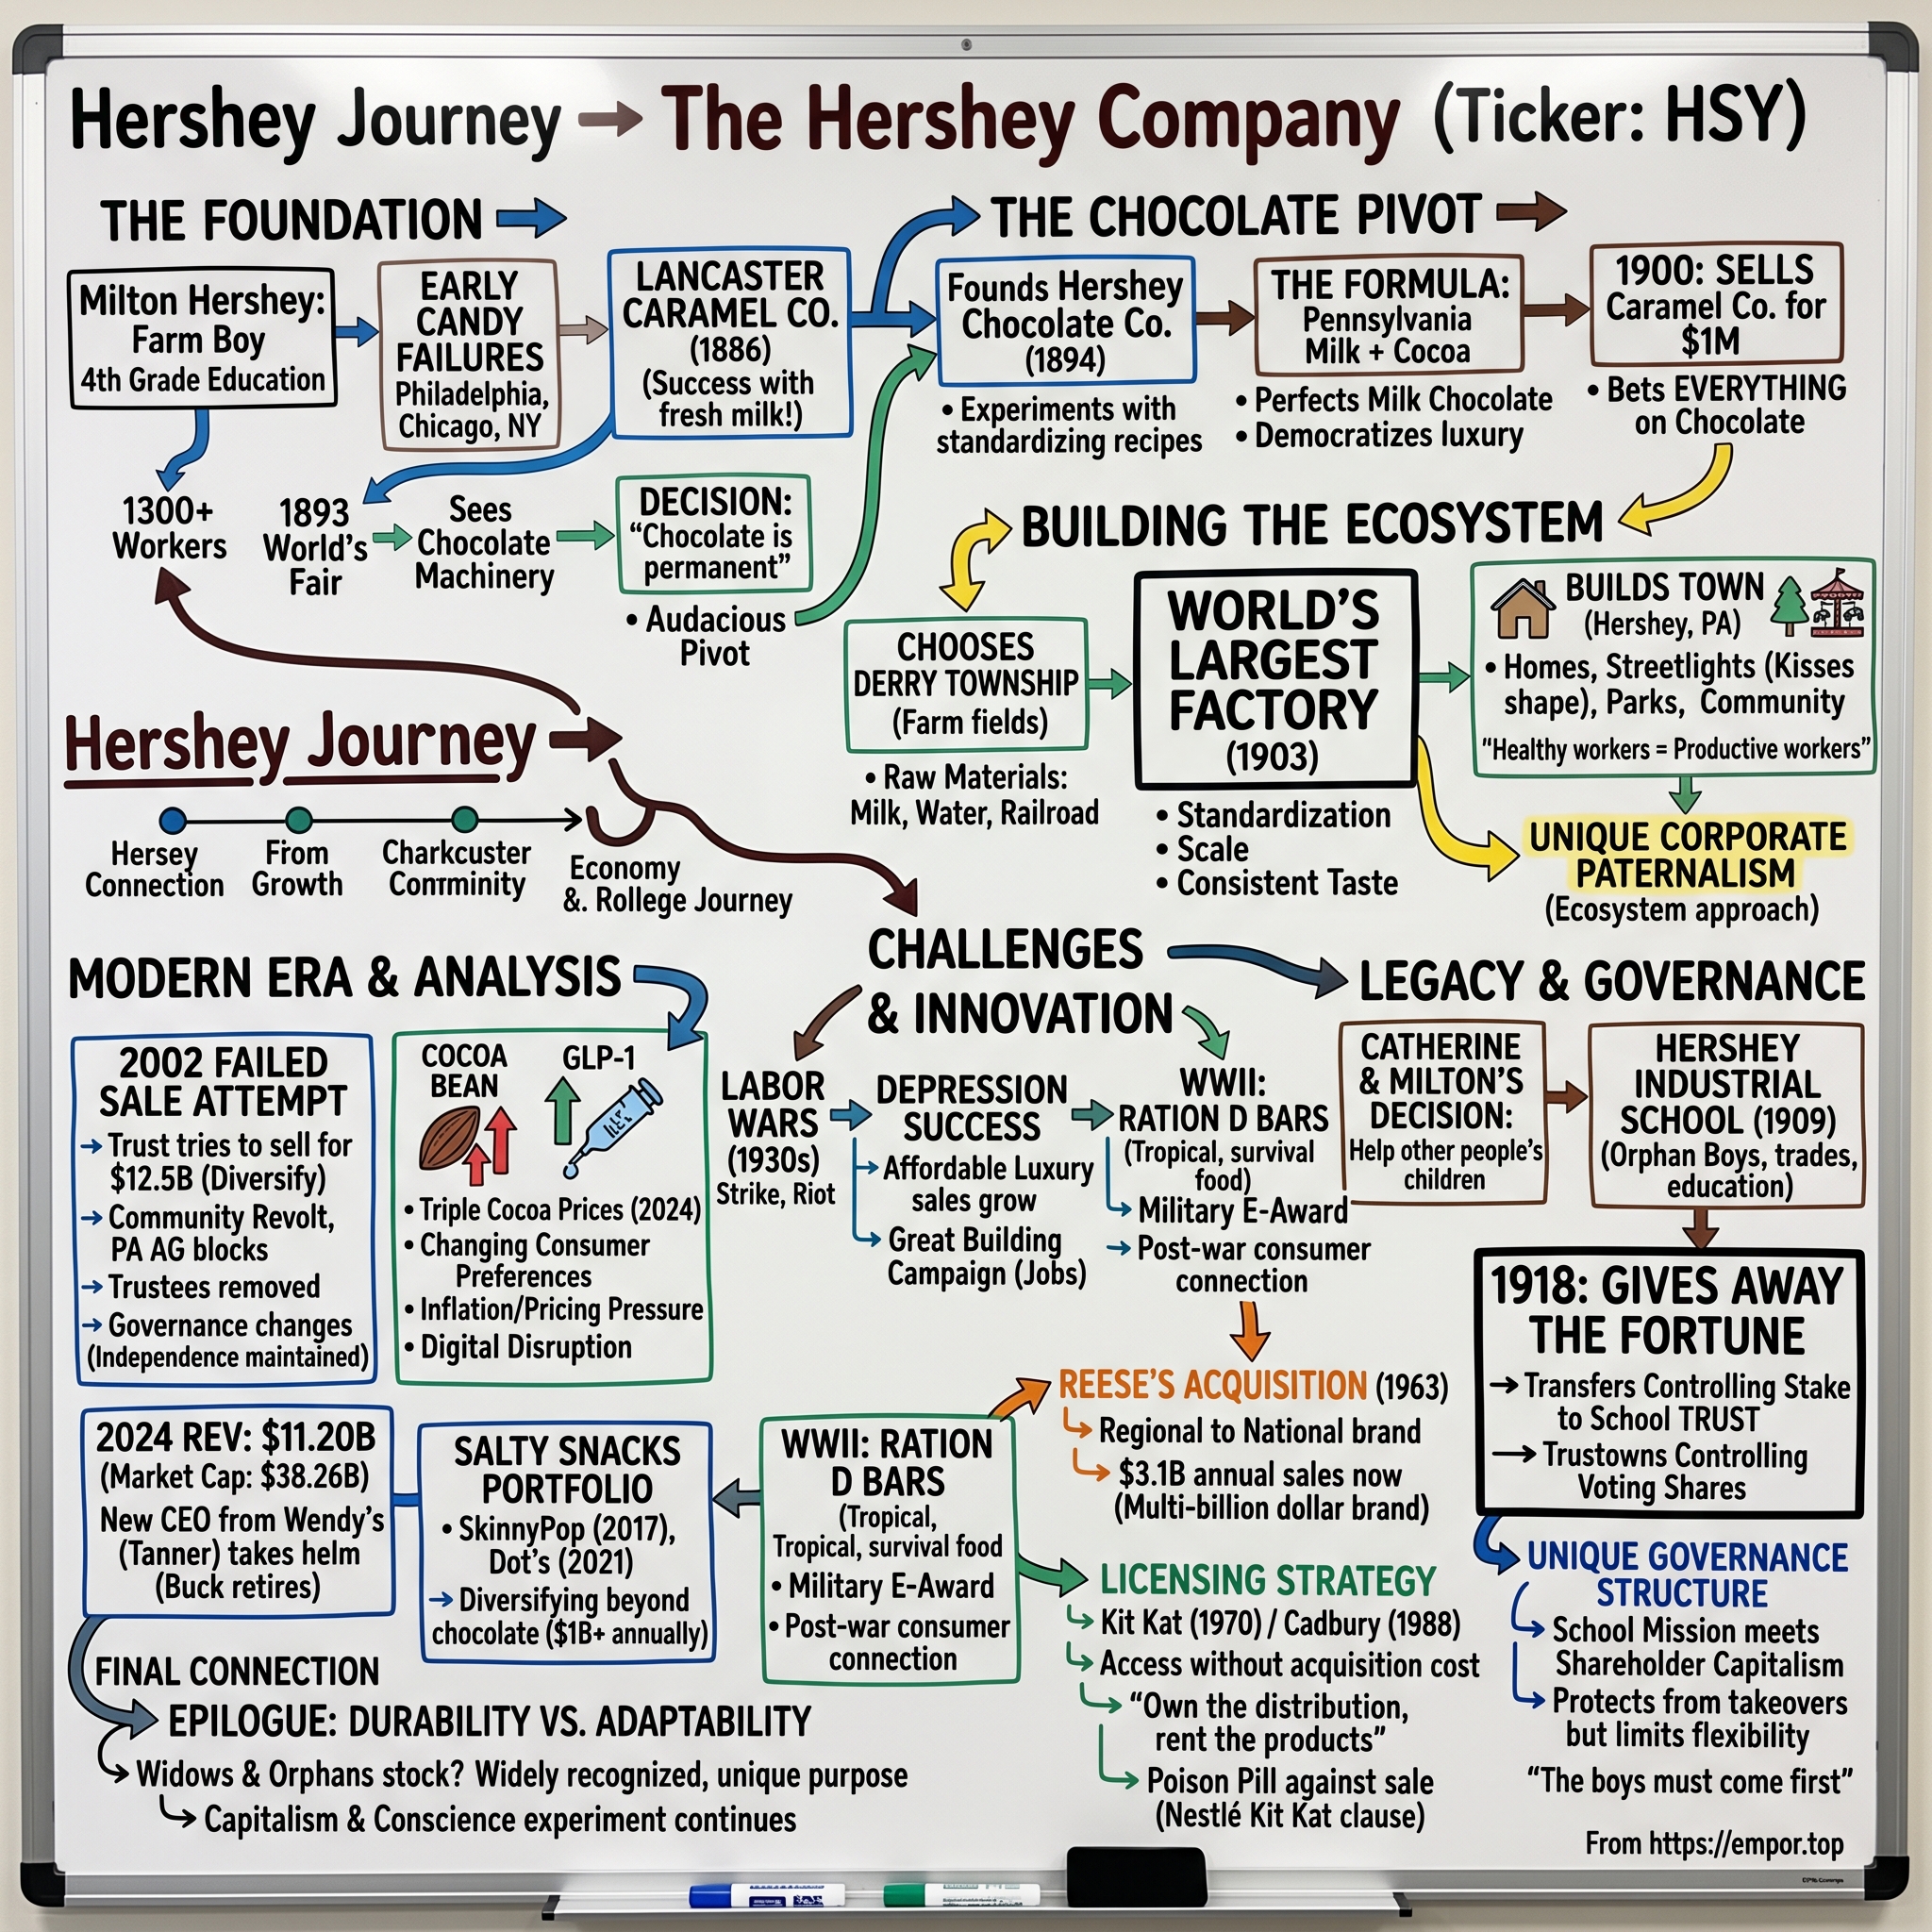
The Hershey Company: America's Sweetest Industrial Story
I. Cold Open & Episode Premise
On the morning of November 13, 1918, a sixty-one-year-old widower in central Pennsylvania signed away almost everything he owned. There was no press conference, no ribbon-cutting. Milton S. Hershey transferred 5,000 shares of the Hershey Chocolate Company into a perpetual trust for a small school for orphaned boys that he and his late wife Catherine had founded nine years earlier.1 The transaction stayed within a tight circle for five years. When the Harrisburg Evening News finally broke the story in November 1923, the headline put a number on it: "$60,000,000 Gift Confirmed." The New York Times followed days later.1 Hershey had kept quiet, he explained, because he did not want business rivals to misread his motives.1
That quiet signature remains the single most consequential fact about The Hershey Company. More than a century later, the Hershey Trust Company — acting as trustee for the Milton Hershey School Trust — holds 54.6 million shares of Class B stock carrying ten votes apiece, plus roughly two million ordinary common shares. Combined, those holdings gave the Trust the right to cast 79.0% of the votes at the 2026 annual meeting.2 Wall Street owns most of the economic value; a school board in Derry Township, Pennsylvania decides what happens to it.
That arrangement raises a question that frames the entire story: had Milton Hershey sold the company and allowed the trust to diversify, would the Milton Hershey School be wealthier today — and would anyone outside Pennsylvania still know his name? The answer matters to investors in HSY, because the structure that made the company famous is also what constrains it.
The investment case, stated plainly, rests on several tensions. Hershey is one of two dominant players in the U.S. chocolate aisle and is protected against hostile takeover in a way virtually no other publicly listed consumer company is. It is climbing out of the deepest earnings trough in its modern history, the result of a once-in-a-generation spike in cocoa prices. A new chief executive, Kirk Tanner, arrived from PepsiCo and Wendy's in August 2025 with a mandate to rebuild margins. A second business in salty snacks has grown to roughly a ninth of total sales. Yet the Trust that shields the company from unwanted acquirers also limits what management can do with the balance sheet. And cocoa tail risk has not been resolved: as of September 2026, with a strong El Niño forming over West Africa, cocoa futures were still trading well above their pre-crisis range.34
This article follows the arc of that argument — beginning with the origin of the Trust and its governance consequences, then moving through the economics of the chocolate oligopoly, the bet on salty snacks, the cocoa crisis, the capital allocation record, the new CEO's early moves, and finally the bull and bear cases and the metrics that will determine which prevails. The story begins, as Hershey stories must, with a failure.
 Subscribe on LinkedIn
II. Origin Story: Failures, Fresh Milk, and the $1 Million Bet
A decade of failing forward
Milton Hershey was born in 1857 in Derry Township, Dauphin County, Pennsylvania. His schooling was patchy, and in 1872 he apprenticed under a Lancaster candy maker.5 What followed was a decade that would have ended most careers. Between 1876 and 1886, he launched confectionery businesses in Philadelphia, Chicago, and New York — and every one failed. He returned to Lancaster in 1886 with almost nothing.5
The recovery came through caramel. The Lancaster Caramel Company started in a small Church Street shop and grew into one of the region's larger manufacturers.5 Hershey's edge was an ingredient insight rather than a recipe: he built the business around fresh milk, becoming, in effect, a dairy-processing specialist who happened to sell candy. That expertise shaped everything that followed.
Chicago, 1893
The pivot came at the World's Columbian Exposition in Chicago in 1893, where Hershey observed German chocolate-making equipment in operation.5 He purchased the machinery and, in 1894, established the Hershey Chocolate Company as a subsidiary of his caramel operation.5 For six years, chocolate was a secondary line, used mainly as a coating.
Then came the capital-allocation decision that defines him. On August 10, 1900, he sold the Lancaster Caramel Company to the American Caramel Company for $1 million in cash.6 He retained the chocolate company, its machinery, and a rented portion of the old factory to continue production.6 The company archives record his reasoning: caramel was a fad nearing its end; chocolate would last.6
The logic repays attention. Hershey walked away from a profitable, proven business to concentrate entirely on a product that barely existed in American mass-market form. In 1900, milk chocolate was a European luxury import. His contribution was to apply his fresh-milk knowledge to industrialize production — driving unit costs low enough to sell a bar for a nickel. That was manufacturing as a competitive moat, a century before the terminology became fashionable. He then built a factory, and a town to surround it, among the dairy farms of Derry Township.
Why the prologue still matters
The origin story is prologue, not thesis, but it leaves three fingerprints on today's company. The first is a habit of concentration: Hershey made one enormous bet on chocolate, and the company remains overwhelmingly a chocolate business. The second is a structural emphasis on scale manufacturing and cost discipline. The third, and most consequential for the governance structure introduced in the preceding section, is that Hershey married in 1898 and never had children.5 A founder with no heirs and a fortune concentrated in a single company faced an unavoidable question about succession. His answer is the next chapter.
III. The Town, the Trust, and the Governance Structure That Changed Everything
A company town with a purpose
Picture Hershey, Pennsylvania, in the 1910s. Worker housing, parks, a trolley line, a bank, utilities — all built by the chocolate company for its workforce. The motives were mixed. A rural factory needs a stable, healthy workforce, and a pleasant town discourages workers from leaving for Philadelphia.
On November 15, 1909, Milton and Catherine Hershey signed the Deed of Trust that created the Hershey Industrial School, now the Milton Hershey School.5 Its original deed restricted enrollment to white male orphans — a requirement not removed until 1970.7 Catherine died in 1915.1 Three years later came the 1918 gift of the company shares, the consequences of which were introduced in the preceding section.
How the control structure works
Today's arrangement has three layers. The Milton Hershey School Trust is the charitable trust. Hershey Trust Company is its trustee. The Trust's main asset is its stake in The Hershey Company, held largely through Class B shares carrying ten votes each. As of March 6, 2026, the Trust held 54,612,012 Class B shares and 2,066,119 common shares, giving it 79.0% of votes when both classes vote together.2 Set against the company's roughly 203 million diluted shares, the Trust's economic ownership works out to a little over a quarter of the business.8 A quarter of the economics, four-fifths of the votes.
The mechanics also explain why the Trust cannot quietly sell down its stake without surrendering control. Class B shares convert into common stock on sale, shedding their ten-to-one voting weight in the process.9 Every Class B share the Trust sells therefore cuts its voting power ten times faster than its economic stake. Its occasional sales of ordinary common shares barely move either number. The structure is built to persist.
The link extends into the boardroom. Three of Hershey's eleven directors also sit on Trust or school boards, including the independent chair, Maria T. Kraus. Under a February 2026 amendment, electing the chair requires the agreement of Hershey Trust Company.2 The company's own proxy describes this as "a direct link between the Board and our stockholders."2 That description is accurate, provided the stockholder in question is the Trust.
The school the structure funds is substantial by any measure. It serves roughly 2,100 low-income students with free housing, food, clothing, and education, spending about $90,000 per student each year.7 It is also well-capitalized. Between 1999 and 2019, Trust assets grew nearly fourfold, from $4.5 billion to $17.4 billion, and by 2020 the Trust had accumulated more than $1 billion of unspent income.7 A 2021 investigation by ProPublica, the Philadelphia Inquirer, and Spotlight PA found an average spending rate of about 2.2% of assets since 2002, two attorney general settlements over the previous decade, and board members paid at least $110,000 a year.7
That finding reveals a quiet tension at the heart of the structure. The Trust primarily needs Hershey to keep paying dividends so it can fund the school. It has no obvious need for the company to grow faster, take larger risks, or maximize its share price. In 2020, the Trust committed $350 million to a new preschool initiative and set aside a $900 million emergency reserve — equal to roughly 2.7 years of operating costs.7 Those are the choices of a cautious endowment, not an aggressive owner. For public shareholders, that caution cuts both ways: it makes reckless moves unlikely, and it makes transformational ones just as unlikely.
The 2002 test: when the owner tried to sell
The best evidence of how this structure behaves under stress comes from 2002. That summer, the Trust's board concluded that concentrating so much of its portfolio in one stock was imprudent and put the company up for auction. Wm. Wrigley Jr. Co. reportedly bid $12.5 billion, a 42% premium to Hershey's pre-auction share price. Nestlé and Cadbury Schweppes submitted a joint bid.1011
Then the town revolted. Pennsylvania Attorney General Mike Fisher, then running for governor, went to court and argued a sale could devastate the community; a judge issued a temporary injunction.10 After a ten-hour meeting in September 2002, the Trust's board voted to halt the auction.10 One banker told Reuters the outcome had "nothing to do with anything other than the politics."10
The episode is the clearest challenge to the comfortable narrative that the Trust is simply a patient, benevolent long-term owner. In 2002, the Trust's own fiduciaries decided that diversification served the school's interest. Politics overruled them. From the school's perspective, a 42% premium and a diversified endowment might well have been worth more over time than a concentrated stake in one confectioner. That cannot be proven, but it is a serious argument, and nothing since has settled it.
The pattern repeats
The structure has blocked or chilled every serious approach since. In 2007, Cadbury's chief executive approached Hershey's then-CEO Richard Lenny about a combination. The Trust accused Lenny of withholding information. Lenny resigned, eight directors departed in what became known as the "Sunday night massacre," and the talks collapsed.11 In 2016, Mondelēz offered roughly $23 billion, or $107 a share in cash and stock, even offering to relocate its headquarters to Hershey and retain the Hershey name. The board rejected the offer unanimously, and Hershey's stock was already trading above the bid price at the time.12 That same year, the Pennsylvania attorney general's office had pushed long-serving Trust board members to step down.11
Set side by side, these episodes point to a consistent pattern with an inconvenient conclusion. The Trust does not function as a single, coherent owner with a stable plan. It operates as a political institution whose decisions turn on the sitting attorney general, the town's disposition, and the composition of the board at any given moment. It blocked a sale its own fiduciaries wanted (2002), ousted a CEO who explored a deal (2007), and rejected a bid it considered inadequate (2016). The one constant is that no one has managed to buy Hershey. The resulting moat is real, but it rests as much on local politics as on anything in the company's charter — and politics can shift. That structure also shapes the economics of the business itself, which is where the story turns next.
IV. How the Core Business Works: Oligopoly, Shelf Space, and Seasonal Cash Flows
The checkout lane
Stand at any American grocery checkout and count the chocolate. Reese's cups, Hershey's bars, Kit Kat, Kisses — then a smaller wall of M&M's, Snickers, and Twix. Almost everything within arm's reach comes from two companies: one public and trust-controlled in Pennsylvania, the other private and family-owned in Virginia. That shelf is the economic engine of The Hershey Company.
Hershey describes itself as the largest producer of quality chocolate in North America.9 Statista estimated its share of the U.S. chocolate market at roughly 35.5% in 2022, with Mars slightly ahead in overall confectionery.13 Ferrero, Lindt, and Mondelēz are meaningful but smaller. In fiscal 2025, the North America Confectionery segment generated $9.48 billion of Hershey's $11.69 billion in net sales — about 81% of the total — and $2.49 billion of segment income, a 26.3% margin even in the worst cocoa environment the company has faced in its modern history.8
Porter's five forces, applied to a chocolate bar
Supplier power is high. Cocoa is sourced overwhelmingly from a handful of West African countries, trades on thin and speculative futures markets, and cannot be substituted in a product whose entire identity is chocolate. Hershey hedges using futures and options over horizons of three to twenty-four months.14 That smooths costs in a normal cycle but cannot absorb a sustained price shock — as the 2023–2025 episode demonstrated, and as section VI examines in detail.
Buyer power is moderate, and more concentrated than it appears. In 2024, roughly 27% of Hershey's consolidated net sales flowed through McLane Company, the wholesale distributor that serves Walmart, among others.9 A single distribution relationship accounts for more than a quarter of revenue. The brand still gives Hershey leverage — shoppers who want Reese's rarely accept a generic peanut-butter cup — but a retailer controlling checkout real estate can squeeze promotional terms, and a distributor at that scale has little trouble making its preferences known.
The threat of new entrants is low. Building a national chocolate brand requires decades of advertising investment, manufacturing scale, and the kind of seasonal execution that only repetition teaches. About 74% of Hershey's manufacturing capacity sits inside the United States.9 That footprint is a barrier as much as it is a cost center.
Substitutes are a moderate and rising threat. The most significant substitute is not a competing candy bar but a drug. A Cornell study published in December 2025 tracked roughly 150,000 households and found that those adopting GLP-1 weight-loss medications cut grocery spending by 5.3% within six months, with spending on sweets, baked goods, and savory snacks falling by approximately 10%.15 GLP-1 use in those households rose from about 11% in late 2023 to more than 16% by mid-2024.15 The mechanism is category shrinkage rather than brand switching: people eat less candy, not a different brand of it.
Rivalry is moderate in chocolate and intense in salty snacks. The U.S. chocolate category behaves like a disciplined duopoly; management repeatedly described it as "rational" in late 2025, though analysts noted price gaps against Hershey's largest competitor in king-size bars at convenience stores.16 Salty snacks are a different contest. There, Hershey faces PepsiCo's Frito-Lay, and — since Mars closed its roughly $36 billion Kellanova acquisition in December 2025 — a competitor that now owns Pringles and Cheez-It as well.17
Hamilton Helmer's 7 Powers
Branding is Hershey's strongest power. Reese's, Hershey's, Kisses, and Jolly Rancher carry decades of habituated consumer preference. The evidence that the power is real: Hershey pushed through double-digit price increases in 2025 and 2026 and, by management's account, still gained share across seasons in the first half of 2026.19 The evidence that it has limits: volume fell sharply when those increases landed, as section VI recounts.
Scale economies are real but shared with Mars. National manufacturing, direct store delivery, and category-management teams are fixed costs spread over the largest volume base in U.S. chocolate. Scale protects Hershey against the Ferreros of the world, but not against a rival of comparable size.
Cornered resource is the most structurally unusual power Hershey holds, and it derives from a license. In 1970, British confectioner Rowntree granted Hershey the U.S. rights to Kit Kat; Rolo followed in 1971.18 When Nestlé acquired Rowntree in 1988, it inherited the license along with a clause stipulating that any change in control of Hershey returns the rights to Nestlé. At the time, Kit Kat represented about $300 million in annual sales, or roughly 7% of Hershey's revenue.18 Hershey must hit minimum volume thresholds each year, and it met that requirement in 2024.9 Kit Kat is worth more inside Hershey than in any acquirer's hands — which makes it simultaneously a cornered resource and a structural deterrent to acquisition, reinforcing the political barriers described in section III.
Counter-positioning comes from the Trust, almost incidentally. No rival can replicate "controlled by a charitable school trust that cannot easily be compelled to sell." That protects management from activist shareholders but, as section VII argues, also caps what minority shareholders can realistically expect to realize.
Switching costs, network effects, and process power are weak or absent. A consumer can switch candy bars at zero cost. What keeps them returning is habit — a brand effect, not a structural lock-in.
Why the margins were real
The 2025 segment results clarify where Hershey's profit actually originates. North America Confectionery earned a 26.3% segment margin in the worst cocoa year in the company's recent history. Salty snacks earned 19%. International earned almost nothing.8 Nearly all of the company's profit flows from one segment in one country, supported by a duopoly structure and a portfolio of brands built over a century.
One channel deserves particular attention: what the industry calls "immediate consumption" — the single bar bought at a gas station or convenience store and eaten within minutes. These transactions carry higher margins than take-home multipacks, reinforce brand habits, and turn on winning a few square feet of counter space. CEO Kirk Tanner has said he is "passionate about the convenience channel." In October 2025, he noted that chocolate sales in convenience stores were growing at roughly 6%.16 Hershey said approximately three-quarters of its units sold for under $4,16 keeping the product in impulse-purchase territory even after significant price increases.
The convenience channel is also where rivalry with Mars is sharpest. Analysts in late 2025 pointed to price gaps in king-size bars following Hershey's increases. Chief Financial Officer Steve Voskuil acknowledged the issue directly: "Some of those gaps are closing. Some of those gaps may hang around for a while."16 It was a candid signal that the duopoly does not always move in lockstep on pricing.
The seasonal machine
Hershey's calendar is organized around four holidays: Valentine's Day, Easter, Halloween, and Christmas. Seasonal packs are designed, manufactured, and shipped months in advance, and retailers commit shelf space early. The date of Easter alone can shift quarterly results by several percentage points. On the Q2 2026 earnings call, management noted that a shorter Easter in 2027 made 2% a reasonable "starting point" for North America Confectionery growth in that year.19 Halloween carries even higher concentration. When the holiday falls on a Friday, roughly a third of the season's sales compress into the final week — a dynamic Tanner described after a disappointing 2025 Halloween.16
That seasonality makes inventory planning, input-cost hedging, and retail execution consequential skills rather than routine logistics, and it leaves the company exposed when any one of them slips. The 2025 results supplied a clear illustration.
The broader conclusion from the industry structure is that Hershey's pre-crisis margins were earned rather than circumstantial. They rest on a genuine duopoly, a portfolio of habit brands, and a Kit Kat license that no acquirer can inherit intact. But the structure has one acute vulnerability — the cocoa supply chain — and one slow-moving headwind in a population consuming less sugar. Management's answer to both has been to build a second category.
V. Building the Salty Snacks Platform: The Second Act Bet
The strategic logic
In December 2017, Hershey's leadership stood before investors to explain why a chocolate company was paying $1.6 billion for a popcorn maker. The logic was straightforward. U.S. confectionery grows slowly, historically in the low single digits. A company controlled by a trust that cannot easily sell itself or issue large amounts of stock needs a second growth engine it can fund with cash and debt. Salty snacks share the same retailers, the same checkout-adjacent aisles, and much of the same distribution infrastructure. Popcorn and pretzels also reduce exposure to cocoa — the input risk that, as the next section recounts, eventually proved severe.
The execution has been more uneven than the logic.
The deal record
Amplify Snack Brands (2017–2018). Hershey paid $12 a share, approximately $1.6 billion including assumed debt, for the maker of SkinnyPop, Paqui, Tyrrells, and Oatmega. The price implied roughly 14.8 times 2017 adjusted EBITDA, including about $20 million of expected synergies.20 CEO Michele Buck described the deal as bringing "scale and category management capabilities to a key sub-segment of the warehouse snack aisle."20 Within months, Hershey sold Tyrrells, the British crisps brand that came with the package, to KP Snacks; terms were not disclosed.21 SkinnyPop grew slowly for years afterward. By 2025, the brand was undergoing a refresh, and CEO Kirk Tanner pointed to new multipacks and portion-control formats as catalysts for renewed momentum.16 The fairest verdict is that Hershey paid a growth multiple for a brand that has not recovered its pre-acquisition growth rate.
ONE Brands (2019). Hershey paid $397 million for a maker of low-sugar, high-protein bars.22 The acquisition functions as a hedge against wellness trends, including the GLP-1 dynamic introduced in the preceding section. Notably, the Cornell study found that GLP-1 households actually increased spending on nutrition bars — which, if sustained, would favor ONE.15 Hershey has never disclosed ONE's revenue separately, so its commercial progress cannot be assessed from public filings.
Dot's Homestyle Pretzels and Pretzels Inc. (2021). Hershey paid $1.2 billion for Dot's and its contract manufacturer, which together generated about $275 million in net sales in the twelve months to September 2021.23 Dot's, founded by Dot Henke in North Dakota, had captured roughly 9% of the $2 billion pretzel category in five years and accounted for 55% of that category's growth in the prior year.23 Buying the manufacturer alongside the brand was sound vertical integration. By 2025, Tanner said Dot's had become "the leader in the Pretzels category."16 That makes it the standout acquisition in the salty portfolio. It is not without complications, however. In the second quarter of 2026, demand outpaced supply: Hershey was forced to use spot freight, and salty segment margin fell 500 basis points as a result. New capacity is not expected online until 2027.2425
Pirate's Booty and the puffs opportunity. The Amplify deal also brought Pirate's Booty, a puffed rice-and-corn snack with a following among parents of young children. Tanner has noted that puffs represent the third-largest subsegment of the salty category at more than $4.5 billion in annual sales and has said Hershey is "just scratching the surface" there.16 That is a reasonable claim. It has not yet been tested at scale.
LesserEvil (2025). In April 2025, Hershey announced the acquisition of an organic popcorn and puffs maker. Buck described it as adding "a multi-category, better-for-you snacks platform" to the company.26 The deal closed in November 2025 for $769.1 million in cash, plus up to $200 million in contingent consideration tied to earnings targets over several years.14 Hershey has not disclosed LesserEvil's revenue. Its contribution to segment growth in 2026 — roughly 20 to 22 percentage points per quarter on a quarterly segment base of approximately $300 million — implies an annual run rate of somewhere in the $250–$300 million range.2724 If that estimate is roughly correct, Hershey paid something between two and a half and three times sales before the earnout — a price that embeds a significant assumption about future growth.
What the numbers say
Setting ONE Brands aside, Hershey has spent roughly $3.6 billion on three salty acquisitions, with potentially more to follow if the LesserEvil earnout is triggered. In fiscal 2025, before LesserEvil made a full-year contribution, the North America Salty Snacks segment generated $1.27 billion in net sales, up 11.9% year over year, and $241 million in segment income — a 19% margin.8 Measured against the approximately $2.8 billion spent on Amplify and Dot's, that works out to a high-single-digit pre-tax return before any corporate overhead allocation. It is respectable but falls well short of what a disciplined acquirer aims to earn, and it is materially below what the chocolate business generates on its own assets.
Organic growth tells a more instructive story than acquired growth. Salty snacks delivered 18% organic growth and double-digit volume gains in the fourth quarter of 2025.28 That momentum then slowed — to 5.6% organic growth in the first quarter of 2026 and just 0.6% in the second, when Dot's supply constraints and heavier promotional spending collided.2724 The segment has demonstrated that it can grow. What it has not yet demonstrated is that it can grow consistently without either acquiring new volume or accepting margin compression to keep velocity.
Weighing the thesis
The case for building a second growth engine through acquisitions holds up, but only in a narrower form than management has typically presented. Dot's shows that Hershey can identify and scale a strong brand when it also controls the manufacturing. SkinnyPop illustrates the risk of paying a peak-growth multiple for a brand without a structural moat. And as section VII examines, Hershey's longer acquisition record includes deals that ended in write-downs.
The salty platform is strategically coherent and financially adequate. It is not yet proven. The test is concrete: once the Dot's capacity additions come online in 2027, can organic salty growth — excluding the LesserEvil contribution — run consistently in the mid-to-high single digits? If it can, the diversification thesis strengthens materially. That question will become more pressing as the story turns to the cocoa shock that hit the chocolate side of the business during the same period management was building this platform.
VI. The Cocoa Crisis: When the Core Business's Biggest Risk Became Undeniable
A market that broke
For more than a decade, cocoa behaved like a sleepy commodity. Between 2010 and 2023 it traded in a band of roughly $2,000 to $3,500 per metric ton.29 Then West Africa stacked one disaster on another: El Niño-driven drought, wildfires, the cacao swollen shoot virus, aging trees and years of underinvestment by smallholder farmers.29 Speculative money piled in on top of a genuine shortfall. By December 2024, cocoa had hit about $12,000 a ton, roughly six times its 2022 level.29
Imagine running a company where one ingredient, and the one your whole brand depends on, suddenly costs five or six times as much. That is what Hershey faced.
How hedging turned a spike into a two-year squeeze
Hershey's hedge book explains why the pain arrived late and lasted long. The company locks in cocoa prices up to two years ahead.14 When prices spike briefly, hedges protect margins until prices fall back. When prices stay high for more than two years, each new round of hedges is bought at the higher level. So the crisis showed up as a slow, grinding squeeze that peaked well after the futures market itself did, not as a single bad quarter.
The numbers show how deep it went. In fiscal 2025, Hershey's adjusted gross margin fell 610 basis points to 37.2%. The reported gross margin, which includes mark-to-market hedge swings, collapsed by 1,380 basis points to 33.5%.8 Reported EPS fell 60% to $4.34 and adjusted EPS fell 32.7% to $6.31.8 Sales still grew 4.4%, entirely because of pricing: prices added about 6 points while volume and mix subtracted 1.8
How management talked about it
Tracking management's language across the crisis is one of the best ways to judge its credibility.
In February 2025, under Michele Buck, Hershey guided 2025 adjusted EPS down by about a third, to $5.54–$5.86, and warned of 650 to 700 basis points of gross margin compression. Buck said the company continued "to view today's high cocoa prices as transient."30 CFO Steve Voskuil told analysts the company had "very good visibility into our cost basket."30 In hindsight, both statements look reasonable.
In July 2025 a new cost appeared. U.S. import tariffs were estimated at $170–$180 million for the year, and Hershey cut its outlook to a 36–38% decline in adjusted EPS.31 Tariffs were a policy shock, not an operating mistake, but they show how little room the company had left.
That same quarter showed how much noise the 2024 ERP switchover had left in the comparisons. Second-quarter 2025 sales jumped 26%, with volume up about 21 points. The increase reflected retailers rebuilding inventory after the prior year's ERP-related drawdown, plus Easter timing, not a sudden surge in demand.31 Buck tied the path forward to "strategic pricing, enhanced productivity, and technology enabled efficiency and speed."31 Investors trying to read Hershey's underlying demand through 2024 and 2025 had to look through these distortions, which is one reason the price and volume split matters so much now.
By October 2025, now under Tanner, the outlook improved to a 36–37% decline, and the tariff estimate eased to $160–$170 million.32 On that call Voskuil reminded analysts that cocoa was "still up over 70%" from 2023 levels. He also said the company was planning for an elasticity of about minus one, meaning volume falls roughly one percent for each percent of price increase.16
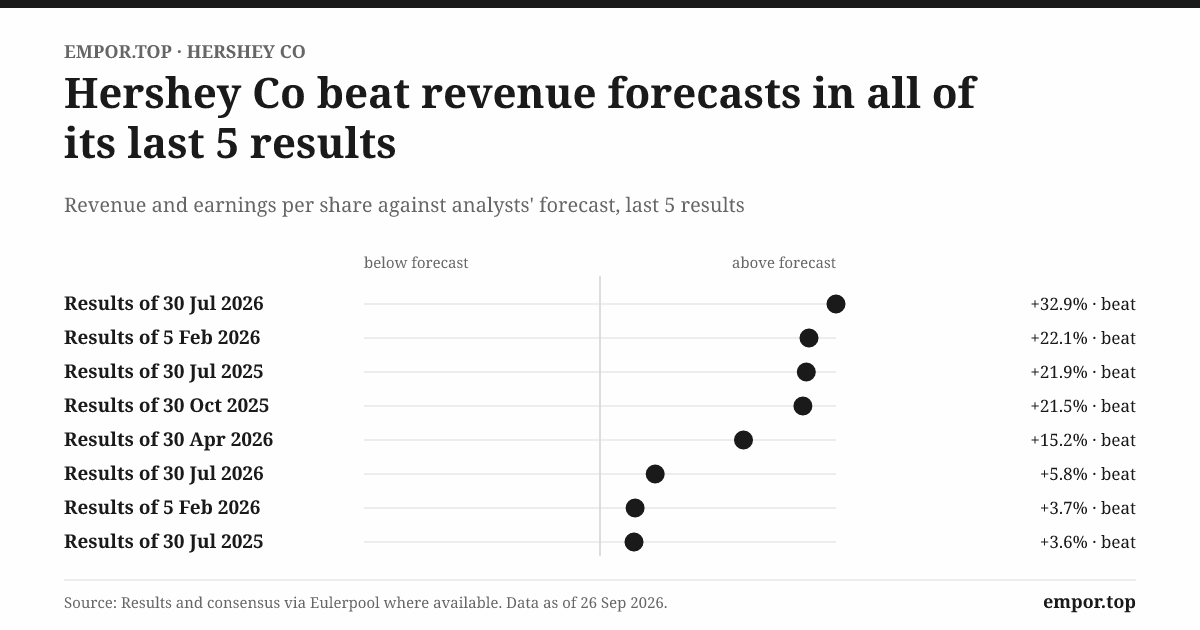
The final result, $6.31, came in well above the original February range.830 Management guided conservatively in a crisis and then beat its own numbers. That is the pattern of a team that understood its cost basket, even if one guidance cut along the way was driven by tariffs.
A word on reported versus adjusted earnings
Hershey's hedge accounting makes its reported earnings swing sharply, and investors need to know which number to watch. The company marks its open cocoa and other commodity derivatives to market each quarter through reported results, then strips those unrealized gains and losses out of adjusted earnings until the underlying cocoa is actually used. When cocoa prices fall, the losses on hedges placed at higher prices pull reported profit down. When prices rise, the reverse happens. In the second quarter of 2026, reported EPS jumped 629% to $2.26 while adjusted EPS rose 57% to $1.90.24 Neither figure is wrong, but the adjusted number is the better guide to the underlying business, and the gap between the two is a rough measure of how much hedge volatility is in the pipeline. This is an accounting judgment worth keeping in mind, not a red flag.
The most revealing exchange came when an analyst asked whether Hershey would give back some of its price increases once cocoa fell. Voskuil did not promise any rollback. He noted that cocoa was still well above where "the cocoa inflation journey" began, adding: "we haven't fully recovered from that."16 In plain English, Hershey intends to keep most of its pricing and use falling cocoa to rebuild margin. That is rational for the company. It also makes the 2027 volume trend a real test of whether consumers go along with it.
The volume question
Pricing saved the income statement, but it came at a cost to volume that is easy to miss in the headline numbers. In the second quarter of 2026, North America Confectionery organic sales grew 4.2%. Behind that were about 14 points of price and roughly 10 points of volume decline.24 In International, price added about 10 points and volume fell about 8.24 Part of that was timing. Retailers had let inventories run low around the April switch to new price packs and then restocked, and Easter shifted shipments between quarters.19 But a 10-point volume decline is not just noise. It means consumers are buying fewer bars at the new prices.
Management says elasticity is running "slightly better" than planned.19 That may be true against a cautious plan, and it is not the same as saying demand is unharmed. This tension between price and volume is why volume appears among the three key KPIs later in this article.
The AAA program: savings that arrived during the storm
On February 2, 2024, Hershey's board approved "Advancing Agility & Automation." The program was expected to cost $200 to $250 million through 2026 and to deliver about $300 million of ongoing annual savings by the end of 2026, including severance for workforce reductions.33 Hershey expected about $100 million of those savings to land in 2026.8 By the March 2026 Investor Day, the broader transformation program was described as targeting roughly $400 million of net savings over 2024–2026.34
Two points of skepticism apply. First, the timing. Hershey launched a major cost program after cocoa had already begun its climb, not before. That raises a fair question about whether the pre-crisis cost structure was as lean as the old margins made it look. Second, savings programs in packaged food are often partly reinvested, and Hershey is doing exactly that. It told investors that 2026 would bring a double-digit increase in advertising, including the first major campaigns for Hershey's and Reese's in eight years.28 That may be the right call for the brands. It also means investors should not expect AAA savings to drop straight into profit.
Where cocoa stands now
Cocoa fell 40–45% in 2025 as supply recovered.29 On the February 2026 call Tanner said Hershey expected supply surpluses and believed the "new equilibrium is likely to be above what we've seen in historic levels." He added that the company was "hedged above current market levels" for 2026, which would allow further relief in 2027 if prices stayed flat.28 By July 2026 management said it had "good visibility into cocoa deflation next year," even if futures stayed at current levels.19
But the market has not settled down. NOAA gave a 95% probability of a very strong El Niño in late 2026.4 Forecasts for the 2026/27 cocoa balance range from a 300,000–400,000 ton deficit (Guan Chong) to surpluses of about 82,000 to 111,000 tons (BMI, Hedgepoint).4 Cocoa traded around $5,600 a ton on September 25, 2026, down about 19% from a year earlier but still far above the old band. Analysts warned that output could fall about 20% in Côte d'Ivoire and 13% in Ghana.3
The honest conclusion is that the cocoa thesis has moved from "crisis" to "recovery with a fat tail." Hershey's 2026 guidance calls for gross margin to rise by "just below" 400 basis points, to around 41%.1928 That is a real recovery, but still short of where margins were before the crisis. Whether 2027 brings a further lift depends on hedges already placed and on the weather in Côte d'Ivoire this winter. The next question is what the company does with its cash while it waits.
VII. The Trust Constraint and Capital Allocation Record
Two sides of the same structure
Hershey's structure works like a castle wall: it keeps out raiders, but it also keeps the owners inside.
What the Trust enables. With 79% of the votes held by one holder, no hostile bid or proxy fight can succeed.2 Management can take a long view without worrying about activists over a bad quarter. And the story of "chocolate that funds a school" carries real goodwill with consumers and communities.
What the Trust constrains. First, large mergers are hard. Any deal that required issuing enough stock to dilute the Trust's voting control would need the Trust's blessing and, in practice, the attorney general's. In practice Hershey's M&A has been limited to what cash and debt can fund. Second, the board is not fully independent of its controlling holder. Trust representatives sit on it, and the Trust must agree to the choice of chair.2 Third, and most important for valuation, public shareholders have no realistic path to a takeover premium. The Mondelēz bid in 2016 showed what a strategic buyer might pay, and the board turned it down.12
The capital allocation scorecard
Dividends. This is the strongest part of the record. The dividend paid on September 15, 2026 was Hershey's 386th consecutive regular dividend on its common stock.35 The common dividend now stands at $1.452 a quarter.35 A company that kept paying through a 60% drop in reported earnings was clearly putting a high priority on the payout. The Trust relies on those dividends to fund the school, so the priority is unsurprising.
One detail in the dividend announcement shows how the structure works. The Class B shares, almost all held by the Trust, receive a lower dividend than the common stock: $1.320 against $1.452 a quarter.35 The Trust accepts less cash per share in return for ten times the votes. It is a small but telling price for control.
Buybacks. Hershey is not a timid repurchaser. It bought back $443.6 million of stock in the first half of 2026 and added a $500 million authorization in June.1425 Management says buybacks rank behind organic investment and M&A, and it has "nothing more planned" for the rest of 2026.19 Buybacks also slowly raise the Trust's percentage ownership, so they fit its interests too. The Trust itself occasionally sells small blocks of shares, most recently 20,000 shares in September 2026 at around $169, a trivial amount next to its Class B holding.36
M&A. This is the weakest part of the record, and it needs a longer lookback than the salty deals alone. In late 2013 Hershey agreed to buy 80% of the Chinese candy maker 金丝猴 Shanghai Golden Monkey, and it later bought the rest, for about $577 million in total.21 Within a year it booked a $249.8 million impairment. CEO J.P. Bilbrey admitted the distributor network was "not as stable as we believed," and 2015 sales expectations were cut from at least $200 million to about $90 million.37 Hershey sold the business in 2018.21 Krave jerky, bought for $220 million in 2015, was written down in early 2020 and sold that year, along with the Scharffen Berger and Dagoba artisan chocolate brands.38 Tyrrells was sold months after it arrived with Amplify.21
Put next to Dot's, which has clearly worked, and SkinnyPop, which has been mixed, the record shows a company that has sometimes paid too much, been too optimistic about distribution and brand momentum, and then acted honestly and fairly fast when deals failed. That is better than a company that hides its mistakes, but it does not support calling Hershey a disciplined acquirer. It argues for skepticism about LesserEvil's price until organic results prove otherwise.
The balance sheet. Total debt stood at about $5.6 billion at the end of June 2026, against $791 million of cash.14 That is manageable for a company whose management targets free cash flow above $1.8 billion by 2028.34 It does, however, limit the size of any future acquisition that has to be funded without issuing stock.
The unresolved tension
The 2002 episode never really went away. The Trust's charitable duty is to the school. The school would arguably be safer with a diversified endowment. Yet the Trust's political role in the town makes selling almost impossible. Every major capital decision at Hershey, from how much to pay out to whether to pursue a big merger, happens inside that tension. The person now running the company inside those limits is new to it.
VIII. Kirk Tanner and the Current Management Moment
From route salesman to the corner office
In 1992, a newly minted accounting graduate from the University of Utah took a job as a sales associate at Frito-Lay.39 His name was Kirk Tanner, and he stayed at PepsiCo for 32 years. He led Frito-Lay North America's West division as a senior vice president, ran sales for PepsiCo UK and Ireland, served as president of PepsiCo Global Foodservice, and finally became CEO of PepsiCo Beverages North America, a $28 billion business.40 He describes his leadership style as servant leadership: "The CEO is on the bottom. The frontline… how do we help them succeed?"39
In February 2024 he left PepsiCo for the first time to become CEO of Wendy's.39 About seventeen months later, on July 8, 2025, Hershey announced that he would succeed Michele Buck, effective August 18, 2025.40 Buck stayed on as a special adviser through June 2026, followed by a consulting arrangement.2
The Frito-Lay background is directly relevant to the salty snacks strategy. Frito-Lay is the benchmark for building and running a snack portfolio through store-level execution. The Wendy's stint was short. A short tenure is not proof of anything, but it means Tanner's record as a sole CEO is thin, and investors will be judging him mostly on what he does at Hershey.
ONE Hershey
At the March 31, 2026 Investor Day at the New York Stock Exchange, Tanner laid out a strategy to "Lead Next Generation Snacking."41 The core idea, branded "ONE Hershey," is to sell sweet, salty and functional snacks through a single commercial organization. That means one customer team per retailer and one supply chain, with three pillars: a next-generation portfolio, "retail of the future" and a modern supply chain.34 Management's financial framework calls for organic sales growth of 2–4% in 2026 and 2027, double-digit EPS growth during the margin recovery, and 6–8% EPS growth from 2028.34 Among the stated goals are more $1 billion brands, including Dot's, and a larger share of sales from faster-growing platforms.34 Tanner's summary: "The strategy is clear. The team is ready."41
Much of what Tanner inherited came from his predecessor. Michele Buck's "Leading Snacking Powerhouse" vision drove the Amplify, ONE Brands, Dot's and LesserEvil deals, and her team sold Krave and the artisan chocolate brands to focus the portfolio.4038 Tanner's early moves look more like an operator's refinement of that strategy than a break from it. He has combined the commercial teams, stepped up advertising, focused on convenience-store execution and on "tentpole" marketing events between the big holidays, and made visible bets on innovation such as Reese's Oreo, which he called the top driver of innovation growth in the category.16
His own definition of success for 2026, given in October 2025, was measured: grow with or ahead of the category and rebuild margin "over a few years," while continuing to invest in the brands.16 It was a deliberately modest bar. The company then guided to a 30–35% jump in adjusted EPS, which shows how much of 2026 was always going to be mechanical recovery rather than management skill.
Testing the credibility
The fair way to judge Tanner is to separate what the company promised from what it delivered.
The inherited guidance record is good. As section VI showed, 2025 results came in above the original February 2025 range despite a tariff shock.308
Tanner's own first guidance cycle is on track so far. In February 2026 he guided 2026 adjusted EPS to $8.20–$8.52, up 30–35%.8 After a strong first half, with organic growth of 5.8% and adjusted EPS up 28.4%, the company narrowed the range upward to $8.36–$8.52 in July.24 Even at the top of that range, 2026 EPS would still be about 9% below 2024's adjusted $9.37.30 Recovery is under way, but it is not complete.
The tone on calls is consistent but carefully guarded. Asked in July 2026 whether the 2027 framework still held, Tanner said "nothing we see today, commodities or otherwise, would cause us to move away from that framework."19 On the Dot's supply problems he acknowledged "growing pains" and pointed to capacity arriving in 2027, which is a specific plan.19 He has been less forthcoming on price gaps with competitors, preferring to say that share changes were "largely driven by innovation."19 Analysts' repeated questions about price gaps with the biggest competitor suggest the gaps deserve closer attention than management gives them.
The activist's case that cannot be run
With 79% of the votes in one set of hands, an activist campaign at Hershey could never win a vote. But it is worth writing down what an activist would say. The most valuable thing for public shareholders would be for the Trust to diversify, either through a sale or a gradual reduction in its voting control. That is exactly what Pennsylvania politics has blocked. An activist would also question the M&A record, the near-zero profitability of International, and whether a board whose chair must be acceptable to the Trust can really hold management to account on returns. None of these questions can be forced to a vote. Some investors treat that as the price of stability. Others treat it as a reason to stay away. The International business is a smaller, clearer example of the same tension between ambition and returns.
IX. The International Segment: Small, Improving, Not Yet Material
Hershey's international business is the part of the company most people forget, and for good reason. In fiscal 2025 it generated $941.6 million of sales, down 0.7%, and just $3.3 million of segment income, a margin of 0.4%.8 In the third quarter of 2025 it lost $13.6 million.32 Voskuil explained why: overseas, Hershey's products are often premium-priced and cocoa-heavy, and it is a smaller player in most markets. As a result it felt the cocoa shock harder, and "the elasticity impacts are also more severe."16
There are real bright spots. Management singled out Brazil, the United Kingdom and India as the strongest markets in the first half of 2026, with Mexico held back by a weak economy.19 Segment sales grew 5.7% in the second quarter of 2026, but the margin was negative 2.3%, and management warned that further restructuring would weigh on margins in the second half.2419 China, where the Golden Monkey deal failed, is a reminder of how hard it is to buy distribution in markets Hershey does not understand.
International is not part of the investment case today. At about 8% of sales and roughly break-even, its main contribution is as an option. If India or Brazil can grow into businesses the size of Mexico within a few years at a double-digit margin, International would start to matter. Until then it is a place to watch for restructuring charges, not growth. The bigger risks sit elsewhere.
X. Risk Radar: The Four Mechanisms That Could Break the Thesis
1. Cocoa settles higher, for longer
The most important risk is not another price spike. It is a cocoa market that never returns to the old band. West African production faces structural headwinds: aging trees, swollen shoot disease, and farm economics that discourage replanting.29 Management itself expects a "new equilibrium" above historic levels.28 If cocoa stabilizes at $5,000–$6,000 a ton rather than the pre-crisis range below $3,500, Hershey cannot rebuild its former margins without keeping consumer prices high. Higher prices suppress volume. Lower volume raises unit costs and gives private label and substitutes room to gain ground. The roughly 10-point volume decline in North America Confectionery during the second quarter of 2026 illustrates how that loop could tighten.24
2. GLP-1 and the shrinking sweet tooth
As the industry structure section noted, the Cornell study published in December 2025 found that households adopting GLP-1 medications cut spending on sweets by roughly 10%.15 The same study found that about a third of users discontinued the drugs during the observation period, after which food spending reverted to prior levels.15 That moderates the near-term threat. The real risk is gradual: a slow, compounding drag on category volume rather than an abrupt collapse. ONE Brands bars are Hershey's only direct hedge against the wellness shift, and their commercial scale remains undisclosed. Separately, several U.S. states have begun restricting candy purchases under SNAP. Management reported that the impact has run in line with internal plans and, in large states such as Texas and Florida, below the levels seen in earlier-adopting states.19 That is a policy headwind to monitor, not a thesis-breaker.
3. Execution risk inside ONE Hershey
Tanner is combining three sales organizations, integrating LesserEvil, expanding Dot's manufacturing capacity, increasing advertising spending, and completing the AAA cost program — all within his first eighteen months in the role. The company has relevant history on complex operational change. In 1999, Hershey rushed a $112 million SAP, Siebel, and Manugistics rollout live just before Halloween and was unable to fill roughly $100 million of orders; the stock fell more than 8% when CEO Kenneth Wolfe disclosed the shortfall.42 The April 2024 ERP upgrade was managed more deliberately: retailers pre-built inventory in the first quarter, and North America Confectionery sales then fell 20.7% in the second quarter as that inventory was worked down — a result the company had planned for and communicated to analysts.43 The lesson is that Hershey can manage complex change when it builds adequate lead time, and the Dot's supply constraints of mid-2026 suggest parts of the current program are still catching up.
4. The Trust itself
The least likely risk is also the most binary. The Trust's legal duty runs to the Milton Hershey School. A future attorney general, court, or reconstituted board could conclude that duty requires diversification — and a sale could follow. Or, at lower intensity, the Trust could continue making decisions shaped more by local politics than by portfolio logic, as the record from 2002 onward suggests it sometimes has. Neither scenario can be modeled with precision, but any holder of HSY carries exposure to both.
Also on the radar
Two further concentrations deserve notice. Approximately 27% of 2024 net sales flowed through a single distributor, McLane Company; a meaningful change in terms with McLane or the retailers it serves would register quickly in Hershey's results.9 Trade policy is the other. Tariffs cost Hershey an estimated $160–$170 million in 2025, and management modeled roughly $200 million of incremental tariff exposure for 2026, while hoping that cocoa — which cannot be grown commercially in the United States — might eventually be exempted as trade agreements were negotiated.3216 Neither concentration is likely to break the investment thesis on its own, but each narrows the margin for error in a recovery plan whose assumptions depend on cheaper inputs, stable distribution, and steady policy.
XI. The Investment Case: Bull vs. Bear
Hershey is unusual because it is two things at once: a high-quality branded consumer company and a governance-constrained vehicle that cannot be sold and finds it hard to restructure. The bull and bear cases disagree not only about earnings but about which of those two identities matters more.
The bull case
Cocoa is a cycle, not a new regime. Prices have already fallen by more than half from the December 2024 peak.293 Hershey says it has good visibility into lower cocoa costs for 2027.19 If AAA savings and cheaper cocoa come together, gross margin could return toward pre-crisis levels in 2027 and 2028, and management's plan for double-digit EPS growth during the recovery would look reasonable.34
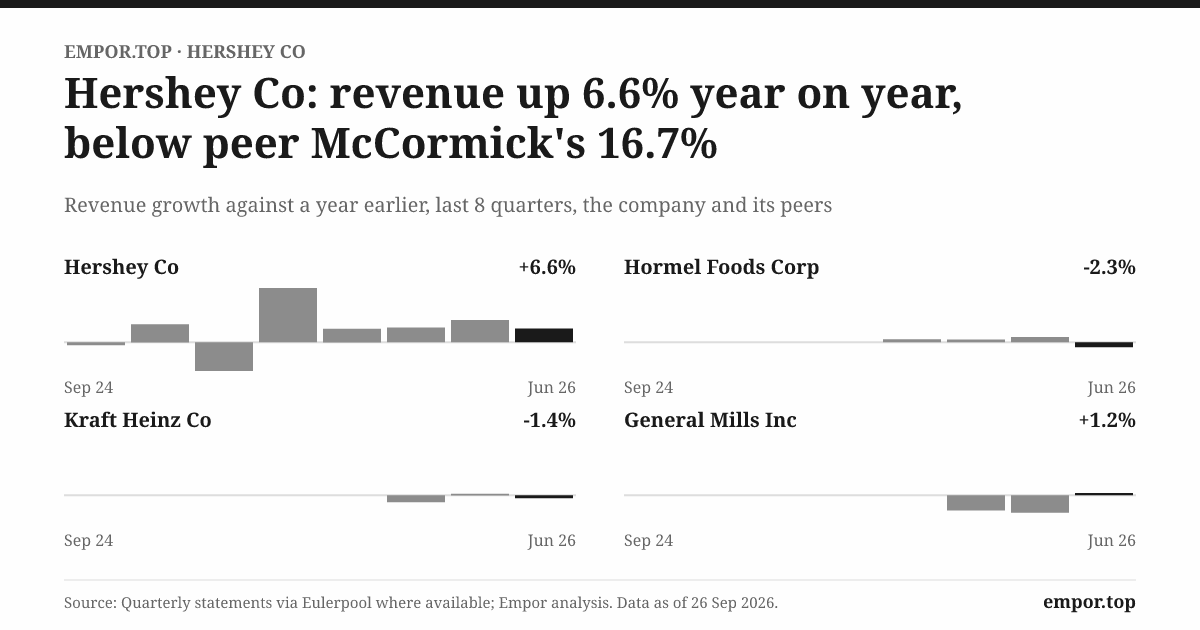
The brands held. Hershey raised prices by double digits and still grew sales 4.4% in 2025 and 8.7% in the first half of 2026.824 Most units still sit below $4 at the shelf.16 These are habit purchases that have survived every previous health trend.
The Trust provides a floor. No distressed sale, no hostile raid and no forced breakup. Kellanova, by contrast, ended up being sold to Mars.17 Hershey cannot be forced down that road.
Salty snacks lower the cocoa exposure. Dot's leads its category. Salty reached about 11% of sales in 2025 and grows faster than chocolate over time.816 Tanner's Frito-Lay background is a good fit for running it.
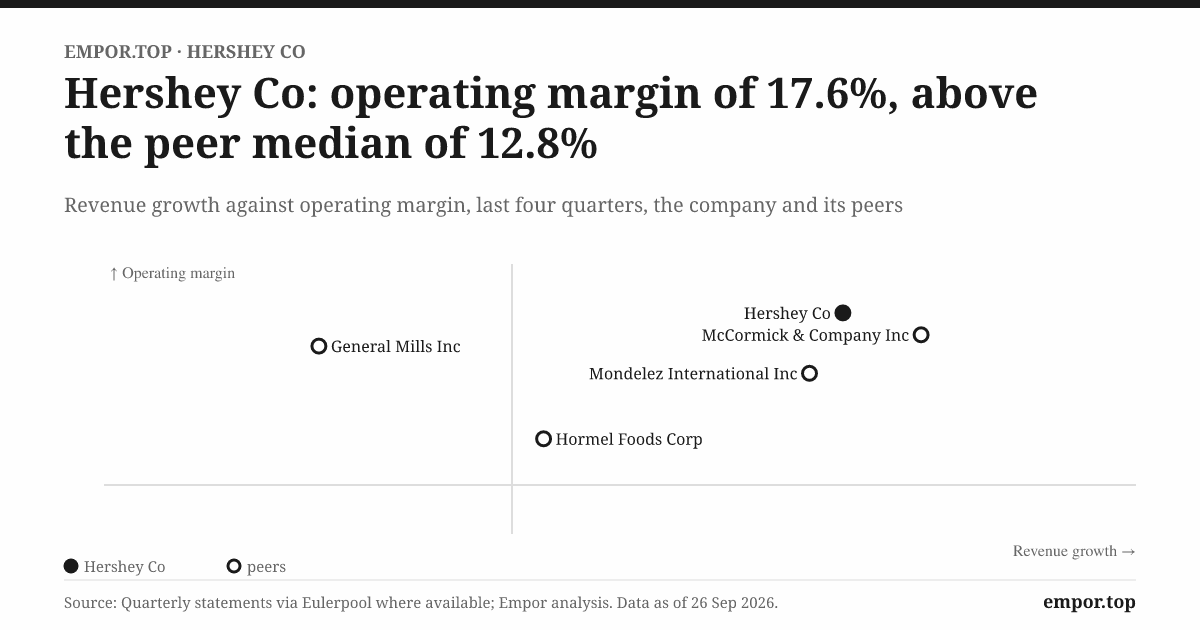
Cash generation stays strong. Management expects free cash flow above $1.8 billion by 2028, enough to fund the dividend, bolt-on acquisitions and some buybacks without new stock.34 Even in the 2025 trough, the core segment kept a margin most packaged-food companies would envy.8
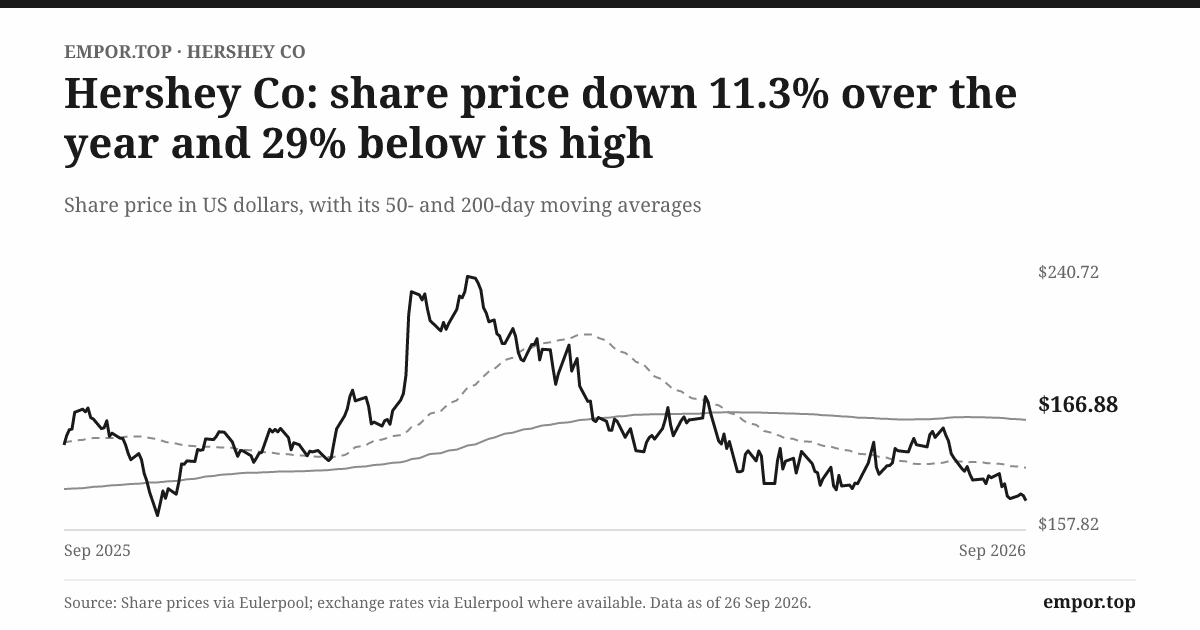
The valuation already reflects the damage. At around $166–$171 in September 2026, the stock traded at about 25 times earnings, and its five-year performance was roughly flat.36 Bulls would argue the price reflects trough earnings more than lasting damage.
The bear case
The M&A record is poor. Golden Monkey, Krave and Tyrrells were all written down or sold, and SkinnyPop underdelivered.373821 If LesserEvil follows SkinnyPop's path, the salty strategy will have consumed capital without creating much value.
Cocoa may never return to the old range. Management itself expects a higher equilibrium.28 The 2026/27 crop is exposed to a strong El Niño.4 Each round of price increases pushes more consumers toward private label and cheaper substitutes.
Volume is falling. A 10-point volume decline in the core segment is not a rounding error, whatever the timing noise.24
Shareholders are minority partners. With 79% of the votes held by the Trust, public investors cannot earn a takeover premium, force a sale or elect a board that puts them first.2
Mars is now larger in snacks. Mars paid about $36 billion for Kellanova, adding Pringles, Cheez-It, Pop-Tarts and RXBAR to M&M's, Snickers and Twix.17 That is a private, patient competitor in both of Hershey's categories.
Tanner is still unproven. His strategy makes sense, but it is complex and being carried out while the core business is still recovering.
Weighing the frameworks
Porter's analysis shows attractive economics in chocolate held back by a single hostile supplier market. Salty is structurally less attractive, with more competitors and lower margins. Helmer's framework finds three real powers: brand, scale and the Kit Kat license. Only brand is clearly stronger than Mars's equivalent. Against its closest peer, Hershey has similar strengths and one extra weakness. Mars is private, so it can accept lower margins for longer without worrying about the share price. Hershey, answerable to both public shareholders and a school, has less room to wait out a price war.
The sum of the evidence supports a narrower claim than either side prefers. Hershey's moat in chocolate is intact but more price-sensitive than it looked before 2024. Salty is a real business that has not yet proven itself as an engine. And the governance structure puts a floor under the downside and a ceiling on the upside.
What would change the verdict
Two things would move the balance meaningfully toward the bull case. The first is a clean 2027: cocoa costs falling as management expects, gross margin moving back into the 40s, and North America Confectionery volume turning positive as price increases lap. The second is proof that salty growth can come from Hershey's own brands. That means Dot's supply fixed, SkinnyPop growing again and LesserEvil growing faster inside Hershey than it did on its own.
Two things would move it toward the bear case. The first is a failed El Niño crop that pushes cocoa back toward $8,000 or more and forces another round of price increases on consumers who are already buying fewer bars. The second is another acquisition write-down, which would suggest the salty strategy is repeating the pattern of Golden Monkey and Krave rather than Dot's.
Myth vs. reality
Myth: Hershey owns roughly half of American chocolate. Reality: the best available third-party estimate put Hershey's U.S. chocolate share at about 35.5% in 2022, with Mars slightly ahead across confectionery as a whole.13 That makes Hershey a leader in a duopoly, not a monopolist, and it faces a rival that can match it on scale.
Myth: Pricing power made Hershey immune to cocoa. Reality: pricing protected revenue, not profit. Adjusted EPS fell by about a third in 2025 even as sales grew, and by mid-2026 volume in the core segment was falling about 10 points against roughly 14 points of price.824 The brands bent without breaking. That is a smaller claim than immunity.
Myth: The Trust is a patient owner that never wanted to sell. Reality: in 2002 the Trust itself ran an auction and received a bid at a 42% premium. The state attorney general and local opposition stopped the sale, not the Trust's own judgment.10 Hershey stays independent because of politics as much as the owner's preference.
Myth: Hershey is a disciplined serial acquirer. Reality: Dot's has worked, but Golden Monkey took a $249.8 million impairment within about a year, and Krave was written down and sold within five years.3738 The record is mixed, and it justifies waiting for organic proof on LesserEvil.
Myth: GLP-1 drugs will empty the candy aisle. Reality: GLP-1 households did cut spending on sweets by roughly 10%, but about a third of users stopped the medication and their spending went back to normal.15 It is a slow headwind on volume, not a sudden collapse, and it is best tracked through the volume KPI below.
The three KPIs that matter most
-
Adjusted gross margin, quarterly. This is the single best read on whether cheaper cocoa and AAA savings are showing up in profit. Reference points are the 37.2% trough in 2025, management's implied 2026 level of around 41%, and pre-crisis levels in the low-to-mid 40s.828 A sustained move back into the 40s would confirm the recovery case. A plateau near 40 would suggest pricing has been permanently reset lower relative to costs.
-
North America Confectionery volume, quarterly. Watch the split between price and volume. As pricing fades in 2027, volume needs to stop falling and start recovering. If volume keeps declining even as price increases slow, it would point to real demand damage rather than a temporary reaction to higher prices.
-
North America Salty Snacks organic growth, annually. Excluding LesserEvil, this shows whether the platform can grow by itself. Consistent mid-to-high single-digit organic growth would support the platform thesis. Growth stuck in the low single digits would mean acquisitions are the only real growth lever.
XII. Playbook: What Hershey Teaches
Anatomy of a confectionery moat. Scale, brand, seasonal execution and shelf control add up to pricing power that has survived health trends, private label and ordinary commodity cycles. The 2023–2025 cocoa spike showed its limit. When the main input rose sixfold, pricing power protected revenue but not volume or margins.
The best deal in Hershey's history cost almost nothing. The 1970 Kit Kat license required little capital up front. It created one of the company's biggest brands, and because of the change-of-control clause it also works as a takeover defense.18 It is a model that cannot be copied, because it depended on a moment in history when a British confectioner needed an American partner.
Giving it away is a governance decision. Milton Hershey's gift solved a childless founder's problem of succession, and it also permanently put public shareholders second to a charity. The lesson is not "give it all away." It is "understand the governance structure you are creating when you give." Founders who put control into foundations, from Hershey to Novo Nordisk, create institutions with their own politics.
Hedging is not the same as security of supply. Hershey has chosen financial hedging over owning its supply chain. That works when prices move normally and fails when a shock lasts longer than the hedge book. Food companies with a single critical commodity may need both hedges and supply diversification. Management's comments in 2025 about pursuing alternative cocoa sourcing suggest it has learned this.16
Conservative guidance builds credibility. Hershey entered 2025 guiding to a one-third drop in adjusted EPS, then beat that range despite an unexpected tariff bill.308 Guiding low in a crisis cost the stock some goodwill in February 2025, but it gave management credibility it could use later. By July 2026, analysts were probing how much cushion was built into the 2027 framework rather than questioning whether it was realistic, and Tanner could point to a first half that ran ahead of plan.1924
Integration debt is real. Buying a "better-for-you" brand and running it through a traditional packaged-food machine can dull what made the brand special. SkinnyPop is the cautionary tale, and Dot's is the counterexample. Whether LesserEvil's organic, founder-led identity survives being folded into ONE Hershey is the next test.
XIII. Epilogue: Milton's Bargain
Go back to that November day in 1918. A man who had failed three times, then made a million dollars on caramels, then bet it all on chocolate for ordinary people, gave the whole enterprise to a school for orphans because he had no children of his own. In doing so he created the most unusual governance structure in American business.
Today the Milton Hershey School serves around 2,100 children from low-income families, many of whom would otherwise have few good options.7 Its endowment, built largely on Hershey dividends and Hershey stock, is among the largest of any school in the country.7 The price of that mission is a public company whose shareholders will likely never receive a control premium, and whose board answers partly to a charitable purpose.
What remains open is whether Kirk Tanner can prove that ONE Hershey, with sweet, salty and functional snacks run with Frito-Lay-style discipline, creates the second growth engine that Hershey's leaders have pursued for most of the past decade without fully delivering. He has to do it while cocoa settles, while Mars grows larger, and inside a structure that makes bold moves hard.
There is a certain symmetry to it. Milton Hershey's own career was a lesson in concentration: three failures, one caramel fortune, and then everything on chocolate. The company he left behind is still concentrated in the same way, in one product, one country, one commodity and one controlling owner. That concentration built the moat. It is also why a single bad cocoa crop in West Africa could cut the company's reported profit by more than half in a single year.
The final investment question is not about chocolate. Owning HSY means owning a minority stake in a trust-controlled institution. It comes with iconic brands, durable but not unlimited pricing power, a trough earnings moment and a second business that is real but not yet proven. Investors are paying for that whole package, not just for the chocolate.
XIV. Recent Developments
Tanner's first full cycle. Hershey entered 2026 guiding for net sales growth of 4–5%, with roughly 1.5 points of that coming from LesserEvil, and adjusted EPS of $8.20–$8.52.8 The first quarter came in ahead of plan: adjusted EPS rose 12.4% on 7.9% organic growth, and adjusted gross margin reached 40.4%, the clearest sign yet that cheaper cocoa was beginning to show up in profit.27 The second quarter added more evidence. Adjusted EPS rose 57% to $1.90, and management narrowed full-year guidance to $8.36–$8.52 in adjusted EPS on 3–3.5% organic growth.24 Management expects the third quarter to produce the fastest year-over-year earnings growth of the year, as it laps the peak cocoa and tariff costs of late 2025.19 Even at the top of the updated range, however, 2026 EPS would remain roughly 9% below 2024's adjusted $9.37 — recovery under way, not yet complete.
LesserEvil integration. LesserEvil contributed about 20 percentage points to salty segment growth in the first quarter and roughly 22 in the second.2724 Tanner described the brand as "performing very well," though Hershey has not disclosed separate revenue figures.19 Until it does, the claim cannot be tested against the roughly $250–$300 million annual run rate implied by those contribution figures and the size of the segment base.
Cocoa. Futures traded around $5,600 a ton in late September 2026 — down about 19% from a year earlier but still well above the pre-crisis range. Warehouse stocks sat at a two-year high, providing some buffer, while a strengthening El Niño threatened the 2026/27 West African crop.34 Hershey's open commodity derivatives carried a notional value of $504 million at the end of June 2026, down from $973 million at year-end — a sign that the hedge book is rolling toward lower-cost contracts, though the exposure to a renewed supply shock has not disappeared.14
Mars–Kellanova. Mars completed its roughly $36 billion acquisition of Kellanova on December 11, 2025.17 No direct overlap with Hershey's popcorn and pretzel brands has been reported yet, but the combined entity now competes for the same snack-aisle shelf space and retailer attention across both of Hershey's segments — a competitive shift whose full effect on promotional terms and distribution priority will take time to surface.
The Trust. The 2026 proxy confirmed the Trust's voting power at 79.0% and formalized the new rule requiring Trust agreement on the choice of board chair.2 The Trust made small sales of common shares in 2026, most recently 20,000 shares in September at around $169, but those transactions left its control position unchanged.36
Capital returns. The quarterly common dividend stands at $1.452, and the September 2026 payment extended the unbroken run of regular dividends to 386 consecutive quarters.35 Hershey repurchased $443.6 million of stock in the first half of 2026 and added a $500 million authorization in June, with management saying it had nothing further planned for the rest of the year.1425 Together, the dividend and buyback pace signals confidence in cash generation during the recovery — though both are constrained, as section VII noted, by the debt load and the Trust's structural preference for the dividend above all else.
XV. Links & Resources
Readers who want to go deeper will find the primary documents in Hershey's SEC filings: the 2026 proxy statement on Trust voting control, the fiscal 2024 annual report, and the mid-2026 quarterly report covering hedging positions and acquisition accounting.2914 Quarterly earnings releases and call transcripts from 2025 and 2026 trace management's language on cocoa costs, pricing strategy, and the salty snacks build in real time.2819 On the Trust's history and finances, the 2021 ProPublica investigation — conducted jointly with the Philadelphia Inquirer and Spotlight PA — and the Milton Hershey School's own account of the 1918 gift provide the most detailed public record of how the endowment has been managed and what it spends.71
References
-
The Gift and Vision That Amazed the World — Milton Hershey School ↩↩↩↩↩
-
The Hershey Company 2026 Proxy Statement (Form DEF 14A) — SEC EDGAR, 2026-03-25 ↩↩↩↩↩↩↩↩↩↩
-
Cocoa — Price, Chart, Historical Data — Trading Economics, 2026-09-25 ↩↩↩↩
-
Sharp Futures Losses and Divergent 2026/27 Balance Forecasts — CocoaIntel, 2026-09-02 ↩↩↩↩↩
-
Milton S. Hershey: A Favorite Son of Lancaster — LancasterHistory ↩↩↩↩↩↩↩
-
HersheyArchives@30, Part 4: Selling the Lancaster Caramel Company — Hershey Community Archives ↩↩↩
-
America's Richest School Serves Low-Income Kids. But Much of Its Hershey-Funded Fortune Isn't Being Spent. — ProPublica / The Philadelphia Inquirer / Spotlight PA, 2021-05-28 ↩↩↩↩↩↩↩↩
-
Hershey Reports Fourth-Quarter and Full-Year 2025 Financial Results; Provides 2026 Outlook (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-02-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
The Hershey Company Annual Report on Form 10-K for Fiscal 2024 — SEC EDGAR, 2025-02-18 ↩↩↩↩↩↩↩
-
Hershey Says No, Bankers Cry Foul — Forbes, 2002-09-18 ↩↩↩↩↩
-
Hershey's Trust Has History of Vetoing Deals — Fox Business, 2016-06-30 ↩↩↩
-
Hershey Rejects $23 Billion Mondelez Takeover Offer — NBC News, 2016-07-01 ↩↩
-
The Hershey Company Quarterly Report on Form 10-Q for the Quarter Ended June 28, 2026 — SEC EDGAR, 2026 ↩↩↩↩↩↩↩↩
-
Ozempic is changing the foods Americans buy — Cornell Chronicle, 2025-12 ↩↩↩↩↩↩
-
Earnings call transcript: Hershey Q3 2025 beats expectations, stock dips — Investing.com, 2025-10-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Mars completes $36B Kellanova acquisition — Virginia Business, 2025-12-11 ↩↩↩↩
-
Hershey (HSY) Q2 2026 Earnings Call Transcript — The Motley Fool via The Globe and Mail, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Hershey to acquire Amplify Snack Brands for $1.6 billion — Food Business News, 2017-12-18 ↩↩
-
Hershey posts Q2 sales growth after selling Tyrrells and Golden Monkey — ConfectioneryNews, 2018-07-27 ↩↩↩↩↩
-
Hershey buys One Brands for $397M, expanding bar options — Food Dive, 2019-08-28 ↩
-
Hershey buys Dot's Homestyle Pretzels and its co-manufacturer for $1.2B — Food Dive, 2021-11-10 ↩↩
-
Hershey Reports Second-Quarter 2026 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Hershey beats Q2 2026 estimates as shares slip premarket — Investing.com, 2026-07-30 ↩↩↩
-
Hershey to buy healthier snacks maker LesserEvil — Food Dive, 2025-04-03 ↩
-
Hershey Reports First-Quarter 2026 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-04-30 ↩↩↩↩
-
Hershey (HSY) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-05 ↩↩↩↩↩↩↩↩
-
Bitter before sweet: The extraordinary journey of cocoa prices — Nairametrics, 2026-03-01 ↩↩↩↩↩↩
-
Cocoa prices impacting Hershey's 2025 forecast — Food Business News, 2025-02-07 ↩↩↩↩↩↩
-
Hershey Reports Second-Quarter 2025 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2025-07-30 ↩↩↩
-
Hershey Reports Third-Quarter 2025 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2025-10-30 ↩↩↩
-
The Hershey Company Form 8-K: Advancing Agility & Automation Initiative — SEC EDGAR, 2024-02-02 ↩
-
The Hershey Company (HSY) Investor Day 2026 Summary — Quartr, 2026 ↩↩↩↩↩↩↩
-
Hershey Declares Quarterly Dividends — PR Newswire, 2026-07-29 ↩↩↩↩
-
Hershey Trust Sells 20,000 Shares for $3.4 Million — The Motley Fool, 2026-09-23 ↩↩↩
-
Hershey troubled in China — Food Business News, 2015-08-10 ↩↩↩
-
Hershey to divest Krave and artisan chocolate brands — Food Dive, 2020-04-27 ↩↩↩↩
-
Signature: An exclusive interview with Wendy's CEO Kirk Tanner — Nation's Restaurant News, 2024 ↩↩↩
-
Kirk Tanner Appointed President and Chief Executive Officer of The Hershey Company (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2025-07-08 ↩↩↩
-
Hershey Investor Day press release: Lead Next Generation Snacking (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-03-31 ↩↩
-
Supply Chain: Hershey's Bittersweet Lesson — CIO, 2002-11-15 ↩
-
Hershey Reports Second-Quarter 2024 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2024-08-01 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube