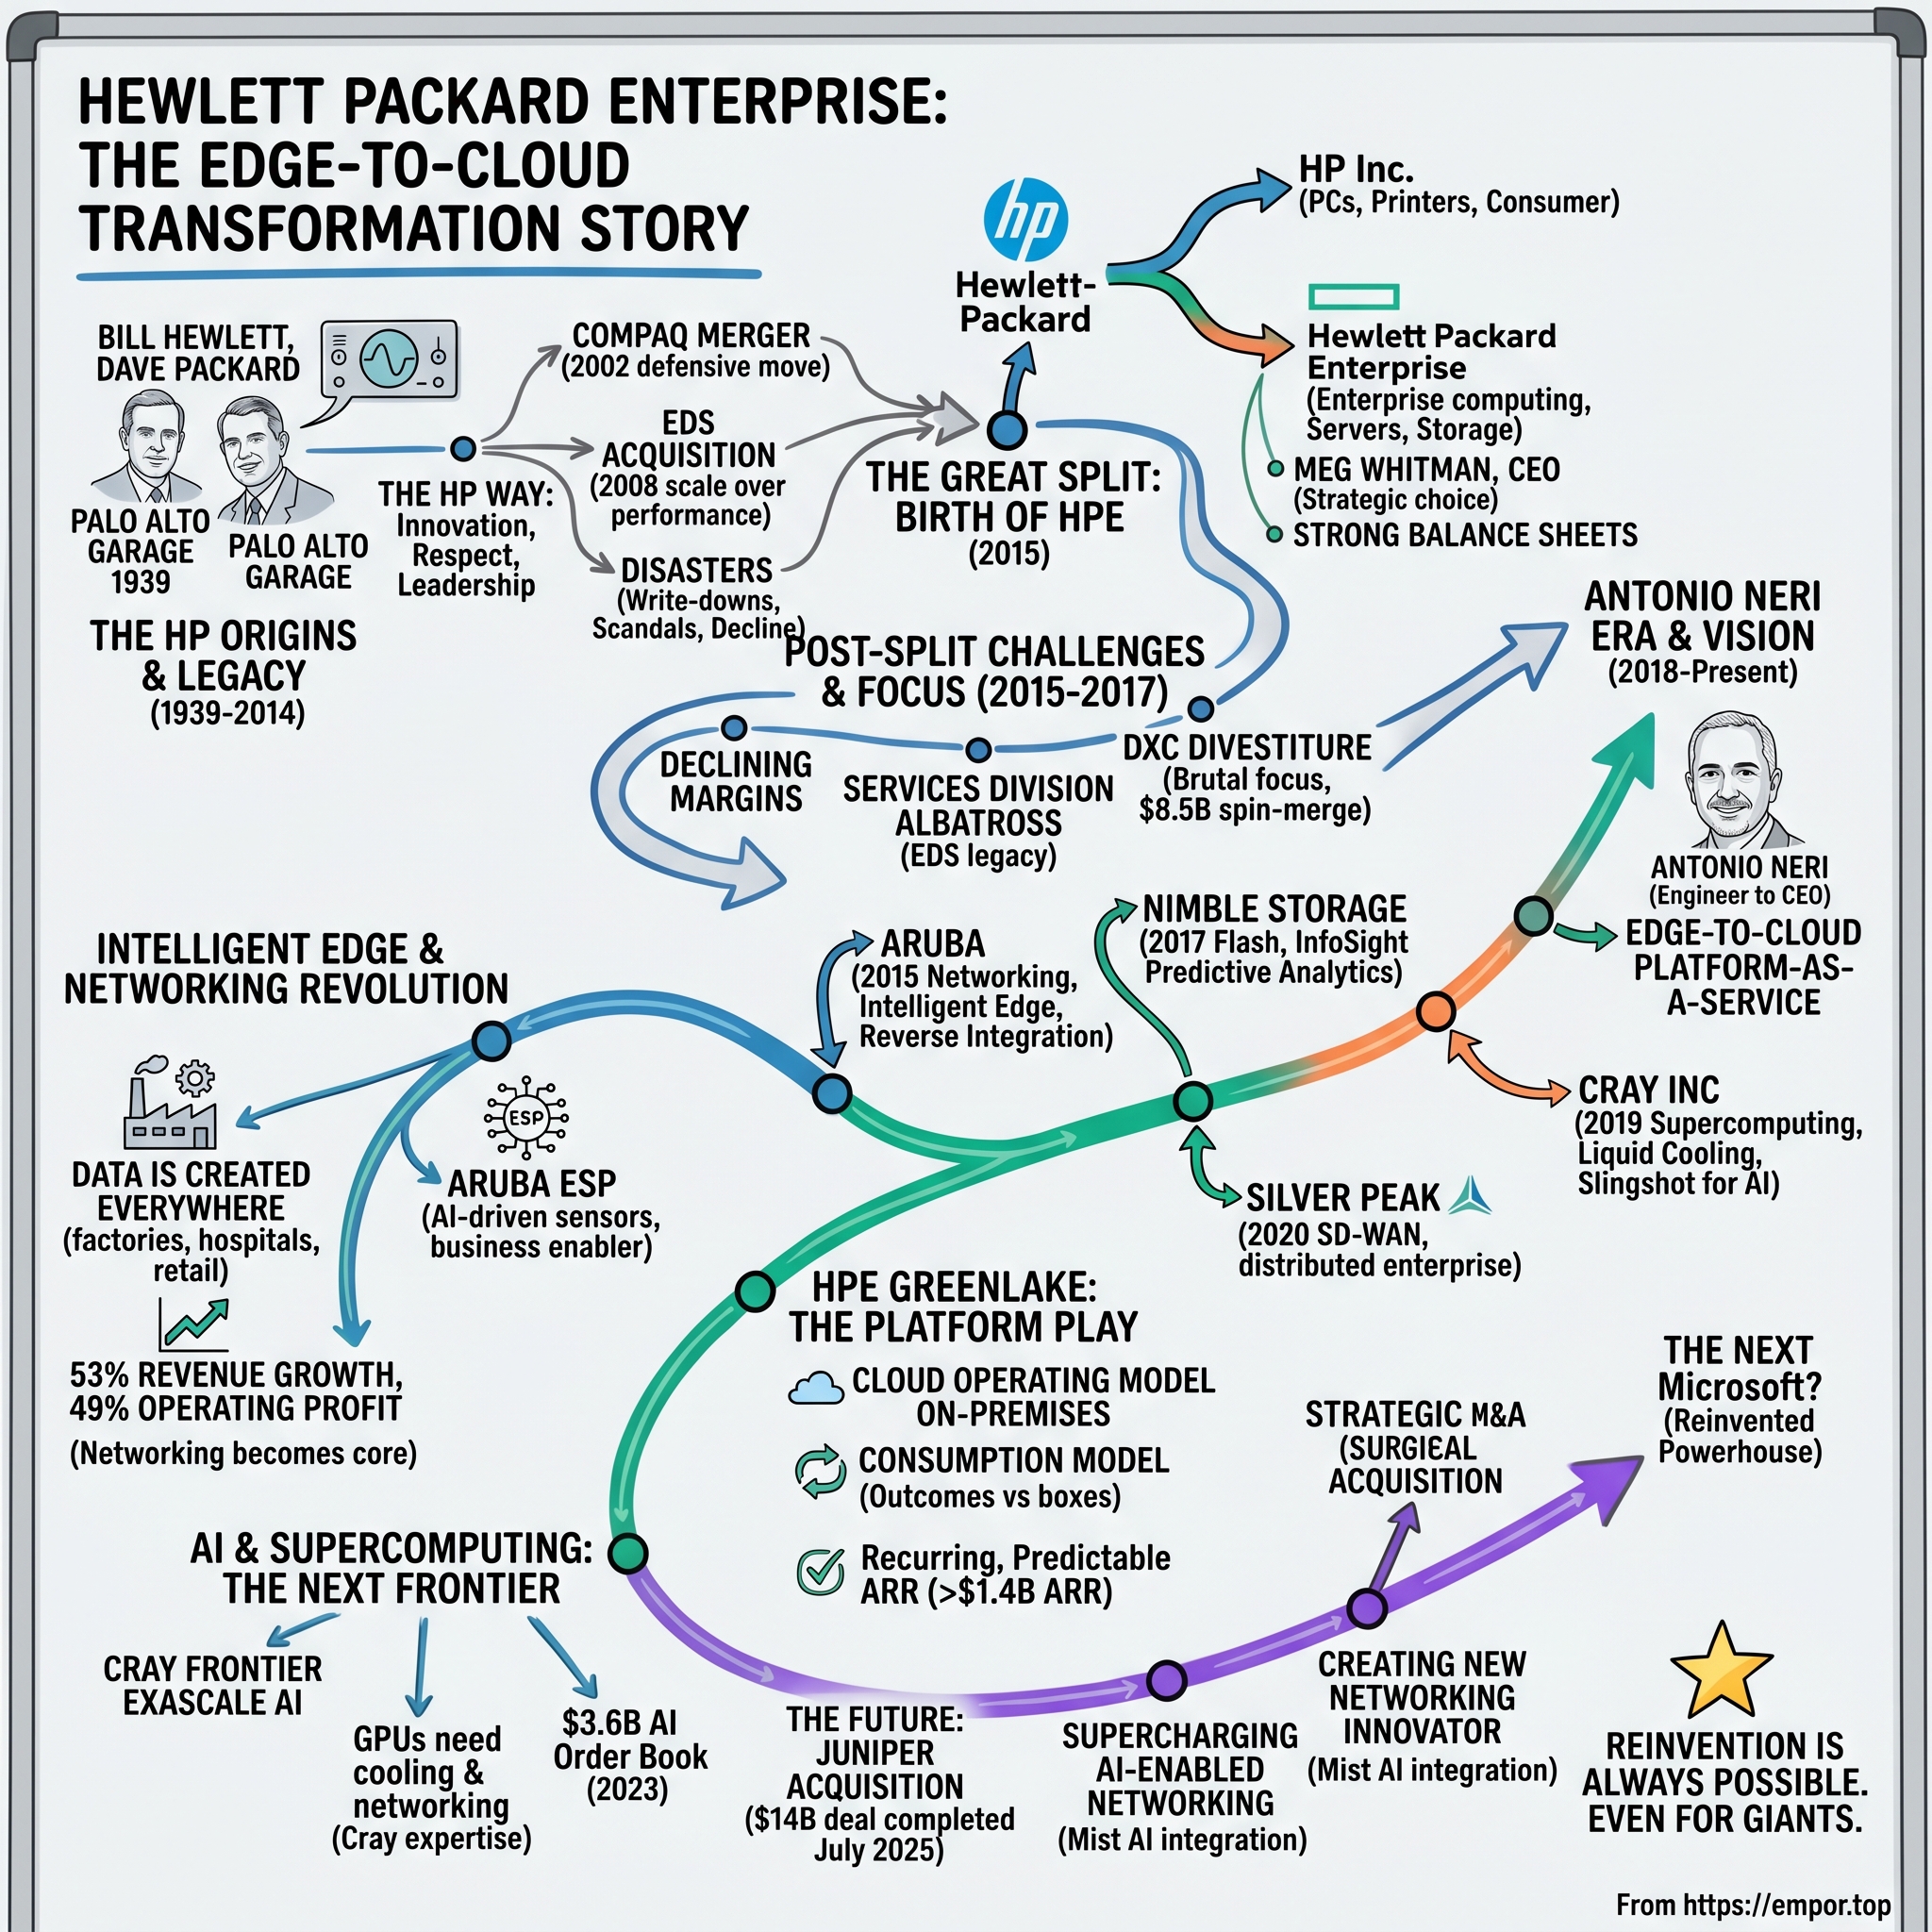
Hewlett Packard Enterprise: The Edge-to-Cloud Transformation Story
I. Introduction & Episode Roadmap
On the evening of September 2, 2026, Hewlett Packard Enterprise reported the strongest quarterly results in its eleven-year history. Revenue surged 34% year over year to $12.2 billion, non-GAAP gross margin reached a record 40.4%, and non-GAAP diluted earnings per share topped one dollar for the first time.1 Management raised its full-year outlook for the third time in six months and outlined a fiscal 2027 framework targeting at least $5 billion in free cash flow.1 Yet in after-hours trading, the stock fell.2
That market reaction captures the central tension surrounding the company. Investors have seen HPE deliver record headline numbers before, and the performance prompts a fundamental question: what kind of company generated this quarter? Is it an emerging platform business whose software-like pricing power is finally showing up in operating results, or is it a legacy enterprise hardware vendor riding a cyclical memory-chip shortage that temporarily allowed server manufacturers to reprice their order backlogs?
The underlying structural challenge is straightforward. Headquartered in Spring, Texas, Hewlett Packard Enterprise represents the enterprise half of one of Silicon Valley's foundational companies. Its largest revenue engine still sells what hardware engineers refer to as "sheet metal"—standard x86 servers and storage arrays installed in enterprise data centers. It operates in a landscape where hyperscale cloud providers, the world's largest computing buyers, primarily design their own infrastructure and procure it directly from contract manufacturers in Taiwan. Under conventional industry assumptions, a legacy hardware vendor in that position faces gradual commoditization.
Under Chief Executive Officer Antonio Neri, HPE has pursued a three-part strategy to counter that trajectory: first, sell traditional infrastructure as a service through its GreenLake platform, shifting customers to monthly recurring consumption models; second, expand aggressively into networking, the segment within its portfolio that commands structurally higher, software-like margins; and third, commit significant balance-sheet capital to that shift by acquiring Juniper Networks for roughly $14 billion in cash, a transaction announced in January 2024 and completed in July 2025 following extended antitrust scrutiny.34
The baseline financial picture reflects that transition. In fiscal 2025, which ended October 31, HPE generated $34.3 billion in revenue. Networking contributed $6.9 billion at a 23.3% operating margin, while the much larger Server segment generated $17.7 billion but produced an operating margin of just 7.6%.5 In November 2025, the company restructured its financial reporting into three segments: Networking, "Cloud & AI" (combining servers, storage, and financial services), and Corporate Investments and Other.6
The bull thesis holds that HPE is transforming into a networking-first enterprise that also supplies servers—a business mix deserving higher valuation multiples. The counter-thesis remains equally defined. Skeptics argue that GreenLake operates primarily as hardware leasing packaged with a cloud interface; that AI server shipments pass most of their economic margin through to semiconductor suppliers such as NVIDIA and AMD; that Juniper was acquired near a cyclical peak with substantial debt; and that competitors such as Cisco Systems and Arista Networks maintain strong defensive moats. Furthermore, critics point out that much of the fiscal 2026 margin expansion stemmed from memory-pricing dynamics that management has acknowledged will normalize.
This analysis examines that debate systematically. It traces the corporate lineage from Bill Hewlett and Dave Packard through decades of conglomerate expansion, examines Meg Whitman's structural breakup of Hewlett-Packard, dissects HPE's segment economics, and evaluates GreenLake's financial reality. It then audits the company's acquisition history from Aruba to Juniper, assesses the balance between prestige and profitability in supercomputing and artificial intelligence, and maps out the competitive landscape. Finally, it outlines an executive scorecard, strategic takeaways, and three core performance indicators that will determine which version of HPE emerges.
To evaluate HPE's effort to move beyond commodity hardware, it is essential to examine how that business was constructed, and how close the original enterprise came to faltering under its own conglomerate scale.
 Subscribe on LinkedIn
II. From the Palo Alto Garage to Conglomerate Sprawl: The DNA and Legacy Hangover
The garage and the oscillator
On January 1, 1939, two Stanford engineering graduates, Bill Hewlett and Dave Packard, formalized a partnership with $538 in pooled capital and set up shop in a rented garage behind a house on Addison Avenue in Palo Alto.7 Their first commercial product was an audio oscillator, an electronic instrument designed to generate clean test tones used to evaluate sound equipment. Walt Disney Studios noticed the design and, after requesting modifications, purchased eight units to help calibrate the theater sound systems for the 1940 release of Fantasia.7 It was a modest initial order, but it established the operational pattern that defined HP for half a century: engineer reliable, high-precision instruments for technical specialists, and let product performance build the commercial reputation.
What distinguished HP over the long term was less the oscillator itself than the management philosophy underneath the company—what became known across the technology sector as "the HP Way." Hewlett and Packard instituted decentralized business units, management by walking around, open-door access for engineers, employee profit-sharing, and a deep institutional resistance to layoffs. Decades before Silicon Valley normalized stock options as the standard compensation mechanism to retain talent, HP had built an organization where employees operated with the mindset of equity owners. That heritage explains why modern HPE executives still frame the enterprise around engineering discipline and customer trust. Yet as subsequent decades proved, a celebrated engineering culture does not constitute an economic moat on its own.
From instruments to everything
A strong corporate culture can also underwrite undisciplined expansion. Over the 1980s and 1990s, HP moved from test-and-measurement instruments into minicomputers, commercial personal computers, and desktop printers—a product category that became a massive cash engine. In 1999, the company spun off its original instruments division as Agilent Technologies, effectively severing ties with the business that had established its founding identity.8 What remained was an enterprise computing vendor determined to chase top-line scale.
That scale arrived in 2002, when Chief Executive Officer Carly Fiorina pushed through a $19 billion merger with Compaq Computer over the vocal opposition of Walter Hewlett, the co-founder's son.8 The transaction transformed HP into an industry giant in PCs and x86 servers. It also tethered the company to market segments where the most valuable intellectual property belonged to outside suppliers: microprocessors designed by Intel and operating systems controlled by Microsoft. The ProLiant server family, which remains a core product line inside HPE today, originated at Compaq. It also introduced a persistent strategic dilemma: how does an enterprise vendor sustain premium operating margins when it primarily packages other companies' silicon?
The decade of expensive answers
Throughout the 2000s, HP attempted to answer that question through an aggressive series of debt-financed acquisitions. In 2008, under Chief Executive Mark Hurd, the company purchased IT outsourcing provider Electronic Data Systems for roughly $13.9 billion, betting that managed services would generate stable, recurring revenue to counterbalance cyclical hardware demand. Four years later, HP wrote down approximately $8 billion of that value, conceding that the acquired services assets lacked the durable pricing power management had projected.9 In 2010, HP engaged in a fierce public bidding war with Dell for virtualized storage provider 3PAR, ultimately paying $33 per share—an enterprise value of $2.35 billion—after Dell had opened the bidding at $18.[^10] That auction reflected HP's strategic anxiety to protect storage margins as much as it validated 3PAR's clustering architecture.
The low point of the acquisition strategy arrived with Autonomy. In 2011, under short-tenured CEO Léo Apotheker, HP agreed to pay $11.1 billion for the British enterprise search and software vendor, attempting to manufacture software-like margins overnight. The transaction unraveled almost immediately. In November 2012, HP recorded an $8.8 billion impairment charge, attributing more than $5 billion of the write-down to what it alleged were extensive accounting improprieties and disclosure misrepresentations at Autonomy prior to the sale.10 The ensuing legal battles lasted well over a decade. Autonomy founder Mike Lynch was acquitted in a U.S. federal criminal trial in 2024 and died weeks later when his yacht sank off the coast of Sicily; in July 2025, a UK High Court judge ruled that Lynch's estate and his former finance director were liable to HPE for more than £700 million—a small fraction of the roughly $4 billion in damages HPE had pursued.11
What the hangover teaches
For enterprise investors, the record of that decade yields a straightforward conclusion: HP accumulated massive revenue without establishing structural defensibility. Electronic Data Systems, Autonomy, and the Compaq PC franchise added substantial top-line scale, but none of them gave enterprise customers high switching costs or pricing leverage. Instead, the transactions produced a conglomerate that was simultaneously too complex to operate efficiently and too commoditized to generate premium returns. Crucially, HP entered the modern cloud era—pioneered by Amazon Web Services—without a coherent architectural response to off-premises infrastructure.
That legacy is directly relevant to today's HPE. While the completed acquisition of Juniper Networks involves a mature, audited infrastructure vendor rather than an unvetted software firm, it represents another balance-sheet bet intended to pivot the portfolio toward higher-margin revenue. The historical record suggests that investors should evaluate disclosed operating cash flows rather than strategic synergy targets. By 2014, HP's board of directors concluded that the conglomerate structure was no longer salvageable—and that the only way to unlock shareholder value was to divide the company in half.
III. Meg Whitman & The Great Unbundling: The 2015 Split & The Spin-Mergers
The decision to cut
When Meg Whitman arrived as chief executive in September 2011, the former eBay chief had no background in enterprise hardware and inherited an escalating corporate crisis. Within weeks of her arrival, the accounting issues surrounding Autonomy began to surface. By October 2014, she had reached a conclusion that her predecessors had long resisted: Hewlett-Packard would be far more manageable as two separate companies than as an unwieldy conglomerate.
On November 1, 2015, the separation took effect. Hewlett-Packard Company renamed itself HP Inc. and retained personal computers and printers, while shareholders received one share of the newly formed Hewlett Packard Enterprise for each HP share held.12 HPE assumed the enterprise portfolio: servers, storage, networking, technology services, software, IT outsourcing, and financial services. HPE began regular-way trading on the New York Stock Exchange under the ticker "HPE" the following day, with Whitman as its CEO.12
The strategic rationale appeared clean: HP Inc. would serve as a cash-generating engine in mature end markets, while HPE would operate as a dedicated enterprise infrastructure vendor free to invest and reshape its balance sheet. What investors did not fully appreciate at the time was how aggressively Whitman intended to slim down the enterprise operation.
The enterprise entity forfeited what had long been the parent company's most lucrative asset: printing supplies. Ink and toner cartridges, purchased repeatedly by commercial and retail customers, provided a classic razor-and-blades cash engine that remained with HP Inc. HPE, by contrast, started life with no equivalent annuity. Its enterprise servers followed multi-year capital replacement cycles, its IT services contracts faced margin pressure from low-cost offshore rivals, and its software division was a collection of disparate acquisitions that had never cohered. In that context, every major strategic initiative HPE has pursued since 2015—from GreenLake's consumption billing to the acquisition of Juniper Networks—represented an effort to engineer the high-margin recurring cash flow it lacked at separation.
Whitman recognized that the company's fundamental challenge was not insufficient revenue, but an excess of low-margin revenue. Her response was to shrink HPE deliberately—a disciplined, if counterintuitive, choice for a Fortune 50 executive whose standing was conventionally measured by top-line scale.
The buy that set up everything
Before the split was finalized, HP made an acquisition that would quietly determine HPE's future. On March 2, 2015, HP agreed to acquire Aruba Networks, a Sunnyvale-based wireless networking company, for $24.67 per share in cash, representing an equity value of about $3.0 billion.13 Aruba had roughly 1,800 employees and $729 million in fiscal 2014 revenue, having compounded sales at roughly 30% a year for five years.13 Although modest in size relative to HP's broad hardware operations, Aruba was profitable, growing, and built around software-managed Wi-Fi at a time when enterprise workforces were shifting from fixed Ethernet cables to mobile connectivity. That transaction quietly established the software architecture and networking leadership that would anchor HPE's portfolio transformation in the years that followed.
The spin-merger playbook
Whitman's subsequent portfolio reshaping relied on tax-efficient financial engineering. Rather than selling underperforming units for cash and incurring substantial capital gains taxes, HPE executed spin-mergers—transactions patterned on the Reverse Morris Trust structure—in which divisions were spun off to HPE shareholders and immediately merged with third-party operating companies.
The first target was Enterprise Services, the legacy EDS business, which was capital-intensive, heavily staffed, and experiencing structural revenue contraction. HPE merged the unit with Computer Sciences Corporation, and on April 3, 2017, the combined entity began life as DXC Technology, with about $26 billion in annual revenue.14 HPE reported that the deal delivered approximately $13.5 billion of value to HPE and its shareholders, including a $3 billion cash payment to HPE, while pre-merger HPE holders owned about 50.1% of DXC.14
The second transaction addressed software. On September 7, 2016, HPE agreed to spin its non-core software assets, including remnants of Autonomy, Mercury Interactive, and ArcSight, and merge them with UK-based Micro Focus in a transaction valued at about $8.8 billion. HPE shareholders would own 50.1% of the combined company and HPE would receive a $2.5 billion cash payment.15 The deal closed on September 1, 2017.[^17]
Myth vs. reality: did unbundling create value?
The conventional narrative portrays the spin-mergers as an unalloyed success: HPE offloaded its most troubled businesses tax-efficiently and emerged as a focused enterprise vendor. The underlying financial record is considerably more nuanced, depending on which portfolio an investor held.
For shareholders who retained the distributed shares in DXC and Micro Focus, the outcome was poor. Micro Focus struggled almost immediately with the integration of HPE's software assets, suffered years of revenue decline, and was ultimately acquired by OpenText in January 2023 for 532 pence per share—an enterprise value of roughly $6 billion, well below the $8.8 billion valuation attached to HPE's software assets alone in 2016.16 DXC endured persistent revenue contraction and repeated restructurings in the years after its formation. The equity value management projected at the time of the transactions failed to materialize for investors who held what they were given.
For the stub company that kept the HPE name, however, the verdict was more favorable. HPE shed tens of thousands of services employees, eliminated a large portion of the goodwill from the EDS and Autonomy era, and removed the operational distraction of running businesses it could not fix. It also collected more than $5 billion in cash from the two transactions combined.1415 The reality of the unbundling is not that it generated broad shareholder wealth in aggregate, but that it gave HPE a cleaner, more defensible operating core.
That core was what Whitman handed to her successor when she stepped down in early 2018. The next question was what, exactly, that core was worth, and the answer lies in segment-level economics that headline financial results often obscure.
IV. Anatomy of the Machine: Segment Economics, Profit Pools, & The Hardware Trap
A tale of two margins
Consider two distinct businesses operating under the same corporate roof. The first sells roughly $16 billion of equipment a year, commands the bulk of the supply chain, and keeps about ten cents of operating profit on each dollar in a favorable year. The second generates approximately $4.5 billion—barely a quarter of that volume—yet converts nearly twenty-five cents of every dollar into operating profit. Determining which unit represents the true core of the enterprise is central to assessing HPE.
That asymmetry defined HPE's financial anatomy in fiscal 2024, the final year under its legacy four-segment reporting structure. The Server division posted $16.2 billion in revenue with an 11.2% operating margin. Hybrid Cloud, primarily comprising storage assets, brought in $5.4 billion at a narrow 4.5% margin. Intelligent Edge, anchored by Aruba, generated $4.5 billion at a 24.6% margin. Financial Services, the company's captive leasing division, produced $3.5 billion at a 9.0% operating margin.17 In aggregate, Intelligent Edge accounted for roughly one-sixth of corporate revenue but generated nearly a third of total segment operating profit—a disproportionate share that widened whenever server margins contracted.
What each business actually does
Server operates as HPE's volume engine, delivering ProLiant rack servers for standard corporate workloads alongside the high-performance supercomputing and artificial intelligence clusters inherited from Cray. At its core, an enterprise server is a specialized computing system engineered for continuous data center operation. HPE designs the motherboard, chassis, thermal cooling, and proprietary management firmware known as Integrated Lights-Out (iLO), which enables administrators to configure and troubleshoot systems remotely. However, the most economically valuable components—microprocessors, memory modules, and graphics processing units—are sourced from third-party suppliers including Intel, AMD, NVIDIA, Samsung, SK Hynix, and Micron. That structural dependency explains both the segment's top-line scale and its chronic margin volatility.
Hybrid Cloud, reorganized as Storage within the Cloud & AI division, sells enterprise storage arrays such as the Alletra product line alongside associated management software. The unit has struggled with sustained profitability. In the second quarter of fiscal 2025, HPE recorded a $1.4 billion goodwill impairment against the reporting unit after concluding that its carrying value exceeded fair value.18 The non-cash write-down represented a formal accounting admission from executive leadership and external auditors that past investments, including historical storage acquisitions, had failed to justify their original purchase price.
Intelligent Edge, now integrated into the expanded Networking segment, supplies campus and branch infrastructure: Wi-Fi access points, Ethernet switches, software-defined wide area networking (SD-WAN), and the Aruba Central cloud orchestration platform. Financial Services provides equipment leasing and structured asset management, serving as the captive balance-sheet mechanism that underpins GreenLake's pay-as-you-go consumption model.
Financial Services warrants careful scrutiny because it remains the least visible yet most predictable component of the business model. In fiscal 2025, the division generated approximately $3.5 billion in revenue at a 10.3% operating margin—consistent profitability within a corporation prone to cyclical hardware swings.5 Operating much like the captive finance unit of an automotive manufacturer, the division retains title to the hardware while clients pay through periodic installments, allowing HPE to capture an interest spread between its borrowing costs and lease rates. The underlying risks mirror those of commercial lending: counterparty credit defaults and residual-value risk when decommissioned assets return at lease expiration. In the third quarter of fiscal 2026, Financial Services revenue held virtually flat year over year at $883 million, even as server sales surged—reinforcing its function as a balance-sheet stabilizer rather than a top-line growth driver.1 Crucially for equity investors, the segment enables HPE to market flexible consumption pricing without forcing clients to arrange third-party credit, though its debt obligations form an integral part of HPE's consolidated balance-sheet leverage.
The new scoreboard
The consolidated reporting structure following the Juniper integration highlights that disparity. In fiscal 2025, which incorporated only four months of Juniper operations, Networking generated $6.9 billion in revenue at a 23.3% operating margin, whereas Server yielded a 7.6% operating margin on $17.7 billion and Hybrid Cloud returned 5.8% on $5.8 billion.5 At the October 2025 Securities Analyst Meeting, management noted that networking already generated approximately half of HPE's non-GAAP operating profit and targeted roughly 60% by fiscal 2028.1920
The core valuation debate therefore turns on multiple expansion: whether public markets will value an expanding networking business generating more than $7 billion in high-margin revenue on a standalone software-and-networking multiple, or apply a conglomerate discount reflecting the capital-intensive, lower-margin server and storage divisions tied to it.
Myth vs. reality: the server moat
The argument that HPE possesses a durable economic moat in servers typically rests on three pillars: integrated management software, global enterprise support networks, and an entrenched worldwide channel of resellers. While each asset provides commercial utility, none has historically insulated operating margins during cyclical downturns.
The first test of pricing defense is customer substitution. Over the past decade, the world's largest server purchasers—hyperscalers including Amazon Web Services, Microsoft, Alphabet's Google, and Meta Platforms—largely bypassed branded original equipment manufacturers such as HPE and Dell. Instead, they designed custom hardware architectures through the Open Compute Project and procured systems directly from original design manufacturers in Taiwan, including Quanta Computer, Wiwynn, and Foxconn. That procurement pattern offers compelling disconfirming evidence: the industry's most technically sophisticated, high-volume buyers consistently refused to pay branded hardware markups.
The second test involves price realization during periods of market stress, where HPE's operating record reveals structural vulnerability. On the fiscal first-quarter 2025 earnings call in March 2025, Neri acknowledged execution missteps, telling investors that "we could have executed better," explaining that traditional server pricing "did not adequately account for the valuation of our inventory" and that "higher discounts due to aggressive pricing competition" compounded the problem.21 Segment operating margin dropped to 8.1%, falling well short of management's 10% to 11% guidance range.21 HPE simultaneously announced approximately 2,500 job reductions, prompting a sharp decline in the share price.22 A franchise possessing authentic economic pricing power rarely discovers at quarter-end that competitive discounting has eroded its inventory margins.
The third test has unfolded across fiscal 2026, pointing in the opposite direction. Beginning in late 2025, an acute shortage of DRAM and NAND flash memory—spurred by generative AI clusters consuming immense allocations of high-bandwidth memory—drove upstream component costs sharply higher. HPE responded by enacting repeated price increases starting in November 2025, contracting quote validity periods, and inserting contractual clauses that permitted repricing on backlog orders if component expenses escalated prior to shipment.23 The financial impact was immediate: the Cloud & AI segment achieved a 17.0% operating margin in the third quarter of fiscal 2026, propelled by a 35% surge in server revenue on record average selling prices.12
Does this surge validate a structural server moat? The disclosed results qualify the thesis rather than prove it. In an industry-wide supply squeeze where all hardware vendors raised quotes in unison, HPE demonstrated disciplined cost pass-through. Yet management's forward guidance establishes clear boundaries. Chief Financial Officer Marie Myers cautioned on the September 2026 earnings call that gross margin would "moderate toward more historical levels," citing a larger mix of lower-margin AI server systems and "the normalization in traditional servers."2 That outlook describes an acute cyclical pricing window rather than permanent economic defensibility. The decisive metric for investors will be Cloud & AI operating profitability once memory supply loosens, a condition Neri projected would persist through 2027.2
The fundamental strategic question is whether HPE can insulate commodity hardware with stickier, higher-margin software and recurring services. Delivering on that promise became the core mandate of GreenLake—and the signature strategic bet of Antonio Neri when he succeeded Whitman.
V. Antonio Neri’s Master Plan: Edge-to-Cloud & GreenLake Dissected
The call-center engineer
In 1995, a young Argentine engineer named Antonio Neri took a job at Hewlett-Packard's customer support center in Amsterdam, answering calls from clients whose equipment had failed.24 It was about as far from the executive suite as a career in technology could start. Over the next two decades, Neri rose through HP's customer service ranks into engineering and product leadership, oversaw the server and storage divisions, and became HPE's president. In February 2018, he succeeded Whitman as chief executive officer.24
The biographical trajectory signaled a cultural shift. HP's previous chief executives had been, in turn, a consumer-marketing executive (Fiorina), an operational cost-cutter (Hurd), an enterprise software strategist (Apotheker), and a consumer-internet executive turned restructuring specialist (Whitman). Neri was an engineer who understood firmware, manufacturing logistics, component supply chains, and the immediate operational headaches of enterprise data center administrators. The structural risk of an insider, however, is that deep technical familiarity with hardware can obscure when the underlying hardware business model itself is the strategic constraint.
The promise
In June 2019, at HPE's Discover conference in Las Vegas, Neri made the pledge that defined his tenure. "In the next three years HPE will be a consumption-driven company," he told attendees. "Everything we deliver to you will be available as a service."25 At the time of the announcement, GreenLake accounted for more than $2.8 billion in total contract value across more than 600 enterprise customers.25
The pitch addressed a genuine structural tension in enterprise computing. Public cloud platforms allow organizations to pay strictly for capacity consumed, scale compute dynamically without upfront capital expenditure, and eliminate long-term provisioning risk. Yet many enterprises cannot or will not migrate entirely to public cloud providers like Amazon Web Services or Microsoft Azure: financial institutions and healthcare systems face strict data sovereignty mandates, manufacturing plants require near-zero latency, and organizations with steady, predictable workloads frequently find that public cloud hosting becomes prohibitively expensive, particularly when paying data egress charges to retrieve proprietary information. GreenLake promised cloud-like operational billing for physical hardware deployed directly inside the customer's private facility: HPE delivers and installs the infrastructure, meters utilization, and bills monthly.
A commercial analogy clarifies the economic distinction: purchasing an enterprise server outright is like buying a car, while public cloud resembles hailing an on-demand ride. GreenLake operates like a long-term vehicle lease with a per-mile usage charge, where the dealer parks spare vehicles in the customer's driveway to guarantee immediate standby capacity as needs expand.
HPE fulfilled the technical terms of that pledge: by 2022, Neri stated that the company had delivered on its commitment to offer its entire portfolio as a service.26 Yet catalog availability is not equivalent to customer adoption. Providing a flexible consumption option across a hardware catalog is fundamentally different from converting the core revenue base into recurring software subscriptions. For investors, the decisive question was always what portion of HPE's revenue would realistically transition to consumption billing, what operating margins that revenue would command, and how much balance-sheet capital would remain encumbered along the way.
The numbers management chose to show
HPE's primary metric for tracking this operational shift was Annualized Revenue Run-Rate, or ARR, which annualizes the final quarter's recurring revenue from GreenLake and related software and support subscriptions. ARR reached $1.9 billion at the end of fiscal 2024, up 49% year over year, and climbed to $3.2 billion at the close of fiscal 2025, up 63%—a growth rate bolstered by the consolidation of Juniper's recurring software and support revenue.175 Management established a fiscal 2026 target of $3.5 billion.5 On the September 2026 earnings call, management disclosed that GreenLake's customer base had grown 18% year over year to approximately 52,000 organizations.2
Myth vs. reality: is GreenLake a SaaS business?
The strategic claim is that GreenLake transforms HPE from a cyclical box-shipper into a high-margin, sticky, cloud-like platform. The empirical record narrows that claim considerably.
The first constraint is contract composition. An on-premises consumption contract bundles several disparate elements into a single monthly invoice: physical hardware financed over the multi-year term, maintenance and technical support that HPE previously billed as separate service contracts, and a layer of orchestration and management software. Only that final software component exhibits the economics of software-as-a-service. HPE has never disaggregated ARR into pure software versus financed hardware and support in a format that allows investors to isolate high-margin recurring software, despite persistent analyst scrutiny.
The second constraint is capital intensity. Pure software companies write code once and distribute it at negligible marginal cost, typically generating gross margins of 75% or higher. GreenLake requires HPE or its financing partners to manufacture, deliver, and configure physical infrastructure before receiving consumption revenue. That model absorbs working capital, leans heavily on the Financial Services balance sheet, and incurs steady equipment depreciation. Economically, the offering functions more like structured equipment leasing packaged in a software wrapper than authentic cloud software.
The third constraint involves customer unit economics. For large, highly predictable enterprise workloads, corporate finance teams routinely determine that purchasing servers outright—or committing to reserved capacity instances in the public cloud—proves more economical than paying an ongoing premium for on-premises flexibility they rarely exercise. That economic calculation establishes a natural ceiling on how much traditional hardware spending will transition to consumption billing.
The final consideration centers on disclosure practices. ARR served as the headline operational metric in every fiscal 2025 earnings announcement. Yet in both the first-quarter and third-quarter earnings releases of fiscal 2026, ARR was absent from the headline financial summary.271 Companies modify reporting presentation for multiple operational reasons, including the post-Juniper segment consolidation. However, when an enterprise stops highlighting the flagship metric it previously promoted as definitive proof of strategic transformation, investors must examine whether the underlying momentum has slowed.
The verdict: GreenLake functions as an effective commercial vehicle and a valuable sales motion, particularly for data-sovereignty requirements and dedicated private artificial intelligence clusters. What the financial record refutes is the premise that GreenLake converts HPE into a high-margin software enterprise. What remains unproven is whether GreenLake materially elevates customer switching costs over the long run. The disclosure that would substantiate that thesis is a separate, audited reporting line showing high-margin pure software ARR expanding faster than physical hardware shipments.
If GreenLake alone could not liberate HPE from the cyclical hardware trap, networking offered an alternative path. Neri's most consequential strategic decisions were balance-sheet acquisitions designed to accomplish precisely that shift.
VI. The M&A Crucible: From Aruba’s Home Run to the $14B Juniper Megadeal
The home run
The benchmark for HPE's networking ambitions was established with the 2015 acquisition of Aruba Networks. Aruba's founders had built the enterprise as an agile challenger to Cisco's entrenched dominance in enterprise campus networking, and large-scale hardware acquisitions routinely risk suffocating an acquired engineering culture. HP largely avoided that pitfall by preserving the Aruba brand and granting the business operational autonomy. Intelligent Edge revenue expanded from $729 million in fiscal 2014 to a peak of more than $5 billion in fiscal 2023, before an industry-wide inventory digestion cycle trimmed revenue to $4.5 billion in fiscal 2024, while operating margins held firm in the mid-twenties.1317 Measured by cumulative operating cash flow relative to purchase price, Aruba stands as one of the most successful enterprise hardware acquisitions of that decade.
In July 2020, HPE complemented that footprint by acquiring Silver Peak for approximately $925 million.28 Silver Peak specialized in software-defined wide-area networking (SD-WAN), a technology that routes enterprise network traffic dynamically between distributed branch offices and cloud environments over standard internet connections rather than expensive, dedicated private circuits. The transaction closed a clear capability gap in Aruba's portfolio just as remote work decentralized corporate network architectures, and the software was integrated into Aruba's unified edge orchestration platform.
The mixed bets
Other balance-sheet bets proved less enduring. In March 2017, HPE agreed to acquire Nimble Storage for $12.50 per share, representing an equity purchase price of roughly $1.0 billion net of cash alongside $200 million in assumed equity awards.29 Nimble's core asset was InfoSight, a predictive analytics engine that ingested telemetry from enterprise storage arrays to diagnose hardware vulnerabilities before they precipitated outages. InfoSight was deployed across HPE's broader product portfolio as a genuine technical success. Yet the acquisition failed to reverse market-share erosion against specialized storage competitors such as Pure Storage and Dell, and the $1.4 billion Hybrid Cloud goodwill impairment recorded in fiscal 2025 served as formal accounting recognition that the storage portfolio had failed to generate the economic returns management had projected.18
In May 2019, HPE agreed to acquire supercomputer manufacturer Cray for $35 per share, or approximately $1.3 billion net of cash.30 Cray contributed Slingshot high-performance interconnect fabric alongside the specialized engineering required to build the world's first exascale computing systems. However, the transaction also saddled HPE with fixed-price government research contracts and milestone-dependent delivery acceptance, introducing quarterly margin lumpiness into hardware results—a trade-off examined in Section VII.
The watershed
On January 9, 2024, HPE announced an agreement to acquire Juniper Networks for $40 per share in cash, an equity value of roughly $14 billion that represented a 32% premium over Juniper's unaffected share price.3 The strategic thesis mirrored the Aruba transaction on a much larger scale. While Aruba was concentrated in campus wireless networks and enterprise branch switching, Juniper brought enterprise routing for telecommunications carriers and hyperscale cloud providers, high-density data center switching, and Mist AI—a cloud orchestration platform widely regarded by enterprise network administrators as a leading artificial intelligence engine for automated network operations. Executive leadership asserted that the combination would double HPE's networking footprint and elevate the segment to more than 50% of total operating income.34
Executing the transaction required significant balance-sheet leverage. At announcement, HPE secured approximately $14 billion in fully committed term loan facilities.3 In September 2024, the company issued $1.35 billion of mandatory convertible preferred stock bearing a 7.625% dividend—slated to convert into common equity around September 2027—and issued senior unsecured notes to fund the cash purchase price.31 It also established roughly $12 billion in delayed-draw term loan facilities.18 By the start of fiscal 2026, consolidated net leverage stood at approximately 3.1 times.32
The regulatory gauntlet
The European Commission cleared the transaction unconditionally in the summer of 2024.33 The U.S. Department of Justice took a far more skeptical stance. On January 30, 2025, the DOJ filed an antitrust lawsuit to block the deal, alleging that HPE and Juniper constituted the second- and third-largest providers of enterprise-grade wireless local area networks in the United States, and that combining them would leave HPE and market incumbent Cisco controlling roughly 70% of the domestic market.34
On June 28, 2025, less than two weeks before trial was scheduled to begin in federal court, the parties reached a settlement. HPE agreed to divest Instant On, its wireless and switching product family tailored for small businesses, and conduct an auction for a perpetual, non-exclusive license to the source code of Juniper's Mist AI operational software for competing vendors.3536 With those behavioral and structural concessions in place, the acquisition closed on July 2, 2025.4
The resolution prompted legal and political friction. Roger Alford, a senior DOJ antitrust official who was dismissed after objecting internally to the proposed decree, publicly alleged that political lobbying had improperly influenced the department's decision to settle.37 A coalition of state attorneys general subsequently sought to intervene during judicial review under the Tunney Act, the federal statute requiring a court to determine whether an antitrust consent decree serves the public interest.38 The presiding federal court denied the states' emergency motion to halt integration in January 2026, held a formal hearing in March, and on August 12, 2026, entered final judgment finding the settlement in the public interest and rejecting the states' substantive legal challenges.39 Through the third quarter of fiscal 2026, Instant On continued to be reported within HPE's Corporate Investments and Other segment pending formal divestiture.6
Although the legal cloud has dissipated, the settlement leaves two clear operational consequences. First, Juniper's primary software asset, Mist AI, has been licensed to competitors, partially diluting its exclusivity in commercial bake-offs. Second, the protracted regulatory battle and resulting political scrutiny established an elevated bar for any future large-scale transactions requiring antitrust review.
Stress-testing the price
Whether the $14 billion purchase price generates economic value depends on multi-year post-merger execution, where initial operational indicators remain mixed but encouraging. At the October 2025 Securities Analyst Meeting, management established a conservative multi-year framework: networking revenue expansion of 5% to 7% annually from fiscal 2025 through fiscal 2028, operating margins reaching 25% to 28%, and at least $600 million in annual run-rate cost synergies.20 For fiscal 2026, leadership guided to low-to-mid single-digit revenue growth and operating margins in the low twenties as integration investments peaked.20
Through the first nine months of fiscal 2026, networking operating margins hovered near 22%.1 In the third quarter of fiscal 2026, networking revenue expanded 10% on a normalized basis—adjusted as if Juniper had been consolidated across both periods—while product orders surged 36%.2 Data center networking revenue more than doubled, carrier routing benefited from full product inclusion, and customer orders for networking gear deployed in AI data centers reached $700 million in the quarter, anchored by an expanded partnership with Oracle to deliver HPE Juniper infrastructure for gigawatt-scale AI computing clusters.12 Executive leadership also reported that cost synergies were tracking ahead of original projections.2
These milestones offer tangible proof points, particularly in high-performance AI data center switching where Arista Networks has historically held a commanding market position. Yet the broader thesis that Juniper elevates HPE into a Cisco-class networking powerhouse commanding structural software-and-networking valuation multiples remains an unproven hypothesis until operating margins hit the promised 25%-plus threshold and integration between two operating systems and two management consoles is achieved without customer attrition. On the September 2026 earnings call, financial analyst Amit Daryanani probed the operational gap between 10% realized revenue growth and 36% order expansion; management attributed the divergence to supply-chain bottlenecks and projected revenue acceleration in upcoming quarters.2 The coming fiscal year will test whether that conversion occurs.
If Juniper represents HPE's pursuit of recurring, high-margin profitability, supercomputing and AI infrastructure represent its commitment to engineering prestige and gross hardware volume. Historically, those two objectives have rarely pointed in the same direction.
VII. The AI & Supercomputing Conundrum: Exascale Glory vs. GPU Commodity Economics
The fastest machines on Earth
In May 2022, the TOP500 ranking of the world's supercomputers verified a new benchmark. Frontier, an HPE Cray EX system deployed at Oak Ridge National Laboratory in Tennessee, achieved 1.1 exaflops, becoming the first machine to officially break the exascale barrier of one quintillion calculations per second.40 To put that computing speed in perspective, if every person on Earth performed one calculation every second, it would take humanity more than four years to complete what Frontier calculates in a single second. Frontier also earned the top ranking on the Green500 list for supercomputing energy efficiency.40
In November 2024, HPE and AMD reached that threshold again with El Capitan at Lawrence Livermore National Laboratory. Developed for the National Nuclear Security Administration, the system was benchmarked at 1.742 exaflops, registering as the fastest computer ever measured and marking HPE's third exascale delivery for the U.S. Department of Energy.41 These installations represent formidable engineering accomplishments, requiring custom interconnect fabrics, direct liquid cooling routed straight to processor packages, and complex multi-cabinet systems integration that only a select group of global vendors can deliver.
Direct liquid cooling warrants close examination because it represents one of the few areas in server engineering where manufacturing expertise creates tangible technical differentiation. Modern artificial intelligence accelerators generate intense thermal concentrations that traditional forced-air ventilation cannot manage; a single high-density rack can draw as much electrical power as dozens of homes. Direct liquid cooling functions much like an automotive radiator, circulating fluid through cold plates bolted directly onto microprocessors to absorb and transfer heat far more effectively than air. Engineering and deploying these closed-loop hydraulic systems reliably at scale—preventing leaks within enterprise facilities never designed for plumbing inside computing racks—demands deep operational discipline. HPE acquired that specialized proficiency building supercomputers for national research laboratories, and that know-how translates directly into high-density commercial AI clusters. The competitive limitation is that Dell Technologies, Super Micro Computer, and Asian original design manufacturers have invested heavily in similar liquid-cooling capabilities, making thermal management an engineering lead to defend rather than an insurmountable economic moat.
From labs to the enterprise
The commercial surge in generative artificial intelligence following late 2022 opened a path to monetize HPE's supercomputing heritage. Training large frontier models and running enterprise inference workloads require clusters of accelerator servers linked by ultra-low-latency networks and cooled with industrial intensity—architecturally identical to research supercomputers. In fiscal 2025, HPE reported $6.8 billion in cumulative AI systems orders.42 During the third quarter of fiscal 2026, AI systems orders expanded 30% sequentially to $2.4 billion, while realized AI systems revenue reached $1.6 billion; following the close of the quarter, HPE announced a multibillion-dollar inferencing agreement with a major hyperscaler for internal enterprise AI operations.2 Meanwhile, customer orders for Private Cloud AI, a turnkey on-premises hardware and software stack aimed at corporate data centers, grew at a triple-digit pace.2
Myth vs. reality: profitless prosperity?
The strategic narrative suggests that artificial intelligence infrastructure will serve as a multi-year engine of revenue growth and operating margin expansion for HPE's server operations. The empirical record strongly supports the top-line volume, but consistently contradicts the margin thesis.
The underlying constraint lies in the bill of materials for an accelerated server. An enterprise AI system can retail for hundreds of thousands of dollars per unit, but the vast majority of that invoice reflects the cost of NVIDIA or AMD graphics processors alongside high-bandwidth memory chips. HPE provides the chassis design, board integration, liquid cooling infrastructure, diagnostic testing, and logistics delivery—valuable engineering work that nevertheless captures only a modest slice of the total equipment bill. In economic terms, it resembles a high-end restaurant serving dishes built around expensive imported truffles: the revenue per plate is substantial, but the truffle purveyor captures the bulk of the profit pool.
HPE's executive leadership has acknowledged that dynamic in financial disclosures. On the fiscal first-quarter 2025 earnings call, Chief Financial Officer Marie Myers attributed part of the server margin compression to AI inventory friction during the industry transition from NVIDIA's Hopper architecture to Blackwell, describing the shift as "an industry-wide challenge."21 In September 2026, Myers cautioned that consolidated gross margin would moderate as AI systems represented a larger share of product shipments, explicitly identifying AI server volume as dilutive to gross margin.2 Reflecting that limited financial visibility, HPE does not break out standalone operating margins for AI systems or supercomputing, having folded high-performance computing into the broader Server segment during its fiscal 2024 reporting reorganization.
Two additional structural pressures compound the challenge. First, purchasers of large AI clusters—including hyperscale cloud providers, sovereign AI initiatives, and government research facilities—are sophisticated, price-conscious institutions willing and able to redirect volume to Dell, Super Micro Computer, or contract manufacturers. Second, extended component lead times require HPE to purchase expensive silicon months before recognizing revenue, generating a working-capital drag that fixed-price government contracts can exacerbate if a milestone payment slips due to upstream component delays.
That working-capital exposure is tangible on the balance sheet. At the close of the first quarter of fiscal 2026, HPE's inventory stood at $6.9 billion, rising sequentially as the company deliberately stockpiled memory modules and related components to secure delivery capacity, while outstanding purchase commitments increased in parallel.23 During an acute semiconductor shortage, that inventory operates as a commercial asset: it enables HPE to fulfill orders while competitors face supply constraints, locking in component pricing before market quotes escalate. In a supply glut, however, that same inventory transforms into an impairment risk—the precise dynamic that pressured server profitability in early 2025 when previous-generation GPU inventory depreciated faster than anticipated.21 For equity investors, the balance-sheet inventory line represents an implicit bet on component price trajectories, and management must be evaluated on how cleanly it normalizes working capital when cyclical supply tightens or loosens.
Certification is not commercialization
Frontier and El Capitan stand as undeniable technical breakthroughs. Yet the commercial record of Cray and HPE's supercomputing operations indicates that engineering leadership has converted into top-line revenue far more reliably than into operating profit. The generative AI hardware wave has exhibited the identical pattern: robust order intake paired with executive guidance that consistently treats AI volume as a mix headwind to gross margin.
The most instructive test ahead centers on AMD's "Helios" rack-scale AI platform, where HPE serves as a primary integration partner. On the September 2026 earnings call, Neri declined to incorporate Helios into HPE's fiscal 2027 financial framework until delivery schedules become clearer, while characterizing the market opportunity as "tens of billions of dollars" and pointedly highlighting custom networking silicon.2 That distinction is revealing. If HPE's economic returns from artificial intelligence infrastructure stem increasingly from proprietary Slingshot and Juniper-derived networking fabrics rather than low-margin server assembly, the AI effort becomes a networking story with structurally superior economics. The decisive performance indicator for investors is not headline AI revenue growth, but whether the operating margin of the Cloud & AI segment expands as AI server shipments scale.
With the individual operational engines examined, the broader strategic question is how defensible HPE's overall enterprise footprint remains against entrenched networking incumbents and low-cost server rivals across the global technology landscape.
VIII. Strategic Frameworks: 7 Powers & Porter’s Five Forces
The war room
Evaluating HPE's competitive durability requires placing the company directly opposite its four primary rivals: Dell Technologies, which matches HPE in enterprise servers, storage, and AI clusters; Cisco Systems, the incumbent in enterprise networking with a massive installed base and an expanding software footprint; Arista Networks, which built an exceptionally profitable franchise selling high-speed data center switches to cloud providers; and the hyperscale cloud platforms themselves, which operate simultaneously as HPE customers, partners, and structural substitutes. The central question for enterprise investors is how many of HPE's competitive advantages can withstand concerted pressure from each.
Hamilton Helmer's 7 Powers
Applied systematically to HPE's portfolio, Helmer's framework reveals an uneven competitive profile across seven potential sources of durable advantage.
Scale economies are moderate. HPE procures microprocessors and memory modules in massive volumes and operates a global manufacturing and field-service network, but it possesses no scale advantage over Dell in servers and commands no pricing leverage over semiconductor suppliers such as NVIDIA, which unilaterally set accelerator prices.
Network effects are weak across compute and storage, but emerging in networking. Cloud orchestration platforms such as Aruba Central and Mist AI aggregate telemetry from millions of connected endpoints to diagnose operational anomalies autonomously. As more network devices join the platform, the underlying machine-learning models improve. That feedback loop creates a data-driven advantage, though the antitrust settlement requiring HPE to auction a source-code license for Mist AI means competing vendors can establish a baseline on that same software foundation.36
Switching costs represent the company's most durable economic power, but they remain concentrated in networking. Replacing thousands of wireless access points and Ethernet switches across an enterprise, university, or hospital campus entails substantial physical labor, operational downtime risk, and staff retraining—incentivizing enterprise IT buyers to stay with their incumbent vendor through periodic refresh cycles. In standard enterprise servers, by contrast, switching costs approach zero; migrating virtual machines or software containers between an HPE ProLiant and a Dell PowerEdge server is routine.
Cornered resource is largely absent. HPE designs no proprietary general-purpose microprocessors or accelerator silicon, relying instead on merchant silicon from Intel, AMD, NVIDIA, and Broadcom. Juniper's custom routing silicon provides a partial exception in specialized carrier and telecom hardware, and Neri's commentary regarding AMD's Helios architecture signals longer-term interest in proprietary networking silicon, but that capability represents strategic optionality rather than an established competitive moat.
Counter-positioning offered temporary differentiation when GreenLake launched in 2019, because public cloud providers could not easily introduce on-premises hardware without challenging their pure-consumption economic model. Hyperscalers neutralized that asymmetry by introducing their own hybrid appliances, including AWS Outposts, Microsoft Azure Stack, and Google Distributed Cloud, leaving HPE with minimal structural advantage in consumption billing.
Process power is moderate. HPE's deep institutional expertise in direct liquid cooling, complex exascale supercomputing integration, and global field-service logistics is difficult for smaller vendors to match quickly. However, Dell, Lenovo, and Asian original design manufacturers have demonstrated comparable engineering capabilities at enterprise scale.
Branding carries institutional weight across mission-critical enterprise IT and public-sector procurement, where the legacy adage that enterprise buyers face little career risk selecting an established vendor retains practical influence. Yet the brand commands little pricing power or loyalty among cloud-native developers and software architects.
The war game
Simulating commercial competition from each competitor's perspective highlights HPE's operational vulnerabilities and tactical defenses.
Dell's playbook against HPE relies on manufacturing scale and aggressive pricing. In standard server procurements where enterprise clients view hardware specifications as interchangeable, Dell can discount bids by several percentage points to secure market share—a tactic it has deployed in high-density AI clusters to capture flagship reference customers. HPE's counter-strategy is to cross-sell servers alongside campus networking, storage arrays, and captive financing through GreenLake, a bundled proposition Dell cannot duplicate in high-performance networking without third-party partnerships. That architectural bundling represents a primary strategic justification for the Juniper acquisition: it provides HPE a seat at the table in data center negotiations where standalone compute would devolve into a pure commodity auction.
Cisco's playbook leverages entrenched enterprise incumbency. Most Fortune 500 corporations maintain pervasive Cisco switching and routing footprints, and Cisco's commercial pitch emphasizes that consolidating networking, cybersecurity, and observability under a single enterprise vendor reduces administrative overhead. Cisco's vulnerability stems from customer perception of management complexity and high licensing costs—precisely the opening Aruba and Juniper Mist seized by offering streamlined, cloud-managed, AI-assisted network operations. However, the post-merger integration phase represents Cisco's primary competitive window: any operational friction, product roadmap confusion, or sales-force disruption between Aruba Central and Mist AI gives Cisco's enterprise account teams an opening to win back accounts.
Arista Networks' playbook centers on elite performance within high-speed data center switching. Having established dominance by supplying switches to hyperscalers, Arista has pushed aggressively into enterprise campus networks and AI back-end clusters. HPE's customer orders for AI networking and its collaboration with Oracle demonstrate that Juniper's data center fabric provides a viable competitive counterweight, but Arista's established tier-one customer relationships and software margins remain formidable.2
The hyperscalers' strategy remains the most consequential long-term threat: continuously absorbing enterprise workloads into centralized cloud infrastructure. Every corporate workload migrated to AWS, Azure, or Google Cloud permanently reduces the total addressable market for on-premises enterprise hardware. HPE's counter-argument contends that enterprise AI inferencing over proprietary data, strict data sovereignty regulations, and escalating cloud hosting costs will anchor a substantial share of enterprise computing in private data centers—a plausible thesis, but one that HPE's financial disclosures have yet to validate quantitatively.
The strategic synthesis is unmistakable: HPE's durable competitive advantages reside almost entirely in networking, where switching costs and emerging data network effects offer defensive moats. That concentration explains why executive leadership staked the company's balance sheet on the Juniper acquisition.
Porter's Five Forces
Industry rivalry remains intense across every operating segment. In servers and storage, HPE and Dell engage in aggressive, deal-by-deal price competition. In networking, Cisco's market share and Arista's data center dominance leave little room for operational missteps, while the Department of Justice's antitrust complaint highlighted that HPE, Juniper, and Cisco controlled approximately 70% of the domestic enterprise WLAN market prior to the merger.34
Supplier power is exceptionally high. Intel and AMD control enterprise x86 microprocessors; NVIDIA commands an overwhelming share of AI accelerators; and three semiconductor manufacturers produce the vast majority of global DRAM. The memory supply squeeze of fiscal 2026 illustrated that supplier concentration can cut both ways: while universal component cost inflation allowed vendors with contractual pass-through provisions to reprice backlogs and temporarily expand gross margins, suppliers inevitably reassert their pricing leverage once production constraints normalize.
Buyer power is high in enterprise compute and moderate in networking. Large enterprise procurement departments routinely run competitive bake-offs between HPE and Dell to extract price concessions, while hyperscale and sovereign purchasers of AI infrastructure negotiate aggressively on system margins. In networking, campus switching costs temper buyer leverage, but large enterprise clients still command significant volume discounts.
Threat of substitutes is very high over a multi-year horizon. Public cloud platforms represent the ultimate substitute for on-premises data center hardware, and every corporate application re-architected for cloud-native infrastructure permanently displaces a potential server sale.
Threat of new entrants is low to moderate in traditional enterprise accounts, where extensive reseller channels and global field support create high barriers to entry. However, original design manufacturers in Asia already dominate hyperscale server shipments and pose a persistent threat of moving up-market into tier-two cloud and large enterprise accounts.
These strategic frameworks reinforce a single conclusion: HPE's long-term economic durability hinges entirely on the health and execution of its expanded networking business, alongside management's discipline in preventing cyclical server and storage operations from eroding capital during market downturns. Evaluating that execution requires a rigorous audit of executive leadership's strategic track record.
IX. Management Credibility, Incentives, & Capital Allocation Under Stress
Following the money
Executive compensation highlights where leadership's financial incentives lie. For fiscal 2025, Antonio Neri received total compensation of approximately $23.5 million. His base salary of $1.35 million represented less than 6% of that sum, while stock awards accounted for roughly $19.6 million.43 That pay package produced a CEO-to-median-employee compensation ratio of 316 to 1.43 Because the bulk of that equity is structured around performance conditions, Neri's personal wealth is designed, in principle, to align with shareholder returns. In practice, that alignment depends on the specific performance benchmarks the board selects and how demanding those targets are—details contained in the proxy statement's compensation discussion that investors should examine directly rather than take on faith.
Where management delivered
HPE's operating record demonstrates areas of clear competence. Management steered through the 2020 to 2022 pandemic supply disruptions without the operational breakdowns that hobbled several hardware peers, scaled the Aruba franchise after acquisition, and brought the Juniper transaction across the finish line despite a federal antitrust challenge. Moreover, fiscal 2026 brought a sequence of upward guidance revisions: in December 2025, management projected revenue growth of 17% to 22% and non-GAAP diluted earnings per share between $2.25 and $2.45; by September 2026, those targets had risen to 34% to 37% top-line growth and $3.75 to $3.85 in earnings per share.51
Deleveraging also progressed ahead of schedule. Bolstered by roughly $1.4 billion in gross proceeds from selling its remaining stake in Chinese joint venture H3C, HPE exited the third quarter of fiscal 2026 with net leverage at 1.8 times—beating its two-times leverage target more than a year early.244 Concurrently, management committed to returning at least 75% of fourth-quarter free cash flow to shareholders.1
Where management strained trust
A thorough management audit, however, must balance operational achievements against strategic missteps and shifting corporate disclosures.
The March 2025 reset. Just five months after concluding fiscal 2024 with confident forward guidance, leadership slashed its outlook, openly citing internal execution failures in server pricing and inventory management.21 While the candor was commendable, the sudden operational lapse underscored the vulnerability of server forecasting.
The guidance windfall. The dramatic upward revisions of fiscal 2026 require similar qualification. Much of that outperformance stemmed from an industry-wide memory shortage that management neither forecasted nor expects to endure. At the October 2025 analyst meeting, leadership outlined targets of at least $3.00 in non-GAAP earnings per share and free cash flow exceeding $3.5 billion by fiscal 2028.19 Thanks to cyclical component pricing dynamics, the company now expects to surpass both benchmarks in fiscal 2026, two full years ahead of schedule.1 While that windfall bolstered near-term results, it reflects external market conditions rather than structural operating improvements, complicating efforts to model HPE's normalized earnings power once supply bottlenecks ease.
Narrative drift on the calls. Comparing earnings call transcripts over an eighteen-month span illustrates that volatility. In March 2025, management attributed server margin contraction to internal pricing miscalculations, aggressive peer discounting, and inventory valuation markdowns.21 By September 2026, responding to questions from Morgan Stanley analyst Erik Woodring regarding traditional server profitability, Chief Financial Officer Marie Myers explained that record quarterly margins reflected a favorable deal mix and cautioned that server pricing would normalize as industry supply constraints loosened.2 Both explanations were forthright, and both point to the same structural reality: server profitability remains hostage to broader commodity cycles rather than insulated by proprietary pricing power. Management deserves credit for frankness, but investors cannot treat peak cyclical margins as a permanent baseline.
The ARR fade. Corporate disclosure choices tell a similar story. As detailed in the examination of GreenLake, Annualized Revenue Run-Rate served as the company's marquee transformation metric across fiscal 2025, only to recede from headline earnings releases within a year of closing the Juniper acquisition.271
The leverage reversal. For years, executive leadership highlighted balance-sheet conservatism and regular share repurchases as foundational pillars of its capital allocation strategy. The Juniper transaction sharply altered that posture, requiring substantial balance-sheet debt, the issuance of mandatory convertible preferred stock slated to dilute common equity in 2027, and a dramatic curtailment of share buybacks—totaling just $447 million through the first nine months of fiscal 2026.631
The activist in the room
In April 2025, Elliott Management disclosed an investment of more than $1.5 billion, establishing itself as one of HPE's five largest shareholders.45 By July, HPE had entered into a formal cooperation agreement: Robert Calderoni, chairman of KLA, joined the board to chair a newly formed Strategy Committee, and Elliott secured the right to appoint a board representative.46
An activist presence offers an illuminating lens on corporate governance. An activist investor naturally focuses on the core structural questions confronting HPE: Does the capital-intensive storage division warrant ongoing balance-sheet support following substantial asset impairments? Should the lower-margin, cyclical server operation be formally separated from the high-margin networking franchise? And has executive leadership set multi-year financial targets calibrated to be comfortably beaten rather than to stretch operating performance? Under the cooperation pact, Elliott agreed to a standstill provision barring a proxy contest for at least one year.45 Whether the Strategy Committee ultimately recommends substantive portfolio changes or merely ratifies the existing roadmap remains a central governance question for institutional investors.
What emerges is a leadership team capable of agile tactical execution and refreshing candor during operational setbacks, but one whose overarching strategic narrative has pivoted repeatedly—from consumption-based infrastructure to artificial intelligence and on to enterprise networking—while its recent financial crest owes substantial credit to macro supply dynamics outside its control. That interplay between strategic intent and cyclical reality frames the broader lessons HPE's corporate evolution offers to enterprise technology investors.
X. Playbook: Business, Operating, & Investing Lessons
Lesson 1: Revenue tells investors where a company is busy; profit pools tell them where it is valuable
For most of its operating history, HPE was characterized by its largest top-line contributor: an enterprise server manufacturer. Yet evaluating the business through segment operating profit reveals a fundamentally different enterprise: a high-margin networking business anchored to a large, cyclical server operation. Investors who assessed HPE strictly by headline revenue consistently misjudged where its economic value resided. The broader investing principle applies across enterprise conglomerates: map the underlying profit pools first, then examine whether capital allocation follows them. At HPE, management eventually aligned balance-sheet capital with those higher returns, but only after spending a decade committing resources to lower-margin segments like storage.
Lesson 2: Changing how customers pay does not change what they are buying
GreenLake transitioned customer procurement from upfront capital expenditures to monthly consumption billing. That operational flexibility offers genuine utility to enterprise IT departments and helps smooth top-line revenue volatility. However, unless an offering delivers proprietary software that creates durable switching costs, the underlying unit economics remain tethered to the physical hardware and captive financing that support it. Multiple expansion stems from controlling the software control plane—the orchestration layer that dictates enterprise purchasing decisions, as Mist AI and Aruba Central achieve in networking—rather than repackaging the financing structure.
Lesson 3: In a gold rush, check who sells the gold
Surging enterprise demand for artificial intelligence has generated substantial order volume for server manufacturers. Yet when the overwhelming majority of a system's bill of materials consists of proprietary silicon sourced from concentrated semiconductor suppliers, the systems integrator effectively functions as a pass-through distributor for those suppliers' margins. Management's explicit disclosure that accelerated AI systems dilute consolidated gross margin confirms that structural dynamic. Durable economic rent in computing infrastructure accrues to whoever controls the scarcest input—and inside HPE's portfolio, proprietary high-speed networking fabric represents a far scarcer asset than standard server assembly.
Lesson 4: Conglomerates are fixed by subtraction, then by focused addition
Conglomerate sprawl cannot be resolved through internal synergy initiatives. HP restructured by dividing in two, pruning underperforming assets through tax-efficient spin-mergers, and subsequently deploying balance-sheet capital under Antonio Neri to scale its highest-margin business. The lesson is not that corporate divestitures automatically create aggregate shareholder wealth—as investors who held distributed shares in DXC Technology and Micro Focus experienced firsthand. Rather, a management team's discipline in shedding low-return, distracting businesses is often the prerequisite for making targeted balance-sheet additions succeed.
These operational principles set up the central valuation question: given that structural reality, what does the core investment thesis actually rest on, and what operational signals would invalidate it?
XI. The Investment Spine: Bull vs. Bear, Critical KPIs, & The Forward Verdict
The bull case
A networking company in a server company's clothing. The bull case posits that the Juniper acquisition gives HPE a networking business on track to exceed $10 billion in annual revenue, with customer orders expanding significantly faster than recognized revenue and artificial intelligence data center wins—including the Oracle collaboration—establishing a foothold in Arista's core market.2 If segment operating margins reach management's target range of 25% to 28% and networking supplies roughly 60% of operating profit, the argument follows that public markets will eventually value HPE like a specialized networking infrastructure provider rather than a commodity hardware assembler.1920
Hybrid cloud pragmatism. Enterprise IT leaders are reassessing off-premises public cloud migrations, constrained by data sovereignty mandates, escalating data egress expenses, and security requirements to run artificial intelligence models behind corporate firewalls. HPE's customer base of roughly 52,000 GreenLake organizations and triple-digit order expansion in Private Cloud AI reflect early traction in that enterprise repatriation trend.2
The enterprise AI wave. As artificial intelligence shifts from foundation model training—dominated by hyperscale cloud operators—to private model inferencing within corporate data centers, HPE's global reseller channel, direct field service, and on-premises engineering become stronger competitive assets. Leadership cited more than 1,200 internal artificial intelligence use cases, including over 300 active in production, as a commercial roadmap for enterprise customers navigating that transition.2
The financial momentum. Management's preliminary fiscal 2027 framework projects revenue growth between 13% and 17%, non-GAAP diluted earnings per share growth of 16% to 20%, operating margins of 14% to 15%, and at least $5 billion in free cash flow—an outlook that excludes any potential upside from AMD's Helios platform.12
The bear case
The windfall reverses. The central counter-thesis warns that the gross margin expansion achieved in fiscal 2026 is fundamentally cyclical rather than structural. Non-GAAP gross margin expanded from 31.5% in fiscal 2025 to 40.4% in the third quarter of fiscal 2026, propelled by contract repricing during an industry-wide memory shortage.51 Leadership has explicitly cautioned that margins will moderate toward historical levels.2 If upstream memory supply normalizes faster than anticipated and server manufacturers resume aggressive price competition, the Cloud & AI segment could surrender those margin gains, jeopardizing the fiscal 2027 financial framework.
Integration friction. Harmonizing Aruba and Juniper across network operating systems, enterprise sales forces, and management consoles presents substantial execution risk. Engineering attrition, roadmap ambiguity, or sales disruption could create commercial openings for Cisco in enterprise campus accounts and Arista in cloud data centers. The divergence between 36% order expansion and 10% normalized revenue growth in networking highlights operational conversion bottlenecks alongside commercial demand.2
Balance sheet leverage and equity dilution. Although net leverage has moderated, total outstanding debt stood at approximately $20.2 billion at the end of July 2026, and mandatory convertible preferred stock issued to finance the Juniper acquisition will convert into common equity around September 2027, expanding the diluted share count.631
AI commoditization. If gross margins on accelerated AI servers remain structurally compressed because semiconductor vendors capture the bulk of component value, expanding AI shipments will dilute consolidated profit margins even as headline revenue expands, while simultaneously tying up substantial working capital in high-cost processor inventory.
Weighing the evidence
Where does the empirical record leave the core investment thesis? It refutes the most ambitious claims for GreenLake: HPE has not transformed into a software business, and executive reporting has grown less transparent regarding the specific metrics required to evaluate that transition. It narrows the server moat to an opportunistic defense: HPE can pass along cost inflation during industry-wide semiconductor shortages, but its fiscal 2025 execution stumble and leadership's own forward guidance argue against durable pricing power in enterprise compute. That leaves the networking thesis intact but unproven: Aruba's operational track record is established, early post-merger Juniper metrics are promising, and artificial intelligence data center wins are tangible, but segment margins remain below long-term targets and organizational integration is ongoing.
In sum, the fundamental case for HPE rests primarily on whether it can execute as a networking enterprise, while the compute and storage businesses function as cyclical, cash-generative complements that will periodically surprise investors in both directions.
The activist stress test
An institutional investor or activist interrogating the portfolio would press management on four unresolved questions.
First, portfolio structure: if networking constitutes the enterprise's high-margin economic core, why retain it within a conglomerate tied to a server division subject to volatile memory pricing and a storage business that required a $1.4 billion goodwill impairment?18 The standard counterargument—that hardware bundling wins enterprise data center bids—remains commercially plausible but unproven in public disclosures.
Second, reporting transparency: with ARR omitted from headline earnings summaries and AI systems operating margins undisclosed, investors cannot independently evaluate the underlying durability of either recurring consumption revenue or accelerated hardware profitability.
Third, capital allocation: HPE returned just $324 million to common shareholders during its record third quarter of fiscal 2026, appropriately prioritizing rapid debt retirement; however, because the mandatory convertible preferred stock will convert into common equity in late 2027, share repurchases must accelerate materially simply to neutralize share-count dilution.231
Fourth, executive accountability: multi-year incentive compensation benchmarks calibrated prior to the memory pricing windfall will be exceeded by substantial margins, requiring the board's compensation committee to articulate clearly how it distinguishes durable operational execution from cyclical semiconductor dynamics when awarding executive pay.
The risk radar
A disciplined risk assessment identifies five external variables that directly affect HPE's operating model:
Component supply represents the most immediate variable. Neri indicated that supply constraints across DDR5 memory, NAND flash, and advanced semiconductor packaging would persist through 2027—a condition that underpins hardware average selling prices but constrains unit volume shipments and elevates the financial consequences of inventory misallocation.2
Trade policy and tariffs remain an operational hazard. Supply-chain friction and shifting import duties disrupted server margins in early 2025, contributing to the cost-reduction program enacted that March.22
Geopolitical exposure has narrowed significantly following the completed divestiture of HPE's equity stake in Chinese joint venture H3C, which removed a complex foreign regulatory and operating overhang.44
Cost of capital and debt service warrant scrutiny because HPE carries more than $20 billion in total debt obligations, though rapid operational deleveraging reduces immediate refinancing vulnerability.6
Regulatory and antitrust scrutiny has receded following the federal court's August 2026 final judgment approving the Juniper consent decree, though administrative scrutiny could re-emerge if antitrust regulators revisit behavioral compliance requirements.39
The three KPIs that matter most
1. Networking segment operating margin and normalized revenue growth. This is the central barometer of the transformation. Management committed to achieving 25% to 28% operating margins by fiscal 2028 after holding near 22% across the first nine months of fiscal 2026.201 Investors must track whether segment profitability progresses toward that band as product order backlogs convert into recognized revenue, and whether the combined sales force defends enterprise market share against Cisco and Arista.
2. GreenLake recurring revenue mix, and whether HPE keeps disclosing it. The critical issue is what proportion of recurring revenue represents high-margin proprietary software—such as Aruba Central, Mist AI, and GreenLake orchestration tools—versus financed hardware amortization and conventional hardware maintenance. The omission of ARR from headline financial summaries in fiscal 2026 obscures this dynamic, making disclosure transparency an essential gauge of strategic health.271
3. Free cash flow conversion. Free cash flow relative to non-GAAP operating profit provides the cleanest measure of whether reported net income translates into real cash or is absorbed by accelerated AI inventory, memory purchase commitments, and captive financing receivables. In fiscal 2025, free cash flow totaled just $986 million against non-GAAP diluted earnings per share of $1.94; full-year fiscal 2026 guidance projecting at least $3.75 billion in free cash flow represents a sharp operational turnaround.51 Sustaining that elevated cash conversion as memory pricing normalizes will determine whether HPE has achieved genuine structural transformation or merely capitalized on a cyclical peak.
XII. Epilogue & Forward Horizon
Eighty-seven years after two engineers pooled $538 in a Palo Alto garage, the company that carries their names bears little resemblance to what they founded—or even to what Meg Whitman left behind in 2018. Hewlett Packard Enterprise is no longer a scientific instrument maker, a personal computer giant, an IT outsourcer, or a software conglomerate. It is a focused enterprise infrastructure provider whose operating earnings increasingly stem from the switches, routers, and access points that connect distributed computing environments, anchored by a large, cyclical server business.
That portfolio shift has delivered tangible operational milestones. The Aruba acquisition demonstrated that HPE could acquire, preserve, and scale a high-margin networking franchise. The Juniper Networks transaction, cleared after an intense regulatory contest, provides the portfolio breadth required to compete across enterprise campus networks, cloud data centers, and AI infrastructure fabrics. Balance-sheet deleveraging has outpaced management's original schedule, and fiscal 2026 is on track to generate the most profitable results in the company's eleven-year history.
Yet enterprise investors have navigated cyclical crests before, with record quarterly earnings that ultimately rested on supply dynamics outside management's control. The memory pricing windfall will eventually normalize, as executive leadership has acknowledged. Artificial intelligence server shipments will continue driving top-line revenue while compressing consolidated gross margins, an economic reality leadership has also conceded. When those cyclical tailwinds subside, HPE's normalized earnings power will depend on the structural durability of its expanded networking franchise and the discipline with which management deploys the free cash flow it generates.
The decisive question for investors is therefore straightforward: can Antonio Neri execute the largest networking integration in two decades and lift segment operating margins into the high twenties before the server cycle turns, or will the structural economics of merchant silicon and hyperscale cloud pull HPE back into the cyclical commodity trap it has spent a decade attempting to escape?
References
-
HPE reports fiscal 2026 third quarter results (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2026-09-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
HPE (HPE) Q3 2026 Earnings Call Transcript — The Motley Fool, 2026-09-09 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
HPE to acquire Juniper Networks to accelerate AI-driven innovation — Hewlett Packard Enterprise Newsroom, 2024-01-09 ↩↩↩↩
-
Hewlett Packard Enterprise closes acquisition of Juniper Networks — Hewlett Packard Enterprise Newsroom, 2025-07-02 ↩↩↩
-
HPE reports fiscal 2025 fourth quarter results (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2025-12-04 ↩↩↩↩↩↩↩↩
-
Hewlett Packard Enterprise Form 10-Q for the quarter ended July 31, 2026 — U.S. Securities and Exchange Commission, 2026 ↩↩↩↩↩
-
How did EDS lose $8bn in value in four years? — Computer Weekly, 2012 ↩
-
HP Takes $8.8 Billion Hit From 'Misrepresentations' By Company It Bought — NPR, 2012-11-20 ↩
-
Court rules estate of Mike Lynch and ex-business partner owe HPE over $940 million — CNN Business, 2025-07-22 ↩
-
HP Board of Directors Approves Separation — HP Inc. Investor Relations, 2015 ↩↩
-
HP to Acquire Aruba Networks (Exhibit 99.1, Form 8-K) — Aruba Networks / SEC, 2015-03-02 ↩↩↩
-
Hewlett Packard Enterprise Completes Spin-off and Merger of its Enterprise Services Business with CSC — GlobeNewswire, 2017-04-03 ↩↩↩
-
HPE announces spin-off and merger of non-core software assets with Micro Focus (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2016-09-07 ↩↩
-
OpenText Buys Micro Focus — OpenText Investor Relations, 2023-01-31 ↩
-
Hewlett Packard Enterprise Reports Fiscal 2024 Fourth Quarter Results (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2024-12-05 ↩↩↩
-
Hewlett Packard Enterprise Form 10-Q for the quarter ended July 31, 2025 — U.S. Securities and Exchange Commission, 2025 ↩↩↩↩
-
HPE details strategic and execution priorities to drive enhanced shareholder value at HPE Securities Analyst Meeting 2025 — Hewlett Packard Enterprise Newsroom, 2025-10-15 ↩↩↩
-
Insights From HPE's 2025 Securities Analyst Meeting — SoftwareReviews (Info-Tech Research Group), 2025 ↩↩↩↩↩
-
Hewlett Packard Enterprise First Quarter Fiscal 2025 Earnings Conference Call Transcript — Hewlett Packard Enterprise Investor Relations, 2025-03-06 ↩↩↩↩↩↩
-
HPE to lay off 2,500 staff as stock craters on mixed earnings results and tariffs — SiliconANGLE, 2025-03-06 ↩↩
-
HPE (HPE) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-03-16 ↩↩
-
Antonio Neri – President & Chief Executive Officer — Hewlett Packard Enterprise ↩↩
-
HPE Discover 2019: Company Vows Big Expansion of As-a-Service Business — BizTech Magazine, 2019-06 ↩↩
-
HPE chief Antonio Neri discusses as-a-service, GreenLake's impact and the critical importance of silicon — SiliconANGLE, 2022-06-29 ↩
-
HPE reports fiscal 2026 first quarter results (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2026-03-09 ↩↩↩
-
HPE is acquiring SD-WAN provider Silver Peak for $925M — SiliconANGLE, 2020-07-13 ↩
-
HPE to Acquire Nimble Storage (Exhibit 99.3, Form 8-K) — Hewlett Packard Enterprise / SEC, 2017-03-07 ↩
-
HPE to Acquire Supercomputing Leader Cray (Exhibit 99.1, Form 8-K) — Hewlett Packard Enterprise / SEC, 2019-05-17 ↩
-
Hewlett Packard Enterprise announces pricing of public offering of mandatory convertible preferred stock — Hewlett Packard Enterprise Newsroom, 2024-09-10 ↩↩↩↩
-
HPE Announces Sale of Its Remaining H3C Stake for $643 Million — Yahoo Finance ↩
-
European Commission Clears Proposed Acquisition of Juniper Networks by HPE — European Commission, 2024-07-31 ↩
-
Justice Department Sues to Block Hewlett Packard Enterprise's Proposed $14 Billion Acquisition of Rival Wireless Networking Technology Provider Juniper Networks — U.S. Department of Justice, 2025-01-30 ↩↩
-
HPE and Juniper Networks reach settlement with U.S. Department of Justice — Hewlett Packard Enterprise Newsroom, 2025-06-28 ↩
-
Justice Department Requires Divestitures and Licensing Commitments in HPE's Acquisition of Juniper Networks — U.S. Department of Justice, 2025-06-28 ↩↩
-
Ex-DOJ antitrust official tears into agency leadership over MAGA-friendly lobbying — The Hill, 2025-08 ↩
-
Attorney General Ellison asks to intervene in court review of alleged corrupt $14B antitrust settlement — Minnesota Attorney General's Office, 2025-10-16 ↩
-
Gibson Dunn Wins Approval of HPE's Settlement of DOJ Challenge to $14 Billion Juniper Merger — Gibson Dunn, 2026-08-14 ↩↩
-
Frontier supercomputer debuts as world's fastest, breaking exascale barrier — Oak Ridge National Laboratory, 2022-05-30 ↩↩
-
Lawrence Livermore National Laboratory's El Capitan verified as world's fastest supercomputer — Lawrence Livermore National Laboratory, 2024-11-18 ↩
-
Hewlett Packard Enterprise Fiscal 2025 Fourth Quarter Earnings Conference Call Transcript — Hewlett Packard Enterprise Investor Relations, 2025-12-04 ↩
-
Hewlett Packard Enterprise 2026 Proxy Statement (Form DEF 14A) — U.S. Securities and Exchange Commission, 2026-02-11 ↩↩
-
Hewlett Packard Enterprise sells 13.8% stake in H3C Technologies for $986.8 million — Investing.com, 2026 ↩↩
-
HPE inks cooperation agreement with activist investor Elliott — SiliconANGLE, 2025-07-16 ↩↩
-
Hewlett Packard Enterprise announces board enhancements to support ongoing transformation and drive shareholder value — Hewlett Packard Enterprise Newsroom, 2025-07-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube