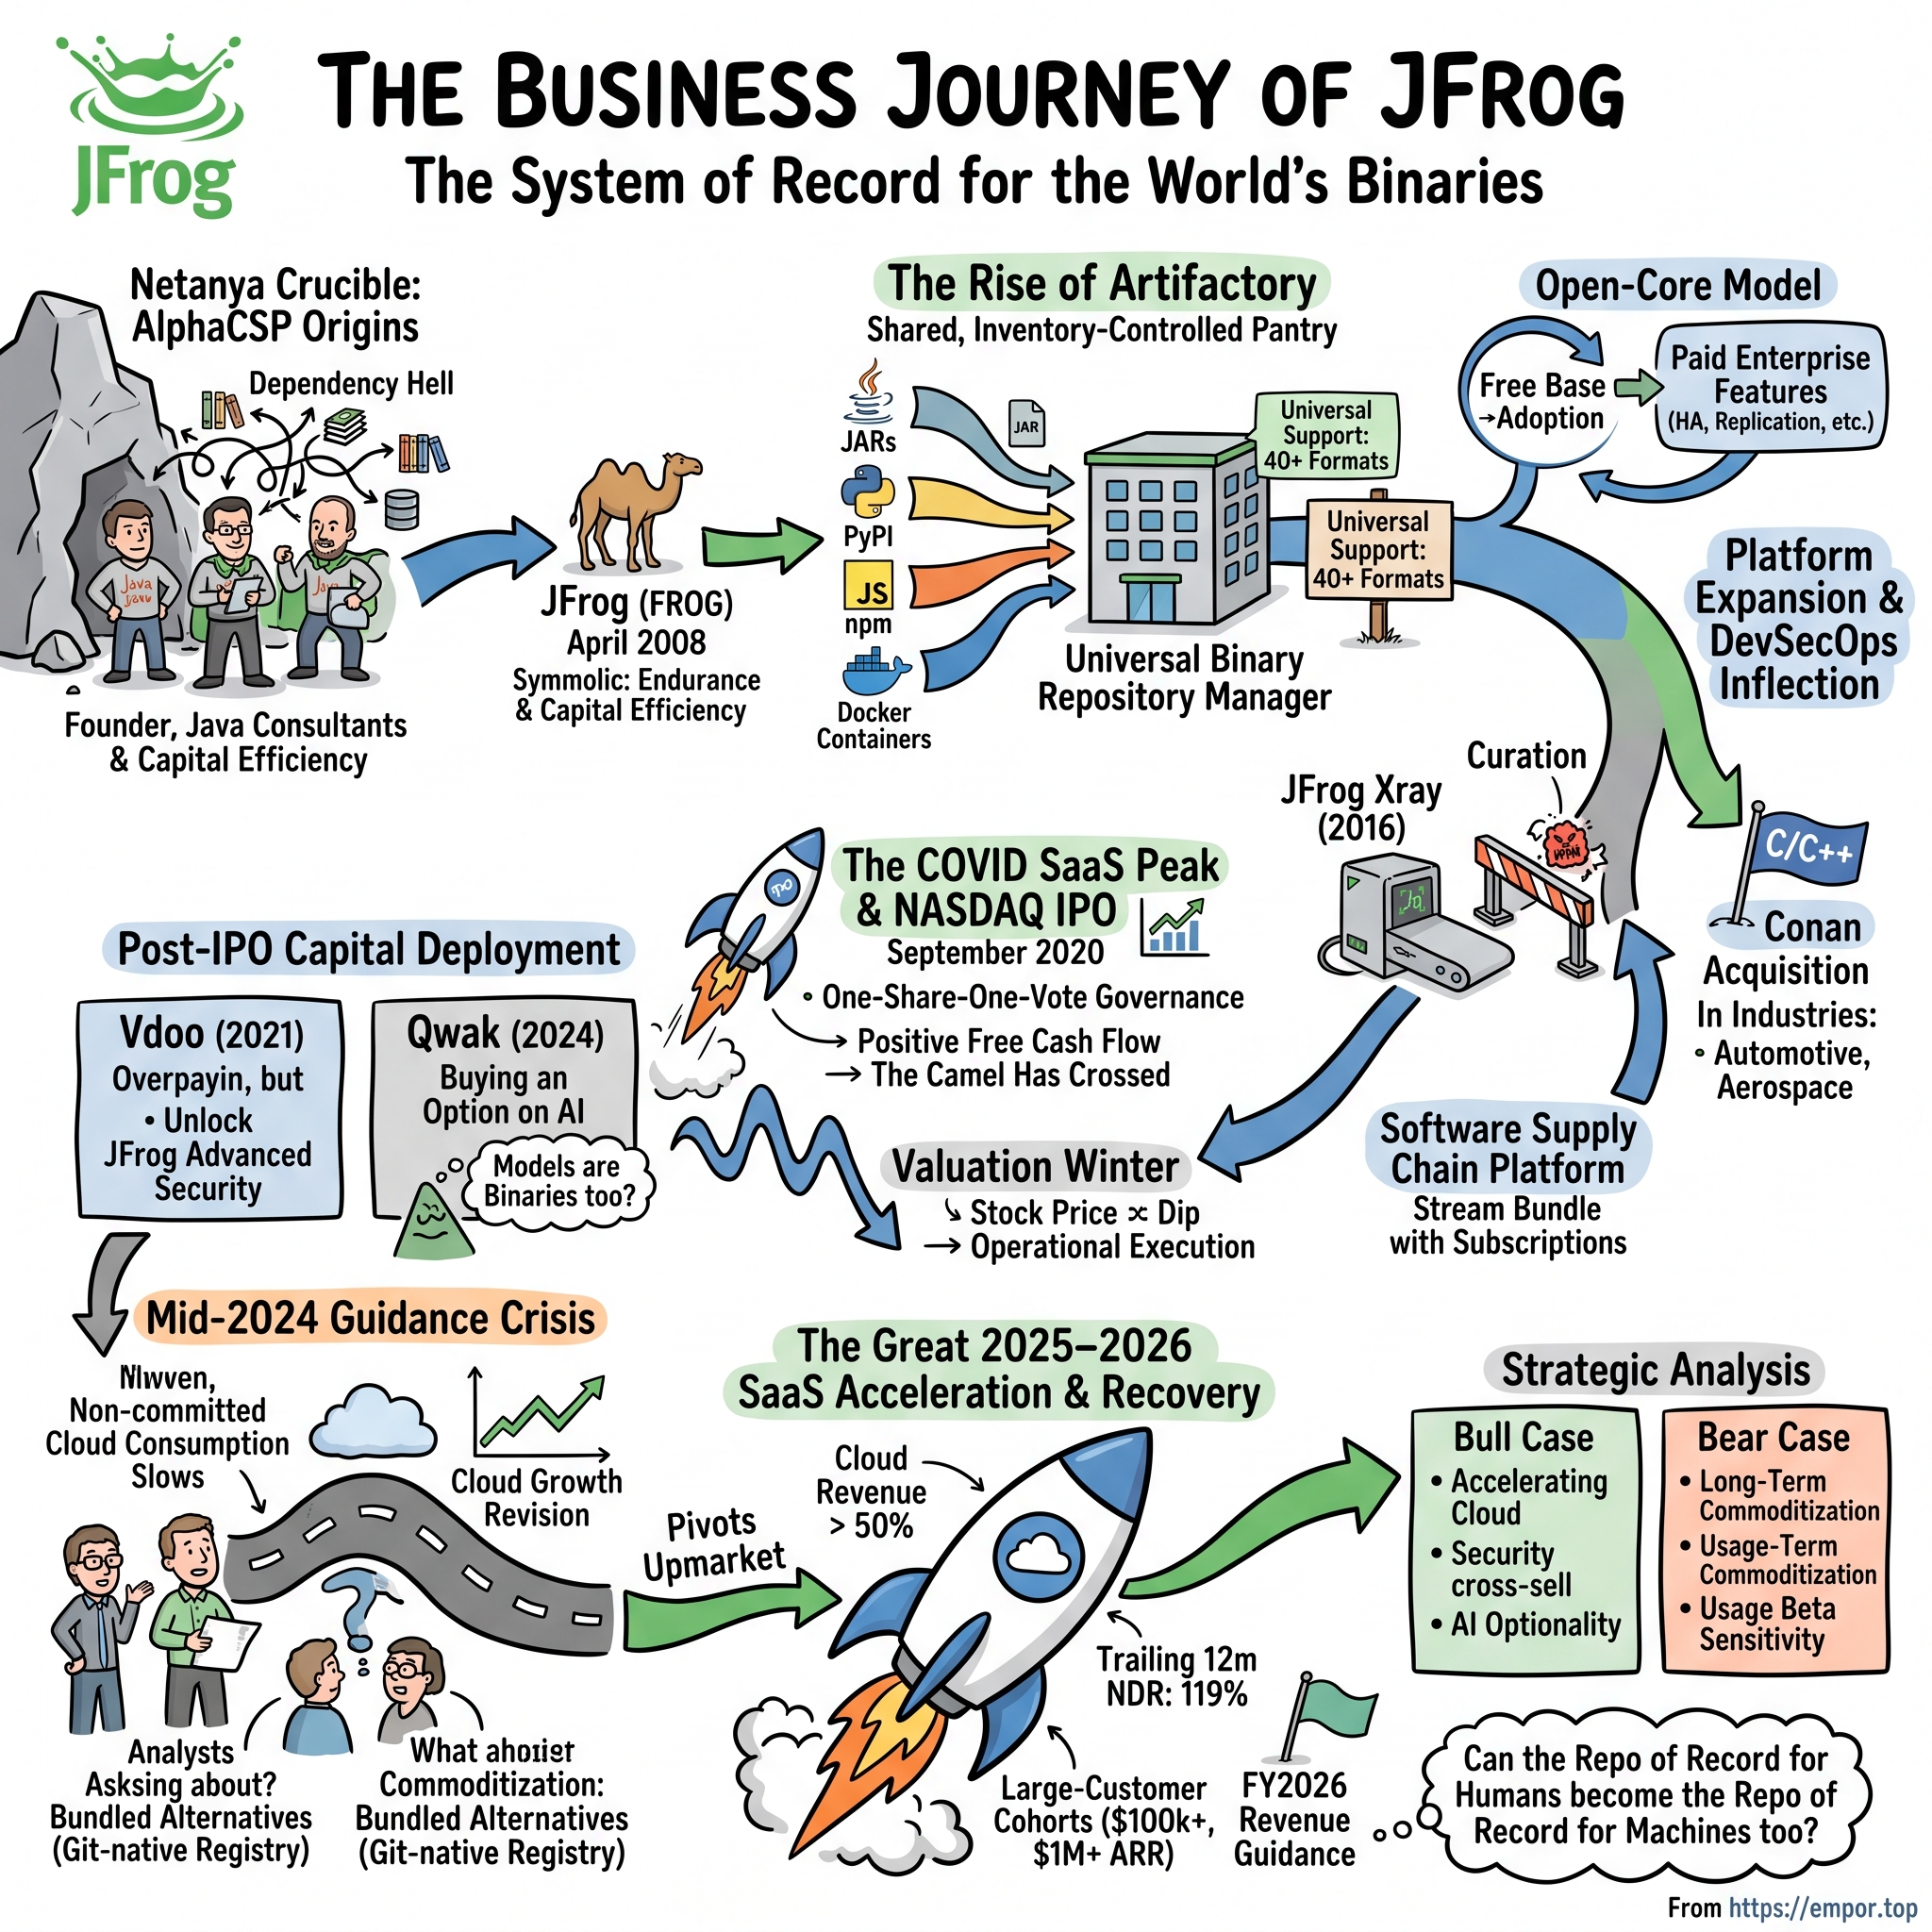
JFrog: The System of Record for the Binary and AI Era
I. Introduction & Episode Roadmap
There is a category error sitting at the heart of how most people think about software, and JFrog Ltd. has spent eighteen years quietly monetizing it.
Ask an intelligent generalist where software "lives," and they will say GitHub. That is where the code is. That is where developers argue in pull requests, where open-source projects accumulate stars, where Microsoft paid $7.5 billion in 2018 to plant its flag. Source code is the glamorous layer — it is human-readable, it is what gets screenshotted, it is what an AI coding agent writes.
But here is the thing: computers do not run source code. Not one line of it. Source code is a set of instructions written for humans to read and machines to translate. What actually executes on a server in Virginia or a car's engine control unit or a phone in someone's pocket is a binary — a compiled, packaged, machine-readable artifact. A Docker container. A .jar file. An npm package. A .dll. And increasingly, a multi-gigabyte file of neural-network weights that we have agreed to call a large language model.
Think of it like a restaurant. Source code is the recipe. The binary is the actual plated dish that goes out to the customer. GitHub is a magnificent, world-changing library of recipes. But no one eats a recipe. Somebody has to run the kitchen, track which dish went to which table, confirm that nothing in it was contaminated, and keep a record for the health inspector. That somebody, for a very large fraction of the Fortune 100, is ג'ייפרוג בע"מ JFrog Ltd. — ticker FROG on the NASDAQ, headquartered simultaneously in Netanya, Israel and Sunnyvale, California.1
JFrog's flagship product, Artifactory, is a binary repository manager. In plain terms, it is the warehouse and the customs office for every compiled thing an enterprise produces or consumes. Every build a developer runs deposits an artifact there. Every deployment to production pulls one out. Every open-source package downloaded from the public internet passes through it on the way in. That position — sitting between the world's public code and a company's production servers, touching every artifact in both directions — is what management calls being the "system of record" for the software supply chain. It is a genuinely strong position, and much of this story is about how an unglamorous caching utility grew into it.
The AI Catalyst
Which brings us to why this company is interesting right now, in the summer of 2026, rather than as a historical curiosity.
For roughly two years, the consensus fear about developer-tools companies was that AI would eat them. If a machine writes the code, why pay for the tools that help humans write code? Seat-based pricing looked structurally doomed. The entire software-tooling complex traded like a melting ice cube.
JFrog's argument is that this gets the causality exactly backwards, and the argument has an elegant mechanical logic to it. AI coding agents do not reduce the amount of software; they multiply it. And critically, JFrog does not charge by the developer seat for its core product — it charges by consumption, by the volume of data flowing through and stored in the platform. So when a developer supervising three coding agents triggers ten times as many builds as they used to, each build compiling into artifacts, each pulling in open-source dependencies, the meter runs ten times faster. On the fourth-quarter 2025 earnings call, chief executive and co-founder שלומי בן חיים Shlomi Ben Haim reached for the same metaphor repeatedly: a "tsunami of binaries."2
The early numbers are not nothing. Cloud revenue grew 50% year over year in the first quarter of 2026 and crossed half of total revenue for the first time in the company's history.3 Whether that reflects a durable structural shift or a burst of AI experimentation that normalizes is, genuinely, the central unresolved question — and one that management itself has been unusually careful not to overclaim, for reasons we will get to.
The Roadmap
This is the arc. We will start with three Israeli technologists running a Java consulting shop in the mid-2000s who got tired of watching clients waste afternoons downloading the same libraries over slow connections, and who built a cache to fix it. We will go deep on why binary management is architecturally a different problem than source-code management — because if you do not understand that, none of the competitive dynamics make sense.
Then the war. We will examine how JFrog survived being bundled against by Microsoft, GitLab, Amazon, and Google, and why "we are the Switzerland of binaries" turned out to be a more durable position than it sounds. We will walk through the capital-markets story: a 2020 IPO into euphoria, a brutal 70%-plus drawdown, and a resurgence that has taken the market capitalization to roughly $10.5 billion as of mid-July 2026.
We will scrutinize the two acquisitions that define management's capital-allocation record — Vdoo in security and Qwak in machine learning — including the meaningful gap between the headline price of the Qwak deal and what actually got recorded on the balance sheet. We will run the business through Helmer and Porter. And we will be honest about the things that would break the case: the bundling threat, the geopolitical concentration of engineering talent, the margin math of hosting other people's petabytes, and the uncomfortable fact that this company has never reported a profit under generally accepted accounting principles.
Let's start in Israel, in the years when nobody thought binaries were worth thinking about.
 Subscribe on LinkedIn
II. The Origin Story: Java Consulting and the Birth of Artifactory
Picture a mid-2000s enterprise Java development team, and picture the specific, grinding, unglamorous misery of the thing they did every single morning.
A Java application in that era was not one program. It was a Jenga tower of dependencies — dozens or hundreds of pre-built libraries, each a .jar file, each written by someone else, each with its own dependencies. To build the application, a developer's machine had to fetch every one of those .jar files from public servers scattered around the internet. On a corporate connection in Tel Aviv in 2006, that meant waiting. And waiting. And then discovering that one library had been silently updated, that the version on your machine did not match the version on your colleague's machine, and that the build now failed for reasons no one could reconstruct.
Worse was the question that made auditors nervous: which exact compiled version of this thing is running in production right now? Frequently, nobody knew. The artifact had been built on someone's laptop, copied to a shared drive, renamed, and deployed. The community had a name for this genre of suffering — "JAR hell."
Three men were watching this happen from an unusually good vantage point.
The Founders
Shlomi Ben Haim was the commercial mind. He joined AlphaCSP Ltd. — an Israeli firm that implemented Java software applications for enterprises — in October 2000, and rose to become its chief executive in June 2006, staying through mid-2009.4 AlphaCSP was itself successful enough to be acquired by the Malam Group.4 Running it gave Ben Haim something most technical founders never get: years of direct exposure to what enterprise buyers complain about, how procurement actually works, and which pain is severe enough that a CIO will write a check. He is, by consistent evidence across a decade of public appearances, a relentlessly on-message operator — a CEO who repeats a strategic phrase until it becomes furniture. That trait shows up later, both as a strength and as something an investor should discount for.
יואב לנדמן Yoav Landman was the builder. He spent 2002 through 2008 at AlphaCSP as a senior consultant working on distributed computing and enterprise build systems — precisely the domain where JAR hell was most acute.4 JFrog's own IPO prospectus describes him, flatly, as "the creator of JFrog Artifactory."4 He became and remains chief technology officer.
פרדריק סימון Frederic Simon co-founded AlphaCSP and served as its global chief technology officer.4 He became JFrog's chief architect and the company's most visible technical evangelist in the developer community — the one at conferences explaining why any of this mattered.
The three of them were not outsiders with a clever idea. They were practitioners who had personally eaten the pain, repeatedly, on client sites, for years.
A Correction to the Founding Myth
The commonly repeated version of this story says Landman wrote the first lines of Artifactory in 2008. The record suggests the code is older. The Artifactory open-source project was registered on SourceForge on August 19, 2006, created by users corresponding to Simon and Landman.5 So the honest sequence is: the open-source tool came first, in roughly 2006, born as a side project to scratch a consultant's itch; the company came later, once the tool had proven it had legs.
That distinction matters more than it seems. It means JFrog was not a business plan in search of a product. It was a product that accumulated users first and had a business bolted onto it afterward — the developer-led, bottom-up distribution model that would define everything the company did next.
The original scope was modest to the point of banality. Artifactory did two things. It sat between the developer and the public internet and cached every library it fetched, so the second developer to need it got it instantly from the local server. And it gave the team one shared, authoritative place to put the binaries they built themselves, so that "which version is in production" had an answer.
That is it. That is the whole initial product. A cache and a shelf.
The Leap
By 2008 the open-source project was being adopted inside large companies with no salesperson ever having called them. Developers were installing it because it solved their Monday morning. That is the signal the founders acted on. JFrog was incorporated under Israeli law on April 28, 2008, with all three founders serving from that month.4
They made an early structural decision that persists: the twin-headquarters model. Engineering and research sit in Netanya, Israel; commercial and executive leadership sit in Sunnyvale, California.1 The logic was that Israeli engineering talent was the company's raw material while American enterprise buyers were its market, and pretending otherwise would compromise both. As of the end of 2025, that split remained pronounced — roughly 1,800 employees globally, of whom about 950 were in Israel and about 400 in the United States.1 Slightly more than half the workforce sits in one country. Hold that thought; it becomes a genuine risk factor later.
The Early Capital
JFrog's funding history is worth dwelling on because it is unusually restrained for a company of its eventual size, and because the popular telling gets the sequence wrong.
The first institutional round came late and small: a $3.5 million Series A led by Gemini Israel Ventures, announced in June 2012 — four years after incorporation.6 For a company that would eventually list at a multibillion-dollar valuation, spending its first four years essentially self-sustaining is a meaningful data point about the founders' temperament. A $7 million Series B followed in July 2014, with VMware participating alongside Gemini.7
Only in January 2016 did the company raise real money — a $50 million Series C that brought in Scale Venture Partners, Sapphire Ventures, Battery Ventures, Vintage, and Qumra.8 (The common claim that Gemini and Scale were both early backers compresses four years and two rounds; Scale arrived at the Series C, not the Series A.) The largest private round came in October 2018: $165 million led by Insight Partners.9 The board composition reflected this lineage directly, with directors appointed by Gemini, Scale, and Insight.4
Total private capital raised before the IPO was on the order of $225 million — modest for a company that would go public two years later at a multibillion-dollar valuation. The company had been forced by its own frugality to build a product that sold itself, because for its first four years it could not afford a sales force to sell it.
That is the origin. Now we need to understand why the thing they built is architecturally harder to displace than it looks.
III. Universal Binary Management: Why This is a "System of Record"
On March 22, 2016, a developer named Azer Koçulu got into a naming dispute with a messaging company called Kik. Kik's lawyers wanted the npm package name "kik." Koçulu refused. npm, the registry that hosts JavaScript packages, sided with the company and transferred the name. Koçulu, furious at what he read as corporate overreach, unpublished every one of his 250-plus packages from npm in protest.10
One of them was called left-pad. It was eleven lines of JavaScript. It did exactly one thing: add spaces or zeros to the left side of a text string.
Within hours, large parts of the internet's build infrastructure stopped working. Node.js broke. Babel broke. Thousands of projects at Facebook, PayPal, Netflix, and Spotify could no longer be built or installed, because somewhere deep in their dependency trees, something depended on something that depended on left-pad, which had been downloaded 2.5 million times the previous month and now simply did not exist.10 npm's chief technology officer took the unprecedented step of forcibly restoring a deleted package version.10
For enterprise technology executives, the incident was a revelation with the force of a near-miss plane crash. Their production software — the systems running their banks, their factories, their hospitals — rested on a foundation of free code maintained by volunteers who could delete it on a Tuesday afternoon because they were annoyed.
And here is where the sales pitch wrote itself: organizations running Artifactory as a caching proxy were structurally insulated. Their builds pulled left-pad from their own local cached copy, not from the public registry. The upstream deletion was, to them, a non-event. The mechanism is exactly the boring one the founders built in 2006 — the local cache — and it turned out that the boring mechanism was also a risk-management control.
That is the moment binary management stopped being a developer convenience and started being a CIO-level concern. Let's unpack why it is technically distinct.
Recipes Versus Dishes
Source-code management — Git, GitHub, GitLab — is optimized for a very specific problem: tracking changes to text over time. Its central insight is the "diff." When someone edits one line in a thousand-line file, Git does not store a new copy of the file; it stores the difference. Text is small, text is compressible, and text changes incrementally. Git is a brilliant machine for versioning small mutable text.
Binaries violate every one of those assumptions.
A binary is large — a Docker container image can be hundreds of megabytes; a machine-learning model can be tens of gigabytes. A binary is immutable — you do not edit version 1.2.3 of a compiled library; you compile a new one and call it 1.2.4. And a binary is opaque — you cannot meaningfully diff two compiled files, because a one-line source change can scramble the entire output.
So the architecture has to be different. Instead of tracking deltas, a binary repository must deduplicate at the file level (store one physical copy of an identical layer used by five hundred containers), stream very large files efficiently to thousands of simultaneous machines, and replicate those files across continents so a build server in Bangalore is not pulling gigabytes from Virginia.
This is a fundamentally different engineering problem — closer to running a content delivery network than to running a version control system. Which is precisely why GitHub adding a package registry does not automatically make it a credible Artifactory replacement at enterprise scale, and why this distinction underpins the whole competitive analysis to come.
The Universality Play
The second breakthrough was scope, and it emerged from an observation about how large companies actually look on the inside.
A big enterprise does not have "a" technology stack. It has dozens. The Java team uses Maven. The front-end team uses npm. The data scientists use PyPI and Conda. The infrastructure team uses Docker and Helm. Embedded engineering uses C/C++ libraries. Each ecosystem shipped with its own incompatible registry, and each team ran its own — meaning a bank might operate eight separate binary repositories, each with its own access controls, its own backup regime, its own audit gaps, and its own person who knew how it worked and was about to change jobs.
Artifactory's proposition was consolidation: one system speaking all those dialects natively. In May 2025 JFrog announced native support for more than 40 package types; the current product documentation claims more than 50.11 The FY2025 annual report describes it as supporting "all major software package technologies."1
The strategic consequence is subtle but large. A single-language registry is a tool, and tools get swapped. A system that is simultaneously the registry for every language a company uses becomes the only place where a complete inventory of the company's compiled software exists. It stops being a tool and becomes an inventory of record. Nothing else in the building can answer the question "what compiled software do we have."
The Metadata Engine
Which leads to the third layer, and the one that converts a storage product into a compliance product.
Artifactory does not just hold files. It records, for each artifact, a structured web of facts: when it was built, by whom, from which source commit, using which build tool, containing which open-source components under which licenses, and passing which tests.1
Why does that matter commercially? Because regulators started demanding it. The "software bill of materials" — an ingredient list for software, exactly analogous to the nutrition label on a cereal box — moved from best practice to requirement in regulated industries and government procurement. A company that cannot produce, on demand, a complete ingredient list for the software it shipped has a compliance problem.
And that list is only derivable at the point where the compiled artifact and its metadata coexist. Not from the source repository, which does not know what was ultimately compiled and shipped. This is the strongest structural claim in the JFrog story, and it is a claim about physics rather than about marketing: the ingredient list has to be generated where the ingredients are assembled.
The company would spend the next decade discovering that this position — sitting on the metadata as well as the files — was worth vastly more than the storage itself. But first it had to survive some very large companies deciding they wanted the same real estate.
IV. The DevOps Wars and the Platform Pivot
Every successful infrastructure company eventually receives the same unwelcome compliment: a much larger company decides your product should be a feature of theirs.
For JFrog, that compliment arrived from two directions at once, and it arrived while the company was still private and comparatively small.
The Bundling Threat
The first flank was source-code management. Microsoft acquired GitHub in 2018 and set about turning it from a code-hosting site into an end-to-end developer platform — issues, code review, automation via GitHub Actions, and, inevitably, GitHub Packages, a binary registry. GitLab pursued an even more explicit "single application for the entire DevOps lifecycle" strategy, with a built-in package registry as a checkbox on the feature list.
The logic was obvious. If a company already hosts its source code with you and runs its build automation with you, the build output has to go somewhere — so why not here? The registry need not be excellent. It needs to be adequate and adjacent, and it can be priced at approximately zero because it is a retention feature for a much larger contract.
The second flank was the hyperscalers. Amazon Web Services launched CodeArtifact. Microsoft offered Azure Artifacts. Google had its own container and artifact registries. Their pitch was similarly gravitational: your compute is here, your storage is here, your data egress fees are lowest if everything stays here, so keep your artifacts here too.
This is the classic bundling squeeze that has killed a long list of best-of-breed infrastructure companies. The threat is not that the bundled product is better. It is that "free and already in the contract" beats "better" for the very large population of buyers whose needs are ordinary.
The Counter-Strategy
JFrog's response was to lean into the one thing none of those competitors could credibly offer: neutrality.
The argument ran roughly as follows. A cloud provider's artifact registry is, by design, an instrument of lock-in — its purpose is to make leaving that cloud expensive. But large enterprises had spent the late 2010s deliberately building multi-cloud and hybrid architectures precisely to avoid that outcome. They ran production on Amazon and analytics on Google and a regulated workload in their own datacenter, and they were not going to accept a system of record that only functioned inside one vendor's walls.
Meanwhile the source-code platforms treated registries as a secondary feature — good enough for a startup with one language and one cloud, structurally under-invested for a bank with eleven package types, cross-continental replication requirements, and an air-gapped environment for regulated workloads.
So JFrog positioned Artifactory as the cloud-neutral layer: run it on Amazon, Azure, Google, on your own hardware, or all four simultaneously, with binaries replicating between them. Ben Haim's shorthand for this, used consistently across years of public appearances, is that JFrog is "the Switzerland of binaries."12
It is a good line, and it identifies a real structural advantage. It is also worth being precise about what it does and does not protect. Neutrality is a powerful argument for the sophisticated multi-cloud enterprise with genuine complexity. It is a much weaker argument for a mid-market company running entirely on one cloud with three package types, for whom the bundled registry genuinely is good enough. The evidence over the following decade supports exactly that split reading: JFrog's growth concentrated relentlessly in large enterprises, while management repeatedly and openly acknowledged letting low-spend customers go. The moat is real at the top of the market and thin at the bottom.
M&A Building Blocks
Two acquisitions in this period show the founders' strategic instincts — one of which aged considerably better than the other.
Conan, announced November 17, 2016. JFrog acquired the open-source C/C++ package manager; the price was not disclosed.13 This looks, in hindsight, like one of the shrewdest small deals in developer tooling.
Here is why. Every modern language arrived with a package manager built in — Java had Maven, JavaScript had npm, Python had pip. C and C++, the languages that predate all of them, never got one. And C/C++ is not a legacy backwater: it is the language of embedded systems, automotive control units, aerospace, defense, medical devices, telecom equipment, and high-frequency trading. Ben Haim framed the opportunity precisely at the time, noting that the C/C++ community "is sitting on the world's largest codebase" yet "most of them simply don't have a solution for their binary management," with roughly 4.5 million C/C++ programmers globally.13
By acquiring the emerging open-source standard for that ecosystem, JFrog gained a defensible position in industries with three characteristics that make for excellent customers: extremely long product lifecycles, heavy safety regulation, and near-total inability to switch vendors casually. An automaker that must retain and audit the exact binaries in a car's braking system for decades is not price-shopping repository managers.
Shippable, announced February 21, 2019. JFrog acquired this continuous-integration company to add build automation natively; the price was not disclosed.14 The technology became JFrog Pipelines.
This one did not work, and it is worth saying so plainly because it is a useful check on the "disciplined capital allocation" narrative that management and its supporters lean on. GitHub Actions launched into general availability at almost exactly the same time and, being free and adjacent to where the code already lived, became the default for an enormous share of the market. JFrog Pipelines never achieved comparable adoption. The company placed it under feature freeze in November 2024 and set its end of life for May 1, 2026 — meaning that as of this writing, the product built from the Shippable acquisition has been formally discontinued.15
The honest reading is that JFrog tried to expand horizontally into CI/CD, met a bundling competitor with structurally better distribution, and lost. The company absorbed the loss without drama and redirected toward security and machine learning, where its binary position gave it an edge no one else had. That redirection is defensible and arguably wise. But an investor evaluating management's acquisition record should note that the scorecard is not unblemished, and that the same bundling dynamic that killed Pipelines is precisely what the bear case says could eventually pressure the core.
Meanwhile, the company was about to do something that would put all of these strategic questions under a much brighter light.
V. The IPO, the SaaS Transition, and the Market Chasm
On September 16, 2020, JFrog priced its initial public offering at $44.00 a share, selling 11,568,218 shares — 8,000,000 newly issued by the company and 3,568,218 from existing holders — and raising roughly $352 million in primary proceeds, with Morgan Stanley, J.P. Morgan, and BofA Securities leading.[^16]
Then the market got a look at it. The first trade came at $71.27, about 62% above the offer price. It closed its first day at $64.79, up 47%.16 At the offering price the company was valued at roughly $3.9 billion.17
It is worth pausing on those figures, because the version of this story that circulates in investor conversations tends to inflate them — a first-day pop "past $80" and a valuation "over $8 billion." Neither is supported by the record. The first-day high was $71.27, and the company was worth under $4 billion at the offer price.1617 The stock did climb further over the following two weeks, reaching the mid-$80s in late September 2020, but that was a subsequent run, not the IPO print. The distinction matters because the inflated version makes the subsequent drawdown look like a bubble deflating from an absurd peak, when the more accurate story is a reasonably-priced software IPO that then got swept up in the late-2020 mania along with everything else.
What was unambiguously extreme was the multiple. Against 2020 revenue, the company was trading at a valuation that only made sense in a world of zero interest rates and unlimited patience for growth. That world had about fourteen months left.
The Transition Nobody Enjoys
Underneath the market drama, JFrog was attempting one of the genuinely hard maneuvers in enterprise software: migrating from self-managed licenses to cloud consumption.
The old model was beautiful for a software vendor. A customer bought a license, installed Artifactory on their own servers, and paid an annual fee. The customer paid for the hardware, the electricity, the storage, the bandwidth, and the person who kept it running. The gross margin on that revenue approaches the margin of selling a spreadsheet — you ship bits and collect money.
The cloud model inverts the cost structure. JFrog now runs the service, which means JFrog rents the servers from Amazon or Google, pays for the storage of the customer's petabytes, and — this is the painful part for a company whose product is moving very large files — pays the data transfer and egress fees when those files move. The revenue quality is arguably better because it is recurring and consumption-linked and expands automatically with usage. But the gross margin is structurally lower, and the transition period looks ugly, because the high-margin license revenue decelerates before the cloud revenue is large enough to carry the business.
Every investor who lived through the on-premises-to-SaaS transitions of the 2010s knows the shape of this. It is a valley you have to walk through, and while you are in it, your reported metrics look worse than your underlying business.
The Chasm
JFrog walked into that valley at the exact moment the macro environment turned hostile.
As interest rates rose through 2022 and the software bubble deflated, high-multiple, unprofitable growth companies were repriced with brutal efficiency. JFrog's shares fell to around $20 by late 2022, closing the year with a market capitalization of roughly $2.14 billion — a decline of well over 70% from the highs.18
The bear case in that period had three specific and non-frivolous components. First, that the cloud transition would permanently compress gross margins as hosting costs scaled with revenue. Second, that enterprises entering a cost-optimization cycle would attack exactly this kind of consumption-based infrastructure spend — storage is the classic thing a CIO tells a team to go clean up. Third, and most fundamentally, that the bundling competitors would render the standalone repository a commodity.
The company kept growing through it — revenue rose from $280 million in 2022 to $350 million in 2023 — but growth alone does not defend a multiple when the market has decided to stop paying for growth.19
The Management Response
What management did during the chasm is, from a governance standpoint, the most informative stretch of the company's history — more informative than the good years, because anyone looks disciplined when the numbers cooperate.
They did not do the two things that destroy long-term value in this situation. They did not chase growth by acquiring unrelated revenue, and they did not sell the company. Ben Haim publicly rebuffed take-private speculation and kept the strategy pointed at the same destination.
Instead they did the unglamorous operational work: restructuring the sales organization's incentives away from license counts toward cloud consumption and platform-level packages, and pushing customers toward the top-tier "Enterprise Plus" subscription that bundles the full platform rather than selling Artifactory as a standalone tool.
That last move is the strategic heart of the recovery. Selling a repository is selling a component, and components get compared on price against free alternatives. Selling a platform — repository plus security plus governance plus distribution — changes the competitive frame entirely, because no bundled registry from a cloud provider offers the equivalent. It moves the conversation from procurement's spreadsheet to the chief information security officer's risk register.
The evidence that this worked is in the customer mix. Enterprise Plus subscriptions grew from 54% of revenue in the fourth quarter of 2024 to 57% a year later, and reached 58% in the first quarter of 2026.203 Revenue from that tier grew 36% across 2025 — meaningfully faster than the company overall.20 The company was not just growing; it was systematically converting a tool business into a platform business.
But the thing that made the platform worth buying was a capability JFrog did not have in 2020, and had to go acquire.
VI. The DevSecOps Turnaround: Moving Up the Value Chain
In December 2020, investigators disclosed that attackers had compromised SolarWinds, a network-management software vendor, and had done something that the entire security industry had theorized about but rarely seen executed at scale. They had not stolen data from SolarWinds. They had inserted malicious code into SolarWinds' build process, so that the company's own legitimate, digitally signed software updates — shipped to roughly 18,000 customers including multiple United States federal agencies — carried a backdoor.
Think about what that defeats. Every customer did everything right. They downloaded software from the legitimate vendor, over a legitimate channel, with a valid signature. And they were compromised anyway, because the poison was introduced between the source code and the shipped binary.
This is the conceptual hinge of JFrog's entire second act, so it is worth stating precisely. The dominant security tools of the 2010s — the category leader being Snyk — scan source code and declared dependencies. They read the recipe and check the ingredient list for known-bad ingredients. That is genuinely useful and catches a great deal. But it cannot, by construction, catch something that was introduced during compilation, or a malicious package substituted at build time, or a discrepancy between what the recipe says and what is actually on the plate.
The only place to catch that class of attack is by examining the finished binary. And there was a company that already had every finished binary.
The Vdoo Acquisition
On June 29, 2021 — near the absolute peak of software valuations — JFrog announced it would acquire Vdoo Connected Trust Ltd., an Israeli product-security company, for a total purchase price of $300 million, of which approximately $90 million was payable in JFrog ordinary shares and the balance in cash.2122 The deal closed on July 19, 2021.
Vdoo, founded in 2017, had raised roughly $70 million in venture capital. JFrog paid over four times the company's total funding, in a quarter when it was using its own richly valued stock as partial currency. At the time it looked like precisely the kind of bubble-era deal that generates a goodwill impairment two years later.
It did not turn out that way, and the reason is instructive. Vdoo's specialty was analyzing compiled binary artifacts — devices, firmware, finished software — to find vulnerabilities without access to source code. That is an unusual and difficult capability, and it happened to be exactly the missing piece in JFrog's architecture. JFrog had the artifacts and the metadata and the position in the pipeline; it lacked the analytical engine to interrogate what was actually inside the files.
Critically, management integrated the technology into the platform rather than running it as a standalone product line. This is the distinction between accretive and destructive acquisition behavior in enterprise software, and it is worth being explicit about why. A standalone acquired product means a separate sales motion, a separate roadmap, a separate profit-and-loss statement to defend, and an organizational tumor that eventually needs surgery. An absorbed capability makes the core product more valuable and raises the price of the existing contract. JFrog did the latter.
From Repository to Supply-Chain Security
Two products emerged from that integration, and understanding the difference between them explains the revenue model.
JFrog Curation is a gate at the entrance. Before any open-source package from the public internet is allowed into the organization, Curation evaluates it against policy — is this package known-malicious, is its license acceptable, does it meet the company's standards — and blocks it if not. It is a firewall for open-source dependencies. Notably, it is priced by seats rather than by consumption, which the chief financial officer clarified explicitly when an analyst probed the monetization mechanics.12
JFrog Advanced Security and Xray work inside the perimeter. Once artifacts are stored, these continuously scan for vulnerabilities, exposed secrets, and problematic dependency relationships, so that what eventually ships to production has been examined.
The strategic elegance is that neither product requires the customer to adopt a new workflow. The artifacts are already flowing through Artifactory. Turning on security is a configuration change and a bigger invoice, not a migration project. That is about the lowest-friction upsell available in enterprise software, and it is the single best explanation for the expansion metrics that followed.
The Evidence
By the end of 2025, JFrog's "security core" products — Advanced Security and Curation, explicitly excluding the older Xray product — comprised more than 10% of the company's ending annual recurring revenue, and 7% of full-year revenue.20 More forward-looking: security represented 16% of remaining performance obligation at year-end 2025, up from 12% a year earlier.20 Since remaining performance obligation captures contracted-but-unrecognized revenue, a rising security share indicates customers signing longer, larger commitments specifically inclusive of security.
The operating metrics moved in concert. Net dollar retention — which measures how much more (or less) the existing customer base spends this year versus last, and is the cleanest single indicator of whether a software product is genuinely embedding itself — reached 119% for the trailing four quarters as of December 31, 2025, up from 116% the prior year.1 Customers spending more than $1 million annually grew from 52 to 74 over the course of 2025, a 42% increase.20 Gross retention held at 97%, meaning almost nobody left.20
Then the market handed JFrog an unsolicited demonstration. Through late 2025, a series of large-scale attacks on the npm ecosystem — culminating in the incident the developer community named "Shai-Hulud" — compromised open-source package maintainers at scale. Management reported that customers running Curation were protected, and that demand accelerated measurably afterward.20
An analyst on the fourth-quarter call, Radi Sultan of UBS, asked the sharp version of the question: were these incidents one-time events, or should investors model a permanently elevated threat environment as a structural growth driver? Ben Haim's answer was that attackers had shifted from targeting source code to targeting the binaries and package maintainers, that coding agents had made attackers faster too, and that the trend "will only grow."2
An independent reading should hold two things simultaneously. The mechanism is real — attacks on the package ecosystem genuinely have increased, and a product that gates package ingestion genuinely benefits. But revenue driven by fear responses to news events is not the same quality as revenue driven by planned budget cycles, and a quarter of unusually strong Curation bookings following a headline breach should not be extrapolated linearly. Ben Haim, to his credit, gave the more disciplined framing when Michael Cikos of Needham asked whether one could size the revenue impact of a given attack: the only responsible way to think about it, he said, was to look at how many existing enterprise customers had not yet adopted security at all.2 That is a defensible answer, and notably not the promotional one.
Security moved JFrog up the value chain. The next act attempted something more ambitious.
VII. The AI Catalyst: Copilots, Qwak, and JFrog ML
There is a metaphor Ben Haim used on the first-quarter 2026 earnings call that captures the entire AI thesis better than any slide.
Think about photography before digital. Film was expensive. Each frame cost money to buy and money to develop, so a photographer waited for the sunset and took one careful shot. Then digital arrived, the marginal cost of an image collapsed to zero, and behavior changed completely — people now take forty shots and sort later. The number of photographs in the world exploded by orders of magnitude.
His argument is that AI has done precisely this to source code. Writing code used to be expensive and slow, rationed by the supply of human developers. With coding agents, the marginal cost of producing code has collapsed. So people produce vastly more of it.12
And here is the mechanical consequence that matters for this business: every one of those code changes, to become real, must be compiled and packaged. It becomes a binary. It pulls in open-source dependencies. It gets stored, scanned, and eventually deployed. JFrog charges by consumption. The photographs all have to go somewhere, and JFrog rents the album.
Does the Evidence Support the Thesis?
This is the part where an independent assessment has to be careful, because the narrative is seductive and the company has an obvious incentive to tell it.
The supporting evidence is genuinely strong. Cloud revenue grew 45% in fiscal 2025 to $243.3 million, then accelerated to 50% growth in the first quarter of 2026, reaching $78.9 million and representing 51% of total revenue — the first quarter in company history where cloud exceeded self-managed.203 Total first-quarter revenue was $154 million, up 26%.3 Management characterized the acceleration as broad-based rather than concentrated in AI-native customers, with the chief financial officer stating explicitly that the strength was not concentrated in one geography or industry.12
Most tellingly, management raised its full-year baseline cloud growth assumption from a range of 30–32% given in February to 33–35% in May, and lifted its net dollar retention floor from 117% to 118%.203 Net dollar retention itself reached 120% in the first quarter.3 Raising forward assumptions three months after setting them is a meaningful signal, because it is costly to reverse.
The complicating evidence is equally important, and it comes from management's own mouth. Much of the cloud outperformance came from customers exceeding their contractual minimum commitments rather than from customers signing larger commitments. Brad Reback of Stifel pushed directly on why customers would absorb expensive overages rather than negotiate a better committed rate. Ben Haim's answer was revealing: boards are demanding AI adoption top-down, nobody yet knows what steady-state usage looks like, and a chief financial officer asked to commit will ask "commit to what?" So customers accept the overage and keep the meter running.12
That is an honest answer, and it identifies the precise fragility in the thesis. Usage-over-commitment revenue is the least durable revenue in a consumption business. It is real cash today, but it can normalize if AI experimentation cools or if customers optimize. Management has been consistent and disciplined about this: guidance is built only on contracted commitments, explicitly excluding usage above minimums.203 Sanjit Singh of Morgan Stanley noted that the full-year raise was smaller than the quarterly beat, and the chief financial officer confirmed the reason — the beat was driven by uncommitted usage, which by policy does not enter guidance.12
That is genuine guidance discipline, and it deserves credit. A management team wanting to maximize the near-term narrative would have flowed the beat straight into the annual guide. This one did not. The flip side, which an investor should hold onto, is that this conservatism is also a tacit admission that management does not yet know how much of the current surge is durable.
The Qwak Acquisition, and a Correction
On June 23, 2024, JFrog agreed to acquire Qwak AI Ltd., an Israeli machine-learning operations platform founded in 2021, in a deal widely reported at approximately $230 million.23[^25]
The reported figure requires an important adjustment, and this is exactly the sort of detail that separates a headline from the accounts. According to JFrog's fiscal 2024 annual report, the actual purchase consideration recorded was $177.5 million — approximately $163.7 million in cash, 377,181 ordinary shares valued at roughly $13.4 million, and a small amount of replacement equity awards — with the acquisition closing on July 9, 2024.19 The gap between the $230 million headline and the $177.5 million recorded consideration consists of retention packages for Qwak employees — additional cash and shares vesting over three years — which accounting rules classify as post-combination compensation expense rather than purchase price.19
Two observations follow. First, the widely circulated description of this as a "$230 million cash acquisition" is wrong on both the amount and the structure. Second, the structure itself is informative: JFrog put a substantial portion of the deal value into multi-year retention for the acquired team, which is what a buyer does when it is purchasing people and know-how rather than a finished revenue stream.
Models Are Just Big Binaries
The strategic logic for Qwak is the cleanest in the company's history, and it rests on a single observation that is obvious once stated and easy to miss.
A trained machine-learning model — a set of neural network weights, whether a PyTorch checkpoint or a large language model — is a large, immutable, opaque file produced by a build process. Which is to say: it is a binary. It has the same lifecycle problems as a Docker container. Where did it come from? What data trained it? Which version is in production? Does it contain anything malicious? Who approved it? Can we reproduce it?
The machine-learning world in 2024 was answering these questions the way the Java world answered them in 2006 — badly, with files on shared drives and tribal knowledge. JFrog had spent eighteen years building the answer for a structurally identical problem.
Qwak's technology became JFrog ML, integrated into the platform rather than sold separately — consistent with the Vdoo playbook.1 The proposition is that a model should live in the same governed system of record as every other artifact, subject to the same scanning, the same access policy, the same audit trail.
There is a real economic angle here that management has been explicit about. Asked how model storage compares to traditional artifacts, Ben Haim noted that because pricing is consumption-based and models are physically far larger than conventional binaries, there is "better potential for monetizing on storage."2 A ten-gigabyte model consumes vastly more of a billable resource than a ten-megabyte library. That is a straightforward and credible mechanism — though it also means revenue becomes more sensitive to storage pricing, which is exactly where hyperscalers compete hardest.
Hugging Face, NVIDIA, and the Registry Land Grab
In March 2025, JFrog and Hugging Face — the dominant public hub for open-source AI models — announced an expanded partnership integrating JFrog's scanner into the Hugging Face platform.24 The mechanism mirrors Curation exactly: developers pull open-source models from the public hub, malicious or non-compliant models get filtered at the gateway, and approved models land in the enterprise's private repository. Ben Haim characterized Hugging Face as functioning as a top-of-funnel channel while also serving existing customers who use it as a source for externally-obtained models.2
The company then extended the same pattern into newer AI primitives with notable speed. It partnered with NVIDIA to serve as a registry within NVIDIA's enterprise AI stack, launched a registry for MCP servers — the emerging protocol layer through which AI agents interact with software systems — and, in the first quarter of 2026, introduced a registry for AI agent "skills," announced with NVIDIA.12
The underlying pattern recognition here is genuinely sharp. Each new AI primitive — models, MCP servers, agent skills — arrives as a novel artifact type that enterprises immediately need to manage, secure, and govern. And each is, structurally, another binary. As Ben Haim put it when an analyst asked about MCP registries: every software provider now ships an MCP server, and an MCP server is binary code, so customers asked for somewhere trusted to put them.12
Whether this converts into material revenue is unproven. These are new products against uncertain adoption curves, and management has not disclosed revenue attributable to any of them. What can be said is that the company has demonstrated a repeatable capability to recognize a new artifact class early and ship a registry for it, and that this capability rests on genuine architectural advantage rather than marketing. Optionality is the right word — real, but not yet in the numbers.
VIII. Management, Incentives, and Corporate Governance
There is a moment in the fourth-quarter 2025 earnings call that tells you more about this management team than any governance disclosure.
Ittai Kidron of Oppenheimer asked Ben Haim a deliberately awkward question: in a world where AI might do everything, in what way is AI a risk to JFrog? It is the kind of question that invites a defensive non-answer.
Ben Haim's response was that the industry stands "at the edge of a cliff," with credible people predicting outcomes ranging from a productivity renaissance to wholesale human replacement, and that his job was to keep the company focused and differentiated. Then the actual answer: "My biggest risk is that I will get confused and start to follow trends and not serve my enterprise with what we do best, being the system of record."2
Naming strategic drift as the primary risk, rather than a competitor or a macro condition, is a revealing self-assessment from a founder-CEO — particularly one running a company in a sector where the temptation to chase adjacent hype is overwhelming. It is also, conveniently, a risk he controls. Take it as a genuine signal of temperament, appropriately discounted.
Founder Continuity
Ben Haim and Landman have run this company in the same roles since April 2008 — eighteen years of continuity through an IPO, a business-model transition, a 70% drawdown, and a technology regime change.4 In enterprise software, where founder departure typically follows the IPO within a few years, that is unusual and generally valuable: the people who built the architecture are still deciding what it becomes.
Simon, the third co-founder, transitioned off executive duties but remains on the board.25
Shareholding and a Necessary Correction
Insider alignment at JFrog is real but requires precision, because the figures commonly cited do not match the filings.
Per the definitive proxy statement filed April 7, 2026, with ownership measured as of March 13, 2026: all executive officers and directors as a group — twelve people — held 14,340,832 shares, or 11.8% of the company.25 That group figure is accurate as commonly reported.
The individual figures are frequently misstated. As of that date, Ben Haim held 4,252,153 shares, or 3.5%; Landman held 5,701,119 shares, or 4.7%; and Simon held 3,524,466 shares, or 2.9%.25 The often-quoted "3.7% / 4.59 million shares" for Ben Haim does not correspond to any single proxy — the share count is closest to the March 2024 proxy, where he held 4,561,181 shares, but that represented 4.2% of a smaller share base at the time.25 The Vanguard Group held 7.8%, making the founders collectively a larger bloc than the largest institutional holder.25
The direction of travel is worth noting: Ben Haim's stake has declined steadily across successive proxies — 4.2% in March 2024, 3.9% in March 2025, 3.5% in March 2026.25 Some of that is dilution from share issuance; some is sustained selling.
Trading Patterns
Insider selling at JFrog has been persistent and, through the first half of 2026, substantial. Securities and Exchange Commission filings show Landman disposing of 150,000 shares on June 29, 2026 at approximately $89.99, alongside a series of smaller sales earlier that month.26 Ben Haim sold 65,999 shares on the same date at approximately $90.03, following roughly 93,000 shares across three tranches on June 8, and further sales in early July at prices between $93 and $95.27 Simon sold roughly 120,000 shares on July 1.27 The chief financial officer, the chief revenue officer, and multiple directors also sold during the period.
The charitable and probably correct reading is that this is programmatic 10b5-1 diversification by founders whose net worth is overwhelmingly concentrated in one illiquid-until-recently position, executed into strength after a very large share-price appreciation. That is rational personal finance, not a signal about business quality.
The reading an investor should nonetheless hold alongside it: the selling is broad across the executive team rather than isolated, it accelerated as the stock approached its highs, and the founders' aggregate percentage ownership has declined for three consecutive years. None of this is a governance red flag. It is simply a fact pattern worth tracking rather than dismissing.
Executive Compensation
Compensation is heavily equity-weighted, as is standard. Ben Haim's base salary was $625,000 per the 2026 proxy, with a target annual bonus of 75% of salary, and the balance of compensation delivered in performance share units and restricted stock.25 Total chief executive compensation for fiscal 2024 was $10,292,799, against a median employee figure of $213,228 — a ratio of 48.3 to 1, which is unremarkable-to-low for a United States-listed technology company of this size.28
One structural governance feature deserves mention because it is genuinely unusual for a NASDAQ-listed company. As an Israeli company, JFrog is subject to the Israeli Companies Law, which requires shareholder approval for the compensation of controlling shareholders and certain executives — including Ben Haim and Landman.28 This is a meaningfully stronger check than the advisory "say on pay" vote that United States-incorporated companies face, where shareholder disapproval carries no binding force.
Capital Allocation, Stress-Tested
Here is where an independent assessment has to push back on the tidy narrative.
The favorable case is straightforward: two significant acquisitions in eighteen years, both tightly adjacent, both integrated into the core rather than run as separate businesses, no empire-building, no unrelated diversification. Set against the enterprise-software peer group — where sprawling acquisition programs and subsequent impairments are routine — that is genuine discipline. In February 2026 the company authorized its first share repurchase program, of up to $300 million, funded from a balance sheet holding $741.2 million in cash and short-term investments as of March 31, 2026, with no debt.312
Now the pushback, and it is the single most important thing in this section.
JFrog has never reported a profit under generally accepted accounting principles. In fiscal 2025, on revenue of $531.8 million, the company reported a GAAP operating loss of $91.9 million and a net loss of $71.8 million.201 It simultaneously reported non-GAAP operating income of $92.1 million.20 That is a swing of roughly $184 million between the two presentations, and essentially all of it is stock-based compensation, which totaled $156.7 million in 2025 — up from $131.1 million in 2024 and $95.2 million in 2023.1
Stock compensation equal to roughly 29% of revenue is high even by software-industry standards, and it is growing faster than revenue. It is a real economic cost: it transfers ownership from existing shareholders to employees. The dilution is visible in the share count, which rose from approximately 99.2 million weighted-average shares in 2022 to 116.2 million in 2025 — roughly 17% dilution in three years.191
This is the activist's opening, and the argument writes itself. A skeptical investor would observe that the $300 million buyback, against $156.7 million of annual stock issuance to employees, functions substantially as an offset to dilution rather than a genuine return of capital — the company is buying back shares it is simultaneously printing. They would note that free cash flow of $142.2 million in 2025, while genuinely strong at a 27% margin, is flattered relative to GAAP earnings precisely because stock compensation is a non-cash charge.20 And they would argue that a company describing itself as disciplined while diluting shareholders by 17% over three years is using a selective definition of discipline.
The counter-arguments are fair and should be given their weight. Cash generation is real and growing — operating cash flow rose from $74.2 million in 2023 to $145.7 million in 2025.1 Non-GAAP operating margin expanded from roughly 17% in the fourth quarter of 2025 to 21.4% in the first quarter of 2026, indicating genuine operating leverage as revenue scales.203 Competing for elite engineers in Israel and Silicon Valley against companies printing their own richly valued equity is not optional. And the trajectory matters: if revenue compounds at 18% while stock compensation growth decelerates, the GAAP gap closes over time.
But an investor should treat the non-GAAP operating margin as the optimistic bound and the GAAP loss as the pessimistic bound, and understand that the truth about shareholder economics sits between them and depends entirely on whether dilution moderates from here. This is the most legitimate criticism available against an otherwise well-run company, and it should not be waved away with the observation that everyone in software does it.
IX. Playbook: Hamilton Helmer's 7 Powers & Porter's 5 Forces
Strip away the narrative and ask the only question that matters for a long-term owner: what actually stops a better-capitalized competitor from taking this business, and how do we know?
Hamilton Helmer's 7 Powers
Switching Costs — the dominant power, and it is dominant. This is the load-bearing wall of the entire investment case, and unusually, it is measurable rather than asserted.
Consider what migrating off Artifactory actually requires at a large enterprise. You must move petabytes of stored artifacts without losing any, because some of them are the exact binaries currently running in production and others must be retained for regulatory purposes — as Ben Haim noted, seven years for a bank, forty-five for an automaker.12 You must reconfigure every continuous-integration pipeline, of which a large enterprise may have thousands, each maintained by a different team. You must rebuild replication topology across regions and clouds. You must re-establish access controls and audit trails. You must preserve the accumulated metadata, or you lose the ability to answer historical compliance questions. And you must do all of this without a build outage, because a build outage means the company cannot ship software.
The measured evidence: gross retention of 97%.20 That figure — meaning roughly three of every hundred revenue dollars churned away in a year — is the most important single number for assessing this power, because it is behavioral rather than rhetorical. In a market where free alternatives are bundled into products these customers already own, 97% of revenue staying put is not explained by inertia alone. Combined with net dollar retention of 120%, the customer base is not merely staying; it is spending materially more each year.3
Scale Economies — significant and real, but narrower than claimed. Operating a globally replicated binary distribution network with high availability is genuinely capital- and expertise-intensive. A startup cannot casually replicate it. But the honest qualification is that the largest competitors — Amazon, Microsoft, Google — possess vastly superior infrastructure scale. JFrog's advantage is not raw scale; it is specialized scale, tuned to a specific workload, combined with the neutrality that prevents any single hyperscaler from serving multi-cloud customers credibly. That is a real but conditional advantage, and it should be described as such rather than as an insurmountable barrier.
Cornered Resource — moderate, and the weakest of the three. Eighteen years of accumulated engineering knowledge about universal package management and binary metadata schemas is genuinely rare, and the Conan acquisition cornered specific expertise in C/C++ dependency management. But knowledge walks. This power is real, defensible against startups, and considerably less protective against a determined hyperscaler willing to hire aggressively.
Branding, Counter-Positioning, Process Power, Network Economies — largely absent, and it is worth saying so rather than manufacturing them. There is developer mindshare, but not consumer-style brand pricing power. There is no meaningful network effect: one company's Artifactory instance does not become more valuable because another company adopts it. A rigorous assessment finds one dominant power, one significant power, one moderate power, and four that do not apply. That is a solid but not extraordinary structural profile.
Porter's Five Forces
Rivalry: High. Sonatype's Nexus remains the most direct competitor in binary repositories, with a similar architectural approach and a strong position in some enterprises. Snyk competes aggressively in developer-focused security, approaching from the source-code direction. And every hyperscaler and source-code platform offers an adjacent registry. Competition is intense and structurally permanent.
Threat of Substitutes: Moderate, and asymmetric by customer size. This is where the analysis must be careful rather than reflexive. GitHub Packages, GitLab's registry, and cloud-native registries genuinely are good enough for a great many organizations. A startup on one cloud using two package types has no reason to pay JFrog.
The critical insight is that this threat is concentrated almost entirely at the low end — and JFrog's own behavior confirms it. The company deliberately consolidated approximately 300 lower-spend customer accounts into parent entities in 2025 and openly acknowledged letting low-average-selling-price customers go to focus on enterprise.202 Total customer count of approximately 6,600 as of December 2025 is not comparable to prior years because of that methodology change — an accounting nuance worth flagging for anyone attempting to build a customer trend line.1
The strategy is explicit: cede the commodity bottom, fortify the complex top. The evidence that it is working is that customers spending over $100,000 annually reached 1,168 at year-end 2025 and 1,225 by the first quarter of 2026, representing 77% of annual recurring revenue.203 Concentration risk is low, with the top ten customers accounting for roughly 9% of revenue.1
Bargaining Power of Buyers: Moderate. Large enterprises negotiate hard, and the current dynamic of customers running over commitments while resisting larger contracts is itself a form of buyer leverage — they are declining to commit precisely because commitment is what gives the vendor pricing certainty. But 97% gross retention establishes the ceiling on that leverage: they can extract discounts, but they cannot credibly threaten to leave.
Threat of New Entrants: Low. Building a secure, universal repository supporting fifty-plus package ecosystems, with global replication and enterprise governance, is a decade-scale engineering commitment against an incumbent with entrenched switching costs. Venture capital has largely not attempted it.
Supplier Power: Moderate, and rising in importance. This is the force most analyses omit and the one most relevant to JFrog's specific economics. The suppliers are the hyperscalers, who provide the compute, storage, and — critically — the data egress on which the cloud business runs. As cloud becomes the majority of revenue, JFrog's gross margin becomes progressively more hostage to the pricing of firms that also compete with it. Management addressed this directly, describing improved commercial terms with all major cloud providers during 2025 and a "stronger long-term gross margin strategy."20 Non-GAAP gross margin has held remarkably steady — 83.3% for fiscal 2025 and 83.8% in the first quarter of 2026 — even as cloud mix rose sharply, which is real evidence of cost discipline.203
But management guided to non-GAAP gross margins of 82–83% for 2026, explicitly below the current run-rate, precisely because cloud will be a larger share of revenue.3 That guidance is management telling investors, in advance, that mix shift will cost them a point of margin. It is honest, and it quantifies a structural headwind that does not go away.
The synthesis: a genuinely strong competitive position resting primarily on one exceptionally durable power, validated by hard behavioral metrics, in a market with permanent competitive pressure at the low end and a structural margin headwind from its own suppliers.
X. The Investment Spine: Bull vs. Bear Case & Key KPIs
By July 2026, the market had substantially re-rated this business. The shares traded around $86.75 on July 20, giving a market capitalization of roughly $10.5 billion, against a 52-week range of $34.05 to $99.22 — a stock that has roughly doubled off its lows and sits near record territory. Institutional ownership stood at approximately 86% of shares outstanding across 347 filers as of the first quarter of 2026.
That re-rating means the easy money — buying a misunderstood business during a transition at two times revenue — has been made. What remains is the harder question of whether the AI-driven acceleration is structural or cyclical.
The Three KPIs That Matter
Cutting through the disclosure, three metrics carry the case. An investor tracking only these would capture nearly all the relevant signal.
1. Cloud revenue growth rate. This is the primary engine and the cleanest read on whether the AI thesis is real. It is also where the guidance-versus-reality gap is most informative: management guides on committed revenue only, so the spread between actual cloud growth and the baseline assumption measures the magnitude of uncommitted usage. A narrowing spread with rising commitments would indicate the AI surge is converting into durable contracts. Continued wide spreads would suggest experimental usage that has not yet been locked down.
2. Net dollar retention. The single best measure of whether the platform strategy is compounding. It aggregates three distinct expansion vectors — more consumption, security attach, and tier upgrades — into one number, and it is the metric that most directly tests whether switching costs translate into pricing power.
3. Customers with annual recurring revenue above $1 million. The clearest indicator of enterprise platform consolidation, and the segment where competitive advantage is genuinely strongest. This is where JFrog either wins the complex enterprise or does not.
Two secondary indicators deserve peripheral attention: gross retention, as the early-warning system for competitive displacement, where any move below the mid-90s would be a serious signal; and non-GAAP gross margin against the 82–83% guided range, as the test of whether hyperscaler cost pressure is being contained.
The Bear Case
Bundling and price compression. Microsoft can afford to give away a package registry and basic supply-chain security indefinitely, because for Microsoft these are retention features attached to a vastly larger relationship. This does not threaten JFrog's largest customers, whose complexity requirements the bundled products do not meet. It absolutely threatens the mid-market and constrains pricing at the margin. The evidence that this is already happening is JFrog's own strategic retreat from low-spend accounts — a rational response, but a retreat nonetheless. The bear's version: JFrog is being slowly compressed into a shrinking premium niche while the commodity layer beneath it is competed to zero.
Geopolitical concentration. With roughly 950 of approximately 1,800 employees in Israel, JFrog carries genuine single-country operational risk.1 The mechanism is specific rather than abstract: Israeli military reserve mobilization can remove key engineers from their posts with little notice, disrupting release schedules. This is not hypothetical — Ben Haim referenced the human toll on the Israeli team explicitly in closing the fourth-quarter 2025 call, noting the return of hostages and expressing hope for regional stability.2 The company continued executing through that period, which is meaningful evidence of resilience. But concentration risk of this magnitude does not disappear because it has been survived once.
The SaaS margin squeeze. Already quantified above: management has guided to margin compression from mix shift, and the suppliers setting the input costs are also competitors. If storage and egress pricing moves against JFrog faster than tier upgrades offset it, the model's economics degrade at precisely the moment cloud becomes the dominant revenue stream.
The dilution question. The GAAP-versus-non-GAAP gap and 17% three-year share-count growth remain the most legitimate structural criticism, and the buyback only partially addresses it.
The AI thesis could be cyclical. The most underrated risk. If the current binary surge reflects a wave of enterprise AI experimentation rather than permanent workflow change, consumption could normalize. Ben Haim himself acknowledged on the first-quarter call that not a single customer runs a fully autonomous development process, and that the current state is "more in an experimental kind of mode."12 That is candid, and it cuts directly against extrapolating the current growth rate.
The Bull Case
Neutrality is structurally defensible. The multi-cloud enterprise cannot use a hyperscaler's registry as its system of record without accepting the lock-in it spent a decade engineering away from. This is not a preference; it is an architectural constraint, and it is the reason the top of the market is not contestable by the parties best resourced to contest it.
Security is a high-margin, low-friction attach. Growing from nothing to over 10% of ending annual recurring revenue and 16% of remaining performance obligation in roughly two years validates the mechanism.20 The runway is quantified by management's own framing: most existing enterprise customers have not yet adopted security at all.2 Selling more to customers who already trust you, through a configuration change rather than a migration, is the highest-quality growth available in enterprise software.
AI artifacts represent genuine optionality. Models, MCP servers, and agent skills are all new artifact classes requiring exactly the governance JFrog has spent eighteen years building. The storage economics are favorable because models are physically enormous. The partnerships with Hugging Face and NVIDIA position the company at the on-ramps.2412 None of this is yet material to revenue — which is precisely why it is optionality rather than thesis.
The consumption model is structurally aligned with AI. Perhaps the most important point. Seat-based software companies face an existential question if agents replace developers. JFrog, charging by consumption, benefits when agents outproduce humans. Whatever else is uncertain, the direction of the AI shock to this particular revenue model is favorable.
Myth Versus Reality
Three consensus beliefs about this company do not survive contact with the filings, and correcting them sharpens the case in both directions.
Myth: JFrog IPO'd at an $8 billion valuation and the subsequent collapse was a bubble deflating. Reality: it priced at $44, valuing the company near $3.9 billion, and closed its first day at $64.79.[^16]1617 The 2022 drawdown to roughly $2.14 billion was severe, but it started from a less absurd base than the folklore suggests.18
Myth: JFrog bought Qwak for $230 million in cash. Reality: recorded purchase consideration was $177.5 million in cash and stock, with the remainder structured as multi-year employee retention that accounting treats as compensation, not purchase price.19 The company was more disciplined than the headline implies.
Myth: JFrog's acquisition record is unblemished. Reality: the Shippable acquisition produced JFrog Pipelines, which lost decisively to GitHub Actions and reached end of life on May 1, 2026.15 Management redirected competently, but the record includes a real strategic loss to precisely the bundling dynamic that anchors the bear case.
Assessing Management Credibility
The most useful test of a management team is not what it says in a good quarter but whether its story stays consistent when tested.
On that standard, the record is strong in a specific and verifiable way. Comparing the fourth-quarter 2025 call to the first-quarter 2026 call, the framing did not shift opportunistically. Both emphasized the same three drivers — cloud consumption, security attach, and Enterprise Plus adoption. Both explicitly declined to guide on usage above commitments, using nearly identical language about derisking large deals and excluding uncommitted usage.203 When a beat came in that could have been flowed through to raise the annual guide aggressively, it was not.12
Management has also been willing to give unhelpful answers. Ben Haim characterized AI adoption as still experimental at a moment when overclaiming would have been rewarded.12 When Jason Ader of William Blair pressed the chief financial officer on whether an $800 million fiscal 2027 revenue target was merely aspirational given the implied acceleration required, the answer was a redirect to 2026 execution and a note that the target "does not reflect our conservative or responsible guidance philosophy" — an acknowledgment, in substance, that the long-term model is not the operating plan.2 That is more candid than most, though an investor should note the target was neither reaffirmed nor formally withdrawn, which leaves an ambiguity worth watching.
The fair conclusion: guidance discipline is demonstrated rather than asserted, narrative consistency across calls is high, and the willingness to name uncomfortable truths is above average for the sector. The offsetting concerns are the persistent dilution, sustained insider selling into strength, and a long-term revenue target left in an undefined state.
XI. Epilogue & Surprises
Return, for a moment, to Netanya around 2006. Three consultants who have spent years watching enterprise Java teams waste their mornings waiting for library downloads decide to build a cache. Not a platform. Not a category. A cache — the least glamorous artifact in computer science, a thing whose entire purpose is to make a boring operation faster by storing a copy of something nearby.
Twenty years later that cache underpins a business worth roughly $10.5 billion, sitting between the world's open-source ecosystem and the production systems of most of the Fortune 100.
The Lesson
The transferable insight is about where durable positions form in technology, and it runs against instinct.
The glamorous layer of any stack attracts capital, talent, and attention — and therefore attracts competition, commoditization, and bundling. GitHub is a more famous company than JFrog and always will be. But fame is not the same as defensibility. The layers that prove hardest to dislodge are frequently the ones nobody wants to work on: the plumbing, the registry, the boring system that everything else assumes is there.
JFrog's position derives from three compounding decisions, none of which looked strategic at the time. It chose the unglamorous side of the divide — binaries rather than source code — which gave it a technical problem the source-code platforms were not architected to solve. It chose universality over specialization, which converted a tool into an inventory of record. And it chose neutrality over alignment with any single cloud, which made it the only credible system of record for enterprises that had deliberately refused to pick one.
The second lesson is about integration. The two acquisitions that worked — Vdoo and Qwak — worked because they were dissolved into the core product rather than preserved as separate businesses. The one that failed, Shippable, failed because it attempted horizontal expansion into a market where a bundling competitor had structurally better distribution. The pattern is consistent: buy capabilities that make the existing position more valuable; do not buy adjacent markets where someone else owns the entry point.
The Big Surprise
The genuine surprise in this story is the AI reversal, and it is worth stating carefully because it is easy to overstate.
Through 2023 and 2024, the consensus fear was that AI would destroy developer-tools companies. If machines write the code, the tools that help humans write code lose their reason to exist. That fear was coherent, and for seat-priced businesses it may yet prove correct.
What the consensus missed was a distinction it did not think to make: the difference between tools that help write software and infrastructure that stores and governs the software once written. AI attacks the first category and feeds the second. More code produced means more binaries compiled, more dependencies pulled, more artifacts stored, more scanning required, more governance demanded — and JFrog charges by the volume of exactly those things.
The company most exposed to the fear that AI would eat software tooling turned out to be positioned on the receiving end of the flood. As Ben Haim noted in closing 2025, the argument the company had made for fifteen years — that the binary, not the source, is the primary asset — was being validated by the very technology investors feared.2
But the appropriate posture is measured rather than triumphant, and management's own words support that. Not a single customer runs a fully autonomous development pipeline.12 Much of the current cloud surge is uncommitted usage that has not yet converted to contracts.12 The AI artifact registries are unproven as revenue. The bundling pressure at the low end is real and permanent. The company still does not earn a GAAP profit, and the gap between its two sets of books is substantial and growing in absolute terms.
What can be said with confidence is narrower and more useful than the narrative: JFrog occupies a structurally defensible position in a layer of the technology stack that is becoming more important rather than less, its customers demonstrably do not leave, they demonstrably spend more each year, and the direction of the AI shock to its particular revenue model is favorable rather than hostile. Whether the current rate of acceleration persists is genuinely unknown — and management, to its credit, has said so more clearly than most.
The recipe has never been more abundant. Somebody still has to run the kitchen, plate every dish, and keep the record of what went out.
References
-
JFrog Ltd. Form 10-K for the Fiscal Year Ended December 31, 2025 — SEC.gov, 2026-02-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JFrog Fourth Quarter and Fiscal Year 2025 Financial Results Call Transcript — JFrog Ltd., 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩
-
JFrog Announces First Quarter 2026 Results (Form 8-K, Exhibit 99.1) — SEC.gov, 2026-05-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JFrog Ltd. Prospectus (Form 424B4, IPO) — SEC.gov, 2020-09-15 ↩↩↩↩↩↩↩↩
-
Artifactory Open-Source Project Registration — SourceForge, 2006-08-19 ↩
-
JFrog raises $3.5m led by Gemini Israel Ventures — Globes, 2012-06-27 ↩
-
JFrog Closes $7 Million Series B Round — PR Newswire, 2014-07-16 ↩
-
JFrog Takes Big Leap Forward With $50 Million Round — TechCrunch, 2016-01-20 ↩
-
JFrog Secures $165 Million Investment to Lead Universal DevOps in the Enterprise — Insight Partners, 2018-10-04 ↩
-
How one developer just broke Node, Babel and thousands of projects in 11 lines of JavaScript — The Register, 2016-03-23 ↩↩↩
-
JFrog (FROG) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-05-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JFrog Acquires Conan, Bringing DevOps to C/C++ — PR Newswire, 2016-11-17 ↩↩
-
JFrog Acquires Shippable, Delivers Complete DevOps Pipeline Automation from Code to Production — PR Newswire, 2019-02-21 ↩
-
JFrog Pipelines Deprecation and End of Life — JFrog Documentation ↩↩
-
JFrog Stock Pops On First Day Of Trading — Crunchbase News, 2020-09-16 ↩↩↩
-
From $3.9 billion IPO to $7 billion today: JFrog's steady climb back to the top — Calcalist (CTech) ↩↩↩
-
JFrog (FROG) Market Capitalization History — StockAnalysis.com ↩↩
-
JFrog Ltd. Form 10-K for the Fiscal Year Ended December 31, 2024 — SEC.gov, 2025-02-14 ↩↩↩↩↩
-
JFrog Announces Fourth Quarter and Fiscal Year 2025 Results (Form 8-K, Exhibit 99.1) — SEC.gov, 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JFrog to Acquire Vdoo to Deliver End-to-End Continuous Security from Development to Device (Form 8-K, Exhibit 99.1) — SEC.gov, 2021-06-29 ↩
-
JFrog buys security co Vdoo for $300m — Globes, 2021-06-29 ↩
-
JFrog buys Israeli AI co Qwak for $230m — Globes, 2024-06-25 ↩
-
JFrog and Hugging Face Team to Improve Machine Learning Security and Transparency for Developers — JFrog Ltd., 2025-03-04 ↩↩
-
JFrog Ltd. Definitive Proxy Statement (Schedule 14A) — SEC.gov, 2026-04-07 ↩↩↩↩↩↩↩
-
Form 4 Statement of Changes in Beneficial Ownership, Yoav Landman — SEC.gov, 2026-07-01 ↩
-
Form 4 Statement of Changes in Beneficial Ownership, Shlomi Ben Haim — SEC.gov, 2026-07-10 ↩↩
-
JFrog Ltd. Definitive Proxy Statement (Schedule 14A) — SEC.gov, 2025-04-07 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube