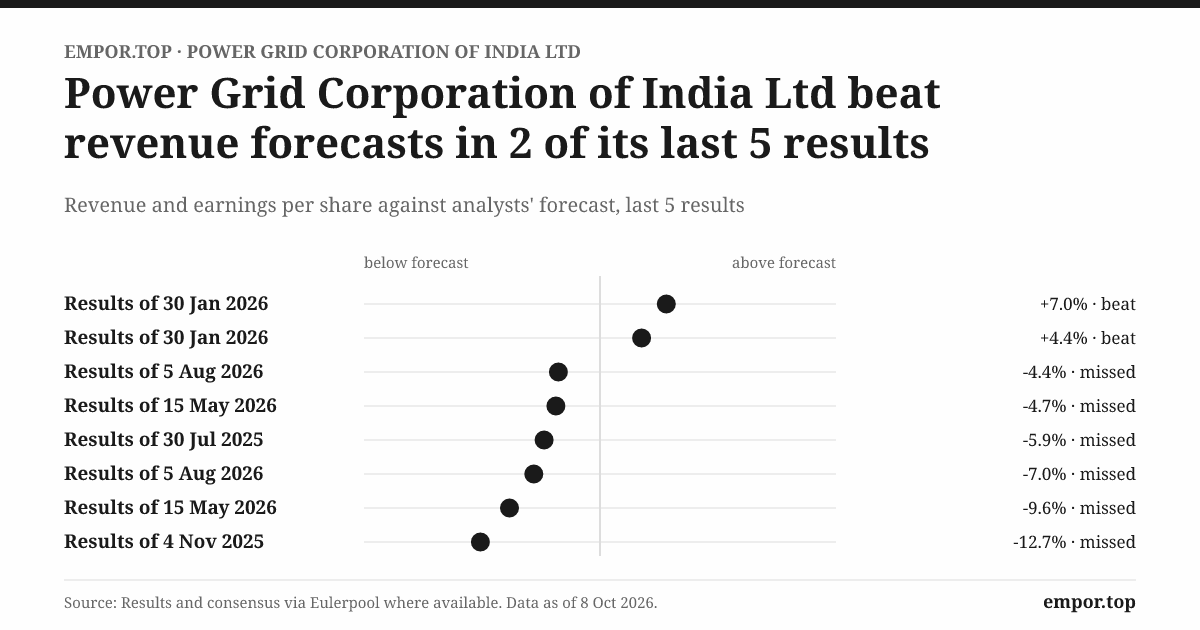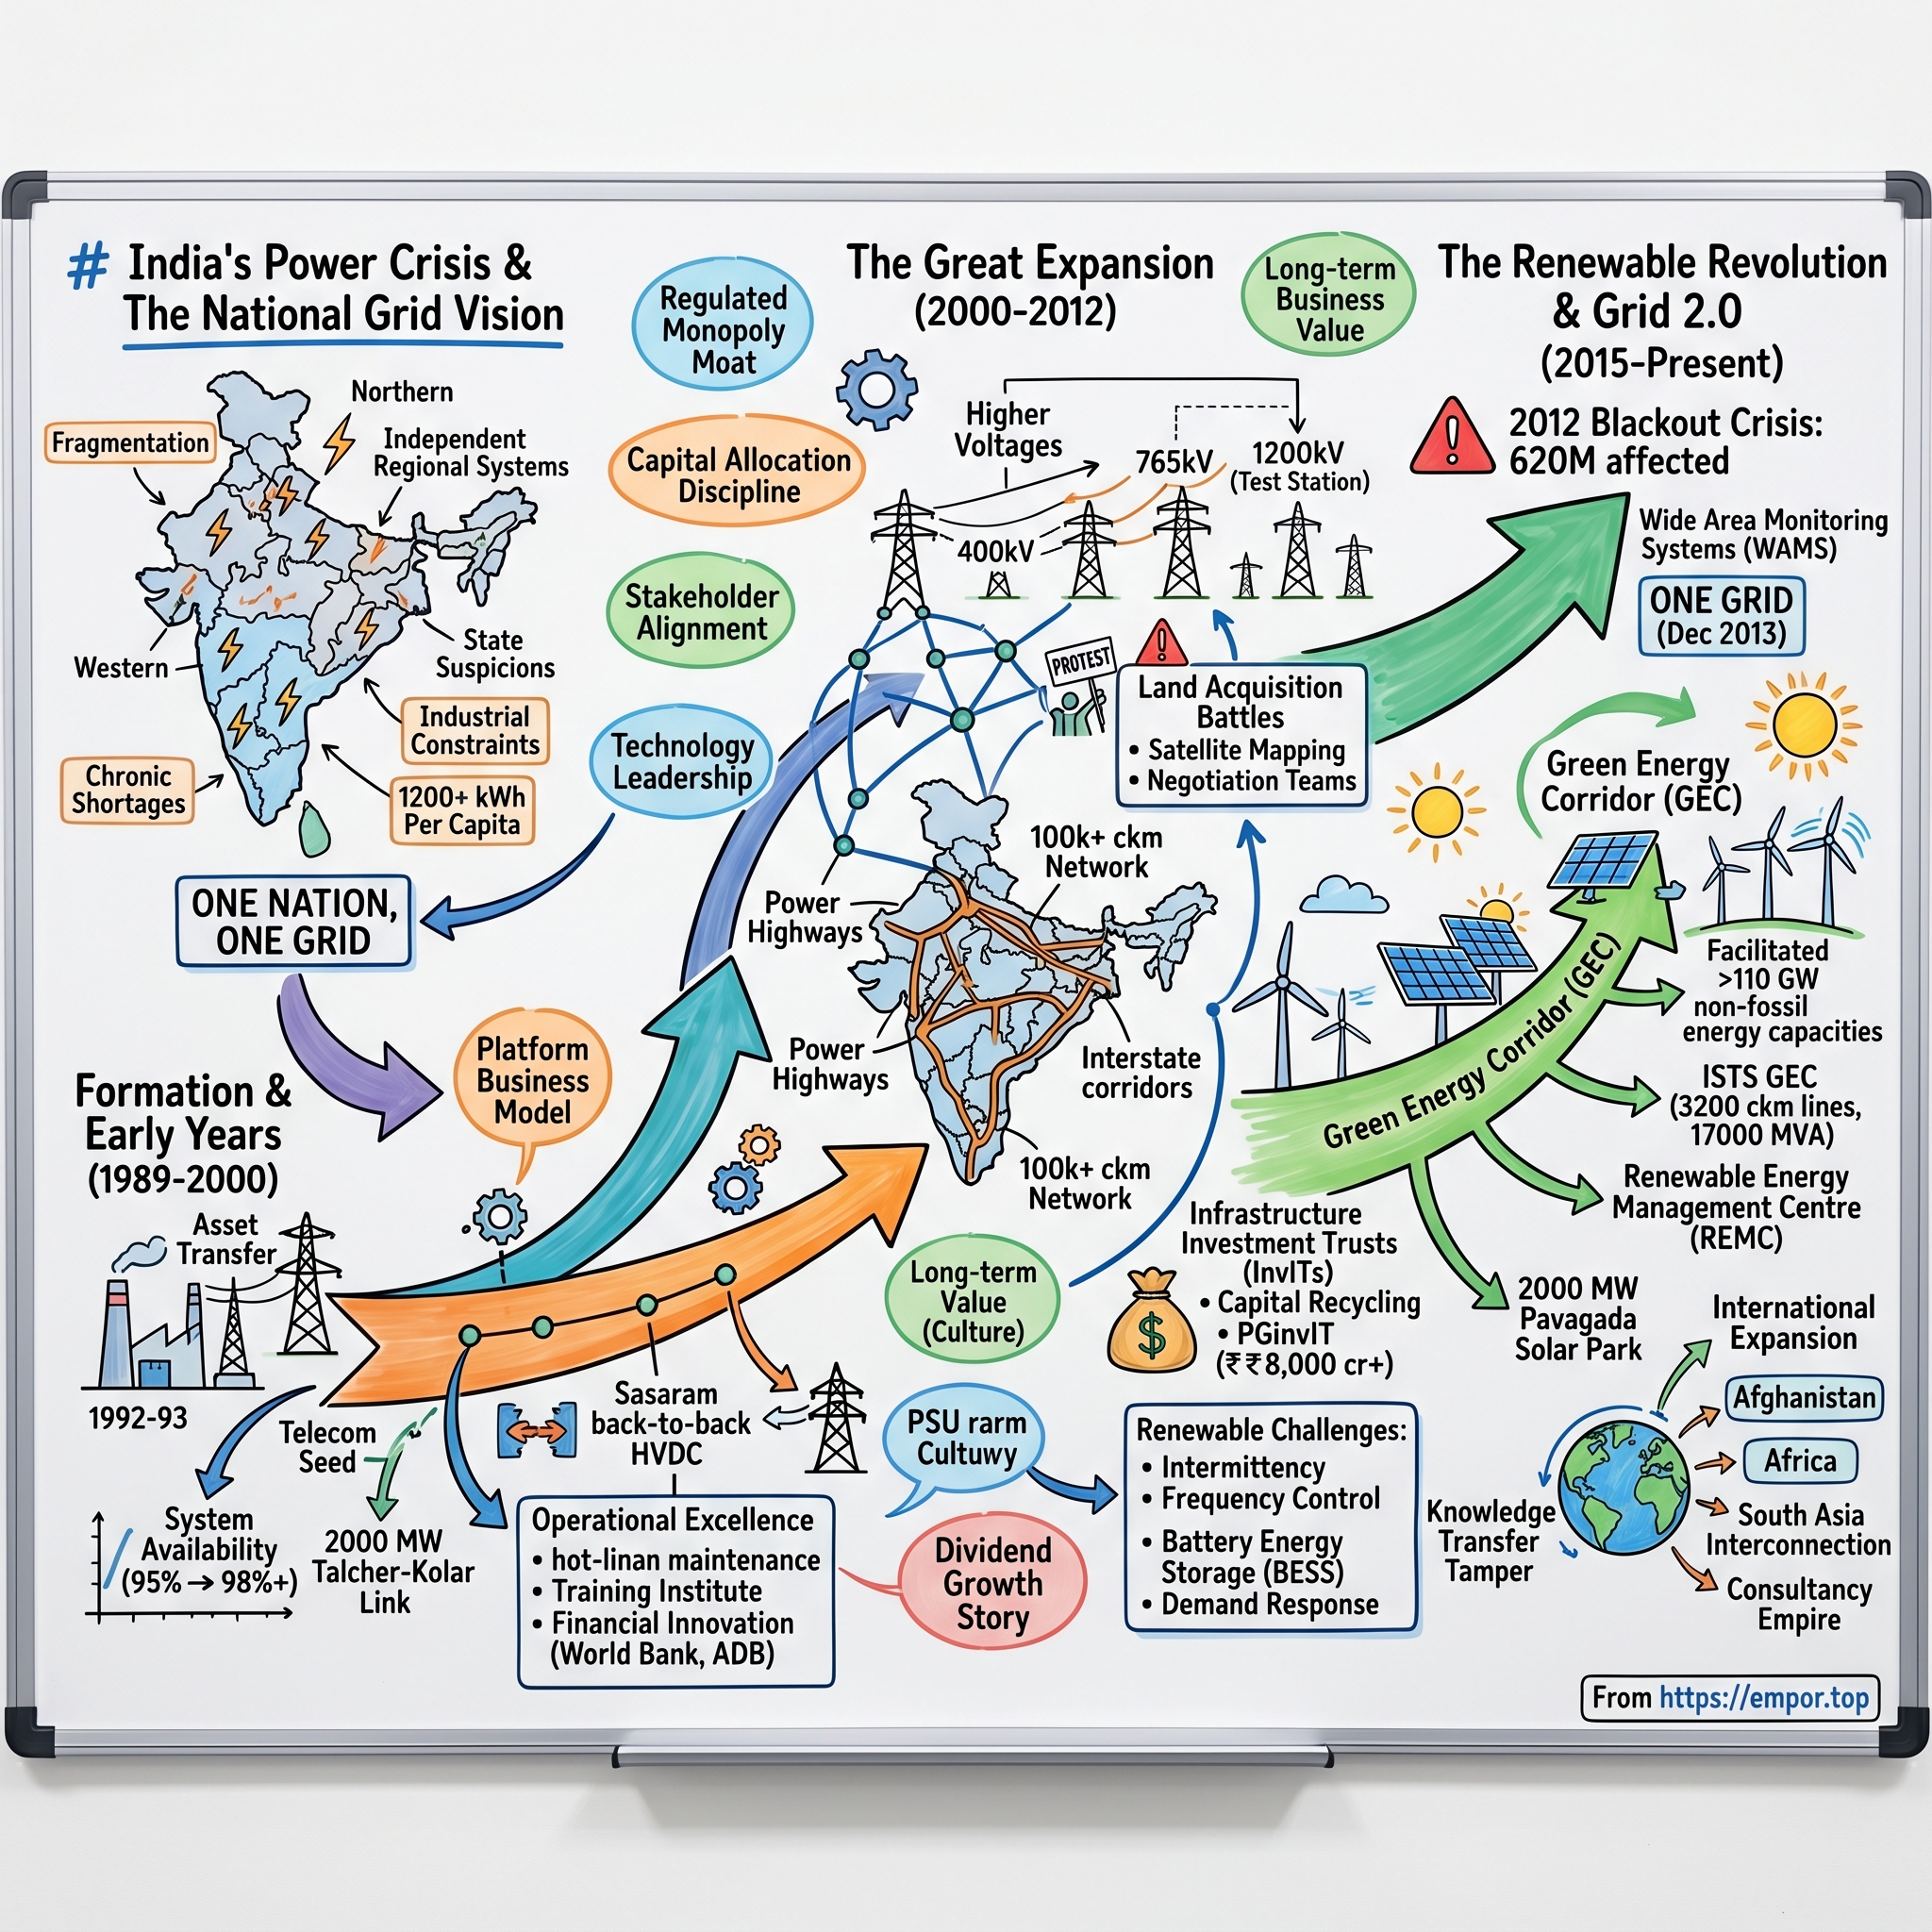
Power Grid Corporation of India: The Sovereign Toll Road of Indian Electrons
I. The Tollbooth on 1.4 Billion People
At about half past two in the morning on July 30, 2012, the Northern Grid of India fell over. Lines tripped, generators disconnected themselves to stop damage, and the cities of the north went dark. Engineers restored most of it within hours. Then, at around one in the afternoon the next day, it happened again, and this time the collapse did not stop at the edge of the north. It ran east into Bihar, West Bengal and Odisha and north-east toward Assam, until three of India's five regional grids had gone down together.2 More than 600 million people lost power. That was roughly half of India and close to one in eleven people alive. Trains stopped between stations. Miners were trapped underground in West Bengal until the lifts could be restarted. Traffic lights went out across Delhi. It is still remembered as the largest blackout in history.
Here is the strange part. The company that owned most of the high-voltage lines that failed that week did not shrink after the disaster. It grew. Over the next decade, Power Grid Corporation of India built the corridors that turned five separate electrical islands into a single grid running at one frequency from Ladakh to Kanyakumari. It became one of the most profitable infrastructure businesses in any emerging market. On October 8, 2026, the market values it at about ₹2.38 lakh crore, roughly $24.6 billion.[^3] Its lines were available to carry power about 99.8% of the time, year after year.[^2]
To understand why that is not a contradiction, it helps to think of Power Grid as a toll road where the toll is paid whether or not cars drive on it. The company does not generate electricity and does not sell it to households. It owns the motorways that move bulk power between states, and the regulator pays it for keeping those motorways open, not for the traffic. A recession, a cool summer or a collapse in coal prices barely touches its revenue. What matters is how much it has built, whether the lines are ready, and what return the regulator allows on the money it put in.
The cash tells the same story more bluntly. Over the twelve fiscal years to March 2026, Power Grid reported about ₹1.42 lakh crore of net profit. Over the same years, its operations generated about ₹3.3 lakh crore of cash, more than twice its profit.1 That gap is not a trick. A transmission tower is depreciated over decades, so each year the accounts charge a large cost that does not leave the bank, and the cash piles up underneath the reported earnings. For a long-term investor, this is the first fact to hold: the reported profit understates how much money comes through the door, and the real question is always what the company does with it.
For thirty years the answer was simple. The government nominated Power Grid to build a line, the regulator approved the cost, and the company earned a fixed return on its equity in that line. That arrangement is ending. New interstate lines are now auctioned, and Power Grid must bid against Adani, Sterlite and Tata on price, like everyone else. The sovereign toll road is being asked to compete for its own future.
Three questions run through the rest of this story. The first is whether Power Grid can keep earning returns on equity in the high teens as auctions replace nominations, because auctioned projects pay less and carry cost risk the old ones never did. The second is whether India's renewable build-out, which needs more than ₹2 lakh crore of new transmission, will force the company to cut its dividends and stretch its balance sheet, or whether there is more slack in it than the market assumes. The third is whether the sharp improvement in how fast state power distributors pay their bills is permanent, or a temporary effect of a 2022 rule that forced them to clear old dues in instalments that are now running out.
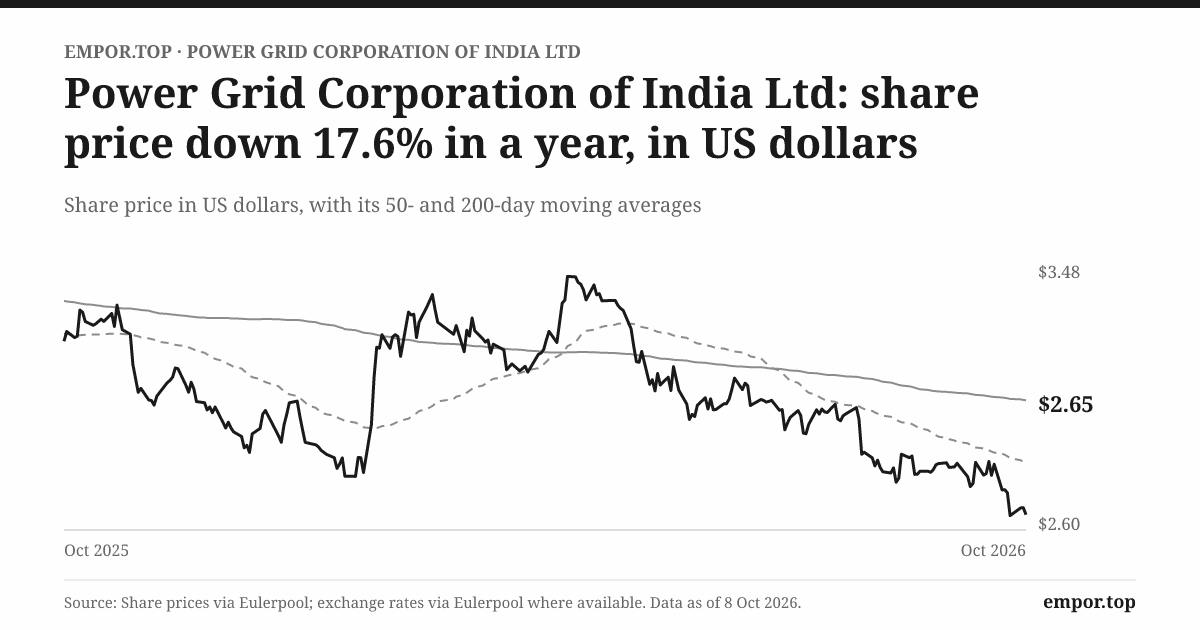
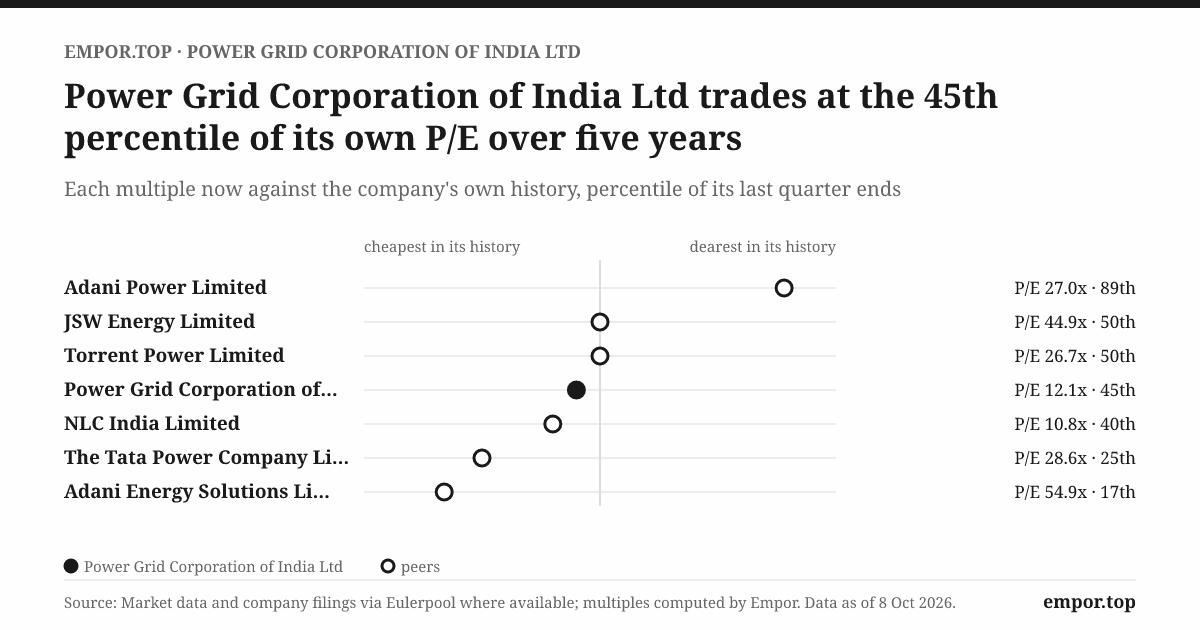
Tonight, Power Grid carries the bulk of India's interstate power, with rating agencies crediting it with roughly 84% of interstate transmission capacity.3 The stock trades at about 12 times trailing earnings, below its own five-year median of almost 14, with a dividend yield of about 3.5%.[^3] It has also just swung back into a heavy spending phase. That price says investors see a safe, slow utility whose best years of returns are behind it. The story of how it got here suggests the truth is more interesting, and starts with a country whose electricity could not cross a state line.
 Subscribe on LinkedIn
II. The Anatomy of Chaos: Five Fragmented Islands (1989–2000)
Picture India's power system in the late 1980s as five neighbouring kingdoms that did not trade. The north, the west, the south, the east and the north-east each ran its own grid. Inside each one, State Electricity Boards generated, transmitted and sold power, and most of them did it badly. Farmers received electricity free or nearly free because politicians promised it. Industry paid inflated tariffs to make up the difference. Theft and line losses swallowed a large share of what was generated. The boards ran losses, borrowed to cover them, and paid their suppliers late or not at all.
The geography made it worse. India's coal sits mostly in the east, in the fields of Bihar, Odisha and what is now Jharkhand. The demand was in the north and the west, where the farms, factories and fast-growing cities were. In a functioning market, the east would have sold its surplus west. But the regional grids were not synchronised, meaning their alternating current did not rise and fall in step. Connecting two grids out of step is like coupling two trains moving at different speeds: something tears. So the east could have spare power on the same evening that Delhi was running rolling cuts, and nothing could move it across.
In 1989 the Government of India made a decision that shaped everything that followed. It incorporated a new company, first called National Power Transmission Corporation and soon renamed Power Grid Corporation of India, and gave it the transmission lines that the big central generators had built to carry their own output.1 NTPC, the coal giant, NHPC, the hydro company, and NEEPCO in the north-east handed over their high-voltage networks. Over the following years the new company took over operation of the regional load dispatch centres too.
Why split transmission from generation? Because whoever owns the road can decide who gets to drive on it. A generator that owned the only line out of a coal belt could block a rival's power, or charge it whatever it liked to pass through. A separate transmission owner, paid the same whichever plant's electrons flowed, had no reason to favour anyone. That is the founding logic of Power Grid, and it matters today: it is exactly the logic the government invoked in 2026 when it decided Power Grid itself had become too close to the planning of the grid, a decision this story will come to.
The early years were technical warfare and political grind. State boards did not want to give up control of lines crossing their territory. The engineers had to find ways of moving power between grids that were not in step. The answer was high-voltage direct current, which sidesteps the problem because direct current has no rhythm to match. At Vindhyachal, on the border between the northern and western regions, Power Grid's predecessors commissioned a back-to-back HVDC station, which takes alternating current from one grid, turns it into direct current, and immediately turns it back into alternating current in step with the other grid.[^2] It works like a gearbox between two engines turning at different speeds. Similar links followed between other regions. They were expensive and could carry only limited amounts of power, but for the first time a megawatt could cross a regional border without risking the collapse of both sides.
The bigger threat was money. Power Grid's customers were the same state boards that could not pay anyone. By the late 1990s, the boards owed central public sector companies tens of thousands of crores, and the dues were growing faster than anyone could collect them. A transmission company whose customers do not pay is not an annuity; it is a lender of last resort with towers. The question at the end of the decade was whether the central government would let its own companies drown in state arrears, or invent a way to make the states pay. The answer would turn Power Grid from a fragile public works department into the cash machine it became.
III. The Architect of Return: The CERC Tariff Settlement (2000–2010)
In 2001 a committee chaired by Montek Singh Ahluwalia, then a member of the Planning Commission, was asked to clean up the mess. Its recommendation was blunt. The accumulated dues of the state boards to central power companies would be securitised: converted into tax-free bonds the states issued, with surcharges partly waived, so the old debts became tradable paper rather than a permanent grievance. To stop the same thing happening again, the Government of India, each state government and the Reserve Bank of India signed what became known as the Tripartite Agreement. If a state failed to pay a central power company, the central government could deduct the money from the state's share of central funds held at the Reserve Bank.[^2]
It is hard to overstate what that clause did. It meant Power Grid's customers were not really the state boards. In the last instance, they were the states' own transfers from the Centre. A utility that would otherwise have been lending to some of the weakest credits in India was now, in effect, lending against the Indian state. The proof is in the record: across the two decades since, Power Grid's receivables have stretched in bad years but its actual write-offs of unpaid bills have been negligible.[^2] That is not good collection work. It is architecture.
The second pillar arrived with the Electricity Act of 2003, which gave legal force to the Central Electricity Regulatory Commission and made it the body that sets tariffs for interstate transmission.4 The commission's tariff regulations, renewed in five-year blocks, turned Power Grid's business into something close to a formula.
The formula is worth walking through slowly, because the whole investment case rests on it. When Power Grid completes a regulated line, the commission treats the project as funded 70% by debt and 30% by equity, whatever the actual mix. The company then gets back, through its tariff, four things. The first is its interest cost on the debt. The second is depreciation, which returns the capital over the life of the asset. The third is operating and maintenance expenses, set at normative levels. The fourth is a return on the equity portion, fixed for most of the company's history at 15.5% after tax, and grossed up for the corporate tax rate so that the tax bill also passes to customers.4 Even currency swings on foreign loans pass through, so a weaker rupee does not dent profit.[^2]
Now notice what is missing. Nothing in that formula depends on how much power flows through the line. The tariff is paid on availability: if the line stands ready to carry power, the company earns its full charge. Below a normative availability of 98%, the charge is cut; above it, the company earns an incentive.4 Power Grid has run its system above 99.8% available, which lets it collect that bonus every year, worth several hundred crore.[^2] Imagine a landlord paid the same rent whether the tenant uses the flat or not, plus a bonus for keeping the plumbing perfect. That is the model.
Why did the regulator design it this way? Because transmission is a strange asset. A line is built for peak flows that might happen only a few hours a year, and its value lies in being there when needed, which is the moment the 2012 blackout made painfully clear. Paying it by volume would starve exactly the spare capacity a grid needs. The design was sound economics. It also happened to give Power Grid's shareholders an unusually clean bargain: every rupee of equity they put into an approved project earned a known return for decades.
The rest of the world noticed. In October 2007 the government sold shares in an initial public offering at ₹52 each, and followed in November 2010 with a follow-on offer at ₹90.1 Foreign institutions bought into what was, functionally, an Indian sovereign bond with an equity kicker: guaranteed returns on a growing asset base, backed by a payment mechanism that ran through the Reserve Bank. The return on equity was capped, but the base it applied to was set to grow as fast as India could build lines.
The weakness of the formula sits inside its strength. Profit depends entirely on how much capital the company deploys and gets approved. Stop building, and earnings stop growing. Get a cost overrun disallowed, and that money earns nothing. And the 15.5% is not a law of nature; it is a number the commission resets every five years. The company's profitability was always a gift renewed on schedule. For most of this decade, though, the bigger constraint was not the formula but how slowly India was building, and it took the worst night in the grid's history to change that.
IV. The Blackout and the Birth of "One Nation, One Grid" (2010–2015)
The second collapse, on July 31, 2012, began a few minutes after one in the afternoon. The northern states had been drawing more power than they were scheduled to for days, during a weak monsoon that sent farmers' pumps running hard. The western region was exporting heavily to cover the gap, and a few key lines between the two had been taken out for maintenance or upgrades. The load piled onto a thin set of corridors. When a protective relay on the 400-kilovolt Bina–Gwalior line tripped, the power that line had been carrying rushed onto neighbouring lines, which tripped in turn. Within seconds the northern, eastern and north-eastern grids had separated from the west and collapsed, taking tens of thousands of megawatts of generation with them.2
The official enquiry did not single out one villain.2 It found that states had overdrawn power even as the grid's frequency fell, ignoring instructions from the dispatchers to cut back. It found that the links between regions were too weak for the flows they were carrying. It found that automatic defence systems, which should have shed load in an orderly way to save the rest of the grid, were inadequate or did not act. In other words, the grid had grown faster in demand than in backbone, and nobody had the authority or the tools to force discipline in the moments that mattered.
A private company might have been ruined by that report. Power Grid was handed a mandate. The lesson Delhi drew was not that the company had failed but that India had under-built transmission, and Power Grid was the only organisation able to build at the needed scale. The government's Twelfth Five-Year Plan, already under way, put transmission at the centre, and Power Grid's annual capital spending climbed to somewhere between ₹20,000 crore and ₹30,000 crore a year.[^2]
What did that money buy? Two kinds of super-highway. The first was 765-kilovolt alternating current lines, the highest voltage in regular use in India, which can carry several times as much power as the 400-kilovolt lines they joined. The second was ultra-high-voltage direct current links running at 800 kilovolts, which move huge blocks of power over long distances with low losses. The Biswanath Chariali–Agra link carried hydro power from the north-east through the narrow strip of land near Siliguri known as the Chicken's Neck, across most of the width of the country. The Champa–Kurukshetra link, rated at 6,000 megawatts, was built to carry power from the coal plants of Chhattisgarh to the north.[^2] If the 1990s back-to-back stations were gearboxes, these were pipelines.
Then came the moment the engineers had worked toward for a quarter of a century. On December 31, 2013, the Southern Grid, the last region still running out of step with the rest, was synchronised to the national grid through a 765-kilovolt line between Raichur and Sholapur.[^2] India now had one grid at one frequency, among the largest synchronous grids in the world. The government called it "One Nation, One Grid, One Frequency." The practical meaning was more prosaic and more valuable: a surplus in Odisha could now cool a flat in Chennai.
The bill showed up on the balance sheet. By March 2015 Power Grid's borrowings had grown to about $16 billion, and its debt was more than two and a half times its equity.1 For an ordinary company that would be alarming. For Power Grid, it was the formula working as designed: the regulator assumed 70% debt in every project, so a company building fast should look leveraged, and its free cash flow was deeply negative, at about minus $2.3 billion that year.1 The real risk was not the debt but whether the regulator would approve the costs and the states would pay the tariff. Both held.
There was one more change, and it would echo a decade later. The dispatchers who run the grid minute by minute had sat inside Power Grid. After the blackout, the government accelerated their separation into a standalone company, the Power System Operation Corporation, later renamed Grid Controller of India.[^11] The reasoning was the same as in 1989. Whoever decides which lines carry power should not be the company that owns them. That principle had now been applied twice to Power Grid, and it would be applied a third time. But first came a period when the company stopped needing to spend so much, and started handing money back.
V. The Harvest Phase and the Cash Windfall (2016–2023)
There is a particular quiet that falls over a construction company when its big projects finish. The tower crews move on, the procurement teams shrink, and the finance department notices that cash is arriving faster than it is leaving. Power Grid hit that moment around 2019. The great corridors built after the blackout were coming into service one by one, and the pipeline of new nominated projects behind them was thinning. Annual capital spending, which had run at ₹25,000 crore to ₹30,000 crore, fell to around ₹9,000 crore to ₹10,000 crore a year between fiscal 2021 and fiscal 2023.[^2]
The effect on free cash flow was dramatic. From roughly minus $2.3 billion in fiscal 2015, it rose steadily until it reached about $4 billion in fiscal 2023.1 Nothing about the business had changed except that the company had stopped pouring concrete. The depreciation charges on the new lines, more than ₹12,000 crore a year, kept arriving as cash while the reported profit stayed modest.[^2] This is where that two-to-one ratio between operating cash and net profit really bit.
So where did the money go? Over the twelve years to March 2026, Power Grid produced about ₹96,000 crore of free cash flow and paid out about ₹71,000 crore as dividends, nearly three-quarters of it.1 The dividend payout as a share of profit rose from under a fifth in the mid-2010s to a peak of 72% in fiscal 2024.1 With the government owning more than half the shares, those dividends were also a reliable income stream for the national budget, which is worth remembering whenever someone asks why a state company would pay out so much. The rest went to paying down debt. Borrowings fell from about $21 billion in fiscal 2019 to about $15 billion in fiscal 2024, and debt to equity dropped from around 2.5 times to under 1.5 times.1 The stock became a favourite of income funds for a simple reason: it paid them like a bond and occasionally rose like a share.
There was also a piece of financial engineering. In May 2021 Power Grid sponsored the Powergrid Infrastructure Investment Trust, the first infrastructure investment trust floated by an Indian state-owned company. It moved five operating transmission companies it had won in competitive auctions into the trust, sold units to the public, and kept a 15% stake as sponsor.5 The logic was elegant: finished lines with locked-in tariffs are worth more to a pension fund looking for steady yield than to a builder looking for its next project, so sell them to the pension fund and recycle the cash. It was a test of whether Power Grid could become a developer that builds, sells and builds again, rather than a holder of everything forever. The company has not repeated the trick at scale since, which suggests that the trust was more a proof of concept than a new operating model.
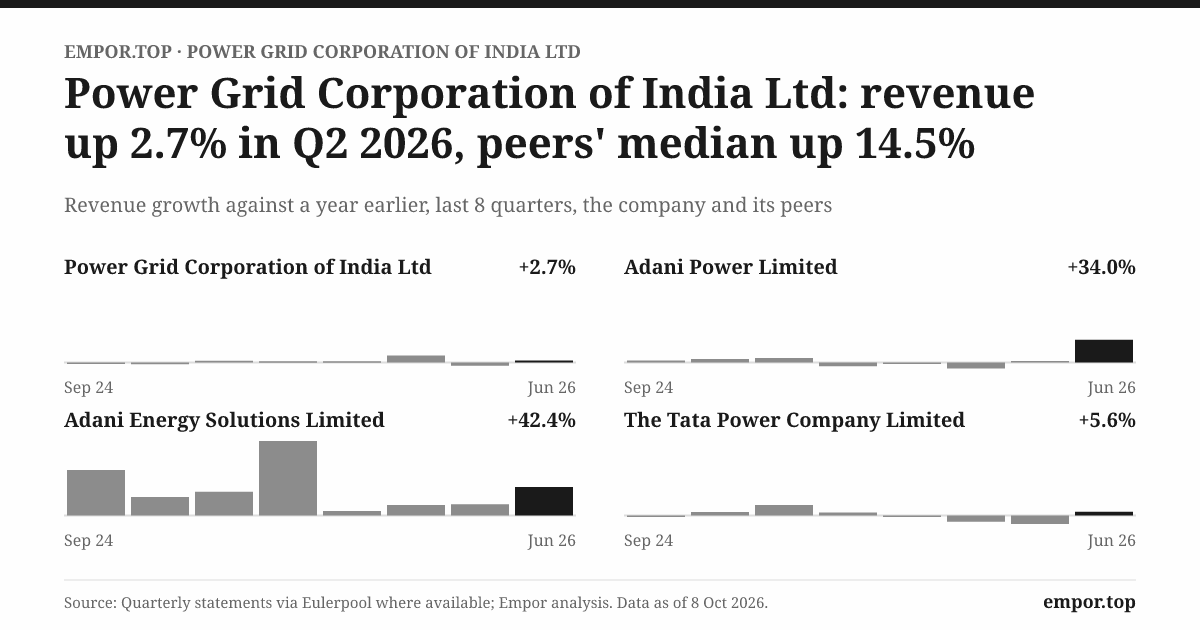
Was the harvest a sign of a mature business that had arrived, or just a pause? The company's own numbers answer that. Revenue grew at about 8.5% a year over the decade to fiscal 2026, but only about 0.8% a year over the last three of those years.1 Under cost-plus regulation, revenue is the return on yesterday's construction. If you stop building, revenue stops growing, almost to the decimal. Net profit kept rising faster, by about 6.6% a year over those three years, but largely because the company was paying less interest as it paid down debt.1 That is a one-time tailwind, not an engine. The harvest was real cash, but it was the cash of a business digesting its last big meal, not of a compounder.
The investor lesson of these years is that Power Grid's best moments for shareholders on cash were also its worst moments for growth. The two cannot both be had at once. And just as the company settled into its role as a dividend machine, the rules of how it would get its next meal changed.
VI. Competitive Disruption: The TBCB Arena and the Adani Threat
The modern transmission auction looks nothing like the old nomination. A government-appointed bid process coordinator publishes a project: a line from point A to point B, a substation, a deadline. Developers submit sealed bids, and the number they bid is a single annual transmission charge they will accept for the next 35 years, levelised so that it is the same every year.4 The lowest bid wins. The winner builds, owns, operates and maintains the line, and is paid that fixed charge as long as the line is available. If the steel costs more than expected, or a village holds up the route for two years, that is the winner's problem. There is no true-up.
India had experimented with these Tariff-Based Competitive Bidding auctions since the late 2000s, but for years a large share of interstate work still went to Power Grid by nomination. That has been progressively closed off, with competitive bidding now the default route for new interstate transmission, leaving nomination for exceptional cases such as strategic or urgent projects.4 The entitlement era, in which a new line meant a new slice of 15.5% equity return, is ending for most of the new work.
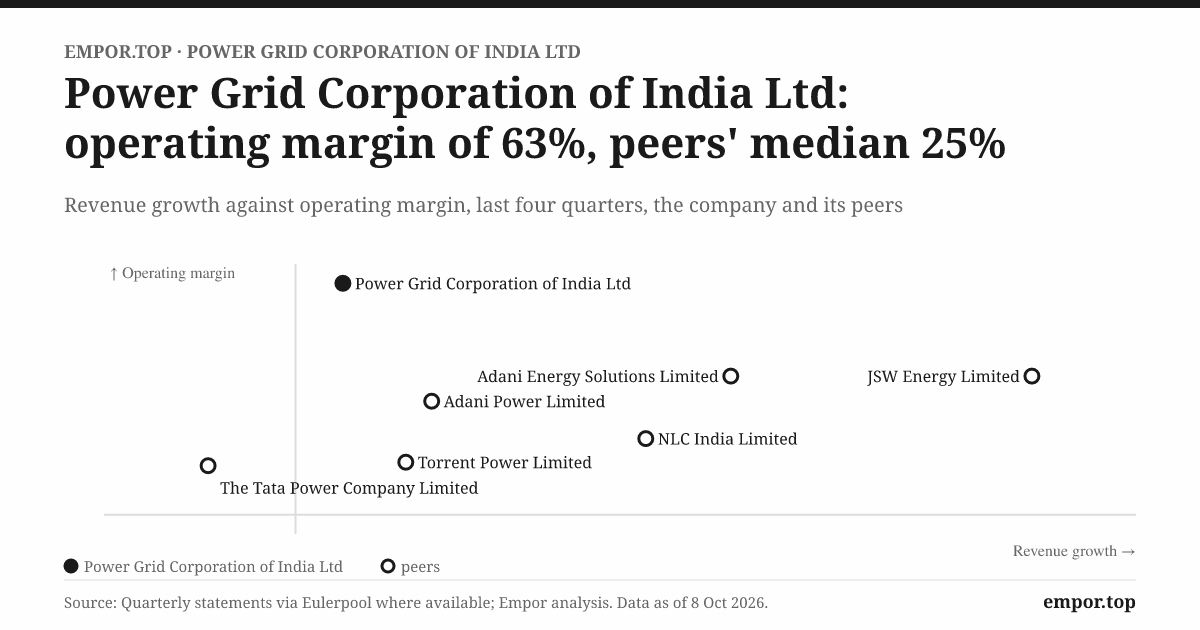
Into this arena walked the most aggressive private player in Indian infrastructure. Adani Transmission, now Adani Energy Solutions, built its network partly by winning auctions and partly by buying: it acquired the Mumbai transmission and distribution business of Reliance Infrastructure and transmission lines from the Essar group, then pushed into smart meters and city distribution. Sterlite Power and Tata Power competed too. The market priced the contest in a revealing way: Adani Energy Solutions has traded at more than 35 times earnings, while Power Grid trades at about 12.6 Investors are paying almost three times as much for a rupee of Adani's profit as for a rupee of Power Grid's, betting on growth over certainty.
How should Power Grid win a price war? Its best weapon is the price of money. A transmission line is mostly capital, so whoever borrows cheapest can bid lowest. Power Grid's bonds carry the top domestic rating, AAA from CRISIL and ICRA, while international agencies cap it at the sovereign's level.37 That rating lets it borrow at rates that, by the company's and analysts' accounts, are often 50 to 100 basis points below those of private conglomerates.3 On a 35-year asset, that difference compounds into a meaningful edge in the bid. Add procurement scale with equipment makers and three decades of building in every kind of terrain, and the company has real advantages. Its history in the auctions bears that out: Power Grid has won a large share of competitively bid interstate projects, often cited as around 40% to 50% by value in recent years.[^2]
The weaknesses are real too. Private developers move faster on land, push contractors harder on margin, and pay executives with bonuses and stock that a state company cannot match. And here is the deeper cost: the auction itself sets the return. Under nomination, Power Grid earned 15.5% on equity plus a pass-through of costs. In an auction, the winner is whoever is willing to accept the lowest return, and bids in recent years have implied equity returns in the low teens or below.3 A delay or cost overrun pushes the realised return lower still. Meanwhile the regulator trimmed the allowed return on new regulated projects to 15% for the 2024 to 2029 tariff period, from 15.5%.4
So the claim that Power Grid can beat private developers holds, but only in a narrower form. Its cheap money lets it win. It does not let it win at the old returns. Every rupee of new capital now earns less than the rupees that came before it, and the blended return on equity can only drift down as the auctioned share of the asset base rises. The number that will confirm or falsify how far it drifts is the return on equity of the company's auctioned subsidiaries against its regulated parent, which shows up in segment disclosures over the next two annual reports.
There was one more fight inside this one. Power Grid had housed the Central Transmission Utility, the statutory body that plans the interstate grid and helps decide which projects get tendered, first as a division and then as a subsidiary, Central Transmission Utility of India Limited. Private bidders had long complained that the company competing in auctions should not sit next to the planner that designs them. In March 2026 Power Grid's board approved the sale of its entire stake in that subsidiary to Grid Controller of India.8 For the third time in its history, a piece of authority was carved out of Power Grid to keep the market fair. What remains is a commercial bidder, competing on price, and about to face the largest build-out India has ever attempted.
VII. The Renewable Supercycle: Evacuating the Deserts (2024–2026)
Drive west from Bhuj in Gujarat into the salt flats of Kutch and the horizon fills with solar panels. Khavda is being built into one of the largest renewable energy parks in the world. Further north, in the Thar Desert around Bhadla in Rajasthan, solar farms already stretch for kilometres. The sun and wind in these places are superb. The trouble is that almost nobody lives there. The power has to travel hundreds or thousands of kilometres to the cities and factories that use it, which means new transmission on a scale India has not built before.
India has committed to 500 gigawatts of non-fossil generating capacity by 2030, and the Central Electricity Authority's transmission plan to connect it calls for well over ₹2 lakh crore of new interstate lines and substations.9 Power Grid's share of that is the biggest by far, and it has shifted the company back into building mode with startling speed. Cash spent on investing rose from about $1.6 billion in fiscal 2024 to $4.1 billion in fiscal 2026.1 Free cash flow, which had been $4 billion three years earlier, turned negative again at about minus $600 million.1 The harvest is over.
The engineering problem underneath is one of mismatched clocks. A solar park can go from bare land to producing power in 12 to 18 months. A 765-kilovolt line or an HVDC station takes three or four years, needs forest and land clearances, and requires thousands of towers to be planted in fields whose owners must be compensated one by one. Build the generation first and you get stranded solar farms with nowhere to send their power; build the lines first and you risk building lines to farms that never arrive. India has already seen both problems in different corners of Rajasthan and Gujarat. Power Grid is in the middle of that timing game, which is why execution, not demand, is the risk that matters.
Renewable power also changes what a grid has to do. Coal plants spin heavy turbines that steady the grid's frequency; solar panels do not. When clouds pass over a desert, output can swing sharply in minutes. To keep the system stable, Power Grid has been installing static synchronous compensators, essentially power-electronics shock absorbers that inject or absorb reactive power, and experimenting with large battery storage and with dynamic line rating, which uses sensors to let a line carry more power when the weather cools it.[^2] These investments mostly earn the same regulated or auctioned returns as the lines, so they deepen the asset base rather than open new businesses.
The capital allocation pivot is clearest in the dividend. The payout fell from 72% of profit in fiscal 2024 to about 45% in fiscal 2026.1 That is still a healthy dividend, but it is the company quietly telling income investors that the cash now has a better use. The good news is the balance sheet. Debt to equity of about 1.5 times leaves a lot of room before the company returns to the 2.5 times it carried at the height of the last cycle.1 That is the hidden slack the second central question asks about, and it is real. The bad news is that the slack will be spent on assets that, at the margin, earn less than the old ones.
There are other businesses at the edge of the picture. Power Grid strings optical fibre along the top of its towers, in the ground wire that protects lines from lightning, and leases that fibre to telecom companies and enterprises through a subsidiary.[^2] It runs a consultancy that advises other utilities at home and abroad, and it has moved into smart meters and transmission inside states, where many networks are far less efficient than the interstate grid. Each of these is profitable and some are strategically useful. Together, telecom and consultancy are only a few percent of revenue.[^2] They are worth noting and not worth paying for. The economic driver is still towers and wire, and the money will only arrive if the states keep paying for them, which for most of Power Grid's history was the thing that kept its finance team awake.
VIII. The Counterparty Paradox: The LPS Miracle and DISCOM Fragility
In June 2022 the Ministry of Power published a set of rules with a dull name and a sharp edge: the Electricity (Late Payment Surcharge and Related Matters) Rules, 2022.[^5] Their purpose was to end a game that state distribution companies had played for decades. A distributor short of cash would simply stop paying generators and transmission companies, knowing that cutting off a state's power was politically unthinkable. The suppliers became involuntary lenders, carrying months of unpaid bills at no interest.
The rules changed the game in two ways. First, they took the mountain of old, overdue bills and converted it into instalments. A distributor could pay its legacy dues in up to 48 monthly instalments, provided it never missed one.[^5] Second, they set a hard rule for current bills. A distributor that did not pay within the deadline faced automatic regulation of its access to power: it could be blocked from buying on the short-term power exchanges and have its supply curtailed, with the sanctions escalating as the default continued.[^5] For the first time, not paying had an immediate, mechanical cost that a chief minister could not negotiate away.
The effect showed up quickly in Power Grid's books. Debtor days, the number of days of revenue sitting in unpaid bills, had peaked at about 132 in fiscal 2022 as the pandemic stretched state finances.1 By fiscal 2025 they had fallen to about 65, roughly half.1 In fiscal 2026 they rose back to about 92, still well below the peak.1 The cash released was substantial, and part of the reason fiscal 2023 and 2024 were such strong years for operating cash flow.
There is a structural reason Power Grid bears less of this risk than a generator might. Interstate transmission charges are pooled. Every user of the interstate grid pays into a national pool according to a formula, and the pool pays the transmission owners.4 Power Grid therefore does not depend on any single state, and a late payer's shortfall is spread across the system rather than falling on one line. Behind the pool sits the Tripartite Agreement and its claim on state transfers. That is why the company has kept its provisions for bad debts close to nil.[^2]
But the counterparty paradox is real. The rules cured Power Grid's working capital without curing its customers. The state distributors remain collectively loss-making in many years, squeezed between politically set tariffs and the cost of free or subsidised farm power. The money to pay Power Grid on time has to come from somewhere, and often it comes from state budgets, from new borrowing, or from delaying something else. The improvement in debtor days is a statement about enforcement, not about the solvency of the buyer.
That raises the question at the heart of this chapter. What happens when the 48-month legacy instalments run out in 2026 and 2027? On one side, the instalments themselves will no longer be due, which frees state cash. On the other, the enforcement only works if the ministry is willing to cut off exchange access to a large state in the middle of an election campaign or a heatwave. That has not been seriously tested at scale. The bounce in debtor days from 65 back to 92 in fiscal 2026 is a small warning sign worth watching, not yet proof of a reversal.
The verdict is that the improvement is structural in its rules and contingent in its politics. If debtor days stay below 90 as the legacy instalments end, the 2022 rules will have done something no reform since the Ahluwalia settlement managed. If they climb back above 120, the old curse will have returned. And whether the state, as Power Grid's owner and its customers' owner at once, chooses to enforce its own rules leads directly to the question of how that owner runs the company.
IX. Governance, Leadership, and the PSU Discount
On April 1, 2026, Burra Vamsi Rama Mohan took charge as Chairman and Managing Director of Power Grid, succeeding Dr. R. K. Tyagi, whose tenure ran from January 2024 until the end of March 2026.8 Vamsi Rama Mohan is the kind of leader Indian state companies produce: a career engineer who rose through the projects side of the business, the part that actually puts towers in the ground. His tenure runs to July 2030, long enough to see most of the renewable build-out through.8 In August 2026 Amol Babulal Taori was appointed Director (Finance), taking over the role that will manage the borrowing the build-out needs.8
Vamsi Rama Mohan's appointment fits the pattern. Power Grid's leaders tend to come from inside, through technical ranks, and they bring deep knowledge of the network and steady continuity. What they do not bring is ownership. Pay for the chairman and directors follows government pay scales for public sector companies, roughly ₹60 lakh to ₹1.2 crore a year, with no stock options and no equity at all.[^2] The leader of a company worth ₹2.38 lakh crore earns less than a mid-level partner at a Mumbai law firm. That has an upside: there is little incentive for aggressive accounting or empire-building to pump a share price. It has a downside: there is also little incentive to fight for shareholder returns when the government wants something else.
The board has its own weakness. Independent directors at state companies are appointed by the government, and the appointments are often slow. Power Grid has repeatedly had fewer independent directors than listing rules require, which has drawn compliance notices and fines from the stock exchanges.8 Shareholder resolutions still pass with overwhelming support, but with the government holding more than half the votes that is not much of a test.[^2]
The audit record is cleaner. Power Grid's accounts are audited jointly by private chartered accountancy firms appointed by the Comptroller and Auditor General of India, and the CAG then conducts its own supplementary audit. In recent years, that supplementary audit has returned no comments, and the auditors' opinions have been unmodified.[^2] The material accounting judgment sits in regulatory deferral accounts, where the company books amounts it expects to recover through future tariff orders. That is standard for regulated utilities, but it means some reported income depends on the regulator's future decisions.
Related-party dealings are mostly with other state companies, NTPC, NHPC and the grid operator, on regulated terms, and the company pays no royalty or management fee to its owner.[^2] The real related-party transaction is the dividend. The government's 51.34% stake, unchanged for years, makes it the largest recipient of every payout.10 It also sits just above the majority the government needs to keep Power Grid a government company, so further sales by the state are limited. That removes one source of pressure on the share price, the fear of a giant block sale, but locks in another: the state will remain in control, with all the priorities that entails.
Who owns the rest has been shifting. Foreign institutions have cut their stake from nearly 29% in mid-2024 to about 24% by June 2026, while domestic institutions, especially mutual funds, have raised theirs from about 16% to about 21%.10 Foreign money, which can choose among the world's utilities, has been leaving; Indian savers, steered by monthly mutual fund flows, have been buying.
Put all this together and the stock's discount makes sense without any scandal to explain it. Power Grid trades at about 12 times earnings, below its own five-year median of almost 14 and far below private peers.[^3] Its return on equity of nearly 20% over the last twelve months would earn a premium in many markets.[^3] Part of that recent figure is flattered by a one-time tax credit in the March 2026 quarter, when the company's tax line swung to a gain and net profit nearly doubled from a year earlier.1 Strip that out and the underlying return is closer to the 17% to 18% the company has earned for years. The discount reflects a judgment that the owner, not the minority shareholder, will decide how that return is used. Is there a reason to believe the company's advantages can overcome that? That question deserves a proper look at the moat.
X. Frameworks & Moat Analysis: Why Power Grid Wins (and Where It Fails)
Stand at the foot of a transmission tower in a forest in the Western Ghats. The line running through it took years of clearances to build: forest department approvals, wildlife assessments, compensation for every tree felled. The corridor it runs along, cleared and legally protected, is perhaps 50 metres wide and hundreds of kilometres long. Now ask whether any rival, however well-funded, could build a second one next to it. The honest answer is almost certainly not, at least not quickly and not cheaply. That image is the best place to begin weighing Power Grid's moat.
Hamilton Helmer's framework of seven powers asks where durable advantage comes from. Power Grid's strongest is what Helmer calls a cornered resource. Its rights of way across India's states are, in a densely populated country with fragmented land holdings and fierce resistance to acquisition, very close to irreplaceable. A private developer can raise billions in Singapore. It cannot easily buy a straight line through five Indian states. And existing corridors can often be upgraded to higher voltage, so each one is an option on future capacity.
The second is scale economies, mostly in capital. Power Grid's AAA domestic rating and the sheer size of its borrowing let it raise money more cheaply than private rivals, which is its decisive edge in auctions.3 Its purchasing scale with equipment makers such as Hitachi Energy, Siemens Energy, BHEL and Larsen & Toubro helps too.[^2] The third is process power: decades of practice keeping lines at 99.8% availability through Himalayan snow, desert dust and coastal cyclones.[^2] That is hard to copy, but less decisive than it sounds, since the regulator's availability bonus rewards anyone who matches it.
The rest of the powers are thin or absent. There are no switching costs, because state distributors do not choose their transmission owner; they pay into a national pool, and power takes whatever path physics dictates.4 There are no network effects in Helmer's sense: connecting another solar farm does not make Power Grid's existing lines more valuable to anyone else. Electricity has no brand, and Power Grid's model offers no counter-positioning against rivals, who now bid on identical terms.
Michael Porter's five forces sharpen the picture. The threat of new entrants is moderate and rising, because the government actively wants competition in auctions, and capital is not scarce for big conglomerates or infrastructure funds. The bargaining power of buyers is the biggest problem: the buyers are state-owned distributors backed by state politicians, and behind them the regulator sets the return, so pricing power belongs to the state, not to Power Grid. Supplier power is moderate, since the most specialised equipment, such as HVDC valves and 765-kilovolt transformers, comes from a small number of global manufacturers, and supply shortages have pushed up prices and lead times across the industry. Substitutes are weak today. Rooftop solar and batteries can serve homes and small businesses, but the steel plant and the data centre still need bulk power moved across the country. Rivalry is escalating, through auctions designed to squeeze margins.
The most important test of the moat is whether it has held where it was challenged. Power Grid's monopoly on new interstate lines was taken away by policy, and it did not stop rivals from entering. But in auctions it has kept winning a large share, which shows the cost-of-capital advantage is real.[^2] The record therefore narrows the moat rather than rejecting it: Power Grid owns an irreplaceable existing network and has an edge in winning new work, but it no longer owns the right to earn its old returns on new work. The moat protects the share; it does not protect the price.
That distinction matters for valuation. Power Grid trades at about 5.9 times enterprise value to EBITDA.[^3] That is a low multiple for an asset with this level of certainty, and the market seems to be pricing a slow fade in returns rather than a collapse. Whether that fade is too pessimistic or not pessimistic enough is the real argument between bulls and bears.
XI. The Bull vs. Bear Case & Skeptical Stress Test
Imagine a fund manager in Mumbai with two names on the screen. On one side, Power Grid at about 12 times earnings with a 3.5% yield. On the other, Adani Energy Solutions at more than 35 times.[^3]6 Same industry, same grid, same regulator, three times the price. The manager has to decide which story to believe.
The bull case begins with the size of the job. India has promised to connect 500 gigawatts of clean power by 2030, which requires roughly doubling its interstate transmission capacity, and Power Grid is the organisation with the engineering depth to absorb ₹20,000 crore to ₹25,000 crore of annual capital spending.9 More spending on regulated or auctioned assets means a bigger asset base, and a bigger asset base means more revenue, reversing the stagnation of the last three years. The bull points to the cost of capital: in a world of higher interest rates, the company that borrows cheapest wins more auctions, and Power Grid borrows cheaper than anyone in its market.3 The bull points to the balance sheet: at about 1.5 times debt to equity, the company could borrow more than ₹50,000 crore before returning to its previous peak leverage, so it can fund the build without issuing shares or slashing its dividend to nothing.1 And the bull points to the price: at an earnings yield above 8%, investors are being paid well to wait, and international transmission owners such as National Grid in Britain and Red Eléctrica in Spain have generally traded at higher multiples.
The bear case starts where the bull's ends. Returns on new work will be lower. The regulator cut the allowed return on new regulated assets to 15%, and auctioned projects earn less still.4 Every year that more of the asset base is auctioned, the blended return on equity drifts down from the high teens. The bear points to free cash flow, which turned negative at about minus $600 million in fiscal 2026, and notes that if spending rises toward ₹25,000 crore a year, it will stay negative for years.1 The payout has already fallen from 72% to 45%; there is room for it to fall further, which would test the patience of the income funds that have held the stock. The bear also points to execution. Rights of way are getting harder to secure as farmers demand higher compensation and forest clearances face litigation. Power Grid's contingent liabilities, mostly tax disputes and contractor claims, stood at about ₹11,600 crore at the last full disclosure, roughly a tenth of net worth.[^2] And the bear points to the distributors: when the instalment schedule of the 2022 rules ends, will the states keep paying on time?
There is also an activist's critique that neither side always says aloud. Power Grid's owner has goals beyond shareholder returns. If the government needs a sub-economic line built to a border region, or a strategically important link that private developers will not bid for, it can nominate Power Grid. If it needs a higher dividend to plug a budget gap, it can ask for one. The company's management has no equity to protect and limited room to push back. That is not a fault of any individual; it is the structure. A skeptical long-short investor would focus on two things: whether the company starts accepting auction returns below its cost of equity to hold market share, and whether it gets saddled with strategic projects that add assets without adding returns.
Weighing the two, the evidence leans toward a narrower version of the bull case. The growth in the asset base is likely to be real, because the transmission plan is concrete and Power Grid is winning a large share of it. The return on that growth will be lower than in the past, which the bulls tend to understate. The balance sheet can carry the build-out, which the bears tend to understate. The stock's discount looks less like a mistake than like a fair price for a company that will grow faster and earn less, under an owner who sets the terms.
Three numbers will decide which side is right. The first is the rate at which Power Grid capitalises new assets, turning spending into earning lines; it needs to run above roughly ₹20,000 crore a year for revenue to grow meaningfully again, and its direction is now upward after the lull, with investing outflows reaching about $4.1 billion in fiscal 2026.1 The second is the company's auction win rate and the return implied by its winning bids; if it keeps winning while keeping equity returns above roughly 11%, the cost-of-capital moat is doing its job, and if it wins only by bidding lower, the bears are right. The third is debtor days, which stood at about 92 in fiscal 2026, up from 65 a year earlier; holding them below 90 as the old instalments end would show the 2022 rules have changed behaviour for good.1
XII. Playbook: Business & Investing Lessons
The first lesson comes from the commission's tariff formula of the early 2000s. Get paid for keeping the road open, not for the traffic. Power Grid's availability tariff made its revenue indifferent to demand, fuel prices and recessions, and that single design choice is why a company with towers in every state could be valued like a bond. For anyone designing infrastructure contracts, or buying businesses built on them, the lesson is that how a company gets paid matters more than what it builds. A toll road paid by cars is a bet on the economy. A toll road paid for open lanes is a bet on the contract.
The second lesson comes from the auction rooms after nomination ended. When the product is identical, the cheapest money wins. Power Grid cannot outrun Adani on land deals or contractor squeezes, but it can borrow more cheaply, and in a 35-year bid that is enough to keep winning. The catch is that cheap money wins the contract, not the margin. A cost-of-capital edge buys market share in a competitive auction; it does not buy back the returns that competition took away.
The third lesson comes from the Tripartite Agreement and the government's 51% stake. A sovereign umbrella keeps out the rain and blocks out the sun. The same state that guarantees Power Grid will be paid by the states also guarantees it will never be run purely for its minority shareholders. Investors in state-controlled companies should price both sides of that promise, and stop expecting one without the other.
The fourth lesson comes from the harvest years after the blackout corridors were finished. In a regulated utility, today's free cash flow is tomorrow's stagnation. Power Grid's best cash years were its slowest revenue years, and its return to growth has come with negative free cash flow. Investors who chase the yield at the top of the harvest are buying the end of a cycle, not the start of one.
The fifth lesson is the one written in the forest corridor. Money can be raised anywhere, but a right of way through India has to be earned one field at a time. Power Grid's lasting advantage is not its engineering or its rating, which others can approach, but its existing corridors, which no one can replicate on any useful timescale. When the return on new work fades, that is the asset that keeps the company relevant.
XIII. Epilogue
Tonight Power Grid stands where it stood in 2012, at the centre of India's ambitions for electricity, but with a very different job. It is worth about ₹2.38 lakh crore.[^3] Its balance sheet is the strongest it has been in more than a decade, with debt at under one and a half times equity.1 It has just started a spending cycle as large as the one that followed the blackout, aimed this time at the deserts of Rajasthan and Gujarat. And it is doing so for the first time as a company that must win most of its work on price.
Several moments over the next two years will tell the story. The first is the next annual report, for fiscal 2027, which will show how much of the company's profit now comes from auctioned projects and what return they actually earn. If those subsidiaries earn returns in the low teens and the blend holds near 17%, the first central question will have a reassuring answer. If the blend slides toward 15% or below, the market's low multiple will look prescient.
The second is the first full year after Power Grid hands the central planning utility to Grid Controller of India. Without any connection to the body that designs the grid, Power Grid becomes a purely commercial bidder. If its win rate holds, the cost-of-capital edge is real. If it falls sharply, part of what looked like competitive strength was proximity to the planner.
The third is the performance of state distributors as the instalment schedule of the 2022 rules reaches its final tranches. The early warning will be debtor days and the age of receivables in the half-yearly results. A steady number under 90 would mean India has finally made its distributors pay on time. A climb back toward the old peaks would mean the old pattern has returned in a new form.
Behind all three sits a larger tension. India needs Power Grid to build faster than at any time in its history, and to do so at lower returns, while paying a dividend to an owner that needs the cash and serving customers that are often broke. The question is whether the company will be allowed to act as a disciplined commercial developer, saying no to bad bids and bad projects, or whether it will be conscripted, as it has been before, into building whatever the nation needs at whatever return the nation can afford.
XIV. Outro
Go back to that afternoon in July 2012, when the dispatchers in Delhi watched the frequency fall and the north, east and north-east of India disappear from their screens. It looked, for a few hours, like the end of the idea that the Indian state could build infrastructure at scale. Instead it became the start of the most integrated grid the country has ever had, and the source of one of its most reliable cash machines.
Power Grid Corporation of India does not generate the spark, and it does not sell the flame. It simply owns the steel and aluminium veins through which the world's largest democracy breathes, and it is paid for keeping them open. For three decades that was enough. The next decade will test whether owning the veins is still worth as much when everyone else is allowed to build them too.
References
-
Annual Reports Archive — Power Grid Corporation of India ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Enquiry Committee Report on the Grid Disturbances on 30th & 31st July 2012 — Ministry of Power, GoI ↩↩↩
-
CRISIL Rating Rationale: Power Grid Corporation of India Limited — CRISIL Ratings ↩↩↩↩↩↩
-
CERC Terms and Conditions of Tariff Regulations 2024–29 — Central Electricity Regulatory Commission ↩↩↩↩↩↩↩↩↩
-
Powergrid Infrastructure Investment Trust (PGInvIT) Annual Reports & Investor Updates ↩
-
Bloomberg Company Overview & Peer Comps: Power Grid Corp of India — Bloomberg ↩↩
-
ICRA Credit Rating Rationale: Power Grid Corporation of India Limited — ICRA Limited ↩
-
BSE Corporate Announcements & Shareholding Patterns: Power Grid — BSE India ↩↩↩↩↩
-
National Electricity Plan (Transmission) for 500 GW Non-Fossil Capacity by 2030 — Central Electricity Authority ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube