Power Finance Corporation: The Balance Sheet Behind India's Grid
I. The Lender That Cannot Say No
In late March 2019, in the last days of India's fiscal year, a state-owned lender in New Delhi made one of the stranger acquisitions in modern corporate finance. Power Finance Corporation borrowed money and wired about ₹14,500 crore to its own controlling shareholder, the Government of India, to buy the government's 52.63% stake in REC Limited, the other big state lender to the power sector.12 Nothing changed hands in the physical world. No new power plant was financed and no new customer was won. The money went from one arm of the state to the budget of another, the government counted it toward its disinvestment target, and the two lenders that had together financed most of India's electricity system found themselves under one roof.
That transaction is a good place to start, because it shows PFC as it really is. On paper it is a non-banking finance company, registered with the Reserve Bank of India as an infrastructure finance company. In practice it is something odder: the balance sheet through which the Indian state funds, disciplines and occasionally rescues its own electricity system.[^3] It lends to state distribution companies that have been technically insolvent for most of their existence, to generation and transmission utilities, and increasingly to private solar and wind developers. Its consolidated loan book has grown to roughly ₹11 lakh crore, about $115 billion.[^4]
Here is the puzzle. A lender with that kind of customer base should earn thin, nervous returns. PFC earns about 18% on its equity, a figure that would flatter most private banks.[^4] Over the twelve months to June 2026 it made close to $2.9 billion in profit.[^5] And yet the market values the whole thing at about $11 billion, roughly 4 times trailing earnings and about 0.7 times book value.[^4] Investors are being offered a franchise that has compounded profits at around 15% a year for a decade, at a price that implies they expect something to go badly wrong.
Three questions run through this story. The first is whether that 18% return is the product of genuine lending skill, or a carry trade built on the state's borrowing cost and the state's power to make its own utilities pay. The second is whether asset quality can survive the shift from lending to state-backed thermal and distribution utilities toward private renewable developers, which have no sovereign behind them. The third is whether the REC takeover built a more efficient machine, or a regulatory trap in which the group cannot merge because merged exposures to a few states would break India's concentration rules.
The verdict this story will argue is that PFC is less a bank than a policy-enforcement arm with a banker's balance sheet. Its equity compounds because sovereign backing caps its cost of funds, and its political mandate forces it into exactly the borrower concentration that would terrify any private credit committee. Whether that combination is a moat or a trap depends on a variable no spreadsheet captures: the willingness of New Delhi to keep forcing state governments to pay their electricity bills.
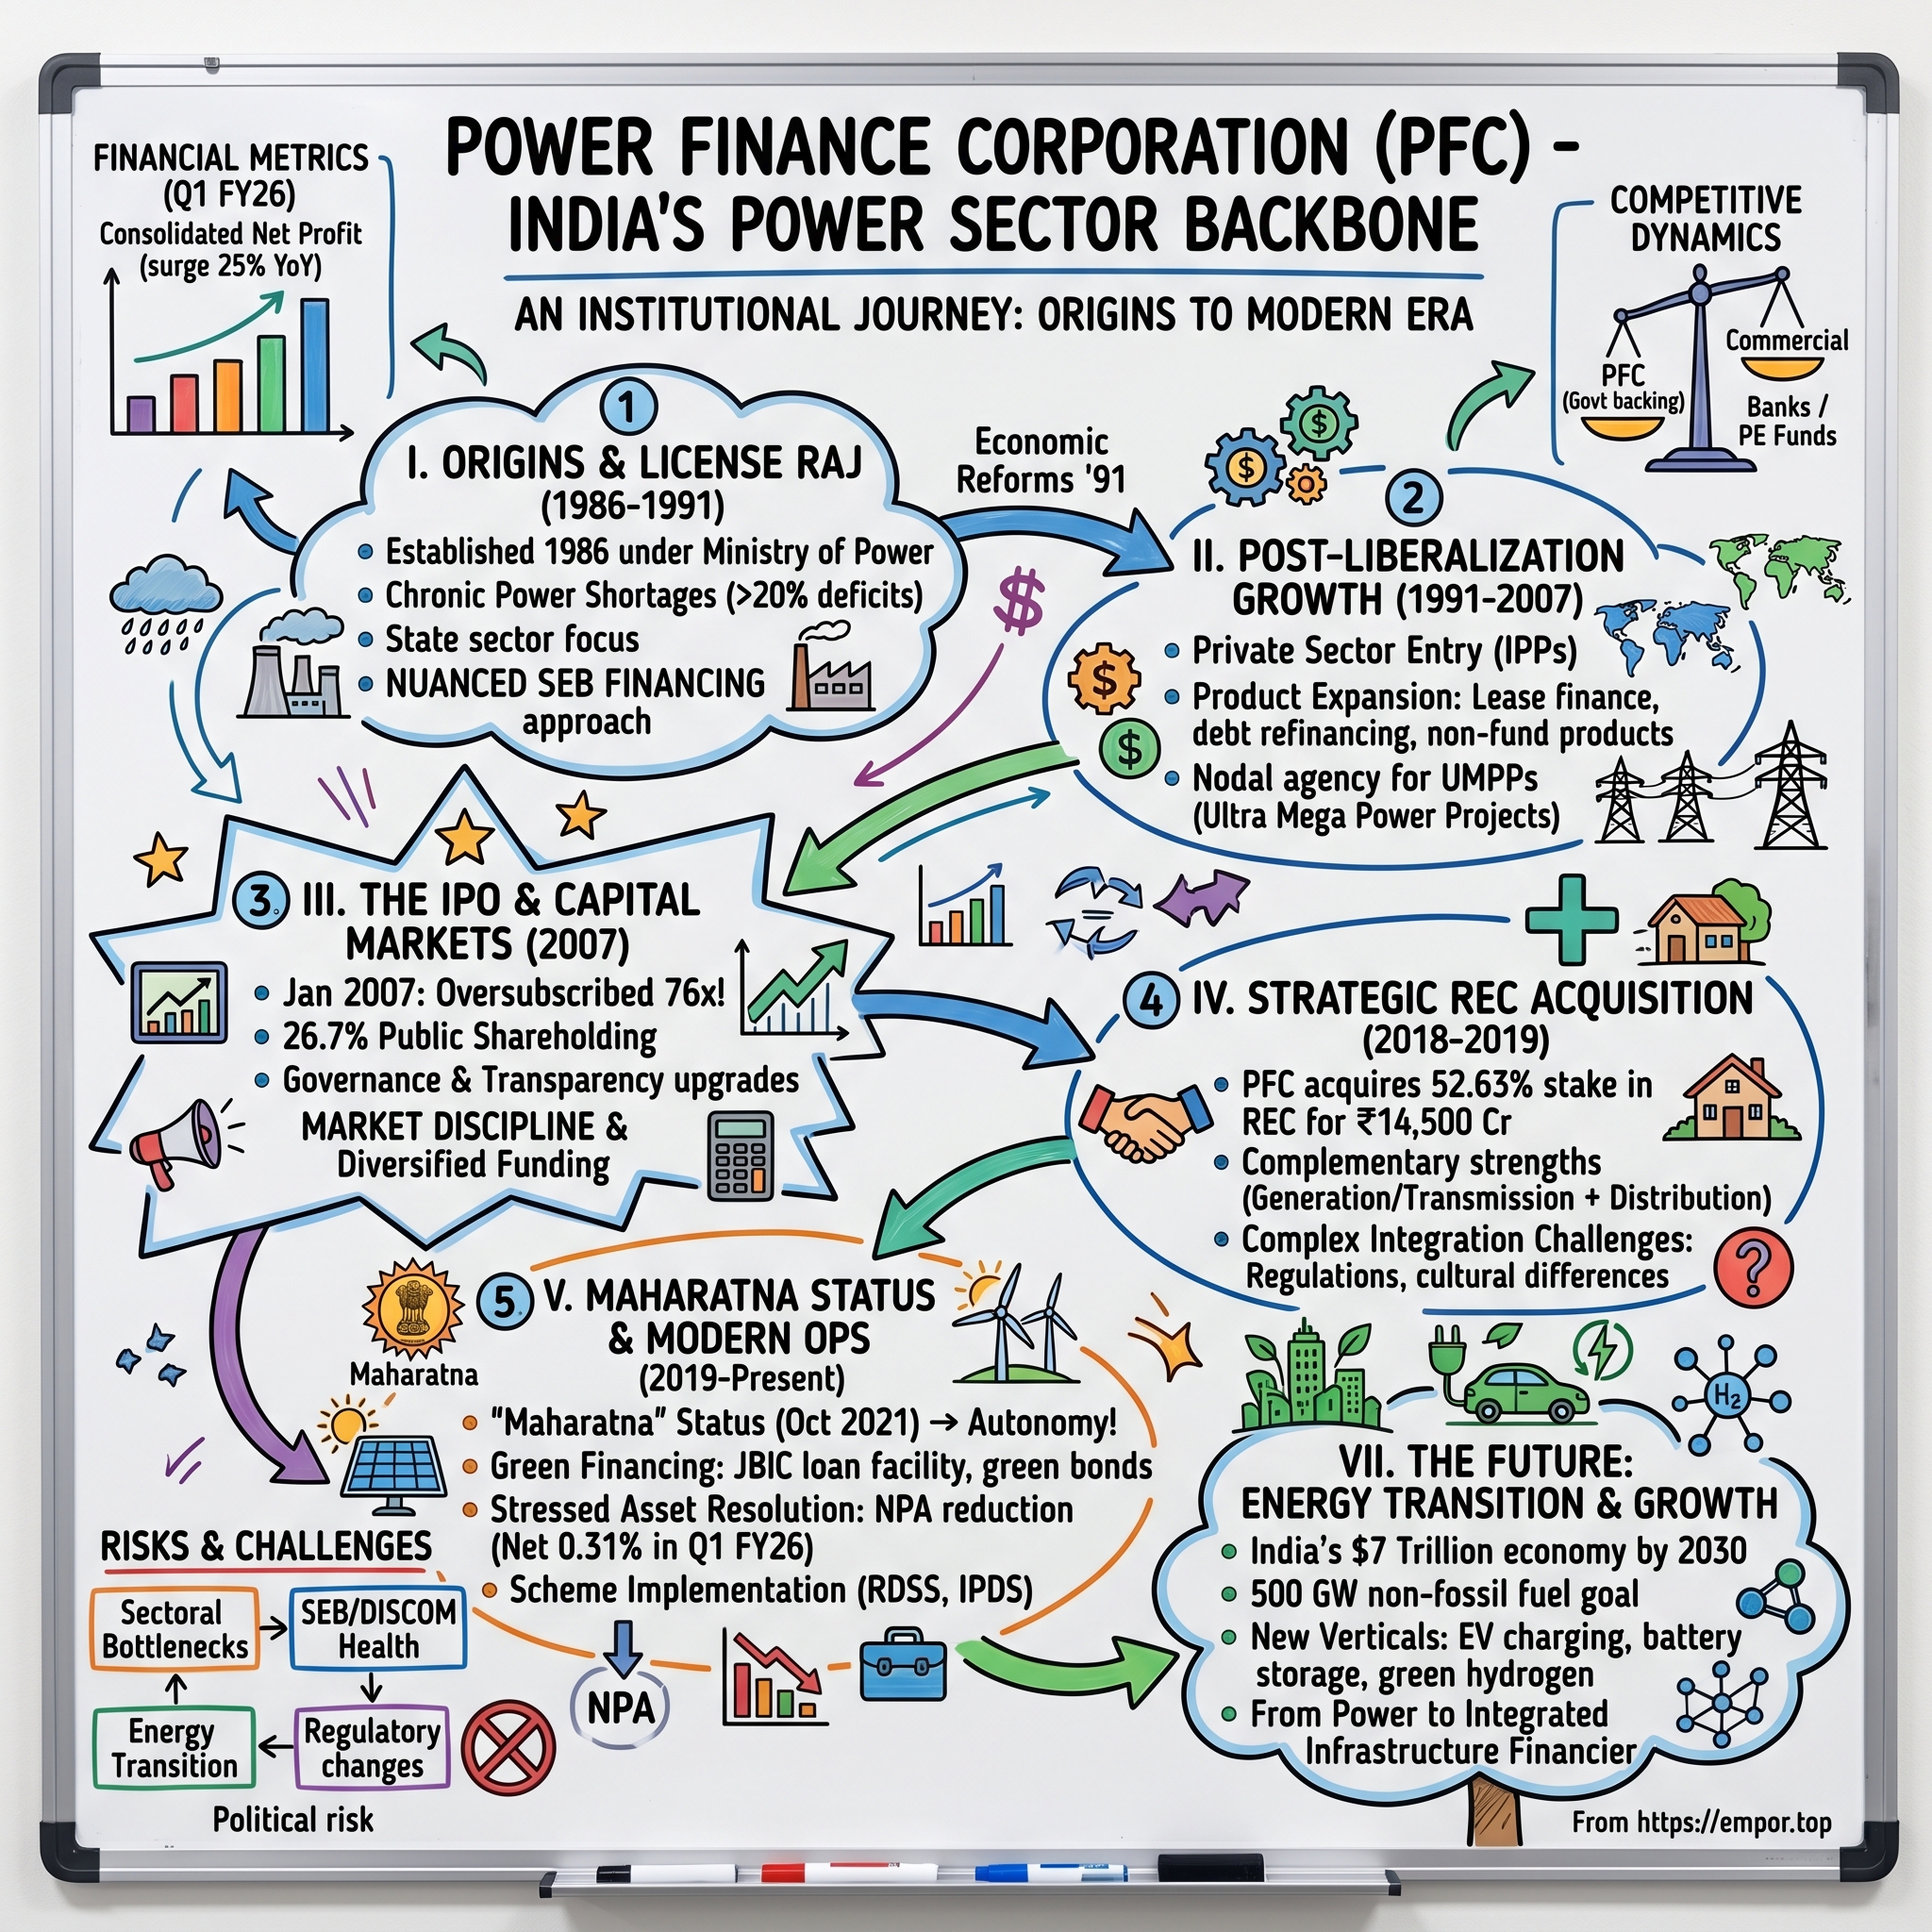
The story runs from the blackouts of the 1980s, through the private power gold rush and its collapse, into the REC deal, the payment-discipline rules that rescued the book, and the battle to fund India's renewable buildout. It begins in a country that could not keep its lights on.
 Subscribe on LinkedIn
II. The Blackout Years and the Special Purpose Vehicle (1986–1991)
In the India of the mid-1980s, a power cut was not an event. It was the weather. Factories ran diesel generators as a matter of course, farmers planned irrigation around the few hours the pumps had current, and peak demand regularly outran supply by a double-digit margin. The machinery responsible for this was a set of State Electricity Boards, one per state, that generated, transmitted and sold power under the direct control of state politicians.
The boards were designed to fail commercially. Tariffs were set by state governments that answered to voters, so farmers often received power free or nearly free, and the gap was meant to be covered by charging industry more and by subsidy payments from state budgets that arrived late or not at all. Meanwhile a large share of the power the boards generated simply vanished, lost to old wires or to theft, in what Indian regulators would come to call aggregate technical and commercial losses. A board that cannot bill for a large share of its output and cannot charge a fair price for the rest has no money to build plants.
Commercial banks were no answer. Indian banks of the era funded themselves with deposits that could leave at short notice, and a power plant pays back over fifteen or twenty years. Lending long against short money to a borrower whose revenue depended on a chief minister's mood was the kind of mismatch that sinks banks. The development financiers of the day, institutions such as ICICI and IDBI in their early forms, were built to fund industrial projects, not to become the permanent creditor to state governments' electricity departments.
So in July 1986, the Ministry of Power did what the Indian state did with most intractable problems of that era. It created a company. Power Finance Corporation was incorporated as a wholly government-owned entity with a narrow mission: to be a dedicated wholesale funding channel for the power sector.[^3] It would not take deposits. It would borrow in the bond market, with the implicit and sometimes explicit backing of the government, and lend that money long to state utilities for generation and transmission projects.
The design choice mattered more than it looked. By refusing deposits, PFC escaped the short-money problem that made banks reluctant. By borrowing as a state entity, it got money cheaper than any private lender could. And by specialising in one sector, it built an appraisal staff that understood boilers, transmission lines and power purchase contracts in a way a generalist bank officer never would. The cost was that its entire customer list was, in effect, the Indian state's own electricity departments.
That created the double mandate that still defines the company. PFC was supposed to be nation-building, financing the plants that would end the blackouts, and commercially viable, earning enough to service its bonds. The two pulled against each other from the start. A ministry that wanted a plant built in a politically important state could lean on a lender it owned outright. The early managers learned to live inside that tension by attaching conditions, insisting on project oversight, and relying on the fact that a state government would rarely let its own electricity board default to a central government company.
That reliance is the first clue to the whole story. PFC was not created because someone found a profitable gap in the market. It was created because the market had refused the job. Its moat, from day one, was that nobody else wanted its customers. In 1991, India's economy opened, and for the first time other people would want to build power plants.
III. Liberalization, Private Independent Power Producers, and the First Trap (1991–2007)
The 1991 balance-of-payments crisis forced India to open up, and electricity was one of the first sectors where the government invited private capital in. The pitch was simple: the state could not afford to build all the plants the country needed, so private developers, domestic and foreign, would build them and sell power under long-term contracts. The first wave of these independent power producers was halting and, in the famous case of Enron's Dabhol plant, disastrous. But the idea took hold.
The decisive moment came with the Electricity Act of 2003. It removed the need for a licence to build a generation plant, pushed states to break their monolithic boards into separate generation, transmission and distribution companies, and created independent regulators to set tariffs. What followed was a gold rush. Business groups that had never run a power plant announced thousands of megawatts of coal-fired capacity, confident that a power-starved country would buy every unit.
PFC rode that wave. It moved beyond plain term loans to state utilities into a wider kit: lending to private developers, financing equipment, discounting bills, and refinancing debt. It became the natural financier for anyone building generation in India, because no other lender knew the sector as well or could borrow as cheaply. The private book, small at first, became a growth engine.
The government also handed PFC a showcase role as the nodal agency for Ultra Mega Power Projects, giant coal plants of around 4,000 megawatts each. The model was elegant. PFC set up shell companies, secured land, water, coal linkages and clearances, then auctioned the shells to private developers who bid on the lowest tariff. Tata Power's Mundra plant and Reliance Power's Sasan plant emerged from that process. The UMPPs were meant to show that India could build power at scale and at low cost. They would also show, in time, what happens when developers bid aggressively for twenty-five-year contracts on assumptions about imported coal prices that did not hold.
In early 2007, at the height of this optimism, PFC went public. The IPO of shares with a ₹10 face value drew demand of roughly 76 times the shares on offer, an extraordinary signal of how much investors wanted exposure to India's power buildout.3 The government kept firm control, and further sales over the following years gradually brought its stake down to the roughly 56% it holds today.[^7] Listing did something useful: it put a market price on the company and forced quarterly disclosure on a lender that had only ever answered to a ministry.
The consensus story of this period is triumphant: a state company modernised, diversified and listed at a premium. The record suggests something more uncomfortable. Opening the book to private developers meant taking on borrowers whose only backstop was the project itself, in an industry where fuel, land, environmental approvals and the creditworthiness of the buyer were all outside the developer's control. PFC had spent twenty years learning that state utilities rarely default because their owners will not let them. It now lent to private companies whose owners could, and would, walk away. The seeds of the next decade's crisis were being planted in the same years that the IPO book was being oversubscribed.
IV. The Great NPA Crisis and the Thermal Graveyard (2008–2018)
Picture a newly built coal plant somewhere in central India around 2015. The boilers are installed, the chimney is finished, the transmission line runs to the edge of the site. There is no coal in the yard and no customer under contract. The plant sits silent while interest on its loans accrues every month. Across India, dozens of plants looked like that one, and together they became the largest pile of bad loans in the country's banking history.
The causes stacked on top of each other. Coal India could not deliver the fuel it had promised, and imported coal became far more expensive after Indonesia changed its export pricing rules. Environmental and land clearances stalled for years. Distribution companies, drowning in their own losses, stopped signing long-term power purchase agreements, preferring cheap spot purchases or simply buying less power and imposing cuts. Then, in 2014, the Supreme Court declared the allocation of more than two hundred captive coal blocks illegal and cancelled them, pulling the fuel supply from under projects that had been built on the assumption of owning their own mines.
PFC had lent into this. The private thermal projects it financed during the boom years began to fall into stress, then into the insolvency process under the Insolvency and Bankruptcy Code once it arrived in 2016.[^8] The test of the 2007-era thesis, that PFC's sector expertise made it a better judge of power projects than generalist banks, came back negative. PFC's appraisers did not see the coal shortage, the PPA drought or the court ruling coming any better than the State Bank of India did. On the private book, specialist knowledge did not translate into superior underwriting.
The damage surfaced in the accounts. In the year to March 2017, net profit collapsed by about 64%, to roughly $333 million, as provisions surged and an unusually high tax charge, close to 58% of pre-tax profit, hit the bottom line.[^5] Return on equity fell to about 6%.[^4] Gross bad loans kept climbing for two more years, and by around the time of the REC deal they had passed 7% of the book.[^8] For a company whose whole pitch was safety, that was a humbling number.
So why did PFC not collapse, the way several private lenders and some public banks effectively did? The answer lies in the shape of the book. Private developers were a minority of the portfolio, perhaps a sixth or a fifth of it. The great majority, more than 85%, was owed by state-owned utilities.4 Those utilities were often desperately late payers, but they did not formally default on principal, because their owners, the state governments, stood behind them and because the central government had many ways to make a recalcitrant state pay a central lender. The same customer base that capped PFC's valuation also kept it alive.
The accounting changed underneath all this. From 2018, PFC moved to Indian Accounting Standards and the expected credit loss model, under which a lender books provisions for losses it expects rather than waiting for a loan to go bad. Loans are sorted into three stages: performing, showing significant deterioration, and impaired. The independent auditors have since drawn attention, through an emphasis of matter, to the way PFC's expected credit loss estimates depend on valuation models and parameters assessed by outside agencies.[^10] It was not a qualification of the accounts, but it is a reminder that the provisions a lender reports are estimates built on judgements, and in a sector where collateral is a half-built power plant, those judgements carry a lot of weight.
The lesson of the thermal graveyard was that PFC's safety came from its owners' power over its borrowers, not from its own credit selection. That lesson would shape what came next, because just as the bad-loan cycle peaked, PFC's own owner needed a favour.
V. The REC Takeover: Divestment Deal or Corporate Masterstroke? (2018–2019)
In December 2018, the Cabinet Committee on Economic Affairs approved a deal that had been circulating in New Delhi for months: PFC would buy the government's controlling stake in REC Limited.1 On the surface it read as a consolidation of two lenders doing similar work. Underneath, the motive was fiscal. The government had set itself a target for selling stakes in state companies that year and was running short. Selling REC shares into the open market would have depressed the price and taken time. Selling them to another government company was quick, clean and fully counted toward the target.
REC had its own history. Founded in 1969 as the Rural Electrification Corporation, it had spent decades funding the wires that brought power to villages, and by 2018 it was nearly as large as PFC and lent to largely the same state utilities. The two companies had competed for the same borrowers for years, which was itself a curious arrangement for two lenders owned by the same ministry.
The terms were straightforward. PFC bought about 1.04 billion REC shares at ₹139.50 each, for a total of roughly ₹14,500 crore, and completed the purchase in March 2019.12 It paid entirely with borrowed money, issuing no new equity of its own. That choice is the key to understanding both the deal's appeal and its cost.
Start with the appeal. PFC paid roughly 0.7 times REC's book value for control of a profitable, AAA-rated lender.5 Buying a bank-like business below book, with cash raised at quasi-sovereign rates, is the kind of trade that compounds nicely if the asset earns well, and REC did. Over the following years REC's dividends flowed up to PFC, and PFC's consolidated profits reflected a lender twice its former size. By that narrow measure, PFC's shareholders were not robbed.
Now the cost. Consolidating REC's balance sheet more than doubled reported group borrowings, from about $36 billion to about $80 billion in one year, and debt to equity peaked at about 12.6 times in the year to March 2020.[^4] Equity did not grow to match because PFC had paid in cash rather than shares. That spike in leverage is mostly an accounting effect of consolidation, since REC's debt was always REC's, but it made the group look stretched at the worst moment of the bad-loan cycle. And PFC's minority shareholders had no real say over a deal designed to fix their controlling shareholder's budget arithmetic.
The deeper problem was regulatory, and it is why, more than seven years later, PFC and REC remain parent and subsidiary rather than one company. The Reserve Bank limits how much of its own capital a non-bank lender can lend to any single borrower or group of related borrowers. PFC and REC each lend heavily to the same handful of large states, Uttar Pradesh, Tamil Nadu, Maharashtra and others. Kept separate, each company's exposure to, say, Tamil Nadu's power utility can sit within its own limit. Merged, the exposures add up while the capital base, though larger, does not grow fast enough to keep pace, and several states would breach the limits overnight.6 A merger would therefore shrink the combined group's capacity to lend to its biggest customers, which is the opposite of what consolidation is supposed to achieve.
So the deal settled into an awkward middle. The group behaves partly like a consortium, with the two lenders often co-financing large projects, and partly like two competitors that happen to share an owner. The administrative duplication remains. The verdict on the takeover is mixed: financially it has been accretive for PFC, but it was conceived to solve New Delhi's problem rather than PFC's, and the operational integration that would justify it remains blocked by rules the government itself would have to bend. A lender that had just been used to plug a budget gap now had twice the exposure to the same troubled customers. What rescued it was not the deal. It was a set of rules New Delhi wrote three years later.
VI. The Reform Stick: UDAY, RDSS, and the Late Payment Surcharge Breakthrough (2019–2024)
On June 3, 2022, the Ministry of Power notified a set of rules with the unglamorous title of the Electricity (Late Payment Surcharge and Related Matters) Rules.[^13] They may be the most important document in PFC's modern history, though PFC did not write them and is not named in their title.
To see why, go back to the disease. A distribution company buys power from generators and sells it to homes, farms and factories. If its tariffs are below cost, its losses high and its state government's subsidy payments late, it falls behind on paying the generators. The generators, starved of cash, fall behind on paying their lenders. For decades this chain of unpaid bills ran from village meters all the way up to PFC's balance sheet. Previous fixes had failed. The UDAY scheme of 2015 had states take over much of their utilities' debt and promise to cut losses and raise tariffs, but the promised improvements in billing and collection largely did not stick, and dues built up again.
The 2022 rules changed the mechanism rather than the promises. Under them, a distribution company that failed to pay its generators on time could have its access to the short-term power markets and to the inter-state grid progressively cut off, until it cleared its dues.[^13] Accumulated arrears could be paid off in instalments, but missing those instalments brought the same consequence. For the first time, non-payment had an immediate, automatic and politically embarrassing cost: a state that did not pay could find its own people facing power cuts. States paid. The backlog of overdue bills owed to generators fell sharply over the following months and years.
Alongside the stick came a carrot. In 2021, the government launched the Revamped Distribution Sector Scheme, with an outlay of about ₹3.03 lakh crore, to fund smart prepaid meters, network upgrades and loss reduction.[^14] Grants under the scheme were tied to states meeting conditions on losses, timely subsidy payment and financial reporting. PFC and REC were made the nodal agencies to run it, which meant the lenders to the distribution companies were also the gatekeepers of the money the distribution companies most wanted.[^14]
The effect on PFC's book was dramatic. Gross bad loans fell from more than 7% around 2019 to about 1.6% by March 2025, and net bad loans, after provisions, dropped to about 0.4%, the lowest in the company's history.[^8] More than three quarters of the remaining impaired loans are covered by provisions.[^8] Much of that improvement came from resolving the old private thermal cases, some of which were bought by stronger operators as power demand recovered and idle plants regained value. The rest came from state utilities paying on time.
The consensus reading is that PFC engineered a turnaround. The more accurate reading is that the Indian state did. PFC's loan officers did not suddenly become better at picking borrowers. The government changed the rules so that its borrowers had to pay, and handed PFC a scheme that put it in the position of a creditor holding the purse strings. That distinction matters for investors, because a turnaround built on coercive policy lasts exactly as long as the policy does. The question is not whether PFC's credit culture improved; it is whether New Delhi will keep enforcing the grid cut-offs when a state election approaches and the state in question belongs to an ally. Meanwhile, the money to lend into this cleaner world has to come from somewhere, and that is where PFC's real advantage lies.
VII. The Funding Engine and Treasury Moat
Most of what makes PFC profitable happens not in a power plant but on a trading desk in Mumbai. When PFC sells a ten-year bond, investors price it only a little above the yield on the Indian government's own bonds of the same tenor, a margin of a fraction of a percentage point. Every rupee PFC lends starts from that low cost, and no private lender in India, however well run, can borrow that cheaply for that long.
The reason is the rating and the owner. PFC is rated AAA by all three major domestic agencies, CRISIL, ICRA and CARE, and each of them names its strategic importance to the government and the government's majority ownership as the first pillar of that rating.457 Bond investors, from pension funds to insurers, treat PFC paper as nearly sovereign. That status is the asset that does not appear on the balance sheet.
The liability side is built from several layers. Domestic bonds make up the majority of borrowings, bank term loans a fifth or more, and foreign-currency debt, in dollars, euros and yen, roughly a sixth.5 A particular privilege sits inside the domestic layer: PFC is one of the few issuers allowed to sell so-called 54EC bonds, which let an individual who has sold property or other assets defer capital gains tax by parking the proceeds in the bonds for five years. The coupon is low, but buyers accept it because the tax saving does the work. It is sticky, cheap retail money that an ordinary lender cannot touch.
Foreign borrowing introduces a different risk. If PFC borrows dollars and lends rupees, a falling rupee raises its repayment cost. The company says it hedges about 95% of its foreign-currency exposure within a five-year horizon, using currency swaps and forward contracts.5 That keeps the rupee's slide, which has been substantial over the decade, from becoming a hole in the income statement, though hedging is not free and its cost eats into the spread on foreign money.
Then there is the cost base, which is almost comically small. PFC runs its standalone business with a few hundred employees, roughly five hundred people, while the group's assets have grown to about $140 billion.[^4][^7] Operating costs are a sliver of income. A lender that does not run branches, collect deposits or serve retail customers can scale its book enormously without adding staff. The company's revenue is only about nine cents for each dollar of assets, because it is a thin-spread wholesale business, but almost none of that revenue is consumed by overhead.[^4]
Why can banks not simply take this business? Indian banks must park a slice of their deposits in government bonds and with the central bank, and must direct a share of lending to priority sectors such as agriculture and small business. Those requirements raise the effective cost of every rupee a bank lends to a power utility. They also face their own sector exposure limits, and many still carry scars from the thermal bust. In periods of excess liquidity banks do pick off the best transmission and renewable projects, but they rarely want to be the permanent creditor to a weak state utility.
So the moat is on the liability side. PFC's edge is not that it lends better than banks; the thermal crisis showed it does not. Its edge is that it borrows cheaper than almost anyone and spends almost nothing to run the machine. The limit of this advantage is the third central question: when interest rates rise, PFC's bond costs move faster than its lending rates to state utilities reset, and its margin compresses. The company's net interest margin, a little above 3% in recent years, is the gauge of whether the funding moat still pays.[^8] That machine now has to fund a very different kind of borrower.
VIII. The Green Pivot and the Private Developer Dilemma
At the Glasgow climate summit in November 2021, India announced a goal of 500 gigawatts of non-fossil generating capacity by 2030. Back in New Delhi, the target translated into an enormous financing problem: solar parks across Rajasthan and Gujarat, wind corridors in the south, pumped hydro storage in the hills, and the transmission lines to connect it all. PFC, the lender that had built India's coal fleet, set out to finance its replacement.
The renewable book has grown quickly, by about a quarter in a year to more than ₹60,000 crore, and renewables made up about 14% of PFC's loans by March 2025, against about 41% for state distribution companies, 34% for conventional generation and 7% for transmission.4 Management talks of pushing renewables to a much larger share over the decade. PFC also started borrowing for the purpose abroad, with an inaugural green bond of about $400 million in 2017.[^7]
The shift changes the nature of the risk. A loan to a state distribution company is a bet on a government's willingness to pay, backed by the payment-discipline rules. A loan to a private solar developer is a bet on a project: on whether the panels arrive at the price assumed, whether the land is secured, whether the power can actually be evacuated, and whether the buyer honours the tariff. That last point has a history. In 2019, the newly elected government of Andhra Pradesh sought to reopen and cut tariffs on wind and solar contracts signed by its predecessor, holding back payments for months before the courts stepped in.8 It was a reminder that a state-backed buyer is not the same thing as a reliable one when the contract becomes politically inconvenient.
The private borrowers are larger and better capitalised than the coal developers of 2010. Groups such as Adani Green, ReNew and Tata Power have deep sponsors and access to global capital. But the thermal bust also featured large, well-connected groups, and it was not the weak sponsors that caused the damage so much as industry-wide shocks that hit every project at once. The renewable equivalents are already visible: module prices whipsawed by import duties on Chinese panels, curtailment when the grid cannot absorb midday solar, and aggressive auction bidding that leaves projects with thin margins for error.
Transmission is the bottleneck that ties these risks together. A solar park finished before its connecting line is a modern version of the coal plant with no fuel: an asset that cannot earn but must still pay interest. India has repeatedly had capacity waiting on lines in Rajasthan and elsewhere. PFC is also lending beyond power, into metro rail, electric vehicle charging and other infrastructure, which widens its field but takes it further from the sector expertise that was supposed to be its edge.
Does PFC's history reject the claim that it can finance the transition safely? Not outright. It narrows it. The record says PFC's own appraisal did not protect it the last time it lent heavily to private power, so the safety of the green book will depend on project structure, sponsor strength and whether state buyers honour contracts, not on PFC's sector knowledge alone. The figure that will tell investors which way it is going is the share of loans in the second, watch-list stage of provisioning, which flags deterioration well before a loan turns bad. If that number climbs as the renewable book grows, the 2012 cycle is repeating. The other half of the answer lies with the people deciding where the money goes, and who they answer to.
IX. Governance, Executive Pay, and the Maharatna Reality
In October 2021, the government granted PFC "Maharatna" status, the top tier of its classification for state-owned companies, which gives the board more freedom to invest in joint ventures and subsidiaries without seeking ministry approval each time.9 It was a badge of trust, and also a reminder of the hierarchy: the board's freedom is something the ministry grants, and can take back.
The person running the company since 2023 is Parminder Chopra, the first woman to lead PFC. She is a career PFC finance officer who spent decades inside the company's treasury and finance functions before rising to director of finance and then to chairperson and managing director.[^7] That background fits the institution: PFC's real business is raising money cheaply and allocating it under policy direction, and it is run by someone who grew up in the raising.
What she is paid tells its own story. Her remuneration was about ₹91 lakh in the year to March 2025, a little over $100,000 and far less than a hundredth of a percent of the company's profits.[^7] Pay is set by public-enterprise scales, not by the board, and has nothing to do with the share price. That removes one kind of agency problem: no executive at PFC is going to juice short-term earnings to hit a stock-option target. It creates another: nobody at the top is personally rewarded for creating value for minority shareholders, either.
The board shows the strains typical of a state company. Independent director seats sometimes sit vacant while the central government processes appointments, which has left PFC at times short of the independent directors that India's listing rules require.10 The government holds about 56% of the shares, none of them pledged, and resolutions routinely pass with near-unanimous institutional support.1011 Foreign investors held about 20.5% by June 2026, a little more than in March, and domestic institutions about 14.5%.11
Related-party dealings are substantial but run in the open. The large flows are dividends from REC, co-financing with it, and fees for running government schemes. None of them go to a private promoter's family, and there is no brand royalty or management fee extracted from minority shareholders.[^20] By the standards of Indian corporate governance, that is clean.
The real governance risk is not theft. It is direction. The same owner that elevated PFC to Maharatna status used its balance sheet in 2019 to meet a budget target, and could in principle ask it to fund an off-budget scheme, absorb a struggling state's debts, or pay out a special dividend in a tight fiscal year. The company's own history provides an example: the REC deal was exactly such a use, and it worked out acceptably for shareholders largely because REC was cheap. A minority investor in PFC is a co-investor with a government that has other priorities, and the discount at which PFC trades is, in part, the price of that partnership. Forty years of that partnership leave lessons worth drawing out.
X. Playbook: Business & Investing Lessons
Over the decade to March 2026, a lender run by a few hundred people grew its profits at about 15% a year, paid out a median of about 30% of its earnings in dividends, and brought its leverage down from more than 12 times equity to under 8 times.[^4][^5] It did this while lending mainly to companies that have been technically insolvent for most of their existence. That combination contains a handful of lessons that belong to PFC and to almost nobody else.
The first lesson is that a lender's moat lives on the liability side. The moment that captures it is the bond desk in Mumbai pricing ten-year PFC paper a whisker above the government's own. PFC never needed to out-underwrite the State Bank of India; the thermal crisis proved it could not. It needed only to borrow cheaper than everyone else and spend nothing running the machine. For investors studying any lender, the place to look first is not the loan book but the funding stack. A lender is only as good as its cheapest rupee.
The second lesson is that a bad balance sheet is not the same as a bad debtor. India's distribution utilities have been loss-making for generations, and yet the principal PFC lent them kept coming back, because the borrower's owner was a state government and the state government's owner, in a fiscal sense, was New Delhi. When the payment chain finally tightened, it was because the central government threatened to switch off grid access, not because any utility turned profitable. The wider point for investors is that credit quality is a property of the enforcement system, not just of the borrower. Insolvent is not the same as unwilling, and the gap between them is policy.
The third lesson is that deals done for the owner's convenience leave structures that outlast the convenience. The REC purchase closed a hole in the 2019 budget in a single transfer. Seven years on, the two lenders still cannot merge, because combining them would breach the very exposure limits that keep each of them safe. Consolidation by fiat built a group that cannot consolidate. For anyone evaluating a state-directed acquisition, the question is not whether the price was fair on the day but whether the transaction leaves the acquirer able to do what it bought the target for.
The fourth lesson is that extreme operating leverage cuts both ways. Running a $140 billion balance sheet with a few hundred people produces a cost-to-income ratio a private bank can only dream of. It also means very few eyes on each project. That was tolerable when the borrowers were state utilities with sovereign backing. It was not tolerable when the borrowers were private coal plants waiting for fuel, and it will be tested again on solar parks waiting for transmission lines. Lean is a virtue in lending only as long as the borrower does not need watching.
Taken together, the lessons say PFC's success is real but borrowed: borrowed from the state's credit, the state's grid controls and the state's appetite for keeping utilities afloat. That is a durable foundation, but not one PFC controls. The next question is what all this is worth, and why the market prices it so low.
XI. Strategic Moat, Porter's Forces, and Hamilton Helmer's 7 Powers
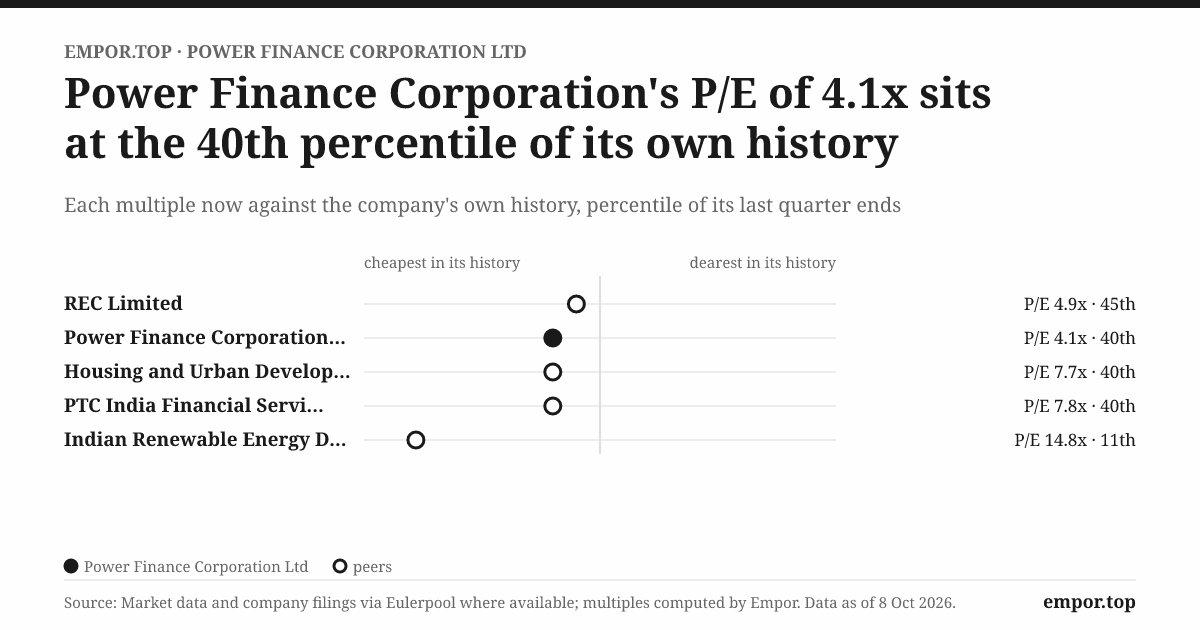
Put PFC next to India's most admired private lenders and the gap is startling. HDFC Bank and Bajaj Finance have traded for years at several times their book value. PFC trades at about 0.7 times book, about 4 times earnings, with an earnings yield of about 24% and a dividend yield of about 4.6%.[^4] Its own five-year median earnings multiple is only about 4.7 times, and REC trades in a similar band.[^4]12 The market is not mispricing PFC in a hurry; it has priced the whole category this way for years. So the question is whether PFC's advantages are real and, if they are, why investors refuse to pay for them.
Run Hamilton Helmer's framework, which asks which of seven sources of durable advantage a business possesses. PFC has a plausible claim to three. The first is scale economies on the funding side. PFC and REC together are among the largest non-government issuers in the Indian bond market, and that volume, combined with the rating, gives them the finest non-sovereign borrowing spreads in the country. A new entrant could not replicate that without both the size and the ownership.
The second is a cornered resource, though it is a resource the state can redistribute. Maharatna status, the ability to sell tax-advantaged 54EC bonds, and the nodal role in schemes such as the distribution reform programme are all privileges granted by the government rather than earned in the market. They are cornered only as long as the government does not hand them to someone else, and the government has already shown, by running REC as a parallel lender, that it is happy to spread them across more than one company.
The third, process power, is the weakest of the three. PFC claims four decades of specialised appraisal of power projects that commercial banks cannot match. The historical record narrows this claim sharply: on the private thermal book, PFC's appraisal produced losses broadly in line with generalist banks. Its process power is real in the narrow skill of structuring loans to state utilities and running government schemes, not in picking winners among private projects. Of Helmer's other powers, network effects, switching costs, brand and counter-positioning do little work here; a state utility borrows from whichever state lender offers the money.
Michael Porter's five forces sharpen the picture. The threat of new entrants is very low, because no private company can assemble a quasi-sovereign rating and a ₹11 lakh crore balance sheet. The bargaining power of suppliers, the bond investors, is low, because they treat PFC as a near-sovereign proxy and compete to buy its paper. Rivalry is unusual: PFC's only real competitor is its own subsidiary, and the two often co-lend rather than fight. Substitutes are a moderate threat, mainly banks that cherry-pick the best transmission and renewable projects when they are flush with deposits.
The force that explains the valuation is the bargaining power of buyers, and it is high. State distribution utilities, about 41% of the book, are captive in the sense that they have few alternatives, but their fiscal weakness limits how much PFC can charge them, and their owners can lean on PFC politically.4 When a buyer is both your largest customer and a branch of your shareholder's political family, pricing power is limited by politics as much as by the market.
So the verdict on the moat is that it is real but fenced. Funding scale and state-granted privileges reliably deliver high returns on equity, and have done so for most of the past decade. But the ceiling on those returns is set by the creditworthiness and political behaviour of state governments, and the market prices that ceiling in. A 4 times earnings multiple is not an oversight. It is a statement that investors think the profits belong partly to the state, and that the state may one day want them back. With the moat mapped, the case for and against owning the shares comes into focus.
XII. Analysis & Bull vs. Bear Case
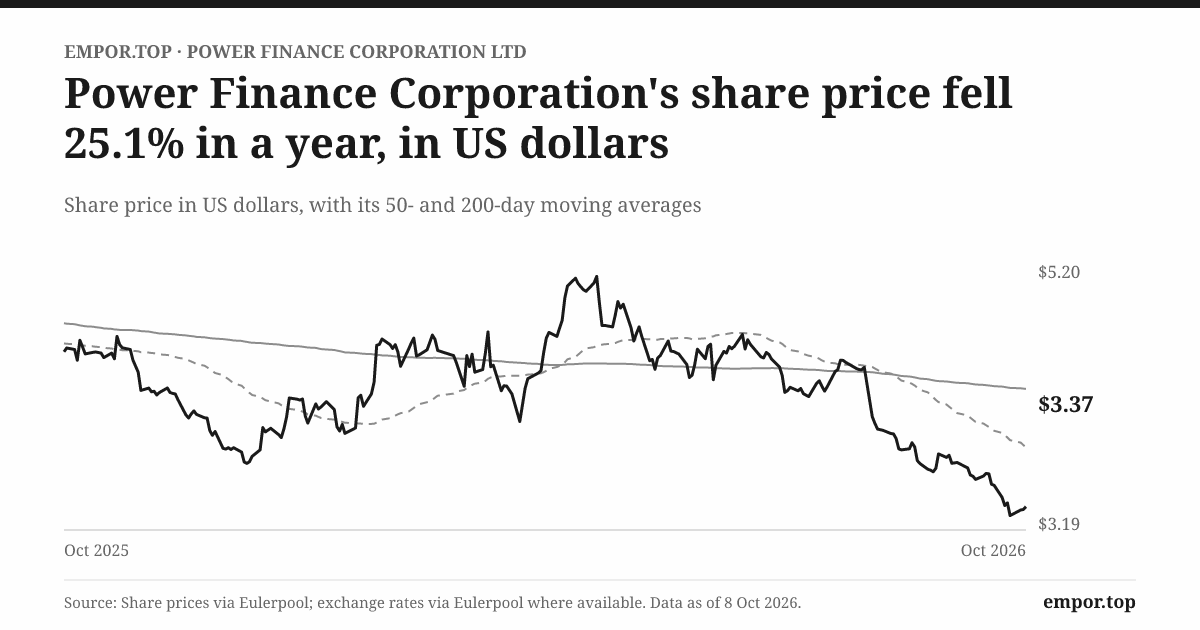
Imagine an investment committee in October 2026 weighing a position in India's state-owned infrastructure lenders. The stock has fallen about a third from its 52-week high, to around ₹326, and trades below book value.[^4] The last quarter's revenue was flat against a year earlier, and profit grew only about 2%.[^5] On the table are a lender earning 18% on equity with record-low bad loans, and a lender whose customers are state governments in an election cycle. Both descriptions are accurate.
The bull case begins with demand. India's electricity consumption keeps rising with industrialisation, air-conditioning and electrification of transport, and the government's own planning assumes peak demand will keep climbing steeply through the decade. Every gigawatt of new generation, every transmission corridor and every smart meter needs financing, and PFC sits at the centre of that pipeline as lender and as scheme administrator. The bull would argue that this is a volume business with a near-guaranteed volume runway.
The bull's second pillar is asset quality. Net bad loans at about 0.4% and coverage above three quarters of impaired loans make the book cleaner than at any time in its history.[^8] The payment-discipline rules have changed the incentive structure of the whole sector, not just PFC's customers. If they hold, the bad-loan cycle of the 2010s was a one-off born of private thermal excess, not a recurring feature.
The third pillar is capital and cash returns. Standalone capital adequacy above 23%, against a regulatory minimum of 15%, means PFC can keep growing without issuing shares.13 The company has never needed a rights issue in its listed life; its share count has grown only through bonus issues in 2016 and 2023.14 It pays out roughly a third of profits, and with the stock below book, a 4.6% dividend yield is paid while waiting for any re-rating.[^4][^5]
The bear case starts with concentration. The top ten borrower groups account for more than 40% of the loan book, and most of them are state utilities.4 Every rating agency names that concentration, together with heavy exposure to a single sector, as the main constraint on PFC's credit profile.457 A single large state reneging on discipline, through a populist free-power promise after an election, would not merely dent PFC; it would test whether New Delhi is willing to cut off a big state's grid access in practice rather than in theory.
The bear's second point is the stuck structure. Because the REC merger is blocked by exposure rules, the group carries two head offices, two boards and two treasuries while competing with itself for the same borrowers. Any efficiency case for the 2019 deal remains unrealised, and an activist investor, if such a thing could exist at a state company, would ask why minority shareholders of PFC should fund a holding structure that exists mainly because of a budget target.
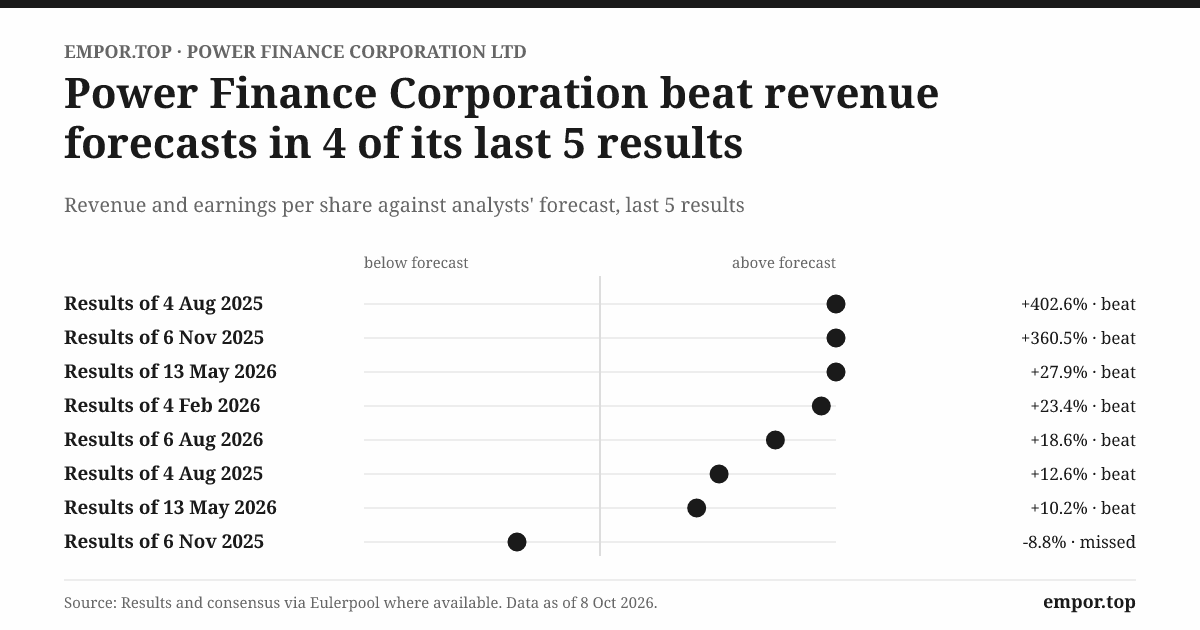
The bear's third point is the green pivot, which moves the book from sovereign-adjacent risk to private project risk at a time of thin auction tariffs, volatile module prices and transmission delays. And the fourth is the growth slowdown. Revenue growth decelerated from above 20% in 2023 to roughly zero by mid-2026.[^5] Some of that is lower interest rates passing through to floating-rate loans, and some is slower disbursement. Either way, a lender priced for no growth that stops growing will struggle to re-rate.
Weighing these, the case reduces to a bet on policy durability. If the payment rules and scheme conditions hold through the state election calendar, the book stays clean and the returns stay high, and the low multiple is a durable discount for political risk rather than a forecast of loss. If they slip, concentration does the rest. Three measures will show which way it is going. The first is net bad loans, about 0.4% at the last annual reading and trending down; a move back toward 1% would be the earliest warning.[^8] The second is net interest margin, a little above 3%, which shows whether the funding advantage survives changing rates.[^8] The third is the share of loans in the watch-list stage as the renewable book grows. None of these predicts the stock. They predict whether the story stays the same.
XIII. Epilogue
Somewhere in the Ministry of Power in New Delhi sits the unresolved file on what to do with PFC and REC. The options have not changed much since 2019. The government could merge the two and seek relief from the Reserve Bank on exposure limits for state utilities, accept the parent-subsidiary arrangement as permanent and stop pretending integration is coming, or find some third structure in between. Each path changes what PFC is. A merger with regulatory relief would create one dominant lender to the sector with a single, cheaper overhead. A permanent holding structure would leave PFC as, in large part, a listed wrapper around a listed subsidiary. Until the file closes, the group remains suspended between the two.
The second decisive moment is political and already under way. A string of state elections tests whether governments that promise cheap or free power will keep paying their utilities' bills, and whether New Delhi will enforce the grid cut-offs against them if they do not. The payment rules have worked through a period of political calm. They have not yet been tested by a large state openly defying them. If they hold, the case that PFC's asset quality has structurally improved grows much stronger. If enforcement is quietly suspended for a friendly state, investors will learn that the turnaround was a policy, and policies change.
The third is the first wave of large green hydrogen, storage and offshore wind financings. These are technologies with little operating history in India and business models that depend on subsidies, offtake contracts and export markets that do not yet fully exist. How PFC structures and prices those loans, and what share of them drift into the watch-list stage in the first few years, will show whether the lender learned from the coal decade.
Behind all three sits the money. The distribution reform scheme still has much of its roughly ₹3 lakh crore outlay to run, and PFC's role as its administrator gives it leverage over the very borrowers it lends to.[^14] That leverage ends when the scheme ends. What replaces it will matter as much as any merger decision.
So the tension that has run through this story remains. A state-owned financier earns high returns because the state stands behind it, and trades at a deep discount because the state stands behind it. The open question is whether those two facts can ever be separated, or whether the low multiple is simply the permanent price of a sovereign's embrace.
XIV. Outro
On a summer night, the lights of the National Capital Region stretch to the horizon: apartment towers, metro stations, malls and factories, all humming on a grid that loses money on much of the power it delivers to farms a few hundred kilometres away. Not far from Connaught Place, in the offices of a company with a few hundred employees, sits the balance sheet that paid for much of that grid.
Forty years after it was set up to do a job no one else would take, Power Finance Corporation earns close to $3 billion a year and roughly 18% on its equity, lending to customers that by most commercial standards should never have been lent to at all.[^5] It began in 1986 as the state's answer to banks that refused the job. It became, in March 2019, the state's answer to a budget gap. Today it is something stranger still: a hugely profitable lender whose profits depend on keeping a chronically broken, indispensable public utility alive. India's lights stay on partly because PFC lends, and PFC keeps getting paid partly because New Delhi can switch the lights off.
References
-
PIB Release: PFC completes acquisition of 52.63% stake in REC Ltd — Press Information Bureau, 2019-03-28 ↩↩↩
-
Economic Times: Power Finance Corporation buys government stake in REC for Rs 14,500 crore — Economic Times, 2019-03-29 ↩↩
-
Reuters Company Profile: Power Finance Corporation Ltd — Reuters ↩
-
CARE Ratings Rationale: Power Finance Corporation Ltd — CARE Ratings, 2025-03-24 ↩↩↩↩↩↩
-
CRISIL Rating Rationale: Power Finance Corporation Ltd — CRISIL, 2025-06-12 ↩↩↩↩↩
-
Moneycontrol: Why PFC-REC merger faces regulatory roadblocks under RBI exposure norms — Moneycontrol, 2023-11-20 ↩
-
ICRA Rating Rationale: Power Finance Corporation Ltd — ICRA, 2025-04-18 ↩↩
-
Bloomberg Company Overview: Power Finance Corp Ltd — Bloomberg ↩
-
PIB Release: PFC achieves Maharatna Status — Press Information Bureau, 2021-10-12 ↩
-
PFC Corporate Governance Report & Voting Results 38th AGM — BSE India, 2024-09-27 ↩↩
-
PFC Shareholding Pattern Filing Q1 FY2026-27 — National Stock Exchange of India, 2026-07-15 ↩↩
-
CARE Ratings Rationale: Power Finance Corporation Ltd — CARE Ratings, 2025-03-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube