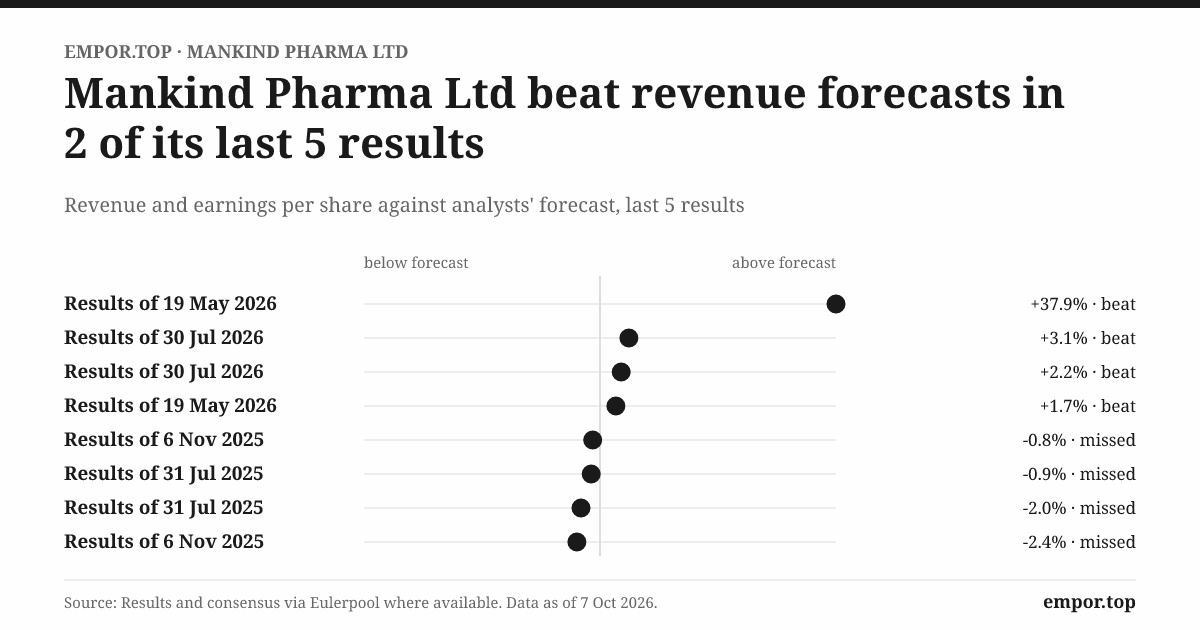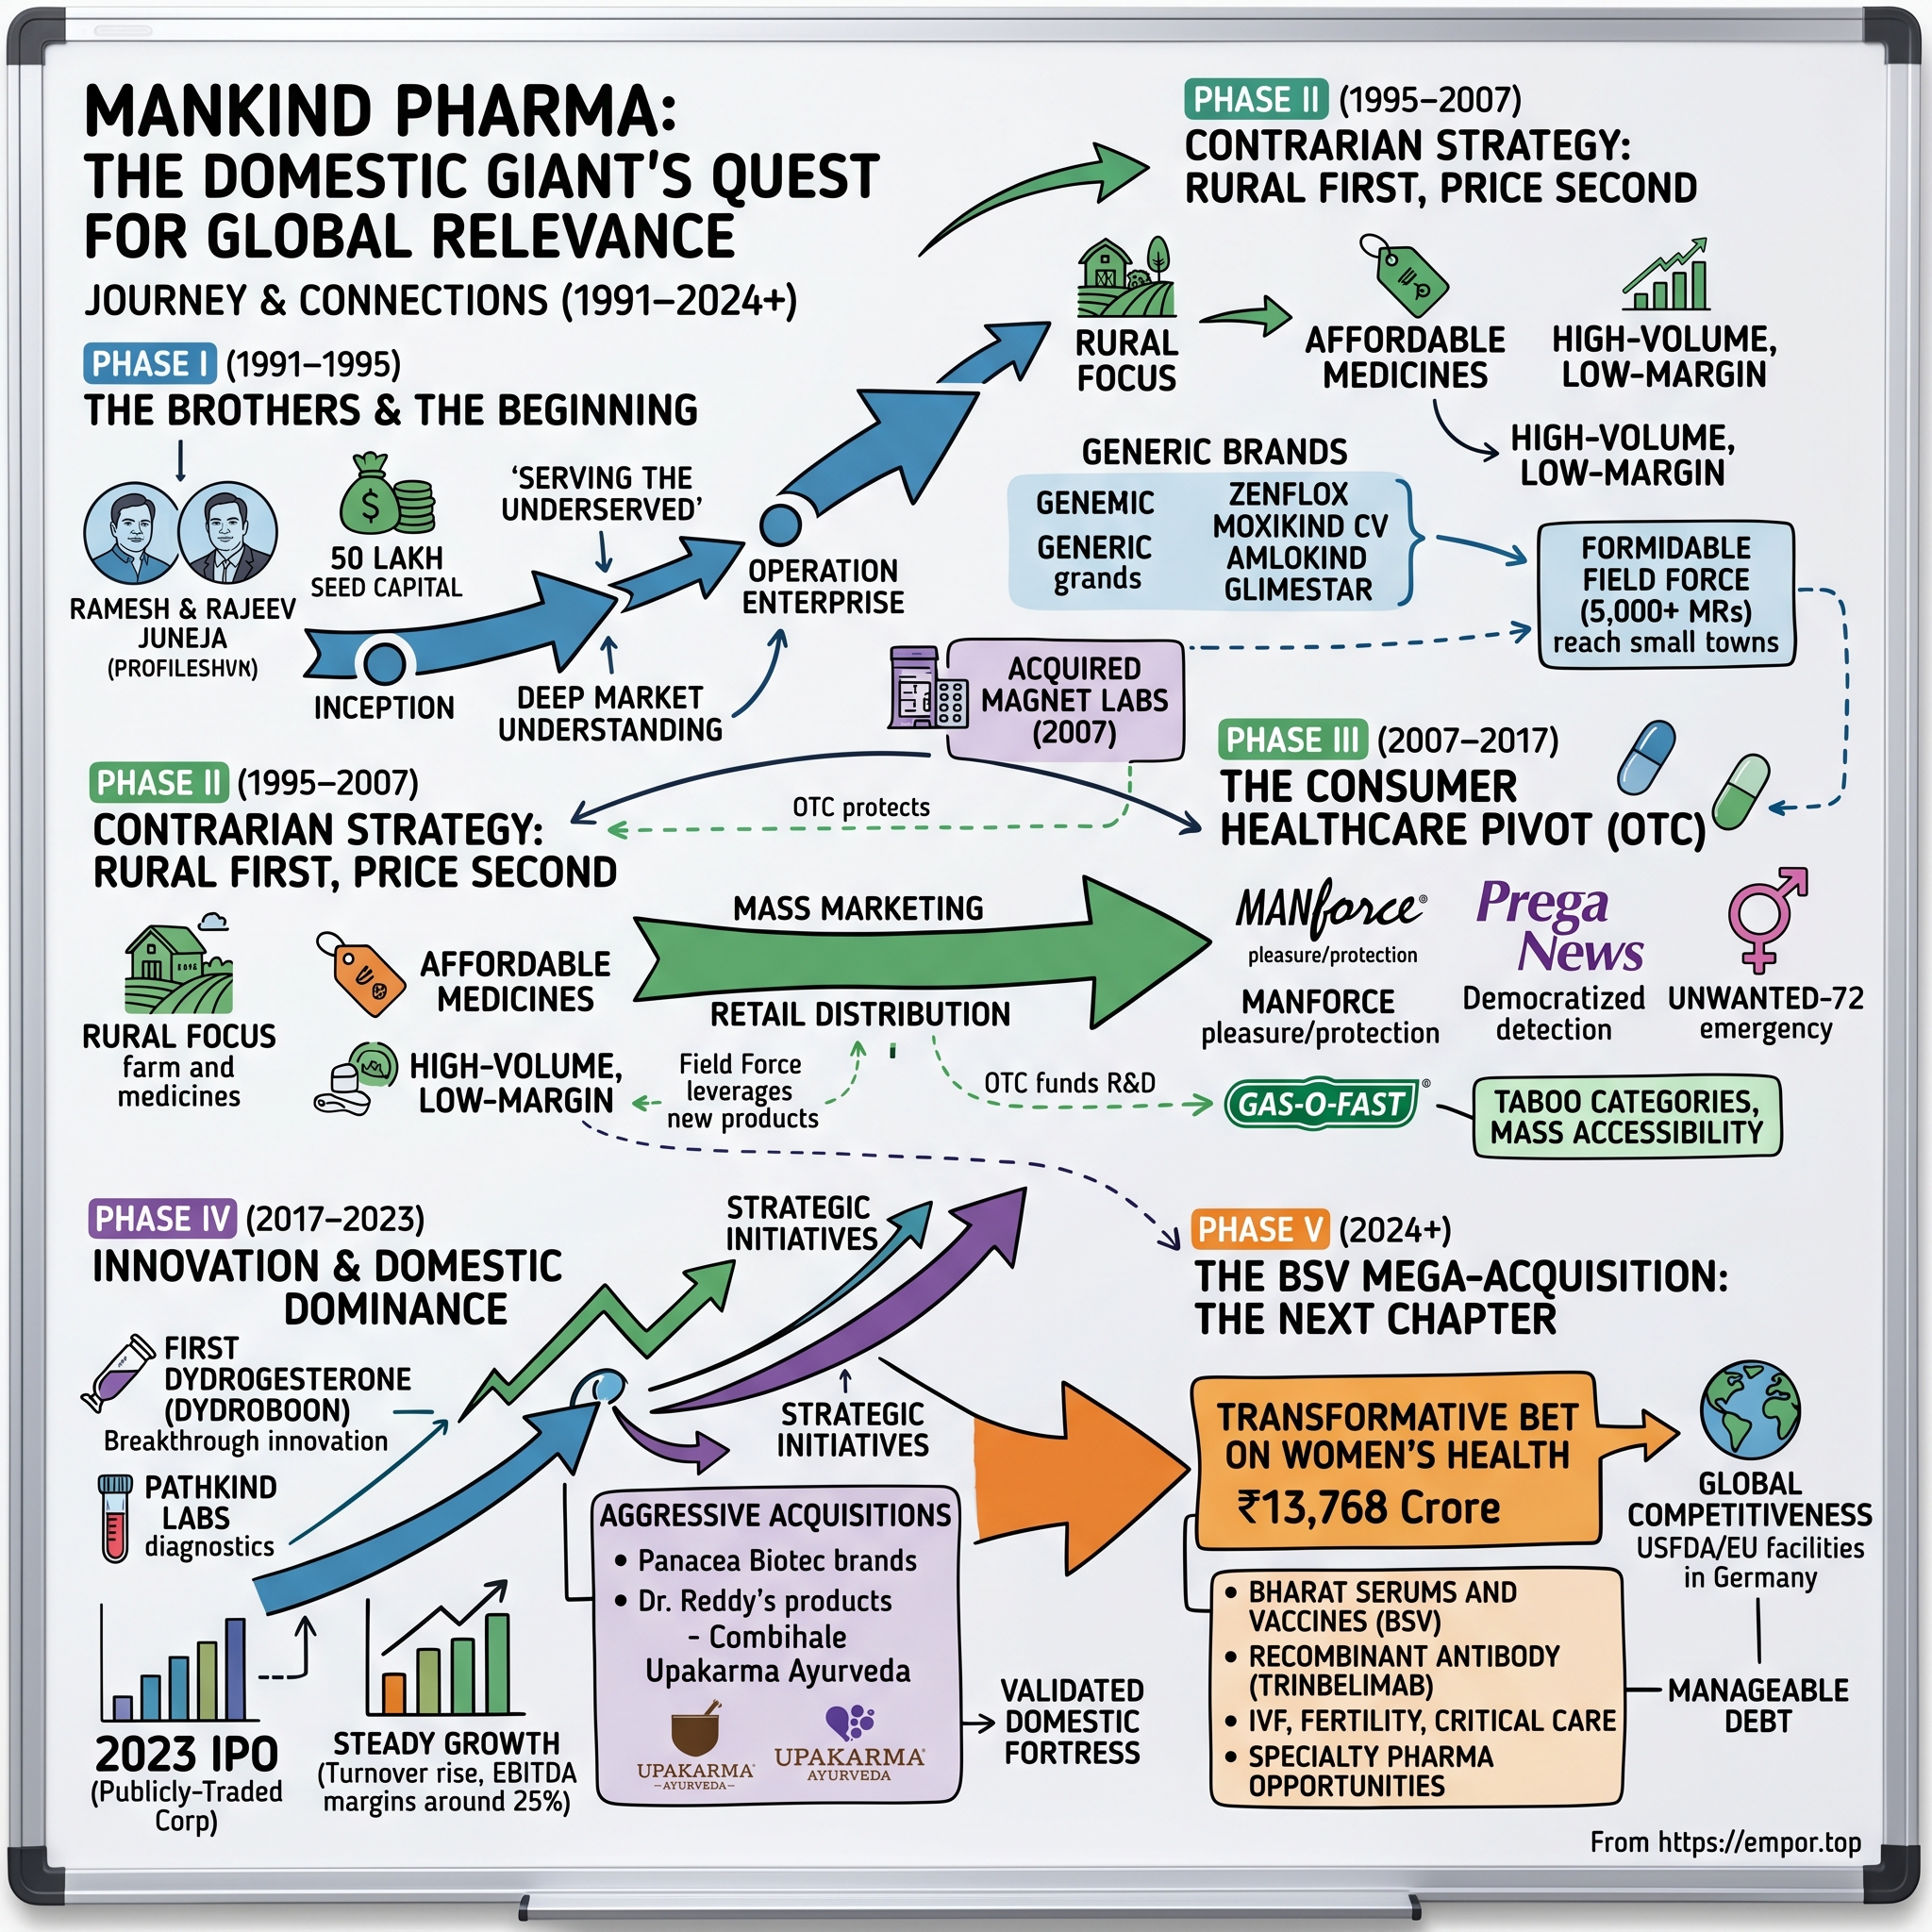
Mankind Pharma: The Domestic Giant's Quest for Global Relevance
I. Introduction & Episode Roadmap
The first week of May 2023 should have been a pure celebration for the Juneja family. On May 9, Mankind Pharma shares began trading on India's stock exchanges at a premium of roughly 20% to the ₹1,080 issue price8. The offer had been oversubscribed about fifteen times, and qualified institutional buyers bid for nearly fifty times the shares set aside for them1. Two brothers who had started the business with ₹50 lakh of family money had become the founders of one of India's most valuable drug companies.
Two days later, Income Tax Department officials showed up at the company's premises to carry out a search[^14].
It is hard to find a better opening image for this company. On listing day the market priced Mankind as India's most efficient domestic pharmaceutical machine. The tax officers were there to examine what that machine actually spent to win doctors. Those two pictures still sit side by side three years later, and the stock market has to decide between them every trading day.
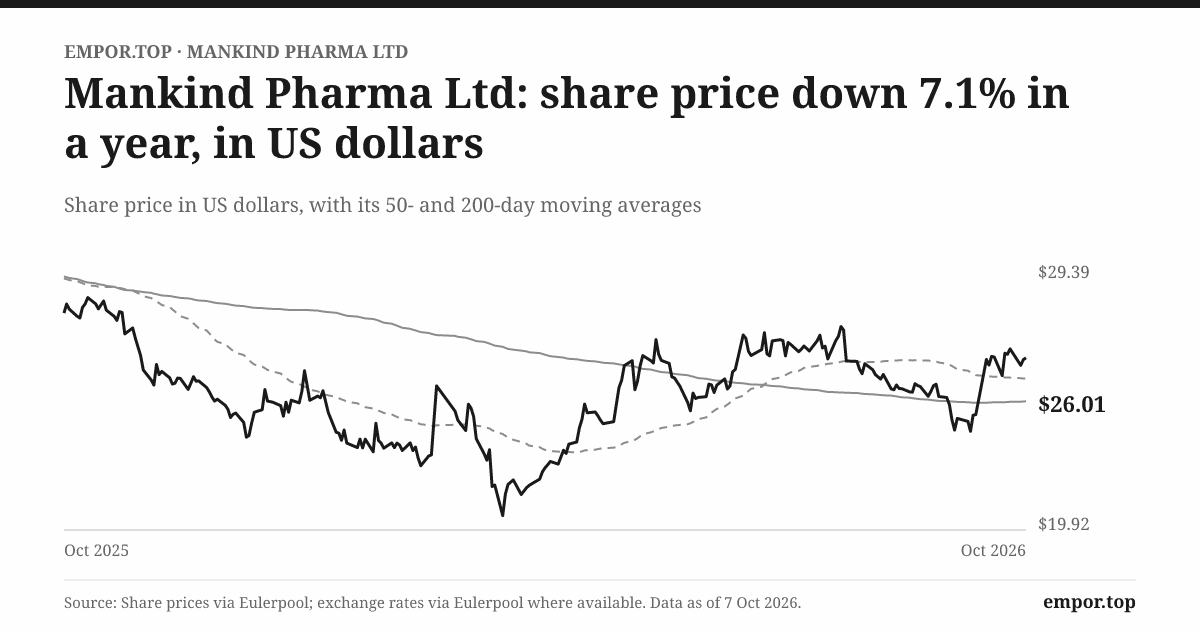
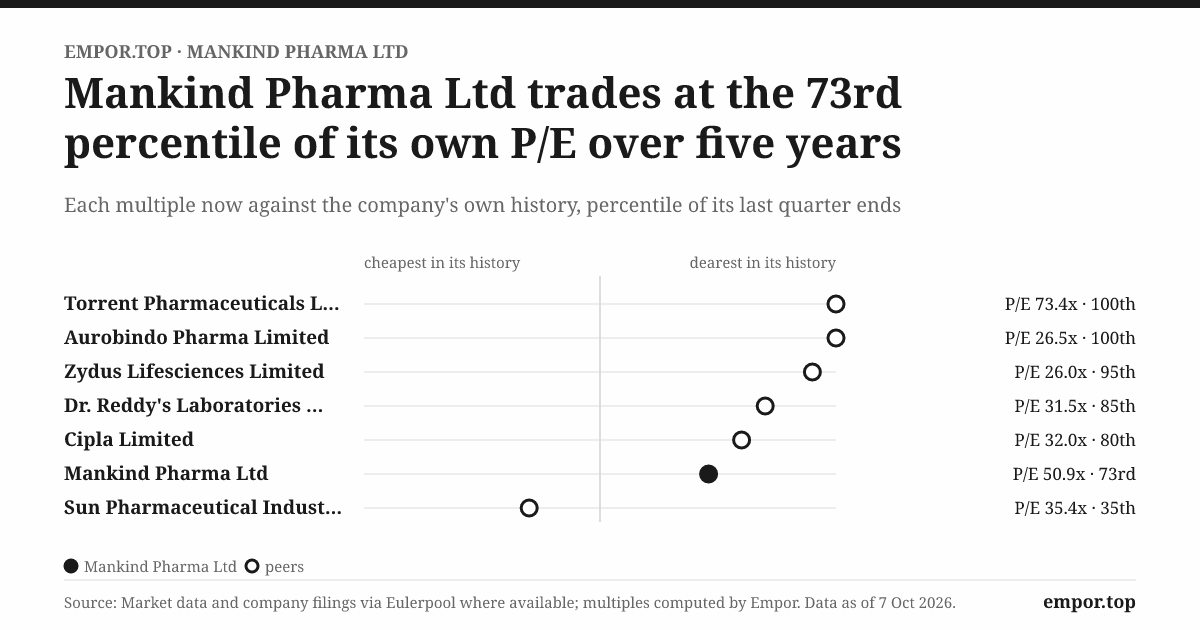
As of October 7, 2026, Mankind is worth about ₹103,880 crore ($10.7 billion). It trades at roughly 51 times trailing earnings, close to its own five-year median of about 49 times2. About 86% of its revenue comes from India2, which makes it unusual among India's pharma majors. Sun Pharma, Dr. Reddy's, Cipla and Lupin built their fortunes as "pharmacies to the world", filing generic applications with the US Food and Drug Administration and selling into American pharmacy chains. Mankind mostly stayed home. It ranks fourth in the Indian Pharmaceutical Market (IPM) by value, with about a 4.7% share, and second by volume, with about 6.1%. Its products are written on more than 53 crore prescriptions a year2.
That gap between value rank and volume rank is the whole company in miniature. Mankind sells more units than almost anyone in India at lower average prices than its peers. It got there with a field force of more than 18,500 medical representatives calling on more than 500,000 doctors2, many of them in towns that the multinationals and Mumbai's export champions never thought worth a visit.
The central question is whether a company built on cheap branded generics for India's hinterland can turn itself into a higher-barrier specialty and biologics business. The alternative is that a ₹1 lakh crore valuation is running ahead of what the business can deliver. In 2024 Mankind made its biggest wager on that transformation: it paid ₹13,768 crore for Bharat Serums and Vaccines (BSV), its first large debt-funded deal2. The bill shows up across the financial statements. Return on capital employed fell from the twenties to about 13%, reported profit fell 3.9% in FY2026 even though revenue grew 17%, and goodwill and intangibles now make up more than half of total assets2.
The verdict in brief: Mankind built a formidable domestic commercial engine by serving "Bharat", the India of small towns and rural clinics, while its peers chased export dollars. Its premium valuation now depends on three things at once: moving from low-cost acute pills to complex biologicals, paying down the BSV debt, and getting through a tax dispute that goes to the heart of how Indian pharma sells.
This story moves in six arcs:
- The bootstrapped start in Meerut and the brothers' rejection of the export playbook.
- The "Bharat" distribution engine: cheap antibiotics, small-town doctors, short cash cycles.
- The consumer-health detour that made condoms, emergency contraception and pregnancy tests into household brands.
- The move from acute to chronic therapies, and the Panacea Biotec deal.
- The IPO, the tax search, and the BSV mega-acquisition.
- The moat analysis, the skeptic's stress test, and the lessons.
The story begins with a man carrying a sample bag through western Uttar Pradesh.
 Subscribe on LinkedIn
II. The Medical Rep's ₹50 Lakh Rebellion (1991–1995)
Picture western Uttar Pradesh in the late 1970s: dust, cycle rickshaws, and a young medical representative named Ramesh Juneja on his rounds. His bag held samples and literature, and his day was a string of visits to general practitioners in Meerut and the surrounding towns. Before founding Mankind he spent years as a front-line representative, including about eight years at Lupin1. That job teaches one thing very well: which doctors actually prescribe, which drugs their patients can afford, and which brands never reach the shelf of a small-town chemist.
Mankind did not start in a laboratory. Its founders were salesmen who knew the prescription pad better than the reactor vessel. Ramesh's younger brother Rajeev Juneja joined him in the trade, and together they formed the core of what became a family-run company1. Today Ramesh is Executive Chairman, Rajeev is Vice Chairman and Managing Director, and Sheetal Arora, a member of the extended family, is CEO2.
The company was incorporated in 1991. Its corporate identity number still carries that year and the Delhi registration2. Commercial operations began in earnest in 1995 with about ₹50 lakh of pooled capital1. For scale, that would buy a modest house in a Delhi suburb. It does not buy a drug-discovery program.
The 1990s landscape. India's pharma industry had been shaped by the Patents Act of 1970, which protected manufacturing processes rather than molecules. Indian chemists could legally reverse-engineer any drug through a different route, and a generation of companies became world-class at doing so. When liberalisation opened the economy in 1991, the ambitious ones looked west. The US generics market paid in dollars, and the route to it ran through FDA-inspected plants and Abbreviated New Drug Applications (ANDAs), the filings that let a generic copy an off-patent drug. Ranbaxy, Dr. Reddy's, Sun and Lupin all made that pilgrimage.
The contrarian insight. The Junejas saw something different from the ground. Most Indians lived in rural and semi-urban areas, were served largely by general practitioners and informal practitioners, and were barely touched by the big brands' detailing. The multinationals priced for metro specialists, and the Indian champions were reallocating management attention toward New Jersey. That left a gap in Indian towns of 50,000 to 5 lakh people. It was a market of large volume and modest margin, where the winner would be whoever could get affordable branded generics into the most clinics.
Is this an origin myth tidied up after the fact? Partly. Every successful company eventually tells a story about seeing what others missed. But the record supports the essential claim. Even at its 2023 IPO, Mankind was overwhelmingly a domestic business. It had built its scale in India, with exports a small sideline1. Its peers had the reverse mix. What looked like a lack of ambition turned out to be a choice about where to compete.
Why the choice mattered. A US generics business is a commodity auction. A handful of wholesalers and pharmacy buyers hold most of the bargaining power, prices for a molecule can fall by more than half within a couple of years of launch, and a single FDA warning letter can freeze a plant. A domestic branded-generics business is a relationship business. A doctor in Agra who trusts a rep and a brand keeps writing the brand name, and the chemist dispenses it. Prices are lower than in the US, but they are far stickier. The Junejas chose the business where a salesman's skill compounds instead of the one where a regulator's inspection can wipe out a year.
The trade-off was real. Mankind gave up dollar revenue, the prestige of export rankings, and, for a long time, any claim to scientific credibility. It held zero product patents of note. It was what Mumbai's pharma elite might have called a "trading company with factories". The next decade showed how much that underestimated it.
III. Selling to "Bharat": The Low-Price, High-Volume Rural Bet (1995–2007)
Imagine a clinic in a district town in the late 1990s: a single room, a wooden bench, a queue of farmers with fevers and coughs, and a doctor who sees sixty patients before lunch. Representatives from the big multinationals rarely call here. When a young Mankind rep walks in, speaking the local dialect and carrying an antibiotic priced well below the market leader, he is not interrupting the doctor. He is solving the doctor's problem, because a patient who cannot afford the prescription does not get better and does not come back.
That clinic was the atom of the Mankind machine.
The product strategy was simple. Take well-established molecules whose patents and novelty had long expired, launch them under a memorable "-kind" brand, and price them noticeably below the leaders. The early portfolio leaned on anti-infectives. The ofloxacin brand Zenflox and the amoxicillin-clavulanate combination Moxikind-CV became workhorse brands. Later, cardiovascular and diabetes brands such as Amlokind (amlodipine) and Glimestar (glimepiride) brought the same playbook to chronic therapies1. A 30–50% discount to the leaders is how the company and the trade described the early pricing gap. Mankind does not publish a product-by-product price history, but the volume-versus-value gap that persists today is the lasting evidence of the strategy. A company ranked second by volume and fourth by value is, by definition, selling below the average price of its peers.
The field-force playbook. Mankind hired reps locally, people who knew the towns, spoke the language and understood that a rural practitioner's day had nothing in common with a Mumbai cardiologist's. The incentives rewarded prescription counts rather than prestige detailing. Over time the organisation grew into a sales army of more than 18,500 reps covering more than 500,000 doctors2. Every new rep added coverage, coverage added prescriptions, prescriptions added volume, and volume lowered the unit cost of the factories and the distribution network. That in turn paid for more reps.
The flywheel, stated plainly: - Low pack prices pull in volume from patients and doctors that the leaders priced out. - High volume spreads manufacturing and distribution costs, so thin per-pack margins still add up to fat absolute profits. - Profits fund more reps in more towns. - More reps deepen doctor loyalty that an urban-focused rival cannot cheaply replicate. To match Mankind's prices, the rival would have to cut prices on its own lucrative metro business.
That last step is classic counter-positioning, a concept revisited in Section VIII. Incumbents could see what Mankind was doing. Copying it would have damaged their existing business.
Working-capital discipline. A low-margin business dies if its customers pay late. Mankind sold through stockists and carrying-and-forwarding agents on short cycles, and the numbers show it. In FY2019, the earliest year in the consolidated series, debtor days stood at about 162. That is unusually tight for Indian pharma, where distributors routinely stretch payments. The figure has since risen to the mid-40s2, mostly because BSV's institutional and hospital customers pay more slowly. Debtor days are worth watching for exactly that reason. They are the clearest sign of whether the BSV mix is changing the quality of Mankind's cash.
The first acquisition. Mankind began buying capabilities fairly early. Acquiring Magnet Labs gave it a foothold in neuropsychiatry and CNS therapies1. It was small, but it set a pattern: Mankind bought therapeutic adjacencies and then pushed them through its own distribution pipe.
A historical falsification test. The obvious objection to a low-price generic franchise is that low price is not a moat. Any competitor can cut its price, a chemist can substitute an equivalent, and the doctor's loyalty is to the molecule, not the brand. If that were the whole story, Mankind's share should have been competed away as rivals woke up to the rural opportunity. The record says otherwise. A quarter-century later Mankind still ranks second in the IPM by volume, and its prescription count has led the market for years. Rating agencies cite it as having the highest prescription volumes for eight straight years45. Rivals did not make that ranking disappear.
The record also narrows the claim. Mankind's value share of about 4.7%2 is lower than its volume share, so the moat protects how many packs it sells far more than what it can charge for them. The disadvantage showed up in FY2025, when a field-force restructuring caused domestic volume growth to slow to around 0.5%[^7]. The machine is powerful, but it needs constant feeding, and when it stalls the drop is visible within quarters. The honest version of the claim is that Mankind has a durable distribution advantage, not durable pricing power.
By 2007 the machine was humming. The brothers then did something no one expected of a company of salesmen: they took their brands into the bedroom.
IV. Breaking the Bedroom Taboo: Manforce, Prega News, and the OTC Pivot (2007–2017)
In the late 2000s, Indian television viewers began seeing advertisements unlike anything a pharmaceutical company had put on air. Manforce condom ads were bold, flirtatious and occasionally scandalous. Prega News ads showed a woman learning she was pregnant at home, privately, on a card that cost about as much as a cup of coffee and a samosa. This was a doctor-detailing company that had never needed consumer advertising. Now it was speaking straight to the consumer on topics most Indian households did not discuss at the dinner table.
That was a commercial risk as well as a cultural one. The general practitioners who made Mankind were often conservative men in small towns. Would they balk at a company whose brand flashed across late-night television in condom commercials? Evidently not. The prescription business kept growing alongside the consumer one.
The consumer brands that resulted: - Manforce condoms competed against the government's subsidised Nirodh and against imported premium brands. It used flavour variants and aggressive pharmacy placement to become the category leader1[^15]. - Prega News turned pregnancy testing from a clinic visit into an affordable, private purchase and took a dominant share of the home-test market1[^15]. - Unwanted-72 brought emergency contraception to pharmacy counters in semi-urban India1. - Gas-O-Fast (antacid) and AcneStar (dermatology) extended the formula into everyday ailments2.
The Ken reported that Mankind built India's largest condom and pregnancy-kit brands largely through this mix of advertising and distribution[^15]. The company says Manforce and Prega News rank first in their categories2. The exact share figures circulating in coverage vary, so the safe statement is that these are category leaders by a wide margin, not a precise percentage.
Why this worked, and why it was clever. The consumer brands rode on infrastructure Mankind already had. The same chemist counter that stocked Moxikind-CV and Amlokind could display a Prega News strip at almost no extra distribution cost. In effect Mankind attached a consumer-goods business to a pharma distribution network, and the incremental spend was advertising rather than reps. A consumer brand also has a property a prescription brand lacks: the buyer asks for it by name. A chemist can quietly substitute a cheaper amoxicillin. It is much harder to substitute a pregnancy test the customer has seen on television.
There was a regulatory dividend too. Indian price controls under the National List of Essential Medicines (NLEM) are aimed at prescription drugs considered essential. Consumer wellness brands sit largely outside that regime. As price caps tightened over the following decade, the OTC portfolio gave Mankind a profit pool the regulator could not easily touch.
How much does the consumer business contribute? Mankind reports it within its domestic business rather than as a separately audited segment with its own margins2. The claim that consumer margins exceed prescription margins is plausible given the absence of rep costs, but the company does not publish a segment margin to prove it. Investors should hold it as a likely truth, not a demonstrated one.
An entity boundary worth noting. The Juneja family also built Pathkind Labs, a pathology and diagnostics chain, but held it outside the listed company. Pathkind Diagnostics Private Limited is a promoter-controlled related party. Its sales from Mankind amounted to about ₹1 crore in FY20262. Its revenue, labs and growth belong to the family, not to Mankind shareholders.
Why keep it out? The family has not explained this publicly. One reading is benign: diagnostics is a different business with different capital needs. The less comfortable reading is that the family kept some attractive healthcare adjacencies for itself, a pattern it has repeated with packaging suppliers and real estate (see Section VII). It is not a scandal. It is a reminder that the listed company is one slice of a larger family healthcare enterprise, and investors own only that slice.
The consumer pivot proved Mankind could build brands. The next decade asked a harder question: could it build science?
V. The Domestic Fortress and the Chronic Leap: Dydroboon to Panacea (2017–2023)
The danger Mankind faced in the late 2010s did not look like a competitor. It looked like a government notification. Each time the National Pharmaceutical Pricing Authority (NPPA) added molecules to the NLEM ceiling-price list, some of Mankind's acute brands (antibiotics, painkillers, gastro drugs) lost pricing headroom overnight. A company that already competed on price was now being told by the state where that price could sit. Periodic bans on "irrational" fixed-dose combinations, a category Indian generic makers had used heavily, added to the pressure2.
The strategic answer was to move up the value chain, toward therapies patients take every month for years and toward molecules that are hard to make.
The chronic shift. Chronic therapies (cardiac, anti-diabetic, CNS and respiratory) made up about 27.9% of Mankind's domestic sales in FY2018. By FY2026 the figure was about 38.5%2. That is a meaningful change, but its pace matters: roughly a point and a bit a year over eight years. Chronic prescriptions are valuable because they recur. A diabetic patient on a Mankind brand refills every month, and the doctor rarely switches a stable patient. The shift is real but gradual, and acute therapies still account for more than 60% of domestic sales.
The Dydroboon story. Dydrogesterone is a synthetic hormone used in threatened miscarriage and infertility treatment. For decades the market belonged to Abbott's Duphaston, because the molecule is notoriously hard to make: its synthesis requires a light-driven step that most generic chemists avoid. Mankind developed its own route and launched Dydroboon, putting a domestic challenger into one of the most sensitive categories in women's health1. Its large network of gynaecologists, already built through Prega News and Unwanted-72, gave the launch a ready audience.
Dydroboon matters strategically because it was the first time Mankind's edge was chemistry rather than price or reach. It also shows how the pieces of Mankind reinforce each other. The consumer women's health brands built gynaecologist relationships, and the complex molecule monetised them. That logic later shaped the BSV deal.
Buying brands, not building them. In 2022 Mankind bought Panacea Biotec's domestic formulations brands, moving into transplant, nephrology and specialty diabetes. Business Standard reported completion of the sale in April 20229, for about ₹1,872 crore. The deal made FY2022 an unusual year in the cash-flow statement: free cash flow was negative that year, the only negative year in the eight-year record2, because acquisition spending exceeded operating cash. The company also acquired respiratory and other brands carved out of larger companies and took a majority stake in Upakarma Ayurveda1.
The manufacturing footprint. Mankind built a network of about 25 manufacturing facilities and several R&D centres across India, much of it in tax-advantaged hill-state locations such as Himachal Pradesh and Sikkim1. In-house manufacturing keeps cost of goods low. As Section VI shows, the tax holidays attached to some of those plants later became part of a dispute.
Historical falsification: was this an R&D company now? The tempting narrative after Dydroboon is that Mankind became an innovator. The spending record rejects that. R&D was about ₹188 crore in FY2023, or 2.1% of revenue, and rose only to about 2.8% in FY2026, with most of the increase coming from BSV's biologics2. Global innovators spend 15–20% of sales on research, and India's export-oriented generic majors typically spend 6–9%. Mankind's skill is process chemistry, fast commercialisation and distribution, not discovery. Dydroboon is best read as an isolated technical win harvested through a superb sales channel. It is not proof of a pipeline.
What the financials say about this era is mixed. Revenue grew at high-teens rates. Operating margin, however, fell from about 33% in FY2019 to about 19% by FY20232. Part of that is accounting comparability across early years, but part is real: a bigger field force, chronic-therapy investments, and price-cap pressure all ate into the margin. The fortress got bigger without getting more profitable per rupee of sales. That set up the next chapter: the family needed liquidity for its backers, and the company needed a new growth engine.
VI. Going Public Clean: The ₹4,326 Crore Secondary Exit and the Tax Raid (2023)
The listing ceremony in May 2023 was a classic Indian capital-markets spectacle: brokers in suits, a gong, the founders smiling for the cameras. On May 9 the stock opened about 20% above the ₹1,080 issue price8. The institutional book had been oversubscribed about 49 times, the overall issue about 15 times, while the retail portion was undersubscribed1. Large funds were enthusiastic, and small investors were wary.
The structure of the IPO deserves a close look. Every one of the roughly 4 crore shares on offer was sold by existing shareholders. The offer raised about ₹4,326 crore, and none of it went to the company12. The sellers were private equity backers, ChrysCapital through Cairnhill and Capital International through Beige, plus members of the promoter family1.
What the zero-primary structure tells investors. A company sells new shares when it needs money. Mankind did not. Its balance sheet carried almost no debt, and operations threw off cash. The IPO was a liquidity event for the backers and a price-discovery event for the family, not a capital raise. That is not a criticism. It is better than a company issuing shares to fund vanity capex. But investors should be clear that the IPO's purpose was to let owners sell. The price they were offered was set by sellers.
Then came the search. Within days of listing, income tax officials began a search under Section 132 of the Income-tax Act at Mankind premises[^14]. Mint reported searches at multiple locations[^14]. The search itself did not sink the stock, but its consequences now sit in every annual report.
The forensic findings. Assessment orders issued after the search proposed aggregate adjustments of about ₹1,869 crore. The largest piece, about ₹1,574 crore, disallowed sales-promotion and marketing spending under Section 37(1). That section bars deductions for expenditure that is illegal or prohibited, and since a 2022 Supreme Court ruling it has been applied to freebies given to doctors in breach of medical-council ethics rules2. Another ₹257 crore partially disallowed tax-holiday deductions for hill-state plants under Sections 80IC and 80IE2.
Why this matters beyond the numbers. A Section 37(1) disallowance is an accusation about the business model, not just a bookkeeping disagreement. The tax department is saying that a large share of what Mankind spent to win doctors was the kind of inducement the law will not let it deduct. Mankind's sales engine is its field force and its doctor relationships, so the dispute goes to the core of how the company competes. It also applies across Indian pharma: the whole industry has used doctor conferences, travel and gifts, and the tax department's posture since 2022 targets them all.
The auditor's warning. Mankind's joint statutory auditors, S.R. Batliboi & Co. and Bhagi Bhardwaj Gaur & Co., did not qualify their opinion. They included an Emphasis of Matter drawing attention to the tax proceedings and noted that the matter "may have an adverse effect on the functioning of the Group"2. An Emphasis of Matter is the auditor saying the numbers are fine but that the reader must look at this. It is a yellow flag, not a red one, and it has persisted.
Where the money stands. Disputed income tax demands pending before the Commissioner of Income Tax (Appeals) total about ₹898 crore across years from FY2014 to FY2024. Mankind has deposited about ₹228 crore under protest2. Management's position is that the assessment orders ignore tax already paid and deductions the company voluntarily disallowed in its own returns, and that the demands will be contested2. That is management's argument. The appellate authorities have not yet ruled.
To put it in perspective, the largest disallowance, about ₹1,574 crore, is close to a full year of Mankind's net profit (about ₹1,938 crore in FY2026)2. The cash at risk is lower, because a disallowance raises taxable income rather than becoming a liability one-for-one. At India's corporate tax rates, the realistic incremental tax plus interest on the whole adjustment would be in the hundreds of crores rather than thousands, and a large part has already been demanded and partially deposited. The risk is real but probably survivable. The bigger cost may be the precedent: if Section 37(1) disallowances stick, Mankind's effective tax rate on future marketing spend rises.
A small governance footnote. Late 2024 brought unusual churn in the company secretary role. One CS left at the end of November, his replacement was appointed in early December and exited in early January, and a third was appointed on January 9, 20253. Taken alone it is minor. Next to a live tax dispute and a large acquisition, it is the kind of detail an attentive investor notes and watches.
The IPO and the search framed the stakes. Fourteen months later Mankind made the decision that defines the current story.
VII. The ₹13,768 Crore Gamble: Buying BSV to Build a Specialty Platform (2024–2026)
On July 25, 2024, Mankind announced that it would acquire Bharat Serums and Vaccines from Advent International[^13][^5]. The headline price was around ₹13,630 crore, and the final consideration came to about ₹13,768 crore once the deal closed in October 20242. For a company whose largest prior deal was Panacea, roughly ₹1,900 crore, this was a jump of an order of magnitude. A company famous for an unlevered balance sheet was about to borrow billions of rupees.
What Mankind was buying. BSV is a specialty biopharma business focused on women's health, fertility and critical care. Its products include recombinant and urinary fertility hormones (FSH, menotropins) used in IVF, anti-D immunoglobulin used in Rh-incompatible pregnancies, and plasma-derived and critical-care biologicals[^5]. In FY2024 it generated about ₹1,723 crore of revenue, growing about 20%, with roughly 28% EBITDA margins[^5].
A simple analogy shows why this matters. Making a chemical generic is like following a well-known recipe in a commercial kitchen: competent cooks anywhere can do it. Making a biological is like brewing a particular beer with a living yeast strain. The organism, the fermentation conditions and the purification steps are the product, and two plants following "the same recipe" can produce materially different results. That is why regulators demand much more evidence before approving biological copies, and why fewer companies can make them. BSV gives Mankind entry into a market where the barrier is the manufacturing know-how rather than the sales force.
The strategic logic, according to management on the acquisition call, was that BSV's fertility and pregnancy portfolio fits naturally with Mankind's existing women's health franchise (Prega News, Unwanted-72, Dydroboon) and its gynaecologist network. Mankind's reach could push BSV's products deeper into India, and BSV's science could give Mankind higher-value products to sell[^6]. It is a coherent story. It is also, so far, mostly a management claim. The test is whether BSV keeps growing at around 20% under Mankind ownership.
The price. At roughly eight times revenue and about 28 times EBITDA[^5], Mankind paid a full multiple, well above the four-to-five times revenue typical of Indian branded-formulation deals. Defenders argue that biological assets with high barriers deserve a premium. Skeptics note that Advent, a sophisticated seller, chose to sell at that price.
Financing the deal. The cash came from three sources: - Equity. In September 2024 Mankind raised about ₹3,000 crore through a qualified institutions placement, issuing about 1.43 crore shares at around ₹2,100[^11]2. It was Mankind's first primary equity raise since listing. It diluted the promoters from about 76.5% at IPO to just under 75% by March 20252. - Bonds. About ₹5,000 crore of listed secured non-convertible debentures (NCDs) in three series: ₹1,250 crore due April 2026, ₹1,250 crore due October 2026, and ₹2,500 crore due November 2027, all at coupons just under 8%, secured by a pledge of BSV shares26. - Short-term paper and internal cash. Commercial paper of nearly ₹1,933 crore at FY2025 year-end bridged the rest, together with Mankind's own treasury2.
Shareholders approved the borrowing limit, the acquisition, the QIP and the pledge by postal ballot, with assent above 99.5%73. The free float outside the promoters is small, so that number says more about the family's control than about minority enthusiasm.
The toll on reported earnings. The P&L changes are easiest to follow as three steps: 1. Interest rose from almost nothing to about ₹429 crore in FY2025 and about ₹639 crore in FY20262. 2. Depreciation and amortisation jumped to about ₹886 crore in FY2026 from about ₹621 crore2, mostly because acquisition accounting revalues BSV's brands and technologies as intangible assets that are then written down each year. 3. Exceptional items, including about ₹130 crore of integration charges, hit FY20262.
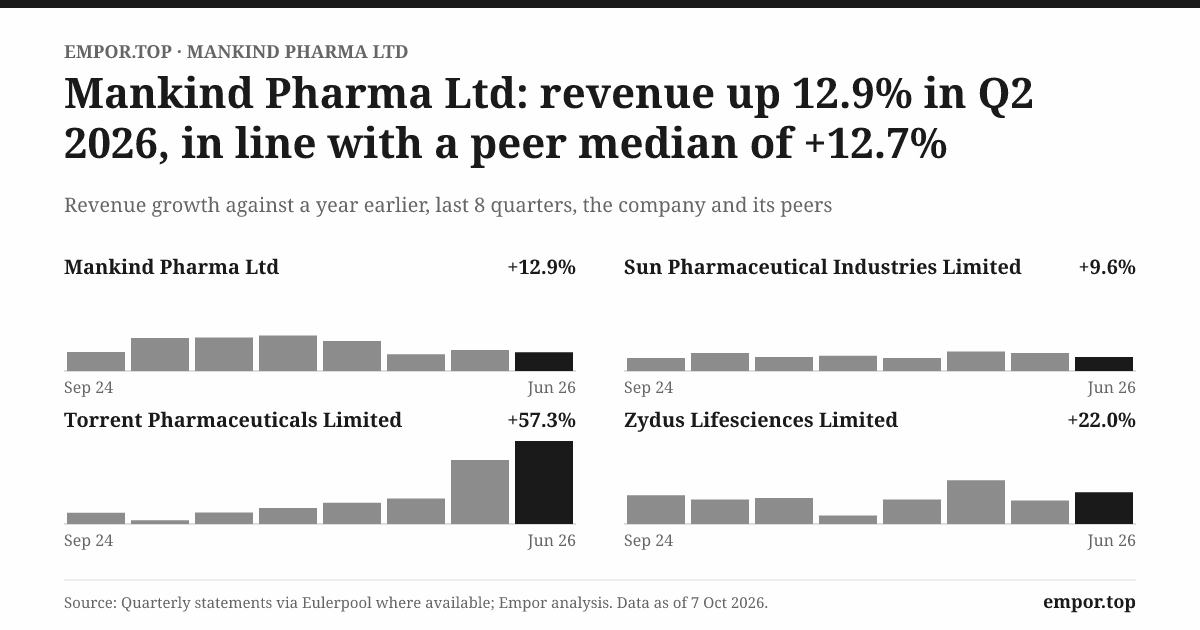
The result: revenue grew 17% in FY2026 to about ₹14,278 crore, but net profit fell 3.9% to about ₹1,938 crore2. The business sold more, and the deal's financing and accounting consumed the growth. Return on capital employed fell from about 23% in FY2024 to about 13% in FY20262. Two things depressed it at once: earnings were burdened, and capital employed ballooned with goodwill.
The balance sheet now carries the deal. Goodwill of about ₹6,493 crore and other intangibles of about ₹9,168 crore add up to roughly ₹15,661 crore, about 56% of total assets2. Goodwill is the premium paid over identifiable assets, essentially Mankind's bet on BSV's future growth. Under Indian accounting standards it is tested annually for impairment. If BSV underperforms the forecasts behind the price, a write-down follows.
The deleveraging. The most reassuring part of the story is what happened next. In FY2026 Mankind generated about ₹3,121 crore of cash from operations, up from about ₹2,413 crore2. It retired all of its commercial paper. Gross borrowings fell from about ₹8,483 crore to about ₹6,204 crore within a year, and net debt fell from about ₹5,784 crore to about ₹3,932 crore, roughly 1.1 times adjusted EBITDA24. The first ₹1,250 crore NCD tranche was repaid on schedule on April 16, 20262. ICRA and CRISIL both kept their AA+ ratings with stable outlooks, citing Mankind's domestic position and cash generation while flagging the leverage and tax litigation45.
Weighing the deal so far. Did Mankind overpay? The honest answer is that it paid a full price for a scarce asset, financed it more conservatively than the headline debt suggests, and has started paying it down faster than skeptics expected. What the deal has not yet proven is that the combination is worth more than its parts. Management's synergy narrative, Mankind's reach multiplying BSV's products, is plausible and unproven. On the Q4 FY2026 call, management pointed to BSV's growth and integration progress[^7]. The proof will be in BSV's reported growth and margins over the next two to three years, not in calls.
There is also a capital-allocation pattern to confront. The company that once prided itself on disciplined organic growth has now done two major deals in four years. The first, Panacea, produced a negative free-cash-flow year. The second turned a net-cash balance sheet into a levered one, and a third of the purchase price was funded with new equity. That is not diworsification: both deals sit squarely in branded pharma. It is, however, a regime change in how aggressively Mankind uses its balance sheet, and investors should price it as such.
That brings the story to the deeper question: what exactly protects Mankind's profits?
VIII. The Moat and the Machine: Hamilton Helmer's 7 Powers & Porter's Five Forces
Picture a carrying-and-forwarding agent's warehouse on the outskirts of Lucknow before dawn. Cartons of Moxikind-CV, Amlokind, Manforce and Prega News sit stacked on pallets, waiting for trucks bound for stockists in Sitapur, Bahraich and Gonda. From there they go to chemist shops, and from the chemists to patients whose doctors were visited last week by a Mankind rep. Mankind sells through more than 16,000 stockists and agents2. The scene is unglamorous, and it is the moat.
Does Mankind have a structural advantage, or just a large sales force anyone with money could replicate? Helmer's framework separates the two.
Hamilton Helmer's 7 Powers
- Scale Economies: High. More than 18,500 reps spread the fixed costs of marketing, distribution and manufacturing across more than 53 crore prescriptions a year2. A new entrant trying to reach the same doctor density would pay for the same infrastructure with a fraction of the volume. This is Mankind's strongest power and the one with the most evidence: a decades-long top-two volume rank24.
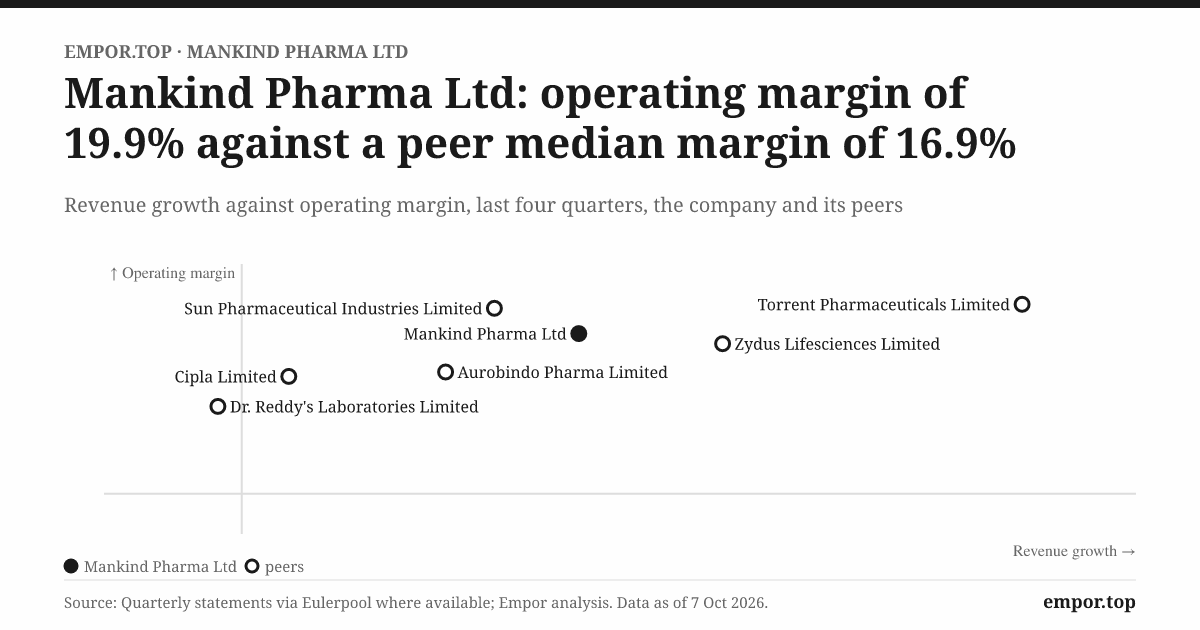
- Process Power: High. Mankind's low-cost manufacturing, its supply-chain coordination with stockists, and its ability to launch a "-kind" brand fast across thousands of towns are embedded routines that took decades to build. Evidence: it still earns about a 19% operating margin2 while pricing below the market.
- Branding: Moderate in Rx, High in OTC. Prescription loyalty belongs mostly to the doctor. A patient rarely knows or cares that their amlodipine is Amlokind. In consumer health, though, Manforce and Prega News are names customers ask for, which gives real pricing power in categories the regulator mostly ignores.
- Network Effects: Absent. A patient taking Moxikind does not make it more valuable for anyone else.
- Counter-Positioning: Historically High, Now Diminishing. In the 1990s and 2000s, incumbents could not match Mankind's prices without hurting their metro margins. That advantage fades as Mankind itself moves into chronic therapies, metros and specialty biologics. There it competes with Torrent, Sun and Abbott on conventional terms. Metro and Class 1 cities already account for more than half of its sales2. Mankind has become more like the incumbents it once out-positioned.
- Switching Costs: Low to Moderate. Chronic patients rarely switch a stable therapy, but chemists can substitute generics, and Indian policy increasingly encourages it.
- Cornered Resource: Emerging via BSV. BSV's biological manufacturing know-how, its fermentation and plasma-processing capabilities, and its regulatory approvals are hard to replicate quickly[^5]. This is the power Mankind lacked for most of its history, and buying it was the strategic purpose of the deal. A caution belongs next to the claim: a cornered resource that was bought rather than built must still prove it can grow under its new owner, and certification is not commercialisation.
The verdict on the moat. Mankind's moat is real, but its shape matters. It protects volume and reach (scale and process) far more than price. Its consumer brands carry real pricing power within a modest part of revenue. Its new cornered resource has been paid for but is still being proved. This explains why the BSV deal looked, from management's chair, close to a necessity: a domestic generic franchise with no proprietary science faces slow margin erosion from price caps and substitution.
Porter's Five Forces
- Buyer power: Low. No single customer accounts for 10% or more of revenue2. Mankind sells to thousands of stockists, and the prescribing decision belongs to hundreds of thousands of doctors. The state is the exception: it effectively acts as a buyer through NLEM price caps, and that regulatory "buyer power" is the binding constraint on acute pricing.
- Supplier power: Low. APIs and raw materials come from multiple sources. Related-party purchases from promoter-linked packaging and process firms (A.S. Packers, J K Print Packs, N.S. Industries, ANM Pharma and others) totalled about ₹197 crore in FY2026, around 1.6% of material costs2. The amount is immaterial. The governance question is not.
- Threat of substitutes: High. Nearly every molecule Mankind sells is off-patent, and an equivalent generic is always on the shelf. Jan Aushadhi government generic stores add to the pressure.
- Threat of new entrants: Low to Moderate. Building an 18,500-strong field force with decades of doctor relationships is slow and expensive. Digital B2B distribution platforms and e-pharmacies are a longer-term threat to how the detailing machine works.
- Competitive rivalry: Intense. Sun, Abbott India, Cipla, Torrent, Alkem, Macleods and others fight for every therapy area. No one in the Indian market holds more than about 8% value share.
Together the frameworks describe a company with a strong but narrow moat in an intensely competitive market. It now needs the BSV acquisition to add a second kind of advantage. That frames the lessons and the investor debate.
IX. Playbook: Business & Investing Lessons
1. Win Bharat before you chase Bombay. In 1995 the Junejas drove past the metro markets the multinationals coveted and sold to small-town general practitioners in Meerut and Agra. Thirty years later they rank second in the country by volume. The lesson for founders is that the best market is often the one incumbents consider beneath them, because their disdain is your counter-positioning. Mankind's fortress was built on the doctors its rivals didn't think worth the petrol.
2. De-stigmatise the counter to own the category. Prega News and Manforce did not win through chemistry. They won by turning embarrassment into convenience on national television. A company that makes a taboo purchase easy owns the category for a generation, because nobody else will spend the money to make it awkward again. Whoever says the unsayable first gets to name the category.
3. Clean earnings turn cash into firepower. From FY2019 to FY2026 Mankind generated about ₹12,679 crore of operating cash against about ₹11,406 crore of net profit, more cash than profit, and paid out barely 1% of its free cash flow as dividends2. That cash discipline is what let a company with no history of leverage absorb a ₹13,768 crore deal and still cut its debt by more than a quarter within a year. Mankind's balance sheet was its acquisition currency long before its shares were.
4. Financial engineering has an amortisation clock. After BSV, Mankind's factories and reps were busier than ever, revenue rose 17%, and reported profit still fell2. Interest and the amortisation of acquired intangibles separate operating reality from accounting reality for years after a large deal. Investors who judge an acquirer on headline EPS in the first two years judge the financing, not the business. A big deal buys a company and a few years of bad-looking earnings, and investors should expect both.
5. The regulatory bill always arrives. Doctor incentives built Indian pharma's volume, and in May 2023 the tax department arrived to price them[^14]2. The ₹1,574 crore Section 37(1) disallowance is less a fine than a repricing of the industry's sales model. A sales engine that runs on hospitality eventually gets audited for the hospitality.
X. Bear vs. Bull Case & Skeptical Stress Test
Picture the Q1 FY2027 earnings call in the summer of 2026. Analysts ask the questions that matter: whether chronic growth is accelerating, whether BSV is holding its margins, and how the company will repay ₹2,500 crore of NCDs due in November 2027. The CFO walks through the deleveraging path. The first-quarter numbers give management something to point to: revenue up about 13% year on year and net profit up about 30% from a depressed base, as interest costs eased2. The question behind every analyst question is the same: is the stock priced for this, or for perfection?
How the market prices Mankind. At about 51 times trailing earnings and about 25 times EV/EBITDA, with a free-cash-flow yield of about 1.3%2, Mankind trades in line with its own five-year history, which was set mostly before the BSV deal when returns on capital were much higher. Among peers, it sits closer to Torrent and Abbott India, which also trade at premium domestic-franchise multiples, than to Sun or Alkem, which trade at lower ones. The market is paying a premium domestic multiple for a company whose returns on capital are, for now, below those of its own past. The implicit assumption is that BSV will lift returns back up as debt and amortisation fall away.
The Bull Case - A domestic shield. About 86% of revenue comes from India2, largely insulated from US generic price erosion, FDA inspections, tariffs and currency moves. Forex sensitivity is small: a 1% move in the dollar shifts pre-tax profit by only a few crore2. - A specialty platform. BSV puts Mankind into fertility, IVF and critical care, which are high-barrier markets where it can earn more per patient. - A cash machine. Operating cash flow above ₹3,100 crore a year2 means the remaining NCDs can, on current trends, be repaid from internal cash. - Owners with skin in the game. Promoters own about 72.6%, with zero shares pledged2, and executive pay was flat in FY20262.
The Bear Case - A valuation with no cushion. At about 51 times earnings and a 1.3% FCF yield, the price assumes years of steady compounding with no setbacks. - The intangibles overhang. Goodwill and intangibles of about ₹15,661 crore are more than half of total assets2. If BSV's growth falls short, an impairment would hit book value and confidence. - The tax overhang. About ₹898 crore of disputed demands are pending, and the wider Section 37(1) theory could affect future marketing deductions2. The auditor's Emphasis of Matter will stay until there is an appellate ruling. - Acute fragility. More than 60% of domestic sales are still acute therapies exposed to price caps and substitution, and FY2025 showed how quickly volume growth can stall when the field force is reorganised[^7]. - Governance asymmetry. The three promoter-executives earned about ₹44 crore in FY2026, between about 164 and 387 times the median employee2. Family-owned packaging suppliers and a family-owned diagnostics chain remain outside the listed company. With the public float so concentrated in institutions, minority shareholders' influence is limited.
The activist's view. A skeptical long/short investor would ask four things. Why are packaging suppliers owned by the family rather than the company, even if the amounts are small? Why was the company's real estate historically moved to a promoter vehicle (Appian Multiventures)1? Why is the board chaired by a founder-executive rather than an independent director? Will the next big deal be financed with discipline? None of these is an accusation of wrongdoing. Together they describe a family company that grants outside shareholders a minority role, which an activist would argue deserves a discount rather than a premium.
Weighing it. The evidence supports the view that Mankind's commercial engine is excellent and its cash generation is real. It does not yet support the view that BSV has made Mankind a specialty company. That is unproven, with the first data positive but short. The market's multiple treats it as close to proven.
The three KPIs that matter most 1. Chronic share of domestic sales. Latest: about 38.5% in FY2026, up from about 27.9% in FY20182. Rising slowly. A faster climb would confirm that the portfolio shift is reducing price-cap risk. 2. Net debt to EBITDA. Latest: about 1.1 times at FY2026, down from about 1.9 times a year earlier24. Falling. A continued decline without new equity would confirm that the BSV financing was well judged. 3. BSV growth and margin. Latest: about 20% growth and 28% EBITDA margin at acquisition[^5]. Management reports the integration as on track[^7]. Any sustained slip below those levels would undercut the price paid and raise the impairment question.
XI. Epilogue: The Settling Events
Tonight, October 7, 2026, Mankind Pharma is a ₹1 lakh crore company in the middle of the biggest transformation of its 31-year commercial history. Its factories are busy, its reps are on the road, and its balance sheet is still carrying the BSV deal. The stock sits within 3% of its 52-week high2. The market, for now, is giving management the benefit of the doubt. Four events will decide whether it was right to.
The debt milestone. In nine days, on October 16, 2026, the ₹1,250 crore Series 2 NCDs fall due2. Repaying them on time would leave only the ₹2,500 crore Series 3 tranche, due November 20272. If Mankind retires both from internal cash, it will have financed India's largest domestic pharma acquisition in recent years without refinancing distress and with only one equity raise. A refinancing would not be a disaster, but it would show the cash machine is not quite as strong as the narrative claims.
The tax verdict. Somewhere in the appellate system, a ruling from the CIT(Appeals) or the Income Tax Appellate Tribunal will decide whether the ₹1,574 crore Section 37(1) disallowance stands2. If it is quashed, the auditor's Emphasis of Matter can go away and a cloud over the sales model lifts. If it is upheld, Mankind faces a cash bill and the uncomfortable precedent that the cost of winning doctors is no longer fully deductible. The decision will matter beyond Mankind, to every Indian company that sells through doctor engagement.
The goodwill test. Every March, auditors will test the roughly ₹6,493 crore of BSV goodwill for impairment2. Each year without a write-down validates the price a little more. One write-down would reframe the whole acquisition.
The governance transition. The founding brothers are in their sixties and seventies. The next decade will show whether family-linked suppliers and adjacencies are brought inside the listed company, whether the board becomes more independent, and how leadership passes from founders to the next generation and professional managers.
Behind all four sits the central question: can a company that won by being cheaper and closer become a company that wins by being better and harder to copy? Mankind has bought the ingredients. It has not yet shown the result.
XII. Outro: The Prescription from Meerut
Go back to Meerut in 1995. Two brothers, ₹50 lakh, and a bag of antibiotics priced for people the industry had decided were not worth the trip. Their peers were building FDA-grade plants and booking flights to New Jersey. The Junejas were booking time with a small-town doctor, then the next one, and then the one after that, for thirty years.
The irony is that by staying home, Mankind built a business that the export champions now envy, one where an Indian rep's relationship with an Indian doctor is worth more than a US approval. Now, with a ₹13,768 crore bet on biologics, Mankind is trying to become the scientific company it never needed to be. Whatever comes of that bet, the founding insight already holds: Mankind Pharma conquered India by realising that the most valuable market in healthcare was not the richest patient in the world, but the millions of ordinary people everyone else forgot to serve.
References
-
Mankind Pharma Limited Red Herring Prospectus — Axis Capital / Book Running Lead Managers, 2023-04-14 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Annual Report 2025-26 — Mankind Pharma Limited, 2026-07-09 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Annual Report 2024-25 — Mankind Pharma Limited, 2025-07-15 ↩↩
-
Rating Rationale: Mankind Pharma Limited — ICRA Limited, 2026-02-24 ↩↩↩↩↩
-
Rating Rationale: Mankind Pharma Limited — CRISIL Ratings Limited, 2025-10-29 ↩↩
-
Intimation of Credit Rating on Listed NCDs — National Stock Exchange of India / Mankind Pharma, 2024-11-06 ↩
-
Scrutinizer's Report on Postal Ballot Voting Results — BSE India / Mankind Pharma, 2024-09-05 ↩
-
Mankind Pharma Debut: Stock Lists at 20% Premium to Issue Price — Reuters, 2023-05-09 ↩↩
-
Panacea Biotec Completes Sale of Domestic Formulations Brands to Mankind Pharma — Business Standard, 2022-04-04 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube