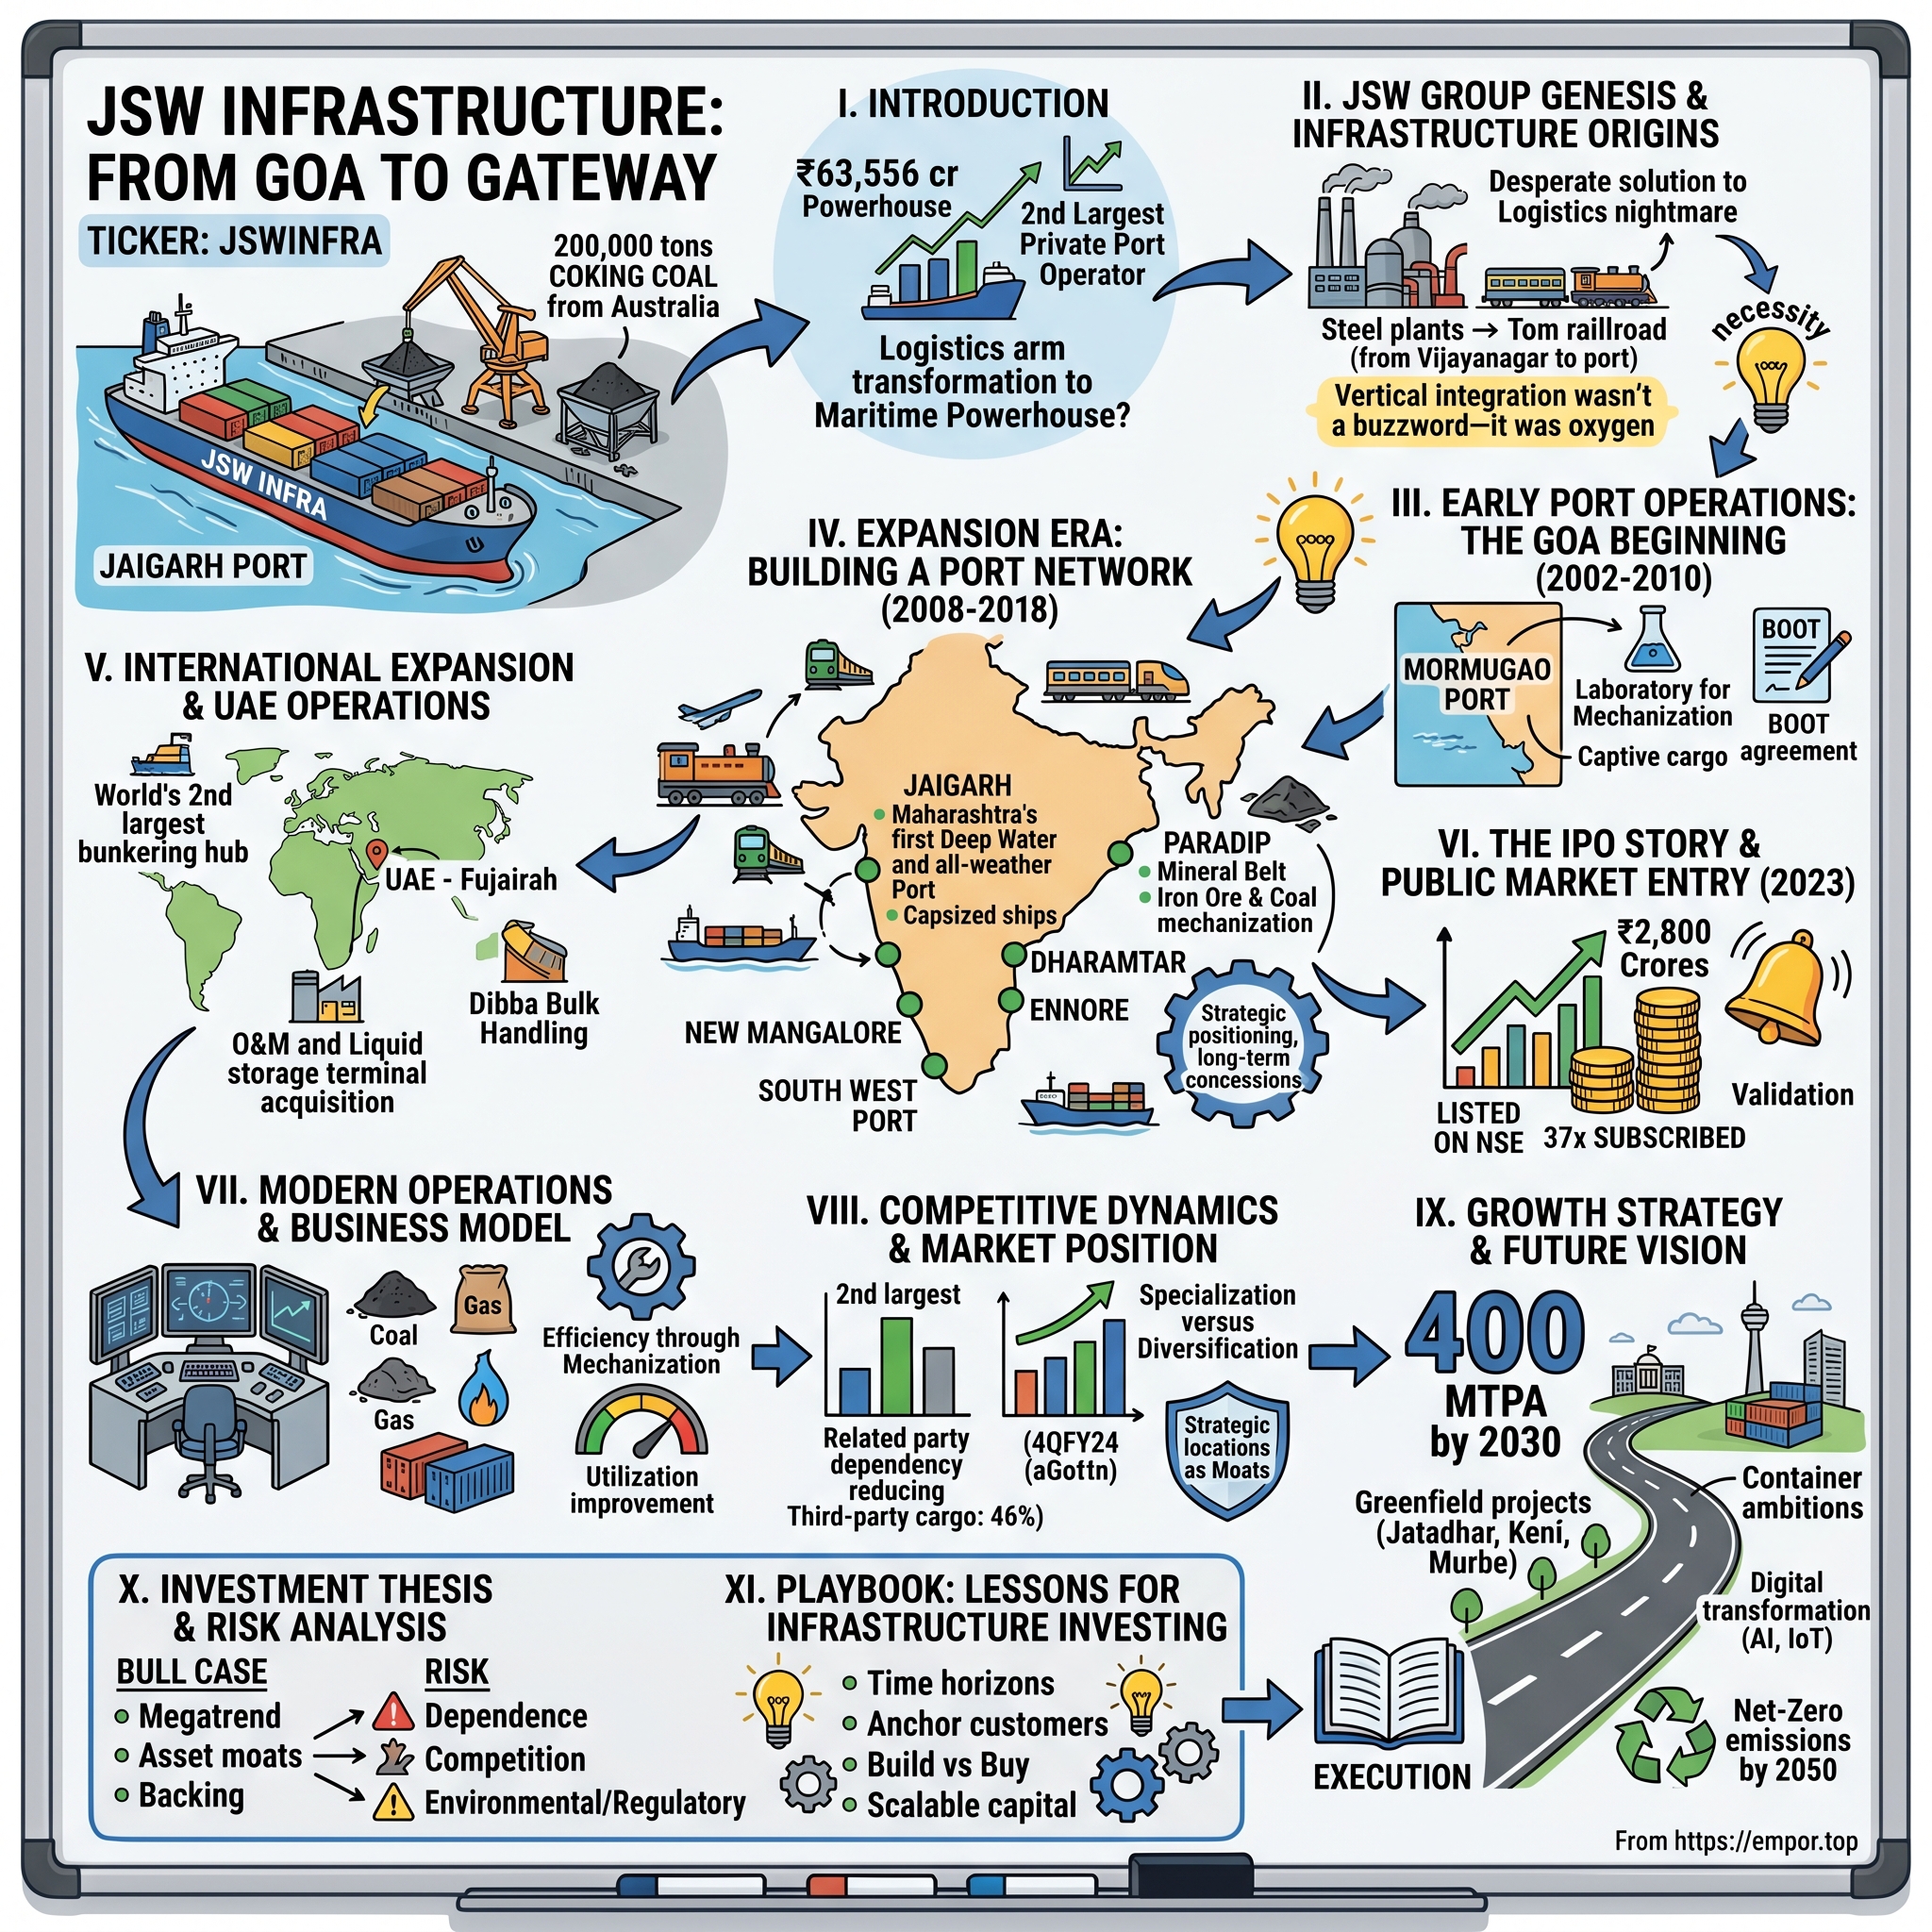
JSW Infrastructure: The Port Built for the Steel Mill
I. The Cargo Has Two Owners
Picture a bulk carrier tied up at a mechanised berth on India's west coast. Its holds are full of coal, and the coal has somewhere to be: a blast furnace a few hundred kilometres inland that has to keep running. Grab cranes lift the cargo onto conveyors, conveyors carry it to a stockyard, and from there it goes by rake or barge towards the plant. Everything in that scene belongs to JSW Infrastructure. The coal usually belongs to its sister company.
That split between who owns the dock and who owns the cargo is where this story has to start, because the company's name makes it easy to blur. JSW Infrastructure is the listed ports and logistics business of the JSW Group, promoted by Sajjan Jindal and the Sajjan Jindal Family Trust.1 Its consolidated accounts include its ports, terminals and logistics subsidiaries.
They do not include JSW Steel, JSW Energy or JSW Cement. Those companies sit outside the listed perimeter as customers and related parties.1 So when a JSW Steel expansion makes headlines, the port company's shareholders get the cargo and the tariff. They do not get the steel margin.
The size of that customer relationship is clear from one line of the related-party note. In FY2026 JSW Infrastructure reported ₹5,361 crore of revenue from operations.1 About ₹2,047 crore of it, roughly 38%, came from sales to related parties, and ₹1,665 crore of that came from JSW Steel alone.1 On those figures JSW Steel is not one customer among many.
It is close to a third of the business. Yet the third-party side is not small either. In the quarter to June 2026, third-party cargo was 48% of the volume the company handled.2 That is about half the cargo at those berths belonging to someone who could, at least in principle, take it elsewhere.
This story is organised around four questions that run through it. The first is who supplies the cargo, and whether growth comes from an outside market or from the parent's own expansion. The second is what makes these ports hard to displace when India has other operators, some of them much larger. The third is whether a construction programme measured in tens of thousands of crore will earn its cost. The fourth is what today's share price already assumes about the answers to the first three.
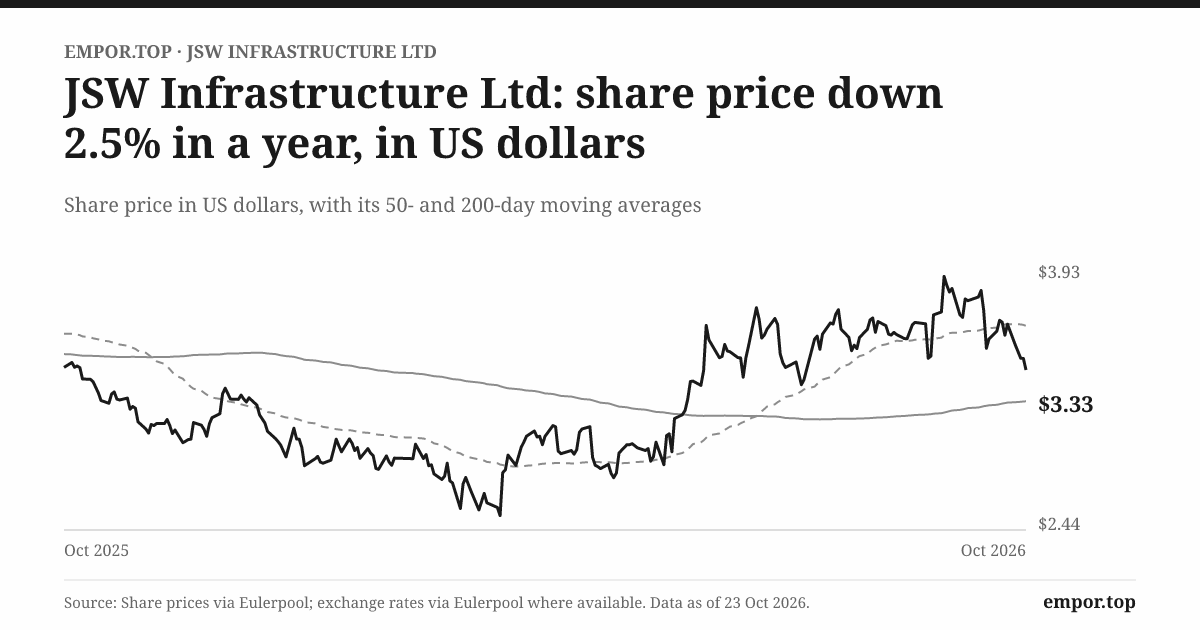
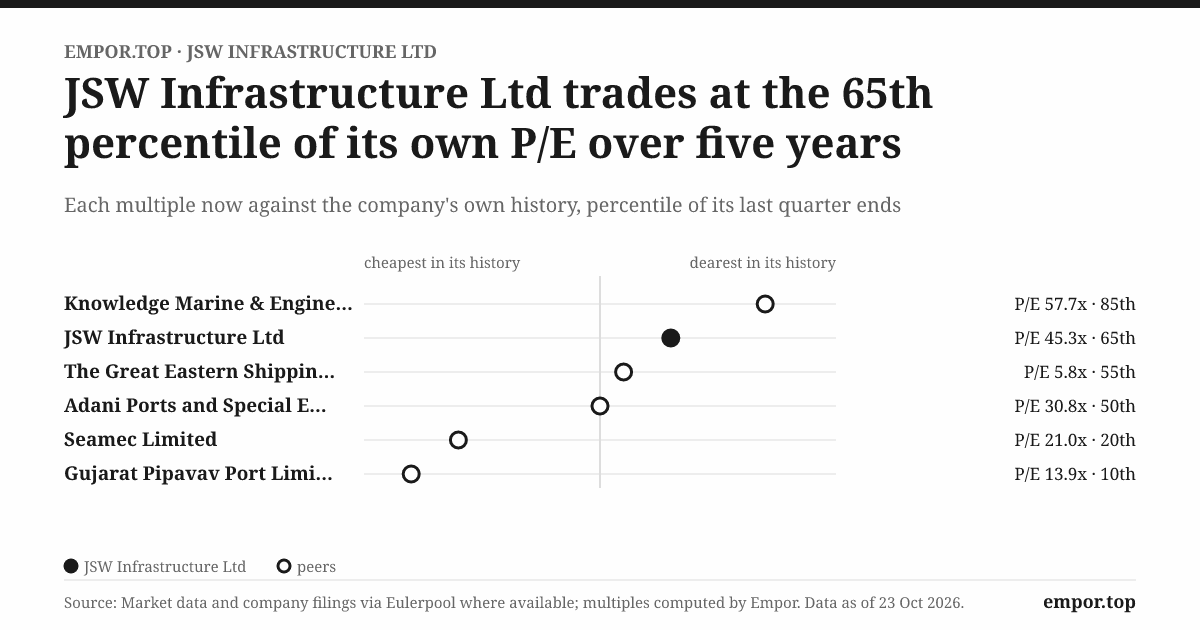
The market has an opinion on that last one. On 23 October 2026 the shares traded at ₹316, valuing the company at roughly ₹67,000 crore, or about 45 times trailing earnings.3 That is above the stock's own five-year median of about 41 times.3 It is also well above what investors pay for India's two closest listed comparisons: about 30 times for Adani Ports and Special Economic Zone and about 14 times for Gujarat Pipavav Port.45
Put another way, a buyer at today's price earns about 2.2% of the purchase price in current profit, and is betting that the profit will grow a lot faster than the price.
What does that bet need? It needs JSW Infrastructure to turn a portfolio built mostly around one industrial group into a network that outside customers fill. It also needs the company to finish and fill new capacity on time, and to keep cash left over after it pays for the buildout.
None of those things is impossible. None of them is in the bag either. The case for the stock rests on a listed ports business with real third-party growth, but its parent is still a major customer, and at this valuation there is little room for execution to slip.
To see why the parent's cargo is so tangled into the company, go back to the problem the first port was built to solve: a steel mill in the middle of the Deccan that needed a way to reach the sea.
 Subscribe on LinkedIn
II. A Berth for Vijayanagar
A steel plant is a machine for moving rock. For every tonne of steel it ships, it has to bring in iron ore, coking coal and fluxes in multiples of that weight. Vijayanagar, JSW Steel's flagship plant at Toranagallu near Ballari in Karnataka, sits inland. Iron ore was available nearby, but much of the coking coal that a modern blast furnace needs had to come from overseas, and finished steel had to reach markets beyond the Deccan plateau.
The cost of a tonne of steel therefore depended heavily on what happened between a ship's hold and a furnace's charging floor.
Sajjan Jindal, who built JSW Steel into the group's core business, understood the problem from the plant floor. Big plants far from the coast are hostage to rail rakes, port congestion and other companies' berthing priorities. A steelmaker that lets a third party control its route to the sea is giving away its biggest variable cost.
The JSW answer was to build the route itself. South West Port Limited was incorporated in 1997 to handle cargo for the group, and in 2002 it took up a concession at Mormugao in Goa, the closest major harbour to Vijayanagar with a rail link across the Western Ghats.6 The logic was simple. A mechanised berth with dedicated unloaders could empty a coal ship faster than general-purpose facilities, and a stockyard tied to the railway could send cargo inland without the delays that come with sharing a crowded public quay.
Each saved hour lowered demurrage charges, the penalties a charterer pays when a ship waits too long, and each smoother transfer cut the risk of a furnace running short.
From Goa the model spread up and down the coast, following the group's plants. Jaigarh, a deep-water port in Ratnagiri district in Maharashtra, became a large all-weather facility serving the group's industrial needs on the Konkan coast. Dharamtar, a river port near Mumbai, linked by barge to JSW Steel's plant at Dolvi.6
Over time the company added coal and iron-ore terminals at Paradip on the east coast, plus terminals at Ennore and Mangalore, so its map came to look like a shadow of the group's industrial footprint.6 In FY2025 group companies still accounted for about 51% of the cargo the company handled.7
That origin explains both the strength and the weakness of the business. The strength is that the first assets came with a reason to exist. A port is costly, slow to build and useless without volume. A port with an anchor customer already shipping millions of tonnes can be planned, financed and run at a utilisation rate that a speculative greenfield project would envy.
The anchor also gave the company room to learn the operating craft of berths, cranes, dredging, conveyors and rail evacuation without the pressure of winning every tonne in the open market.
The weakness is the same fact in a different light. If the anchor customer is also a sister company controlled by the same promoter, the port's commercial terms are set inside the family. The listed company's shareholders then have to trust that tariffs, volumes and payment terms are struck at arm's length, because they cannot easily check. The port company's fortunes also become a derivative of steel and power cycles, whatever its brochure says about diversification.
That listed boundary matters here: steel remains outside it.1 When Vijayanagar ramps up production, which management said had reached about 18 million tonnes a year of capacity by January 2026, the port company gains throughput and logistics work.8 It does not gain a share of the steel spread, and it cannot cushion a steel downturn with steel profits it never earned.
So the early model left one question unanswered for years. A captive logistics arm can run a fine port for its parent. Could it also win cargo from anyone else, on terms that would make it a business rather than a cost centre with a ticker?
III. The Port That Had to Find Other Customers
The cleanest way to understand a port's revenue is to follow one ship through its call. The vessel pays for berthing, pilotage and other marine services as it arrives. Its cargo is then unloaded, moved, weighed and stacked, and the cargo owner pays per tonne for that handling. If the cargo sits in the yard, storage charges begin. If the port arranges the onward rake or truck, there is a logistics fee.
JSW Infrastructure's FY2026 revenue broke down along exactly those lines. Cargo-related services brought in about ₹3,306 crore, the clear majority. Vessel-related services added about ₹659 crore, storage and allied services about ₹492 crore, and other port services about ₹190 crore, with logistics cargo handling and transportation contributing about ₹674 crore.1
That breakdown shows what drives the economics: the number of tonnes crossing the quay and the kind of tonnes they are. A tonne of coal and a tonne of containerised auto parts do not earn the same tariff or need the same equipment. More volume on fixed assets lifts margins, and a richer cargo mix lifts revenue per tonne.
It also shows why capacity is the most misunderstood number in Indian ports. A berth's rated capacity is a statement about engineering: how many tonnes a year the cranes, conveyors and stockyards could physically handle under assumed conditions. It is not a statement about demand. A port rated at 50 million tonnes that handles 25 million is a half-empty factory, carrying the full depreciation of a full one.
In FY2025 JSW Infrastructure handled about 117 million tonnes of cargo against an installed capacity well above that, which means a large slice of the nameplate earned nothing that year.79 Throughput, not capacity, pays the bills.
The company's progress in winning outside customers therefore matters more than its capacity announcements. On that measure the record is real. Third-party cargo rose from about 40% of volumes in FY2024 to about 49% in FY2025.109 By the December 2025 quarter third-party cargo was about 50% of throughput, with management reporting third-party volumes up about 10% from a year earlier.8 That is not a rounding error. About a tenth of the cargo mix moved from family to strangers in a couple of years, which is evidence of external demand for these berths.
Two qualifications narrow what that evidence proves. The first is that the share is a ratio, so it moves when the group's own cargo stalls as well as when outside cargo grows. The second is more important: management told investors the share will swing back. On the January 2026 call, Rinkesh Roy, the managing director and chief executive, said the new iron-ore slurry pipeline and the Jatadhar port would initially carry entirely group cargo, and that by FY2027–28 the mix should land at about 53% to 55% group against 45% to 47% third-party.8
So the third-party share that bulls point to as proof of independence is, by the company's own guidance, set to fall as the next wave of assets comes on. Over the next two years, then, the share will measure the building programme as much as commercial success.
Contracts tell a similar story. The rating agency ICRA says take-or-pay agreements with certain group entities commit them to minimum quantities, so the port is paid even if the cargo does not show up.7 That gives the business a floor. But ICRA also says actual group volumes have substantially exceeded those minimums, which means the floor sits well below current volumes.7 The company does not disclose a portfolio-wide minimum volume, tariff formula or contract term, so an outside investor cannot tell how much of today's revenue would survive a hard year at the group's plants.1
One take-or-pay arrangement is visible because it shows up as a lump: a contract with an LNG-terminal customer at Jaigarh produces roughly ₹70 to ₹75 crore of income that the company books in the fourth quarter each year.8
Beneath the widening customer list, the cargo is still concentrated. Coal and iron ore made up about 83% of FY2025 cargo.7 Those two commodities feed the same two industries, steel and thermal power, whose cycles tend to rise and fall together with Indian infrastructure spending and Chinese import demand. A port can have dozens of third-party customers and still be one commodity downturn away from a bad year. Volume diversification, in other words, is not the same thing as end-market diversification.
The Paradip iron-ore terminal shows the problem in miniature. In the nine months to December 2025 its volumes fell by about 3.9 million tonnes, which management blamed on "challenging macroeconomic conditions in the seaborne iron ore export market".8 Most of Paradip's iron-ore cargo, Roy said, had been third-party rather than group.8 That is exactly the cargo the diversification story celebrates, and it proved exposed to a market that had nothing to do with the terminal's equipment or its operating record.
Monthly volumes were recovering by late 2025, but the episode is a reminder that location and machinery do not protect a port from commodity or customer shifts.8
The verdict from this period is mixed but useful. JSW Infrastructure has shown that its berths can attract outside cargo in meaningful size, which a purely captive operator could not claim. It has not shown that its business is independent of steel and power, and its own guidance says group cargo will regain the majority. That raises the industry question underneath everything else. If several operators along the same coast can move the same coal, what protects JSW's economics when a customer has a choice?
IV. The Moat Is a Map, a Concession and a Railway
Follow one shipment from start to finish. A tonne of iron ore leaves a mine in Odisha's Keonjhar belt, rides a truck or rake to a railhead, crosses several hundred kilometres of track, waits in a stockyard, is reclaimed onto a conveyor and is poured into a vessel bound for a steel mill. At each handoff the tonne either moves on or waits, and waiting costs money.
A ship idle at anchorage burns charter hire. A plant short of ore throttles a furnace. A rake stuck behind a congested siding wastes a locomotive. Customers do not pay ports for the shoreline. They pay for the certainty that the whole chain will work, and the shoreline is just the most visible link.
That framing explains where JSW Infrastructure's advantage lies and where it stops. The company's network now spans dry bulk, break bulk, liquids, gas and containers, across both Indian coasts and a small international footprint.2 By July 2026 management put capacity at about 186 million tonnes a year, with a target of 300 million by FY2028 and 400 million by FY2030 or earlier.11
The earnings engine is still the dry-bulk business, mechanised coal and ore handling at Jaigarh, Dharamtar, Goa, Paradip, Ennore and Mangalore. The container and liquid terminals, including those at Jawaharlal Nehru Port, Tuticorin, Kolkata and Mangalore, are real but smaller pieces that function more as options on India's container and energy trade than as today's profit centre.118
Size the company against its two listed peers. Adani Ports and Special Economic Zone is the dominant private operator in Indian ports, with a far larger network, a much bigger container business and its own logistics arm. Its earnings base is far larger than JSW's, and the market prices it at about 30 times earnings and 20 times EV/EBITDA, the enterprise value-to-operating profit ratio.4 Gujarat Pipavav Port, at the other end, is a single-port operator on the Saurashtra coast with a container and bulk mix, valued at about 14 times earnings and 9 times EV/EBITDA.5
JSW sits between them in scale and above both in valuation. These companies are not interchangeable. Adani is a diversified national network, Pipavav a focused regional port, and JSW a bulk-heavy network tied to an industrial group that is reaching for containers and logistics. Comparing them shows what the market is paying for, not who will win the same customers.
Michael Porter's five forces help organise the competitive evidence. Start with buyers. A steel mill or power utility on the west coast can choose among several ports where geography and capacity allow, and India's coastline has many: major ports run by government trusts, state-concession minor ports, and private terminals inside major ports. Buyer power is therefore real wherever two ports sit within reasonable rail or road distance of the same plant. The threat of new entry is lower, because a new port needs a concession from the state or a port authority, environmental clearance, land or reclamation, dredging and rail links, a process that takes years.
That barrier is real but not absolute, since the bidding for Bengal's planned Tajpur deep-sea port in 2022 drew both Adani and JSW, with Adani emerging as the highest bidder.12 Concessions are auctioned, and the auction prices in much of their future value.
Rivalry among existing ports depends on the route. On the Konkan coast, JSW's Jaigarh and Dharamtar handle cargo that could physically go through other ports around Mumbai, but the anchor plants at Dolvi and in the hinterland make JSW the natural route for group cargo. Substitutes are partly a matter of transport mode.
Rail-to-plant for domestic coal, coastal shipping and the slurry pipeline the company is now building can all change how bulk commodities move. Suppliers matter less than in many industries, though the Indian Railways is effectively a monopoly supplier of the rail link that makes many ports work.
Hamilton Helmer's framework asks which durable power, if any, explains returns above the cost of capital. JSW's strongest plausible claim is what might be called local advantage, a mix of cornered resources and switching costs. A concession at a deep-water site next to an industrial cluster is a scarce asset. Add mechanisation and integrated rail or conveyor evacuation, and a customer's cost of switching to another port rises, because the alternative route is slower or more expensive. The group take-or-pay minimums add contractual demand on top of the geography.
That claim has to pass three tests before it counts as a moat. The first is substitution, whether a customer actually leaves when an alternative appears. The Paradip episode shows that third-party customers move or vanish with the trade. The second is price realisation, whether the company can raise tariffs above inflation. Here the regulatory reality is that tariffs at terminals inside major ports have been regulated, and Roy said on the January 2026 call that free pricing applies under the newer concession agreements at JNPA, Tuticorin and Kolkata, while for existing terminals "a call will be taken by the ministry" with no date he could give.8
The third is retention, which would be visible in port-by-port utilisation, customer tenure and unit-cost data. The company does not publish port-level utilisation, customer retention, tariff realisation or unit costs. What it publishes establishes scale and volumes. It does not by itself prove pricing power or returns better than peers'.
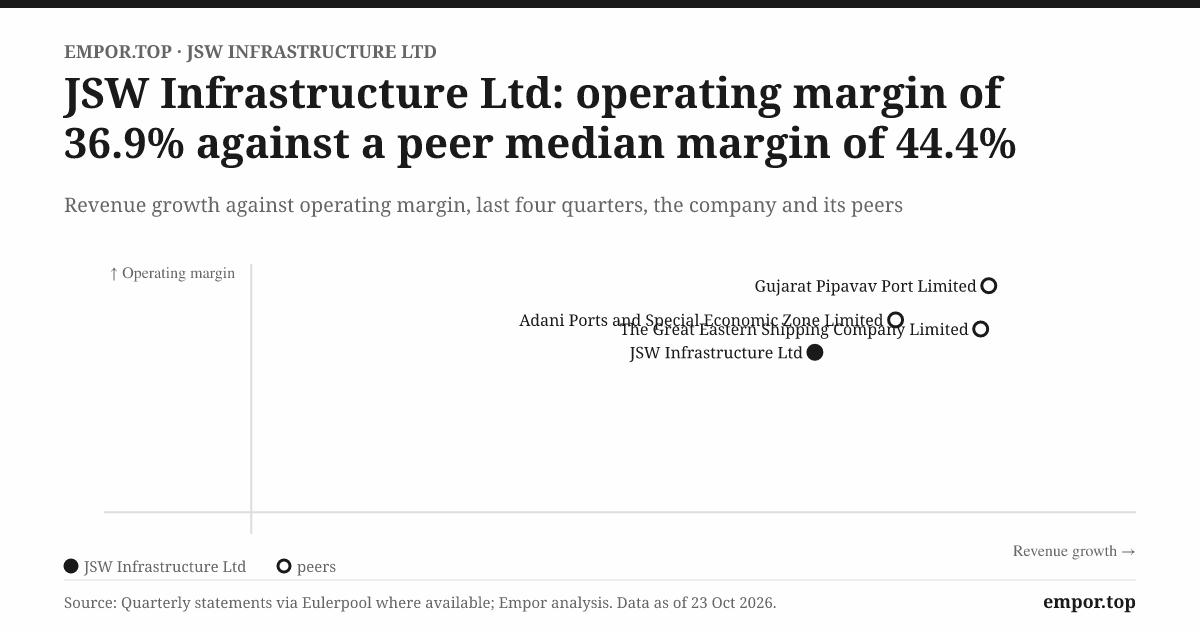
The return record itself narrows the claim. Return on capital employed was about 10.8% in FY2026, down from about 16% in FY2023, as heavy construction and new assets diluted returns.1 Port EBITDA margins are high, around 50% in the June 2026 quarter, down from about 52% a year earlier.11 That is the profile of a good infrastructure asset, not yet of a business with a pricing umbrella over a national market.
The reasons management gave for the margin dips are instructive. In January 2026 Roy said growth had come mostly from lower-margin terminals at JNPT and Tuticorin, and the CFO pointed to about ₹17 crore of one-off repairs and preventive maintenance at Jaigarh and the Paradip coal terminal.8 In July the explanation was Fujairah's lost volume, plus another ₹8 to ₹9 crore of one-off cost to shift a crane at Jaigarh.11 Each answer was specific and plausible. Together they show something important: the newest volume is coming from terminals that earn less per tonne than the mature bulk clusters, so growth and margin are pulling in slightly different directions.
The fair verdict is that JSW holds a genuine but route-specific advantage: long concessions, strategic locations and integrated evacuation that create a local cost and reliability edge around its own clusters. Utilisation at new ports outside those clusters, and tariff realisation at terminals with free pricing, are the measures that would show whether the edge travels.
Which leads to the next move. If the moat lies in the route as much as the berth, the obvious way to deepen it is to own more of the route. JSW Infrastructure decided to buy it.
V. Buying the Route Beyond the Berth
In June 2024 JSW Infrastructure agreed to buy a controlling stake in a company most port investors had never studied closely. Navkar Corporation ran container freight stations, an inland container depot and rail-linked logistics around Panvel and Somathane near Mumbai, plus an inland terminal at Vapi in Gujarat.13 For a port company that wanted to move from shoreline to doorstep, Navkar offered something that takes years to build from scratch: licences, rail sidings, customs-bonded facilities and land close to the country's busiest container gateway.14
The price looked like this. JSW agreed to acquire 70.37% of Navkar from its promoters, at a stated enterprise value for the whole company of about ₹1,644 crore and cash consideration of about ₹964 crore for the stake.1314 Before the deal, Navkar had reported FY2023 revenue of about ₹709 crore and net profit of about ₹92 crore.14 Divide the enterprise value by those figures and the deal priced Navkar at roughly 2.3 times sales and 18 times net profit.
The ratios mix dates, since enterprise value is struck in 2024 and earnings are a year earlier, and they are no substitute for an EBITDA-based comparison. Still, they make one point plain. On the disclosed figures this was not a distressed bargain. JSW paid for the strategic position, and the investment case depends on integration and incremental returns, not on the label "strategic".
There is early evidence on that point, and it is more encouraging than the purchase price. Roy said on the January 2026 call that Navkar had been generating about ₹3 crore a month of operating EBITDA when JSW took over and had risen to about ₹13 crore a month.8 In the June 2026 quarter Navkar reported about ₹191 crore of revenue, up 38% from a year earlier, with operating EBITDA up 62% to about ₹33 crore.11
Annualise that quarter and Navkar is earning roughly ₹130 crore of EBITDA against the ₹1,644 crore enterprise value, about 12.5 times. That is a reasonable but not spectacular multiple for a logistics platform, and it improves only if growth continues. The turnaround is real. Whether it reflects JSW cargo being routed through Navkar or genuinely new third-party business is not something the company splits out.
Logistics has its own economics, and they are not a port's. An inland depot or a container rake fleet has to keep high utilisation to pay for itself, and the competition includes the state-owned Container Corporation of India and a crowd of private operators. Navkar's yard is only as valuable as the trains that run through it.
The international additions are smaller than the headlines that greeted them. JSW owns a liquid storage terminal at Fujairah in the UAE, and separately holds operation and maintenance contracts at the ports of Fujairah and Dibba.8 The distinction matters. Owning a terminal or holding a concession means the company carries the asset, the depreciation and the upside. An O&M contract means it runs someone else's port for fees, with limited capital at risk and limited control.
At Fujairah the O&M arrangement paid off in 2025, when volumes beat the minimum commitment and JSW shared in profits on about 0.8 million tonnes of incremental cargo.8 Then the 2026 conflict in the Gulf hit. In the June 2026 quarter Fujairah's contribution was negligible, and the CFO said port EBITDA would have been about ₹65 to ₹70 crore higher without the disruption, about a tenth of the segment's quarterly profit.11
The company said it had lodged insurance claims and expected a resolution by the end of October 2026.11 That is a fair sizing of international expansion: useful, occasionally lucrative and exposed to geopolitics that no port operator controls. The same applies to the 27-million-tonne greenfield port in Oman that JSW agreed in January 2026 to develop with Minerals Development Oman, at a stated investment of about US$419 million.8
At the time of the July 2026 call, the concession agreement was still to be signed.11 PNP Port, a smaller acquisition near Dharamtar, fits the same pattern of bolt-on capacity that strengthens a cluster rather than redefining the company.15
The most revealing deal came in December 2025, because the seller was family. JSW Infrastructure proposed to buy 100% of three group entities that owned railway rakes, the long trains of specialised wagons that Indian Railways lets private operators run under its wagon-investment schemes.168 The notice gave an enterprise value of about ₹1,212 crore, which it said was about 8.1 times estimated FY2027 EBITDA on a fleet of 25 rakes.16 The CFO later said those rakes should contribute about ₹150 crore of EBITDA.8
Roy explained where the wagons run: one set carries clinker between eastern locations, another hauls iron ore into Vijayanagar, and another carries finished steel out of it.8 By July 2026 management was counting 25 rail rakes in its existing fleet, and the FY2026 accounts show a ₹670 crore asset acquisition from JSW Shipping and Logistics, a group company.111
Look at that from a minority shareholder's seat. An 8.1 times forward EBITDA multiple is not obviously rich for a rolling-stock business. But the EBITDA estimate depends on the wagons staying busy, and they are kept busy by JSW Steel's plants. The listed company paid the promoter group for assets whose earnings come largely from the promoter group's cargo.
That does not make it a bad deal, and shareholders were asked to vote on it as a related-party transaction.16 It does make it a test of capital allocation that independent directors and minority investors should judge on its returns, not its strategic fit.
Management's ambitions here are large. It has spoken of about 25 logistics terminals across India within three years, a combined fleet of about 250 rakes, and logistics EBITDA guided to about ₹450 to ₹500 crore in FY2027 and ₹750 to ₹800 crore in FY2028.811 When an analyst referred to a ₹2,000 crore logistics EBITDA ambition by FY2030, the CFO said further acquisitions or construction of container freight stations and inland depots would be needed.8 That is candid, and it means the logistics plan is a capital-spending plan.
The follow-up test is concrete. Investors should look for volumes each acquisition brings in, segment margins, working capital, and above all returns on the money paid. The logistics segment's EBITDA margin rose to about 31% in the June 2026 quarter from about 15% a year earlier, which is the right direction.11 The size of the bet means the evidence will need to keep coming. And all of this spending needed money that a captive group port had never raised on its own, which is why the company had already walked onto the public stage.
VI. The IPO Bought Time—and a Public-Market Clock
On the morning in October 2023 when JSW Infrastructure's shares began trading on the NSE and BSE, the group was trying something it had attempted before. Business Standard described the listing as another attempt by the JSW Group to scale up its port business through the capital markets.17 This time the structure was unusual for an Indian promoter-led IPO. It was a fresh issue of about ₹2,800 crore, with no offer for sale: the promoters sold nothing.6 Every rupee raised went into the company.
That design said something about the promoter's intent. Many Indian IPOs are partly exits, with founders or private-equity owners selling down. Here the promoter group kept its shares and diluted only to the extent new stock was issued. The prospectus earmarked the proceeds for repaying debt and funding expansion, including capacity at Jaigarh and the Mangalore container terminal.6
Roughly 23.5 crore shares were sold, which works out to about ₹119 a share.6 At ₹316 in October 2026, investors who bought in the IPO have seen the share price rise to roughly two and a half times in three years.3
After the IPO, the promoter group still held about 85.6% of the company.6 That created its own obligation. Indian listing rules require listed companies to reach at least 25% public shareholding within a set period, which meant the promoter group would have to come down by more than ten percentage points. The company could do that by selling promoter shares, which would hand cash to the family, or by issuing new shares, which would put cash into the company. It chose the second.
In February 2026 the board sought shareholder authority to issue up to 25 crore shares through permitted routes, including a qualified institutional placement, a share sale to institutional investors without a full public offering.18 The placement that followed raised about ₹7,503 crore, more than two and a half times the IPO.11 By the end of June 2026 about ₹6,555 crore had arrived, and management said the issue supported both the capex programme and the minimum public-shareholding requirement.11
Rinkesh Roy described it on the July call as "a landmark" deal with strong participation from global and domestic institutions.11 Shortly after it closed, Moody's assigned the company a Baa3 rating with a stable outlook, an investment-grade international rating.19
The capital raise transformed the balance sheet in a quarter. At the end of FY2026, borrowings were about ₹6,410 crore.1 By the end of June 2026, with the placement money in, management reported gross debt of about ₹7,094 crore against cash and bank balances of about ₹9,863 crore, a net cash position of roughly ₹2,800 crore.112 A company in the middle of the largest building programme in its history now held more cash than debt.
The ownership map changed with it. At the end of September 2026 the promoter and promoter group held 73.93%, the public 25.90% and an employee trust 0.17%.20 Within the public float, foreign institutions held about 12.5% and domestic institutions about 8.5%.20 The company had about 4.1 lakh shareholders, roughly 411,000 individual and institutional accounts.20 Sajjan Jindal remained chairman, and the September filing showed no promoter shares pledged or otherwise encumbered.20 In a country where promoter pledges have often been an early warning sign of stress elsewhere in a group, that is a clean reading.
Two observations follow. The first is that the promoter's choice to raise money for the company rather than sell shares is good alignment on its face. The family's economic interest grows only if the company's value grows. The second is that dilution is a real cost. Every rupee of future profit is now shared across more shares, so the new capital has to earn its keep simply to keep earnings per share where they were.
The June 2026 quarter illustrated the point: profit after tax fell to about ₹358 crore from about ₹390 crore a year earlier, partly because other income dropped as treasury balances were drawn down for capex before the QIP money arrived.11 As the cash sits in deposits, it will earn interest, as the CFO noted, but interest on bank deposits is not why anyone buys a port stock at 45 times earnings.11
The listing also started a clock that the company did not face as a captive operator. Public investors measure returns per share, quarter by quarter, and they compare the company with alternatives. Fresh equity can fund a very large capex plan. It cannot make the projects productive. That job falls to the construction schedule.
VII. Four Hundred Million Tonnes Is a Construction Schedule
Stand on the beach at Jatadhar, on the Odisha coast near Paradip, and the future port is mostly a set of pile foundations and dredged channels. In January 2026 management reported pile foundations about 40% complete and about 5.6 million cubic metres of dredging done, with a completion target of March 2027.8 A few hundred kilometres inland, a 302-kilometre iron-ore slurry pipeline was being welded and lowered into its trench.
By the end of June 2026, about 251 kilometres, around 83% of its length, had been lowered, and management said it remained on track for March 2027.11 These are the projects that turn a capacity target into something a ship can actually tie up to.
The plan behind them is enormous. ICRA estimates planned capex of about ₹25,000 to ₹30,000 crore over five to six years.7 Business Standard reported in December 2024 that the company was aiming for 400 million tonnes of capacity with about ₹30,000 crore of capex by FY2030.21 For a company whose annual revenue is a little over ₹5,000 crore, that is like a household earning ₹5 lakh a year committing to build ₹30 lakh worth of houses over six years. It is affordable only if the houses get tenants.
Here is how the projects break down. The brownfield work extends existing clusters. At Jaigarh, major equipment packages have been awarded, and at Dharamtar the conveyor system and barge unloaders are being built.11 These expansions depend heavily on the steel expansion at Dolvi, which management said in January 2026 was ramping from about 10 to 15 million tonnes a year.8
The CFO said the brownfield projects were modelled at 50% utilisation because the steel expansion was expected to commence in the second half of the year.8 At South West Port in Goa, consent to operate was raised to 12 million tonnes a year from 11, and the Mangalore container terminal expansion took that terminal from 4.2 to 6 million tonnes.11
The greenfield ports are the bigger bet, because they reach regions the existing network does not serve. Murbe, on Maharashtra's Palghar coast north of Mumbai, received environmental clearance in the June 2026 quarter, along with approval for rail connectivity to the Dedicated Freight Corridor, the high-capacity freight railway line running towards north India.11 Management said the concession agreement would be signed within two to three months and construction would start around December 2026 or January 2027.11 Keni, in Karnataka's Uttara Kannada district, is behind schedule.
An analyst on the July 2026 call said the project had been deferred by about a year, and Roy attributed the delay to the state's coastal-zone authority not being constituted for six to seven months, which he said was "beyond our control."11 He expected environmental clearance in about three to four months.11 Jatadhar, as noted, is the most advanced, and its anchor contract was novated after Odisha government approvals.11
Add containers and logistics. In Kolkata, JSW won berths 7 and 8 at the Syama Prasad Mookerjee Port and then the integrated development of the Outer Container Terminal and Berths 1 to 5 at Netaji Subhas Dock under a public-private partnership, which management said would take its Kolkata container capacity to about 1.4 million TEUs, the standard twenty-foot container unit.811 The CFO put the first phase's capex at about ₹740 crore and its steady-state EBITDA at about ₹70 to ₹90 crore a year, rising to about ₹300 to ₹350 crore across all three phases.11
On phase one, that is roughly a 10% to 12% EBITDA return on capital before taxes and maintenance capex. That is acceptable for infrastructure, but only if utilisation reaches the 75% to 80% management expects.11
The construction sites mean nothing until they produce cash. FY2026 capex was about ₹2,495 crore, about 47% of revenue, after about 53% in FY2025.1 Capital commitments, contracts already signed but not yet paid, more than doubled to about ₹4,087 crore at March 2026 from about ₹1,729 crore a year earlier.1 By June 2026 management spoke of a further ₹5,500 crore committed through orders for machinery, long-lead items and civil works.11
For FY2027 and FY2028 combined, the company plans to invest about ₹16,500 crore, about ₹13,000 crore in ports and ₹3,500 crore in logistics.11 Those are the years in which the real cash goes out.
The quarterly calls show how the guidance has shifted. On the January 2026 call, Sumit Kishore of Axis Capital pointed out that FY2026 capex guidance had come down by about ₹2,000 crore, from ₹4,000 crore for ports and ₹1,500 crore for logistics to a combined ₹3,500 crore.8 The CFO, J. Nagarajan, said purchase orders were on track but payments had been deferred into the next two years using bank guarantees and letters of credit.8 That is an honest and plausible explanation, and it also means the spending wave is backloaded into FY2027 and FY2028.
On volumes, management guided for about 123 million tonnes in FY2026, then about 6% to 7% growth in FY2027, then "a massive ramp-up" to 165 to 175 million tonnes in FY2028.8 By July 2026, with Fujairah disrupted, management guided to about 127 million tonnes for FY2027.11 Management also guided in January 2026 for EBITDA to rise about 15% in FY2027 and roughly double from the FY2026 level by FY2028.8 FY2028 is the year that makes or breaks the forecasts.
That forecast should be read beside the company's own history of targets. In earlier years, JSW Infrastructure aimed for 200 million tonnes of capacity by 2020, a goal it did not reach on schedule.17 Around the 2023 IPO the ambition was 300 million tonnes by 2030.17 The target has since moved to 400 million tonnes by FY2030 or earlier, with an intermediate goal of 300 million by FY2028.11 Raising the target while the previous one was still in progress does not mean the company has failed.
Capacity did grow, to about 186 million tonnes today.11 But the record narrows confidence in specific dates. The current programme has more approvals, more funding and more physical progress behind it than the 2020 target ever did, so the right stance is somewhere between belief and dismissal: credible as an investment programme, not yet proven as a return outcome.
The execution risks each have a direct economic mechanism. A delayed public hearing or coastal-zone clearance pushes back construction, which pushes back revenue while interest and overheads continue. Delayed commissioning postpones throughput on capital already spent. A ramp-up below plan lowers the return on that capital for years, because port depreciation does not care whether the berth is full. And that commodity concentration links utilisation at the new ports to commodity cycles.
Group-heavy assets such as Jatadhar and the slurry pipeline reduce that risk through take-or-pay contracts. The slurry pipeline alone, the CFO said, could produce about ₹800 crore of EBITDA "if constructed on time" at margins around two-thirds.8 But those same assets increase dependence on the parent.
So the forward test is concrete: project-by-project commissioning dates, budget variance, utilisation and EBITDA on each new asset. Until those appear, the profit-and-loss account will show the cost of the buildout before it shows the reward, which is exactly what the cash-flow statement already reveals.
VIII. The Profit Arrives; the Free Cash Does Not
There is a puzzle in JSW Infrastructure's twelve-year cash record. From FY2015 through FY2026 the company reported cumulative net profit of about ₹6,911 crore.1 Over the same years its operations generated about ₹12,224 crore of cash, about 177% of the profit.1 By that measure this is a cash machine: every rupee of reported profit has been backed by almost two rupees of operating cash.
Yet over the same twelve years cumulative free cash flow, operating cash minus capital spending, was only about ₹565 crore.1 In FY2026 free cash flow turned negative, by roughly ₹500 crore, as capex outran operating cash.1
Both facts are true, and the gap between them is the story of a port company. Start with why operating cash runs ahead of profit. A port's largest cost is depreciation, the accounting charge that spreads the cost of berths, cranes and dredging over their useful lives. Depreciation reduces profit but costs no cash in the year it is charged. In FY2026 depreciation and amortisation were about ₹614 crore, against profit before tax of about ₹1,873 crore.1 Add back a charge that size each year and operating cash naturally exceeds net profit.
Now follow where the cash went. Most of it went back into the ground. FY2026 capex of about ₹2,495 crore was four times the year's depreciation charge.1 When a company spends several times its depreciation, it is not just maintaining its assets; it is building new ones. That is why free cash flow is so thin. The company is not leaking cash. It is reinvesting nearly all of it, plus borrowed and raised money, in more capacity.
Dividends have been a small part of the story. They totalled about ₹284 crore over the twelve years, all of it paid in the last two.1 The median payout ratio across the period was zero, and it rose to about 11% of profit in FY2026.1 Cash and short-term investments grew from about ₹23 crore at the end of FY2014 to about ₹2,320 crore at the end of FY2026, an increase of nearly ₹2,300 crore.1
Notice what that implies: free cash flow and dividends together could not have produced that cash pile. It was built with debt, the IPO and retained profit, not with free cash surplus.
The real analytical question is the split between maintenance and growth capex. A port has to keep spending to stay where it is: re-dredging channels, replacing conveyor belts and overhauling cranes. The company does not separate maintenance from growth capex in a way that lets outsiders compute true owner earnings. A reasonable outside guess is that maintenance spending sits somewhere near or below the depreciation charge, which would imply that underlying owner earnings are healthy and the negative free cash flow is a deliberate investment choice.
But that is an inference. Until the company discloses the split, investors are taking it partly on trust.
The cash conversion ratio deserves one more look. Operating cash as a share of EBITDA was about 70% in FY2026, down from above 100% in FY2021 to FY2023.1 Part of that decline is working capital. Trade receivables rose from about ₹809 crore to about ₹1,058 crore during FY2026, and unbilled revenue jumped from about ₹48 crore to about ₹184 crore.1
When the money owed to a company rises faster than its revenue, more of its profit sits on the balance sheet rather than in the bank. That is not alarming at this scale, but it is a trend worth watching, and it comes back when the question turns to who owes the money.
Then there is other income. In FY2026 the company earned about ₹346 crore of other income, about 18.5% of profit before tax, mostly interest on bank deposits.1 That is a meaningful cushion under reported earnings, and it will grow while the QIP money sits in deposits. It also means a slice of the earnings the market capitalises at 45 times is treasury interest that will shrink as the cash is spent on construction. The June 2026 quarter showed that mechanism in action, as lower treasury balances pulled down other income and profit.11
One more feature of the earnings deserves a footnote in any cash analysis: lumpiness. The Jaigarh LNG-terminal contract also makes fourth-quarter comparisons lumpy.8 Contracted shortfall payments are real cash, but they are compensation for cargo that did not arrive, not evidence of throughput.
The end point is the QIP-funded cash balance. Liquidity has improved dramatically, and the company can fund its committed programme without stress. But a cash pile is not a return. The question is what the money earns once it becomes concrete and cranes, and part of the answer depends on who will pay to use them. The biggest payer, by a distance, is the parent.
IX. The Parent's Cargo Is Both the Customer and the Caveat
JSW Steel paid JSW Infrastructure about ₹1,665 crore in FY2026.1 Put that number in context. It is almost a third of the port company's revenue, and more than its entire logistics and storage businesses combined. Every port company would love a customer that size. Every minority investor should ask who sets the price.
Two different measures describe the relationship, and they answer different questions. The group-cargo share, about 51% of FY2025 tonnage and about 52% in the June 2026 quarter, measures how many tonnes crossing the quay belong to group companies.72 The related-party sales figure, about ₹2,047 crore or 38% of FY2026 revenue, measures how much money those companies paid.1 The gap between a roughly half share of tonnage and a smaller share of revenue suggests group cargo, mostly coal and iron ore moved in bulk, earns less per tonne on average than the third-party mix, or that some third-party revenue comes from higher-value services such as containers, liquids and logistics.
The company does not publish revenue per tonne by customer type, so the reason cannot be confirmed. But the gap is a clue that group volumes underpin the network's utilisation more than its margin.
The full flow of money between JSW Infrastructure and the group goes beyond sales. In FY2026, related-party sales were about ₹2,047 crore, up from about ₹1,726 crore in FY2025.1 The company also bought about ₹87 crore of goods and services from related parties, about ₹195 crore of capital goods, and paid about ₹670 crore for an asset acquisition from JSW Shipping and Logistics.1 That last item, the rail-rake purchase, shows the relationship running both ways. The group is a customer, a supplier and now a seller of assets to the listed company.
The annual report describes these as ordinary-course transactions.1 It does not set out a general transfer-pricing method, and it shows no quantified brand royalty or management fee in the FY2026 notes.1 Lease rent paid to group companies was trivial, under ₹1 crore.1 At the consolidated level the company reports very little related-party interest expense, about ₹0.10 crore, which means it is not borrowing materially from the family.1
That rules out some of the classic ways a promoter can extract value from a listed affiliate. It does not reveal whether the tariffs charged to JSW Steel are better, worse or the same as those charged to outsiders.
Does the group pay late? The disclosed terms give a partial answer. The company says credit periods for services range from one to 90 days, with or without security.1 Receivables at the end of FY2026 were about ₹1,058 crore, plus about ₹184 crore of unbilled revenue, and debtor days stood at about 72.1 On the reassuring side, the ageing table classifies receivables as good and unsecured, with no balance showing a significant increase in credit risk or classified as credit-impaired.1
The allowance for doubtful debts fell to about ₹1.03 crore from about ₹8.36 crore.1 And the debtor-day figure is far below the peak of about 230 days in FY2021, a year when the company's receivables were much more stretched.1 Customers, group and outside, are paying. The jump in unbilled revenue is a timing item that should unwind as invoices are raised, and if it does not, that will show next year.
Where the company does not disclose, the honest answer is that investors cannot know. It does not publish top-five or top-ten customer shares, supplier concentration, or port-by-port contract minimums.1 Nor does it explain how much of each take-or-pay floor is binding in a weak year. These gaps matter because the next round of growth is explicitly group-heavy. Management has said the slurry pipeline and Jatadhar will be entirely group cargo at first, and the rail rakes are deployed largely on group routes.8
So which is it, safety or leverage? The evidence supports a narrower answer than either camp offers. Group demand is commercially valuable: it fills berths, anchors financing and comes with minimum-volume contracts that rating agencies count as a strength.7 It is not a free moat. It concentrates demand on steel and power, both cyclical.
It puts the parent on both sides of key negotiations. And the disclosures do not give a group-wide transfer-pricing formula or full contract economics. The single figure that will say the most over the next few years is the third-party share of volume, which stood at 48% in the June 2026 quarter and is guided lower, measured alongside third-party revenue growth.28
All of this makes the people at the top of the company, and the incentives they work under, part of the investment case.
X. The People, the Promises and the Price
Sajjan Jindal's group has a habit of building big and early, and the port company bears the same imprint. It was conceived as part of a group strategy, its expansion has tracked the group's plants, and its most consequential deals, from the rail rakes to the greenfield ports serving group cargo, are tied to the group's industrial plans. As promoter chairman he sets that direction.1
Day-to-day delivery belongs to Rinkesh Roy, who succeeded Arun Maheshwari as chief executive in November 2024.1 Roy has brought a railway operator's emphasis to the job: on the calls he talks fluently about rake types, wagon-investment schemes and freight-corridor links, which fits a strategy built around owning the route to the hinterland.8 In September 2025 J. Nagarajan replaced Lalit Singhvi as chief financial officer; Singhvi stayed on as a strategic adviser and board member.111 Those transitions put a new management team in charge of the most capital-intensive phase in the company's history.
Pay is one place where the disclosures leave questions open. FY2026 related-party disclosures show about ₹63 crore of salaries, commissions and perquisites to key managerial personnel, down from about ₹193 crore in FY2025.1 A fall of two-thirds in a single year is unusual. The annual report does not present the aggregate figure on a fully comparable basis by executive, and it does not explain the FY2025 total as a one-off.
Leadership changes, share-based pay and severance may all play a part, but the company leaves investors to work that out. For a business earning profit in the low thousands of crore, ₹193 crore was a large number, and the governance question is why.
Ownership alignment is strong on paper. The promoter remains heavily invested, with no shares pledged.20 That means the family has every reason to want the share price to rise. It does not prove that every decision benefits minority holders, especially where the family sits on the other side of a transaction.
Financial resilience is strong, too, after the QIP. At the end of FY2026, lease liabilities were about ₹489 crore, separate from borrowings.1 After the placement, management reported a net cash position in June 2026.11 ICRA cited FY2025 debt of about 2.2 times operating profit before depreciation and interest coverage of about 8.6 times, comfortable levels for a ports business.7
ICRA's downgrade trigger, net debt above 3 times operating profit on a sustained basis, is a long way from where the company stands today.7 CARE reaffirmed its AA+ stable rating in October 2026, and ICRA's AA+ stable rating dated from January.227 Both agencies note the same risks: a large capex plan, ramp-up risk and cargo concentration.7
Currency is the risk that matters within that strong position. A large share of the debt is in US dollars, including US$400 million of 4.95% senior secured notes due 2029.1 The company reports about ₹5,026 crore of foreign-currency monetary liabilities and says some of its revenue is linked to dollar tariffs, providing a natural hedge.1 It designates the dollar borrowings as cash-flow hedges against that revenue, which pushes currency swings into other comprehensive income rather than profit.
In FY2026 the effective portion of those hedges recorded a loss of about ₹348 crore before tax in other comprehensive income.1 That loss does not hit reported earnings, but it is real economic exposure. If the rupee keeps weakening, the cost of repaying the notes in 2029 rises, and the hedge relies on dollar-linked revenue holding up.
The legal and regulatory items are small but should be named. Contingent liabilities were about ₹149 crore at March 2026, up from about ₹61 crore, with disputed GST claims accounting for about ₹124 crore.1 The company has appealed the GST credit issue and says it cannot estimate the timing of any outflow.1
Capital commitments remain large.1 The auditor's opinion was unmodified, with the impairment assessment of investments in and loans to subsidiaries flagged as a key audit matter, a natural focus for a holding company that funds new projects through special-purpose subsidiaries.1
Now the price. JSW's valuation still carries a sizeable premium to both peers.345 The market is paying a sizeable premium for JSW's growth, more than for India's largest port operator. What has earnings growth looked like lately?
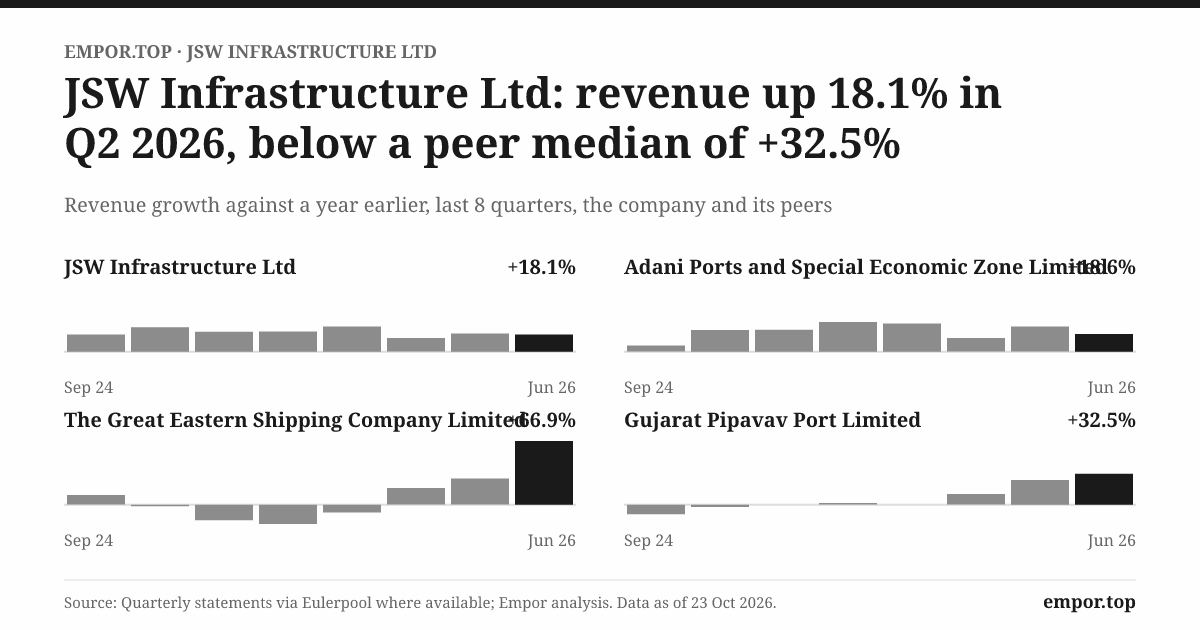
FY2026 revenue grew about 20%, but net profit grew only about 1%, and profit fell from a year earlier in both the March and June 2026 quarters.111 Higher depreciation from new assets, lower treasury income and a higher tax rate all played a part. The multiple is therefore resting on forecasts, especially management's guidance that EBITDA would roughly double by FY2028.8
A skeptical long-short investor would ask a simple question. What return must the new berths and logistics assets earn to justify paying 45 times today's profit? Assume, generously, that the ₹16,500 crore planned for FY2027 and FY2028 earns a 15% pretax return once it is fully utilised. That adds about ₹2,500 crore of operating profit, before depreciation, interest and tax, at maturity, not in FY2028. Meanwhile, the QIP diluted the share count, and the treasury income on the raised cash will fall as it is spent.
If commissioning slips by a year, or utilisation lands at the 50% the CFO modelled for the brownfields rather than higher, the earnings that justify today's price arrive later. The current multiple prices a successful growth path more than a proven return on the latest capex wave.
That is where the full weighing has to begin.
XI. Analysis & Bull-versus-Bear Case
Imagine a new terminal opening on India's west coast within sight of an established rival. The rival has a bigger network, deeper customer relationships and a logistics business of its own. The newcomer has a steel group behind it and a set of fresh concessions, but it is still raising money and pouring concrete for its next wave.
Analysts on the July 2026 call asked JSW exactly this question about Murbe, which will compete for container and bulk cargo with Jawaharlal Nehru Port and Adani's Hazira.11 Roy's answer was speed of execution plus "door-to-door services" through the logistics network.11 That is the bull case in one sentence. Whether it is true is the whole question.
The bull case starts with the physical asset. Ports are hard to replicate, because a deep-water concession next to an industrial cluster is scarce and the approvals take years. JSW's concessions are long-lived, and its brownfield sites already have rail and conveyor links. India's industrial clusters need reliable logistics, and steel capacity, in particular, is growing. The third-party share has risen in two years from about 40% to about half, which is direct evidence that outside customers value these berths.98
Navkar's turnaround shows the logistics thesis can work in practice, at least on one platform.8 The QIP removed immediate funding risk, and the rating agencies are comfortable.72219 If the slurry pipeline, Jatadhar and the brownfield upgrades all deliver on schedule, the FY2028 EBITDA target is plausible, and the company would emerge as India's clear second private port operator with a nationwide logistics network.
The bear case starts with scale and concentration. Adani Ports is far larger and already offers the integrated port-plus-logistics service JSW is building, so in any contested market JSW is the challenger.4 Customers can choose among ports wherever geography allows, and the Paradip iron-ore experience showed that third-party bulk cargo is fickle.8
The company is still about 83% coal and iron ore and still draws about 38% of revenue from group affiliates, and management expects the group share of volume to rise again.718 The valuation already sits above the company's own history and both peers, while recent profit growth has stalled.
Helmer's seven powers sharpen the debate. Scale economies favour Adani more than JSW nationally, although JSW enjoys local scale in its own clusters. Network economics, in the sense that each new customer makes the service more valuable to the next, are weak in bulk ports. Counter-positioning is absent, since nothing in JSW's model is something Adani cannot copy. Switching costs exist where a plant is tied to a port's evacuation system, which is strongest for the group itself.
Brand counts for little in bulk logistics. Cornered resources, in the form of concessions at particular sites, are JSW's clearest power, though they are bought at auction. And process power, the operating know-how to run mechanised bulk terminals efficiently, is real, though margins around 50% in the ports segment suggest the company is good at it rather than uniquely better than peers.11 Taken together, the powers support the route-specific advantage already established, not a national franchise.
The logistics thesis needs testing against economics rather than ambition. Navkar contributes a platform, and its margins and EBITDA are improving.11 The rail rakes come with group cargo built in.8 But last-mile logistics is a fragmented, competitive business, and synergies must show up in segment margins and returns, not in fleet counts or terminal announcements. The ₹2,000 crore logistics ambition that analysts referenced will need more acquisitions or construction, by the CFO's own admission.8
Capital strength meets the same test. The QIP reduced immediate pressure, and net cash in June 2026 gives the company years of runway.11 But the committed programme could still stretch execution, and the dilution from the placement raises the bar for per-share returns. A company with net cash and a ₹16,500 crore two-year plan will most likely return to net debt by FY2028, and the rating agencies will then focus on whether new assets are generating the operating profit to service it.7
Three operating measures matter most from here. The first is the group share of cargo volume, now about 52% and guided towards 53% to 55% as group-dedicated assets come on.28 A reading that stays near half while total volume grows would show genuine third-party traction. The second is throughput and utilisation at newly commissioned assets, particularly Jatadhar, the slurry pipeline and the Jaigarh and Dharamtar expansions, against the volume path to 165 to 175 million tonnes in FY2028.8
The third is cash flow after capex, which was negative in FY2026 and will tell investors whether the network can fund itself once the building peaks.1
For valuation, the measure that matters is incremental operating profit and return on capital from the capacity additions. Return on capital employed was about 10.8% in FY2026 and has drifted down as construction outpaced earnings.1 If it rises as projects open, the premium multiple can be justified. If it stays flat, the market will compare JSW with its peers and the company's own five-year history and ask why it should be worth more.
None of this resolves into a verdict on the stock. It resolves into a clear statement of what each side needs. The bull case rests on converting a location-led port platform into a broader third-party logistics network. The bear case is that group-linked commodity cargo, project risk and a premium valuation leave returns dependent on execution that has not yet happened.
XII. Playbook: Business & Investing Lessons
The first lesson goes back to the berth at Mormugao. South West Port existed because a steel mill needed it, and that guaranteed traffic financed the first asset and taught the company its trade. Nearly three decades later, the parent remains a major customer, and the next wave of projects again serves its plants. An anchor customer is the cheapest capital an infrastructure business will ever get, because it removes demand risk exactly when the asset is most fragile. But the anchor's bargaining power persists, shifting from the construction phase to the pricing phase. For founders building inside a group, and investors buying into one, the line to remember is this: an anchor customer can finance the beginning; it cannot be the whole market forever.
The second lesson comes from Paradip and the auction at Tajpur. JSW's ports have an advantage near the plants that need them, but that advantage did not protect Paradip when the iron-ore export market turned, and Adani outbid JSW for a new deep-sea site in Bengal.812 Geography is a moat only within the radius of a railway line. Investors should value port companies cluster by cluster, not as single national franchises, and should treat every claim of "pan-India" competitive advantage as a hypothesis to be tested at each new site. A port is a local advantage, not a national moat by itself.
The third lesson comes from Navkar and the rail rakes. Navkar's EBITDA rose after JSW took control, a genuine improvement.8 The rakes came from the family at about 8 times forward EBITDA, with earnings that depend on JSW Steel cargo.16 Both deals may prove sensible. The lesson is about how to judge them: not by the strategic slide, but by the traffic and returns that arrive afterwards. Buying the route is only smart if the traffic follows at a price the returns can carry.
The fourth lesson is about the company's history of capacity targets, which have moved from 200 million tonnes by 2020 to 400 million by 2030 or earlier, with 300 million now promised by FY2028.1711 Capacity grew, but a nameplate number is an engineering fact, and the market keeps rewarding it as if it were a commercial one. Investors in any infrastructure company, from ports to data centres to power plants, should ask for utilisation and return on each new asset, not the size of the order book. A target is a promise about construction; utilisation is the proof of value.
The fifth lesson is about the placement that turned net debt into net cash in a single quarter.11 That raise gave JSW Infrastructure years of runway and, by issuing new shares rather than selling promoter stock, aligned the family with outside shareholders. It also diluted everyone and, for now, lets bank interest pad the earnings. The money buys management time to finish the berths. It does not buy the returns. Equity can buy time, but only cash returns can make the time worthwhile.
XIII. Epilogue
Tonight, in late October 2026, JSW Infrastructure stands in an unusual place for a ports company: rich in cash, short of finished projects, and valued as if the projects were already full. Its balance sheet and credit ratings are strong.112219 It is spending faster than ever, with much more ordered since March 2026.111 And its share price embeds the expectation that the next eighteen months will go to plan.
The next moments that decide the story are already on the calendar. In March 2027 the slurry pipeline and Jatadhar are due for completion.811 If they open on time and their take-or-pay contracts start paying, the company gets its biggest single boost in EBITDA and the FY2028 guidance looks reachable. If either slips, the "massive ramp-up" in FY2028 slides into FY2029, and the multiple has to carry another year of waiting.
Around the turn of 2027 construction is supposed to begin at Murbe, and Keni's environmental clearance should arrive if the coastal-zone process moves as management expects.11 Each of those milestones is a test of the company's new management team, and of the gap between a capacity target and a commissioning certificate.
Alongside the projects, three readings will tell the story quarter by quarter. Watch the group versus third-party share of cargo, the utilisation of new capacity and the port-level cargo mix, especially whether non-coal, non-ore cargo grows. Compare annual capex with the budget and commitments, then track incremental EBITDA and return on capital as the new assets open. And watch working capital: whether receivables, now at about 72 debtor days, and unbilled revenue grow faster than revenue, and whether operating cash continues to exceed profits once growth capex is set aside.1
Geopolitics will intrude too. The Fujairah terminal's recovery, the insurance claim that management expected to resolve by the end of October, and the Oman concession all depend on events in the Gulf that no port company controls.11 These are small parts of the business, but they are the parts most likely to surprise in either direction.
There is also a quieter policy question running underneath the coming quarters. Management has said the newer terminals at JNPA, Tuticorin and Kolkata have freedom to set tariffs, while the ministry has yet to decide whether older terminals inside major ports get the same freedom.8 A favourable decision would let the company reprice some existing berths; no decision leaves those tariffs where they are. Roy said discussions were continuing but would not give a date, which is the right answer to treat as no answer at all.8
The central questions from the beginning still have no settled answers. Cargo from the parent remains essential, and guidance says it will grow faster than outside cargo for a while. The moat is real but local. The expansion is funded but not yet earning. The price assumes success. Only after the operating evidence arrives does it make sense to revisit the valuation. Until then the story turns on execution and conversion: projects must open, cargo must arrive, receivables must collect, and cash must remain after capex.
XIV. Outro
Somewhere on the Konkan coast tonight, a bulk carrier is easing away from a JSW berth. Its holds are empty, the coal already on a conveyor heading inland, and the cranes are already swinging towards the next arrival. Nearly three decades ago that next ship would have been carrying cargo for one customer, a steel plant on the Deccan plateau. Today, about half the cargo it carries belongs to someone else.2
That is the whole tension of JSW Infrastructure in one image. It is still a bridge between the JSW Group and the sea, now trying to prove the bridge can carry a much wider economy, from containers at Kolkata to iron ore at Jatadhar to whatever new industries take root behind Murbe. The 400-million-tonne target is the ambition. Whether the berths fill with strangers' cargo is the test. The port began as a way to move steel. Its future depends on what else it can move.
References
-
Integrated Annual Report 2025–26 — JSW Infrastructure, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q1 FY2027 Results Presentation — JSW Infrastructure, 2026-07-21 ↩↩↩↩↩↩↩
-
Quarterly Results and Call Transcripts — JSW Infrastructure ↩↩↩↩
-
Adani Ports ratios — Stock Analysis, accessed 2026-10-23 ↩↩↩↩
-
Gujarat Pipavav Port ratios — Stock Analysis, accessed 2026-10-23 ↩↩↩
-
JSW Infrastructure Limited: Ratings reaffirmed and assigned for enhanced amount — ICRA, 2026-01-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q3 FY2026 Earnings Call Transcript — JSW Infrastructure, 2026-01-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q4 and FY2025 Results Presentation — JSW Infrastructure, 2025 ↩↩↩
-
JSW Infrastructure announces Q4 and FY2025 results — JSW Group, 2025 ↩
-
Q1 FY2027 Earnings Conference Call Transcript — JSW Infrastructure, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Tajpur Port Bid: Adani Emerges Highest Bidder in Fight with JSW — ET Infra, 2022-03-18 ↩↩
-
JSW Infrastructure Agrees to Acquire Navkar Corporation — The Economic Times, 2024-06-28 ↩↩
-
Investor Presentation, September 2024 — JSW Infrastructure ↩↩↩
-
Postal Ballot Notice, December 2025 — JSW Infrastructure ↩↩↩↩
-
JSW Group makes another attempt to scale up cement, port business — Business Standard, 2023-09-27 ↩↩↩↩
-
Postal Ballot Notice, February 2026 — JSW Infrastructure, 2026-02-20 ↩
-
Moody's rating exchange filing — JSW Infrastructure, 2026-07-02 ↩↩↩
-
Shareholding Pattern, quarter ended 30 September 2026 — JSW Infrastructure ↩↩↩↩↩
-
JSW Infra aims for 400 MTPA capacity with capex of Rs 30k crore by FY30 — Business Standard, 2024-12-19 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube