Jio Financial Services: A Reliance Stake That Wants to Be a Lender
I. Introduction & Roadmap
On a July morning in 2023, the National Stock Exchange opened a special pre-open session for a company that had never traded. No IPO, no roadshow, no order book built by bankers. Jio Financial Services had simply been carved out of Reliance Industries, and the market had to work out what a share of it was worth. The answer came back at ₹261.85.12
That number was a guess about a promise. Mukesh Ambani's group had spent two decades turning telecom and retail into national utilities, and now it said finance would be next. What happened after the stock began trading in August was less triumphant. Index funds that had held it only because it came out of Reliance had to sell, and the shares hit a series of lower circuits in their first trading sessions.2
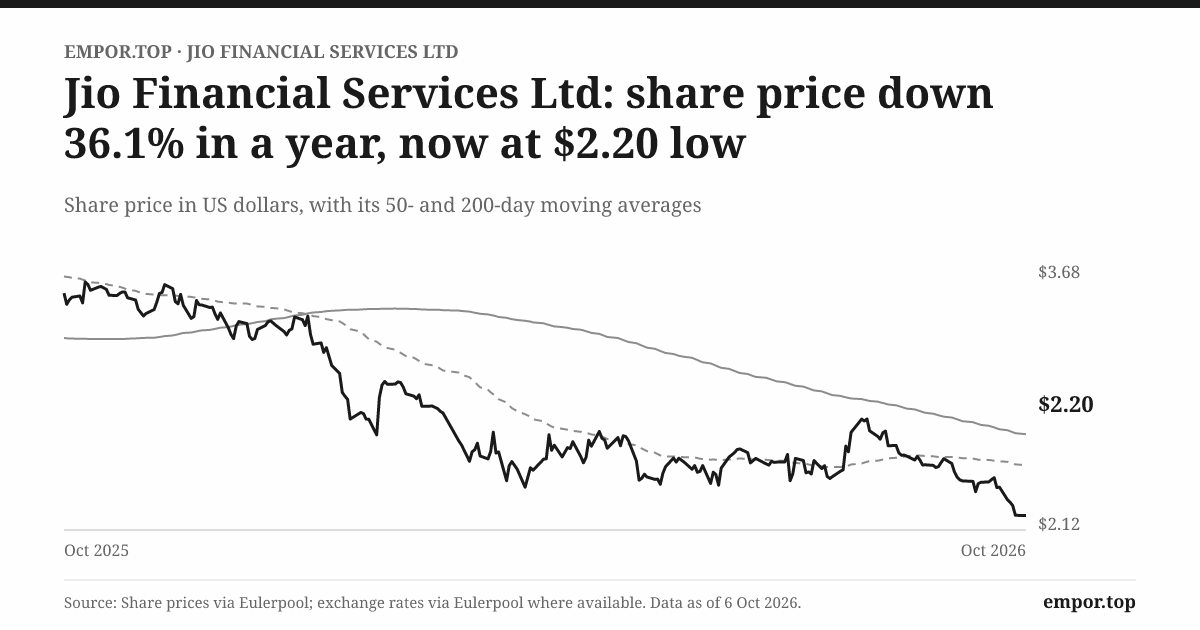
Three years on, on 6 October 2026, the stock closed at ₹212.27. That is below the price the market found on that first morning, and it was the lowest close of the past year, about a third below the 52-week high of ₹315.[^5] The company is worth about ₹134,800 crore, roughly $14 billion.[^5]
Here is the puzzle the rest of this story tries to solve. On one measure JFSL looks almost absurdly cheap: the market values it at about 1.1 times the book value of its equity. On another it looks absurdly expensive: about 84 times the last year's earnings.[^5] Its return on equity is around 1.5%, about what a savings account pays in a bad year.[^5]
Both numbers are right, and they describe two different companies wearing one ticker. The book value is mostly a block of Reliance Industries shares, about 6.1% of Reliance, received in the demerger.34 The earnings, by contrast, increasingly come from a young lending business that is spending heavily to grow up. A cheap price on the shares it owns, an expensive price on the profits it makes: that is the whole riddle.
So this is a story built around four questions.
First, is JFSL an operating financial company, or mostly a holding vehicle for Reliance shares?
Second, can a lender that roughly tripled its book in a year keep its loans clean?
Third, how much of the growth depends on transactions with the rest of the Reliance group?
Fourth, will margins recover as costs settle, or is the fat margin of 2023 gone for good?
It helps to be clear about what this story is not. It is not about Jio's telecom network, Reliance Retail's stores or the refineries in Jamnagar. Those belong to Reliance Industries. JFSL shares the Jio brand and the Ambani promoter family with them, and nothing else on its balance sheet comes from those businesses except the dividend cheque on its Reliance stake.
Management and much of the coverage describe finance as a "fourth engine" for the Ambani empire, next to energy, telecom and retail. The consolidated numbers say something more modest. In the year to March 2026, JFSL reported revenue of about $400 million and net profit of about $177 million.[^5] For a group whose individual businesses earn billions, that is not yet an engine. It is a pilot light, and whether it catches is the question investors are paying for.
To see why the Ambanis wanted finance at all, the story has to go back briefly to a company that carried their name long before Jio did.
 Subscribe on LinkedIn
II. Why the Ambanis Wanted Finance, Briefly
Reliance has been in finance before. Reliance Capital was set up in 1986, in Dhirubhai Ambani's era, as the group's money arm.[^8] When Dhirubhai died in 2002 and his sons Mukesh and Anil fought over the empire, the settlement that followed handed financial services to Anil. Reliance Capital went with him, and over the following decade and a half it slid into debt trouble and eventually insolvency. For Mukesh, that split left a gap: the most valuable consumer franchises in India and no balance sheet to lend against them.
The restart was slow and modest. In 2015 the Reserve Bank of India gave Reliance in-principle approval for a payments bank, a stripped-down licence that lets a company take small deposits and move money but not make loans.5 It was a toe in the water, run with State Bank of India as a partner.
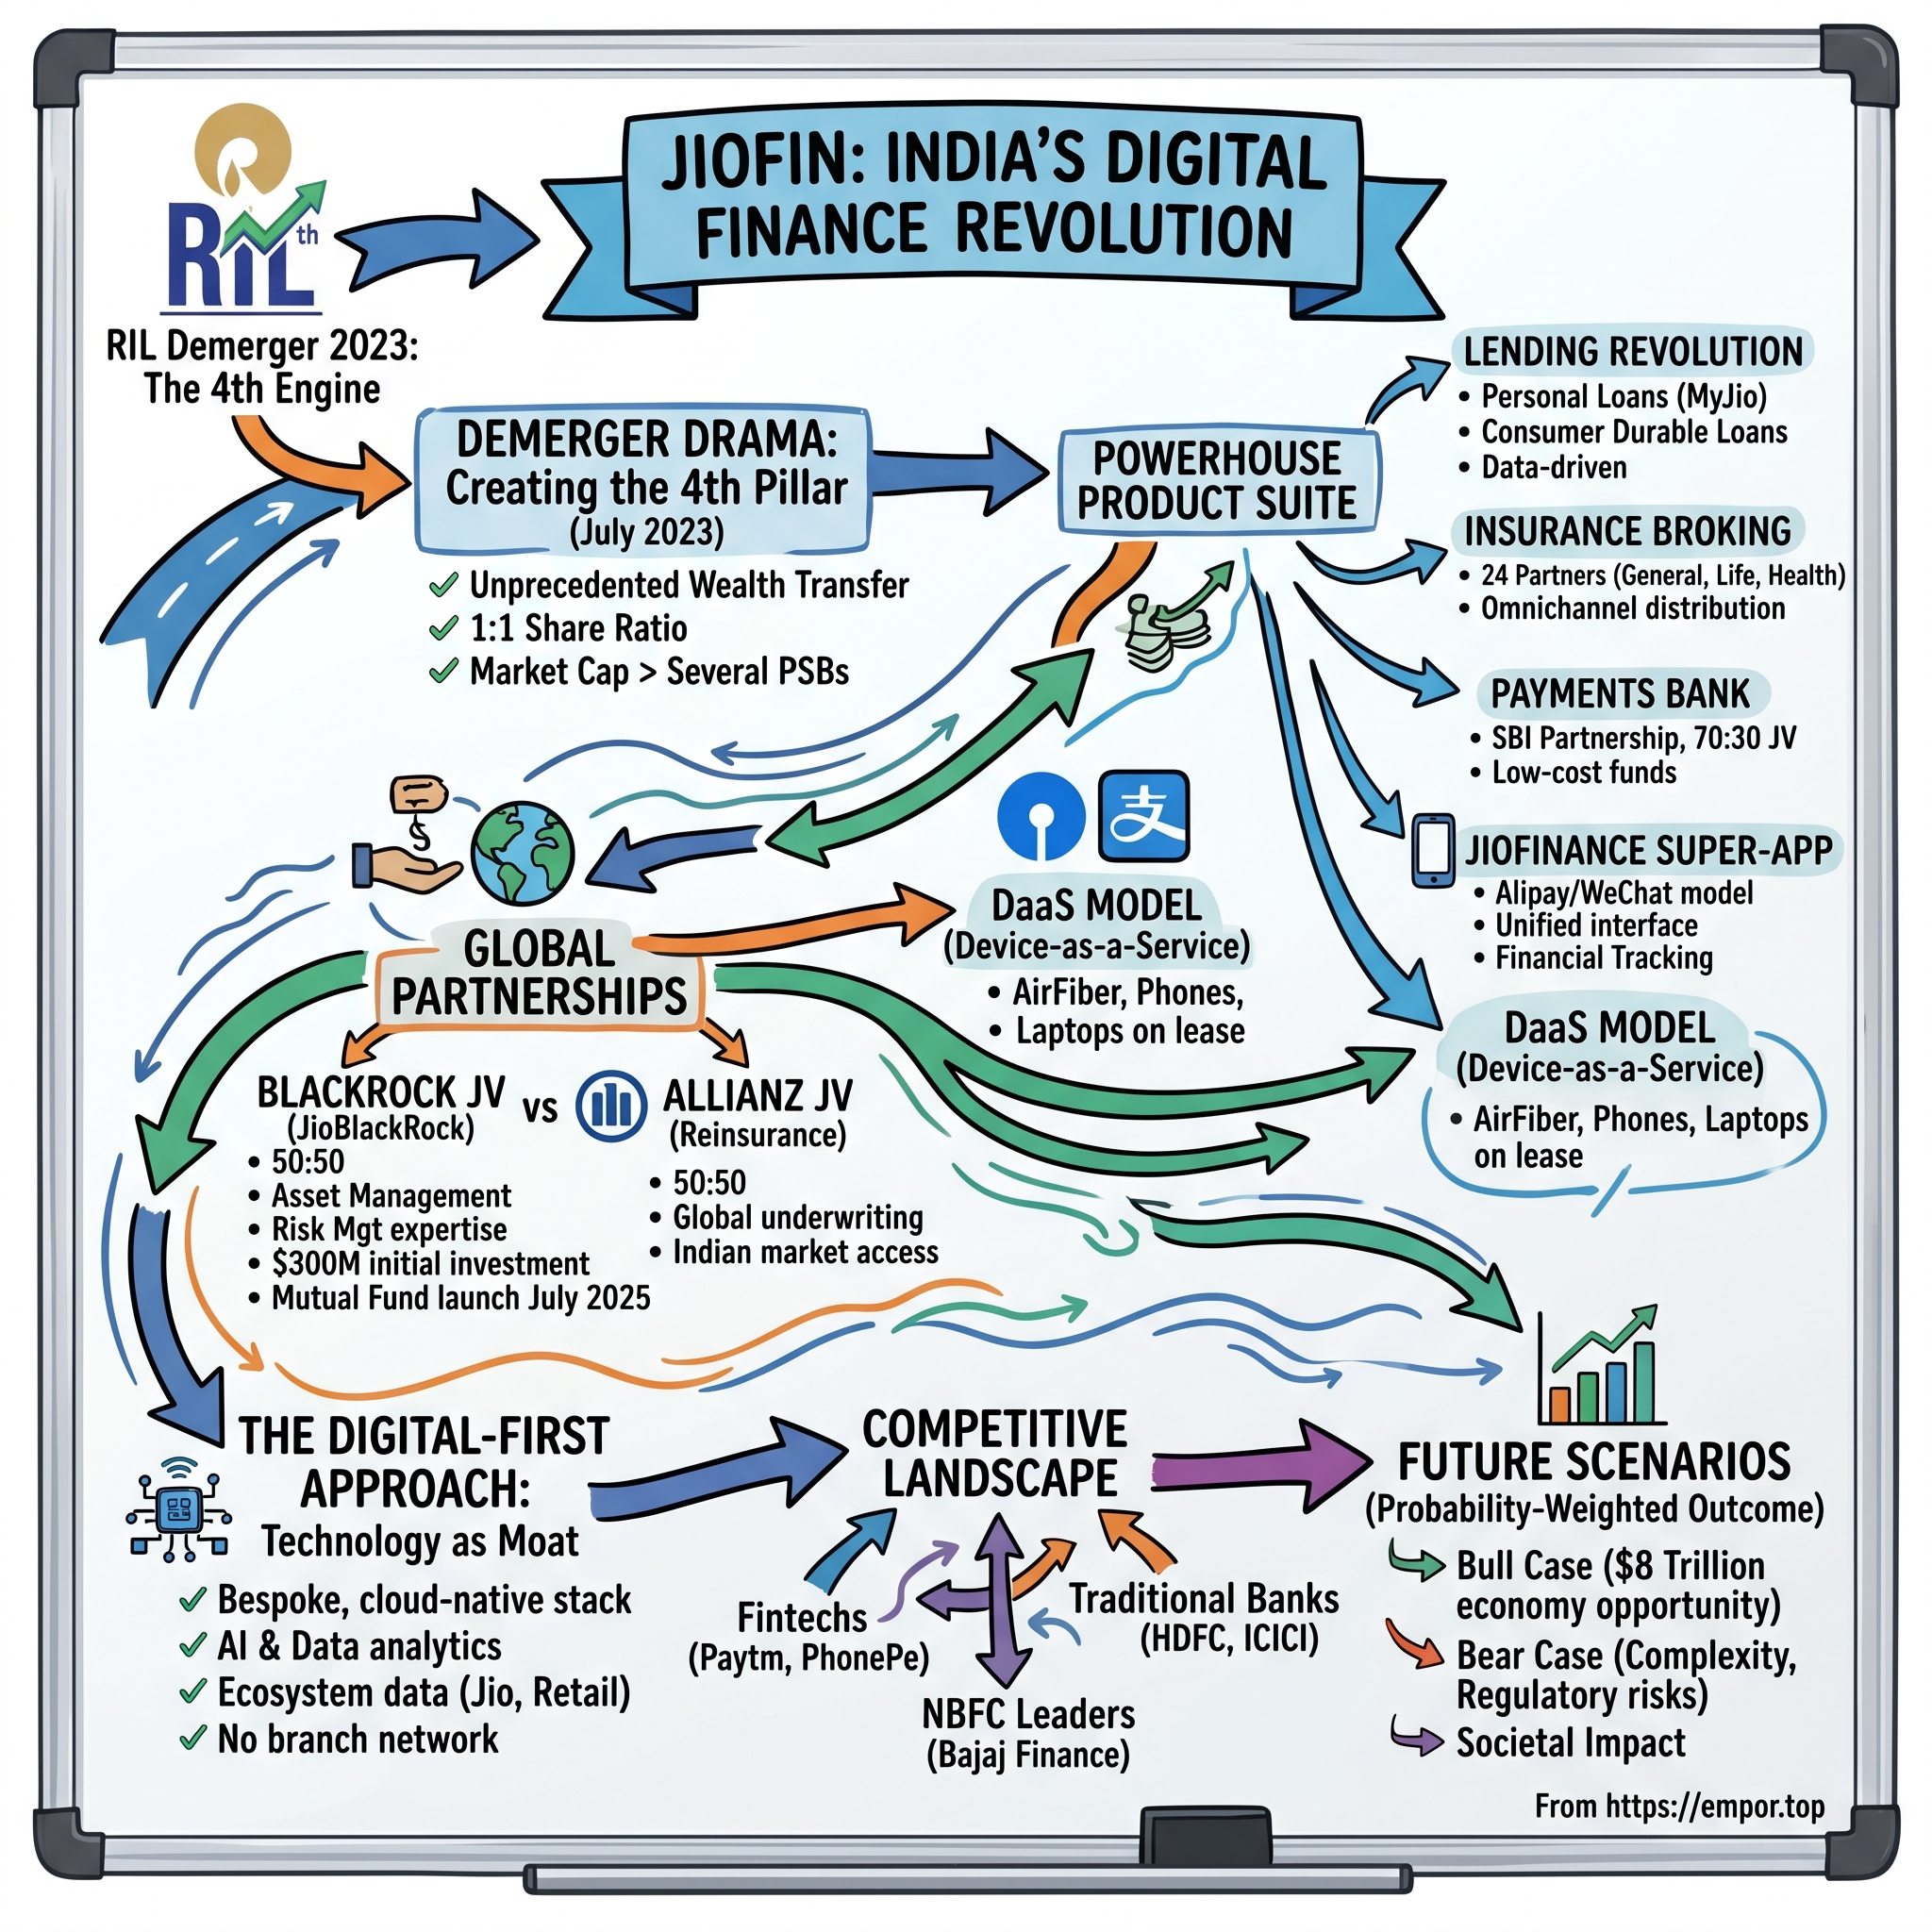
The real move came in 2023, when Reliance demerged its financial-services arm into a separately listed company and gave it the Reliance shares that had been sitting inside it.[^8] Shareholders of Reliance received one JFSL share for each Reliance share they held.[^8]
Why the old numbers lie
Anyone pulling up JFSL's history in a data terminal sees a decade of numbers going back to 2015. They should be ignored. Before the demerger the listed entity was a small investment shell inside the group, swinging between losses and revenue of a few tens of millions of dollars.[^5] In the year to March 2023, revenue was about $4.8 million. The following year, the first full year as JFSL, it was about $224 million.[^5]
That is not growth. It is a different company moving into an old legal wrapper. Any five- or ten-year growth rate computed across that break is an artefact, and any comparison of today's margin against the "shell years" says nothing about how the business works.
The intended edge
Why would a telecom-and-retail group want its own financial company? The strategic logic was straightforward. Jio has hundreds of millions of mobile users; Reliance Retail runs thousands of stores. Each touchpoint is a place to offer a loan, an insurance policy or a payment account, and each transaction generates data about who is likely to repay. In the pitch, distribution and data would let JFSL find borrowers more cheaply than a bank with branches.
It is a good theory. The rest of this story tests it against what the company has actually lent, and to whom. As later sections show, the loan book so far is dominated by corporate loans and loans against property, the least distribution-led products in finance. The Jio edge is asserted far more than it is visible.
Before any of that, though, there is the question of what the company already owned on the day it listed, because that block of shares still explains most of its value.
III. The Demerger and the Stake Nobody Talks About
The special pre-open session on 20 July 2023 had an odd purpose. Reliance's own share price had to be adjusted for the value it was giving away, and the only way to measure that value was to let the market bid for a company that did not yet trade. When the session closed, the market had implied ₹261.85 per JFSL share.2 Index providers kept JFSL inside their indices at that price, which meant that every passive fund tracking the Nifty or Sensex suddenly held a stock it would have to sell once the company listed and was removed.
When trading began on 21 August 2023, the selling arrived. JFSL hit its lower circuit, the daily limit on how far a stock can fall, in several consecutive sessions.2 This was mechanics, not a verdict on the business. But it set the tone. The stock has rarely been priced as a lender since; it has been priced as a basket of Reliance shares with an option attached.
The asset on the balance sheet
Look at JFSL's balance sheet at March 2026 and one line dominates. Investments came to about $18.0 billion, against shareholders' equity of about $15.2 billion and cash of only about $400 million.[^5] Total assets were about $18.5 billion.[^5] The loan book is real and growing, but it is a small slice of that.
The investments are mostly the 6.1% stake in Reliance Industries.4 The Ken, the business publication, worked through the arithmetic and concluded that more than three-quarters of JFSL's value comes from that stake.4 The market value of JFSL and its book value are therefore both, to a large extent, a reflection of Reliance's share price.
This explains the strange multiples in the opening. A price-to-book of 1.1 is not a sign that investors think a lender is cheap. It is a sign that investors are paying roughly face value for a portfolio of listed shares, plus a little for everything else.[^5] And an ROE of 1.5% is what happens when a huge equity base made of shares that yield a modest dividend sits under a small operating business.[^5]
The dividend that props up the profit
The cleanest way to see the holding-company problem is a single quarter. In the three months to June 2026, JFSL reported dividend income of about ₹509 crore.1 In the same quarter its pre-provision operating profit, the profit before setting aside money for bad loans and before tax, was about ₹505 crore.1
Put those two figures side by side and the implication is stark. If the dividend sits inside that operating profit, then everything else JFSL does, lending, payments, insurance, leasing and asset management together, roughly broke even before provisions in that quarter. The quarter's profit was almost entirely a dividend cheque. The payer is not broken out in the quarterly summary, but the timing and size are consistent with the annual Reliance dividend landing on a 6.1% stake.14
That is also why JFSL's profits are lumpy. The September quarters of 2023, 2024 and 2025 each show net profit roughly double the quarters around them.[^5] A lender's earnings should not jump every September. A holder of Reliance shares, which receive Reliance's annual dividend once a year, does. In 2026 the dividend appears to have landed in the June quarter, which flatters the most recent results; the next section returns to that.
The stake as a credit asset
There is an irony here. The same stake that depresses ROE is what makes JFSL cheap to fund. CRISIL, the rating agency, rated Jio Credit AAA and explicitly cited JFS's holding in an AAA-rated Reliance as a source of financial flexibility.3 A lender with a pile of liquid blue-chip shares behind it can borrow on terms that a start-up NBFC never could.
So the stake does two jobs. It anchors the valuation and it lowers the cost of money. What it does not do is make JFSL a good business on its own. Selling it would raise ROE and remove the funding cushion at the same stroke.
Who owns JFSL
The Ambani promoter group held about 47.12% after listing, up from 45.8% before it.3 Foreign and domestic institutions and millions of retail shareholders who received shares in the demerger hold most of the rest.2 Promoters holding just under half means the family controls the company in practice, while public shareholders bear most of the economic exposure to whatever it does with its capital.
The company has started to return a little of that capital. JFSL paid its first dividend, fifty paise per share, out of FY25 profits; the cash went out in FY26 and equalled about a fifth of that year's net profit.[^5] A company paying shareholders out of dividends it receives from its parent's shares is, again, behaving like a holding vehicle.
The verdict on the first central question is clear on value: JFSL is still mostly a Reliance stake. On earnings, it is close to a dead heat, and the deciding figure is the operating business excluding dividends, which in June 2026 was roughly zero before provisions. The more interesting question is whether that changes, and the answer lives in the lending arm.
IV. Building a Lender From Zero: Jio Credit
In the three months to June 2026, Jio Credit disbursed about ₹11,250 crore of new loans.6 That is about 2.7 times what it lent in the same quarter a year earlier, and more than the entire loan book was worth fifteen months before.16
That last comparison is the striking one. At March 2025, Jio Credit's assets under management were about ₹10,100 crore.3 By June 2026 they were about ₹30,700 crore, up about 163% in a year.6 Building a ₹30,000 crore book from close to zero in roughly two and a half years is an achievement of execution and funding. Whether it is an achievement of underwriting is a separate question, and no one, including the rating agency, can yet answer it.
What kind of lender is this?
Begin with what Jio Credit lends against. At March 2025, about 46% of the book was corporate lending, about 41% was loans against property, about 10% was home loans and the remaining 3% other products.3 The top 20 borrowers accounted for about 29.8% of the book.3
That mix does not look like the Jio thesis. Loans against property, where a small business owner pledges a building, and corporate loans, where a relationship manager negotiates with a finance director, are sold through bankers and brokers, not through an app on a telecom subscriber's phone. They are sensible products for a new lender with cheap money: secured, chunky, quick to build volume. But they test the funding advantage, not the distribution advantage.
Concentration matters here too. When almost 30% of a lending book sits with 20 borrowers, a single bad credit decision can move the whole company's numbers. A retail lender spreads risk across millions of small loans. A corporate lender concentrates it in a few large ones.
The competitive field
India's lending market splits into banks, which take deposits and are heavily regulated, and non-bank financial companies, NBFCs, which borrow wholesale and lend on. Jio Credit is an NBFC. Its competition includes banks such as HDFC Bank, which can lend from cheap savings deposits, and NBFCs such as Bajaj Finance, Tata Capital and L&T Finance, each of which has built books many times Jio Credit's size over decades. By scale, Jio Credit is still a small entrant in a crowded room.
Group-backed NBFCs are a familiar pattern in India. Tata Capital and L&T Finance both lean on parent names for funding. The industry's history also contains group-backed lenders that grew fast and then stumbled, which is why rating agencies treat promoter support as a cushion, not a guarantee.
Funding: the evidenced edge
What Jio Credit has that most newcomers lack is cheap money. CRISIL rated it AAA/Stable for long-term debt and A1+ for short-term paper, its highest grades, and reaffirmed those ratings in July 2025.3 At that point Jio Credit had sanctioned or rated facilities of about ₹9,000 crore of bank lines, ₹30,000 crore of non-convertible debentures and ₹6,000 crore of commercial paper.3
How much of that AAA belongs to the business, and how much to the parent? CRISIL's own list of strengths is revealing: the promoter's track record, the Jio brand, JFS's stake in an AAA-rated Reliance, an experienced management team and strong liquidity.3 Its list of constraints is equally telling: early-stage operations, untested underwriting, borrower concentration and modest core earnings.3 Read together, the rating is a rating of the group's support, not of a loan book's history. That is not a criticism; it is what an AAA for a two-year-old lender has to mean.
Leverage has risen quickly. Jio Credit's gearing, debt divided by net worth, went from essentially zero in FY24 to about 1.2 times at March 2025, on a net worth of about ₹4,900 crore.3 At the consolidated level, borrowings rose from about $470 million to about $2.5 billion in the year to March 2026, though debt-to-equity stayed low at about 0.16 because the equity base is mostly Reliance shares.[^5] That consolidated ratio flatters the lender; the relevant leverage is the subsidiary's.
Reading the cash flow
For a lender, the cash-flow statement is not a test of earnings quality. Making a loan is cash going out of operations, and borrowing to fund it is cash coming in through financing. JFSL's FY26 statement shows exactly that shape: about $2.4 billion raised through financing and about $2.5 billion deployed through investing.[^5] Operating cash flow swung from about −$1.2 billion in FY25 to about +$130 million in FY26.[^5] These are lending and treasury flows. They say the company is growing its balance sheet with borrowed money, which is what a new lender does, and nothing more.
The test not yet taken
CRISIL reported nil delinquencies at 31 March 2025 and called asset quality "yet to be tested."3 That phrase deserves weight. A loan made in 2025 that will default typically does so a year or two later, after the borrower has run through its cushion. When a book triples in a year, most of it is less than twelve months old, and the bad-loan ratio is held down simply because the denominator is full of fresh loans.
This is the mechanism investors need to watch. Credit costs arrive after the growth, not with it. The rate cuts that made 2025 and 2026 a good time to lend also compressed spreads and pulled marginal borrowers into the market. Jio Credit's next two years will show whether its underwriting was disciplined or merely early.
The verdict on the second central question: volume is proven, underwriting is not. A clean record on a young book is not evidence of skill; it is an absence of evidence. The figures that will settle it are Jio Credit's gross non-performing assets and stage-3 loans as the 2025 and 2026 vintages season.
Building that book cost a great deal of money, and the cost shows up in the margins.
V. The Margin Collapse and the Bounce
In the quarter to March 2026, JFSL's revenue was almost double what it had been a year earlier. Its net profit fell by about 14%.[^5] Operating margin, which had been 87% in the June quarter of 2023, came in at about 32%.[^5]
That is the kind of quarter that makes analysts reach for the expense lines. Revenue up 97%, profit down: something in between grew faster than the top line.
Decomposing the collapse
Start with what the 2023 margin actually was. In JFSL's first quarters, revenue was mostly treasury income and dividends on the Reliance stake, and costs were tiny because there was almost no business to run. A margin of 87% was not a feature of a great lender. It was the margin of a portfolio with a skeleton staff.[^5]
As the operating businesses came alive, three kinds of cost arrived at once. The first is interest: a lender that borrows ₹20,000 crore pays interest on it, and that expense scales with the book. The second is people and technology for the lending, payments, leasing and insurance arms. The third is the cost of new businesses such as reinsurance, where premiums come in as revenue but claims reserves and payouts go out as expense.
By the June 2026 quarter, total expenses were about ₹1,000 crore, up about 291% from a year earlier.16 Revenue from operations was about ₹2,000 crore, up about 227%.1 When costs grow faster than revenue, margins fall, however impressive the top line looks. Pre-provision operating profit rose only about 38%.1
For the full year to March 2026, the result was revenue up about 73% and net profit down about 3%.[^5] JFSL earned less in its third year than in its first.
The bounce, and what is inside it
Then came June 2026. Net profit was about ₹830 crore, up about 156% on the year and roughly three times the March quarter's ₹272 crore.16 Operating margin rebounded to about 51%.[^5]
It is tempting to call that a turn. The decomposition says wait. The quarter contained the roughly ₹509 crore dividend described in Section III, which in earlier years had landed in September quarters.1[^5] It contained about ₹266 crore of reinsurance premiums from the first full quarter of a new business, which is revenue with liabilities attached.6 And it contained genuinely higher lending income: interest income of about ₹960 crore, up about 165%, and Jio Credit net interest income of about ₹257 crore, up about 118%.16
Strip out the dividend's timing and the picture changes. The year-on-year comparison flatters June 2026 because June 2025 had no equivalent dividend. The September 2026 quarter will likely look weak against September 2025 for the same reason. Seen over the eight quarters before June 2026, profit was flat to falling.[^5]
Is the 2023 margin gone?
Yes, and it should be. A lender cannot run at 80% operating margins; banks and NBFCs carry interest and staff costs that a share portfolio does not. The useful question is not whether margins return to 2023 but what margin the operating business settles at once it is mature. Large Indian NBFCs earn returns on equity in the mid-to-high teens. JFSL's ROE is about 1.5%.[^5] The distance between those two numbers is the size of the bet.
Management has described the cost build as investment in technology and distribution that will be absorbed as volumes grow. That claim is testable: cost-to-income should fall quarter by quarter as the book grows. The company has not published a target date for it, and the latest quarter's cost growth ran ahead of revenue growth, which is the opposite of operating leverage.1
The verdict on the fourth question: the 2023 margin was a portfolio margin and will not return; the June 2026 bounce is mostly a dividend in a different quarter, with real but smaller improvement underneath. The settling figure is cost-to-income and ROE excluding the Reliance stake over the next two to four quarters.
If lending is where JFSL makes its money, distribution is where it was supposed to find its customers.
VI. Payments Bank, the App and the Distribution Test
In May 2024, JFSL rolled out the JioFinance app, a single app for UPI payments, a bank account, insurance and loans.6 It was the public face of the distribution thesis: take a Jio phone user and turn them into a financial customer with a few taps.
Two years on, the app had around 9 million average monthly active users.6 The payments bank had about 3.9 million accounts and about ₹617 crore in deposits.6 These are real numbers built quickly. They are also small against a Jio subscriber base in the hundreds of millions, which is the comparison management's own pitch invites.
Why UPI makes almost no money
India's Unified Payments Interface lets anyone send money from any bank account to any other, instantly and for free. That is wonderful for consumers and terrible for payment apps. Person-to-person and most merchant UPI transfers carry no fee to the user, by policy, so apps such as PhonePe and Google Pay, which between them process the overwhelming majority of UPI transactions, earn little from the payments themselves.5 They make money by selling loans, insurance and merchant services to the users the free payments attract.
JFSL's payment-solutions business shows what that looks like in practice. In the June 2026 quarter, it booked gross fee income of about ₹176 crore but net fee income of only about ₹24 crore.6 In plain terms, almost all of the money flowing through it was passed on to others. A take rate that thin is a pipe, not a moat.
The payments-bank question
The payments-bank model has a rough history in India. Several companies that received licences alongside Reliance in 2015 gave them back without ever starting, and others struggled, because a bank that cannot lend has to live on fees and float.5 The best-known survivor, Paytm Payments Bank, was ordered by the RBI in early 2024 to stop taking new deposits.5
Against that record, Reliance bought out State Bank of India's stake in the payments bank, making it a wholly-owned subsidiary.6 The case for doing so is control: a bank account is the anchor for a customer relationship, and a fully owned bank can be integrated with the app and the lender. The case against is that it adds a business with a structurally poor earnings model. With ₹617 crore of deposits, the payments bank is not yet a material funding source for a lender with a ₹30,000 crore book.6
What would prove the thesis
The comparison that matters is not JFSL against PhonePe on UPI share. JFSL is not going to win the payments war, and does not need to. The test is whether app users convert into borrowers, policyholders and investors at a cost below what Bajaj Finance or HDFC Bank pay to acquire the same customer. If Jio's reach is an edge, it should show up as a growing share of retail loans originated through the app, at lower acquisition cost. The current loan mix, dominated by corporate and property loans, shows no sign of it yet.
The verdict: reach is real, monetisation is small. The super-app idea and the comparisons to China's 蚂蚁集团 Ant Group that circulated around the listing remain claims without numbers behind them. The insurance broking arm, which distributes policies from multiple insurers, is a similar story of distribution waiting for proof.
Where JFSL lacks capability, it has borrowed it, from two of the biggest names in global finance.
VII. The Joint Ventures: Renting Credibility
On 26 July 2023, before JFSL had even listed, BlackRock announced a 50:50 joint venture with it to enter Indian asset management.[^9] The world's largest money manager would bring products and investment process; JFSL would bring distribution and the Jio name. The announcement did more for the listing narrative than any line in the demerger scheme.
A second partnership followed with Allianz, the German insurer, covering reinsurance and, later, general and life insurance.8 The Allianz Jio reinsurance venture began writing business, and its first full quarter brought about ₹266 crore of premiums.6 The general-insurance JV was still awaiting regulatory approval at the time of the June 2026 results.6
What a partner actually brings
In finance, joint ventures with global names do two things. They import product, risk management and compliance knowledge that would take a decade to build. And they reassure regulators and customers that a newcomer will behave. Indian asset management has precedent: HDFC AMC was built in partnership with Standard Life, and the Nippon brand in Indian mutual funds came from a Japanese partner buying into Reliance Capital's fund business.
One argument that circulated at the time held that BlackRock's presence would limit the promoter group's influence over the asset-management business. That is a claim about governance inside a private JV, and nothing in the public record allows it to be tested. Fifty-fifty ventures usually give each partner veto rights; what that means in practice will only show up if the partners disagree.
Size them honestly
The JVs are small. Asset-management fees, even if JioBlackRock gathers assets quickly, accrue to a JV that JFSL owns half of, and are accounted as a share of JV profit rather than consolidated revenue.1 Reinsurance premiums are revenue, but reinsurance is a low-margin, capital-hungry business whose profits depend on claims that take years to emerge. Regulatory approvals and launch dates are milestones, not revenue.
The investment terms matter for judging whether JFSL paid a sensible price. Each partner committed initial capital to the asset-management JV at launch.[^9] Listed Indian asset managers such as HDFC AMC trade at high multiples of earnings because the business is capital-light once scaled, which is part of why a new entrant's licence and brand can be worth a great deal. Whether that value ever reaches JFSL's shareholders depends on assets gathered, not on the partner's name.
The verdict: optionality, not yet material. The forward measures are JioBlackRock's assets under management and the Allianz ventures' premiums and combined ratios once the general-insurance JV is live.
The partners from outside the group are only half of the counterparties that matter. The other half carry the Reliance name.
VIII. How Much Is the Reliance Group?
In May 2024, JFSL sent its shareholders a postal ballot.7 Among the resolutions was approval for related-party transactions in which its leasing arm would buy equipment from Reliance Retail and lease it to customers of Reliance Jio Infocomm.7 The authorisation ran to as much as ₹36,000 crore over FY25 and FY26.7 Voting closed in June 2024.7
Read that structure slowly. A Reliance company sells the equipment. A JFSL company buys it with borrowed money. A Reliance company's customers use it. The group sits on both sides of the transaction, and JFSL's balance sheet sits in the middle.
What device-as-a-service is
The business is simple to explain. Instead of a Jio customer buying an internet router or set-top box, Jio Leasing owns it and charges a rental. For the telecom business, that removes the hardware from its own balance sheet and makes service cheaper to start. For JFSL, it creates a stream of lease income backed by thousands of small devices.
Whether that is an independent financing business or a funding arm for the group depends on the price. If the lease rate is set at market terms and the residual risk is properly priced, JFSL earns a fair return for providing capital. If the lease rate is set low to help the telecom arm, JFSL's minority shareholders subsidise the parent. The ballot authorised the transactions as being at arm's length and in the ordinary course of business; independent shareholders cannot check the pricing from public disclosures.7
The governance test
Indian rules require that related parties abstain from voting on material related-party transactions, so the outcome depends on the non-promoter shareholders.5 The resolution passed.7 That is the minimum bar, not evidence of a good deal. Institutional investors in India often approve group transactions because voting against a controlling family has little upside.
The scale is the point. Against an operating business whose lending book was around ₹10,000 crore in early 2025, an authorisation of up to ₹36,000 crore for one group transaction is enormous.37 Even partially used, it could make leasing to Jio customers a substantial share of JFSL's balance-sheet growth. Add the brand, which JFSL uses under licence from the group, and the dividend from the Reliance stake, and the group is present in JFSL's revenue, its funding, its assets and its customer base.
The answer, with a caveat
So how much of the growth depends on Reliance? On profit, a great deal: in the latest quarter, the dividend from Reliance shares was about equal to all operating profit before provisions.1 On the balance sheet, the Reliance stake is most of the assets.[^5] On the operating business, the related-party share of revenue is reported in the annual report's related-party note, while the 52%-plus figure that circulates on aggregator sites conflates transaction volumes with revenue and should not be treated as a revenue share.
The fair conclusion is that the group is not a side influence on JFSL. It is the foundation. The lending book to outside borrowers and the JVs with BlackRock and Allianz are where independence could emerge, and they are the smaller part.
A group this present also chooses who runs the company.
IX. The People Running It
JFSL's chairman is K.V. Kamath, the banker who turned ICICI from a development-finance institution into India's largest private bank and later ran the BRICS New Development Bank.[^5] His appointment signalled that the group wanted a financial company built by bankers, not by telecom engineers. Hitesh Sethia, the managing director and chief executive, spent most of his career at ICICI Bank, including running its operations abroad, before joining JFSL.[^5] Isha Ambani, Mukesh Ambani's daughter, sits on the board as a non-executive director, which ties the company to the next generation of the family.[^5]
It is a credible line-up on paper. A team of ICICI-trained bankers is exactly what CRISIL had in mind when it cited an experienced management team among Jio Credit's strengths.3
The record, short as it is
Three years is a short record. Even so, a few things can be tested.
On volume, management has delivered: the book grew from about ₹10,000 crore to about ₹30,700 crore in fifteen months, and quarterly disbursements nearly tripled.63 Whatever the company signalled about building scale, it built it.
On profitability, the record is weaker. Net profit fell in FY26 even as revenue grew 73%.[^5] Sethia has argued that the company's own technology stack will let it serve customers at lower cost than incumbents. That claim sits awkwardly next to expenses growing about 291% in a year.1 It may yet prove right as volumes catch up, but the evidence so far runs the other way.
On joint ventures, timelines have been long. The BlackRock venture announced in 2023 needed regulatory approvals before it could sell products, and the Allianz general-insurance JV was still waiting at mid-2026.6[^9]
Capital allocation
JFSL has made no acquisitions to benchmark. Its capital allocation record consists of three things: entering joint ventures rather than building alone, buying out SBI's stake in the payments bank, and borrowing to grow the lending book while keeping the Reliance stake. The first is sensible. The second added control over a business with poor economics. The third is the big call: holding a large block of a single listed stock earning a low single-digit dividend yield, instead of monetising some of it to fund the lender.
Management has framed its culture around what it calls the "4Rs": reputation, regulatory adherence, return of capital and return on capital.[^5] The first two are visible in the clean regulatory record and the AAA rating. On the fourth, the 1.5% ROE speaks for itself.[^5] On the third, a dividend of fifty paise a share is a start, paid largely out of Reliance's own dividend.[^5]
Pay, board turnover and AGM voting dissent are set out in the annual report's governance section. On the earnings calls, analysts have pushed repeatedly on the same points: when costs stop outrunning revenue, how credit costs will behave, and what the company intends to do with the Reliance stake. Answers on the first two have tended toward long-term framing rather than numbers.
The verdict: a credible team with a short record that has hit volume and missed operating leverage. The test of capital discipline is whether ROE excluding the stake rises in FY27.
Credible people are necessary. Whether they have a durable edge to work with is a separate question.
X. Frameworks: Moat, Forces and Powers
Picture a small manufacturer in Pune who needs ₹2 crore against his factory. He can call his HDFC Bank relationship manager, who has known his account for a decade. He can call a Bajaj Finance agent. Or he can try Jio Credit, which may offer a slightly lower rate because its funding is cheaper. What makes him pick Jio, and what makes him stay?
That is the moat question in one scene, and it should be argued once, here.
Porter's five forces
Rivalry is intense. Indian lending has dozens of large banks and NBFCs, many with decades of customer data and branch networks. Loans are a commodity; a borrower with good credit will move for a small rate difference.
Threat of entrants varies by business. In payments, barriers are low and margins thin, as the ₹24 crore net take on ₹176 crore of gross fees shows.6 In banking licences and insurance, barriers are high, which is precisely why JFSL needed partners for insurance and asset management.
Buyer power is high in corporate lending. Big corporate borrowers negotiate hard and can tap bonds or banks instead. With 46% of the book in corporate loans and the top 20 borrowers at almost 30%, Jio Credit sells much of its product to customers with considerable bargaining power.3
Supplier power here means the providers of money: banks, bondholders and commercial-paper buyers. The AAA rating weakens their power over JFSL, which is the strongest point in its favour.3
Substitutes abound: bank loans, bond markets, gold loans, informal credit.
Regulation sits above all of it. The RBI's scale-based rules for NBFCs tighten capital and governance requirements as lenders grow, so the bigger Jio Credit gets, the more it is regulated like a bank.5
Helmer's seven powers
Scale economies: not yet. JFSL is small, and its costs have grown faster than revenue.1
Network effects: none in lending. Payments have weak network effects, but UPI is interoperable, so they belong to the system rather than to any app.
Counter-positioning: the claim is that a digital, low-cost lender can undercut branch banks. Every Indian fintech has made the same claim, and incumbents like HDFC Bank and Bajaj Finance have built strong digital channels of their own. Not evidenced.
Switching costs: low. A borrower can refinance elsewhere.
Branding: the Jio name is recognisable and trusted for connectivity. Whether trust in a telecom brand transfers to lending is unproven, and in lending, brand matters less than price.
Cornered resource: this is the one that holds. The combination of the Reliance stake, the group's credit standing and the AAA rating gives JFSL access to cheap money that a standalone newcomer cannot match.3 It is real, and it is borrowed from the parent.
Process power: too early. Underwriting process power is proved only through a credit cycle.
Risk radar
Only a handful of risks touch the economics. The credit cycle is the first, given a young, concentrated book. Interest rates are the second: falling rates helped volume, and a reversal would raise funding costs faster than a fixed-rate property book can reprice. Regulation is the third, both NBFC capital rules and any tightening of related-party scrutiny. Data privacy is the fourth; a business built on telecom-user data operates under India's new data-protection law and sits at the boundary of what group companies may share.
The verdict: one evidenced power, cheap funding, which comes from the group. Distribution, brand and data are asserted and not yet visible in spreads, take rates or loan mix.
Which leaves the question every investor has to answer for themselves.
XI. Bull vs. Bear
Imagine two analysts looking at JFSL on 6 October 2026, the day it closed at its 52-week low, about a third below its high.[^5]
The first builds a sum of the parts. She takes the Reliance stake at market value, adds the lending book at roughly its book value, and assigns small values to the payments bank, leasing and the JVs. Because the stake is most of the value and the market price is close to book, she concludes the market is paying little or nothing for the operating businesses. If Jio Credit becomes a normal NBFC earning a normal return, she argues, the optionality is close to free.
The second looks at earnings. He sees a company trading at 84 times trailing profit, against its own five-year median of about 118 times.[^5] He sees EV-to-sales of about 29 times and an earnings yield of about 1.2%.[^5] Strip out the Reliance dividend and the operating business barely broke even before provisions last quarter.1 To him, the stake is not free optionality; it is a share portfolio that a JFSL investor could own directly, with a holding-company discount, a related-party overlay and an unseasoned lender attached.
Both are describing the same facts.
What the bull needs
For the bull case to work, three things must happen. Credit costs must stay low as the 2025–26 vintages season. Costs must start growing more slowly than revenue, so that ROE excluding the stake rises toward the teens. And the Jio distribution thesis must finally show up as cheap retail customer acquisition, so that JFSL's lending mix moves from corporate and property loans toward higher-yielding retail products sold through its app.
What the bear needs
For the bear case, only one thing has to go wrong: credit costs. A concentrated corporate book can turn on a few names, and a single large default in a book where the top 20 borrowers are 30% would wipe out quarters of thin operating profit.3 A second path is slower: costs keep running ahead, ROE stays near 1–2%, and the stock drifts as a discounted Reliance tracker.
The activist's question
A skeptical shareholder would ask why public investors should hold a sub-2% ROE company whose biggest asset is a stake in its own promoter. The obvious answer would be to monetise part of the stake to fund the lender and lift returns. The obvious reason that does not happen is that the stake underpins the rating and the family's control structure. Public shareholders, in effect, pay for the promoter relationship through low returns on capital.
The FCF yield of about −7.5% should not be read as a warning; for a lender, negative free cash flow means loans are being made.[^5]
Three KPIs that matter
Investors can ignore most of the dashboard and watch three numbers.
First, Jio Credit's gross NPA and stage-3 ratio. CRISIL reported nil delinquencies at March 2025.3 Direction from here is the single most important signal.
Second, ROE excluding the Reliance stake and its dividend. In the June 2026 quarter, operating profit before provisions excluding dividends was close to zero.1 It needs to rise.
Third, the related-party share of revenue and assets, especially leasing to Jio customers. The larger it becomes, the more JFSL is a group financing arm rather than an independent lender.
The verdict: the price can be called cheap only if the stake is the anchor and the lender is an option; it can be called expensive only if one values earnings. The market is pricing a holding company with a lottery ticket.
XII. Playbook: Lessons
"A stake in your parent isn't a business." In June 2026, JFSL's dividend from Reliance shares roughly equalled its entire pre-provision operating profit. A balance sheet full of a parent's shares can make a company look large, safe and cheap on book value, while hiding that the operating engine is still idling. For investors in any group demerger, the first job is to subtract what the parent handed over and look at what is left.
"Growth is not underwriting." Jio Credit tripled its loan book in about a year with zero delinquencies, and the rating agency itself called asset quality untested. In lending, the fastest growth comes from saying yes, and the bill comes later. The lesson for founders building lenders is uncomfortable: the quarters that look best are the ones whose loans have not yet had time to go bad.
"A group brand is both a moat and a leash." The Reliance name gives JFSL an AAA rating and cheap money. The same name brought a ₹36,000 crore authorisation to finance the group's own customers, with the group on both sides of the deal. The thing that lowers a group company's cost of capital is the same thing that decides where its capital goes.
"Reach is not revenue." Mukesh Ambani's telecom playbook was to spend heavily, price low and win scale, then monetise a captive market. It worked in telecom because Jio could eventually raise tariffs. In payments, the regulator sets the price at zero. Hundreds of millions of telecom customers turned into 9 million monthly app users and a ₹24 crore net take on payments in a quarter. Scale-first works only where someone will eventually let you charge.
XIII. Epilogue: The Next Decisive Moments
Tonight JFSL sits at its 52-week low, with a lending book of about ₹30,000 crore, a payments bank fully under its control, two global partners and a block of Reliance shares worth most of the company. The next twelve months will answer more of the four questions than the previous three years did.
The first moment is the September 2026 quarter's results. Last year's September quarter held the Reliance dividend; this year's will not, because the dividend landed in June. A weak headline profit comparison is therefore all but baked in. What matters inside it is whether operating profit excluding dividends turned positive and whether cost growth finally fell below revenue growth. If it did, the fourth question starts to tilt toward recovery. If not, the 2023 margin was not the only thing lost.
The second is the asset-quality disclosure as the 2025 vintage turns a year old. A gross NPA ratio that stays near zero through FY27 would be the first real evidence for the underwriting claim. A rise driven by a few large corporate names would confirm the concentration risk and test how much the AAA really depends on the parent.
The third is the insurance and asset-management calendar: approval of the Allianz general-insurance venture and JioBlackRock's first meaningful asset disclosures. Neither will move earnings soon. Both will show whether the partners are building businesses or holding licences.
The fourth is the next rating review for Jio Credit. A reaffirmed AAA with a larger, older book would say that the funding edge is holding. Any change in outlook would say the parent's backing is no longer enough on its own.
Behind all four sits the question nobody at JFSL has answered: what is the Reliance stake for? Kept forever, it guarantees a low ROE. Sold, it undermines the rating and the family's control. Until that is settled, JFSL remains two companies sharing one share price.
XIV. Outro
On a July morning in 2023, the market paid ₹261.85 for a promise: that the group which had turned India's phones and shops into national utilities would do the same with money. Three years later, the price is about ₹212, and the promise is still mostly a promise. The loans are real, the partners are real and the app is real, but what the market actually values is the slice of Reliance tucked inside the company.
JFSL is that rarest of things: a company whose largest asset is a piece of its own parent, priced as a portfolio while it tries to prove it can be a bank. If the lender grows up, the stake will one day look like scaffolding. If it does not, the scaffolding was the building all along.
XV. Recent News
The most recent reported quarter, to June 2026, brought a profit jump driven largely by dividend income, alongside a near-tripling of loan disbursements.16
XVI. Links & Resources
Primary filings, results and announcements are available through the company's investor-relations page and the NSE and BSE filing pages listed below.[^5]29
References
-
Jio Financial Services (JFSL) Q1 FY27 Results Update — IIFL, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JIOFIN corporate announcements, price and shareholding — NSE ↩↩↩↩↩↩
-
Jio Credit Limited Rating Rationale — CRISIL, 2025-07-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
What's left of Jio Financial when you strip away Reliance? — The Ken ↩↩↩↩
-
RBI press releases: NBFC, payments bank and scale-based regulation — RBI ↩↩↩↩↩↩
-
Jio Financial Q1: NBFC arm sees 173% rise in loan disbursements — Medianama, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Postal ballot notice: related-party and leasing approvals — NSE, 2024-05-23 ↩↩↩↩↩↩↩
-
Allianz Group press releases: Jio reinsurance and insurance JV — Allianz ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube