Hindustan Petroleum: The Fuel Seller That Can’t Always Set the Price
I. The Quarter the Pump Price Couldn’t Save
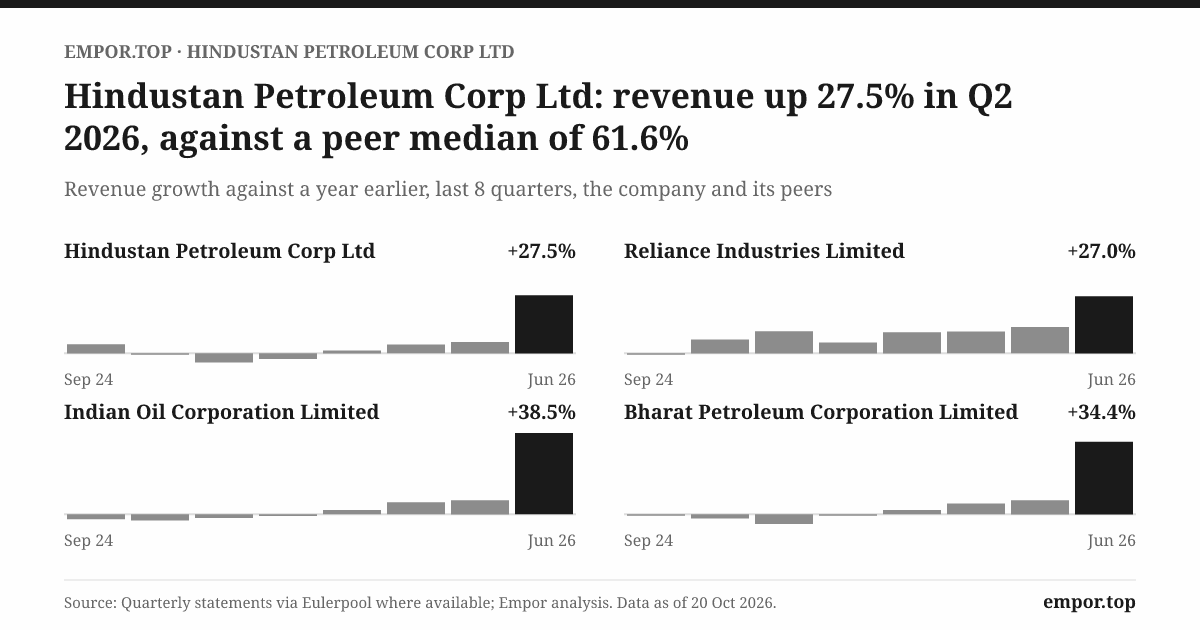
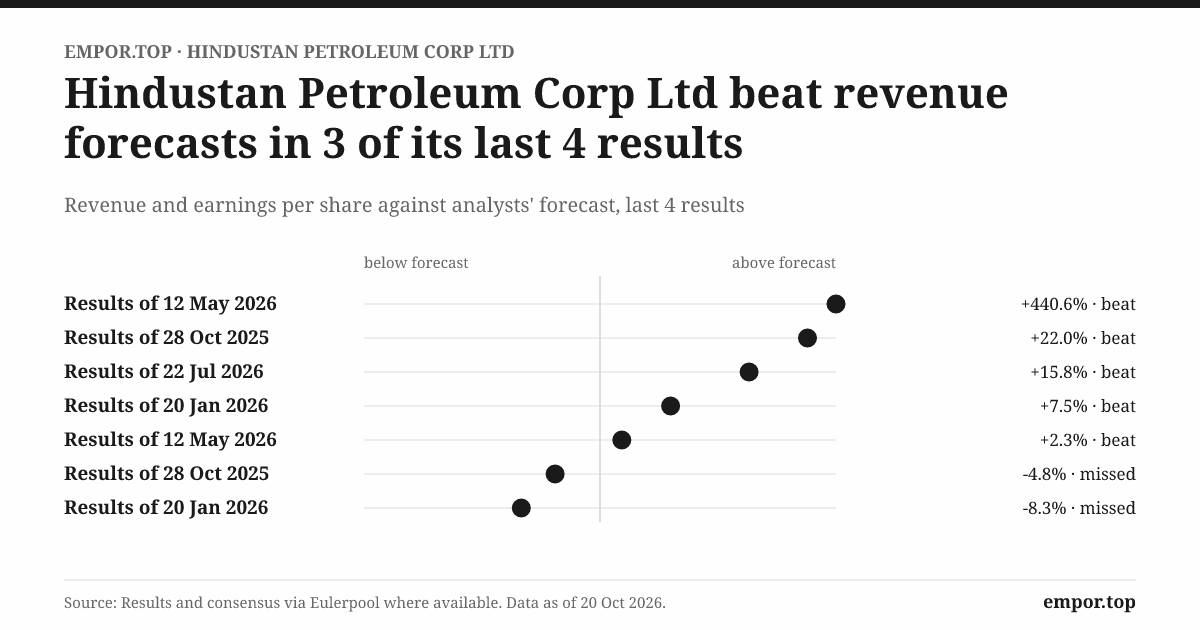
On the evening of July 22, 2026, the board of Hindustan Petroleum Corporation approved a set of quarterly numbers that looked like two different companies stapled together.1 The first company was having a remarkable spring. Its refineries had run at more than their nameplate capacity, its gross refining margin had leapt to $23.80 a barrel from barely $3 a year earlier, and its sales of products had risen by about a fifth to roughly ₹1.45 lakh crore.1 Indian drivers, truckers and households had bought fuel at a pace that sometimes stretched the supply chain to its limit; on some days, the chairman later said, HPCL had to push 40% more product into the market than usual.2
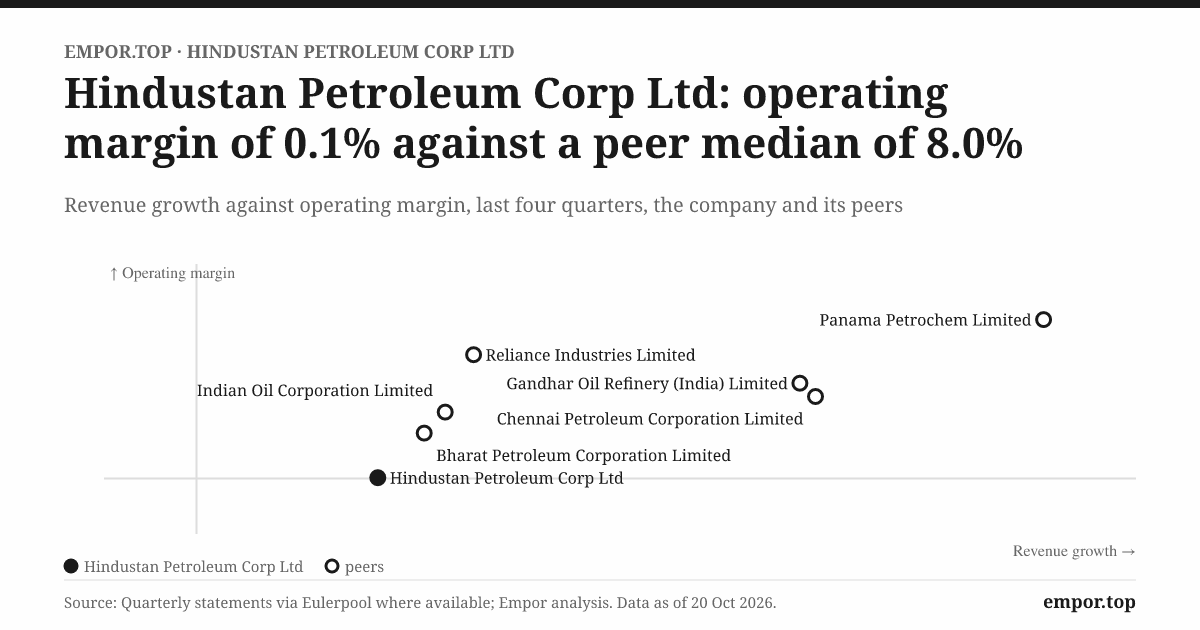
The second company was bleeding. For the three months to June 2026, HPCL posted a standalone pre-tax loss of about ₹17,400 crore and, after a deferred-tax credit cushioned the blow, a net loss of ₹11,526 crore.1 At the consolidated level, the group lost ₹12,265 crore, roughly $1.3 billion, on an operating loss of about $1.9 billion.13 A year earlier the same quarter had produced a profit of more than ₹4,000 crore.1 The board declared no dividend.1
How does a company sell more of the most essential product in the economy, at a time when its refining margins are the best in years, and still lose more money in one quarter than it earned in all of some recent years? The answer sits at the pump. In late February 2026, the conflict between the United States and Iran escalated, shipping through the Strait of Hormuz was disrupted, and Brent crude went above $100 a barrel.42
India's pump prices barely moved. They had been largely frozen since April 2022, and the first increase in more than four years, ₹3 a litre, came only on May 15, 2026, some sixteen days after assembly elections in four states had ended.54 Even after two further small hikes took the rise to nearly ₹5 a litre, oil marketing companies were still losing an estimated ₹8 to ₹10 on every litre of petrol and diesel they sold.4
On the earnings call the next morning, Chairman and Managing Director Vikas Kaushal put a number on the hole. HPCL's marketing under-recovery for the quarter, the gap between what fuel cost and what the pump price allowed, was "upwards of INR26,000 crores," about ₹20,000 crore of it on petrol and diesel and the rest on cooking gas.2 "Every liter which you and I were buying from petrol pump was being subsidized by one of the three OMCs," he said.2
Kaushal also described a quarter in which the usual rules of the industry were suspended. Refiners ran crudes they would never normally choose, simply because the usual ones were stuck on the far side of the Gulf; public and private companies lent each other storage and product; and HPCL drew crude from the country's strategic petroleum reserve at market prices.2 Inventory made it worse: HPCL had deliberately stocked extra crude in a frightening market, then watched prices fall about $25 in a matter of weeks before the quarter closed, forcing a write-down.2
That is the puzzle this story sets out to solve. HPCL is a fuel seller with growing volumes, two coastal refineries, a national retail network and a brand-new refinery in the Rajasthan desert. Yet a single quarter of crude shock, combined with pump prices that politics would not let rise, wiped out roughly a fifth of its standalone net worth and pushed its debt-to-equity ratio from 0.8 to about 1.5 in three months.1 The question is whether HPCL can earn reliably from selling essential fuel when the price at the pump is, in practice, not entirely its own to set.
Three threads run through the answer. The first is pricing: whether HPCL's profits are a business or a residue, the margin left over after the government has decided what consumers should pay. The second is Barmer, the 9 million-tonne refinery and petrochemical complex HPCL controls with the state of Rajasthan, whose approved cost has risen to ₹79,459 crore.6
Barmer could close a long-standing gap between what HPCL sells and what it refines, or it could become a costly obligation that absorbs the cash for years. The third is competition: what advantage, if any, HPCL can defend against Indian Oil's larger scale, Reliance's world-class refining complex and Bharat Petroleum's similar public-sector franchise.
One boundary needs to be drawn before going further. Since 2018, HPCL has been a subsidiary of Oil and Natural Gas Corporation, which owns about 55% of it.7 ONGC pumps crude oil and gas out of the ground, and when crude prices spike its upstream earnings tend to rise. None of that money belongs to HPCL's minority shareholders. HPCL's accounts consolidate its own subsidiaries and joint ventures, not ONGC, so the group's scale cannot be borrowed to flatter the listed refiner.7 When this story talks about HPCL's cash, margins and returns, it means HPCL's alone.
To understand why a listed company with five lakh shareholders can be told, in effect, to sell below cost, it helps to go back to the day the state took it over.
 Subscribe on LinkedIn
II. Foreign Oil Becomes a State Utility
The popular version of HPCL's history begins in 1911, and the company itself likes to say it has operated in India "for 100+ years."8 That date is real, but it belongs to someone else. In 1911, the Standard Oil Company began marketing petroleum in India, selling kerosene to light homes across a colony that had little refining of its own.8
HPCL as a corporation did not exist for another sixty-three years. What it inherited was not a founder's vision but the physical bones of American oil companies: terminals, depots, a refinery on the edge of Mumbai, and the habit of selling fuel to a vast country one tin and one pump at a time.
The postwar decades built those bones. In 1952, Standard Vacuum Refining Company of India, known as Stanvac, was incorporated to build a refinery in Bombay, and in 1955 Caltex Oil Refining (India) was incorporated to do the same on the east coast at Visakhapatnam.8 Stanvac changed its name to Esso Standard Refining Company of India in 1962, and in 1969 a joint venture called Lube India commissioned a lubricant refinery in Mumbai.8 These were efficient, foreign-owned businesses operating in a country whose leaders increasingly regarded oil as too strategic to leave to foreigners.
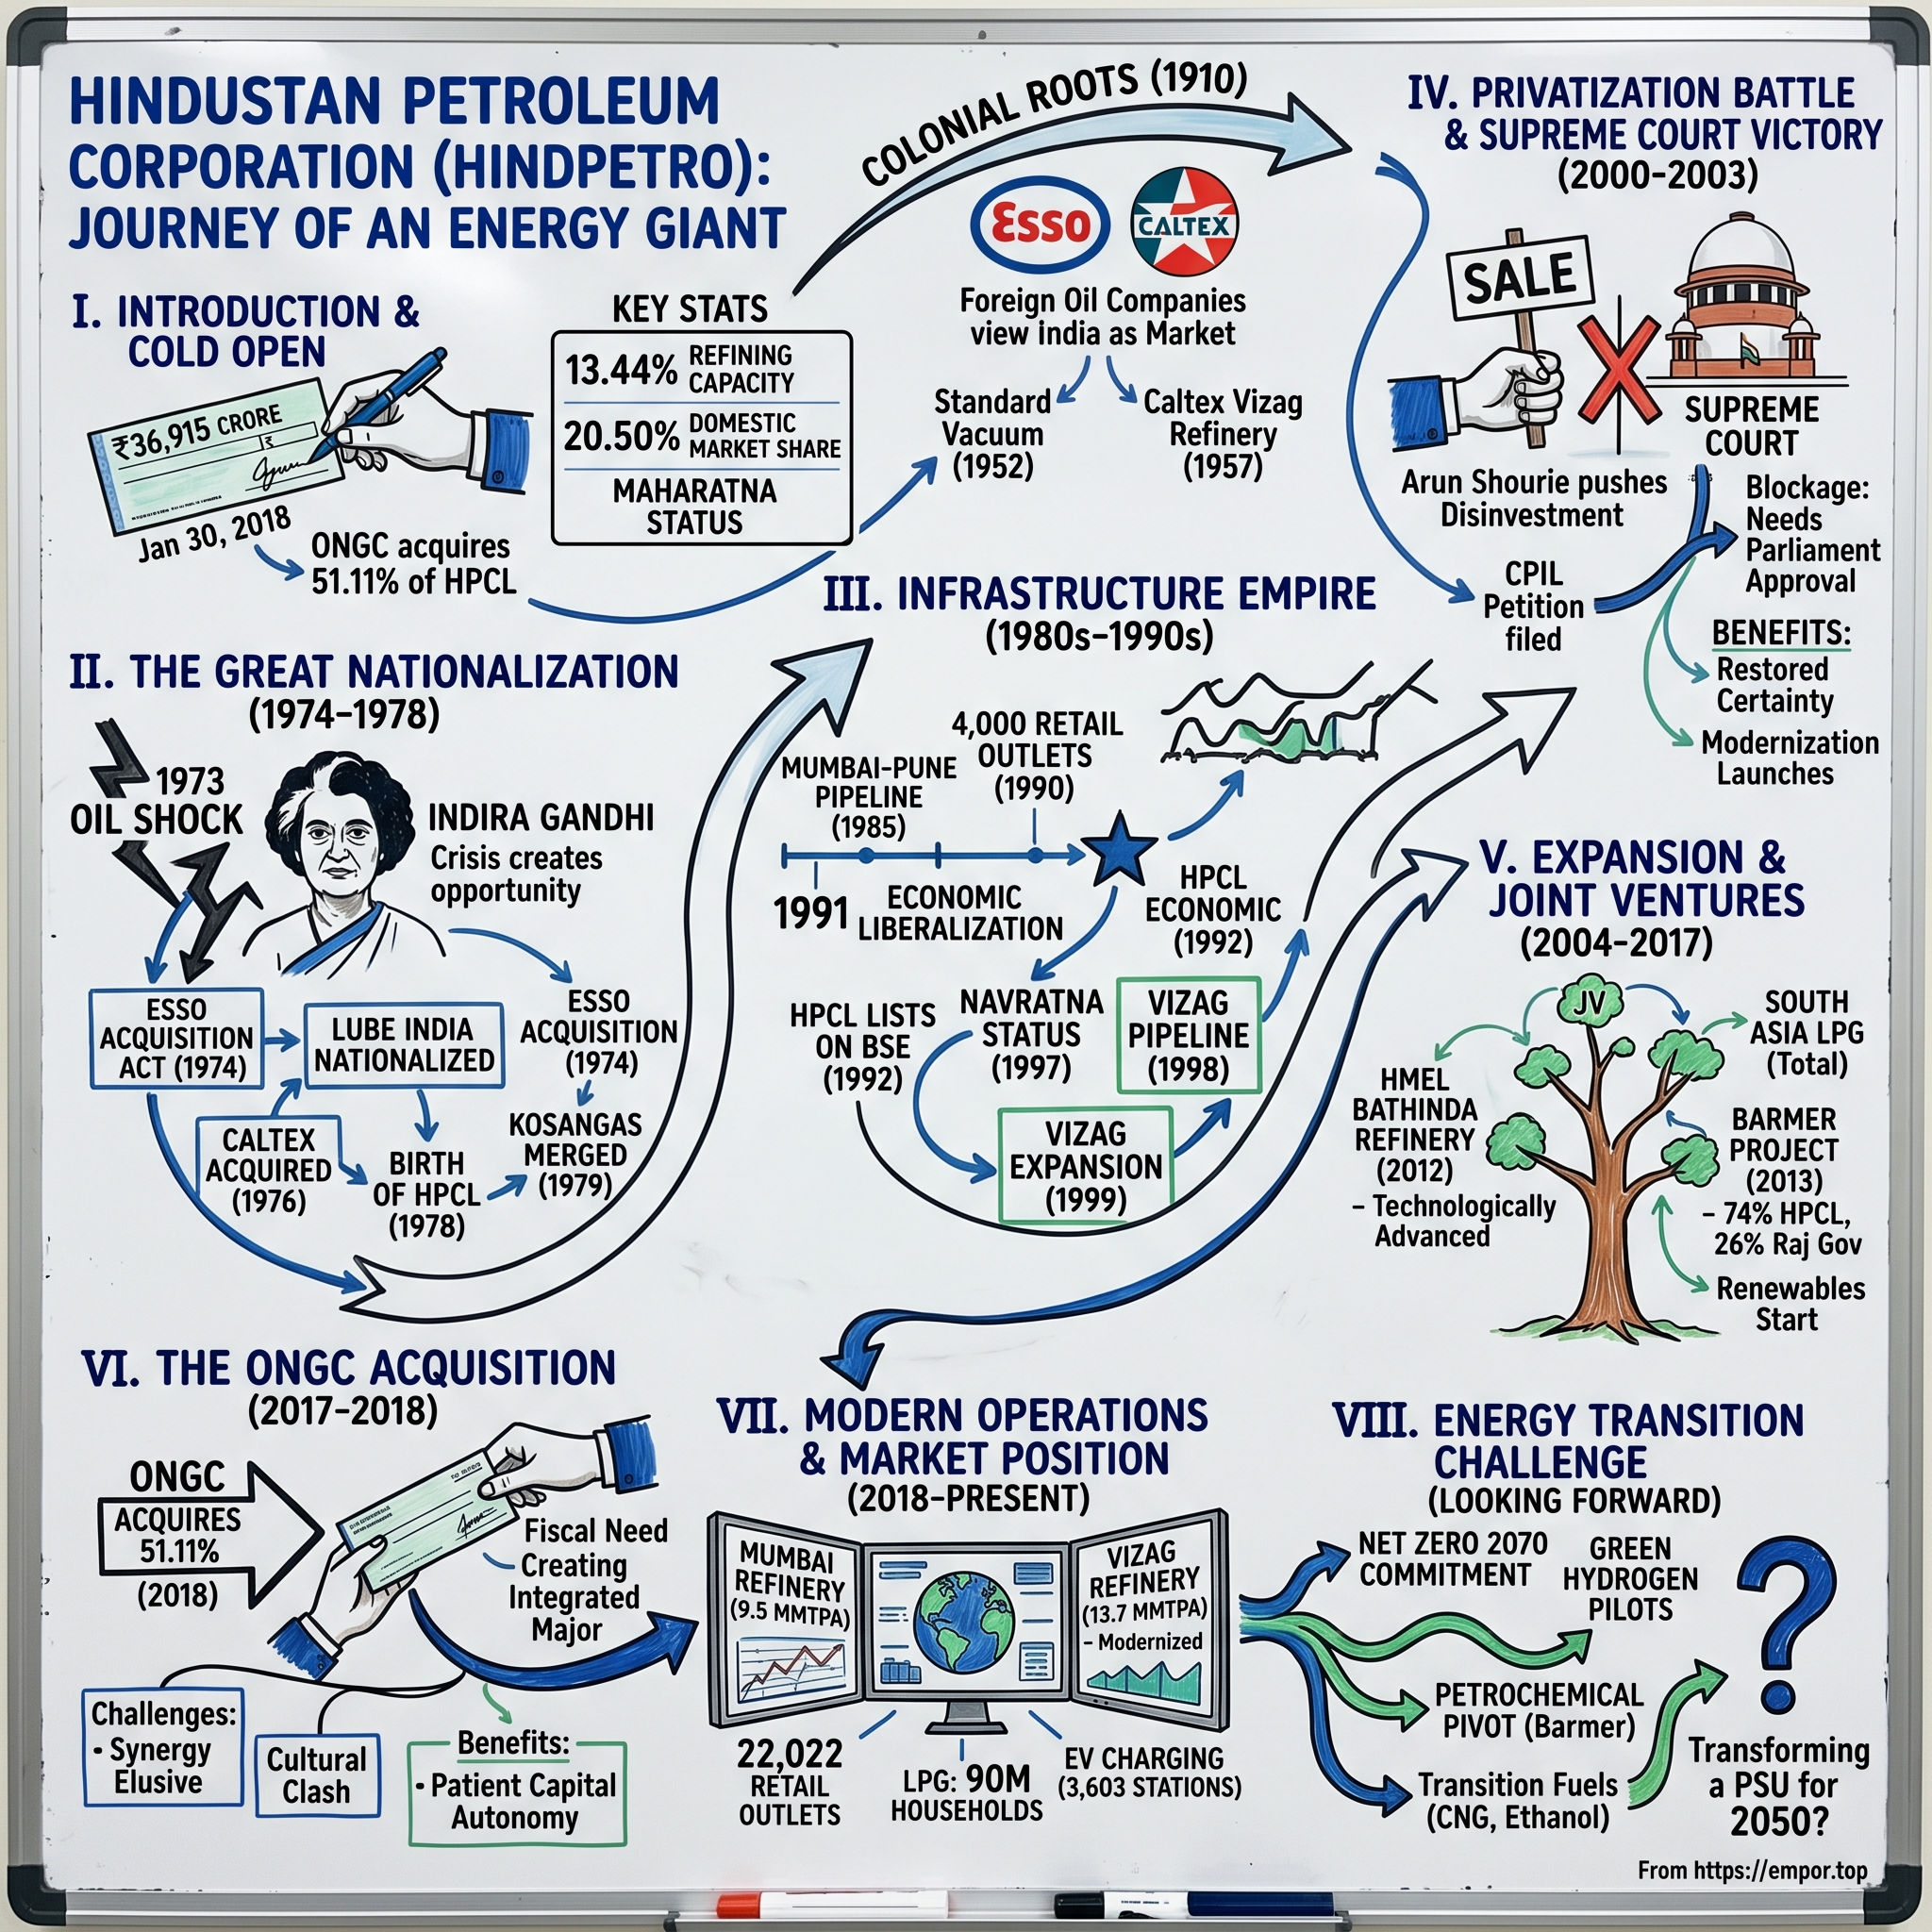
The break came in 1974. Parliament passed the ESSO (Acquisition of Undertakings in India) Act, which transferred Esso's Indian undertakings to the state, and the government formed Hindustan Petroleum Corporation by amalgamating Esso and Lube India.98 In 1978, the Indian undertaking of Caltex was merged into HPCL as well, bringing with it the Visakh refinery that today is the company's largest.8 Within four years, the government had stitched two foreign oil businesses into one public company with refineries on both coasts.
What did nationalization change? Above all, it changed the purpose of the business. A foreign oil company sells fuel to make a return for its shareholders. A government company in the India of the 1970s sold fuel to keep the economy moving at prices the state chose, under an administered pricing system in which cost-plus formulas and government pools did the arithmetic. HPCL's job was to refine and distribute; the government's job was to decide what everything cost. That bargain explains much of what followed for the next fifty years.
What it left in place was the operating machine. The refineries, the marketing habits and the retail network were inherited, not built from nothing. HPCL's identity dates from 1974; its assets date from the era of Standard Oil and Caltex. The company that resulted was a hybrid from birth: a commercial refiner by trade and an instrument of energy policy by ownership.
Over the following decades that hybrid became more commercial without becoming fully commercial. HPCL earned Navratna status in 1997, a designation that gave its board more financial autonomy.8 Around the turn of the century, the government decided it wanted to sell its controlling stakes in HPCL and its sister company Bharat Petroleum. The plan ran into the Supreme Court. On September 16, 2003, a bench of Justices S. Rajendra Babu and G.P. Mathur ruled in Centre for Public Interest Litigation v. Union of India that the government could not disinvest HPCL and BPCL by executive action so that they ceased to be government companies.9 The acquisition laws had vested these undertakings in the state, and the court held that changing that required Parliament to repeal or amend those laws.9 The court was careful to say it was not judging the policy of disinvestment, only the method.9 But the practical effect was to lock HPCL into public ownership unless lawmakers chose to act, and none did.
That ruling explains the shape of HPCL's life ever since. When the government eventually wanted to monetize its stake, it sold not to the market but to another state company, ONGC, which kept HPCL a government company in law. Oil prices had been controlled by executive orders rather than by statute, and they were later freed the same way, which meant they could be quietly reined in again without a vote in Parliament.9
HPCL competes with private refiners, raises money from global bond markets and has public shareholders who expect dividends. It also answers, through its parent and its ministry, to a government that cares about inflation, elections and cooking gas for the poor.
The unresolved inheritance of 1974 is therefore not a matter of history. It is the central fact of the investment case. HPCL runs like a private company most of the time, and like a public utility when it matters most. The cleanest way to see the cost of that dual nature is to look at what happens to its profits when crude oil moves.
III. The Pump Price Is Deregulated. The Politics Aren’t.
Officially, India freed the pump price years ago. Petrol prices were deregulated in June 2010 and diesel in October 2014, which meant that in principle the oil marketers could move retail prices in step with international product prices.7 Walk into an HPCL outlet in Mumbai, Delhi or Chennai, though, and the number on the board for most of the last four years told a different story. Apart from a ₹2-a-litre cut in March 2024, it barely changed from April 2022 until May 2026.4 Over the same period, crude went up, down and up again. The price was deregulated. The politics were not.
To see why that matters so much, it helps to understand that HPCL makes money in two different places, measured in two different units.
The first profit pool is refining. A refinery buys crude oil by the barrel, priced in dollars, and splits it into petrol, diesel, jet fuel, LPG and heavier products, which it sells at prices linked to regional benchmarks in Singapore. The difference between the value of everything that comes out and the cost of the crude that went in is the gross refining margin, quoted in dollars per barrel.
Think of it as a bakery's margin between the flour it buys and the bread it sells. When product cracks, the spread between a product price and crude, are wide, a refinery prints money; when they are narrow, it scrapes by. For HPCL, these margins have often been modest: the company's own "core" refining margin, stripped of inventory effects, was about $6.54 a barrel in the June 2025 quarter.10
The second profit pool is marketing. HPCL buys refined products, whether from its own refineries, a joint venture or a competitor, at those international-parity prices, then sells them to customers at the pump or the LPG counter at a retail price. The marketing margin, measured in rupees per litre or per cylinder, is what remains after taxes, freight and dealer commissions. In a truly free market, the marketer would raise prices when costs rose and keep a steady margin. In India, the pump price is the most politically visible number in the economy, and when crude spikes, the marketing margin is what gets squeezed first.
These two pools are linked, which is why HPCL's annual profits swing so violently. Domestic sales made up more than 97% of revenue in FY2025, about ₹4.54 lakh crore against roughly ₹10,800 crore of exports, and the company reports a single downstream petroleum segment.7 Natural gas, renewables, biofuels and the new LPG brands are real but small strategic lines; they are not separate engines that can carry the company when fuel economics turn. HPCL is, overwhelmingly, a business of buying crude and products at global prices and selling fuel at Indian prices.
The year the freeze bit, and the year it paid
FY2023 was the stress test. After Russia invaded Ukraine in February 2022, crude and diesel prices surged, and India's retail prices stayed frozen for months. HPCL's marketing economics turned steeply negative, and the company reported a standalone net loss of ₹8,974 crore for the year.11 Debt piled up as the company borrowed to buy crude it then sold at a loss; by Kaushal's later account, debt-to-equity reached 2.33 at the worst point of that crisis.2
Then the cycle reversed, and FY2024 showed the other face of the same mechanism. Crude eased, but pump prices did not fall to match. The marketing margin that had been negative became unusually fat, and HPCL earned a record standalone profit of ₹14,694 crore.11 The rebound was so strong that a proposed rights issue to fund green investments was dropped.7 FY2026 was better still, with standalone profit of ₹17,175 crore.2 Taken together, the three of them, IOC, BPCL and HPCL, earned about ₹77,281 crore in FY2026, more than double the year before.4
What do those two years prove? Not that HPCL has pricing power. They prove that HPCL's earnings are what is left over after the government decides how fast the pump price should follow crude in each direction. When crude rises and prices are frozen, HPCL loses. When crude falls and prices stay sticky, HPCL wins back some of what it lost.
The record profits of FY2024 and FY2026 were not evidence of a moat. They were, in large part, the policy cycle paying back what it had borrowed in FY2023. The point matters, because an investor who capitalizes the good years at a normal multiple is assuming the pay-back always arrives on time and in full. There is no contract that says it must.
It would be unfair to say the state left the oil marketers entirely alone in 2026. On March 27, it cut the special additional excise duty on petrol and diesel by ₹10 a litre, giving up revenue so that the companies could absorb more of the crude shock without raising pump prices.4
It also imposed levies on exports of diesel and jet fuel, which kept more product at home but clipped refiners' export earnings.1 Even so, officials said the burden absorbed at the peak reached as much as ₹24 a litre on petrol and ₹30 on diesel.4 The government shared the pain. It did not share it equally, and it decided the split.
Seen through that lens, the June 2026 quarter was FY2023 compressed into three months and sharpened. Management's explanation on the July 23 call broke into four parts. The first was the marketing under-recovery of more than ₹26,000 crore for the quarter, mostly on petrol and diesel.2 The second was LPG: the domestic cylinder lost about ₹510 for the quarter as a whole, ₹680 in June and ₹490 in July.2 The third was inventory: HPCL deliberately carried more crude than usual into June 30 because supplies were uncertain, and then prices fell about $25 within weeks.2
When an analyst asked for the size of the inventory hit, Kaushal declined to give a figure but offered a clue: without it, he said, "the loss number would have been on the other side of five-digit number by a good margin."2 The fourth was crude sourcing itself. Most of HPCL's term contracts were with Saudi, Iraqi and Emirati suppliers whose cargoes were trapped behind the Strait of Hormuz, so its refineries had to run whatever crude they could get rather than the crudes they were designed for.2
Against those losses sat a refining margin that looked spectacular on paper. That $23.80 a barrel was reported before the special additional excise duty and cess the government had imposed on certain fuel exports, and the company did not disclose what it was after the levy.14 Kaushal also warned that the headline figure reflected timing as much as skill: some days, Visakh posted margins above $30 because of the price at which a particular crude parcel had been bought, and the next day the number could look very different.2 Even so, the Visakh refinery, reported as a branch, lost ₹2,636 crore in the quarter after inventory losses.1
There is a revealing detail in how the losses were split. Analysts on the call pointed out that Bharat Petroleum, reporting the same week, showed much stronger refining margins. Kaushal declined to compare, saying he had called BPCL's chairman to congratulate him, and pointing to structural differences: BPCL refines more, and HPCL's Mumbai refinery lacks a delayed coker that lets competitors squeeze more value from heavy crude.2
The answer was reasonable, but it also conceded the point. On a structural basis, HPCL is the smallest refiner of the three state oil marketers, and it buys more of what it sells, so when marketing turns negative it is the most exposed.
The cooking-gas ledger
Underneath the pump-price story sits a quieter account that tells investors even more about who really sets the economics. Domestic LPG, the cylinder of cooking gas in almost every Indian kitchen, is priced by the government well below what HPCL pays for it on world markets. The shortfall is not booked as revenue. At March 31, 2025, HPCL had accumulated about ₹10,895 crore of under-recovered LPG costs that it did not record as revenue or as a receivable, because the government had not authorized compensation.7
In economic terms, it means ₹10,895 crore of real cash spent buying gas was sitting in a ledger that only a policy decision could turn back into money.
The decision did come, partly. On August 8, 2025, the Union Cabinet approved ₹30,000 crore of compensation to the three state oil marketers for domestic LPG losses, payable in twelve instalments, with the petroleum ministry to decide the split.12 CRISIL expected HPCL's share to be roughly 27% to 28%.13 The ministry later set HPCL's compensation at ₹7,920 crore, for losses up to March 2025 and expected up to March 2026, paid in twelve monthly instalments from November 2025; three of those, ₹1,980 crore, were booked in the June 2026 quarter.1
That sounds like a happy ending. It is not quite one. The compensation covered less than the losses already incurred, and the cooking-gas deficit kept growing. The unrecognized negative buffer was ₹12,799 crore at March 2026 and ₹16,406 crore by the end of June 2026, up about ₹3,600 crore in a single quarter.1 The government had paid, but late, partially and on its own schedule. A shareholder who treats this buffer as an ordinary receivable from a customer is making a mistake: it is a claim on a future political decision, not a debt with a due date.
The practical test for HPCL's pricing model is therefore simple to state and hard to pass. During a sustained rise in crude, do pump prices adjust automatically, or does policy once again delay the pass-through until after the next election? The record so far, from 2022 and again in 2026, points one way: prices are held when it matters politically and released gradually afterwards.
Kaushal himself was careful on the call not to promise anything about government support, saying "it's not my brief to talk on what the government is going to do."2 He did, however, set a modest ambition: "red quarter we cannot avoid at this time, but we would also not want to have a red year."2
The verdict on pricing power is that HPCL has very little of it in the sense investors usually mean. What it has is a policy cycle that has, so far, eventually paid back its losses with interest, as in FY2024 and FY2026. That is a real source of earnings, but it is lent, not owned. And there is a second, structural reason the losses hit HPCL so hard: unlike its peers, it does not refine enough of the fuel it sells.
IV. Twenty-Four Million Tonnes of Refineries—and Still Buying Elsewhere
A truck driver pulls into an HPCL outlet on a highway in Punjab and fills his tank with diesel. The pump carries HPCL's blue-and-red logo. The diesel may well have been refined by HPCL. It may also have come from the Bathinda refinery down the road, run by a joint venture HPCL only half owns, or from a tanker of product bought from another refiner altogether.
The driver neither knows nor cares. For HPCL's shareholders, though, the answer makes all the difference. In the June 2026 quarter, about half of the diesel HPCL sold came from its own refineries, about 27% from the HMEL joint venture, and about 24% was bought from others.2
That supply gap is the clearest way to understand where HPCL sits in India's oil industry. It is a big marketer attached to a medium-sized refiner.
Start with the map of capacity. As of April 1, 2026, India had about 267 million tonnes a year of installed refining capacity.14 Indian Oil owned roughly 70 million tonnes across nine refineries, before counting its subsidiaries.14 Reliance's two Jamnagar complexes together held about 68 million tonnes, on a single site in Gujarat.14 Bharat Petroleum owned about 35 million tonnes across Mumbai, Kochi and Bina, and Nayara's Vadinar refinery held 20 million tonnes.14
HPCL owned two refineries: Mumbai, at 9.5 million tonnes, and Visakh, at 15 million tonnes, for a total of 24.5 million.14 That is about 14% of the country's capacity by CRISIL's count, and less than half of Reliance's Jamnagar.13
Two more entries carry HPCL's name and should be kept separate. HPCL-Mittal Energy's Bathinda refinery, rated at 11.3 million tonnes, is a joint venture in which HPCL holds about 49%.1415 HPCL Rajasthan Refinery's 9 million-tonne Barmer complex is a 74%-owned joint venture.146 Neither is wholly owned, and both are accounted for as joint ventures, so their profits reach HPCL only as a share of earnings, not as revenue.2 Counting everything, HPCL describes itself as having 35.8 million tonnes in FY2026 and expects 45.3 million tonnes by FY2028 once Barmer is fully running.8
Now put the marketing footprint beside it. HPCL sold about 51.5 million tonnes of products in FY2026, through more than 25,000 retail outlets and about 6,400 LPG distributors.8 Rating agencies credit it with roughly a quarter of India's transport-fuel sales and rank it the country's second-largest LPG marketer.1613 It owns the second-largest product pipeline network in India, more than 5,400 kilometres of it.8
The arithmetic is unforgiving. HPCL's own refineries processed about 6.5 million tonnes of crude in the June 2026 quarter, an annual pace of roughly 26 million tonnes, while it sold about twice that much product.18 The difference has to be bought.
Where the missing barrels come from
The gap shows up plainly in the income statement. In FY2025, HPCL's purchases of stock-in-trade, finished products it bought rather than made, came to ₹2,47,546 crore, more than half of its total operating expenses.7 HMEL alone supplied ₹60,453 crore of that, about a quarter of all purchased product.7 HPCL owed HMEL about ₹3,378 crore in trade payables at year end.7
This is related-party trade at a scale that deserves attention. HPCL pays no royalty or brand fee to ONGC, and its sales to related parties are small.7 But the purchases from HMEL are not incidental; they are a core part of how HPCL fills its network. The joint venture itself is a decent business in ordinary times: in the June 2025 quarter, HMEL earned a refining margin of a little over $7 a barrel and EBITDA of about ₹1,000 crore, according to HPCL's then finance director, Rajneesh Narang.10
But a good refinery owned half by someone else is not the same as a good refinery owned outright. HPCL buys HMEL's fuel at formula prices and keeps the marketing margin, positive or negative; it receives only its share of HMEL's profit.
Transactions with other government-controlled companies, which would include crude bought from ONGC, are exempt from detailed disclosure under Ind AS 24, so their full scale is not visible to shareholders.7
Why does buying product matter so much? Because a marketer that buys at import-parity prices and sells at a frozen pump price has no refinery margin to cushion it. When crude rose in 2026, HPCL's refining arm earned big margins on the barrels it refined, but on every barrel it bought from others, it paid the full high price and earned only the negative marketing margin. Kaushal said as much on the call: "One of the things which has hit us this quarter is our need to satisfy our marketing footprint by buying from third-party players."2
Lay the industry out through Michael Porter's five forces, and HPCL's position becomes clearer.
Suppliers are strong. Crude is bought on a global market dominated by state producers such as Saudi Aramco, ADNOC and Iraq's SOMO, alongside Russian sellers and domestic crude from ONGC.7 HPCL is a price-taker, and in 2026 it learned that its supplier relationships could be severed by geography overnight.2
Buyers are individually weak but collectively powerful in a peculiar way. No single customer accounts for a meaningful share of revenue; the motorist filling up has no bargaining power at all. But the government, acting on the motorist's behalf, sets the political ceiling on what HPCL can charge. The real "buyer power" in this industry sits in the finance and petroleum ministries.
Rivalry is intense and lopsided. Indian Oil is bigger at everything. Reliance runs one of the most complex refining sites in the world and sells fuel through its own retail venture. BPCL is HPCL's nearest twin, but with more refining capacity. Nayara owns a large Gujarat refinery and a retail network of its own.14
Substitutes are arriving slowly: electric vehicles, ethanol blending into petrol, compressed natural gas in cities. HPCL is participating in all three, with 2,253 CNG stations and 5,533 EV charging points at its outlets by March 2026.8 But each one, in the long run, shrinks the barrel of petrol and diesel on which its marketing margins depend.
New entrants face a high barrier in refining, which needs tens of thousands of crore of capital and years of approvals, but a lower one in retail, where private players have been adding outlets for years.
The forces point to one honest conclusion. HPCL's network is a real asset, but evidence that it confers pricing power or switching costs is thin. Customers can switch pumps across the road. Fuel is a commodity with standardized specifications. A quarter-share of transport-fuel sales tells you HPCL has scale; it does not tell you HPCL can charge more.
The 2026 crisis offered an unusual natural experiment. When crude spiked and the state-owned marketers held their prices down, demand shifted toward their pumps. Kaushal acknowledged that HPCL's outlet throughput rose "because of the demand state-owned enterprises had on their retail outlets," not because of anything HPCL did.2 In other words, the volume came precisely because the public-sector pumps were selling below cost.
HPCL's own attempts to make its outlets more productive are instructive. A retail improvement program called Abhyuday was rolled out at about 4,500 outlets in FY2026. Kaushal was candid: "It wasn't the most successful program."2 A second version now runs at 4,900 outlets, and management says those outlets are growing 100 to 150 basis points faster than comparable ones.2 That is an encouraging start, but it is management's measurement, and it is early.
The verdict is that HPCL's distribution supports scale, not a uniquely protected moat. The KPI that would reveal whether the network is strengthening is not the count of outlets, which every marketer is increasing, but HPCL's fuel-market share and volume growth measured against Indian Oil and BPCL over a full cycle.
Which brings the story to its central tension. If HPCL sells far more than its refineries can supply, then new refining capacity could fix the gap. Barmer was supposed to be that fix. But a refinery is only a solution if the capital it consumes earns a return, and before that question can be answered, there is a prior one: who actually controls the capital?
V. ONGC Buys Control, but HPCL Keeps Its Own Economics
On Saturday, January 20, 2018, the Government of India signed an agreement with ONGC to sell its entire 51.11% stake in HPCL.17 The price was ₹473.97 a share, for about 78 crore shares, a total of ₹36,915 crore, paid in cash in an off-market transaction.18 Two days later, Petroleum Minister Dharmendra Pradhan briefed the press. "ONGC-HPCL integration is the first innovative vertical integration," he said, and ONGC would become India's first vertically integrated "oil major."17
The idea had been announced in the 2017–18 Union Budget as a plan to create larger, integrated oil companies.17 Its logic was simple on a whiteboard. ONGC produced crude; HPCL refined and sold fuel. Together they would span the whole value chain, from well to pump, with more capacity to bear risk and take large investment decisions.17
It is worth being precise about what this deal was and was not. It was a sale of shares by the government to a company the government controls. HPCL did not buy anything, and it did not receive a rupee. Its own capital allocation was untouched. The deal changed who owned HPCL, not what HPCL owned.
Was the price fair?
The headline price invites easy judgments. At ₹473.97, ONGC paid about 14% more than HPCL's closing price the previous trading day of ₹416.55, and more than 10% above its 60-day weighted average.18 ONGC's valuation adviser, EY, had suggested ₹475 a share plus a control premium; Citi had suggested ₹500.18 So the price sat near the lower end of the advisers' range and modestly above the market.
How ONGC paid for it says something about whose needs the deal served. ONGC had only about ₹12,000 crore of cash reserves at the time, so its board raised its borrowing limit from ₹25,000 crore to ₹35,000 crore and lined up bank loans to fund the purchase.18 The government collected nearly ₹37,000 crore toward its disinvestment target in a single transaction. The parent took on debt. HPCL itself received nothing and changed nothing on the day the deal closed.
What the record does not provide is a comparison with other control transactions in Indian or global refining at the time. Without that, calling the deal cheap or expensive from the headline alone would be guesswork. The fairest reading is that it was a market-referenced transfer of control at a modest premium, structured to suit the government's fiscal needs as much as either company's strategy.
What changed, and what didn't
The minister promised that HPCL would "continue to be a Board-managed Central Sector Public Enterprise and will maintain its distinct identity and brand value."17 That is, in fact, what happened. HPCL kept its listing, its board, its brand and its separate accounts. Its financial statements consolidate its subsidiaries and equity-accounted joint ventures such as HMEL and HRRL, not ONGC.7
ONGC's stake rose from 51.11% to 54.90% without it buying another share. In March 2021, HPCL bought back about 10.5 crore of its own shares at ₹250 each, spending about ₹2,632 crore; ONGC did not tender, so its proportion grew.7 The buyback, executed in the open market, was a sign of a company with cash to spare at the time.8 It also, less visibly, shrank the free float.
Did ONGC's ownership change HPCL's operating prospects? The strategic pitch rested on crude-supply links, procurement synergies and the financial heft of a larger group. Some of that is visible. Rating agencies cite ONGC's parentage as a core support for HPCL's AAA rating, and CRISIL lists a reduction in ONGC's shareholding below 51% as a trigger that could lower it.13 That support is worth something in cheaper borrowing.
What is harder to find is evidence of operational transformation flowing from the parent. HPCL's refining margins did not converge with its stronger peers after 2018; an analyst on the July 2026 call noted that over the previous twenty quarters, HPCL had rarely reported refinery margins better than Indian Oil or BPCL.2 And when the 2026 crisis came, ONGC's ownership did nothing to stop pump prices being held below cost. Upstream ONGC may have benefited from higher crude; downstream HPCL bore the under-recovery. Within a group, that is just money moving from one pocket to another. For HPCL's minority shareholders, it is a loss.
So the verdict on the acquisition is limited but clear. ONGC's control strengthens HPCL's credit and its standing, but it cannot by itself make pump prices commercial, and it has not obviously made HPCL a better refiner. The real test of the parent era is not the 2018 deal at all. It is the giant project HPCL has spent most of that era trying to finish.
VI. Barmer: The Refinery That Grew Before It Opened
On April 20, 2026, the Rajasthan refinery was ready for its big day. The inauguration was scheduled; the crude distillation unit, the first unit any barrel of crude passes through, was running. Then a fire broke out in the CDU. The inauguration was called off, the unit was shut for rework, and a project that had already been years in the making was delayed once more.2
Twelve days earlier, on April 8, 2026, the Cabinet Committee on Economic Affairs, chaired by Prime Minister Narendra Modi, had approved a revised project cost for the refinery: ₹79,459 crore, up from ₹43,129 crore.6 HPCL was to put in an additional ₹8,962 crore of equity, taking its total equity investment to ₹19,600 crore.6 The scheduled commercial operation date was July 1, 2026.6
The cost rise was about 84%. In plain terms, the refinery nearly doubled in price before a single litre of fuel was sold.
The project is owned by HPCL Rajasthan Refinery Limited, a joint venture in which HPCL holds 74% and the Government of Rajasthan 26%.6 It sits at Pachpadra, in the Balotra district of the Thar desert, an unusual place for a refinery. Part of the logic was to process locally produced Mangala crude from Rajasthan's oil fields; imported crude would arrive by pipeline from a terminal at Mundra on the Gujarat coast.68
The complex is designed to refine 9 million tonnes a year and produce 2.4 million tonnes of petrochemicals.6 More than 26% of its output is meant to be petrochemicals: about 1 million tonnes of polypropylene, half a million tonnes each of two kinds of polyethylene, and smaller amounts of benzene, toluene and butadiene.6
It is also designed to make about 4 million tonnes of diesel and 1 million tonnes of petrol a year.6 HPCL calls it a refinery with a Nelson complexity index of 17, a measure of how sophisticated its processing units are, and says its polyethylene and polypropylene units will be the largest in India.8
Why does the petrochemical part matter? Because plastics are a different profit pool. Polypropylene and polyethylene are sold to packaging, auto and consumer-goods makers at market prices, not at prices set in a ministry. For a company whose fuel margins are subject to politics, a stream of product priced by the market is genuinely attractive.
How the cost got away
Construction was launched in January 2018, at the earlier cost of ₹43,129 crore.196 By May 2025, HPCL was aiming to start crude processing in October 2025 and petrochemicals in January 2026.20 In August 2025, Kaushal told analysts the overall program was 88% complete, with the refinery section more than 95% finished and the petrochemical section at 73%.10
On that same call, an analyst asked directly about cost escalation, noting that almost ₹60,000 crore had been spent against an overall estimate of about ₹72,000 crore. Kaushal replied that on hard costs, "we do not anticipate any major changes from the last estimate," while acknowledging that delays would add interest during construction.10 Eight months later, the approved figure was ₹79,459 crore.6 Whether the extra seven-thousand-odd crore was mostly financing cost or something else, the company has not disclosed a breakdown. What is clear is that the final cost came in above the number the market was given in August 2025.
The timeline slipped in the same way. In January 2026, HPCL said crude processing would begin by the end of that month.15 The fire in April forced another delay. HPCL declared scheduled commercial operation on June 22, and the asset was dedicated to the nation on July 4, 2026.221 Barmer is no longer a future project. It is an operating refinery still learning to walk.
It is easy to mistake the ₹79,459 crore for HPCL's own bill. It is not. That is the full cost of the joint venture's project, funded by equity from both partners and by debt raised by HRRL itself. HPCL's direct claim is its equity: ₹19,600 crore in total.6
But equity is not the whole exposure. At March 2025, HPCL had ₹13,674 crore of unexecuted capital commitments toward its joint ventures, primarily Barmer.7 HRRL's lenders are owed money on loans that Srividya Venkataraman, HPCL's new Director of Finance, described in July 2026 as "high-cost rupee term loans." She outlined a plan to refinance part of them through hedged foreign borrowing and to go back to banks for repricing once operations stabilize.2 If those plans fall short, the most likely source of extra support is HPCL itself.
Because HRRL is accounted for as a joint venture, HPCL will show only its share of HRRL's profit or loss, not its revenue.2 The refinery will therefore not swell HPCL's reported sales. What it is meant to do is reduce how much fuel HPCL has to buy from third parties, and over time send profit and dividends up to the parent.
On the July 2026 call, management laid out a ramp-up path in unusual detail. The crude unit was running at about 60% of capacity, after being tested briefly at full rates.2 Utilization for the September quarter was expected to be about 50%, rising to 80% to 85% from October and close to full on the refining side by the fourth quarter of FY2027.2
The petrochemical units would take longer, toward the end of the financial year.2 Director of Refineries S. Bharathan pointed to a challenge peculiar to an inland site: any surplus intermediate product cannot simply be shipped out by sea, so every unit has to be brought up in balance with the others.2
If that plan holds, the supply picture changes sharply. Kaushal said that by next year, about 56% of HPCL's diesel would come from its own refineries, 40% from joint ventures, and only the balance from third parties.2 "On a run rate basis, third quarter onwards, I would hardly be dependent on anybody except my own refineries and my JVs for diesel," he said.2
That is the promise. The proof will come in four places. The first is throughput: whether Barmer actually runs at 80% and then close to 100% when management says it will. The second is realized refining margin, which must cover the higher interest and depreciation of a newly built ₹79,000-crore asset. The third is petrochemical yield and sales, in a market where, as an analyst pointed out in 2025, spreads had been depressed for years by global overcapacity.10 The fourth is debt service: whether HRRL can pay its lenders from its own cash without HPCL writing more equity cheques.
The precedent at Visakh
There is a useful precedent for judging how quickly technical milestones turn into money at HPCL. The Visakh refinery was modernized and expanded from 8.3 to 15 million tonnes a year at a cost of about ₹30,609 crore.8 The centerpiece was a residue upgradation facility, or RUF, a unit designed to take the heaviest, cheapest leftovers from crude processing and crack them into diesel and other valuable products. In layman's terms, it turns the bottom of the barrel into the middle of the barrel.
The technology is formidable. Kaushal described a reactor running at about 380 bar and 400 degrees Celsius, with walls 25 centimetres thick, and said the technology provider, Lummus, had never run a unit this large.2 It also widens the range of crudes HPCL can buy, letting it run cheaper, heavier grades.10
In August 2025, HPCL said it was targeting commissioning of the RUF "in the next few weeks" and expected to capture its benefits in the second half of FY2026, as the unit stabilized around October and November.10 In July 2026, nearly a year later, the unit was still being stabilized after "unexpected technological challenges."2
Kaushal hoped for a good run in the September quarter and full stabilization in the one after.2 He also made a striking promise to an analyst who had pointed out HPCL's history of trailing peers on refining margins: "One year later you should ask me the same question on the same call, and you will have an HPCL asset which will have the highest margin."2
The Visakh record does not reject the case for Barmer. It narrows it. HPCL can build complex, first-of-a-kind assets, but its record shows that commissioning dates slip and the payoff arrives later than first guided. The right measure of Visakh's success is not technical completion but the realized refinery margin over the next four quarters; the same will be true of Barmer.
Two other pieces of optionality deserve a mention, but only a brief one. In January 2025, HPCL's subsidiary commissioned a 5 million-tonne-a-year LNG import terminal at Chhara in Gujarat, built for about ₹4,750 crore.22 Its operating record is too short to judge whether it will earn an attractive return. HPCL's research centre in Bengaluru has filed 661 patent applications and been granted 246, and the company spent about ₹391 crore on research in FY2025, less than a tenth of a percent of revenue.7 Patents show capability. They are not a profit pool until they produce one.
Responsibility for all of this falls on Vikas Kaushal, who became chairman and managing director in March 2025.23 His appointment was itself a break with tradition. The government's headhunting board had interviewed eight candidates in June 2024 and rejected them all, leaving the top job vacant after Pushp Kumar Joshi retired on August 31, 2024.23 Kaushal, then 53, was a chemical engineer from Panjab University with an MBA from IIM Ahmedabad who had spent three decades as a consultant, latterly as Kearney's global leader for energy and process industries.23
He had advised HPCL itself, among others, but had never run an operating company.23 He reportedly took an 80% pay cut to take the role, and was the first private-sector consultant appointed to head a blue-chip public company.23
His style on calls is distinctive: candid about failures, fond of analogies, and quick to deflect questions about government policy or peers. He named the Abhyuday program a disappointment, joked that his head of refineries might be "evading" questions about the RUF, and compared refineries to children with different abilities.2 He launched a cost-improvement program called Samriddhi, which he said delivered about ₹1,600 crore in its first year, and in July 2026 set a target of ₹1,500 crore on a run-rate basis for its second edition.2
The structure he works within is less flexible than his style. Executive pay at HPCL is set by government guidelines, with no profit commissions or stock options; the combined pay of all whole-time directors was about ₹5.64 crore in FY2025.7 Stock exchanges repeatedly fined HPCL in FY2023, FY2024 and FY2025 because the government had not appointed enough independent directors to meet listing rules.7 HPCL's management has a clear plan and a candid voice, but not the equity incentives or the board independence that would normally align it with minority shareholders.
All of this returns the story to one blunt question. If HPCL's big projects keep needing more money before they produce earnings, will the cash engine be strong enough to carry them and still pay shareholders?
VII. The Cash Is Real. So Are the Claims on It.
Here is a fact that surprises people who know HPCL only from its headlines. Across the twelve years from FY2015 to FY2026, a period that included a collapse in crude, a pandemic, a war in Ukraine and the FY2023 loss, HPCL generated about ₹1,62,650 crore of cash from operations.724 Its cumulative net profit over the same twelve years was about ₹82,977 crore.24 The business produced nearly twice as much cash as it reported in profit.
And yet, by the end of that period, HPCL had less cash than when it started. Its cash and short-term investments fell from about ₹7,300 crore at the end of FY2014 to about ₹3,300 crore at the end of FY2026.24 Where did all that money go?
Why the cash runs ahead of the profit
Two mechanisms explain the gap between profit and cash. The first is depreciation. Refineries, pipelines and terminals are expensive, long-lived assets, and their cost is written off against profit over many years without any cash leaving the building. In FY2025 alone, depreciation and amortization came to about ₹6,154 crore.7
The second is working capital, and here HPCL enjoys an unusual advantage. Its retail customers pay immediately, in cash or by card. Its suppliers of crude and products give it weeks of credit. At March 2025, HPCL owed suppliers about ₹29,800 crore while customers owed it only about ₹11,780 crore.7 Over the decade, its working capital has typically been negative, in the range of about 29 to 38 days of sales, and its debtor days fell to just six in FY2026.24 In effect, HPCL's suppliers fund part of its business.
That float is a genuine strength, but it is not free money. It reverses when crude prices spike, because HPCL has to pay more for every cargo while the pump price stays frozen. The June 2026 quarter showed how quickly that can happen: Kaushal said HPCL's debt had been rising by about ₹1,900 crore a week for thirteen weeks.2 Standalone debt rose from about ₹47,600 crore at March 2026 to about ₹72,600 crore by the end of June.1
Where the money went
Most of the cash went back into the ground. Standalone capital spending ran at roughly ₹14,000 to ₹16,800 crore a year from FY2021 to FY2025.78 Over the five years to June 2026, HPCL says it invested about ₹72,686 crore, including roughly ₹22,500 crore on refining capacity and about ₹18,200 crore of equity in joint ventures and subsidiaries, principally Barmer.8
After that capex, free cash flow over the twelve years came to about ₹52,116 crore.24 Dividends took about ₹27,171 crore of that, or roughly 52%.24 The payout ratio has swung widely, from about 13% of profit in FY2024 to 65% in FY2020, with a median near 35% and a payout of about 18% in FY2026.24 The rest of the free cash, along with new borrowing, paid for debt service, buybacks and the gap left by bad years.
At first glance, the market seems to be offering HPCL's cash for very little. On FY2026 figures, the free-cash-flow yield on the current market value was about 20%.24 That number, though, rests on a single unusually strong year, when crude was soft and pump prices were sticky. It is not a normal year's cash, and the next twelve months began with a quarter in which HPCL borrowed about ₹25,000 crore to keep fuel flowing.1
There are also real claims on future cash that a quick yield calculation ignores. At March 2025, HPCL had about ₹21,333 crore of capital commitments not yet provided for, of which about ₹13,674 crore related to its joint ventures.7 It reported contingent liabilities of about ₹5,002 crore, mostly tax and arbitration disputes.7
Separately, HPCL had more than ₹9,800 crore of disputed tax dues that it had not deposited, pending in various forums, including about ₹3,268 crore of central excise disputes before the appellate tribunal stretching back to 1994, and sales-tax and VAT disputes of about ₹1,426 crore before the Supreme Court and ₹2,775 crore before high courts.7 Those gross amounts are not the same as the reported contingent liabilities, and HPCL has carried such disputes for decades without a catastrophic ruling. But an adverse final judgment on historical indirect taxes is a genuine, if remote, call on cash.
Then there is the currency. HPCL buys crude in dollars and borrows partly in dollars. At March 2025, its net unhedged US-dollar liability was about ₹30,390 crore, and by its own sensitivity analysis, every 1% fall in the rupee against the dollar would cut profit before tax by about ₹304 crore.7 Among its dollar debt is a $500 million bond carrying a 4% coupon and maturing in July 2027.7
None of this makes HPCL fragile. Its debt-to-equity ratio had fallen to about 0.85 by March 2026, from 2.19 at March 2023.24 CRISIL rates its long-term debt AAA with a stable outlook, and ICRA does the same.1316 It has refinanced dollar loans at tight spreads and has deep access to Indian banks.
But it is worth being precise about what the rating measures. CRISIL's rationale rests explicitly on HPCL's strategic importance to the government and on expected support from the government and ONGC, and it names project-implementation risk and margin volatility as offsetting weaknesses.13 A AAA rating says lenders will almost certainly be repaid. It does not say that each project earns its cost of capital for shareholders.
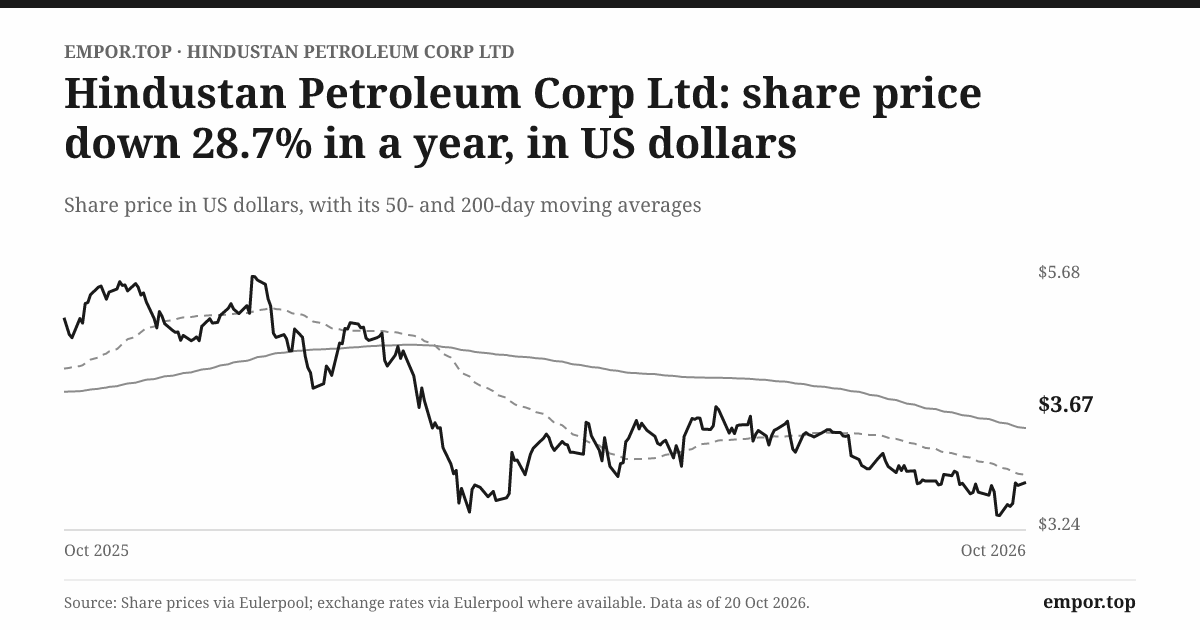
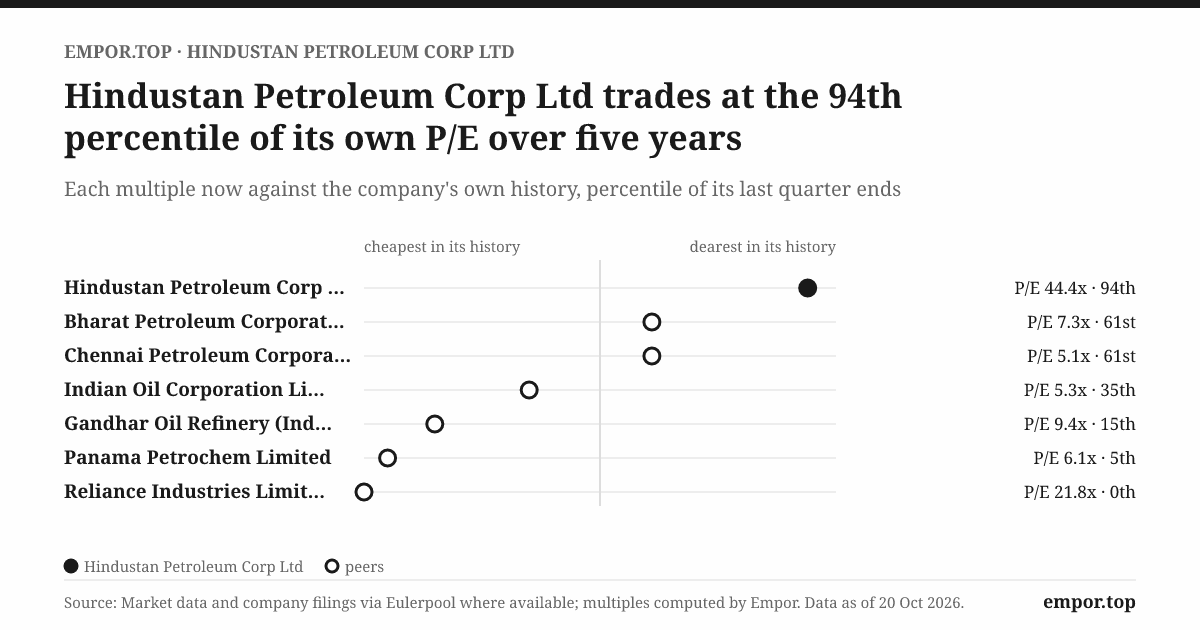
The market has drawn its own conclusions. At ₹348.50 on October 20, 2026, HPCL was valued at about ₹74,155 crore, around 30% below its 52-week high of ₹499.24 Its trailing price-to-earnings ratio of 44 times looks absurd next to a five-year median of about six times, but that is an artifact: one quarter's loss has erased most of the last twelve months' earnings.24 The clearer signals are the price-to-book ratio of about 1.1 and price-to-sales of about 0.2.24 The market is pricing HPCL as a cyclical utility whose book value is real but whose earnings cannot be extrapolated.
Who has been buying at these prices is telling, too. In the year to March 2025, Indian mutual funds raised their combined stake from about 15.5% to about 19.3%, while foreign portfolio investors trimmed theirs from 13.8% to about 12.6% and insurers cut theirs from 6.7% to 4.2%.7 The number of shareholders rose from about 4.1 lakh to 5.4 lakh.7 ONGC's 54.90% is locked, so the float is effectively a contest between domestic funds that see a cheap state utility and foreign investors wary of the policy risk.
On the July 2026 call, one investor complained that a market value of about ₹80,000 crore was "absurd" next to plant and machinery worth about ₹1 lakh crore.2 Book value, though, is only worth what the assets can earn, and that is precisely what the market doubts.
The verdict on the cash is that it is genuine and robust in normal years, but that most of it has been reinvested, and much of what remains is spoken for. Which raises the question every investor eventually has to answer: is there a reason this company should win from here?
VIII. Analysis & Bear vs. Bull Case
Picture the two sides of the ledger on a single day. The share price stands at ₹348.50, and on trailing dividends the stock yields about 7%.24 A few months earlier, the same company reported a quarter in which it lost about $1.3 billion.1 The bull and the bear are looking at the same company. They are simply asking different questions about it.
The case for HPCL
The bull begins with demand. India is one of the few large economies where fuel consumption is still growing, with volumes historically tracking GDP and vehicle ownership at something like 4% to 6% a year.7 HPCL sells about a quarter of the country's transport fuel through more than 25,000 outlets and is the second-largest LPG marketer.168 It owns refineries on both coasts, an expanded Visakh complex with one of the most advanced residue-upgrading units in the country, and now a share of a highly complex inland refinery with a large petrochemical stream.8
The bull then argues that the capex cycle is finally ending. Kaushal says HPCL is "at an end of a long capex cycle," with the FY2027 capex budget around ₹9,700 crore and likely lower, well below the ₹14,000-plus crore of recent years.2 If Barmer and the RUF reach full output, the bull says, HPCL becomes nearly self-sufficient in diesel, earns refining margin on far more of what it sells, and starts collecting petrochemical profits priced by the market rather than the ministry. The balance sheet, which went from 2.33 times debt-to-equity after Ukraine to 0.8 in about three years, can repair itself again.2
Return on invested capital was about 16.6% in FY2026, which, if sustained, comfortably exceeds HPCL's cost of capital.24 And at 1.1 times book, the bull says, the market is paying little for the chance that the cycle turns favorable again, as it did in FY2024.
The case against
The bear does not stop at "oil is volatile." The deeper objection is that the government can still delay price pass-through whenever it chooses, and has done so twice in four years. The 2026 freeze, the first price increase in more than four years coming only after state elections, and a growing LPG deficit all show that the state treats HPCL's margins as a policy instrument.51
Second, refining margins and the rupee can swing earnings independently of anything management does. Third, Barmer's cost rose 84% from its approved figure, its schedule slipped repeatedly, and its petrochemical economics are unproven in a market with global overcapacity.610 Fourth, the RUF at Visakh has taken nearly a year longer to stabilize than management guided in August 2025.102 And over the long run, electric vehicles, ethanol blending and compressed natural gas will gradually eat into the petrol and diesel volumes on which HPCL's network depends.
A skeptical activist would sharpen this into one question. If HPCL were told to maximize commercial returns, could it refuse an uneconomic public-service obligation, or reprice one? The record says no. In 2026, it sold fuel below cost while its board and management spoke of keeping "the wheels of the nation in motion."2 When an investor on the July call asked whether the government would compensate the company, Kaushal could only say that past support had "been taken into account" and that specifics were for others to discuss.2 Government support protects HPCL's lenders. It does not, by itself, protect its minority shareholders.
Hamilton Helmer's framework of seven powers asks what gives a business durable, above-average returns. Run HPCL through it, and the result is sobering.
Scale economies exist, but HPCL has less of them than Indian Oil or Reliance; it is the smallest of the three state refiners.14 Network economies, in Helmer's sense, do not apply: one more customer at an HPCL pump does not make the pump more valuable to others. Counter-positioning does not fit either, since HPCL's business model is essentially the same as BPCL's and Indian Oil's.
Switching costs are close to zero for fuel. HPCL's new premium cooking-gas brand, HP Navya, launched in July 2026 with on-demand delivery, is an attempt to build a brand that customers might pay more for. Management plans to take it to 200 to 250 mostly urban cities by Diwali, partly through quick-commerce partners such as Swiggy in Bengaluru, but even management's own ambition, moving about 50 lakh cylinders to the premium format within two or three years, would be a small slice of the business.2
Branding helps a little; HPCL says it was listed among the top twenty brands in India.2 Yet the 2026 crisis showed that price, not brand, drives behavior at the pump.
Cornered resources are partial. Barmer's access to local Mangala crude and HPCL's coastal sites are real assets, and the government's preference for state marketers in a crisis is a resource of sorts. But it cuts both ways, since the same government sets the price. Process power, the hardest-won of the seven, would show up in refining margins persistently above peers. HPCL has, by an analyst's count, rarely managed that over the last five years.2
The conclusion is that HPCL has assets and reach that matter, but little evidence of any of the seven powers in a form that protects pricing. Its strongest advantage, if it has one, is integration: the combination of coastal and inland refineries, joint-venture supply and a national network. That advantage depends on Barmer and Visakh performing as designed.
Compared with its rivals, HPCL sits in an awkward middle. Indian Oil has nearly three times HPCL's wholly owned refining capacity, and Reliance almost as much on a single site in Jamnagar.14 BPCL refines about 35 million tonnes against HPCL's 24.5 and has historically reported stronger refining margins.142 Nayara runs a single 20 million-tonne refinery with its own retail network.14
HPCL's distinction is that it sells more than it makes. That made it the most exposed of the three state marketers when marketing margins went negative, and it is why Barmer matters more to HPCL than any single new refinery would to Indian Oil or Reliance. The group-level scale of ONGC does not change this; ONGC's upstream earnings are not HPCL's.
Three indicators will settle most of the debate. The first is the unbooked LPG deficit and the marketing under-recovery on petrol and diesel, which together measure how much of HPCL's margin the state is withholding. The LPG buffer stood at about ₹16,406 crore at the end of June 2026 and was rising.1
The second is the gross refining margin, read net of inventory effects and export levies. The reported $23.80 for the June quarter flattered the underlying picture; the cleaner comparison is the core margin of about $6.54 a year earlier, against which the RUF and Barmer must deliver a lasting uplift.110
The third is Barmer's utilization. It was running at about 60% in July 2026, with management guiding to 80% to 85% from October and near-full refining output by early 2027.2
Land the analysis honestly, and the conclusion is conditional. HPCL has the assets and reach to benefit from India's energy demand, but the evidence for durable pricing power is weak. Whether its scale becomes an advantage or merely more capital tied up in the cycle will be decided by two things: how Barmer ramps up, and how the government behaves during the next crude spike.
IX. Playbook: Business & Investing Lessons
Go back to two moments. The first is April 2022, when crude was surging after the invasion of Ukraine and the price on HPCL's pumps was frozen where it stood, for what would turn out to be most of four years.4 The second is April 2026, when the Cabinet doubled the cost of the Rajasthan refinery and a fire delayed its opening. Between them, those moments contain most of what HPCL teaches.
The first lesson is that a regulated price can turn a growth business into a loss-maker overnight. HPCL kept its pumps open and its volumes flowing through FY2023 and still lost ₹8,974 crore, because the price it could charge was frozen while its costs were not.11 The same mechanism produced the 2026 loss and the ₹16,000-crore cooking-gas deficit sitting outside the balance sheet.1
The wider point for any investor is that when a customer is also the regulator, revenue growth is not the same as pricing power. In HPCL's case, the line to remember is this: a frozen pump price is a loan from the shareholder to the voter, and the borrower sets the repayment date.
The second lesson is that a network is an advantage only if it can be supplied at the right cost. HPCL built one of India's largest fuel-retail networks without the refining capacity to fill it. In good years, buying the gap from HMEL and other refiners was a convenience; in bad years, it meant paying full price for barrels it then sold at a loss. For founders building distribution-heavy businesses, the parallel is direct: the reach you build downstream is only as valuable as the cost at which you can feed it.
The third lesson is that a project's capacity is not its return. Barmer's 9 million tonnes and its petrochemical units were announced years ago as a solution. They arrived 84% over the original approved cost, after a series of missed dates and a fire.6 The capacity is now real. The return has yet to appear. A refinery is valued on its throughput, margins and debt service, not on the day it is dedicated to the nation.
The fourth lesson is that cash conversion is not free cash. HPCL's operations produced nearly twice its reported profit over twelve years, thanks to depreciation and supplier credit.24 But capex absorbed most of it, and the company ended the period with less cash than it began with. The cash was real. It was simply already committed before shareholders could see it.
The fifth lesson concerns people. In 2025, the government did something unusual and handed HPCL to a consultant who had spent his career advising oil companies rather than running them.23 Within eighteen months, he had launched cost programs, rebranded cooking gas, admitted a failed retail initiative in public and steered a fire-delayed refinery into operation. Those are real changes. But no amount of operational talent changed the most important number in the June 2026 quarter, which was set in Delhi. A new chief executive can fix a process; only a price can fix a margin.
What makes these lessons HPCL's own is the combination. The operating skill is evident: refineries running above nameplate, a large network kept supplied through a war, and complex new units commissioned. The limits are just as visible: a government that can set the price, a board whose independent directors depend on government appointments, and executives whose pay is fixed by guidelines rather than tied to the share price.7 HPCL is a well-run machine whose output is decided partly by someone else.
X. Epilogue
Tonight, in the desert at Pachpadra, a refinery that was a set of construction cranes for most of the last decade is processing crude. If management's plan holds, Barmer should now be running at 80% or more of its capacity, with its petrochemical units approaching start-up.2 HPCL is still absorbing the largest capital commitment in its history, ₹19,600 crore of equity in a project that cost far more than first promised.6
The next chapter will be written in a series of specific moments. The nearest is the September-quarter results, due in the coming weeks, which will show how much of the June inventory loss reversed, how the marketing margin recovered after the May price increases, and whether Kaushal's hope of avoiding "a red year" still looks realistic.2
After that come Barmer's milestones. Investors should watch three things: whether the refinery reaches the 80% to 85% utilization management guided to from October, whether the petrochemical units start and sell their output in early 2027, and whether HRRL refinances its high-cost loans without HPCL putting in more equity.2 A smooth ramp would vindicate the case that Barmer fixes HPCL's supply gap. Another round of delays or sponsor support would confirm the bear's fear that it is mainly an obligation.
At Visakh, the question is whether the RUF finally runs steadily and lifts realized refining margins. Kaushal has, in effect, set his own test: by July 2027, an HPCL refinery should have the best margin in its peer group.2 That is a clear and checkable promise.
Then there is policy. The LPG buffer, the payments still due under the 2025 compensation, and any new compensation for the 2026 losses will reveal how fully the state repays what it borrowed from HPCL's shareholders.1 The next time crude spikes, whether pump prices follow promptly or are frozen once again will matter more than any project.
The open questions remain the ones this story began with. Will the new capacity earn more than its cost? Can the cash support both capex and dividends? Can HPCL keep its margins when policy and commodity prices pull in opposite directions? The answers will come from quarterly results, not inauguration speeches.
XI. Outro
Come back to the pump on that Mumbai street. The price on the board is the easiest number in Indian business to see. Anyone can read it from across the road. The margin HPCL keeps on each litre is almost invisible, and in the spring of 2026 it was negative.
That is the bet in HPCL. On one side sit scale, essential demand, two coastal refineries, a new one in the desert and a business that throws off cash in normal years. On the other sit a government that sets the price when it matters, a capital program that has run long and over budget, and a cooking-gas deficit of more than ₹16,000 crore that no customer owes and no court can collect.1
HPCL is, in the end, a national fuel network whose commercial fortunes still turn on a single political question. When the cost of energy rises, who is allowed to pay for it?
References
-
HPCL posts Rs 11,526-crore Q1 loss as it holds down fuel and LPG prices through West Asia crisis — PSU Watch, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q1 FY2026–27 Earnings Call Transcript — Hindustan Petroleum Corporation via StockScans, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Petrol, Diesel Prices Hiked Again; Fuel Rates Jump Nearly ₹5 per Litre in Less Than 10 Days — Moneylife, 2026-05-23 ↩↩↩↩↩↩↩↩↩
-
Petrol, Diesel Prices Raised by ₹3 Per Litre as West Asia Crisis Hits OMCs — Moneylife, 2026-05-15 ↩↩
-
Cabinet approves revision in cost and investment in equity for HPCL Rajasthan Refinery Limited — Press Information Bureau, 2026-04-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
73rd Integrated Annual Report 2024–25 — Hindustan Petroleum Corporation Limited, 2025-07-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Investor Presentation Q1 FY2026–27 — Hindustan Petroleum Corporation Limited, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Centre for Public Interest Litigation v. Union of India — Supreme Court of India, 2003-09-16 ↩↩↩↩↩
-
Q1 FY2025–26 Post-Earnings Conference Call Transcript — Hindustan Petroleum Corporation Limited, 2025-08-08 ↩↩↩↩↩↩↩↩↩↩
-
72nd Annual Report 2023–24 — Hindustan Petroleum Corporation Limited, 2024-07-27 ↩↩↩
-
Cabinet approves Rs 30,000 crore as compensation to oil companies for LPG subsidies — The Tribune, 2025-08-08 ↩
-
Hindustan Petroleum Corporation Limited Rating Rationale — CRISIL Ratings, 2025-10-27 ↩↩↩↩↩↩
-
Installed Refinery Capacity as of 1 April 2026 — Petroleum Planning & Analysis Cell, Government of India ↩↩↩↩↩↩↩↩↩↩↩↩
-
HPCL to begin crude processing at Barmer refinery by January end — Reuters via The Economic Times, 2026-01-22 ↩↩
-
Hindustan Petroleum Corporation Limited Rating Rationale — ICRA ↩↩↩
-
Acquisition of HPCL by ONGC — Press Information Bureau, 2018-01-22 ↩↩↩↩↩
-
ONGC pays Rs 36,915 crore to acquire govt's 51.11% stake in HPCL — Business Today, 2018-01-20 ↩↩↩↩
-
HPCL aims to start crude unit at 9-MMtpy Rajasthan refinery in October — Hydrocarbon Processing, 2025-05-20 ↩
-
India's first greenfield integrated refinery complex starts operations — S&P Global Commodity Insights, 2026-07-06 ↩
-
HPCL commissions Chhara LNG terminal — Indian Infrastructure, 2025-02-03 ↩
-
Kearney's Vikas Kaushal appointed HPCL chairman — PTI via The Week, 2025-03-07 ↩↩↩↩↩↩
-
Financial Performance — Hindustan Petroleum Corporation Limited ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube