HDFC AMC: The Toll Road on India's Savings
I. Cold Open: One Fee Line, Two Kinds of Profit
The quarter ended on 31 March 2026, and on the surface it looked like any other quarter for HDFC Asset Management Company. Money kept arriving. Salaried Indians kept their monthly SIPs going, and the fund house's assets stood near record highs. Revenue in the quarter grew about 26% on the year before. Then came the bottom line: net profit was 2.5% lower than a year earlier, and net margin had dropped to about 55%, from more than 70% in a typical quarter.1
Nothing broke in the business. No big client left, no fund blew up, and no regulator wrote a letter. What moved was the company's own savings account. HDFC AMC keeps almost all of its balance sheet invested in securities, largely mutual fund units, and marks them to market every quarter. When markets wobble, that book wobbles, and the swing goes straight into reported profit.
This is the puzzle at the centre of the story. HDFC AMC runs two businesses under one income statement. The first is a toll road: it charges a small annual percentage on roughly ₹9.35 lakh crore of other people's money in HDFC Mutual Fund. The quarterly average in Q1 FY27 was ₹9,351 billion, or 11.2% of the industry.2 The second is a treasury of about ₹9,400 crore of the company's own money. That treasury earned ₹498.73 crore of "other income" in FY26, about 13.4% of profit before tax.1 Investments are 94% of total assets.1
The two businesses behave very differently. The toll road grew its operating profit (profit before tax less other income) by 17.8% in FY26.1 The treasury's income fell about 11% in the same year, as mark-to-market gains shrank.1 So the reader needs to keep two numbers in mind: the one the business earns and the one the market hands it.
The toll road itself is an unusually good business. Operating margins on fee income sit in the high 70s. There is no debt. Return on equity is about 31%. In FY26 the company paid out about two-thirds of its profit as cash dividends.1 Very few businesses anywhere combine those four traits, and fewer still have a structural tailwind like India's slow move from bank deposits and gold into market-linked savings.
That is also why the stock is expensive. At about ₹2,354 a share on 6 October 2026, HDFC AMC was worth about ₹1.0 lakh crore, or roughly 34 times trailing earnings.4 Four questions decide whether that price is a fair toll. Can AUM growth still carry a mid-30s multiple? How much of reported profit comes from markets rather than fees? Can the fee rate hold against SEBI and the move to cheap passive products? And does capital flow back to shareholders fairly, given that HDFC Bank owns just over half the company?
To answer them, the story runs through a joint venture formed to fill a hole UTI left behind, a star fund manager whose departure tested whether the franchise was a person or an institution, an IPO that raised nothing for the company, a bank merger that changed the parent, and a slow squeeze on the fee rate that no amount of AUM growth can fully hide. By the end the reader should be able to judge the toll, the traffic and who sets the price.
The story begins in 1999, when India's mutual fund market belonged to one state institution and everyone else was a newcomer.
 Subscribe on LinkedIn
II. A Late Entrant With the Right Parents (1999–2003)
In late 1999, Indian mutual funds meant one name: Unit Trust of India. For decades UTI's Unit Scheme 1964 had been where middle-class families parked savings that did not go into fixed deposits, post-office schemes or gold. Private fund houses had been allowed in since the early 1990s, but they were small, and many of the foreign entrants were struggling to build trust with Indian savers.
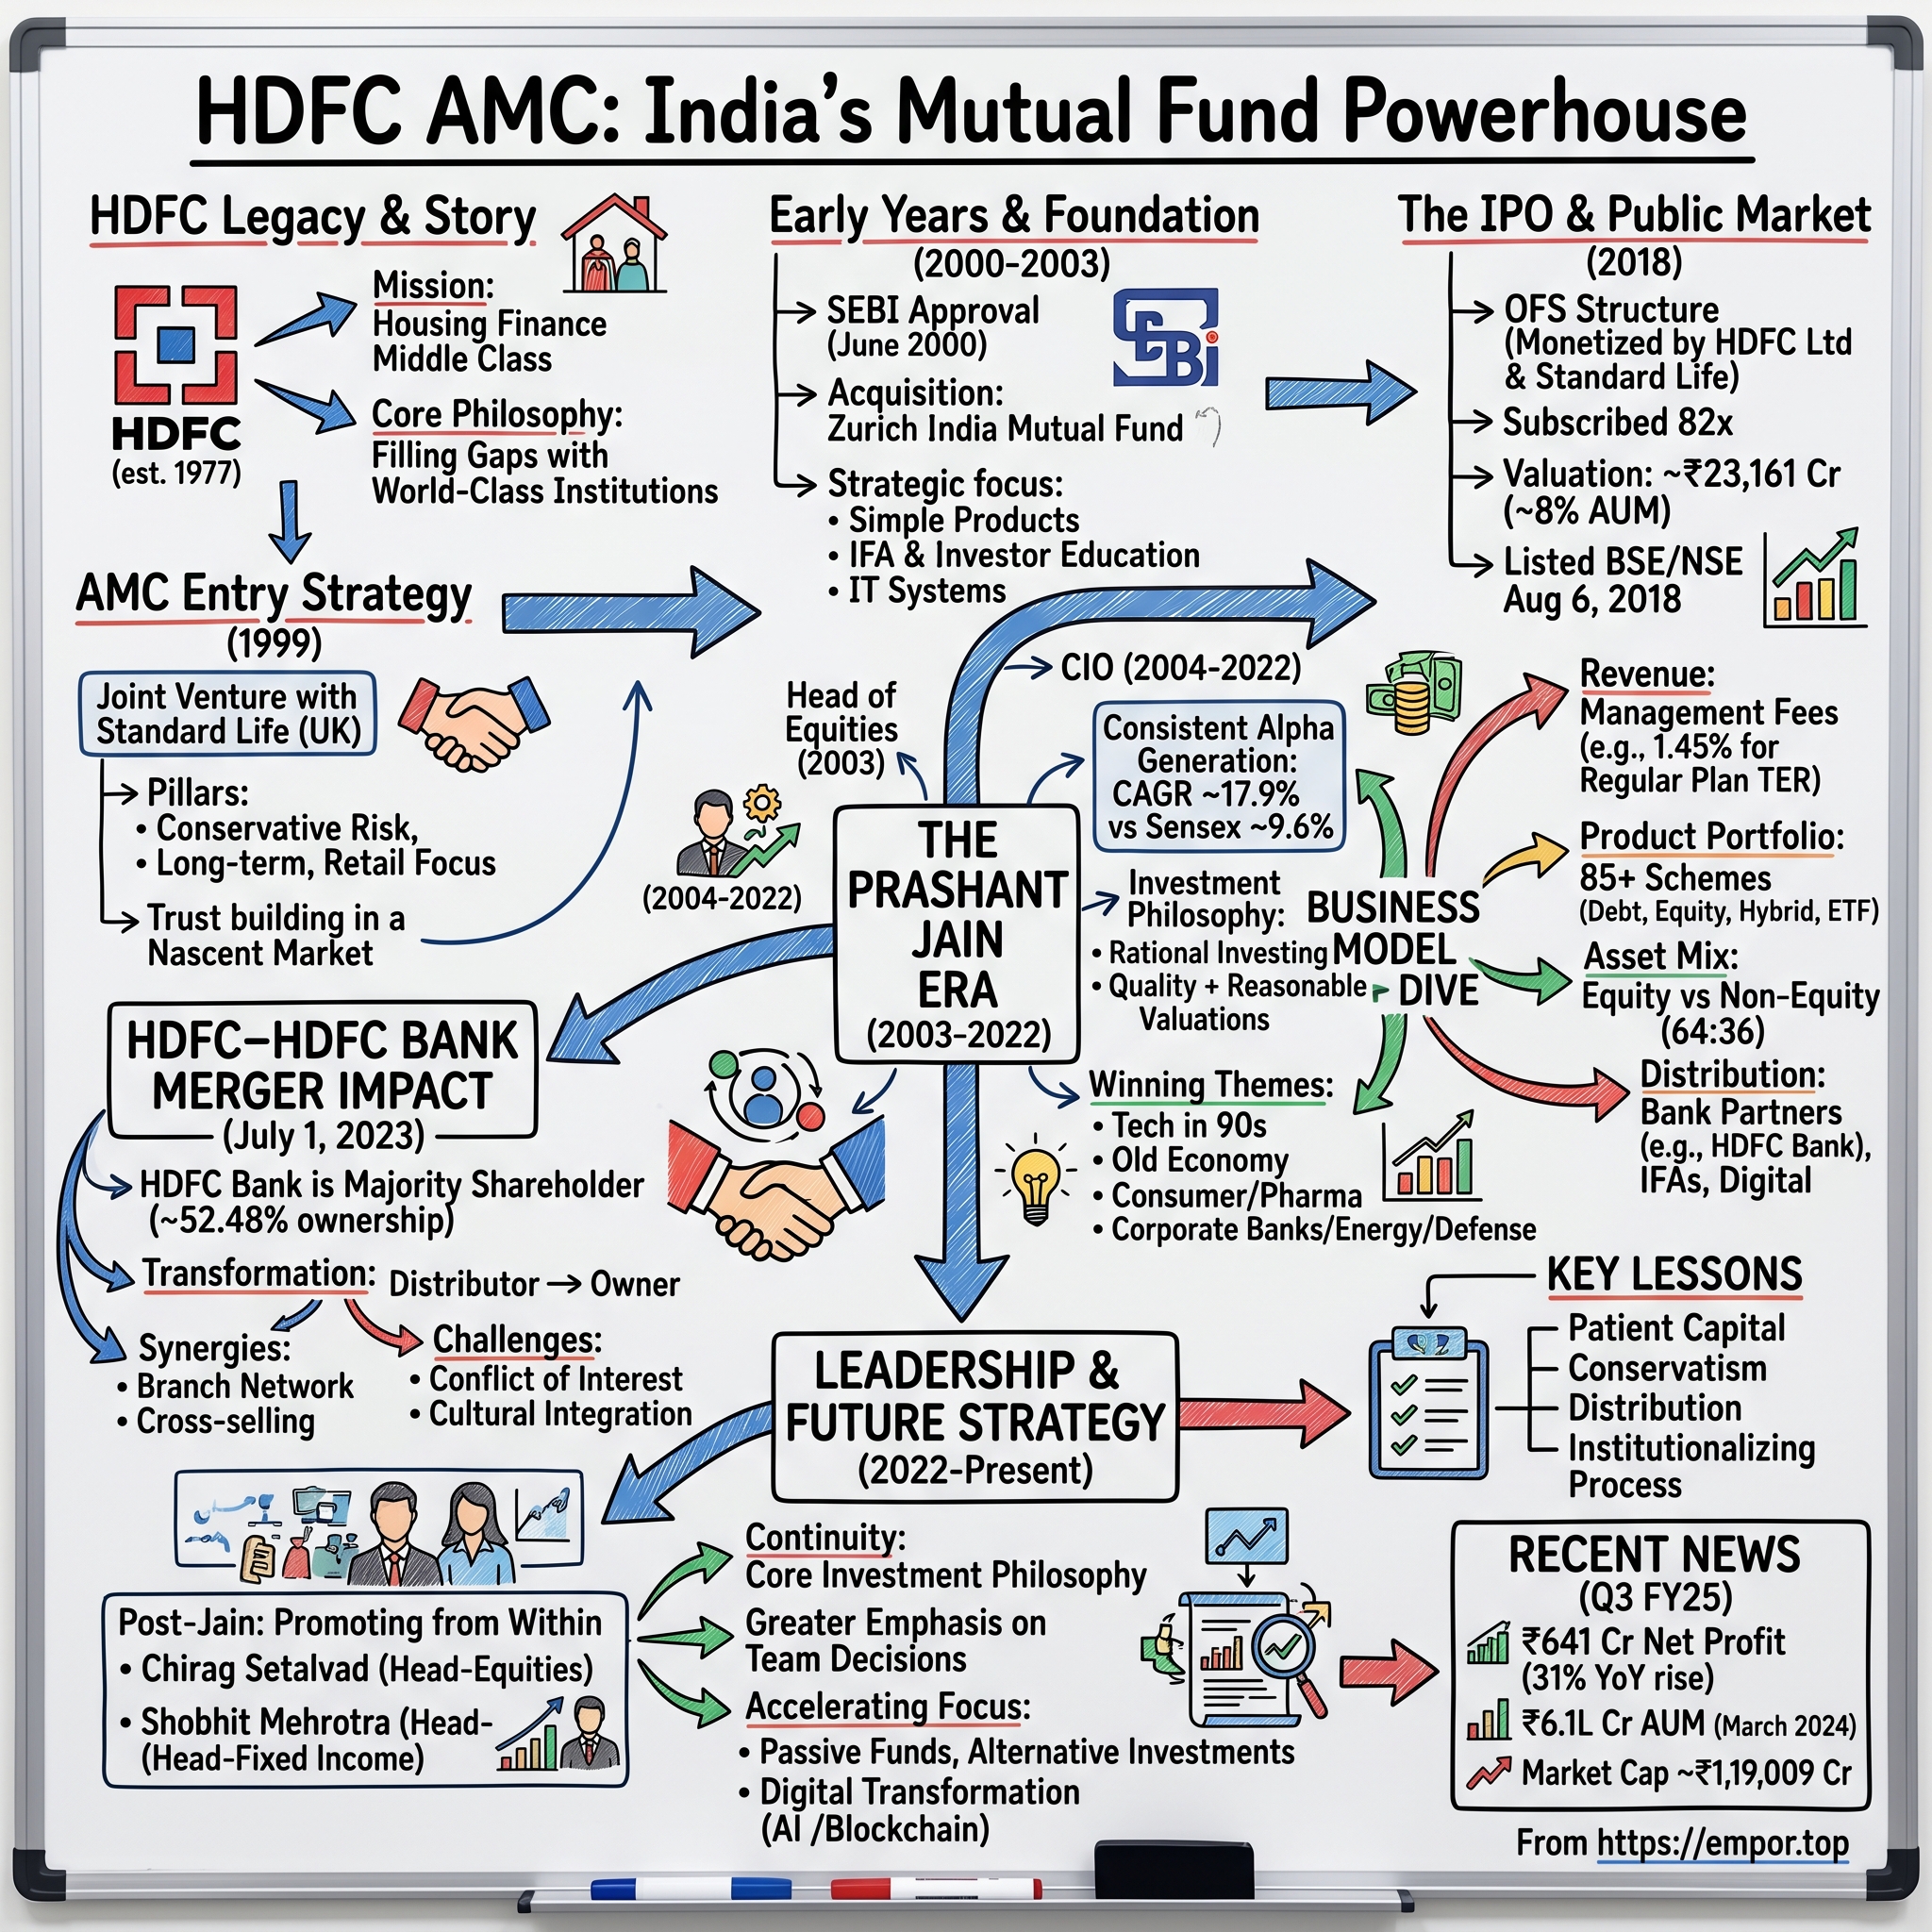
Into this market walked an odd couple. One was Housing Development Finance Corporation, the mortgage lender Deepak Parekh had made into India's most trusted private financial brand. The other was Standard Life Investments, the Edinburgh fund manager. HDFC Asset Management Company was incorporated in December 1999 and received SEBI approval to act as manager of HDFC Mutual Fund in 2000.5
Why would a late entrant earn a fee at all in a market where the incumbent was a quasi-sovereign giant? The answer was the brand. Indian households do not hand their savings to strangers. HDFC had spent two decades lending against homes with a reputation for clean books and conservative underwriting. The name told a first-time investor that this firm would still be there in twenty years. Standard Life brought investment process and global practice. HDFC brought the one thing a fund house cannot build quickly: trust.
That trust is still on the AMC's income statement. The company pays a trademark licence fee to HDFC Bank, which now owns the brand after the 2023 merger, to use the HDFC name. In FY26 that fee was ₹15.88 crore.1 It is a small number, but it shows that the most valuable asset in the business belongs to someone else, and the AMC rents it.
The second move came in 2003, when HDFC Mutual Fund took over the schemes of Zurich India Mutual Fund.5 Zurich's Indian equity schemes came with an investment team that had built a strong record in equity funds. For HDFC, which until then had been seen mostly as a debt and balanced-fund house, the deal provided an equity franchise almost overnight. It was the template for buying scale at a moment when a foreign seller wanted to leave. The price and the exact AUM transferred are best read from the company's own offer document; what matters for today is that it remains the only meaningful acquisition in the company's history.6
The joint-venture structure lasted far longer than many in Indian finance. Standard Life, later part of abrdn, stayed as co-promoter through the IPO and gradually sold down. It sold its last shares in June 2023.4 By then the mortgage parent itself was about to disappear into HDFC Bank, and the AMC's promoter changed from a housing lender to the country's largest private bank.
For an investor today, the origin story matters for one reason: HDFC AMC never had to win on price. It won on name, then on distribution, and only then on performance. That order matters, because in the era that followed the company's reputation became tied to one fund manager's long-term calls, and the market had to work out whether the brand or the man was carrying the fee.
III. The Star Manager Era and Its End (2003–2022)
For most of two decades, HDFC Mutual Fund's equity identity was the identity of its chief investment officer, Prashant Jain. His style was patient, valuation-conscious and often contrarian: buying public-sector banks and cyclicals when they were unloved, holding through drawdowns, and refusing to chase the market's favourite growth stocks. When it worked, as in the years after the 2003 market turn and again after the 2008 crash, HDFC's flagship equity funds were among the best-performing large funds in India. Distributors could sell HDFC funds with two names, the brand and the manager.
Then came 2018 to 2020. Indian markets were led by a narrow set of high-quality, high-multiple consumer and financial stocks. Value funds lagged. HDFC's flagship funds trailed peers and benchmarks for several years in a row. At the same time, two other forces hit the business.
The first was regulation. In 2018 SEBI capped total expense ratios for equity schemes on a sliding scale that cuts the allowed fee as a scheme gets bigger.7 For the largest fund houses, whose flagship schemes were huge, this was a direct cut to fee yield. It also showed the pattern that still defines the industry: the regulator, not the market, sets the ceiling on what a fund may charge, and it lowers that ceiling as funds grow.
The second was Covid. Markets crashed in March 2020, AUM fell with them, and the fee line followed. The result shows up clearly in the income statement. Net profit grew only 5.0% in FY21, 5.1% in FY22 and 2.2% in FY23.1 For a business used to compounding at high double digits, that was three years of standing still.
In 2022, Jain left the fund house after nearly two decades. The market's question was blunt: was HDFC's equity franchise a person, or an institution? If it was a person, assets should have followed him out. Distributors would move SIPs, institutional investors would pull money, and the AMC's share of active equity would shrink.
The record since then is the test. Net profit rose 36.5% in FY24, 26.6% in FY25 and 16.2% in FY26.1 By Q1 FY27 the company held 12.8% of the industry's active equity QAAUM, and its equity-oriented mix was 65.7% of AUM against 56.6% for the industry.1 Equity is where fees are richest, so a franchise that was bleeding after its star manager left would not look like this.
There are honest limits to the test. The recovery came during one of the strongest periods for Indian equities and domestic flows on record, and value as a style came back into favour after 2021. A rising tide lifted nearly every fund house. Part of HDFC's rebound reflects its own funds' improved relative performance as the style cycle turned, and part reflects the market. Separating the two cleanly is not possible from the company's disclosures.
The verdict is that history rejects the strong form of the key-person fear: the franchise did not shrink after the CIO left. It does not prove that performance will hold. Since the transition the investment function has been run as a team with several senior fund managers and a broader process, rather than around a single name. That lowers single-person risk but creates a different one: if a team-run process underperforms for three years, there is no star to blame and no obvious fix to sell to distributors.
This era was measured against a crowded field: SBI Funds Management, ICICI Prudential AMC, Nippon Life India Asset Management, Kotak Mahindra AMC, Aditya Birla Sun Life AMC and UTI AMC. Through the slow years, several gained relative ground. The forward test is simple. Watch HDFC's share of active equity AUM. If it holds near 12.8% through a period of weaker relative performance, the franchise is the institution. If it slides, the market was right to worry in 2022, just early.
Before any of that played out, though, the public market had already put a price on the franchise, back when the star was still at his desk.
IV. The 2018 IPO: What the Market Paid For
In late July 2018, HDFC AMC opened its initial public offering at ₹1,100 a share. The book was heavily oversubscribed, and the stock listed at a sharp premium on 6 August 2018.6 Many of the investors who bid were the same kind of people who held HDFC's funds: Indian households who knew the name and liked the idea of owning the fund house rather than just the fund.
What did they buy? Not a capital raise. The roughly ₹2,800 crore offer was an offer for sale by the promoters, HDFC and Standard Life, who sold part of their stakes.6 Not a rupee went to the company. That is the first thing to understand about HDFC AMC as a capital-markets story: it has never needed outside capital. It has no borrowings, and its FY26 annual report shows no equity raise, buyback, preferential issue or warrant issue.1 The IPO was a liquidity event for owners, and a price discovery event for everyone else.
The best way to compare an asset manager's price over time is market value as a share of the assets it manages. At listing, HDFC AMC was valued at roughly 8% of its AUM. Today the market value of ₹100,816 crore, on about ₹9.35 lakh crore of QAAUM, works out to roughly 11% of AUM.42 The market now pays more for each rupee under management than it did in 2018. Part of that reflects a richer equity mix, since equity rupees earn more fee than debt rupees, and part reflects the market's faith in India's long-term savings shift.
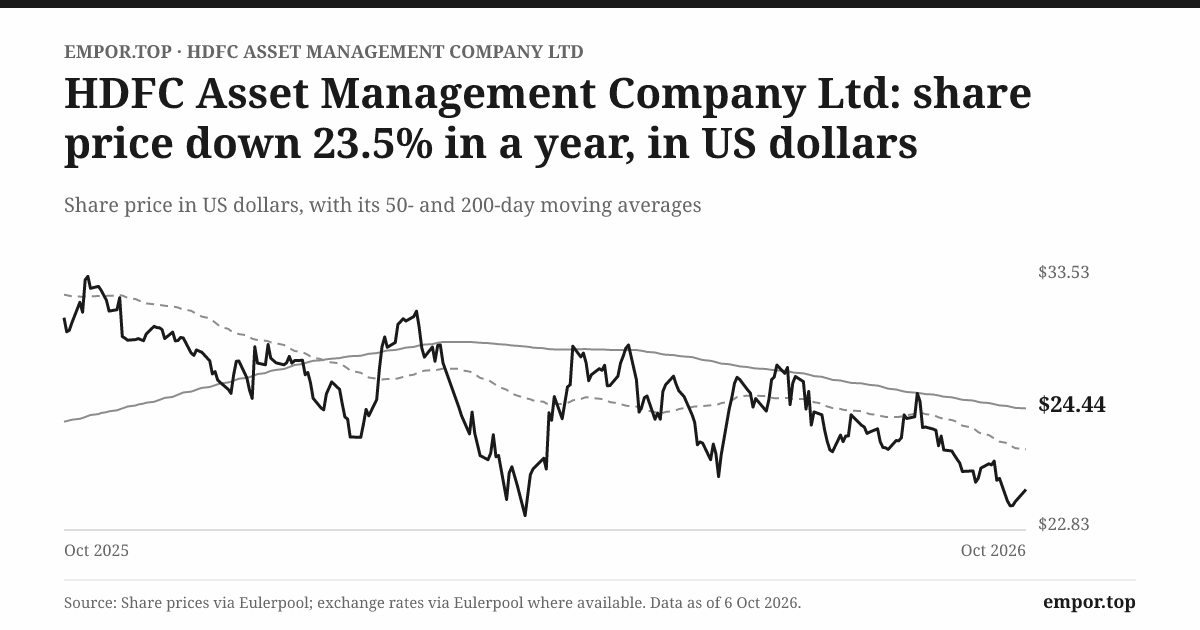
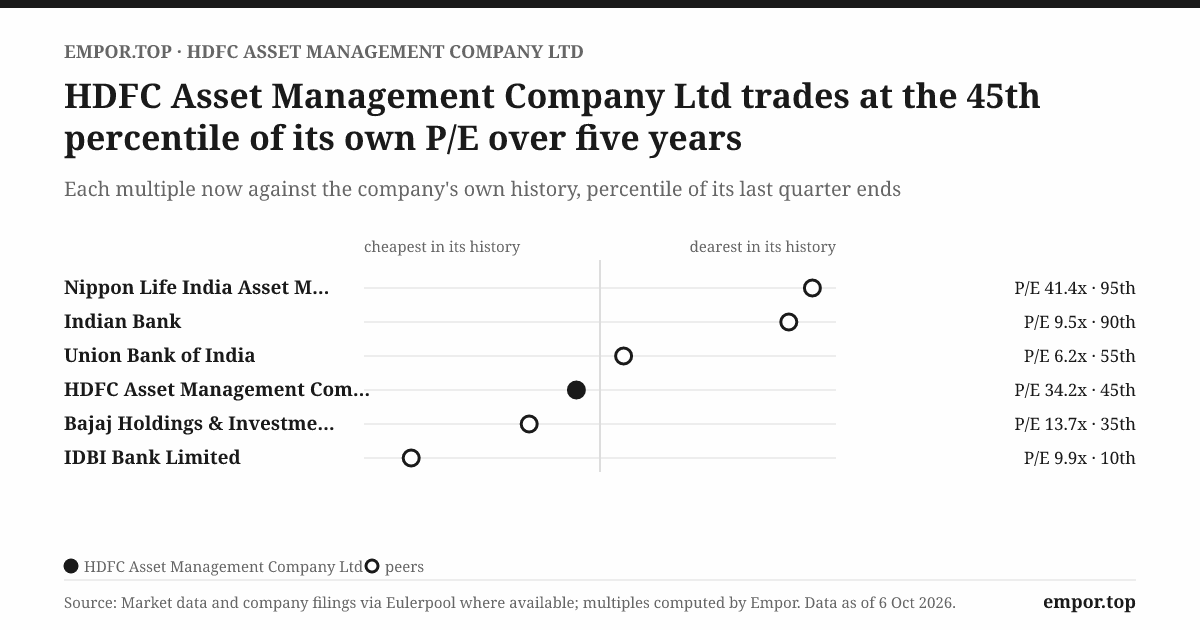
On earnings, the price is closer to its own history than the AUM multiple suggests. The stock trades at about 34.2 times trailing earnings against a five-year median of 36.6 times.9 The share price of about ₹2,354 is roughly 19% below its 52-week high of ₹2,899.4 In other words, investors are paying slightly less per rupee of profit than they usually have, while paying more per rupee of AUM than at listing. The two fit together only if profit per rupee of AUM has risen, which it did in the years of operating leverage, and the fee-yield squeeze in Section V threatens that.
Ownership today is concentrated but simple. HDFC Bank held 52.37% at 31 March 2026. Foreign portfolio investors held 24.45%, domestic mutual funds 8.44%, and individuals 7.51%, across 435,815 shareholders.1 Free float is about 47.6%, and a quarter of the company is in foreign hands. That ties the stock to global flows into Indian financials. When foreign investors sell India, they sell liquid, high-quality names like this one first, regardless of what SIP flows did that month.
One technical point matters for anyone reading the per-share history. In November 2025 the company issued 1:1 bonus shares, doubling the share count. Equity share capital went from ₹106.90 crore to ₹214.20 crore.1 Some data series restate earlier years for the bonus and some do not, which is why one summary table shows FY25 earnings per share falling almost 37%. Profit did not fall. The share count doubled. Net profit rose 16.2% in FY26, which is the clean figure.1
For investors the IPO's lesson is simple. Public shareholders bought into a business that throws off cash and needs none back. What they did not buy was control over the fee rate, which belongs to SEBI, or over the brand, which belongs to the parent. To see why the fee rate matters so much, follow a single SIP from a phone to the income statement.
V. The Fee Machine: How an AMC Actually Earns
It is the first working day of the month in Pune. A 29-year-old software tester's salary lands in her account in the morning. By the afternoon an auto-debit of a few thousand rupees has moved into an HDFC equity fund through a mobile app. She does not think about it. That is the point.
Multiply that moment by millions. In March 2026 alone, SIP and STP flows into HDFC Mutual Fund were about ₹4,875 crore, up 33% on a year earlier.1 Individual investors account for 69% of the fund house's monthly average AUM, against 61% for the industry.1 And 97% of transactions are now digital.1 HDFC AMC has, in effect, become part of the monthly plumbing of Indian salaries.
The pricing unit
Here is the mechanism in plain terms. HDFC AMC does not own the money. Unitholders do. The AMC is paid an annual investment management fee, a percentage of each scheme's assets, accrued daily. If a scheme has ₹1,000 crore and the AMC's share of the fee is, say, 0.6% a year, the AMC earns about ₹6 crore a year from it, a little each day. If the market rises 10%, the scheme becomes ₹1,100 crore and the fee rises 10% the same day, with no extra work. If the market falls 25%, the fee falls 25%.
Each scheme's total expense ratio is capped by SEBI, and the AMC's management fee is one part of that ratio.7 Equity schemes carry far higher fees per rupee than debt or liquid funds, which in turn charge more than index funds and ETFs. Direct plans, bought without a distributor, carry lower expense ratios than regular plans, because no distributor commission is embedded. So the AMC's revenue is not just AUM; it is AUM multiplied by mix, and mix is the whole game.
The clue: fees trailing AUM
In FY26, investment management fees from HDFC Mutual Fund were ₹4,103 crore, up 17.84%. Average AUM grew 19.05%.1 Fees grew more slowly than the assets they are charged on. That gap is the fee yield easing: each rupee managed earned a little less than the year before.
The reasons are familiar. SEBI's sliding-scale caps mean that as each scheme grows, its allowed fee rate falls. Debt, liquid and passive products grow alongside equity and pull the average down. Investors keep moving to direct plans. None of this is sudden, but it is steady.
Management has pointed investors to an operating margin corridor of roughly 33 to 35 basis points on AUM, as reported in analyst coverage of recent results.2 That is the number to hold them to. If operating profit per rupee of AUM stays in that band, the toll road is intact even as the gross fee rate eases. If it drifts below, scale benefits are no longer offsetting price cuts.
One family, one regulator
Of ₹4,118.53 crore of revenue from operations in FY26, ₹4,103.15 crore, about 99.6%, came from HDFC Mutual Fund.1 On paper that looks like extreme customer concentration. In practice it is structural: the AMC exists to manage that fund family, and the schemes pay their fees reliably. Receivables are only about two weeks of revenue.1 The real concentration is regulatory. One SEBI circular on what schemes may charge reaches nearly every rupee of revenue at once.
The cost side
Costs tell the second half of the margin story. Employee costs were ₹480.88 crore in FY26, up 23.9%, while revenue from operations grew 17.7%.1 Employee cost rose to about 11.7% of revenue, from 11.1%.1 Depreciation rose about 24%, as leased premises and technology spend grew.1 Total expenses grew 17.5%, a touch below revenue, only because other expenses grew just 7%.1 The company had 1,713 permanent employees.1
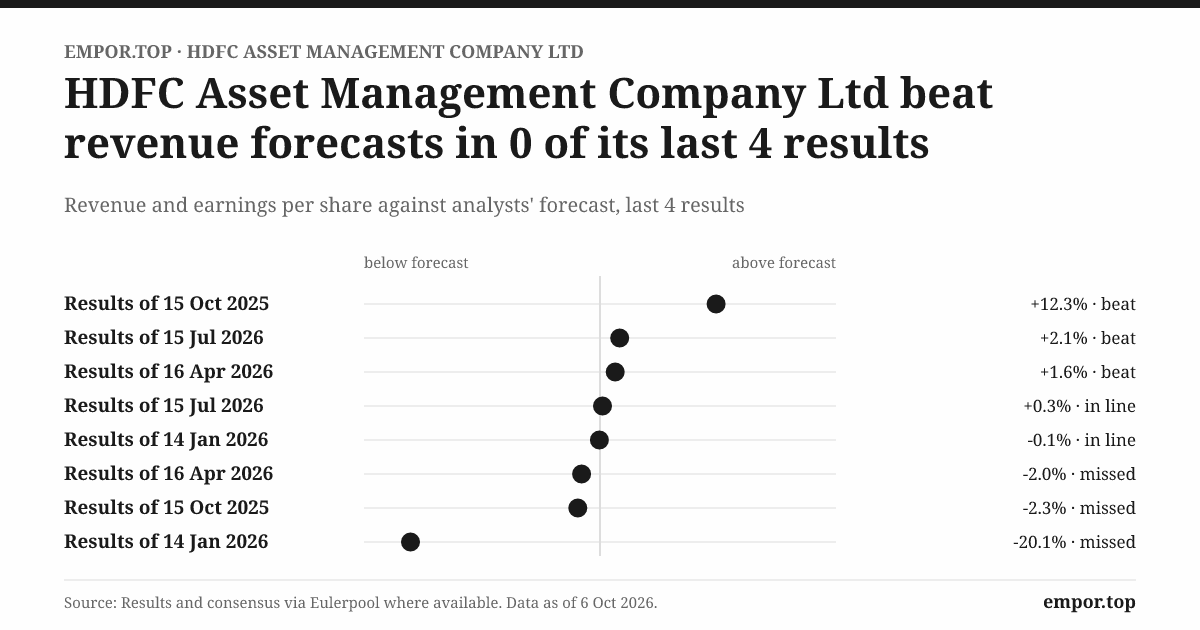
That decomposition explains the quarterly margin path. Operating margin peaked at about 80% in the December 2024 quarter. By June 2026 it was 75.5%, against 78.1% a year earlier.1 In Q1 FY27 revenue grew 13.6% and net profit 12%, to about ₹837 crore.2 With revenue growth slowing and people costs, including stock-based pay, still compounding in the twenties, margin compresses. This is not a crisis. It is what happens when a fee business's revenue growth falls toward its cost growth.
Reinvestment is people, not plant
HDFC AMC needs almost no capital. Spending on property, equipment and intangibles was ₹22.60 crore in FY26, about 0.5% of revenue.1 The reinvestment that matters is people and brand: advertising of ₹53.48 crore, up 15%, and software and allied services of ₹52.92 crore.1 The company says it uses AI in research, investor engagement and operations.1 The technology threat is not that software replaces the fund manager. It is that technology makes cheap products easier to buy: index funds and direct plans on apps cost almost nothing to distribute and charge a fraction of an active fund's fee.
Distributors: the hidden layer
One cost barely appears. Distributor commissions on mutual fund schemes are paid out of the schemes' expense ratios, not the AMC's own expenses. The AMC's own fees-and-commission expense was only ₹5.91 crore, mostly for PMS, AIF and advisory products.1 The company does not break out in its annual report how much AUM comes through its top distributors, including HDFC Bank. That matters, because the distributor is the real buyer of a mutual fund, as the next section argues.
The verdict from the fee machine: retail equity is the richest seam in Indian asset management, and HDFC over-indexes to it. But fees are already growing slower than AUM, and costs are growing faster than fees. The machine still prints cash. It prints a little less of it per rupee each year. Whether that is a moat holding steady or a moat slowly eroding is the question for the industry-structure lens.
VI. Moat or Toll Road? Industry Structure, Porter and Helmer
Picture a mutual fund distributor in Ahmedabad, an independent adviser with a few hundred clients. A new client wants to start a ₹10,000 monthly SIP in a flexicap fund. The adviser has thirty-odd fund houses to choose from. All are regulated by the same SEBI rules, all report the same disclosures, and all fall within the same expense-ratio caps. What makes the adviser pick HDFC?
That one decision, repeated across tens of thousands of distributors and platforms, is the whole competitive question. Answer it, and the moat is clear.
Scale
HDFC Mutual Fund held 11.2% of industry QAAUM and 12.8% of active equity QAAUM in Q1 FY27.1 By total AUM, SBI Funds Management is larger, helped by its parent bank's reach and its role in large government and retirement mandates; AMFI's monthly data show the ranking.8 ICICI Prudential AMC is HDFC's other large rival in active equity. Behind them sit Nippon Life India, Kotak, Aditya Birla Sun Life and UTI, each with a meaningful but smaller share.8
Hamilton Helmer's seven powers
Scale economies are real. Fund management costs are mostly people and technology, and they do not rise in step with AUM. A ₹1 lakh crore fund needs nowhere near ten times the team of a ₹10,000 crore fund. That is why HDFC's operating margin rose from the mid-50s a decade ago to the high 70s.1 But SEBI's sliding caps pass part of that scale benefit back to investors, so scale protects margin more than it lifts price.
Branding is the second power and the oldest. A household investor choosing a fund house for a 20-year SIP buys trust first. The HDFC name was the founding advantage and remains one, though it is rented from the parent.
Counter-positioning cuts against HDFC rather than for it. A pure passive house can offer index funds at a fraction of the fee without hurting an existing profit pool. HDFC can launch index funds too, and does, but every rupee that moves from its active equity funds to its own index funds earns far less. The incumbent's richest business is exactly what a low-cost challenger targets.
Switching costs are low for the investor. Moving from one fund to another takes minutes on an app, apart from exit loads and capital-gains tax. What keeps money in place is inertia, the SIP habit and the tax friction, not lock-in. Network effects and cornered resources are weak or absent. Process power is arguable at best: investment process can be copied, and talent can leave.
Porter's five forces
Buyer power sits with the distributor and the platform, not with the unitholder. Large banks, national distributors and investment apps decide what goes on the shelf. HDFC Bank is the largest distributor in the group, but it also sells rival funds. Supplier power is mostly talent: fund managers and analysts, whose pay is the AMC's biggest cost line and is growing fastest. Substitutes include index funds, ETFs, portfolio management services, AIFs, direct equity and, for conservative savers, bank deposits. New entrants keep coming as SEBI licenses new fund houses, including fintech-backed ones aimed squarely at low-cost passive investing. Rivalry is intense in performance and distribution but cannot be fought on headline price, because the regulator sets the band.
Then there is the force Porter does not list: the regulator itself. SEBI sets the ceiling on what the product may cost and has lowered it before.
The verdict
The moat is real but narrow in a specific way. Brand, distribution reach and scale economics protect HDFC's share and margin. They do not protect its price, because price is set outside the company. Investor switching costs are low, and passive products are a counter-positioned threat.
Falsification bears this out. The 2018 TER cut and the share shifts between fund houses during HDFC's weak performance years both show the moat bending under regulation and relative performance. It did not break, and share recovered, but it bent.
The forward test is one ratio: revenue from operations as basis points of average AUM, FY24 through FY27. If it declines by a few basis points a year while operating profit per rupee of AUM holds near the 33–35 bps corridor, scale is winning. If both slide, the toll road is being repriced from above.
The parent that owns the brand, and whose branches sell the funds, changed in 2023. That changed who the AMC answers to.
VII. The Bank Merger and the Parent's Embrace (2023–Now)
On 1 July 2023, Housing Development Finance Corporation ceased to exist as a separate company and merged into HDFC Bank. For HDFC AMC, the change happened overnight on paper and slowly in practice. Its promoter was now India's largest private bank, with thousands of branches and tens of millions of customers.4 The same month, abrdn completed its exit, and HDFC Bank became the sole promoter.
The bull case for the merger was obvious. A bank sees customers every day, holds their salaries and knows when a fixed deposit matures. If even a fraction of HDFC Bank's customers move savings into HDFC Mutual Fund through the branch or the app, that is a distribution channel no rival can easily copy.
The bear case is subtler. HDFC Bank is a distributor with its own economics. It sells many fund houses' products, and it earns commissions from all of them. It has every reason to keep a broad shelf, both for its customers and to stay on the right side of regulators. Group synergies are claimed easily and proven rarely. The only proof that counts is in the AMC's own numbers: share of industry AUM and of active equity. Those stand at 11.2% and 12.8%.1 They are healthy, but the company does not disclose how much of its AUM the bank's channel brings, so the bank's contribution cannot be isolated.
What the parent charges
The cost of the relationship can be measured. In FY26 the AMC paid HDFC Bank about ₹36 crore in total: trademark licence fees of ₹15.88 crore, lease rent of ₹13.81 crore, fees and commission of ₹3.77 crore and smaller administrative charges.1 That is about 0.9% of revenue from operations. The annual report states that all such transactions are at arm's length and no more favourable than third-party terms, and that there were no material related-party transactions requiring separate disclosure.1
The one item to watch is the trademark fee. It grew 20.6% in FY26, faster than revenue's 17.7%.1 At ₹16 crore it is immaterial today. But it is the cleanest window into whether the parent's take is creeping up. Track it as a share of revenue from FY23 to FY27. If it stays flat, the relationship is a light tax. If it rises steadily, the parent is quietly repricing the brand it rents out.
The largest flow between the two companies is not a charge at all. HDFC Bank received ₹1,009.62 crore of dividends from the AMC in FY26, up from ₹785.26 crore.1 That aligns the parent with minority shareholders: the bank gets its cash the same way everyone else does, pro rata.
The auditor and the small print
The auditor, B S R & Co., gave an unmodified opinion. Its key audit matter was revenue recognition on management fees, because fee rates are entered manually across many schemes with different terms.1 That is not a red flag, but it is worth noting: an error in rate entry, across a fund house this large, would hit revenue directly. Disputed income-tax and GST demands and one small investor claim add up to about ₹19 crore, immaterial against FY26 profit of ₹2,859 crore.1
The verdict: the parent's drag is small, and its dividend take aligns its interests with minorities. The real question, whether the bank lifts the AMC's share, cannot be answered from the AMC's disclosures, and the share data are the only evidence. Which puts the spotlight on the people who run the AMC day to day, and how they are paid.
VIII. The People in Charge Now
The headline in the FY26 annual report is not dramatic until one reads the remuneration table. Navneet Munot, managing director and CEO, received total remuneration of ₹15.45 crore, up 44.5% from ₹10.69 crore.1 A few pages away, the same report gives his pay rise as 6.04%, excluding the value of ESOPs exercised.1
Both are true. The gap is share-based payment, which rose from ₹1.13 crore to ₹3.99 crore, while short-term benefits rose from ₹9.00 crore to ₹10.86 crore.1 The lesson for the reader is to check which number a company leads with. Here the company quotes the smaller one in its statutory pay disclosure, which is the convention, but the larger one is what the company recognised as cost.
The CEO
Munot came to HDFC AMC as an investment professional, not a banker. Before HDFC he was chief investment officer at SBI Funds Management, one of HDFC's main rivals, and earlier worked at Morgan Stanley's Indian fund business. He is known in the industry as a writer and speaker on long-term investing and investor education, and for an equity view built on process rather than personality. That background fits the post-2022 HDFC: a fund house that wants to be seen as an institution with a system, not a stage for one star.
His record on promises is mostly a record of what he has not over-promised. Management has pointed analysts to an operating margin corridor on AUM rather than to aggressive growth targets.2 In the Q1 FY27 discussion the topics analysts pressed on were margin and fee yield: why operating margin fell to 75.5%, and how SEBI's review of expense ratios might hit revenue.2 Answers on cost growth were concrete, tied to employee costs and investment in the business. Answers on regulation were necessarily vague: the company cannot know what SEBI will decide, and said as much.
The CFO, Naozad Sirwalla, saw his pay fall 3.23% in FY26.1 No change of MD or CFO occurred during the year.
Pay against profit
At ₹15.45 crore, the CEO's pay was about 0.54% of profit after tax.1 For a business earning nearly ₹2,900 crore, that is not excessive. More striking is the split across the company: average pay for managerial staff rose 4.34%, against 14.16% for non-managerial staff.1 Median employee pay rose 16.4%.1 For a talent business, that pattern makes sense, but it also shows where cost pressure comes from.
The skeptic's question
An activist would ask a pointed question. Why does a company that needs no capital, pays out most of its profit and has a dominant parent issue so much equity to staff? Under the 2025 scheme the company granted about 22.9 lakh options and 5.3 lakh performance stock units, adjusted for the bonus.1 The answer the company would give is talent retention: fund managers and analysts can walk across the street, and stock that vests over years keeps them. That answer is credible for an asset manager, where the product is people.
The harder half of the question is who approves it. A promoter-controlled board approves equity for staff paid for by all shareholders. Shareholders, though, were comfortable. The 2025 ESOP scheme drew 98.75% approval, with only 1.25% against.1 The bonus issue drew 2.49% against.1 Dissent is low.
The board
The chair is Deepak Parekh, non-executive, the banker most associated with the HDFC name and the man who presided over the group from the mortgage company's early years to the merger. Five directors are independent.1 Separating the chair from the CEO is good practice, though Parekh's long association with the group means the board's independence from the HDFC culture is limited by design.
The verdict: pay is small against profit, dilution is modest, and dissent is low. Incentives are long-dated and tied to the share price, which aligns management with minority shareholders. Insider ownership is low, so alignment rests on options rather than on large owned stakes. The question that remains is what the company does with the cash these people generate.
IX. Where the Cash Goes: Dividends, Treasury and the ₹9,400 Crore Book
Open HDFC AMC's balance sheet at 31 March 2026 and two numbers sit side by side, a long way apart. Cash and bank balances: about ₹24 crore. Investments: ₹9,396 crore.1 The company keeps almost nothing in the bank. Almost everything sits in securities, mostly mutual fund units, including its own schemes, plus debt instruments.
Profit into cash
Standalone cash from operations was ₹2,530 crore in FY26, against profit after tax of ₹2,859 crore, about 88%.1 That is a healthy ratio, up from about 84% in FY25. The gap has a clear cause. Most of the ₹498.73 crore of other income is net gain on financial assets marked at fair value: ₹453 crore of it.1 These gains are in profit but not in cash until the units are sold. Tax paid and a rise in receivables also take a little.
So operating cash is honest, and reported profit is flattered by mark-to-market gains in a rising market. In a falling one the same gains turn to losses, as the March 2026 quarter showed. The core fee profit converts to cash very well.
Where the cash went
Free cash flow was about ₹2,507 crore.1 Dividends paid in the year were ₹1,925 crore, about 67% of profit.1 The board recommended a final dividend of ₹54 a share for FY26, against ₹45 a share, bonus-adjusted, for FY25.1 Measured on the dividend declared rather than cash paid in the year, the payout is about 81%.1
What isn't paid out goes into the treasury book. That book grew from about ₹8,289 crore to ₹9,396 crore in FY26.1 Uncalled commitments on partly paid investments, mostly to alternative investment funds, rose to ₹456.90 crore from ₹321.62 crore.1 Some of this is seed capital and regulatory "skin in the game" that SEBI requires fund houses to keep in their own schemes. Some is surplus that has nowhere else to go.
An activist would ask why a company with no capital needs keeps a book roughly as large as its equity. The answer is part regulation, part caution, part optionality. The cost is that a large part of the balance sheet earns a market return, not a 30% return on equity, and makes reported earnings noisier. The breakdown between own-fund equity, debt and AIF holdings is in Note 7 of the annual report, and the most useful thing an investor can do is read it.1
The rest of the balance sheet
There is no debt. The "borrowings" in some data series are lease liabilities on office premises; finance costs of ₹13.27 crore are the interest unwinding on those leases.1 Trade receivables were ₹158 crore, about 14 days of revenue, mostly owed by the funds themselves.1 A decade ago receivables were 78 days of revenue.1
Capital allocation record
There is not much of one, and that is the point. The 2003 Zurich deal remains the only meaningful acquisition. There is no recent deal to judge. The international subsidiary in GIFT City and the alternatives business are small: the AMC's own fees-and-commission expense for PMS and AIF products, ₹5.91 crore, gives a sense of scale.1 The company's choice has been to pay out most of its cash and keep the rest invested. That is disciplined in the sense of avoiding empire-building, and passive in the sense of carrying a large market-linked book.
The verdict: cash conversion is healthy, the payout is generous, and the gap between profit and cash is the treasury. Which brings the story to what can go wrong, starting with the market itself.
X. Risk Radar
Imagine a bad morning. Indian equities fall 25% over a few weeks, as they have before. For HDFC AMC, the damage is immediate and mechanical. Equity AUM falls about the same amount. Fees, accrued daily on that AUM, fall with it. Then the treasury book marks down, and other income turns negative. The stock, which already fell 43% at its worst over the last five years and has one-year volatility of about 32%, falls further.9 Nothing about the franchise changed; the meter just ran slower.
Market level
This is the first and largest risk, and it is not avoidable. Fees are a percentage of market value. The cushion is the SIP habit: monthly flows that keep arriving even in falling markets, buying more units at lower prices. If SIPs hold, AUM recovers faster than prices. If investors stop SIPs and redeem in a long bear market, as they did in earlier cycles, AUM and revenue fall together. SIP persistence through the next downturn is the real test of how much of India's savings shift is habit and how much is momentum.
Regulatory fee caps
The second risk is the regulator. SEBI has reviewed expense ratios repeatedly and cut them in 2018.7 A further cut, or a change in how fees may be split between AMC and distributor, would hit the fee line across the whole fund family at once. Because 99.6% of revenue comes from one fund family, there is nowhere to hide. Separately, SEBI's March 2026 circular and May 2026 consultation on intraday borrowing by schemes concern HDFC Mutual Fund's liquidity management, not the AMC's balance sheet. ICRA reaffirmed its [ICRA]A1+ rating on ₹25,000 crore of the fund's intraday bank facilities in June 2026, and flagged the new rules as a constraint.3
Mix shift to passive
The third risk is slow and structural. Every rupee that moves from an active equity fund to an index fund or ETF earns a fraction of the fee. HDFC can capture some of that flow with its own passive products, but at a far lower yield.
Second-order risks
Cybersecurity and operational error matter in a business where 97% of transactions are digital and fee rates are entered manually across many schemes, as the auditor noted.1 And key-person risk has changed shape: the 2022 transition showed the franchise survives one departure, but a team-run process depends on keeping the team.
The verdict: three risks hit the economics directly: market level, regulatory caps and passive mix shift. The rest are second-order. All three act on the same line: revenue as basis points of AUM.
XI. Playbook: Lessons From the Toll Road
Own the customer's habit, not the customer's choice. The software tester in Pune does not choose HDFC every month. She chose once, and the auto-debit chooses for her. HDFC's richest asset is not a fund's performance in any given year, but millions of standing instructions that run without a decision. For founders, the lesson is that a recurring default beats a repeated sale. For investors, it is that the habit is the asset to value, and a downturn is when it is tested. A SIP is a decision made once and paid forever.
A brand is a licence you pay your parent for. In 1999, the HDFC name was the only reason a latecomer could charge a fee next to UTI. In 2026, the AMC still pays rent on that name, and the rent grows a little faster than revenue. The lesson for minority shareholders in any group company: the most valuable asset may not be on your balance sheet, and its price is set by the controlling shareholder. At HDFC AMC, trust is the product, and the product is leased.
When the star leaves, count the AUM, not the headlines. In 2022, the market braced for an exodus that did not come. The assets stayed, and the share of active equity held. The lesson is to test key-person risk with numbers: share, flows and mix, before and after. A franchise is what is left when the famous name walks out the door.
When someone else sets your price, volume and mix are your only levers. SEBI cut expense ratios in 2018 and may do so again. HDFC cannot raise prices; it can only win more equity rupees and run them more cheaply. That makes the business a superb compounder in a rising market and a price-taker forever. The best toll road in India still does not set its own toll.
XII. Bull vs. Bear and KPIs
Two analysts sit down with the Q1 FY27 result. Revenue up 13.6%. Profit up 12%, to about ₹837 crore. Operating margin 75.5%.21 One sees a pause in a long compounding run. The other sees the start of a fee squeeze that the multiple has not yet priced in. Both are reading the same numbers.
What the price assumes
At about 34 times trailing earnings, 23.5 times EV/EBITDA, almost 11 times book and a 2.3% dividend yield, HDFC AMC is priced as a high-quality compounder.49 The P/E sits just below its five-year median of 36.6 times. Profit has compounded at about 16.6% a year over five years and 19.6% over ten, and FY26 and Q1 FY27 growth sit at or below those rates.1 So the market is paying a near-normal multiple for growth that is currently below normal. That works only if growth re-accelerates with AUM and mix, or if the fee yield holds. The case rests on mix and yield, not AUM growth alone.
The closest listed peers, Nippon Life India AM, UTI AMC and Aditya Birla Sun Life AMC, can be compared on NSE and Screener.49 HDFC has generally traded at a premium to them, reflecting its higher equity mix and margins. The premium is the market's bet on the moat described in Section VI.
The bull case
India's savings shift is far from over. Mutual fund AUM is still small relative to GDP and to bank deposits, and SIP flows grow even in choppy markets.8 HDFC is positioned in the richest segment: its equity mix of 65.7% is well above the industry's, and retail investors are 69% of its AUM.1 It needs no capital, pays out most of its profit and has survived both a star's departure and a fee cut. If AUM compounds in the high teens and operating margin per rupee of AUM holds near its corridor, earnings compound near the long-run rate and the multiple is justified.
The bear case
Fees already trail AUM. Costs, led by employees and stock-based pay, are growing faster than revenue.1 Treasury income makes reported profit swing with the market. SEBI may cut fees again. Revenue depends on one fund family, so one regulatory change hits all of it. Passive products erode the richest pool slowly. And the stock has fallen 43% at its worst in the last five years, which shows what happens when the market starts to doubt the growth.9
Myth versus reality
Myth: HDFC AMC is India's largest fund house. Reality: by total AUM, SBI Funds Management is larger; HDFC's leadership is in active equity, where it holds 12.8%.81 Myth: FY25 earnings fell sharply. Reality: the bonus issue doubled the share count; profit rose. Myth: the business is pure fee income. Reality: about an eighth of pre-tax profit comes from the treasury book.
The KPIs that matter
First, fee yield: revenue from operations as basis points of average AUM. The latest reading is that fees grew 17.84% against average AUM growth of 19.05% in FY26, so the yield is easing.1 Its direction tells the investor whether SEBI, passive products and direct plans are winning against mix.
Second, active equity share of industry QAAUM, now 12.8%.1 It is the best single test of the moat: brand, distribution and performance all show up there. Pair it with operating margin in basis points of AUM as the cost cross-check: if share holds while margin per rupee falls, costs are the issue; if both fall, the franchise is.
These two numbers answer most of the four central questions together. Everything else is noise or follows from them.
XIII. Epilogue: What Decides It Next
Tonight, 6 October 2026, HDFC AMC stands at about ₹2,354 a share, almost 19% below its 52-week high.4 The fund house manages over ₹9 lakh crore. Its SIP book keeps growing. Its fee rate keeps easing. Its costs keep rising a little faster than revenue. And its market value is about ₹1 lakh crore, a figure that already assumes the toll road keeps running.
The next few months bring a series of moments that will settle the central questions.
The first is the Q2 FY27 result in the coming weeks. If profit growth stays near 12%, the slowdown is real. If it re-accelerates with AUM, the June quarter was a pause. More important than the headline is the gap between revenue growth and average AUM growth. If revenue keeps trailing AUM by more than a point or two, the fee yield is sliding faster than scale can offset.
The second is SEBI's review of expense ratios. A mild outcome would remove the largest overhang on the stock. A sharp cut would test, for the second time in a decade, how fast HDFC can rebuild margin through scale. In 2018 it took the company several years and a bull market.
The third is the next down-market quarter. The March 2026 quarter showed what treasury income can do to reported profit in a small wobble. A real drawdown will show how much of earnings moves with the book, and whether the SIP habit holds when the screen turns red.
The fourth is quieter: the FY27 AGM votes on pay and related-party items, and the trademark fee as a share of revenue. They will show whether the parent's take and management's pay are stable, or creeping.
The tension that remains is the one that has defined the company since 2018. HDFC AMC is a wonderful business: high margin, no capital needs, a growing market and a trusted name. But the price it charges is set by a regulator, the brand it uses is owned by its parent, and the money it manages belongs to someone else. It owns the toll booth, not the road, not the toll and not the cars.
XIV. Outro
Back to that phone in Pune, on the first working day of the month. A few thousand rupees leave a salary account and buy units in an HDFC equity fund. The investor will not think about it again for years. She will not compare fee rates, read a fact sheet or watch the CIO's interviews. Somewhere in that transaction, a sliver of a percent a year will flow to HDFC AMC, every day, for as long as she stays.
Multiply that by millions of people and twenty years, and that is the whole business. It is the most boring and most powerful idea in Indian finance. HDFC AMC does not make the money; it gets paid a basis point at a time for holding other people's patience.
References
-
27th Annual Report 2025-26 — HDFC Asset Management Company, hosted by HDFC Bank, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
HDFC AMC corporate announcements, results and shareholding pattern — NSE ↩↩↩↩↩↩↩↩
-
HDFC Mutual Fund — Investor relations and disclosures, HDFC AMC ↩↩
-
HDFC AMC IPO prospectus (RHP, July 2018) — SEBI offer documents ↩↩↩
-
SEBI circulars on mutual fund expense ratios and intraday borrowing — SEBI ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube