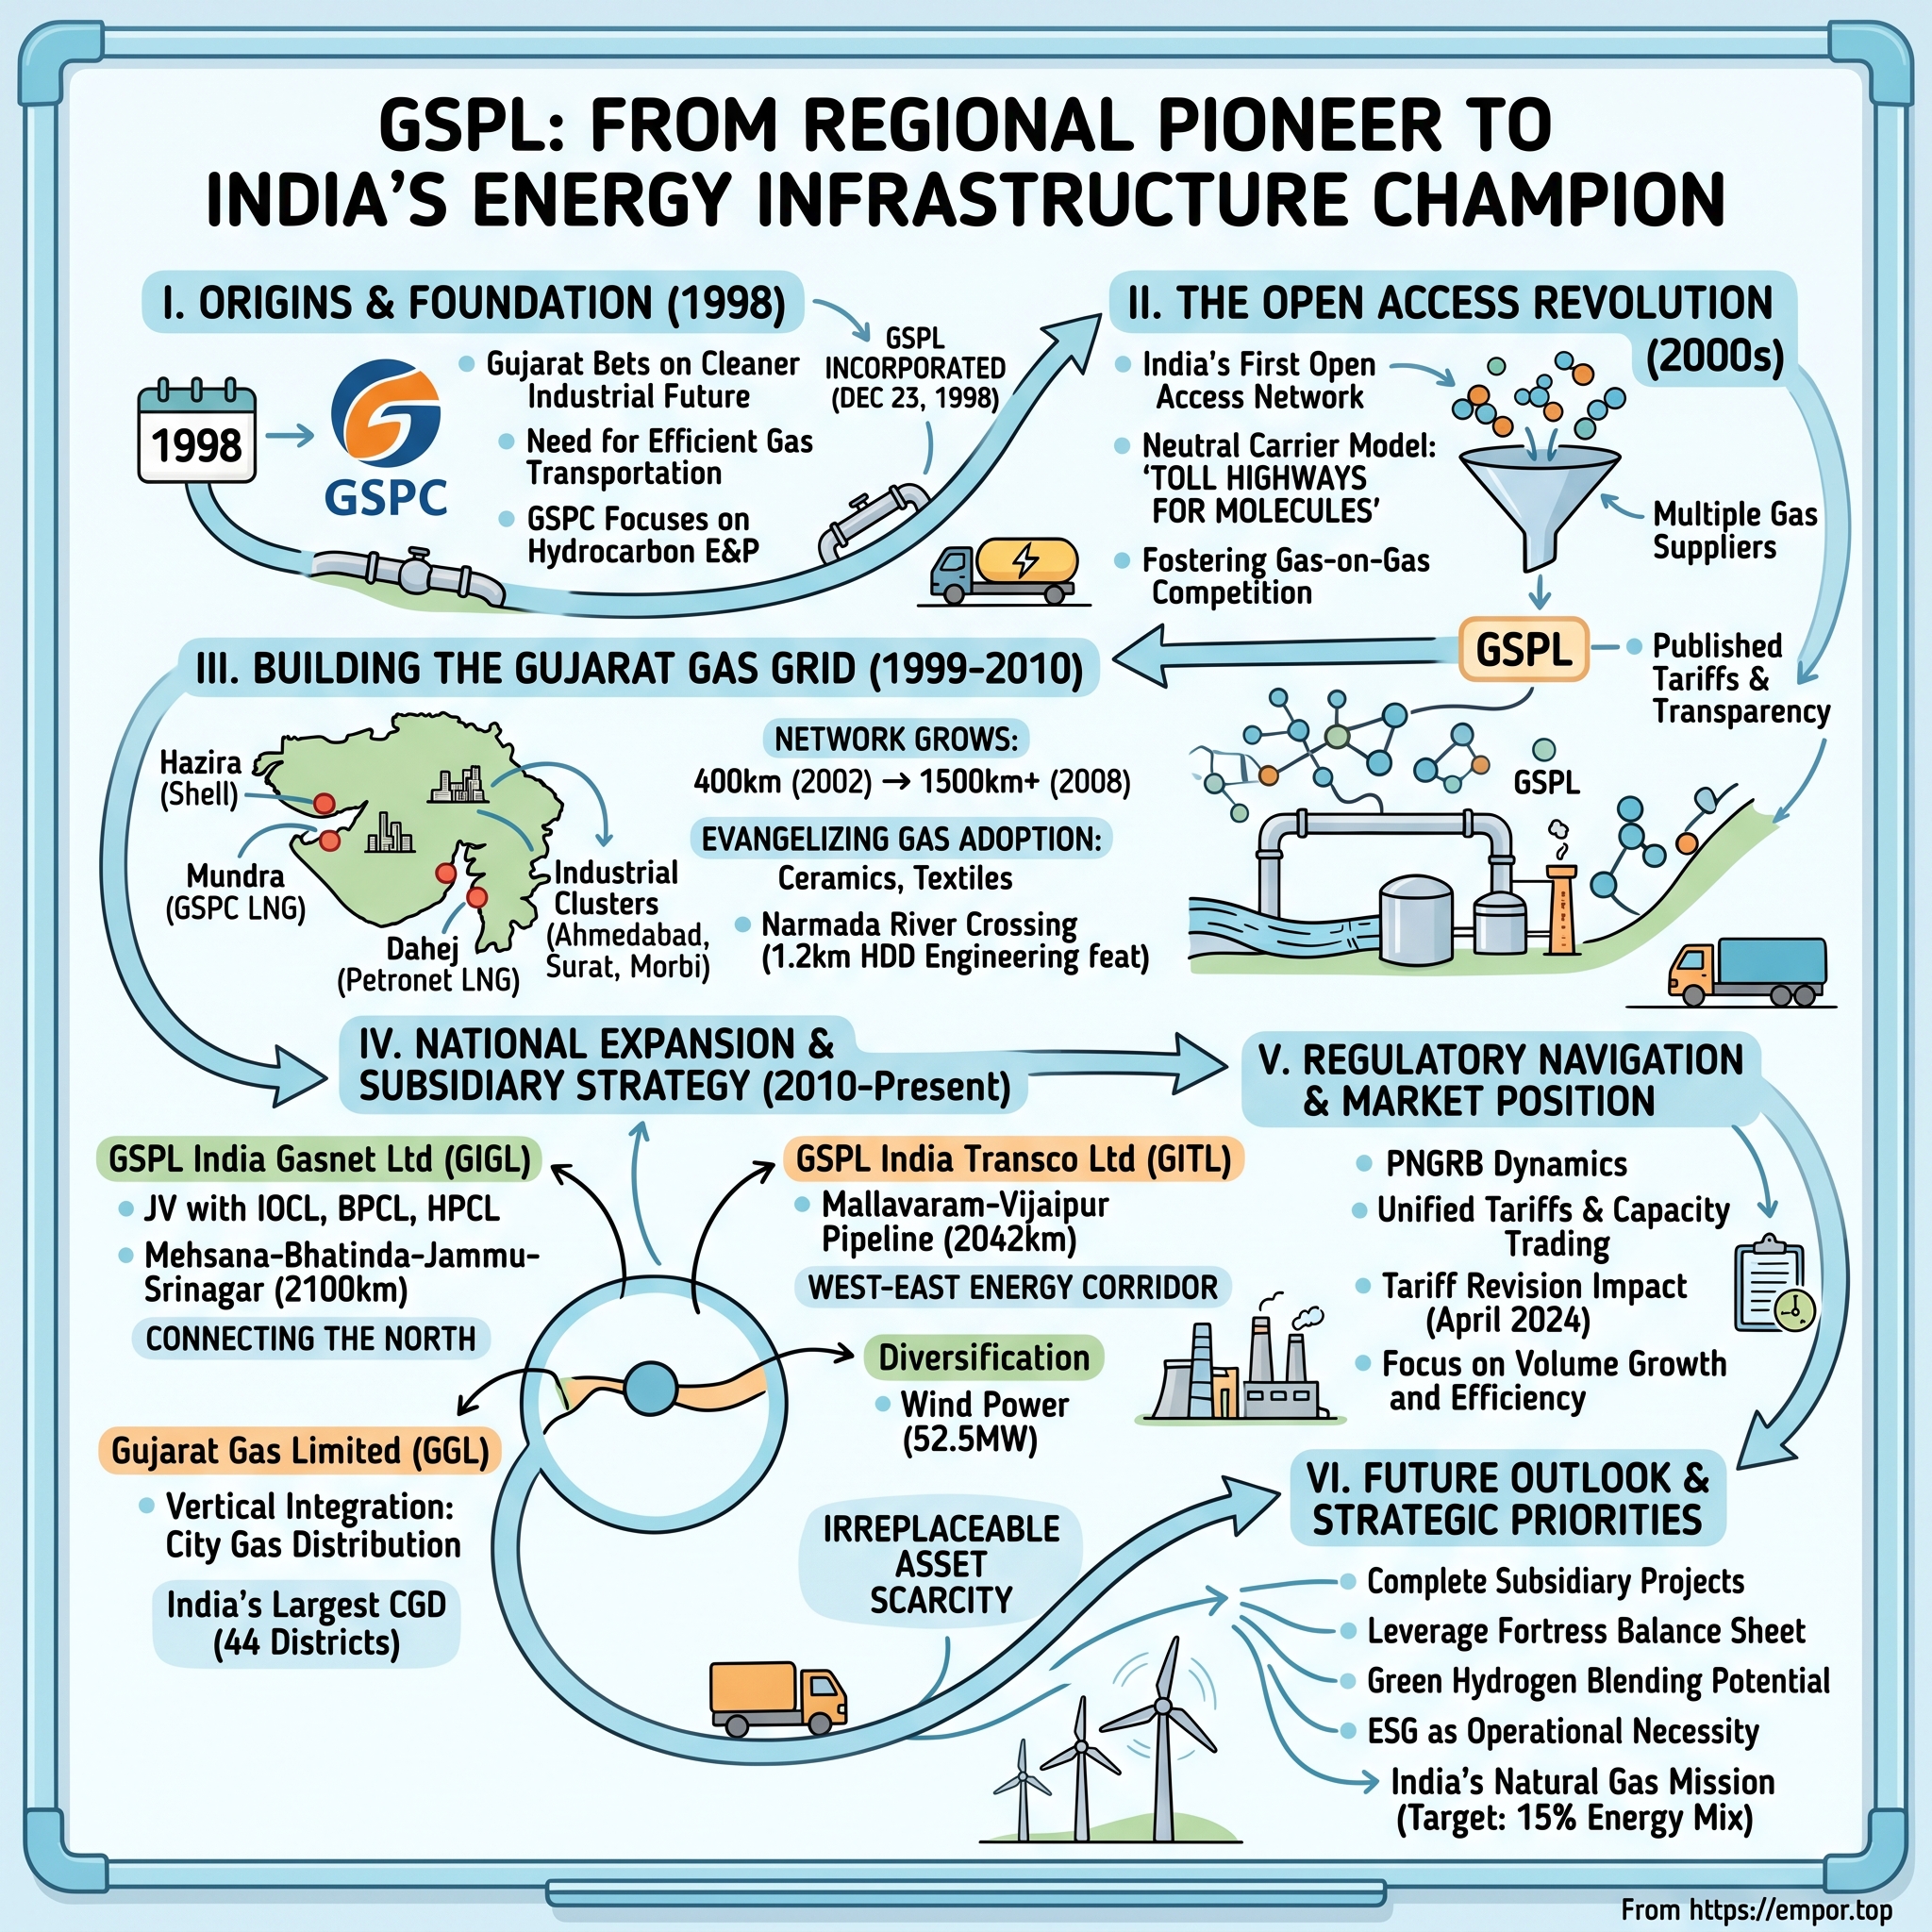
Gujarat State Petronet: The Steel Grid, The Tariff Shock, and The Great Unbundling
I. Introduction & The Tollbooth Paradox
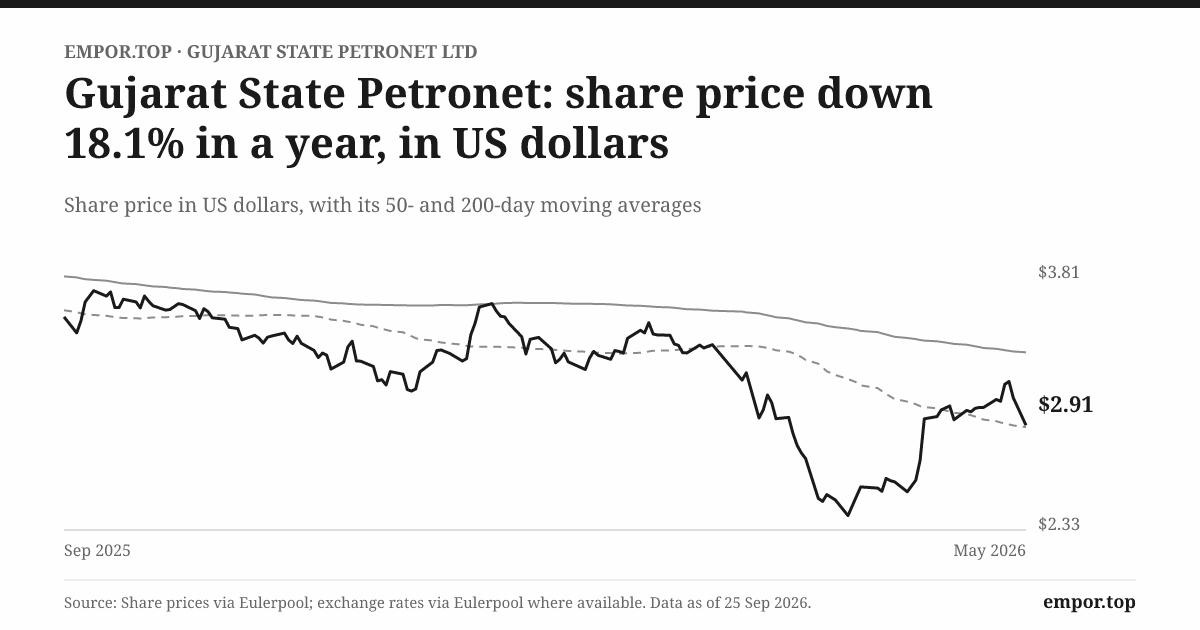
On the morning of Monday, April 22, 2024, sell orders for Gujarat State Petronet piled up before the market could find its footing. By 9:23 a.m. the stock was locked at its 20% lower circuit at ₹302.30 on the BSE, with pending sell orders for 4.57 million shares that could not find a buyer.1 Nothing had exploded. No pipeline had ruptured. No customer had defaulted. Over the weekend, three members of a regulatory board in New Delhi had signed a 94-page document, dated Saturday, April 20, that rewrote the economics of a 2,000-plus kilometre steel network in Gujarat.2
That document, a tariff order from the Petroleum and Natural Gas Regulatory Board (PNGRB), slashed the levelized transmission tariff on GSPL's High-Pressure Gas Grid to ₹18.10 per million British thermal units, effective May 1, 2024.2 The provisional tariff had stood at ₹34.00, and GSPL had requested ₹50.77.1 The utility had entered the review seeking a rate increase and emerged with its tariff cut nearly in half. With roughly 564 million shares outstanding, the single-day collapse erased roughly ₹4,000 crore in market capitalisation,3 an amount equal to nearly three years of the pipeline's FY24 operating profit of ₹1,504 crore.4
Four months later came a second shock, delivered by the owner rather than the regulator. On August 30, 2024, the boards of the GSPC Group companies approved a composite restructuring scheme to merge Gujarat State Petroleum Corporation (GSPC), GSPL, and GSPC Energy into Gujarat Gas Limited (GGL), while carving out GSPL's gas transmission business into a newly listed pure-play entity, GSPL Transmission Limited (GTL).5 The scheme took effect on May 1, 2026. On that date, Gujarat State Petronet, listed on the NSE under the ticker GSPL since 2006, ceased to exist.6
This is the story of a company that no longer exists in its historical form, and that is precisely why it warrants close examination. The pipeline network, now spanning roughly 2,878 km according to GTL's own disclosures, operates inside GTL.7 The cash, the gas trading desk, the city gas distribution franchise, and the legacy holding-company structure now reside inside Gujarat Energy. Investors who held GSPL now own shares in both entities, requiring a clear understanding of where the operational and regulatory risks landed.
The Paradox at the Centre
Gujarat serves as the primary gateway for India's natural gas imports. It remains the country's largest gas-consuming state, accounting for about 40% of domestic consumption, and GSPL constructed the grid linking Gujarat's LNG import terminals and offshore landfall points to its refineries, fertilizer plants, power stations, and city gas networks.4 On paper, the asset represented a classic toll road: a physical monopoly, regulated returns, and captive customers with no viable alternate routing. In practice, investors who underwrote that thesis encountered three structural vulnerabilities over the ensuing five years.
First, a regulator that sets guaranteed returns can also take them away. Second, a state-owned parent entity can deploy a listed subsidiary's balance sheet for group-level objectives. Third, a physical monopoly over pipelines does not confer a monopoly over energy demand: when imported LNG became cost-prohibitive, ceramic kiln operators in Morbi switched to propane, taking their volumes with them.
The Questions That Drive This Story
Three central questions govern this analysis. Can an infrastructure asset sustain a durable economic moat when an independent regulator can unilaterally reset its return profile? How did a regional pipeline utility evolve into the holding company of India's largest city gas distributor, and why did it require a complex restructuring to eliminate a persistent 50% to 60% holding-company discount?8 Finally, what are regulated infrastructure returns worth when anchor industrial customers can switch to alternate fuels within a single price cycle?
The narrative tracks Gujarat's industrial expansion from the late 1990s through the creation of the open-access grid, the bailout of an over-leveraged parent, the protracted execution hurdles of two interstate pipelines, the 2024 tariff reduction, and the eventual unbundling, culminating in 2026 as conflict in the Persian Gulf upended the economics of industrial propane.
 Subscribe on LinkedIn
II. Origins: Gujarat's "Gas Capital" Vision & The GSPC Ecosystem (1998–2005)
Picture the western coast of Gujarat in the late 1990s. The Hazira–Dahej–Vadodara–Ahmedabad belt was already crowded with petrochemical plants, fertilizer complexes, textile mills and steel furnaces, many of them burning naphtha, fuel oil or coal because gas was hard to come by. The one great national gas artery, GAIL's Hazira–Vijaipur–Jagdishpur line, carried gas allocated by New Delhi, mostly to federal priorities such as fertilizer and power. A mid-sized dyeing unit in Ahmedabad or a tile maker in Saurashtra was, in effect, at the back of the queue.
The Gujarat government's answer was to stop waiting. GSPC, its energy arm, had been incorporated by the state in 1979 as a petrochemical corporation and had moved into energy resources from 1994.5 On December 23, 1998, it incorporated a separate company to build pipelines: Gujarat State Petronet Limited.9 The first gas flowed in November 2000, through a short Hazira–Mora segment of about 14 km.9
The Strategic Bet: Own the Gate, Not the Gas
The founding logic was geographic. Gujarat has the coastline for deepwater ports and LNG regasification terminals, at Dahej and Hazira and later Mundra. Whoever controlled the high-pressure pipes that carried regasified LNG inland would sit at the gate of India's imported gas. The grid expanded in steps: Amboli–Dahej by 2001–02, Paguthan–Baroda by 2003–04, and the Baroda–Ahmedabad–Kalol line and a Gandhinagar spur by 2004–05, when the network reached about 448 km.9
The more interesting choice was the business model. GAIL at the time bought gas, transported it and sold it, all within one company. That arrangement tends to create a conflict of interest: a pipeline owner that also sells gas has an incentive to favour its own molecules. GSPL was set up as a pure open-access transporter. It does not buy or sell gas; it charges a tariff for moving other people's gas through its pipes.4 That removes commodity-price risk from the income statement. As later sections show, it does not remove commodity-price risk from volumes.
Going Public
Pipelines are expensive to build, and the state wanted outside capital. GSPL's initial public offering ran from January 24 to 28, 2006, at ₹27 per share, raising ₹372.60 crore through a fresh issue. It was subscribed 48.41 times and listed on February 16, 2006, at around ₹40, roughly 49% above the issue price.10 Investors were paying for a clear idea: a regulated monopoly connecting India's gas entry points to its most industrialized state, with no commodity exposure.
The Bureaucratic Matrix
GSPL was never a founder-led company. It is a government company controlled through GSPC, whose Articles give it the right to appoint a majority of GSPL's directors.4 Its leadership came from the Indian Administrative Service. The FY2023-24 annual report shows how far that went: Raj Kumar, IAS, served as GSPL's Chairman & Managing Director while also serving as the 31st Chief Secretary of the Government of Gujarat, the state's top civil servant, from January 31, 2023. He drew no remuneration from GSPL.11 Milind Torawane, IAS, was Joint Managing Director from April 10, 2023.11 When Raj Kumar retired as Chief Secretary on January 31, 2025, the post passed to another IAS officer, Pankaj Joshi, who was appointed Chairman & MD from February 7, 2025.12
For investors this governance model has a practical consequence. The people running the company are able, often well-regarded administrators, but their careers, incentives and loyalties run to the state government, not to the share price. There were no founder stakes and no stock-option pools. That did not matter much while GSPL was simply building pipes in Gujarat. It mattered a great deal once the state needed the company's balance sheet for something else, which is where the story goes after the grid was built.
III. Building the Gujarat Gas Grid: The High-Pressure Iron Moat (2005–2015)
A high-pressure gas pipeline is mostly invisible. An observer driving through rural Gujarat might spot only a yellow marker post at the edge of a cotton field, a fenced valve station beside a highway, or a compressor station humming near an industrial estate. Buried underground, carbon-steel pipe up to 30-odd inches in diameter moves gas at pressures far exceeding that of a car tyre across hundreds of kilometres, monitored from a central control room. From its 2006 IPO proceeds onward, GSPL spent a decade laying that system across Gujarat.
By 2024, the operational grid stretched across roughly 2,706 km.5 By September 30, 2025, it reached about 2,795 km, serving 25 of Gujarat's 33 districts,4 and disclosures from GTL placed the network at approximately 2,878 km as of March 31, 2026.7 The grid connects to gas collection points near the Hazira fields, Shell's Hazira LNG terminal, Petronet LNG's Dahej terminal, GSPC LNG's Mundra terminal, and newer entry points at Swan Energy's floating terminal and the Chhara LNG terminal.4 Supply also arrives from third-party networks: PNGRB's 2024 tariff order noted that significant volumes of Reliance–BP's KG-D6 gas enter GSPL's network at Bhadbhut via Pipeline Infrastructure Limited (PIL), the operator of the East–West pipeline.2
Crucially, the grid is bi-directional, allowing gas to flow in either direction across most of the network depending on which terminal or field is supplying and which industrial cluster is consuming.5 That operational flexibility means that when Dahej runs near peak capacity while Mundra is quiet, or when domestic KG-D6 volumes displace imported LNG, the operator can reroute flows without laying new pipe. Incremental capacity now comes through targeted debottlenecking rather than expensive trunk lines. PNGRB's capacity study, for instance, credited a compressor installation at Gana with adding 0.4 million standard cubic metres per day (MMSCMD) to system capacity, while tie-ins at the Swan terminal and Chhara added 0.4 MMSCMD and 0.8 MMSCMD, respectively.2 Measured against a network handling roughly 30 MMSCMD, those incremental gains underscored that network expansion had shifted from greenfield trunk lines to targeted interconnects.
How the Moat Works, in Plain Terms
Consider the economics of a city's municipal water mains. A competitor rarely lays a parallel set of pipes down the same street, because the existing network already satisfies demand and the upfront cost of digging up the road is prohibitive. GSPL's transmission business operated on the same logic, anchored by three competitive advantages.
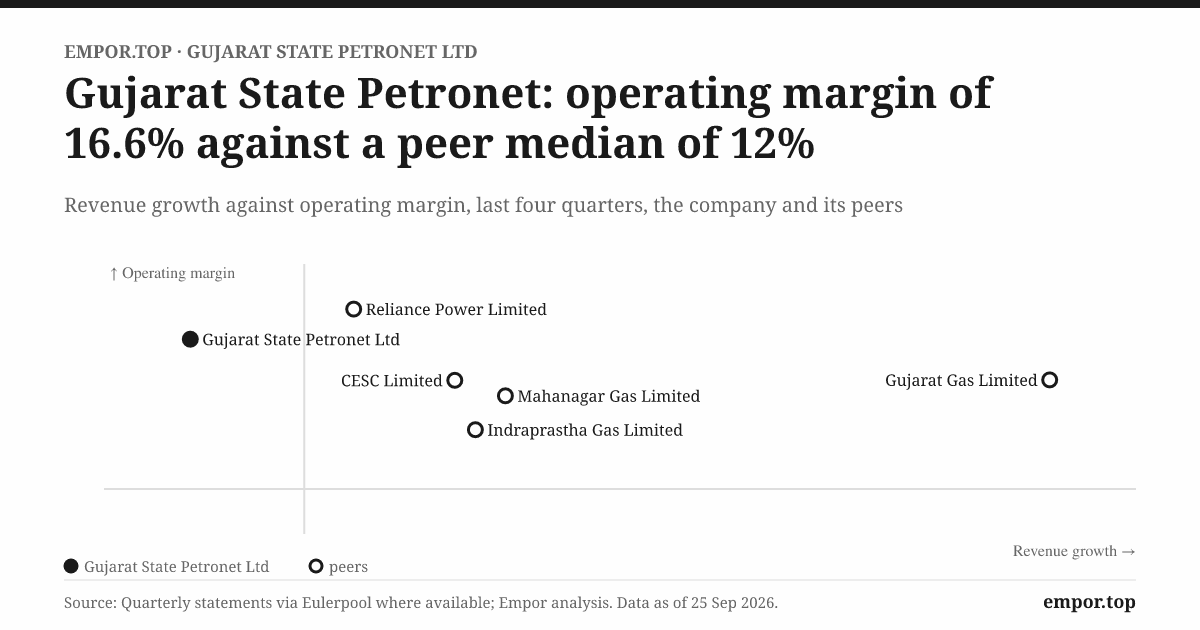
First came high upfront capital expenditure and low variable costs. The heavy spending went into steel, trenching, compression stations, and Supervisory Control and Data Acquisition (SCADA) monitoring systems. Once the pipes were underground, the marginal cost of moving an additional unit of gas was negligible. Credit rating agency CARE highlighted the resulting financial profile: the pipeline business maintained an operating margin (PBILDT) of 73% even in FY25, the very fiscal year its tariff was slashed.4
Second came right of use. Laying high-pressure pipe demands a contiguous corridor across private farmland, river crossings, railway tracks, and dense industrial estates. Securing those easements is slow, politically sensitive work. Within Gujarat, GSPL enjoyed the administrative weight of the state government. Outside Gujarat, as later interstate ventures demonstrated, acquiring right of use proved far more difficult.
Third came statutory exclusivity. Under Indian regulations, pipeline developers must win exclusive authorizations through a formal PNGRB bidding process designed to prevent duplicate infrastructure.4 The regulator effectively protected the franchise from competition, but that protection came with an inescapable trade-off: the authority that safeguards the monopoly also caps its toll.
Contracts and Customers
GSPL executed gas transmission agreements ranging in tenure from a single month to more than 15 years. Most of these contracts featured "ship-or-pay" provisions requiring off-takers to pay for approximately 90% of contracted capacity regardless of whether they nominated actual gas volumes.4 As of September 30, 2025, contracted volumes stood at 41.84 MMSCMD, moderating from 44.48 MMSCMD in August 2024.4 While ship-or-pay terms provided downside protection, the revenue shield was narrower than the phrase "infrastructure annuity" implied. A substantial portion of the volume was tied to short-tenure agreements, leading CARE Ratings to cite "past experience" of periodic renewals rather than long-term contractual lock-ins as the basis for volume stability.4
The customer profile also underwent a fundamental shift. During the network's early years, anchor demand came from power and fertilizer plants, whose off-take fluctuated with government subsidy allocations and international feedstock prices. Over time, city gas distribution (CGD) emerged as the grid's primary volume driver. By the first quarter of FY26, CGD networks accounted for 10.8 MMSCMD of GSPL's total throughput of 29.7 MMSCMD, followed by refineries and petrochemical plants at 6.3 MMSCMD, power utilities at 3.8 MMSCMD, and fertilizer complexes at 3.4 MMSCMD.3 One CGD customer in particular—Gujarat Gas—would ultimately transform GSPL's corporate destiny.
A Footnote in Wind
Alongside its pipeline footprint, GSPL installed 52.5 megawatts of wind generation capacity across Gujarat's Rajkot and Porbandar districts, underpinned by long-term power purchase agreements with state power distributor GUVNL.45 In FY25, those wind installations produced roughly 86.5 million kilowatt-hours of electricity.4 At prevailing feed-in tariffs, wind power generated only a nominal sliver of overall group revenue. It served as a state-sponsored renewable energy obligation rather than a core strategic pivot, having virtually no bearing on the underlying investment thesis.
By 2015, the core intrastate steel network was largely complete. The pivotal questions confronting management shifted from engineering to capital allocation: how to deploy the cash flow throwing off from the grid, and whose interests that capital would ultimately serve.
IV. Capital Allocation Twists: The 2012 BG Deal, The 2018 GSPC Bailout, & The Holdco Trap
In October 2012, a statement from the GSPC Group quoted its managing director, Tapan Ray: "We are pleased to announce this acquisition that enhances GSPC group's presence in the state of Gujarat."13 The acquisition was BG Group's 65.12% controlling stake in Gujarat Gas Company Limited, India's oldest private city gas distributor, which had laid its first piped-gas connection in Ankleshwar in 1989.5 The buyer was an unlisted GSPC Group entity, Gujarat Distribution Networks Ltd, paying ₹295 a share, or ₹2,463.8 crore.13
Inflection Point 1: Buying the Retail End
Following the block purchase, GSPC launched a mandatory open offer for an additional 26% of Gujarat Gas at ₹314.17 a share.14
The transaction price stood out because it priced below the prevailing market quote. Gujarat Gas had closed at ₹336.70 the previous trading day, and the stock fell 11.6% intraday once the ₹295 deal price became public.14 Analysts interpreted the discount as evidence that BG Group had grown wary of regulatory pressure on city gas marketing margins.14 The first major capital-allocation inflection point was therefore rooted in regulatory risk: an experienced multinational chose to exit Indian gas distribution partly due to PNGRB oversight. For GSPC, the transaction linked its gas trading and transmission assets directly to an established retail network. In 2015, the group merged GSPC Gas and the acquired company into a single unified entity, Gujarat Gas Limited.5
The KG Basin Hole
GSPC's other flagship venture proved disastrous. During the 2000s, the state promoter announced major deepwater gas discoveries in Krishna-Godavari offshore block KG-OSN-2001/3, borrowing aggressively to develop the high-pressure, high-temperature Deen Dayal West field. Trial production commenced in 2014, followed by commercial production in April 2016, yet the reservoir never yielded the prolific volumes promised in early announcements. By March 31, 2015, GSPC's debt had escalated to ₹19,716 crore, and against an approved field development budget of $2.75 billion, cumulative spending had already reached $2.83 billion.15 It became a textbook case of a geological discovery failing to translate into commercial viability—and it created the financial overhang that shaped everything GSPL's minority shareholders subsequently endured. In August 2017, state-owned ONGC completed the acquisition of GSPC's 80% participating interest for ₹7,738 crore.15 While substantial, that cash infusion addressed only part of a liabilities burden that analysts estimated at roughly ₹13,000 crore even after the sale.16
Inflection Point 2: The 2018 Inter-Se Transfer
At this juncture, the parent's distress directly reached GSPL's minority shareholders. On March 19, 2018, GSPL's board approved the acquisition of up to a 28.4% stake in Gujarat Gas from GSPC through an inter-se promoter transfer.17 GSPL already held 25.8%.16 Management framed the transaction around operational synergies, noting that city gas was one of GSPL's primary customer segments, that Gujarat accounted for roughly a third of national gas consumption, and that direct ownership would "facilitate better synchronization" across networks while enabling "faster roll-out of CGD networks on the strength of stronger balance sheet."17 The transaction was executed through secondary block trades during the final week of March 2018—including a 10.49% block at ₹836.25 per share on March 28—leaving GSPL with a 54.2% majority stake and turning Gujarat Gas into its consolidated subsidiary.9 Based on prevailing market quotes, the equity transfer was valued at approximately ₹3,300 crore.16
Public equity markets delivered an immediate verdict: GSPL's shares fell 6% following the announcement.17 Nomura projected that GSPL would need at least ₹2,500 crore in fresh borrowings to fund the transaction, swinging its balance sheet from net cash into net debt, while ICICI Securities calculated that an entirely debt-funded buyout could reduce FY19 earnings by 18%.16 More fundamentally, Nomura articulated the governance overhang that troubled institutional investors: if GSPL's cash flows were repeatedly harnessed to shore up its parent, the subsidiary's own equity profile would deteriorate.16
Testing the "Synergy" Claim
The strategic rationale had superficial merit: an open-access transmission spine and an urban distribution grid are natural commercial partners. Yet the transaction structure pointed toward a different primary objective. The seller was an unlisted parent company burdened by debt from exploration losses; the buyer was a publicly listed subsidiary endowed with a clean balance sheet and substantial cash generation. GSPL paid market price with no competitive auction and received no control premium for absorbing group obligations. Crucially, the synergy justification never satisfactorily explained why GSPL needed equity ownership of the distributor rather than continuing its long-standing role as an open-access transporter. The record points instead to a state-directed reallocation of capital from a publicly traded utility to alleviate promoter debt, wrapped in the rhetoric of corporate strategy. The fact that the severe financial dilution feared by analysts largely failed to materialize—GSPL's standalone borrowings declined from ₹1,626 crore in FY20 to zero by FY23—mitigated the economic damage, but it did not alter whose interests the transaction had served.5
The Holding-Company Trap, 2018–2024
After 2018, GSPL's consolidated financial statements were dominated by Gujarat Gas, a retail gas distributor generating annual revenues of ₹16,000 crore to ₹17,400 crore between FY22 and FY24, with EBITDA margins hovering between 12% and 14%.5 Standalone transmission, by contrast, delivered roughly ₹1,500 crore in operating profit on revenue of ₹2,032 crore in FY24.4 Two fundamentally distinct operations—a capital-intensive, regulated toll road and a margin-sensitive, commodity-exposed retailer—were blended into a single consolidated income statement.
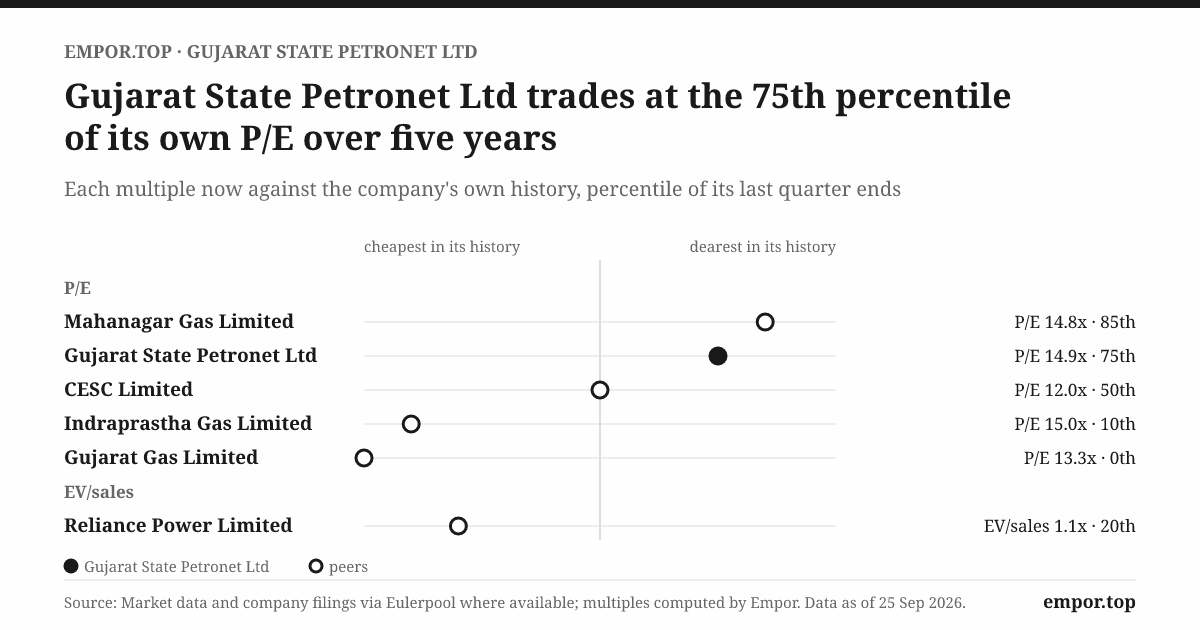
Equity markets responded by imposing a severe holding-company discount. Brokerages including JM Financial routinely marked down GSPL's equity holding in Gujarat Gas by 50% to 60%.8 The GSPC Group's own restructuring presentation acknowledged the penalty directly, conceding that "GSPL's growth [was] not fully reflected in its valuation due to holding company discount."5 Market pricing on August 29, 2024, the eve of the restructuring announcement, laid bare the distortion: with Gujarat Gas capitalized at ₹41,531 crore, GSPL's 54.17% equity stake was worth roughly ₹22,500 crore on the screen. GSPL's total market capitalization stood at ₹23,657 crore.5 Backing out the listed stake implied that investors valued the entire 2,700-kilometre intrastate transmission monopoly at approximately ₹1,160 crore—less than a single year of its pre-cut operating cash flow. While that valuation reflected the April 2024 tariff shock, it nonetheless treated an indispensable state energy backbone as virtually worthless.
Sell-side sum-of-the-parts valuations illustrated the same structural suppression. As late as August 2025, JM Financial's target price for GSPL assigned ₹93 per share to the standalone pipeline, ₹225 to the Gujarat Gas stake (even after narrowing its modeled discount to 20%), and ₹22 to its 27.5% holding in Sabarmati Gas.3 Even under more constructive assumptions, the physical steel grid accounted for barely one-quarter of the company's estimated equity value.
The holding-company structure also constrained capital return. GSPL could not monetize or distribute value from its Gujarat Gas holding without diluting state control, an option the promoter would not entertain. Before the restructuring eventually dismantled the structure, however, GSPL attempted another avenue for capital deployment: expanding its pipeline footprint across state borders.
V. The National Expansion Quagmire: GIGL, GITL, and the Mirage of Interstate Pipelines
In July 2011, GSPL's ambitions extended well beyond Gujarat. PNGRB authorised two major interstate pipelines to GSPL-led consortia: a 2,012-kilometre line from Mehsana in north Gujarat to Bhatinda in Punjab and onward to Srinagar in Jammu and Kashmir, and the 1,881-kilometre Mallavaram–Bhopal–Bhilwara–Vijaipur pipeline, running from the Krishna-Godavari coast of Andhra Pradesh into central India.1819 Both ventures were owned 52% by GSPL, 26% by Indian Oil, 11% by BPCL, and 11% by HPCL.1819 Had both been completed as designed, GSPL would have established an interstate transmission network capable of rivaling GAIL.
The Claim
The investment case for GSPL India Gasnet (GIGL) and GSPL India Transco (GITL) centered on commercial optionality. The projects were designed to replicate GSPL's open-access model in high-demand industrial states, lift system-wide throughput, and elevate the utility from a regional network into a national gas transporter. Crucially, both authorizations were won through competitive bidding on fixed levelized tariffs over 20 to 25 years, rather than under PNGRB's traditional cost-plus model.1819 That contractual structure proved decisive: a fixed bid tariff protects the gas shipper rather than the builder when capital costs rise or nominated volumes fail to arrive.
What Actually Happened: GITL
GITL's pipeline was engineered to evacuate offshore gas from the KG basin, but that production never reached the projected scale. Of the 1,881 km authorised, GITL commissioned only phase I—a 364.42-km spur connecting to the Ramagundam fertilizer plant in Telangana on October 14, 2019—laying an 18-inch pipe instead of the contracted 42-inch pipe.19 CARE reports that GITL told PNGRB the rest of the project is "not viable due to low natural gas supply and demand," that the authorisation has not been surrendered, and that GITL and PNGRB are in several litigations over scope, missed schedules and the unilateral diameter reduction.19 In FY25, the truncated line moved just 2.08 MMSCMD for ₹87.52 crore of revenue, and throughput fell to about 1.02 MMSCMD in the first half of FY26 when the anchor fertilizer plant shut for repairs.4 A corridor conceived as a national trunk line now effectively operates as a single-customer feeder.
What Actually Happened: GIGL
GIGL progressed further, but at an agonizing pace. Its initial 442-km phase began operating in November 2018. Over subsequent reviews, the route's authorized scope was whittled down from about 2,012 km to 1,929 km and ultimately to 1,693.5 km, while the Srinagar leg was dropped.18 Sanctioned project costs were revised upward to ₹7,384 crore.18 On August 22, 2024, GIGL formally declared commercial operation on 1,417.8 km after descoping the unfinished pieces, and it surrendered ₹787 crore of unused sanctioned debt.18 Meanwhile, a key 130-km trunk section from Bhatinda to Jalandhar has had "no movement" because of right-of-way problems.18
Physical completion did not translate into commercial utilization. In FY25, GIGL carried an average of 3.7 MMSCMD against firm contractual commitments of 7.38 MMSCMD, leaving overall capacity utilisation below 10%.18 Revenue fell to ₹239.67 crore, and finance costs pushed the business to a net loss of ₹265.32 crore after interest, resulting in an interest coverage ratio of just 0.51 times.18 The sponsors put in about ₹81 crore in April 2025 to cover the shortfall, and GSPL expected to invest a further ₹200 crore of equity over two years.184 At March 31, 2025, GSPL's investments and loans in the two joint ventures equalled 14% of its net worth.4
The Verdict on the Optionality Claim
Fourteen years of execution evidence have dismantled the original optionality thesis. That national-expansion case rested on two premises: that upstream domestic gas supplies would arrive, and that GSPL's ability to secure land corridors in Gujarat could be replicated across northern and central states. The collapse in KG basin output disproved the resource assumption for GITL, while protracted right-of-way disputes in Punjab disproved the right-of-use assumption for GIGL. What survives is a much narrower reality: GIGL is a completed, lightly used pipeline that could become useful if north Indian refinery and fertilizer demand grows (CARE cites IOCL Panipat, HPCL-Mittal Energy and National Fertilizers as potential anchor loads).18 The key operating metric to watch is straightforward: does GIGL's actual throughput move from under 4 MMSCMD toward its contracted 7.7 MMSCMD?18 Until then, the interstate joint ventures are a drain on cash, not a growth engine.
Within Gujarat, however, network demand proved far less immune to fuel substitution than the "toll road" label implied, largely because of one town full of kilns.
VI. The Anchor Customer & The Fuel-Switching Vulnerability: Morbi & Spot LNG
A drive into Morbi, in Saurashtra, reveals a skyline dominated by factory chimneys. More than 1,000 plants manufacture ceramic and vitrified tiles for India, the Middle East, and Europe, collectively forming Asia's largest ceramics cluster.20 Their industrial tunnel kilns run continuously at temperatures exceeding 1,000 degrees Celsius, with fuel accounting for more than 30% of total production costs.20 Before 2022, the vast majority of that thermal energy came from natural gas delivered by Gujarat Gas and transported to the city gate through GSPL's high-pressure network. Morbi alone accounted for roughly 70% of Gujarat Gas's total industrial gas sales.20
The Claim
The initial investment thesis held that industrial gas demand in Gujarat would expand steadily, propelled by environmental mandates banning coal and petcoke, alongside national policy targets to lift natural gas from roughly 6% of India's primary energy basket toward 15%.5 Under that projection, transmission volumes across GSPL's pipeline grid were expected to rise continuously.
The 2022 Test
Russia's invasion of Ukraine in early 2022 delivered an abrupt test to that assumption by sending global spot LNG prices surging. By March 2022, Business Standard reported that Gujarat Gas was supplying Morbi with only 80% of contracted volumes at baseline rates, requiring factories to purchase any incremental fuel at spot prices between ₹150 and ₹160 per standard cubic metre, compared with an agreed baseline of ₹62.20 That spike followed an earlier price increase, as Morbi's industrial gas rates had already climbed from ₹32 to ₹58 per cubic metre six months earlier.20 "Several units will have to forego production and orders," warned K.G. Kundariya, chairman of the Win-tel Group.20
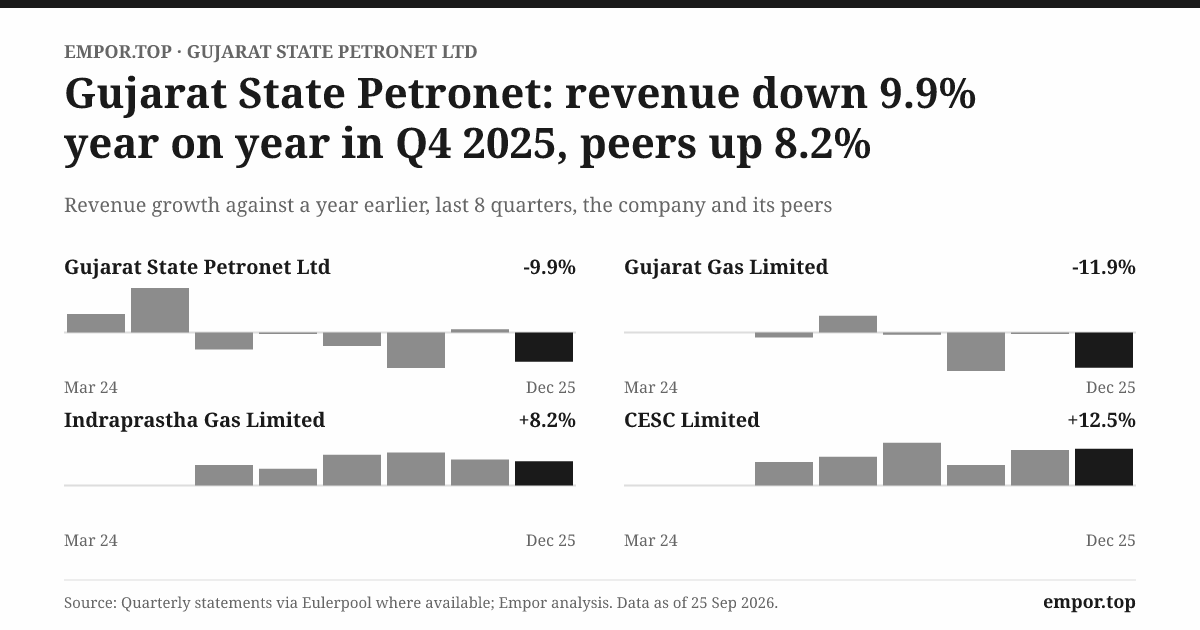
Rather than absorbing the prohibitive cost of imported LNG, dozens of ceramic manufacturers retrofitted their facilities with propane storage and vaporizers. The resulting demand destruction registered immediately across GSPL's pipeline system. Transmission throughput averaged roughly 38 MMSCMD in FY20 and 37 MMSCMD in FY21, slipped to 34 MMSCMD in FY22, and dropped to just 25 MMSCMD in FY23—a decline of about one-third from peak volumes—before clawing back to around 30 MMSCMD in FY24.5
The more revealing outcome emerged once international LNG prices cooled: the lost pipeline demand did not return. By February 2026, on the eve of the next geopolitical shock, a DeshGujarat report identified 377 Morbi units running on piped natural gas and 415 operating on propane, with propane supplying nearly 70% of the industrial cluster's aggregate fuel requirement of roughly 5.6 MMSCMD.21 Having incurred the upfront capital expenditure to install propane-handling infrastructure, factory owners faced minimal ongoing friction to toggle between feedstocks. Morbi's tile makers had effectively acquired a permanent dual-fuel option.
The 2026 Reversal
That dynamic reversed sharply when conflict in the Middle East disrupted maritime supply chains. On February 28, 2026, military strikes by the United States and Israel against targets in Iran severely disrupted commercial shipping through the Strait of Hormuz.22 Because India imports the vast majority of its propane and liquefied petroleum gas (LPG) from Gulf producers, the maritime bottleneck curtailed feedstock availability within days. By March 6, approximately 100 propane-dependent Morbi units had shut down, and the regional ceramics association warned that 400 more could follow.22 The energy crisis compounded on March 18, when retaliatory strikes damaged two liquefaction trains at Qatar's Ras Laffan complex; QatarEnergy indicated that repairs could take three to five years, taking about 17% of its export capacity offline.23 By mid-April, factory closures were so widespread that only 142 Morbi units were operating.21
Piped natural gas suddenly became the only fuel physically accessible to the cluster. On Gujarat Energy's June 1, 2026 earnings call, management reported that the number of Morbi units consuming gas had jumped from 83 plants (drawing about 0.36 MMSCMD) in March to 710 plants (drawing about 8 MMSCMD) by late May, even with prices hovering around ₹75 per cubic metre and despite the utility itself losing two scheduled LNG cargoes in May and June.24 The imported propane that had eroded pipeline throughput in 2022 was suddenly the fuel facing acute physical shortages.
What This Says About the Moat
From a competitive standpoint, the threat of substitute fuels poses a structural vulnerability for GSPL, and it operates symmetrically in both directions. GSPL maintains an indisputable physical monopoly over the steel pipeline grid traversing Gujarat, but it holds no monopoly over the thermal energy consumed in Morbi's kilns. Industrial throughput across the network responds directly to the price and availability spread between delivered LNG and imported propane. The 2022 episode disproved the thesis of secular, irreversible industrial gas growth. The 2026 supply crunch did not revive that thesis; rather, it demonstrated that transmission volumes simply track relative fuel economics and physical access wherever an external shock lands. For an open-access pipeline operator, fuel switching introduces commodity exposure that was never contemplated in the toll-road thesis: GSPL does not take commodity price risk on its balance sheet, but its capacity utilization remains entirely dependent on end users choosing gas. The decisive operational metric remains the landed price differential between delivered LNG and imported propane at Morbi—an indicator examined among the key operating metrics in Section X.
Volume volatility, however, represented only half of the challenge confronting the pipeline network. The other half was the regulated tariff charged per unit of gas moved—and in April 2024, the regulator intervened to reset it.
VII. The Regulatory Guillotine: PNGRB's 2024 Tariff Order & The Moat Broken
The April 2024 order is a dense, 94-page document packed with spreadsheet reconciliations, culminating near the end in a pivotal table.2 That schedule begins at GSPL's requested tariff of ₹50.77 per MMBTU and walks down, line by line, to ₹18.10. Examining that walk-down illustrates how a regulated pipeline tariff is constructed—and how rapidly it can be dismantled.
How a Pipeline Tariff Is Set
The PNGRB calculates pipeline tariffs using a discounted cash flow methodology. The regulator aggregates the pipeline's approved capital expenditure and operating expenses across its economic life, adds an allowed post-tax return of 12% (grossed up to a pre-tax 16.04% from FY23 onward), and divides that aggregate revenue requirement by the expected volume of gas.24 The output is a single "levelized" tariff per unit of energy moved. The mechanism functions much like a mortgage schedule: capital expenditure represents the principal, operating costs are running expenses, the allowed return serves as the interest rate, and the projected gas volume determines the number of units amortizing the pool. Adjust any single variable, and the required unit toll shifts accordingly.
For GSPL's High-Pressure grid, the PNGRB fixed the asset's economic life at 30 years starting November 3, 2001, establishing November 2, 2031 as the terminal date of the tariff model.2 That constrained window was critical: when the order took effect in 2024, it left roughly seven years to recover whatever capital the model still owed the utility—or to claw back whatever revenue the company had already over-collected.
GSPL entered the review with an expansive claim. The utility proposed a cumulative capital expenditure base of ₹9,166.72 crore across the network's life cycle: an opening asset base of ₹3,676.93 crore at its 2012 authorization, ₹2,120.41 crore of actual spending between FY13 and FY23, and ₹3,369.38 crore of projected capital outlays from FY24 to FY32.2 More than a third of the submitted capital base represented unspent future investments—precisely the forward-looking assumptions an assertive regulator scrutinizes most aggressively.
The Walk from ₹50.77 to ₹18.10
The regulator's formal reconciliation detailed how the tariff unraveled.2 First, disallowed capital outlays eliminated ₹13.75 per MMBTU from GSPL's requested rate. The PNGRB ruled that only capital additions that directly expanded system capacity or yielded demonstrable consumer benefits qualified, disallowing multiple proposed future pipeline extensions. Second, reductions in approved operating expenditure pared away another ₹8.70. Finally, an upward adjustment to the volume divisor shaved off an additional ₹10.92.
The volume divisor requires precise unpackaging, as market commentaries frequently misunderstood its mechanics. The PNGRB did not calculate tariffs against the grid's total nameplate capacity. Instead, it adopted the historical average of actual throughput between FY20 and February 2024, which came to 31.67 MMSCMD. GSPL had requested a forward projection of just 26 MMSCMD, citing structural demand headwinds.2 The utility maintained that lower volumes were permanent, while industrial customers argued otherwise. Torrent Power, one of the network's anchor off-takers, submitted that GSPL had transported 31.42, 33.26, and 35.13 MMSCMD across FY18, FY19, and FY20, emphasizing that the volume divisor remained "a critical element in determination of tariff."2 The regulator side-stepped GSPL's conservative forecast and applied the 31.67 MMSCMD historical baseline, adding a caveat that the tariff "would be reviewed in the next financial year if there is a considerable variation in actual volume flows" from that benchmark.2
The Line Few People Discussed
A secondary reconciliation in the order, bridging the previous provisional rate of ₹34.00 to the newly mandated ₹18.10, reveals the true driver of the headline reduction. Recalculated with updated capital and operational parameters, the grid's baseline levelized tariff amounted to roughly ₹29.22. The single largest deduction—a negative adjustment of ₹11.12—carried the technical heading "prospective implementation from 01.05.2024."2 In practice, GSPL had billed off-takers at ₹34.00 for years while retrospective modeling indicated a lower toll was warranted. Rather than ordering an immediate cash refund of past collections, the regulator concentrated the entire payback adjustment into the remaining seven-year horizon of the pipeline's economic life. A substantial portion of the 47% tariff cut was therefore an accounting clawback for historical over-recovery rather than a structural reassessment of future operating costs.
For equity investors, that distinction carried profound implications. It meant that the ₹18.10 tariff reflected an aggressive, accelerated settlement of prior collections, suggesting a mechanical pathway for rates to normalize upward once that true-up expired, if the grid's operating life were extended past 2031, or if fresh capital spending won regulatory approval. Yet it also exposed the utility's structural vulnerability. While PNGRB regulations permit economic life to be extended in ten-year increments "depending on the satisfactory compliance of the service obligations," that renewal remains entirely discretionary, placing the pipeline's post-2031 terminal value firmly in regulatory hands.2
Where the Unified Tariff Fits
GSPL's High-Pressure grid also forms an integral leg of India's national unified pipeline tariff framework, alongside GAIL's interstate corridors, GIGL, and GITL. By mid-2023, the Gujarat grid handled approximately 28 MMSCMD of unified-tariff volume.25 Under this national pooling architecture, end customers pay a distance-tiered zonal rate across interconnected networks, with central clearing settlements remitting revenue to individual pipeline operators strictly on the basis of each entity's authorized levelized tariff. While the pooling structure harmonizes transportation costs across geographies for consumers, it does not alter the underlying ₹18.10 rate determining GSPL's transmission top line. Market narratives positing that the unified tariff would automatically lift GSPL's realizations conflated customer billing with operator settlements; any real revenue expansion required an explicit regulatory upward revision in the company's standalone tariff.
A Peer Comparison That Stings
The asymmetric nature of that regulatory discretion became stark when contrasted with GAIL, which manages roughly 70% of India's gas transmission infrastructure.4 In November 2025, the PNGRB concluded its tariff review for GAIL's integrated pipeline network. GAIL had petitioned for ₹77.98 per MMBTU. In its ruling, the board observed that an immediate "true-up of all the parameters at this stage would lead to sudden significant increase in tariff and can place unexpected financial pressure on customers," while balancing that "the interest of the pipeline entity is also to be protected." Rather than implementing a sharp adjustment, the regulator awarded GAIL an interim tariff increase from ₹58.61 to ₹65.69 per MMBTU effective January 1, 2026, deferring the remaining true-up reconciliations until 2028.26 The contrast was acute: the same regulatory authority smoothed GAIL's tariff trajectory to buffer customer impact while executing a swift, unmitigated downward adjustment on GSPL. While structural differences existed—GSPL's grid was older, carried a higher depreciation base, operated closer to the end of its modeled economic life, and carried historical over-recoveries—the divergent treatment underscored how widely regulatory discretion can swing, and how severely that discretion penalized GSPL.
What Broke and What Did Not
The standalone financial results following the order captured the immediate impact. Total operating income dropped from ₹2,032 crore in FY24 to ₹1,111 crore in FY25, even though transmission volumes held virtually flat at 11,032 MMSCM compared to 11,159 MMSCM a year earlier.4 Return on invested capital fell from 26.1% to 12.3%, and return on equity slipped from 13.1% to 7.7%.3 Yet the core cash engine did not seize up: operating margins held steady at 73%, the company carried zero debt, and it maintained roughly ₹1,997 crore in surplus cash and liquid investments.4 The utility's smaller Low-Pressure network, governed by its own separate tariff of ₹4.07 per MMBTU, was largely immaterial to group outcomes; the High-Pressure grid remained the economic foundation of the franchise.4 Following the decision, CARE retained GSPL's rating at AA+ while placing it on "Rating Watch with Developing Implications" ahead of the corporate restructuring, observing that the business remained "exposed to regulatory risk" despite the theoretical "cost-plus nature of tariff."4 GSPL appealed the order before the Appellate Tribunal for Electricity (APTEL), arguing that the tariff determination infringed its right to recoup prudently incurred costs "and obtain the stipulated reasonable rate of return."1112 By August 2025, management confirmed to analysts that its parallel writ petition challenging the ruling in the Delhi High Court remained pending.3
The physical moat survived intact: no competitor laid parallel steel, and contracted off-takers continued to ship gas. But the economic moat—the franchise's capacity to generate returns well in excess of its cost of capital—was effectively severed. Investors learned that excess returns in regulated infrastructure do not reside in the physical asset; they exist at the pleasure of an administrative formula that can be recalibrated without grandfathering. The question that followed was how management and the state promoter would respond.
VIII. Transcript Intelligence: Confronting the Shock in Analyst Calls (2024–2025)
In most corporate earnings coverage, the quarterly conference call is where management's composure is tested under fire. GSPL presented an unusual case. Standalone conference-call transcripts for the quarters immediately following the April 2024 tariff order were not publicly available, precluding verification of unrecorded verbal exchanges. What remained was an extensive written record: audited annual reports, post-earnings sell-side research notes, credit rating agency disclosures, and the GSPC Group's own restructuring investor presentation. Together, those records revealed a leadership team that addressed the regulatory shock not through aggressive commercial pivots or operational guidance, but through administrative appeals, legal filings, and corporate reorganization.
The First Reaction: Law and Process
In August 2024, GSPL's FY24 annual report addressed the tariff revision under its statutory review of material changes. The filing confirmed the reduction to ₹18.10 per MMBTU, noted that the utility had lodged an appeal with APTEL, and contended that the decision infringed "the right of GSPL as the Authorized Entity to recover the capital expenditure and operational expenditure being incurred by GSPL and obtain the stipulated reasonable rate of return thereto."11 In a separate section, the report affirmed that no regulatory or judicial orders threatened the company's "going concern status."11 Both assertions were technically accurate, yet the contrast captured the gulf between corporate solvency and shareholder value: a business can remain entirely viable as a going concern while its economic returns are dismantled.
Institutional analysts reacted with unvarnished dismay. Motilal Oswal characterized the PNGRB ruling as "a major disappointment," noting it had modeled a 15% tariff contraction rather than a 47% cut, and slashed its FY25–26 earnings estimates by 40% to 45%. The brokerage underscored the valuation distortion by pointing out that the standalone pipeline contributed just ₹180 to its ₹450 per-share target price.1 That metric crystallized how secondary the transmission grid had become in market modeling: the physical steel network that justified GSPL's initial existence accounted for barely 40% of its modeled equity value.
Management also looked outward for demand recovery. The annual report observed that if international LNG prices remained competitive, "there is a chance that the Government may extend" mandates requiring gas-fired power stations to generate electricity "for a longer term."8 While economically plausible, the commentary highlighted a persistent theme in GSPL's executive posture: prospective catalysts were framed around policy directives, regulatory leniency, and global commodity markets rather than internal commercial initiatives.
The Grind: Quarter by Quarter
Operational results over the subsequent quarters traced that vulnerability. Throughput stood at 36.4 MMSCMD in the first quarter of FY25 before sliding to 29.7, 29.0, and 25.8 MMSCMD across the next three quarters, before edging back to 29.7 MMSCMD in the first quarter of FY26 on the back of a 2.7 MMSCMD uptick in power-sector off-take.3 Operating expenses per unit of gas transported spiked in the fourth quarter of FY25, compressing the pipeline's quarterly EBITDA margin to 52%.3 Maintaining a "Hold" recommendation, JM Financial pointed to a "muted transmission volume growth outlook" alongside the halved tariff, assigning an equity value of just ₹93 per share to the standalone pipeline compared to ₹225 for GSPL's holding in Gujarat Gas.3 By August 2025, the company reiterated that its parallel writ petition challenging the tariff order before the Delhi High Court remained pending.3 No hearing schedule or resolution timeline was provided.
A quieter regulatory clause carried far greater financial significance. In its 2024 order, the PNGRB had committed to reviewing the tariff schedule if actual transmission volumes diverged materially from its 31.67 MMSCMD benchmark.2 Actual throughput averaged roughly 30.2 MMSCMD across FY25, and subsequent disclosures from successor GTL indicated that FY26 volume dropped further to 27.88 MMSCMD.427 Whether management formally petitioned the board for an upward tariff reset under that volume-shortfall provision was never disclosed in public filings. For investors, that administrative true-up represented a much faster, mathematically grounded avenue for rate relief than years of appellate litigation.
The Capital Allocation Question
The muted operational response brought capital allocation under sharper scrutiny. With zero debt and roughly ₹1,997 crore in surplus cash and liquid balances, why did a utility facing capped investment returns retain so much liquidity? GSPL maintained a dividend of ₹5 per share across both FY24 and FY25.1112 Against FY24 earnings of ₹22.80 per share, that represented a modest 22% payout ratio; as net profit fell in FY25, the same ₹5 distribution absorbed roughly 35% of earnings of ₹14.31 per share, returning about ₹282 crore to shareholders.312
At the same time, the company maintained a capital expenditure blueprint of approximately ₹3,380 crore through FY29—precisely the sort of forward-looking network expansion that the PNGRB had just penalized by disallowing speculative outlays from the tariff base.42 Management indicated that those outlays would be funded primarily through internal cash generation and existing liquid reserves.4 Yet deploying internal cash into steel pipelines offered no guarantee of commercial payback: whether that capital would ever earn its statutory return depended entirely on the benevolence of future regulatory orders, not management's willingness to invest.
The Pivot to Structure
By late August 2024, the parent group chose to resolve its valuation bottleneck through corporate engineering rather than regulatory remediation. During the August 31, 2024 investor presentation detailing the composite scheme, management explicitly cited that "GSPL's growth [was] not fully reflected in its valuation due to holding company discount" as a primary motivation for the reorganization.5 Unable to engineer an immediate restoration of pipeline tariffs, leadership sought to unlock value by separating the assets.
Public markets welcomed the gambit. GSPL's share price surged 47% in eleven trading sessions, rallying from ₹318.55 on August 16 to an intraday peak of ₹469.60 on September 2, 2024.8 The re-rating reflected optimism over unwinding the holding-company discount, yet it bypassed the fundamental operational reality: reshuffling corporate entities on an organizational chart could eliminate the holding-company penalty, but it could not alter the regulated unit toll of the underlying steel grid.
IX. The Great Restructuring: De-Merger, Amalgamation, and GSPL Transmission (2024–2026)
For decades, the GSPC Group operated as a stacked corporate pyramid. The Government of Gujarat held 55.65% of GSPC. GSPC held 37.63% of GSPL. GSPL held 54.17% of Gujarat Gas, while GSPC directly held an additional 6.53%.5 Each corporate tier maintained its own board of directors, its own Indian Administrative Service leadership, and routine related-party transactions with the others. On August 30, 2024, the boards of all three entities convened to approve a composite scheme to unwind that intricate structure.5
The Mechanics
The transaction unfolded in four synchronized steps. First, GSPC, GSPL, and GSPC Energy merged into Gujarat Gas. Under the agreed swap terms, GSPC investors received 10 Gujarat Gas shares for every 305 GSPC shares held, while GSPL shareholders received 10 Gujarat Gas shares for every 13 GSPL shares.5 Second, the amalgamated Gujarat Gas carved out the pipeline transmission assets into a separate entity, GSPL Transmission Limited (GTL), distributing one share of GTL for every three shares held in the enlarged Gujarat Gas.5 Third, GTL would pursue an independent listing on the Indian exchanges. Fourth, the surviving parent utility was rechristened Gujarat Energy Limited.6 Valuation assessments were conducted by Ernst & Young Merchant Banking Services and SSPA & Co., with Fortress Capital and Saffron Capital providing fairness opinions for GSPL and Gujarat Gas, respectively.5 The scheme established retrospective appointed dates of April 1, 2024 for the amalgamation and April 1, 2025 for the demerger.5
Beyond corporate streamlining, the demerger was compelled by legal mandate. The official restructuring presentation stated plainly that the "demerger of natural gas transmission business is to ensure adherence to regulatory requirement."5 Folding GSPC's sprawling gas-trading operations into the same corporate vehicle as the pipeline grid would have housed both the fuel merchant and the common-carrier transmission spine under a single roof—violating the open-access unbundling rules that defined GSPL from its inception. The carve-out was not merely a financial engineering exercise to unlock shareholder value; it was a regulatory necessity.
The Timeline, and the Slippage
The restructuring timeline experienced recurring delays against initial guidance. The August 2024 investor presentation targeted completion by August 2025.5 By December 2025, credit rating agency CARE reported that management expected completion by January 2026.4 Shareholders endorsed the scheme by an overwhelming majority in October 2025, following favorable voting recommendations from institutional proxy advisory firms SES and IiAS.6 The Ministry of Corporate Affairs sanctioned the final order on April 17, 2026, and the composite restructuring formally took effect on May 1, 2026.628
The subsequent share issuances followed in tranches. Gujarat Energy allotted 62.27 crore equity shares to former GSPC and GSPL holders against a May 12 record date, with those shares commencing secondary trading on June 18, 2026.29 Successor pipeline entity GTL allotted 31.27 crore shares on July 8, 2026, against a July 2 record date, and submitted its formal listing application. However, those shares remained locked in depository accounts pending final trading permissions from the stock exchanges.30 On Gujarat Energy's June 1, 2026 earnings call, management said it expected GTL's listing approval "by end of July '26."24 As of late September 2026, exchange disclosures have yet to confirm an official trading debut date for GTL.
The overall restructuring concluded roughly nine months behind its inaugural schedule, and the standalone listing of the pure-play transmission grid drifted past executive guidance. While procedural friction across SEBI, the stock exchanges, tax authorities, and corporate law tribunals is routine in large public reorganizations, the lag remained an essential benchmark against executive commitments.
What GSPL Holders Traded Into
For equity holders in GSPL, swapping into the merged retailer and marketer introduced a fundamentally different earnings profile. GSPC's gas trading franchise operates far from a predictable utility annuity. Its trading volumes contracted from roughly 19 MMSCMD in FY20 to approximately 11 MMSCMD in both FY23 and FY24, while EBITDA swung wildly from ₹1,345 crore in FY21 up to ₹3,407 crore in FY23 before retreating to ₹1,332 crore in FY24.5
During the June 2026 earnings call, when an analyst pressed leadership on whether those merchant trading profits were sustainable, management answered with a single word: "Absolutely."24 Disclosed operating data, however, presented a more nuanced picture. Trading volumes dropped 19% in FY26 even as operating margins widened, and forward profitability remained tethered to the pricing spreads on its imported liquefied natural gas portfolio—comprising 2.96 million tonnes per annum of long-term contracts primarily linked to Brent crude, alongside 1.36 million tonnes under agreements with QatarEnergy and Uniper—during a fiscal year when Qatari liquefaction facilities suffered severe geopolitical outages.2423
Who Owns What Now
Following the unbundling, the shareholding architecture resolved into two parallel public entities. The Government of Gujarat holds a direct 38.80% equity interest in both listed companies, expanding to approximately 56% when factoring in allied state-controlled public sector undertakings.6 In GTL's July 2026 regulatory filing, the promoter group held 38.94% while the public held 61.06%, distributed among 302,185 individual and institutional shareholders.31
Asset boundaries were clearly partitioned. GTL holds the core 2,800-plus kilometre Gujarat pipeline grid alongside GSPL's legacy 52% equity stakes in interstate pipeline joint ventures GIGL and GITL.6 Gujarat Energy, meanwhile, absorbed the municipal gas distribution network, GSPC's merchant gas trading desk—characterized by management as India's third-largest—upstream exploration and production rights across 16 fields and exploration blocks, 123.9 megawatts of operational wind capacity, minority interests in gas-fired generation stations and the Mundra LNG regasification terminal, and an estimated ₹6,800 crore in consolidated cash and liquid financial assets.32246
The Bull Case for the Structure
The structural bull case rested on clean investment demarcations. By dissolving the intermediate entity, the pervasive holding-company discount was mechanically extinguished. Investors seeking regulated utility returns from gas transmission could hold GTL as a pure-play infrastructure toll road. Conversely, market participants seeking exposure to India's retail gas expansion and merchant trading spreads could allocate capital directly to Gujarat Energy. Operationally, housing upstream trading and downstream city gas distribution inside a single balance sheet eliminated friction and recurring related-party transactions between GSPC and Gujarat Gas.5 In addition, Gujarat Energy inherited approximately ₹7,200 crore in accumulated tax losses from GSPC, providing a substantial fiscal shield with roughly ₹1,900 crore in unabsorbed tax benefits still remaining as of the June 2026 call.24
The Skeptic's Stress Test
An activist investor would raise three structural questions. First, did former Gujarat Gas minority shareholders receive a fair bargain? They inherited GSPC's merchant trading volatility, a 10% residual interest in the troubled Krishna-Godavari offshore block, and two stranded gas-fired power generation assets that management disclosed were operating at plant load factors of just 1.0% and 6.5%. While executive leadership insisted those power stations were not an operational drag and merely required strategic repositioning,24 management sidestepped questions regarding whether the generation plants generated positive EBITDA, offering no operational figures.24
Second, did former GSPL minority holders receive appropriate value for surrendering a debt-free pipeline franchise and roughly ₹2,000 crore in net liquid cash? The swap valuations were established by independent valuers across corporate entities directed by the same state promoter, with no public market benchmark for unlisted GSPC. While an overwhelming majority of voting public shareholders approved the scheme and GSPL's equity rallied sharply upon the initial announcement, the underlying swap math reflected negotiated administrative valuations rather than an open-market auction.
Third, will corporate governance and capital allocation discipline genuinely improve? When analysts on the June 2026 call inquired how Gujarat Energy intended to deploy its ₹6,800 crore cash hoard, management suggested that capital allocation plans would be shared with investors in the following quarter, while noting that McKinsey & Company had been engaged to formulate a ten-year strategic blueprint that included inorganic acquisitions.24 With the cash residing under the stewardship of the same state promoter, whether that surplus capital translates into substantial dividend distributions or is directed toward capital-intensive acquisitions will provide the definitive test of whether the unbundling transformed state stewardship—or merely reorganized the corporate chart.
That leads to what the pipeline business, now separated, actually looks like.
X. The Business Today: Segments, Economics, & The 1-3 KPIs That Matter
At the Bhadbhut tie-in near Bharuch, the grid's core function remains immediately visible. Gas from the Dahej LNG terminal, domestic supply from Reliance's KG-D6 fields arriving via Pipeline Infrastructure Limited's East–West corridor, and fuel bound for Surat's CNG stations or Ahmedabad's kitchens all pass through valves operated by what is now GSPL Transmission.2 The corporate architecture changed on May 1, 2026, but the physical movement of gas did not.
The Transmission Business (GTL)
GTL operates a medium- to high-pressure network spanning approximately 2,878 km.7 Across FY26, transmission throughput averaged 27.88 MMSCMD.27 The utility is constructing targeted source interconnects, including the 98-km Jamnagar–Dwarka pipeline, the 284-km Anjar–Palanpur corridor linking Mundra LNG to northern Gujarat and GIGL, and the 35-km Dahej–Bhadbhut segment. It is also expanding city-gas tie-ins across Bhavnagar, Narmada, and rural Ahmedabad, with prospective lines planned toward Amreli, Mandvi, and Tarapur.7 Regulatory disclosures identify Prakash Karnik as GTL's chief executive.33
Following the April 2024 tariff reset, the transmission franchise settled into the financial profile of a low-growth, cash-generative utility. During the first half of FY26, standalone operations delivered ₹558 crore in operating revenue and ₹376 crore in operating profit (PBILDT), preserving an EBITDA margin of roughly two-thirds.4 Realized transmission revenue stood at approximately ₹1,016 per thousand cubic metres in the first quarter of FY26 against cash operating expenses of ₹302.3 Return on capital, which hovered in the mid-20% range prior to the regulatory order, compressed into the low teens according to estimates from JM Financial.3 Meanwhile, GTL's 52% equity stakes in interstate joint ventures GIGL and GITL continue to register net losses, requiring sponsor equity support rather than contributing earnings.1819
The Distribution and Trading Business (Gujarat Energy)
Gujarat Energy operates at a much larger scale and carries substantially more cyclical exposure. For FY26, the consolidated company reported EBITDA of ₹3,772 crore and net profit after tax of ₹2,299 crore, driven by roughly ₹1,900 crore in EBITDA from city gas distribution and approximately ₹1,300 crore from merchant gas trading, and declared a dividend of ₹8.90 per share.24 The city gas franchise spans 44 districts across 27 geographic authorizations in six states and one union territory, reaching record sales of 12.34 MMSCMD in the first quarter of FY27.32 By 2024, the retail network encompassed approximately 22 lakh domestic piped natural gas connections, over 810 CNG stations, and roughly 40,200 km of distribution pipelines.5 The company has also advanced the state government's "LPG Free Zone" initiative, converting 2,835 residential societies—representing about 4.86 lakh households—entirely to piped gas by May 2026.624 Industrial pricing illustrated the pricing power conferred by regional geopolitical disruption: Morbi ceramic units paid approximately ₹75 per cubic metre in May 2026, compared to ₹68 in other industrial clusters.24 Executive leadership guided toward long-term gas trading margins of 4% to 6% and targeted 25% to 30% segment growth by FY31.24 However, that ambition contrasts with recent volume delivery: merchant gas trading volumes declined 19% in FY26 to 10.2 MMSCMD.24
The Three KPIs That Matter
For investors tracking the unbundled entities, and GTL in particular, three core metrics govern the underlying economics.
1. Daily transmission volume (MMSCMD) across the Gujarat grid. Throughput serves as both the operational engine of transmission revenue and the critical divisor in regulatory tariff formulas. The PNGRB benchmarked the levelized tariff against an assumed baseline of 31.67 MMSCMD, explicitly pledging a review if actual volume flows diverged considerably.2 Sustained throughput below that threshold strengthens the mathematical case for an upward tariff reset, whereas higher volumes bolster near-term cash generation but weaken the argument for regulatory relief. In parallel, comparing contracted capacity—which stood at 41.84 MMSCMD as of September 2025—against actual throughput reveals how much downside protection the ship-or-pay contractual buffer provides.4
2. The approved levelized tariff and realized transmission revenue per unit. Operating profitability hinges on legal appeals pending before APTEL and the Delhi High Court, potential regulatory true-ups under the volume-shortfall clause, approved additions to the capital expenditure base, and, decisively, whether the PNGRB grants an extension of the grid's economic life beyond November 2031.23 On a quarterly basis, realized transmission revenue per thousand cubic metres provides the clearest operational gauge of net cash realization.
3. The Morbi fuel-parity spread. Expressed as the landed cost of delivered natural gas relative to imported propane per unit of thermal energy, this pricing spread dictates fuel switching across Asia's largest ceramic manufacturing hub. As demonstrated in recent cycles, that differential drove industrial volumes away from the pipeline grid toward propane in 2022, before geopolitical supply shocks abruptly forced kilns back to natural gas in 2026.202124 It remains the most reliable leading indicator of the grid's industrial throughput.
Tracking these three indicators shifts the analysis from evaluating whether the network remains a viable asset to assessing how risks and prospective returns align across the newly separated entities.
XI. The Playbook: Lessons from Gujarat's Steel Highway
Many investors who backed GSPL at its 2006 public debut believed they were buying a straightforward proposition: underground steel, a statutory monopoly, and regulated returns. Two decades later, the corporate record yields four lessons that extend far beyond Gujarat.
1. A Regulated Tollbooth Is a Licence, Not a Moat
The PNGRB's 2024 tariff order did not breach GSPL's physical moat; no competitor laid a parallel pipeline. Instead, it reset the price. The regulator disallowed capital expenditure that did not directly expand capacity, pared back operating expenses, benchmarked throughput against a historical baseline the company disputed, and compressed a retrospective clawback for past over-recoveries into the final seven years of the asset's modeled economic life.2 By contrast, the board's November 2025 order for GAIL demonstrated that the same regulator can phase in adjustments gradually to buffer customer impact when it chooses to exercise forbearance.26 The takeaway is fundamental: in regulated infrastructure, pricing power resides entirely with the regulator. Analyzing these utilities requires scrutinizing the administrative rulebook as closely as the physical grid—dissecting its methodology, its historical discretion, and the terminal dates of regulatory review cycles.
2. A Sovereign Parent Is a Shareholder With Its Own Priorities
The 2018 acquisition of Gujarat Gas shares directly transferred liquidity to an unlisted parent encumbered by deepwater exploration losses in the KG basin, funded by a listed subsidiary accountable to public minority shareholders.1516 Nomura's warning that the transaction risked turning GSPL into a financial buffer for its parent captured the structural governance hazard.16 That same state promoter orchestrated the 2024 composite restructuring, established the share swap ratios, and now stewards roughly ₹6,800 crore in liquid assets inside Gujarat Energy.24 For minority investors in state-controlled enterprises, every major capital-allocation announcement demands a clear-eyed inquiry: whose balance sheet is truly being relieved, and who bears the downside when strategic rationales fall short?
3. State Advantages Stop at the State Border
Within Gujarat, GSPL leveraged state administrative backing to assemble right-of-use corridors across a 2,800-plus kilometre network. Outside its home state, that bureaucratic leverage evaporated. In Punjab, right-of-way disputes stalled a critical 130-km trunk section for more than a decade.18 In Andhra Pradesh and Telangana, GITL constructed a truncated 18-inch pipeline rather than the authorized 42-inch corridor, and the offshore gas projected to fill the line never materialized.19 The competitive advantages of a state-backed utility are largely jurisdictional. Any prospective interstate expansion proposed by GTL must be evaluated against this uneven operational history.
4. A Carrier Without Commodity Risk Still Has Volume Risk
GSPL's foundational pitch to public equity markets was that it took no commodity-price risk because it never bought or sold the molecules.4 The industrial kilns of Morbi demonstrated the boundaries of that protection. When anchor industrial customers possess dual-fuel infrastructure, an international price surge in liquefied natural gas does not hit the pipeline as an unpaid bill; it hits as demand destruction. In 2022, industrial substitution swung against the grid as ceramic makers pivoted to imported propane. In 2026, geopolitical maritime blockades swung volumes back to piped natural gas. In both directions, throughput—and the operating cash flow it generated—was dictated by commodity spreads the utility does not set and end-user fuel substitutions it cannot control.
Myth vs. Reality
Myth: GSPL carried 40% of India's gas. Reality: Gujarat consumes about 40% of the country's natural gas, and GSPL operates the primary high-pressure grid serving that regional demand. Nationally, the utility remains the second-largest pipeline transporter, trailing far behind GAIL's roughly 70% transmission share.4
Myth: the 2024 tariff cut was purely punitive. Reality: A substantial portion of the reduction was an accounting clawback for past revenue over-recoveries, concentrated by the regulator across the brief remaining window of the grid's modeled economic life.2 While that true-up severely compressed immediate earnings, it also implies that unit tariffs could normalize upward if the regulator extends the pipeline's operational life beyond 2031 or approves fresh capital spending.
Myth: open access removed commodity risk. Reality: Operating as a pure toll road insulated GSPL's income statement from direct gas procurement losses, but it left throughput fully exposed to fuel-switching dynamics—as evidenced when transmission volumes dropped from roughly 38 MMSCMD in FY20 to 25 MMSCMD in FY23 as industrial consumers switched to propane.5
Myth: the restructuring was purely about unlocking value. Reality: Unbundling transmission into an independent listed entity was a statutory necessity to comply with open-access regulations, ensuring that natural gas transportation remained legally partitioned once GSPC's large merchant gas trading desk was folded into Gujarat Gas.5
These lessons shape the balance of arguments for GTL and Gujarat Energy from here.
XII. Bull vs. Bear Case & What to Watch
By September 2026, the ticker GSPL no longer trades on Indian bourses. Former shareholders hold shares in Gujarat Energy alongside allotted, though not yet secondary-trading, shares in GTL. Upstream, Qatar's LNG export infrastructure remains partly impaired by regional conflict.23 Downstream, Morbi's ceramic kilns have pivoted back to natural gas at roughly ₹75 per cubic metre.24 At the core of the transmission business, the regulator's April 2024 tariff order remains under legal appeal, while the pipeline network's modeled economic life approaches its terminal date in November 2031.2 Evaluating the surviving assets requires weighing the structural arguments across both entities.
The Bull Case
A clean pure-play. Once secondary trading commences, GTL offers public investors a debt-free, open-access pipeline monopoly traversing India's largest gas-consuming state, completely unburdened by a holding-company structure and operating at an EBITDA margin exceeding 70%.4 The persistent 50% to 60% holding-company discount previously applied to the Gujarat Gas equity holding was largely eliminated during the market re-rating that followed the restructuring announcement in August 2024.8 The open question is how the market will value GTL's regulated cash flows strictly on their own merits.
Mean reversion in the tariff. The negative adjustment of ₹11.12 per MMBTU for "prospective implementation" represented a retrospective accounting clawback concentrated into the brief remaining horizon of the grid's modeled life.2 If the PNGRB extends the pipeline's economic life beyond 2031, admits fresh capital expenditure into the regulated asset base, or recalibrates the unit toll because actual throughput has fallen short of the 31.67 MMSCMD volume divisor, the levelized tariff would mechanically adjust upward. While this represents a logical inference derived from regulatory tariff mechanics, it does not reflect any formal regulatory commitment and remains entirely subject to the board's administrative discretion.
New supply sources and security of supply. Pipeline interconnects to the Swan Energy and Chhara LNG import terminals are complete, while the Anjar–Palanpur and Jamnagar–Dwarka corridors are engineered to link incremental supply basins to the core grid.47 Furthermore, the 2026 propane supply bottleneck demonstrated to industrial consumers that piped natural gas provides superior supply security during periods of maritime disruption in the Persian Gulf.24
The Bear Case
Permanent tariff repression. The PNGRB is under no statutory obligation to grant rate relief. Its 2024 tariff order disallowed forward-looking capital outlays deemed speculative, and the regulator will apply that identical scrutiny to GTL's ₹3,380 crore capital expenditure program through FY29.24 If the grid's economic life is extended under stringent capital-base conditions, return on capital could remain suppressed in the low teens or lower.3
Structural industrial defection. The 2022–2026 operational record confirms that dual-fuel switching is institutionalized behavior across Morbi's ceramic cluster. Prior to the 2026 geopolitical conflict, imported propane satisfied nearly 70% of the industrial hub's aggregate thermal demand.21 Once maritime supply routes normalize through the Gulf, and with Qatar's LNG liquefaction trains impaired for multiple years, the delivered thermal price spread could easily tilt back in favor of propane.23 Reflecting this structural substitution, transmission throughput across the pipeline network has failed to match its FY20 baseline of approximately 38 MMSCMD in any full fiscal year since.527
The interstate drag. GIGL operates at less than 10% capacity utilization and requires ongoing sponsor equity infusions, while GITL remains embroiled in regulatory litigation with the PNGRB over unilateral pipeline downsizing and an incomplete corridor.1819 Both legacy joint ventures now sit on GTL's balance sheet.
Contract roll-off. Total contracted transmission capacity declined from 44.48 MMSCMD in August 2024 to 41.84 MMSCMD by September 2025.4 Although the utility has historically renewed expiring gas transmission agreements, a significant portion of the portfolio comprises short-tenure contracts. Any downturn in renewal nominations—such as gas-fired power stations returning to idle status as spot LNG prices rise—would register swiftly across transmission revenues.
Porter's Five Forces, Applied
Competitive rivalry within Gujarat is low, as the PNGRB grants exclusive geographic pipeline authorizations that prevent duplicate trunk infrastructure.4 The threat of new entrants is similarly muted by statutory exclusivity, although physical interconnects with third-party networks—such as Pipeline Infrastructure Limited's East–West corridor feeding the grid at Bhadbhut—mean gas volumes can enter Gujarat through alternative supply routes.2 Buyer power is moderate to high: anchor customers including Gujarat Energy, refineries, and power utilities represent concentrated off-take, contract tenures are often short, and major off-takers like Torrent Power routinely petition the PNGRB against higher tariffs during regulatory hearings.24 Supplier power is low regarding pipeline equipment and steel, but upstream gas producers and LNG liquefaction facilities in the Persian Gulf hold substantial leverage over input supply and delivered pricing. The threat of substitute products is high among industrial customers, as Morbi's rapid migration between natural gas and propane demonstrated. Crucially, the dominant governing force sitting outside Porter's traditional framework is the regulator, which directly determines permissible returns, capital recovery, and unit pricing.
Hamilton Helmer's 7 Powers, Applied
Within Hamilton Helmer's 7 Powers framework, GTL clearly commands two structural advantages. It possesses scale economies, derived from high fixed upfront capital investments in underground steel that generate negligible variable operating costs per unit of throughput. It also holds a cornered resource in its contiguous statutory rights-of-use and sovereign-backed pipeline authorizations across Gujarat. The business exhibits only weak switching costs: while industrial customers cannot economically construct alternative pipeline connections, they can switch thermal fuels with minimal friction once dual-fuel burners and vaporizers are installed. GTL lacks network economies in the traditional two-sided sense, process power, counter-positioning, or branding power. The fundamental vulnerability is that GTL's two genuine powers—scale and cornered rights-of-way—are precisely the parameters that the PNGRB regulates and caps. Helmer's framework evaluates whether an enterprise can generate persistent economic profits exceeding its cost of capital; for GTL, that outcome rests entirely on administrative tariff orders. In contrast, GAIL commands superior nationwide scale, and its November 2025 tariff determination was buffered by regulatory forbearance.26 That divergence underscores that administrative discretion, rather than physical infrastructure alone, dictates the dispersion of returns across India's gas transmission sector.
The Calibrated Conclusion
The multi-decade operational record narrows the original GSPL investment thesis rather than completely invalidating it. The thesis of a "physical monopoly" remains validated: no commercial competitor has duplicated the intrastate steel grid. The thesis of a "reliable toll-road annuity" has broken down: pipeline returns remain vulnerable to unilateral regulatory resets and end-user volume volatility, as the 2022 demand contraction and the 2024 tariff order proved. The thesis of "national expansion optionality" has been thoroughly disproved by fourteen years of execution delays across GIGL and GITL. The thesis that the "holding-company discount would be unlocked" has been structurally fulfilled via the demerger, although whether group-level capital allocation will genuinely prioritize minority shareholder returns remains unproven. A constructive trajectory for the transmission asset would require a favorable appellate ruling or administrative true-up that raises the levelized tariff, an extension of the grid's modeled economic life beyond 2031 on reasonable terms, sustained throughput exceeding the regulator's 31.67 MMSCMD volume divisor, and surplus cash from Gujarat Energy distributed to shareholders rather than deployed into speculative acquisitions. Conversely, the investment case would deteriorate further upon another adverse tariff adjustment, a swift reversion of Morbi's kilns to imported propane once Gulf shipping normalizes, or renewed capital calls to absorb joint-venture losses at GIGL and GITL.
What to Watch
The formal secondary trading debut date for GTL and its initial standalone market valuation.30 Judicial rulings from APTEL or the Delhi High Court, alongside disclosures indicating whether GTL petitions the PNGRB for an administrative upward tariff reset under the volume-shortfall clause.23 The regulatory framework and timeline the PNGRB applies to extending the High-Pressure grid's economic life beyond November 2031.2 Shifts in Morbi's industrial fuel mix as Persian Gulf LPG supplies normalize, tracked through the landed price differential between delivered LNG and imported propane.2124 GIGL's actual throughput progress toward its 7.7 MMSCMD contractual commitments.18 And, inside Gujarat Energy, concrete capital-allocation disclosures detailing whether its estimated ₹6,800 crore cash reserve is returned to shareholders or deployed into inorganic acquisitions.24
References
-
Shares of Gujarat State Petronet tank 20% on PNGRB's revised tariff order — Business Standard, 2024-04-22 ↩↩↩
-
Tariff Order: GSPL High Pressure Gas Grid (TO dated 20.04.2024) — Petroleum and Natural Gas Regulatory Board, 2024-04-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gujarat State Petro. 1QFY26 Result Update — JM Financial Institutional Securities, 2025-08-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Press Release: Gujarat State Petronet Limited (Revised) — CARE Ratings, 2025-12-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gujarat Gas Limited & Gujarat State Petronet Limited: Investor Update on 'The Scheme of Arrangement' — Gujarat Gas Limited, 2024-08-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
GSPC Group's Scheme of Arrangement takes effect (Press Release) — Gujarat Gas Limited, 2026-05-01 ↩↩↩↩↩↩↩↩
-
Gujarat State Petronet rebounds 13% on heavy volumes; zooms 47% in 11 days — Business Standard, 2024-09-02 ↩↩↩↩↩
-
Gujarat State Petronet Ltd Company Summary — IIFL Capital / India Infoline ↩↩↩↩
-
Gujarat State Petronet Limited 26th Annual Report 2023-24 — NSE Archives, 2024-08-28 ↩↩↩↩↩↩
-
Gujarat State Petronet Ltd Directors Report (FY2024-25) — IIFL Capital / India Infoline ↩↩↩↩
-
GSPC to acquire 65% stake in Gujarat Gas — Business Standard, 2012-10-03 ↩↩
-
Street cautious on Gujarat Gas after BG sellout — Business Standard, 2012-10-05 ↩↩↩
-
ONGC completes Rs 7.7k cr acquisition of GSPC — Business Standard (PTI), 2017-08-04 ↩↩↩
-
GSPL stock: Gujarat Gas stake buy if funded via debt to impact bottom line — Business Standard, 2018-03-21 ↩↩↩↩↩↩↩
-
GSPL falls 6% after board approves stake buy in Gujarat Gas — Business Standard, 2018-03-20 ↩↩↩
-
Press Release: GSPL India Gasnet Limited — CARE Ratings, 2025-06-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Press Release: GSPL India Transco Limited — CARE Ratings, 2025-12-08 ↩↩↩↩↩↩↩↩
-
Largest ceramic manufacturing cluster bears brunt of gas price hike — Business Standard, 2022-03-17 ↩↩↩↩↩↩↩
-
142 Ceramic Units Operational in Morbi: Gujarat Gas — DeshGujarat, 2026-04-15 ↩↩↩↩↩
-
Nearly 100 ceramic units shut in Morbi due to fuel supply disruption — Telangana Today, 2026-03-06 ↩↩
-
The Battle for Hormuz Will Reshape the Global LNG Market — CSIS, 2026-08-05 ↩↩↩↩
-
Gujarat Gas Ltd (GUJGASLTD) Q4 2026 Earnings Call Transcript — AlphaStreet, 2026-06-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Tariff Order: Unified Tariff for the National Gas Grid (effective July 2023) — Petroleum and Natural Gas Regulatory Board, 2023-06-28 ↩
-
Tariff Order: Tariff Review of Integrated Natural Gas Pipeline (INGPL) of GAIL (India) Limited — Petroleum and Natural Gas Regulatory Board, 2025-11-27 ↩↩↩
-
GSPL Transmission Limited (GTL) — Official Website, 2026 ↩↩↩
-
Centre Clears GSPC Group Restructuring; Gujarat Gas to Be Renamed Gujarat Energy Limited — DeshGujarat, 2026-04-18 ↩
-
Receipt of Final Listing and Trading Approval for 62,27,14,719 Equity Shares — Gujarat Energy Limited, 2026-06-17 ↩
-
Gujarat Energy Shareholders Get GTL Shares After Demerger; Key Details — PSU Connect, 2026-07 ↩↩
-
Shareholding Pattern as on 08.07.2026 — GSPL Transmission Limited, 2026-07-08 ↩
-
Gujarat Energy Q1 Results: CGD Volume Hits 12.34 MMSCMD — ScanX, 2026-08 ↩↩
-
Important Officers Contact — GSPL Transmission Limited, 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube