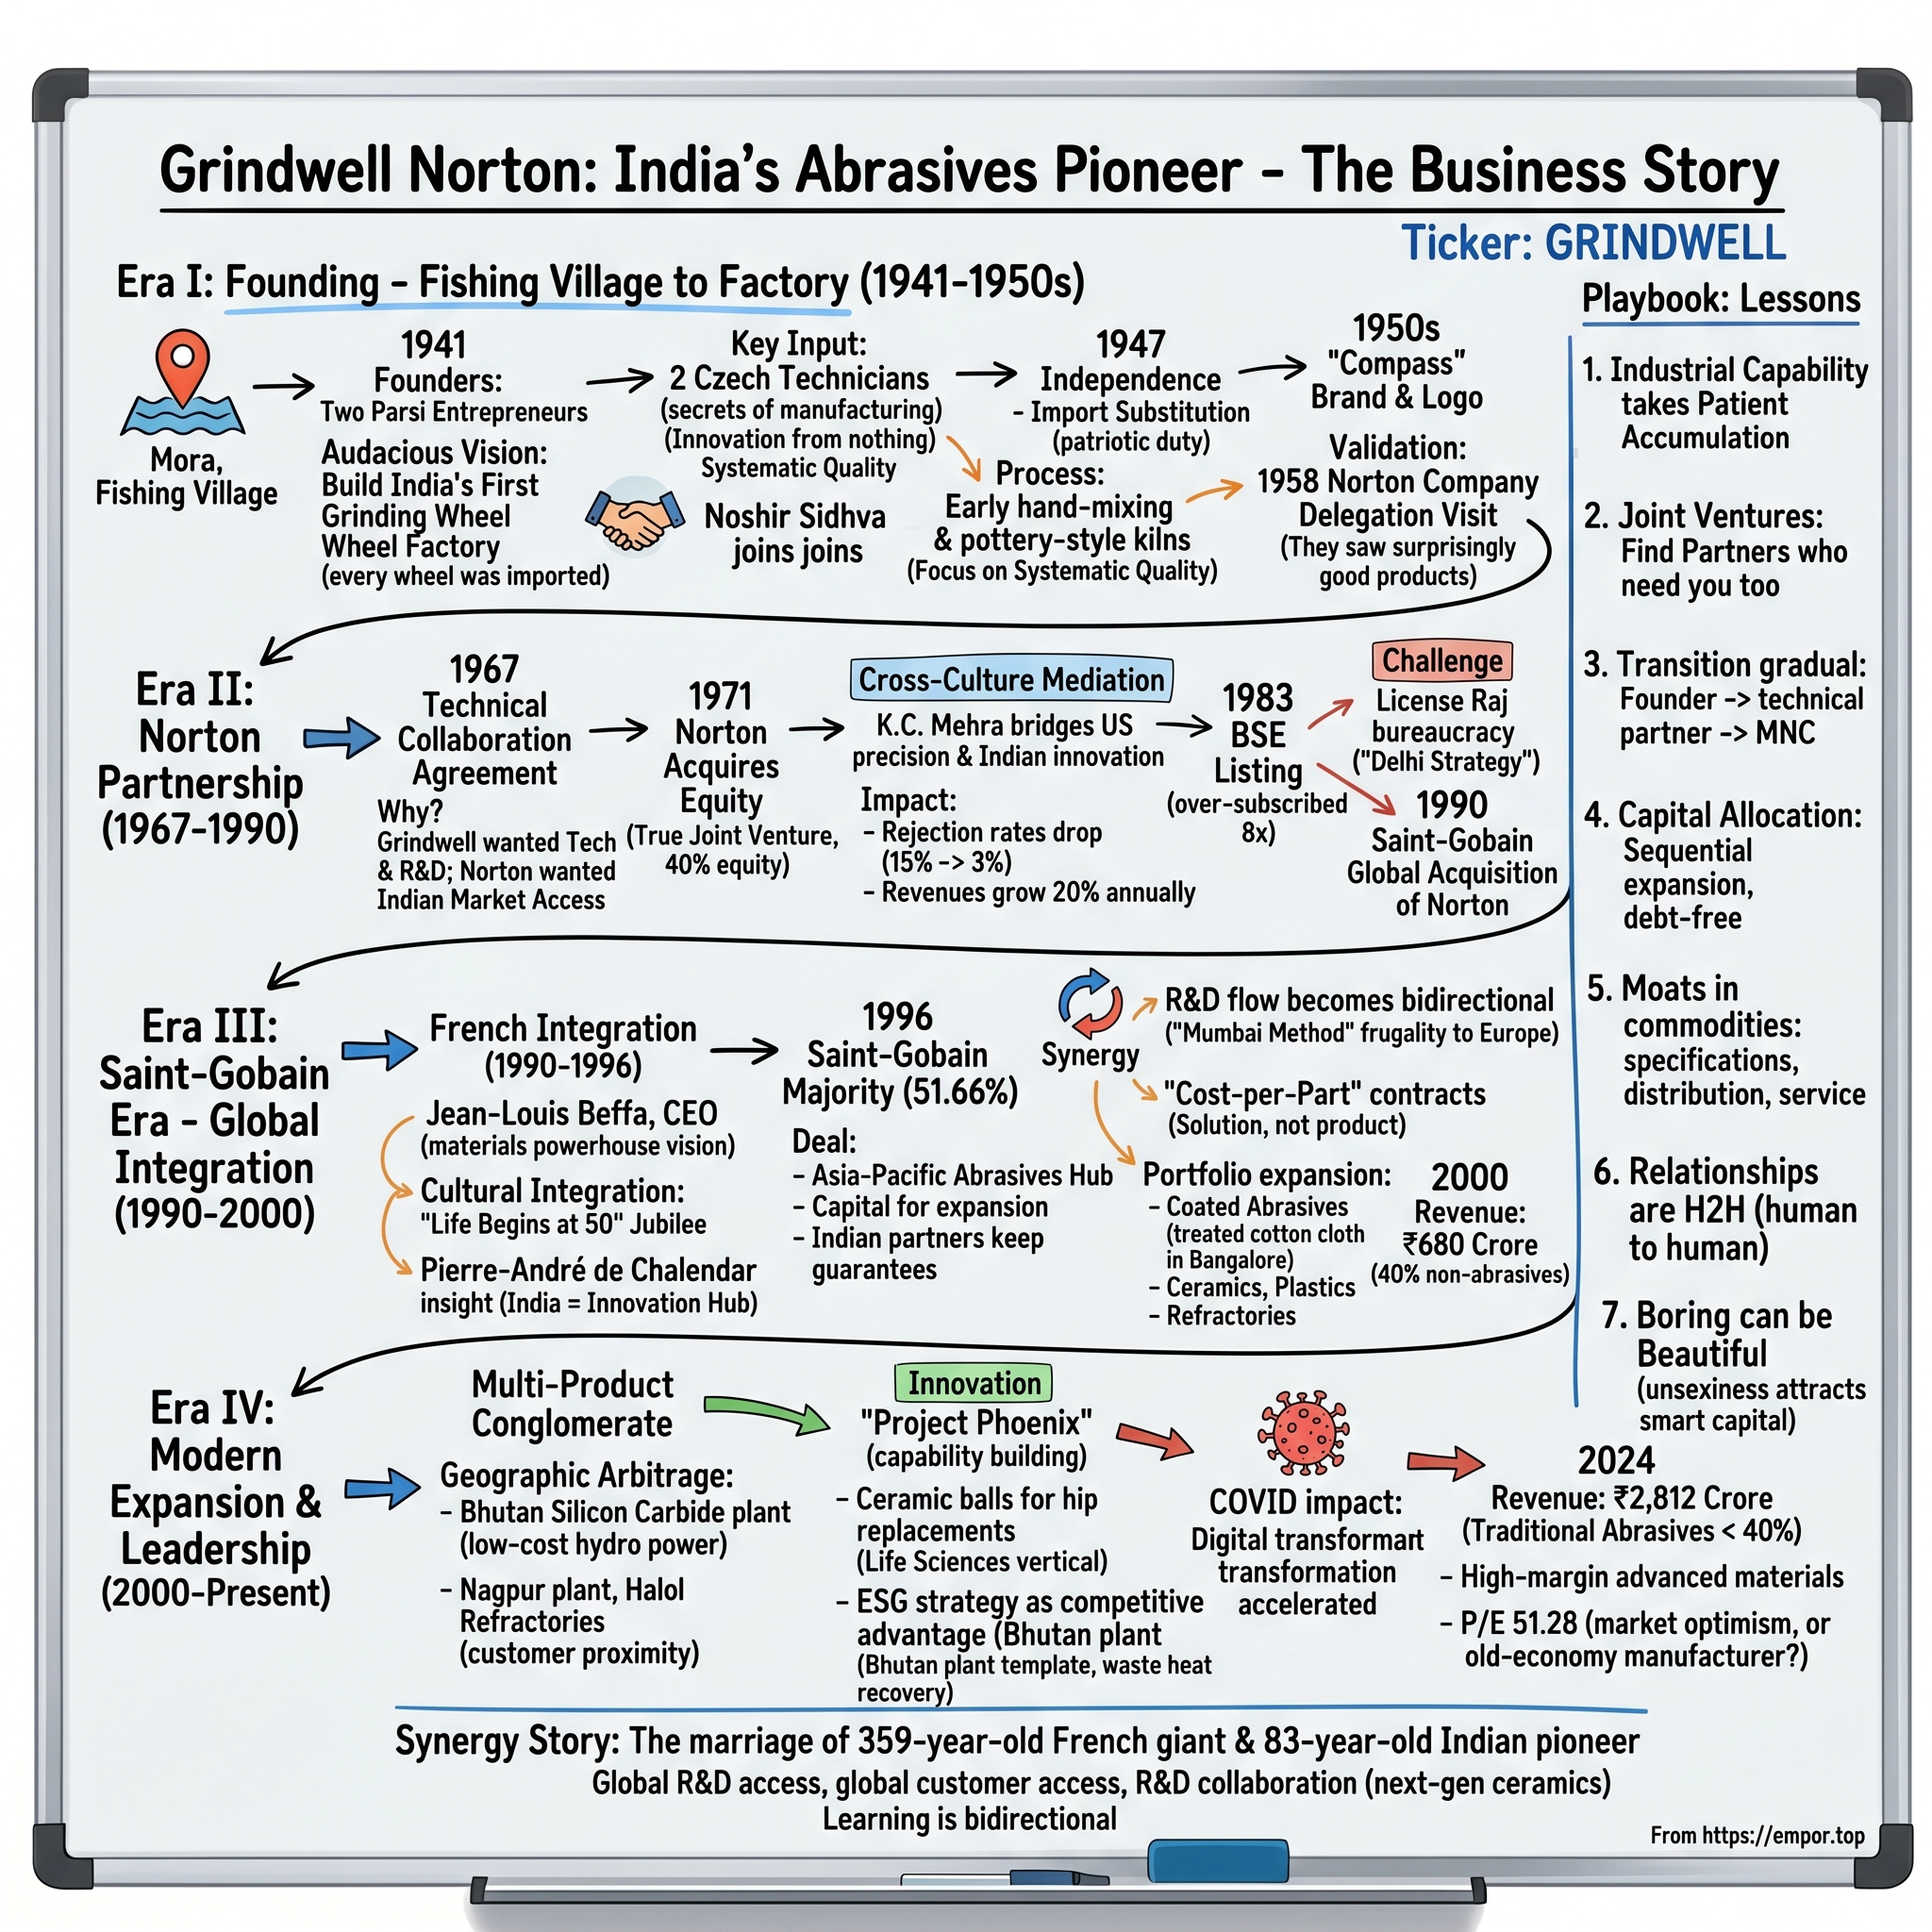
Grindwell Norton: The French-Indian Industrial Compounder
I. Introduction & The Industrial Razor-and-Blade Thesis
Stand on the shop floor of a crankshaft line in Pune and listen. Under the whine of the spindles is a sound machinists learn to respect: a vitrified grinding wheel, spinning at tens of metres per second, taking microns off hardened steel. If the wheel is engineered correctly, the finished component meets tolerance and the line keeps moving. If the wheel is flawed—too soft, poorly balanced, or hiding an internal crack—an expensive forging is scrapped, production halts, and in the worst case, a disintegrating wheel becomes dangerous shrapnel.
Move from that shop floor to a steel melt shop in Jamshedpur, a float-glass furnace in Gujarat, or a biologics suite in Hyderabad, and the identical economic logic applies to refractory linings, silicon carbide shapes, and silicone tubing. Consumables of this kind rarely attract management attention until one of them fails.
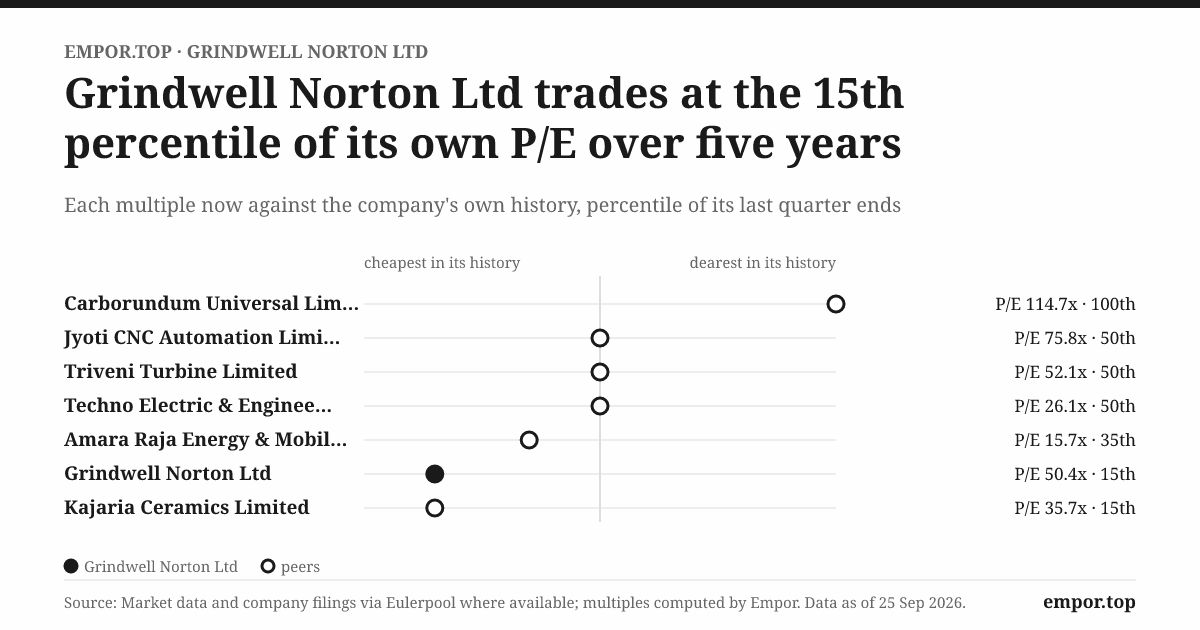
A significant share of these critical products carries the Norton name, manufactured in India by Grindwell Norton Limited (NSE: GRINDWELL). As one of the country's oldest industrial franchises, the company carried a market capitalisation of about ₹21,800 crore in September 2026 at a share price near ₹1,973, trading at roughly 50 times trailing earnings.1 That multiple presents an analytical puzzle. Indian equity markets typically award such valuations to consumer goods leaders and software exporters, yet here it attaches to an industrial manufacturer best known for sandpaper, cut-off discs, and furnace refractories.
The operating scale remains modest. For the fiscal year ended March 2026 (FY26), Grindwell Norton reported consolidated revenue from operations of ₹3,073 crore, up 9.3%, and net profit of about ₹417 crore.12 Operating margins have remained within a dependable band of 16% to 20% for more than a decade, while return on capital employed has hovered between 20% and 28%, with the board distributing approximately half of FY26 profit as dividends.1 The balance sheet carries minimal leverage: borrowings at the end of March 2026 stood at about ₹61 crore against total assets of roughly ₹3,400 crore.1
Corporate parentage accounts for a substantial part of this premium. Two Saint-Gobain entities—Saint-Gobain Abrasives Inc. in the United States and the French holding company SPAFI—hold 26.77% and 24.56%, respectively, while Saint-Gobain India Private Limited owns an additional fraction, giving the French multinational 51.6% voting control. Equity held by descendants of the original Indian founding families brings total promoter ownership to 58.04%.2 Saint-Gobain itself traces its roots to 1665 as the royal mirror manufacturer to Louis XIV; in 2025, the parent group reported sales of €46.5 billion alongside an 11.4% operating margin.34
The operational question is how a venture established in 1941 in a coastal village across the harbour from Bombay developed into one of the highest-return assets in Saint-Gobain's global portfolio. The strategic question cuts deeper: abrasive grains, grinding wheels, and refractory bricks are frequently dismissed as cyclical commodities. How does a producer of these materials sustain economics that resemble a consumer brand franchise, and does the empirical record justify paying 50 times earnings?
The investment thesis rests on an industrial application of the razor-and-blade model. An abrasive wheel or refractory lining represents an insignificant line item in a customer's total operating budget, yet it governs the uptime, yield, and dimensional tolerances of capital-intensive production assets. When industrial buyers select products based on process reliability and risk mitigation rather than initial purchase price, the supplier captures steady pricing power, recurring replacement demand, and resilient gross margins.
This analysis examines that proposition against Grindwell Norton's historical execution. It maps where competitive advantages remain defensible—in high-precision bonded wheels, engineered ceramics, and specialty performance polymers—and where they face structural erosion, particularly in commodity thin wheels and coated abrasives pressured by Chinese imports, alongside merchant silicon carbide. It also assesses the governance trade-offs minority shareholders navigate while tethered to a 360-year-old French multinational.
The story unfolds across six acts. The first details the wartime founding in Mora and the subsequent joint venture with Norton. The second examines the 1990 contested takeover of Norton in Massachusetts that transferred control to Paris. The third dissects the domestic abrasives duopoly shared with the Murugappa Group's Carborundum Universal (CUMI). The fourth charts the strategic diversification into technical ceramics and performance plastics.
The fifth applies a capital allocation stress test centered on the 2022 acquisition of PRS Permacel and the parent company's boundaries on corporate scope. The sixth articulates the competitive dynamics, valuation scenarios, and key strategic priorities for leadership. The origins date to the Second World War, in a seaside hamlet, through the enterprise of two Czechoslovak refugees unable to return home.
 Subscribe on LinkedIn
II. Origins: The Fishing Village & The Versailles Glassmaker (1940–1996)
A kiln by the sea
In 1941 Bombay operated as a congested wartime port, and Indian industry relied almost entirely on imported precision consumables. Grinding wheels arrived from Britain, Germany, and the United States, but naval blockades and wartime shipping disruptions made deliveries erratic. Across Bombay harbour, in the coastal village of Mora near Uran, an improbable domestic substitute took root. According to corporate records, P. H. Sidhwa and R. D. Sidhwa partnered with two Czechoslovak technical experts, F. B. Lima and E. J. Kaufmann-Kavan, to begin fabricating grinding wheels in 1941 under the name Grindwell Abrasives.56 The venture marked the first commercial production of grinding wheels in India.6
The partnership balanced commercial capital with specialized industrial chemistry. The Sidhwas contributed local financing and distribution networks, while the Czechoslovak partners supplied formulation knowledge from Central Europe's abrasives sector. Vitrified wheel manufacturing functions as an exacting discipline of chemical recipes: grain sizing, bond matrices, pressing tonnage, and tight thermal firing curves. Mora provided practical operating advantages: land was inexpensive, labor was available, and water access facilitated the transport of heavy abrasive grain and ceramic bonds by barge. More than eight decades later, Mora remains the anchor of the company's manufacturing footprint. The site forms part of a four-plant abrasives network spanning Bengaluru, Nagpur, and Baddi in Himachal Pradesh, and in FY26 transitioned part of its power demand to captive wind energy.2
Grindwell was incorporated in its modern corporate form on July 31, 1950.2 Unlike many multinational subsidiaries where early promoters were bought out, Grindwell Norton's founding families remain on the share register. The Mahajan and Narang families hold a combined 6.4% equity interest classified under the Indian Promoters' Group, with Aakil Mahajan serving on the board as a non-executive promoter director.2
The Norton alliance
During the 1950s and 1960s, domestic industrialization advanced behind protective import substitution walls. Emerging sectors—commercial vehicles, state railways, industrial bearings, and heavy engineering—required dimensional tolerances that artisanal kilns could not supply. To bridge that quality gap, Grindwell turned to Norton Company of Worcester, Massachusetts. Established in 1885 as the Norton Emery Wheel Company from a local pottery business, Norton had expanded by the early 20th century into the pre-eminent manufacturer of grinding wheels and the primary global producer of silicon carbide.7
According to Grindwell Norton's historical filings, the cross-border partnership originated as a technical collaboration in 1967 before converting into a financial joint venture in 1971, creating Grindwell Norton Ltd.8 That staged entry mirrored the regulatory environment of the period: strict foreign-exchange controls and industrial licensing made technical agreements the standard initial step, with foreign equity participation following once operational footing was proven.
The transaction served complementary strategic aims. Norton secured direct access to a ring-fenced, tariff-protected domestic market that resisted standalone foreign entry. Grindwell gained continuous access to proprietary grain formulations, vitrified bond patents, and processing expertise from the global market leader. The resulting arrangement endured: for more than five decades, the Indian business has drawn upon its foreign partner's international research and development pipeline, an arrangement highlighted in the FY26 annual report as a foundational operating advantage.2
Surviving the License Raj
Between 1970 and 1990, industrial policy under the License Raj prioritized bureaucratic patience over rapid expansion. New capacity additions required government industrial permits, foreign exchange for imported capital equipment was tightly rationed, and overseas equity stakes faced statutory caps. Grindwell Norton could not unilaterally build out scale when industrial demand accelerated; management had to apply for capacity authorizations, de-bottleneck existing kilns, and allocate available production among domestic customers.
This regulatory climate insulated incumbent producers holding valid industrial licenses while fostering persistent capital discipline. Grindwell Norton adopted operational habits that define its corporate culture today: conservative leverage, brownfield debottlenecking over greenfield speculation, and reliance on overseas partner patents rather than capital-intensive domestic basic research. While those practices preserved balance sheet stability and high capital returns, Section V evaluates whether that inherited conservatism now acts as an operational constraint in high-growth adjacencies.
The fight in Worcester that changed Mora
The corporate restructuring that shifted Grindwell Norton's ultimate parentage from Massachusetts to Paris occurred during a hostile cross-border takeover. In March 1990, the British conglomerate BTR launched an unsolicited $1.64 billion tender offer for Norton Company at $75 per share.7 Norton's board, led by chairman John M. Nelson, mounted a defense, seeking white-knight bidders and petitioning federal courts to block BTR representatives from gaining board seats.79 In April 1990, Compagnie de Saint-Gobain entered with an agreed $90-per-share all-cash offer that valued Norton at roughly $1.9 billion, closing the transaction in August of that year.97 At the time of the acquisition, Saint-Gobain generated roughly $11 billion in annual sales.9 Norton gave the French group full horizontal coverage across all three primary categories of industrial abrasives: bonded grinding wheels, coated abrasive rolls and discs, and superabrasives.3
Norton's minority interest in Grindwell Norton transferred to Saint-Gobain as part of the transaction.6 Following India's 1991 economic reforms easing foreign direct investment caps, Saint-Gobain increased its equity stake in 1996, establishing Grindwell Norton as its first majority-owned operating subsidiary in India.6 While many multinational joint ventures from that era dissolved over royalty disagreements, technology transfer disputes, or parallel wholly owned subsidiaries, Grindwell Norton became the principal operational platform for Saint-Gobain's broader industrial footprint in the country.
The subsequent operating record demonstrates unusual stability. The partnership avoided public friction between foreign and domestic promoters, retaining the founding families as minority shareholders while preserving an operating structure characterized by French technical input, domestic operational management, and an independent board chair. Yet stability does not guarantee complete alignment. The formal relationship that grants Grindwell Norton privileged technology rights also defines clear operational boundaries, establishing corporate scope restrictions that represent a primary governance consideration for minority shareholders. Before evaluating those boundaries, the analysis turns to the core domestic abrasives duopoly that underwrites the company's operating cash flows.
III. The Indian Abrasives Duopoly: GNO vs. Carborundum Universal (CUMI)
Two companies, two philosophies
Picture two trade-fair booths side by side at an industrial engineering expo in Chennai or Pune. One displays the Norton logo under a Saint-Gobain banner, its marketing material emphasizing application engineering: part yields per wheel, cycle-time reductions, and microscopic surface tolerances. The other booth belongs to CUMI, the Carborundum Universal flagship of Chennai's Murugappa Group, and its narrative begins upstream at the smelter, showcasing fused alumina, silicon carbide, and zirconia synthesized from mined minerals. Both sell equivalent consumables to an identical customer base, yet each operates on a fundamentally different thesis regarding where economic value resides in abrasives.
Grindwell Norton's FY26 annual report addresses the competitive landscape directly, noting that the Indian abrasives industry "currently has two major players offering a full range" of products, that Grindwell Norton maintains market leadership, and that numerous smaller, mid-sized, and international producers operate along the periphery.2 An independent research assessment from 2023 estimated Grindwell Norton's share of the aggregate abrasives market at roughly 26% against CUMI's 25%, while placing Grindwell's share of the organised segment between 30% and 35%.10 While third-party estimates lack the precision of audited disclosures, the structural reality is clear: two domestic manufacturers of comparable scale anchor an otherwise fragmented competitive field.
What an abrasive actually is
The underlying product taxonomy reflects how material removal is engineered. An abrasive consists of hard mineral grains—primarily aluminium oxide, silicon carbide, or for demanding tolerances, synthetic diamond and cubic boron nitride (CBN)—bonded to a matrix or backing to shape workpieces with high precision.
- Bonded abrasives fuse mineral grains into solid geometric forms, predominantly wheels, using vitrified ceramic bonds or synthetic resins. These tools machine precision industrial components such as bearings, crankshafts, transmission gears, cutting inserts, and razor blades. Grindwell Norton produces more than 15,000 distinct product specifications annually, customized largely to order.2
- Coated abrasives adhere mineral grains to flexible backings of paper, cloth, or vulcanized fibre, converting them into sheets, belts, and discs. Non-woven abrasives—open-web synthetic fibre pads engineered for surface preparation and finishing—fall within this category.2
- Thin wheels comprise reinforced cutting and grinding discs mounted on handheld angle grinders across fabrication yards and building sites. Volume demand tracks the ongoing adoption of low-cost power tools replacing manual cutting techniques.2
- Superabrasives incorporate synthetic diamond or CBN for specialized high-hardness applications across automotive lines, precision bearings, solar wafer slicing, and semiconductor electronics.2
Functionally, a bonded precision wheel operates like a surgeon's scalpel, while a retail thin wheel resembles an over-the-counter utility blade. Both abrade metal, but their purchasing dynamics, switching costs, and pricing structures inhabit separate economic worlds.
Distribution channels diverge just as sharply. Precision abrasives sell directly to industrial accounts, with Grindwell Norton's application engineers frequently stationed inside customer plants to calibrate wheel composition to specific CNC grinding cycles. Retail abrasives reach independent fabricators and construction crews through tiered distribution networks and neighborhood hardware dealers. Grindwell Norton has moved to digitize both workflows. An in-house customer relationship management platform coordinates direct accounts and retail channel distribution, while channel partners place orders and track inventory through a dedicated portal and mobile application.2
That distribution footprint serves as a frontline defense in the retail tier, where low-cost Chinese imports and domestic paint manufacturers battle for dealer shelf space. An industrial consumable absent from the local distributor's counter when an artisan needs a replacement disc forfeits the sale, irrespective of brand prestige.
International shipments offer an incremental outlet. Total export revenue expanded to approximately ₹507 crore in FY26 from ₹470 crore in FY25, with abrasives serving as the principal driver.11 In discussions with capital markets analysts, management confirmed that the business carries no meaningful direct exposure to Middle Eastern markets.11 Exports represent a modest fraction of turnover, and overseas expansion remains constrained by Saint-Gobain's global production mapping, which dictates which regional markets Indian facilities may serve.
The economic engine
Abrasives remain Grindwell Norton's largest operating division by revenue. In FY26, the segment generated ₹1,491 crore, accounting for roughly 49% of consolidated net sales, reflecting top-line growth of approximately 6%. Segment operating profit reached ₹192 crore, yielding an operating margin of 12.9%.2 While stable, this profitability profile runs counter to market perceptions of a high-margin consumer-grade monopoly: abrasives contributed only about 39% of total segment operating profit in FY26.2 Segment margins have also oscillated within a constrained corridor for nearly a decade: hovering near 13.8% across FY18 and FY19, dipping to 11.5% during the FY20 industrial downturn, recovering to around 14% between FY22 and FY24, and softening to 12.9% in FY25.12
The underlying razor-and-blade dynamic is governed by the customer's cost structure. A crankshaft grinding wheel represents a fraction of an engine manufacturing budget, yet it determines component scrap rates, cycle throughput, and worker safety. A plant superintendent who substitutes an unproven wheel to shave 5% off tooling costs only to halt a transfer line has miscalculated industrial risk. Accordingly, Grindwell Norton's 2026 investor communications, summarized in research by Prabhudas Lilladher, emphasize transitioning from a "product-led" to a "solutions-led" engagement model, where commercial value is tied directly to customer uptime and process yield rather than unit shipments.11
End-market diversification provides structural insulation. Grindwell Norton reports that no single customer vertical represents more than 15% of total abrasives consumption, even though automotive original equipment manufacturers, Tier-1 component suppliers, and the automotive aftermarket collectively constitute a significant demand anchor.2
CUMI: the vertically integrated rival
Carborundum Universal pursues an antithetical operating architecture. CUMI is integrated upstream into electrominerals, refining the synthetic alumina, silicon carbide, and zirconia grains that abrasives converters consume, while pursuing cross-border scale via overseas acquisitions. That strategy produced consolidated FY26 revenue of ₹5,149 crore, significantly exceeding Grindwell Norton's top line.13 Yet vertical integration and geographical dispersion have introduced pronounced earnings volatility. In FY26, CUMI recognized ₹135 crore in exceptional charges, dominated by ₹119 crore associated with the voluntary liquidation of its German abrasives subsidiary, Awuko, alongside asset impairments at Foskor Zirconia in South Africa—an asset CUMI acknowledged in its earnings release had failed to deliver sustained profitability since FY2013.13
Compounding those headwinds, CUMI's Russian electrominerals subsidiary, Volzhsky Abrasive Works (VAW), was subjected to United States sanctions, depressing division-level profits.13 Consequently, CUMI's consolidated net profit attributable to shareholders contracted from ₹293 crore to ₹195 crore in FY26.13
At the group level, that divergence highlights Grindwell Norton's defensive strengths. Generating over twice CUMI's consolidated bottom line on a substantially smaller revenue base, Grindwell Norton incurred zero cross-border restructuring charges, while its disciplined FY26 capital expenditure of ₹119 crore stood well below CUMI's ₹309 crore commitment.213 Concentrating on domestic downstream conversion shielded returns on capital.
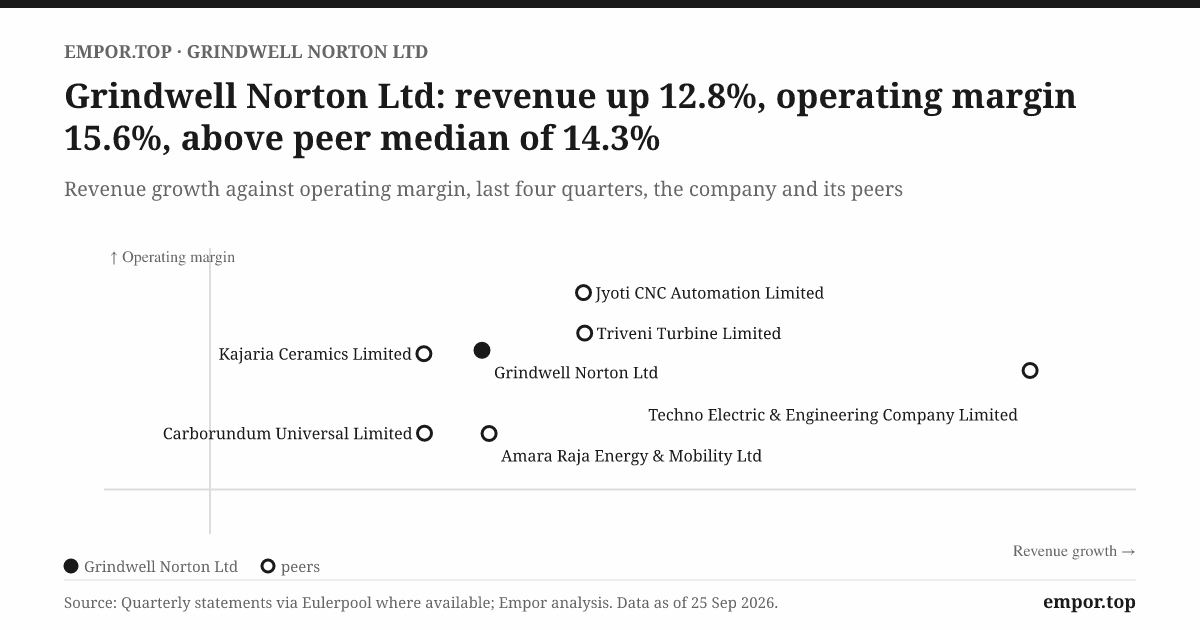
However, a granular examination contradicts the conventional market assumption that Grindwell Norton commands superior profitability in core abrasives. CUMI's standalone Indian abrasives operations generated FY26 revenue of ₹1,270 crore and profit before interest and tax (PBIT) of ₹194 crore—an operating margin near 15%, outperforming Grindwell Norton's 12.9% abrasives segment return on comparable revenue.132 Variations in corporate segment reporting warrant caution in drawing definitive conclusions.
Nevertheless, disclosed FY26 performance does not support the view that Grindwell Norton commands structural pricing premiums in domestic abrasives. While CUMI's consolidated abrasives division appears substantially diluted—reporting ₹97 crore of PBIT on ₹2,271 crore of turnover—that drag stems entirely from international units.13 Domestically, the two peers operate on roughly equivalent operational footing; Grindwell Norton's consolidated return premium reflects its avoidance of speculative overseas assets and the profit contribution of its non-abrasives businesses.
Adjacent competitors flank the duopoly. 3M India commands leadership in surface micro-finishing and specialized coated abrasives, while Wendt (India), an affiliated Murugappa Group entity, focuses on high-precision superabrasives.13 At the lower end, unorganized domestic converters compete strictly on price. Grindwell Norton's FY26 disclosures identify two emerging structural threats: domestic paints and adhesives manufacturers leveraging established retail distribution networks to "penetrate the market in a short period of time," alongside power-tool distributors importing private-label Chinese abrasives to bundle with equipment sales.2
Historical falsification: the abrasives moat test
The claim: Norton branding and Saint-Gobain technology protect Grindwell Norton's abrasives portfolio from commoditisation and price erosion.
The strongest evidence against it emerges from management's disclosures and operational performance. During the May 2025 analyst meeting, leadership disclosed that approximately one-third of the abrasives portfolio faces direct Chinese competition in the domestic market, concentrated in commodity coated rolls, non-woven pads, and thin wheels.12 In FY25, abrasives revenue grew by just 3.3%, while segment margins contracted by roughly 100 basis points to 12.9%, weighed down in part by higher depreciation charges on newly commissioned lines.12 Grindwell Norton's FY26 risk disclosures explicitly caution that "with multiple global Abrasives players focusing on India, some pressure on the Company's key, high-margin products can be expected."2 During the fourth quarter of FY26, abrasives revenue rose 15% year-on-year while operating margins remained flat, an outcome management and research analysts attributed to aggressive pricing by Chinese importers, subdued export demand, and heightened domestic rivalry.14
Upstream raw material exposure introduces an additional vulnerability. Grindwell Norton imports a substantial portion of its crude and processed abrasive grains, exposing gross margins to fluctuations in international mineral benchmarks and currency depreciation.10 Unlike CUMI, Grindwell Norton does not operate captive bauxite mines or electro-fusion smelters capable of hedging grain inflation. Management's FY26 review of its performance polymers segment similarly identifies rupee depreciation as an ongoing margin risk because of that unit's import intensity.2
The counterevidence is tangible as well. In FY26, leadership cited "a measurable improvement in market standing against a key competitor in India," with segment sales and operating earnings both expanding by approximately 6%.2 At the June 2026 analyst briefing, management highlighted market-share gains driven by localized product development and digital channel integration.11 Regulatory shifts, including the rationalization of export incentives on foreign products and a depreciating rupee, increased landed import costs, partially insulating domestic manufacturers.11 Grindwell Norton also took strategic equity in a domestic coated-abrasives paper manufacturer to mitigate dependence on imported backing substrates, while ramping up a continuous non-woven production line commissioned in 2024 to support domestic demand and export allocations.1211
Verdict: Historical execution qualifies the thesis. A durable economic moat exists across precision bonded wheels, superabrasives, and customized engineering solutions, where customer qualification hurdles, application engineering, and the steep cost of component failure deter switching. Conversely, the moat is negligible in standard thin wheels and utility coated sheets, where private labels, paint company distributors, and low-cost Chinese imports compete on transaction price. Even in precision tooling, bonded wheels contend against specialized European manufacturers rather than Chinese exporters.12 In semiconductor-grade superabrasives, the most sophisticated tools continue to be imported from Saint-Gobain's global facilities rather than manufactured domestically.11 The key metric for testing this narrower advantage over an industrial cycle is the division's operating margin. A franchise commanding authentic pricing power should recover to and sustain the 14% margins recorded between FY22 and FY24 as new capacity is absorbed. An operating margin lingering near 13% despite volume expansion would demonstrate that the premium brand is defending market share through price concessions rather than genuine pricing power.
If the abrasives division merely compounds in step with broader industrial activity at low-teens operating margins, it cannot by itself rationalize a 50-times multiple. That valuation rests on a secondary portfolio that public equity markets frequently overlook.
IV. Up the Value Chain: The High-Margin Ceramics & Plastics Pivot (2000–2024)
Inside the furnace
Consider a secondary steel plant—an induction furnace in the industrial belts of Punjab or Chhattisgarh—melting scrap metal into billets around the clock. The refractory lining shielding that furnace dictates how many operational heats the melt shop achieves before shutting down for a costly relining. A refractory formulation that endures ten additional heats delivers economic value far exceeding its initial purchase price.
Grindwell Norton's Performance Ceramics and Refractories business built a structured customer-retention initiative around this operating reality, branded as the "Steel Club." Through the programme, the company conducts regular training sessions at customer facilities and its own plants, focusing on furnace operating practices, metallurgical quality, and energy efficiency.2 The commercial mechanism mirrors the abrasives razor-and-blade model transferred to high-temperature metallurgy: the customer purchases plant uptime and component yield, while the consumable material serves as the delivery vehicle.
From side business to profit engine
The Ceramics & Plastics (C&P) segment represents the most significant structural evolution in Grindwell Norton's modern corporate history. In FY14, the division contributed roughly 27% of consolidated turnover and 28% of operating profit (EBIT); by FY23, those proportions had expanded to approximately 41% of revenue and fully half of operating earnings.10 For FY26, the division reported revenue of about ₹1,311 crore, marking a 10% increase, while segment operating profit rose roughly 15% to ₹231 crore, translating to an operating margin of 17.6%.2 Consequently, the segment now produces more operating profit than the legacy abrasives business on a smaller revenue base.
Yet the division's margin trajectory has proved far less linear than secular compounder narratives assume. Institutional brokerage data trace C&P operating margins from a band of 14% to 15% between FY18 and FY20, surging to between 23% and 24% during FY21 and FY22, holding near 23% in FY23, before compressing to 19.6% in FY24 and 17.6% in FY25.12 The operational drivers behind that compression are instructive. During the May 2025 analyst briefing, management conceded that the FY23 margin peak had been propelled by extraordinary post-pandemic export orders from United States pharmaceutical manufacturers, cautioning investors that the division was unlikely to recapture 20%-plus margins in the absence of comparable life-sciences windfalls.12
Much of the margin expansion recorded during the early 2020s was cyclical rather than structural. Operating performance rebounded in the fourth quarter of FY26, when C&P revenue expanded 23% year-on-year and operating margins recovered to 19.7%, followed by a roughly 45% increase in segment operating results in the first quarter of FY27.1415 While that operational rebound is tangible, it spans only a handful of quarters, and executive management itself has explicitly discouraged extrapolating peak margins across an entire industrial cycle.
The four pillars
1. Silicon carbide (Tirupati and Bhutan). Silicon carbide is an ultra-hard synthetic mineral synthesized by reacting high-purity silica sand and petroleum coke at extreme temperatures in electric furnaces, serving vital roles across bonded abrasives, high-temperature refractories, iron foundries, and stone polishing.2 Because the electro-thermal synthesis requires massive electric power inputs, production economics hinge on low-cost baseload energy—explaining the strategic geography of the company's smelters. Grindwell Norton manufactures silicon carbide at Tirupati in Andhra Pradesh and through Saint-Gobain Ceramic Materials Bhutan, a manufacturing subsidiary located near Phuentsholing. While corporate consolidated accounts show Grindwell Norton holding a 70% equity stake in the Bhutanese operating entity, the directors' report categorizes the unit as "wholly-owned."2 Proximity to Himalayan hydroelectric generation established the foundational investment logic.
Operating results in FY26, however, challenged the proposition that captive smelting provides a permanent competitive moat. In its annual review, management acknowledged "a difficult year for the Silicon Carbide business," citing reduced sales volumes and compressed operating earnings driven by low-priced imports, while noting that the Bhutanese operating subsidiary faced headwinds from "increased power and input costs."2 The domestic market is contested by three primary Indian manufacturers alongside aggressive merchant shipments originating from China, Vietnam, and Russia.2 While management articulated expectations that evolving geopolitical supply friction would benefit domestic producers in FY27, that guidance remains a forward-looking assumption rather than an accomplished operational outcome.2 Favorable power geography offers a partial cost buffer, but it has not insulated division margins against cross-border price deflation.
2. Performance ceramics and refractories. Operating manufacturing plants in Bengaluru and Halol in Gujarat, this division manufactures engineered refractories for primary blast furnaces, secondary electric-arc melt shops, non-ferrous metallurgical lines, petrochemical processing, carbon black reactors, and waste-to-energy facilities, alongside technical ceramic components for sanitaryware kiln furniture, tableware, industrial wear resistance, and ballistic personnel armour.2 To deepen its technical offering, the company broadened its long-standing technology partnership with Japan's 品川リフラクトリーズ Shinagawa Refractories, expanding beyond tap-hole clays into blast-furnace trough and runner castable formulations marketed under co-branded arrangements.2 During FY26, Grindwell Norton installed additional production capacity at Halol for silicon-impregnated and reaction-bonded silicon carbide—advanced engineered ceramics engineered for severe thermal shock and abrasive wear environments.2 Management also secured freehold industrial land adjacent to the Halol complex to support long-term greenfield and brownfield expansion.2 Complementing these investments, the company commissioned a second tap-hole clay manufacturing line in FY26 and substantially completed an expansion at its Alathur ceramics facility in Tamil Nadu.11 However, export shipments originating from Alathur scaled at a slower pace than initially budgeted due to pending North American regulatory and customer qualification approvals.11
The product suite extends well beyond ferrous steelmakers. The company identified petrochemicals as "a very strong area of growth," driven by sustained capital deployment into carbon black manufacturing, synthetic gasification, and catalytic reforming. Grindwell Norton supplies high-performance refractory linings engineered for liquid- and solid-feedstock gasifiers, as well as secondary reforming solutions for commercial fertilizer complexes.2 In thermal processing, the division upgraded its proprietary "Total Burner Solutions" systems for steel annealing and continuous galvanizing furnaces, which leadership reports reduces customer fuel consumption while lowering emissions of nitrogen and sulphur oxides.2 While these individual product lines represent niche revenue streams, collectively they demonstrate a deliberate strategic pivot away from marketing undifferentiated refractory bricks toward engineering comprehensive thermal-containment systems that resist direct price commoditization. Concurrently, Grindwell Norton's manufacturing joint venture, Advanced Synthetic Minerals, completed debottlenecking and quality-enhancement initiatives in FY26, expanding top-line revenue by approximately 15%.2
The commercial defensibility of performance refractories rests on steep switching costs. A structural failure or premature wear-out in a blast-furnace hearth or a petrochemical gasifier forces unbudgeted production shutdowns, idling downstream processing assets and generating losses that dwarf any initial savings on refractory procurement. Consequently, plant managers rarely substitute proven refractory formulations for untested suppliers. Nevertheless, the business remains closely tied to cyclical capital expenditure cycles across steel, basic chemicals, and flat glass. FY26 performance illustrated that macro vulnerability: robust domestic demand drove internal volume gains, but export shipments contracted amid global geopolitical friction and United States tariff barriers.2
3. Performance Polymer Solutions (PPS). Among Grindwell Norton's divisions, Performance Polymer Solutions is the least understood by public equity markets, yet it commands the highest theoretical economic moat. Operating from specialized plants in Bengaluru and Ambernath, Maharashtra, the division encompasses five specialized business lines: EQYO (automotive PTFE bearings and precision-moulded components), Omniseal Solutions (spring-energised polymer and metal seals engineered for cryogenic and extreme-pressure environments), Life Sciences (pharmaceutical-grade silicone and thermoplastic tubing, single-use fluid-handling bags, and manifold assemblies), Tape Solutions (specialty adhesive films, wire-harness tapes, and thermal foams for electric vehicles), and Performance Film Solutions.2 Reflecting stringent production standards, the Ambernath manufacturing facility maintains AS 9100 aerospace certification alongside IATF 16949 automotive compliance.2 At the June 2026 institutional investor briefing, leadership highlighted a roster of advanced applications: fluoropolymer Furon-branded fluid-handling tubing and valves for semiconductor fabrication plants, spring-energised seals for space launch vehicles, compressive thermal-runaway barriers and dielectric insulation tapes for electric-vehicle battery packs, and complete gamma-irradiated single-use assemblies for commercial biopharmaceutical manufacturing.11
The economics of single-use bioprocessing provide a compelling case study in customer lock-in. Manufacturing monoclonal antibodies or vaccines resembles pharmaceutical brewing conducted under strict aseptic conditions. Traditional biomanufacturing relies on fixed stainless-steel bioreactors that require exhaustive cleaning and regulatory re-validation between production campaigns. Modern facilities increasingly substitute these with pre-sterilized, single-use polymer liners, tubing sets, and fluid manifolds that are deployed once and discarded. When a biopharmaceutical company secures regulatory approval for a commercial drug using a designated tubing or bag assembly, that component is written into the drug master file submitted to health authorities. Switching to an alternative supplier requires costly comparability testing and regulatory re-filing, creating substantial switching costs that protect incumbent margins.
Nevertheless, PPS execution has demonstrated sharp earnings volatility. Following the pandemic-era export surge in FY23, management cautioned analysts in May 2025 that life-sciences export demand remained depressed and was "unlikely to recover soon."12 By June 2026, leadership reported that export shipments of single-use assemblies to European and North American accounts had resumed following protracted customer qualifications, forecasting that volumes would "scale gradually."11 While that commercial resumption stabilizes the division's growth outlook, the multi-year hiatus illustrates the extended validation lead times required before specialized design wins translate into steady operating cash flows.
4. ADFORS and other materials. A niche business line converts Saint-Gobain's proprietary ADFORS technical textiles, providing industrial-grade geogrids and high-tenacity polyester reinforcement meshes used in open-cast mining and civil infrastructure.10 While operationally profitable, its financial scale remains modest relative to the broader enterprise.
Historical falsification: the "advanced materials compounder" test
The claim: The expansion of Ceramics & Plastics transforms Grindwell Norton from a cyclical industrial supplier into a structural, high-margin advanced materials compounder.
The supporting evidence is compelling. Over the decade leading to FY24, the division's contribution to consolidated operating profit expanded from 28% to nearly 50%.10 C&P systematically outpaced the core abrasives portfolio across the cycle, driving its revenue contribution from approximately a quarter of sales to more than 40%.10 The business continues to introduce mission-critical consumables tailored to structural growth markets, including semiconductor manufacturing, ballistic defense armour, space flight systems, and commercial biopharmaceuticals.
The counterevidence highlights persistent cyclicality. The division's operating margin curve—climbing from 15% in FY20 to a peak near 24% in FY22 before retreating toward 17.6% in FY25—demonstrates that the post-pandemic profit surge was heavily amplified by transient export demand rather than permanent pricing power.12 In merchant silicon carbide, domestic pricing power eroded under pressure from lower-cost Asian imports in FY26, while refractory export volumes contracted under foreign tariff headwinds.2
Commercial commercialization timelines also frequently lag corporate announcements. Ceramic defense armour provides a clear example of the friction between manufacturing readiness and revenue realization: while Halol capacity additions were completed and ballistic qualification testing was characterized as "on track" in May 2025, neither management disclosures nor sell-side research have documented meaningful commercial revenues from defense sales since that date.12 Furthermore, the transition toward electric vehicles carries structural trade-offs. While Performance Polymer Solutions supplies adhesive thermal foams and dielectric barrier tapes for EV battery packs, an electric drivetrain completely eliminates precision-ground internal combustion components such as camshafts, crankshafts, and multi-speed transmission gearing—historically the most consumable-intensive grinding applications in automotive manufacturing. Disclosed portfolio reviews by management acknowledge that its commercial EV exposure consists almost exclusively of polymer tapes and thermal pads rather than high-margin bonded grinding wheels.11
Verdict: The advanced materials thesis survives, but in a significantly more qualified form. Ceramics & Plastics has broadened the enterprise's operating scope and elevated consolidated returns on capital. In particular, Performance Polymer Solutions exhibits the classical attributes of a specialty compounder: multi-year qualification barriers, high switching costs, and continuous technical leverage derived from Saint-Gobain's global research pipeline. Yet diversification has not insulated the business from industrial capital expenditure cycles, and management has explicitly reined in expectations for segment margins above 20%. The critical operational test for this transition will occur during the next cyclical downturn in domestic steel or petrochemical capital expenditure: if Ceramics & Plastics sustains operating margins in the high teens while abrasives volume contracts, the structural compounding thesis will stand verified.
Crucially, this portfolio transformation was engineered almost entirely through organic capital allocation and brownfield expansion. Section V examines the rare exception to that internal playbook—the 2022 acquisition of PRS Permacel—and evaluates a mounting cash reserve that tests what corporate governance permits management to do with its balance sheet.
V. Capital Deployment & M&A: The PRS Permacel Acquisition Benchmark
The conservative default
For most of its listed history, Grindwell Norton's capital allocation has followed a straightforward formula: fund brownfield capacity from operating cash, lift the dividend payout ratio, and park the residual surplus in liquid treasury assets. Financial disclosures illustrate the predictability of this model. In FY26, the company generated approximately ₹542 crore of consolidated operating cash flow and deployed about ₹119 crore into property, plant, and equipment, up from ₹94 crore in FY25.2 Over the past decade, the dividend payout ratio advanced from the mid-30% range to roughly 51% across FY25 and FY26,1 culminating in a board-recommended dividend of ₹19 per share for FY26.14
Capital spending accelerated in FY26 toward longer-term capacity. Capital work in progress on the Halol performance ceramics and refractories expansion climbed to about ₹16.6 crore at the close of March 2026 from ₹2.2 crore a year earlier, alongside the acquisition of contiguous freehold industrial land at the same site.2 Yet these commitments remain modest relative to operating cash generation. The cadence is classic Grindwell Norton: capital deployment occurs in modular phases, within existing manufacturing hubs, across businesses with demonstrated unit economics, and without debt financing. While this discipline shields the balance sheet from execution risk, it also cannot absorb the cash flow the underlying franchise generates.
The unallocated balance has accumulated accordingly. By March 2026, the consolidated balance sheet carried roughly ₹1,489 crore in treasury investments and cash balances unassigned to operating divisions, a sum that includes an equity holding in unlisted sister company Saint-Gobain India Private Limited (SGIPL), examined in Section VI.2 Excluding that corporate investment, approximately ₹1,170 crore of surplus liquid assets sits on a consolidated balance sheet of about ₹3,440 crore. Earlier market commentary pegged the group's cash reserve at ₹400 crore to ₹600 crore; while accurate in previous cycles, that range substantially understates current liquidity.
This cash buffer creates a structural drag on headline returns. At the operational level, the underlying assets generate exceptional capital productivity. At the end of March 2026, segment assets of roughly ₹1,871 crore against segment operating liabilities of about ₹784 crore implied an operating capital base of approximately ₹1,090 crore. On that operating base, the company generated ₹498 crore in pre-tax segment earnings, reflecting a pre-tax return above 40% on capital actively deployed in operations.2 However, consolidated return on equity stood at roughly 16% and return on capital employed at about 21%, because nearly half the asset base consists of low-yielding treasury balances and corporate stakes.1 In FY26, treasury interest income contributed about ₹17 crore, alongside an additional ₹49 crore in unallocated corporate income.2 Grindwell Norton runs an efficient industrial operating machine encased in an increasingly passive balance sheet.
The May 2022 exception: PRS Permacel
Grindwell Norton's single material acquisition during this era was modest in scale, yet it provides an instructive test of management's willingness to deploy capital externally. On May 6, 2022, the company entered into an agreement to acquire PRS Permacel Private Limited, an Indian manufacturer of specialty adhesive tapes and thermal insulation labels, closing the transaction on May 27, 2022, for a net cash consideration of ₹121.1 crore.1617 Permacel originated within the PRS Group, an industrial enterprise founded by the Premchand family in 1856.
Permacel operated a manufacturing facility in Ambernath near Mumbai with a workforce of 176 employees, supplying engineered adhesive solutions and insulation products to industrial manufacturers, Indian Railways, urban metro networks, two-wheeler builders, and electric-vehicle platforms.18 EY acted as financial adviser to Grindwell Norton, while Allegro Capital advised the seller.18 From a strategic standpoint, Saint-Gobain sought to integrate Permacel's production lines into its Composite Systems business unit, aligning with the parent group's global "Grow & Impact" strategic roadmap.18
Valuation metrics reflected an asset turnaround thesis. In FY21, the final full fiscal year disclosed prior to the transaction, Permacel generated revenue of about ₹126 crore and net profit of roughly ₹2.3 crore.16 Grindwell Norton paid approximately 1.0 times sales—a reasonable entry multiple for specialty technical adhesives—but more than 50 times trailing net earnings. The transaction was optically inexpensive on top-line scale yet full on trailing earnings, predicated on the assumption that Saint-Gobain's formulation chemistry, global procurement scale, and customer access could lift operating margins from low single digits toward group thresholds.
Because the ₹121 crore cash outlay represented less than a quarter of a single year's operating cash generation, execution stumbles carried negligible balance sheet risk. The transaction was formalized when the National Company Law Tribunal approved the scheme of amalgamation in 2023, merging Permacel into Grindwell Norton with retrospective operational effect from the acquisition date.19
What happened next
Post-merger integration encountered immediate headwinds. During the May 2025 institutional investor meeting, management disclosed that rapid platform redesigns and component configuration shifts among domestic EV customers had triggered volume declines and product phase-outs for certain legacy Permacel lines. Leadership responded by recalibrating the product pipeline toward engineered battery pack seals, compression and thermal-runaway pads, and dielectric insulation films.12 Operational traction improved over the subsequent year. At the June 2026 analyst briefing, management confirmed that Permacel had been fully absorbed into the Tape Solutions division, that earlier factory labor disruptions had been resolved, and that the acquired business had exceeded internal budget forecasts for revenue expansion and operating profitability, prompting the board to evaluate follow-on capacity additions.11
Historical falsification: the M&A execution test
The claim: Grindwell Norton can deploy its liquid balance sheet as an industrial aggregator, consolidating fragmented domestic manufacturers across specialty consumables and performance materials.
The evidence: The empirical record rests on a single acquisition, and the findings are inconclusive. Management exercised pricing discipline on top-line revenue and avoided the speculative cross-border write-downs that burdened peer Carborundum Universal. Executive commentary also indicates that the acquired asset is tracking ahead of its initial turnaround plan. Conversely, the operational integration required significant remediation, navigating automotive design obsolescence and site-level industrial labor disputes. Because Grindwell Norton does not separately break out Permacel's post-acquisition turnover or division-level operating margins, management's assertion that the asset has exceeded expectations cannot be independently audited through regulatory disclosures. More fundamentally, four years after the Permacel acquisition, leadership has completed no subsequent transactions, allowing cash reserves to accumulate without strategic redeployment.
Verdict: The industrial platform-aggregator thesis remains unproven. Grindwell Norton has demonstrated that it will not overpay for corporate targets and can stabilize a small, troubled operating site. It has not established that it can source, execute, or integrate acquisitions at a scale capable of moving the consolidated needle. Validating this aggregator thesis requires two tangible milestones: a second, transparently disclosed transaction in technical materials, and segment-level margin evidence demonstrating that specialty tapes are accreting to, rather than diluting, Performance Polymer Solutions returns.
The ultimate constraint on aggressive capital deployment, however, may not stem from managerial risk aversion in Mumbai. It reflects how Saint-Gobain delineates operational scope across its various corporate entities in India.
VI. The French Parent Dynamic: Saint-Gobain Governance, Royalties, & Unlisted Sisters
Two companies, one parent
In February 2025, Saint-Gobain completed a $1.025 billion cash acquisition of FOSROC, a construction chemicals manufacturer based in Dubai with an extensive operating presence across India, the Middle East, and the Asia-Pacific region. The transaction added roughly $487 million in annual sales alongside 20 manufacturing facilities.20 A year later, Saint-Gobain’s 2025 annual review reported that its Indian operations had captured incremental market share through an expanding portfolio of light and sustainable construction solutions, integrating FOSROC and securing major commercial project wins, including the new international airport in Navi Mumbai.4
None of that growth flowed through Grindwell Norton. It was channelled entirely through Saint-Gobain's unlisted corporate network in India, where Saint-Gobain India Private Limited (SGIPL) houses the parent group's architectural flat glass, gypsum plasterboard, and construction chemicals assets. This bifurcation highlights the central governance dynamic confronting minority shareholders in Grindwell Norton. Public investors secure privileged access to Saint-Gobain's proprietary materials science and process formulations, but strictly within the operational boundaries Paris assigns to the listed vehicle: abrasives, technical ceramics, silicon carbide, performance polymers, and a captive digital services centre. Saint-Gobain’s fastest-growing Indian verticals—high-volume construction solutions and specialty building chemicals—remain sequestered outside that perimeter.
Yet the corporate separation contains a nuance frequently overlooked in public analyses. Grindwell Norton holds roughly 28.5 lakh equity shares in SGIPL, carried on its consolidated balance sheet at a fair value of approximately ₹315 crore at the end of March 2026, up from roughly ₹260 crore twelve months earlier.2 Statutory auditors flagged the valuation of this unquoted sister-company holding as a key audit matter: the carrying value is derived from an independent appraiser's discounted cash flow model premised on a weighted average cost of capital of about 14.6% and an assumed terminal operating margin near 19%. A single-percentage-point shift in either assumption moves the equity valuation by approximately ₹15 crore to ₹30 crore.2 The listed company thus retains a modest indirect economic participation in its unlisted sibling's compounding. However, representing roughly 1.4% of Grindwell Norton's total market capitalisation, this minority holding is too fractional to bridge the structural divide between the two corporate vehicles, while its carrying value remains inherently tethered to internal group projections.
The price of the passport
A more direct and recurring financial obligation is the technology royalty. For FY26, Grindwell Norton reported consolidated royalty expenses of roughly ₹54 crore, rising from about ₹48 crore in FY25 and representing approximately 1.8% of net operational revenue.2 The primary beneficiary was Saint-Gobain Abrasives Inc. in the United States, which received approximately ₹33.5 crore.2 Concurrently, that same American entity and the French holding company SPAFI collected roughly ₹97 crore in shareholder dividends during the fiscal year.2
Evaluating the fairness of this royalty requires balancing two perspectives. By the prevailing benchmarks of multinational industrial subsidiaries in India, where royalty and technical fees frequently run between 3% and 5% of turnover, an effective rate below 2% is comparatively modest. Corporate disclosures underline that Grindwell Norton enjoys comprehensive access to Saint-Gobain's global research and development infrastructure, drawing on advanced materials laboratories in Northborough, Massachusetts, alongside Saint-Gobain Research India in Chennai.2 Conversely, Grindwell Norton’s internal standalone research expenditure amounted to just 0.16% of revenue in FY26.2 The Indian enterprise operates with almost complete reliance on its foreign parent for foundational formulation chemistry and process patents.
This arrangement is operationally capital-efficient, but it establishes royalty remittances as the principal conduit for upstream value transfer to Saint-Gobain. Because the remittance is calculated as a fixed percentage of sales, the absolute rupee payout expands automatically with volume growth, regardless of how much application engineering or local process adaptation is executed by domestic teams in Mora or Bengaluru. The royalty rate remains stable as a proportion of turnover, but absolute cash outflows compound upward while technological dependency runs strictly one way. An activist institutional shareholder would not necessarily demand the elimination of the royalty, but would reasonably press the audit committee to publish a transparent, benchmarked royalty transfer policy.
INDEC: a profitable captive with a ceiling
Beyond industrial materials, Grindwell Norton houses the India Development Centre (INDEC), Saint-Gobain's global captive information technology hub. Operating from India, INDEC delivers enterprise application development, digital infrastructure management, and cybersecurity services to Saint-Gobain business units across the world.2 What originated as an ancillary support function has evolved into a meaningful contributor to consolidated earnings: in FY26, the Digital Services division generated approximately ₹222 crore in revenue, expanding 21% year-on-year, and delivered segment operating profit of roughly ₹58 crore—an operating margin of about 26%.2 That margin surpasses the profitability of both industrial operating segments.
The company's statutory filings, however, delineate clear structural limits to this expansion. Employing roughly 650 technical personnel, the captive centre operates strictly under a "cost-plus model." Management's operational review notes explicitly that "growth in this segment is limited and future growth can happen only on account of cost inflation," with division earnings further subject to foreign-exchange volatility and hedging outcomes.2 Grindwell Norton’s most lucrative segment by margin is, by design, an internal cost-centre pass-through whose pricing power and workflow volumes are determined entirely by the overseas parent. It generates steady cash flow and demands minimal capital expenditure, but it represents a captive service contract rather than an autonomous compounder. Equity investors who value Digital Services at multiples typical of independent IT services exporters misunderstand its underlying economic architecture.
Stress test: what an activist would ask
A disciplined minority investor evaluating Grindwell Norton's governance would concentrate on four structural issues. The first is corporate scope: there is no publicly disclosed, legally binding charter defining which product adjacencies belong to listed Grindwell Norton and which are reserved for unlisted SGIPL. The second is balance sheet efficiency: unallocated liquidity of roughly ₹1,170 crore earns passive treasury yields on the balance sheet, even as actively deployed operating capital generates pre-tax returns above 40%. The third is transfer pricing: technology royalties, captive IT billing schedules, intra-group raw material purchases, and the valuation models governing the SGIPL equity stake all involve related-party negotiations with Paris. The fourth is granular disclosure: post-acquisition unit economics for PRS Permacel, division-level profitability for merchant silicon carbide, and the revenue conversion timeline for ceramic defense armour remain undisclosed in statutory reporting.
To date, the public record reveals no overt shareholder friction. Grindwell Norton’s board is led by an independent chairman, and the audit committee routinely pre-approves related-party contracts under statutory regulatory frameworks.2 The multinational arrangement functions smoothly, but its structural benefits accrue predominantly to the foreign parent. Minority shareholders shoulder that governance trade-off through an elevated valuation multiple rather than overt cash leakage. Whether that compromise remains compelling depends on how enduring the company’s competitive moat proves when tested against cyclical headwinds and structural industry transitions.
VII. Powers, Moats, & The Historical Falsification Layer
A test in Coimbatore
Consider a tool-room supervisor in Coimbatore facing a batch of hardened alloy steel dies and a choice among three grinding wheels. A Norton wheel carries a noticeable price premium. A CUMI wheel costs slightly less. An unbranded import costs a fraction of either. If the supervisor has previously scrapped an expensive workpiece with a defective wheel, the decision is straightforward: process reliability and component yield comfortably outweigh the initial procurement cost. If the task is rough deburring on a construction site, the economic calculation reverses just as quickly. Grindwell Norton’s competitive moat is fundamentally an aggregation of these discrete shop-floor decisions, looking either formidable or fragile depending on who makes them. Strategy frameworks provide genuine analytical clarity only if they respect that operational divide.
Hamilton Helmer's 7 Powers
Process Power: High in bonded wheels and engineered ceramics. Dynamic wheel balance, grain-bond chemical recipes, precise thermal firing curves, and custom refractory formulations represent tacit operational knowledge accumulated across eight decades at Mora, Bengaluru, and Halol, drawing directly on technical lineage from Worcester. Corporate disclosures corroborate this dynamic: management explicitly noted that its primary competition in high-precision bonded wheels originates from specialized European manufacturers rather than low-cost Asian exporters.12 In specialized industrial categories where proprietary process parameters dictate manufacturing yield, low-cost rivals have struggled to gain meaningful traction.
Switching Costs: High in precision tooling and regulated niches; negligible in commodity lines. Single-use polymer tubing specified in biopharmaceutical drug master files, engineered refractory linings qualified for continuous blast-furnace campaigns, and cryogenic seals certified for space launch vehicles all require prolonged, capital-intensive customer requalification. The opposite holds across retail thin wheels and standard coated abrasives, where low-cost Chinese imports and domestic paint company distributors have captured dealer shelf space with minimal resistance.2
Branding: Moderate to high, yet economically bifurcated. In machine shops and distribution corridors across India, the Norton badge serves as a recognized shorthand for dimensional precision and shop-floor safety, with executive leadership citing "strong brand equity, built over decades" as a primary competitive differentiator.2 Brand equity, however, does not translate automatically into unconstrained pricing power: operating margins in the core abrasives division have remained confined below 14% for nearly a decade.12
Cornered Resource: Moderate, and leased rather than owned. The company’s genuine cornered asset is continuous, privileged access to Saint-Gobain’s advanced materials research, proprietary grain chemistry, and international patent portfolio.2 That advantage is tethered directly to the multinational parentage and requires a recurring royalty payout of roughly 1.8% of operational sales. Similarly, low-cost Himalayan hydroelectric power at the Bhutan silicon carbide smelter initially mirrored a structural cost advantage, yet FY26 operating performance demonstrated that captive smelting can still be undercut by low-priced overseas merchant supply and rising local utility tariffs.2
Scale Economies: Moderate. A nationwide distribution footprint, an extensive portfolio of over 15,000 distinct product specifications, and consolidated raw material procurement afford Grindwell Norton scale advantages against smaller regional converters. They provide little insulation, however, against massive state-backed Chinese manufacturers operating with substantial global volume advantages.
Network Effects: Non-existent. Industrial abrasives, technical ceramics, and polymer seals generate no positive consumption externalities; a product’s utility does not expand as other industrial plants adopt it.
Counter-Positioning: Negligible internally, with emerging threats from outsiders. Domestic paint and adhesives manufacturers leveraging their dense existing dealer networks to distribute retail abrasives are actively counter-positioning against Grindwell Norton’s higher-touch industrial distribution model.2
What the powers add up to
Synthesizing these dynamics reveals a defining characteristic of the enterprise. Grindwell Norton’s most durable defenses reside in process power and switching costs—attributes that depend on continuous, high-touch application engineering inside customer facilities rather than top-down scale economies or consumer-style advertising campaigns. This distinction carries practical operational consequences. The economic moat is ultimately maintained by people: application engineers calibrating wheel bonds to CNC grinding cycles in a bearing plant, refractory engineers training melt-shop crews through the Steel Club, and technical teams qualifying polymer tubing for biologics suites.2
Were leadership ever to pare back technical service teams to defend short-term margins in an industrial downturn, the competitive moat would quietly degrade long before the erosion appeared in financial statements. The company’s strategic transition toward a "solutions-led" engagement model—anchoring commercial value to customer uptime and process yields rather than unit sales—directly reflects this reality.11 It remains a proposition that can only be validated over an entire capital expenditure cycle through customer retention and realized margins, rather than an isolated set of quarterly figures.
Porter's Five Forces
- Threat of new entrants: Low in precision engineering; rising across the commodity tier. Sophisticated kiln chemistry, specialized bonding formulations, safety certifications, and lengthy customer qualification cycles protect bonded precision wheels and engineered refractories. In utility lines, however, statutory filings document new entrants and importers capturing market share rapidly across power-tool accessories and retail thin wheels.2
- Supplier power: Moderate to high. Grindwell Norton depends on imported crude and processed grains, synthetic resins, and specialty polymer feedstocks, with management repeatedly identifying rupee depreciation, raw material inflation, and energy cost volatility as persistent operating risks across multiple segments.210
- Buyer power: Asymmetric. Independent fabricators and local hardware dealers wield minimal bargaining leverage. Conversely, large automotive manufacturers and tier-one steel producers run structured multi-vendor procurement programmes, routinely using CUMI and European specialists to check Grindwell Norton’s pricing.
- Threat of substitutes: Low to moderate. Grinding remains irreplaceable for sub-micron surface finishing on hardened metals, but systemic industrial shifts—including near-net-shape casting, additive metal manufacturing, and the transition toward electric vehicles—structurally reduce the volume of metal removal required per vehicle.
- Rivalry: Disciplined duopoly at the high end; transactional price competition at the base. Grindwell Norton and Carborundum Universal compete primarily on product performance, customer service, and technical uptime in organized domestic accounts, while fragmented converters and Chinese imports wage aggressive price wars in retail channels.
The consolidated falsification matrix
Claim 1: "A pristine balance sheet proves exceptional capital stewardship." Grindwell Norton carries zero long-term debt, has avoided shareholder dilution and asset write-downs, and has steered clear of destructive cross-border mega-acquisitions. That discipline is real. Yet treasury investments and unallocated cash balances represent approximately 43% of total assets, explaining why consolidated return on equity hovers near 16% even while capital deployed in operating divisions generates pre-tax returns above 40%.21 While the board has gradually expanded the dividend payout ratio, it has executed no share buybacks to return surplus cash. Verdict: Narrowed. Capital stewardship has been exceptionally prudent, but distinctly passive. The critical metric to track is unallocated cash as a proportion of total assets: true capital stewardship would be demonstrated by reducing that ratio, either through disciplined redeployment into high-return operating assets or through expanded shareholder distributions.
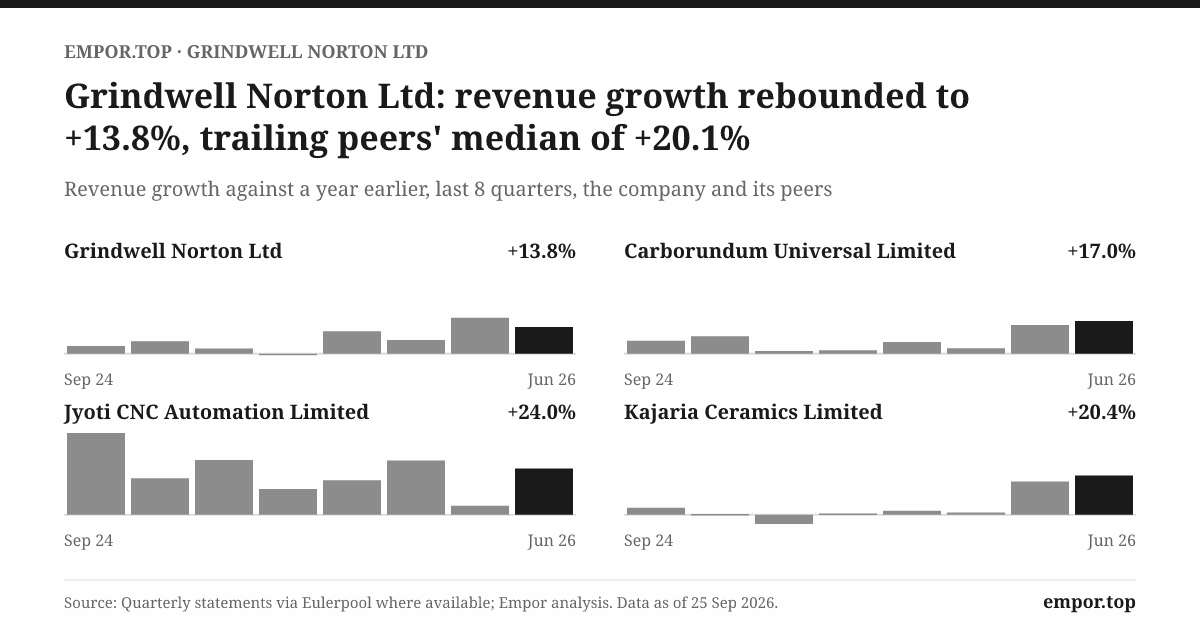
Claim 2: "Multinational parentage guarantees secular outperformance." Over the decade through FY26, consolidated revenue expanded at a compound annual rate of about 10%, while net profit compounded near 14%.1 While respectable, that trajectory barely outpaced nominal growth in Indian industrial production. During the macro slowdown between FY19 and FY21, revenue stagnated, shifting from about ₹1,598 crore to ₹1,638 crore.1 In FY25, consolidated net profit contracted roughly 4% despite top-line growth of 5%.111 Verdict: Rejected in its strong form. Association with Saint-Gobain secures technical resilience and operational safety, not immune secular expansion. Grindwell Norton compounds in step with broader domestic manufacturing and industrial capital cycles, with product mix providing an incremental tailwind.
Claim 3: "Premium brand equity guarantees pricing power." Disclosed operating performance in Section III demonstrates that pricing power is strictly confined to high-precision and highly regulated niches, and does not extend to commoditized thin wheels or utility coated abrasives. Verdict: Narrowed, as established by the empirical margin record.
With the contours of the competitive moat established, the evaluation shifts to leadership: the executives managing these assets, their strategic commitments, and how their disclosures compare with audited results.
VIII. Management Credibility, Governance, & The 3 Core KPIs
The insider's return
On April 1, 2025, Venugopal Shanbhag assumed leadership as managing director for a five-year term, succeeding B. Santhanam, who retired at the end of March 2025.21 The appointment represented a homecoming. Shanbhag originally joined Grindwell Norton in 1991, rotating through operational roles across Saint-Gobain's Indian abrasives and mobility businesses. His career included an early assignment from 1995 to 1996 at Saint-Gobain's Grinding Technology Centre in the United States, running Saint-Gobain Sekurit in Thailand until August 2020, and serving as managing director of Saint-Gobain Sekurit India until May 2024.21 A mechanical engineer with roughly 35 years of industrial experience,2 Shanbhag drew total compensation of approximately ₹3.96 crore in FY26, representing about 35 times the median employee remuneration.2
This background fits the Saint-Gobain archetype: an operational insider schooled in shop-floor engineering and rotated across corporate divisions and geographies, rather than an entrepreneurial founder or an external turnaround executive. Governance at the board level reflects a similar continuity. The board is chaired by Subodh Nadkarni, an independent non-executive director, and balances Saint-Gobain nominees with representation from the original Indian promoter families.2 Executive director Hari Singudasu reinforces that institutional memory, having served the enterprise since 1998.2
Communication style and consistency
Unlike many listed Indian mid-cap peers, Grindwell Norton does not host quarterly earnings conference calls. Instead, executive management convenes an annual institutional analyst and investor meeting, held most recently in late May 2026. Sell-side research summaries of these proceedings constitute the primary public record of management commentary.11 Leadership provides no formal forward-looking revenue or margin guidance. While this policy limits quantitative accountability, it spares the company the cycle of aggressive near-term targets followed by quarterly rationalizations.
Comparing management commentary across recent investor meetings provides a useful measure of managerial consistency:
- Ceramics margins. During the May 2025 investor meeting, management explicitly guided that Ceramics & Plastics was unlikely to recapture its 20%-plus operating margins from FY23.12 Subsequent performance validated that conservative stance: segment operating margins rebounded to 19.7% in the fourth quarter of FY26 and maintained healthy top-line expansion into the first quarter of FY27, yet remained below pandemic-era highs.1415 Management's restraint proved well calibrated.
- Life sciences exports. In May 2025, leadership projected that an export recovery in biopharmaceutical single-use tubing was "unlikely soon." By June 2026, management disclosed that export shipments to European and North American accounts had resumed following protracted customer re-qualifications.1211 The turnaround delivered an operational upside, while demonstrating the unpredictable lead times inherent to highly regulated component supply chains.
- Permacel. Corporate commentary transitioned from acknowledging electric-vehicle component redesign losses in 2025 to asserting that the acquired specialty-tape business was "exceeding expectations" by mid-2026.1211 While the strategic rationale is plausible, the claim remains impossible for external investors to verify without dedicated segment disclosures.
- Chinese competition. Management has consistently characterized low-cost Asian imports as a manageable challenge that localized product innovation and high-touch customer engineering can neutralize.1211 However, stagnant abrasives margins during the volume rebound in the fourth quarter of FY26 indicate that price competition remains an active headwind rather than a resolved historical threat.14
Audited disclosures provide a second layer of diligence. Statutory auditors Kalyaniwalla & Mistry LLP highlighted two key audit matters for FY26: revenue recognition—focusing on year-end cut-off risks and subjective management estimates for customer discounts, incentive schemes, and product returns—and the fair-value assessment of the unquoted equity holding in sister entity SGIPL.2 Neither finding is atypical for a manufacturing enterprise operating across tiered distribution networks while holding an unlisted affiliate stake, and the audit opinion contained no qualifications on either count.
Nevertheless, these two accounting areas represent the primary junctures where executive discretion directly influences reported financial statements. Outside of these provisions, the balance sheet exhibits clean legal hygiene. The directors' report documents no material regulatory penalties or court orders impairing the company's going-concern status, alongside an absence of proceedings under the Insolvency and Bankruptcy Code.2 The principal pending litigations involve routine direct-tax assessments that the company is contesting before appellate authorities.2
On balance, management communication is sober, technically grounded, and disciplined. Disclosed challenges generally match shop-floor realities. The central limitation remains the deliberate opacity of reporting: external shareholders cannot independently inspect the profitability of merchant silicon carbide, post-merger margins for Permacel, commercial revenue conversion in ceramic defense armor, or the precise revenue scale of single-use life sciences solutions.
Ownership and incentives
The shareholding structure explains why this conservative operating culture encounters little activist resistance. As of June 2026, the promoter group controlled 58.04% of total equity, domestic institutional investors held roughly 19.6%, foreign portfolio investors held 5.2%, and retail public shareholders accounted for approximately 17.2%.1 Promoter shares carry no encumbrances or pledges.11 Domestic mutual funds own approximately 17.5% of the company, outstripping foreign institutional participation more than threefold.11 This domestic institutional concentration carries significant implications for market pricing: Grindwell Norton's 50-times multiple is sustained primarily by Indian asset managers seeking clean balance sheets and established corporate governance among multinational manufacturing subsidiaries.
The three KPIs that matter
- The margin spread between Ceramics & Plastics and Abrasives. The core investment thesis depends on structural portfolio mix. If Ceramics & Plastics—led by Performance Polymer Solutions—continues to outpace legacy abrasives while sustaining operating margins in the high teens, consolidated profitability expands and supports the valuation premium. A sustained compression in that margin spread, whether caused by pricing erosion in ceramics or an inability to pass through polymer feedstocks, would dismantle the specialty compounder narrative.
- The abrasives segment operating margin across an industrial cycle. This metric provides the definitive test of whether the Norton brand commands genuine pricing power against low-cost Chinese imports, domestic paint-distribution entrants, and a formidable domestic peer in CUMI. Reclaiming and sustaining division operating margins near 14% would substantiate an enduring competitive moat. Conversely, a multi-year stagnation near or below 13% would confirm that volume growth is being bought through pricing concessions.
- Cash conversion and treasury accumulation. Tracking consolidated operating cash flow against reported net income verifies underlying earnings quality. More crucially, monitoring the balance between capital expenditure, dividend distributions, and liquid treasury balances reveals whether executive leadership is reinvesting to compound operating assets or simply running an industrial manufacturing business enclosed within an expanding savings account.
With these three operational indicators established, the evaluation turns to the contrasting valuation scenarios and strategic choices facing the enterprise.
IX. Bear vs. Bull: The Cyclical Industrial vs. Advanced Materials Compounder
Two readings of the same year
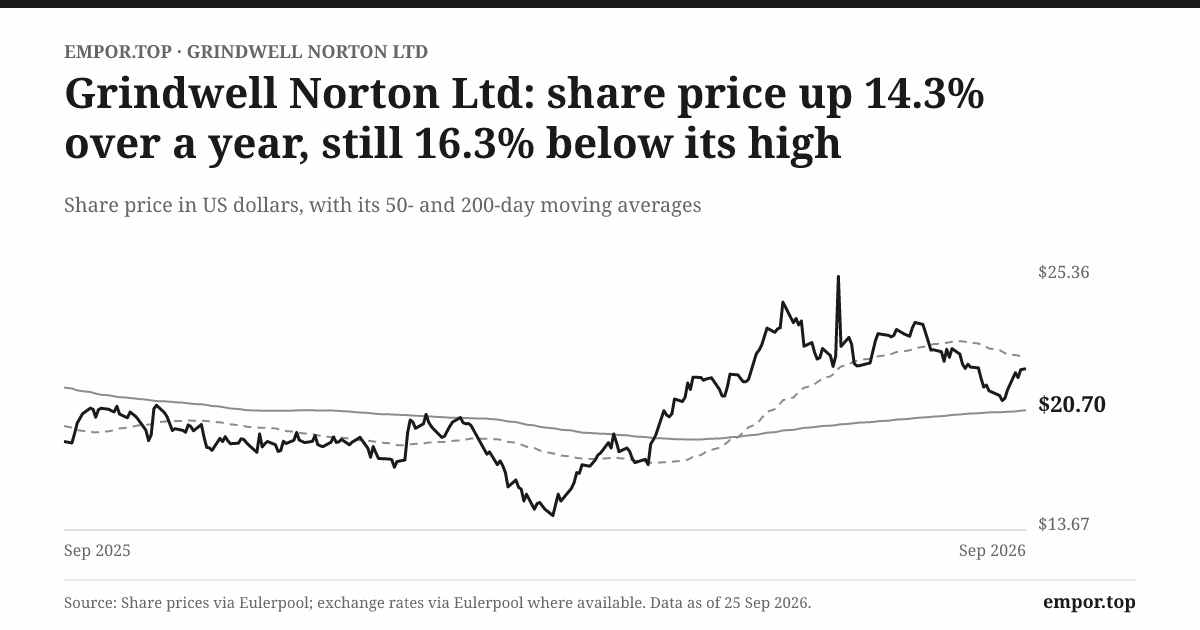
Over the twelve months leading into May 2025, Grindwell Norton's share price retreated roughly 32% from a 52-week peak near ₹2,960, pressured by contracting net earnings and mounting market concern over Chinese import competition.12 Institutional brokerage Prabhudas Lilladher downgraded the stock to Hold that month.12 A year later, following an operational rebound in the fourth quarter, the same brokerage upgraded its recommendation to Accumulate in May 2026.22 Following the release of first-quarter FY27 financial results on July 24, 2026, the equity traded above ₹2,000 at roughly 54 times trailing earnings.23 Across that period, the underlying business swung from a 4% profit contraction to approximately 12% profit expansion. The market valuation fluctuated far more dramatically than underlying operating cash flows—a defining characteristic of the stock.
The bull case
Indian capital spending directly aligns with the operating portfolio. Management's FY27 demand outlook points to steady expansion across automotive, primary steel, infrastructure, and general engineering, alongside faster growth across electronics, semiconductors, defence, and aerospace.2 Each vertical consumes Grindwell Norton consumables: precision vitrified wheels, engineered refractories, cryogenic seals, or single-use bioprocessing components.
Product mix continues to tilt toward higher-margin segments. Ceramics & Plastics already generates more segment operating profit than the legacy abrasives business.2 If Performance Polymer Solutions, life sciences fluid systems, and engineered ceramics continue expanding faster than the corporate baseline, consolidated operating margins can advance from the high teens toward the low twenties without requiring aggressive margin expansion in any individual business. First-quarter FY27 performance provided an early demonstration of that dynamic: revenue expanded 14%, net profit rose 22%, and the EBITDA margin reached approximately 19.6%.15
Specialized end markets are contributing to incremental volume. In corporate disclosures, management reported that its abrasives lines have secured a meaningful presence in solar glass edge-finishing, that leading consumer electronics and mobile device manufacturers are emerging as commercial accounts for specialty tapes and abrasives, and that the company supplies spring-energised seals and specialized abrasives for aerospace component fabrication and maintenance.11 Superabrasives are now manufactured locally across resin, metal, electroplated, and vitrified bonds.11 While none of these individual applications is yet large enough to warrant separate segment reporting, collectively they represent the primary driver of any sustained growth above the baseline expansion rate of Indian industrial production.
Growth capital expenditure is largely commissioned. Upstream investments in the domestic coated-abrasives paper partnership, the continuous non-woven line, higher-tonnage hydraulic presses, the Halol refractories expansion, and life-sciences manufacturing lines were largely funded and absorbed between FY23 and FY26.1211 As demand volumes absorb this installed footprint, fixed-cost operating leverage should follow, reversing the temporary margin drag created by elevated depreciation charges in FY25.12
Balance-sheet resilience through industrial downcycles. Operating with zero long-term debt and more than ₹1,000 crore in liquid surplus assets, Grindwell Norton maintains the financial capacity to sustain capital investments and support critical customer accounts through cyclical slowdowns while overleveraged peers retrench. Peer Carborundum Universal's FY26 exceptional charges and overseas subsidiary write-offs illustrate the balance-sheet hazards that Grindwell Norton's conservative posture helped avoid.13
The bear case
Valuation multiples leave little room for execution error. At approximately 50 times trailing earnings, the market price discounts continuous, mid-teens earnings growth over a multi-year horizon.1 The profit contraction recorded in FY25 demonstrated how swiftly equity markets penalize an operational plateau. If medium-term growth settles into the 8% to 10% range seen between FY24 and FY26 and the market multiple compresses from 50 times toward 35 or 40 times, shareholders could face an extended period of weak returns even while the operating business executes reliably.
Structural headwinds in automotive abrasives remain persistent. The ongoing transition away from internal combustion engines and multi-speed gearboxes eliminates several of the most grinding-intensive components in vehicle manufacturing. Disclosed portfolio reviews indicate that Grindwell Norton's current electric-vehicle commercial exposure consists primarily of adhesive tapes and thermal-barrier pads rather than high-margin precision grinding wheels.11 Over the longer term, the continuous adoption of additive manufacturing and near-net-shape metal casting exerts a similar downward pressure on precision material removal volumes.
Core group growth remains sequestered in unlisted entities. Saint-Gobain's fastest-growing Indian business verticals—encompassing construction chemicals, architectural flat glass, and gypsum plasterboard—compound entirely within unlisted corporate entities. The parent group's $1.025 billion acquisition of FOSROC represents the clearest recent example of strategic scale being directed away from the listed platform.20 Grindwell Norton's modest minority equity holding in sister entity SGIPL does not fundamentally bridge that corporate separation.2
Cross-border price deflation in commodity tiers. Corporate risk disclosures explicitly identify low-cost Chinese competition across commodity coated rolls, retail thin wheels, non-woven pads, and merchant silicon carbide, with leadership warning that competitive intensity is expected to remain high.122 Cross-border price competition in standard utility lines represents a permanent structural feature of the abrasives landscape rather than a temporary cyclical disruption.
The current risk radar
Only a select number of macroeconomic risks directly influence the operating model, each transmitting through a well-defined channel:
- Raw material volatility and energy tariffs. Statutory risk reviews in the FY26 annual report warn that geopolitical friction continues to elevate procurement costs for industrial raw materials and consumables while disrupting maritime supply chains.2 The margin effect transmits with a cyclical lag: input costs for crude abrasive grains, synthetic resins, and polymer feedstocks rise first, while compensatory price increases to customers follow one or two quarters later. Management responded to power tariff increases by securing captive renewable energy, acquiring equity in a wind-solar hybrid project through Jamnagar Renewables Two and approving a follow-on investment in a Sunsure Energy vehicle, following the termination of an earlier green-power agreement in April 2026.2
- Tariff barriers and export qualification delays. United States tariff policies and international trade friction weighed on engineered refractory exports in FY26, while the volume ramp-up at the Alathur ceramics plant remains dependent on protracted North American customer and regulatory qualification approvals.211
- Foreign-exchange transmission. Rupee depreciation operates as a double-edged sword: while it increases landed costs for competing imports, it simultaneously elevates procurement costs for imported raw grains and specialty polymers. The Performance Polymer Solutions division explicitly cites rupee depreciation as an operational margin risk because of its high import intensity.2
- Statutory labour regulations. India's revised labour codes, which took effect on November 21, 2025, were highlighted in fourth-quarter FY26 regulatory disclosures, though the ultimate financial impact remained unquantified by the company.14
None of these individual variables threatens corporate solvency. However, each has the capacity to interrupt an earnings growth trajectory that a 50-times multiple assumes will remain uninterrupted.
Porter and Helmer in brief
The strategic frameworks examined in Section VII lead to a straightforward synthesis. Grindwell Norton commands authentic process power and customer switching costs across roughly half of its portfolio, leases its primary cornered resource from its foreign parent, and possesses neither network effects nor counter-positioning advantages. High-end rivalry with Carborundum Universal remains disciplined and economically rational, while price competition across retail and commodity lines is severe. That combination supports a durable industrial business; it does not establish an unassailable compounder. The bull case requires the high-moat portion of the portfolio—advanced ceramics, superabrasives, and performance polymers—to systematically outpace commodity lines. The bear case requires only that equity markets decide that 50 times earnings is an excessive valuation for an industrial manufacturer compounding top-line turnover near 10%.
Myth vs. reality
- Myth: Grindwell Norton commands structurally higher operating margins in abrasives than Carborundum Universal. Reality: In domestic Indian abrasives operations, the two peers run on roughly comparable margins near 13% to 15%. Grindwell Norton's consolidated return premium stems from its broader corporate portfolio, non-abrasives profitability, and the avoidance of loss-making cross-border acquisitions.132
- Myth: Surplus balance-sheet cash amounts to roughly ₹500 crore. Reality: Excluding strategic affiliate holdings, unallocated liquid reserves exceed ₹1,100 crore, creating a substantial passive drag on consolidated return on equity.2
- Myth: Ceramics & Plastics is a perpetual 22% to 26% margin business. Reality: Division margins reached that elevated corridor only between FY21 and FY23, propelled by extraordinary post-pandemic export demand; margins subsequently normalized between 17% and 20%, precisely in line with management's public guidance.122
- Myth: INDEC represents an autonomous, high-growth information technology services exporter. Reality: The captive digital development center operates on an internal cost-plus transfer model, with management explicitly noting that future top-line expansion is structurally constrained to cost inflation.2
Assuming the underlying operating franchise is sound and the prevailing valuation multiple is demanding, the pivotal strategic question is what operational levers executive leadership can realistically pull to alter that trajectory.
X. Playbook & "If We Were CEOs"
What Grindwell Norton teaches
Low unit cost, high cost of failure. The most defensible industrial consumables operate where a product represents an insignificant fraction of a customer's operating costs but governs a substantial share of operational risk. Grindwell Norton’s strongest franchises—precision vitrified wheels, engineered furnace linings, validated biopharmaceutical tubing, and aerospace seals—fit this profile. Its weakest product lines, including commodity thin wheels and merchant silicon carbide, compete primarily on unit price. Strategic capital allocation requires concentrating investment in the first category while managing the second as cash-generative volume businesses.
Cross-border joint ventures can endure with clear role definition. Few multinational partnerships in India have survived more than five decades with founding families remaining on the share register and no public governance disputes. Structural durability relied on unambiguous boundaries: Saint-Gobain provided formulation chemistry and international patents, domestic leadership managed shop-floor execution, and the founding families retained an equity stake alongside board representation.2
Geographical cost advantages are transitory without technical moats. Siting silicon carbide smelting in Bhutan to tap low-cost Himalayan hydroelectric power established a logical input hedge. Operating performance in FY26 demonstrated, however, that geographic advantages can be eroded by low-cost cross-border merchant imports and rising local utility tariffs.2 Favorable input pricing provides a temporary operational buffer, but it does not substitute for an enduring competitive moat.
If we were running Grindwell Norton
1. Deploy surplus liquidity or accelerate shareholder distributions. With approximately ₹1,170 crore in liquid treasury assets—excluding the strategic SGIPL equity holding—and capital actively deployed in operations generating pre-tax returns above 40%, maintaining substantial passive balances remains the primary drag on consolidated returns.2 Establishing a formalized capital allocation framework would resolve this drag: if internal investments cannot clear disciplined return hurdles, surplus funds above a defined operating reserve should be distributed through special dividends or targeted share buybacks. Any buyback programme would require structured coordination with the foreign promoter to navigate statutory minimum public float and promoter holding limits.
2. Institutionalize external acquisitions into a repeatable programmatic strategy. The turnaround of PRS Permacel demonstrated that domestic management can stabilize an underperforming operating asset and realign its product portfolio.11 Building on that operational foundation would involve executing targeted bolt-on acquisitions in specialty adhesive tapes, high-performance seals, precision tooling, or engineered ceramics businesses operating at margins above 15%, accompanied by transparent segment-level disclosures that enable investors to evaluate post-merger integration.
3. Accelerate domestic life sciences and semiconductor manufacturing capabilities. Single-use fluid-handling assemblies and Furon-branded fluoropolymer components address high-growth domestic industries defined by multi-year regulatory and customer qualification timelines.11 Expanding certified domestic cleanroom capacity ahead of broad commercial demand would establish early incumbent switching costs, embedding Grindwell Norton's components into drug master files and semiconductor tooling specifications before competing global suppliers establish domestic footprints.
4. Articulate a transparent corporate charter with unlisted affiliates. Publishing a formal, board-approved operational perimeter defining which product lines belong to listed Grindwell Norton and how new Saint-Gobain commercial opportunities in India are allocated would impose minimal friction on the French parent. Resolving this ambiguity would eliminate the single largest governance discount confronting minority public shareholders.
5. Expand segment disclosure across specialized growth verticals. Providing granular financial reporting on merchant silicon carbide, Performance Polymer Solutions, and specialty tapes, alongside clear commercial milestones for ballistic defence ceramics, would enable equity markets to evaluate and price high-return growth drivers independently, rather than blending them into a consolidated corporate average.
XI. Epilogue: The 80-Year Compounding Engine
The kilns at Mora are still firing. The coastal village where two Sidhwas and two Czechoslovak technical partners began fabricating grinding wheels in 1941 now anchors an enterprise producing more than 15,000 abrasive specifications each year. Its operational footprint lines steel furnaces, seals space launch-vehicle valves, insulates electric-vehicle battery packs, and develops software for the French parent that once cast the mirrors of Versailles.52 Over eight decades, the business has navigated wartime supply disruptions, the License Raj, a hostile cross-border takeover in Massachusetts, post-1991 liberalization, waves of low-cost Chinese imports, and a volatile post-pandemic export cycle. Through it all, the founding families have remained on the share register, and the balance sheet has remained unburdened by long-term debt.
That operational record is exceptional in one dimension and ordinary in another. It demonstrates that an industrial consumables supplier can generate high returns on actively deployed capital when it prices process reliability and customer uptime rather than commodity tonnage. Yet it also reveals distinct structural boundaries. Top-line expansion has tracked the broader rhythm of Indian industrial production rather than accelerating far ahead of it. Saint-Gobain's fastest-growing domestic building materials businesses remain sequestered in an unlisted sister company. Meanwhile, a substantial portion of shareholder equity rests in passive treasury holdings rather than productive operating capacity.
Grindwell Norton is not a high-growth technology platform. It is a disciplined, well-engineered industrial supplier tethered to one of the world's fastest-growing manufacturing economies: its wheels machine the steel, its refractories contain the heat, and its polymer seals secure the fluids. Whether that franchise justifies trading near 50 times trailing earnings depends on the three operating metrics traced across this analysis: the profitability spread between ceramics and legacy abrasives, the resilience of abrasives margins across an industrial downcycle, and whether leadership redeploys its accumulating cash reserves to expand operating assets or continues to house an industrial compounding engine inside an expanding savings account.
References
-
Grindwell Norton Ltd — Consolidated financials, ratios and shareholding — Screener.in, 2026-09-25 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Grindwell Norton Limited Annual Report 2025-26 (filed with NSE) — Grindwell Norton Limited, 2026-06-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Compagnie de Saint-Gobain S.A. company history — Encyclopedia.com ↩↩
-
Saint-Gobain: Full-Year 2025 Results — MarketScreener, 2026-02-26 ↩↩
-
Grindwell Norton Limited — About Us (company profile, Mora, Uran) — IndiaMART ↩↩
-
Norton turns to French white knight to elude BTR takeover — UPI Archives, 1990-04-25 ↩↩↩
-
Alpha: Grindwell Norton Ltd. — Equity Research Desk — FundsIndia, 2023 ↩↩↩↩↩↩↩
-
Grindwell Norton (GWN IN) Analyst Meet Update: Leveraging Capacity, Innovation and New-Age End Markets — Prabhudas Lilladher, 2026-06-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Grindwell Norton (GWN IN) Analyst Meet Update: Persistent headwinds temper near-term outlook — Prabhudas Lilladher, 2025-05-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carborundum Universal's Full Year 2025-26 and Q4 2025-26 results press release — Murugappa Group, 2026-05-14 ↩↩↩↩↩↩↩↩↩↩
-
Grindwell Norton Q4 FY26 profit up 28% with ₹19 dividend — Multibagg, 2026-05 ↩↩↩↩↩↩
-
Grindwell Norton Q1 FY27: Profit up 22%, margin at 19.6% — Multibagg, 2026-07-24 ↩↩↩
-
Grindwell Norton Limited completed the acquisition of PRS Permacel Private Limited — MarketScreener, 2022-05-27 ↩↩
-
Grindwell Norton concludes acquisition of PRS Permacel — ICICI Direct, 2022-05 ↩
-
PRS Permacel Acquired by Grindwell Norton — Energetica India, 2022-06-07 ↩↩↩
-
Disclosures under Regulation 46 of SEBI LODR (Scheme of Amalgamation of PRS Permacel) — Grindwell Norton Ltd. ↩
-
Saint-Gobain Finalizes Fosroc Acquisition in $1B Deal — Engineering News-Record, 2025-02 ↩↩
-
Grindwell Norton gains after appointing Venugopal Shanbhag as MD — Capital Market, 2025-02-21 ↩↩
-
Grindwell Norton Analyst Upgrade Faces Margin Pressures — Whalesbook, 2026-05-11 ↩
-
Grindwell Norton Q1 FY27: Margin Expansion Drives 22% Profit Growth Despite Revenue Moderation — MarketsMojo, 2026-07-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube