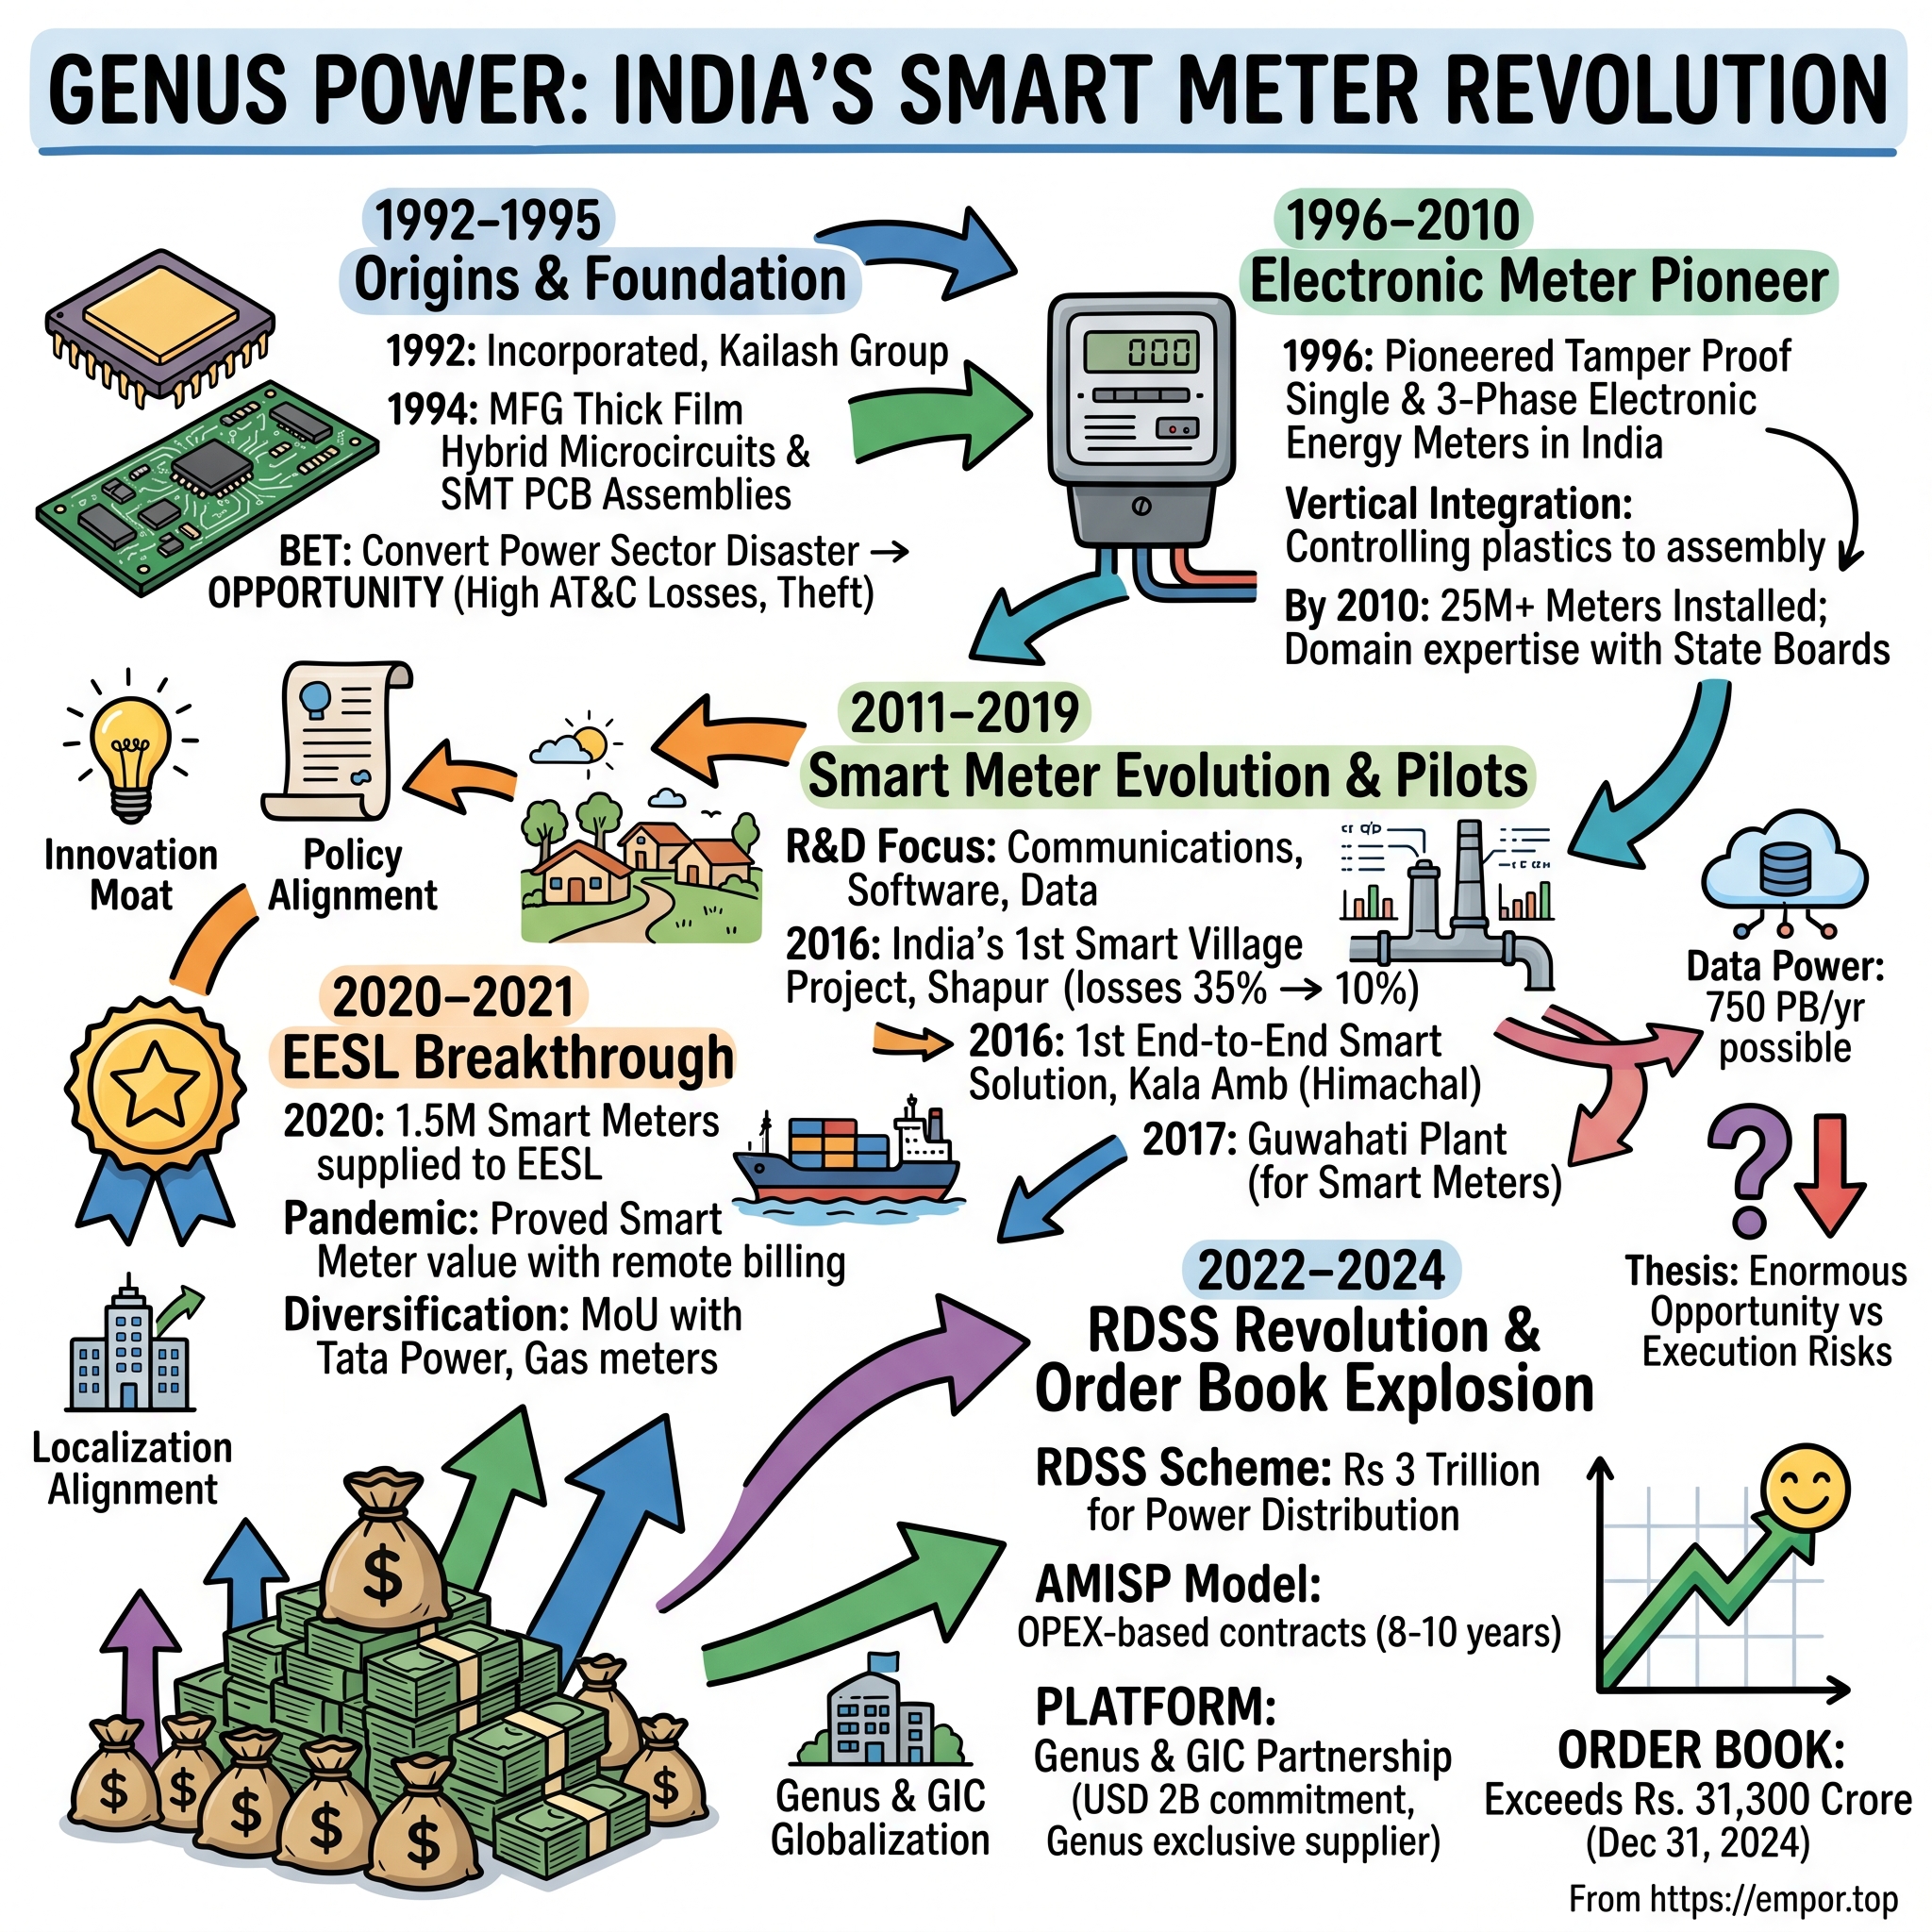
Genus Power: The Sovereign Bet on India's Smart Grid
I. Introduction & Episode Roadmap
A phone call from Singapore
On July 4, 2023, a family-run meter manufacturer from Jaipur announced a partnership that seemed vastly out of proportion to its balance sheet. Gem View Investment Pte Ltd, an affiliate of Singapore's sovereign wealth fund GIC, signed definitive agreements with Genus Power Infrastructures to create a joint platform to bid for, finance, and operate smart metering concessions across India. GIC would own 74% of the platform and Genus 26%, with the two partners committing to an initial pipeline carrying a capital outlay of roughly US$2 billion.1 A second GIC affiliate, Chiswick Investment, agreed to inject up to Rs. 519 crore into Genus itself through warrants convertible into 15% of the company on a fully diluted basis.1 Genus would serve as the platform's exclusive supplier of smart meters and associated services.1
To put that commitment in perspective, consider the scale of the company sitting across the negotiating table. In FY23, Genus reported consolidated revenue of about Rs. 808 crore and net profit of roughly Rs. 29 crore.2 Fifteen months after the GIC announcement, its order book—spanning the GIC platform and all associated project vehicles—stood at Rs. 31,776 crore net of taxes.3 That figure represented nearly forty years of FY23 revenue booked on paper. A company that began by assembling thick-film microcircuits had emerged, almost overnight, as a primary contractor in the largest meter replacement initiative ever attempted in a democracy.
This is the story of how that transaction came together, and what that massive order book does—and does not—mean.
The problem that created the market
India's state electricity distribution companies, or discoms, have long been the weakest link in the country's power value chain. Electricity is generated and transmitted, only to leak away at the final mile: siphoned through illegal wire hooks, consumed by unmetered agricultural pumps, billed on rough estimates, or billed and never collected. The industry terms this aggregate technical and commercial (AT&C) loss. For decades, these persistent cash drains turned state-owned discoms into chronic loss-makers that routinely delayed payments to suppliers and depended on state government bailouts.
The central government's response, launched in July 2021, was the Revamped Distribution Sector Scheme (RDSS), with a total outlay of Rs. 3,03,758 crore, including gross budgetary support of Rs. 97,631 crore from New Delhi.4 Its flagship ambition was to replace roughly 250 million conventional consumer meters with prepaid smart meters, alongside feeder and distribution-transformer metering and loss-reduction works.4 In practice, the policy aimed to equip households across a nation of 1.4 billion people with digital, remotely monitored cash registers that report consumption data directly back to the utility.
The structural twist
The more consequential shift was not simply the scale of RDSS, but the mechanism chosen to fund it. Earlier government initiatives operated largely as straightforward hardware tenders: a discom ran a competitive bid, purchased meters from the lowest bidder, and hired contractors to install them. RDSS pivoted to an integrated service model, formally known as TOTEX (total expenditure). Under this framework, an Advanced Metering Infrastructure Service Provider (AMISP) designs, builds, finances, owns, operates, and eventually transfers the entire system. The AMISP is paid monthly, per meter in service, over a multi-year concession contract.5 Instead of buying physical equipment up front, the utility effectively rents operational outcomes.
That structural change reshaped the entire sector. It transformed a hardware manufacturing business into a capital-intensive project finance industry. The model rewarded operators with access to patient, low-cost capital, while penalizing equipment vendors whose balance sheets could not bear long-term concession financing.
The roadmap
This analysis follows three core threads. The first traces how industrial policy and chronic state-level utility deficits converged to create one of the largest single Internet of Things (IoT) procurement rollouts in the world. The second examines the financial engineering Genus used to participate at scale without overleveraging its balance sheet—specifically through its 74:26 platform structure with GIC. The third delivers a reality check on the fundamentals: the gap between a nominal order book, the back-ended cash flows of concession agreements, and the credit quality of the state utilities ultimately funding them. Along the way, the inquiry evaluates the bull case against the company's operating record, including an investigation linked to a Bihar contract, persistent working-capital demands, and an order book that has contracted rather than expanded since late 2024.
To understand why a global sovereign wealth fund partnered with Genus, and why Genus needed sovereign backing, the story begins with a modest manufacturing venture in Jaipur during the early 1990s.
 Subscribe on LinkedIn
II. Origins & The Electronic Metering Frontier (1992–2010)
The spinning disc
For most of the twentieth century, an Indian electricity meter was a small glass box housing a spinning aluminium disc—the classic Ferraris induction meter. It was elegant nineteenth-century physics and an open invitation to theft. A strong magnet held against the casing could slow the disc. A pin slipped through the housing could stop it. A bypass wire could route current around the device entirely. Meter readers walked door to door recording figures in notebooks, and when access was blocked, they simply estimated. The resulting commercial losses were far from a rounding error; they were a principal reason discoms bled cash.
Into this operating landscape stepped the Kailash Group, a Rajasthan-based business family whose commercial interests would expand across paper, coal and coke, commodities, and power equipment. Genus Power Infrastructures was established in 1992,6 with its corporate records documenting its initial operations as the manufacture of thick-film hybrid microcircuits and surface-mount printed circuit board assemblies.7 Today, the company describes itself as an integral part of a Kailash Group that it values at roughly US$500 million.8
The patriarch, Executive Chairman Ishwar Chand Agarwal, is a commerce graduate whose board profile credits him with more than five decades of operating experience across power, paper, coal and coke, apparel, and agri-commodities.9 That diversified background matters: Genus was never a standalone technology startup. It was an operating unit within a multi-business family conglomerate, and the next generation inherited both an engineering franchise and the group's surrounding structural complexity.
The next generation divided management responsibilities along functional lines. Rajendra Kumar Agarwal—referred to in corporate communications as Raj Agarwal—is an electronics engineer who became Managing Director and CEO, overseeing technology, research and development, and corporate strategy. Jitendra Kumar Agarwal, holding an MBA in marketing, leads commercial operations as Joint Managing Director. Meanwhile, Vice Chairman Kailash Chandra Agarwal is profiled as a specialist in corporate restructuring, finance, banking, and investor relations.9 One family member directed product engineering, one led sales, and one managed financing. That internal division of labor would prove decisive when the enterprise's long-term trajectory came to hinge on capital structuring rather than hardware design alone.
1996: from components to meters
The pivotal strategic turn came in 1996. Genus reported that it pioneered tamper-proof single-phase and three-phase electronic energy meters in India that year and commenced commercial production of electronic meters.7 The industrial logic was straightforward: a business already fabricating dense electronic assemblies possessed the core capabilities to build meters without moving parts—solid-state devices that logged tampering attempts digitally instead of silently undercounting power consumption.
The product milestones that followed traced an engineering operation systematically addressing distribution loopholes and expanding technical capabilities. Multi-function and multi-tariff meters arrived in 1999, followed by automated meter reading and prepayment meters in 2005. The company commissioned a dedicated manufacturing plant in Haridwar in 2006. In 2007, Genus reported becoming the first Indian company to secure DLMS certification for electronic meters—a standardized communications protocol that would later become a mandatory requirement under national smart metering frameworks. In 2009 and 2011, it obtained international prepayment certifications (STS and SABS).7 Concurrently, in 2005, the company branched into engineering and construction contracts for power distribution.7
This progression demonstrated an enterprise that was early to adopt new technologies and disciplined in obtaining technical certifications. What it did not demonstrate was an ability to convert technical firsts into enduring commercial pricing power.
The reform wave and the L1 reality
The early 2000s brought a series of central government reform initiatives encouraging state utilities to replace mechanical meters with electronic units. For equipment vendors, the transition drove substantial volume. It failed, however, to deliver strong operating margins. The primary buyers were state-owned utility monopolies that procured equipment exclusively through lowest-bidder (L1) competitive tenders, divided contract volumes among multiple qualified suppliers to prevent vendor pricing leverage, and routinely deferred payments.
Historical falsification — did early leadership create an incumbent's moat? The optimistic interpretation of this era suggests that early entry into electronic metering established an unassailable competitive moat for Genus. The long-term financial record contradicts that thesis. Between FY16 and FY23, consolidated revenue stagnated and moved unpredictably: standing at about Rs. 858 crore in FY16, dropping to Rs. 642 crore in FY17, crossing Rs. 1,000 crore in FY19 and FY20, before tumbling to Rs. 609 crore in FY21 and recovering to Rs. 808 crore in FY23.2 Operating margins drifted between 9% and 17%, while net profit peaked at Rs. 89 crore in FY16 before sliding to Rs. 29 crore in FY23.2 Cash collection was equally strained: debtor days were already around 176 in FY16.2 On the eve of the GIC transaction, an analyst on the company's earnings call pointed out that debtor days had hovered around "200 days-plus" for four or five consecutive years—an observation management did not dispute.10
The historical evidence firmly challenges the notion of an enduring incumbency advantage. Two decades of technical milestones provided Genus with an extensive installed base, pre-qualification credentials, and entrenched utility relationships. They did not, however, confer pricing power or the ability to collect receivables on schedule from cash-strapped state utilities. Any thesis that Genus commands pricing power today must explain what structurally altered that dynamic, as the record between 1996 and 2021 indicates the public buyer consistently retained the upper hand.
That structural imbalance would soon be tested again, even more rigorously, when the next wave of procurement arrived under a centralized national buyer armed with a reverse-auction gavel.
III. The Lost Decade & The EESL Trap: From Hardware Vendor to Reverse-Auction Casualty (2011–2021)
A smart village in Gujarat
In 2016, in the village of Shapur in Gujarat's Junagadh district, Genus deployed a smart metering setup for state distribution company PGVCL that it described as India's first smart village project.7 That same year, at Kala Amb in Himachal Pradesh, it implemented what it characterized as India's first end-to-end smart metering solution.7 These small, tightly managed pilots proved that meters, communications networks, and back-office software could function together under Indian field conditions. They also revealed a harsher commercial reality: a successful technical pilot is not a commercial purchase order.
Through the late 2010s, Genus continued assembling the operational foundations of an advanced metering company. It commissioned a manufacturing plant in Guwahati, Assam, in 2017, rolled out 3G-capable smart meters in 2018, established an Advanced Metering Infrastructure (AMI) laboratory, and in 2019 deployed what it described as India's first narrowband IoT setup for AMI alongside Vodafone Idea.7 Each milestone broadened technical capabilities, but none altered the underlying economics of selling hardware to state-owned discoms.
The national buyer arrives
The late 2010s introduced a new type of customer. Energy Efficiency Services Limited (EESL), a joint venture of state-owned power utilities, spearheaded the Smart Meter National Programme by pooling demand across multiple states into massive, centralized tenders. Demand aggregation created unprecedented scale and drove aggressive price discovery. Genus became a primary volume beneficiary: in 2020, it reported becoming the first company in the Asia-Pacific region to supply 1.5 million smart meters to EESL.7
Centralized procurement, however, proved a double-edged sword for manufacturers. While it dangled contracts of unprecedented size, it also concentrated all purchasing power in a national monopsony whose explicit mandate was driving down unit costs through reverse auctions. Furthermore, the EESL framework unbundled the meter from the broader operating system. A smart meter deployed in the field without reliable communication to utility head-end software functioned, economically, as little more than an expensive conventional meter. While tender-specific meter pricing was not disclosed in the materials reviewed for this account, the company's income statement reflected the commercial fallout.
The income statement verdict
The financial record underscored that vulnerability. Genus's consolidated revenue dropped from about Rs. 1,060 crore in FY20 to Rs. 609 crore in FY21 and Rs. 685 crore in FY22.2 Operating margin contracted sharply from roughly 17% in FY21 to about 9% in FY22, while net profit slid from Rs. 69 crore in FY21 to Rs. 29 crore in FY23.2 Return on capital employed dropped to around 6% in FY22.2 While the COVID-19 pandemic, global semiconductor shortages, and a nationwide pause in utility tenders ahead of new policy schemes contributed to the decline, the primary cause was structural. When a single public buyer dictates technical specifications, delivery schedules, and price, an equipment manufacturer's returns inevitably compress toward its cost of capital—and often fall below it.
This period left Genus at its most exposed. Revenue contracted, working capital remained trapped in overdue receivables, and the company needed sizable bank guarantees merely to participate in tenders. It was also during this stretch that promoter share encumbrances, examined later in this account, emerged as an active concern for public market investors.
Historical falsification — the gas and water optionality
Alongside electricity metering, Genus sought to build optionality across adjacent utilities. In 2021, it launched smart gas meters with communications capability; in 2022, it established a dedicated production facility and commenced commercial gas meter manufacturing; and in 2023, it introduced an ultrasonic water meter.7 Management presented these launches as the foundation of a multi-utility franchise, maintaining that narrative in subsequent investor updates. On its second-quarter FY26 earnings call in November 2025, management outlined an estimated domestic replacement demand of 12 to 14 crore gas meters over five to six years and suggested water could emerge as "a larger market than electricity meters within 4-6 years."11
The test for investors, however, is commercial conversion rather than product development. Genus does not break out gas or water equipment as a separate reportable business segment; the enterprise has operated almost entirely as an electricity metering business alongside a small strategic investment portfolio that was subsequently demerged.12 Across the FY24 through FY26 earnings transcripts reviewed for this account, management consistently discussed gas and water as prospective opportunities rather than reporting material revenue contributions from them.1113 Five years after its initial gas meter launch, the multi-utility thesis remains intact as an ambition but unproven in audited financial results. A meaningful re-evaluation of that segment requires verifiable commercial evidence: a disclosed gas or water order book, or a revenue line substantial enough for management to quantify. Until then, the multi-utility portfolio represents an unexercised option rather than core earnings value.
The lost decade therefore left Genus with two fundamental lessons: selling commoditized hardware to a monopsony buyer offered no lasting economic return, and technical certifications did not automatically translate into commercial revenue. The Revamped Distribution Sector Scheme, launched in 2021, promised an exit from this trap—but only for an operator capable of financing its way through the door.
IV. The RDSS Watershed & The AMISP Architecture (2021–Present)
Rewriting the contract
For the leadership of a loss-making state discom in 2021, the operational dilemma was stark. Smart meters promised to curb power theft and raise collection efficiency, but state utilities possessed neither the capital budget to purchase millions of devices up front nor the balance sheet to absorb procurement risks after earlier centralized programs left meters struggling to communicate with legacy utility systems. RDSS offered cash-strapped discoms a restructured bargain: central government grants would fund a portion of the project outlay, while a private concessionaire financed the remainder, installed the hardware, managed the communications network and software stack, and collected monthly fees over the life of the concession.
Rural Electrification Corporation, serving as the scheme's nodal agency, codified this structure into a standard bidding document. Under its provisions, the AMISP retains ownership of the metering assets throughout the concession term. Monthly service compensation commences only after meters transition into the operation and maintenance phase following "Operational Go-Live"—a project milestone certified exclusively by the discom.5 The framework establishes an operation and maintenance window of 93 months alongside an installation milestone compressed to 27 months, holding the concessionaire liable for liquidated damages if deployment extends past that 27-month window.5 The contract concludes at the earlier of ten years or when accumulated "meter-months" hit the contracted total.5
How the money actually flows
In economic terms, the AMISP model functions like an equipment lease bundled with an upfront construction and systems-integration contract. The concessionaire quotes an all-in rate per meter for the complete system. The central government subsidy is netted off against this figure, and the remaining capital outlay is amortized evenly over 93 months and disbursed as a per-meter-per-month (PMPM) fee. An analysis by the Prayas Energy Group, an independent energy policy research organization, formalized this arithmetic: the monthly fee equals the awarded tender rate minus the per-meter subsidy, divided by 93. Central subsidies were capped at the lower of 15% or Rs. 900 per meter for regular states, and 22.5% or Rs. 1,350 for special-category states.14
In practice, tender pricing diverged substantially across states. Prayas found awarded rates for single-phase consumer installations ranging from roughly Rs. 7,236 to Rs. 12,118 per meter, with a national median near Rs. 8,839. Monthly service fees spanned an equally wide range—from approximately Rs. 60 per month in West Bengal to Rs. 167 in one Madhya Pradesh discom—with no clean relationship between contract size and price.14 For investors, this wide dispersion highlighted a crucial structural reality: contract economics were dictated tender by tender and state by state, rather than through a uniform national benchmark.
The payment security mechanism formed the second pillar of the framework. To mitigate chronic utility payment delays, the standard bidding document requires the discom to establish a Direct Debit Facility over its online consumer collections using an automated waterfall mechanism: consumer bill payments and digital recharges received from the 11th working day of each month to the 10th working day of the next are swept directly into an AMISP account until its dues are paid in full.5 Establishing this facility is a mandatory condition precedent to awarding the contract. If a discom's existing term lenders decline to provide consent, the utility must put in place an acceptable alternative, such as a letter of credit or escrow through REC.5 In functional terms, the structure grants the private concessionaire senior priority over a dedicated share of the discom's daily digital collections, intercepting cash before it reaches utility debt service or internal payroll accounts.
The balance-sheet dilemma
This structure created a formidable barrier for traditional hardware vendors. Under TOTEX, the concessionaire must finance millions of physical meters, communication modems, installation crews, cloud hosting infrastructure, and head-end software systems up front, recovering that capital expenditure gradually over seven to eight years. At a median award rate of roughly Rs. 8,800 per meter,14 executing a concession portfolio of ten million meters implied an upfront capital commitment in the region of Rs. 9,000 crore before financing costs.
Genus lacked the balance-sheet depth to carry commitments of that scale on its own. At the close of FY23, its equity capital and reserves represented only a small fraction of the capital demanded by large-scale concessions, while total borrowings had climbed and annual operating cash flow was modest.2 Genus had begun participating as an AMISP under TOTEX in 2022,7 and in May 2023 it signed a US$49.5 million funding agreement with the U.S. International Development Finance Corporation to support smart meter deployment.7 Yet for a mid-sized hardware manufacturer, bidding directly for multiple multi-thousand-crore concessions on its own balance sheet posed an unviable dilemma: severe equity dilution, perilous balance-sheet leverage, or forfeiting participation in the most expansive procurement cycle in Indian utility history.
Why the program has moved slower than the headlines
The initiative's headline ambitions were also met with operational friction on the ground. By early 2026, figures cited in industry coverage of Genus's Q3 FY26 results showed that 19.78 crore meters had been sanctioned under RDSS and 12.43 crore had been awarded, but actual field installations stood at 4.07 crore.15 That execution pace mirrored earlier findings by Prayas, which documented that by March 2025 only about 5% of the national 250-million consumer-meter target had been installed, and just 1.9% were running in prepaid mode.14 Protracted delays in finalizing model tender documents, establishing certified communication test beds, executing vendor empanelment and state approvals slowed the early years.16
For an equipment vendor, this implementation lag proved to be a double-edged sword. On one side, it stretched the operational runway: because meeting national installation targets would require several years beyond initial schedules, market demand avoided an abrupt cliff in 2026. On the other side, implementation delays lengthened the working-capital cycle, as every month a manufactured meter sat uninstalled or awaiting operational certification was a month capital remained locked up without yielding monthly concession revenue.
The AMISP architecture had transformed electricity metering into long-term infrastructure project finance. Genus could no longer rely solely on manufacturing capacity and laboratory certifications; it required an infrastructure sponsor equipped with patient, low-cost capital. It moved to secure the largest partner available.
V. The GIC JV Masterstroke: Solving the Balance Sheet Constraint
Two days later, on the conference call
On July 6, 2023, two days after the initial announcement, Vice Chairman Kailash Chandra Agarwal walked analysts through the transaction on an investor call. A science graduate whose board profile listed more than a dozen other group directorships, from Genus Paper & Boards to Kailash Coal and Coke,9 he led the discussion. The platform, he explained, would act as the AMISP and "prime bidder" on design-build-finance-operate-transfer concessions, with Genus serving as its exclusive technical partner for meter supply, installation, and technology.10
He then outlined the financial arithmetic that would define the company's operating profile over the next three years. Approximately 60% of the total project value won by the platform was projected to accrue to Genus as equipment supplier and installation contractor, with the remaining 40% staying with the platform. Genus's equity commitment for its 26% stake was capped at US$211 million, while the platform's US$2 billion total capital outlay would be funded through a mix of equity and debt, targeting 30 million meters installed over three to four years.10 When an analyst modeled a rough cost of approximately Rs. 10,000 per meter to arrive at a potential Rs. 30,000 crore platform pipeline, Agarwal concurred that roughly 60% would flow directly to Genus, a baseline the Joint Managing Director later clarified included taxes.10 Meanwhile, the warrants issued to GIC affiliate Chiswick were priced at Rs. 112.88 each.10
Anatomy of the structure
The strategic logic distributed operational and financial risk across two distinct corporate tiers.
Concession risk—the capital locked up for seven to eight years alongside direct exposure to discom payment delays—sat predominantly within the platform and its project special purpose vehicles, 74% owned by GIC. Genus's own balance sheet was insulated from full project leverage, carrying only its 26% pro-rata equity commitment rather than the debt of entire concessions.
Manufacturing and installation earnings, realized during the upfront rollout phase, accrued directly to Genus. Every meter deployed by the platform represented hardware manufactured, delivered, and integrated by Genus.
The long-term operating annuity was shared. Asked whether 26% of platform operational earnings would also flow back to Genus, Agarwal confirmed: "Yes, because Genus is a 26% partner there."10
The legal architecture was reflected in credit and regulatory filings. Rating agency CRISIL identified the joint venture as Gemstar, held 74% by Gem View and 26% by Genus, while noting that Chiswick Investment held a 15% equity stake in Genus itself.6 Corporate disclosures also showed the Managing Director holding directorships in Gemstar Infra India Private Limited and concession project vehicles such as Genus Assam Package-3 SPV Limited.9 By June 30, 2026, Rs. 22,183 crore of Genus's Rs. 24,020 crore executable order book—roughly 92%—originated from contracts awarded under the Gem View joint venture.17
For the listed operating company, management framed the transaction as both a volume driver and a cure for its chronically sluggish working-capital cycle. On the July 2023 call, Agarwal noted that Genus's working-capital cycle stood at "approximately 250 days or even more," suggesting it could fall to 60% or 65% of that level because Genus would receive payments directly from the platform rather than waiting on state discoms.10 Asked whether debtor days would decline, he replied that "surely it will come down," while declining to commit to a specific target.10
What the market heard
GIC framed the transaction in measured institutional language. Ang Eng Seng, its Chief Investment Officer of Infrastructure, said GIC was pleased to partner with "one of the leading metering businesses in India" to create a new smart meter platform.1 For a sovereign wealth fund, the asset class offered long-dated, contracted, inflation-sensitive cash flows backed by critical public infrastructure, paired with an industrial partner handling on-the-ground manufacturing and execution.
For Genus, the agreement provided three distinct advantages: growth capital via the warrant subscription, institutional sponsorship that reassured commercial lenders, and an infrastructure partner with the balance sheet to hold concession assets over a decade. CRISIL's rating rationale subsequently highlighted "financial flexibility with presence of GIC" as a core credit strength.6
Historical falsification — the sovereign platform stress test
The bull thesis holds that the GIC platform secures Genus a captive order pipeline while shielding its balance sheet from project-finance strain. The operating record supports a more qualified reality.
First, the working-capital promise was only partially realized. Receivable days stood at 207 in March 2025, down only marginally from 215, while gross current assets stretched to 370 days, according to CRISIL.6 Operating cash flow remained negative through FY24, FY25, and FY26, registering cash burns of roughly Rs. 152 crore, Rs. 443 crore, and Rs. 219 crore, respectively.2 Operational improvement did eventually materialize: CRISIL observed receivables improving to between 130 and 140 days by September 2025,6 and management reported total working-capital days at 274 in March 2026.13 Yet that figure remained close to the level management had flagged as problematic in 2023, falling far short of the drop to 60% or 65% of prior levels floated on the investor call.
Second, the structure introduced significant related-party exposure. CRISIL reported short-term advances to related parties of roughly Rs. 195 crore as of March 2025, primarily to support Gemstar platform projects, and flagged increased financial support to group entities or platform project companies as a potential credit downgrade trigger.6 In addition, Genus remained obligated to fund its 26% equity share in project vehicles on a staggered basis.6 The sovereign shield protected the balance sheet from senior concession debt, but it did not come without capital demands.
Third, pricing discipline works both ways. Management maintained in 2023 that equipment sales to the platform would take place at "competitive arm length pricing" between distinct corporate entities,10 explaining that Genus quotes its supply price prior to each tender bid, after which the platform determines its own markup.10 While sound from a corporate governance perspective, this framework also means GIC, as a 74% equity owner targeting concession-level returns, has every incentive to scrutinize hardware and deployment costs. An exclusive supplier designation guarantees captive volume within the platform; it does not guarantee vendor pricing power.
Fourth, counterparty concentration fundamentally inverted. Prior to the transaction, Genus's credit risk was dispersed across dozens of individual state utilities. By mid-2026, more than 90% of its executable order book ran through a single joint venture.17 While the ultimate financial health of the projects remains tied to discom collections, Genus's primary commercial counterparty is now concentrated in a single partner.
The historical evidence leaves the "balance-sheet shield" thesis intact, but significantly more nuanced than initial headlines suggested. The platform allowed Genus to participate in tenders at a scale that would have overwhelmed its standalone balance sheet—a decisive strategic breakthrough. Yet it did not eliminate working-capital drag, it added related-party funding commitments, and it traded discom diversification for platform concentration. The operating metric that would confirm the stronger bull claim is sustained positive cash flow from operations alongside continued platform expansion; the indicator that would challenge it is an expansion in advances to Gemstar entities alongside falling debtor days, which would suggest working capital has merely migrated across related corporate accounts.
With a funded concession pipeline secured, the operational question shifted to whether Genus could manufacture and deploy smart meters faster than its competitors, and whether rapid installation could establish an enduring competitive advantage.
VI. Core Business Dynamics: Scale, Tech Stack, & Competitive Warfare
The factory floor
On an automated surface-mount assembly line in Jaipur, reels of silicon chips feed high-speed pick-and-place machines, circuit boards glide through reflow ovens, and finished electronic meters are sealed, calibrated, and boxed in polycarbonate casings with integrated SIM cards or radio modules. Replicating that process across multiple manufacturing locations explains how the company met the sudden surge in procurement across FY25 and FY26. Genus operates manufacturing plants in Jaipur, Haridwar, and Guwahati, with total annual capacity reaching roughly 1.8 crore meters, according to CRISIL.6 On its third-quarter FY25 call in February 2025, management confirmed that production had commenced across its expanded capacity,18 and by early 2026 the company brought an integrated manufacturing facility online at Kotputli in Rajasthan alongside its legacy plants.19
The Guwahati plant, established in 2017,7 carries strategic geographic weight: it sits adjacent to the northeastern and eastern states where RDSS procurement has been heaviest, including Assam, one of the first states where Genus secured operational go-live certifications.20
That manufacturing footprint translated into substantial physical volume. Genus delivered 94 lakh meters in FY25, according to CRISIL,6 and produced another 90 lakh meters in the first half of FY26 alone.11 By February 2026, the company reported installing 1 crore smart meters under RDSS across nine states, with roughly 2.5 crore Genus-manufactured smart meters active nationwide, including approximately 1.5 crore units deployed through competing AMISPs and utility partners.1921
What Genus actually sells
Electricity metering represents virtually the entire operating business. The company historically carried a small "strategic investment" division—a legacy holding operation that was subsequently demerged into a separate listed entity, Genus Prime Infra, under an arrangement where shareholders received one Rs. 2 share for every six Rs. 1 shares held; following approval by the National Company Law Tribunal, approximately 5.08 crore shares were allotted.12 The transaction removed a non-core capital allocation distraction from the listed operating company's balance sheet, though it did not sever ties to the broader promoter group.
Within its core market, Genus sells an integrated systems architecture rather than standalone hardware. Under an AMISP concession, the contractor must supply the head-end system that communicates with field devices, the meter data management software that converts consumption data into billing records, the wide-area communications network, and ongoing operational maintenance for up to a decade. To support this expanded scope, Genus built an in-house software engineering team exceeding 300 personnel19 and developed an end-to-end suite of smart metering hardware, enterprise software, and SaaS platforms for utilities.6
The technology stack, in plain English
At its technical core, a smart meter combines an electronic energy meter with a digital two-way radio. The communications module transmits consumption telemetry back to the utility and receives operational commands, such as executing remote disconnections when a prepaid balance is exhausted.
Deployments rely on two primary network topologies. Cellular meters house an internal SIM card and communicate across public mobile networks, including narrowband IoT protocols engineered for low-power industrial devices—an architecture Genus tested in 2019 during an early NB-IoT deployment with Vodafone Idea.7 Radio-frequency mesh meters, by contrast, communicate peer-to-peer, relaying data packets across neighboring devices until reaching a centralized network gateway—an arrangement suited for dense urban housing where mobile signals struggle to penetrate interior walls.
Operating these networks requires standardized protocol interoperability. Genus became the first domestic manufacturer to secure DLMS certification for its electronic meters in 2007,7 adopting the open DLMS/COSEM standard that allows meters from one hardware vendor to communicate with head-end software from another. While essential for nationwide scale, that open architecture cuts both ways commercially.
Hardware manufacturing also carries supply-chain dependencies. While Genus reports that its smart meters achieve over 60% domestic value addition, critical internal disconnect relays continue to be procured from both Indian and Chinese suppliers.11 CRISIL estimates that imported inputs account for 40% to 45% of total meter component costs.6 This import exposure creates direct operating vulnerabilities: management lowered its FY27 operating margin guidance specifically in response to rising raw material expenses,13 while foreign-exchange fluctuations pass directly into the landed cost of imported electronic components.13
Market share: two different numbers
Assessing the company's competitive position requires distinguishing between its two operating roles. On its fourth-quarter FY26 earnings call, management estimated its market share at 22% to 23% as an AMISP concessionaire, but above 30% as a meter manufacturer.13 The difference between those two figures reflects the volume Genus generates by selling finished hardware to competing concessionaires—a commercial flexibility management explicitly confirmed on its July 2023 investor call: "We can supply to anybody, any AMISP."10
The competitive map
The competitive landscape divides into two distinct tiers.
The first tier consists of pure-play hardware manufacturers. HPL Electric & Power reported an order book exceeding Rs. 3,400 crore in February 2025, with smart meters comprising the vast majority of its metering division's forward commitments.22 Schneider Electric expanded its domestic presence by acquiring Larsen & Toubro's electrical and automation portfolio—which included utility metering operations—alongside Temasek affiliate MacRitchie for Rs. 14,000 crore.23 Secure Meters, an unlisted competitor based in Udaipur, maintains an established engineering presence with privately held financials, while smaller regional fabricators contest localized state tenders.
The second tier comprises large-scale AMISP concession platforms with substantial capital resources. Adani Energy Solutions announced on February 5, 2026, that it had installed 1 crore smart meters across state discoms within roughly 24 months of initiating its rollout, was deploying approximately 25,000 meters daily, and held aggregate concession mandates for roughly 2.5 crore meters across five states.24 IntelliSmart, a joint venture between EESL and the National Investment and Infrastructure Fund, operates as another major concession platform. On Genus's July 2023 investor call, the Joint Managing Director identified Adani, Montecarlo, NCC, and GMR as active AMISP competitors.10
The Adani operational comparison provides a useful industry benchmark. Adani's cumulative RDSS installations matched Genus's deployment total at the same point in early 2026,2419 demonstrating that Genus does not hold a commanding scale advantage at the concession platform level. Where Genus differentiates itself is vertical integration: it couples an AMISP bidding vehicle with internal, large-scale meter manufacturing plants. By contrast, Adani's rollout announcements cited intra-group affiliates for systems software, data architecture, and workforce deployment, but made no reference to an in-house hardware manufacturing base.24 That structural divergence allows Genus to monetize competitor rollouts by supplying hardware to rival bidding consortia.
War-gaming a tender
The mechanics of an RDSS concession award illustrate how these competitive dynamics play out. A state discom packages several million consumer connections across multiple operating circles into a competitive tender. Bidding consortia—including the Genus-GIC joint venture, Adani Energy Solutions, IntelliSmart, and independent infrastructure contractors—assemble project estimates covering meter fabrication, communications networking, software integration, field installation, and long-term maintenance. Each AMISP layers its cost of capital and hurdle rate over those operating costs, submitting a single bundled service bid. The technically qualified bidder quoting the lowest net price per meter wins the concession.5
In that bidding structure, the Genus platform operates with two structural advantages: it sources metering hardware at internal manufacturing cost rather than paying vendor markups, and it draws on equity backing from GIC. Yet its competitors bring countervailing strengths. Adani leverages group balance-sheet scale and extensive operational experience managing regulated transmission and distribution assets;24 IntelliSmart benefits from the institutional relationships and procurement history of its co-parent, EESL. Furthermore, when rival AMISPs win tenders against the GIC platform, they frequently turn to Genus to supply the underlying hardware.
That dual positioning creates an unusual commercial balance. With roughly 1.5 crore Genus smart meters deployed through competing AMISPs and utility contractors by early 2026,19 the company serves simultaneously as a direct concession rival and a primary equipment vendor to the broader market. That dual role diversifies manufacturing revenue across competing project vehicles. It also caps hardware pricing power, because an equipment vendor cannot aggressively raise supply prices on competitors without prompting them to qualify alternate component manufacturers.
Historical falsification — can switching costs protect the leader?
The argument that proprietary software protocols and high switching costs insulate Genus from competitive erosion encounters a procurement authority explicitly committed to vendor neutrality. In December 2025, Union Power Secretary Pankaj Agarwal reiterated that the central government intended to enforce strict protocol interoperability across national rollouts: "There should not be any locking between any manufacturer and any protocol."25 The standardized RDSS regulatory framework awards concession packages strictly to the lowest technically compliant financial bidder,5 with individual states tendering separately under widely divergent contract terms and price realizations.14
The historical evidence substantially narrows the scope of the switching-cost thesis. Once an AMISP secures a specific concession, it remains firmly entrenched throughout the multi-year contract term because it finances, owns, and operates the integrated metering infrastructure. Across new contract awards, however, every incremental tender package triggers an unbundled price auction where open communication standards render physical hardware interchangeable. The primary operational metric for investors to monitor is Genus's win rate across newly awarded concession tenders, rather than the historical size of its cumulative installed base.
Manufacturing scale and vertical integration explain how Genus secures concession volumes. Converting those paper contracts into durable cash generation, however, depends on the complex financing dynamics of the concession contracts themselves—an area where operating reality diverges sharply from headline announcements.
VII. Unit Economics & Cash Flow Anatomy: The DBFOOT Reality
Following a single meter
Consider the path of a single-phase meter traveling from a Genus assembly line to a residential wall in Assam. Under the pricing baseline established on the July 2023 investor call, the platform wins a concession at an all-in rate of roughly Rs. 10,000 per meter, inclusive of taxes.10 Approximately 60% of that contract value—about Rs. 6,000—accrues directly to Genus for manufacturing, installing, and integrating the meter and its communications systems.10 Genus books this revenue upfront as hardware is delivered and installed, which explains why its top-line earnings expanded dramatically long before cash began flowing from the underlying concession.
The platform, by contrast, operates under a design-build-finance-operate-own-transfer framework, spending capital that it recovers only through monthly service fees spread across 93 months following Operational Go-Live.5 On the second-quarter FY26 call, management noted that monthly billing commences roughly 45 days after achieving go-live certification.11 At that point, out of 80 lakh meters Genus had physically deployed, approximately 42 lakh had completed site acceptance testing, and only 40 lakh had secured formal operational go-live approval.11 That gap between physically installing a meter and having it formally recognized as an earning asset represents the central timing mismatch governing the entire business model.
Where the profit shows up, and where the cash does not
On the income statement, the expansion appeared extraordinary. Consolidated revenue roughly doubled from about Rs. 1,201 crore in FY24 to Rs. 2,442 crore in FY25, before nearly doubling again to about Rs. 4,751 crore in FY26.2 FY26 EBITDA reached approximately Rs. 960 crore—an operating margin of around 20%—while profit from continuing operations climbed to roughly Rs. 605 crore.12
The cash flow statement told a far more sobering story. Operating cash flow remained negative in each of FY24, FY25, and FY26, culminating in more than Rs. 800 crore of cumulative cash drain across three years of record accounting profits.2 Total borrowings escalated from about Rs. 1,366 crore in FY25 to about Rs. 2,302 crore in FY26,2 leaving net debt at roughly Rs. 1,573 crore as of March 31, 2026, predominantly in short-term facilities.13 In simple terms: Genus was recognizing earnings far faster than it could collect cash, funding the working-capital deficit through commercial debt.
Management addressed this divergence directly. On the fourth-quarter FY26 call, leadership stated that rapid revenue growth had absorbed about 40% of incremental operating cash in FY26—down from 80% to 85% in FY25—and projected that working capital would consume about 20% in FY27, with operating cash flow turning positive the following year.13 Concurrently, management guided for a 50-to-75-day improvement in working-capital days over FY27.
While this presented a clear operational trajectory, the timeline itself proved fluid. In February 2026, an executive told CNBC-TV18 that the company expected to achieve cash-flow positivity by the end of FY27.26 By May 2026, formal guidance softened, forecasting working-capital gains in FY27 and deferring positive operating cash flow into the year after.13 A twelve-month slip does not constitute a crisis, but it reflects a moving target that investors must monitor closely.
The payment security stress test
On paper, the Direct Debit Facility offers one of the strongest payment safeguards in Indian infrastructure: AMISP service fees are intercepted directly from digital consumer collections before the discom receives the funds.5 The structural vulnerability is that this mechanism operates only once meters are live, billing, and collecting. If devices cannot be converted into prepaid mode, or if a state government halts prepaid billing in response to public dissatisfaction, the cash flowing into that payment waterfall diminishes sharply.
This risk is not hypothetical. In April 2026, Uttar Pradesh halted the replacement of legacy meters with prepaid smart meters following intense consumer pushback over sudden bill increases, mandatory installations, and power disconnections despite positive balances. Prior to the freeze, the state had installed more than 78 lakh smart meters—over 70 lakh in prepaid mode—against a total target of roughly 3.5 crore units. The state government constituted a four-member expert committee and introduced interim protections, including grace periods and advance disconnection alerts.27 Nationally, the central government extended the overall RDSS deadline by two years to March 31, 2028, with nationwide deployment standing at 7.24 crore smart meters by June 30, 2026—just 28% of the original target. Official reviews cited public resistance, cellular communication network gaps, and backend data bottlenecks for the delay.16
Genus has also faced localized project scrutiny. In August 2025, the company filed stock exchange clarifications confirming that no liquidated damages had been levied on its Rajasthan contracts and that no agreements had been terminated, describing field delays as industry-wide. It also denied reports of being blacklisted in Goa, emphasizing that the High Court had quashed a 2024 internal administrative memo restricting its participation.20 While these disclosures provided clear, on-the-record refutations, they highlighted the recurring operational hazards native to public utility contracts: execution delays, the threat of liquidated damages under a rigid 27-month installation clock,5 and state-level political discretion.
Inside the working-capital machine
Why does the cash conversion cycle remain so stubborn? A national smart metering rollout is fundamentally an expansive field logistics operation reaching into thousands of towns and villages. Semiconductors and relays must be ordered and financed months in advance. Assembled meters sit in regional warehouses waiting for field crews. Once installed, units must wait for site acceptance testing, then for utility go-live certification, and finally for the initial 45-day billing cycle to run its course. Each operational phase locks up capital.
The financial data illustrates the sheer scale of that commitment. Inventory days stood at roughly 223 in FY25 before moderating to about 170 in FY26, while debtor days declined from around 204 to 115 over the same period.2 On the second-quarter FY26 call, management noted that internal inventory days had compressed from 187 to 126, while acknowledging that elevated buffer inventory remained tied up across multiple project sites.11 Credit rating agency CRISIL observed inventory holding around 160 days in the first half of FY26, noting that the company's bank working-capital lines of Rs. 816 crore were running at an average utilization of 93%.6 Operating credit lines at more than nine-tenths of capacity leaves very little margin to navigate unexpected field disruptions.
This dynamic also highlights a critical accounting nuance. Because Genus recognizes revenue on hardware delivery and installation, while the concession platform collects cash gradually over multi-year operational cycles, the profit-and-loss statement can show robust earnings even as liquidity remains locked in field inventory, platform receivables, and pro-rata equity contributions. That divergence does not reflect financial impropriety; it is the inherent mechanics of the concession model. But it makes reviewing the cash flow statement and related-party schedules far more illuminating than reading the income statement alone.
The analytical conclusion
The unit economics of the model are highly lucrative for an equipment manufacturer, but exceptionally demanding on its balance sheet. Genus captures an upfront manufacturing and installation margin that registers quickly in reported earnings, alongside a 26% share in a long-term annuity that has only just begun to pay out. The Direct Debit Facility provides a credible structural defense, yet its efficacy hinges on meters operating in prepaid mode across states where prepaid billing remains politically sensitive. The operational evidence indicates that the framework succeeds where state utilities maintain steady political commitment, as demonstrated by deployment progress in Bihar,14 and stalls where that resolve falters.
That persistent tension between ambitious commitments and cash realization leads naturally to the executives making the promises and the governance framework that oversees them.
VIII. Management Credibility, Capital Allocation, & Governance Stress Test
The family at the controls
The boardroom roster reflects the family-dominated leadership established three decades ago. Ishwar Chand Agarwal serves as Executive Chairman, alongside Kailash Chandra Agarwal as non-executive Vice Chairman. Managing Director and CEO Rajendra Kumar Agarwal directs technology development, research, and corporate strategy, while Joint Managing Director Jitendra Kumar Agarwal leads commercial sales and business development, balancing executive duties with board seats at industry body IEEMA and joint-venture vehicle Gemstar Infra India.9
The independent directorships provide direct institutional ballast. Among them sits Subhash Chandra Garg, a 1983-batch IAS officer who served as India's Economic Affairs Secretary from 2017 to 2019, briefly served as Power Secretary in 2019, and previously held office as an Executive Director at the World Bank.9 His presence lends senior regulatory and fiscal insight, underscoring how deeply an advanced metering concessionaire's fortunes remain tethered to civil service decision-making.
The leadership of the finance function has shifted as well. The company appointed Nathu Lal Nama as Executive Director and Chief Financial Officer in February 2026.26 For an enterprise whose primary operational hurdle is converting accounting profits into cash receipts, the finance chair carries operational weight second only to the chief executive's.
How management talks when the news is bad
A revealing gauge of management candor is how leadership communicates when near-term visibility deteriorates. On the third-quarter FY25 earnings call in February 2025, Jitendra Agarwal acknowledged that no significant tenders were expected over the ensuing six to nine months, while management conceded that the working-capital cycle was unlikely to improve over the following two quarters.18 When questioned about margin expansion, Kailash Agarwal urged analysts to focus on full-year averages rather than chasing quarterly fluctuations.18 While this showed a willingness to temper near-term enthusiasm, the call's conservative EBITDA margin guidance of 15% to 16%18 was quickly overtaken when full-year FY25 operating margins landed near 20%.6 The episode pointed to a broader communication pattern: management has frequently framed operating margins cautiously, while projecting an optimism on cash flow that execution has yet to match.
Guidance discipline: the record
Management credibility is best judged by promises against outcomes, and on that measure the operating record is mixed.
On revenue, Genus has consistently delivered. In July 2023, management guided for Rs. 1,200 to Rs. 1,400 crore of revenue for FY24;10 it delivered about Rs. 1,201 crore, touching the lower end of that range.2 For FY25, it targeted roughly Rs. 2,500 crore with 15% to 16% EBITDA margins;18 it closed at about Rs. 2,442 crore—a narrow top-line miss, but accompanied by operating margins of around 20%, well above guidance.6 For FY26, it raised its initial target from Rs. 4,000 crore at an 18% margin to Rs. 4,500 crore at 20%;11 it completed the year delivering roughly Rs. 4,740 crore, with EBITDA margin around 20%.12 Over three years of rapid acceleration, the revenue trajectory reflected steady upward revisions rather than serial disappointment.
On margins, the narrative has been less steady. In November 2025, management guided for FY27 revenue of Rs. 5,500 to Rs. 6,000 crore at a 20% EBITDA margin.11 By February 2026, an executive publicly suggested that margins could reach close to 22%.26 Yet by May 2026, formal guidance shifted to Rs. 6,000 to Rs. 6,500 crore at 18%, with leadership citing rising raw material costs.13 While raising revenue targets to compensate for lower margins was an honest operational adjustment, the revision arrived within three months of a far more buoyant forecast.
On cash generation, the record has been far more fragile. The structural compression of the working-capital cycle promised in 2023 took significantly longer to materialize than initial communications suggested, and the timeline for turning operating cash flow positive has slipped by a full fiscal year.
The opening results of FY27 reaffirmed the top-line momentum. In the first quarter of FY27, revenue expanded approximately 45% year-on-year to Rs. 1,364.88 crore, while consolidated net profit grew roughly 43% to Rs. 196.64 crore, even as seasonal delivery schedules caused revenue to soften by about 11% sequentially from the fourth quarter of FY26.17
The ED investigation
The most serious governance event in Genus's recent history occurred on December 3, 2024, when the Enforcement Directorate searched the company's corporate office and the chairman's residence. Genus stated that it extended full cooperation to the authorities and maintained that the inquiry would cause no disruption to ongoing business operations.28 The stock immediately fell to its 5% lower circuit limit.28
The context emerged in an ED prosecution complaint filed on December 16, 2024, before a special court in Patna against Sanjeev Hans, a Bihar-cadre IAS officer who had served as chairman of Bihar's state power holding company. According to media reporting on the chargesheet, the ED alleged that Genus, which secured smart meter contracts in Bihar valued between Rs. 3,300 and Rs. 3,800 crore in 2022 and 2023, routed Rs. 60 crore to Hans through subcontracted work channeled via entities controlled by his associates. The reported chargesheet did not indicate that Genus itself had been formally charged.29 On the third-quarter FY25 investor call in February 2025, management acknowledged that the broader fallout from the search remained uncertain.18
These assertions remain allegations in an ongoing money-laundering inquiry rather than judicial findings of guilt, and their legal resolution was not disclosed in the materials reviewed for this account. Yet their commercial materiality is clear: Bihar was an anchor AMISP market for Genus, the allegations center directly on the state procurement mechanisms that underpin the entire sector, and any adverse legal determination could carry reputational damage or affect the company's eligibility in future utility tenders.
Encumbrances and the family's stake
Promoter ownership contracted from roughly 50.5% in March 2020 to about 39.3% in June 2026, a dilution pattern consistent with GIC's warrant investment.2 Third-party market data indicated that approximately 68.55% of the remaining promoter holding was pledged or encumbered as of June 2026.30 Under regulatory disclosure rules, the classification of "encumbrance" encompasses non-disposal undertakings provided to lenders as well as traditional share pledges, meaning the aggregate figure does not solely represent margin-call exposure; nonetheless, it reflects substantial leverage rather than progressive de-pledging. In an April 2026 disclosure, the promoter group confirmed that no new encumbrances had been created during FY26 beyond those already on record.31
The market narrative suggesting that the sovereign partnership would prompt a rapid reduction in promoter encumbrances is not borne out by disclosures through mid-2026. While encumbered shares have ceased rising, the proportion remains elevated and represents an ongoing monitoring point for institutional investors.
The activist's checklist
A skeptical investor evaluating Genus would focus on four unresolved questions. First, why has operating cash flow remained negative through three consecutive years of record accounting profits, and what specific milestone guarantees that cash drain will end? Second, how much of Genus's capital remains tied up in advances and equity commitments to related Gemstar platform entities, and are those exposures expanding? Third, what is the status and contingent liability surrounding the Bihar procurement investigation? Fourth, why do promoter holdings remain so heavily encumbered in a business with a multi-thousand-crore market valuation, and what group-level liabilities do those pledges secure? None of these issues are obscure; all represent core operating questions that long-term shareholders must require management to answer.
Credibility and corporate governance establish the ceiling on the valuation multiple the market will assign to Genus's reported earnings. How durable those earnings remain against competitive and technological forces is the subject of the structural analysis that follows.
IX. Strategic Strategy Analysis: 7 Powers & Porter's 5 Forces
The chess board
Consider the Indian smart metering market as a chessboard with an unusual structural constraint: the state owns the board, sets the rules, and serves as the sole commercial buyer. Every strategic framework applied to the sector must be evaluated through that monopsony lens.
Hamilton Helmer's 7 Powers
Scale economies — real, but contestable. An annual manufacturing capacity of roughly 1.8 crore meters,6 coupled with 94 lakh meters delivered in FY256 and production of 90 lakh meters in a single half-year,11 provides Genus meaningful purchasing power over semiconductors, disconnect relays, and polycarbonate enclosures, while spreading fixed research and software development expenses across high volumes. Yet scale does not confer an insurmountable barrier: established competitors such as HPL Electric and Schneider Electric operate large manufacturing facilities, while Adani Energy Solutions demonstrated that a well-capitalized challenger can deploy 1 crore smart meters within roughly two years.24 Scale offers operational leverage, but it does not deter well-funded rivals.
Network effects — absent. Connecting an additional smart meter to a discom's distribution network does not increase the value of existing meters to the utility or to end consumers.
Counter-positioning — moderate. Genus's hybrid architecture—an established meter manufacturer holding a 26% equity stake in a dedicated concession vehicle—allows it to compete simultaneously as an AMISP prime bidder and as a merchant hardware supplier to rival concessionaires.1013 Pure-play manufacturers lacking institutional capital struggle to absorb the balance-sheet demands of long-term concessions, while pure concessionaires without in-house factories must buy meters from external vendors. The durability of this positioning remains limited, however, as competitors can replicate the arrangement by aligning with infrastructure sponsors, as IntelliSmart demonstrated through its joint venture with the National Investment and Infrastructure Fund.
Switching costs — contract-bound. Within an awarded concession circle, switching costs are exceptionally high because the AMISP finances, owns, and maintains the integrated hardware and software stack over an operating life of up to ten years.5 Across successive procurement rounds, however, switching costs largely evaporate: mandated open communications standards and the central government's strict protocol interoperability policy ensure that field hardware remains interchangeable.25
Branding — negligible. Utility tenders evaluate proposals strictly on technical pre-qualification and lowest compliant bid, leaving corporate brand equity with virtually no pricing leverage in contract awards.5
Cornered resource — absent. While the joint venture with GIC provides vital equity scale and balance-sheet flexibility, sovereign and private infrastructure capital is not proprietary to Genus; competing platforms secure comparable institutional backing through sovereign wealth funds, private equity, or domestic corporate parents.
Process power — moderate and plausible. More than three decades of engineering meters tailored to Indian grid conditions, securing the domestic industry's first DLMS certification in 2007,7 and executing repeated manufacturing scale-ups demonstrate genuine operational know-how. The definitive proof of proprietary process power, however—such as verifiably lower field failure rates or faster discom operational go-live certifications relative to peers—remains undisclosed in public filings.
Porter's Five Forces
Bargaining power of buyers — extremely high. State discoms, central nodal agencies, and state power ministries define technical specifications, award contracts strictly through lowest-cost bidding, hold unilateral authority over operational go-live certifications, and retain the political discretion to suspend prepaid rollouts, as demonstrated by regulatory interventions in Uttar Pradesh.275
Bargaining power of suppliers — moderate. With imported inputs accounting for an estimated 40% to 45% of total meter component costs,6 global semiconductor pinches, relay shortages, or currency depreciation can rapidly compress operating margins, as evidenced by management's downward revision to FY27 margin guidance.13
Threat of new entrants — moderate. Mandatory technical qualifications, multi-year operating track records, and substantial balance-sheet requirements establish formidable barriers against uncapitalized newcomers; however, deep-pocketed infrastructure conglomerates have entered the sector swiftly and captured significant market share.24
Threat of substitutes — negligible. For regulated grid revenue collection, automated two-way metering infrastructure faces no viable technological substitute at the consumer edge.
Rivalry among existing competitors — intense. Concession tenders are contested through unbundled reverse auctions, forcing operators to price each contract from scratch, while management explicitly flagged intensifying pricing competition across the sector on its second-quarter FY26 earnings call.11
The strategic conclusion
Genus's competitive advantage is tangible but bounded: it operates as a vertically integrated manufacturer-concessionaire in a sector where the public buyer systematically designs away structural pricing leverage. Its moat rests on manufacturing scale, execution speed, and institutional capital access via GIC, rather than customer lock-in or pricing power. That positioning supports a substantial, profitable operation, but one whose returns will be renegotiated tender by tender and state by state.
Those structural dynamics translate directly into a set of operating lessons that apply well beyond smart metering.
X. Playbook: Business & Investing Lessons
Lesson 1: The sovereign wealth arbitrage
When an addressable market outgrows an operating balance sheet, an enterprise does not have to lever itself to capacity. Genus effectively borrowed its partner's cost of capital and investment horizon: a patient sovereign sponsor could hold concession assets for a decade, allowing Genus to concentrate on manufacturing and field deployment. The payoff emerged in top-line revenue that expanded from about Rs. 808 crore in FY23 to about Rs. 4,751 crore in FY26.2 The cost registered in expanding related-party commitments and commercial concentration in a single platform partner.617
Lesson 2: Certification is not commercialization
Genus accumulated technical firsts across three decades, from pioneering tamper-proof electronic meters and securing India's first DLMS certification to deploying early smart village pilots, end-to-end smart metering networks, and NB-IoT AMI architectures.7 None of those milestones, on its own, generated pricing power or sustained commercial scale. The commercial breakthrough stemmed from shifts in procurement policy and concession financing rather than hardware design alone. That historical pattern offers a cautionary baseline for adjacent opportunities, suggesting that enthusiasm around smart gas and water metering warrants restraint until verifiable, disclosed orders materialize.
Lesson 3: Monopsony procurement pulls returns toward the cost of capital
A decade of selling commoditized hardware to state power monopolies produced volatile operating margins and single-digit returns on capital in cyclical troughs.2 Migrating up the value chain into multi-year concession contracts offered an operational exit from the equipment-vendor trap. Yet that transition still leaves the concessionaire tethered to a public monopsony that procures every project package through lowest-bidder competitive tenders.5
Lesson 4: A payment security mechanism is only as good as the politics beneath it
A direct debit facility establishing senior priority over digital consumer payments provides formidable legal protection on paper.5 Yet the mechanism presumes end users are active in prepaid mode and paying through channels the concessionaire can monitor. When regional politics push back against prepaid conversion, as occurred in Uttar Pradesh in April 2026,27 the cash feeding that payment waterfall quickly thins. For infrastructure investors, contractual security structures must be stress-tested against state-level political realities, not just statutory clauses.
Those lessons frame the final inquiry: from here, what validates the bull case, and what threatens to break it?
XI. The Investment Thesis & Bear vs. Bull Case
The three KPIs that decide the story
1. Order inflow versus order book burn-down. The executable order book peaked at about Rs. 31,776 crore in September 2024,3 and subsequently contracted across four consecutive quarters: to Rs. 28,758 crore in September 2025,11 roughly Rs. 27,000 crore in December 2025,15 Rs. 25,173 crore in March 2026,13 and Rs. 24,020 crore in June 2026.17 That steady decline is the mechanical consequence of manufacturing execution outpacing new contract awards. To counter this burn-down, management highlighted an active industry bidding pipeline of roughly Rs. 1,20,000 crore covering approximately 15 crore meters,15 alongside expected FY27 tenders covering roughly 9 crore meters across key states including Haryana, Madhya Pradesh, Punjab, and Tamil Nadu.13 Whether Genus can capture its historical market share from that upcoming procurement wave is the single most critical variable determining revenue visibility for FY28 and beyond.
2. Operating cash flow and working-capital days. Management guided for a 50-to-75-day improvement in working-capital days in FY27 and targeted positive operating cash flow in FY28.13 This metric serves as the definitive test of whether record accounting profits can successfully translate into liquid cash.
3. Operational go-live conversion. The proportion of physically installed meters that receive formal utility certification and transition into active billing dictates when monthly annuity income begins to flow—both to clear Genus's manufacturing receivables and to generate cash distributions from the platform where it holds a 26% stake.115
The bull case
The bull case rests on manufacturing execution and operating scale. Genus expanded consolidated revenue roughly fourfold across two fiscal years while maintaining EBITDA margins near 20%,12 set an installation target of at least 1 crore meters in FY27 supported by manufacturing capacity exceeding 1.8 crore meters,15 and guided for FY27 revenue between Rs. 6,000 and Rs. 6,500 crore.13 With nationwide deployments covering only a modest fraction of the central government's ultimate target, the official extension of the RDSS deadline to March 31, 2028, lengthens the operational runway rather than curtailing it.16
The second pillar centers on the emerging concession annuity. As operational go-live certificates accumulate across project circles, the joint venture begins collecting per-meter-per-month service fees for up to 93 months.5 Genus's 26% pro-rata share of those platform distributions represents a modest contributor to near-term earnings, but could evolve into a predictable, high-margin cash flow once capital-intensive field installations wind down. If realized, that recurring revenue could prompt public markets to value Genus in part as an infrastructure concession owner rather than purely as a cyclical hardware fabricator, although management has not publicly quantified the projected size or timing of that annuity payout.
The third pillar is balance-sheet normalization. If operating cash flow turns positive on management's guided timeline, net debt could begin to decline, related-party funding advances could abate, and the market discount linked to elevated promoter share encumbrances could narrow.
The bear case
The bear case begins with backlog depletion. The executable order book has contracted by roughly one-quarter from its peak.317 If the next wave of state utility tenders suffers prolonged delays, administrative fragmentation, or aggressive price competition from well-funded rivals such as Adani Energy Solutions,24 Genus's revenue could peak in FY27 and decline thereafter, reclassifying a perceived structural compounder as a cyclical capital-goods vendor.
The second risk is political and execution friction. Uttar Pradesh's administrative freeze on prepaid meter replacements27 and widespread timeline slippage across national RDSS timelines16 underscore the vulnerability of concession schedules to local public pushback. Slower utility approvals defer the onset of concession annuities, while protracted field delays risk triggering liquidated damages under the contractual 27-month clock.5
The third vulnerability lies in operating margins. Management trimmed its FY27 EBITDA margin forecast to 18% in response to escalating raw material costs,13 while credit rating agency CRISIL identified operating margins slipping to 15% to 16% or below as a specific trigger for a credit rating downgrade.6 Because imported components account for 40% to 45% of total meter bill-of-materials costs and concession contracts are structured at fixed prices,6 currency depreciation or global semiconductor disruptions would pass directly into operating profit.
The fourth concern is corporate governance and structure. The Enforcement Directorate investigation surrounding the Bihar utility contracts remains legally unresolved in public disclosures reviewed for this account,29 promoter share encumbrances remain high,30 and more than 90% of the executable order book sits with a single related-party joint venture.17
The risk radar
Beyond the primary thesis, three second-order operational dynamics warrant close attention.
Cybersecurity and data privacy. Because a connected smart meter possesses the technical capability to disconnect household power remotely, grid integrity is paramount. The standard bidding document requires concessionaires to deploy a key expert in cybersecurity,5 while research by the Prayas Energy Group highlighted uneven state-level protocols concerning data privacy and consumer awareness.14 A significant network breach or mass-disconnection software glitch would quickly escalate into a political crisis rather than a routine technical defect.
Trade and currency exposure. In August 2025, Genus informed the stock exchanges that it held no active supply contracts with the United States and manufactures its products domestically,20 mitigating direct export tariff vulnerabilities. The far more substantial exposure runs in reverse: reliance on imported components leaves operating costs directly exposed to global supply pinches and foreign-exchange fluctuations.6
Credit ratings and refinancing. CRISIL reaffirmed Genus at AA-/Stable in November 2025 and expanded its rated bank facilities to Rs. 4,927 crore,6 reflecting substantial banking support. The rating agency's explicit downgrade triggers, however, closely mirror the bear thesis: operating margin compression, stalled working-capital recovery, and heightened financial support to platform project entities.6
Weighing the case
The accumulated evidence supports a clear but qualified conclusion. Genus has established that it can manufacture and deploy hardware at national scale, and the equity structure with GIC effectively unlocked its balance-sheet constraints. The operating record does not yet demonstrate unassailable pricing power, a proprietary technology moat, or a self-funding business model.
The investment thesis therefore rests less on whether Genus is an accomplished manufacturer—a capability the operational record largely validates—and more on three unresolved milestones: whether it can replenish its contracting backlog at viable margins, whether accounting profits finally convert into positive operating cash flow, and whether persistent governance overhangs begin to recede.
Beyond the installation boom lies a longer question: what these meters become once they are all in the ground.
XII. Epilogue: The Grid of 2035
The meter as a sensor
A smart meter is not the destination; it is an electrical grid's outermost nerve ending. Once a household transmits consumption telemetry every few minutes, a utility can introduce dynamic time-of-day tariffs—charging premium rates during evening peaks and discounting power at midday when solar generation floods the grid. It can identify an overloaded transformer before it fails, balance rooftop solar feeding back into local feeders, and eventually coordinate electric vehicles that both draw from and discharge into the network.
India's power sector remains early in that architectural transition. With approximately 7.24 crore smart meters installed by mid-2026 against a national target exceeding 25 crore,16 the foundational data layer is only beginning to take shape. Genus has positioned itself for that evolution, pointing to an in-house software engineering team exceeding 300 personnel alongside enterprise software and SaaS platforms designed to generate recurring utility revenue.619
Yet the investor's skepticism applies here as well. Enterprise data platforms, dynamic pricing engines, and predictive grid analytics remain future opportunities, and Genus's operating history reflects a protracted lag between demonstrating technical capability and converting it into commercial revenue. Furthermore, the economic value of the data layer typically accrues to whoever controls the consumer interface and core utility software—and in India's power architecture, that entity is almost invariably the state-owned discom itself.
Final reflection
Genus's three-decade trajectory offers a case study in how industrial champions are actually built in emerging markets. The business was not made by engineering an early electronic meter, nor by piloting a smart village, nor by shipping 1.5 million smart meters to a centralized national buyer. Its real breakthrough lay in surviving long enough for public policy to restructure the rules of procurement, and then securing a sovereign capital partnership that allowed a family-run manufacturer to ride a state-directed infrastructure wave without collapsing under its balance-sheet weight.
Whether that transition yields an enduring infrastructure franchise or merely represents a single, spectacular cyclical upcycle will be decided over the coming years in three places: in the order book, on the cash flow statement, and in a Patna courtroom where the governance integrity of its public utility contracts remains under review.
References
-
GIC Affiliate and Genus Power & Infrastructures Limited to set up a Platform to fund Smart Metering projects — GIC Newsroom, 2023-07-04 ↩↩↩↩
-
Genus Power Infrastructures Ltd consolidated financials and shareholding — Screener ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Genus Power: Order book crosses Rs.30,000 crore — T&D India, 2024-10-30 ↩↩↩
-
Revamped Distribution Sector Scheme (RDSS) — Ministry of Power, Government of India ↩↩
-
Features and Guidance Notes of SBD for Appointment of Advanced Metering Infrastructure Service Provider — REC Limited (RDSS Nodal Agency) ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Genus Power Infrastructures Limited — Rating Rationale — CRISIL Ratings, 2025-11-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Milestones — Genus Power Infrastructures Ltd ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Brief Profile of Directors — Genus Power Infrastructures Ltd, 2025-01 ↩↩↩↩↩↩
-
Genus Power Infrastructures Business Update Conference Call on GIC Transaction (transcript) — Genus Power, 2023-07-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Genus Power Infrastructures Ltd Q2 2026 Earnings Call Highlights — GuruFocus, 2025-11-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Genus Power Posts Strong Q4 And FY26 Results — Construction World, 2026-05-22 ↩↩↩↩↩
-
Genus Power Infrastructures Ltd Q4 2026 Earnings Call Highlights — Yahoo Finance, 2026-05-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Smart Metering in India: A work in progress — Prayas (Energy Group) ↩↩↩↩↩↩↩
-
Genus Power sees accelerated smart metering project execution in Q3FY26 — T&D India, 2026-02 ↩↩↩↩
-
Smart Meter Mission Loses Momentum As Installation Targets Slip — The Secretariat, 2026 ↩↩↩↩↩
-
Genus Power Infrastructures Ltd Q1FY27 Results — ICICI Direct, 2026-08-13 ↩↩↩↩↩↩↩
-
Genus Power Infrastructures Ltd Q3 2025 Earnings Call Highlights — Yahoo Finance, 2025-02-14 ↩↩↩↩↩↩
-
Genus Power Crosses 1 Crore Smart Meters — SolarQuarter, 2026-02-12 ↩↩↩↩↩↩
-
Genus Power Falls 6% Despite Clarification on Projects — HDFC Sky, 2025-08-29 ↩↩↩
-
Genus Power Reaches 10 Mn Smart Meters as RDSS Scales — Construction World, 2026-02-23 ↩
-
HPL Electric & Power Ltd: Smart meters dominate order book — T&D India, 2025-02-10 ↩
-
Schneider acquires L&T's electrical and automation unit for Rs 14,000 crore — VARINDIA, 2019-04-19 ↩
-
Adani Energy Solutions delivers landmark 1 crore Smart Meters across discoms — Adani Group, 2026-02-05 ↩↩↩↩↩↩↩
-
India seeks interoperability in smart meters, eyes 307 GW coal capacity by 2035: Power Secretary — The Tribune, 2025-12-07 ↩↩
-
Genus Power Targets ₹60 Billion Revenue by FY27, Expects Cash-Flow Positivity — ScanX, 2026-02-25 ↩↩↩
-
Why Uttar Pradesh Paused Prepaid Smart Meter Rollout After Public Protests — Asianet Newsable, 2026-04-21 ↩↩↩↩
-
Genus Power Shares Hit 5% Lower Circuit as ED Conducts Search — EquityPandit, 2024-12-05 ↩↩
-
Arrested Bihar IAS Sanjeev Hans 'accumulated Rs 100 cr assets, took bribe for contract' — ED chargesheet — ThePrint, 2024-12-19 ↩↩
-
Genus Power Infrastructures Ltd Downgraded to Hold Amid Mixed Technical and Valuation Signals — MarketsMojo, 2026-09-17 ↩↩
-
Genus Power confirms no new encumbrance on shares in FY26 — ScanX, 2026-04-08 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube