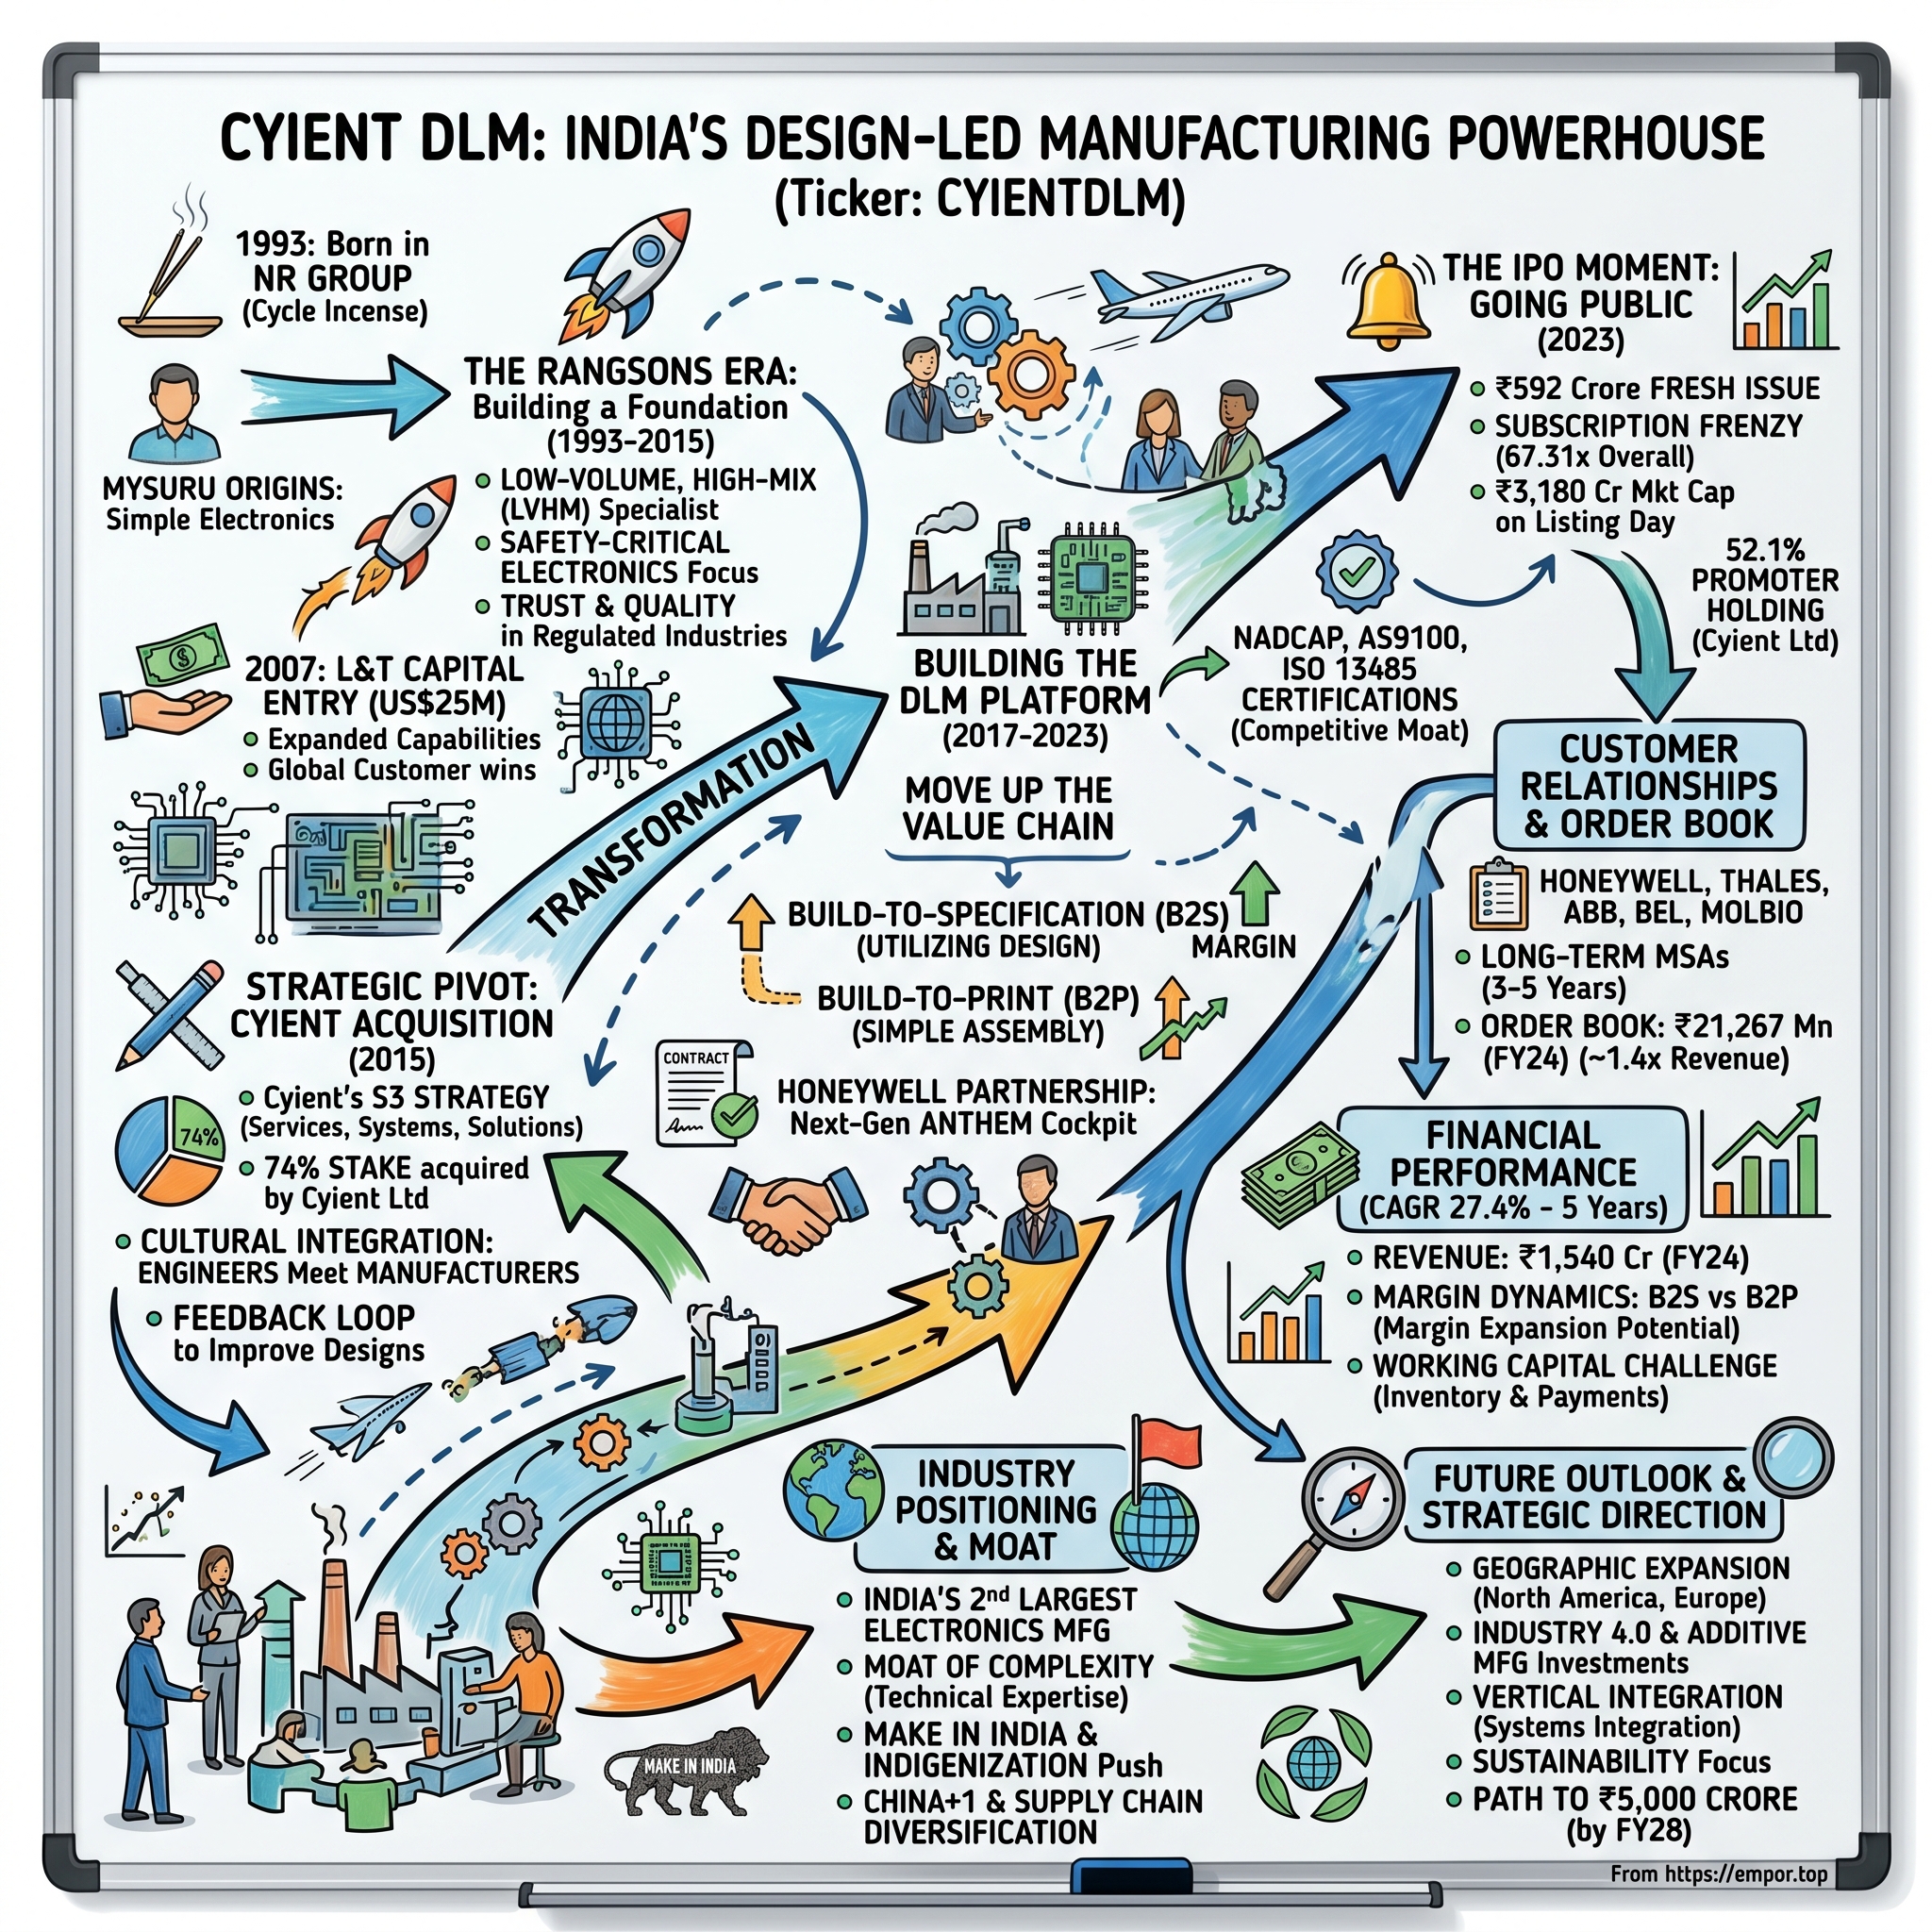
Cyient DLM: The Anatomy of a High-Reliability Electronics Platform
I. Introduction & The Strategic Crucible
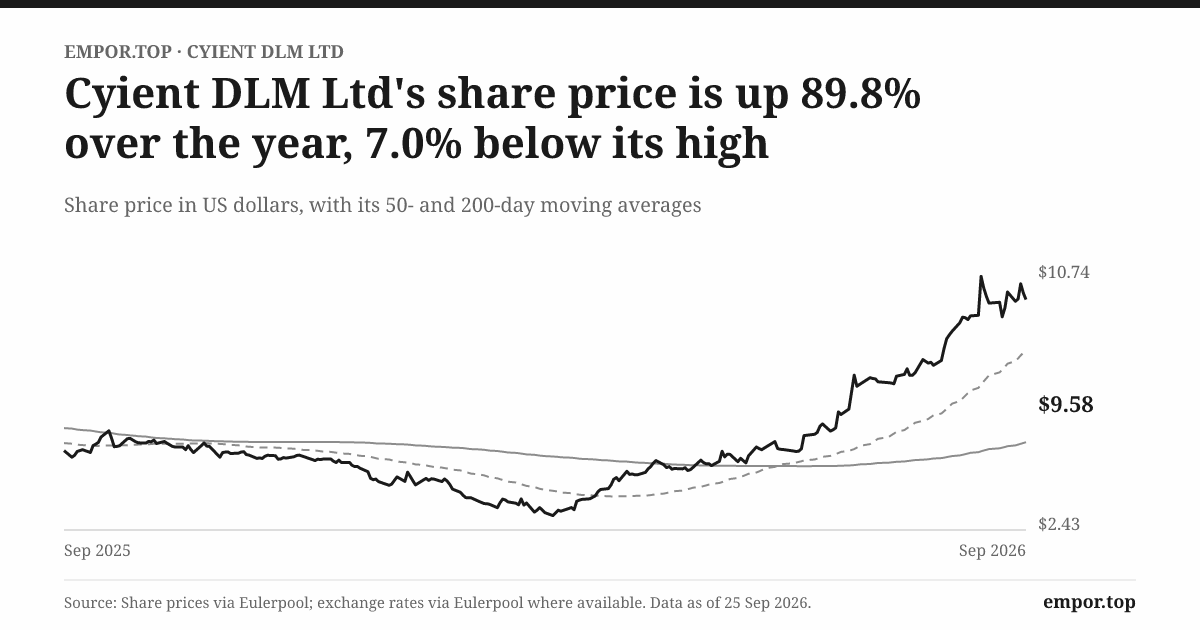
On March 30, 2026, a stock that had listed on India's exchanges less than three years earlier at a 52% premium sank to ₹264.95, dipping just below the ₹265 issue price at which initial public offering investors had entered.12 That drop erased every rupee of listing-day euphoria. Revenue for the fiscal year was heading toward a 17% drop, the largest customer program in company history had wound down, and the chief executive who led the public listing had departed ten months prior.34
Six months later, on September 25, 2026, the stock closed near ₹931, pricing Cyient DLM at a market capitalization of roughly ₹7,390 crore, or approximately $880 million.5 Operational fundamentals across the manufacturing footprint in Mysuru, Hyderabad, Bengaluru, and Torrington, Connecticut had not altered overnight. Instead, market sentiment shifted toward a renewed growth narrative: a record order backlog, four consecutive quarters of double-digit EBITDA margins, and an executive roadmap pledging to evolve a pure-play contract manufacturer into an owner of proprietary products and intellectual property.67
This round trip—from market darling to discounted orphan and back to a premium multiple—frames Cyient DLM's operating reality. The company has repeatedly been valued on what it might become rather than on its present commercial baseline. The purpose of this analysis is to evaluate both dimensions.
The High-Reliability Paradox
The baseline begins with the physical products. Cyient DLM manufactures printed circuit board assemblies, wire harnesses, full-system "box builds," and precision-machined components.8 Unlike mass-market consumer electronics manufacturing, where millions of uniform smartphones run off high-speed assembly lines, Cyient DLM produces tens, hundreds, or low thousands of specialized units across intricate configurations for cockpit avionics, defence platforms, medical equipment, and industrial automation.
Manufacturing professionals describe this operating profile as high-mix, low-volume. A practical comparison is between a fast-food franchise and a compounding pharmacy. The fast-food kitchen scales on standardized throughput and minimal cost per unit. The compounding pharmacy prepares customized prescriptions in tightly controlled batches, where a single quality failure carries catastrophic consequences. Commercial pricing, operational margins, and client retention stem directly from this operational discipline. In aerospace, suppliers must secure rigorous certifications, including AS9100D and Nadcap, before delivering a single flight-certified component; once certified, switching vendors requires complete customer re-qualification.96 That barrier insulates relationships, yet it also enforces protracted onboarding schedules, capital-intensive inventory cycles, and substantial revenue concentration among a small roster of primary clients.
The Core Thesis Under Examination
The corporate identity itself articulates a strategic thesis: "Design-Led Manufacturing." The core proposition is that the business can migrate upward from build-to-print manufacturing, where clients supply technical blueprints for exact physical execution, to build-to-specification contracts, where clients outline functional parameters and Cyient DLM engineers the underlying product architecture. The eventual destination is proprietary product and platform ownership. Management outlined this progression during the Q1 FY27 earnings call in July 2026 through three operational phases: Strengthen, Expand, and Transform. The framework targets EBITDA margin bands of 9–11% in the near term, 11–13% across FY27–29, and 13–18% from FY30 onward as build-to-specification programs and platform rights scale.76
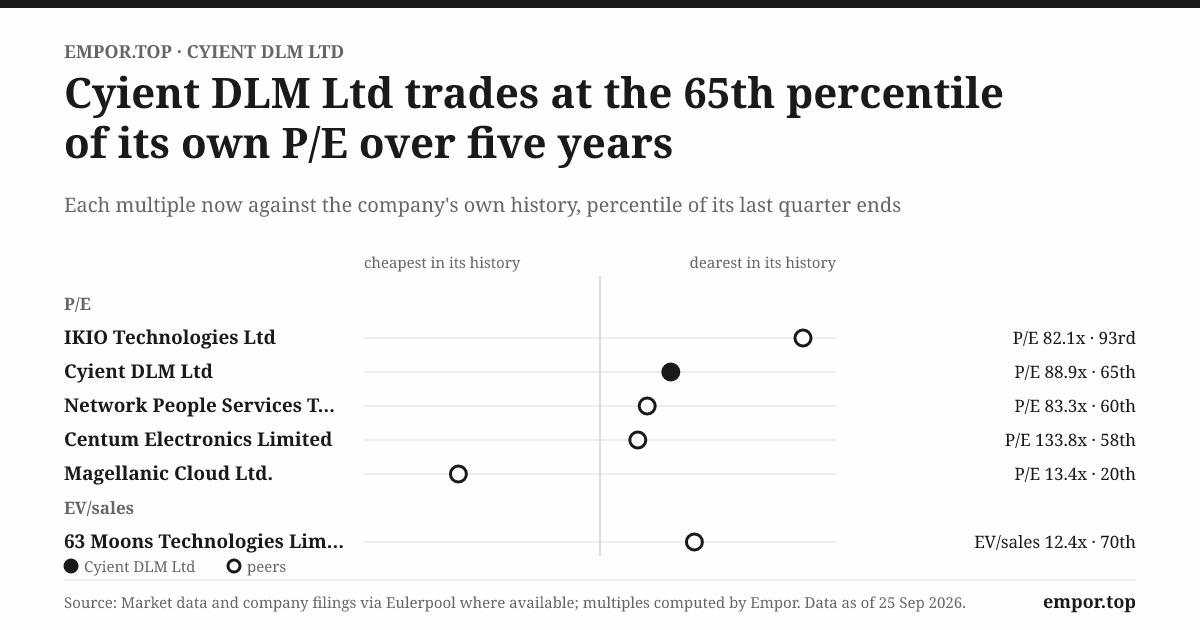
The capital allocation question remains straightforward: does the commercial track record justify a valuation multiple near 88 times trailing earnings,5 or is Cyient DLM primarily a certified contract manufacturer operating with severe customer concentration alongside an early-stage design practice? The disclosed data indicates that the current business remains predominantly contract manufacturing, with the higher-margin design business operating as an emerging commercial option that has only recently begun contributing to revenue.
Myth Versus Reality
Three prevailing market assumptions require calibration against the operating disclosures.
First is the perception that Cyient DLM operates primarily as a domestic defence enterprise driven by India's indigenization policies. In reality, domestic business generated only 6% of revenue in Q1 FY27, with defence representing 9% of the mix; revenue remains heavily tilted toward export demand from international aerospace, industrial, and healthcare clients.6 The domestic defence expansion was real, but it was driven by a single large program that has concluded.
Second is the assumption that an expanding order book guarantees linear quarterly growth. The operating record shows that a record order backlog coincided with a 17% revenue decline in FY26, illustrating that backlog converts to revenue on client delivery schedules rather than manufacturer target dates.310
Third is the premise that "Design-Led Manufacturing" reflects the current revenue mix. As Section VI demonstrates, design-linked revenue commenced only in FY26 and accounted for a single-digit percentage of total revenue that year.11 Divergences between strategic framing and actual revenue delivery explain much of the stock's historical volatility.
The Snapshot
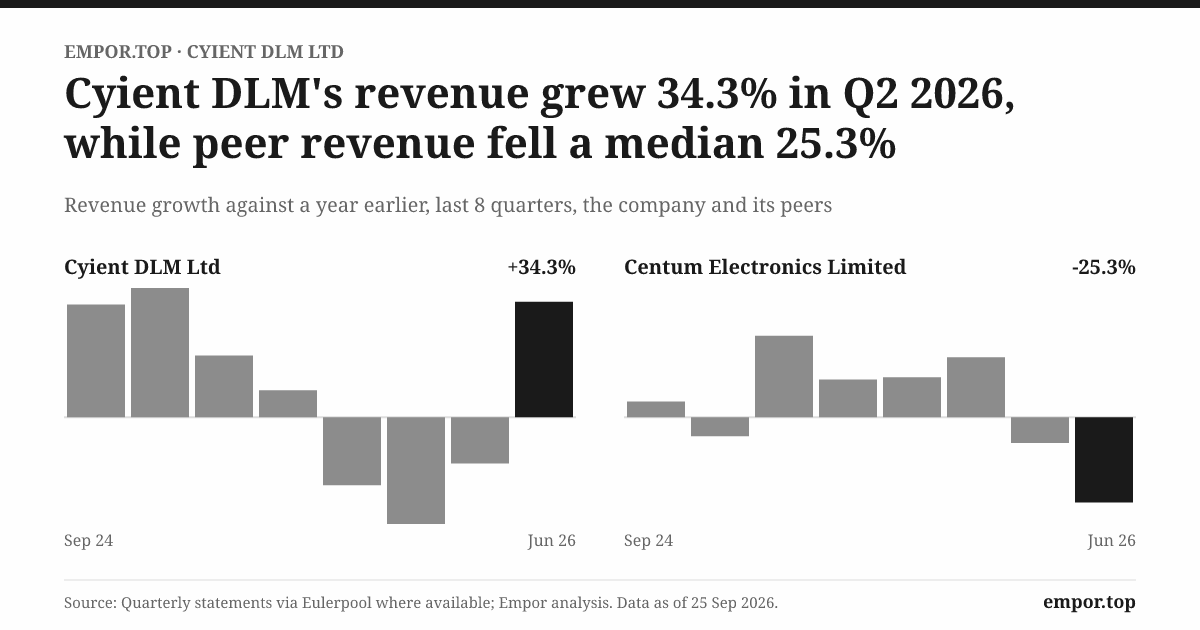
As of late September 2026, Cyient DLM trades on the NSE under the ticker CYIENTDLM and on the BSE under the security code 543933.12 Revenue performance has mirrored program delivery cycles: sales expanded 43.2% to ₹1,192 crore in FY24 and another 27.5% to ₹1,520 crore in FY25, before contracting 17% to ₹1,262 crore in FY26 following the conclusion of the anchor defence contract.13143 Normalized EBITDA margins stood at 10.3% in FY26 and 10.5% in Q1 FY27, as quarterly revenue rebounded 34.3% year on year to ₹374 crore.36
The company's order backlog reached ₹2,599 crore at the end of June 2026, its highest reported total since listing, supported by a quarterly book-to-bill ratio of 1.5 times.6 That visibility carries an important operational nuance: management defines the backlog strictly as confirmed purchase orders in hand rather than estimated lifetime contract values, making it a firm but near-term delivery indicator.10
The story unfolds across seven stages: the Mysuru incense-manufacturing origins; the buyout by parent company Cyient; the 2023 initial public offering; the underlying unit economics; the United States acquisition of Altek; an empirical review of core management claims; and an evaluation of competitive dynamics alongside bull and bear cases. The journey starts, unexpectedly, with agarbathi.
 Subscribe on LinkedIn
II. The Rangsons Genesis: The Incense Scion’s Electronic Gamble (1993–2015)
In the old industrial quarters of Mysuru, the air still carries traces of sandalwood. This is the city where N. Ranga Rao established a small trading venture in 1948—a business that evolved into N. Ranga Rao & Sons and, under the family's second generation, grew into what the family describes as the world's largest manufacturer of incense sticks under the Cycle brand.15 For most family enterprises, that commercial scale would have defined the firm's ambition.
Pavan Ranga, an engineer by training who later completed an MBA, chose a different path. On June 30, 1993, Rangsons Electronics was incorporated to build electronics in a country that barely had an electronics supply chain.1615 India's economy had opened to market reforms only two years earlier. Key components had to be imported, customs clearances were slow, and the global electronics manufacturing services sector was concentrating across East Asia around high-volume players assembling consumer hardware by the millions.
Choosing the Hard Path
A Mysuru start-up could not out-scale manufacturing hubs in Taiwan or southern China on commodity circuit boards. Rangsons deliberately targeted the corner of the market where scale matters least and reliability matters most: complex, low-volume assemblies for industrial, medical, and defence customers. By 2007, the company operated four facilities across Bengaluru and Mysuru alongside a procurement office in China, and it claimed a compound annual growth rate of 65% over the preceding five years.17
That expansion caught the attention of Larsen & Toubro. In 2007, L&T Capital, an investment arm of the Indian engineering conglomerate, bought a stake in Rangsons for approximately ₹100 crore.17 An L&T operations executive observed at the time that Rangsons had a "great opportunity" to become "a global end-to-end solutions provider in EMS."17 Coming from one of India's prominent engineering and defence groups, the transaction signalled that a family-run Mysuru electronics shop could be trusted with mission-critical assemblies.
The physical reality of the factory floor illustrates why that qualification mattered. A bare circuit board arrives etched with copper pathways. Automated screen printers deposit solder paste onto microscopic contact pads, pick-and-place robots position hundreds of components onto the paste, and the assembly travels through a reflow oven that fuses the solder into permanent electromechanical joints. This surface-mount technology forms the core of modern electronics assembly. On a commercial smartphone line, an identical board configuration runs continuously in the millions. For a defence radio, a production run might total only a few hundred boards, each accompanied by detailed inspection records and lot traceability back to the batch of every semiconductor used. The assembly machines are similar; the operating discipline and documentation around them are not.
The Structural Ceiling
By the mid-2010s, Rangsons had established an operational footprint qualified with global original equipment manufacturers (OEMs) across defence, aerospace, medical, automotive, telecommunications, and industrial markets.18 Yet the business confronted the structural barrier that frequently constrains promoter-led electronics manufacturing services providers: working capital. In high-reliability manufacturing, the assembler routinely procures components—often long-lead, military-grade integrated circuits—months before it can integrate, deliver, and invoice the final product. Faster growth locked up increasing amounts of cash in inventory and trade receivables. Furthermore, Rangsons lacked an internal design-engineering team, leaving global OEMs to utilize the facility primarily as a build-to-print shop.
This tension established a recurring pattern in the company's operating history. Regulatory certifications and customer audit qualifications create a defensible barrier against new entrants, but they do not automatically confer pricing power, nor do they reduce the cash intensity of component procurement. A family enterprise with a certified quality management system but a finite balance sheet required a corporate parent with deeper capital reserves and front-end engineering talent. That parent operated roughly 500 kilometres north, in Hyderabad.
III. The Cyient Takeover & The S3 Strategy (2015–2022)
B.V.R. Mohan Reddy had built his enterprise on digital blueprints. An engineer trained at IIT Kanpur and the University of Michigan, he founded Infotech Enterprises in Hyderabad in 1991 to sell engineering services to global customers.19 Over two decades, the company—rebranded as Cyient in 2014—developed into a prominent outsourced engineering partner for aerospace, rail, and utilities clients. It could design an avionics enclosure on a computer screen, but it possessed no facilities to build the physical hardware.
That operational boundary carried direct strategic implications. Pure engineering services are billed by the hour, whereas manufacturing earns recurring revenue on every unit shipped across the multi-year lifecycle of a program. For an engineering services provider serving global aerospace prime contractors, acquiring a certified production facility offered the prospect of an integrated design-to-delivery capability alongside stickier client retention.
The Deal Mechanics
On January 2, 2015, Cyient announced a definitive agreement to acquire 74% of Rangsons Electronics in an all-cash deal, with Managing Director Krishna Bodanapu stating that the company "fits extremely well in Cyient's business."18 Business Standard reported the consideration at about ₹290 crore.20 The transaction completed on February 4, 2015.16
The remaining 26% stake followed four years later. In January 2019, Cyient agreed to buy the outstanding equity from the sellers for ₹42.5 crore, "in line with the terms of the Share Purchase Agreement entered into... in January 2015."21 Comparing the two transactions reveals a sharp divergence: the initial 74% stake implied an equity valuation of roughly ₹392 crore for the entire company, whereas the final 26% buyout implied a total valuation of only about ₹163 crore. Because the specific contractual terms governing the second tranche were not publicly detailed, that gap likely reflected pre-agreed formulaic pricing rather than a collapse in underlying value. Either way, Cyient assembled full ownership for a combined outlay of roughly ₹332 crore—a modest cost compared with the valuation public investors would later assign to the business.
The S3 Blueprint
Cyient framed the acquisition around what it called its S3 strategy: services, systems, and solutions.18 The electronics business was renamed Cyient DLM on January 18, 2017.16 In February 2018, a scheme of amalgamation folded in Techno Tools Precision Engineering, a wholly owned subsidiary, adding precision machining to the electronics capabilities.16 To expand capacity beyond Mysuru and Bengaluru, construction began on a new manufacturing facility in the Hyderabad special economic zone in 2019, and operations started there in 2020.16
The Hyderabad plant sits in the GMR Aerospace and Industrial Park near the city's airport, the address that serves as Cyient DLM's registered office.12 Proximity to an aerospace cluster carries tangible operational value: aerospace customers audit suppliers in person, and high-reliability components benefit from compressed logistics chains and direct airport access.
Honeywell and the Anthem Signal
The most significant customer validation of this era arrived in July 2022, when Cyient announced a multi-year deal with Honeywell to manufacture Honeywell Anthem, which the partners called aviation's first cloud-connected cockpit system.22 Cyient's role centered on "turnkey manufacture and testing" of the line-replaceable units that make up the avionics suite.22 Cyient DLM later described it as "a substantial multi-million-dollar contract."16 By the time of the initial public offering, Honeywell, Thales, ABB, and Bharat Electronics Limited (BEL) were established anchor customers, with an average relationship length of more than 11 years.8
In aviation, a "line-replaceable unit" is essentially a modular, sealed electronics enclosure—such as a display processor or communication unit—designed so that technicians can unplug and replace it directly on the tarmac without taking the aircraft apart. Building and testing those modular boxes is precisely the low-volume, high-scrutiny assembly work that suits Cyient DLM's manufacturing discipline. Yet the Anthem program also highlights an essential timing dynamic in aerospace manufacturing: lead times are measured in years. Although the Anthem partnership was announced in July 2022, management stated in July 2026 that initial production builds for the Honeywell work won years earlier were only then ramping.227 A marquee contract signed in 2022 was, four years later, still an early-stage production story.
Financially, the Cyient era was defined by steady scaling and expanding profitability. Revenue rose from ₹457 crore in FY20 to ₹832 crore in FY23, and EBITDA margins expanded from about 3% to about 11% as higher manufacturing volumes absorbed fixed plant overhead.8 That operational progress required patient capital. The FY20 baseline had been an unprofitable year, meaning the business required more than five years under Cyient's ownership before generating double-digit margins. The period also briefly showcased medical technology, with Cyient DLM's pandemic-era diagnostic equipment manufacturing winning a NASSCOM social-impact award in 2021.16
By 2022, Cyient DLM had grown large enough—and structurally different enough from its parent—that housing a capital-intensive manufacturing enterprise within an asset-light engineering services firm created operational and financial friction. The next transition was financial rather than operational.
IV. The IPO & The Balance Sheet De-Risking (2022–2023)
Consider two fundamentally divergent businesses sharing a single balance sheet. One sells billable engineering hours, carries negligible inventory, and generates mid-teens operating margins. The other procures millions of rupees in electronic components months in advance, navigates protracted customer qualification cycles before booking revenue, and yields high single-digit margins. Consolidated together, the manufacturing arm diluted the parent company's return on capital, while the parent's consolidated multiple obscured the standalone value of the hardware franchise. Separation offered a clean structural resolution.
Montalbano Arrives
On November 24, 2022, Cyient announced the appointment of Anthony Montalbano as chief executive officer of Cyient DLM and Ram Dornala as chief operating officer.23 Montalbano brought more than 30 years of leadership experience across engineering and electronics manufacturing services.23 His background included senior operational roles at Flex, one of the world's largest contract manufacturers, along with subsequent leadership positions at Aricent and Wipro's engineering services business.23 For an enterprise preparing for an initial public offering, installing an executive with global contract-manufacturing credentials served as a clear signal of operational maturity to institutional investors and multinational aerospace clients alike. Managing Director Krishna Bodanapu framed the leadership appointments around Cyient DLM's "unique positioning in the market for complex, low-volume electronics manufacturing."23
The June 2023 Offering
The initial public offering opened on June 27, 2023, and closed on June 30, 2023, establishing a price band of ₹250 to ₹265 per share for a ₹592 crore fresh issue of equity.2 Investor demand was heavy across categories: the offering was subscribed 67.31 times overall, driven by 90.44 times in the qualified institutional buyer category and 49.22 times among retail investors.2 On July 10, 2023, the shares debuted at ₹403 on the National Stock Exchange, delivering a 52% premium over the issue price.2425
At the upper band of ₹265, the public issue valued the company at an equity capitalization of approximately ₹2,100 crore, or roughly 66 times its FY23 earnings.8 Rich multiples were standard across India's high-reliability electronics peers; Kaynes Technology was trading around 92 times trailing earnings during the same period.8 Public markets were pricing an expansive growth narrative—centered on Indian electronics indigenization, defence procurement mandates, and China-plus-one supply-chain shifts—rather than established historical profitability.
The transaction structure also carried an important strategic distinction: it contained no offer for sale. In many Indian corporate carve-outs, the parent company or private-equity sponsors monetize their holdings by selling secondary shares, leaving the operating company with no fresh funds. Here, Cyient accepted equity dilution rather than cashing out, ensuring that every rupee raised went directly onto the operating company's balance sheet to fund working-capital requirements. This structure addressed the chronic cash constraints of high-reliability manufacturing, while leaving the corporate parent with a substantial equity holding that could be monetized once public-market liquidity developed—a dynamic that became relevant fourteen months after listing.
Where the Money Went
Accounting for a pre-IPO placement, the company raised gross proceeds of roughly ₹663 crore.1426 The prospectus earmarked ₹291 crore for working capital, ₹161 crore for debt repayment, ₹98 crore for general corporate purposes, ₹70 crore for acquisitions, and ₹44 crore for capital expenditure.14 Management retired the outstanding debt ahead of schedule, prompting credit rating agency ICRA to observe that working capital borrowings dropped to nil in FY24.26 Relieved of heavy interest expenses, finance costs fell, allowing net profit margin to expand from approximately 3.8% in FY23 to 5.1% in FY24 as net profit grew 92.9% to ₹61.2 crore.813
The capital expenditure line revealed a telling divergence between planned capacity additions and operational reality. By March 2025, the company had spent just 6.7% of its original capex allocation.14 In January 2026, management sought shareholder approval to reallocate ₹36.85 crore from capex to working capital, reducing the planned capex outlay from ₹43.57 crore to ₹6.72 crore; shareholders approved the resolution on March 9, 2026, with 99.997% of votes cast in favour.27 The company cited shifting tariff developments, international supply-chain realignment, and heightened working-capital requirements as the rationale for the change.27 While this adjustment was conducted transparently through regular corporate governance channels, it highlighted a fundamental operational principle: in high-reliability electronics manufacturing, growth absorbs cash through component inventories far more rapidly than it requires new physical floor space.
The Scorecard on the IPO
On the balance sheet, the primary objective was met: leverage fell sharply, and ICRA's March 2026 rating of AA- (Stable) cited the fortified post-IPO net-worth base.26 The public valuation story, however, proved considerably more turbulent. The stock traded up to close at ₹788.50 on the eve of the parent company's August 2024 block sale,28 dropped below its ₹265 issue price by March 2026,1 and then rebounded to more than three times that trough by late September 2026.5 That extreme volatility is diagnostic: equity markets have struggled to establish an anchor valuation for Cyient DLM because its financial results remain dominated by a handful of large programs whose revenue conversion is inherently lumpy. To understand how that operational reality plays out in the numbers, the analysis turns next to the unit economics across each manufacturing segment.
V. Segment Anatomy & Operating Economics: Where the Profits Actually Flow
Inside a Cyient DLM facility, the operational diversity is visible on the shop floor. One surface-mount assembly line places components onto circuit cards for a commercial cockpit display; an adjacent cell routes wire harnesses for an industrial motor drive; another completes mechanical integration on a sealed enclosure for a medical diagnostic device. Each batch demands its own assembly documentation, dedicated test fixtures, and quality sign-offs. Yet while physical product configurations rotate continuously, the client roster remains concentrated—an asymmetry that governs the company's underlying unit economics.
The Mix Has Already Transformed Once
As recently as FY25, aerospace and defence together accounted for "close to 70%" of company revenue, according to management commentary on the Q2 FY26 earnings call.29 By Q1 FY27, that distribution had altered significantly: aerospace contributed 42% of revenue, industrial expanded to 32%, MedTech represented 16%, defence fell to 9%, and automotive and other lines generated roughly 1%.6 The geographic profile shifted in tandem. India accounted for 29% of revenue in Q4 FY25, predominantly from defence contracts; by Q1 FY27, domestic sales dropped to 6%, with international markets generating the remaining 94%.146
Much of this realignment stemmed not from a deliberate portfolio rebalancing, but from the mathematical conclusion of a single anchor program. Defence revenue fell 88% year on year in Q3 FY26 and 68% in Q4 FY26, contractions the company attributed to the completion of a major contract in FY25.123 On a July 2024 earnings call, Chairman Krishna Bodanapu noted that for much of the manufacturing work Cyient DLM executed for Bharat Electronics Limited, "the ultimate customer is the Indian Navy."30 When that naval program concluded, consolidated revenue contracted, India's share dropped, and the corporate sales mix tilted toward export accounts and industrial customers as an arithmetic certainty.
Aerospace: The Economic Engine
Aerospace forms the primary foundation of Cyient DLM's commercial identity. The client list spans Honeywell, Thales, and—according to the company's FY25 investor presentation—Boeing contracts for a battery diode module and precision-machined components, along with a cabin management system partnership with Deutsche Aircraft.14 In November 2024, Honeywell selected Cyient DLM to manufacture its Micro Vapor Cycle System, an aircraft cooling technology, under a program projected to run for 16 years.31 Yet during the Q1 FY27 earnings call, executive Velagapudi noted that Honeywell awards won "several years back" were only then entering initial production builds, with volume ramp-up projected across the following 18 months.7
That extended runway illustrates both the strategic appeal and the operational friction of aerospace manufacturing. Programs reliably generate revenue for a decade or more, but they require years of qualification before reaching full production scale. On the same call, a senior executive described aerospace as "a double-edged sword. It's very, very difficult to get into. But once you are in you're in."7 The executive contrasted that structural stability with data-centre manufacturing, observing that "it is up now. It will go down that's just how some of these technology-related businesses work."7 It was a candid assessment from an executive team simultaneously presenting artificial intelligence infrastructure as an emerging growth avenue.
Industrial: The Unexpected Second Pillar
The industrial segment historically operated in the background of aerospace and defence. In October 2024, then-CEO Anthony Montalbano told analysts that an incoming industrial client could develop into "a top three or four" account the following year and potentially "a top one or two" client thereafter.32 While company disclosures have not identified whether that specific customer achieved those volume targets, the broader segment expanded rapidly: industrial revenue increased 90% year on year in Q1 FY27, reaching nearly a third of total corporate sales.6 New client additions in FY26 included a semiconductor-equipment manufacturer that initiated series production in Q4 FY26, alongside an automotive component line that secured its IATF quality audit and began commercial shipments.3
Industrial contracts typically feature shorter qualification cycles and faster conversion from purchase orders to shipments than aerospace programs, which reduces working-capital lockup. Conversely, the segment is directly exposed to broader corporate capital expenditure cycles, with semiconductor equipment manufacturing subject to sharp cyclical swings.
MedTech: Real, but Mostly Bought
The expansion in medical technology was largely inorganic. Following the consolidation of United States-based Altek in Q4 FY25, MedTech revenue rose 296% year on year, while industrial sales grew 84%, "inclusive of Altek."14 That initial surge quickly stabilized; by Q1 FY27, MedTech revenue growth was flat year on year.6 While the segment requires rigorous compliance under standards such as ISO 13485, which Cyient DLM maintains,9 public disclosures provide little evidence to date that organic medical manufacturing is expanding rapidly enough to shift the company's overall profile.
What Is Actually Being Built
Beyond industry verticals, product categories offer a secondary perspective on manufacturing complexity. Printed circuit board assemblies remained the largest revenue contributor at 48% of sales in Q1 FY27, but full-system box builds—integrated units enclosing circuit boards, complex cabling, and precision-machined housings—grew 85% year on year to become the second-largest product class.6 Box builds previously contributed 31% of revenue in Q3 FY26, compared with 21% a year earlier.12
This shift carries operational importance because a complete box build captures a larger share of the client's end product. While an individual circuit board is an intermediate component, a box build represents an integrated subsystem requiring greater assembly labour, functional testing, and mechanical integration per unit. Expanding the proportion of box builds offers tangible evidence of the company moving up the manufacturing value chain, even within build-to-print contracts. While less margin-accretive than proprietary design or build-to-specification intellectual property, it represents practical value capture that is already visible in reported revenue.
What the Mix Shift Did to Margins
The most revealing operational trends appear not in segment breakdowns, but in the underlying cost structure. In FY25, raw materials consumed 73% of revenue; by FY26, that ratio had dropped to 60%.143 This divergence demonstrates that the anchor defence program inflating FY25 revenue consisted largely of low-margin, pass-through component procurement with limited domestic value addition. Executive leadership acknowledged this dynamic in July 2024, noting that "one part of our business is at a lower margin."30 When that program ended, full-year revenue dropped 17%, but normalized EBITDA fell only 10.3%, allowing normalized operating margins to improve to 10.3%.3
For investors assessing corporate quality, the FY25 revenue peak overstated the company's durable commercial baseline, while the FY26 margin improvement reflected the elimination of low-margin pass-through volume rather than an expansion of core pricing power. The clearer test of operating quality is whether operating margins can remain above 10% as top-line revenue re-accelerates. The Q1 FY27 margin of 10.5% during a 34% revenue rebound provided an initial positive indicator.6 A single quarter, however, does not establish an enduring trend, bringing the analysis directly to the management assertions that warrant empirical scrutiny.
VI. Historical Falsification Layer: Testing the Thesis Claims
Every growth company presents an investor deck, and every deck relies on strategic assertions. The analytical discipline is to take the four claims most central to Cyient DLM's premium valuation and evaluate each against the company's operating record, in its own words, across the longest available historical horizon.
Claim 1: "Cyient DLM Is a Design-Led Manufacturer"
The corporate identity has emphasized design-led manufacturing since January 2017.16 Front-end engineering capability was central to the 2023 initial public offering pitch, when the company categorized its manufacturing solutions into build-to-print assembly and build-to-specification design.25 By July 2024, the chief financial officer highlighted an "increased share of B2S business" as a primary structural lever for future margin expansion.30
Yet commercial filings reveal that build-to-specification programs began contributing to revenue only in FY26. In July 2025, executive Velagapudi stated that FY26 build-to-specification volume would represent "probably 5% of the revenue."33 In January 2026, incoming Chief Financial Officer R.M. Subramanian estimated the contribution at "about 6% to 7% in the current year," with double-digit share anticipated in FY27.11 In October 2025, management disclosed that build-to-specification contracts accounted for "more than 10% of the order book."29 When analysts inquired in April 2026 regarding four new defence anchor clients on build-to-specification programs, Velagapudi confirmed that series production would commence toward the close of FY27 and scale in FY28.10
Two operational nuances further qualify this progression. First, during Q1 FY27, raw material costs increased partly due to "procurement related to B2S," demonstrating that the design segment remains in an upfront investment phase rather than generating immediate margin accretion.7 Second, build-to-specification billing generates contract assets, which management characterized in April 2026 as "unbilled revenue... more from the B2S thing."10 While booking revenue ahead of customer invoicing complies with standard percentage-of-completion accounting for engineering milestones, it represents an accrual-heavy balance-sheet entry that investors must monitor closely as design contracts expand.
The verdict: the historical operating record contradicts the strong version of the claim. For nine years following the 2017 corporate rebranding, Cyient DLM operated, in revenue terms, almost exclusively as a build-to-print contract manufacturer. A narrower reality survives: the company has established an authentic, early-stage design practice, supported by a dedicated engineering facility that expanded from 6,000 to 15,000 square feet in Q1 FY27,6 alongside an engineering development pipeline that includes Japanese electric aircraft developer SkyDrive, whose vehicles are 12 to 18 months from production.7 The validating milestone will be build-to-specification revenue achieving double-digit share in FY27, as pledged. A shortfall would indicate that "design-led" positioning remains primarily an aspirational marketing label.
Claim 2: "Long-Term Relationships Make Revenue Predictable"
Customer longevity is well established: anchor accounts had partnered with the business for more than 11 years on average by 2023.8 Client concentration is equally pronounced. On the Q4 FY25 earnings call, leadership acknowledged that its top five customers generated "roughly 80% of our business and that will continue even next year."34 Credit rating agency ICRA estimated that the top five clients contributed approximately 75% to 80% of revenue,26 while CRISIL cited 68% in September 2025.35 The variance reflects differing reporting dates and measurement bases, but every evaluation depicts an operating model where a handful of procurement officers dictate annual financial performance.
Management's forward guidance illustrates how customer concentration disrupts top-line visibility. In July 2024, leadership stated it was "confident of a 30% CAGR over a three-year period."30 By January 2025, then-CEO Anthony Montalbano tempered expectations, clarifying that "it's not meant to be a firm 30% year-on-year guide."36 By April 2025, executive leadership declined to provide annual guidance altogether, noting that "one deal can quickly change everything."34 The reported outcome: revenue rose from ₹832 crore in FY23 to ₹1,262 crore in FY26, translating to a three-year compound annual growth rate of roughly 15%—approximately half the initial projection.83
The verdict: the claim fails empirical scrutiny as originally framed. Enduring client relationships provide account stickiness and switching barriers, not delivery schedule predictability. What remains defensible is a more modest proposition: the firm purchase backlog provides approximately twelve months of operational visibility, and management's current operational commitment is year-on-year revenue expansion across each quarter of FY27.10 Sustaining that growth profile across four consecutive quarters serves as the immediate test of whether multi-year revenue lumpiness has been tempered.
Claim 3: "The Parent Will Always Protect the Minority"
Cyient Ltd has historically provided meaningful financial backing to its manufacturing arm. ICRA highlighted a "demonstrated track record of funding support from the parent," including inter-corporate loans and corporate debt guarantees.26 Yet on August 21, 2024, the parent entity sold approximately 1.15 crore shares—a 14.5% equity stake—via a block sale at a floor price of ₹748.65, representing a 5% discount to the preceding market close and raising roughly ₹861 crore.28 The transaction lowered Cyient's stake from 66.66% to 52.16%, with capital directed toward the parent's independent corporate priorities, including its semiconductor venture, strategic investments, and parent-level debt retirement.2837
One month later, CRISIL adjusted Cyient DLM's credit rating from AA (CE)/Stable to A+/Positive following the formal removal of the parent company guarantee.35 While neither corporate action directly compromised minority shareholders, together they demonstrated that the parent treats its DLM holding as both an operational asset and a flexible source of balance-sheet liquidity. With Cyient's stake recorded at 52.12% as of December 2025, any subsequent block sale of scale would dilute its ownership below majority control.26
The verdict: the claim holds only in qualified form. The corporate parent has functioned as a supportive yet pragmatically self-interested owner. The primary governance metric to track is any future change in promoter shareholding; a secondary placement reducing parent ownership below 50% would provide a definitive signal regarding how Cyient leadership values strategic control against independent capital requirements.
Claim 4: "Operating Leverage Will Lift Margins Steadily"
Financial performance over four fiscal cycles demonstrates margin stability rather than linear expansion. EBITDA margins stood at approximately 11% in FY23, 9.3% in FY24, 9.0% as reported in FY25, and 10.3% on a normalized basis in FY26.813143 In FY26, personnel expenses expanded 21.8% even as total revenue contracted 17%, driven by front-loaded investments in international sales coverage, build-to-specification design teams, and United States operational overhead.3
Working capital trends demonstrate similar volatility. Net working capital cycles compressed to 79 days at the close of FY24, running ahead of management's targeted operating benchmark of 100 days.1430 A single quarter later, that metric jumped to 171 days. Net working capital registered at 127 days at the end of FY25, 145 days at the conclusion of FY26, and 161 days in Q1 FY27.146 Measuring on a broader balance-sheet basis, CRISIL calculated gross current assets, net of cash, at 236 days as of March 2025.35 Management attributed the FY26 inventory accumulation to advance procurement of long-lead electronic components and manufacturing ramp-ups on incoming programs.10
The verdict: the claim remains unproven by disclosed performance. Operating margins have remained contained within a 9% to 11% corridor across four fiscal years—matching the baseline parameters management's own roadmap designates for the initial "Strengthen" phase.6 The year-end working-capital efficiency achieved in FY24 proved to be an isolated balance-sheet snapshot rather than a permanent operational standard. The operational test is whether EBITDA margins can sustainably break into the targeted 11% to 13% band across FY27 to FY29 without driving further working capital absorption. Those operational disciplines were put to the test in the sole major deployment of corporate acquisition capital: the cross-border purchase of Altek.
VII. The Cross-Border M&A Expansion: Benchmarking Altek Electronics
Torrington is a small industrial city in Connecticut's Litchfield County, far removed from Mysuru in geography and operating environment. Altek Electronics, established there in 1972, operates an 80,000-square-foot plant manufacturing circuit boards and box builds for medical, industrial, and defence customers.3839 Its most commercially critical asset, however, is a regulatory credential rather than a machine: Altek is ITAR-registered, qualifying the facility to manufacture defence articles controlled under the United States International Traffic in Arms Regulations.9
The Deal Points
Cyient DLM's board approved the acquisition on October 3, 2024, through its wholly owned subsidiary Cyient DLM Inc., and announced the transaction the following day.3938 The agreement established an upfront purchase price of $23.4 million on a cash-free, debt-free basis, along with a performance-linked earnout of up to $5.8 million, setting the maximum transaction value at $29.2 million.38 Altek generated $37.2 million in revenue during calendar 2023.38 That top line implied a valuation multiple of roughly 0.63 times sales at the upfront price and 0.78 times at the maximum earnout. Because Altek's operating earnings were not disclosed, an EBITDA multiple cannot be independently verified. To finance the purchase, Cyient DLM fully deployed the ₹70 crore acquisition reserve earmarked from its initial public offering proceeds.14
On the surface, the valuation appeared modest. Acquiring a certified United States contract manufacturer at less than one times sales, at a time when Indian electronics manufacturing services providers traded at steep earnings multiples, resembled classic cross-border valuation arbitrage. Chairman Krishna Bodanapu characterized the acquisition as "a pivotal moment" that expanded the company's global operating footprint.39 Altek subsequently contributed approximately ₹175 crore in revenue during the roughly six months it was consolidated in FY25.35
The Strategic Geometry
The commercial premise rested on a dual-shore manufacturing model: routing final assembly and ITAR-controlled defence work to Connecticut while directing labour-intensive sub-assemblies to production lines in India. In April 2025, as United States import tariffs emerged as an operational concern, management framed Altek as a strategic buffer to "avoid tariffs by leveraging our existing facility for onshore production and final assembly."14 The company's FY25 strategy deck explicitly designated "North America defense and ITAR work" as a primary commercial target.14
The regulatory framework of ITAR—the International Traffic in Arms Regulations—explains why that onshore footprint mattered. The United States government classifies many military electronics components as controlled defense articles. Manufacturers handling those components or technical data must register with the State Department and restrict access to qualified domestic personnel. An offshore facility in Mysuru or Hyderabad, regardless of quality certifications, cannot legally bid on or access those controlled technical packages without protracted government clearances. Acquiring Altek functioned like purchasing an operational asset with a pre-existing regulatory passport: obtaining that clearance organically would have taken years, whereas the underlying plant is standard contract manufacturing. The commercial payoff, however, depends entirely on winning controlled American defence programs—and Cyient DLM has not publicly disclosed any contract wins directly attributable to Altek's ITAR status.
The Record So Far
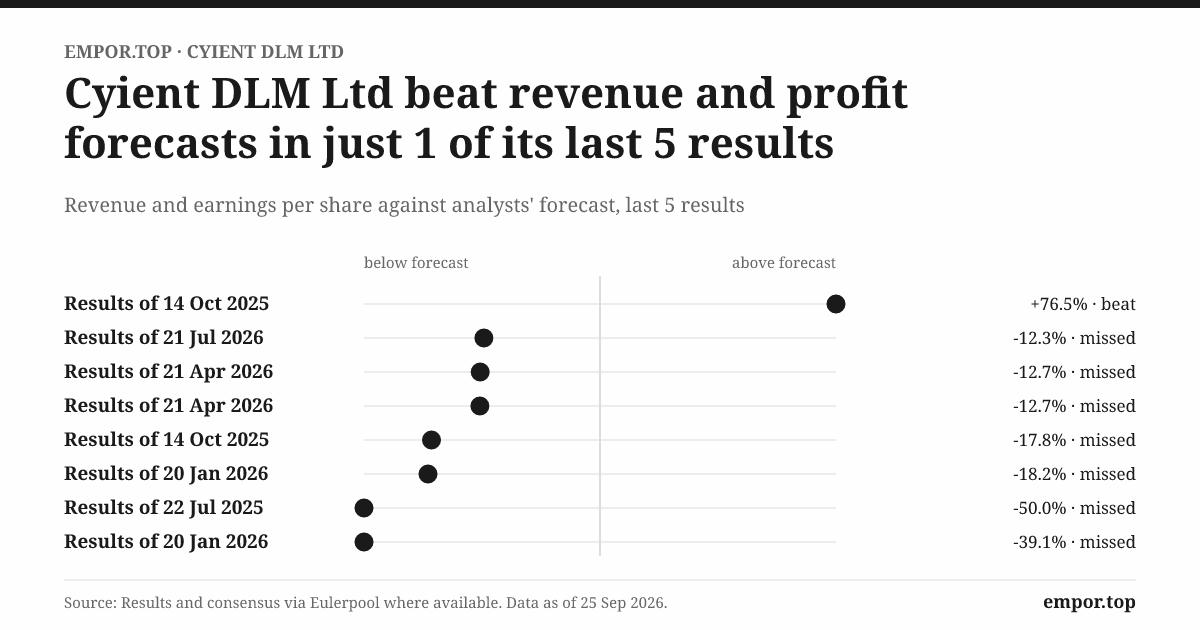
Operational friction surfaced in Q2 FY26. The chief financial officer explained that the contingent earnout was "tied" to "certain performance conditions" and that because "those performance conditions have not been met," Cyient DLM reversed ₹195.7 million of the earnout provision, booking the sum as other income.293 He maintained that "the acquisition is intact, the company is doing well."29 Yet the reversal introduced a notable accounting distortion: while reported profit after tax rose 7.6% in FY26, normalized profit after tax fell 24% once the earnout credit was excluded.3 Investors focusing solely on headline net profit would have overlooked an underlying operational contraction.
By April 2026, executive disclosures pointed to broader integration headwinds. The chief financial officer acknowledged that United States operating margins are structurally lower than domestic Indian margins, that the tariff "overhang still continues," and that cross-border customer synergies were exhibiting "a little bit of slowness," having "just started on a trial basis."10 During the call, an analyst challenged leadership directly, observing that the "Altek acquisition didn't go according to plan... because you reverse the earnouts."10 Executive Velagapudi responded by highlighting early cross-selling progress, citing the first synergy purchase order from an existing Cyient DLM India client placed with Altek alongside Altek's faster book-to-ship cycle, in which roughly half of incoming orders convert into shipments within the same fiscal year.10
Transaction overhead created further financial drag. The Altek acquisition incurred ₹8 crore in one-time deal expenses in Q3 FY25, and in Q3 FY26 the company wrote off ₹17.75 million on an unconsummated transaction described in disclosures as "the deal that did not go through."1412 Despite those headwinds, management continues to list "M&A: Europe Defense" as an active corporate goal.3
The empirical record shows that while Altek was acquired at an undemanding entry multiple and provided a valuable ITAR-registered American facility, it has so far failed to meet its own performance earnout targets, diluted consolidated margins, and produced cross-border manufacturing synergies that remain in an early trial phase. For public-market investors, the transaction serves as a cautionary benchmark: an attractive entry multiple does not demonstrate value creation until operational integration flows through to cash earnings. Acquisition execution and operational integration ultimately depend on leadership stability—and Cyient DLM experienced an executive transition at the top in the very midst of this integration.
VIII. Leadership Transition, Governance & Auditor Deep-Dive
The resignation letter was brief. On May 8, 2025, Anthony Montalbano stepped down as chief executive officer of Cyient DLM for "personal reasons," after roughly two and a half years in the role.4 The company stated that no other material reasons applied, and Managing Director Rajendra Velagapudi assumed responsibility for overall operations with immediate effect.4 The executive who had steered the company through its initial public offering, orchestrated the Altek acquisition, and publicly introduced the 30% growth target departed before any of those strategic initiatives had fully matured.
The Insider-Operator
Velagapudi is an operational insider rather than a dealmaker. He began his career in 1987 at Ford's truck division and worked at Bajaj Tempo and Bharat Earth Movers on powertrain design for commercial and off-highway equipment.40 He holds a master's degree in automobile engineering from the Madras Institute of Technology and a master's in design from Cranfield University in the United Kingdom.40 Having joined Cyient in 1999, he rose to senior vice president and head of its engineering operations unit before being appointed managing director of Cyient DLM in April 2017.40 He now serves as the company's managing director and CEO.40
On investor calls, his communication style is plain and operational. He addresses questions regarding purchase orders, factory floor execution, and production schedules rather than expansive market narratives, and he has repeatedly declined to provide annual revenue guidance.33107 That consistency provides grounding after the volatile 30% growth projections, even if it leaves public markets with fewer formal targets against which to measure progress. His appointment indicates that the corporate parent views current priorities as factory-level execution: converting the order backlog into billable shipments, winning incremental purchase orders, and keeping working capital in check.
The finance leadership turned over in parallel. Shrinivas Kulkarni, chief financial officer during the 2024 earnings calls, was still presenting in October 2025; by January 2026, R.M. Subramanian had assumed the role and was presenting as CFO.302911 Two executive transitions at the top within a single year are not uncommon for a young listed enterprise, but they signify that the management team currently presenting the Strengthen-Expand-Transform roadmap is not the group that formulated the initial commitments.
Board and Ownership
Krishna Bodanapu, who leads the parent company, serves as chairman of Cyient DLM.6 Credit rating agency ICRA highlighted the "overlap in leadership representation at the board level" as a defining element of the parent linkage.26 As of March 31, 2025, the parent entity held 52.16% of the equity, domestic mutual funds owned 27.48%, resident retail individuals held 14.69%, and foreign portfolio investors held 2.38%.9 The substantial mutual-fund position means domestic institutions, rather than global portfolio managers, act as the decisive swing shareholders.
The parent relationship carries a direct balance-sheet dimension as well. ICRA noted that Cyient Ltd has historically supported the subsidiary through inter-corporate loans and corporate guarantees, expecting leverage metrics to improve partly through the "repayment of the loan extended by the parent."26 While such arrangements are routine within Indian corporate groups, they represent related-party transactions whose commercial pricing and terms warrant ongoing scrutiny in statutory filings. With the parent company's executive chairman also presiding over the Cyient DLM board, independent directors shoulder the responsibility of evaluating whether intra-group arrangements protect minority shareholders as effectively as the controlling promoter.
Auditors and Controls
S.R. Batliboi & Associates LLP, an EY network firm, was reappointed as statutory auditor for a five-year term at the annual general meeting held on June 28, 2024.941 The statutory audit report for FY25 contained no qualifications, reservations, or adverse remarks, and the secretarial audit report was similarly clean.9 KPMG Assurance and Consulting Services serves as co-sourced internal auditor.9
The key audit matters highlighted in the FY25 report outline the core financial friction points of the business: revenue recognition, inventory valuation, and, in the standalone accounts, the valuation of investments, which required testing the cash-flow forecasts supporting asset carrying values.9 These priorities directly reflect the operating realities of high-reliability manufacturing: the timing of revenue milestones under complex percentage-of-completion contracts, the true realizable value of long-lead components stored in warehouses, and whether cross-border acquisitions are carried at defensible balance-sheet valuations. While a clean audit opinion confirms formal regulatory compliance, the specific areas emphasized by auditors pinpoint exactly where an investor's diligence should focus. The next question is how Cyient DLM compares against the domestic and international peers competing for the same high-reliability programs.
IX. Competitive Field & Structural Economics: Porter's 5 Forces & 7 Powers
Imagine a procurement meeting at a European avionics prime contractor. On the table are competing bids from a scaled Indian contract manufacturer expanding into chip packaging, a design-heavy domestic defence electronics specialist, an established American assembly house, and Cyient DLM. The procurement committee's decisive question is not who offers the lowest price per unit, but who can withstand repeated factory audits, maintain zero-defect delivery schedules, and support an aerospace program across a fifteen-year lifecycle. That operational calculus defines the competitive field.
The Peer Group
Kaynes Technology represents the scale benchmark among domestic peers. In FY26, it reported revenue of ₹3,626 crore, up 33.2%, with an EBITDA margin of 15.8% and an order book exceeding ₹8,000 crore.42 Operating at nearly three times Cyient DLM's revenue scale and generating operating margins roughly five percentage points higher, Kaynes has directed substantial capital toward semiconductor packaging and printed circuit board fabrication. That divergence illustrates that high-mix, low-volume electronics manufacturing does not inherently restrict operating margins to the 10% threshold.
Data Patterns demonstrates the financial value of proprietary design ownership. The company reported FY26 revenue of ₹925 crore and an EBITDA margin of roughly 40%, supported by an order book of ₹2,062 crore.43 Although its order backlog is smaller than Cyient DLM's ₹2,599 crore total, its operating margin is nearly four times higher because it designs, engineers, and retains intellectual property on the radar and electronic warfare platforms it supplies to Indian defence agencies. That comparison establishes the theoretical ceiling of what Cyient DLM's build-to-specification ambitions could deliver—and demonstrates how far the current commercial model remains from that operational profile.
Syrma SGS, Centum Electronics, and Avalon Technologies complete the listed domestic peer group, with respective portfolio exposures to consumer and automotive electronics, space and defence microelectronics, and North American box-build integration. On the global stage, multinational contract manufacturers such as Jabil, Sanmina, and Flex dwarf every Indian peer in component procurement scale and global purchasing power.
What Customers Say With Their Awards
Customer procurement actions provide clear evidence of operational standing. In FY25, Cyient DLM received one of only three supplier awards presented globally by Honeywell that year, special recognition from BAE Systems, and an award for a strategic avionics manufacturing program from Thales.14 In Q3 FY26, an aerospace client presented the company with a risk-mitigation award for sustaining delivery reliability on an intricate circuit board program.12 These accolades confirm that global aerospace primes view the company's factory floors as dependable production environments.
Industry awards, however, do not confer pricing power. Cyient DLM's operating margins remained confined within the 9% to 11% corridor throughout the period in which it accumulated these honours.36 In high-reliability electronics manufacturing, that dynamic reflects the foundational commercial compact: original equipment manufacturers reward rigorous quality compliance and on-time delivery with program renewals and incremental unit volumes, but they rarely concede price increases. The supplier secures customer retention, while the client retains pricing leverage.
Hamilton Helmer's 7 Powers
Applying Hamilton Helmer's strategic framework reveals a distinct structural asymmetry in Cyient DLM's market position.
Switching costs represent the company's primary economic moat. Once an electronic assembly is certified inside a commercial flight-control computer or engine management unit, migrating production to a rival contract manufacturer requires costly component re-qualification, updated regulatory documentation, and fresh customer audits. Management's observation during the Q1 FY27 earnings call that "once you are in you're in" captures this dynamic directly.7 Yet while switching barriers defend existing programs against vendor displacement, they confer security over production volume rather than pricing leverage.
Process power is moderate. Quality credentials such as Nadcap accreditation for circuit card assemblies and cable harnesses, AS9100D aerospace certification, ISO 13485 for medical systems, and ITAR registration in the United States represent years of accumulated institutional discipline that a new entrant cannot rapidly duplicate.9 Nevertheless, established international and domestic competitors maintain comparable quality accreditations, making these standards a baseline requirement for bidding rather than an exclusive operational advantage.
Cornered resource remains negligible. Under build-to-print contracts, all intellectual property, product designs, and functional architectures remain the exclusive property of original equipment manufacturers such as Honeywell or Thales. The only durable assets are the customer relationships themselves and, prospectively, proprietary product architectures developed under early-stage build-to-specification contracts.
Counter-positioning, scale economies, network effects, and brand are essentially absent. Cyient DLM executes a standard contract-manufacturing playbook without a structural business-model advantage that established incumbents cannot adopt. Furthermore, its component purchasing volumes remain smaller than domestic peers such as Kaynes and a fraction of global electronics manufacturing leaders.
Porter's Five Forces
Michael Porter's industry forces framework clarifies why operating margins remain tightly bounded across fiscal cycles.
Buyer power is exceptionally high. With the top five clients generating approximately 75% to 80% of corporate revenue, customer procurement teams dictate delivery schedules, payment terms, and component inventory lead times.26 Credit rating agency ICRA noted that Cyient DLM successfully negotiates pass-through arrangements for component cost fluctuations "despite the significantly larger scale of its customers," which mitigates raw-material inflation, but the underlying scale asymmetry remains the dominant structural reality.26
Supplier power is moderate to high. Raw materials consumed 60% to 73% of revenue in recent fiscal years, and industry-wide electronic component shortages disrupted delivery timetables during FY26.31410 Cyient DLM carries limited procurement leverage against global semiconductor fabricators, leaving production schedules vulnerable to component allocation cycles.
Threat of new entrants is low in high-reliability aerospace and defence manufacturing, where plant-level audits, traceability systems, and regulatory certifications require multi-year investments before booking commercial shipments.
Threat of substitutes is negligible, as mission-critical hardware assemblies and ruggedized electronic subsystems cannot be replaced by commercial-grade components or purely software-driven solutions.
Competitive rivalry is bifurcated: competition is intense during initial qualification and bidding for new platform awards, but muted once a program enters series production and manufacturing fixtures are deployed on the shop floor.
The structural synthesis is that high-reliability electronics manufacturing protects incumbent vendors while constraining operating margins. Cyient DLM's primary competitive advantage is that its production cells are already integrated inside long-lifecycle aerospace platforms; its strategic constraint is that contract manufacturing offers limited leverage to lift margins beyond the single-digit to low-teens corridor. To examine how executive leadership articulates these operating dynamics and how public-market analysts test management's assertions, the analysis turns next to the transcripts of the quarterly earnings calls.
X. Earnings Transcripts & Conference Call Forensic Record
Quarterly conference calls are where an executive narrative collides with market skepticism in real time. Examining two years of Cyient DLM earnings transcripts reveals a leadership team that turned progressively cautious as initial projections slipped, countered by sell-side analysts whose questioning grew increasingly pointed.
The Working Capital Victory Lap (FY24 to Q1 FY25)
At the close of FY24, Cyient DLM reported net working capital of 79 days and trade receivables of just 57 days—an operational benchmark that seemed to validate management's post-IPO discipline.14 Leadership had established an operating target of 100 days.30 Yet only three months later, in Q1 FY25, net working capital spiked to 171 days. When an analyst asked on the July 2024 call whether the 100-day target remained achievable, the chief financial officer stood firm: "We maintain that guidance," pledging "substantial improvement in Q2."30 In practice, net working capital has failed to return to that 100-day threshold in any quarter since.146
The same call revealed factory capacity utilization of roughly 55%, providing immediate operational context for why the fresh capital expenditure budgeted during the initial public offering was left largely unspent.30
The Revenue Hole (Q2 and Q3 FY25)
By October 2024, analysts turned their attention from balance-sheet cycle times to incoming order volume, pressing executives on why new order inflows had lagged for eight or nine consecutive quarters and asking whether client concentration—with the top ten customers generating 80% to 85% of revenue—was stalling growth.32 Then-CEO Anthony Montalbano reframed the issue around customer value rather than physical throughput, arguing that Cyient DLM might provide "a $10 million solution" that clients valued like "a $100 million type of solution," asserting that "this business is not as price sensitive."32 While highlighting high switching costs, the response sidestepped the core question regarding stalled pipeline expansion.
Three months later, during the Q3 FY25 call in January 2025, that revenue shortfall became undeniable. When asked whether the three-year 30% compound annual growth target remained intact, Montalbano walked back the commitment, conceding that "there definitely could be some lag on years" and clarifying that the target was "not meant to be a firm 30% year-on-year guide."36 The same quarter absorbed the transaction overhead from the Altek acquisition, further depressing reported results.14
The Reset Year (FY26)
In July 2025, after the anchor Bharat Electronics program tied to the Indian Navy concluded, analysts pressed for visibility on replacement orders. Managing Director Rajendra Velagapudi offered no near-term relief, admitting that "we don't have any clear indication of the repeat order, when it is going to happen."33 By October 2025, Chairman Krishna Bodanapu sought to reassure investors, stating that the BEL order pipeline had been "completely refreshed with a much better margin revenue."29 While defence revenue rebounded 35% year on year in Q1 FY27, it remained far below its FY25 peak.6
The most contentious exchange arrived in April 2026. Pointing out that rival domestic manufacturers were expanding their order books by 35% to 40%, an analyst challenged management directly: "Is there a structural issue why we are not able to grow?"10 Velagapudi insisted that "there is no structural challenges," attributing sluggish order momentum to having only recently onboarded a dedicated international sales team.10 The explanation identified an operational bottleneck, but asked investors to rely on forward execution rather than demonstrated delivery.
The October 2025 call also illustrated how leadership reframed the wind-down of its primary customer contract. In prepared remarks, management described a sales distribution where aerospace, industrial, and medical equipment had supplanted the previous defence-dominated baseline as "a much healthier portfolio and a mix that we are comfortable with."29 While accurately summarizing the resulting mix, the realignment was not the execution of a pre-planned diversification strategy; it was the arithmetic byproduct of the naval contract rolling off. Concluding the session, Bodanapu acknowledged that operating margins had "barely passed 10" percent that quarter before reaffirming future expansion, noting that certain build-to-specification programs "run into 20 years."29 Yet multi-decade program lifecycles represent a mixed blessing: while they provide generational baseline visibility, they also ensure that initial revenue ramps arrive slowly and dilute across extended schedules.
The January 2026 transcript uncovered a parallel disclosure pattern regarding high-margin design work. Only under persistent analyst questioning during the Q&A session did incoming CFO R.M. Subramanian reveal that build-to-specification contracts would contribute only 6% to 7% of FY26 revenue, a baseline figure omitted from management's prepared slides.11 When the defining metric of a corporate turnaround emerges only through analyst cross-examination, investors are forced to treat standard investor presentations with heightened scrutiny.
The Roadmap Call (Q1 FY27)
By July 2026, the executive narrative had pivoted back toward long-term expansion. Management outlined an addressable global electronics manufacturing services market reaching $1.1 trillion by 2033, highlighted prospective entry into robotics and artificial intelligence data centres, and reaffirmed a target operating margin corridor of 13% to 18% by FY30.7 Yet when analysts pressed for concrete revenue milestones supporting those emerging categories, executives demurred, stating that granular projections remained internal operational targets.7
The sequence across eight quarters of earnings calls highlights an enduring dynamic. In prepared remarks, leadership routinely champions expanding total order backlogs, technical certifications, and multi-year secular tailwinds. In the Q&A sessions, sell-side analysts consistently circle back to three unresolved operational friction points: client concentration, working-capital absorption, and protracted program conversion timelines. Over time, executive leadership has grown noticeably more cautious about issuing explicit numerical guidance. While that reticence shields management from missed quarterly forecasts, it also leaves public markets with fewer objective yardsticks to measure operational accountability—the very vulnerabilities that define the core investment risks.
XI. The Core Risk Radar: What Can Break the Machine
Customer concentration and program roll-off. Customer concentration represents an operational hazard that has already materialized on the income statement. When the anchor naval contract executed for Bharat Electronics concluded, full-year revenue dropped 17% in FY26.3 Today, that customer exposure has shifted primarily toward Honeywell and Thales, accounts that management projected would expand at an "extraordinary" pace in FY27.7 In high-reliability aerospace manufacturing, any schedule postponement on a Honeywell production ramp, a build-rate reduction by airframe manufacturers such as Boeing or Airbus, or an unexpected platform phase-out would strike the top line immediately.
Parent monetization. With Cyient Ltd holding a 52.12% equity interest as of late 2025, the parent entity has minimal headroom to monetize additional shares without relinquishing outright majority control.26 The August 2024 block sale demonstrated that the parent treats its subsidiary holding as a flexible source of capital when funding needs arise.28 A subsequent secondary placement of scale would decisively alter corporate governance by bringing parent ownership below the 50% threshold.
Altek and M&A execution. Cross-border acquisition risks have already surfaced in operating disclosures: the forfeited performance earnout, structurally compressed American margins, and slow commercial cross-selling between India and Connecticut are established facts on the corporate ledger.10 Management's stated pursuit of an additional acquisition in European defence would test executive integration bandwidth once more.3 Furthermore, credit rating agency ICRA has explicitly highlighted larger-than-anticipated, debt-funded acquisitions as a primary trigger for negative credit rating action.26
Supply chain and geopolitics. In FY26, regional conflict in West Asia disrupted shipping timetables and delayed material shipments, while industry-wide semiconductor and component shortages hindered factory delivery schedules.10 Management's operational response—procuring long-lead components months in advance—safeguards production schedules against assembly-line downtime, but it mechanically inflates inventory buffers and strains working capital. Meanwhile, persistent tariff uncertainty in the United States continues to complicate the commercial logic of Altek's dual-shore assembly model.10 Layered on top of supply-chain friction, foreign-exchange volatility produced a currency loss in Q1 FY27, underscoring the exposure of an export-heavy cost and revenue structure.7
Accounting judgments. Headline earnings figures mask critical accounting interventions. In FY26, the reversal of the Altek performance earnout flowed directly through other income, transforming what was an underlying contraction in normalized net profit into a reported increase.3 Concurrently, early-stage build-to-specification revenue has expanded primarily through unbilled contract assets, booking revenue ahead of customer invoicing.10 Management also regularly reports "normalized" operational metrics that strip out transaction fees and non-recurring charges; while helpful for underlying trend analysis, this practice demands vigilance to ensure exceptional items do not become chronic fixtures of the income statement. While none of these accounting treatments suggests irregularity—and the statutory audit report for FY25 was clean and unqualified—each area represents an accrual junction where management estimates directly influence reported profitability.9
Diversification risk. Expanding into robotics and hardware for artificial intelligence data centres represents a logical adjacency for a high-reliability electronics assembler. Yet an executive's candid observation that data-centre demand "will go down" at some point is an explicit caution against valuing that lane at peak-cycle economics.7 Venturing into rapid-cycle technology markets while concurrently incubating build-to-specification design capabilities and integrating a cross-border American acquisition threatens to overstretch an executive leadership team that has only recently settled into place.
While these structural vulnerabilities are common across contract manufacturing, Cyient DLM's corporate trajectory offers valuable empirical lessons for capital allocators evaluating the high-reliability electronics sector.
XII. The Playbook: Enduring Business & Investing Lessons
Spinoffs reveal value, then reveal reality. Carving out Cyient DLM from its parent company gave public markets an unobstructed view of a standalone electronics manufacturing business. The 2023 initial public offering priced the equity at approximately ₹2,100 crore, unlocking substantial value above Cyient's combined acquisition outlay of roughly ₹332 crore across 2015 to 2019.82021 Yet independent listing and standalone reporting also exposed the operational lumpiness that corporate consolidation had previously masked. An initial public offering does not reshape a commercial model; it merely grants investors an unvarnished look at the business that already exists.
The "design-led" label needs a revenue test. Public equity markets routinely assign premium valuation multiples to proprietary engineering, product platforms, and intellectual property. The fundamental diligence question for investors evaluating design-led positioning is straightforward: what percentage of current revenue actually originates from design contracts rather than execution assembly? At Cyient DLM, that figure remained negligible for nearly a decade following the initial rebranding, and by FY26 it still represented only a single-digit share of total revenue.11
Acquisitions are regulatory keys, not proof of value. Acquiring Altek secured an operating asset that is exceptionally difficult to replicate organically—an ITAR-registered manufacturing facility in the United States—at an entry valuation below one times sales.389 Yet the subsequent reversal of the performance earnout demonstrates that an undemanding acquisition price and sound strategic geometry cannot substitute for operational integration to generate cash earnings.29
In EMS, growth consumes cash. The balance-sheet trajectory—from the temporary working-capital compression in FY24 to the formal reallocation of IPO capital expenditure into working capital, and net working capital climbing back near 160 days in 2026—reinforces a foundational industry reality: in electronics manufacturing services, scaling operations is financed directly through the working-capital cycle.14276 Contract manufacturers that mitigate this cash trap typically rely on structured milestone billing and substantial customer advances. At Cyient DLM, customer advances fell from 81 days in Q1 FY24 to approximately 15 days in Q1 FY27, indicating that clients are funding far less of the working-capital burden than before.146
These operational realities frame the concluding investment debate: looking ahead, what specific execution milestones must materialize to validate the premium valuation multiple, and what structural vulnerabilities could derail the narrative?
XIII. The Bull vs. Bear Case: The Investment Spine
The Bull Case
Aerospace programs are entering their ramp phase. Executive leadership expects manufacturing volumes for Honeywell awards secured years earlier to ramp across the next 18 months, accompanied by sustained expansion from Thales.7 Concurrently, the 16-year Micro Vapor Cycle System contract provides long-duration production visibility.31 As global aerospace primes increasingly direct manufacturing packages to certified Indian suppliers, Cyient DLM's pre-existing audit qualifications position it at the front of the queue.
The order backlog sits at historic highs. With an order book of ₹2,599 crore and a quarterly book-to-bill ratio of 1.5 times, firm purchase orders provide tangible support for management's commitment to deliver year-on-year revenue expansion in every quarter of FY27.610
The revenue mix has stabilized. With the run-off of the low-margin naval defence contract complete, the company has diversified across commercial verticals, maintaining EBITDA margins above 10% for four consecutive quarters.6 Most notably, the industrial segment has expanded to generate roughly a third of corporate revenue.6
Build-to-specification represents an authentic commercial option. If build-to-specification contracts reach a double-digit share of sales in FY27 and the four anchor defence programs transition into series production by FY28, management's margin expansion roadmap gains fundamental credibility.1110
The balance sheet remains fortified. Credit rating agency ICRA maintains an AA- (Stable) rating, supported by ₹309 crore in cash and liquid investments as of December 2025 alongside minimal reliance on working-capital credit lines.26
The Bear Case
Valuation discounts distant execution. Trading at roughly 88 times trailing earnings, the market price reflects substantial execution from the future Expand and Transform phases, despite current operating margins remaining anchored within the initial Strengthen band of 9% to 11%.56
Historical delivery has lagged management targets. The three-year 30% revenue growth projection materialized as an annualized expansion of roughly 15%; the 100-day net working capital target drifted out to approximately 160 days; and the operational performance earnout for the Altek acquisition was ultimately forfeited.303629
Customer concentration remains an acute hazard. The top five clients continue to generate roughly 75% to 80% or more of total revenue, leaving corporate earnings vulnerable to any schedule adjustment or platform phase-out by a single key buyer.2634
Promoter and minority interests are not fully aligned. The parent corporation has already executed a 14.5% secondary block sale to fund parent-level capital needs and formally withdrew its corporate debt guarantee.2835
Domestic peers demonstrate superior unit economics. Kaynes Technology generates operating margins roughly five percentage points higher at nearly three times the revenue scale, while Data Patterns commands roughly 40% operating margins by retaining intellectual property across proprietary platform designs.4243
The Activist's Stress Test
A skeptical institutional investor evaluating the corporate registry would focus on four core operational vulnerabilities.
First, capital allocation discipline: initial public offering proceeds earmarked for manufacturing capital expenditure were largely diverted to working capital, the sole cross-border acquisition failed to meet its contractual earnout milestones, and a prospective secondary transaction was abandoned after incurring formal transaction costs.272912 A disciplined allocator would demand a rigorous return-on-capital framework before supporting management's prospective European defence acquisition.
Second, executive accountability: both the 30% top-line compound growth target and the 100-day working-capital efficiency metric went unfulfilled, while the leadership figures who introduced those commitments have departed, leaving the current management team to establish its own operating credibility from scratch.304
Third, disclosure transparency: statutory presentations routinely omit customer-level revenue concentration figures and regular build-to-specification progress metrics, requiring market participants to extract essential operating baselines through quarterly analyst cross-examinations.11
Fourth, promoter ownership headroom: with the parent company's shareholding hovering near 52%, any subsequent block sale by Cyient Ltd would directly test market demand and introduce the prospect of a controlling promoter relinquishing majority ownership.26
A balanced defense from executive leadership would emphasize the record order book, four consecutive quarters of double-digit operating margins, and an expanded international direct-sales organization.610 While these represent genuine operational achievements, they remain recent developments; the core question of an activist stress test is whether those improvements will endure across a complete industrial cycle.
Weighing the Case
The historical record disproves the most aggressive bull assertions: Cyient DLM is not yet a design-led enterprise, its quarterly revenue remains subject to customer delivery cycles rather than manufacturer timetables, and operating margins have not demonstrated structural expansion beyond baseline levels. Equally, the operating evidence refutes the most dismissive bear critique—that the business is merely an undifferentiated contract assembler. Its entrenched aerospace audit credentials, multi-decade original equipment manufacturer relationships, and low entry multiple on an ITAR-registered American production asset represent durable operational moats that an incoming competitor cannot quickly recreate.
The objective middle ground is a certified, high-reliability contract manufacturer incubating an early-stage design practice, priced by public markets on the assumption that its higher-margin design ambitions will successfully scale. The concluding epilogue outlines the precise operational milestones that would confirm or invalidate that thesis.
XIV. Epilogue & The 3 Forward KPIs to Watch
Thirty-three years ago, an engineer from Mysuru's incense-manufacturing family set out to build circuit boards in an economy with virtually no domestic electronics supply chain. Today, Cyient DLM operates five manufacturing plants across Mysuru, Hyderabad, Bengaluru, and the United States, counting several of the world's prominent aerospace primes among its clients.26 The corporate trajectory has already encompassed a family-owned start-up, a corporate buyout, an oversubscribed initial public offering, a sharp cyclical contraction, and a swift market rebound. The next chapter will be decided by three operating indicators.
1. B2S revenue share. Management has pledged a double-digit revenue contribution in FY27, up from an estimated 6% to 7% in FY26.11 This metric provides the cleanest empirical test of whether "design-led" describes an authentic commercial capability or merely a marketing label.
2. Net working capital days. Management's 100-day operating target established in 2024 remains unachieved, with the metric registering at 161 days in Q1 FY27.306 If revenue growth accelerates while this cycle compresses, the operating model is maturing; if the figure climbs, top-line expansion is being financed directly by balance-sheet cash absorption.
3. Revenue share outside the top five customers. With the five largest accounts generating roughly 75% to 80% of revenue, the volume contributed by the remaining customer base is the decisive measure of whether international sales hiring, new client wins, and vertical diversification are genuinely insulating the enterprise from the risk that a single program's completion can erase a year of growth.26
References
-
Cyient DLM Ltd Slides to All-Time Low Amid Stock-Specific Sell-Off — MarketsMojo, 2026-03-30 ↩↩
-
Cyient DLM Ltd IPO Date, Price Band, Lot Size, Subscription & Allotment Details — m.Stock, 2023 ↩↩↩
-
Investor Presentation Q4 FY26 — Cyient DLM, 2026-04-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cyient DLM CEO Anthony Montalbano resigns; Rajendra Velagapudi to oversee operations — Business Upturn, 2025-05-09 ↩↩↩↩
-
Cyient DLM Ltd Share Price — Mirae Asset Sharekhan, 2026-09-25 ↩↩↩↩
-
Investor Presentation Q1 FY27 — Cyient DLM, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of the Earnings Call Q1 FY27 — Cyient DLM, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cyient DLM Ltd – IPO Note — FundsIndia Equity Research Desk, 2023-06 ↩↩↩↩↩↩↩↩↩↩
-
Cyient DLM Annual Report FY2024-25 — Cyient DLM, 2025 ↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of the Earnings Call Q4 FY26 — Cyient DLM, 2026-04-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of Earnings Call Q3 FY26 — Cyient DLM, 2026-01-20 ↩↩↩↩↩↩↩↩
-
Investor Presentation for the quarter ended 31 December 2025 — Cyient DLM via BSE, 2026-01-20 ↩↩↩↩↩↩↩
-
Cyient DLM Reports Robust Q4 and Annual Results, with 92.9% YoY growth in PAT — Cyient DLM, 2024-04-23 ↩↩↩
-
Investor Presentation Q4 FY25 — Cyient DLM, 2025-04-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Three generations, one successful family business — N. Ranga Rao & Sons ↩↩
-
Cyient DLM History: Our Journey in Advanced Manufacturing — Cyient DLM ↩↩↩↩↩↩↩↩
-
L&T Capital buys stake in Indian EMS provider Rangsons Electronics — VentureOutsource, 2007 ↩↩↩
-
Cyient to acquire majority stake in Rangsons Electronics — Cyient, 2015-01-02 ↩↩↩
-
Cyient Signs Definitive Agreement to Acquire 74% Stake in Rangsons Electronics — Business Standard, 2015-01-02 ↩↩
-
Cyient to acquire remaining 26% stake in EDSM subsidiary — Business Standard (PTI), 2019-01-22 ↩↩
-
Cyient Partners with Honeywell to Manufacture Honeywell Anthem, the First Cloud-Connected Cockpit System — Cyient, 2022-07-18 ↩↩↩
-
Cyient Strengthens Leadership at Cyient DLM to Expand its Manufacturing Business — Cyient, 2022-11-24 ↩↩↩↩
-
Cyient DLM IPO Listing Day Report: Debuts at 52% Premium Over Issue Price — Moneycontrol, 2023-07-10 ↩
-
Cyient DLM shares make a strong D-Street debut; stock lists at 52% premium at Rs 403 — BusinessToday, 2023-07-10 ↩↩
-
Cyient DLM Limited: [ICRA]AA- (Stable); assigned — ICRA, 2026-03-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cyient DLM shareholders approve variation in IPO proceeds utilization through postal ballot — ScanX, 2026-03-09 ↩↩↩↩
-
Block Deal: Cyient offloads 14.5% stake in Cyient DLM — BusinessToday, 2024-08-21 ↩↩↩↩↩
-
Transcript of Earnings Call Q2 FY26 — Cyient DLM, 2025-10-14 ↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of Investor Conference Call Q1 FY25 — Cyient DLM, 2024-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Cyient DLM Wins Long Term Deal with Honeywell Aerospace — Cyient DLM, 2024-11-06 ↩↩
-
Transcript of Investor Conference Call Q2 FY25 — Cyient DLM, 2024-10-21 ↩↩↩
-
Transcript of Investor Conference Call Q1 FY26 — Cyient DLM, 2025-07-22 ↩↩↩
-
Transcript of Investor Conference Call Q4 FY25 — Cyient DLM, 2025-04-22 ↩↩↩
-
Cyient DLM Limited Rating Rationale — CRISIL Ratings, 2025-09-22 ↩↩↩↩↩
-
Transcript of Investor Conference Call Q3 FY25 — Cyient DLM, 2025-01-21 ↩↩
-
Cyient Sells 14.5% Stake in Cyient DLM for Rs 883 Crore via Block Deal — The Economic Times, 2024-08-21 ↩
-
Cyient DLM Expands To US With $29.2M Altek Electronics Acquisition — Electronics For You, 2024-10 ↩↩↩↩↩
-
Cyient DLM acquires Altek Electronics — Cyient DLM, 2024-10-04 ↩↩↩
-
Rajendra Velagapudi, Managing Director & CEO — Cyient DLM ↩↩↩↩
-
Cyient DLM Annual Report FY2023-24 and Notice of AGM — Cyient DLM, 2024 ↩
-
Kaynes Technology Posts 33 Per Cent Revenue Growth In FY26 — Construction World, 2026-05-15 ↩↩
-
Data Patterns (India) Limited FY26 Revenue Surges 31% with Strong Order Growth — InvestyWise, 2026-05-22 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube