Spotify: The Toll Road Built on Someone Else's Land
I. Cold Open & Roadmap
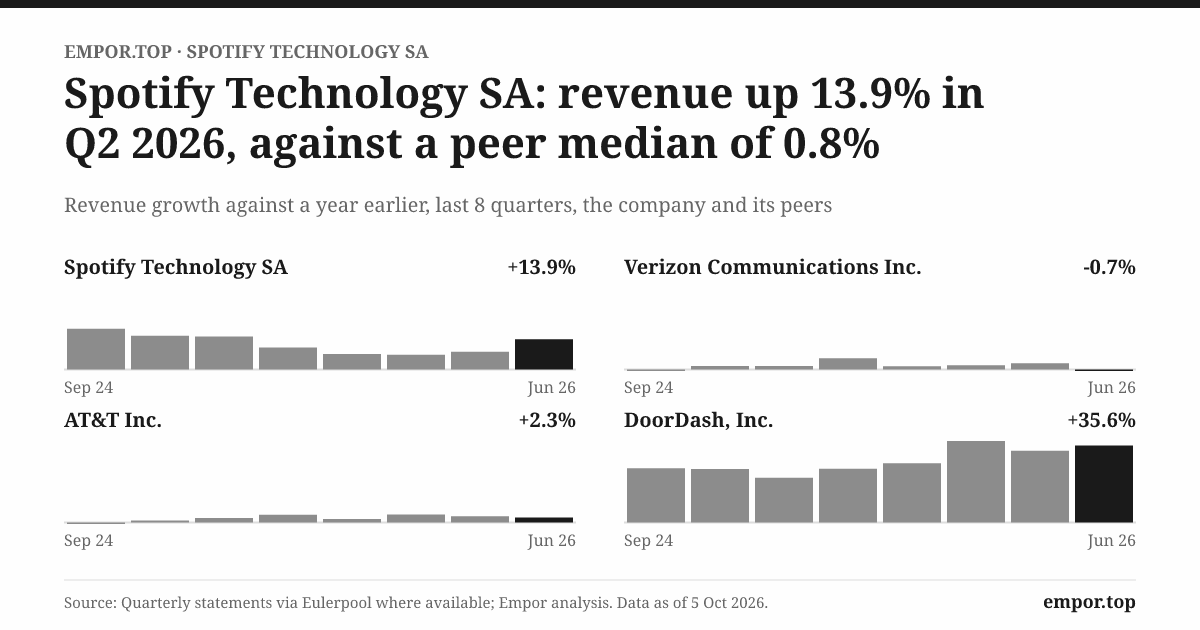
Picture the numbers Spotify put out in the summer of 2026. Three hundred million people paid for the service every month1. Seven hundred and seventy-seven million opened the app at least once a month1. In the three months to June the company booked €4,777m of revenue1, about 14% more than a year earlier1. And the company that served all of those people employed roughly 7,300 full-time staff, almost exactly the headcount it had at the end of 202512.
Now rewind a decade. In 2017 the same company lost about $426m at the operating line on roughly $4.6bn of revenue, an operating margin of about minus 9%3. It had borrowed more than a billion dollars through convertible notes3. It had never earned an annual operating profit. Plenty of smart people believed it never would, because the business model looked like a pipe that carried other people's music and handed most of the money back to them.
By the second quarter of 2026 the operating margin was about 13.7%13. That swing, from roughly minus 9% to plus 14%, is the hook of this story. It is also the trap. Over the eleven years from 2015 to 2025, Spotify's cumulative net profit was still slightly negative, at about minus €495m, while its operating activities threw off about €7.7bn of cash3. The accounting story and the cash story are two very different films about the same company.
So here is the verdict up front, hedged once: Spotify finally makes money, and the money is real, but the largest single cost in the business is still the toll it pays to the record labels and music publishers who own the songs. Two-thirds of every euro of revenue leaves the building before Spotify pays a single engineer1.
The episode runs on four questions. Is the margin expansion structural, or does it lean on price rises and a cost line that moves with the share price? How much of reported earnings is operating profit, and how much is tax and fair-value noise? Can a deliberate shift from user growth to monetisation keep revenue growing in the low teens? And, the question that hangs over everything, who actually captures the value: the founders, the rights holders, the app-store owners, or the shareholders?
The road map runs like this. First, a Swedish entrepreneur's bet that you could beat piracy by building something better than piracy, and the price he paid the labels for permission. Then the 2018 direct listing that went public without banks or new money and kept the founders in control. Then the podcast spending spree that briefly made Spotify an "audio company" and ended in retreat. Then the margin flip of 2023 to 2026. Then the toll collectors: labels, publishers and app stores. Then the founders' handover and the moat audit, the valuation, and the moments that will settle the case.
One tension sits under all of it. About 69% of the shareholder votes sit with two founders14, while the labels effectively set the cost of goods. Shareholders own the economics but control neither the governance nor the supply chain. Every number that follows should be read with that in mind, starting with the deal that created the company in the first place.
 Subscribe on LinkedIn
II. Why a Swede Beat Napster's Orphans (Founding to Launch, 2006–2011)
The pirate-era bet
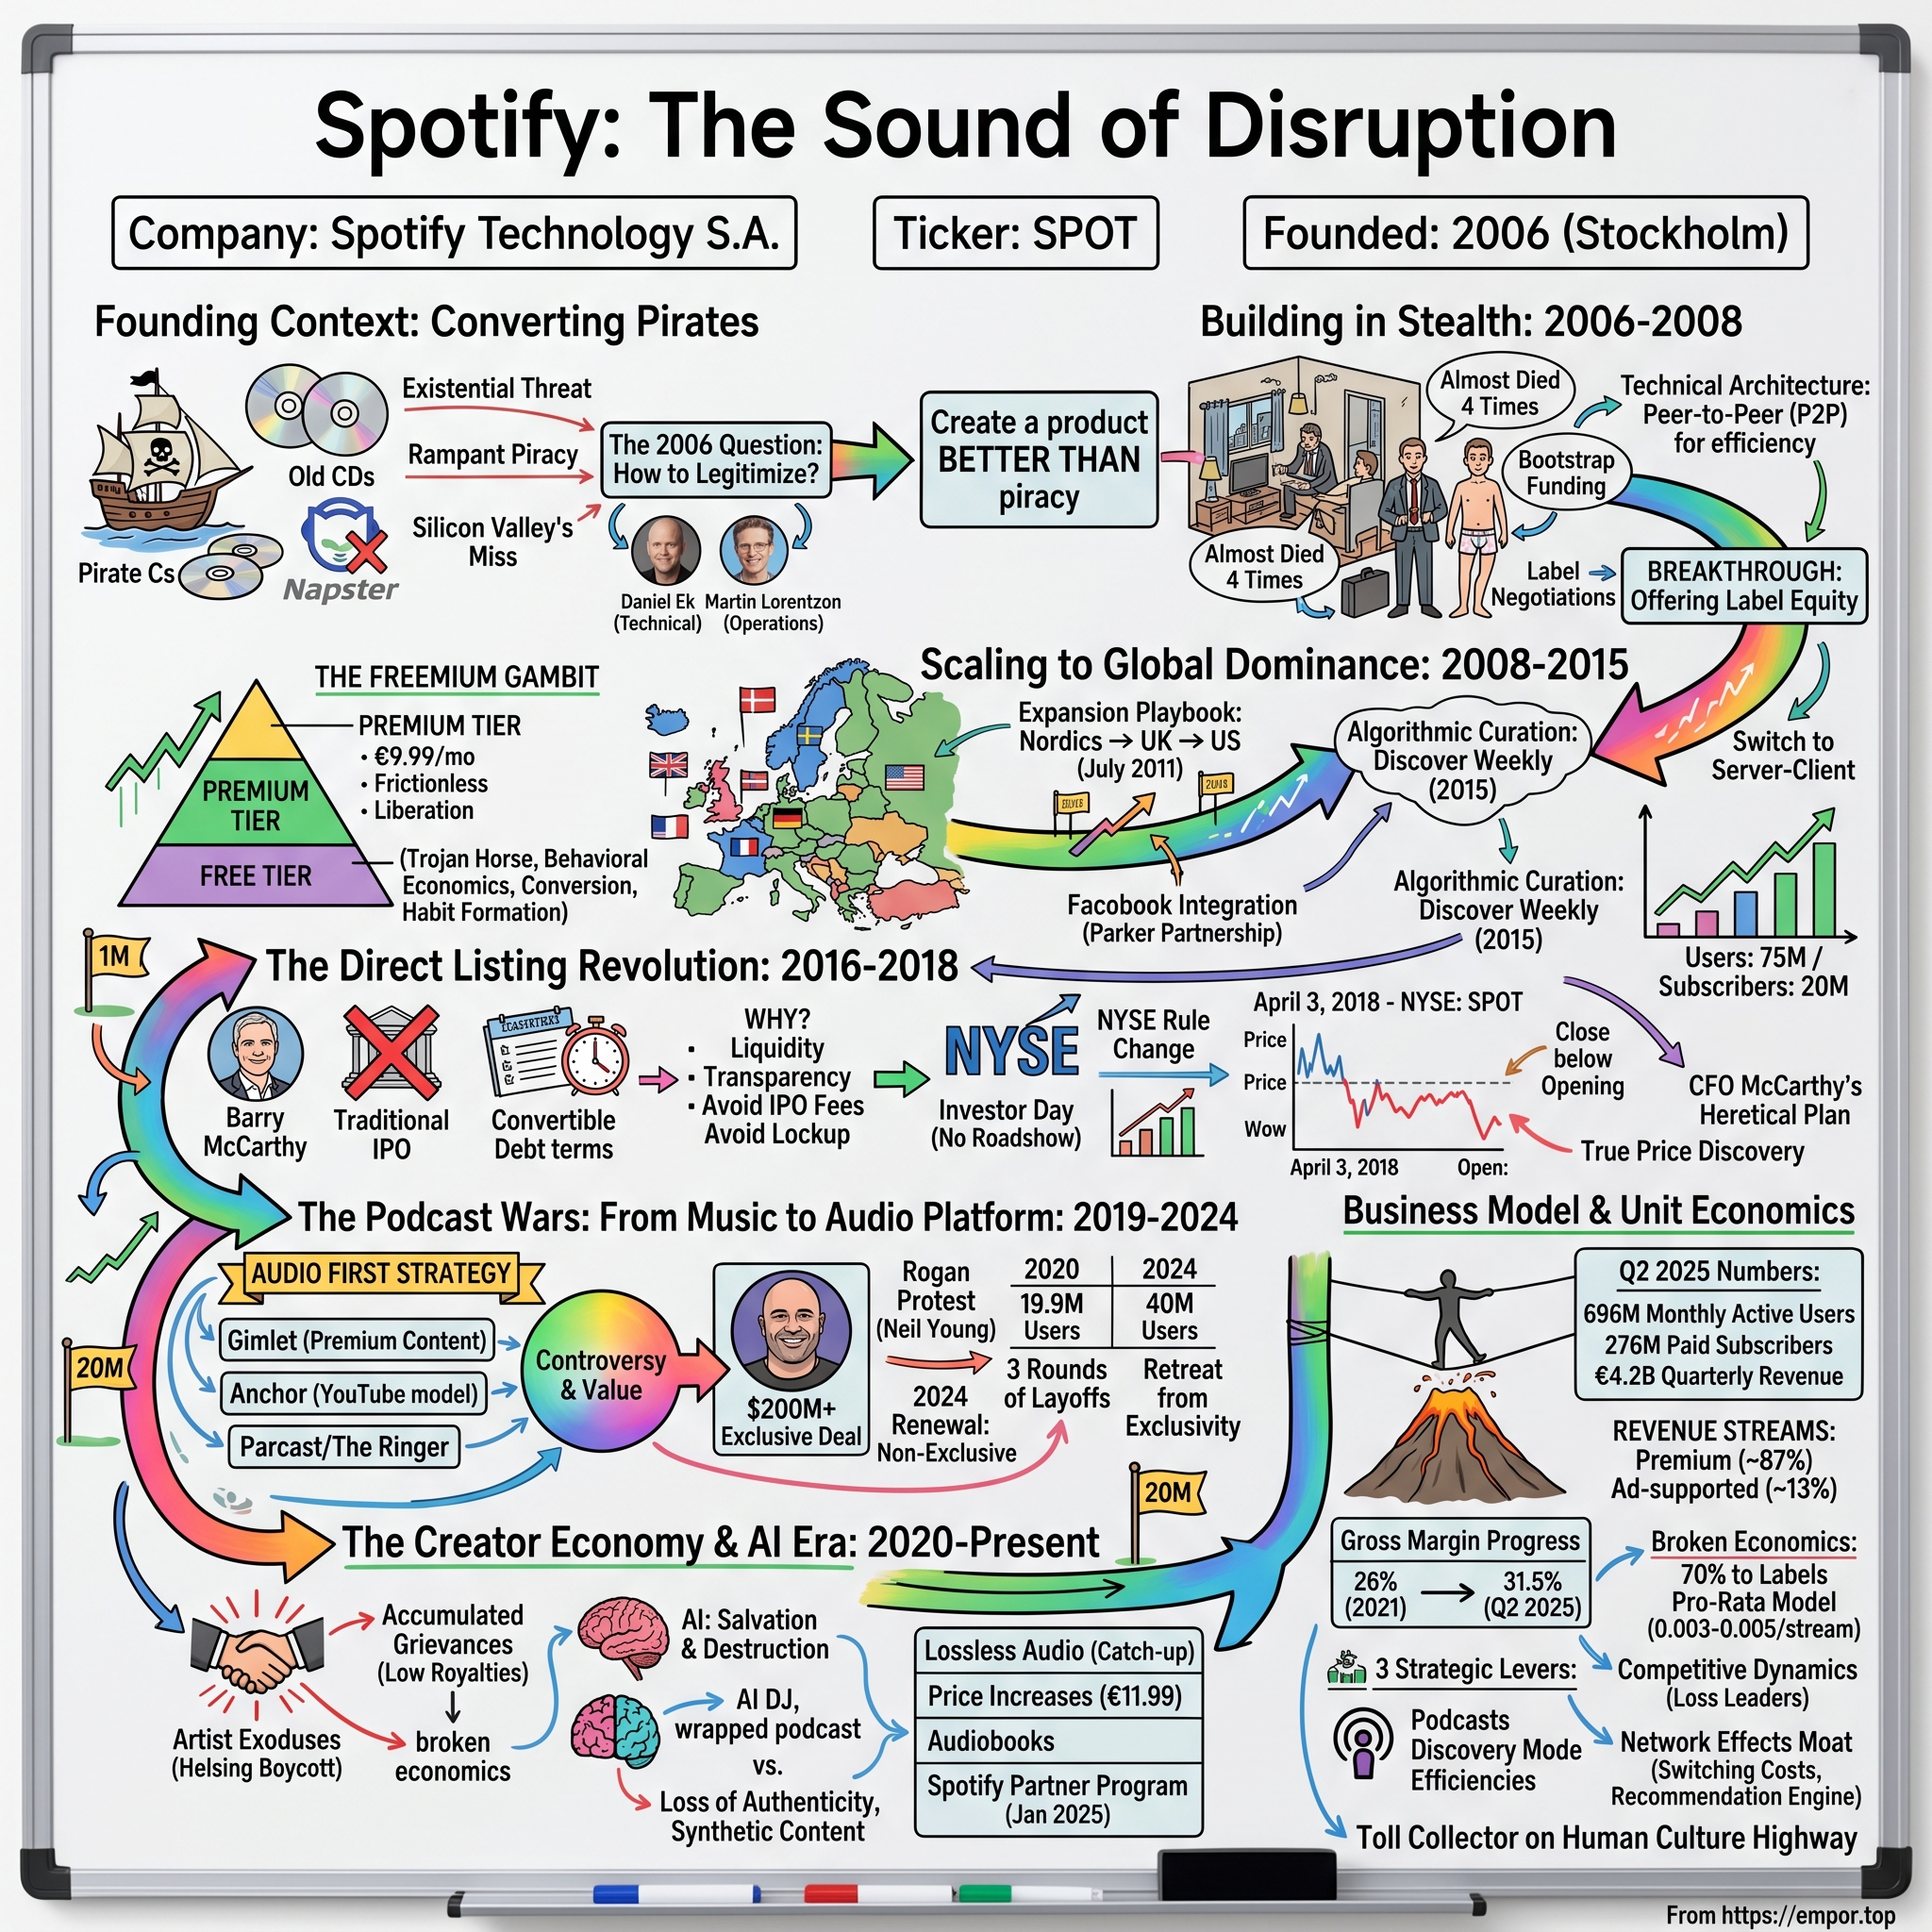
Stockholm in 2006 was an odd place to start a music company. Sweden was then one of the world's capitals of file sharing: The Pirate Bay ran out of the country, and broadband was fast and cheap. Recorded music revenue had been falling for years since Napster cracked open the CD business. A young Swedish engineer named Daniel Ek, who had sold an advertising technology company and was wealthy by his early twenties, came to a conclusion that sounded naive to the music business and obvious to anyone under thirty: you cannot legislate piracy away. You can only beat it with a service that is better than piracy.
Better meant faster. The early Spotify prototype was famous inside the Stockholm tech scene for one thing: you clicked a song and it played, effectively instantly, as if the file were on your hard drive. That was the work of a small engineering team that included Ludvig Strigeus, the developer behind the popular BitTorrent client µTorrent. The first architecture borrowed piracy's own trick, a peer-to-peer network in which listeners' computers helped serve music to one another, cutting bandwidth costs. Later, as the company grew and mobile took over, it moved to a conventional client-server model. The point was never the plumbing. It was the feeling of having every song ever recorded, instantly, for free or nearly free.
Ek's co-founder, Martin Lorentzon, was older and already rich from the online marketing company Tradedoubler. He supplied early capital and the patience of someone who did not need the next round to close. The pair split the roles in a way that would echo for twenty years: Ek the product-obsessed public face, Lorentzon the quiet shareholder whose voting power would later exceed Ek's own4.
The price of permission
Technology was the easy part. The hard part was the labels. Spotify could not legally play a single song without licences from Universal, Sony, Warner and EMI (then still independent), plus the publishers who own the compositions. Those companies had just watched Napster vaporise a large share of their revenue. They had no reason to trust a Swedish start-up offering to give their catalogue away for free with ads.
So Ek and Lorentzon spent the better part of two years negotiating, and the deal they struck set the economics of the company for good. The labels granted licences; in return they received royalty terms that sent most of the revenue back to them, advances and minimum guarantees, and, according to Spotify's own listing documents, equity stakes in the company5. The F-1 filed ahead of the 2018 listing describes the major labels as shareholders and as parties to licence agreements that the company itself listed among its key risks5.
The launch came in October 2008 in a handful of European markets, with an invite-only beta that made access feel scarce and a little cool6. The United States, where licences were hardest to get, took until July 20116. That three-year gap is the clearest measure of label leverage. The best product in the world could not enter the largest music market until the rights holders said yes.
Freemium as a wedge
The model Spotify launched with was freemium. The free tier, supported by ads, was an acquisition funnel: get people listening, build their playlists, make the app part of their lives. Premium, ad-free with offline listening and on-demand mobile play, was where the money came from. The labels tolerated the free tier only because it fed paying users.
Fifteen years later the split still tells the story. In 2025 subscriptions brought in about 89% of revenue and grew about 11%, while ad-supported revenue was about 11% of the total and slipped about 1%1. The free tier was never meant to be a great business on its own, and it still is not. Its job is to convert.
Myth versus reality: "freemium won"
The popular telling is that freemium was a stroke of genius that inevitably won. The record is more uncomfortable. Spotify lost money at the net line every single year from 2015 through 2023, with annual losses ranging from roughly a quarter of a billion dollars to about $1.4bn3. For most of its life the funnel was very good at producing users and very bad at producing profit, because every incremental stream carried a royalty bill.
The fair conclusion is narrower than the myth. Freemium proved that a legal service could beat piracy on convenience and that a large share of free listeners would eventually pay. It did not prove that the distributor of licensed music could earn attractive margins. That second claim was only settled in 2024, and it was settled by price rises and cost cuts as much as by the funnel.
The founding deal is why every later margin question in this story traces back to 2006–2008. The founders traded equity and favourable terms for access. The labels got a seat at the table and a share of every euro. What the founders kept, it turned out, was control of the company itself, and that is where the next chapter begins: on the floor of the New York Stock Exchange, with no bankers in sight.
III. The Direct Listing: No Banks, No Raise (2018)
The morning without a bell-ringing banker
On April 3, 2018, Spotify's shares began trading on the New York Stock Exchange in a way almost nobody had attempted with a company of its size57. There was no initial public offering. No underwriters bought shares and handed them to favoured clients. No new shares were sold, so the company raised no money. Existing holders, employees, early investors and the labels among them, simply became able to sell on the open market.
The exchange set a reference price of $132, and the first trade crossed at $165.907. On a normal IPO that pop would have been "money left on the table", a gap between what the company received and what the market would pay. Here there was no table. Spotify received nothing and gave up nothing, and the price was set by buyers and sellers rather than a book-building process run by banks.
Ek framed it as a principle. Spotify did not need the cash, did not want the lock-ups, and did not want bankers choosing who got allocations. That was true. It was also convenient, because a direct listing involved no new shareholders voting a fresh charter into place. The governance structure the founders had built in private came across intact.
Cleaning the balance sheet on the way in
The financial engineering before the listing is easy to miss. At the end of 2017 Spotify's shareholders' equity was only about $268m, and it carried roughly $1.1bn of borrowings, largely convertible notes issued to investors in 20163. Those notes were expensive, with a coupon that stepped up the longer the company stayed private, and they converted into shares at a discount on listing. One year later, at the end of 2018, borrowings were zero and equity was about $2.5bn3. The convertibles had turned into stock.
So the listing was not quite "no dilution". The dilution happened in the conversion of the notes, which were the cost of staying private for longer than the investors wanted. What the direct listing avoided was the second layer of dilution and the banker fees of a conventional IPO.
The company went back to the debt markets later. In 2021 it issued exchangeable senior notes, and borrowings rose again to about $2.1bn3. Those notes sat on the balance sheet at about €1,458m at the end of 20251, and Spotify repaid them in 2026, leaving them at zero by the second quarter2. The full arc, then, is a company that borrowed as a private start-up, converted that debt on listing, borrowed again cheaply in its pandemic-era peak, and repaid it from its own cash once the business turned profitable. That is a reasonable record. It is not the record of a company that never needed outside money.
The keys stay with the founders
The more consequential feature was governance. Spotify is a Luxembourg company, and its founders hold "beneficiary certificates" on top of their ordinary shares. These certificates carry votes but no economic rights. The effect is a dual-class structure in all but name.
At the end of 2025, by the company's ownership disclosures, Ek owned about 13.9% of the ordinary shares but controlled about 28.8% of the votes, and Lorentzon owned about 9.3% of the shares but controlled about 40.5% of the votes1. Together, roughly 24% of the economics carried roughly 69% of the votes. Tencent, the Chinese technology group (腾讯 Tencent), held about 8.1%, the result of a 2017 share swap with its music arm, 腾讯音乐 Tencent Music Entertainment15.
What does that mean in practice? Spotify files the results of its annual general meetings with the SEC on Form 6-K8. With nearly seven in ten votes in two pairs of hands, those results tell an investor very little about what outside shareholders think. A resolution can pass comfortably with a majority of independent holders against it. So the voting record proves that the founders' wishes prevail. It cannot prove that outside shareholders agree.
The listing, then, was a governance choice as much as a financing one. It gave employees and early backers liquidity, kept the bankers out, and locked in founder control. Shareholders who bought on April 3 bought a share of the profits of a company they could not steer. For the next four years those founders steered it toward the most expensive bet in its history.
IV. The Audio Empire That Wasn't: Podcasts, Rogan, and the Retreat (2019–2024)
The spree
In February 2019 Spotify announced it was buying Gimlet Media, the prestige podcast studio, and Anchor, a tool that let anyone record and distribute a podcast from their phone6. Parcast, a studio known for true-crime shows, followed weeks later. The combined price for the package was reported at roughly $340m67. In early 2020 it added The Ringer, Bill Simmons's sports and culture network, for a price reported at about $196m7.
Then, in May 2020, came the deal that made headlines everywhere. Spotify signed an exclusive licence for The Joe Rogan Experience, then the most popular podcast in the world, for a sum reported at more than $200m7. Rogan's back catalogue would vanish from YouTube and Apple Podcasts. If you wanted Joe, you came to Spotify. The stock rallied hard, and at its peak in early 2021 the market valued the company at more than $70bn; even around the Rogan announcement it was worth roughly $46bn7.
The thesis
The logic was elegant on a whiteboard. Music was a toll road: every stream paid a royalty to the labels, so the more people listened, the more Spotify owed. Podcasts were different. Spotify could own the content outright, or license it on a flat fee, so every extra hour of podcast listening cost almost nothing at the margin. Shift listening time from music to talk, sell ads against it, and gross margin would rise. Ek talked about Spotify becoming "the world's leading audio platform", not just a music app.
There was a second, quieter benefit. Every hour a listener spent on owned content was an hour the labels did not get paid for, which strengthened Spotify's hand in licence talks.
What actually happened
The record does not flatter the thesis. In 2022 Spotify posted an operating loss of about $693m on about $12.3bn of revenue3. In 2023, still deep in the podcast build-out, it lost about $482m at the operating line3. These were the two worst operating years since the listing, and they came at the very height of podcast spending.
Then management unwound the bet itself. Gimlet and Parcast were merged into a single studio in 2023, and most of their original shows were cancelled6. Spotify cut its workforce three times that year, culminating in a December 2023 round that removed about 17% of staff6. In 2024 it renewed the Rogan deal, reportedly for about $250m, but this time non-exclusive: the show returned to YouTube and Apple, and Spotify kept a share of ad sales7. The exclusivity that had been the whole point of the 2020 deal was abandoned.
Management's own actions are the strongest evidence here. A company does not walk away from exclusives, merge its marquee studios and lay off a sixth of its staff if the original strategy is working. These moves amounted to a public admission that buying audio content was not the same as buying audience habit.
Benchmarking the cheques
Was the price too high? Comparable audio deals give a rough yardstick. SiriusXM paid about $325m for Stitcher in 2020, and iHeartMedia paid about $55m for Stuff Media in 2018, both deals that brought large catalogues and ad sales teams9. Spotify's combined outlay on Gimlet, Anchor, Parcast and The Ringer was of the same order as the biggest of those deals, before counting the Rogan licence and hundreds of millions in other exclusive talent contracts.
Set that against what the ad business produced. Advertising, which includes podcast ads, was still only about 11% of revenue in 2025 and shrank slightly that year1. In the second quarter of 2026 it grew about 3%2. Several years and well over a billion dollars of audio investment later, the ad line is a small, slow-growing slice of a business whose profits come overwhelmingly from music subscriptions. On the evidence, the podcast spree was the clearest capital-allocation miss in Spotify's public history: the company overpaid relative to the advertising revenue the assets ever generated.
What survived
Two things are worth keeping in proportion. First, podcasts did do something for engagement: Spotify became one of the two largest podcast platforms, and video podcasts now run on the app. That is a real option on future ad revenue. But an option that has grown ads by low single digits deserves a low weight until it shows up in the numbers.
Second, the more promising bet in this period turned out to be audiobooks. Spotify folded fifteen hours a month of audiobook listening into Premium in 2023 and later launched Audiobooks+, an add-on for heavier listeners. By the second quarter of 2026 Audiobooks+ had passed $100m of annual recurring revenue29. That is small next to €17bn of annual revenue1, but it converts in a way podcasts never did: people pay for it directly. As the next chapters show, bundling audiobooks into Premium also opened a fight with the songwriters.
The podcast story ends with the core business doing the heavy lifting. The music subscription, the toll road itself, carried the company out of the losses. How it did that is the story of the margin flip.
V. The Year the Margin Flipped (2023–2026)
December 2023
On December 4, 2023, Ek sent a memo to staff announcing that Spotify would cut about 1,500 jobs, around 17% of its workforce6. He acknowledged that the company had over-hired in the cheap-money years and said that it needed to be "relentlessly resourceful". It was the third round of cuts that year. The memo read like a founder conceding that the empire-building phase was over.
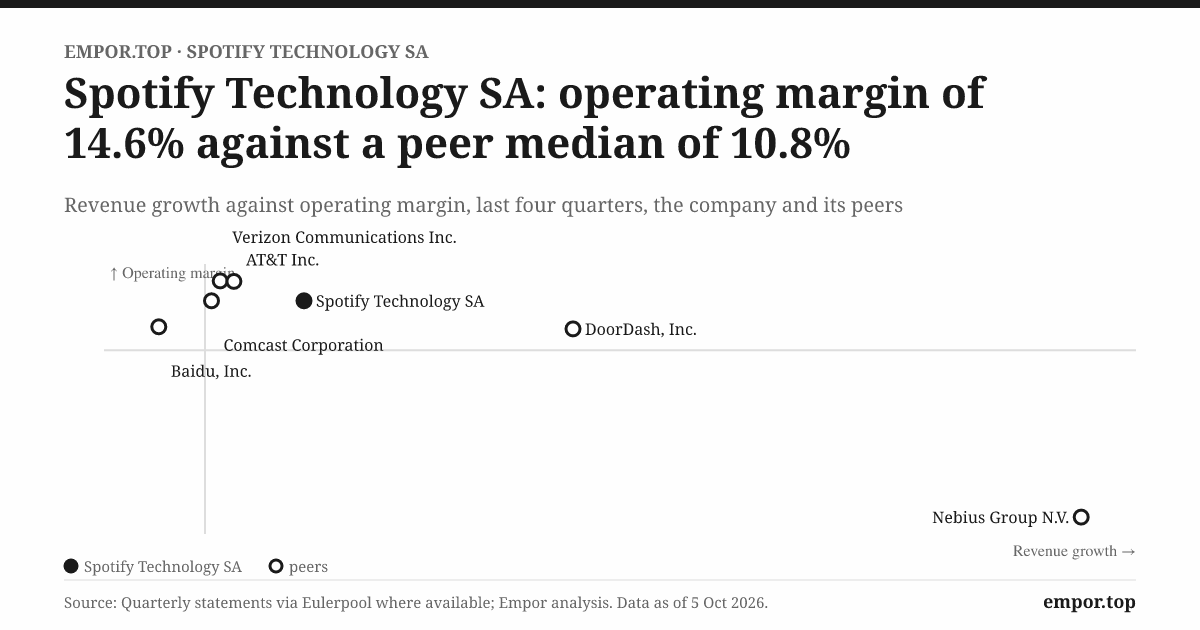
What followed was one of the sharpest profit turnarounds among large technology companies of the decade. Operating profit swung from a loss of about $482m in 2023 to a profit of about $1.5bn in 2024 and about $2.5bn in 20253. In the four quarters to June 2026 it reached about $3.1bn3. Quarterly operating margin moved from about minus 7.8% in mid-2023 to about 13.7% in the second quarter of 202632.
Decomposing the flip
Where did the margin come from? Break it into three pieces.
The first is gross margin, what is left after royalties, payment processing and other direct costs. It stood at 33.4% in the second quarter of 20262, several points higher than it had been in the loss years. Part of that is mix and efficiency: audiobook and podcast economics, marketplace tools that let labels pay for promotion, and better ad pricing. A larger part is price. Spotify raised Premium prices repeatedly from 2023 onward, and because many label deals pay rights holders a percentage of revenue, price rises do not widen the gross margin percentage much on their own. What they do is grow the gross profit pool in absolute euros on a fixed operating cost base.
The second is operating expense. That is where the leverage shows most clearly. In the second quarter of 2026, research and development cost about €403m, sales and marketing about €390m, and general and administrative about €148m2. Together that is roughly a fifth of revenue: about 8.4%, 8.2% and 3.1% respectively. Headcount was about 7,323 at the end of 2025 and about 7,302 at the end of June 202612, essentially flat while revenue grew 14%. Management has said headcount will stay flat through the year4. Spend is still growing, just more slowly than revenue.
The third piece is social charges, a quirk of Swedish payroll rules. Spotify accrues payroll taxes on employee share awards, and the charge rises and falls with the share price. When the stock soared, social charges ate into operating profit; when it fell, they shrank. In the fourth quarter of 2025 they came in at about €50m, about €67m below the company's own forecast4, and in the second quarter of 2026 they were about €1m2. With the shares down nearly 40% from their 52-week high, this line is flattering operating profit right now. It will bite again if the stock recovers.
Structural or not?
So is the margin expansion structural? The honest answer is "partly". Flat headcount and minimal capital spending look durable. Gross margin is a negotiated outcome that depends on label and publisher terms and on how far price rises can run. Social charges are noise tied to the share price. And management is already reinvesting some of the gains: it has guided to about €200m of extra full-year spending on marketing and AI23. A company harvesting a permanent margin would not need to tell investors it is spending more. This one is choosing to.
Profit versus cash
The cash story is stronger than the profit story, and the reason is worth understanding. In 2024 cash from operations was about 154% of EBITDA, and in 2025 about 124%3. Spotify collects more cash than it books in operating profit.
The mechanism is negative working capital. Subscribers pay up front, monthly or annually. Spotify pays the labels and publishers later, often quarterly. In between, it holds the cash. Working capital stood at about minus 107 days of revenue in 20253, which means suppliers and customers together fund more than three months of revenue for the company. Think of a theatre that sells tickets months before it pays the actors. The float is real and free.
But a float has a catch, and the answer to the "is this durable?" question is clear: it only grows while the business grows. If subscriber growth stalls, the float stops growing and the extra cash stops arriving; if the business shrinks, the float unwinds and drains cash. Spotify's cash conversion is a feature of growth, not a permanent property of the model. Free cash flow of about €3.3bn over the last twelve months2, and about €797m in the second quarter of 2026 alone2, is the cleaner anchor for what the business earns, provided growth holds.
Earnings quality
Net profit is where the reported numbers get noisy. In the September and December 2025 quarters, net profit of about $1.1bn and $1.4bn far exceeded operating profit of about $680m and $816m3. For the full year the effective tax rate was about 0.5%3, and two quarters showed negative tax rates, consistent with the company recognising deferred tax assets on past losses as profitability became more certain1. A tax credit of that kind is a one-off accounting benefit, not an operating earning.
Fair-value moves cut the other way. In the second quarter of 2025, operating profit was about $461m but pre-tax profit was only about $54m3, because a rising share price inflated the value of the exchangeable notes Spotify owed, and the company booked that increase as a finance cost1. With the notes repaid, that particular swing is gone. Fair-value moves on Spotify's investment holdings, including its stake in Tencent Music, still flow through the finance lines. In the second quarter of 2026, finance income of about €86m against finance costs of about €21m left net finance income of about €65m2, roughly 9% of pre-tax profit.
FY2025 reported diluted EPS was about €10.51 on profit attributable to shareholders of about €2,212m1. A listener should discount that number. Operating profit and free cash flow are the figures that describe the business.
One small note completes the picture. Receivables are tiny for a business this size. Debtor days fell from about 46 in 2015 to about 19 in 20253, and the balances are owed mainly by advertisers and app-store partners rather than consumers. Nothing in that line looks alarming.
The margin flip, then, is real, and partly durable. What sets its ceiling is the next subject: the people who own the songs and the companies that own the phones.
VI. Pricing Power vs. the Toll Collectors: Labels, Publishers, and the App Stores
Each price rise is a negotiation
Every time Spotify raises the price of Premium, it is really running three negotiations at once. One is with the subscriber, who might cancel. One is with the labels and publishers, whose share of revenue rises in step. And one is with Apple and Google, whose app stores control how Spotify can tell users about the new price.
By 2026 Premium cost €11.99 a month in a number of European markets after successive increases49. The results in the second quarter of 2026 show what the increases bought. Premium subscribers reached about 300m, up about 9%, and Premium average revenue per user was about €4.89, up about 7%2. (ARPU is far below the sticker price because of family and student plans, cheaper emerging markets and currency.) Subscription revenue made up about 89% of total sales1.
So far the subscriber has said yes. That is the evidence for pricing power, and it is real: subscribers kept growing through several rounds of increases.
Testing the pricing-power claim
The test that would falsify pricing power is churn after price rises and a slowdown in net additions. Spotify does not publish churn by market. The best proxy is net adds. In the second quarter of 2026 Spotify added about 7m Premium subscribers2, and in the fourth quarter of 2025 it added about 9m to reach 290m4. Those are healthy numbers for a service of this scale. They narrow the risk but do not eliminate it: the increases are recent, and the evidence of churn tends to show up over several quarters.
The other piece of evidence is management's own behaviour. Spotify guided monthly active users to about 788m for the third quarter of 20262 and said it was deliberately slowing MAU growth by adding friction and more ads to the free tier in some emerging markets3. That is a company choosing revenue per user over reach. A company confident in its pricing power would do exactly this. A company that had run out of new users might also do it.
The real cap on profit
But pricing power over subscribers is not the same as pricing power in the business. Spotify's gross margin of about 33.4%2 means roughly two-thirds of revenue goes to royalties and direct costs. The major labels (Universal, Sony and Warner) and the publishers set the terms of that two-thirds in private licence deals. Spotify does not disclose how much it pays each label or the exact structure of the minimum guarantees1.
For songwriters in the United States, the rate is set publicly. The Copyright Royalty Board, a panel of judges at the Library of Congress, sets the mechanical royalty rates that streaming services pay for compositions10. Its rulings are the single largest regulatory lever on Spotify's gross margin. A ruling that raises the songwriter share by a point or two of revenue would directly reduce gross profit.
The bundle fight
The audiobook bundle showed how sharp that lever is. When Spotify added audiobooks to Premium in 2024, it reclassified Premium in the United States as a "bundle" under the CRB's rules. Bundles carry a lower mechanical rate, because part of the price is attributed to the non-music content. The songwriter royalty pool fell. The Mechanical Licensing Collective, which collects those royalties, sued11. A US court dismissed the MLC's suit in early 2025, though the MLC sought to keep fighting119.
Older disputes fit the same pattern. Wixen Music Publishing sued for $1.6bn in 2017 over unpaid mechanical royalties, and the case was settled in 20185. Eight Mile Style, a publisher of Eminem's early catalogue, challenged both Spotify and the Music Modernization Act in 2019; Spotify prevailed in 20249. None of these cases broke the company. All of them were fights over the same thing: how big a slice of each subscription goes to the people who wrote the songs.
The second toll
Then there is the app-store toll. Apple and Google charge commissions on in-app purchases, and for years both restricted how apps could direct users to cheaper ways to pay on the web. Spotify's own annual report warns that these rules may not apply to the platform owners' competing apps, such as Apple Music and YouTube Music1. Spotify long ago stopped letting iPhone users subscribe inside the app to avoid the fee, at the cost of a clunkier sign-up. European rules under the Digital Markets Act and a 2025 US court ruling loosened some of these restrictions7. But the underlying fact is plain. Apple and Google own both a rival music service and the store that Spotify depends on.
The verdict is clear and should be hedged only once. For now, price rises and bundling carry Spotify's growth, and subscribers have accepted them. The rights-holder share is the real cap on profit, and it is set by people Spotify does not control. That raises the obvious governance question: who inside Spotify gets to decide how hard to push?
VII. Founders, Pay, and the Handover
The new structure
On the fourth-quarter 2025 call in February 2026, Spotify presented a new leadership structure built around two long-serving executives: Alex Norström, who had run the subscription business, and Gustav Söderström, the product and technology chief4. The company's annual report names them as co-presidents and co-chief executives, with Ek moving to the role of executive chairman1. Christian Luiga serves as chief financial officer1.
It was a quiet transition for a founder-run company. Ek had been chief executive for nearly two decades, and the move did not change the vote: with Lorentzon, he still controls about two-thirds of it1. In practice, Ek remains the person investors look to on strategy.
Credibility, scored by behaviour
Management's record can be judged by what it promised and what it delivered. On cost discipline, the 2023 reset delivered almost exactly what it promised. On podcasts, the promises of an audio empire with higher margins did not come true, and management never put a public number on the write-down of that ambition; it simply changed strategy.
Guidance discipline is mixed but explainable. The largest source of misses has been social charges, which depend on the share price and are almost impossible to forecast. In the fourth quarter of 2025 they came in about €67m below guidance4, helping the operating beat. For the third quarter of 2026, management guided to about €670m of operating income2. An investor reading the results on the next earnings day should separate any beat or miss into its operating and social-charge parts before judging it.
Share-based compensation is a material cost in a business that pays engineers partly in stock. Spotify reports it in its annual report alongside key-management compensation1, and the related-party note covers its dealings with Tencent Music1. None of these figures changes the picture of the business. They matter mainly because they explain why the company buys back shares: partly to offset the dilution its own equity awards create.
The stress test: cash without a dividend
A sceptical activist would press on capital allocation. Spotify held about €9.4bn of cash and short-term investments at the end of June 20262, and after repaying the exchangeable notes it has no meaningful debt beyond leases. It has never paid a dividend3. In the first half of 2026 it bought back about $662m of shares, roughly 30% more than in 2025, retiring about 2.2m shares, or around 1% of the total2.
Three questions follow. Why hold so much cash in a business with negative working capital, where suppliers already fund operations? Why buy back at about 26 times earnings12 rather than return cash through a dividend? And what does a free-cash-flow yield of about 3.7% say about the price being paid on those buybacks?
The answers the company has given are about flexibility: cash protects it in licence negotiations and lets it invest when opportunities appear. That is a defensible position. But it is also exactly what a founder-controlled company would say. Control is locked, so the discipline on management comes from the share price, not the vote. That is a neutral fact about the structure, not a judgment of any individual.
Reputation clues
Two episodes from the artist side are worth a sentence each. In 2022 Neil Young pulled his music from Spotify over the Rogan podcast, and others followed briefly7. In 2025 some artists removed their catalogues over Ek's investment company, Prima Materia, leading a funding round in the defence-technology firm Helsing7. Neither had a measurable effect on subscriber numbers. They are reminders that the people who supply the product are also its most vocal critics.
With the governance question settled, the next question is the one that decides whether any of this matters for the long term: how strong is the moat?
VIII. Moat Audit: Porter, Helmer, and the Competition
The listener who doesn't leave
Imagine a listener in Chicago or Berlin who opens Apple Music, YouTube Music or Amazon Music and finds the same hundred million songs. The price is roughly the same. The audio quality is similar or better. Switching would take an afternoon. And yet, mostly, she does not switch.
That puzzle is the moat question in one image. Spotify has about 300m paying subscribers and about 777m monthly users2, more than any Western rival. It has no exclusive catalogue. So what holds people?
Porter's five forces
Supplier power is very high. Three major labels control a majority of the recorded music people stream, and publishers control the compositions. Every streaming service needs all of them. A service that lost one major label would lose a large share of the music its users want, so the labels can extract terms. This is the defining force in the industry, and it is why gross margin sits near a third2.
Buyer power is low. Spotify's customers are hundreds of millions of individuals, each paying around ten euros a month. None has bargaining power.
Substitutes are the real long-term threat. YouTube is the largest free music platform in the world. Short-video apps such as TikTok and its Chinese twin 抖音 Douyin have become a primary way younger listeners discover songs. And AI-generated music, which Spotify itself lists among its risk factors1, could eventually supply cheap, unlicensed tracks that compete for listening time.
The threat of new entrants is limited. A new service would need licences from every major label and publisher, plus the scale to justify minimum guarantees. That barrier protects Spotify from start-ups but not from Apple, Google and Amazon, who have deep pockets and their own platforms.
Rivalry is intense but rational. The big players have kept prices close to one another, and raised them in rough step.
Helmer's seven powers
Scale economies are present. Spotify spreads its fixed costs, product, engineering and marketing, across the largest subscriber base in the West, which is why flat headcount produced such operating leverage. Its rivals subsidise music from other businesses and can afford lower margins, so scale alone is not a decisive edge.
Switching costs are present but soft. Playlists, listening history and "Discover Weekly"-style recommendations are hard to rebuild elsewhere. The more years a listener spends on Spotify, the better it knows her taste. The AI "Large Taste Model" that Spotify discusses on its calls is an attempt to deepen this: about a quarter of active users now use the app's AI features, such as the AI DJ and AI playlists3. That data is a genuine advantage, but tools to move playlists between services already exist.
Habit and brand play into this. Spotify is the default verb for music streaming in much of the world. Network effects are weak: listeners do not gain much from each other being on the same service, beyond shared playlists and the year-end "Wrapped" ritual.
Counter-positioning is thin. Spotify's early advantage was that the labels, iTunes and piracy could not copy a free, legal, instant service without cannibalising themselves. That advantage is long gone. Cornered resources, such as exclusive catalogues, Spotify does not have. Process power, its ability to ship product and run experiments quickly, is real but hard to measure.
The numbers that do and don't help
Two figures look like moat evidence but are not. Return on invested capital was about 267% in 20253, an extraordinary number that reflects how little capital the business uses rather than how strong its position is. With negative working capital and almost no fixed assets, invested capital is close to zero, so almost any profit produces a huge ratio. Asset turnover of about 1.143 reflects the large cash pile more than the business.
Peer scale helps more. Spotify does not publish market share, and rivals publish little. Apple and Amazon do not break out subscriber numbers for their music services. Tencent Music, the leader in China, reports its own paying users separately. What can be said is that Spotify is the largest paid music service outside China by its own reported subscriber count2.
The verdict
The moat is real but narrower than the margin suggests. Scale, data and habit hold users, and the subscriber growth through price rises shows it. But the catalogue is identical across services, which means the labels have more bargaining power over Spotify than Spotify has over its users. The confirming signal would be gross margin holding or rising through the next round of major-label renewals. The falsifying signal would be a licence deal that forces gross margin back down, or a rise in churn after the next price increase.
That is the moat. Now the playbook: what Spotify's story teaches founders and investors.
IX. Playbook: Lessons From Spotify
Rent the catalogue, own the relationship
The vivid moment is 2008–2011: a product so good it felt like magic, waiting three years for permission to launch in America. Spotify proved that you can build a giant on rented inventory if you own the customer's habits. It also proved the cost. Every song on Spotify belongs to someone else, and that someone sets most of the price. The lesson for founders building on licensed content, whether music, data or models, is that the relationship is yours but the margin is negotiated. The line to remember: You can own the listener and still rent the music, but the landlord sets the rent.
Spend to shrink
The vivid moment is December 2023: a founder telling a sixth of his staff they no longer had jobs, followed by a swing of roughly $3bn in annual operating profit within two years36. The lesson is not that layoffs create value. It is that the operating leverage Spotify had always promised investors was hidden under a cost base that had grown with the hype. The line: The profit was always there; it was buried under the headcount.
Buying audio is not buying habit
The vivid moment is the Rogan exclusive of 2020, and its non-exclusive renewal four years later7. Spotify paid top dollar for content and audiences, then discovered that listeners came for the music and stayed for the music. Exclusivity did not move them, and the ad revenue never caught up. The line: You can buy a show; you cannot buy the habit of listening to it on your app.
Direct listing keeps the keys
The vivid moment is April 3, 2018, with the first trade at $165.90 and no bankers in sight7. The direct listing became the model for other founder-led companies that wanted liquidity without dilution or underwriter fees. It also carried the founders' voting control straight into public markets. The line: A direct listing sells the shares and keeps the keys.
The lessons point to the same tension. Spotify's founders built the most-used music service in the world, kept control of it, and finally made it profitable. What they never owned was the road. That is what the market is now trying to price.
X. Bull vs. Bear and the Valuation
The price on the screen
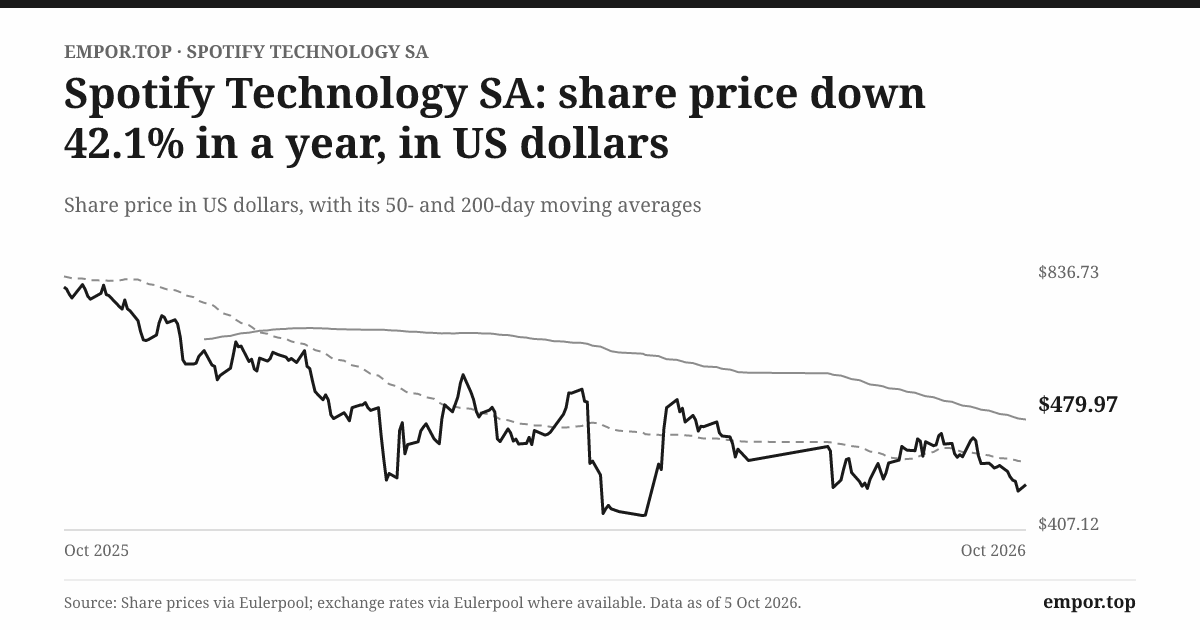
On October 5, 2026, Spotify's shares closed at about $428.5212, about 38% below their 52-week high of about $69212. Over the past year the stock's annualised volatility was about 55%, and over five years it has fallen as much as 53% from a peak12. This is not a quiet utility stock. It is a company whose valuation swings with investors' confidence in the next licence deal and the next quarter's margin.
At that price the market values the company at about $99bn, or about $89bn net of cash12. The shares trade at about 26 times trailing earnings12. That looks cheap next to the stock's own five-year median of about 88 times, but the median is a poor anchor: it was inflated by years when earnings were close to zero. Earnings themselves are noisy, given the tax credits described earlier, so the more useful measures are enterprise value at about 22 times EBITDA and about 30 times operating profit, and a free-cash-flow yield of about 3.7%12.
What does that price assume? Roughly this: that operating profit keeps growing faster than revenue for several more years, that gross margin does not slip in the next licence round, and that the cash float keeps growing. It is a price for continued operating leverage, not for perfection. Netflix, the closest comparison as a subscription media platform with high fixed content costs, has traded at similar or higher multiples on higher margins13. Warner Music, a supplier, has typically traded at lower multiples on its own stable royalty streams14. Spotify sits between the two: valued more like a platform than a supplier, but with the supplier's margin as its constraint.
The bull case
The bull case runs on price and leverage. Subscribers have accepted several rounds of increases, with ARPU rising about 7% and subscribers about 9% in the latest quarter2. Add-ons such as Audiobooks+ and future higher-priced tiers can push revenue per user further. Headcount is flat, capital spending is minimal, and roughly €3.3bn of annual free cash flow sits on a balance sheet with net cash2. If gross margin creeps up and operating costs grow more slowly than revenue, operating margin keeps expanding and today's multiple looks reasonable in hindsight.
The bear case
The bear case runs on the toll collectors. Label and publisher contracts can claw back margin at each renewal, and a CRB ruling can raise songwriter rates. The free tier is slowing by design, and if the funnel narrows too far, Premium growth slows with it. AI-generated music may flood platforms with cheap supply, which could either lower Spotify's costs or erode the value of a curated catalogue; nobody knows yet. Reported earnings are flattered by tax credits and finance gains. And the cash float that makes free cash flow look so strong would shrink if growth slowed.
Weighing them
On the evidence, the bull case is strongest on cost and the bear case is strongest on the labels. Spotify has shown it can control its own costs; it has not shown it can control its largest one. The case turns on two things: gross margin through the next major-label renewals, and the ad business finally growing.
Three things to watch
The first KPI is Premium net additions together with ARPU: about 7m net adds and €4.89 ARPU, up about 7%, in the latest quarter2. Both rising together is the sign of pricing power that does not cost subscribers.
The second is gross margin: about 33.4% in the latest quarter2, up from the loss years. It is the clearest single read on the balance of power with the labels.
The third is advertising revenue growth: about 3% in the latest quarter2. If podcast and video advertising are going to justify the money spent on them, this is where it will show.
XI. Epilogue: The Next Moments That Decide It
Tonight Spotify stands as a profitable, cash-rich, founder-controlled company with a share price well off its highs. The next few months bring the moments that will settle much of the case.
The first is third-quarter 2026 results, due in late October. Management guided to about €670m of operating income and about 788m monthly active users2. A beat driven by operations rather than social charges would support the argument that margin expansion is durable. A miss on users, if it came with weaker Premium net adds, would suggest the free-tier friction is costing more than management expected. Either way, investors should strip out social charges before deciding what the quarter means.
The second is the cycle of major-label licence renewals and any CRB proceeding on songwriter rates10. Spotify does not disclose renewal dates for individual labels. What can be said is that every renewal is a test of the central question: who captures the value? A deal that keeps gross margin around a third, or lets it rise, would show that scale gives Spotify negotiating leverage. A deal that pushes it down would show the opposite.
The third is quieter but important for anyone valuing the earnings. The next annual report's tax note will show how much of the deferred tax asset on past losses has been recognised, and how much remains. That settles how much of the 2025 net profit was a one-off accounting gain and how much future earnings will be taxed at a normal rate1.
Set against the four questions, the outcomes map simply. If margins hold through renewals, the expansion is structural, not just a price story. If tax normalises without hurting cash flow, operating profit was always the right anchor. If ad revenue grows alongside subscriptions, the monetisation strategy can sustain double-digit growth. And if the labels win the next round, the answer to who captures the value will be the same as it was in 2008.
The tension that remains is the one that has always defined Spotify: a company that owns the listener's attention, but not the songs.
XII. Outro
Go back to the opening scene. About 7,300 people now serve about 300m paying subscribers and hundreds of millions more who listen for free. Spotify has become one of the most efficient media companies in the world, and in the last two years one of the most profitable. Yet most of each euro a subscriber pays still goes to someone else: the labels, the publishers, the songwriters, the app stores.
The company that set out to beat piracy did beat it. It built the most profitable toll road in music. It just never owned the land the road runs on. Spotify won the listener, but it is still negotiating with the people who own the songs.
References
-
Form 20-F FY2025 — SEC, 2026-02-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Form 6-K, Q2 2026 results (Exhibit 99.1) — SEC, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Spotify Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Spotify hits 290m paid subscribers in Q4, posts $2.5bn annual operating profit for 2025 — Music Business Worldwide, 2026-02 ↩↩↩↩↩↩↩↩
-
Spotify F-1 registration statement filings (2018 direct listing) — SEC EDGAR ↩↩↩↩↩
-
Spotify 6-K filings list (quarterly results, AGM notices and voting results) — SEC EDGAR ↩
-
Music Business Worldwide — industry coverage of label deals and royalties ↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube